Small Cap Value Report (Tue 16 Feb 2021) - BWNG, NEXS, CLX, BLTG, SYME, Virgin Wines

Good morning, it’s Paul & Jack here with the SCVR for Tuesday.
Agenda -
Paul's section:
N Brown (LON:BWNG) - Substantial Director buying.
Nexus Infrastructure (LON:NEXS) - very vague trading update, looks like a veiled profit warning to me.
Blancco Technology (LON:BLTG) - interim results, not up to scratch in my view. Lots of costs capitalised into intangibles, as usual.
Supply@me Capital (LON:SYME) - vague statement about delayed relisting. I cast my eye over the admission document (it's not pretty!)
Virgin Wines - intention to float.
Jack's section:
Calnex Solutions (LON:CLX) - recent IPO continues to exceed expectations. Shares are expensive but there's good growth here.
.
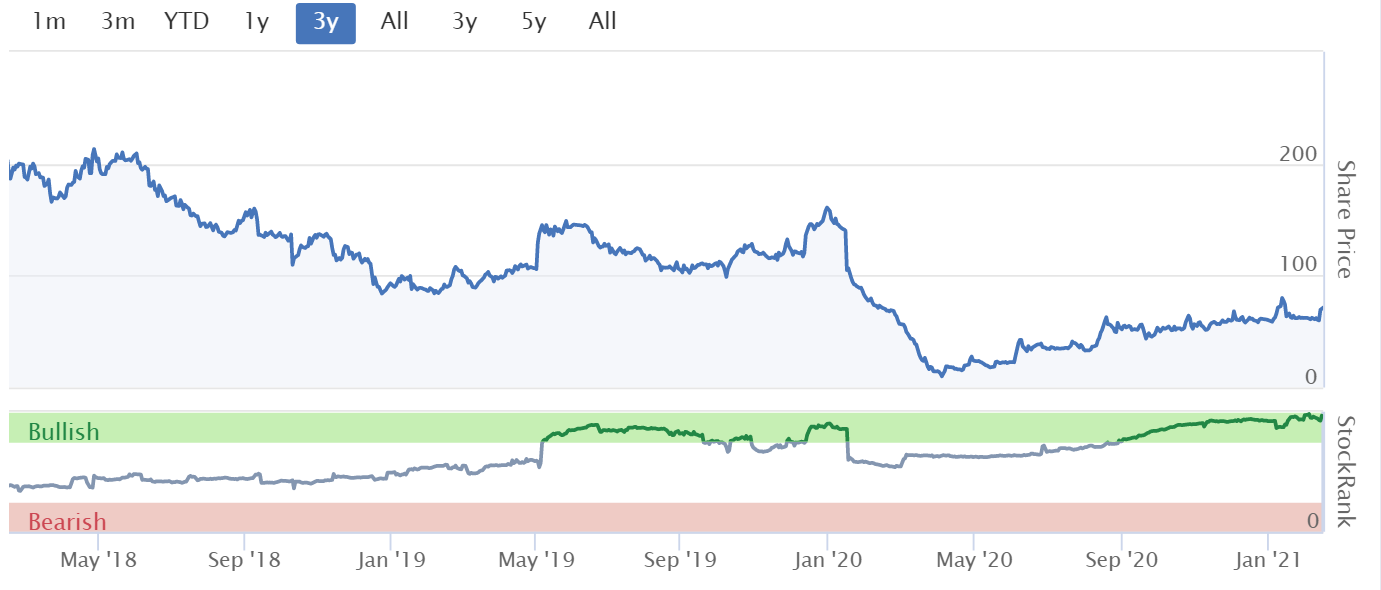
N Brown (LON:BWNG)
71.3p - mkt cap £328m
Jack flagged some Director buying here last week, so I’ve had a quick recap.
Here are my notes on 15 Jan 2021, from the Q3 trading update. This showed an improving, albeit still negative revenue trend. My conclusion was “potentially interesting”. It’s been on my watchlist, so the Director buying RNSs got automatically emailed to me recently, with Jack also jogging my memory to look at them.
Lord David Alliance is the major shareholder here, with 40% (he’s a billionaire, according to Wikipedia), and cornerstoned the recent fundraising (and move to AIM).
15-Feb-2021 - Joshua Alliance (a NED) increases from 3.88% to 4.61% on 12 Feb 2021 (21,213,800 shares now held). That’s a purchase of 3.365m shares at 64.65p, costing £2.175m
This change was announced twice, in a Director shareholding, and a Holding in Company announcements.
12-Feb-2021 - Joshua Alliance (a NED) increases from n/a to 3.88%, and now has 17,848,800 shares. This is an increase of 7,848,800 shares, bought at 65.0p, for £5.1m. The original 10.0m shares were bought in the placing in Dec 2020, at 57p, costing £5.7m.
The internet says that Joshua is the 31-year old son of 88-year old Lord Alliance.
Doing a bit more googling suggests that they got a whitewash as part of the last fundraising, which ensured going over 30% did not trigger a requirement for the family to launch a takeover bid, under Takeover Panel rules.
My opinion - with the Alliance family now owning 52%, and Joshua having just spent £7.3m buying shares in the open market, it’s probably safe to assume that the company could continue to report further improved trading.
For that reason, I’m getting more interested in this share.
EPS forecasts fell a lot, and now include dilution from the Dec 2020 fundraising (which increased the share count by 59% to 460.5m). If it achieves forecast of about 9p EPS for FY 02/2021, then the market might wonder why the rating is only a PER of 7.9 - which looks very low for an eCommerce/extended credit business.
In the past, N Brown was a bit of a mess, with lots of things needing a proper sort out. Heavy Director buying suggests to me that some progress has probably been made. Combine that with the low valuation, and I think this share is now looking interesting as a possible purchase.
.
.
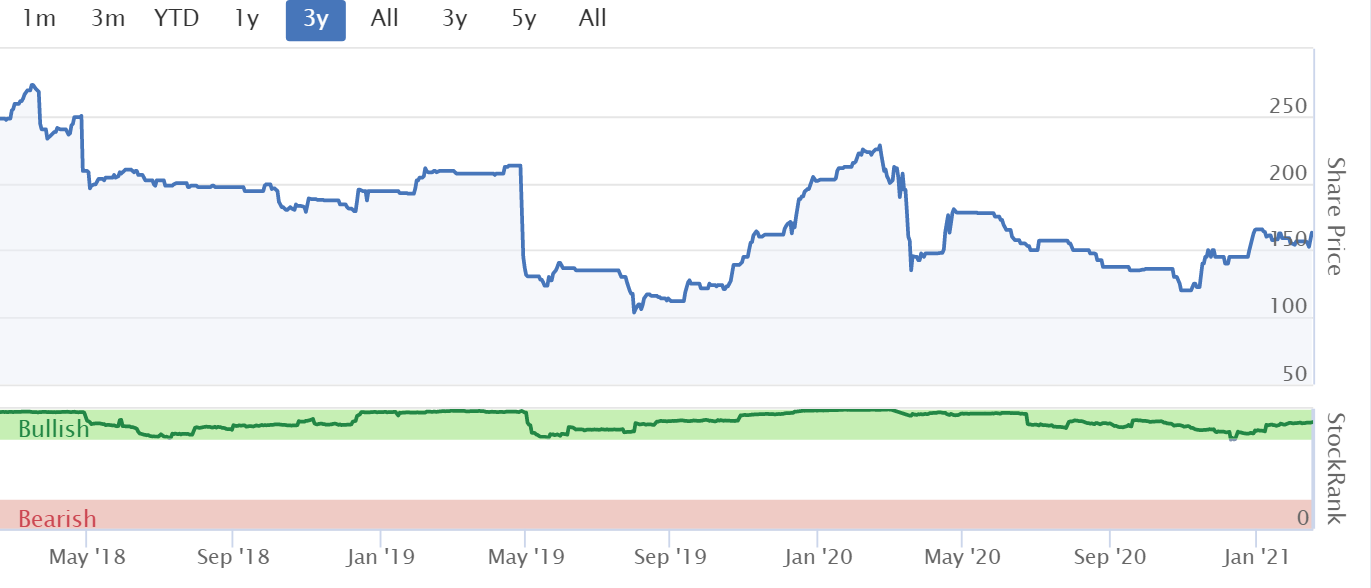
Nexus Infrastructure (LON:NEXS)
163p (pre market open) - mkt cap £74m
This infrastructure company floated in July 2017, but I lost interest in it gradually as results seemed a bit erratic. It has a 30 Sept 2021 year end, and reports today on trading, at its AGM.
Today’s update is not terribly informative. Summarising it -
- Market fundamentals good, due to Govt stimulus for housing, renewable energy, and electric vehicle charging.
- Trading conditions good at TriConnex and eSmart, both performing ahead of base case in June 2020 placing
- Tamdown - continued challenges due to covid. Trading towards downside scenario. Expected to improve as industry activity normalises.
- Strong balance sheet (no figures given)
- Order book of £279m (no comparison figures given)
Outlook -
… Nexus remains on-track to implement its recovery and growth strategy with a return to pre-Covid levels of activity in FY22."
That implies FY 09/2021 won’t be much good then, so is this a profit warning?
Last full year results - FY 09/2020, I’ve had a quick review of these numbers, to fill in some of the gaps left by today’s trading update.
The group made a small adjusted loss of £(2.5)m, which I can understand due to the pandemic. The order book was £282m, so the figure of £279m given today is slightly down.
Tamdown is by far the largest division, producing 68% of total group revenue. It says that Tamdown had its “best quarter for work winning since 2019” in Q1 to date (Oct-mid Dec 2020) - this sounds a lot more bullish than the update today for Tamdown.
eSmart Networks looks insignificant at this stage, only producing £2.2m revenues in FY 09/2021.
The last reported balance sheet, at 30 Sept 2020, looks OK, with £26.4m NTAV.
My opinion - today’s update seems very vague. There are no figures given re performance, and no mention of overall performance versus expectations. It mentions how the various divisions are performing, but we’re not told how significant each one is.
There’s nothing available on Research Tree, so it’s anyone’s guess how the company has been briefing analysts. I can only conclude, from the lack of information in the update, that this seems to be a rather clumsy attempt to obscure a profit warning. The share price has opened down 13p, 8% this morning, which suggests other people agree that this sounds a negative update, but with no specific figures. The company certainly needs to review its communications strategy.
With nothing concrete in the update, and no broker notes available, I’ll just avoid this share until the interim numbers come out. Then we might be able to make sense of how it’s actually trading.
Stockopedia seems to like it, with a high StockRank.
.
.
Blancco Technology (LON:BLTG)
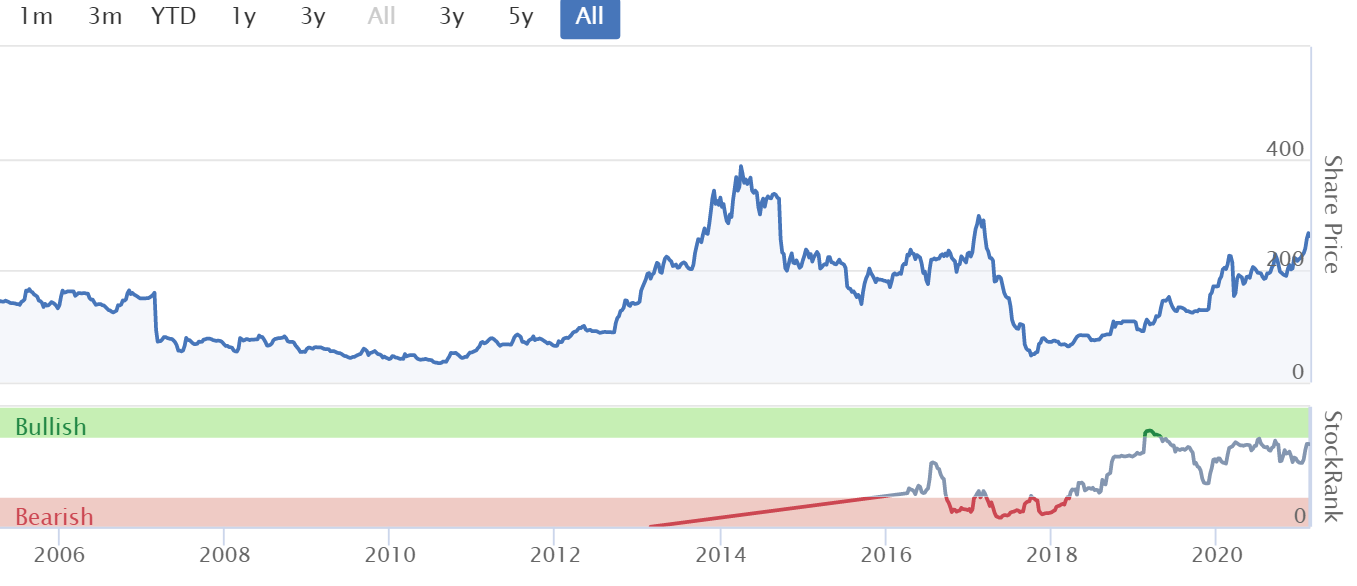
268p (down 1% at 08:57) - mkt cap £198m
Continued momentum driven by underlying structural growth with strong progress anticipated in second half
Blancco Technology Group plc (AIM: BLTG, "Blancco", the "Company" or the "Group"), the industry standard in data erasure and mobile device diagnostics, is pleased to announce its unaudited interim results for the six months ended 31 December 2020.
It hasn’t taken me long to unpick these numbers, and work out that Blancco doesn’t really make much money! That’s why it hasn’t paid any divis since 2017.
EBITDA is meaningless, because the company capitalises a lot of costs onto the balance sheet. EBITDA ignores this capitalisation, and also ignores the amortisation of it too. It’s like waving a magic wand to make millions of pounds of cash outflows vanish - i.e. fantasy. Capitalisation of costs is reasonable, but you have to base valuation on numbers which include either the capex, or the amortisation charge. EBITDA ignores both, so is meaningless.
H1 revenue was flat vs H1 LY, at £17.4m
Profit before tax was only £0.5m (down 21%)
The cashflow numbers shown in the financial highlights are not real to my mind, because they’re ignoring so many costs. If we look at the cashflow statement itself, the £5.2m of operating cashflow is halved by £2.6m in capitalised development spend. If you look at the last full year, then £5.7m of operating cashflow was largely consumed by £4.7m in capitalised development spend. In other words, the business doesn’t generate much cashflow at all, after all costs are taken into account.
Outlook - Blancco faced some headwinds in H1, namely covid disruption (fair enough) and a contract ending which generated £1.4m in H1 LY.
The commentary sounds upbeat, e.g.
The Board is confident that Blancco is positioned to deliver sustained levels of growth going forwards in line with our expectations."
It certainly needs to deliver strong growth, as the £200m mkt cap doesn’t stack up at all on the basis of the H1 numbers.
Note that share based payments are adjusted out, but are quite considerable, and recurring. I would treat this as payroll costs, so adjust them back in. That’s £767k in H1.
Balance sheet - is modest, once you deduct the £71.5m intangible assets, we get to only £4.9m NTAV.
My opinion - these figures don’t show a cash generative business. The profits & supposedly positive cashflows come from adjustments and capitalising costs. Once you unpick that, there’s really not much here. That’s why it can’t pay dividends, because it’s not generating any reliable cashflows.
It might be that business may improve in future, and the commentary seems confident about an improved H2. It needs to deliver that, to get anywhere near justifying the £200m market cap. I wouldn’t pay a quarter of that, based on these figures.
I see this share as quite risky - because the valuation seems to have run so far ahead of reality (where reality is genuine cash generation). It's the sort of thing that gets really whacked when the bull run ends, and the market starts to properly scrutinise the real world numbers. Hence, if it fails to deliver the strong growth it promises, then I see this share price as an accident waiting to happen.
The company has disappointed before remember (see the long-term chart below). It was set up by financial engineers, and hyped up well beyond reality, then the price began collapsing shortly after a £17m Director sale of shares in 2014. Therefore, I would keep a very close eye on Director transactions in the future.
.
.
Supply@me Capital (LON:SYME)
Suspended at 0.51p - mkt cap £167m
A reader talked me into having a look at this share quite recently, but unfortunately I didn’t tag it in the report, so it’s not coming up on a search result. Amazingly there are 32.75bn shares in issue! Which gives me an inkling that it’s probably not at the top end of the market’s quality offerings.
From what I can remember, I followed through the various news announcements concerning this share, and concluded that it’s currently impossible to value. That’s because we don’t really know what the business that was reversed into the cash shell, is actually like. It’s some Italian asset funding company, providing loans against customers’ inventories - not a good business model historically, that’s why hardly anyone does it any more.
Regarding the suspension of its shares, this seems to be what has happened:
21 Jan 2021 - Temporary suspension, pending publication of accounts for FY 12/2019 and H1 2020 accounts.
28 Jan 2021 - Statutory, audited accounts for FY 12/2019 published.
29 Jan 2021 - Interim Results for the 6 months to 30 June 2020 published.
4 Feb 2021 - Update on Relisting - SYME says that it has remedied the technical DTR breach, by publishing its financial statement. Delays are now with the FCA. No FCA investigation is underway.
The process has taken longer and is more complex than normal due to the change in accounting reference date, RTO transaction occurring during the period, and multiple financial statements that have been issued.
16 Feb 2021 (today) - Update on Restoration of Listing - the company is in regular contact with the FCA. Temporary suspension of shares is not having any operational impact. Timetable for relisting is outside its control.
My opinion - it seems a rather unusual situation. Relistings normally happen quite quickly. Last time I looked at this share, I concluded it wasn’t possible to form a view because the published accounts relate to the cash shell, not the business that was reversed into it.
It occurred to me this morning that the Admission Document would have more information. So I’ve had a browse through it. This confirms my suspicions that there’ nothing of any substance here. The historic, and pro forma accounts for the Italian operating company are laughable, as you can see. It’s just a startup:
.

.
Clearly what they’ve done, is come up with a bonkers high valuation in the RTO, probably with a view to selling as many shares as possible to gullible punters, before the valuation collapses at a later date, when people realise there’s nothing of any substance here.
The balance sheet is also a complete joke! (see below). The only significant asset is intangibles, created out of thin air!
.

.
An alternative view might be that, given it’s got something to do with blockchain, maybe we should just value it at a trillion euros, and all go on a frenzied buying spree when the shares return from suspension? You can probably guess what my conclusion is on this share - one for mug punters only, but in this market, you could end up fluking a multibagger, as all sorts of rubbish is multibagging right now. Remember though that it’s not a profit until you’ve sold.
We're very clearly in the final, euphoric mania of a bull market, where stuff like this can go stratospheric for a little while. It's reminding me more by the day, of what 1998-99 was like. We all know how it's going to end, the only question is the timing of the bubble bursting.
I'm also a fan of the Grant Williams podcasts mentioned here several times by readers. He has such interesting guests on (usually bearish, and dismayed!), and the interviewing style is very good - just let the experts talk, and don't interrupt them. You have to pay now, and I think the content is so good, that paying $120 for a year's subscription, is well worth it. A recent guest was saying that shorting is now too dangerous, as Gamestop demonstrated, because so many market participants are now completely ignoring fundamentals.
I remember when it got like that in 1999 too, and it ran on for far longer than most people thought it could. Most people realised that what was happening (speculative tech shares going parabolic) couldn't last, but the party carried on for an amazingly long time. Plus there were very strong rallies on the way down
Eventually, the mania in speculative stocks sucked money out of value shares, which were clobbered in a dash for mostly trash. The interesting point though, is that when the tech bubble finally burst in early 2000, Grant Williams points out that value shares did a lot less badly than speculative shares in the ensuing market rout that went on until early 2003.
I can remember giving up on tech shares in mid 2001, and focusing on deep value, and did extremely well for the next 2 years, that was how I got started as a professional investor. On the basis that I'd made 16-times my money in the bear market of 2001-2, with no leverage, going long of oversold value shares, so should do more of it, with my day job of being a CFO taking up too much of my time!
Thinking about the USA in particular, there must be millions of people who think it's easy to make money from shares, and Bitcoin. They buy every dip, thinking it's a fail-safe way to make big bucks. Little do they know that, sooner or later, the market will chew them up & spit them out. All the warning signs are there, that we're not far from a market top, in my opinion. When buy the dip stops working, I think everything is in place for a really big correction.
.
Virgin Wines UK plc
This calls itself one of the UK’s largest direct-to-consumer online wine retailer.
Today’s announcement is a whet our appetite thing, with bullet points telling us about the business. It sounds quite interesting actually.
A few numbers also appear:
Last twelve months (“LTM”) to 31 Dec 2020: revenues £71.0m, EBITDA £7.7m.
The plc is newly created, so I’ve looked for the operating company on Companies House website, which seems to be Virgin Wines Holding Company Ltd (company number 7970057). The most recent filed accounts for FY 06/2019 show a small business (revenues of £42.5m), delivering modest growth of 6.4% revenues on the prior year, and operating around breakeven, £164k PBT, versus a £(617)k loss the prior year. There is £1.2m p.a. interest costs from investors though, included within that breakeven result, based on £12m in shareholder loans. The financial backers are Mobeus Equity Partners LLP, and Connection Capital LLP.
So my immediate question is, have they had a one-off bonanza from lockdown, with pubs shut, and maybe fluffed up the figures for an opportunistic float? It’s probably likely to be a private equity full or partial exit, by the looks of the shareholders. There are various classes of share capital, which would need to be cleaned up into a single class of ordinary shares as part of the float, if it goes ahead.
The telegraph reports here that the valuation is to be set at c. £100m, which looks steep to me, given that there’s not a long track record of profitability.
My opinion - good luck to them, and I very much welcome the current spate of new listings. We need fresh blood, as the London market has become stale, with many of the best companies disappearing from takeover bids, and too much speculative junk left behind from previous investing fads.
Virgin Wines looks an OK company, nothing special though. It’s been around for a while, and the big question is whether profits during lockdown will be sustainable once people can go to the pub again? I shall await the admission document with bated breath. Also, I wonder what the financial arrangements are for it to use the Virgin name?
.
Jack’s section
Calnex (LON:CLX)
Share price: 118p (pre-market open)
Shares in issue: 87,500,000
Market cap: £103.25m
There have been a couple of intriguing IPOs recently, with one of the top candidates being £CLX. Today we have an update (we looked at CLX in a little more detail here if interested), from this designer, producer and marketer of test and measurement solutions to telecoms networks operators.
Founded in 2006 by CEO and 21% shareholder Thomas Cook, CLX is headquartered in Linlithgow, Scotland, with additional locations in Belfast, Northern Ireland and California in the US, and with sales teams in China and India.
Its trusted products play an important and entrenched role in validating the performance of critical infrastructure in this global growth area. The global network it has established of partners also provides a worldwide distribution capability, allowing it to rapidly introduce developed and acquired solutions to a large potential customer base.
I have a positive impression of its prospects, and this update goes some way to validating that impression. The only question now is valuation, given the shares are not quite the bargain they were. Congratulations to holders so far - an exceptional return in such a short timeframe:

The COVID-19 pandemic has not disrupted Calnex’s operations - in fact the board believes it may have brought some revenues forward into FY21.
As a result, CLX anticipates revenues for FY21 will be ahead of market expectations. In addition, as a result of lower travel and event costs due to COVID-19 restrictions, higher margins are expected to be achieved in FY21 than would have been anticipated, which will result in the Company's profitability also being ahead of market expectations in FY21.
Momentum is expected to continue into FY22, and the group expects a healthy order book.
Tommy Cook, Chief Executive Officer and founder of Calnex, comments:
We continue to make good progress executing on our growth strategy, investing in our product offering and people to capitalise on the growth of the telecoms testing market as the industry transitions to 5G and the cloud computing sector continues to grow. We are delighted to have delivered this strong performance in our first period as a PLC and continue to look to the future with confidence.
Conclusion
With the long-term underlying growth drivers continuing as the market transitions to 5G and cloud computing, the board is confident that Calnex can deliver its historical growth rates over the long-term.
There are good structural growth trends here: one is the migration of the mobile networks to 5G, a second is the emerging Internet of Things, and a third is the shift to cloud computing mentioned above. Calnex can drive sustainable revenue growth from each of these trends.
The global market for mobile network testing alone has been estimated by Frost & Sullivan to be around $1.3bn in 2020, and is forecast to grow at a CAGR of 11.5% and exceed $2bn by 2024. The same consulting firm estimates the global high speed ethernet test equipment market to be around $1.3bn in 2020 and also expects this market to grow to $2bn by 2024.
The only real debate here is on valuation - at 7.5x TTM sales and 30.2x forecast earnings, Calnex does look ‘expensive’ from a relative valuation standpoint. That and will the brought forward revenue have any impact on the coming financial year? It seems as though the board is confident this will not happen.
But Calnex looks to be a quality operator with an entrenched and important position in a growing global market. There are some good shareholders here, too - the CEO and founder is the largest, and Slater Investments has also taken a chunk. That type of institutional shareholder is expecting material growth, I would wager.
I’m interested to see how the share price reacts to this news as Calnex looks potentially like a good long term hold. Perhaps it will prove to be one of those companies that always looks ‘expensive’ but ultimately backs the valuation up with growth. On the other hand, maybe there will be a pullback at some point. Plenty to consider here.
More detail will be released in Calnex’s preliminary results for FY21 in late May.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

105 comments
I appreciate these are doubtless dumb questions!
Hi Wilbraham,
These are not dumb questions at all, but the answers have been done to death on the internet if you have a quick Google. I lost interest in bitcoin many years ago and only ever got involved due to my expertise in hardware acceleration of cryptographic algorithms. Basically, mining requires a "Proof of Work" computation which is based on the SHA-256 hashing algorithm. It is that computation that is at the very heart of mining and the reason the world is full of very hot Nvidia GPU's :-)
I could feel people's eyes glazing over as typed that, so I'll stop now...
All the best, Si
"I can remember giving up on tech shares in mid 2001, and focusing on
deep value, and did extremely well for the next 2 years, that was how I
got started as a professional investor. On the basis that I'd made
16-times my money in the bear market of 2001-2, with no leverage, going
long of oversold value shares, so should do more of it, with my day job
of being a CFO taking up too much of my time!"
Gosh Paul I wish you would write that book!! It would be fascinating.
Regards
Michael
Seconded. I think it's much needed.
I have just read Blancco's interims. They seemed extremely positive until I followed up your comments on capitalising of costs !
As for Supply@me Capital (LON:SYME) , it reminds me very much of Tungsten which fell off a cliff a few years ago after their then chairman did a magnificent job of extolling the wonders of invoice financing.
Supply@me Capital (LON:SYME) sounds like a bag of spanners to me. The asset based lending arena is full of very competent and experienced lenders. They typically only consider inventory alongside debtors. This seems like a high risk business to me.
As much as I value your blogs I believe you are wildly out on SYME. Some of the people on board are at the top of their game in the industry and have moved to SYME as can see what is on the horizon.
Be interesting if you revisit this blog in 6 months as it will be a completely different picture.
Of course, I'm happy to revisit the facts & figures on Supply@me Capital (LON:SYME) as things develop, that's what I do with everything. I just report on the facts. I went through the facts in the article above. It's a startup with nothing of any commercial substance at this stage, as I demonstrated with excerpts from the prospectus.
I've been in the UK small caps market for over 25 years, and have seen literally hundreds of blue sky promotions like this. They often attract a passionate shareholder base, convinced they are the next big thing. Do you know how many of this type of share succeed long-term? Virtually none.
Good luck with it, but this is bull market punting, not investing.
Regards, Paul.
Supply@me Capital (LON:SYME) I have to say the spiel reminds me a bit of Eddie Truell's Tungsten (LON:TUNG) which was meant to revolutionise invoice discounting...yada yada. Needless to say I took a large loss in my more inexperienced investing days. I now like to see some real numbers indicating progress or otherwise just happy to trade speculatively off the chart only!
Btw Paul - I recently met the Virgin wines management team and after the presentation, despite it being a very well run business (metrics / profitability far better that Naked Wines (LON:WINE) ), I concluded that a large part of this years profit uplift has come from COVID (basically they've attracted a younger demographic than normal given lockdown) and I expect this to unwind over time. Note that there's been no Private Equity interest at the valuation and so they've decided to IPO.
ps. look out for the customer churn stats etc in the prospectus.
How about 165 Companies with agreed Terms, each paying a non refundable £16k Due Diligence fee.
That was up to December 2020. SYME only started onboarding companies in March.
This is about £2.13 Billion worth of Inventory from various international and UK companies held by these 165 companies to be monetised by SYME, with SYME taking approx. 1.5% of this in additional fees. Each company is tied into a minimum 3 Year Contract.
That is a decent return.
Once the Funder is released from the NDA SYME will really come into it's own and we will laugh at these bashing articles.
SYME are very much working away in the background putting the right people in places to make this 'Fly' as per the CEO's comments.
They have recently appointed Stuart Nelson as Head of Risk Management in the UK. I very much doubt he would have left his 18 Year Senior Director role with S&P Global to join a company with such little potential as the original article and some of these comments suggests.
nicobus - I think that Virgin are trying to take advantage of the sentiment behind Naked Wines. Naked are miles ahead with expansion in the US and their own infrastructure and wine producing partners.
Could not agree more on SYME. Took a bull mkt punt and it suddenly went from 0.03 to 0.86 in less than three weeks on "speculation". Now suspended and no idea where next (only have a small holding). Let us see whether it comes back and at what price. This is exactly why we need Paul.....to point out how bonkers valuations often are in these crazy times. Understand how difficult it can be to read if heavily invested!
Regards (LSE:SYME)
In the month and a half of the suspension of the stock from the London Stock Exchange, Supply @ ME was not idle, it kept the business going and worked alongside the regulators to better explain its service model and, consequently, the its accounting structure: “we have communicated a lot in the past weeks, we have managed to get to know each other better and to provide the Financial Conduct Authority with the information requested: all in all, the stop to listing was useful”, CEO Alessandro Zamboni told websim.it.
The Italian fintech that allows companies to immediately obtain the value of the stock can be bought again from March 9: the stock closed on Friday at 0.50 pence, a price that is worth 162.7 million pounds. In the first four days of trading, the daily volumes were in the order of seven million pieces, but this summer it had reached almost two billion: a whirlwind of exchanges that allowed Supply @ ME to arrive on one of the stages of importance of the great world finance: “we have been in the reel of CNBC for a long time, together with the big names of Nasdaq”, continues Zamboni.
Such interest is probably justified by the prospects for success of his business, the monetization of the warehouse. Supply @ ME has succeeded in building a bridge on the void that is created when a company ends the production of its goods, or, in the case of a wholesaler, when the purchased goods arrive in its warehouse, and the moment in which the goods and merchandise are sold. In this period, companies often need liquidity, "a need that the traditional credit system serves only partially, with loans that arrive after a long time and are worth a maximum of 50% of the inventory value", explains Zamboni .
Supply @ ME manages to quickly get the liquidity that companies need, using the resources made available by financial entities that have them in abundance and are desperate for profitable investment solutions.
Building the tube that safely brings the liquidity of assets under management to companies has not been easy, in fact there have been technological, accounting, regulatory and logistical complexities that have taken more than five years to resolve. But all this is behind us, because today Supply @ ME is able to value a warehouse, proceed with its securitization with the issue of a short-medium term financial security that is underwritten by asset managers: the latter are happy because they have a return, companies meet their need at a fair price (not being a loan). The circle closes when the goods from the warehouse are sold to the end customer.
Supply @ ME obtains commissions from all this: "on a warehouse worth 100 euros, we receive an income that is worth about 1.5 euros at the EBITDA level and one euro at the net result level", adds the number one of the group.
To date, Supply @ ME has come to analyze 165 companies, with a total inventory of approximately two billion euros. On the basis of these numbers, it follows that the next income statement could also reach a net result of 20 million euros, if all the companies analyzed were considered eligible.
These figures, however, are not seen, or are only partially seen, because it is as if we were in the year zero. Something will be evident at the end of the month or at the end of April, when the company will respectively provide a trading update and publish the 2020 financial statements, but the boom in revenues and profits should be seen this summer, with the publication of the accounts. in the first half of 2021. At this moment, at 0.50 pence, the stock is suffering a high “delivery risk”, but it is also an investment opportunity for those who do not want to wait to see certified results.
Hello
Some chat and uncertain vibes in here on K3 Capital (LON:K3C) - perhaps a bit of a slippery fish due to a number of circumstantial factors and big acquisitions do present a risk.
Dave Hill a frequent poster here asked for 2021 'quality' picks. K3C was mine not as I thought would be highest but as was a !certain! gain. So here's a note:
https://www.stockopedia.com/co...
Hasty by me so apologies for typos etc. I will go back and review too
Apologies if you're sick of explaining this, timarr, but am I wrong in thinking blockchain is enormously energy-intensive (eg for 'mining' cryto-currencies)?
Yes, it's very energy intensive, and what's worse, needs more and more energy with time. Think of it as like a traditional pit mine - in the early days the inventors/pioneers were picking bitcoins off the surface at almost zero cost or need for energy. Then when all the easy bitcoins were had, they moved to digging a shallow pit but they were still able to mine bitcoins with a shovel. Now you need to get one of those big Caterpillar earth movers, fill it up with diesel, put very expensive tyres on it, and drive it 10 miles to the bottom of the pit to mine your coins and then drive it 10 miles back to the top.
All the best, Si
Indeed. Bitcoin consumes more electricity than Argentina.
Indeed. Bitcoin consumes more electricity than Argentina.
Oh, don't mention Argentina! That reminds me I'd just returned from a holiday there this time last year. I remember in the car back from Heathrow the driver telling me that he was hacked off because he'd had cancellations from his clients who were no longer attending the Mobile World Congress in Barcelona because of some virus in China... it was the first I'd heard of it.
All the best, Si
lol si, you have reminded me of a certainty every publican knows. If you want to know what is going on in a city, take a taxi and start talking to the guy. The stuff you can learn is amazing.
I was in Dublin last March 6th for the Ireland - Italy rugby match on my birthday. We were supposed to be 3 couples but the match was cancelled and the other two couples cancelled so me and the wife headed on our own. The city was deserted despite 5,000ish Italians estimated to have still made the trip. We got in a taxi to take us to the restaurant. The (obviously racist) driver said “you aren’t Italian are you?” We told him no, we were from Belfast. ‘Thank feck” he said “you looked smart (I think he meant well dressed) so I couldn’t be sure”. We chatted about what a disaster was looming for the Dublin taxi trade on the way to the restaurant. The line I couldn’t forget came just at the end “How do you say feck off in eyetie anyway?” What struck me was the almost total terror the man displayed.
The restaurant owner told us business was a disaster and he didn’t know what he would do. I had been taking profits all through March (CV terrified me from January) and was at 40% cash already. That week I sold everything (including half the pension funds - never done that before). Thank god for taxi drivers.
"Indeed. Bitcoin consumes more electricity than Argentina."
Indeed it does. Yet kids worldwide playing facebook and instachat on their smartphones use more than crypto-miners. Which is the better value for humanity? Developing and supporting the next worldwide currency allowing holders to regain their financial freedom and escape inflationary monetary policy? Or kids wrecking their eyes and social development while making the owners of big tech(who have the power to censor and ban the democratically elected President of the USA) ever richer and more despotic?
Keep mining 'em fellas.
Just to show my huge ignorance of Bitcoin:
1. Why does it have to be mined, at ever-increasing energy cost per coin as it approaches its limit? Why can't ''they'' simply rule that as from, say, next week there will be no more Bitcoins mined? I get that most hard commodities are mineable (while soft commodities have almost limitless supply) but many stores of value have finite supply - think Mona Lisas, Picassos, Ferrari 250s. Surely in that event, BTC would become an even better inflation hedge, once it had risen to its 'new' value? (OK this presumably goes against the original rules with in-built halvening etc, but it's an interesting thought experiment.)
2. Once we 've stopped the extreme waste of mining new BTC, does the energy cost of processing BTC transactions and updating the distributed blockchain become de minimis? If not, it seems a poor currency for anything except high value transactions.
3. Have other cryptos hit a finite limit, or do they all follow the continued mining model?
I appreciate these are doubtless dumb questions!
Hey Wilbraham, I’m not an expert and will happily be corrected.
As I understand it:
1) The concept of mining was introduced because there had to be a reason for blockchain when the thing was invented. Blockchain basically adds all the transactions before it in a list so therefore if there are a number of people running PCs with the entire blockchain on it in the world, everyone knows it is trustworthy and no-one can steal/ hack/ invent bitcoins as all those PCs have to agree on the chain. If one PC is hacked and tries to connect to the network all the rest immediately know they don’t have the same information and it is excluded. This gives surety for holders. However, there has to be a reason why people would run an ever increasingly huge program that holds this information. The reason was mining.
As people’s computers held the Blockchain, they were also paid (in Bitcoin) for that by solving increasingly more difficult math problems. The limit of Bitcoin was capped at 21m in the hope that by then there would be enough people owning valuable Bitcoin that it will be worth it for them to run the blockchain themselves. In the meantime, there was an ever increasing network of computers that held the chain.
The “they“ you refer to is interesting. Bitcoin is actually really totally “decentralized” - the owners can vote by forking to change the rules but it is probably unlikely that big active owners (miners) would vote for a change that put them out of business. We’ll see.
2) There’s massive innovation and a lot of competition on the transactional front. Right now, Bitcoin is really just a store of wealth. However, the lightning network and a host of stable coins are aiming to make this as fast as you want (basically they hold a store of “slow” Bitcoin and handle the individual transactions). I may be wrong but I actually don’t see this as a long term problem for Bitcoin - either one of the payment processors will do it or an up and comer will ‘steal’ the business.
3) Bitcoin is different from the rest of the crypto’s as they are effectively owned by individuals/ corporations. So even if they publish rules they can (and often have) change them to issue more. For me, there isn’t a good reason to hold anything but Bitcoin.
Despite above I don’t hold Bitcoin (sold last of my small position last week) and don’t plan to buy anytime soon.
How about 2001 and 2002?
It's not the FTSE100 that is overvalved. But look at some of the US shares.
When the Govt. support is taken away a lot of companies will go bankrupt, what about all the bad debts and unemployment?
There's lots of info available on Supply@me Capital (LON:SYME) if you read through the previous RNS. The concept is also explained on their website here. They are creating a new asset class from the sale of inventory. It is not the same as inventory finance or a loan as the article states.
I agree that on the surface the company doesn't look valuable or have good prospects, but you have to look deeper.
Company inventory is monitored by the platform and exchanged for coupons which are then converted to cash by funders, so the transaction is classed as a true sale of inventory. This model has been legally scrutinised by 2 of the big 4 accountants.
The potential investors are buying into is being first to market with a new concept and the inventory monitoring and risk analysis technology that the company has developed over the last 4 years prior to RTO. This alone could be valuable and banks are already working with the company to use the platform for their own customers. "...as announced on 27 July, the pool of 272 companies originated by one of the two Italian "Self-Funder" institutions that has resulted in the initial selection of 29 corporates upon which due diligence will commence."
As of the end of November, the company had signed up 152 businesses who have all gone through due diligence and paid an onboarding fee awaiting funding. "For the extended financial period to the year ending 30 September 2020, revenues are expected to be approximately £2.3m."
The only uncertainty to investors currently is when the first transaction will be completed. Once that is done the concept is proven and the business can begin expanding into its key territories as identified with partnerships already in place. Without that, the company is going nowhere, but this is the chance you take with new startup investments.
Great post Michael, nice to see some balance to the very negative 'attack' nearly on SYME.
I am very surprised to see this on Stockopedia. Calling investors or potential investors 'mug punters' for example.
It reminded me a lot of that failed share basher at Shareprophets.com. They and their army of shorters have a proven track record of calling the market wrong and enticing people to sign up to their monthly £6.99 subscription using very extravagant headlines.
Hi Paul,
Thank you very much for taking a look at N Brown (LON:BWNG) N Brown, I commented yesterday regarding the two sets of Director buys. Thank you also to Jack for bringing your attention to this.
I have bought in this morning.
Change is what brings about increases in share price in my book and you can't say that N Brown aren't changing.
Unspotted titbit?
Whilst doing my own research before buying, I think there is one thing I don't think anyone has spotted.
N Brown (LON:BWNG) stated that they had provided for £17m of bad debts in their Financial Services Arm.
In fact, you highlighted that in their Q3 trading update that cash collection from this activity had remained stable. If we look at other lenders lending to poor people (Non-standard Finance (LON:NSF) etc.) then we can see that cash collection has not plummeted but remained robust.
So that's my two cents to add to the equation.. most of £17m dropping into the balance sheet is probably worth a few pennies to the SP in my view.
A couple of other things I've noticed. Jeffries seem to have updated their target to 95p and Schroders have increased their holding slightly today.
On N Brown (LON:BWNG) one thing to watch out is the FCA investigation into BNPL credit in the eCommerce area, which is where they play in.
The investigation is mostly into the "wild west" at the moment, of the likes of Klarna, Clearpay, etc that aren't really regulated and potentially getting lots of people into expensive debt.
BWNG is fully FCA regulated already and above board. So in theory any new FCA rules will impact them the least. However, you never know what will come out. For anyone looking to take a sizeable stake, I would read the latest FCA consultation documents to see potentially where the rules are headed.
I've just spent a few hours looking at Calnex £CLX following their trading update today. I decided not to buy any because of three factors. 1) The shares are too expensive. 2) Their listed history is rather short. 3) Orders have been brought forward from FY2 to FY1. This is likely to mean that FY1 forecasts will be revised upwards, but that FY2 forecasts will be revised downwards. As FY2 EPS forecasts are already showing a 3% decline on FY1, I concluded that it is likely that after the forecasts for both years are revised, that it will show quite a big EPS drop from FY1 to FY2. However, I did struggle a bit with this last point, because one could argue that it is a good thing for orders to be brought forward. What are peoples opinions on this last point?
Enjoyed Paul's column today. Funnily enough, I was talking about the dot com bubble last night to an online investor and mentioned Look Smart plc: its value rose from $23 million to $5 billion (!!) within weeks, but it lost 99% of its value almost overnight as the bubble burst.
Bitcoin today broke through the $50,000 levels and Argo Blockchain (LON:ARB) hit 250 pence. Not bad for a stock that was below 3p last March! The company has now been forced to put out a "speeding ticket".
In my view there are a lot of small cap dawgs at the moment with crazy market caps. It is easy to make money on them on the way up. Small novice investors are apparently pouring money into anything and everything. There are stacks of stocks in the risers list today that are up 700 per cent and more since before the pandemic. Often on almost nothing. A known investor has bought a few at a cheap price for instance. The directors are "confident". The hole in the ground is "promising". On the way down the situation will look very different with large spreads and selling will not be easy. It is ever thus and history always repeats itself. Make money by all means but arguing they are "good value" or "cheap" is a different matter.
I think your review of (LON:SYME) was very harsh indeed.
For anyone interested in SYME please read the attached research document regards the progress of the company.
Financial Accounts relating to RTO does not tell you the true story of SYME and it's potential.
See culminated research document using the below link.
https://drive.google.com/file/d/1BDJVtKyCYrAp1FSWf8sgwijsWVswJSNx/view
SYME Shareholders Group on FB provides sensible, measured opinion and research.
Supply@Me Capital (LON:SYME)
Hmm, posters suggesting moving to a stock-specific FB group away from the harsh glare of dissenting opinions, what could possibly go wrong?
Yet another red flag IMO, the '@' in the name was just amber in comparison!
I've worked in investment banking for 23 years and during that time have worked on all sorts of projects including transactions that have financed inventory and, in particular, have worked on "inventory monetisation" deals (as SYME likes to call them).
On the "inventory monetisation" front we did large deals with oil, metals, grains and other highly liquid hard/soft commodities. These deals are relatively straightforward because you simply buy the product, paying somewhere between 90% to 99% upfront, and then you hedge your price exposure via derivatives. It's of vital importance that you can hedge your price exposure because if the company can't buy the commodity back from you then you'd otherwise be stuffed trying to liquidate that position.
I provide this example because I've seen the CEO of SYME claiming that their product is new and unique but it's not. Banks have provided this product for years, we do it against warehouse/depositary receipts and so the commodity never moves and we do it at a lot lower rates of interest than SYME who claim that they're going to charge 6%! 1% is much more likely!
I'd also make the point that the 90% to 99% that is paid upfront is important because in order to get an asset of balance sheet under IAS 39 the company has to receive "substantially all" of the value of that asset. Accountants interpret "substantially all" as meaning at least 90%. I note that SYME are only paying 85% upfront and so I would immediately question the off-balance sheet nature of the product that SYME claim because I don't think that they meet the basic test under IAS 39.
Finally, I've seen SYME claim that they're going to get banks and others to finance an SPV in order to do their deals. Let me explain why this isn't going to happen.
The SYME product is economically the same as "non-recourse lending". That is to say that if the client company doesn't buy back the inventory then the ultimate lender has no recourse to the client for any funds; their only recourse is to the underlying inventory which SYME propose is sold via an agent.
Banks already provide non-recourse inventory finance products for other inventory (ie finished goods that's not a commodity), the typical form is an "ABL" (Asset Backed Loan). As a matter of policy we didn't do them as we considered the risk to great. However, if you search around you will find that there are banks and other finance house that will do Asset Backed Loans against inventory. In such cases the lender only typically provides 50% value against the inventory and the basic reason for that is to protect themselves against risk. If the client doesn't buy the inventory back (for whatever reason) then they want to know that they'll be able to go out and liquidate the collateral (inventory) and get their money back. Hence 50% is typically the maximum that a lender will lend against inventory.
SYME claim that they're going to provide 85% upfront when they buy the inventory from the client and that this will be financed by debt. But why would a lender be prepared to lend 85% when their normal limit is 50%? The simple answer is that they won't.
All of this probably explains why SYME have secured no funding have not got a single client to sign a contract. This little fact is hidden in SYME's Going Concern statement in the recent annual results:
"The ability of the group to acquire inventory is reliant on investment funding being received, whilst the group is in advanced negotiations with several interested partners no investment has been secured, if no investment is secured the group cannot acquire inventory and generate the service fee income.
In addition the group has a portfolio of interested customers, with some having signed term sheets. The cashflow model assumes a growth in customer base in line with the interest that has been received in the product but there is uncertainty over the ability of the group to be able to secure these new customers."
See: https://www.investegate.co.uk/...
It should go without saying that I think that the CEO has over-embellished the story from his side.
Not all companies have the benefit of being able to hedge this risk with derivatives to have those deals available to them, but you know that already.
The basis of the platform is to understand the inherent risk and mitigate against it. This is the exciting opportunity for this tech to change the industry. Hence the risk is lowered and the % of funds can far exceed what the banks can offer.
The main risk at the moment is funding like you say. The company knows this which is why they are putting together the captive bank so this is not a blockage to its future growth.
Good luck, gambling on the jam tomorrow potential with Supply@me Capital (LON:SYME)
That's not what I do here. I look at facts & figures.
Supply@Me Capital (LON:SYME) - it's quite helpful when a company includes something like "@" in its name - you just know straight off that it's not going to be a good place to place your money.
A wonderfully robust approach to investing.
I guess being named after a river or a piece of fruit may have received the same opinion originally.
BOTB Best of the Best
This stock is often mentioned here and it just popped up in my momentum watch list as the current price has hit 2,700p. I am aware that it has a number of takeover offers.
Does anyone know what the offer prices are?
There is numerous "Takeover panel " note in the news section but I can not fined the offer price. Plus there is no website mentioned here in Stocko.
Is it too late to buy this stock?
Any help would be much appreciated.
Best Of The Best (LON:BOTB) no offers just lots of interest (apparently). Also pretty spectacular recent growth
Thank you Housemartin2 ( what happen to Housemartin1)
The company issues a statement about 7 months ago saying it was talking to interested parties and that's been the story since then. In the meantime the company has gone from strength to strength and the increases now I assume are a result of the expected continued growth story in the stock.
I continue to hold from around 250 although I have top sliced several times and might do again as it constantly becomes very large on my portfolio (about 15% at the moment.)
The bulls will tell you its heading towards 4000 or 5000 on continued expansion and growth or even maybe a bid finally. The bears say it's easy to replicate and subject to legislation. Your decision of course whether to jump in or not
Thank you Brookeda that very helpful ( don't you love Stocko) I think I will go for it, I know Paul loves this stock, and 5000 sounds very nice.
Good luck with your investing.
I have held Best Of The Best (LON:BOTB) for some time and was considering topping up my position yesterday but the spread put me off. Now I see most of it would have been eliminated by the rise today. Don't think there is much point waiting unless there is a correction soon as the liquidity is very poor.
.
Paul, thanks for your timely write-up on £BLTG this morning as I was about to wet my toes.
I had better add that since the inception date in October 2019 my 20-software company virtual portfolio Blancco Technology (LON:BLTG) has virtually returned 100% leaving all but one other, Sdi (LON:SDI) at 319%, in the dust. Still a splendid performance and maybe more to come after exiting Covid-19's day.
Trouble is, just because things are going up strongly in price in this roaring bull market, doesn't necessarily mean they're any good! BLTG is a good example of that - the share price has risen 5-fold in the last c.3 years, but the figures today show that there's really nothing there. If it can't show much stronger financial performance, then the downside risk looks very bad to me, sooner or later. People have forgotten what bear markets are like, when all this momentum unwinds, and share prices reset to brutally lower levels.
A lot of SPs went up yesterday on low volume which is bearish, and of those which did very well yesterday many are red today
Quite a few are not down, as well, such as Sylvania Platinum (LON:SLP), BP (LON:BP.), Batm Advanced Communications (LON:BVC), SDI (LON:SDI), Next Fifteen Communications (LON:NFC), Ferrexpo (LON:FXPO), Central Asia Metals (LON:CAML). Yes Saga (LON:SAGA) is down slightly. I think it is quite common for shares, which have large rises, to pull back the next day as some take profits.
Hi Paul
We are still well off the FTSE 100 peaks in the last five years so may be a bit further to run.
You call that a peak, more like a molehills, the FTSE100 has done hardly anything over the last 20 years.
The FTSE250 has done considerably better and is not far off the peak of the last 20 years.
The AIM100 and FTSESmallcap are at 10 year peaks.
The more I look at Sdi (LON:SDI) the more I like it. Prior to the trading update the price was 120p and the PEG was 2.3.
The price is now 167p with a PEG of 0.9.
This will grow organically and also by acquisition.
To me this seems like a growth share at reasonable value.
Has anyone recieved any extra excess shares from Surface Transforms, I thought we were meant to get them last week. AJ Bell have ring fenced my money but so far nothing has been credited.
I'm parinoid that the big institutions have taken everything and left us with nothing
I’m with iWeb and received 10% extra shares on 12 February. This was less than I applied for as the issue was oversubscribed. I have not yet received cash refund for the shares I didn’t receive.
HL applied my entitlement today (this afternoon). I also received funds back for the extra I applied for, so just got the 1 for 38 allocation
I thought the following exchange worth sharing here, since data has been the subject of some discussion in recent SCVRs.
I have been chasing Stockopedia to show the broker forecast on React (LON:REAT) since Allenby first commenced coverage about six months ago. Stockopedia were responsive on this but it took an inordinate time to correct, the explanation being:
Our data providers confirmed that they had loaded this information onto their databases, but there was an issue with the data flowing through to the platform that we use to pull the data to update our StockReports. They have now resolved this issue and the estimates were updated on the StockReport this morning.
My response to this was ...
Thanks, xxxxx. I appreciate your persistence on this. However, these forecasts are only appearing six months after the broker initiated coverage. I strongly believe that Stockopedia need to demand higher standards from their data suppliers if they are to meet the expectations of their subscribers, who expect the site data to be accurate and up-to-date. Perhaps this is something you could highlight to your management?
Encouragingly, Stockopedia responded:
You have highlighted a good point here and I can confirm that we are investigating several areas of our data provision where we are looking to improve, broker updates being notably amongst this.
We are currently in discussions with our data providers who have responded with positive feedback on how areas of the product will be improved moving forward. We are hoping that these improvements should start to feed through by the end of this year, but rest assured, this is something we are keen to find a solution for.
Whilst it may take some time for these improvements to feed through, we are optimistic that broker coverage and other areas of the data collation process will be more timely as time progresses.
So progress, hopefully, but still very slow.
EC
Good points very well made.
Given the whole ranking system is data driven, and it is always being highlighted how well, on average, the higher ranked stocks perform, it is frustrating that so much of the data is regularly so out of date both in terms of:
As you highlighted, the broker forecast update delays are often farcical and frequently make analysis very dificult. In the circumstances, I guess its still a positive that despite these flaws I still find the SR system of considerable use.
From Numis,
*NEXUS INFRASTRUCTURE (BUY 205p): AGM trading update. Nexus reports that TriConnex and eSmart Networks are trading ahead of the group’s base case scenario set out last June, with Tamdown trading more in line with the downside scenario (although activity continues to pick up). Whilst there are a few moving parts, this suggests no change to our FY21 estimates. Looking further forward, Nexus has reiterated that it remains on-track to return to pre-Covid levels of activity in FY22, which is also in line with our forecasts. Based on the strong momentum in TriConnex and eSmart Networks (driven by regulatory tailwinds), the expected recovery in Tamdown (as housebuilding activity normalises), plus the group’s strong balance sheet (NSe FY22 net cash: £24m), we continue to see scope for share price upside. We therefore reiterate our Buy recommendation.
Thanks Trevor, that's really helpful info you posted from Numis (who exclude most of us from seeing their reports, despite getting privileged information from companies - scandalous in my opinion).
If they've told the Numis broker not to change his forecasts, then why didn't NEXS include a trading in line with expectations comment in today's update? Maybe they're a bit behind, but are hoping to catch up in H2?
All in all, a complete mess in terms of communications from Nexus. Why would anyone want to buy or hold the share, when they're failed to explain clearly how they are trading? It's so annoying from my point of view. I wasted an hour trying to unpick that trading update, to work out what they're trying to say. They could have just issued an in line, or broadly in line with expectations statement, and saved us all the time & hassle.
Regards, Paul.
Paul, After working in the financial markets for over 40 years Ive learned more from yours and other subscribers views than I ever did in the city. You and Stockopedia are fulfilling a vital role. Fantastic!
How kind, thank you Trevor!
I have recently joined Stockopedia and am relatively new to investing, so please forgive me if I seem a little unsure.
I have looked at Calnex on another platform which I use as a backup. According to this, the shares are £223.0% overvalued with a fair value quoted of £0.37. I have also looked at N Brown, which appears to have a very high level of debt? On the plus side though, I note that there has been considerable insider buying.
Five out of six analysts are giving the valuation on Calnex and as I have done very well with my shares on this particular platform, I am a little torn between the two. Am I being I little too cautious, as I check all the parameters on this site before I decide to look into it any further.
Hi John,
Intrinsic valuations can be fairly subjective and sensitive to inputs. There are a few different models you can use to arrive at a valuation. For example, if this platform is computing intrinsic value as some sort of multiple of net asset value, then lots of companies these days have asset-light balance sheets and can look very expensive on older valuation metrics (like Calnex Solutions (LON:CLX) ). That's just one example, though. The devil is in the detail.
But make no mistake, Calnex Solutions (LON:CLX) is expensive across most valuation metrics. In that case, the important consideration is whether the market is correctly anticipating future profitable growth, or if the company is set to outperform those expectations. CLX looks to be able to do that given past performance and the growing market it operates in, but it probably also needs to do that in order to justify its valuation today.
Re. N Brown (LON:BWNG) - I'm less familiar with this one, but I believe the debt is secured against its credit book, so this debt is less risky and (I assume) less expensive that it might be for other companies. It is a turnaround though, so there's plenty of execution risk in terms of its operations.
If you want a little more info about Stocko and investing, this video is good. You can also find much more detail in the Learn area.
Thank you Jack for taking the time to reply.
Hi John, re Calnex Solutions (LON:CLX) : The other platform sounds like Simply Wall St - there is a button to 'View Data' to view the model, underlying data and calculation of the valuation. It is an automated process, usually extrapolating forecast earnings 10 years into the future and then applying a certain discount rate to arrive at the present value of those forecast cash flows. You need to compare that against your own projections - sometimes the assumptions can be way off - nobody is sanity checking it, it's all done by computers. In this case, they are saying the valuation per share is 37p, so 223% overvalued compared to the current sp of £1.18.
It hinges on whether you think their projections are vaguely sensible, or just a case of GIGO (Garbage in, Garbage out).
Hi John
With N Brown (LON:BWNG) you need to check how they are accounting for the loan book to customers, as similar to Next (LON:NXT) they are very much trying to sell the clothes for credit, so it does some slightly different things with the finances and balances. Probably best to look for one of Paul's historical write ups on either company as he will explain it a lot better than me!
Tommy
Morning Paul /All. On a quiet day (maybe Friday) I'd love to hear your macro thoughts at the moment and how your thinking about your overall portfolio. As you stated yesterday at the moment there's a lot of "this is so easy" seeing almost daily gains in our portfolios. Aware of the famous quote of being fearful when others are greedy I am starting to get a bit nervous of the gains and am almost daily considering lopping some gains and either parking them in cash or in something non volatile (Utilities, REITS (non office/retail.)) Would love to hear how others are thinking about this at the moment? We really seem to be at the crazy part of the cycle now but beyond inflation (which I think is still some time off) or a new virus strain which the vaccines don't work on, I struggle to see what the catalyst of the correction could be?
Hi Brookeda. I couldn't agree more. I'm extremely nervous because this really is too easy at the moment when all around us the real economy is in deep freeze. The true impact of Brexit may well be obscured by the pandemic, but a recent claim by the Road Haulage Association was that exports to the EU fell by 68% in January. Whatever the truth of that statistic, it is clear that exporters , particularly small and medium size businesses, are facing friction in trading with Europe.
Governments and central banks on both sides of the pond are flirting with some extremely dangerous policies in their increasingly desperate attempts to put off the day of reckoning for the reckless debt explosion that they have presided over during the last 40 years (Trump borrowed more than Obama who in turn had borrowed as much as all previous presidents combined.)
If you want a bucket of cold water to wash away the weird market euphoria, then I would highly recommend the excellent End Game podcast by Grant Williams (https://podcasts.apple.com/gb/...). Some of the technical language is beyond my comprehension but if you listen to all the episodes, the underlying narrative becomes clear and the scale of the mess we are in is nothing short of terrifying.
The interview with Mike Green on the perverse impact of passive funds, which barely existed 20 years ago, is frightening enough on its own. The analogy of driving a car uphill faster and faster is a good one. I don't know what the catalyst will be, but when the car stops, it will travel back down the hill at frightening speed.
I'd like to second the End Game series from Grant Williams and his podcast output in general. What's alarming about the End Game is the incredible quality of the interviewees and the almost total lack of alarm they display when talking about various topics such as the influence of passive investments (models where the value of the US stock market goes to zero), money printing and monetising debt (the end of fiat currencies as we know it), and the US pensions crisis ($3 trillion black hole and counting).
As for my own anecdotal evidence, I manage my own small portfolio as well as a portfolio of equities for my dear old Ma, and yesterday my Ma's entire portfolio increased by 3.8%. In one day. To my mind the markets are pricing in not a return, but perfection + a boom, which I just cannot see happening. Much smarter fund managers than I am are talking real assets, commodities, and precious metals, and reducing exposure to anything 'growth'.
Ma and I have discussed and she is comfortable with going to a mix of cash and precious/commodities metals ETFs and returning in 12 months as the name of her game is wealth preservation. I'm a good thirty years younger (and dumber) so have positioned myself across a range of N. American gold and uranium mining stocks, oil-adjacent stocks such as tanker companies (P/Bs of 0.18-0.4!), commodities (Sylvania Platinum (LON:SLP)) and UK shares that I hope are counter cyclical such as Redde Northgate (LON:REDD) and Cmc Markets (LON:CMCX) .
I want to be far away from anything that looks like 'the future'; hydrogen, renewables, EVs, Bitcoin, Tech, online retail, biotechs. In my humble opinion this is a collective wish for something to save us from the mess we are in, the magic bullet that will require no effort on our parts- be it changing lifestyles to de-carbon society, or a significant period of austerity to handle the debt mountains. Papa Musk will save us with the hyperloop!
No.
I agree with Jeremy Grantham, that the bubble will lose air as earnings numbers start to come in through Q2/3 and don't match the vaccine euphoria sentiment. I can see something like Tesla missing another sales target (never mind people realising that the entire company is humbug from top to bottom) and it acting like the 1p miss that Cisco posted in the dotcom bubble that spiked the unwind.
It'll be an interesting 12-18 months. Best of luck everyone.
Mentioning this as I haven't seen it referenced here before. There is a library in Edinburgh (virtual only now of course), called the Library of Mistakes, with the tag line changing the world one mistake at a time. They used to do regular seminars on the history of finance, and financial mistakes, and a lot of these are online. Many are quite obscure, but it might be useful to temper over enthusiastic purchases.....
I think it is quite different from the dot.com bubble. Then no profits were being made. Now we have companies like Alphabet and Apple. They are not expensive. I have no idea what share of the EV market Tesla will take but we know the world is changing and we can't ignore it - no more new petrol or diesel cars in the UK by 2030. Over the past 50 years I have read so many forecasts of doom and we are still here. I just don't read these forecasts. They know no more than you or I. Buy companies that you love. My largest holding (not a suggestion as you may not love it) is Disney. It will still be around in 50 years.
I never have time for podcasts (I find it much faster to read), so I've no idea what the underlying ideas are, but it sounds as if they're around the market as a bubble. While I wouldn't disagree with that, the strongest strings pulling prices are in the economy. Which is where it gets scary and hard to predict since it's as easy to see pressures pulling it up as those pulling it down. And the pulling is getting quite intense.
If you have access, I'd suggest looking at the Big Read in today's FT. Goes through the schools of thought about what's going on and what should be done (Biden stimulus being the trigger for the discussion). Most commentators don't appear to have much insight, but there's a few that have and they mention other events and mention other names whose ideas that ought to be looked at.
The underlying issue that they're mostly avoiding is that no-one has reasonable data on how things work now and no-one knows why. The old relationships no longer hold so attempts to 'fix' things become ever more extreme. Increased money supply (conventional definition) produces no growth and no inflation, so let's try doubling it. Levers only function when the end you can move produces an effect on your target object.
Economies are increasingly interconnected, productivity growth appears disappointing (that could be as much about the measures as anything else), mass migration, ageing demographics, simultaneous expansion of both the unemployed underclass and the parasitical overclass; but none of these are necessarily the cause of the breakdown.
The only safe conclusion is that current stability is apparent not real and that real movement, when it does start, could be explosive. And the stockmarket is froth where the bubbles might quietly dissolve or get blown away completely.
I think this would be most interesting - Paul, if you choose to do so, can I suggest it is done as as separate thread as there is likely to be a lot of feedback/input and I for one would not want the topic to be lost in an SCVR. I think it will be a discussion that will run and run.
On the subject of it "being too easy" I have learnt over the years to try and not confuse luck with talent .... and I am still trying. I would recommend watching
The theme is what professional gamblers can teach business and stresses how wary they are of luck. Good watch unless you are a Newcastle fan!
Like many of us, I am feeling pretty clever right now - (always a warning sign!). I am asking myself where I have I been lucky and where does it look like good judgement.
Berksbee,
Thanks, I really enjoyed that, one of my best friends(RIP) was a sporting bookmaker and some of the completely irrational punter behaviour he experienced made my toes curl.
Richard
Just reading a tip from the papers on Sunday for Eenergy (LON:EAAS) It looks like a really interesting concept to me and I have bought in. They target public sector where capex is hard to get agreed. As such it is hard for a school to invest £200k upfront to reduce energy costs in the long term. Eenergy Group come along and install the bulbs in return for a 10 year contract that offers the school a 30% reduction in costs with no upfront outlay. Thgey back this off by way of project funding. They will build a subscription type business of recurring revenue from top quality public sector debtors. Highly topical, political pressure to go green, win-win situation.
The write up said, "The Financial Mail on Sunday's Midas column recommended readers 'buy' shares of eEnergy, the distributor of Light Emitting Diodes.
The tipster explained how a large secondary school would have to shell out £200,000 to change from traditional flourescent light to the much more efficient LED's.
In a nutshell, while the upfront cost was "high", the long-term savings were "huge" and far friendlier towards the environment.
That was also the company's business model, helping schools make the switch by offering lighting as a service.
In exchange for a monthly fee which encompassed the related maintenance costs for the LEDs, schools would be able to slash their electricity bills by more than 30%.
Eenergy already serves over 450 schools but there are more than 32,000 others in the UK which still depend on old lighting.
Not surprisingly perhaps, care homes have started to sign up and firms in other sectors are following suit.
To take note of, LED light is softer and has been linked to fewer call in sick days among workers.
Eenergy also helps its clients to source the cheapest green energy and the firm is planning to move into heating as a service too - with the potential for cutting energy bills by half.
The company's sales are expected to more than triple over the fronthalf of 2021 to around £13.8m, helping to push the firm into the black for the first time ever.
"Companies, schools, hospitals and Government departments are increasingly keen to reduce their carbon emissions," Midas said."
It’s an interesting concept that Eenergy (LON:EAAS) have. However, I would have thought that the problem will be that any facilities management company that can find the capital backing could do the same thing. But the fact that this opportunity even exists this late in the ‘green revolution’ shows just how slow and ponderous some sectors can be. The lack of a sustainable competitive advantage is worrying though. Achieve significant success and the business is easily copied limiting the upside. If the success is not significant then not a great investment.
But perhaps there’s a lot more to this than appears to be the case on an initial glance.
I like it but I think that you are right. eEnergy disclose how they fund the projects. They use Susi Partners.
It would not take a huge market share to create a very profitable business that could also roll out additional products.
As it moves towards profits I think the market sentiment will be positive. It will be a target for certain focussed funds.
Re £EEAS I agree with both you and Graham Ford above - this is a Buy'n'Build strategy so has no real intrinsic moat but is operating in a really interesting and rapidly growing area (electrification of light and heat to decarbonise to go green AND save money - a dream combo to sell to esp the education and public sector bodies they are focused on.
However, supply currently being met by loads of small companies with a few key sticky local contacts/contracts that lack scale to cut cost in purchasing and upsell/cross sell complementary services. This is where a limited moat can be created by being (among the first) to create a brand and scale offer in the area. There are obvious complementary businesses to upsell/cross sell eg solar roofing and batteries for the remaining electricity - very profitable in school holidays to sell unused solar back to grid in peak periods.
(They also talk about licencing an App to 100 electrical contractors to target smaller SME opportunities. I am more sceptical here - it sounds good 'techno, techno' babble but a lot of work to run.)
The larger customer offer of a +/- 30% reduction in electricity in Yr 1 and very big LT savings but no capital upfront will be very appealing to cash strapped schools/LA's wanting to go green. On a £100K pa energy bill that another teacher for 'free'. Their business model immediately transfer this capital requirement/risk to a finance house who in return get a discount and a very secure cashflow, effectively backed by the govt. (EDIT - Missed adding the key sentence from my notes that this means each incremental contract is typically cash positive and thus they could need surprisingly little cash to scale up, certainly vs many small competitors. This is where being on AIM can really help.)
The market is so large and converting so fast that a few medium sized companies will emerge from this area in next few years and this looks as if it has the mgt and model to be a winner.
Two key worries
1. The Govt has found the magic money tree so it may simply make huge amounts of grant money available to schools to go green and create jobs (I would - the social return must be >10% pa whilst borrowing cost is almost nothing and its a surefire political winner) . If the govt do this, then this will be a much less execution only project.
2. This approach will be 'normal' in 10 years so what will the company do then? Effectively, this is a bet on being ahead of the curve now and later selling out to a bigger, slower players in a few years - encouragingly, this is what the CEO did when he built and sold The Hut Group to Trinity Mirror in 2005 !! The presentations are very slick for a small company.
Not sure what to make of K3 Capital (LON:K3C) results today.
They kind of look okay but I'd like to know why admin expense has ballooned so much? It's a bigger group than last year but admin has grown much more. There's about £1.6 M of acquisition costs but even allowing for that there's a big increase, which naturally puts a big dent in profits.
Outlook sounds positive though which might save the share price.
Agree re admin expenses - no explanation that I can see apart from a couple of (I assume) one-offs associated with the two acquisitions. If you drop those out, I get a 27% EBITDA margin v 41% last time. That's a pretty substantial drop. You then factor on amortisation (now £532K v 20K), contingent payments and and one-off acquisition costs and profits end up being lower than they were (50% lower on a per share basis). There is a call on Thursday to go through them. Will be interesting to hear what they have to say. In the meantime I am wondering whether to hang on or sell for a quick (small) profit.
The vast majority of this can be reconciled via the Divisional breakdown in the accounts - Quantuma (as per other administrators in the sector) is just naturally heavier on personnel costs relative to the other divisions of K3 Capital (LON:K3C)
Of the c. £9.5m increase in Admin expenses as the newly enlarged group, Quantuma Payroll was £5.3m of this and their overheads were £1.9m. That's 75% of the increase right there.
Further, of the Admin Expenses reported for H1, 11.5% were the one-off acquisition costs related to both randd and Quantuma. Hope this helps.
Thank you. So looks like we can expect K3 Capital to have lower profit margins in future but hopefully revenue growth and removal of the acquisition related one-offs will get eps back on an upward-trend
I should think so.
The blended rate margin may well be lower but this is already anticipated in the forecasts in the market. (finnCap currently have EBITDA margin for 2021-2023 increasing annually from approx 28-31%).
I think more importantly, we have to recognise that H1 to end of November 2020 and 4 months from Quantuma are not the best overall comparator, given it has been an unusually tough market for the Insolvency practitioners. (Regrettably) This is forecast to open up as this year goes on and support schemes are reduced with courts working through any backlog. This combined with any looming CGT changes driving the K3 Business side may have some potential upward pressure on margins?
finnCap increased price target to 323p this morning and K3 Capital (LON:K3C) are doing an Investor presentation on the 18th Feb at 16:30.
Paul, re N Brown (LON:BWNG) and your comment, "Alliance family now owning 52%". Is there a concern the family could take the company private? Would you see this as a risk or not? It's a general question regarding the size of the director shareholding vs free float and whether you take that into consideration when analysing a share purchase.
Hi V4Value,
Re N Brown (LON:BWNG) - it did cross my mind that with Joshua Alliance buying heavily in the market, and the family now at 52%, then maybe the family might be limbering up to buy out the whole thing? Takeover bids do often come from an existing major shareholder. Sometimes elderly moguls do like to do one last big deal, to put their affairs in order for the next generation. that's pure speculation on my part though. I've downloaded Lord Alliance's autobiography, which has very good reviews, so will know more about him once I've read that.
What surprises me with BWNG is that they got a waiver re the Takeover Panel rules, for the placing in Dec 2020. That's fair enough, it makes sense that the Takeover Panel would wave through a refinancing supported by the major shareholder. However, I didn't realise that it seems to have the major shareholder + family carte blanche to carry on buying in the market. Surely that wasn't the intention of the waiver/whitewash from the TP?
Maybe a reader with specific city takeover experience might know?
Regards, Paul.
My morning smallcap tweet:
Town Centre Securities (LON:TOWN) Gama Aviation (LON:GMAA) Supply@Me Capital (LON:SYME) Fusion Antibodies (LON:FAB) Avacta (LON:AVCT) Fox Marble Holdings (LON:FOX) Mercantile Ports & Logistics (LON:MPL) Ocean Outdoor (LON:OOUT) Nexus Infrastructure (LON:NEXS) Calnex Solutions (LON:CLX) Arden Partners (LON:ARDN)
Town Centre Securities (TOWN) FD leaves end Feb and begins 'garden leave'. New FD needed to increase the focus on reducing costs. He is thanked. What happened there? [SP=117.16 Cap=62m]
Gama Aviation (GMAA) FY(Dec) trading: U/L performance, excluding share of losses from its associate China Aircraft Services remained stable in H2. Operational performance partially recovered in H2. [SP=38 Cap=24m]
Supply @ME Capital (SYME) update on unsuspension: talking to FCA, aware that process has taken longer than expected. Er, that's it. [SP=0.51 Cap=167m]. I'm short.
Fusion Antibodies (FAB) CEO scarpers to pursue other opportunities but will become a consultant to the Company. He is thanked. [SP=135 Cap=34m]
Avacta (AVCT) first data for its rapid covid test "show excellent performance of the test in identifying patients with an infectious viral load and no false positive results". Sample size only 76 though. Proceeds to full clinical validation. [SP=154.5 Cap=391m]
Fox Marble (FOX) FY(Dec) rev down 50% of €0.7m as block marble sales fell to €0.1m (€1.2m) due to global travel restrictions impeding international trade in blocks and fall in China demand. "Confident that 2021 will see a gradual return to normal sales volumes." [SP=2.3 Cap=9m]
Mercantile Ports & Logistics (MPL) wins 5 year contract for bulk cargo, expects 2-3MT over next 3 years. Commences March with significant ramp up in Sep. Also cement contract. "I look forward to updating the market as we close further contracts with pipeline customers throughout the course of the year". [SP=0.39 Cap=7m]
Ocean Outdoor (OOUT) guides FY(Dec) rev down 38% and adj EBITDA -£0.4m (+£33m). "The reintroduction of lockdown measures across all territories in Q4 led to brands pulling back on advertising spend and deferring campaigns." Guidance still withdrawn. [SP=7.1 Cap=390m]
Nexus Infrastructure (NEXS) AGM stmt: trading conditions in TriConnex and eSmart "continue to be positive with both businesses carrying significant momentum" but Tamdown more in-line with the downside scenario. "With a strong balance sheet and order book of £279m, Nexus remains on-track to implement its recovery and growth strategy." [SP=164.95 Cap=75m]
Calnex Solutions (CLX) guides FY(Mar) rev and profit ahead of market expectations with higher margins. No £££. "While we have now started to see some signs that this early pull through of orders is reverting to more normal levels, we anticipate entering FY22 with a healthy order book." [SP=116.24 Cap=102m]
Arden Partners (ARDN) FY(OcT rev down 11%, EPS -5p (-8.9p). "Whilst the macro outlook remains uncertain, our second half performance and more recent trading, together with less volatile equity markets and a good M&A pipeline, gives us confidence of a return to profitability in the current financial year." [SP=11.9 Cap=3m]
Ref Supply @ME Capital (SYME) I really don't know what to make of them. They could be sitting on some very interesting tech, but I can't find out any details. They use the right language (IOT/Blockchain etc), but beyond a single slide I can't find out anything on how they integrate with, or monitor, the inventory that the loans will be made against (which IOT/blockchain would imply and to me is the value proposition).
I've even emailed them directly asking if they can share further details, like a whitepaper or an investors presentation, but not had any response. I hold, but not confidently.
I did notice they are the 5th most picked share in the Stockopedia Challenge
I'm very sceptical about the potential of blockchain, because I have yet to see any application other than Bitcoin that wouldn't be better implemented as a centralised system. Nevertheless, the FinTech applications are getting attention, see this discussion hosted by CSFI :
;feature=youtu.be
I'm very sceptical about the potential of blockchain, because I have yet to see any application other than Bitcoin that wouldn't be better implemented as a centralised system.
Hi FREng,
I remember a discussion I had with you and timarr a year or so ago (alas now impossible to find in the Stockopedia mists of time!) where this was my assertion about blockchain and you were both very positive on wider applications of the technology outside of crypto currency. If you don't mind me asking, what has happened to change your mind in the last 12-18 months?
All the best, Si
I remember a discussion I had with you and timarr a year or so ago (alas now impossible to find in the Stockopedia mists of time!) where this was my assertion about blockchain and you were both very positive on wider applications of the technology outside of crypto currency
Well, I haven't changed my mind.
I've recently been working on a number of cross-border regulatory data sharing applications where blockchain is the ideal mechanism: everyone needs certainty, everyone needs transparency, everyone needs to ensure that the data can't be modified without everyone agreeing. Blockchain is very efficient where you want instant and confirmed settlement - because you can essentially commit and confirm the transaction at the same time. It also works well in situations where you want distributed authority.
Unfortunately a lot of so-called blockchain applications can easily be built on a database with permissioned access. But there was a point where adding "blockchain" to your business model added a nought on the end of the funding you could get, so a lot of people did just that. As we come out of the trough of despond we'll see real applications, but I suspect most of them will be in the clearing and settlement infrastructures, outside of most peoples' direct experience.
timarr
Well, I haven't changed my mind.
I didn't assume you had! It just seemed to me that FREng has changed his tune, hence the question :-)
I've recently been working on a number of cross-border regulatory data sharing applications where blockchain is the ideal mechanism: everyone needs certainty, everyone needs transparency, everyone needs to ensure that the data can't be modified without everyone agreeing. Blockchain is very efficient where you want instant and confirmed settlement - because you can essentially commit and confirm the transaction at the same time. It also works well in situations where you want distributed authority.
Unfortunately a lot of so-called blockchain applications can easily be built on a database with permissioned access. But there was a point where adding "blockchain" to your business model added a nought on the end of the funding you could get, so a lot of people did just that. As we come out of the trough of despond we'll see real applications, but I suspect most of them will be in the clearing and settlement infrastructures, outside of most peoples' direct experience.
timarr
Yes, I think we agreed it would have some useful niche applications, but as I recall we were commenting in a thread started following some kind of "blockchain evangelist" on a PiWorld seminar saying it's use would be widespread and find lots of applications that would change the world! This was, and still is, complete nonsense.
All the best, Si
There's been much podcast and chat room hoopla over the pond re this startup blockchain company:
https://www.abaxx.tech/
There's been much podcast and chat room hoopla over the pond re this startup blockchain company:
https://www.abaxx.tech/
It's almost impossible for me to be less interested. I've been doing "blockchain" since 2012 so just laugh at these bandwagon chasers.
All the best, Si
... as I recall we were commenting in a thread started following some kind of "blockchain evangelist" on a PiWorld seminar saying it's use would be widespread and find lots of applications that would change the world! This was, and still is, complete nonsense.
In the sense intended - which is always about consumer focused transactions - it absolutely is nonsense. However, if you look at interbank transactions it isn't completely stupid - for instance, the World Bank reckons that at any given point over $10 trillion is tied up in cross-border transactions slowly wending their way through the system. Freeing that up would make a big difference.
However, the poster boy of such blockchain transactions, Ripple, is under investigation by the SEC on suspicion of securities fraud, so we'll have to see how that pans out ...
https://cointelegraph.com/news...
timarr
Re: Blockchain applications:
Apologies if you're sick of explaining this, timarr, but am I wrong in thinking blockchain is enormously energy-intensive (eg for 'mining' cryto-currencies)?
If so, surely it isn't scalable and therefore it is doomed for all but very niche purposes, for a very limited number of transactions, as soon as folk get real, or users begin to collide with those scaling limits?
If it is in fact possible to make blockchain energy efficient, and therefore scalable, then I do agree that it would have enormous utility for anonomous/confidential digital transactions for which distributed authority is appropriate (both legitimate and illicit).
Apologies if you're sick of explaining this, timarr, but am I wrong in thinking blockchain is enormously energy-intensive (eg for 'mining' cryto-currencies)?
I'm not an expert here, and hopefully timarr will correct this if needed, but my understanding is that it is bitcoin mining that requires vast amounts of energy, as a result of the systems that make mining increasingly hard as it's produced, to limit supply. However, I don't think that block chain technology itself is particularly energy intensive.
Apologies if you're sick of explaining this, timarr, but am I wrong in thinking blockchain is enormously energy-intensive (eg for 'mining' cryto-currencies)?
To ed (and si)
No. This is a reference to the "proof of work" consensus mechanism (aka "mining") used to commit transactions to the Bitcoin blockchain. In essence it's the way that Bitcoin blocks double spending (a Bitcoin is just digital - in theory I can spend it twice and be long gone before anyone knows. The consensus mechanism is the way that this is dealt with on the Bitcoin blockchain).
Blockchain isn't predicated on proof of work - there are plenty of other consensus mechanisms, which use other methods that are less energy intensive. And if we get technical, blockchains can be divided into unpermissioned (such as Bitcoin) and permissioned (where a bunch of agreed actors get together to approve transactions).
As a takeaway - Bitcoin is energy intensive but blockchain doesn't need to be.
timarr
there was a point where adding "blockchain" to your business model added a nought on the end of the funding you could get, so a lot of people did just that.
Reminds me of when the Long Island Iced Tea Company changed its name to 'Long Blockchain':
Did you miss Cloudcoco (LON:CLCO) (Cloudcoocoo) update this morning?
Reporting 'significant' increase in earnings...
A good space to be in, the cloud :)
Morning Paul,
I’d appreciate your thoughts on Calnex Solutions (LON:CLX) if you have chance please. Looks to be a good update.
Many thanks and keep up the great work.
Playing devil's advocate, there's two way to interpret this statement from Calnex Solutions (LON:CLX) update today:
"capitalise on the growth of the telecoms testing market as the industry transitions to 5G"
Glass Half Full View: The first is that Calnex will have more selling opportunities, as telcos have big capex plans for 5G rollout.
Glass Half Empty View: Telcos don't necessarily have to chose Calnex, if there are new/alternative vendors, and/or their 5G tech providers can provide the tech for performance monitoring. Also, their existing tech is in 4G and 3G networks, of which when load starts to drop due to 5G taking up most of the data flows, then do telcos really need monitoring tech anymore? If 4G networks are running at 50%, 30% capacity in the future, then spending tech to monitor performance is not really required.
I would take with a pinch of salt and do more digging in the stickiness of Calnex revenues, with the transition to 5G.