Small Cap Value Report (Tue 16 May 2023) - CNIC, ZYT, ACRL, EQLS, BOO, SHOE

Good morning from Paul & Graham. Thank you to Roland for standing in yesterday - great output as always!
UPDATE at 12:52 - I'll keep going for a while, as I want to look at SHOE and OTB today.
UPDATE at 14:42 - I'll leave it there for today, hope to look at OTB tomorrow.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
We're a bit overwhelmed with the workload today, so will do our best with this lot, but won't be able to cover everything -

Summaries of main sections below
CentralNic (LON:CNIC) - down 2% to 112p y'day (£321m) - Q1 Results - Paul - AMBER
I have a good rummage through the Q1 numbers below, and it's better than I expected overall, although some concerns remain.
Zytronic (LON:ZYT) - 100p pre-market (£10m) - Interims - Graham - AMBER
A recent profit warning was just the latest blow here. Cash is c. half the market cap. A possible recovery play with the sales pipeline due to start maturing over the next year.
Accrol group (LON:ACRL) - 36.5p (+4%) (£116m) - Interims - Graham - RED
I stubbornly maintain my stance despite share price momentum and an earnings upgrade for FY April 2024. I’m not convinced that its real profitability is particularly high or sustainable.
Boohoo (LON:BOO) - up 12% to 43p (£547m) - FY 2/2023 Results - Paul - AMBER
A fair bit of detail below. Profitability has collapsed, but that was already forecast. Outlook is in line. I think the bull & bear points are all worth considering. BOO isn't at all financially distressed, providing the £325m borrowing facility remains available, so I need more information on that to form a firmer view on this share. Trading could well improve as supply chain problems recede, but the glory days of big profits look behind us. Will it remain a listed company? Lots more issues discussed below.
Quick comments
Equals (LON:EQLS)
101.3p (+4%) (£183m) - AGM TU - Graham - AMBER
Equals, the banking and international payments group, confirms that it is “confident in achieving expectations” for FY December 2023. The heavily adjusted forecasts (as of March) suggested an adjusted PBT of £11.5m this year, rising to £15.5m in 2024.
The company is experiencing fast revenue growth and reports that in the 90 working days to 15th May 2023, revenues were up 47% year-on-year to £32.7m. The full-year revenue forecast (again, as of March) was £89m so that looks very achievable based on performance so far. The gross margin has risen to over 50%, which is another significant improvement over performance in 2022.
I’m leaning towards a favourable view on this one. Perhaps I’ll be late to the party, but I’d like to see proof of strong unadjusted performance before I get too excited. But the signs so far are encouraging and I do recommend this for further research. I’d like to understand the USP of Equals’ products, compared to all of the many competitors in the forex/payments sector.
Shoe Zone (LON:SHOE)
Down 16% to 203p (£97m) - Interim Results - Paul - AMBER
I was quite surprised to see the share price down 16% to 203p today, but on reading the interims, can see why some people decided to bank their profits from a terrific bull run over the last 2-3 years. H1 profit is down - adj PBT of £2.5m (H1 LY: £3.1m). I don’t think this matters too much, given that H1 is the seasonally slower half.
Outlook is one brief line, which seems to be trying to say that FY 9/2023 will be in line with market expectations. That’s not really good enough, as checking my previous notes, the bull story with SHOE was that it repeatedly raised forecasts, and had set them low for this year. Zeus has 13.5p forecast adj EPS for this year, so at 203p the PER is 15.0x, which is probably enough for now.
The balance sheet looks OK, and note it’s been paying out divis & buybacks, so cash is reduced. Capex is also increased.
Paul’s opinion - I was more keen on SHOE last time, as the newsflow was more upbeat, with a series of earnings beats last year. This is a bit more subdued today, so I think a reset of the share price back to 200p is probably justified for now. It should benefit from improved supply chains & lower freight cost, and there’s a good chance it might pull off a beat against forecasts in the full year results. So overall I’ll say I’m AMBER on Shoezone, based on today’s rather lacklustre figures, and just an in line outlook statement.
Paul’s Section:
CentralNic (LON:CNIC)
Down 2% to 111.9p
Market cap £321m
Another $4m share buyback has been announced. This follows a $4m buyback which was implemented in Q1 (Jan-Mar 2023) - as shown in the cashflow statement for Q1.
The rest of this announcement sounds standard. Buybacks make sense when the share price is bombed out, although debt reduction might be a good idea too. I like the change in focus (previously announced) from an acquisitions spree which has greatly enlarged, but complicated the group, to organic growth and instead using cashflows to pay down debt and pay some (modest so far) shareholder returns too.
What does CNIC do? Two divisions -
Digital advertising - this is the larger division by revenue, but I can’t find a profit split between the 2 divisions. This seems to be centred on “advertorial” and review websites. Does anyone know if CNIC has disclosed which websites it owns, so we can check them out? (I know they have mentioned some acquired websites, but what others are there?) This doesn’t sound a high quality activity to me. Similarities with XLMedia (LON:XLM) or Tremor International (LON:TRMR) maybe? (which are also on low PERs).
Domain name management solutions - with recurring revenues & revenue sharing agreements.
Q1 Results (Jan-Mar 2023)
The obvious first question - why is a UK-listed company issuing quarterly results, when the requirement here is six-monthly accounts? I queried this with an adviser, who replied that it’s for transparency, so investors and analysts can better get our heads around the numbers, seeing a clean set of quarterly figures without acquisitions muddying the water. OK, that’s fine, I’m happy with additional voluntary disclosures. I wonder if it might also be a precursor to the company trying to list its shares in the USA, where quarterly reporting is required?
Strong revenue growth in Q1, up 24% to $195m (note US dollar reporting).
Zeus has just raised its FY 12/2023 revenue forecast by 7% to $826m - a substantial business? Well, yes and no. It’s low gross margin of only 23.5% in Q1, down a bit from 24.4% gross margin in FY 12/2022. Therefore I am seeing revenue as a vanity number, with most of it being pass-through revenue, so not a share to value on a price to sales ratio (never a good idea in my view!). Indeed, the company calls gross profit “net revenue”. On this basis, the more realistic number is net revenue/gross profit, forecast at $190m for FY 12/2023 (Zeus).
Profitability - Q1 generated adj EBITDA of $21.3m, but only $7.7m operating profit, and just $2.9m of profit after tax (PAT) - here’s the reconciliation -
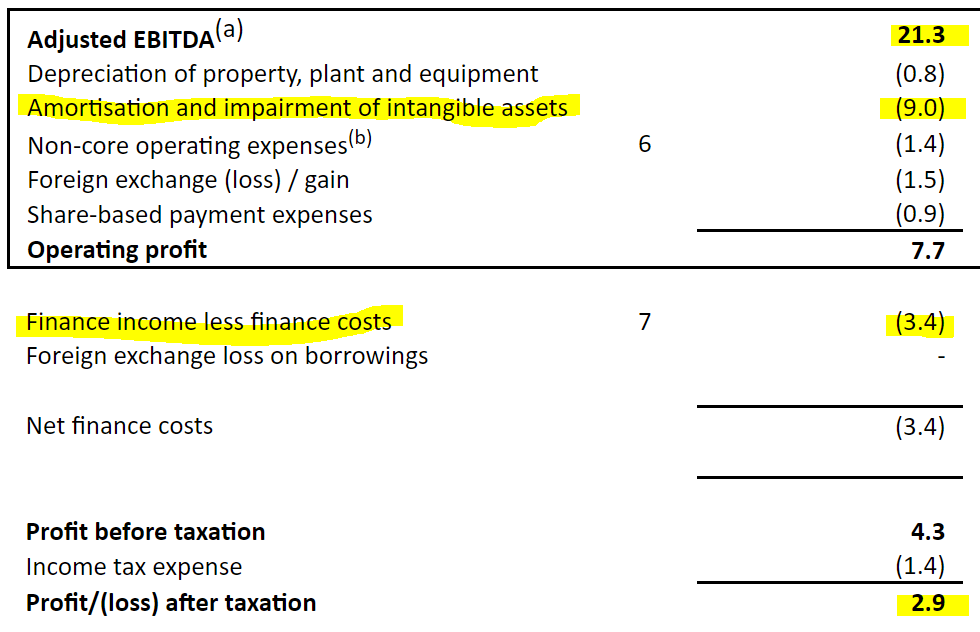
As you can see above, the largest reconciling item is $9.0m (just in Q1, so annualised c.$36m) of amortisation/impairment of intangible assets. The argument is that this is a non-cash charge, so can be reversed out. Is that reasonable? This might surprise you, but having delved into the numbers, I actually think this adjustment can be justified.
The thing I always check, is what type of amortisation is it? Amortisation of goodwill (and similar) can safely be ignored when valuing a company - that’s what most investors and analysts do, and I agree.
Whereas amortisation of other internal costs that have been capitalised onto the balance sheet is very different. The place to look is on the cashflow statement, to see how much of its (usually) payroll costs are being capitalised into intangible assets on the balance sheet, and compare that with the amortisation charge. In this case, not much is being freshly capitalised, as you can see here -
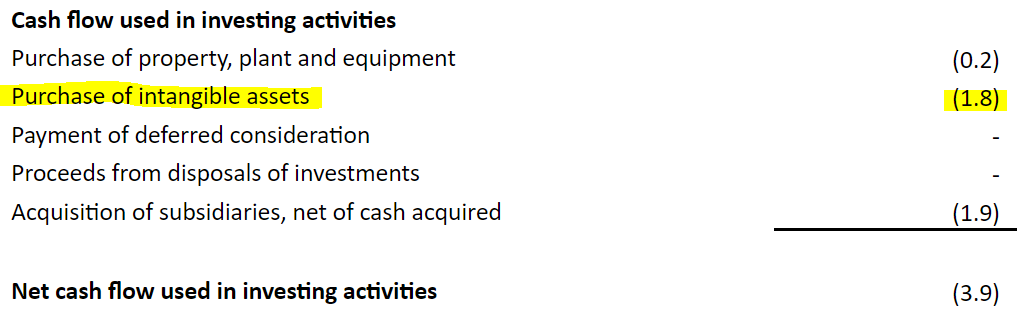
Hence the freshly capitalised costs of $1.8m in Q1 is only one-fifth of the amortisation charge. Therefore, it seems to me that CNIC is indeed cash generative, and its adj EBITDA figure does at least hold some water.
We can’t completely ignore finance charges, and tax though, which is partly why EBITDA is a fairly unreliable concept to me, and doesn’t translate into real world cashflows, precisely because interest costs and tax still have to be paid, so why would you ignore them? Maybe an acquirer might remove these costs, if planning a private equity type deal, with debt loaded up, and taxes avoided? Hence possibly why EBITDA is widely used in acquisition deals.
So I would use a fairly low multiple of EBITDA to value CNIC, maybe 5x its forecast $91.8m FY 12/2023 adj EBITDA? That would be $459m. Add on net debt of $49.3m at end Mar 2023, we get EV of $508m, divided by 1.25 to convert into sterling, and I get £407m. Stockopedia is showing an EV of £377m, so pretty similar, suggesting this share might be priced about right, or slightly too low? But it depends what EV multiple you’re happy to use.
EPS measures for Q1 again show the gulf between statutory & adjusted numbers -
Basic EPS Q1: 1.06 US cents.
Adj EPS Q1: 5.54 US cents
Zeus forecasts 20.8 US cents for the full year, so 16.6p, giving a FY 12/2023 PER of 6.7x - which looks cheap.
What adjustments should we make for the debt? This is a problem area. Net debt reported at 31 March 2023 sounds modest, at $49.3m. However, I’m not at all comfortable with this net figure. Why? Because that net figure breaks down into two large gross numbers -
Gross cash $102.9m, and
Gross bank debt of $147.3m L/T, plus $4.1m S/T = $151.4m
That makes net debt of $48.5m, and there’s a difference of $0.8m relating to derivatives, as explained in note 9, hence we get to net debt of $49.3m.
Simplifying the numbers, CNIC is saying that at 31 March 2023, it was sitting on cash of 2, whilst having outstanding bank borrowings of 3. That doesn’t make any sense! It would cost millions in extra finance charges to borrow a large amount, then sit on the cash, earning a lower level of interest income on it. I think it fixed some of the debt costs, using SWAPs? But I've not done too much digging on the terms of the debt, so you would need to do more work on that yourself if considering a purchase.
What it suggests to me, is that the period end dates are probably spikes up in cash, maybe customers pay at the end of the month? Then a lot of that cash probably goes back out again, days later, thus giving a favourable (but untypical) period end cash balance. That's my hunch, I should emphasise, and could be wrong.
If that wasn’t the case, i.e. if the company sits on c.$100m of cash all the time, then it would just pay off ⅔ of it’s bank debt, surely?
We can get to the bottom of this by the company disclosing its average daily net debt position. All companies should do this routinely, as it’s the only meaningful measure for reported cash/debt. Whereas a snapshot on one day (a balance sheet date) means little to nothing, as it can easily be managed so that it shows a favourable position that is not typical of the day-to-day average cash/debt position.
This is why I find the whole concept of Enterprise Value (EV) to be so dangerous, as you can easily end up over-valuing shares due to basing your valuation on an unrealistically favourable snapshot of net debt/cash position on one day. Average daily net cash/debt (audited) is the number we need, for all companies.
Dividends - a 1.0p maiden divi is being paid on 16 June 2023. That’s a start. With 286.1m shares in issue, it’s a £2.86m cash cost, not much in the overall scheme of things. The buybacks are larger, with $4.0m done in Q1, and $4.0m being done in Q2.
Although note that a 12.4m Euro cash outflow occurred on 8 May 2023, for deferred consideration, which seems to be buried in trade creditors. So I would like to see a full breakdown of what is in trade creditors.
Share based expenses (i.e. free money for the Directors, on top of generous 2022 salary/bonuses of £1m each for the 2 Execs, plus £2.3m for the outgoing CEO) are too high in my opinion, at $5.7m last year. I can understand why outside investors feeling the squeeze of a poor share price performance probably won’t be impressed with nil-cost share options being issued.
The Director dealings page is mixed, with Max Royde (of Kestrel Partners, the biggest shareholder) making repeated purchases, whilst Dayani and Siffrin have been £ multi-million sellers.
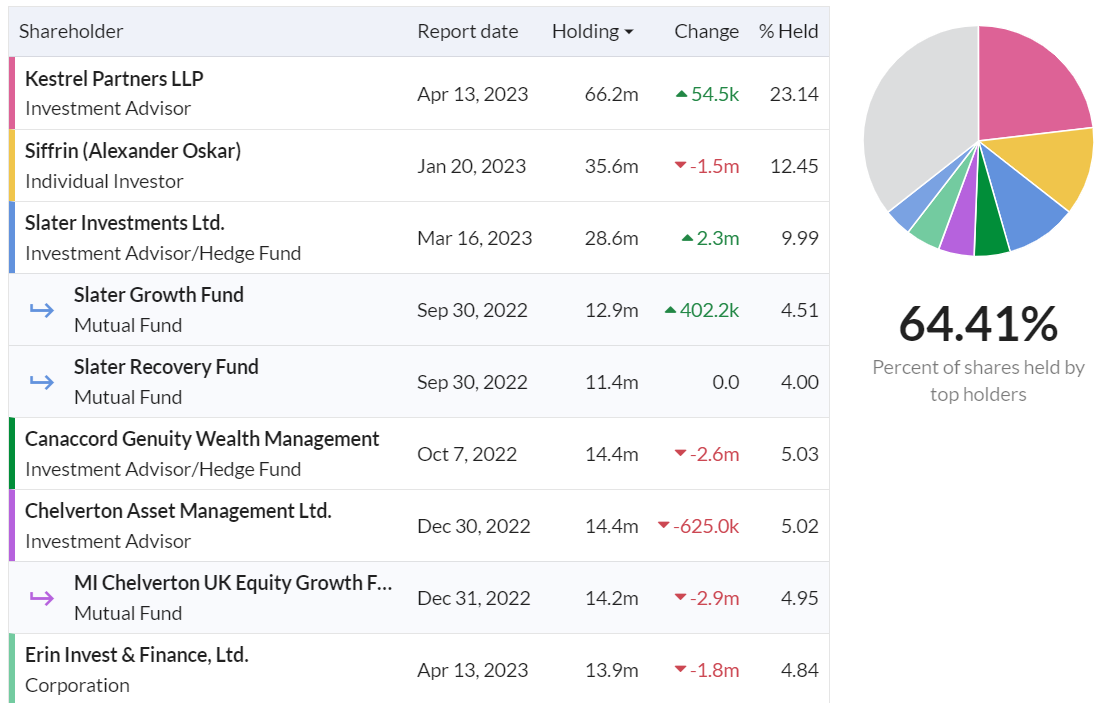
Shareholder register is concentrated, with Kestrel owning 23.1%, Siffrin owns 12.5%, Slater 10.0%, Canaccord 5%, Chelverton 5.0%.
Kestrel and Slater seem to be buyers, with the other large holders all having been sellers -
It’s probably time to wrap this up!
Paul’s opinion - here are my conclusions.
Bull points -
I do think CNIC looks genuinely cash generative, and a large part of the gulf between adjusted, and statutory profit is due to amortisation charges related to previous acquisitions, so I think we can safely ignore that amortisation.
With the acquisition spree now having stopped, it should be possible for CNIC to reduce net debt.
The PER is low, at 6.7x
Over time, assuming it does generate cash in future, the market might re-rate this share.
Bear points and queries -
Awful balance sheet, with negative NTAV of $(175)m. I would be inclined to use this number for valuation purposes, not the (I think probably window-dressed) period end net debt figure of $49m.
Are profits sustainable? We’ve seen many times in the past that digital advertising companies can be big cash generators one minute, and dead ducks the next, when Google or Facebook change their algorithms. The current lowly valuation suggests to me that the market doesn’t think CNIC can necessarily keep churning out good numbers.
How will it be affected by AI and cookies? CNIC says that it doesn't use cookies, so will benefit from them being banned. I don't know anything about this sector, so don't trust my judgement on what the future holds, so am not making any predictions.
Overly rapid expansion - although to be fair, management has addressed this concern, with a revised focus on cash generation & debt reduction.
Gross cash of $103m, and gross bank debt of $151m - this doesn’t make sense. So we need average daily net debt to be disclosed, to better understand reality.
No divisional split of profitability that I can see, so where does the profit actually come from? Advertising, or domain services? What's the split?
Overall, for me, I wouldn’t want to invest in a digital advertising group. I’ve seen too many of them turn out to be bad investments, despite often looking superficially cheap, because things can suddenly change in this sector, and blow up business models overnight. That's often why insiders are keen sellers.
That said, the numbers here are superficially quite attractive, so if you think that profit/cash generation will be sustainable, then it could be worth a look.
Hence overall, I’ll just be neutral, as I can see both sides of the story here. AMBER.
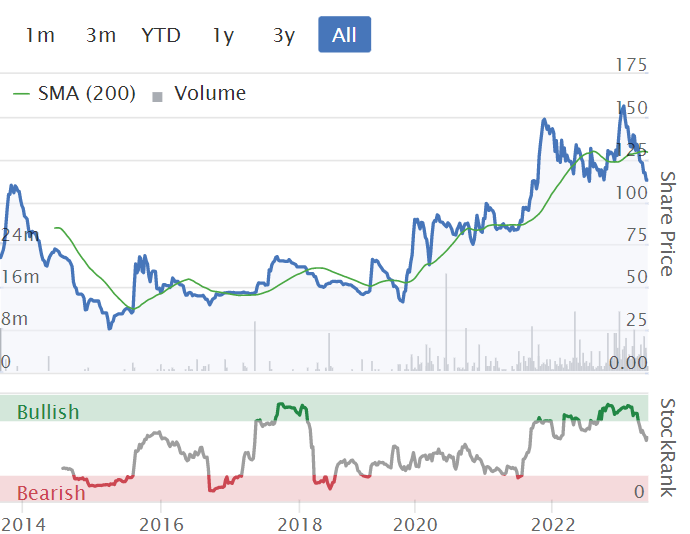
The share price has roughly doubled in the last 4 years - not too shabby -
Boohoo (LON:BOO)
Up 12% to 43p (at 10:15)
Market cap £547m
Lots to digest in this fashion eCommerce group’s accounts.
Key numbers -
Revenue £1,769m (down 11% on LY) - remember that BOO introduced an admin charge for returns this year, so is trying to lose unprofitable orders from customers who are serial returners, and/or treat it like a hire shop.
Gross margin reduced from 52.5% LY to 50.6% this year. Not great, but it’s tons better than Asos (see my recent negative review here). Factory gate and freight cost inflation has hit the whole sector hard. So it’s reasonable to expect some margin improvement in future, as those factors ease.
Profitability has collapsed, but adj PBT actually came in better than broker Zeus expected, at £(1.6)m loss, vs Zeus’s £(8.5)m forecast. Last year adj PBT was £82.5m positive, so that’s a big backward step in performance - which is why the share price has collapsed over the last couple of years.
Adjustments to profit look aggressive to me, so I think reality (subjective) is probably somewhere between the £(1.6)m adj PBT loss, and the £(90.7)m statutory loss before tax.
Net cash is still fine, at £5.9m (a slight improvement on £1.3m last year). The main factor which has boosted things is a dramatic reduction in inventories from £279m last year, to £178m this year. That’s a big difference to Asos, which is very significantly over-stocked, compared with BOO’s now quite lean stocking position.
Net cash also hides a very strange position, with a fully drawn £325m RCF (I still cannot find any disclosure of who the lender is), and a gross cash pile of £331m. As with CNIC in today’s report, why would it borrow all that money, then just sit on the cash pile? We need more information. Note 20 is coy on the facts, but says its a long-dated (2026) borrowing facility, with (no detail) 2 covenants on interest cover, and adj leverage (presumably a multiple of EBITDA?). It’s unsecured too, which is very unusual. We’ll have to scrutinise the Annual Report for more detail on who is providing this large borrowing facility, and what the more detailed terms are. We can’t properly risk assess it without that info.
Exceptional costs of £44.9m looks to be stretching things.
Balance Sheet - apart from the oddity of large gross cash, all of which has been borrowed, the rest of the balance sheet looks fine. Anyone saying BOO is financially distressed is wrong, providing the borrowing facilities remain available. That’s why I think the borrowing covenants, and who the provider is, matter so much.
NAV is £400m, down from £464m last year. There were £132m of intangible assets, so NTAV is £268m, which I think is fine for the time being. This also includes £136m of unencumbered freehold property, in at cost. It’s probably safest to assume that the freeholds have dropped in market value by about a third, but that still means BOO could raise cash of maybe £90-100m if it needed to, from selling, or doing a sale & leaseback of property - a nice cushion there.
Guidance -
FY 2/2024 is seen as being H2-weighted (in revenue growth terms anyway), with H1 expected to be 10-15% fall in revenue. H2 expected to be a return to growth. I’m not bothered about revenue growth, achieving profitable sales is what matters, and that’s the strategy.
Adj EBITDA (not real profit remember!) is guided at £69-78m for FY 2/2024, in a 4.0 to 4.5% range. This is not good, but it’s better than 3.6% actual in FY 2/2023.
Back in the glory days when BOO was highly profitable, and the sector leader for profits, it made c.10% EBITDA margins. I’m struggling to see that returning. So is the company, with a medium-term target of 6-8%, which I’m taking with a pinch of salt.
Heavy capex of £80-90m is due to work on increasing & automating warehousing continuing, and it capitalises about £32m of IT costs onto the balance sheet, which is more than the 17m amortisation charge.
They reckon net debt will go up to 1x EBITDA by year end, so £69-78m. That’s not ideal, but it’s modest net debt still, and much better than Asos again, which is in real trouble with debt & excessive inventories, i reckon. BOO doesn’t have those problems.
It’s probably easiest if I summarise things, in a bull/bear format -
Bull points -
FY 2/2023 results slightly better than expected, and guidance for FY 2/2024 is in line with market expectations, probably why we’re seeing maybe a relief & short-covering rally today?
Big reduction in inventories by 36%, which has been a big benefit to cashflow, with BOO pivoting back to a test & repeat model & shorter lead times post-pandemic.
It should be possible to rebuild margins, at least partially, from the supply chain-driven problems of the last year.
Less competition, with several rivals having effectively gone bust.
Trading overall could improve as new brands, and product categories (e.g. beauty products) build up - having been a drag on profits in the period since acquisition.
Loads of liquidity headroom, but we need to know who the lender is.
Freehold property assets of £136m, unencumbered, gives financial flexibility.
Overall balance sheet is still strong, so I’m not worries about solvency/dilution.
USA distribution centre opening later this year - should dramatically improve the customer proposition (speed of deliveries & returns).
Warehouse automation in Sheffield should provide sector-leading logistics costs.
Bear points -
Profitability has collapsed. So investing here is now a bet on it being able to rebuild profits, which is a lot less attractive to investors than the previously superb profit track record.
SHEIN - the Chinese competitor. It’s difficult to get figures on this, but Shein seems to have devastated the sector, internationally and UK, by undercutting on price.
US legal case - I can’t find much clarity on this.
Departure of key people, especially the family founder of PrettyLittleThing.
Share based charge of £32m seems too high, given the share price collapse, I think mgt need to make more share of the pain.
Dubious exceptional charges - aggressive accounting?
Paul’s opinion - I’ve been very right (2015), and very wrong (2022) on this share in the past, so maybe I should just declare myself neutral to avoid any more controversy? Actually, that’s where I am. It’s not a broken business, and the figures are way better than Asos, which I think is in real trouble. BOO is not in trouble. But is the share an obvious buy right now, not really, if you think that it might be a struggle to rebuild profitability, which is probably how I see it right now.
I should also apologise again to the readers who followed me into BOO. We did brilliantly the first time, but the second time it was a disaster. I didn't think profits would just collapse entirely the way it has done, so sorry for not anticipating the business model would crash in this way. Supply chain has had some impact, but I suspect that Shein might have been the silent assassin in this sector, and only one fellow investor Investore, really rang alarm bells within earshot of me over Shein, but as I couldn't find any firm data on it, I disregarded it, which was a mistake.
But why would the founding family want to keep the shares listed? As mentioned before here, I think the logical thing for BOO to do, is return to a sweatshop model (fast fashion customers don’t give a monkey’s about where the product is made, they just want it at rock bottom price), and go back to being a private company, without all the ESG scrutiny which comes with a stock market listing (but doesn’t trouble its main competitor, which is now Shein).
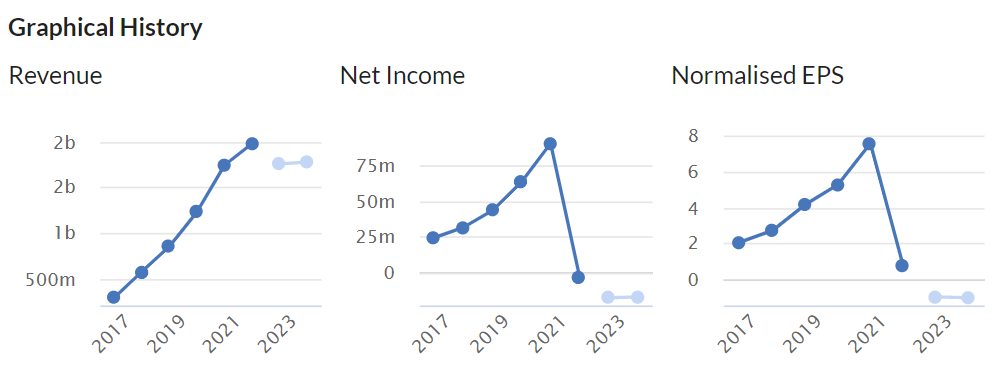
Do I really want to bet on BOO rebuilding its margins? Not really. The attraction for me from this sector has largely gone. Remember its graphs used to be 45% straight lines upwards. This is how they now look - which is not at all attractive any more -
This is the reason that the share price has done this -
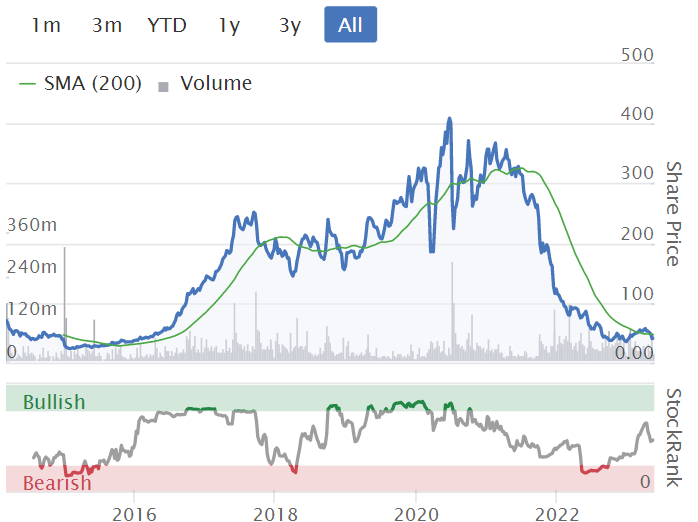
Everything else (like corporate governance, supply chain, ESG etc) is just background noise I think. The shares have collapsed because profits have collapsed. If we get a V-shaped profit recovery, then the shares could do really well, but I'm not convinced that's the most likely outcome. So for now, I'll just watch from the sidelines, AMBER on this one.
Graham’s Section
Zytronic (LON:ZYT)
Share price: 100p (pre-market)
Market cap: £10m
I’ll try to keep this brief given the very low market cap. We last covered this two weeks ago when it issued a nasty profit warning, as it emerged that a customer had overstocked Zytronic’s products, and another important end-customer was in Chapter 11 US bankruptcy.
Revenue forecasts for FY September 2024 were slashed from £13.5m to £8.0 - 8.8m, with (I presumed) another loss-making year. At least the company maintained its traditionally strong cash pile.
Today we have interim results (to March 2023), with the following headlines:
Revenue £4.7m (H1 last year: £5.9m)
Pre-tax loss £0.9m (H1 last year: profit £0.4m)
Net cash £5.4m
The interim chair describes the results as “disappointing”, and says the Board is “working on a number of initiatives to address the headwinds the Group is currently facing so that the Group may return to revenue growth and profitability as soon as practicably possible”.
Let’s skip ahead to the latest outlook statement:
The headwinds caused by the noted effects of the overstocking and Chapter 11 event are expected to remain to the end of the financial year. The positive resumption of business development activities and the Group's Board restructuring with the future Chair appointment, together with other initiatives being pursued, are expected to help position the Group more favourably for a future return to growth.
I note the reference to the “resumption of business development activities” - the company talks about business development taking two years for bespoke projects to mature, with Covid having caused a period of inactivity from 2020-2022.
In other words, they argue that they are still getting back on their feet post-Covid, but can point to a large number of open opportunities that they are working on in their sales pipeline. Supply chain issues also appear to have been resolved now.
Graham’s view
I won’t change my view here: this could be worth researching in more detail, as a potential recovery play, as the market cap is now covered half by net cash. Pre-Covid, they were able to generate a few million pounds of profit every year and their commentary suggests that they are looking to get back to pre-Covid performance levels as soon as their sales pipeline starts to mature (which will take more time).
Against that, you have to weigh the very poor current trading and the risk that the problems could be more fundamental than is apparent from the company’s releases.
I don’t feel confident in either direction and so I’m neutral.
Accrol group (LON:ACRL)
Share price: 36.5p (+4%)
Market cap: £116m
This is “the UK’s leading tissue converter”. We looked at its interim results in January. While acknowledging that it had some bull points, I nonetheless decided to give this stock the thumbs down. I was wary of its focus on adjusted EBITDA rather than real profitability, and its ongoing debt load.
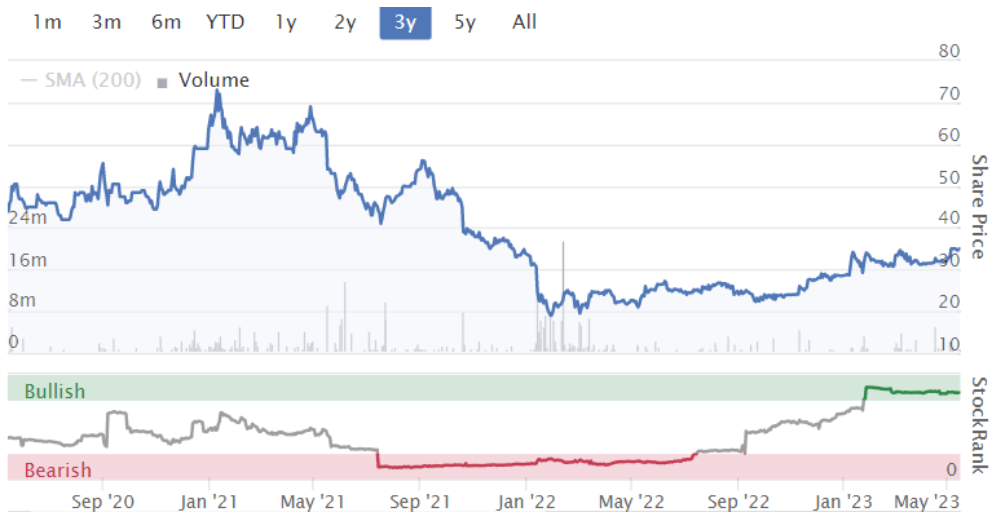
The shares are up another 20% since then as the stock makes a gradual recovery towards the levels seen in 2021:
Today’s trading update is again positive with FY April 2023 full-year results to be “at least in line with market expectations”.
Here’s the key news:
…the Group has continued to perform strongly, gaining further market share through its great value product range, broad retailer base, and new routes to market. The Group has successfully navigated and mitigated the well-reported and substantial inflationary pressures on a broad range of input costs through further process efficiencies and by engaging constructively with its customers to pass-on these additional costs.
Accrol makes paper for the likes of Aldi and Lidl, and the cost-of-living crisis is quite beneficial for discounters, so they are sitting pretty right now!
Some highlights:
FY April 2023 revenues £242m (vs. £230m forecast), up 52%
Adj. EBITDA to be “at least in line with expectations” of £15.5m
Adj. net debt to be higher than forecast (though the RNS does not say this) at £26.8m. The company failed to hit the leverage multiple of 1.5x that it was targeting by year-end.
Volumes up 7.7%, versus a flat tissue market.
Note that inflation is primarily driving the revenue gains, not volumes!
Outlook
Margins to “improve back towards pre-pandemic levels at a faster rate than previously reported”.
However, “prices are expected to soften in the year ahead, while volumes are expected to grow ahead of the overall private label sector”.
Net debt should go back to 1.0x EBITDA (latest was 1.7x).
20% of production capacity remains available to support further volume growth, and the company plans to build its paper mill by the second half of 2025.
Estimates for FY 2024
I’ve dug out a broker note to see the latest estimates.
With tissue prices expected to soften in the current year (FY April 2024), this has knock-on effects. Revenues for the current year are now expected to fall by nearly 5%, back to £230m.
However, with the help of a faster recovery in gross margin than previously anticipated, the adj. EBITDA forecast is raised to £19.3m (from £18.8m).
Graham’s view
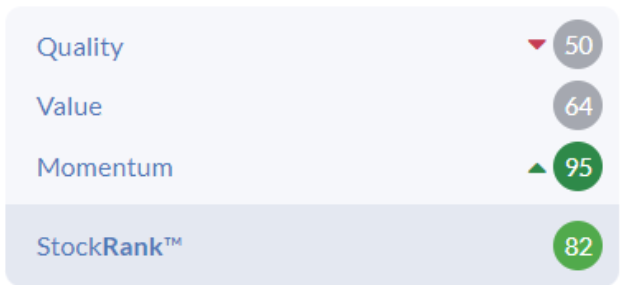
They say that you should cut your losses and for that reason I’m tempted to withdraw my “Red” opinion on this stock, given that it has strong positive momentum behind it currently:
I will give the company credit for reducing its net debt. Even though it failed to hit its year-end target, it is moving in the right direction. That’s important especially as it plans to build a new paper mill, where costs could overrun.
However, I don’t want to change my negative view here as there are still several elements of the stock that make me uneasy, mostly to do with how it presents its results. Many, many different types of cost are excluded from the headline “adj. EBITDA” figure.
If you can find a broker who estimates the actual, reported profits of the business (Liberum is doing this), you’ll find that these estimates are a far cry from the adjusted numbers.
It sort of reminds me of this meme:
The current positive momentum in the share price may continue for some time, but this stock is not for me. It’s producing a commodity product and even if current conditions are favourable, I’m not convinced that it would be comfortable to hold this one for the long-term.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

76 comments
No brain here. But London Stock Exchange (LON:LSEG) on Primary Bid for some cash?.
I'm like a 4 year old child in this 'shark pool' so have no idea what this means - other than suddenly see why GOLD has its attractions - good night, sleep tight - nah!.
Saw one of the two aircraft carriers pulled out of Portsmouth on Sunday night - for me a tear moment, but kids etc not so much.
But why so secretive - it's er not very small, and er probably visible from space, so not sure why no national wavy off - sorry if was on the BBC but unlikely - don't watch it never will.
We all bought some 'rivets' some 'paint' and the fuel for the tugs to tow it out of a harbour because its a 'hulk' as in rather large sitting target. But national pride - shed a tear.
Point is what is LSEG and what significance on the future.
Boohoo (LON:BOO)
Hi Paul
Thanks for the write-up today.
2 quick thoughts from me:
1 - DEBT
I too noticed the peculiar fully drawn debt facility (£325m) and the cash balance (£330m) - very odd.
Also:
Today the debt is stated as being unsecured.
What happened there?
----
2 - INVENTORY
The FY23 cash benefit from reduced inventories therefore looks like it will only be a short term gain.
"Additional exceptional costs associated with the opening of the warehousing facility in the USA will be incurred in the next financial year."
I wonder what the hit will be here and whether it's included in the FY24 capex forecast?
---
The above is enough to dissuade me from investigating further.
A
Hi A
Sonia CIA = Sonia Compounded in Arrears
https://www.bankofengland.co.u...
If those are EBITDA and Adjusted EBITDA (Graham's hilarious illustration above) and if a company insists on reporting adjusted rather than reported numbers - then reported (i.e. real) profits probably look like this
Boohoo (LON:BOO) Regarding whether the company owners could be thinking about a delisting, it seems like they see a positive purpose to being publicly listed. A couple of months ago, they launched their new employee incentive scheme. Management only receive rewards if shares reach 95p, with further payouts up to 395p. The maximum value of the plan is £175m, with CEO in line for a max of up to £50m. The incentive plans goes beyond the executive team to include wider employees.
So at least for the time being, it doesn't look like a delisting is on the agenda?
Hi JAG72,
That's a great point, thanks for the reminder re the recently announced, aggressive employee incentive scheme. That could keep delisting off the agenda for the time being. Although if it looks as if the targets will never be achieved, then interest in the listing could wane.
But a great point, which had slipped my mind, thank you :-)
Regards, Paul.
Cornerstone Cornerstone FS (LON:CSFS) Reported Final results today!
"I should also apologise again to the readers who followed me into BOO."
Paul - no need to apologise. We're all responsible for our own decisions - good and bad. Let's be clear, I give you absolutely no credit for any of my investment successes :) Mind you, there aren't that many to celebrate right now...
Love the EBITDA burger meme. That about sums it up.
Having taken a look at results Id give Boohoo (LON:BOO) 1 manky burger out of 5 (at least it doesnt have mould on like ASOS)
Nicola Foulston must be running out of champagne at the moment ... RBG Holdings (LON:RBGP)
Shein - OMG look at the web site. I will leave you to draw your own conclusions
I remember as a young lad Littlewoods catalogues if that’s what you mean.
Interesting read on Boohoo (LON:BOO) Thanks Paul. It seems to me that boohoo is a case of heads you win, tails you loose. It could go either way or just side ways. A gamble. Too many followers with this share which goes against my Contrarian side to investing making it a big NO NO for me. Good to read your report though.
Me too - I believe there is a negative correlation between followers/chat traffic/tipsters and a share price
Me too - I believe there is a negative correlation between followers/chat traffic/tipsters and a share price
ditto - specifically inverse square of the amount of posts on advfn
LSE and ADVFN - look for large number of (different owner )daily posts - youve just found a great short opportunity
I wonder if the family or a vehicle for the family are involved in the loans for £boo
This would normally be reported in the related part transactions section of the report, if relevant.
that would put them in the position of a principle creditor?
Thank you Paul for the write up on Boohoo (LON:BOO) I am an ex holder and made a lot from 2015 to 2020 and took a real bath recently. But do not apologise. We make our own decisions here.
I am an interested bystander in Boohoo but I have a weakness (or maybe it is a strength) that once I have got burnt by a company (accesso Technology (LON:ACSO) Best Of The Best (LON:BOTB) ) I struggle psychologically to buy back in whatever the bear case and am happy to move on to something else.
There are certainly too many bear points as you list for me to take a position.
The purchase of the central London HQ for £100m doesn’t seem to me to have been good capital allocation and more like hubris when things were going well.
Good luck to holders but I will move on to something else when I stop sitting on my hands, which is what I am doing at the moment. The only trade I have made this year is to sell Alphabet (NSQ:GOOG and top up Microsoft (NSQ:MSFT) but they are both small holdings.
Regards
Michael
Surely must have at least a watching share in Google or Microsoft -they are not going anywhere. Forget 'disruptors' thats yesteryear.
My analysis of Greggs (LON:GRG) :
Sex and drugs and sausage rolls is all your body needs.
This explains everything
My analysis of Greggs (LON:GRG) :
Sex and drugs and sausage rolls is all your body needs.
I can only get one of those in Greggs, but Revolution Bars (LON:RBG) holds the promise of two! Why is it performing so much worse. ;-)
Sold!
"I can only get one of those in Greggs"
any greggs in the toon friday or saturday night after 10pm will give you as much chance as the local rbg down the road - you may have to be careful not to upset the bouncers mind.
Well, as the old saying goes: “the odds are good, but the goods are odd”!
Greggs has bouncers?!...whole new meaning to bun fight
Hi Paul. woud you mind giving your thoughts of the Greggs (LON:GRG) greggs trading update this morning. I realise its a bit bigger than most of the firms you review. im a long term holder of them. Thanks
Hi Christian,
I just had a quick look at Greggs (LON:GRG) - same old story, it's a lovely business, but the shares nearly always look too expensive to me. Today seems only an in line update.
What bulls might be betting on, is that GRG managed to put up selling prices, but could benefit in future from falling food prices (wheat and other food commodities have dropped a lot, but not yet fed into retail prices yet). Also energy costs could come down maybe?
It's complicated, because I don't know how much those things are already priced into the shares, or not.
Regards, Paul.
Have added to my holding in Vertu Motors (LON:VTU) and opened a position in PayPoint (LON:PAY). Like many UK small caps they just appear too cheap. They may of course get cheaper, but trying to time buy at the bottom is a fools errand in my view.
To paraphrase Howard Marks, one of the great investing minds, if a stock is cheap and Oaktree has done its homework we are buyers, if it gets cheaper we will buy more. Once sentiment changes from pessimistic to optimistic and the stock heads north it will become increasingly difficult to buy in any quantity
Listened to recent Moneymaker podcast where Jonathan Davis interviewed Stuart Widdowson manager of Odyssean IT who reiterated the point made by Mark Simpson in a recent post, that forced selling as a result of redemptions from open ended funds is significantly impacting UK small and mid cap shares.
Listened to recent Moneymaker podcast where Jonathan Davis interviewed Stuart Widdowson manager of Odyssean IT who reiterated the point made by Mark Simpson in a recent post, that forced selling as a result of redemptions from open ended funds is significantly impacting UK small and mid cap shares.
That's fine, and may be the case, but I have not seen any significant evidence of this amongst the companies I hold. If it is the case, when and why are these funds going to be buying again? And most importantly, where is the redemption money going? Don't tell me it's people needing to pay their utility bills... I would suggest the money is flowing out and into global ETFs and likely never coming back into UK small caps. Yes, it leaves a lot of companies looking very cheap but companies can stay cheap for a very long time and the risk and opportunity cost of holding them is large. I'll be honest, there's not a day gone by these past few months where I've not asked myself whether I'm trying to push water up hill in holding UK small caps, particularly given the lack of liquidity in most, When you can buy some high quality US large caps on PERs of 10-12 e.g. Paypal, Qualcomm (to name but two) what's the point?
All the best, Si
I don't have any specific issues with what you say Si and it may well be that some American shares are attractively priced at the moment, but I shall stick to my knitting of investing predominantly in UK small caps. However as you indicate patience is often required.
As has been said price is what you pay, value is what you get, although this does not always mean buying stocks that are optically cheap. If one can buy at an asset at a discounted price to its real worth then you tilt the risk/reward see-saw in your favour. The trick off course is determining the real worth.
If public markets continue to ignore sound companies that throw of cash or have desirable assets, the private market is unlikely to do so, irrespective of whether they are UK small caps or where they are listed.
We all have our individual approach to investing and there is more than one way to skin the proverbial cat. Mine has worked well for me to date.
All the best
Vertu Motors (LON:VTU) - looking for this to go private but Mr Forrester may be not for the taking. Always was and always will be a tough market. Selling my car through Auto Trader (LON:AUTO) (paid for ad) and have quotes from Vertu and Motorway (private).
Early days but Motorway seem a smart disruptor. Photograph tyres, all sides, interior, service history and your own damage assessment - chips on windscreen, wheels etc. which only some assessor would do and saves time hassle when turn up and they negotiate your price below what was 'agreed' online through 'damage' i.e. chips on bodywork - yes its in use and goes on motorways duh!
Expect Motorway to do the same but they supposedly pride on putting it out to auction and have shed loads of photos so no surprises (other than mechanical risk).
Their mobile app system works well and get polite reminders. Also free which Auto Trader (LON:AUTO) is not.
Vertu Motors (LON:VTU) give you a local'ish dealership where take it in and get it sold there and then. Assess the car so no 'get out clauses' but expect some negative comments and negotiation but advantage they have taken the risk and assessed it appropriately.
Proof is in the pudding so will see how it goes but cannot invest in it but at least see where a potential disruptor is nibbling away at the listed companies. Don't know about We Buy etc, Car Wow and others.
Forterra (LON:FORT) trading in line. Solid if unsurprising update. Good company, sound finances managing a challenging market well. Is about to formally open the new Desford brick making factory, which I believe is the most modern in Europe.
Brick imports have fallen by approximatively 45%. Outlook, glass half full I would suggest. I hold.
If housebuilding picks up as has been indicated by the major house builders I expect to see a return in time to a share price of well north of £3. In the meantime I shall wait and collect the handsome dividend stream, Current yield around 5.5%. Final dividend of 10.1p payable on 7 July, ex-dividend 16 June.
Current yield should be closer to 10%, assuming they pay their interim divi Sept/Oct.
one ominous cloud is that many fixed rate mortgages will expire in next 12 months and people will struggle with increase in mortgage costs - bound to have an effect on house prices and new builds and hence bricks. The brick imports data is very interesting
Well perhaps, I would like to agree with you (Forterra (LON:FORT) - I hold) , but when I tapped a 25% revenue decrease for the 1st Half into my model the impact on profit is chunky. I'm waiting to see if there is an updated note from Progressive, because its just a guess around costs as to the impact on profits and 2H revenue. But it will need either some dramatic cost cutting (remember lots of fixed costs) or revenue bounce back to hit the current market eps forecast.
Yes, free cashflow is good and the hope that UK bricks can displace imports is a positive, but this government doesn't seem interested in building houses for our population and I'm not sure the next one is going to either, so it looks like we are just reliant on a new Government scheme to drive prices rather than supply.
Thanks Jonno,
Sorry I didn't get round to looking at Forterra (LON:FORT) today, so I appreciate your synopsis of its update.
It's a good company, and looks interesting I think.
I'm still a bit wary of the brick & building products companies, but several could be coming into buying range. I might just wait for bargains to drop into my lap on profit warnings.
Is a 5% yield exciting any more though, when you can get a similar yield on cash, without risking your capital? I'd say no, the picture has radically changed with 4-5% base rates now.
Regards, Paul.
Shoe Zone (LON:SHOE) interim results result in a significant hit to SP this morning, on (in particular) increased wage costs and shipping costs, the former permanent in nature and the latter cyclical so with contrasting effects on the remainder of 2023. The net result is increased LFL sales and reduced profitability. This raises a question about pricing power for SHOE, can they step up (excuse the pun)? My Mum is very pleased with her very new £7.99 slippers, I'd have thought them still a bargain at £8.99 with most of the extra £ dropping straight through to the bottom line.
Online sales are growing at a faster rate than store sales, but the store estate is in great flux so we're not comparing sandals with slippers here. Notably online contribution is 28% of total whereas 'just' 19% of sales. This suggests there are still issues in the store estate and highlights the onerous nature of energy and wage costs.
Your analysis Paul or Graham would be very welcome please.
[I hold]
TEIN
CentralNic (LON:CNIC)
I think I can provide concrete examples of what they get up to.
If you click through one of those "Camper vans being sold for nothing in XXXXXX" (where XXXXX is the address of your ISP, often 300 miles away from your house) amongst the pages of clickbait that flow through like sewage below a Daily Mail website article, you then get taken to a page that lists hyperlinks to various camper van retailers or accessory providers.
Similarly it may take you through to a rather generically named review website which lists 4 products from a sponsoring product provider, comparing them to less competitive rival offerings, and often omitting to mention the market leader, or better value-for-money options. They copy the product review format you might see in PC Pro, Amateur Photographer, Cycling Plus etc (who of course also need walk the line between maintaining advertising revenue and retaining their reputation with readers)
In effect they seek to intermediate in the web browsing experience and steer the consumer away from a whole-of-market view. They will often be picking up the window-shopper rather than someone directly searching for a product on Google or within amazon.
I wouldn't go so far as to question the honesty of the business model, but I am pretty sure they annoy many people (but they don't care as it isn't easy for Joe Public to identify who is behind it), and I suspect the leads they generate are not the highest quality.
A certain proportion of clicks will of course convert - people who are time poor, less suspicious, poorly educated etc
However, the public do eventually get wise to this. With AI it may become very cheap to generate these product placement review websites, at which point the differentiating factor becomes how you attract eyeballs....
Not one for me, but these things can go on for longer than you might expect.
How interesting, thanks Monty Carlo.
I have clicked on those annoying links, saying that retailers are practically giving away unsold cruises, motorhomes, and settees, and it never seems to take me through to anything credible.
IF CentralNic (LON:CNIC) is making money from that kind of thing, then yes it does question their ethics, and yes it definitely questions the longevity of the profit/cashfllows.
No wonder it's priced on a similar low multiple to things like XLMedia (LON:XLM) and Tremor International (LON:TRMR) plus all the other generally lousy digital marketing businesses that have come & gone on the stock market in the last few years.
Still have the now deleted parallel version of this open on another tab. Mr. C was on there so for those whose day is not complete without him here is a screenshot:
OMG did I delete MrC's snapshot? Profuse apologies, I'll send him a sorry message now on WhatsApp!
It was my daughters 2yr old birthday on Saturday. The wife went into Card Factory (LON:CARD) get a big 2 balloon
For some reason my whole post didn't get posted. It was my daughters 2yr old birthday on Saturday. The wife went into Card Factory (LON:CARD) get a big 2 balloon and ended spending 20 quid. I don't think this factored into the share price yet :)....I hold"
Had a browse in the Card factory in Holborn, it's been open since October. I liked the lay out very neat and tidy. I have to say I was amazed at the prices (£1.50 for a decent birthday card). Had a chat with the assistant. She said they were a good company to work for and that the shop had been quite busy. The location itself is not great (between the City and West End) but I liked it. ironically as I carried on the West End I passed a Scribbler so had a look inside. Similar cards were £3.50/£4.00 and the layout was awful (just like Clintons ...which always does my head in because it seems to be utter crap). Anyway just my 2p worth...I hold by the way.
really.. how fascinating
really.. how fascinating
LOL, I think you're channeling our late monarch there! Apparently she had about 20 different ways of saying "how fascinating", ranging from enthusiastic, to highly sarcastic, and a mixture in between. I think I can guess the context you used here ;-)
Guys what do you think of ASOS? Could it be a takeover target at these levels? I'm thinking of the likes of Primark, Shein, Zara, Hedge Funds, Big USA Retailers, Frasers, JD Sports, NEXT.
But the thing that I don't really understand is how Zalando commands a market cap of 8.30 billion vs ASOS 425 million?
On Beach group (LON:OTB) - disappointing half year as it makes a loss even though pre-pandemic it didn't make a loss in the first half.
There's no commentary on whether this is in line with market expectations or not and unfortunately us plebs can't get the broker note via research-tree. Anyone seen what brokers are saying?
V informative post on CentralNic (LON:CNIC) Paul - v many thanks
Paul's comment on On Beach Group (LON:OTB) would be appreciated
I had a quick look at On Beach group (LON:OTB) this afternoon, but have to say I'm struggling to analyse it. There's too much guesswork involved.
On On Beach group (LON:OTB) it looks like a miss on broker forecasts, don't think they can get to 13p EPS for the FY now.
However, there's quite alot of moving parts, and its unhelpful that they haven't provided clearer guidance.
H1 costs were impacted by two things:
Neither of these have been properly explained in the results to help investors understand.
I note that last year's H2 was £9m PBT (statutory), a half year which they incurred quite a bit of extra one-off costs related to the travel chaos last summer.
This H2 upcoming, we should see:
Again, neither of these properly explained in the outlook to help investors understand and quantify.
Management still aren't good yet at giving guidance, and also focusing on what the market cares about now - profits. But I am bullish that they have now carved a dominant position for themselves in the package holiday market, and should see the benefits of pricing power as well as sales growth for the next few years. The downside is lacklustre management (but that is being shaken up), as well as lots of adjusted costs.
(I hold in the Boon Fund)
On Beach group (LON:OTB)
Just had a quick look what an unacceptably cryptic update unless i have missed something. (very sketchy check myu me so i may have missed summit )
From what they have said it seems like momentum is fine - so my taking things at face value unless i have missed something is that they are on track to meet what they said beforfe. If they are nudge nudge wink wink ensuring brokers will reduce forcasts then imho thats an unnaceptable update unless my sketchy check has missed something - surelu they have to clearly yardstick what new expectations are unless they say they are no saying anything about outlook and its clear they have a viewpoint on outlook. Have i missed something here ?
Note if they are not handing out any guidance they should make the very clear in the release - there does appear to be broker forecasts in place so not sure how that tallies up if they are saying we cant give guidance. This is a bad as saga with regard to trying to pin directors down to provide us sharholders in timetly fashion with their best guess however sketchy it is
Morning Paul, will you be covering Boohoo today?
Yes, I want to cover Boohoo (LON:BOO)
Shoe Zone (LON:SHOE)
and On Beach group (LON:OTB)
Paul, good morning, thank you for the thorough analysis of CentralNic (LON:CNIC) . [I hold] .
Updated comment:
After yesterday's brief comment I wasn't expecting further comment from you until after you'd had the opportunity to meet management in person at Mello but hope now you might be able to provide a further update after you've done so.
If you're concerned about the forward reliability of advertising revenue then it's worth noting that advertising accounted for 79% of revenue in 2022, and therefore domain management 21%. 2021 was 63%/ 37%. Growth was almost entirely accounted for by advertising with the domain sector revenue growing in 2022 by less than 3%.
Much depends for investors on whether one believes the advertising model is sustainable therefore. You've highlighted the risk of an external bombshell, (Google changes something and destroys the business model for CentralNic, this is a concern as you mentioned earlier). On the other hand they have recently picked up a contract with Microsoft (Bing).
With regard quality CNIC believes that's what they're all about because (they claim) their process produces high quality heavily filtered product recommendations that are a close match the the online customers search requirement. One can watch a detailed explanation in the first 15 minutes here. This is certainly worth watching for anyone wanting to understand better what CNIC claims it does (and they have at least made a big effort to explain it), which they further claim is privacy safe (cookies) and is 'intelligent' - they believe machine learning and in future AI for example will help them. If one considers the manner by which CNIC connects consumers and advertisers it might well be (in my own opinion) how Google would design it were they doing the job themselves.
Kind regards,
TEIN.
TEIN/Paul looks like a rapid slow down in CentralNic (LON:CNIC) Net Revenues with their Online Marketing division maybe plateauing. Net rev quarterly increased only 15% against 50% increase for last year when all quarters performed strongly. Quarterly growth figures for last year were 43, 60, 55 and 44% respectively so a drop to 15% growth looks significant to me.
Online marketing appears the key driver and CNIC cherry picking the stats included in the headlines, of course. Visitor Sessions and Revenue per 1,000 Sessions seem to be the key performance measures that they use. Quarterly Visitor Sessions for last year were 1.0m, 1.0, 1.3, 1.3. with Q1 this year 1.4m though wrapped up in a trailing twelve month(ttm) stat (why?). Would expect this to be similar for each quarter this year if no further acquisitions so growth may dissipate in H2.
Revenue per 1,000 Sessions only shown on a ttm basis now and has dropped from year end $105 to $102. Comparison with March last year doesn't seem relevant to me as it is a Moving Annual Total stat. Is that fair? I hold here looking for growth and am reconsidering as this looks like it is rapidly going ex-growth.
Online Presence stats are pretty much level with year end on their ttm figures.
Appreciate the financial analysis from Paul and trying to look under the hood at what drives that not second guess it as I'm more marketing and less financial. Am I looking in the right place? Or have I gone down an internet rabbit hole?
Perhaps they could clarify at Mello/when they meet Paul?
Equals (LON:EQLS) included a trading update in their AGM Statement announcement RNS:
"We are delighted to continue to report significant revenue growth. Total revenue in the 90 working days to 15 May 2023 was £32.7 million, an increase of 47%* on the same period in 2022. Expressed as revenue per day, revenue in 2023 was £363k per day against £248k in 2022.
The investment in the Group's platform and Solutions product has been extremely successful and revenues over the same period from Solutions have risen by 102%* to £8.8 million (2022: £4.3 million).
Gross profit margins have also increased to above 50%, which is three full percentage points higher than in the same period in 2022.
* Based on underlying, not rounded, figures."
Morning Paul - what are your thoughts from the Sosandar (LON:SOS) Q&A?
I enjoyed the Q&A with Sosandar (LON:SOS) (I hold) management on Mello last night. As I was getting into the bath, I suddenly thought, gosh I hope my camera isn't switched on LOL, or someone at Mello HQ just got an eyeful :-D
I jotted down a few of SOS mgt comments (and bear in mind they're always super-bullish & enthusiastic) -
Spring season started really well, with March revenues up 32%
App launching in Q2 (July-Sept 2023)
International sales (globally) through GlobalE will start in Q1 FY 3/2024.
Other 3rd party international sales negotiations also underway - "it's already clear that Sosandar brand is in demand"
Confident we'll achieve FY 3/2024 market expectations (Singers note has £58m revs, £3.1m adj PBT, and 1.2p adj EPS)
Question about deal with Sainsburys. Sosandar was approached by the big wholesale customers in every case, who wanted to stock its products online (Next, MKS, J Lewis, Very, SBRY, etc). Aside from Julie, "We're trading brilliantly through Next's website".
Going into a few large SBRY stores as well, first time in physical stores, from Sept 2024. Will be laid out like Dept Stores, with each brand having its own section. Good fit with SBRY customer base, upper-middle.
Size of these deals "could be quite significant", hence why they did another fundraise, to have enough working capital to buy the stock.
Question about which websites sell which items, any difference? Not really, best sellers on our own website are also best sellers on third party websites. Some nuances, but not much.
Question about SOS vs competition (eg. Quiz) - Ali replied, saying women shop many brands, and SOS is only scratching the surface of market share in a huge market. Product differentiation is key to Sosandar's success, this is why the big retail brands want us. Next don't sell third party brands in-store, but do online.
Dubai trade show, Sosandar was in great demand, lots of interest in the brand, and not many other UK brands are expanding overseas.
All overseas expansion is being done in a low risk way, through partners. Yes we've got the bandwidth to do these, one by one.
NB. The above is not comprehensive, as I only wrote down what seemed to me the key points. I don't think there was any new info, this was all reiterating what has been said in the past announcements, just giving a bit more colour perhaps.
All in all, I came away feeling really positive about SOS, and am intending to just hold now, for c.5 years, and just not worry about what happens between now and then, even if growth might disappoint at some stage (it usually does with growth companies). I don't want to get shaken out of this share along the way.
What did other people think?
Regards, Paul.
Thanks Paul for the overview recap. Everything sounds and looks very joined up with capable management unified on their aims and the route to make it happen. As they stated, this is all about a quality product at the right price to a large market segment which is underserved by other brands (high fashion and fast fashion).
It has British success story all over it. Their enthusiasm and passion are driving this forwards. I’m in for the ride and adding. I did recently sell some as overweight and rebalancing, but now ready to add more.
Long term hold that will compound as the growth unfolds.
I had been looking at the Sosander (Sosandar (LON:SOS) ) website for other reasons last week and they had 20% off everything. I've just returned now and they have 25% off everything from 7pm to 11pm. It's been cold, but it's fairly early in the spring/summer season for blanket markdowns. Experienced customers because experts at waiting for the offers and the internal merchandise team are demanding that customers "need a reason to buy". This isn't good for brand building. Personally I am going to steer clear.
25% off? Sound a perfect time to get a new dress for the weekend.
Hi martinck1,
It's worth querying this with the company. The reason I say that, is because ages ago I sold my SOS shares due to worries that they were doing too much discounting. Then afterwards I asked the company, and they said it was targeted, to reactivate lapsed customers, and not available to everyone. Although that might have been via email, or cookies, I'm not sure.
Anyway, I just think it's worth asking the question, rather than jumping to conclusions, because they know what they're doing. Also a certain amount of discounting, special offers, etc, are built into the gross margins. Customers often order more if there's a 20% or 25% time-limited offer, so they'll have crunched the numbers, and worked out what works. It probably also steers people towards slower selling items in some way, I imagine. Good questions for us to ask on the next webinar, so thanks for flagging!
Regards, Paul.
John Wood (LON:WG.)
I had a look at this yesterday following the aborted bid from Apollo and prompt from Paul. It's fair to say its going to be a while before Stocko nos make any sense. There is a rich combination of discontinued business, exceptionals, contract losses et al....so v difficult to analyse. For private investors without access to broker ( co guided) research this is a little annoying. Hey ho it is what it is. None of the newspaper commentary I have seen references any numbers.
John Wood (LON:WG.) geared up through the acquisition of AMEC into the COVID crisis and found itself in a mess with fixed price lump sum contracts. AMEC did something similar in construction a year earlier. The way out for John Wood (LON:WG.) was to sell their Built Environment consultancy business for $1.7bn ...about 15 x EBITDA. These proceeds were received last fall ahead of a CMD. Some had speculated that a portion would be returned to shareholders. Trouble is, Wood Group still have a year cleaning up the business, so cash costs from the deal, tax, and some exceptional from old contracts are still coming through.
What remains I "hope" is fairly clean. Of course the Apollo situation doesn't help....but maybe that's why the shares are potentially cheap. 86% of their contract book is cost reimbursable. I like the industry mix facing Energy (Oil & Gas, Hydrogen, Carbon) and Materials (mineral processing, Chems, life science).
FY 2022 Revenue $5.4bn EBITDA $385m margin 7.1% net debt $400m
Guidance order book +4% in year order book 2023 +10% margin flat
2023 there are $135m exceptionals $60m tax $25m disposal proceeds ..$170m hit ....mostly falling H1.
So first half nos pro forma should be c5% growth at flat margins....net debt excl leases $570m.....top end of their 0.5 - 1.5 range but comfortably within a covenant etc.
They have two cost programmes set to deliver $10-15m IT and $15-20m property over the next couple of years. They also have a rather nice $130m pension surplus.
My best guess... if anyone has a decent forecast please let us know ... for 2024...im putting 2 years growth at 5% and adding $25m cost savings....gives $450m EBITDA .....margin ticking up to 7.5% - debt should be less than $570 ....I will say $550m. This is an EV/EBITDA of 4x. If I put an interest charge at 5% and a tax rate at 20% ... ? then $176m after tax earnings ... which is £140m and an EPS therefore of about 20p. The incentive scheme kicks in at $450m EBITDA. My EPS could be quite wrong - EBITDA less so.
In conclusion sub 150 I think the shares look like they are cheap...BUT until the H1 nos are out you don't know how clean they are....nor whether it's appropriate to use clean nos. The co has had reported exceptional costs for years. Pervious clean up jobs of contract businesses like Serco (LON:SRP) and Capita (LON:CPI) take time. I don't own the stock but think it's interesting enough to look at. The shares fell lower than the pre bid level which is somewhat surprising to me suggesting the market doesn't trust them and is nervous to know what Apollo found. Stocks that do clean themselves up often find favour though, Compass (LON:CPG) perhaps the poster child for this.
Thanks RDHOWARTH, that's fantastic background on John Wood (LON:WG.) - as you say, with so much going on, the published headline numbers won't make any sense, which is why I struggled with it yesterday!
That comment re Amex should say a decade earlier - Apol
Paul - there is a double post of today's SCVR - are you able to merge them?
Maybe like the Boohoo (LON:BOO) results, he's claiming double output, when the results are actually flat (or less in Boohoo (LON:BOO) case.
Sorry about the duplicate post this morning, IT gremlins. Now sorted.
I second KevinS1's comment on your analysis of CentralNic Paul, it's why I'm on here, thank you.
CentralNic (LON:CNIC) Thanks Paul. That's greatly improved my understanding of this company's numbers.
Paul/Graham
I would be interested in your thoughts on the Shoe Zone (LON:SHOE) interims. They seem to be doing a lot of active store management. My own quick DCF calculation allowing for 3% ongoing growth had a present value of 5% higher than current MV, suggesting it is in the right valuation range, based on free cashflow.
Best wishes.
Greyster
I have looked at the interims and have held for almost 2 years now. What I like is the active capital expenditure strategy of making stores and operations more efficient (looking at LED lighting, better insulation, hybrid vehicles etc...) On top of the share buybacks and short leases where they can quickly shut down stores and reopen with cheaper rents, all goes to show that they have their fingers on the pulse and are looking to increase profits by using marginal gains throughout the business. Shipping rates dropping pre-covid levels was also of interest for a wider macro view, although again, this will filter down to the bottom line. If anything, I might be picking up a few shares given that I think this update may not be a strong as some people thought and as the shares have quadrupled since their lows, many might want to take profit - but my yield is locked in at a high level, so I'm looking this 3-5 years.
Wow Paul......what an amazing piece of investigation on CentralNic (LON:CNIC) . This must have taken a long time. Your commitment and enthusiasm is amazing. Thank you.
How kind, thank you KevinS1!
When you find an interesting company, it's like doing a puzzle! With the added benefit that if you get it right, you might make some money from buying the shares too :-)