Small Cap Value Report (Tue 17 May 2022) - ACSO, MER, TRMR, NANO

Good morning! Paul & Jack here.
Agenda -
Paul's Section:
accesso Technology (LON:ACSO) - a fact & figures-free commentary for its AGM today. Although as waffle goes, at least this is positive-sounding waffle!
Nanoco (LON:NANO) - a positive-sounding update on the all-important patent infringement case against Samsung. We don't have enough information to value this share at the moment.
Jack's section:
Mears (LON:MER) - trading ahead of expectations thanks to improving margins and a strong cash performance. The valuation is modest and the yield is good, but this is an historically low-margin business and the share price has struggled to move over the years, which limits my interest.
Tremor International (LON:TRMR) - revenue and EBITDA at record levels in a seasonally quiet Q1, although revenue comes in slightly below forecasts. The valuation is attractive here though, given previous and anticipated rates of growth. Tremor has its fair share of amber flags to investigate - it remains a divisive stock - but a relatively cheap one with some interesting growth prospects. Certainly not without risk though and the share price has been volatile, so I would expect more of the same in future.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
accesso Technology (LON:ACSO)
750p (pre market open)
Market cap £310m
accesso Technology Group plc (AIM: ACSO), the premier technology solutions provider to leisure, entertainment and cultural markets…
Nothing much here, but at least it’s upbeat waffle -
"I'm very pleased with how accesso has started 2022. We've continued our momentum from 2021 and we are executing in line with our plan for the year.
Technology like ours is now a must-have for attraction operators across our industry who are working harder than ever to put guest experience at the forefront of their thinking.
Our solutions enable them to drive revenue, reduce costs and create memorable customer propositions all at once. This year we're continuing to invest to ensure we capture as much of our opportunity as possible, and with our team working with more motivation than ever, we're excited about the future for our business".
My opinion - I generally like trading updates to include some facts & figures.
Is “executing in line with our [Paul: typo corrected, my apologies] plan for the year…” the same as trading in line with expectations? It sounds like it might be, but why introduce doubt by not directly saying so?
This update looks to me as if the PRs have run riot, and managed to avoid saying anything specific!
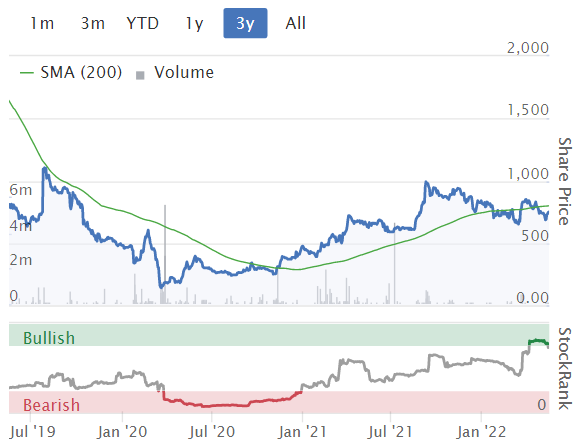
Accesso is obviously a re-opening share, given that it provides ticketing & virtual queuing systems for theme parks. It’s almost impossible to value at this stage, because there’s not a consistent track record of profits or cash generation pre-pandemic.
How much can we rely on broker forecasts, in uncertain times, and with an uncertain business model at Accesso? The StockReport shows the forward PER at 32.6, so it's priced to exceed expectations - brave in the current macro environment. No divis either, because it doesn't generate much (if any) cash.
Good luck to holders, but I can’t see why this is valued at £310m. Particularly as nobody was interested, when it put itself up for sale a while ago.
.
.
Nanoco (LON:NANO)
38p (up 43% at 13:53)
Market cap £117m
We’ve followed this micro cap in the past, but came to the conclusion that the value in the company was entirely dependent on the outcome of patent litigation it had initiated against Samsung. Hence we have no way of knowing what the outcome would be, hence there wasn’t much point in following the company until the outcome of the litigation became known.
As you can see from the 1-year chart below, things seem to be moving in Nanoco’s favour, with a 43% rise today -

.
Today’s update - sounds very positive.
Nanoco Group plc (LSE: NANO), a world leader in the development and manufacture of cadmium-free quantum dots and other specific nanomaterials emanating from its technology platform, announces a significant update to its litigation against Samsung for the willful infringement of the Group's IP.
The US Patent Trial and Appeal Board ('PTAB') has ruled in favour of Nanoco in respect of all 47 claims in the five patents that were subject to inter partes review (IPRs) in the case…
The process is not over yet though, this is just an intermediate stage.
A trial date is expected for late 2022.
Brian Tenner, Chief Executive Officer of Nanoco Group plc, said:
"The strength of Nanoco's case has been amply demonstrated by the PTAB finding in favour of every single one of the 47 claims under the five patents. The question of the validity of our intellectual property has now been very clearly resolved in favour of Nanoco.
"As a result, the trial can now focus on the issue of Samsung's alleged wilful infringement and the appropriate level of damages.
"Nanoco has overcome the first of two major hurdles in the litigation, the validity of our IP. As a result, our confidence in this case has increased further. While there is still much to be done, successfully overcoming this hurdle allows a straight run in to a trial later in 2022. A favourable trial outcome should then deliver a substantial inflection point for Nanoco's prospects and shareholder value."
My opinion - none really, as I’m not an expert on patent trials, so have no idea how much damages would be likely to receive.
A note from Edison today provides more detail. It reckons that Samsung has sold 26m TVs with Nanoco’s technology in them, so presumably damages would be a £x per unit type of settlement? Plus ongoing royalties for use of Nanoco’s patents? Guesswork there on my part. Edison ducks the issue of trying to estimate what damages might be payable by Samsung to Edison, which is a pity, because that’s the key information everyone needs to be able to value the share!
It’s certainly an interesting situation, but with no way of knowing what the upside might be, I can’t value Nanoco shares.
Jack's section
Mears (LON:MER)
Share price: 193.78p (+3.63%)
Shares in issue: 110,953,453
Market cap: £215m
Mears is a services provider to the UK Housing sector, with a range of capabilities including housing management and maintenance. In fact, it is responsible for the maintenance of c.10% of the UK's social housing stock and manages over 10,000 homes for local and central government.
The Group has experienced strong trading in the first four months of its financial year, in particular, driven by continued elevated revenues in its Management-led activities, improving operating margins and excellent cash performance. The Board is therefore pleased to report that the Group's financial results for the first four months to April 2022 are ahead of its expectations, and the Board is increasingly confident in the outturn for the full financial year.
Strong trading, and the valuation is not expensive, so the shares could move this morning. This is a low-margin business though, and things have gone wrong before.
The group adds:
This strong performance has been achieved, notwithstanding a challenging operational backdrop including price inflation and skills shortages, and through a busy period of new contract mobilisations.
After over twenty-six years at Mears, CEO David Miles is set to retire. The group’s COO will replace him.
Conclusion
It’s good to see Mears doing well, but this is a low margin stock with lacklustre returns on capital and this limits my interest.

Profitability is volatile, and I think the business model could remain susceptible to bumps along the road.

The dividend track record is surprisingly good however, and the valuation is modest at around 9.5x forecast rolling earnings with a forecast yield of 4.93%, although dividend cover tends to be below 2x though. Given the pedestrian profitability metrics, I would want a bit more security there.

But the above still signals a desire to return capital to shareholders, and management seems quite stable. The retiring CEO has been at Mears for decades, and the COO that will replace him joined back in 2004.
Ultimately though I come back to the multi-year share price chart, which shows a company struggling to generate serious value for shareholders. If it can keep up the dividend payments then there is an income element to the investment, and it has recently attracted a degree of institutional interest, but it’s not enough to tempt me.

The liquidity scores look quite tight, too, which comes across in the low Z-Score (although the stronger F-Score suggests improvement).

Tremor International (LON:TRMR)
Share price: 460.86p (+3.24%)
Shares in issue: 153,451,112
Market cap: £707.2m
Q1 trading update for the quarter ended 31 March 2022
After a strong run, the Tremor share price has fallen c50% and the company is now back (just about) in SCVR territory. There was a shift in perception here a couple of years back as investors realised that, after many years of acquisitions, the group was finally reaching some sort of inflection point.

That’s because the company, which deals in programmatic advertising, had created an end-to-end platform, meaning it could attract advertisers on one side, websites with advertising space on the other, and add value in the middle with its machine-learning algorithms to quickly and effectively place adverts in a way that both improved advertising rates of return and increased the value of the advertising space in question.
That said, this is a newer type of business model, which comes with its own risk, and there is a degree of mistrust around this stock in my view. That’s due to a few things: director selling, Israeli-based, past disappointments.
Q1 revenue of $71m (+13% organic growth) and a record adjusted EBITDA of $33.6m (+22%), making for an adjusted EBITDA Margin of 47%. That suggests to me the platform is scaling and there is operating leverage here. And it’s worth remembering that Q1 is usually the quietest quarter in terms of ad tech. This does seem to be a slight revenue miss though.
There is a difference between statutory and adjusted results, as well, and you have to go quite far down the press release to find it. Statutory operating profit actually fell by 6% from $15.2m to $14.3m and diluted earnings per share is down 22% from 9 cents to 7 cents (while adjusted diluted EPS is up 20% to 15 cents). This requires a closer look, given the trust issues flagged above. I think, in general, Tremor could probably make its reporting clearer for shareholders.
Video revenue continued to represent the overwhelming majority of total Contribution ex-TAC at approximately 80%. As with a lot regarding Tremor, ‘Contribution ex-TAC’ requires some explanation.
Contribution ex-TAC is defined as our gross profit plus depreciation and amortization attributable to cost of revenues and cost of revenues (exclusive of depreciation and amortization) minus the Performance media cost ("traffic acquisition costs" or "TAC"). Contribution ex-TAC is a supplemental measure of our financial performance that is not required by, or presented in accordance with, IFRS… We believe Contribution ex-TAC is a useful measure in assessing the performance of Tremor International, because it facilitates a consistent comparison against our core business without considering the impact of traffic acquisition costs related to revenue reported on a gross basis.
I would think that traffic acquisition costs are quite an important part of the equation to include?
It looks like M&A might become more of a feature again, with management seeing more attractive valuations:
These strong fundamentals are particularly crucial and beneficial during challenging macro environments and position us well to continue investing in technology, sales, and marketing to drive additional organic growth, continue repurchasing shares, and continue evaluating potential strategic M&A opportunities in a market where valuations and premiums have decreased, to deliver material long-term value to our shareholders.
I think there’s also scope for somebody to bid for Tremor itself, given that it trades at a discount to US peers.
This is a fairly expansive Q1 update. Operational highlights from the company include:
- The completed integration of CTV Ad Server and Header Bidder, Spearad, into Unruly SSP. This is expected to accelerate US growth.
- Unruly and Spearad selected by VIDAA as the group’s ‘strategic sell-side platform’.
- Expansion of TV intelligence solution Reach to 44m US households.
- Strong customer and partner traction in general.
Balance sheet
Is healthy, with $370.8m of net cash position. In fact, the company launched a $75m share repurchase program on 1 March 2022 and has so far repurchased 1,684,510 ordinary shares at an average price of 572.89 pence (total spend of approximately £9.7m in March).
Outlook
Management remains confident in the medium- to long-term prospects of the Company with Tremor well-positioned to further benefit from expected growth trends within digital advertising, CTV, and video, particularly during the second half of the year when it expects to monetize the integration of Spearad, and global ACR data partnership and media relationship with VIDAA.
Q2 guidance is given, with the assumption of ‘no major Covid-19-related setbacks or significant escalation of war’:
- Q2 2022 Contribution ex-TAC in a range of $75 - $80m,
- Q2 2022 Adjusted EBITDA of approximately $40m,
- Q2 2022 Adjusted EBITDA margin as a percentage of Contribution ex-TAC of approximately 50%.
Q1 22 net revenue and Q2 22 guidance of $75-80m are c3-10% light, as some advertisers have postponed spend due to supply chain shortages. Tremor says it has considered this in its projections:
Our guidance also considers the widespread global supply chain issues that limited advertising activity in Q1 2022 in certain verticals such as automobile manufacturing, with the expectation that these challenges could continue to have an impact in Q2 2022, as well as inflationary pressures, and geopolitical and macroeconomic uncertainty.
Conclusion
Tremor has been quite a divisive company in the past, but one that is now much closer to the finished article. It’s very profitable and cash generative, it’s buying back shares, and the enterprise value is currently at just 4x trailing twelve month EBITDA. That suggests to me it’s worth revisiting in more detail after the recent derating.
The group is an Israeli-based UK listing and unfortunately that comes with some baggage. There has been director selling too but from memory this is at least in part due to the group’s US listing. Something to check. Also, there’s no getting around the fact that the business model and terminology used takes some getting used to. Tremor can be a difficult business to understand, and that might make investors pass up on it.
Given the growth on offer and the current valuation, I do think this is a stock to take a closer look at again though. Today is actually a slight revenue miss but we’ve got to consider the valuation here in light of previous and expected double digit growth rates.

PubMatic, for example, trades on c29x forecast earnings with a TTM EV/EBITDA of 11.08x. I see Finn Cap has a price target of 1,700p, some way above today’s share price, so there’s certainly scope for divergent views here. That presents a potential opportunity, but it has also made for a volatile share price in the past.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

58 comments
Paul are we expecting a trading update anytime soon from Revolution Bars Group. My wife was in Revolución de Cuba in Manchester on Saturday and said that it was overflowing. Conscious that no recent trading updates means that the share price has slid along with many other small caps, yet the business appears to be regaining a great deal of traction.
SmartSpace are coming to present at #Mello2022 on both the Wednesday and Thursday so you can all ask questions and meet with the management team face to face for the first time in nearly three years
There are 50 more companies to meet too https://melloevents.com/mello2022-companies/
Plus a big bonus free offer...
If any of you invest in Investment Trusts Funds rather than companies and equities then the first day of Mello2022 will be an enjoyable and educational day out.....FREE TICKETS to our Mello2022 Trusts and Funds event! We have great speakers & 23 Fund managers presenting
Paul,
Re: Acesso
“executing in line with out plan for the year…”
Either that should read 'our',
or it should win an award for the most honest company statement ever!
Hi John,
Thanks for pointing out my typo, what a clanger, sorry!
I've corrected it now.
Best wishes, Paul.
Here's the Vertu Motors (LON:VTU) FY22 results webinar given by Robert Forrester, CEO and Karen Anderson, CFO, yesterday video & podcast. Following the webinar, Paul wrote this superb overview. It certainly was a masterclass on the UK auto market as well as a compelling investment case for Vertu. Robert is superb presenter.
Other webinars this week:
If you are avoiding equities, we have a bonds webinar at 3pm today, with Allia C&C who will discuss their 3-5% yielding bonds, which also support socially responsible organisations. The discussion presentation will be with Allia C&C, an issuer and an investor, so you get every side represented. Join us here.
Tomorrow, 18.5.22, 1pm, we have a presentation by Eneraqua Technologies (LON: ETP) who IPO’d November 2021. They help companies work towards Net Zero through their patented technology in their energy and water efficiency divisions. They have achieved a 3 year CAGR of 38% and cash conversion of 80%. I think they look interesting. Register here.
And again tomorrow, 18.5.22, 4pm SRT Marine Systems (LON:SRT) who are in the marine technology industry, helping to regulate vessels in international waters. The CEO and CFO will present the company, the opportunity, how they are executing on strategy and the outlook. Register here.
We hope you can join us.
Would be interested in any views on Smartspace Software (LON:SMRT) please.
Hope they can make a profit before the cash runs out.
SwipedOn ARR increased by 57% year-on-year to £4.23m (NZ$8.67m) at 31 January 2022 (FY21: £2.70m)
Space Connect ARR increased by291% year-on-year to £0.61m at 31 January 2022 (FY21: £0.16m) At 31 January 2022, Space Connect had 69 customers, an increase of 56new customers in the twelve month period
Recent launch of Korean language variant of SwipedOn visitor management platform
Watkin Jones (LON:WJG) . Half year results. £2.0 billion record pipeline (estimated future revenue), up 43% on last year, of which GBP0.6 billion has already been forward sold; giving us clear visibility of revenue and earnings growth in future years. Offset by "We note the recent passing of the Building Safety Act. Whilst it is unclear as to the exact remedial works that will be required, we have taken an exceptional charge of GBP28 million. We expect these remedial costs to be incurred over a period of up to 7 years."
Watkin Jones (LON:WJG)
""We note the recent passing of the Building Safety Act. Whilst it is unclear as to the exact remedial works that will be required, we have taken an exceptional charge of GBP28 million."
Does anyone have a handle on whether other similar companies may have to take similar hits ? or is this a specific company related issue unlikely to be replicated elswhere?
Also had this company previously flagged up that this £28 mill hit would be coming along about now ? - presumably with no prior provision this has sort of sprung out of nowhere - or is todays hit part of larger earlier provision?
Apologies for being lazy and not doing my own research.
Dear rmillaree
According to the Watkin Jones statement issued this morning, the company has VOLUNTARILY decided to take a remedial charge of £28 million as colin1862 (above) has already stated. This is in addition to £15 million which the company set aside in the last financial year for cladding issues.
Knowing the quality of WJ management, I suspect there is a moral issue here and the company wishes to be seen as acting on the front foot rather than having to be dragged towards a settlement. I have no idea whether or not other building companies will adopt a similar process, but bearing in mind the institutional investors with whom Watkin Jones does business, I am sure it will be well received.
Kind regards
Phillip
Takeover bid announced for Contourglobal (LON:GLO)
Under the terms of the acquisition, KKR will pay 263.6p per share in cash, which is a premium of 36% to the closing share price on Monday.
What do you think, sell just now or wait and see if another bidder emerges?
Hi Paul/Jack - please can we have your thoughts on Tremor International (LON:TRMR) ? Stock seems ludicrously cheap. Good stock rank too.
Apart from the Trade Desk, virtually all adtech is remarkably cheap for the growth rates - see Ironsource, Pubmatic, Perion Network, Magnite etc . It's almost as though the market knows something we don't. I wouldn't expect this to change until recession fears abate or are realised.
Just the fact that pretty much all adtech is still dependent on cookies atm?
Specifically not true for Tremor International (LON:TRMR) ...the demise of cookies is an opportunity
You may be right on Tremor, as I was talking about adtech companies generally, and haven't done any research on Tremor.
But (solely) from your pic you posted in another comment, I don't believe your statement. And I work in digital marketing and have overseen hundreds of millions of ad spending through programmatic display and video. But maybe Tremor has cracked it.
Well, I can't argue with you then ;)
The schematic says nothing about data. Tell me why it means they don't escape cookies?
Victorian Plumbing (LON:VIC) (I don't hold & have been waiting for these results) giving a masterclass in reverse operational gearing in this morning's interims. "An unfortunately timed IPO" (Paul S) called it correctly when it warned recently.
I still can't see value here, but I'm happy to be corrected by readers here with deeper knowledge.
Victorian Plumbing (LON:VIC)
I guess the value is on hope of return to norm in the future (nearly £20 mil profits delivered 2020 - ok covid pre "inflation" tailwinds there ) - a few peeps here couldnt understand why price went under 100p on prior announcement - we are now at 50p - as you say whether its reverse operational gearing or increased costs - times are tough and market cap is still £163 mill still - albeit they do have £33 mill net cash. This might be a good baragin then again it could easily drift lower on no news or delayed worse news - so its fence sitting for me with this one , i could be tempted to pick up some here at some stage though. Can't easily work out if this if profit warning today or not - unless i am mising it there is distinct lack of clarity where they are expecting to end up (ref profits !!) come year end - sigh nil marksout of 10 from me ref this update as we are over half way into year.
I agree. The business is founder led and good, but they IPOd at the optimal time to the benefit of the founder. This has now all unravelled. There is such a headwind in this sector. Cost of living crisis and holidays again will likely take precedence over upgrading bathrooms (which everyone did in the last 2 years). I can see another warning. I am also a tad wary on the enormous marketing spend required for such web-sites. Truly eye-watering.
Victorian Plumbing (LON:VIC)
Hi Mark
I don't hold, but I am keeping a close eye on it as I like a lot of what I see:
We're 2 months into H2 and the company is forecasting modest H2 growth albeit vs a weak comp from last year. If they do miss consensus FY22 revenue forecasts I can't imagine that it will be by much.
Their gross margins are down - like everyone else's - and we're yet to have a full year without IPO costs, which in my opinion are masking the underlying positive fundamentals of the business.
By my estimates the company generated £6.7m of free cash in H1 and should hopefully generate c£15m for the full year. The current EV is c£130m. That doesn't seem too demanding.
Of course, the hope is that there is future growth. Whether that happens is anyone's guess! But with a lot of cash on its balance sheet the risk of insolvency seems low.
If there was one main concern from today, it was that there seems to be a material increase in the CAC. Whether this turns out to be a positive - by driving out weaker competition - remains to be seen.
As I mentioned, I don't have a position at the moment, but it doesn't look too expensive and I am keen to buy in at some point.
A
Any comment on Sureserve (LON:SUR) interims (I hold) welcome * SURESERVE GROUP PLC - HY REVENUE FROM CONTINUING OPERATIONS £126.2M (H1 2021: £101.8M); PROFIT BEFORE TAX FROM CONTINUING OPERATIONS £4.3M, (H1 2021: £3
4% fall on good results...what am i missing?
Would also appreciate a view from the experts on Sureserve (LON:SUR) I have held for a year, never seen any bad news, today's result to the amateur all look positive, but SP hasn't really moved in the year, and down today. NT favourite I believe, what gives?
NT ?
Robbie Burns Naked Trader
Ah OK .
Thank you .
would appreciate same please Paul read ok to me
M&C Saatchi (LON:SAA) .... I think now that £advt have made a firm offer, they are able to buy M&C Saatchi (LON:SAA) in the market. thus adding to the 42% they already own. they have CASH to buy a further c.14% of £SAA. can anyone confirm listing rules on this.
IMO this would mean that the take over has much higher chance of succeeding than current market view.
additionally, although the offer document noted that of £advt were at NAV, the offer would be 237p, there was no mention that off the M&C Saatchi (LON:SAA) shares they already own were marked to market, the offer would now be worth c.250p by my calculations.
disc I hold both
Re ANG - Full year results today which seem very encouraging to me. Sales up 7% (36% on P2Y), healthy mix of online (47%) and retail with the later still partially depressed by closures. Some 4 new store openings plus sensible sounding moves on ranging, stocking and staffing from the still relatively new commercial team seem likely to bear fruit on mix and sales instore this year. Confirmed next year's forecast of 14% revenue growth. Higher margin Own label was up 25% and now seems better resourced internally.
Biggest plus was the confirmation that the European distribution centre in Holland is open to get round all the costs and problems caused by Brexit. (They are NOT happy with Brexit's impact and quantify is overt costs as well as cite intangible increased hassle and paperwork distractions).
They seem very confident in the x3+ Euro-opportunity and it is this that I eventually expect to be the catalyst for some share price growth. In the meantime, UK business looks like steady ship positive on a solid, cash rich base. Can a fishing business be said to be building a moat? Anyway, happy to hold.
Angling Direct - FY results released. Appreciate comment. Hard to believe it is not undervalued, with forecast sales of over £80m against market cap of £37, with cash of £13m and profitable. invested in Euro hub to rebuild growth across Euroland.
Would appreciate you covering Shoe Zone (LON:SHOE) interim results which seem excellent for 26 weeks to 2 April 2022 period:
Profit Before Tax 3.1 M (loss in 2021)
Cash balance increased from £4.1M to £13.9 M due mainly to revenue and profit generated
Dividend restored: Interim 2.5 pence payable in August 2022
Surplus for one of 2 closed defined benefit Pension schemes up to £6.9 million from £5.9 million. The other has deficit of £2.9 M. Same question as Paul posed for another company recently - is any of this payable potentially to the Company?
Energy costs cannily fixed until September 2023
Their returns rate is 10.9% mainly to store which is excellent and efficient. They stress the value of having the stores available in that way
Lease reduction of 37% average in savings on renewal
A company which seems to be navigating the retail space well unlike many others at present
Positive AGM statement from Vitec (LON:VTC)
"Overall, our end markets remain buoyant despite some headwinds. We continue to expect to more than offset inflationary pressures with higher pricing. The Board is increasingly confident about the outlook for the Group for the year."
I am sure that Lord Lee is pleased, as I am.
I hold and if given the opportunity will look to add.
Could Shoe Zone (LON:SHOE) be a shoe in for discussion today? Good interims by the look of it.
Shoe Zone (LON:SHOE) interms look very strong, revenue increase back to pre covid and with the new leases and online mix the business is looking well run. In these difficult times I suspect many people will have to tighten the purse strings and Shoe Zone (LON:SHOE) could benefit
The Vin Murria AdvancedAdvT (LON:ADVT) saga appears to be reaching a conclusion. I would value Paul or Jack providing their perspective on the latest offer. She means business for sure, and has set about replacing the M&C Saatchi Board already. I could potentially soon own an advertising & media business I didn't know I wanted to own - but she has a strong track record and she clearly details the strategic bolt-ons that she is going to go after. Sounds a bit like Sorrell's S4 Capital playbook.
Lecture tonight 6pm: How to value a stock
Positive progress from Tremor International (LON:TRMR) and strong forecast growth going forwards. Incredible job but I am not quite sure how they can possibly award themeselves such high stock based compensation. It is egregious and insulting to shareholders in my view. I hold, and will continue to hold until the true value of this business is realized, but the Rem Committee needs to answer to shareholders on this. I want the Exec Team to be well incentivized, but this is beyond reasonable.
With a massive cash pile, share buy-back, M&A likely at discounted prices and organic growth.......this share price should challenge previous highs by the end of this year. However, in the current market who knows? Would be interested in other perspectives as always.
Finncap have retained their £17 price target (current 470p ish)
CTV market ad spend expected to increase from c$14bn in 2021 to c$29bn in 2024 so opportunity is there.
It has $371m of cash (market cap £680m) with forecast net cash (finncap) of $429m and $575m over the next two years.
Directors share based compensation is large. Finncap forecast $50m this year, dropping to $21.7m next year,
Comp for Tremor International (LON:TRMR) is very large. There's an element of its USA tech. But also a remuneration formula put in place at a stock low a few years ago after the business was experiencing double trauma of its previously dominant performance marketing business withering away and old CEO being binned for losing a civil fraud case. Share price and expectation in the doldrums. Turnaround been spectacular and well beyond what was reasonably expected. I bought at lows on a value plus some underpriced growth optionality basis. I did not forecast what has happened...quite spectacular re-engineering of the business. I've been lucky and did not expect to be holding Tremor at much above 350p given what I could see as their possible optimistic trajectory back when I bought....whereas I've actually bought more at current price (I did sell a decent bit at higher prices so I've bought some back...again lucky there as if I could foresee today's op performance I would not have sold at higher prices and then taken all the subsequent price fall down to current sp)
The CEO Ofer Druker deserves great credit to date...maybe not quite as much compensation but I don't begrudge overall and to a significant extent he has been very lucky with the timing of the design of his comp alongside what has been spectacularly achieved under his leadership. As a shareholder I wouldn't like him to go. Additionally, I'm happy he has a large personal holding now as he has high incentive to see value realised...and I believe there's a lot of further value to be had (unlike many I'm hoping it wont be acquired as that is likely to be low ball relative to value)
The ongoing share price level is super low relative to operational achievements, profitability and peer group (mainly US). There's always a discount UK (RoW!) to US for same business reflecting market liquidity etc. But Tremor could be double current price and still very cheap absolutely and still on too much discount to US peers!
Online advertising tech is fast moving space and always a risk of industry transformation causing obsolescence (see their old performance marketing biz)...but I guess Tremor got stickability for a while partly as a result of an unusual end to end ecosystem for clients that gives the control and security that is important to premium advertisers in a rapidly expanding area of CTV that has been very US focused to date but will expand to RoW
Tremor International (LON:TRMR) can be hard to access as Jack says. There is a lot of detail in historic finnCap notes plus the company has produced number of videos and presentations. This brief one gives a glimpse at some things they do:
https://unruly.co/our-solution...
Tremor is at heart a marketplace. Most of the competing marketplaces are simpler or one dimensional (so either buy or sell side focused) whereas Tremor does the whole ecosystem but it does not tie you to all in or out and you can choose the bits of Tremor you wish to interact with. This means interoperability is very high. This has probably been a great advantage for them during the ongoing ad battles and prevents them being sidelined by industry iterations and battles (a concern people have expressed). In addition, the total control of ecosystem makes them highly desirable for those publishers (sell side) and advertisers (buy side) (ie terminology mirrors newspaper ads!) that are brand and control conscious (and I believe this will drive some of the high margin they enjoy...and should give their overall product durability as its as much a service company as a tech enabling company)
And a pic lifted from finnCap note to give another snapshot of operations (hopefully no one minds the grab!):
Tremor International (LON:TRMR) I hold
Thank you for your take on Tremor. Very interesting. As a holder I agree!!
regards
Michael
Tremor International (LON:TRMR) I hold 7.9% of portfolio. 3rd largest holding
BritishExpat70
"It is egregious and insulting to shareholders in my view."
I agree entirely but then most executive comp is egregious nowadays (Buffett and Munger are good on this towards the end of the 2009 ASM recording).
My relationship with this company goes back to December 2017 and for all of the negatives I do believe that eventually the value here will win out in some form. I have done a quite a lot of research on the three main red flags:
- Debtor/creditor levels. These are normal in this type of business
- Director sales. These are programmed and generally to cover tax charges. That of course doesn't mean the awards that are taxed are not completely unjustified in their size
- Depreciation/Amortisation - much of which is write down of goodwill which can be ignored.
That said they are agressive in some of their adjustments and so one has to work the correct figures oneself. This is my take on the 2021 figures:
Whether it be a market re-rating (because the wake up to the value) plus growth in profits or a take over. But extreme patience is going to be required.
The buy backs are real and the cash one has to assume (unless the company is a complete fraud which I am convinced it is not) is real.
Hope that this is of interest.
regards
Michael
Tremor International (LON:TRMR)
Problem is Michael the share based compensation means the share count is going up even with the buyback
Results from Venture Life (LON:VLG) this morning after long delay due to staffing problems at Grant Thornton.
Adjusted EPS 4.65p substantially ahead of forecast 2.56p giving a p/e of 7.5 at yesterday's close of 35p.
The outlook based on order book ahead of last year is good but modified by "The supply chain issues experienced in 2021 are expected to continue for some time for all businesses, and we have put in place strategies and procedures with both our suppliers and customers to address these. However, the current level of supply chain disruption is unprecedented and cannot be underestimated; our supply chain team is reacting daily to its changes".
Key to increased profitability is the substantial spare capacity at the factories in Bosisio Parini, north of Milan, and Gnesta, Sweden. Any acquisition where manufacturing is transferred there or third party manufacturing agreement would share overheads.
New Chair announced today sounds very experienced.
There could be life in this dog yet! (Yesterday's close 35p one thrd of 12m high). Paul's mate Paul Hill comments here that:
"Finally wrt valuation, at 35p the stock trades on an extremely cheap 5.4x 2022 EBITDA compared to typical OTC consumer firms at often >15x. Plus in Jan’22, Unilever offered GSK £50bn (equivalent to 20x EBITDA) for its much bigger, yet slower growing consumer healthcare division".
Any chance of covering FRP this morning please Paul or Jack? A positive trading update from them. Hopefully a positive read across for BEG which I do hold.
DH2
DH2, I seem to remember Paul holds FRP , with BEG. FRP figs. would seem more up with events, with BEG offering greater value. We also know from BEG recent survey of the sector, that FRP comments confirm exactly what is going on in the sector, with government covid help unwinding , and firms 'real' financial positions being revealed.
Another of our writers mentioned K3C with the BEG survey the other week, I hold all three ,and suggest the stats there[especially in light of recent management RNS confirmation 'all is well' ] should be worthy of investigation. Jack did an interesting writeup a short while ago on K3C. Tony
Hi Tony, thanks for your comments, yes, I have been watching K3C closely too, but haven't 'pulled the trigger' to buy just yet, although things do look rosy there. DH2
PS to both of you. Why do you think K3 Capital (LON:K3C) has fallen away so badly in the last 12 months compared with the other 2? It used to be one of my more profitable holdings, but a 43% fall from 52 week high is really bad. Reasons why it is much worse than Begbies Traynor (LON:BEG) and Frp Advisory (LON:FRP) of course has gone from strength to strength, especially recently.
From my understanding of K3 Capital (LON:K3C) insolvency forms only part of their business, and is more focused on corporate sales, which I would imagine would take a hit in a recessionary environment. In contrast, the others you mention are predominantly insolvency focused, so offer purer plays on this theme.
Thanks. Good point.
Hello tony axon. Thank yo for the reference especially to K3 Capital (LON:K3C) though do you happen to remember when Jack did his bit, or probably how best top find it?
PS for you and Dieselhead2, it is really helpful if you can put the £ sign before the prefix eg Begbies Traynor (LON:BEG), Frp Advisory (LON:FRP) though it only works if you dont put a full stop after it!
ridavies
do you happen to remember when Jack did his bit, or probably how best top find it?
Bring up the stock report and click on Discussions near the top. Jack’s piece is the top of the list presented.
Thanks as always Jim - and re your report on Angle (LON:AGL) yesterday, I meant no criticism on your putting a media report from January 22 on here at this time.
However, I was wondering whether the changes in the market place since then (Russian invasion of Ukraine and almost everyone else's support for Ukraine, militarily and morally, sanctions and the economic impacts from all that; Chinese lock-downs; to name but a few) would have a restraining effect on M&A activity for some time for the Abbot's of this world.
I doubt any of the factors you mention would cause Abbott ($40bn available to spend) or any other large pharma a moment of hesitation if they felt they could buy Angle . The size of the cancer related market both in detection, analysis , treatment and drug trial monitoring is colossal. When FDA approval is given a bidding war could start. AN wants Angle to stay independent and work with others – I’d like to see that – but cynical financial reality may prove too much for some shareholders. More than anything, I’m naive enough to want the system out there saving lives asap whoever owns whoever’s shares.
A cautious and vague outlook from Zytronic (LON:ZYT) today. But there is a very big cashpile, and a continued aggressive share buyback.
I estimate 8p EPS for the FY (H1=3p), and coupled with my assumption of 60p of excess cash and what should be a a c17x valuation for a year in recovery, I come up with a fair value currently of 196p. Which is roughly what it is trading at the moment.
(I hold in the Boon Fund)
Freehold and long leasehold property (without plant and equipment) also worth £3.5m+ by my estimates based on similar size properties (80,000 sqft) in very similar location.
A very positive set of interim results from Sureserve . I hold.
A disappointing reaction to what looked to me like a good set of results from Sureserve (LON:SUR) (I hold) so it would be great to have some comment as to why this might have happened. The challenge of double guessing the difference between expectations and reported outcome is never ending!
They appear to offer the prospect of a growing recurring and low tech revenue stream which must be appealing in these turbulent times.