Small Cap Value Report (Tue 17 Sept 2024) - W7L, JNEO, TM17, MCB

Good morning from Paul and Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
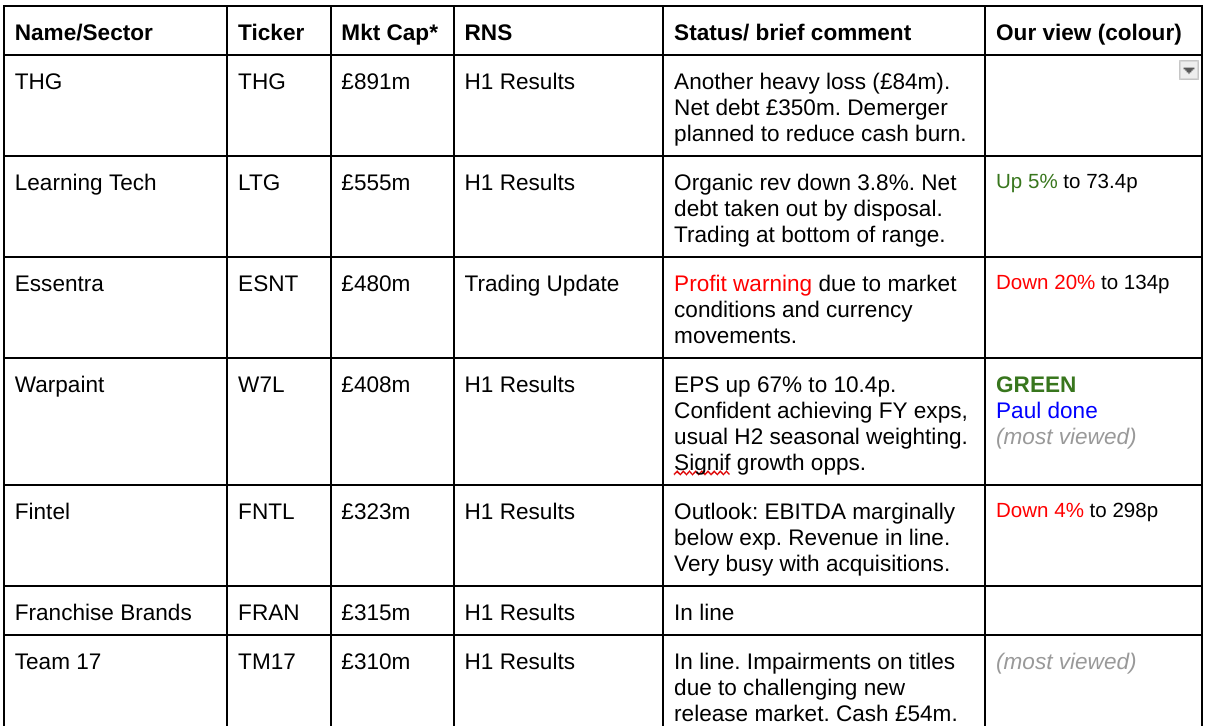
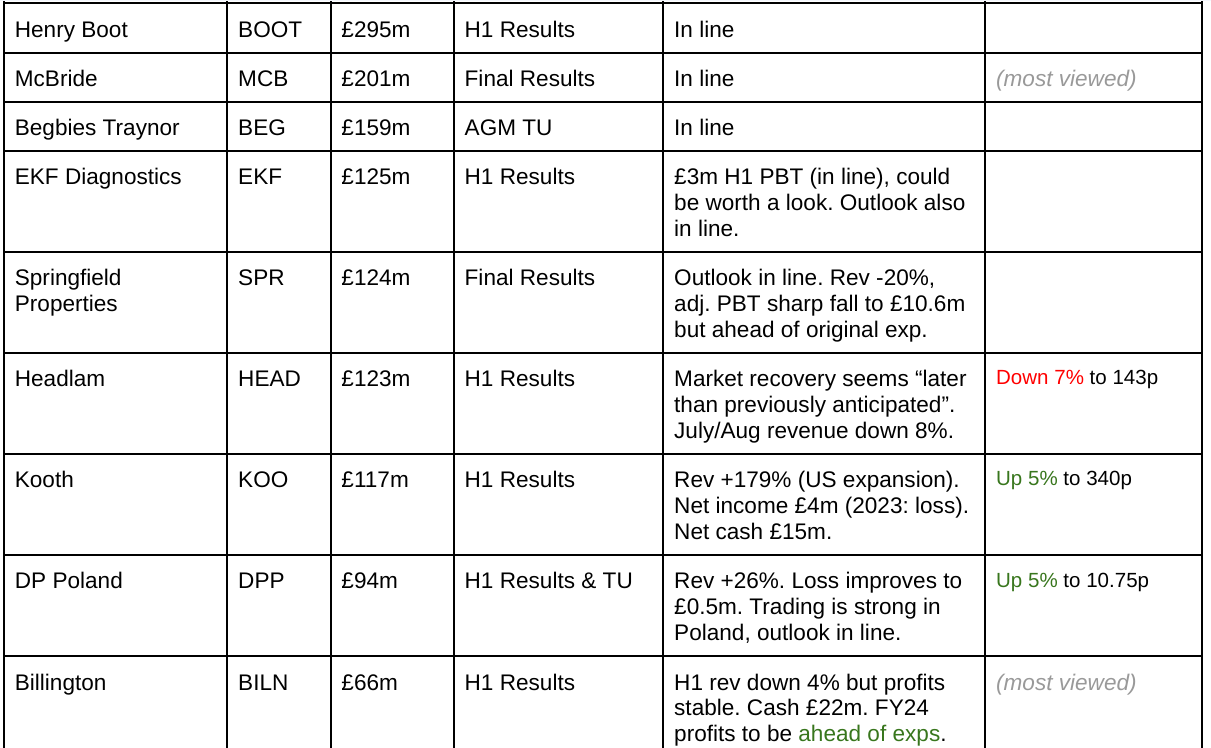
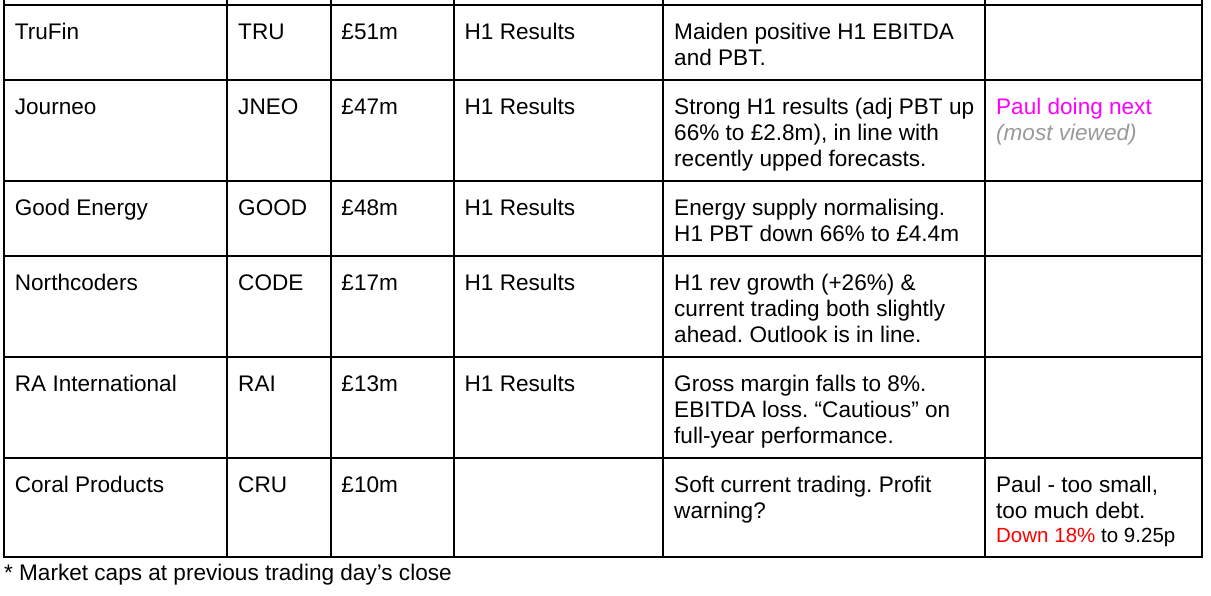
Summaries
Warpaint London (LON:W7L) - 516p (pre market) £401m - Interim Results [in line] - Paul - GREEN
Cracking H1 results, ahead of Shore's forecast, and a FY upgrade this morning (which looks way too conservative, given the heavy H2 seasonality). After the recent c.20% share price pullback, I'm much happier with valuation, so it's an enthusiastic GREEN from me today, the sixth green in a row from us here in 2024.
Journeo (LON:JNEO) - down 1% to 283p (£47m) - Interim Results - Paul - AMBER/GREEN
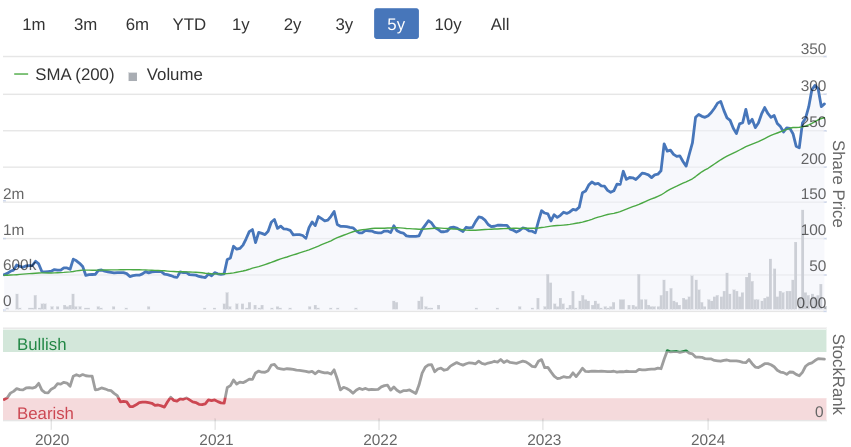
Very good H1 results, which are in line with expectations, as is the FY 12/2024 outlook. Maybe 12x PER is up with events, given that this type of business relies on a constant flow of (sometimes quite lumpy) contract wins? Track record since 2021 has been superb, and shares have more than 5-bagged.
Team17 (LON:TM17) - up 3.5% to 222.5p (£320m) - Half Year Results - Graham - AMBER/GREEN
This is a confident, positive statement with this indie games developer and publisher announcing that it expects to deliver market expectations (on the StockReport, this suggests adj. EPS of 21.8p). With over £50m of net cash and with a large back catalogue generating most of its revenues, I’ll take a mildly positive view on this one.
McBride (LON:MCB) - up 2.7% to 119.7p (£208m) - Final Results - Graham - AMBER/GREEN
This remarkable turnaround story sees this company generating profits far above anything it achieved before the recent inflation crisis. It’s not clear to me how long this situation will last but the company is using the opportunity to rapidly pay down its debts. The current net debt forecast is £111m (for June 2025). This looks like it could have further to run.
Paul’s Section:
Journeo (LON:JNEO)
Down 1% to 283p (£47m) - Interim Results - Paul - AMBER/GREEN
Journeo plc (AIM: JNEO) a leading provider of information systems and technical services to transport operators and local authorities, announces its interim results for the six months ended 30 June 2024 ("H1 2024").
I have a positive impression of Journeo, which started out as a sleepy minnow called 21st Century, selling CCTV systems for buses and trains. Some nifty acquisitions were done, and now it’s all looking a lot more impressive.
We’ve been GREEN here 5 times so far in 2024. There was a strange, irrational spike down to 209p on 16/7/2024, but we stayed at green here, so I hope nobody here panic sold? Stop losses can be a curse with volatile, illiquid shares. These erratic price movements in smaller caps are particularly irksome at present, with many of us suspecting that tax-driven selling ahead of the late October budget could be a contributory factor. I think that’s background noise, and is gifting us buying opportunities mostly, is my best reading of the situation.
H1 figures look healthy -
Revenue +17% to £25.6m in H1 (although only +6% sequentially on H2 2023), helped by acquisitions.
Profit before tax in H1 £2.78m (impressive growth of +67%)
Diluted EPS in H1: 14.76p (+69%)
Outlook comments -
“Strong sales pipeline”
“Record order intake during the period of £24m (H1 2023: £18m)”
“Journeo is evolving into a more capable and resilient business as we aim to become the market-leader for Intelligent Transport Systems. With a growing customer base and a strong sales opportunity pipeline, the Board looks to the future with confidence."
“The Board is pleased with this performance and is confident that we will meet our financial targets and trade in line with market expectations for the full year.”
Balance sheet - NAV £15.3m (growing nicely). This includes £6.8m intangible assets so NTAV is £8.5m.
Net cash is £12.7m (excl leases). Although note it has deferred revenue creditors totalling £9.7m, so the cash pile has mostly come from customers paying up-front before receiving services. I’m surprised at the size of deferred revenue creditors, as I thought JNEO was mainly a contract manufacturing type business. Big deferred revenue creditors suggest it has repeating, software income, which is a good thing. I can’t find a split to show what proportion of revenues are recurring, services type. If anyone knows, please add a comment. I can’t rely on the cash pile remaining in place, until it’s clearer what the nature of the deferred revenue is. If that were to unwind, than the cash pile could largely evaporate, hence why it matters.
Cashflow statement - looks good, and helped by a big reduction in receivables from the last year end. I vaguely recall that previously high receivables being something we queried at the time, so it’s good to see it unwind in H1 this year.
Broker update - thanks to Cavendish for a detailed note today. It has 23.5p EPS pencilled in for FY 12/2024, and notes that H1 results are as expected.
I don’t agree with its argument that the ex-cash valuation is even cheaper, because the cash is offset by deferred revenue creditors, and there isn’t an overall surplus NTAV position.
Hence I make the PER 12.0x, which seems about right to me.
Paul’s opinion - JNEO looks pretty good, and has established an excellent financial track record of growing EPS strongly since 2021. I like its strategy, and the commentary is interesting, with talk of innovative products, with features such as passenger number counting, clever wing mirror cameras to improve safety etc.
No doubt there’s plenty of competition to consider, and this type of business has to constantly win new contracts just to stand still. Hence performance may not necessarily be easy to predict, with the ever present risk of a gap in the order book opening up and delivering a profit warning - as with all small caps that depend on relatively lumpy contract wins.
On balance the I think moderating a little to AMBER/GREEN feels about right, given that this share has already more than 5-bagged since this bull run began in Jan 2021. I don’t see anything wrong with shares needing to pause for breath after such a strong run. It might need an ahead of expectations update to break to new highs, but that’s guesswork obviously.
A more bullish view might be that the good order book and pipeline demonstrate there’s demand for its products, and hence more orders could flow in. I like the emphasis on R&D, in conjunction with customers, developing products that the customers want. So maybe I’m being too short-termist easing down from green to amber/green?
Warpaint London (LON:W7L)
516p (pre market) £401m - Interim Results [in line] - Paul - GREEN
Warpaint London plc (AIM: W7L; OTCQX: WPNTF), the specialist supplier of colour cosmetics and owner of the W7 and Technic brands is pleased to announce its unaudited interim results for the six months ended 30 June 2024 ("H1").
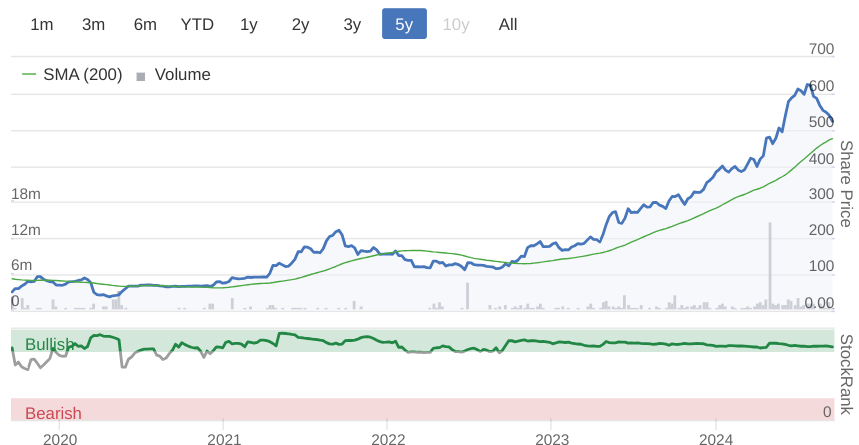
Warpaint is one of our favourite growth companies here at the SCVR. I’ve covered it 5 times previously in 2024 all GREEN, although introducing a note of caution in more recent comments (eg 26/6/2024 at 588p) over the high valuation. Directors sold 7m shares at 450p in May, but retained a huge 43% combined.
On 26/6/2024 Warpaint told the market that H1 was going well, with faster than expected growth. H2 is the seasonally stronger half, due to Christmas gifting & party season boost to makeup sales.
As mentioned before, W7L shares have a wonderfully simple bull case. It sells reasonably priced makeup that end customers like, so the big retailers (internationally) buy more of it, and put it in more of their stores. So organic growth continues, with operational gearing helping profit, and plenty of scope to grow further, given the huge global market. That’s it, there’s nothing more to the business model!
Today’s news -
Interim Results
Revenue +25% to £45.8m (international +30%, now two-thirds of total)
Gross margin up 334bps to 42.5%
Shore Capital says H1 operating profit of £11.0m is ahead of its H1 estimate of £9.5m - good news!
Note that adj EBITDA, operating profit, and PBT are bunched quite close together, as there’s little in depreciation/amortisation, share based charges, or finance costs.
H1 profit before tax is £10.85m (up 76%)
Diluted EPS of 10.3p (up 66%) - and remember H2 is much stronger usually, eg last year H2 was c.double H1 PBT & EPS. If the same pattern holds this year, then maybe we could be looking at c.30p EPS? (Shore ups this year forecast to 23.7p, but says that might prove too conservative - I’d say it’s almost certainly too conservative!).
Put it on 20x my guess of 30p EPS, and I get to a price target of 600p. We’re currently at 530p in the market (08:16), so I think the bull case here looks good after the recent (and I’d say healthy) pullback in share price from the July 2024 peak of c.620-630p. Although I’m making quite ambitious assumptions there with my 600p valuation, that it continues trading its socks off in H2.
Shore reminds us that Warpaint could be just in the early stages of international growth.
Balance sheet & cashflow statement look fine to me, no issues there. It has a modest net cash position, with available bank facilities if needed. There’s no point in over-analysing the numbers, and negative cashflow in H1 is not an issue to me. A rapidly growing business will see cash absorbed into working capital (higher inventories & receivables), plus accelerated tax was another outflow. Also there was more capex (still small at only £1.3m in H1), which it says was due to buying display stands for some retailers, as part of deals to get W7L products into new stores.
Paul’s opinion - the lovely growth story continues. I’m happier with the share price now usefully lower than in the summer, making it a lot easier to justify valuation. So it’s a bright shiny GREEN from me again! The bull story is fully intact, and this looks one of the best long-term buy & hold investments that I’ve seen in the UK market. I’ve been trying to think of things that could go wrong, for balance. China supply issues maybe? Increased competition from Chinese direct-to-consumer companies? Although given the lamentable product quality of some TEMU items I’ve bought, I’m not convinced people would want to rub chemicals from TEMU into their skin! And customers clearly like the W7L brands, so brand value should be growing all the time.
Graham’s Section:
Team17 (LON:TM17)
Up 3.5% to 222.5p (£320m) - Half Year Results - Graham - AMBER/GREEN
Team17, a leading global independent ("Indie") games developer and publisher of premium video games and apps, is pleased to announce its unaudited results for the six months ended 30 June 2024 ("H1 2024" or the "period").
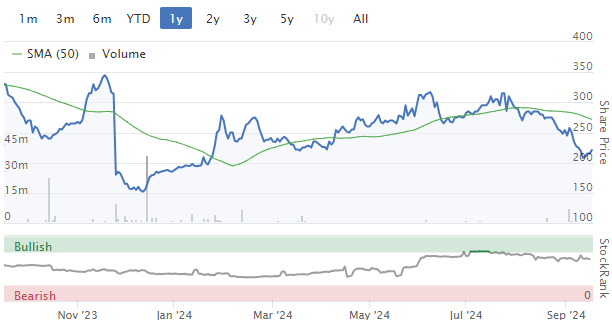
Paul covered the H1 update here.
Today we have confirmation of the H1 numbers and they show continued improvement, i.e.:
Revenues +11% to £80.6m
PBT +53% to £12.4m
Adj. PBT +23% to £19.2m.
To top it off, the company’s cash balance increases from £45m (June 2023) to £54m (June 2024).
Revenue growth is all organic.
TM17’s own games are now responsible for 42% of total revenues (H1 2023: 37%).
The back catalogue is responsible for 92% of revenues (H1 2023: 79%).
Despite the company’s description of its games as being “premium”, these are lower-budget games whose sales tend to have a slow burn compared to the blockbuster titles released by larger studios.
Outlook: in line with market expectations.
New release revenues will be higher in H2. It sounds as though the back catalogue may struggle to match its results in H1, but is expected to give “another good performance”. EBITDA should be more evenly balanced between H1 and H2 than previous years.
CEO comment:
"Looking ahead, there is significant growth potential in our core markets - Indie, edutainment and working simulation games. Our focus on creating a portfolio of games and apps with evergreen longevity, and leveraging our excellent lifecycle management capabilities, ideally positions us to capitalise on this and build a lifetime of play within our growing portfolio and player base."
Graham’s view
TM17 seems to be running smoothly following the departure of long-term CEO Debbie Bestwick from the day-to-day operations (she is currently a NED, and the largest shareholder).
Costs and headcount have stabilised and combined with a stronger sales performance, the company’s profits are on a nice trajectory.
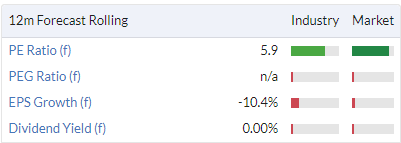
If you’re willing to look past the usual acquisition-related adjustments, especially amortisation, then these shares are cheap on an adjusted basis:
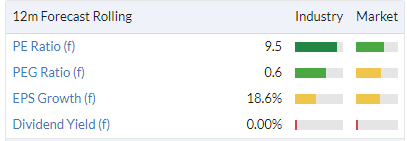
While personally I would be cautious with the adjusted numbers, I do think the valuation should take into account net cash of over £50m. Enterprise value (market cap minus net cash) is £270m.
I have known this company’s name for a very long time (since I was a child), and I’m inclined to take a positive view on it. Back in March 2023, at 405p, I thought the valuation was fair.
Since then, the valuation has been battered by a profit warning and some poor results for 2023, but the business now seems to be enjoying a turnaround. At around 220p, and backed up by a strong balance sheet, I’m happy to upgrade my view on this by one notch to AMBER/GREEN.
McBride (LON:MCB)
Up 2.7% to 119.7p (£208m) - Final Results - Graham - AMBER/GREEN
McBride, the leading European manufacturer and supplier of private label and contract manufactured products for the domestic household and professional cleaning/hygiene markets, announces its preliminary results for the year ended 30 June 2024.
Paul last looked at this in February when he said that excessive gearing was “no longer an emergency, but is a drag on valuation”.
We had been nervous about this one’s survival prospects, but here we are with another successful debt reduction announced by the company today.
Net debt falls from £166.6m (June 2023) to £146m (Dec 2023) and now again to £131.5m (June 2024).
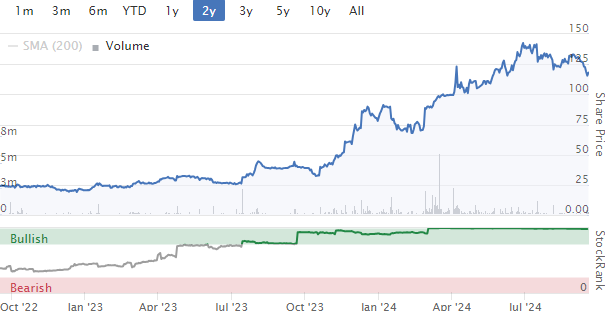
The deleveraging has been associated with a big run-up in the share price, as insolvency has been taken off the table in the short-term::
In terms of profitability, we have:
Revenue +5.2% to £935m
Adj. op profit £67m (2023: £13.5m), slightly ahead of upgraded expectations.
PBT £46.5m (2023: loss of £15.1m).
A stunning return to form that proves the company has successfully passed on input cost inflation to its customers.
Dividends: are not allowed without the consent of the lending group, and are not proposed. Deleveraging should remain the priority for the time being.
Current trading/Outlook: sales volumes are currently in line with expectations for the new financial year (beginning July).
And the full year outlook is in line with expectations, those expectations being adj. operating profit £59.7m and net debt £111m.
In terms of inflation:
Input costs for the main raw materials remain steady, with costs of recycled materials and natural-based chemicals increasing in line with our expectations.
CEO comment:
"It has been an excellent financial and operational performance by the Group. While market dynamics have remained favourable, with a continued consumer trend towards private label across European household cleaning product markets, it is the effective execution of our strategy that has led McBride to capitalise on this environment. Our efforts to further develop our customer partnerships, together with improved consumer insights to support product range developments and innovation led by our specialist divisional teams, will continue to drive future growth.
Graham’s view
I must give credit where it is due: McBride has pulled through some trying times in spectacular fashion. It is now delivering spectacular levels of profitability and becoming a safer investment with every month that passes, as its debt load diminishes.
Is current profitability sustainable? It seems that market dynamics - which include very high demand for private label cleaning products during a cost-of-living crisis - are very much in McBride’s favour, and we should not presume that this will last forever. McBride itself acknowledges that current profitability is “significantly ahead of the historical average”.
Despite a StockRank of 98 and a single-digit PER, I’m not going to let myself get carried away with this one. For me, it remains an AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
*** Springfield Properties - Investor Presentation (FY Results) video recording - September 2024 ***
Innes Smith (CEO), Iain Logan (CFO) and Sandy Adam (Chairman) of Springfield Properties hosted an Investor Presentation covering detailed highlights of the company's Full Year results for the period to 31st May.
Management discussed key objectives achieved during the year, including the reduction in debt, the transformational agreement signed with Barratt Developments and the improvement in Private Housing since year-end. They also discussed the expected sharp increase in demand for housing in the North of Scotland to support the delivery of green infrastructure. The team then answered a range of questions submitted by investors. The full video recording is available for viewing here, divided into chapters: https://youtu.be/Xa_vDFi6IMY
Re Warpaint London (LON:W7L), interesting that the (apparently very conservative) broker forecasts are based only on growth with their existing partners, as per this interview with Sam Bazini...
https://www.directorstalkinter...
They are in talks with other potential partners globally but none of this potential growth is assumed by the broker.
I would say again, it would seem to deliver more leverage and scale for Journeo (LON:JNEO) and Tracsis (LON:TRCS) to merge and put their collective efforts together as a larger player in the Transport, safety and related analytics area. However, I suspect the probable hit on the merger savings for the board of directors, may make a logical joining less than desirable in their eyes. Aggressive takeovers don't really work between AIM companies, so maybe I am in cloud cuckoo land.
However, with Journeo (LON:JNEO) on circa 11x earning and circa 17 x for Tracsis (LON:TRCS) with both of them having plenty of cash, it could be a good punt for Private Equity or a bigger quoted acquirer to make a take over move for them together. There would be operational savings at least at the top.
Team17 (LON:TM17) - Half Year Results - Graham, thank you for your analysis. Much appreciated.
Team17 (LON:TM17)
I second that.
Think there could be good value here as the confidence expressed in the RNS today does not correspond to a share on a PER of less than 10.
Also, I can't help thinking, just look at how much revenue comes from their back catalog - if that (as a software company) was classed as recurring (SaaS) income, this would be on a way higher multiple.
One of Dowgate's shares (incl. Onward Opportunity Fund) - there's a Vox Market Paul Hill interview
Interested to hear others thoughts.
After watching it fall for a while I opened a starter stake today
Sanderson Design (LON:SDG)
Further to my earlier post, I couldn't resist buying a few more at 70.7p; a bargain to my eyes hopefully I'm right?
Sanderson Design (LON:SDG) certainly looks cheap, although I can't decide if it just a 'value trap' given that there has been no revenue growth for years now. Just going back to your earlier post, jonno, I am struggling to understand what is "valuable and irreplaceable " about the William Morris and Arthur Sanderson back catalogues? After all, we are talking wallpaper here and not music or book publishing rights. Can you enlighten me?
Hi Sparkler,
The Morris and Sanderson archive held by Sanderson Design (LON:SDG) originate from the art noveau period, around 1900 and the late 1920s respectively. One can see their value from the various licensing deals the company has done with the likes of Next, Disney, Sainsbury etc. I am no expert but 'art and design' has a value. I recollect the archive being valued at 92p a share several years ago. Its irreplaceable because the designs are viewed as iconic by many and they are not producing them any more. The originators William Morris and Arthur Sanderson are long gone. Looking for an analogy why does an original Mark 1 Golf GTI or Porsche 356 or Series 1 E Type cost a kings ransome. Because they are seen as iconic and examples of great/beautiful cars. That's the best I can do I'm afraid.
I owned a Mark 1Golf GTI as a young man, wish I had kept it!
All the best
Thanks, jonno. That makes sense and I can see that it adds an extra dimension to the 'buy' case. I shall ponder this one a bit further!
I have worked with a team and they used a lot of their products and liked them. My fear is that some of the brands although classic like William Morris can still go out of fashion like Laura Ashley used to come out and go in waves of popularity. The Mr Fox design by Scion Living would be another. I don't know how much effect that has ?
What’s happened to Yiannos?
He’s moved to America - but only figuratively Link
BnB. Yiannos can be found contributing on 'Is the scene set for summer stage 2 discussion'.
What’s happened to Yiannos - I liked him, had some good insights ?
He started a US stocko thread recently.I think he's focusing more on US equities recently.
Hi David
Still here!
I have moved to the thread that Wolf has initiated as I find it more relaxed and concentrated on ideas on stocks backed by charts/numbers.
I still read the main thread and besides you and a couple of others that provide ideas with financial insight the rest of the comments have no interest to me.
I mean today is full of posts about pint prices-cheese prices-even virgin oil prices!
All the best
Victrex (LON:VCT) plc, a UK-based holding company, manufactures and sells high-performance polymers, specializing in PEEK and PAEK-based solutions. It operates through two segments: Sustainable Solutions, focusing on energy, industrial, automotive, aerospace, and electronics markets, and Medical, providing solutions for medical device manufacturers. Its subsidiaries include Victrex Manufacturing Limited, Invibio Limited, and Juvora Limited.
Today's RNS announces the U.S. FDA has approved an Investigational Device Exemption (IDE) for a study of the Freedom® Total Knee System with the Invibio PEEK-OPTIMA™ Femoral Component. In partnership with Maxx Orthopedics Inc., this U.S. study will involve 120 patients and compare the PEEK-OPTIMA™ component to traditional metal components. The U.S. study builds on ongoing clinical trials in Belgium, India, and Italy, which have been progressing well since the first implant in 2021. A regulatory submission in India is also expected soon, with potential market entry for the PEEK Knee in 2025. Jakob Sigurdsson, Victrex's CEO, expressed optimism about the device's transformative impact on joint replacement. The company is also seeing growing interest in PEEK Knee across the medical device industry.
Chart doesn't look great
But plenty of director buys over last few years
Interested to hear from others following/holding. Is it too early to take a starter position?
I can't add much Turbo but Paul Hill is keen and its come up on my personal quant garp screen , I haven't done any research into it but would personally want the chart to start to level off before getting involved.
It was discussed on a recent Paul Hill video with a fund manager last couple of weeks from memory so could be worth having a scan through last couple of weeks of Paul's youtube videos.
Victrex (LON:VCT)
Regards
Andy
https://knowledge.sharescope.c...
Somewhat old but provides colour for those interested. Been on my watchlist for ages too. Distinct lack of broker research so it's DYOR, but superficially it looks like it's becomming good value and high yielding. £40m net debt at Q3 so not highly geared. I'd like to get more comfortable with the LT growth picture, assuming there is a case to answer.
MPAC (LON:MPAC) listened to the meeting yesterday and one thing that I found interesting was that the CFO basically indicated that the pension scheme is now in actuarial surplus. Whilst he didn’t say it explicitly he hinted that it is taking comparatively no time at all to agree requirements because of course interest rates have meant the scheme is in good shape. He also said this will be done before end of year and then “we will move onto next stage” - which, given they have made no secret of the desire to offload the pension scheme seems an obvious pointer.
So I think we should be valuing MPAC (LON:MPAC) excluding pension contributions from next year onwards. I didn’t personally discount the valuation a lot prior to this snippet of info but is nonetheless a benefit assuming I have concluded / read the tea leaves correctly.
The company at which I worked 40 years for took 13 consequetive years holiday in its contributions, when the acturial surplus disappeared the company pension scheme was sold, the committe owning the tea leaves, but it still had to cough up the deficiencies as they came along.
Just a heads up that BILLINGTON HOLDINGS PLC will be holding a meeting re Interim Results today at 3:00pm hosted on Investor Meet Company.
McBride (LON:MCB)
Another share (like Journeo and IG Design and Warpaint) where the chart of recent weeks has implied poor trading or some other problems whereas the reality couldn't be further from the truth.
I really think the lack of liquidity in the small cap market is starting to send out mixed signals for technical analysis purposes, but there are experts here who could perhaps throw more light on this subject matter.
Anyway just wanted to say Graham I agree with all of your analysis except for the part where you say demand for their products may not last forever. I think what has emerged ever more clearly in the last few years is the growth of the discounters (Aldi, Lidl, B&M etc) and they are all about private label products. They are not only a huge sales outlet for Mcbride but they have also reduced Mcbride's dependance on the traditional supermarkets which is partly why I think Mcbride have managed to maintain margins.
Low EV/EBITDA of 3.8x, £82m cash flow pa, small pension deficit, committed deleveraging policy, it's all very positive.
Big negative Teleos have been reducing their holding and we all saw what effect that had on card factory.....
Learning Technologies (LON:LTG)
Really positive market reaction to a lower guidance for FY24, makes me think we are troughing here.
Lots of headwinds but I guess it's all in the price? Keeps ticking up......but I can't make my mind up on what to do.
Journeo (LON:JNEO)
Balance sheet - NAV £15.3m (growing nicely). This includes £6.8m intangible assets so NTAV is £8.5m.Net cash is £12.7m (excl leases). Although note it has deferred revenue creditors totalling £9.7m, so the cash pile has mostly come from customers paying up-front before receiving services.
Not sure i agree with your overall summary here Paul - if we have NTAV of £8.5 thats clearly a decent plus amount overall
As davidjhill has outlined receivables/inventories roughly matches the trade payable / deferred revenue so enough assets here to cover most of these liabilities.
ref deferred revenue a decent chunk (over 2 mill) is simply advances from customer for contract work - thats likely to be upfront payments probably for equipment that is probably sat in inventories - ref the remainder its one of the best credits to show up on the balance sheet where customers are happy for you to bill them in advance for work not completed - they have agreed to pay you so its exactly the opposite of the dreaded "accrued income" where you are doing the work and havent billed and clients may quibble about the bill or paying the bill - almosty nil chance this wont flow through to cash imho normally.
If we start with your £8.5 mill ntav total too we aslo have the following liabilities
£0.95 of lease liabilities - i amy happy to ignore lease liabilities as thats future rent.
£3.0 million of warranty provisions - £2.0 mill of which is is ref business combination - they specifically say they expect the warranty provision will be fully released by 31/12/2028 - these are estimates ref possible costs if stuff went wrong.
Thats £4 million that i am happy to "gloss over" - ok they may have to fork out £2 million of more ref the warranty provisions if their supplied kit fails but the fact they have limited timeframe suggests this was more safety net situation rather than real expectation that they would have to pay out here.
add that £4 mill to the £8.5 mill ntav and you get back t the £12.5 mill cash pile.
For a business that needs to invest (acquisition) to grow its quite rare not to have any debt and not to have a deficit ref working capital - ref the other liabilities i would be happy if they had no matching cash as they will make £4 mill profit next 12 months that could pay down any nasties that turned up that even with no cash.
Note the cash wad might be good comfort blanket for their customers so it could be that their larger customers like to see a reasonably conserative balances sheet with cash on tap if for any reason problems might arise.
I am picky ref my balance sheets normally but i would be happy for them to spend cash wad as long as thats fine with them and customers. even if they might retain half imho thats stilla decebt wad available for acquisitions imho.
Sanderson Design (LON:SDG)
This is a company that I know reasonably well have bought and sold the shares successfully on more than one occasion. It fell as low as 29p during covid and topped out at around 225p post covid.
Anyway at 72p or thereabouts they look really good value from my perspective and I have bought some at a smidgeon under 73p for my daughter's ISA. I would buy some for my ISA but used the spare cash to top up Ramsdens Holdings (LON:RFX) at 219p.
Back to Sanderson Design (LON:SDG) . My investment case comprises:
The company' expectations for the full years are unchanged with trading having stabilised/improved, albeit still a long way to go.
AGM statement 7 August: "The Company's trading update on 27 June 2024 stated that, owing to a deterioration in trading conditions in the UK, brand product sales in May and June had impacted Group turnover in the current financial year. Since then, trading has showed some signs of improvement in July with brand product sales up 6% at constant currency compared with July last year. As a result, total brand product sales in the six-month period to 31 July 2024 were down 7% in constant currency, an improvement compared with being down 9% at the time of the June trading update and driven by North America. The Company continues to trade in line with the Board's expectations for the current financial year, as revised at the time of the June trading update."
Balance sheet (from AGM statement)
"The Group's balance sheet remains strong with net cash of approximately £9.6 million as at 31 July 2024 (H1 FY24: £15.9m), compared with £16.3 million on 31 January 2024. " This equates to about 18% of the market cap of around £52m.
Trading significantly below NAV. Sanderson Design (LON:SDG) owns valuable and irreplaceable archives of William Morris and Arthur Sanderson worth well in excess of the share price. Stockopedia shows NAV at 121p. At the current share price it is not difficult to conceive of an opportunistic bid.
Bottom of the cycle? Sanderson Design (LON:SDG) should be a beneficiary of an upturn in the housing market, albeit well behind building supply companies etc.
In conclusion, the shares are trading at their low since covid, although of course they could go lower with a forward PE of less than 8 and a dividend yield approaching 5%. The share price is at a significant discount to NAV and the company has cash on the balance sheet equating to 18% or thereabouts of its market cap.
Ramsdens Holdings (LON:RFX) another unloved small cap, trading at a PE of 8.5 or thereabouts with a dividend yield in excess of 5%. A beneficiary of the gold price that continues to rise approaching £2000 or $2600 per ounce. Again it has cash on the balance sheet and diverse revenue streams with precious metal trading more than offsetting the slight weakness in FX according to the company. Peter Kenyon, CEO owns more that 3% of the equity.
Just my thoughts.
Sanderson Design (LON:SDG) I have also bought back a small initial holding in the last week, Jonno. Agree with your thesis that it is now good value, with the share price below NTAV, cash on the balance sheet and a strong IP portfolio, paying a reasonable dividend.
Does anyone know if Warpaint are doing a webinar and if so when and how do you register? Thanks
Hi TC99 - Afraid Warpaint London (LON:W7L) have been there and done that this morning @ 9:30 https://finance.yahoo.com/news...
Thanks ezlifeme
I believe Warpaint London (LON:W7L) are going to be on Mello this coming Monday at 17.30pm. While there is a cost to watch these evenings there is usually a decent discount/ first time attending offer. Others may be able to help with this?
Hi Paul,
Have to disagree with you on the cash for Journeo (LON:JNEO)
If you look at receivables and inventory = £14m versus deferred revenue and trade payables the two are broadly equal. So current assets against liabilities does net to c. The cash position.
There is a developing SaaS story here too - recurring revenue on a licence model basis is a growing %age of revenue, so watch that space.
Hi david,
The question I'm asking over deferred revenue, is what is the nature of it, how has it arisen, and is it likely to be sustained? My understanding is that SaaS revenues are quite small at JNEO (albeit rising, as you say). Do you have any numbers on recurring revenue, that's what we need.
Deferred revenue is flagging that one or more customers have paid millions in cash up-front. DR cash, CR deferred revenues. My question is whether the deferred revenue creditor might unwind? Say if a customer gave them say £5m up-front for a big contract, and is drawing down product on a multi-year programme. In that case, as the product is built and despatched, then the deferred revenue line would shrink, as would the cash pile, if it wasn't being replenished with more cash up-front.
We don't seem to know what's in that deferred revenue line, so that would be a good thing to ask mgt on the next webinar.
I think one of the acquisitions came with a large cash pile that a customer had paid up-front, so that might be linked to it?
At this stage, it doesn't look like surplus cash anyway, hence why we'll have to agree to disagree on this point!
Regards, Paul.
Journeo (LON:JNEO)
Lots of questions being asked about deferred and recurring revenue etc. etc.
This is a reminder you can ask mangement about it - presentation is on IMC tomorrow at noon.
Hi Paul
definitely worth asking. As Journeo (LON:JNEO) are on IMC tomorrow if a few of us submit advance questions on the topic then it will give them time to give us a comprehensive answer.
The fact that we differ on this tells me it is sufficiently unclear that mgmt should clarify. perception is reality when it comes to share prices so just the fact we are debating it will be holding the shares back - ie some viewing it as undervalued (me) and others thinking they are good value but not as cheap (you).
Best,
David
JTC I thought I'd give this a mention because it appears on a lot of holdings for mid-cap investment trusts that invest in quality companies.
They announced their interims today, sending the shares down 9%. Revenues are up 21%, as are operating profits. It's all very curious.
It has been public since 2018, which is a little shy of what I'd hope for. Its share count has been increasing at 18% pa over 5 years. Say what? Their ROCE has averaged 5.2%, and their interest cover is 2.5. Stocko gives them a Quality score of 49.
As they say on Dragon's Den: "And for that reason I'm out."
It's interesting to see that it qualifies for Montier's "Unholy Trinity" Screen, caused by low Price to Sales, high asset growth and a poor Piotroski score.
Stocko describes the business as "JTC PLC is a provider of fund, corporate and private client services." It operates in the investment banking and services sector. It seems to be fairly acquisitive. Yesterday it notified that it bought Citi Trust for $80m. In August it proposed the acquisition of Buck UK and European plan admin and trustee businesses. It also announced the completion of the acquisition of First Republic Trust.
It's interesting to see that the PE of the company is 24. We perhaps have a situation here where investors are paying for EPS growth but with poor capital returns. Sounds like a recipe for disaster.
I'm coming to this siituation cold, you understand.
An as expected 9% fall in the IP (LON:IPO) NAV due to the share price fall in Oxford Nanopore Technologies (LON:ONT) in H1 24 but the shares continuing to be at a significant discount to NAV, with cash and their ONT holding making up 65% of the market cap currently. There are immediate catalysts to improve the NAV also - Visa is reportedly in talks to buy Featurespace at a 50% higher valuation than IP (LON:IPO) are valuing it and Istesso are due to report imminently results on its 2b arthritis trials, whilst valuations will clearly benefit from a fall in interest rates. I continue to hold.
Yes, but you do have to believe that Oxford Nanopore Technologies (LON:ONT) is good value. Trading at an EV/Sales of 7x and nowhere near profitability it is clearly still a 'blue sky' investment. May well come good but your large discount to NAV for IP (LON:IPO) might turn out to be illusionary if Oxford Nanopore Technologies (LON:ONT) doesn't deliver.
IP (LON:IPO)
On the IMC call this morning management said that they thought Oxford Nanopore Technologies (LON:ONT) was significantly undervalued.
I'm not sure I agree with that, but if they're correct, then there's even more upside here.
---
Working through the numbers myself just now, and as davidjhill mentioned, the current IP (LON:IPO) market cap (£470m) looks to be significantly covered by:
That leaves £190m worth of market cap being covered by c.£800m of NAV.
I wonder what we're missing for such a large mismatch?
Warpaint London (LON:W7L) Super update on pretty much every metric. Of those, the one that could keep the company really flying is its recent addition of Walmart in the USA to its customer list.
Warpaint London (LON:W7L)
EPS Forecasts are way too low.
H1 This Year 10.3p
H2 Last Year 11.78p
FY Forecast 22.08p
Stockopedia YE Forecast 22.8p
Shore YE Forecast 23.7p
This assumes no eps growth in H2 which is not going to be the case
or
Using This H1 EPS Growth of 66.13%
H1 This Year 10.3p
H1 This Year Growth 66.13%
H2 Last Year 11.78p
H2 LYr + H1 This Yr Growth 19.57p
FY Forecast 29.87p
Stockopedia 22.8p
Exceed Stocko Forecast by 7.07p
Shore Forecast 23.70
Exceed Shore Forecast by FY 6.17p
Yeah, I don't think the operating leverage in the business is being accurately
reflected in the forecasts, they're just going by revenue growth =
profit growth, whereas profit is actually growing way more quickly than
revenue. EPS grew by 67% in H1 but forecasts have it growing at 13% in H2 which seems like a big slowdown.
Those in-line results from Franchise Brands (LON:FRAN) seem to be excellent on many metrics. Couple of new notes on Research Tree. Stephen Hemsley formerly of Dominoes Pizza hoping to repeat past glories, and IMO appears to be delivering.
IMC presentation Tomorrow at 12.45.
Morning Paul & Graham
Such a long list of companies reporting but I note that Diaceutics (LON:DXRX) is missing so I thought I would make a comment. Additional comment appreciated.
Diaceutics (LON:DXRX) work in precision medicine helping pharma find the right patients for their drugs leading to significantly increased rev per therapy and help patients get the right drugs.
All H1 metrics and 2024 forecasts inline including Rev + 24% (28% CC). Nearing the end of a 2 year investment phase so loss-making. Plan was to invest £7m of own cash over 2023 & 2024 so cash looks ahead to me. Diaceutics (LON:DXRX) posted Net cash end June of £16.7m (no debt) - same as end December. CAGR of 27% over 3 years demonstrates significant momentum in the biz which management anticipate to continue or accelerate. As the investment phase ends this year, profitability and cash gen are forecast from 2025. Also of note is the usual 40/60 H1/H2 weighting so although H1 shows a loss, H2 will show a profit leading to a much reduced loss for FY. Going forward the plan is for costs to remain relatively constant but revs to grow approx 27%/ year leading to profitability and cash gen.
I am a firm holder of the stock. Now that the 2 year investment phase is coming to an end and revs growing well, the company has reached a planned inflexion point. Management do what they say and are well invested. As with any company there are risks. Here there are 2 potential main risks. Firstly, contracts don't materialise as hoped, however clients are 17 of the top 20 pharma globally and Diaceutics (LON:DXRX) are embedded in them. Reccuuring revs are expected to reach 70% during 2025.The other concern is competition. Diaceutics (LON:DXRX) say nobody else offers the full suite of products they offer. Additionally no other company is able to offer Daily Signal which allows clients to pinpoint patients suitable for their drugs within 24 hours. I think the nearest competitor's data is weekly which means Diaceutics (LON:DXRX) data is far more accurate and valuable to patients and pharma. The market opportunity is vast , hence the decision 2 years ago to invest for growth, when otherwise they would have been profitable and cash generative.
Begbies Traynor (LON:BEG) AGM update says current year has started well with ‘encouraging activity levels’ and group on track for market estimates. After a decade of consistent growth recent shares decline seems anomalous, we publish new note and retain fair value well above current levels.
As you can read here:
https://www.equitydevelopment....
hVIVO (LON:HVO) interesting - I see Octopus investments has moved above 10% . Looks like they are strong buyers. Good investment team at Octopus so gives me added confidence
I don’t understand what’s going on (or rather not going on) with hVivo’s SP. What more do they have to do to get that price up?
The results are superb and the visibility of their order book is exemplary.
Any ideas?
Hi Andrew,
A game of patience with hVIVO (LON:HVO) I’m afraid.
It’s in a period of consolidation - some indigestion from Cathal selling his stake to institutions has caused certain retail investors to bail, but it is clear that insti’s like Octopus are stake building.
Mo showed a bridge chart of how they get to £100m revenues and 25% margins by 2028 from current levels which was interesting. They have a clear plan and none of it seems to depend on blue sky products but some investors may wait until they see that dial moving up before taking the plunge.
25% of market cap is in net cash and 1Y fwd cash adjusted PER is 12* which is cheap for a good CRO with quality moat but is not so cheap that we should expect immediate fireworks.
But I suspect they can get to a 3p eps closer to 2027 than 2028. If I am right then I’d expect them to ultimately get taken out at 20* + net cash so maybe north of 70p
That’s close to a compound 30% return (a little less if it takes them to 2028). Frankly I’m happy to be patient.
Scratching my head on initial market reaction to Journeo (LON:JNEO)
By end of this year it will have 30% of its market cap in cash and should trade around 30p eps I reckon. That’s a cash adjusted PER of just over 6. That has got to be the wrong price surely? - this is a growing market segment, management have been proven canny with acquisitions and they are growing their SaaS business so smoothing out any order refill lumpiness.
Journeo (LON:JNEO) David I agree it is the wrong price, they are very cheap, there is plenty of runway ahead of them and management haven't put a foot wrong to date.
Maybe it's just the lack of liquidity once again in AIM/Small Caps, it's been dire for 3 years and still not showing signs of improvement, and if these mooted CGT or IHT changes occur then it's probably going to get worse especially as retail clients are the main suppliers of liquidity in these markets.
I find myself increasingly looking up the food chain to mid/large caps which is a shame because I do love this end of the market......
Can't annualise HY 15 EPS for Journeo (LON:JNEO) as very profitable Infotec contract has finished. Really the flat FY25 forecasts imply decent growth in the rest of the business just to replace the lost earnings from this New york subway contract
I agree the Infotech US subway contract is finishing but is actually only 1 quarters worth as it finished end Q3. Revenue will decrease in Infotech but not by that much - may have a £2-3m revenue impact I reckon - maybe £0.4m. I estimate about 3p of EPS. So I am assuming Journeo (LON:JNEO) don’t grow the rest of the business in H2 at all and finish the Infotech contract as planned and I come out at my low end of c. 27p eps.
So unless I am missing something else I expect a beat against analyst estimates of 23p
Journeo (LON:JNEO)
That has got to be the wrong price surely? -
Well it depends - if the growth trajectory in profits can be maintained then yes - personally i dont see massive visibility ref proving to the market they will have ongoing lfl organic growth (forecasts for nex year slap us in the face to say no growth) so i understand why the market isnt yet giving it a growth premium as one decent year with a decent contract that wont be repeated hasnt actually proved much to the market - particularly if profit growth is bought in via acquisitions . Behind the scenes i would say the company seems to be doing everything right and i have increased confidence as time goes on that hopefully management here are conservative and all the ball - if that remains the case and they can get some deals done and upgrade forecasts next year then i think the market will come around to the viewpoint that this is a company that can increase profits yoy medim term. Running a business like this at the forefront of technology and providing manufactured goods is always a tough business as tech moves on with time - they seem to have enough fingers in enough pies though that naturally one would hope they would grow their customer base - its not as if they are short of opportunities in their market niche. Hey ho if price had been up with events i probably wouldnt have bought in here - so measly rating for me is ok.
Harworth (LON:HWG) promotion to the FTSE 250 explains yesterdays share price rise.
Journeo (LON:JNEO) interims read very well. Cheap for what is in large part a software developer. Cash represents a significant percentage of market cap. Happy to remain invested.
I hold both.
My morning smallcap tweet: Share pain
Learning Technologies (LON:LTG) Headlam (LON:HEAD) Ra International (LON:RAI) Scancell Holdings (LON:SCLP) Zinc Media (LON:ZIN) B.P. Marsh & Partners (LON:BPM) Physiomics (LON:PYC) Mediazest (LON:MDZ) Warpaint London (LON:W7L) Fintel (LON:FNTL) Diaceutics (LON:DXRX), Begbies Traynor (LON:BEG), DP Poland (LON:DPP), Team17 (LON:TM17), Franchise Brands (LON:FRAN), Henry Boot (LON:BOOT), McBride (LON:MCB), EKF Diagnostics Holdings (LON:EKF), Journeo (LON:JNEO)
◄Learning Technologies (LTG)► H1-June. Guides FY towards the bottom of guidance (£473-493m) given current trading, in particular at GP Strategies. [SP=70 Cap=554m]. I hold.
◄Headlam (HEAD)► H1-June in line. Outlook - "Timing of market recovery remains uncertain and looks to be later than previously anticipated, with a return to growth now expected at some point during 2025". [SP=153.5 Cap=124m]
◄RA International (RAI)► wins $15-18m 3 year MoD contract for Facilities Management Operations across an East African country, which the Company has already been providing under a separate agreement. [SP=7.5 Cap=13m]
◄Scancell (SCLP)► partnership with PharmaJet for use of latter's Stratis IM Needle-free delivery System in the development of SCIB1/iSCIB1+ cancer vaccine for Advanced Melanoma. [SP=16.7 Cap=155m]
◄Zinc Media (ZIN)► wins two contracts worth £4m, keeps FY24 in line with market expectations of rev £41m and EBITDA £2.1m. [SP=65 Cap=15m]
◄B.P. Marsh (BPM)► H1-July trading - strong performance of underlying portfolio. Funds £80.2m. Plans £4m (10.72p/sh) div for FY25 and 26. Co "remains positive regarding its ongoing performance". [SP=524.88 Cap=195m]
◄Physiomics (PYC)► wins £65k contract to be completed this FY. [SP=0.69 Cap=1m]
◄MediaZest (MDZ)► wins over £500k orders with existing key customers. Delivery in FY24 & 25. [SP=0.08 Cap=1m]
◄Warpaint London (W7L)► H1-June rev up 25% as exp. EPS 10.37p up 67%. Outlook sounds in line. [SP=513.06 Cap=398m]
◄Fintel (FNTL)► H1-June. Guides FY rev in line, EBITDA marginally lower than expectations. [SP=313 Cap=326m]
◄Diaceutics (DXRX)► H1-June. Guides FY rev in line and confident of "ability to deliver upon a forecast shift to profitability and cash flow generation from 2025." FY24 loss miss then? [SP=129.4 Cap=110m]
In line: BEG, DPP, TM17, FRAN, BOOT, MCB, EKF, JNEO
Billington Holdings (LON:BILN) interim results look like a miss at first but as you read down the highlights they end with everyone’s favourite statement:
•
FY24 profits are now expected to be ahead of current market expectations
Combined with major projects restarting and prices stabilising, this looks like good news to me. Will be interesting to see the market reaction (I hold).
Journeo (LON:JNEO)
Fairly new holder here - interims out today look great , as per recent trading update everything 100% on track to meet current year expectations. Can’t find any negatives in the numbers today , revenue will probably drop ref large us contract but that’s just how it works with large jobs. They seem positive enough ref all areas of the business.
balance sheet rock solid plus something so plenty of spare cash for acquisitions and no nasties on the balance sheet - cash flow great and no excessive capitalisation of intangibles/plant.
At present the expectation is that next year the bottom line will be similar to this year - so only negative is that no growth is pencilled in ref profits next year - would be nice if they were confident enough to expect growth next year - hopefully these forecasts are conservative base level leaving some scope for upgrades.
The only issue I can see here is probably the lack of visibility they need to sign new contracts to keep growing hopefully as they grow repeat work and cross selling and ongoing services level will grow - it’s not clear to me though wether their progress may be lumpy if they have had a good spell - or whether numbers look good due to acquisitions. In that regard even tickover next year delivering decent numbers that repeat this year is probably ok.
Ideally decent acquisition that would add £1 mill plus profits with cross selling opportunities without material dilution would be nice - with companies like this I deffo prefer they concentrate on churning out profits - so no sketchy acquisitions please.
Thanks for the excellent summary.
Acquisitions are always a potential threat, but also present a superb opportunity. The JNEO track record is a good one. Additionally, they have Barnaby Kent as a NED now - Barnaby was a major figure in the Ideagen growth story and was the man in charge of integrating in excess of 20 acquisitions, all of them successful and made according to a rigorous template from DD to full on boarding. If ever there was an individual who can influence the quality and rationale behind an acquisition it is he.
Three of my companies have updated this morning so some quick comments in case helpful!
Billington Holdings (LON:BILN) broker upgrades full year EPS estimates over 9%. Cash c.£20m vs market cap of £66m. Notes steel price is lower so projects are restarting. Management very conservative here. Given we must be at/recently passed low point in market this looks cheap to me!
Journeo (LON:JNEO): this had recently had an upgrade so nothing particularly new in this that I see. However, the broker estimate for full year just looks like H1 EPS (+68% on last year) plus last year's H2 so assumes H2 is flat on last year. That doesn't feel right does it so I reckon this could get a further profit upgrade yet. Cash 25% of market cap pre-market opening.
Begbies Traynor (LON:BEG) : trading in-line. Maybe hints at potential acquisitions?
Agree Tortoise
broker forecast for Journeo (LON:JNEO) has stuck at 23p eps. That suggests they will only do 8p in H2 which doesn’t feel right given the order book and the 15p achieved in H1. I must remember to ask management but I reckon it will be closer to 30p (I pencil in somewhere between 27 & 30p) plus £16m of cash. So cash will equate to 95p of the share price which means at my low end a cash adj PER of just over 6*
I don’t know if people have noticed but their SaaS business is growing well too which usually commands a much larger rating. As they point out in the interims they now have a contract in Wales whereby every additional display added to the network (regardless of supplier) is then licensed onto the Journeo cloud platform generating ARR type revenues.
Just to follow-up on Springfield Properties (LON:SPR), a reminder that we are hosting an Investor Presentation tomorrow morning (18th September) at 9.00am with management - you can register here: https://www.equitydevelopment....
Springfield Properties (LON:SPR) - "Attractive growth outlook and 30% discount to peers" - new research report available here: https://www.equitydevelopment....
Springfield is emerging strongly from a challenging year for the housebuilding sector, with debt substantially reduced, private reservations and affordable order book improving and an increasingly confident medium-term outlook.
FY24 results are in line with expectations and ahead of the original targets for the year. The dividend has been reinstated (1.0p final) earlier than forecast, in a sign of confidence. Management’s principal objective at the beginning of the year was to reduce bank debt to <£60m and this was comfortably achieved (£39.9m reported).
The partnership with Barratt at Durieshill is a reminder of the long-term value in the landbank, which also underpins genuine excitement in the prospects for the North of Scotland, a region that will benefit from a sustained and significant increase in investment over the coming years.
Whilst the shares have performed well over the past year, given the confident tone of today’s outlook statement, the Group’s low valuation relative to peers and the exciting opportunity emerging in North Scotland (not yet reflected in forecasts), we reiterate our Fair Value / share estimate of 140p.
Very encouraging Finals report out from Springfield Properties (LON:SPR)
Meeting and exceeding plans for the year- ahead on reducing debt, signs of improvement in the housing market and re-instating a dividend ahead of initially planned. I can not see any negative comments, so looks like it could be a positive day for the share price.
Another record first half from Warpaint London (LON:W7L) . Hopefully the majority of the recent share price decline will be recovered.
Another record first half from Warpaint London (LON:W7L) . Hopefully the majority of the recent share price decline will be recovered.
I’d like to see that too but there’s some weakness in small caps right now that might mean we have to wait. Decent numbers though.
I agree that small caps have been weak recently. However, Warpaint London (LON:W7L) is still looking like a solid long-term hold. I hope that from November onwards both they and some of my other holdings will recover strongly.
Happy holder of Warpaint London (LON:W7L) , currently a three-bagger for me. I just wonder if the share price had got a little ahead of itself. Stocko forecast suggests eps of 22 for the year, and we've got 10.8, with a second half weighting - so is that "in line"? Might be in for a small beat at the end of the year perhaps?
Still no debt, cash in the bank, and plenty of opportunities. I'm not selling (and awaiting a far more professional look at the numbers from Paul!)
Dave
EDIT - just looked, last year they managed 6.2p in the first half, with a full year of 18 EPS. IF the second half this year is anything like that, we are on for a beat.