Small Cap Value Report (Tue 18 May 2021) - FOUR, WJG, SHOE, SDG, ACRL, ESC

Good morning, it's Paul & Jack here, with the SCVR for Tuesday.
Timing - update at 16:17 - all done for today, see you tomorrow.
Agenda -
Paul:
4imprint (LON:FOUR) - a quick look at this North American promotional goods company. It reports a steadily improving recovery in trading. Not an obvious bargain, but it's a good company, probably with some long-term upside on share price.
Watkin Jones (LON:WJG) (I hold) - Half year results to 31 March 2021 look resilient - profits only slightly down on LY H1. Strong balance sheet, pipeline growing, Strong recovery in institutional demand, there's lots to like here. The valuation looks reasonable. Plus we get a 3.5% dividend yield. A good solid long-term value/GARP share, in my opinion.
Shoe Zone (LON:SHOE) - Half year results - better than I expected, and strong growth in online sales is encouraging. Balance sheet is complicated, but I think overall it looks financially OK for now. At this stage I haven't got enough information to assess the company's prospects, so it has to be filed in the don't know/too complicated tray.
Sanderson Design (LON:SDG) (I hold) - a very strong H2 has delivered a good overall result for the year. I like the convincing turnaround & restructuring here, under new management. A bulletproof balance sheet means no dilution has occurred, and won't be needed. If earnings continue rising, then this share could still be good value in my view.
Jack
Accrol Group (LON:ACRL) - mixed update. Better margins, disappointing on sales, and a note of caution regarding rising input costs. Shares have been quite heavily diluted since listing.
Escape Hunt (LON:ESC) - this is an operator of escape rooms so results have been impacted by Covid. There are growth opportunities here, but the shareholder dilution has been massive which reduces the upside.
.
Paul’s section
4imprint (LON:FOUR)
2390p (up 4% at 08:32) - mkt cap £672m
4imprint Group plc, (the " Group "), the direct marketer of promotional products..
I thought we’d have a quick look at this, to see if there’s an economic recovery trade to be had.
Note that almost all revenue comes from North America, with a tiny amount in the UK/Ireland.
Summarising today’s update -
Jan-Apr 2021 saw “very encouraging progress”
Net cash $44m
Order intake (not necessarily the same as revenue) comparisons are 2021 vs 2019, due to 2020 figures being so heavily disrupted by lockdowns (makes sense to me), as follows:
Jan-Feb 2021: down 35% on 2019
March: not stated (strange! why not? Maybe the trend went backwards?!)
April 2021: down 20% on 2019
May 2021 (to date, 3 weeks): down 15% on 2019 - are "order counts" the same as "order intake" for previous periods above? Why the change in terminology?
No overall total provided. Hence this list of figures above looks to me like it's been cherry-picked to show the best bits! (i.e. the truth, but not the whole truth, maybe?). A simple table, showing every month, with the 2019 comparison, and the total, would have been better. I think investors prefer complete transparency, rather than having to work out where the wool is possibly being pulled over our eyes.
The company is "very pleased", expecting further progress in 2021
My opinion - this looks good - an improving trend, as the USA/Canada economies come back to life, with what looks like a V-shaped recovery.
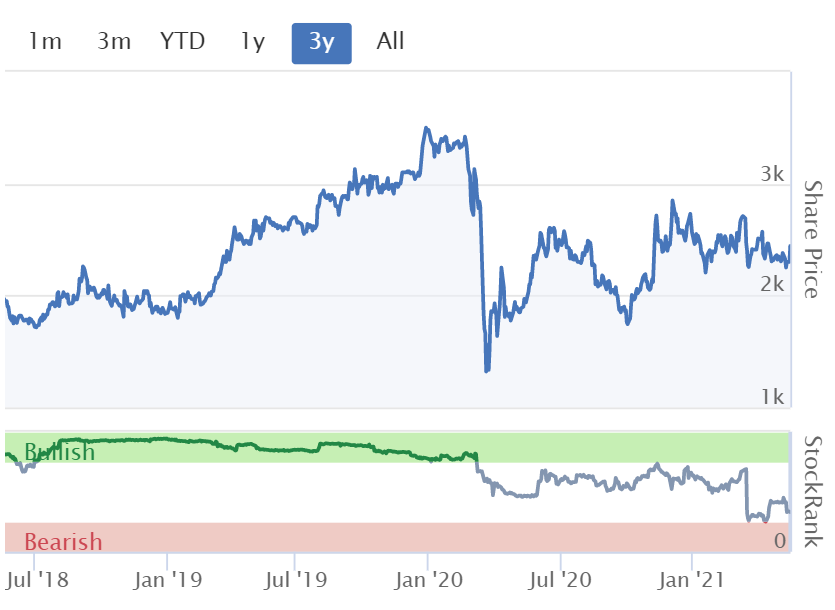
There doesn’t seem to have been any new equity raised during the pandemic, as the share count looks static at 28.1m. Therefore we can draw lines on the chart with impunity!
Peak earnings were c.152p, so I think it makes sense to value the business on the basis that it might take maybe a year or so to get back to that level (I’m optimistic on the macro outlook, due to massive QE & stimulus spending). Put that on a PER of 20, which seems reasonable, and we get to c.3000p per share price target.
Therefore there’s maybe 25% upside on the current share price of 2390p, assuming all goes well. Also, in future, earnings could exceed the previous peak, as FOUR has a long history of decent performance, it's a good business.
Overall, I quite like it - reasonably good long-term upside probably.
.
.
Watkin Jones (LON:WJG)
(I hold)
240p (down 1%, at 10:48) - mkt cap £629m
It’s getting a bit big for us now, but I’m going to continue covering this company here, because I think it’s a good long term investment, and accordingly hold them myself - hence am going to do the research on it anyway, so might as well share my work with you here.
Watkin Jones plc (AIM:WJG), the UK's leading developer and manager of residential for rent, with a focus on the build to rent ('BtR') and purpose built student accommodation ('PBSA') sectors, announces its results for the six months ended 31 March 2021 ('H1-2021' or the 'period').
The numbers look resilient to me - as near as makes no difference to flat for H1 this year, vs H1 last year. Clearly the pandemic is now having little, if any, impact on the construction sector.
.

.
The commentary from WJG’s CEO sums up the main points well (my bolding, as usual) -
Commenting on the interim results, Richard Simpson, Chief Executive Officer of Watkin Jones, said: "As we begin to emerge from the pandemic, we are seeing increasing investor confidence in our market sectors. We've maintained the momentum from the second half of last year and made further good progress in securing new forward sales, adding to our development pipeline and keeping all our construction activities on track.
"All parts of the business have continued to perform well, and whilst our profit for the first half of the year was slightly below last year, this was because the first half last year was largely before the onset of the disruption caused by the pandemic.
"The fundamentals supporting the markets for high quality build to rent and student accommodation assets remain strong, driving growing institutional demand, and combined with the continued progress we have made in the first half of the year, gives us confidence in our future trading."
I won’t repeat the detailed stuff I’ve written before about the company’s business model, other than to say I really like its niche - well-managed large projects, which are forward-sold to institutions that want the rental income, in return for a lucrative developer's margin for WJG.
For me, the investment case is strong, because it’s a reasonably priced, highly profitable, established company, with good barriers to entry (institutions are not interested in working with smaller builders for these buy to rent projects).
Other points which I thought worth mentioning -
All 15 construction projects on track - WJG seems to be particularly good at managing construction projects
Buy To Rent (BtR) is a big growth area for WJG, adding to the student accommodation division. BtR is now 33% of revenue, with a large pipeline - which is set to increase profitability considerably in future - this is the main reason I hold this share (intended for the long-term, like most of my personal holdings)
First co-living scheme in Exeter - this is an interesting growth area, that I think could become popular & lucrative in time. It’s where people live in a studio, but share communal facilities, making for a much more social way of life. This has considerable appeal in my view, because loneliness is a big issue for singletons living in cities.
Government plans to increase taxes on construction companies, to recoup cost of cladding repairs - could be a profit headwind generally for the sector, including WJG - more info needed
Very good balance sheet
Profits are paid out as divis, so we also get a reasonable yield of about 3.5%, which should increase over time as the business grows from its existing pipeline - i.e. there is no need for additional capital, hence it can safely pay out earnings as divis.
Progressive has issued a commissioned research note today, which is helpful. This shows estimates as follows -

.
I hope they don’t mind me including this table. If they complain, I’ll remove it.
Personally, I think the valuation of 15.4x PER looks perfectly reasonable, and I see this as a base level. The pipeline information given in a presentation at the last results, suggests a big increase in revenue & profit as the BtR pipeline converts into building work & sales in the coming years.
Results presentation slides - click on “Presentation” here. It’s a similar format to previous presentations, and there’s a lot of detailed information there, so well worth a look - much easier than ploughing through a long RNS.
There should be an audio presentation up there later, from noon today.
My only query is on slide 18, where there seems to be a gap in the pipeline for FY 09/2022. If I get a chance to speak to management, I’ll ask about how this might affect next year’s results? -

.
The forecasts from Progressive show an increase in revenues & profits for FY 09/2022, so my point about an apparent gap in the pipeline might be a red herring. I’ll try to find out & report back anyway.
My opinion - this looks an excellent business, operating well, in a lucrative niche.
The valuation (on a PER basis) seems reasonable, and the longer term growth prospects look very good.
We’re paid a healthy dividend yield along the way, and the balance sheet is strong.
Put that lot all together, and I think this is a decent GARP (growth at reasonable price) share, also providing income along the way.
The current share price looks about right to me, so it’s more a share for patient, longer-term investors with a value/GARP leaning.
The business model should be a lot less cyclical, and lower risk, than most other construction companies, because the key point is WJG forward-sells projects to institutions, before even breaking the ground on them. That’s the key point of difference that I like the most. Compare that with the awful, low margin, high risk builders competing for major infrastructure projects, and half of them end up going bust when something major goes wrong. Why go near anything like that, when WJG presents a much more reliable, high margin, low risk way of getting exposure to a growth niche in construction?
WJG shares have had a great run recently, like practically everything else in cyclical sectors. Is the valuation now stretched? No, I don't think so. The current price looks reasonable to me.
Note also the very high StockRank below, so the Stockopedia computers agree with my positive view of this business, which I always find reassuring.
.

.
Shoe Zone (LON:SHOE)
68.5p (down 8%, at 12:08) - mkt cap £34m
Shoe Zone PLC ("Shoe Zone", the "Company") is pleased to announce its interim results for the six months to 3 April 2021. (the "Period")
Usual thing for a retailer - it will have been heavily impacted by lockdowns in Q2 (Jan-Mar), but would have been able to trade partially in Q1.
All I’m really interested in are -
- Balance sheet - insolvency and/or dilution risk?
- Online sales - how successful have they been at migrating customers online?
- What is current trading & outlook like, since re-opening?
An an initial glance, I’m quite encouraged by the highlights below - digital growth is strong, and it’s great that they’ve split out the actual numbers, not just % increases.
Also a net cash position is pretty good, after such a difficult year since the first lockdown in March 2020.

.
Balance sheet - is quite complicated for a micro cap. NAV is still positive, at £11.0m.
IFRS 16 has done a lot of damage - the Right of Use Asset is £36.5m, whilst lease liabilities are £55.7m, giving a net deficit of £(19.2)m. If we cancel all those entries, then NAV would rise to a very respectable £30.2m.
Inventories look far too high, at £28.4m, so I think they’re over-stocked.
Pension deficit is £7.9m, and is a nuisance & a cash outflow.
Bank loan is a CLBILS (Govt backed) £15m, which should provide breathing space.
Now that the stores have re-opened, then this looks to me like a balance sheet that could recover over time.
I don’t see any pressing need to raise fresh equity, and owner-managed businesses like this tend to hate dilution, so a placing is unlikely in my opinion.
Current trading - I did a CTRL+F for outlook, but nothing came up. This is all I could see on current trading since re-opening -
No stores were open in the first 2 weeks of the 2nd half. Trading started strongly but has settled down to a more mixed picture of good High Street and retail park sales but weaker shopping centre performance.
I’m mindful of Next recently saying that it expected the pent-up demand to be fairly short-lived.
My opinion - it’s certainly not a basket case. I think the company has a good chance to recover, but to what level? I can’t see retail footfall returning (ever?) to pre-pandemic levels. It’s so much easier to shop online. That could leave SHOE a significantly less profitable business than in the past. It used to make c£10m p.a. profit, could that happen again? I just don’t know.
SHOE has managed to shift a decent amount of sales online, maybe that could compensate for some of the lost physical sales?
Management seem to have been rattled by covid, and seeing a previously cash generative business come close to failure. Hence, as they’ve already said previously, they’re not likely to pay divis for a long time, as debt reduction will be key. I’m not sure what level of debt (if any) would pertain once creditors have been paid up to date.
Overall, I feel there are so many moving parts here, that it’s almost impossible to assess the company’s prospects, and hence how to value it.
How much have rents come down? What happens when business rates kick in again? Labour shortages appear to be occurring now too, so wages are likely to go up. Logistics problems are also mentioned, since the product is imported from China.
It’s too complicated overall, and too uncertain, so I’ll declare myself neutral.
There's been no share dilution, so theoretically, if trading returns to pre-covid levels, then the share price could return to previous levels.

.
Sanderson Design (LON:SDG)
(I hold)
162.5p (up 1%, at 15:39) - mkt cap £115m
The initial market reaction to results this morning was negative, with the share price down. However, it’s gradually recovered, and turned positive now, on high volume (642k shares printed so far, at 15:40). It’s taken me a while to plough through the figures, so apologies for the delay. I think the sellers this morning have probably made a mistake, this looks like a business that’s recovering nicely from the battering it took in H1, from lockdown 1.
Here are my notes -
A dramatic improvement in performance in H2:
H1 (Feb-July 2020): Revenues £38.8m, adj u/l PBT £0.4m, Adj u/l EPS 0.54p
H2 (Aug 2020- Jan 2021): Revenues £55.0m, adj u/l PBT £6.7m, Adj EPS 7.46p
Full year 01/2021: Revenues £93.8m, adj u/l PBT £7.1m, Adj EPS 8.0p
Furlough - £3.1m received, of which £0.4m returned (related to redundancies), so a significant element of the full year profit.
Cost savings implemented in August 2020, annualised savings of £3m for future years, partly helped profit in FY 01/2021. So should drive a further increase in profit in FY 01/2022
No divis - makes sense, when taxpayer assistance has been received. Likely to resume in the new financial year FY 01/2022
Licensing revenues fell from £5.5m last year, to £3.7m in FY 01/2021 - still not bad. This is high quality, high margin income. It shows the value of the extensive back catalogue of designs. There is further scope for growth with licensing, and deal with Next (LON:NXT) starting up, plus important Japanese licensees.
Gross profit margin is impressively high, at 60.8% - very good indeed
Current trading - sales in Feb,Mar, Apr 2021 are slightly ahead of mgt expectations
Outlook - cautiously optimistic
Balance sheet - a joy to behold! £67.5m NAV, less intangibles of £28.3m = NTAV £39.2m - this is very healthy indeed. Zero risk of dilution in my opinion. Didn’t need to raise any fresh equity during the covid crisis.
Pension deficit - the only fly in the ointment. Deficit on balance sheet is only £5.6m, but seems to have sucked out £2.1m contributions in the year - so a nasty drain on cashflow. Deficit expected to be gone by Oct 2026. Next triennial deficit as at 5 April 2021, so should be OK, since equities healthy around that date.
Net cash of £15.1m, and total headroom of £30.5m (including unused bank facilities), so this is a very soundly financed business, no worries here at all.
Cashflow generation - excellent.
My opinion - I hadn’t realised just how good the turnaround/recovery at Sanderson has been, until looking at these numbers. That’s possibly partly because I can’t get hold of any broker research. So I feel private investors have been kept in the dark somewhat. I’m due to speak to management later this week, so will mention that point.
Looking forwards, I think the business has been restructured, modernised, and that the lockdowns have probably accelerated that process, leaving a leaner & more efficient business. The commentary from management alongside today’s figures is comprehensive, and it’s clear that a lot has been done to improve processes. I particularly like the big reduction in SKUs (stock keeping units), so that inventories can be lower, and new product lines have more impact - i.e. launch fewer new lines, but get them right.
I’ve mentioned this before, and I still think that SDG is a treasure trove of brands, and designs, many of considerable historical or even timeless significance, like William Morris. Therefore, even though the share price has gone up a lot, it doesn’t look expensive to me.
EPS this year could recover to maybe 12p (from 8p in the covid year), which is only a PER of 13.5.
Hence why I think if the turnaround continues, there could be considerable further upside with this share, as a long-term holding personally I’m going to sit tight for the foreseeable future.
The StockRank is high at 87.
My only regret, is that I didn’t buy more when I bought a little scrap of them at 42p! Although funnily the enough, the advantage of having a small position is that you forget about it, and suddenly find you’ve got a decent profit. There’s no temptation to bank profits prematurely, if you’ve forgotten you held the shares. Maybe we should do that more often?!
.

.
Jack’s section
Accrol (LON:ACRL)
Share price: 58p (-6.45%)
Shares in issue: 311,354,632
Market cap: £180.6m
Accrol Group (LON:ACRL) is a producer of private label toilet roll, kitchen roll, and tissue products for major UK retailers. It was in the private ownership of the Hussain family until 2014, following which private equity investment was introduced in the lead up to its London AIM listing in 2016.
But the group is now in turnaround mode after a fairly brutal sell off following a profit warning early on in listed life.

The company was established in 1993 by the Hussain family in the Lancashire mill town of Accrington and it promptly achieved sales of over £1m in its first full year of trading. Since then it has built new factory and warehouse with state of the art production lines.
It continues to invest in its manufacturing, and by 2014, the group had grown to over £100m of annual revenue.
Shares are still well below the previous highs but there has also been a lot of dilution, from about 93m shares in issue at IPO back in 2016 to some 311m today.
Trading update
Substantial progress has been made on gross margins in the Period, which are ahead of market expectations.
- Total revenue +1.5% to £136.8m,
- Like-for-like volumes -3.9% (against a total market decline of 5.5%),
- Net debt (pre-IFRS 16) of £14.6m compared with £19.1m in October 2020 (despite the £3.9m net cash acquisition of John Dale in April 2021 and inventory growth)
Adjusted earnings are expected to be in line with expectations, despite a lower than anticipated increase in sales in the year. The great toilet roll shortage of 2020 has had an impact, with COVID-19 panic-buying of branded products. Since then, customers have been working their way through their respective stockpiles and demand has therefore been subdued in recent months.
Accrol claims to have grown market share, though, up from 13% in FY20 to 16% in FY21, with particular progress being made in discounters.
The integration of Leicester Tissue Company (LTC), acquired in November 2020 for an initial consideration of £35.0m is now expected to generate annualised cost synergies of £3.0m. This is 3x higher than anticipated at the start of the acquisition.
Revenue synergy growth has been slower, however, ‘reflecting the market conditions in the period since acquisition’.
The more recent acquisition of John Dale brings ‘a highly scalable flushable and bio-degradable wet wipes business’ into the fold.
Accrol hopes to use Dale’s well invested and more specialised site to build a fully flushable wet wipe business ‘capable of taking an appropriate market share of this £0.5bn sector’.
There is further investment in manufacturing capacity. Accrol is adding capacity at its Leyland converting plant from Q3 of FY22 and is making progress on its paper mill development plans.
Input costs are increasing significantly in the near term given the rise in global pulp prices and other commodities. The group has increased its raw material stock levels in response and says it is making good progress in recovering higher costs - but this is still worth monitoring in case it does develop into a more sustained and troublesome trend.
Conclusion
There are some solid institutional investors in Accroll that have increased their stakes and, presumably, have some faith in the turnaround opportunity here. Directors have been selling though.
The acquisitions and investment show that tangible actions are being taken, but the near term outlook is marred by rising input costs.
This a mixed update. Better margins but disappointing on sales and rising costs. The trend that has held back sales should shortly unwind though, and acquisitions and investments could pave the way for more sustainable growth. Accroll is also returning to dividend payments, with a final FY21 dividend of no less than 0.5p per share.
Given the mix of news though, there is a risk that Accroll could disappoint the market in the shorter term. Longer term, there is a decent chance management can continue to optimise operations and take market share, but the dilution for shareholders so far has been severe, which puts me off.
Escape Hunt (LON:ESC)
Share price: 38.89p (-5.14%)
Shares in issue: 88,620,091
Market cap: £34.5m
We talk about the reopening trade running a little too far. I suspect Escape Hunt (LON:ESC) might be a case in point.
It’s one year relative strength is +389% and the market cap is £34m but the group has had a fairly dire start to listed life, with inexperienced management, slow operational progress, and a calamitous decline in share price.
And as the share price tumbled, the group issued more and more shares, which greatly reduced future value for existing shareholders. In fact, just looking at the numbers now, shares in issue have gone up from 9m to 88.6m in just five years, which is very alarming.
Things have been turning around recently, but don’t be fooled by the share price chart below - due to the massive shareholder dilution, Escape Hunt’s market cap is comfortably bigger today than it was at IPO.
The whole endeavour looks to have been woefully mismanaged from a shareholder perspective.

With hindsight, it’s easy to say that the IPO price was just far too expensive given where Escape Hunt was at in its development.
Looking to the future the group might be in better shape now, but I do not have a favourable view of events so far.
Highlights:
- Group revenue -46% to £2.7m (impacted by Covid),
- Revenue from digital and other play at home products grew from nothing to £230k,
- Group operating loss of £6.4m (2019: loss of £5.9m),
- £4.0m net of expenses raised through an equity placing and open offer, share subscription, and a convertible loan note in July 2020.
Owner operated sites have grown from 9 to 14 in the period and Escape Hunt continues to be very well reviewed on TripAdvisor. Escape Hunt’s owned and operated estate currently stands at 17 sites. Two more sites are upcoming, in Lakeside and Milton Keynes. So it looks like momentum is picking up with the roll out.
Covid closures of all UK sites resulted in 45% of available days lost and restrictions impacted a further 36% of available trading days.
The group has acquired its Middle East franchise. This could be a low risk route to international expansion. The French and Belgian master franchise was also snapped up post period end.
This was funded with another placing to raise £1.3m after expenses in January 2021.
But, after all the shares issued and cash raised, it does look like the company has some promising growth avenues lined up. It highlights five key areas:
- Roll out of owner operated sites - the estate has grown by 89% over the past year and Escape Hunt hopes to be at 20 owner-operated sites by end of 2021.
- US Franchise network progress - this could be a material development and the Houston site is now the 'master site' and education centre for North America. A pipeline of both new and potential conversion franchisees is now in active development.
- International Franchise network progress - EH has acquired its Middle East and France & Belgium franchisees.
- New products and markets - The group has done well to innovate some at home products over lockdown. Remote-play products generated £230k revenue in 2020. There is also the corporate market and development of its 'Escape Hunt for Business' concept.
- Investment in Infrastructure - Completion and implementation of software which allows games masters to manage multiple games at the same time at new sites.
Conclusion
Of course, Covid has not helped and the group has been agile in bringing out remote-play products, but the troubles began long before that.
It’s entirely possible that Escape Hunt has learned from past mistakes and is approaching an inflection point in its roll out. But, with 17 owner-operated sites and a c£35m market cap, Escape Hunt is no longer a deep value bargain.
It might finally be at the point where it can execute a meaningful roll out that will see it through to profitability, but I wouldn’t rule out another placing (particularly given the track record).
The company has cash of £2.7m, has generated a net loss of £6.6m, a net cash from operations outflow of £1.3m, and has spent £2m in investing activities.
The fact that Escape Hunt has managed to destroy so much shareholder value in such a short space of time is concerning. There is a growth opportunity for the company, but the massive dilution so far reduces the upside and puts me off as a potential shareholder.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
Hi Paul, I notice you are due to talk with Sanderson Design (LON:SDG) management this week. Whilst discussing broker research could you also mention about allowing private investors onto the results call please?
I contacted their PR company, Buchanon Communications, but they declined access on the basis that I was not an 'analyst'. I have emailed the company to highlight the issue but hopefully you might mention it.
Many thanks
Chris
Thanks for the reviews Paul and Jack.
Today's report has a lot of interest for me. 4imprint (LON:FOUR) is a long term holding for me, first bought in 2010. I remember at the time when I bought it that it seemed to have a big pension deficit weighing over the share price however they put in a good strategy to deal with that and the share price and company have moved onto better things. This is probably one of my "coffee can" shares. Going into 2020 they were ahead of track for a targeted $1 billion of annual turnover in the not too distance future but covid put a stop to that initial target. Historically management have been very good and exceeded their published targets time and again. Pre-pandemic this was around a 14 bagger for me, however now down a bit but recovering; with today's price action it is close to being a ten bagger again. This is further support for my comment a few days ago on the benefits of long term holding of shares rather than being subject to price action with set stop losses, which often closed me out of good stocks.
Also of interest today is Shoe Zone (LON:SHOE) and Accrol Group (LON:ACRL) which I used to hold, thankfully out now with a conscious decision made to exit these over the last few years. I can testify to SHOE's online offering since I've used it twice this year (slippers and trainers). Pricing is very appealing and the footwear always arrived before the estimated delivery date.
As for Accrol, on reading the commentary I wonder if history could repeat itself and the new management get caught out by raw material prices which they can't control. Once bitten, twice shy so I won't be venturing near this stock again.
Shield Therapeutics (LON:STX) Shield Therapeutics
Recently someone mentioned that STX is now dual listed on OTCQX in the US, FT published an article which mentions OTC which maybe of interest:
https://amp.ft.com/content/0ac...
I believe Watkin Jones (LON:WJG) are in a very good position re quality and letting issues as they tend to do the housing management for their schemes, and so have to live with the consequences of the development. The development arm of the business should get clear feedback and pressure on any quality and design issues, ensuring future quality outcomes. Additionally they have until recently only specialised in student housing. They are now building related skills and expertise in the build to rent market.
I agree Martin. I hold Watkin Jones (LON:WJG) and have topped up today. I would not expect much scope for innovation in this sector but as Paul has already pointed out the co-living initiative is ideal for singletons living alone as well as those fed up with sharing. It is a perfect combination of WJ's experience in building and managing student accommodation and their rapidly growing BuildToRent developments, simply focused on a different occupant category. BTW if anyone doubts the trend towards BuildToRent just read this https://www.bbc.co.uk/news/uk-... I also wonder if WJ might be a take over target like Mccarthy & Stone (LON:MCS) yet to be completed of course.
Watkin Jones (LON:WJG) would surely make an obvious takeover candidate from someone like Legal & General - they have a big capital division and already own a housebuilder, along with a load of other property and infrastructure type investments. Life insurers require long dated, inflation linked cashflows to meet their liabilities and student accommodation/BTR would very much fall into that category.
Any pointers as to the sharp drop in Tracsis (LON:TRCS) over the last few days?
The honest answer is no idea as no news.
I suspect like a lot of things it is sales by those who bought when it rocketed up, selling now that it is reversing the journey. So a few people people like me booking the gain as it is >10% down from peak (it had been a longer term holding but I am still on the rebuilding capital from last year project), and others cutting the loss having bought at or near the peak.
Tommy
I no longer hold Tracsis (LON:TRCS) but will buy again lower
Also it could be a response to concerns over the Indian variant. e.g. Revolution Bars (LON:RBG) has gone down from it's recent high of 40p+ . Informa and Hyve (LON:HYVE) are showing similar falls. Could also be buy the rumour, sell on news theme with lockdown ending.
Tracsis (LON:TRCS) (I hold)
The latest mainly negative share price movement could be due to:
Details here:
https://www.theguardian.com/bu...
Possibly a combination of all 3. Have some paper ready just in case.
A
Anecdotal I know, but I went to my Club yesterday and a pub and cafe in inner west London today. All had very few customers. Perhaps the 'pent up demand' for hospitality is lower than has been anticipated.
Gostevie
Your member of a Club W O W. There's posh
In addition to the already mentioned Woodbois (LON:WBI) and the I-shares ETF £WOOD , maybe worth looking at Mondi (LON:MNDI) and Smurfit Kappa (LON:SKG) - two large cap Super Stocks which both have vertically integrated wood pulp supply chains into their paper and packaging businesses. All held.
A list of the WOOD ETF holdings might give you some ideas although many are North American listed.
https://www.ishares.com/uk/ind...
Gus.
Paul I don't know if you have time but I am interested in Simec Atlantis. They have put a rns out saying they are not a part of GFG Alliance (the collapsing business) although it does own 43% of the issued share cap. My interest is the outcome of this. Presumably someone could pick up 43% quite cheaply but they would be in bid mode straight away. Equally it could be left with an overhang of shares. Are there any other obvious possibilities. I like the idea of the company a stable renewable electricity provider (wave) they also have a patented brick made from paper//cardboard and plastic which can be used in old coal powered stations to produce energy. So good idea all be it a bit expensive and looks to me likely will need to raise money. Just interested in thoughts really if you don't mind.
A lot of uncertainty surrounding their Uskmouth project - that + GFG factor has led to their SP fall.
Hi Camtab
Re: SIMEC Atlantis Energy (LON:SAE)
Sorry to be a bit pedantic but they are not in wave power in any traditional sense (i.e, pretty much anywhere there are waves of appropriate size). Rather they are in tidal currents. I.e. a few specific areas where there is a highly predictable, reliable flow of sub surface water. The first, wave power, has not been exploited at scale successfully as far as I am aware to date. The second, tidal currents is up and running successfully but challenged by cost/subsidy issues.
As regards GFG, they are effectively part of that group due to the large holding. What they are saying I believe is that they don’t think they will be affected by the wider problems at GFG. But, if GFG need to mount a fire sale then that could devastate the share price here.
I voiced my concern that there could be negative consequences here sometime ago.
After the problems with Enron I am rather wary of organisations with opaque structures such as GFG, so I sold out when they took their stake.
Hi Paul
Couple points re Watkin Jones (LON:WJG) FY22 forecast if of interest:
- Pipeline for BTR looks low as 184 units have moved forward to FY21 (although agreed still relatively low vs. other years)
- Revenue is recognised throughout the construction process based on key milestones and not all on practical completion (hence revenue growth still forecasted due to the significant future pipeline).
Thanks,
Claudia
Does anyone know of any completed Watkin Jones (LON:WJG) build to rent schemes and how well they have been taken up by renters? I appreciate WJG are just the developers but future demand will depend on how things work out for their financial institution clients. I occasionally drive past their 315 apartment development by Reading Station and wonder where all the tenants are going to come from, especially given the hundreds of other apartments being developed nearby. In my mind this build to rent move is still a bit speculative driven by the WJG clients having few other options in a zero interest rate world. But it could be a long term shift.
If/when Crossrail eventually opens I guess things will look up for the Reading Station site.
Hi John
As someone who grew up in Reading and then was priced out of buying a house there in his early 30s I have friends still renting there (and can't afford to buy) who talk about the lack of apartments in the town. I think there are still plenty of prospective tenants who want to live in the town and see the links to London as key component of living in the town centre.
Accrol Group (LON:ACRL) - The number of shares in issue as highlighted by Jack is 311 million. The average shares figure on the Accrol page in Stockopedia is 196 million. What explains the difference between these two numbers?
I've always used the Stockopedia average share numbers to weigh up potential dilution over time and will be very grateful for anyone's explanation/ insight to broaden my knowledge.
Tein, the current figure is further down, in the Profile Summary:
311,354,632
The average figure of 196m is for the previous FY. I asked this question myself recently, and Ed Croft set me straight (via the feedback button).
Tein, you need to scroll further down the Stockreport to find the latest number...
The 196m showing further up doesnt include the 116m share issue mentioned here.
Accrol Group (LON:ACRL) Accrol Group. I asked about this for another stock. I'd been doing it wrongly too! For the current figure you need to look at the "shares in Issue" figure further down the page.
Well even at my age I'm still learning something every day! The difference between the current shares in issue and the last year average is the change in the current period then. How simple! Thanks to everyone who replied and helped, I'm better armed for your insight.
Accrol - Jack I think your conclusion here is spot on, short term there is risk here. I worked in the paper industry for over 20 years before becoming a full time investor and so feel I have more insight here than the average investor. I was a holder here but sold on the high a few months ago, as did some of the Directors just after a Mello event where they pitched. At the presentation I raised concerns about future paper prices as pressure was building on timber and hence paper which would then drive up recycled paper where most of this product comes from. They stated they can buy forward and were confident of controlling costs and any future increases in raw materials. This is difficult as this product is so bulky you cannot store significantly more and the paper mills impose price increases on deliveries after a certain date to stop forward ordering and getting around the increase. During Mello they had no plans for a paper mill as they were happy buying on the open market, particular from Turkey. They now have plans for a paper mill which suggests an about turn and possible issues with price increases. Historically when paper starts to rise you often see a period of 2 years of increases where there are 5-8 increases followed by several years of eroding prices. At the other end the discounters will not accept price increases easily and will play hard ball eventually accepting in order to maintain supply but this often goes right to the wire, There is therefore often a lag between having prices imposed on you and being able to pass them on. The cost savings Accrol talk of will help as will any further acquisitions and integration but my feeling is a paper mill is key to real long term success here. 16% market share is not enough to move the dial here in this industry so further acquisitions / growth would be needed. If I was a buyer I would be looking at a window of 2 - 4 years for this stock to improve significantly so medium term positive.
Incidentally on a related topic I was recently talking to a timber importer who told me supply was so tight from Europe that they placed 6 month forward orders without knowing the price until it lands at the docks partly due to Chinese demand. I am buying timber growers ;-)
Hi Portcall909,
Thanks for your industry knowledge re Accrol Group (LON:ACRL)
I've never liked the business model at ACRL. I've followed it here since it floated - it was an opportunistic float, when the company had been making super-normal profits on the back of cheap paper rolls. That all unravelled spectacularly, with a bad profit warning, once rolls of paper shot up in price. The company nearly went bust, and needed a massive restructuring.
I think the turnaround since has been good, but the valuation looks to have got well ahead of itself. The bottom line, is that this is a capital-intensive business, operating on low margins to ruthlessly price-eroding customers (as you say, the discount supermarkets), with errative input prices for the raw material. That's probably the worst combination of factors imaginable!
How can we value any share with such erratic profitability as this? Obviously the bull story is that profitability is now on an even keel & growing strongly. But will that be maintained, when customers are constantly squeezing for the lowest possible price, and commodity prices generally seem to be going through the roof at the moment, as world economies recover?
Too complicated, and too uncertain for me.
Thank you for the comments from all the respondents which have been very helpful . My thoughts on Accrol Group (LON:ACRL) are these. I don’t know where the revenue forecast came from for the full year, but going back to the H1 figures and doing a simple 2 x calculation, I didn’t get to the ones on Stocko. Clearly if you take the Stocko ones, then the results are likely to show a significant miss.
The other significant issue is the inflation in raw material pricing. This was the same sort of quote made by Mcbride (LON:MCB) on May 5th with the same SP effect (Fortunately the SP has recovered somewhat since then).
I have some confidence in the management team and their strategy. They are largely from DS Smith, a top quality company in paper and packaging, recruited by the CEO also from DS Smith who certainly had a big shock when he took over a few years ago in a situation where the pressures had some similarity but were much more serious. Since then, the team have turned the business round, and they have the efficiencies which they claim are better than the branded competition because they have invested, whereas the brands have not. Their two recent acquisitions make very good sense – the first from a built-in output growth and also logistics viewpoint, the second from a market sector and uptrading standpoint.
The world recovery is bound to put short term inflationary pressures on instant demand versus slower supply response. Whether these short term effects turn out to be more permanent is a concern.
As for being beholden to the supermarket wolves, the latter have to get their product from somewhere, and are not immune from inflationary pricing effects. If Accrol Group (LON:ACRL) are more efficient than their competition, are able to build market share, are able to uptrade with a wider set of products, then they should have the scope to win in their sector. We shall see. Certainly the immediate response in the market on the SP seems to have been extreme……..or am I being too simplistic in all the above?
Apart from £wbi are there other wood companies quoted in London?
Woodboisw
I hold £WOOD etf. Also keen to hear of individual opportunities,
Not a wood company but I hold Axs treatment of timber, fantastic product, Axs can not keep up with demand and have had issues with the new treatment pant continued delays on the construction and opening, but worth checking out in my opinion.
I'm a newish subscriber here. Have a large holding in SHOE. Hoping for a write-up too post the results today :-)
Hi simmsc,
Welcome to Stockopedia!
Your wish is my command, I've just published a section on Shoe Zone (LON:SHOE) - you may not like it!
Regards, Paul.
Here are my SCVR heat maps for today (prices as at ~9:15am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you. Please feel free to ignore them if you don't find them useful.
Please read my heat map thread for a great deal of explanation of how the heat maps are formed and how I use them to guide me with my research, and for a full key to the contents.
I very much welcome feedback so if you do have any feedback, not already covered in the heat map thread, it would be very helpful if you could post your comment in the heat map thread rather than the SCVR thread. The more specific and constructive the feed back is, the more that likely it is that I will be able to act upon it. Thank you all for the feedback so far.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
ACRL
I like the management team here and think the turnaround is worth backing
One comment that stands out on the trading statement is "The Group expects volumes across the UK tissue sector to normalise in H1 22 and that its main market, the discounters, will grow strongly, as the UK returns to pre-pandemic shopping patterns."
Reading the Team17 (LON:TM17) annual report (I hold) released today is very encouraging. I think this should be on the 100 bagger list:
The founder and CEO upped her stake from 0% to 22% of the business as reported on April 5th.
The business has rock solid fundamentals, a growing software business, and relatively low risk due to multiple small budget projects and being vehemently against spending on huge budget AAA titles which are a gamble (especially in the light of CD Projekt Red's recent disaster).
Also, the last three director trades were all buys, with the last one being at a higher price than the stock is at the time of writing this today.
I highly recommend reading the annual report.
Team17 (LON:TM17) If she was the founder she must have had more than 0% to begin with.
By memory, think Nicola Foulston had around 13% holding...
Apologies, Debbie Bestwick even!!
I was just going by the delta shown on Stockopedia
It does look like a quality business but your comments regarding director buys do not look to be correct based on the RNS announcements made
I am using stockopedia data obviously
Smiths News (LON:SNWS) Smiths News
Morning Paul,
You briefly posted on this last Monday and there was a Mello presentation in the evening which I missed. Do you still remain positive following that presentation ?
Thanks
Rob
Morning Rob,
Re Smiths News (LON:SNWS) (I hold) - you asked;
Do you still remain positive following that presentation ?
Yes, absolutely. Nothing has changed. SNWS is a very simple investment proposition - a reliably cash generative business, which is slowly contracting structurally as newspapers & magazines decline, but costs are also mainly volume-related and are being managed down at a similar rate, on 3-year plans.
Meanwhile net debt is no longer a problem, it was refinanced last autumn, and there are 2 exceptional receipts expected in the next year - c.£9m refund from the pension scheme surplus, and c.£6m (or is it £9m, can't remember off the top of my head) deferred consideration from the sale of Tuffnells. That should then reduce net debt to c. 1x EBITDA, which is the targeted level.
At that point (assuming no hitches) then the company strategy is to keep net debt static at 1x EBITDA, and pay out all cashflows as dividends (twice covered) and special divis if any additional surplus cashflow.
Divis are restricted in the next year I think, by the banking arrangements.
I worked out that buying now could lock in a dividend yield in the future of 5-10%, very attractive in a low interest rate environment.
So for me, it's a tuck away & forget share, for 1-2 years. Not something I want to hold forever, but I think it's worth 50-100% more than the current price, whereupon I would be selling & moving on.
I also think SNWS could be a bid target, as a cheap way to acquire plentiful cashflows, especially for a business that could make use of a rapid overnight delivery network for its own products. Recently floated Supreme (LON:SUP) struck me as an ideal potential buyer, as it distributes small, high value items to corner shops, e.g. vaping, and batteries.
Hope that helps!
Regards, Paul.
Thanks very much for the update Paul - much appreciated - I hold
Results out today from Sanderson Design (LON:SDG) which I hold. I hope you may be able to comment please Paul.
Market clearly disappointed.
I wonder if some of the drop in Sanderson Design (LON:SDG) is profit taking - it has been on a charge recently. I hold and am happy to keep on holding. May be a "coffee can" share?? Second the request for Paul's view....
Dave
Agree re Sanderson Design (LON:SDG) - I took profits at 144p and my nervousness over speed of recovery for luxury materials. However, after todays results presentation I am v. impressed and suffering from seller's remorse.
The whole presentation and strategy communication was better (and more premium) than before. Very clear 3 year goals including reducing from 20K skus a year ago to 12K in 2 years - it is much easier selling winners. New US distributor is regaining traction in a key market whilst collaboration with Next is being expanded (is SDG a candidate for Next's share in the profit by part owning and partnering strategy?). Licencing news positive.
Almost slipped in was a very material £3Mn pa cost saving following an organizational structure which, whilst painful short term, seems now to much more structured around nurturing creative talent to 'live beautifully'.
UK Factories appear busy and with good plans - 3rd party manufacture is doing OK and absorbing overhead.
Balance sheet looks strong and brands appear to be doing well. Lot of value here IMHO.
Yes, I'll be commenting on Sanderson Design (LON:SDG) - am a bit mentally overloaded at the moment, so please bear with me!
Good Morning Paul are you planning on looking at Watkin Jones (LON:WJG) this morning?
Yes, Watkin Jones (LON:WJG) (I hold) is on my list, I'm currently working on it. All looks fine though, is the quick view!
As you have mentioned in your breakdown, the pipeline of Btr for FY22 is alarming but the pipeline for PBSA is also lower than current year and following years - slightly concerning but perhaps a red herring. The forecast increase in revenue must be coming from somewhere but I can’t work out where from the results. Anything you find out about this would be appreciated!
Topps Tiles (LON:TPT) (I hold) is clearly expecting a very strong H2. H1 results out today, which look in line with the trading update released at the end of H1. But with retail like for like sales in the 5 weeks since 12 April (reopening) up 16.8% on same period in 2019, management is clearly bullish and is saying that they expect to reinstate dividends at year end (paying out approx half of adj EPS) .
However, while the RNS has quite cautious language, I note that Liberum (note available on Research Tree) has materially increased its forecasts for this year and the next two years. For example, Adj EPS forecasts have risen from 3.4p to 5.5p (FY21) and from 5.5p to 6.2p (FY23).
I would expect the stock to be strong on the back of these upgrades. Admittedly, as I am currently a bit negative on the Covid situation, my finger is hovering nearer the sell button than the buy button.
I have yet to do a full read of the Interim results, but my thoughts on risks with Topps Tiles (LON:TPT)
Positives are that we still have a housing transaction boom, lots of household savings itching to be spent, and less holidays this summer means more people will be looking for renovations and DIY.
Morning Paul, could you please look at Shoe Zone (LON:SHOE) today. Trading statement shows some positive with online sales but understandably numbers overall aren’t great. Thanks
I have no position in Shoe Zone (LON:SHOE) but on my quick read of the results (apologies if I missed it elsewhere), I was disappointed they could say nothing more concrete on recent trading than this:
"No stores were open in the first 2 weeks of the 2nd half. Trading started strongly but has settled down to a more mixed picture of good High Street and retail park sales but weaker shopping centre performance."
Whatever follows in the second half of the sentence the words ‘a mixed picture’ never imply good!
The whole interim statement is very short on details.
Newsflow from this business always puzzles me. Over the past year, we've had a big rant about business rates in one of the trading updates. Then this with barely any outlook details, and quantifying anything to make their statements meaningful. For example the following statements from today's Interim Report. Useless!
Especially the last point! With only £4.1m net cash and £16m of current lease liabilities, how much of it is under pressure to unwind in H2 due to delayed rent payments? Please tell us £SHOE!
For me, un-investable with management that can't communicate to shareholders properly.
Yes, I'm aiming to look at Shoe Zone (LON:SHOE) later. Got a lot on my plate at the moment, so please bear with me.
Thanks Paul! your hard work is always appreciated
My morning smallcap tweet:
Batm Advanced Communications (LON:BVC) Tanfield (LON:TAN) CPPGroup (LON:CPP) Accrol Group (LON:ACRL) EKF Diagnostics Holdings (LON:EKF) accesso Technology (LON:ACSO) £CSS Sureserve (LON:SUR) Topps Tiles (LON:TPT) Minds Machines (LON:MMX) SIMEC Atlantis Energy (LON:SAE) Minds Machines (LON:MMX)
BATM Advanced Communications (BVC) delivers two new covid diagnostic tests, a PCR and a rapid test. Also Italian Olympic Committee intends to use co's saliva-based RT-PCR test at Olympics. [SP=87.9 Cap=387m]
Tanfield (TAN) 49% owned Snorkel rev 28% down in Q1. Still in dispute with Snorkel over non issue of FY20 accounts. [SP=2.18 Cap=4m]
CPPGroup (CPP) complates sale of German card protection legacy business for £2.2m less transaction costs. CPP will refrain from any activity in the card protection market that places it in competition with the purchaser in Germany and Austria for 2 years. [SP=520.63 Cap=46m]
Accrol (ACRL) guides FY(Apr) EPS in line despite rev below mkt expectations as consumer stockpiling unwound. Market share 16% (13%). Increasing capacity from Q3, to fulfil the expected increase in demand. Also making progress on paper mill development plans. Outlook - "expects volumes across the UK tissue sector to normalise in H1 22 and that its main market, the discounters, will grow strongly". [SP=62 Cap=193m]. I hold.
EKF Diagnostics (EKF) EKF distributed its investment in Trellis Health to shareholders. Trellis Health is to float on AIM (as announced) and will include holders in the subscription at the time of the float - 28 May. [SP=66.6 Cap=303m]
Accesso Technology (ACSO) guides FY rev above $83m guidance but extra staff and costs may 'temper the profit impact'. [SP=624 Cap=257m]
Crossword Cybersecurity (CSS) plans to majority owned JV to sell in Oman. [SP=NA Cap=NA]
Sureserve Group (SUR) H1(Mar). H2 started ahead of management expectations, [SP=81.25 Cap=131m]
Topps Tiles (TPT) H1(Mar). Outlook - two-year LFL up 17% following easing of lockdown, confident of improved performance. [SP=70.4 Cap=137m]
Minds Machines (MMX) FY(Dec). Outlook - Q1 rev down 4% but EBITDA doubled to $1.6m. [SP=7.2 Cap=63m]
SIMEC Atlantis Energy (SAE) the 43% holder, SIMEC UK Energy Holdings, has 'purportedly' had receivers appointed. "The GFG Alliance has informed SAE that it intends to challenge the validity of the appointment and is seeking appropriate advice. For the avoidance of doubt, SAE wishes to make clear that the above process relates to its major shareholder, SUEH and not to SAE itself." [SP=7.1 Cap=36m]
[Edit] Minds Machines (MMX) FY(Dec). Outlook - Q1 rev down 4% but EBITDA doubled to $1.6m.
Sureserve (LON:SUR) Unaudited Interim Results for the six months ended 31 March 2021 (H1 FY21)
Looking good.
Financial overview
· Revenue up 4.6% to £114.6m (H1 2020: £109.6m)
· EBITA*1 up 22.1% to £4.8m (H1 2020: £3.9m)
· Profit before tax up 71.5% to £4.4m (H1 2020: £2.6m)
· Profit before tax before amortisation of acquisition intangibles up 30.6% to £4.4m (H1 2020: £3.4m)
· Earnings per Share (EPS) from continuing operations up 71.2% to 2.2p (H1 2020: 1.3p)
· EPS excluding amortisation of acquisition intangibles and share based payments up 25.7% to 2.3p (H1 2020: 1.8p)
· Net cash / (debt) excluding lease liabilities increased to £9.7m (31 March 2020: (£3.5m))
· Order book of £371.6m (31 March 2020: £323.7m) providing visibility of earnings with circa 99% covered in FY21
*1 EBITA is defined as operating profit before amortisation of acquisition intangibles. EBITA excludes the profit from Discontinued Operations.
I would also appreciate Paul and/or Jack’s views on these results from Sureserve (LON:SUR) and especially thoughts on the EPS numbers.
Many thanks
Ricardo
Yesterday's 10% jump in the Sureserve (LON:SUR) price has to look like insider dealing of some sort.
Morning all. Another few contract wins for £REAT. ..Too small probably for this board I appreciate but just in case someone is invested. The management do not seem to be doing a bad job at all.
Thanks for this, I know both companies and after a possible rise today, I am going to add on any pullback, in my humble opinion this will easily multibag, not a glamourous industry, but a needed and profitable one DYOR
Acorns and oak trees etc
Lon: REAT.
Agreed lots of positive momentum at React and today's contracts add to this.
Note the director sales on 14th May were NOT a pre-cursor to bad news.
It is multiple director buying that investors should keep tabs on.
React (LON:REAT) - yes, but it is not convincing when a director sells a third of his holding for a not particularly large figure. It would indicate he did not expect the price to go higher very quickly.
React (LON:REAT) - yes, but it is not convincing when a director sells a third of his holding for a not particularly large figure. It would indicate he did not expect the price to go higher very quickly.
Or that they had some pressing personal need. Take, for instance, the director sale at Cerillion (LON:CER) discussed yesterday. And, of course, directors are often not that good at judging investor sentiment.
Generally director trades - particularly multiple trades - are a decent indicator of future trading in small cap stocks. They have little informational value in larger companies.
Ben wrote about this a while ago:
"What they found was that using director dealings as a signal is not straightforward but that it is a comparatively strong indicator in small cap stocks. They looked specifically for strong buy and sell signals and found that when at least three different insiders are trading sizable amounts of stock this produced high returns"
https://www.stockopedia.com/co...
Personally I've only ever found director trades a valuable signal during periods of high volatility. Last year, during the mass panic following lockdown, they were a very reliable gauge of which companies were confident about their future.
timarr
LON:REAT.
Agreed Timarr.
React (LON:REAT) is my second largest holding. I was introduced to them during the Mello Monday Game Changer section on the 8th of Feb. Whilst they are only a 17m cap firm, they are very ambitious. The market they are in is full of very small companies and their approach is to consolidate through acquisition. As they grow, they intend to win bigger contracts from larger firms whom prefer to out source specialist cleaning jobs. They say they are the only company in the Britain who can arrive onsite with in 4 hours, 24 hours a day.