Small Cap Value Report (Tue 19 Dec 2017) - DOTD, KOOV, NWF, KMK

Good morning, it's Paul here.
Firstly, please accept my apologies for the break in coverage last week. Things are back on track now, so we'll have full coverage this week. Hopefully I'll also be able to recap on one or two interesting things from last week too.
Today I'll be reporting on results or trading updates from: DotDigital, Koovs, NWF, and Kromek.
dotDigital (LON:DOTD)
Share price: 97.0p (up 1.0% today, at 08:15)
No. shares: 295.8m
Market cap: £286.9m
AGM statement (trading update) - this company calls itself;
... the leading provider of intuitive software as a service ("SaaS") and managed services to digital marketing professionals through the 'dotmailer' platform
This share has been a long-standing favourite of mine here over the past 5 years, but (stupidly) I've always baulked at the high valuation - even when it was 17p per share! It just goes to show, that good companies grow into, and soon overtake an apparently high valuation.
The company has a 30 June year end, so today's update covers the bulk of H1 06/2018.
"The Group has seen the positive trading momentum highlighted in the 2017 preliminary results continue into the first half of the new financial year.
This progress is in line with management expectations and is driven by strong international sales and growing demand for dotmailer in the ecommerce market...
Sounds good.
Note that the company spent about half its cash pile recently, buying a group of companies called Comapi for £11m. This is a messaging software company, which seems to be in the process of being integrated into DOTD's existing software.
My opinion - this seems a quality outfit, which hasn't put a foot wrong. The market has rewarded that with a multibagger share price over the last 6 years.
The StockRank sums it up very clearly - quality & momentum, but pricey;
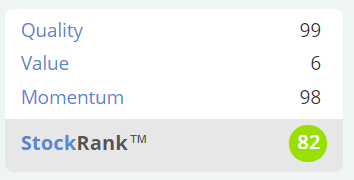
The interesting thing here is that bulls could argue that DOTD is only scratching the surface of its potential markets. More detail is given in today's announcement about the "Connectors" between DOTD's dotmailer platform, and ecommerce leaders such as Shopify, and Magento (which are widely used platforms for ecommerce sites).
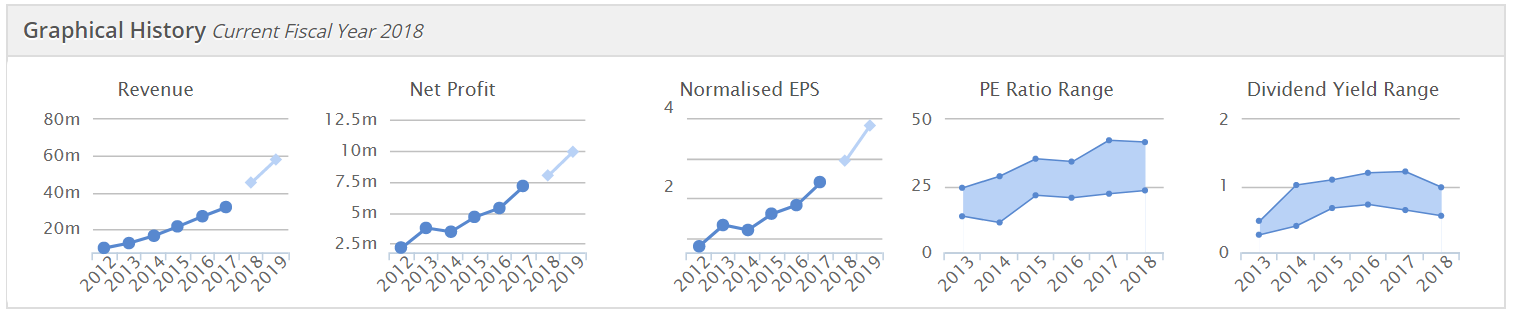
Another impressive trait of DOTD is that its growth is self-funded, so the share count has only increased marginally in the last 5 or 6 years, despite profits soaring. That's mightily impressive. It also has very high profit margins. There's an awful lot to like about this company. It's tempting, even at the current forward PER of 28.5
Koovs (LON:KOOV)
Share price: 16.25p (down 39.8% today, at 09:13)
No. shares: 175.4m
Market cap: £28.5m
Koovs plc (AIM: KOOV), ("Koovs" or the "Company") the fashion-forward business focused on the young Indian e-commerce market, today announces its interim results for the six months to 30 September 2017.
These figures are absolutely dire. To clarify that, the figures are always dire from Koovs, but the one saving grace in the past has been rapid revenue growth. The stock market will often give rapidly growing companies the benefit of the doubt over losses & cash burn, if top line growth is soaring.
What's so shocking about today's results from Koovs, is that revenue growth has completely stopped. Here are a few numbers for H1;
- Revenue £3.9m, down 1.1% on H1 PY (remember that this is meant to be a rapid growth stock)
- Gross profit minus £12k - so they're basically selling clothes for the cost of manufacture
- Overheads £7.7m
- Operating loss £7.7m (remember these are just 6 months figures)
Looking at the balance sheet, there is cash of £5.6m, plus bank deposits of £3.7m, so the company probably has enough cash to last until spring 2018 by my reckoning.
Receivables looks very high, at £7.6m - that's almost a year's revenues sitting in receivables. Seems odd.
There is also "loans & borrowings" of £6.9m, so the net cash figure is minimal. This £6.9m is the convertible (at 40p) 6% loan notes.
The narrative is just delusional nonsense, so best ignored. Businesses that don't have a viable business model always try to sprinkle glitter over things by steering investors towards meaningless KPIs.
Outlook comments - clearly not good, as there's not enough cash to drive growth through marketing. Note also that "sales" here are not the same as "revenues";
With modest additional marketing spend, the important month of November delivered a significant year on year improvement across key metrics, with Sales up by 17% to 1.7m and website traffic up 43%.
However, marketing expenditure is currently significantly down due to the ongoing funding requirements of the Group, which the Company expects to affect FY18 sales overall.
Additional marketing expenditure is conditional upon the timing of closure of the funding programme announced in July 2017, which the Company continues to expect to close shortly.
It's stating the obvious, but a funding round from July which hasn't closed by December, suggests that funders are not too keen to inject more cash. Why would they, since that cash is already earmarked for total destruction.
My opinion - the business model at Koovs has been all wrong since the start. The central overheads are far too large, sales are too small (and not even growing any more), gross margin is nil. Plus there's very little cash left.
It might survive, if funders are prepared to throw more money at it. The existing equity is worth nothing though, on any rational basis.
In my experience, successful eCommerce businesses tend to start small, operate on a shoestring by a driven founder CEO, and keep costs low as they grow. Then after a few years, growth becomes self-funding, and accelerates. Koovs has tried to put the cart before the horse - escalating its central overhead far too high, before it's generated any decent sales momentum.
The worst mistake was under-funding the start-up. If you're going to really go for it, in terms of growth & heavy start-up costs, then the cash required for 3+ years' cash burn needs to be raised up-front, plus a contingency reserve. Koovs has been struggling for cash since 2015, and its repeated funding rounds, are looking increasingly desperate.
Maybe it's time to just admit defeat, and let it fail? Or slash costs to the bone, and try again as a leaner, fitter business?
NWF (LON:NWF)
Share price: 165p (up 0.6% today, at 10:53)
No. shares: 48.7m
Market cap: £80.4m
NWF Group plc ("NWF" or "the Group"), the specialist agricultural and distribution business delivering feed, food and fuel across the UK, today announces a trading update for the half year ended 30 November 2017 and its notice of results date.
A simple, and clear update;
The Group reports that trading for the half year ended 30 November 2017 was ahead of the prior year and the Board remains confident of delivering its full year expectations.
Net debt was also lower than at 30 November 2016.
More divisional performance information is given, which I won't cover here.
Valuation - the valuation is fairly low, as you would expect for a fairly boring, very low margin business;
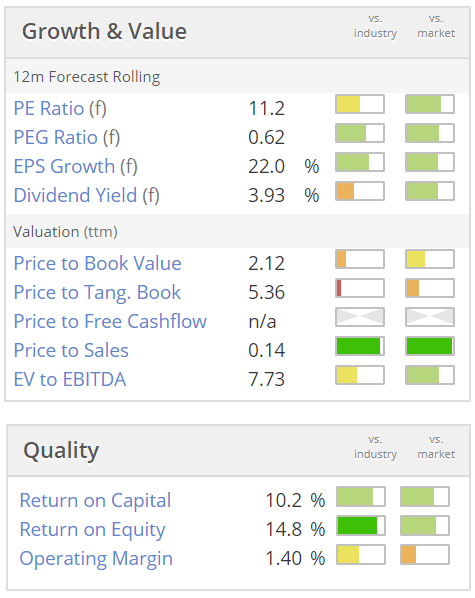
Note that divis are fairly good, and there has been a nice progression with the divis rising 5-6% p.a. - which works well, after a few years' compounding has been allowed to happen.
My opinion - I always almost nod off when looking at this company, it's so boring.
That said, there seems to be a nice turnaround happening, with EPS heading for forecast of about 14.3p this year - well up on the previous 2 years' results.
The valuation seems undemanding, so it might be worth a closer look perhaps?
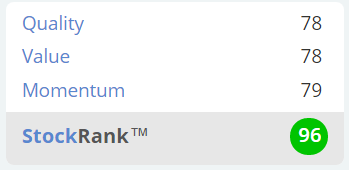
Note the excellent StockRank, which surprises me at being this high;
Kromek (LON:KMK)
Share price: 25.4p (down 5.8% today)
No. shares: 260.4m
Market cap: £66.1m
Kromek (AIM: KMK), a radiation detection technology company focusing on the medical, security screening and nuclear markets, announces its interim results for the six months ended 31 October 2017.
I'm trying to work out why this company is worth £66.1m, when it's reported pretty lame H1 figures today.
Revenue in H1 was only £4.8m, although that is up 27% on H1 LY.
It's still loss-making on all measures - take your pick which profit measure you prefer from the below options;
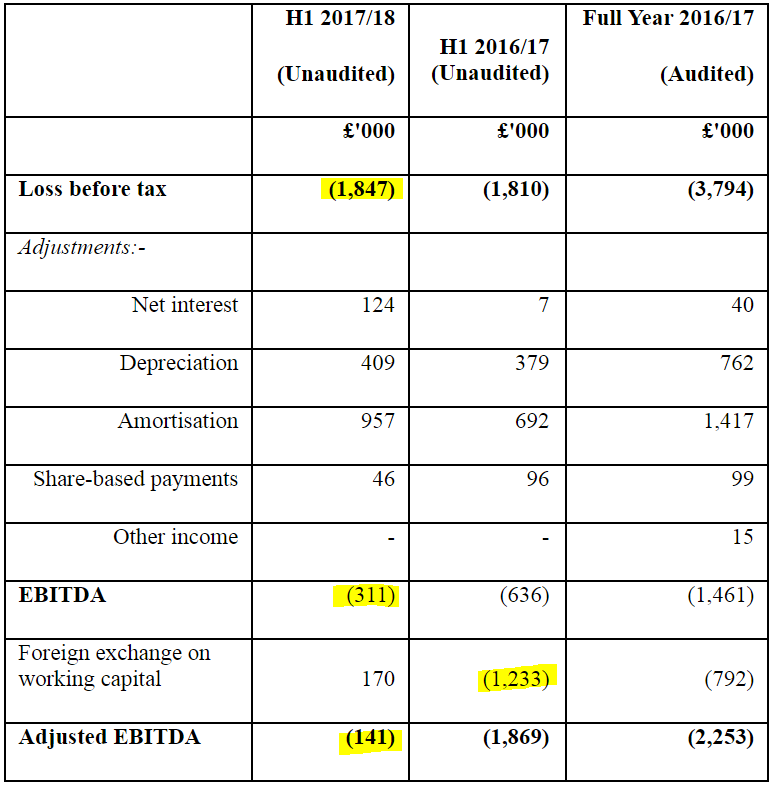
Note also the big forex movements on working capital.
Balance sheet - looks very strong, after a big equity fundraise last year. So it has £15.0m cash in the bank, plus £1.25m long term cash deposits. On the other side, there is a £3.0m borrowings figure, which is unusual (to hold cash, and debt at the same time).
Debtors looks very high too, so that's worth checking out.
Jam tomorrow companies are a bit more tolerable if they have plenty of cash in the bank, as this one does.
Outlook
Kromek entered the second half of 2017/18 well-positioned to deliver revenue growth for the full year and achieving EBITDA breakeven in-line with market expectations. This expectation is underpinned by good visibility of revenues with a significant proportion under signed contract.
The Group continues to benefit from its customers commercially launching next-generation CZT-based products and from the increasing adoption of CZT-based technology across its target markets. TheGroup's products continue to gain traction in all its business segments and Kromek is strengthening its relationships with existing customers as well as enhancing its reputation among potential customers. As a result of this, combined with a strengthened order book and improved revenue visibility, the Board looks to the future with confidence.
My opinion - it's too much of a jam tomorrow share for me. Sometimes jam tomorrow shares do work, but it's fairly rare, and usually takes a lot longer than originally planned. So why pay a premium for an outcome that tends to be unlikely?
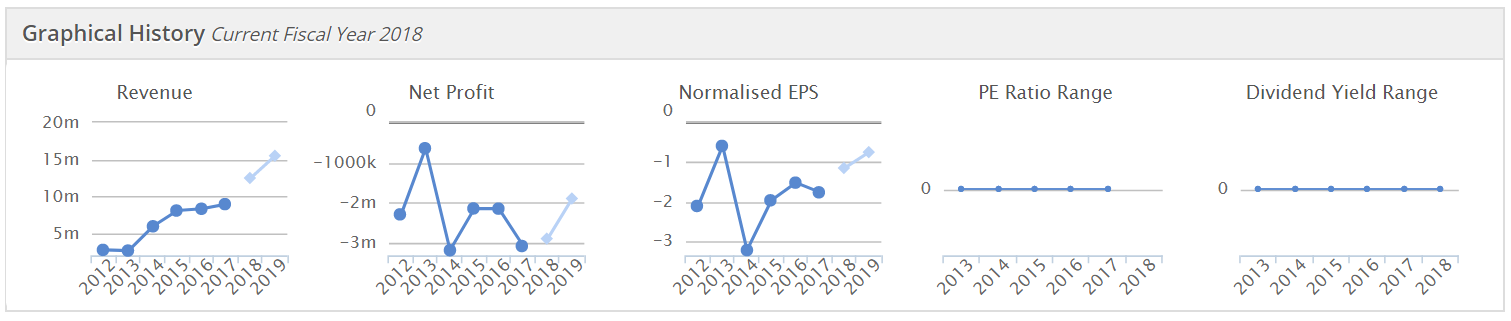
I would want to see a much better progression than the one in the charts below. Kromek seems resolutely mired in the red, despite its rising revenues. As for the PER and dividend yield graphs below - it looks like someone needs to fetch a defibrillator to get things moving here!
Perhaps Kromek's time will come at some point in the future, but that's not something I want to gamble on, especially not at a £66m market cap.
All done for today. See you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
IIRC, Richard Whiting, CEO of NWF (LON:NWF) explains in his investor videos that their margin on the fuel business is 1p per litre. The high pass-through cost of fuel does depress the overall operating margin. However, I think the much better ROE and ROCE figures give a truer indication of the business quality. Boring it might be, but it has been going for over 100 years and the 3 arms to the business give it some resilience. Now retired, I’m happy to keep collecting the dividends
Koovs (LON:KOOV) there was a comment about the large receivables in the text today
"Additionally, £5.90m (INR 516.8m) of marketing funds have been prepaid to secure significantly reduced media rates, and been recorded in the Statement of Financial Position under "Trade receivables, other receivables, prepayments and other assets".
Just all looks like pie in the sky to me. Especially when the CEO and Chairman tell you it's all going so well yet a) it doesn't even make a gross profit, 2) users are down 15% (as a result of reduced marketing?) and cash is dwindling fast.
I managed to short a measly amount at 24p today when it was only down a few % at the open. Paid for my Xmas lunch with friends tmrw. Maybe I'll increase the quality of the wine as welll...or just buy more...!
I want to add a few things on Kromek:
1). Capitalisation development cost has ballooned to £11m, greater than annual sales. The condition for measuring Kromek is based on the number of units sold, regardless of profitability.
2). Annual cash burn is around £6m, but the company is good at raising money. £53m raised since 2011.
3). The market opportunity is less than £800m with market valuation at £66m. I agree with Paul that valuation is on the high side.
4). Risk: reward is 75: 25. It's not about having a large order book or even securing contracts. It's about cash profit from these contracts.
Receivables at £7.6 million for Koovs.
I thought internet retailers got credit card payment before the goods are shipped, so what credible explanation could there be ?
Offering credit to customers when the retailer is likely to run out of cash seems daft.
My guess is that it may have something to do with Souq.com. They have a lot of items listed on the website and it all appears to be available from stock. Could possibly be a sale or return deal. One of the reasons that Koovs have always recorded low gross margins is because they have to commit to large minimum quantities required by suppliers and then clear a lot of excess stock. They don't sell everything below cost! Can't think what else it could be.
Don't know the company or looked at financials but if they selling on consignment basis (and it's been a long time since I had to look at revenue recognition on consignment sales) but from much forgotten memory, consigner (Koovs) should not book revenue until agent (souq.com) sells the goods. They (Koovs) would keep the inventory on their books (physical location might change and associated costs). There should not be a receivable as they get cash at time of sale from agent (unless they give credit as well as risk free stock). If anything I would expect commission payable to the agent. Like I say, I don't know the company beyond scvr so probably completely wrong!
NICL has the fantastic opportunity of being the maufacturer of choice for all soft drinks during the Muslim festive month, unfortunatly this rotates each year to another month and always confuses the pundits as the business is 13 monthly operating in a 12 month world.
If you want to make money on this one buy a couple of months after EID and sell before results. Sooner a Saudi company buys them up the better. I did this for two years and made money, but the strategic message of looking for another "big bang" drink, forget it, they up against coke and pepsi. They are a niche player end of
I used to try to compete with NWF, it was a joke, they are slow and just grow into owning more and more of a shrinking load of farmer shops/supplies. Whenever we came up with some piece of technology the attitude would be "too expensive" so we sold it to the farmers using mail order and internet. Avoid, should be private.
I used to work next to DOTD at the bottome of the last down turn and they really suffer when the market is quiet. The market opportunity is big but there are a shed load of good players with no moat available, buy for the market movements rather than underlying value
A very warm welcome back Paul. I concur with other commenters that absolutely no apology is necessary. I wonder if you might find time to circle back on the preliminary results from Oxford Metrics (LON:OMG) last week. The results looked positive to me but met with little response from the market until today when a 5% drop came against no new announcements. I'd really value your reading of the results announcement. Many thanks.
Oxford Metrics (LON:OMG) Went ex-div at the end of last week, had large director sell and large director options exercised, about half of which were sold. Estimated EPS is reduced from 2017 to 2018 I think and as a result of this Stockopedia stock rank has dropped. Please correct me if I have got any of this wrong.
Thanks murrb. I imagine (hope) it's more to do with going ex-div as the options and director share sales didn't provoke much reaction last week. The CEO and CFO sold around half of their exercised options but the release did make the point that the net shares retained increased each director's shareholding and that the sales were for tax reasons. It didn't look great that they released such upbeat preliminaries and then the CEO, CFO and a NED all sold quite heavily the next day. Nonetheless, I remain long and was encouraged by the results and their clarity of progress towards their five-year strategic growth plan.
HI, Please could you cover the new kid on the block FAB - fusion antibodies?
I don't know anything about Nichols (LON:NICL) and have never covered it before, so will have to decline that one I'm afraid. £575m market cap is a bit above my normal cut-off. Sorry about that.
Regards, Paul.
Paul
Your thoughts on Nichols would be most welcome -thanks
Paul, Gocompare.com's takeover of Vouchercodes may be worth assessing? Not really sure if Vouchercodes is a fading brand? I saw the pitch for Pouch on Dragon's Den and that looks like the way things are going.
Paul, if you get a chance could you cast your eye over the trading update from AIM listed soft drinks manufacturer Nichols (LON:NICL)
When I first read it I thought it was an "in-line" update but the market seems to be interpreting it as a significant profit warning. I would value your views.
I think this is why the Nichols (LON:NICL) shares are down today "In our international business, we anticipate the strong growth trend in Africa to continue in 2018. However, the current conflict in the Yemen coupled with some reported slowing in the Saudi economy indicates that sales to the Middle East region in the year ahead are likely to be less than previously anticipated. As a result, management currently expects low single digit percentage profit growth in 2018 in comparison to the current year."
Good morning Paul, welcome back.
I hope you don't mind me reminding readers that my report into investors' sentiments about the market is now available here.
https://www.stockopedia.com/content/market-sentiment-report-december-2017-255323/
cheers
Francis
Might be a bit too big but am interested in what people think of Gocompare.Com (LON:GOCO) 's acquisition of MyVoucherCodes. I was in GOCO for a little while but it has languished recently, is this the boost it needs?
Koovs (LON:KOOV) looks like it's improving but I would love to hear Paul's thoughts on it compared to Boohoo.Com (LON:BOO) & Sosandar (LON:SOS) etc.
Any thoughts after the Van Elle Holdings (LON:VANL) GM result on Friday? A resounding raspberry from the non Michael Ellis camp to his proposed re-shaping of the board with only a tiny fraction (about 2%) of the non-aligned shareholders supporting Ellis’s motions. Ellis has come out with a response this morning claiming a notional victory -
https://www.investegate.co.uk/michael-ellis/rns/statement-by-michael-ellis-about-the-van-elle-egm/201712190700057060Z/ -
in calling the board to account but the GM vote does seem to be a slap in the face. Trying to work out whether this ends the dispute with the vast majority of the shareholders supporting the board or whether it will rumble on with Ellis bad mouthing the way the business is being run. Potential here for this to undermine the company’s relationship with existing and potential customers, suppliers etc.. Likewise, might Ellis and friends sell up in a fit of pique and move on potentially leaving a 20% overhang of shares looking for a home and taking the shares even lower? On fundamentals the shares look cheap but might become even cheaper still.
Gus.
My morning smallcap tweet:
Alpha Returns (LON:ARGP), Eastern European Property Fund (LON:EEP), Audioboom (LON:BOOM), Hostelworld (LON:HSW)
Alpha Returns Group (ARGP) suspended as nomad resigns. Re-financing not agreed yet. "Beaumont Cornish will not be in a position to provide all relevant nominated adviser confirmations to the Exchange...so will no longer be acting as nominated adviser to the Company."
Eastern European Property Fund (EEP) will delist soon, as mooted.
Audioboom Group (BOOM) very belatedly discloses that a company of which the Chairman is a director entered into administration in May.
Hostelworld (HSW) CFO is leaving in H1 2018. Sounds amicable.
NWF (LON:NWF) trading update
Koovs (LON:KOOV), please - I could do with a laugh!
Paul,
To echo other comments, it's great to see you back again. I had been wondering if Ed had given you the boot, I'm pleased that my concerns were misplaced!
Don't see the real need to apologise to be honest - But are you sure you're back on track? It was the 2 hour finale last night :)
Paul wasn't last week the best week for xmas discos :)
anyways welcome back the best small cap reporter ..
No need to apologise, Paul. Would much rather have the quality of your reports with the occasional break for beers and twitter cheese, than some turgid but guaranteed daily writeup. It's the character and human side of your reports that puts them on a level above all others!
Pastysupper is so right. We can cope with the occasional break in transmitting because what we get from you is proven in depth analysis, independent thinking, your honest opinion and lots more.
You are worth your weight in cheese!
Paul and Graham you are providing a great service to private investor. Many thanks!!!
Last week Luceco (£LUCE) issued a profit warning. I suspect many of your followers would like to read your comments.
Len
Graham commented on Luceco (LON:LUCE) here https://www.stockopedia.com/content/small-cap-value-report-fri-15-dec-2017-ucg-luce-ful-botb-cvr-254388/
Any opinion on Curtis banks Curtis Banks (LON:CBP) welcome.
I got stopped out at 270 - but on reading the RNS it seems to be a one off issue - although they could have handled it better.
Any views welcome