Small Cap Value Report (Tue 19 Dec 2023) - OMIP, SDRY, TSTL, CAV, EXR, GPH

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
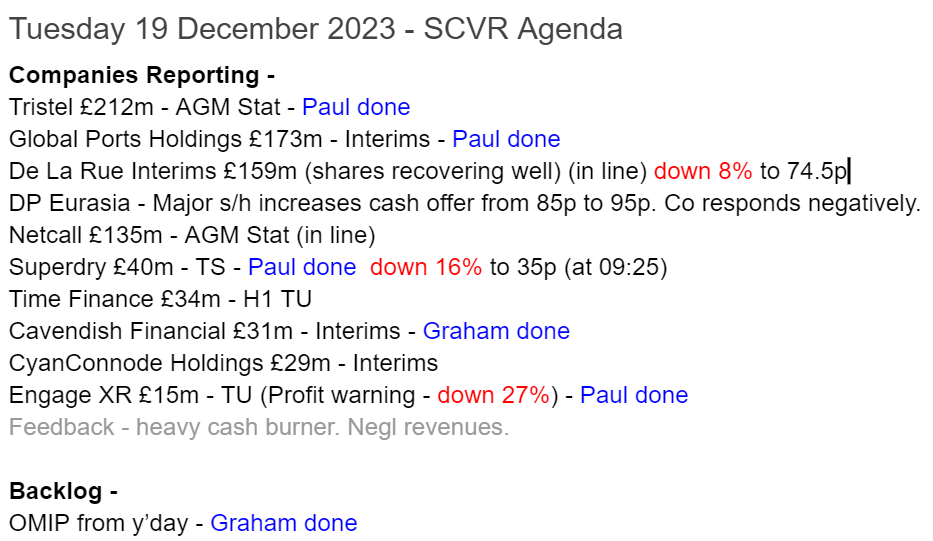
One Media IP (LON:OMIP) - up 3% to 5.4p (£12m) - Trading Update - Graham - AMBER
OMIP’s core business - digital music rights management - delivers in line with expectations. However, the cash balance has declined as OMIP invests in an anti-piracy software subsidiary. I would treat these shares with caution, as the company appears to be sub-scale.
Superdry (LON:SDRY) - down 14% to 36p (£36m) - Trading Statement (profit warning) - Paul - BLACK (profit warning), and RED on fundamentals.
Another profit warning, with poor performance so far in FY 4/2024. I'm not able to quantify the shortfall, as no broker updates currently available. I'm not sure SDRY will survive calendar 2024 in its current form, hence am steering clear. EDIT: I'm told that broker forecasts have been massively slashed. So this looks very bad.
Tristel (LON:TSTL) - up 2% to 455p (£216m) - Trading Update (AGM) - Paul - AMBER/GREEN
H1 update today is brimming with positivity. It doesn't directly mention full year market expectations, but a note from Cavendish seems to suggest that the next update might be ahead of expectations maybe? As always, this share looks very pricey, so it's up to you if you're prepared to pay up for growth and quality, or not!
Cavendish Financial (LON:CAV) - up 5% 8.9p (£32m) - Interim Results - Graham - GREEN
This AIM-focused investment bank reports its maiden interim results following the merger of finnCap and Cenkos under this new name. The cash balance has risen to £17m, over half the market cap, and £7m of operating cost synergies make this almost irresistibly cheap.
ENGAGE XR Holdings (LON:EXR) - down 27% to 2.05p (£11m) - Trading Update (profit warning) - Paul - RED
Contract slippage means that FY 12/2023 falls way short of forecasts. The only saving grace is that it has enough cash left for the time being. It's quite a nice story, but so far EXR has failed to achieve the scale needed to be a viable business.
Global Ports Holding (LON:GPH) - unch 255p (£174m) - Interim Results - Paul - AMBER/RED
An interesting special situation, which I untangle below. It owns operating rights to lots of cruise ship ports, all financed with massive debts - which are now getting a lot more expensive to service. Hence it's not clear to me what, if anything, equity is worth. Needs a lot of detailed research to properly judge that.
Paul’s Section:
Superdry (LON:SDRY)
42p (pre-market) £41m - Trading Statement (profit warning) - Paul - BLACK (profit warning), and RED on fundamentals.
Superdry plc (“Superdry” or the “Group”), today issues a trading update for FY24 covering the 26-week period to 28 October 2023 and an update to current trading covering the 6-week period to 10 December 2023.
An admirably honest headline from this struggling fashion brand -
Despite progress on our cost savings programme and inventory reduction, full year profitability expected to be impacted by well-documented challenging trading environment…
… trading performance has been significantly below management expectations. Profits for the year are therefore expected to reflect this weaker trading seen to date.
There’s plenty of detail, but no specific guidance on how much profit will miss forecasts.
Liberum has published notes on Superdry several times in 2023, but I haven’t seen anything new come through yet on Research Tree today. I'll update if anything comes through later today.
EDIT: A friend tells me that broker forecasts for city insiders have been massively cut for SDRY today, but there's still nothing available to private investors. I'm told that it could be a loss of c.£45m for FY 4/2024. That reinforces my view that this share will be lucky to survive calendar 2024. End of edit.
In a previous note (5 Sept 2023) Liberum forecast a rebound from last year’s £(21.7)m adj LBT, to a much reduced £(1.5)m LBT this year, FY 4//2024. That was based on anticipated sales decline of 6% this year.
Today’s update says H1 has seen retail sales down 13.1%, and wholesale down a whopping 41.1%. Most recent 6 weeks trading in H2 is said to be down 7% LFL.
Therefore, it sounds like actual results for FY 4/2024 are likely to be well below current forecasts, and at a guess I’d say a thumping loss is on the cards, despite (previously announced) £35m cost-cutting.
Paul’s opinion - sadly, there’s still no sign of any turnaround at Superdry. It bought some time through selling off Far Eastern IP, and there could be other similar deals, possibly? Additional debt facilities are also available. So it strikes me that the company is likely to survive this current season, limp into calendar 2024, and then it probably only has one last chance to effect a turnaround during 2024.
Overall then, although the market cap is tiny, the situation looks precarious, hence I won’t be tempted to gamble on a rebound here. The collapse of Joules taught me that it’s not worth the risk, trying to bet on a turnaround of struggling fashion brands.
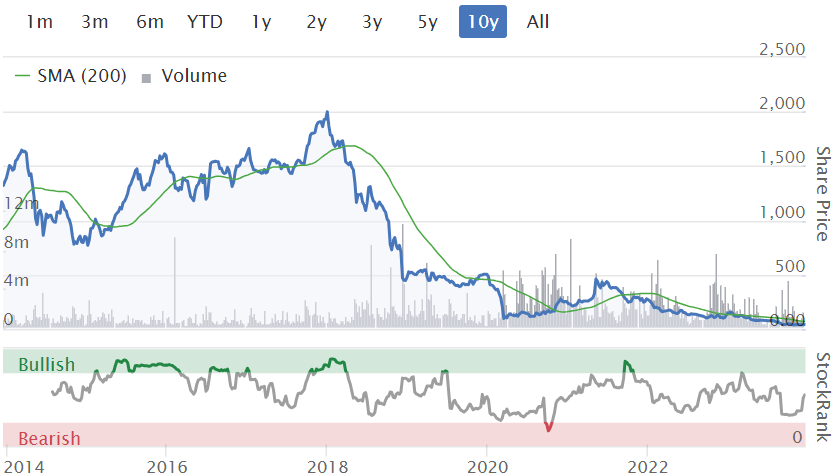
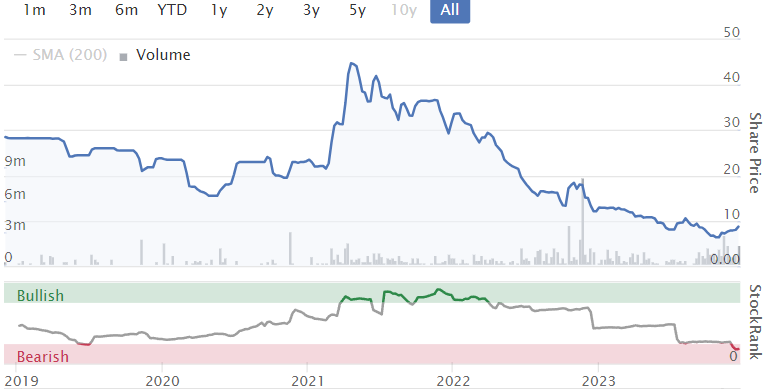
As you can see from the 10-year chart below, this is a structural decline, which set in well before the pandemic -
Tristel (LON:TSTL)
Up 2% to 455p (£216m) - Trading Update (AGM) - Paul - AMBER/GREEN
Tristel plc (AIM: TSTL), the manufacturer of infection prevention products, will hold its Annual General Meeting at 11am today …
H1 has been good - and note the fabulous gross margin, giving excellent operational gearing when sales increase -
"I am pleased to report that the Company has had a record first half with revenue for the six months ending 31 December 2023 expected to be £20.7m, an increase of 18% compared to £17.5m in the first half of last year. Revenue growth has been delivered across all our geographical markets. Gross margin remains above 80% in line with our expectations.
Outlook - sounds confident & upbeat -
"The business is performing strongly on all fronts and the confidence that we expressed in October in our medium-term outlook remains unchanged. With the growth possibilities for our business stronger than ever, and as a business with no debt and forecast cash balances of approximately £10.4m after payment of this year's final dividend on 22 December, we are in a strong position to capitalise upon our global leadership position in the medical device decontamination market."
USA expansion - again, this sounds encouraging -
"In the United States, Parker Laboratories, our manufacturing and distribution partner, completed its first production run for Tristel ULT in early October, following receipt of our FDA approval in June 2023. This has enabled Parker to stock its national distribution network and provide product to the first beta site users. We expect to make steady progress in building our customer base throughout the United States during the second half of our financial year. We remain very excited about our prospects as we begin serving the largest healthcare market in the world.
Broker update - Cavendish helpfully updates us this morning, forecasting 13.7p adj EPS for FY 6/2024. Although it points out that H1 has exceeded this, if we use the same seasonal weighting as last year. Combined with the very upbeat-sounding management commentary, I imagine Tristel is likely to produce one or more ahead of expectations updates over the next 6 months. On a PER of 33.2x (455p/share divided by 13.7p EPS), it needs to!
Forecast for FY 6/2025 is a decent jump to 16.5p - presumably based on royalties from US sales kicking in?
CEO retirement - long-serving founder/CEO Paul Swinney has announced his intention to retire in the next 12 months, after 30 years. That sounds reasonable, and I don’t sense anything untoward from this.
Paul’s opinion - things seem to be going well, and I like everything about Tristel, apart from the price! Bulls need to be certain that Tristel can thrash forecasts, as otherwise the valuation could be too high.
That said, with management so upbeat, and 80% gross margins providing operational gearing, I’m leaning more to the positive side, despite a high valuation, so let’s go with AMBER/GREEN. High StockRank too.
ENGAGE XR Holdings (LON:EXR)
Down 27% to 2.05p (£11m) - Trading Update (profit warning) - Paul - RED
Contracts have slipped, so revenue is now expected at 3.6m to 3.8m euros for FY 12/2023. That’s a long way short of the 7.5m euros consensus shown here on the StockReport.
Heavy losses continue, but it still has enough cash for the time being -
…the Company expects to report an EBITDA loss of approximately €4.6m and a net cash position at the year-end of approximately €7.3million giving us adequate funding to reach break-even in the short to medium term.
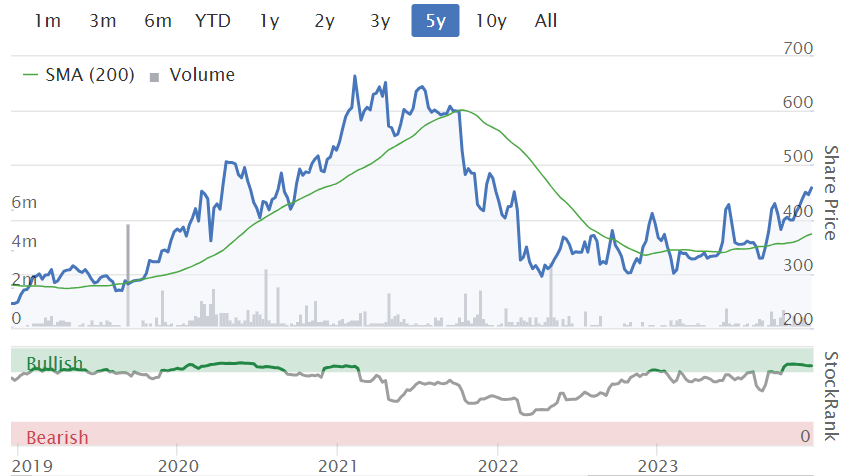
Paul’s opinion - we’ve reviewed EXR here 6 times in the last year and every time it’s been a RED view from us. That’s because, so far anyway, there’s no sign that this is a viable business. Revenue is subscale, hence it racks up heavy losses each year, with 2023 repeating that pattern. The remaining cash pile does give it time to deliver on the promises though. Some of the stuff it’s doing does sound interesting, it’s a nice story, but we need to see better execution, and growth. Until that happens (if!) it’s just a high risk punt, for optimists only. Why get involved, when this type of speculative share nearly always goes wrong on AIM? I’ll just wait on the sidelines, to see how things go, ready to pounce if it reaches a positive turning point.
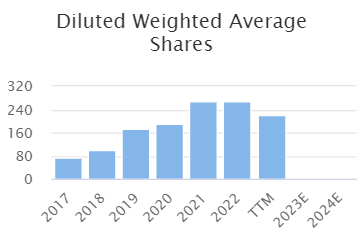
Note also that the share count has considerably more than doubled since it listed, due to fundraisings.
Global Ports Holding (LON:GPH)
Unch 255p (£174m) - Interim Results - Paul - AMBER/RED
Global Ports Holding Plc ("GPH" or "Group"), the world's largest independent cruise port operator, today issues its unaudited results for the six months to 30 September 2023 (“Reporting Period”).
There are only really 2 key questions re this share -
To what extent is profitability increasing, from cruise ships activity post pandemic?
Can it survive given the huge debt burden?
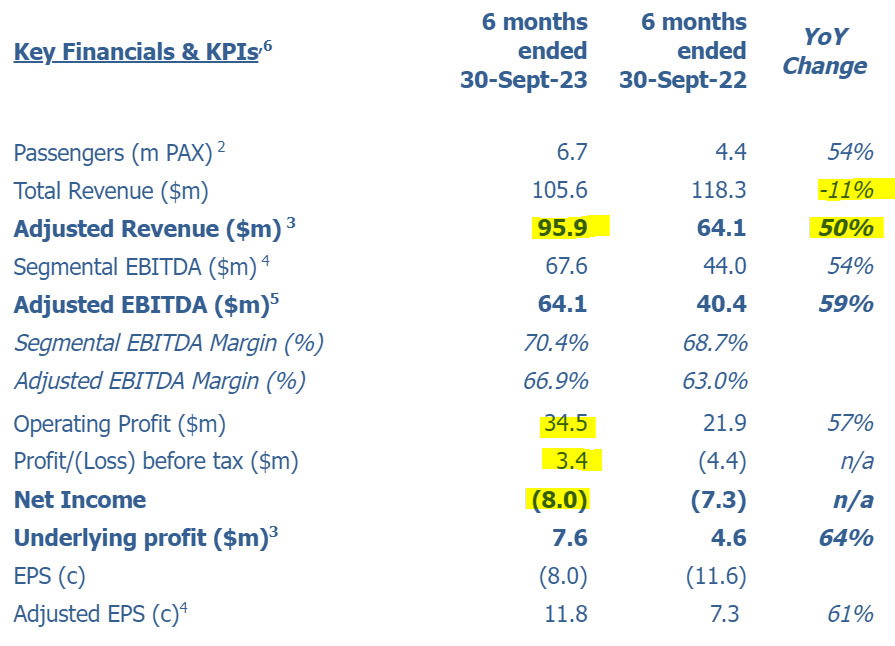
As you can see from the highlights table below, unusually it adjusts revenue heavily to show an adjusted 50% rise. However, the profit gradually disappears from the hefty EBITDA level, to a post-tax loss, given the heavy depreciation, and finance costs.
Net debt - even taking the most favourable number, net debt is gigantic, dwarfing the market cap, and has gone up considerably (note the accounts are in US dollars) -
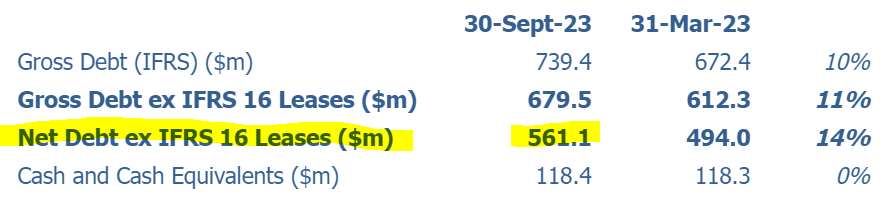
This snippet gives an idea of how this share would need very careful analysis of the structure, terms, and costs of the debt -
GPH issued USD 330 million of secured private placement notes (“Notes”) to insurance companies and long-term asset managers at a fixed coupon of 7.87% shortly before the end of the Reporting Period, mainly to refinance the 2021 Sixth Street loan. The Notes received an investment grade credit rating from two rating agencies and will fully amortize over 17 years, with a weighted average maturity of c13 years. Over 90% of GPH’s gross debt is now fixed and close to 85% of GPH’s gross debt (ex IFRS-16 Leases) is made up of the investment grade rated Notes and the ring-fenced project financed issuance for Nassau Cruise Port
Outlook - more growth is expected -
Demand for cruising remains exceptionally strong and our call reservations for calendar year 2024, are supportive of further significant growth in the business.
Balance sheet - at first sight, this looks dire. NAV of $25m includes $556m of intangible assets. However, looking at note 7, $543m of those intangible assets are rights to operate ports, which presumably GPH paid for, and are then amortised over long periods. Only $13m is goodwill.
So this looks like an unusual situation where the intangible assets are real, and have value. For that reason, I’d be inclined to leave the intangible assets in situ, rather than writing them off.
Overall then, I’d see NAV as being around $12m - negligible for the size of business.
Paul’s opinion - I’ve got my head around this now.
This business owns the rights to operate cruise ports. These rights were financed entirely with huge (and now much more expensive) debt.
All the operating profit is consumed in servicing the debt interest.
Therefore, equity is almost like a call option, on the business being able to increase profits such that equity holders might receive dividends again (which stopped in late 2019).
The trouble is, with the zero interest rate era apparently having now ended, the dynamics have all changed. Debt is now expensive, and the question is whether that will leave anything left for equity holders? If not, then arguably the equity is worth little to nothing.
Hence I’d treat this as a special situation, which would need much more detailed work (e.g. on debt covenants, maturities, etc), to determine if the equity is worth anything.
Just on a superficial look, I can see that the rising finance costs are consuming all the cashflow. Debt is rising because the company has been buying up more intangible asset rights, to further expand its port operations.
Unless you’ve done detailed work to understand all these issues properly, then this share would just be a high risk gamble. One for special situation experts, and mad punters only!
A further risk is that the major shareholder owns 58%.
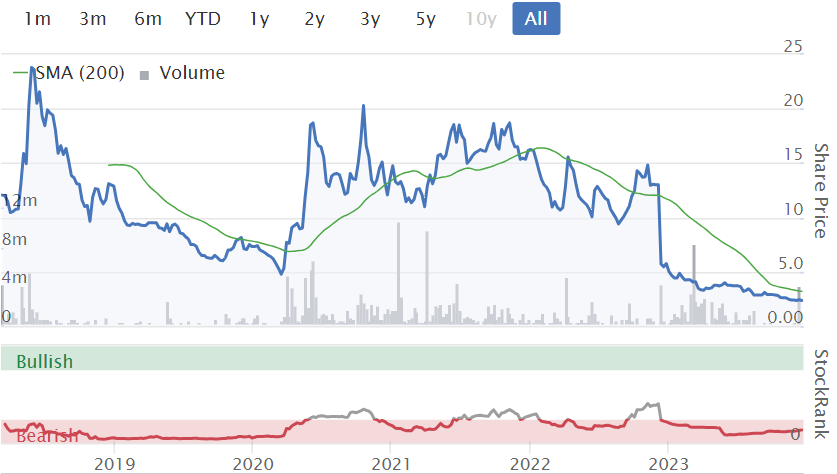
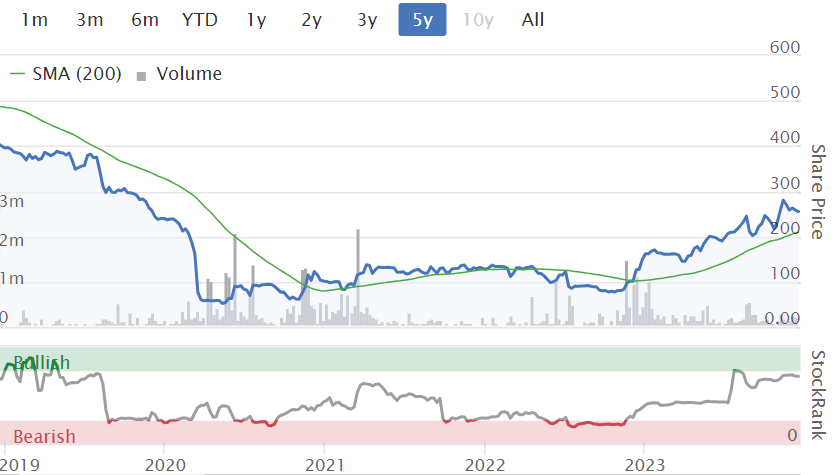
On the upside, the shares seem to be in an established up-trend -
Graham's Section:
One Media IP (LON:OMIP)
Share price: 5.4p (+3%)
Market cap: £12m
We look at this “digital media content provider” very rarely; it’s an investor in musical intellectual property rights “with proven, repeat income streams”.
Today’s update reports that its core business of digital music rights management has delivered in line with expectations for FY October 2023.
Besides the core business, there is also an anti-piracy software subsidiary, TCAT.
Key points:
Revenues £5.4m (up 5%)
Net revenues £3.6m (up 10%)
The definition of net revenues is total revenues minus “distribution charges, royalty costs and other costs”. Perhaps it makes sense to treat net revenues as the real top-line number, rather than gross revenues?
Continuing:
EBITDA £1.4m (last year: £1.8m)
Cash £1.2m (last year: £2.2m), reflecting the strategy to allocate resources towards the software subsidiary TCAT.
CEO comment doesn’t add too much:
These numbers are very much in line with our expectations, notably the continued growth of our music rights management business and the strategy that we set out during the course of this year to reinvest into the future potential of TCAT, our proprietary anti-piracy software tool.
Graham’s view
I’m reluctant to take any stance on this one, as it strikes me that OMIP’s software subsidiary is likely to be at an early stage in its development (considering how small OMIP’s total revenues are, and that TCAT is only a fraction of this). I don’t take any joy in being negative on companies purely because they are small and starting out.
However, if I had to choose a positive or negative stance, I’d probably choose a negative one. It remains true that most early-stage software ventures don’t work out. Meanwhile, OMIP’s management’s decision to invest heavily in software suggests perhaps a lack of excitement around the core business. OMIP has never generated sufficient profits to justify a stock market listing, which itself brings additional delisting risk for investors.
I’ll take a neutral stance on these shares for now. Hopefully they can keep losses low enough to avoid diluting shareholders too heavily over the next couple of years, and their investment in software will be richly rewarded. Be warned, though: the general trajectory here is for the share count to increase.
Cavendish Financial (LON:CAV)
Share price: 8.9p (+5%)
Market cap: £32m
This Cenkos-Finncap combination now has two joint CEOs. This is how they begin these interim results:
"We are delighted with the progress our teams have made in the short time since the merger in September. Careful planning enabled rapid business integration, unlocking £7m of cost synergies, more quickly than we originally forecast.
We are already winning clients and have executed over 20 transactions across all divisions since coming together. Despite the significant one-off costs of merger, our cash balance had risen to £17m on 30 November…
Bear in mind that the market cap here is currently only £32m; to have £17m of cash leaves an enterprise value of only £15m. And then we have £7m of synergies. I’m not sure if I’ve ever seen a company trading at only 2x synergies before! On its face, this is a very, very cheap valuation.
There must be a catch, and the catch is that the company is most likely loss-making, for now. As readers will know, sentiment in UK small-caps is on the floor (particularly for AIM). After the merger, Cavendish is now “the clear no. 1 AIM adviser with over 200 retained corporate clients”.
With Cenkos and finnCap no longer competing with each other, the new combined entity should be, in their own words, “well positioned to benefit from improving market conditions when they come”. In a bull market with regular IPOs and more active trading, I think we can expect great things from Cavendish. But of course nobody knows when that might happen - is 2024 too soon? 2025? 2026?
H1 numbers - these are for finnCap alone from April 2023 until September 7th, the date of the merger.
Then, until September 30th, they include Cenkos.
The adjusted pre-tax loss is £3.6m.
Outlook is relevant for all of us touched by conditions in the market. The key takeaway is that the situation remains difficult for the time being.
I’ve highlighted the part most relevant for investors in Cavendish:
The current interest rate upcycle appears to be nearing completion, but inflationary pressures, although reduced, remain a risk. With relatively higher yields available to investors on cash deposits we continue to see a drag on market demand for UK growth equity. This has continued to adversely impact equity transactions and trading, but private and public M&A activity remains resilient. The breadth of the service offering was a key driver for the merger, putting us in a strong position to weather market conditions. Post-merger enhancements in winning and executing business allied to a tentative pick up of the markets in the last three months has enabled us to get off to a good start in the second half. We look forward to building on this momentum, underpinned by a good pipeline, lower overheads and a strong cash position.
Graham’s view
The key point for me is the £7m of synergies. Here is the company’s description of its cost control achievements:
Merger related advisory and severance costs are materially behind us. Most of the targeted £7m reduction in annualised operating costs, from co-locating and eliminating duplicate roles and support services, has already been achieved.
We are now focused on firmwide cost controls, automation and outsourcing to further reduce our cost base.
So when (if?) revenues recover, we should see enormous operating leverage: the combined revenues of finnCap and Cenkos, but with £7m fewer operating expenses attached to this.
As for balance sheet support, tangible net assets as of Sep 30th were £26m, including cash of £12m. We already know that a flurry of deals in October and November pushed that up to £17m. These are significant numbers given the market cap.
Given all of the above, I’m going to have to stay positive on this one as a highly geared recovery play on the AIM market. If/when sentiment in AIM becomes positive once again, I would expect a huge pop in financial performance here. When that happens, maybe the share price can start to reflect a sunnier attitude.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

82 comments
Anyone follow Lendinvest (LON:LINV) and have any views, short term and longer term, they're willing to share?They listed fairly recently.Their update today was indecipherable for me personally (the detail anyway).I'm keeping an eye on them as they seem to me to be in a similar area of business as Paragon Banking (LON:PAG, which has ten bagged from all time lows since the GFC.I might be way off base though as banking and lending companies reports are difficult for me to start getting to grips with admittedly.Can anyone lend a hand?
Kin and Carta (LON:KCT) Counter bid of 130p by BC partners recommended by management 20 mins before close, cheeky!
For me anything below 150p for Kin and Carta (LON:KCT) is a bit of a steal so I am hoping for a bit more juice from a bidding war. Got caught out badly on this one having ridden it to 310p only to give back all the gains. I’m about flat on capital but irritated with myself. Should have sold when CEO sold for “tax planning” purposes at 300p and then scarpered soon after. That was a clear top.
Writing on the Small Cap Value Report (Wed 11 Oct 2023) Graham reported that the homebuilder and developer Watkin Jones (LON:WJG) shares were down by 67% year-to-date, and down by 83% over five years (33p at time of writing). As reported at that time WJG qualified for Benjamin Graham Deep Value Checklist(Value Investing), and this still applies at the current price of 52.4p. Graham also commented that "...as we’ve previously observed, cyclical companies often look cheap when they are expensive, and then they look expensive when they are cheap." An Intermediate-Term Bullish signal generated on 7 Dec 2023 with an intermediate target price of 68 - 72p has encouraged me to invest in Watkin Jones (LON:WJG) today. I sold my Mercia Asset Management (LON:MERC) to fund the purchase. Using Graham's words, "one for the bottom drawer, perhaps?"
Bottom drawered a few when Graham last did them on here as a potential reverse interest rate play hopefully someday..!
What sort of market is this? On IGG there are shares such as Warpaint London (LON:W7L) you can buy but can't sell, there are others such as Bloomsbury Publishing (LON:BMY) prices are outside of the spread.
The platform is so slow, as if it is going to crash.
Is this just on IG group (LON:IGG)? There have been issues with AIM stocks recently as well.
Everything's fine on hargreaves and jarvis (x-o) today.I've made a few trades.Although you're correct, there were outages reported in the FT on the smallcap exchange in the last few months.Occassionally i do get no trade platform feedback but generally on tidlers, sub 10 million, or during periods of volatility or someone more favoured wanting to sell i'm assuming.
Thanks. IGG platform is back to normal now.
Focusrite (LON:TUNE) I hold.
Small acquisition this morning of Sheriff Technology Limited (trading as OutBoard) up to £3.57m including earn out based on year ending Dec 24. Share price has responded very positively (out of proportion to the news?). Expected to be earnings enhancing. Operating under two sub-brands-TiMax and OutBoard-their products are vital for professionals in the audiovisual industry, particularly in live performances, event management, and the rapidly expanding sector of immersive sound experiences. Tim Carroll said:
"The acquisition of OutBoard represents another strategic expansion within our Audio Reproduction business, enhancing our product range and market reach. OutBoard's innovative products, such as TiMax spatial audio and show control, align perfectly with our mission to deliver exceptional audio experiences within live environments. We are looking forward to integrating OutBoard's technologies and exploring new opportunities in this segment of the rapidly evolving audio industry."
Nice little rise on the back of that news
I've been heavily focused this year on US tech where valuations are getting quite tasty - this being the only sector that has shown proper growth this year. Tech outperformance may continue while subdued growth is anticipated but, once it is expected that earnings will bounce back more broadly, I sense that a rotation out of relatively expensive tech is inevitable. Consequently I've been researching and taking positions in decent quality, high beta cyclicals, the highest quality of which I entered earlier this year near the lows, the other half more recently, they having stayed lower for longer. I do not include in this list longer term holdings like Somero Enterprises (LON:SOM) Volex (LON:VLX) or my collection of high quality US and European Industrials, like Atlas Copco AB (STO:ATCO B), Schneider Electric SE (EPA:SU) and Eaton (NYQ:ETN), which have already re-rated.
Of course, UK mid-caps are a fertile hunting ground for cyclicals and here is my selection of high beta, rotation-friendly, good quality cyclicals, mostly UK-listed, which I have entered in 2023:
Earlier this year
Geberit AG (SWX:GEBN)
Kingspan (ISE:KRX)
Genuit (LON:GEN)
Advanced Drainage Systems (NYQ:WMS)
Aptiv (NYQ:APTV)
Volution (LON:FAN)
Howden Joinery (LON:HWDN)
RS (LON:RS1)
Robert Walters (LON:RWA) (SThree (LON:STEM) is a long term hold)
Recent
Brickability (LON:BRCK)
Headlam (LON:HEAD)
Luceco (LON:LUCE)
VP (LON:VP.)
Porvair (LON:PRV)
This week I've been researching PayPoint (LON:PAY), of which I know there are some fans here. I see tremendous operating numbers and, should growth expectations be met, the shares are clearly great value for their cash flows. The question I'm asking those who know the company better is whether they believe the market will ever re-rate the shares back to a double digit p/e, or will the ex-growth valuation stick, making this an income play only? And if the former, on what grounds? But please without using the phrase "it's an operating system for convenience stores" ;-)
Also delighted to hear recommendations outside of miners, real estate, oil and gas or financials for other, high quality rotation plays. Wynnstay (LON:WYN) is on my list already at a discount to NAV. And I'm looking at Oxford Metrics (LON:OMG) (not cyclical - but cheap for a tech growth stock) but can't account for the forecast rise in revenues of 20% in FY26 (per Sharepad). Can anyone elaborate? Thanks
Robbie Burns bought PayPoint (LON:PAY) at one of his seminars recently.
Robbie Burns bought PayPoint (LON:PAY) at one of his seminars recently.
He did. But has a sell target of 530p which is not enough for me. I’d need to be confident of 40%, not 10%! But then we’re very different investors.
Only 515p target on his sheet but he may hold if momentum is strong.
I know you don't want to hear the "operating system" argument for PayPoint (LON:PAY) - which is the main reason why I invested...
But I'll give you another reason :) I suspect that, looking across Europe, there could be opportunities in some countries to expand into easily, where there is a lack of credible competition. However, this is medium term, long term... the company has never expressed any thoughts of international expansion so far.
(I hold in the Boon Fund)
Thanks for your thoughts. I did a lot of research in the last few days. I don’t see the PayPoint (LON:PAY) customer base under threat, which is good. My main issue is that what could be called the “operating system” strategy might also be described as a scattergun initiative to seek growth in areas adjacent to their declining core. I’m deterred by the sheer number of revenue streams. It feels a bit desperate. That said, this is a cracking income share on an attractive valuation, although it’s capital gains I’m looking for.
PayPoint (LON:PAY) did have a forage into Romania in the past. Cannot remember the exact reasons and drivers of it without digging back (I suspect it was an acquisition that landed them there but not sure if was a desire to be in Romania or whether that was a side effect). Anyway, they reversed out of there a few years back
I hold £PAY. The black cloud hanging over it is the decline in people paying their gas bill etc. at the local corner shop, which is true. However, they've not got much credit from the market for all the effort they've put into tranistioning away from this as a major source of income. I've no idea when they'll re-rate but have been topping up over the last 12 months in the hope that one day Mr Market wakes up and looks at them differently.
PayPoint (LON:PAY) - I exited breakeven after a trip into the abyss a while back and I've not returned yet because amongst other things I'm a bit concerned about the following: https://www.cityam.com/paypoin...
The Liberum broker notes are suggesting that Love2shop and Parcels Digital will provide growth so I'm waiting to see how things go.
I'm a bit concerned about the following: https://www.cityam.com/paypoin...
Interesting find. Whilst an overhang, I do think these can cut both ways. It's a very clear indicator of Paypoint's dominant market position for one. And, for another, in my experience the market is usually quick to discount uncertainty. The market reaction, with shares up 25% within weeks of the news breaking, suggests a relaxed view.
Thanks Graham for the great write up on Cavendish Financial (LON:CAV. ). As I bought it a few weeks ago after the Cenkos/FinnCap merger I found all your comment today reassuring.
Too early to know whether the current AIM index bounce is just a longer than usual Santa rally or the real thing to be built on next year. If it’s the latter upside could as you say be substantial.
FTSE AIM index bottomed at 670p in late October and then was not only down 50% from Sept 2021 peak, but also nearly back to the 2020 covid low. It’s now up about 10% from that recent low at 744.
Cavendish Financial (LON:CAV) looks well worth locking away. It might be a while to wait….but fwiw isn’t there a good chance that the long bear run for AIM and so many quality small company shares has already ended?
I just averaged up a little in my SIPP, history tells us bear markets don't last forever and I think Cavendish have positioned themselves perfectly for when it does finally end. Cavendish Financial (LON:CAV)
and directors buying for a cherry on top https://newsfile.refinitiv.com...
Cavendish Financial (LON:CAV) You've done very well buying these a few weeks ago, if this pulls back to 9p I am going to buy as many as I can get my hands on. I think this is the perfect small cap market cyclical play and with the added reassurance of huge cash pile and director buying today. Nice trade Ken Mitchell.
Always suspicious of fund managers talking their book…particularly the successful ones with significant assets. If he’s talking about a position he’s either got all he wants…OR he wants to create some liquidity to sell. The former is ‘good’ in that you get a reasonably full hold of coattails but the latter could be a painful experience. Double caution if a real tiddler being talked about.
Stocks held but not talked about are interesting…but could be good or bad reason.
Obviously it’s interesting to listen to insights where shared (tho it’s often shallow as not much will be shared with the hoi polloi).
Overall these interviews are investor catnip…in this case by both the interviewee and interviewer…make sure to ask yourself why they want to tickle your tummy.
mojo real out
Generally I agree though I think Mills is the exception.
He is not your typical fund manager and has a lot of his own cash in the game .
…maybe…
But lots of own cash in the game is even more incentive to play the crowd well/cunningly as it’s the pot not the pay cheque that counts.
Moving to other guy. Everyone loves Stan Druckenmiller and view is to listen carefully to what he says and sort of follow his lead. But he’s not a free ride and again wise to assume he’s talking to juice or place his positions (the more you manage relative to underlying liquidity the more it will be latter).
I listen and try to think why the opposite is true. I’m happier (if lonely!) when I disagree.
I think you are definitely off piste with Christopher Mills (and Richard Staveley for that matter)
What is of course key is to listen and use as part of your DYOR .
Their fundamental analysis and level of detail shared in their investment companies I have always found to be both exceptional but open.
Listen to Mills on Hostmore he admits to paying too much and isn’t sure , he certainly isn’t pumping and dumping his dross .
Anyway I’m biased as I ended up with Crestchic following the Mills entry and that was never pump and dump
I never blindly follow any tips or fund managers but I l would say there are 4 worth listening to and following .
Mills is one of the 4
I think you are saying you agree with me but not my universal cynicism .
I’ve got nothing against Mills or Staveley (spoke to latter in bit of detail on a few stocks at Mello - nice guy, v smart, driven etc - happy to invest in his fund and even happier if he chooses one of my stocks AFTER I’m in!). I will just always choose to fade what they say publicly and it’s reasonable to assume (or a good personal safety mechanism at least) that if they are talking then they are nearer to selling than buying
They don't usually disclose stocks they are building positions in, until after they have got their fill, as it could affect the price. Yes good to hold shares and then they start talking about them, same with people like Robbie Burns who has quite a following.
"Always suspicious of fund managers talking their book"
Agree with mojo. Nobody out there (including myself) is so generous as to put money in others' pockets free of charge.
FM interviews can be useful but always got to be careful and not follow in blindly.
I'm interested the Fund managers performance , it is surprising how poor some of these funds have performed, over the last 5 years, They often talk a good game but many don't outperform the market.
l would like to see that shown on every interview.
Fund managers talk are interesting. I look at their holdings and it looks very nice, exactly what I like to have. I look at their performance and it is not very good. The reason ? Their high charges with lots of hidden charges.
The best fund managers are Ourselves!
...and price tells a more honest narrative than devious humans...right? So less room to be a bit cheeky as trader/technician. Not that I am either! (I self identify as a long term orthogonalist)
As with company management, I would be more inclined to trust a fund manager who largely keeps their head down rather than one who does extensive "investor relations". We all over estimate our ability to judge character and these people are master influencers. The reality is that as private investors we are competing with fund managers and therefore our interests are not aligned.
Matthew
I don’t that is always true
Especially with the AIM small caps .
Example titon I held 3% , Rockwood held circa 20.
I knew the catalysts that are needed and so did Rockwood / Harwood .
The small cap market is so thinly traded and if a turnaround plan is clearly needed incumbent management will not budge until they get a big shove .
Titon was unusual but absolutely I was totally aligned with Harwood .
In the end I sold out because I didn’t think the incumbents would be gone so quickly .
These are exceptional times with crazy low valuations and virtually no liquidity and a lot of clear turnarounds that shareholders need to force the pace .
That’s what to keep an eye on .
Absolutely!
No sleight on Mills but he talks to us quite often as well as trading in similar names to many on this board. He’s got quite modest need to sell his fund(s) to us (given success!)…but maybe he’s selling something else?!
And note, Mills is often not a friend of the PI as he’s been known to take private when it suits him or it’s the only avenue to getting his money back. Re Staveley his position in RM (LON:RM.) is interesting and I believe his aim to exit thro a sort of public market event driven strategy (no I don’t mean a sale necessarily) is genuine…but if stuff gets stickier for RM it’s conceivable he could want to take private and bash things about a bit (…and he’d definitely not want to overpay PIs for the privilege)
Exactly, look at Harwood / Mills past record with small companies.
Its good validation that there is hidden value in the shares, when they decide to invest.
But when they are already invested, they don't always push for things that are in PI best interests. Look at RM (LON:RM.) and Fulcrum Utility Services (LON:FCRM^J23) and Appreciate (LON:APP^C23) and Flowtech Fluidpower (LON:FLO) and Seraphine (LON:BUMP^D23).
In the case of Appreciate and Seraphine - yes, they were taken over with nice premiums, but probably quite a bit left on the table.
I don't agree Mojo. You have to know your Fund Manager. Some have terrific turnover in their funds but honestly they wouldn't be trading small cap cannot get the liquidity. Mills size in many of the stocks he gets involved in would preempt him trying to ramp a stock unless a cap raise was due. He is in for the outcome in many cases. As with all things investment you have to watch carefully.
Yes...but.
Have a look at the equity issuance out of the blocklisting facility of the Mills/Stavely closed end vehicles after they've been talking at conferences or PI gatherings....
I count 4 in December for Rockwood?
Yes it may be part of the discount/premium management, and it is perfectly legitimate, but just because they are closed-end doesn't mean they won't enagage in a bit of PR to grow their NAV.
As with all asset managers, at some point they outgrow their niche. Something you generally discover with the benefit of hindsight!
I don't agree Camtab ;)
1) His size in stock makes a 'ramp' more desirable/tempting to fluff his exit - I don't plan on going back and auditing his past interviews and comments but I suspect you will find positions that he has sold not long after mentioning. As he has a keen following (like some others in the small/micro area) all he needs to do his mention lightly and he can get a response...I'm positive he doesn't push hard and then pull the rug so not suggesting great unseemiliness...but a enough to hurt some PI positioning (and if they have followed rather than done work likely shake them out for loss). Just doing his job for customers and himself.
2) When Mills gets it wrong and/or decides that value maximisation is in private market then he can make headaches for PIs as the price PIs will realise for their common holding will not be optimal. This is still a downside of his publicity
I don't have an axe to grind here. Merely stating what I think is obvious and what PIs should think about....you are all free to ignore me just as you are free to ignore the much more illustrious Mr Mills etc
I'm going stop making counterpoints now to people unless something is specifically addressed to me as a Q etc.
TBC 100%! Follow the tips and holdings of all fund managers and, particularly tipsters and promoters (you know who you are!) with great care. Their interests are at best temporarily aligned with you and at worst unaligned or even opposed. This is particularly the case for profile people tipping small/micro cap stocks in here or X....I'd say crudely anything sub £1bn beware.
I always enjoy listening to fund managers talking…because I’m an investment nerd…but I do think there’s some possibility that they might…potentially/always..want to achieve something other than third party private investors getting wealthier independently
Mojo, you asked for my views on our meeting yesterday with Arix Bioscience (LON:ARIX) chief exec.
Please drop me an emailmessage on Richard at mutlow.net and I am happy to share my thoughts.
Ricardow
I hear what you're saying about fund managers talking their own books in interviews, but there's another angle on it - I see them as sales pitches, where the fund manager talks about their process, with the aim being to engage with an audience who like their approach, and then might invest some funds with the manager doing the interview. So it's about demonstrating how clever they are, and attracting fund inflows, in my view.
Macro: what are the likely market impacts from the latest disruption to the shipping route through the Suez Canal? Lessons from the March 2021 blockage by the Ever Given grounding?
"what are the likely market impacts from the latest disruption to the shipping route through the Suez Canal?"
The main lesson I took from the Ever Given was that these impacts hit supply chains unpredictably and they then take a long time to recover. Retailers importing from the Far East were directly affected, all kinds of manufacturers with global supply chains, especially automotive (aerospace not so much) and some commodities. Last time there was also the global shortage of semiconductors affecting supply chains at the same time.
What you don't seem to get is an automatic jump in the price of gold, or oil. I guess (a) the US is such a major oil producer now (b) developed economies are less dependent on oil and gas than they once were and (c) previous supply chain shocks have created resilience as market participants found other ways to get their goods through.
So in summary I would say selected retailers and manufacturers will suffer and it's hard to predict who they are - the smaller the company the fewer options they are likely to have. If you take automotive, shortage of vehicles tends if anything to be good for motor dealers and companies such as Redde Northgate (LON:REDD) (I hold) so I wouldn't be concerned there.
What are your thoughts FREng?
I'm nervous about any company that operates a just-in-time supply chain from the Far East, or that depends on cheap, timely retail goods from there. Taiwan semiconductors may run short. The oil and LNG prices seems likely to rise unless the route reopens. It all makes me less likely to be fully invested!
One company that will be hit is Shoe Zone (LON:SHOE) - they suffered during the last shipping crisis, because their products are low-value, takes up volume, and largely from China.
Another might be Norcros (LON:NXR) as they source loads from China I believe.
Christopher Mills on Vox
Posh bloke talking to brummy bloke we’ll worth a listen.
Highlights are
Pendragon - special situation unfolding with residual business he thinks actually quite valuable .
Sale going through leaves a residual with water more than 7p current value .
But tax treatment on sale means only suitable for isa / pension.
All seems to make perfect sense looks a no brainer
Animalcare, EKF and TC ICAP are other ones that I think are good will add to “starter for 10 list”
Rest of companies a bit out of my circle of competence so not for me .
hi planetx
There doesn't appear to be a recent interview with Christopher Mills on the Vox website.
Are you referring to an older interview? If not, could you please post the link?
Thanks
Snazzy
I listed to it this morning. It came though on apple podcasts>Vox.
I think it is this one - on stockopedia.
https://www.stockopedia.com/co...
SPI was a stand out for me.
It is the only quoted private clinics in this country. Mills like the company and he expects it to be doing much better in the next two years.
Black Country bloke I believe Planet X.
Done some research on Plexus Holdings (LON:POS)
Looking through the financial reports on the plexus website - Page 70 of the annual report.
Section 19 states.
The increase in deferred income over the prior year is due to milestone payments on the significant contract announced in March 2023.The advanced payments are on a short-term rental contract. Revenues will be
recognised when the equipment the rental relates to is deployed, which is expected to be in quarter three of following financial year.
So I am assuming the 4.5mil difference in the balance is a long term contract deployed in Jan - March 2024. This to me means the contract duration is either 6months or 3 months (likely a 3 month), so 1.5mil per month.
If thats the case and the balance of the contract is long term, an extension of 12 months would be 18million revenue when you break down the numbers, Any thoughts? Would love some feedback on anyone’s thoughts on this. Still learning!
Aint nothing going on but the rent -Gwen Guthrie - shoobie doobie, I dodge responsibility. Hiya!
Love of a lifetime! Chaka Khan, whoop I have this effect on people.
Would welcome any thoughts on
You do know OPG Power Ventures (LON:OPG) is Indian based coal power stations? Probably the price coal is a significant risk. Coal prices are low at the moment.
Cracking contract win Filtronic (LON:FTC) . I am a huge fan and recommend anyone interested watch the interview in stockopedia that Paul Hill did with Richard Staveley of Rockwood Strategic (LON:RKW) to understand the potential of Filtronic. Chart breaking out beautifully and it is a company that has turned around and is making big progress in lucrative niches under new management. I think it will be a takeover target next year.
Filtronic (LON:FTC) I must admit that I wasn't expecting much of a movement on this announcement as the SP rose ahead of the RNS (insider trading? surely not) and I assumed something might be announced. So, pleasantly surprised with this morning's rise and hoping it will stick. (Long term holder here)
TIME to be "at least in line with recently upgraded market guidance". Suggests another beat on the way. I hold a small position but think this could be a solid stock next year given the low rating and nice trend.
Time Finance (LON:TIME) I hold, noticed a comment on lse this morning which has validity and may explain the dip:
"Arrears remain at 6%; lending book increased by £18.4m, so the arrears have increased by £1.1m but overall profit is up by only £0.7m. To me an increase in arrears of £1.1m bringing only an increase in profit of £0.7m is not a good tradeoff as the vulnerability to bad debts has
increased too much.
Hopefully this will be explained in some detail at the Interim Results meeting on 25th Jan 2024."
Re Time Finance (LON:TIME) …this is a misreading imo…tax and interest rate increases are better explainers (and are somewhat a one off step increase in terms of impact to profit trend relative to revenue). In addition, its typical for banks to find profits fall once interest rate increases stop as what they pay deposits catches up with what they charge for credit and/or what they receive from interest bearing securities on balance sheet ie net interest margin declines. This is a significant reason for cautious 2024 outlook for U.K. high street banks (not just economic concerns).
Obviously Time isn’t a bank but a similar effect occurs whereby by rate rises impact their cost of funds and they can’t for competitive reasons pass on the full increase for credit they charge…this will be particularly true if they are taking decision to increase credit quality of lending as economic outlook is challenged (sensible banking practice AND Time have shown themselves to be good at risk mgt over time). So there’s a potential double hit to profit there (again it’s more a one-off adjustment). The way Time fund their lending and build book over time means there was a bit of lag in seeing the rate rises pass thro. And if they have improved credit quality a little bit (which is implicit in more asset backed lending) then that protects future profitability if the economy is rough.
But yes…interim will clarify. IMO the situation looks strong still
* re Time Finance (LON:TIME) - choosing to move up credit quality reduces net margin at interest received reduces but funding stays the same
You can't correlate Arrears ££ to PBT ££ when looking at Time Finance (LON:TIME)
Arrears is not a crystallised loss - they may be recoverable. It is just one signal of the credit quality of the book.
When there is a crystallised loss, that is recognised in the P&L as a "net credit loss charge" - see the last final results. This is BEFORE the PBT number.
So the HY PBT of £2.7m, an increase of 35% YoY, is AFTER taking the hits from bad debt.
Now, the key risk of course is if that 6%, for the current lending book, goes up. Then more and more £ will be charged to the P&L before bad debt. For example, it only takes going from 6% to 8% in arrears (and the subsequent impact on credit losses) to wipe out £4m PBT a year, approximately.
But this is the same for any lending institution out there.
The bull case for Time Finance is that they have a business model that works; it is generating a decent return, they have managed to keep credit quality high (despite all the "struggles" that SMEs are going through in 2022 and 2023), and if they manage to unlock more funding sources for lending, they can rapidly scale up their lending book and therefore profits. It is a very operationally geared play in progress. And that is why I'm invested.
(I hold in the Boon Fund)
My morning smallcap tweet: SONG valuations out of tune.
Feedback (LON:FDBK) Filtronic (LON:FTC) Hipgnosis Songs Fund (LON:SONG) Superdry (LON:SDRY) ENGAGE XR Holdings (LON:EXR) Tristel (LON:TSTL), Time Finance (LON:TIME), Netcall (LON:NET), Cyanconnode Holdings (LON:CYAN), De La Rue (LON:DLAR) PCI- PAL (LON:PCIP)
◄Feedback (FDBK)► wins £300k grant. Trading in line [SP=74 Cap=10m]
◄Filtronic (FTC)► wins £4.5m with product qualification starting in Jan and delivery of final production units over 12 mths starting Q4 CY2024. [SP=19.5 Cap=42m]
◄Hipgnosis (SONG)► unsure what its catalogue is worth after independent valuation was much higher than valuation implied by proposed and recent transactions in the sector, in particular, the proposed sale of assets to Hipgnosis Songs Capital. Additional advice from Hipgnosis Song Management Ltd, its investment adviser, was heavily caveated so is delaying H1 results. [SP=69 Cap=840m]
◄Superdry (SDRY)► warns FY24 rev and profit significantly below management exp. H1 rev retail sales down 13% and wholesale, 41% partly due to exiting US wholesale. Recent 6 weeks down 6% LFL. [SP=41.8 Cap=41m]
◄Engage XR (EXR)► warns FY-Dec rev only €3.6-3.8m due to some contracts slipping into FY24 and also no rev from Lenovo VRX all-in-one virtual reality headset until FY24 CEO "can see a clear path to profitability". WIth his VR headset on I guess. "We now have a clear and visible customer base who are growing with us." Airlines have the same problem. [SP=2.62 Cap=14m]
◄Tristel (TSTL)► AGM stmt - guides H1-Dec rev up 18% with gross margin in line. Medium-term outlook remains unchanged. So is H1 rev in line? [SP=448 Cap=212m]
[edit]
◄PCI-PAL (PCIP) ► late yesterday (so it was in the public domain, hence SP rise) UK judge ruled that Sycurio can't appeal her patent ruling and awarded a substantial interim payment of costs. More later when the formal Form of Order is signed. I hold.
In line: TIME, NET, CYAN, DLAR
I wish I'd saved Mr. C's quips so we could run a "Quip of the Year" competition. 3 corkers today, my favourite is on EXR
For any holders of stocks linked to the airline industry: Despite waking up thinking I might need to ditch On Beach group (LON:OTB) due to last nights volcanic eruption. A quick scan of the internet confirms this eruption is very different to 2010 and it is expected to have no impact on the airline industry. For those who like their physical geography, it's due to the lack of a glacier this time around, so melt water isn't mixing with magma, which was the case in 2010 making it highly explosive and creating huge ash clouds.
Cant believe how much this stock has risen by in the last 3 months
It’s incredible, it must have had one of those non disclosable bid approaches that Paul hates .
Maybe, but it could just be a natural turn around after a couple of very good updates. It wasn't that long ago it was over £2.
More to do with the performance and very positive sounding outlook I think. This used to trade on quite a high p/e so the sharp increase is both a reflection of confidence in performance AND returning to a more typical p/e trading range.
IMHO the rise in On Beach group (LON:OTB) is a change of investor sentiment in three areas:
The bear case is such:
For me, the strong rise in the shareprice from sub-100p to now 170p+ is not a surprise. My fair value and exit target is around 240p.
(I hold in the Boon Fund)
The situation in the Red Sea might be more of a worry for oil prices and indeed more importantly wider problems for container deliveries with cargo having to go up the west coast of Africa as opposed to through the Suez canal. Back to 2021!
Hardly, 2021 was mainly about lockdowns, particularly in China. A 10 day shipping delay is nowhere near the same magnitude.
Probably referring to ,when the Suez canal was blocked for 6 days, that did cause quite a bit of disruption.
my biggest share. holding tight. trust pilot suggest their customer experiences are getting much better. fast truck service is a game changer i suppose last time i felt it when i was whizzing pass the security while there was at least an hour long waiting for the others, who wants to delay at an Airport when sunny blue beaches are in sight ! good luck to the holders
I would love Graham's take on Cavendish Financial (LON:CAV) first set of results as a merged entity. I see Cavendish as a geared play on improving market conditions so it could multi bag when equities and particularly IPO activity picks up again and in the mean time we need the share price to be supported by net assets. Cash is at £17m which is a decent chunk of the £30m market cap - net assets are listed at £39m but I am not sure what else they really 'own' given it's mostly a people business.
It sounds like market conditions have started to improve so this may now be in break even or profit territory which would be good against the current backdrop. I hold but bought Cenkos and Finncap (the original entities) far too early in the year so I am down heavily.
The new board member Mark Astaire looks a heavy hitter too Camden National (NSQ:CAC)
Cavendish Financial (LON:CAV) Yes this looks a bit of a steal (unless you think AIM is finished forever). Unfortunately impossible to build a position at these levels, can't get a quote in any sort of size. And now the Directors have been buying this will probably shoot up...
Surprisingly I can get a quote on Cavendish Financial (LON:CAV) for 50,000 shares on IGG. I have a small holding already, many in that sector look very cheap.
Morning all, I think Cavendish Financial (LON:CAV) looks nicely set up for the next bull market
Looking forward to reading Gresham's thoughts on today's update.