Small Cap Value Report (Tue 2 July 2024) - SHOE, SUP, KITW, MERC

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
These are the things we've got so far. I'm going to rush out a section on SHOE before 8am, and Graham's pondering doing some fund manager shares as catchups.
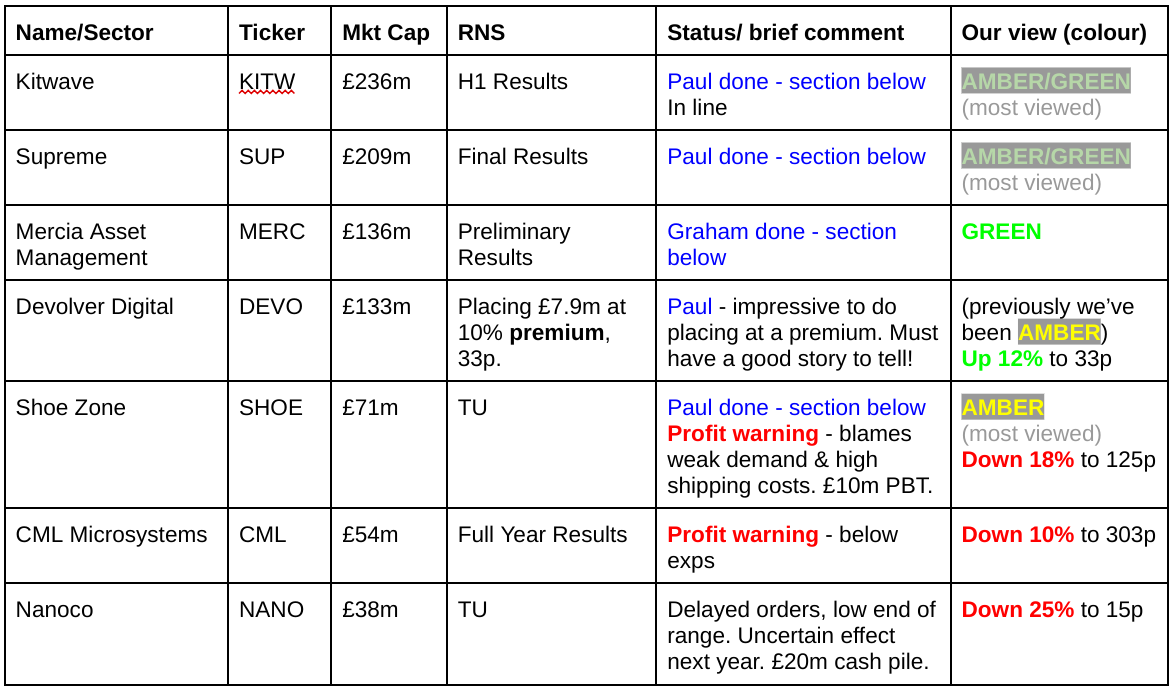
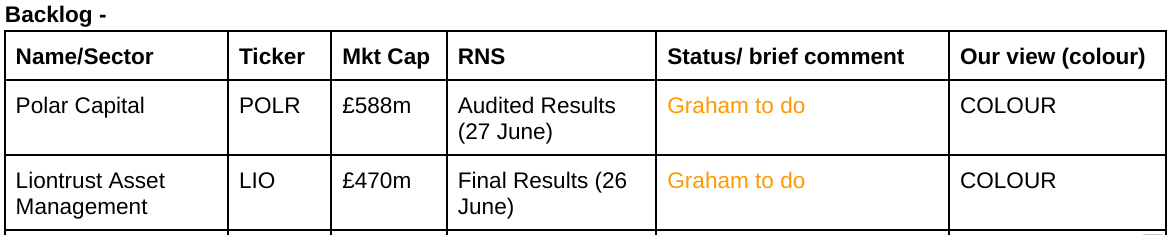
Summaries
Shoe Zone (LON:SHOE) - down 16% to 127p (£60m) - Trading Update [profit warning] - Paul - BLACK (pw) - AMBER on fundamentals
Another profit warning, blamed on higher sea freight costs, and subdued demand (Apr-Jun). Still forecast to be profitable in FY 9/2024, but forecast reduced from £13.8m to £10.0m adj PBT. Balance sheet is OK, so no solvency worries. Expect a nasty drop today, obviously.
Supreme (LON:SUP) - down 6% to 169p (£196m) - FY 3/2024 Results - Paul - AMBER/GREEN
Excellent results, and a PER still modest at c.8x - but I think it deserves a discount due to vaping producing almost 3/4 of the profits. Shares have had a great run up, so I'm moderating from green to AMBER/GREEN.
Kitwave (LON:KITW) - down 6% to 316p (£221m) - H1 Results - Paul - AMBER/GREEN
H1 results are a tad lacklustre, but it's sticking with FY 10/2024 forecasts for now. So I see some potential risk of an H2 profit miss. Balance sheet has a bit too much debt for my liking. That said, I do like the strategy of consolidating a fragmented market, and valuation looks more reasonable after recent falls.
Mercia Asset Management (LON:MERC) - up 6% to 32.9p (£140m) - Preliminary Results - Graham - GREEN
Continued progress as Mercia transitions from a direct investor to a manager of 3rd-party funds. Large mandates were won in FY 2024 and an acquisition in 2022 has also helped to grow and diversify the group. I remain positive here given the deep value on offer and the positive trading momentum.
Paul’s Section:
Shoe Zone (LON:SHOE)
down 16% to 127p (£60m) - Trading Update [profit warning] - Paul - BLACK (pw) - AMBER on fundamentals
Oh dear, I’m sorry to report another profit warning from this cheap Chinese shoes retailer. This might be the third or fourth PW this year?
This time it blames higher costs of sea freight, combined with lower demand than expected in April- June - blamed on unseasonable weather, which I don’t personally accept. People are just buying their shoes elsewhere, is my view - which is something that had begun to concern me last year, with the rise of the Shein/Temu Chinese competition.
What’s the damage? - last time guidance was given as £13.8m adj PBT for FY 9/2024.
This time SHOE guides it down significantly, to £10.0m - quite a hefty miss.
Zeus helpfully updates its spreadsheet & shares it with us - FY 9/2024 EPS is now 16.2p (previously 22.4p).
Zeus expects little recovery in FY 9/2025.
Valuation - with a series of profit warnings, surely the market might now factor in the possibility of a further deterioration in trading? For that reason I don’t suppose SHOE justifies a forward PER much above mid single digits. If we say PER 6x, then it’s only 97p share price.
A bit more generous at 8x, gives us 130p.
I suspect today might see a significant lurch down somewhere into that 97-130p range (writing this at 07:33)
Cyber security incident - was announced on 27/6/2024, but the impact is not expected to be financially material, “at this stage”.
Balance sheet - looks adequate when last reported at 30/3/2024. Although one amber flag is the level of inventories seems quite high.
Paul’s opinion - every time we look at SHOE, we comment on how cheap it looks. But I took us down from green to amber/green last time on a recent profit warning, due to unease that SHOE has changed from constantly beating forecasts, to now constantly missing them. So it’s difficult to avoid the impression that something fundamental is deteriorating at this business, it’s possibly not just one-offs in my view.
That said in the past SHOE has been adept at recovering from shocks like the pandemic, so maybe it’s just having a sluggish year due to not getting its product & pricing right?
The sea freight issue is something we’re already aware of, so I’m now worrying how many more companies are going to be also issuing profit warnings over this? We probably need to be cautious.
Unfortunately, I haven’t got much option other than to move SHOE down again, to just AMBER this time.
All is not lost though, as Zeus is forecasting divis will continue to be paid, 6.5p for this year (previous forecast 9.0p).
Profit should be rising, as SHOE’s strategy has been to close smaller shops, and open larger, more efficient big box shops. So again, I’m puzzled as to why we’re seeing performance worsen, even allowing for some tough macro factors (living wage rises, sea freight, etc). That should all be mopped up by increased sales at a healthy business, so something’s going wrong here I suspect.
Note that over ¾ of the shares are held by just 4 major shareholders, dominated by the founders. De-listing risk a possibility?
Personally I won’t be bottom fishing here just yet. Let’s see where the dust settles.
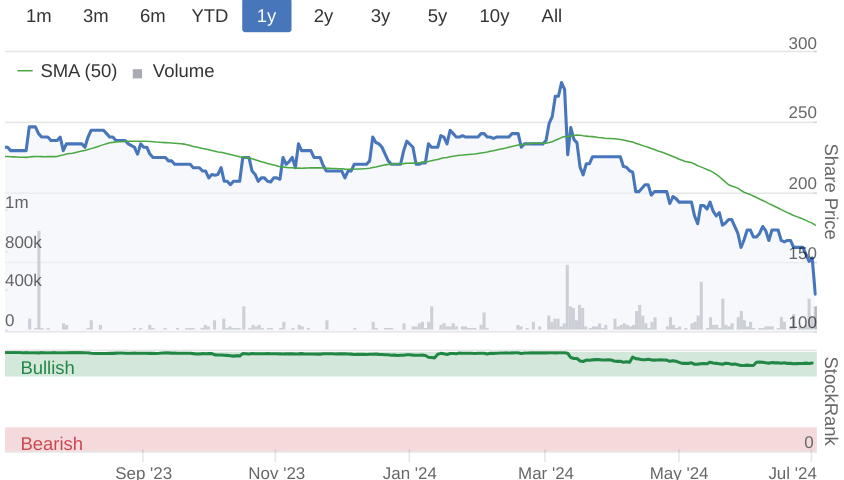
The sliders have slipped off this year -
Supreme (LON:SUP)
Down 6% to 169p (£196m) - FY 3/2024 Results - Paul - AMBER/GREEN
This is the vaping & other consumer products group. It starts off this announcement with an impressive list of achievements -
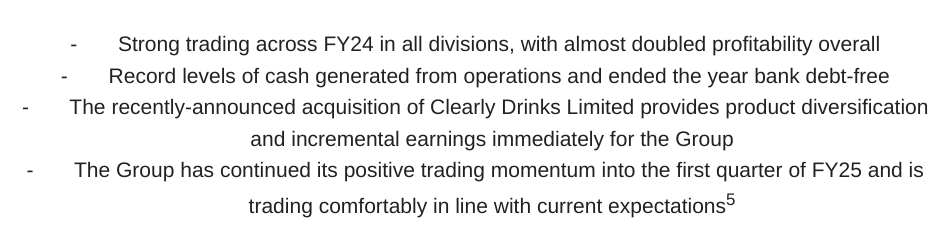
Some superb figures in the highlights table too -
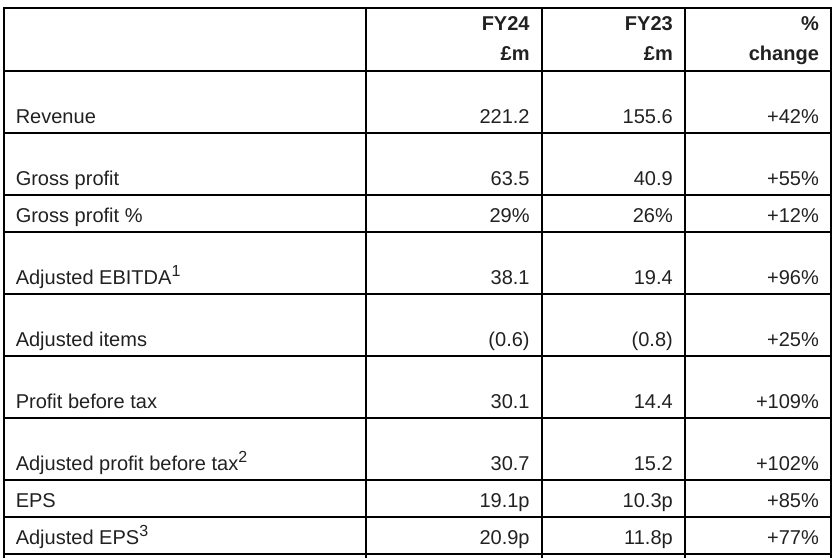
Adj EPS up 77% to 20.9p means at 169p SUP shares are on a PER of 8.1x - still cheap, despite a strong recent bull run.
Outlook - the main point says -
“Supreme forecasts FY25 to be another profitable and highly cash-generative year for the Group. Having made a positive start in Q1, the Group is trading comfortably in line with current market expectations5.”
5Analyst consensus immediately before this announcement for the year ending 31 March 2025 was revenue of £242 million and Adjusted EBITDA1 of £36.9 million
Annoying to see adj EBITDA quoted. As we can see from their highlights table, adj PBT was £7.4m (or 19%) lower than adj EBITDA.
Note also that the market expectations of £36.9m EBITDA for FY 3/2025 is below the actual £38.1m achieved in FY 3/2024, so this looks a soft target. Either that, or there’s no further growth expected from the large jump in profits in FY 3/2024.
This comment from management doesn’t suggest they’re planning for a flat, or declining year, so I imagine SUP is probably set to beat current forecasts (unless something unforeseen goes wrong) -
“FY24 has been a hugely successful period of growth for Supreme and I strongly believe that we remain firmly on track to maintain this impressive growth momentum in FY25 and beyond.”
How much profit comes from vaping? - this isn’t easy to work out, as note 4 (divisional analysis) only shows revenues and gross profits, which excludes overheads - as follows -
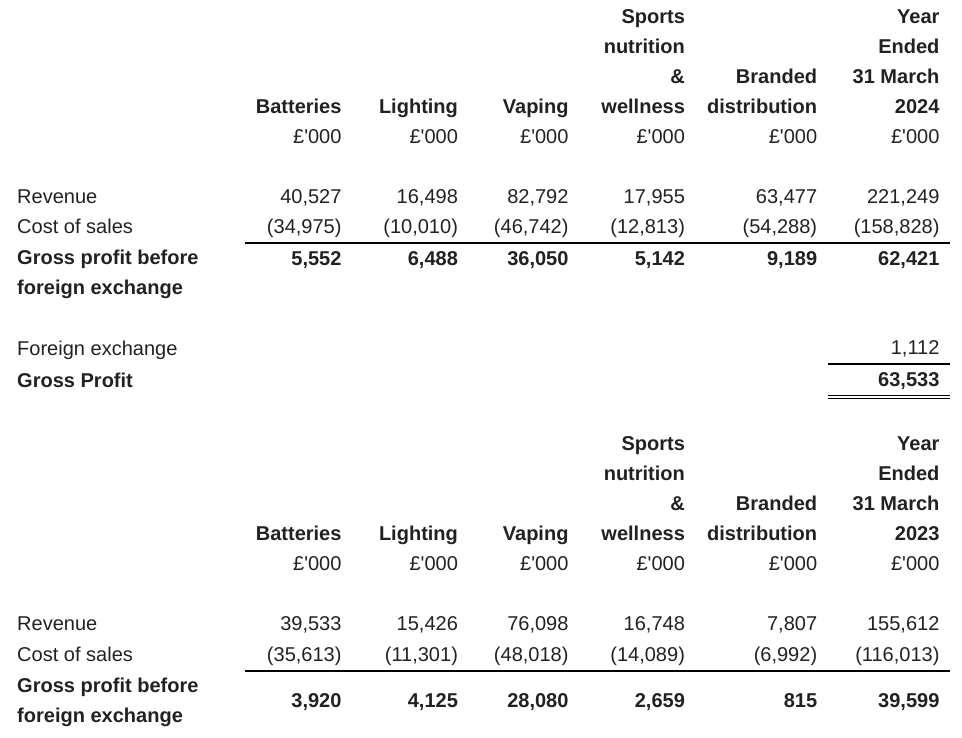
The above table shows that 58% of the group’s gross profit came from its vaping division in FY 3/2024.
However, what it calls “Branded distribution” is also vaping products! Combine those, and 72% of gross profit comes from vaping products. Hence the other products are a sideshow I would argue. Although to be fair, they’ve all shown nice growth.
I don’t know how overheads would be allocated to each division. It talks about being vertically integrated, so assuming it’s an even split, then operating profit for each division would be about half the gross profit numbers above.
I won’t go into all the detail about vaping, and the regulatory threats. SUP plays it all down, but I would want a hefty discount on this share valuation to allow for a potential bombshell on a future Govt say deciding that these products should only be sold on prescription as smoking cessation products, and not be on general sale to any adults. Or competitors seeing that it's a lucrative niche, and coming for some of SUP's market share.
The commentary also mentions Govt possibly imposing tax on vaping products, but I haven’t looked into that. Surely these things should be heavily taxed, to deter nicotine addiction?
We always get a heated debate when this company comes up, so I’ll leave that to readers - keep it clean please girls! ;-)
Balance sheet - is strong, £44m NTAV.
Cashflow statement - looks perfectly healthy to me, so there’s no doubt at all that SUP is a profitable & cash generative business.
Paul’s opinion - I can’t fault these numbers, they’re superb.
I suspect it might beat the FY 3/2025 forecasts too.
The crux with this share is how you view vaping, and the bumper profits SUP is making from it. FWIW my view is that I wouldn’t pay more than a PER of about 8x for a business that is so heavily dependent on one controversial product line.
If we assume c.20p EPS, with some potential upside on that maybe, then I think a share price c.160p sounds about right. That’s slightly below the current price of 169p, and given that SUP shares have had an excellent run up, I’m going to moderate from green to AMBER/GREEN.
Management seem shrewd at finding, and exploiting lucrative niches. So it will be interesting to see how the recent bottled water acquisition develops.
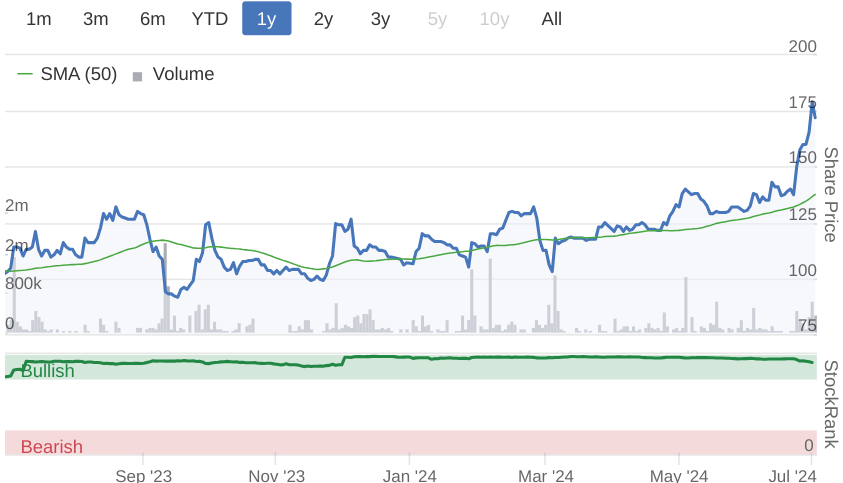
Some profit taking tends to happen in this market, after such a rise -
Kitwave (LON:KITW)
Down 6% to 316p (£221m) - H1 Results - Paul - AMBER/GREEN
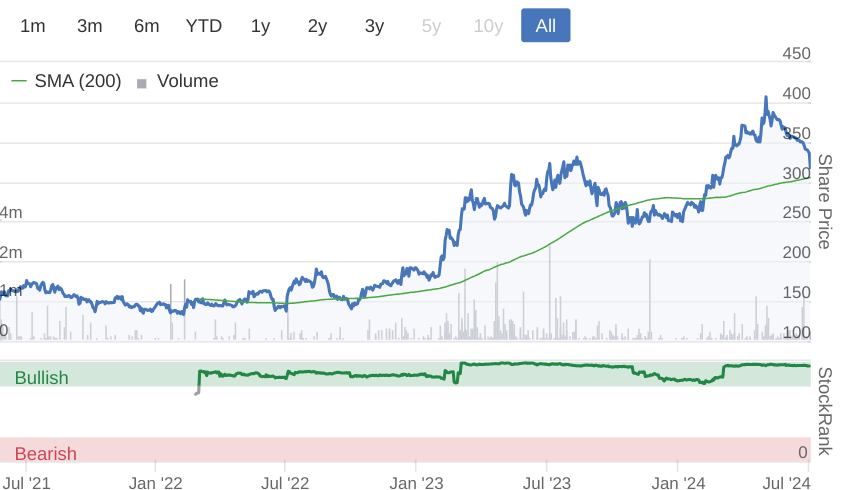
Gosh, quite a volatile share this one. It’s surprising how many small caps soared from autumn 2023 to April 2024, but have since given a lot of that move back. This market definitely feels like profit-taking is a sensible move after big rises, as a lot of them are not sticking.
Time for me to don my smart-ass hat, as checking back I see we suggested on 2/5/2024 that the rise to 407p was likely to turn into profit-taking after a 60% rise, hence a shift down here from green to AMBER/GREEN. With shares now down 22% from that recent peak, I’m wondering if this could be time for us to be buying a bargain thrown at us by someone else’s stop loss kicking in?! KITW is certainly a business that we like here at the SCVR, and we were previously green on it going back to July 2023, when Directors banked £3.3m-worth of shares, as a reminder.
On to today’s H1 results -
“Kitwave Group plc (AIM: KITW), the delivered wholesale business, is pleased to announce its unaudited interim results for the six months ended 30 April 2024 ("the period" or "H1 2024").”
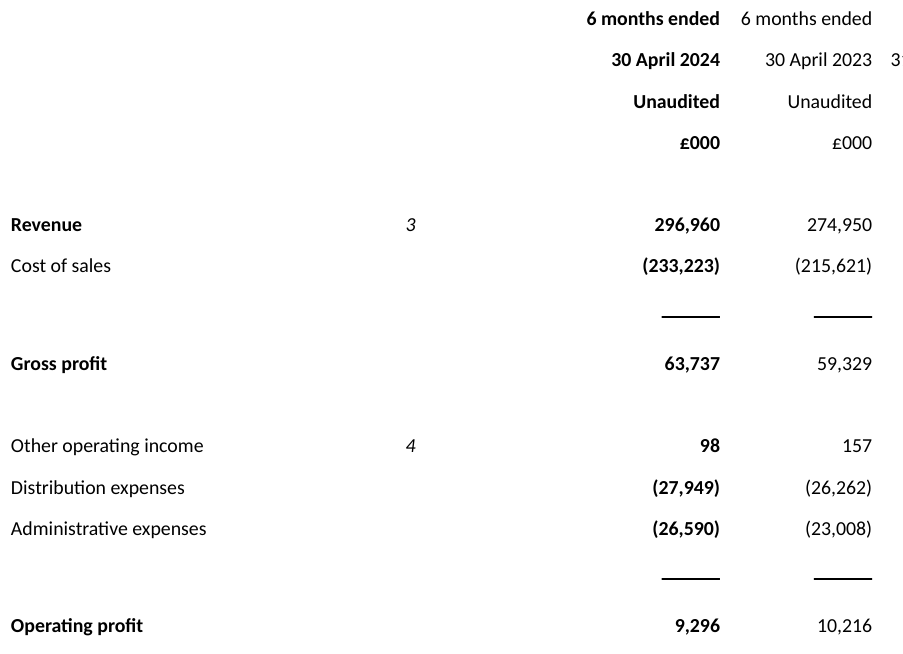
Not great is the quick version on these H1 results. As you can see below from this P&L excerpt, the increased revenue & gross profit wasn’t enough to absorb a larger increase in overheads, particularly administration costs -
Although in mitigation it does comment -
“Investment in the business has continued ahead of future potential growth opportunities, with operational and financial benefits being realised from H2 2024 onwards.”
Finance expenses are up, at a hefty £2.4m, thus eating up c. a quarter of operating profit to arrive at PBT of £6.9m, down 17% on H1 LY.
Seasonality - there was a heavy H2 weighting to profits last year, with H1 being about a third of FY 10/2023 PBT. I seem to recall this might be due to summer sales of drinks & ice creams being important, which fall into H2.
Balance sheet - is weakish, with only c.£7m NTAV, due to this being an acquisitive group (a good strategy, but it does cause the balance sheet to fill up with goodwill at the top, and rather more debt than I would like in the middle and bottom).
No cause for alarm, but personally I would like to see a brake on further acquisitions, and maybe reconsideration of the dividend policy.
Outlook - I’m starting to lean towards giving KITW the benefit of the doubt over these lacklustre H1 numbers -
"As noted in the pre-close trading update, operating profit for H1 2024 is slightly behind the prior year due to investment and lower levels of demand in the Group's Foodservice hospitality customer base. This, alongside the benefits of the increased investment in infrastructure and the inclusion of trade from Total Foodservice in H2 2024 will lead to the Company's annual financial performance having an increased second-half weighting.
"Despite the slight shortfall in operating profit in H1 2024 and the continued wet weather in May and early June, we expect to be in line with market expectations for the full year ending 31 October 2024."
Broker note - good old Canaccord update us helpfully. It's leaving FY 10/2024 forecast unchanged, at 29.9p adj EPS. That means a PER of 10.6x, although there could be some doubt over its ability to deliver the necessary large H2 weighting. Also, a low margin distributor is not likely to ever achieve or sustain a high rating.
Paul’s opinion - I’m much more comfortable with this share now the froth has come off from over 400p to not much above 300p, it’s more sensibly-priced now. Taking into account the debt, and the need for an H2 weighting to hit targets, it’s probably priced about right. That said, I like the strategy of using cashflows to buy up smaller competitors, thus consolidating a fragmented market. Lots of deals have been done over the years, so you hope they won't make any bad mistakes.
Overall, worth considering for deeper research I’d say, but I can’t see KITW as a compelling opportunity.
Even after the recent correction, it's still been an unusually successful float -
Graham’s Section:
Mercia Asset Management (LON:MERC)
Up 6% to 32.9p (£140m) - Preliminary Results - Graham - GREEN
Mercia Asset Management PLC (AIM: MERC), the proactive regionally focused, specialist alternative asset manager with c.£1.8billion of assets under management ("AuM"), is pleased to announce its preliminary results for the year ended 31 March 2024.
This was on my top ideas list for 2024 having already been on it for 2023 (sadly it did not contribute much in terms of share price performance in 2023).
Let’s see how it summarises its progress in FY March 2024.
The official numbers:
Revenue +17% to £30.4m
Pre-tax loss £8m after taking a £17m hit to the fair value of its direct investments.
Cash £47m, net assets £189m (I calculate tangible net assets as £153m).
Most importantly from the point of view of the growing fund management business, assets under management grew to £1.8 billion, up from £1.4 billion a year ago.
This includes both the company’s own capital and third-party funds. Third-party funds grew by 32% to £1.6 billion. Large mandates were received from the British Business Bank.
Underlying profitability: adjusted operating profit is £9.7m (last year: £7.6m). This excludes profits and losses on direct investments and it also excludes £1m of share-based bonuses for management, along with a range of other items.
My personal inclination would be to include share-based payments in my calculations of the company’s profitability, as these payments are just another form of remuneration. I would therefore be inclined to use a figure of c. £8.7m as my measure of the company’s “underlying” profitability. But there are many different ways to calculate this.
Direct investment portfolio: this is no longer of great relevance to the investment case here. But it does still have a balance sheet fair value of £117m (split across 22 investments). The loss that hit the income statement this year related to an impairment at one particular investee company.
Emphasising the lower importance now attached to MERC’s own direct investment portfolio, the company is seeking to be reclassified as a trading company rather than an investing company under AIM rules. This could have (positive) inheritance tax implications for MERC’s shareholders.
The company will not make any new direct investments, but it will continue to support existing investee companies.
Buyback and dividends: a £5m buyback has been completed, and the company is proposing a slightly larger final dividend (0.55p) than last year (0.53p). The dividend yield is c. 3%.
CEO comment:
"The year to 31 March 2024 was characterised by market volatility, high inflation and high interest rates driving up the costs of doing business, alongside geopolitical uncertainty and a thankfully short-lived recession. It is therefore pleasing to have come through these universal headwinds with record organic growth in our assets under management, driven by Mercia's diversified and differentiated approach to making a positive impact for our investors and investees.
"Over the next three years as Mercia continues its natural evolution, and subject to shareholders approving our proposed new investment approach, we will seek to drive AuM to in excess of £3.0billion whilst doubling EBITDA, focused on building value for shareholders and our other key stakeholders as a growing and sustainable, specialist alternative asset manager."
Outlook: nothing specific is given for the year ahead, but the CEO highlights that the goal over the next three years is to become “a leading UK specialist alternative asset manager”.
Estimates: Equity Development have initiated on MERC today with a valuation of 51p, based on a sum-of-parts analysis (fund management business 13p, cash on balance sheet 11p, direct investments 27p). It’s a detailed report (36 pages long) and it provides me with a great deal of confirmation bias, as I’ve been arguing for a few years now that MERC is too big for its market cap.
Analyst Paul Bryant estimates we could see adj. EBITDA of £6.2m next year (2024: £5.5m). (GN note: this figure is lower than adj. operating profit because it excludes net finance income).
Graham’s view
The MERC investment thesis isn’t a simple one. The business model is changing, and it’s currently between two stools, with a large direct investment portfolio on the one hand and a growing (but still small) fund management business on the other.
Partly because of this, the stock can’t be valued on the basis of earnings/EPS/PE ratio. The correct approach, as done by Equity Development, is to look at each of its features in turn and to value them separately. This isn’t easy and while one-off events such as impairments can hit the income statement, we don’t have straightforward financial statements to analyse.
From my point of view, nothing has changed: the company is executing its plan and I maintain my positive stance. In the fullness of time, the direct investments will be realised and the profits at the fund management business will become the main event here.
I continue to believe that the company is just too big for its market cap, both from the point of view of its balance sheet (tangible net assets £153m, which seems more likely than not to be a conservative measure of fair value) and from the point of view that a growing fund management business is thrown in “for free”. So I remain content that this is on my best ideas list for the year.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

72 comments
Supreme (LON:SUP) - video recording Investor Presentation (FY Results) - July 2024
Sandy Chadha (CEO) and Suzanne Smith (CFO) of Supreme plc hosted an Investor Presentation covering details of their results for the year ended 31 March 2024. These included strong trading across FY24 in all divisions, and almost doubling of profitability overall. Management highlighted record levels of cash generated from operations, and ending the year bank debt-free. The team discussed the recently-announced acquisition of Clearly Drinks, which provides product diversification and is immediately earnings enhancing. Finally, Supreme touched on the continued positive trading momentum into the first quarter of FY25, and answered a range of questions submitted from viewers.
?si=BqWh5XPIzSTL0az5Mercia Asset Management (LON:MERC) agree with some other posters and struggle to get excited by them. As it stands nearly all of the value is in the direct portfolio, with the fund management company delivering only tiny profits. However, very difficult to gauge how much the direct portfolio is actually worth, with one of their investments recently being written off - who says there aren't a lot more of these? The fact they now want to wind this down doesn't really fill me with confidence.
Always been put off with their high levels of compensation, and really don't like the fact they adjust share based payments out of profits. The fund management business might be a winner over time, but it's going to need huge levels of growth over several years before it delivers a reasonable profit. Not for me.
Totally off topic I know but have a nice day any fellow Tesla (NSQ:TSLA) holders, nice 30% run in the last 30 days
This is just the start. Good Q2 update, Tesla energy is going very well, autonomous driving will be the next major catalyst and then Optimus the icing in the cake.
I do hold, 50% of my pf.
I had to buy a couple of them a couple of days ago for a hopeful momentum trade for earnings and potential Musk AI talk (i hope he mentions AI more than once during upcoming earnings!) and hope for market enthusiasm for August 8 Robotaxi day.Got lucky with delivery figures being slightly better than expected, was potentially going to buy the dip.. Definitely not a value trade ha.
Tesla (NSQ:TSLA) , along with Apple (NSQ:AAPL, before they recently started mentioning AI for the new Iphone were definitely the couple of megacap laggards.I'm not usually a fomo trader....... but Tesla (NSQ:TSLA) is definitely the institutional momentum fomo trade currently imo.Much prefer the short term downside to GameStop (NYQ:GME) and Chewy (NYQ:CHWY) for example, which i luckily wouldn't touch anymore.Thank god i've finally learned something since joining Stocko... (fingers crossed lol)!!
S4 Capital (LON:SFOR) directors have bought shares worth £500k. Has the worm turned?
That's a decent chunk. Everything I've seen recently would suggest following them in. Unsurprisingly, the big director buys tend to be a great sign!
Majority by Wesley ter Haar, cofounder of Media Monks which he sold for a handsome amount to S4 Capital (LON:SFOR) ...
And he already owns c£15m+ of S4 Capital shares, so another £500k could be seen as not much conviction...
Anyone know if he bought shares between selling Media Monks to S4 and now?
Highlighted on a separate discussion post this morning, but pleased to also share here the summary of our initiation report on Mercia Asset Management (LON:MERC) from today - thanks for the comments above which reference the report too.
"A deeply undervalued specialist in private markets" - link to research: https://www.equitydevelopment....
Mercia is one of the largest investors in ‘regional’ (ex-London) UK growth businesses. Its primary focus is managing funds of around £1.6bn for third parties (FUM) in structures such as Venture Capital Trusts, EIS funds and funds for institutional investors. The business is scaling. FUM has more than doubled in two years. Record net flows exceeded £0.5bn in FY24. And growth is by far the highest among a London-listed peer group.
FY24 revenue grew 18% y-o-y to £30.4m, EBITDA 7% to £5.5m, a margin of 18.2%, likely to ratchet up over the longer term as the business scales further. Indeed, the newly announced Mercia 27:100% growth strategy aims to reach £3bn AUM (FUM + proprietary capital) and £11m EBITDA in 3 years.
Mercia also invests its own capital into a portfolio of ‘direct investments’ (NAV: £189m on 31 Mar 24). Its record is impressive.
A strategic change is to be proposed at the 2024 AGM - to focus primarily on highly profitable and fast-growing fund management, and to stop making new direct investments (while supporting existing investments). This allows Mercia to reclassify from an investment company to a trading company under AIM rules, allowing gains made on shares to be IHT-exempt (under certain conditions).
We see potential for a significant re-rating - our fair value is 51p/share.
Gulf Marine Services (LON:GMS) I hold
After the Placing by Seafox last Friday of c4.6% of the company, I just noticed this RNS;
https://www.stockopedia.com/sh...
Someone called Fiera Capital has just bought a 3.5% stake in the co. I'm hoping that they keep buying, especially if Seafox are exiting their position. This is a Canadian Asset Management Company with AUM of $164 billion.....
Can I raise a completely off-topic matter?
As I understood it until this morning, shares listed on the AIM market are exempt from stamp duty, however, following two transactions today my stockbroker has informed me this is not the case. To gain exemption each company has to apply for exemption and unfortunately that has not happened in the case of Serabi Gold (LON:SRB) or Pan African Resources (LON:PAF) .
Has anyone else noticed this and is the information that has been given to me correct?
Thank you in advance and apologies again for it being both off topic and related to shares that would not be covered here.
Stamp duty on AIM
Welshborderer - a google takes me to : https://docs.londonstockexchan...
The reason is that shares also quoted on a main exchange are not exempt from stamp duty.
Pan African Resources (LON:PAF) is on the main board of the JSE (ticker: PAN)
Serabi Gold (LON:SRB) is quoted on TSX:SBI
Please don't apologise for being O/T as this is of interest to all who use AIM and to me was refreshing (and I learnt something new) after treading through all the rants on vaping that we have here every time Supreme (LON:SUP) reports.
Many thanks for your research and kicking myself for not doing the same. Frankly I spent a good half hour trying to get this response only to be met with 'the dealing room says....' It wasn't so much that I didn't believe them as the frustration there was no signposting to a disclaimer to warn me. The quantities being bought didn't give rise to horrendous sums, it was the principle.
Many thanks for helping out
Bizarrely, you can buy Glencore (LON:GLEN) on the main market and pay no SDRT, if you don't want to pay tax on a resource stock. Yes, I hold.
In his report on Mercia Asset Management (LON:MERC) Graham suggests that the company is seeking to classify as a trading company rather than an investing company and therefore may become IHT exempt .
I would be grateful if anyone could, as far as is possible, indicate the IHT situation for Impax Asset Management (LON:IPX) ; Duke Capital (LON:DUKE) : Polar Capital Holdings (LON:POLR) and Premier Miton (LON:PMI) .Thankyou. KBR
Right now I would not be thinking of IHT relief on Aim shares -I would be surprised if the new government does not tweek the rules - whoever comes to power.
They’ll certainly look at this and other BPR reliefs but to end AIM-eligibility would profoundly impact the market for offerings and the secondary trading
Mercia Asset Management (LON:MERC) have never impressed me much (to paraphrase Shania). Have the top 2 changed or are they just trying to spin a different line having failed as investors? Will they succeed as a small scale asset manager? Do they have a clear enough niche to differentiate their offer from the larger, more financially efficient players?
Looks like another way for the CFO to keep changing his fancy car every year.
Hi most of the fund managers you quote are main market listed bpr only applies to aim listed stock (generally aim fund manager stocks won't qualify for bpr).
Zotefoams (LON:ZTF) has continued to pull back following the initial hype around the Rezorce media launch. Now down 25% from last months 575p as a high, it's trading at 430p. Potentially Nike (NYQ:NKE) results a few days ago may have contributed to the fall, but I believe this is a great example of where illiquid shares can sometimes provide the best opportunities.
To me, and of course there will be many who disagree, this just appears to be a great opportunity to buy in at a lower price before what seems like the inevitable successful market trials. The trials are essentially the final hurdle from an R and D perspective and then Zotefoams are looking at a product ready for sale. Zotefoams paid a lot of money to utilise Shincell to aid production operations once the green light is given on the trials, I can't see them risking all that capital prior to a successful market launch if they weren't highly highly confident. Management reflected this confidence in their investor meet presentation.
In the next couple of months we will also hear about the selected funding partner/s and I think then the scale of the opportunity will become clear and hopefully bigger institutions will come knocking. Maybe I have fallen for management here, maybe I have put too much faith in the product, it could come back to bite. However, I have trusted my gut on this and pushed my position size from 10% to 13% today, more than I would normally allocate to one company, but I feel the risk reward is favourable to any investors buying at these levels. As always DYOR. I am highly biased as this is my largest holding alongside Seplat Energy (LON:SEPL) in a concentrated 16 stock portfolio.
Ben, I would agree with what you say. I will be buying more if the price weakens any further, Rezorce could be a huge change for the company. Prices seem to fall on not that much trading- take Renold (LON:RNO) recently and Kitwave (LON:KITW) recently-to me KITW looks a interesting business that is expanding nicely.
Plenty of other recent risers falling on low volumes - some people taking risk off the table before the much-anticipated Tory wipe-out? Not helped by interest rate cuts now being pencilled in for later in the year and fewer of them. Plus, affected companies reporting higher freight costs and de-stocking continuing longer than had been anticipated.
The run-up in nearly everything that took place between April and June now looks a bit premature and exposed. Many shares went up on very little volume being pushed up by market-makers rather than an imbalance of supply and demand.
Where will it go from here? Surely, the worst possible consequence - the demolition of the Tory party vote - has already been widely suggested and should, in theory, already be discounted? But perhaps not. A residue of over-optimism - created in the last couple of months - probably means that market participants have been reluctant to sell out of positions recently acquired even where those are in profit. Consequently, such an outcome in the election may appear to come as a 'surprise' or, at least, final confirmation that the trend is back down for the time being.
Most reporting seems to anticipate that there will be little change under Labour beyond some attention-grabbing changes such as VAT on private education and CGT on carried gains. Their hands are rather tied by the situation unless they want to experience a Truss-style run on confidence. But the lack of clarity over ISAs, BPR and pensions is ominous given that they have already ruled out changes to corporation tax, income tax, etc.
The bull case is that the economy is improving, that interest rates will inevitably fall by the end of the year and that any Labour policy change will be net beneficial. Disappointment on those counts looks likely to negatively affect sentiment in UK small caps. All the while the flood of funds being sucked out of the UK market to speculate in the US casino gathers pace. And the cheapness of UK stocks in comparison that seemed to be being recognised a couple of months ago doesn't seemed to have sucked any great amount of new money in and the new government will continue to talk about supporting UK markets while fully aware that less than 2% of their own pensions are invested in the UK market.
Sorry if that sounds bleak, but for this market to turn around some wider momentum has to build and that feels as if it has largely evaporated. We seem to be heading back to where we were at the end of last year with isolated story stocks being ramped up by exaggerated interest while the majority of stocks stagnate getting cheaper and cheaper until the odd PE bid emerges. Unless some form of wider confidence is restored a Labour win seems to me likely to coincide with further falls back to where we were at the end of last year.
I hope I am proven wrong!
Most reporting seems to anticipate that there will be little change under Labour beyond some attention-grabbing changes such as VAT on private education and CGT on carried gains. Their hands are rather tied by the situation unless they want to experience a Truss-style run on confidence. But the lack of clarity over ISAs, BPR and pensions is ominous given that they have already ruled out changes to corporation tax, income tax, etc.
Surely labour know they will be out of the door as quick as you like if they take the micky ref taxes. if labour had raised the copr tax rate to 25% massively , hiked dividend taxes , frozen persoanl allowances - reduced amounts where higher rate tax kicks in and frozen vat reg threshold for 5 years (uplift in election year no surprise) - one would probably ben in uproar - tories have done that with little moaning
I for one doubt labour are going to go to town on taxes any more than the tories have done. Not saying something may not give but i dont expect them to do any worse than the tories have done overall. Thast not to say taxes wont be raised if defecit needs sorting.
anyway the proposed chancellor has by the looks of it put her head on the chopping block by saying - to be fair i kinda respect these comments being made - all too easy to get in by saying nothing (that seems to be the labour leaders tactics - even when pressed on pension tax relief he got it totally wrong and had to be corrected by his minions)
Trust me' with your money
https://www.standard.co.uk/new...
Unless some form of wider confidence is restored a Labour win seems to me likely to coincide with further falls back to where we were at the end of last year.
i guess time will tell but not convinced its gonna make much difference myself - i supect the stock market will follow the fortunes of the economy and thats not all driven by the powers that be really is it ? - presumably if they overstep thew mark like Truss clearly did the market will perhaps even keep them in check ?
I think the election will come and go without much of a blip on the stock market, and the factors you mention will continue to play out as they are doing currently. Recent stock declines on low volumes will reverse at some point, and anticipated interest rate cuts, ongoing higher freight costs and de-stocking are key factors that will continue to affect the market. If I was to speculate, then I would have to say the flow of UK funds to the US will continue to decline, and we will see a slow long term market recovery under a more stable government willing to tackle the real economic and structural issues in the UK.
Thank you for your comments on Mercia Graham, we'll be adding and waiting.
Supreme (LON:SUP)
CEO and CFO talk to Paul Hill - some interesting comments on the Clearly acquisition - I don't think market forecasts have fully factored that in:
The. Decision to sell on the first profits warning, or on hints of bad news ahead in an update, or even if just having doubts, that became my selling tactic a while ago, the more so after losing heavily on Boohoo (LON:BOO), has vastly improved portfolio performance.
Gone are the underperforming shares like BOO that I hoped or expected might recover but so often didn’t, and often the falls continued and there were too many such shares hitting overall performance. Why do we hang on and hope they’ll recover? A few do but most don’t.
I’ve never held Shoe Zone (LON:SHOE) and there’s nowt clever in that decision as it went up 7 times from 36p in late 2020 to the 280p peak this year. But had Shoe Zone (LON:SHOE) been in my portfolio it would have gone either in January or if not then, definitely in March.
January 9th.
Good Results and the share price rose to 240p on the day. The only doubt was Paul Scott’s comment about possible competition from SHEIN and TEMU. Having taken a hit on Boohoo (LON:BOO) I might have sold then or top sliced. But overall there was no other obvious sell case then. And the share price gains continued with a peak of 285p.
March 12th.
A mild profits warning. Zeus cut the eps forecast by 9% which was more than Paul Scott had expected, and again Paul warned of that SHEIN/TEMU risk. The share price fell to 232p compared with 280p the day before. A clear enough sell signal this time?
May 21st.
Interim Results were in line BUT Shoe Zone (LON:SHOE) warned about Middle East disruption. The share fell to 176p. Again clear negatives that could mean further warnings ahead. And that warning was in theOUTLOOK statement along with a new a warning about the big negative effect of the minimum wage increase.
It’s often the OUTLOOK section where investors can find those hints of problems ahead. Here’s that May OUTLOOK section:-
“Our original full year profit before tax forecast was £15.2m, which has been revised down to £13.8m, a reduction of £1.4m. At the point at which the original forecast was prepared the consensus was that the National Living Wage would increase to £11.08, but when announced, the increase was to £11.44 which adds £0.4m of cost in our second half. The continuing disruption in the Middle East has increased shipping times and container prices which adds a minimum of £0.5m of cost and due to the large number of stores we have closed, particularly in Scotland, we have provided for an additional £0.5m of dilapidations.”
Today. July 2nd.
Another (predictable ?) profits warning. The sea freight costs issue that Shoe Zone (LON:SHOE) warned about in their March update is cited as a key reason for the fall. Some of the other reasons like the weather sound like excuses…but there seem to be an increasing number of negatives. . And AGAIN today Paul has reminded about the possible hit from Chinese competitors. The share is now down over 50% to 124p from that 285p peak. . It will need to double to get back to that.
Another problem when we hang on to shares we wish with hindsight benefit we had sold, is that it can get to the point where we think “it’s not worth selling now.” IF there’s a good chance of the investment case improving from here, there’s strength in that argument.
BUT does the Shoe Zone (LON:SHOE) Update today give any reasons for expecting that improvement? Or is the risk now yet another warning and a dividend cut or cancellation to go with it? We don’t know yet, but when we hold on to a share that disappoints the risk is the loss ballooning from that no loss or even profitable sell opportunity on the first doubts, to a further big share price fall (as happened with Boohoo (LON:BOO) ) and a 90% or more loser, or worse.
Moral crusader's day again
IG Design (LON:IGR) has come off quite a bit recently. Steep freight cost worries? Paul did mention the possibility if supply chain issues in his full year results roundup.
Yes, freight cost is an issue for IG Design (LON:IGR) but I'm not so sure it's as big an issue as in the past (i.e. when it got walloped during covid). It made op profit savings of $8.7m in FY24 from normalising freight rates, but it also made op profit savings of $34.8m in FY24 just from better sourcing, so there are self help measures it can take to reduce impact imo. Can they repeat the improved sourcing next year ? Who knows. They are also closing down their factory in China & increasing near shoring, (esp in Mexico) so they're aware of need to minimise freight impact. They've also spoken to customers after covid near disaster and agreed to share more cost of possible increased freight rates in future as they took hit themselves during covid. Best way to reduce freight impact is to increase sales and that's next step of their recovery plan so we'll see. I'm a holder so I'm biased but I think mgt here are pretty switched on and I still think it's an interesting recovery play that's not fully played out yet.
IG Design (LON:IGR)
They've also spoken to customers after covid near disaster and agreed to share more cost of possible increased freight rates in future as they took hit themselves during covid.
This is a very good point Joe and one I picked up from listening to the recent Y/E results PI World presentation - it is specifically mentioned.
Profit taking and a market overreaction to 'bad' news has created a suitable buying opportunity for those that have missed out on the way up??
IG Design (LON:IGR) - Not sure it's profit taking after a great update. SP has fallen by 17.5%. I have exited now .
Fear and greed i guess as usual in markets and especially illiquid ones.Once there's some selling, others follow as they either want to protect profit, fear they don't know something others do or run stop losses, sell when 10-20% down on capital, etc.. or just follow the herd.They'll be a good buying opportunity as results weren't bad.Perhaps when it's settled, as some folk like to buy according to technical levels or could rebound beforehand and catch a few out.Fun and games!Illiquidity can naturally potentially create better opportunities though, if you believe in effiicent market theory in a lot of the larger international markets.I mean you can even often buy in at yesterday's price after a great RNS on AIM often.
My guess is it's profit taking. Even after the falls it's on a forward p/e of 10 for a fairly low quality and low margin business, and those profit estimates are a big jump from FY24 (although personally I think they look achievable given the FY24 H2 performance). The European business also saw declining revenues in H2. So I don't blame others for taking money off the table and wish I had done the same at c240p!
Note for Paul.
Chaka Khan on Jamie Callum show tonight @ 9pm Radio 2
i feel for you
Funding Circle Holdings (LON:FCH)
For those who are interested Funding Circle Holdings (LON:FCH) announced the completion of the sale of its American business after the market closed last night, which leaves the profitable UK lending business and the new and fast growing Flexipay business.
I missed the boat here, but on the premise that it is never too late to invest in good company with significant growth potential I opened a starting position recently.
Don’t get the hype with SUP. It’s new forward numbers are going to be down or flat on profit at best. Half of its business will be banned or restricted, a business that is morally wrong too. So out of all the investments I don’t see it as being a great buy now that it’s already had a big move.
Glass half full or empty, as you look at Supreme (LON:SUP. I hold.
With businesses like this which are going to be regulated, better to be the biggest fish in the pond, rather than a new entrant having to get established in the market. Moat.
Why is vaping morally wrong, compared to say, a business that relies on alcohol sales, travel or the exploitation of workers in far flung countries?
Always surprises me when people make comments like this without actually evaluating what is in their portfolio and the harm that most businesses make in pursuit of profit.
Vaping, even among children, may not be considered morally wrong if viewed through the lens of harm reduction and personal autonomy. Some argue that vaping offers a less harmful alternative to smoking traditional cigarettes, potentially reducing overall health risks. But why let facts get in the way...
Why is vaping morally wrong, compared to say, a business that relies on alcohol sales, travel or the exploitation of workers in far flung countries?
Imho think we have enough current legal drugs that we dont need to add new ones that obviously have bad health effects long term. I get vaping for anyone who can prove they have been long term smoker and needs to stop. I dont get vaping for kids who have been never been long term smokers - or who dont have a clear smoing porblem . If one cant see its endemic amongst youngsters and thats totally unconnected with them quitting smoking one has to be blind. So on the basis its obviously bad for health to me its clear use should have been restricted to ex smokers via prescription na dpeople with smoking issues. as with any other vice though once the genie is out of the bottle though its hard to put it back in so imho its probably too late for this new vice to be eliminated.
The addiction is clear and present where you see people feeling the need to have that last puff the minute before the enter or a leave a building or public transport or whatever.
So compared to other stuff yes its no worse no worse - but imho its morally wrong make it super easy for youngster to pick up these new addictions that may last a lifetime - we should be doing anything other than making it super easy for them to pick up this new addiction that is clearly bad for health.
Note the company trots out the party line that its a great smoking cessation tool - which it is. they do not seem to mention that many users would NOT have been long term smokers anyway - imho that % is rapidly increasing compared to ex hard term smokers and probably makes up over 50% of users now. They do not address the issue of vapers who wouldnt smoke as far as i can see. i know plenty of youngsters who vape and most of those have not had smoking problems - plenty who see smoking as very unattractive pastime but vaping as something they do possibly because everyone else does it or they think its edgy.
If God had intended humans to smoke they would fitted a chimney.
*A business that is morally wrong". A strange assertion. Like it or not vaping saves lives
A business that is morally wrong". A strange assertion. Like it or not vaping saves lives
And when sold as a bubblegum substitute, falsely neutered with its cute alcopoppy name, it enslaves children as nicotine addicts. As a marketing strategy!
Yep, perfectly fine. Where do I become a shareholder?
Fair point well made
No need for the hard sell. You had me at ‘bubblegum substitute’.
Let them smoke cigarettes! I paraphrase Marie Antoinette.
You do realise that selling vapes to children are illegal and the majority of people I know that vape LOVE these tacky flavours.
I'm old school and would far prefer a Gitanes, or woodbine flavour, unfortunately, I'm in a minority ;-o)
I'm not too fussed about the moral grounds. I hate the idea of govt interference. Whenever govt interfere then it's usually a disaster. Let free markets work and customer choice, simple supply and demand play out. We invest because of free markets and price discovery. If it becomes socially unacceptable, or attitudes change and enough people stop buying vaping products then market will disappear. I don't want the govt telling me something is wrong, I can work that out for myself thank v much.
It's not just the marketing to children - disposable vapes rely on lithium batteries fused into the plastic shell, which are toxic and likely to burst into flames when they're crushed. Millions get dumped into landfill every year. Rishi Sunak promised to ban disposable vapes 18 months ago , but never got round to it.
Government interference? It's the government's job to regulate/control/ tax dangerous and anti-social products - it's why we have driving tests; speed limits; gun control; age limits on alcohol, tobacco and other addictive products etc.
Supreme (LON:SUP) imo supply succour to suckers then dump their newly addicted mass of previously non-smokers on the NHS for the nation to pay for. Thanks.
Time for Vapes to be made Prescription Only for helping existing smokers to quit or at least manage their addictions. The sooner this is sorted then better. Rishi should have had the courage to stay in office a little longer to resolve issues like this.
We all choose what we invest in. It's up to you. Just look out for the strength of feeling that may lead to changes in legislation down the track.
Supreme (LON:SUP)
Whilst some may find the ‘moral injury’ element of this discussion interesting , Joe Turner has summed it up well.
We bluntly don’t care about each other's views on vaping. We should focus on the bull and bear cases of the investment, and and headwinds and tailwinds we see. Our personal views on what we think of vaping morally are exactly that.
Supreme (LON:SUP)
You can’t force a narrative or agenda that you want on others though. Facts are contrary to suggestions by others here supreme are not the good boys - they still have the flavour names they said they would stop using months ago on their website . The narrative that for kids this is mainly a smoking cessation tool is clearly false. Whatever your outrage thankfully the majority would probably want stronger laws to stop minors being targeted. What the government are doing is too little too late but there should be zero sympathy here for this company when eventually we do get stronger controls it’s just a shame that vaping in under 18’s was ever allowed to be a thing to the extent it is. None of that is anti freedom on any level simple common sense.
Supreme (LON:SUP)
Paradoxically, I’m not forcing ‘my agenda on others’- other people are doing exactly that.
The under 18 rules on vaping are historical and I suspect only relevant to this discussion if there is further regulation and that may affect future share price- as Paul alluded to.
If that happens and the market corrects, then so be it- that’s the risk of owning a stock where 70% of its profit is from non- combustible tobacco.
This isn’t a ‘vox pop’ on what people think about the benefits and harms of vaping., it’s an investment website for small cap investors.
Let’s please keep it as such.
Paradoxically, I’m not forcing ‘my agenda on others’- other people are doing exactly that.
thats probably fair comment David - my point was simply that those demanding free for all often dont get what they want. so anyone in agreement with Joe Turners rant about having soem rules imho deserved a mini bashing as rules are clealry needed and free for all aint ever gonna happen ref vaping.
most would call that societal norms where there is stuff where it doesnbt work how you would like -some may say its them being forced to do stuff - in tat regard we all have to tow the line to lesseer or greater degree.
The under 18 rules on vaping are historical and I suspect only relevant to this discussion if there is further regulation and that may affect future share price- as Paul alluded to.
the fact they say wont do something (target kids) then do that exact thing is not a great advert for their businesss imho. If you want clean cut image dont put fancy names targetted at kids front and centre of your website - in that regard they may get away with it but thats a business risk. Facts are under 18's do vape so there is an issue here that clearly hasnt gone away even if they technically cant smoke.
If that happens and the market corrects, then so be it- that’s the risk of owning a stock where 70% of its profit is from non- combustible tobacco.
Agreed - hopefully for holders there are other options here - it does seem a very well run business i must admit.I am a realist i doubt they will be able to totally clamp down on recreational vaping whatever my opinion on what tehn rules should be - in that regard i doubt it will be on prespcrption only as i would like to see.
This isn’t a ‘vox pop’ on what people think about the benefits and harms of vaping., it’s an investment website for small cap investors.
Well said - i dont generally start off topic stuff - i am weak though in not letting stuff off topic that may leave one sided or i think plain silly alone. If i have a viewpoint on what someone else has said and that seems slanted i tend to respond if i have a viewpoint - at least i can say i didnt start it lol.People do often take offence to my comments all i know that none it is meant to come across as that.
Kitwave (LON:KITW) pretty soggy update - the growth seems to have run out of steam here. Wet weather noted as a factor, but also mentions higher wage costs and increased development costs, leading to a fall in H1 profits. Maintains guidance for FY, but have a feeling they may need to downgrade at some point.
Good morning Paul and Graham. Graham gave Mercia Asset Management Green on April 10th, we hold and I would appreciate a comment if time allows on today's prelims. The Alternative Performance Measures look fine but the Statutory Results less so with Impression Technologies being the main contributor to a £17.3 million loss on the investment portfolio value. A comment on their plan for reclassification as a trading Co would also be welcome.
Supreme (LON:SUP) - FY24 results generate doubled profit, record cash - link to our new research note here: https://www.equitydevelopment....
For the year to 31 March 2024 Supreme reported revenue of £221.2m, +42%YoY, (adj.) EBITDA of £38.1m, +97%YoY and (rptd). PBT of £30.1m, +109%YoY.
Net cash from operations grew 40%YoY to £27.1m, with year-end net cash1 of £11.6m (FY23: £3.2m). (adj.) diluted EPS was 18.19p/share (ED E, 20.2p). We see strong performance at gross level, +55%YoY with margin improvement from 26.3% to 28.7%.
The Group has made timely preparation for the transition to traditional refillable, rechargeable e-cigarettes, allowing it to further scale its c.60 m bottle annual production volumes, or to newer pod devices. Supported by strong cash generation Supreme has maintained its strategy of acquisition in a new product area – Soft Drinks, where we expect a full year of contribution in FY26.
Supreme trades on a FY25E (adj.) EV/EBITDA 5.5x and PE of 9.1x, offers a dividend yielding 2.6% and remains highly cash-generative, as evident in the recent cash-based acquisition of Clearly Drinks for £15.0m.
Our Fair Value remains at 225p/share, still well above current levels despite recent strength.
Supreme (LON:SUP) results:
Revenue £221.2 up 42%, adj eps 20.9p up 77%, divis 4.7p for the year up by 57%, adj new cash up 263%
Outlook sounds good too:
Supreme forecasts FY25 to be another profitable and highly cash-generative year for the Group. Having made a positive start in Q1, the Group is trading comfortably in line with current market expectations5.
· The Company's FY25 trading outlook for the Vaping and Branded Distribution divisions is expected to be largely unaffected by the Government's proposed future disposable vape ban.
· Alongside an ongoing focus on accelerating organic growth and strategic cross-selling, the Company remains committed to exploring complementary acquisition opportunities to further scale our exceptional distribution channels. The recently announced acquisition of Clearly Drinks Limited "Clearly Drinks"), a soft drinks manufacturer and brand owner, on 21 June 2024 for a net consideration of £15 million is directly in line with this strategy. This acquisition provides product diversification for the Group as well as incremental earnings.
https://www.investegate.co.uk/...
My morning smallcap tweet: Fatal Subtraction
Shoe Zone (LON:SHOE) Nanoco (LON:NANO) 1Spatial (LON:SPA) hVIVO (LON:HVO) Ilika (LON:IKA) Batm Advanced Communications (LON:BVC) Checkit (LON:CKT) Capita (LON:CPI) Creo Medical (LON:CREO) Supreme (LON:SUP) Mercia Asset Management (LON:MERC), Kitwave (LON:KITW)
◄Shoe Zone (SHOE)► warns FY-Oct adj pretax only £10m+. Blames container rates and weak Spring Summer sales due to weather. [SP=151.71 Cap=72m]
◄Nanoco (NANO)► warns FY-July rev marginally below consensus (£8.35m) and adj EBITDA towards the lower end of the range of forecasts (£0.5m to £1.5m). It won't get a further production order for its validated first generation sensing products during FY24. Working with customer to determine what's next. [SP=19.78 Cap=38m].
◄1Spatial (SPA)► wins US contracts worth $0.6m ARR. Also a position on a five-year framework agreement with the State of Tennessee. [SP=69 Cap=75m]
◄hVIVO (HVO)► wins field study assessing a flu drug candidate. Most of the rev expected to be recognised in FY25. No £££. [SP=26.67 Cap=181m]
◄Ilika (IKA)► has shipped its first batch of prototype Goliath batteries for customer testing by a tier 1 automotive company. Note previous excitement has proven to be premature elation. [SP=24.25 Cap=41m]
◄BATM Advanced Communications (BVC)► signs strategic partnership and cooperation agreement with a significant global technology, engineering and defence group to deliver BATM's advanced cybersecurity solution to commercial markets. Will get $2.1m minimum in first 2 years for the product customisation phase and the provision of an initial quantity of units, [SP=16.21 Cap=66m]
◄Checkit (CKT)► wins 32 month contract worth c.£250k PA. Checkit is hopeful of signing further similar contracts with this customer. [SP=24.5 Cap=26m]
◄Crapita (CPI)► renews contract to administer the Royal Mail Statutory Pension Scheme for 6 years from 2026. Two year extension option. Total £48m over 8 years. [SP=13.26 Cap=227m]
◄Creo Medical (CREO)► expands agreement with Intuitive Surgical to increase the number of sites in the UK and Europe undertaking combined lung cancer diagnostic and microwave ablation procedures. [SP=33.4 Cap=121m]
◄Supreme (SUP)► FY-Mar. Trading comfortably in line with FY25 expectations of rev £242m and adj EBITDA of £36.9m. [SP=177 Cap=199m]
◄Mercia Asset Management (MERC)► FY-Mar. Pivots to focus on its profitable and fast-growing FuM. [SP=32 Cap=136m]
In line: KITW
Best one yet on Illika Mr C
I think you made a mistake, it's Capita... oh wait ... my bad.
hVIVO (LON:HVO) another contract win, the good news continues
hVIVO (LON:HVO) Nice - but how much revenue will the contract bring in ?
hVIVO (LON:HVO) not really relevant bohenie but I suspect a reasonable 7 figure sum. Probably north of £1000 per volunteer given the costs to a pharma of finding them themselves : can’t remember the number off type of my head but recruitment of volunteers is expensive - so somewhere north of £3m? At a guess.
Of course it is not expensive for hVIVO (LON:HVO) because they have a database stuffed full of screened and qualified volunteers.
But actually that isn’t the point. The point is that today that database is underutilised. Start to use it for field studies and you can add a lot of revenue with very high margins. That will help move the margins of the overall business towards the 25% mark over next couple of years from 20% and revenues towards the £100m mark. That, at least for me,is where the valuation uplift starts to kick in.
There has been a lot of discussion around shipping price rises in the last few weeks. I think Shoe Zone (LON:SHOE) has just given the definitive response on the discussion in their profit warning this morning:
Trading Update
Shoe Zone announces that, further to its AGM Statement released on 12 March 2024 it has continued to experience cost pressures associated with container prices due to a reduction in the supply of shipping vessels and the continuation of a reroute away from the Suez Canal. As a result, container prices have risen significantly over the last six months.
Will be interesting to see the knock on effect for a few other importers this morning.
Luceco (LON:LUCE) springs to mind. SCVR contributor planetx confirmed recently that rates are likely to be high after a chat with a forwarder.
I see Luceco (LON:LUCE) is down over 6% today. I am glad I sold out a few weeks back when the discussion about shipping rates first started as it has pulled back a lot. Once shipping rates news really becomes front and centre and everyone is overly sensitive to it, I will likely buy back in. I think there is a lot of opportunity at Luceco for the company to grow profits *not just profitable growth!*.
There's a surprise :(
£3 million hit from what was reported in May, which isn't pleasant.
Still money in the bank and dividend cover is over x2.
That said, you'd have thought a div cut is more likely than not and my expected 26% may not be solid.
Pressure on container ships pricing seems to be around for a while. But people still need shoes although even my daughter (13) is buying fake stuff with her mates from Temu et al.
I hold in my son's ISA and I should have sold at £2.50, I bought in at circa £.50.
I've let this drift too long, but, but - the market has priced this in I believe - I hope there's not more than a 10% drop and give it 6 months to stabilise and see what H2 brings?
Analyst consensus holding up. I would have expected to see a falling trend since May. Any thoughts?
Ultimate Products (LON:ULTP) ? I hold.
Shoe zone freight costs to blame
Have to say that’s a bit of nonsense .
It’s only in the last month that freight costs have skyrocketed again .
So landed inventory doesn’t have the additional costs .
Not a credible excuse at all .
Exoect the big pain to come in the next 6 months if freight rates truly are a factor .
The claim doesn’t stand up to any sensible scrutiny .
The freight rate increase will be forward looking and should not be wheeled out as an exicuse for poor profits .
Maybe it’s as simple as crap shoes in crap shops.
"Maybe it’s as simple as crap shoes in crap shops."
Brilliant :-)
Just a point though - the trading update on Shoe Zone (LON:SHOE) is for the full year and we are not half way through. So presumably the freight costs refer to the forward prices they are paying rather than now. Ie this is both a forward looking statement and a reduction in sales now. Would be helpful to understand how much relates to each aspect. Historically they’ve been quite good at that level of communication so we need more here.
Funny old world when it comes to the blamethrower cause/effect: Can't see Nike (NYQ:NKE) blaming freight costs for their record 20% recent drop. Can't see adidas AG (ETR:ADS) blaming freight costs for not achieving more than their recent YTD 25% gain (Maybe they 'blame' the Rishi/Samba effect? ps I do think he should have worn British New Balance or Gola!