Small Cap Value Report (Tue 2 Mar 2021) - CALL, BOO, DX., FCCN, CARD, HOTC

Good morning, it's Paul here with the SCVR for Tuesday.
Agenda -
Cloudcall (LON:CALL) (I hold) - yet another placing! (at 81.5p)
Boohoo (LON:BOO) (I hold) - Sky News article re Leicester supply chain (again!) and investigation in USA
Dx (group) (LON:DX.) - Interim results - shares look too expensive still
French Connection (LON:FCCN) - one down, but three more enter the fray - there are now 4 interested parties discussing a possible takeover. Formal Sales Process launched today.
Card Factory (LON:CARD) - Liquidity update, from last week
Hotel Chocolat (LON:HOTC) - Interim results
.
Cloudcall (LON:CALL)
(I hold)
Share price: 81.5p (pre market open)
No .shares: 38.8m + 9.2m new shares = 48.0m
Market cap: £39.1m
This was announced last night, with a follow-up announcement this morning, giving the result.
This is what I posted last night in the comments section of yesterday's SCVR, which many readers probably haven't seen yet -
Cloudcall (LON:CALL) fundraising - not again!!! Checking my notes, the last comment here was on 22 Jan 2021, where I flagged that net cash had fallen to only £3.6m, and expressed my displeasure with the company's performance.
On the upside, the recruitment sector which CALL mainly serves, seems to be recovering well.
Guidance provided in today's RNS for 2021:
Additionally, the Directors are now confident in providing new guidance for the 2021 financial year (for the twelve months to 31 December 2021) and now expect to achieve revenues of £14.0 million, representing an approximate 18 per cent. increase on 2020 revenues.
Not bad, but not amazing either, considering 2020 was suppressed somewhat by covid.
Guidance for 2021 costs is also provided:
The Company is also providing guidance for 2021 operating expenditure, which is expected to be approximately £16.9 million compared to 2020 which is expected to be approximately £13.9 million (including one-time COVID-19 related savings). More details are included in section 3 below.
I'm assuming we can deduct operating expenditure from revenues (as opposed to gross profit), so that would imply a £2.9m loss in 2021.
There's strong operational gearing here, with c.80% gross margins.
Longer term guidance:
Longer term, we continue to focus on achieving monthly EBITDA breakeven by mid-2023 and £50 million revenue run rate in 2026."
My opinion - it could have been worse, the main thing is that the 81.5p price isn't too bad a discount, once we ignore the obvious insider dealing that seems to have been going on!
Clearly, CALL has been disappointing, that's why the market cap is only £28m.
Personally, I'm going to hold this one to the bitter end, more through stubbornness than any strong conviction. It's not a big holding for me anyway. I think one of the American funds bailed out, or reduced, called Kinderhook.
Update today - results of fundraising
Yesterday it said a minimum of £6.0m would be raised in a placing at a fixed price of 81.5p. Plus a further £1.0m offer via PrimaryBid.
Result - additional demand has resulted in the placing being increased to £7.2m, but the PrimaryBid offer has only raised £0.3m, so £7.5m in total. I wonder how long it will take the company to burn through this latest dollop of cash?!
This will mean 9.2m new shares being issued, taking the total in issue from 38.8m, to 48.0m, an increase of nearly 24% - unwelcome, but not disastrously dilutive, and at least there was good demand for the fundraise.
CALL seems addicted to fundraisings, but must have spun a good yarn at the placing roadshow, otherwise it wouldn't have been supported by Instis.
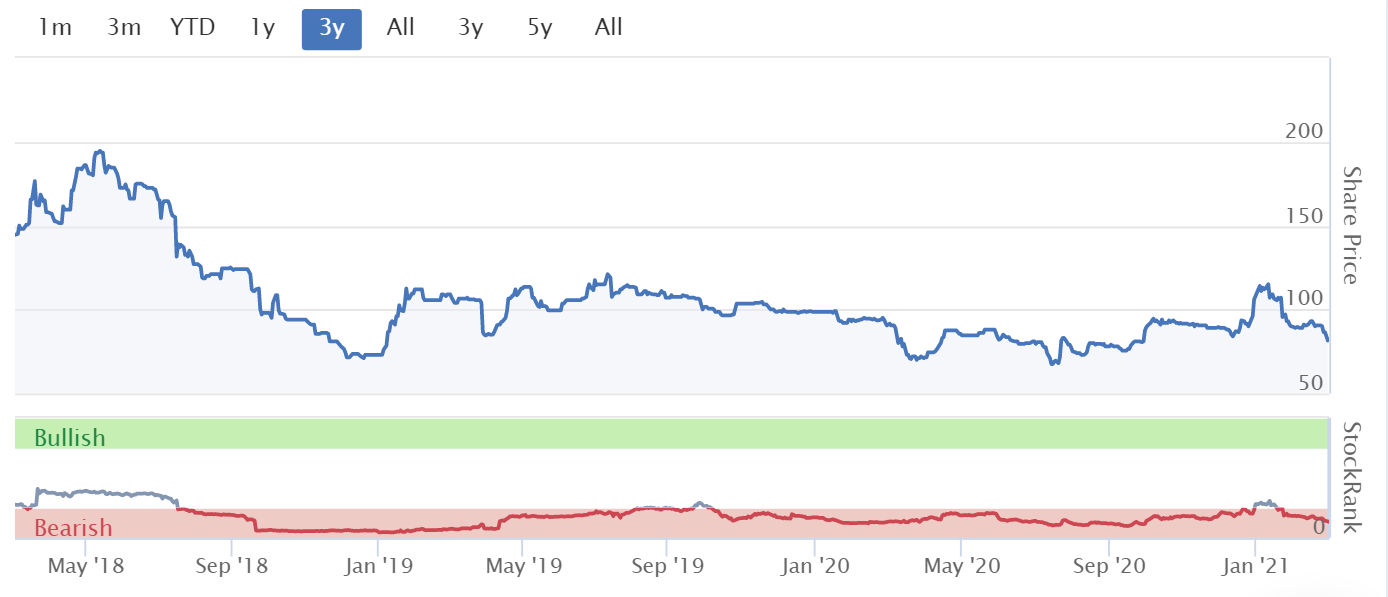
You can see from the chart below, that the share price began falling pretty much around the time the work would have begun on the fundraising in January probably. It's not good is it? I suspected something might be up, because everything else in my portfolio was rising, but CALL started going down.
We really do need reform of the system, to accelerate fundraisings, and suspend shares whilst they are underway. People buying CALL shares in the open market have been buying in a false market in recent weeks, since hundreds of people must have known that a fundraising was underway (and it looks as if somebody somewhere might have been insider-dealing, illegal of course, but rarely prosecuted). Why else would the share price have been falling in a rising market for smaller tech shares?
.
.
Boohoo (LON:BOO)
(I hold)
The Leicester supply chain issue has cropped up yet again. In this story, Sky says that a campaigning lawyer in the UK has stirred up trouble in America by reporting BOO to the US Customs & Border Protection, saying;
US Customs and Border Protection has seen sufficient evidence to launch an investigation after petitions from a campaigning British lawyer.
Sky says that this could lead to the possibility of a US import ban. Clearly that's an unwelcome risk, but this issue has been so comprehensively dealt with by BOO already, that it's in a very strong position to defend itself.
We already know that the third-party suppliers in Leicester were found wanting, with previous investigations, and that BOO has taken extensive action (a lot more than green-washing) to fix the industry-wide problem.
Sky quotes the lawyer as saying;
"What we'd all like, those of us interested in improving labour conditions, is for Boohoo to really get to grips with governance of their supply chain to ensure there is no wage theft and people have proper contracts.
Is he not aware of the extensive action that has already been taken to address this issue? I don't understand why BOO is being treated as if this is a new issue, when it's an old issue that is already being addressed. Therefore, BOO should be able to demonstrate very clearly that it's on the case, and is dealing with it.
I've no idea how US authorities deal with this kind of thing, so we'll have to wait and see how it pans out.
As Sky points out, more than a fifth of sales come from the USA. NastyGal in particular is a US brand that BOO acquired and seems to be trading well.
I suspect this might accelerate the shift of BOO production from Leicester, to lower cost producers in the Far East, where everyone else gets their clothing manufactured, e.g. by people being paid 50p per hour in Bangladesh. Leicester was used for speed to market, not low cost, because of course it's a high cost production area compared with Bangladesh, where apparently 4 million people are employed on far lower wages to make garments.
.
BOO has now issued a statement, which I summarise as;
- Not aware of any investigation, nor received any correspondence from US Customs & Border Protection.
- Confident in actions being taken to improve supply chain
- Continuing to fulfil orders to the USA
- Will work with any authority
- Alison Levitt QC's report stated that no evidence the company itself or its officers have committed any criminal offences
- Summarises all the things it has done to improve the supply chain under its Agenda For Change programme.
.
Dx (group) (LON:DX.)
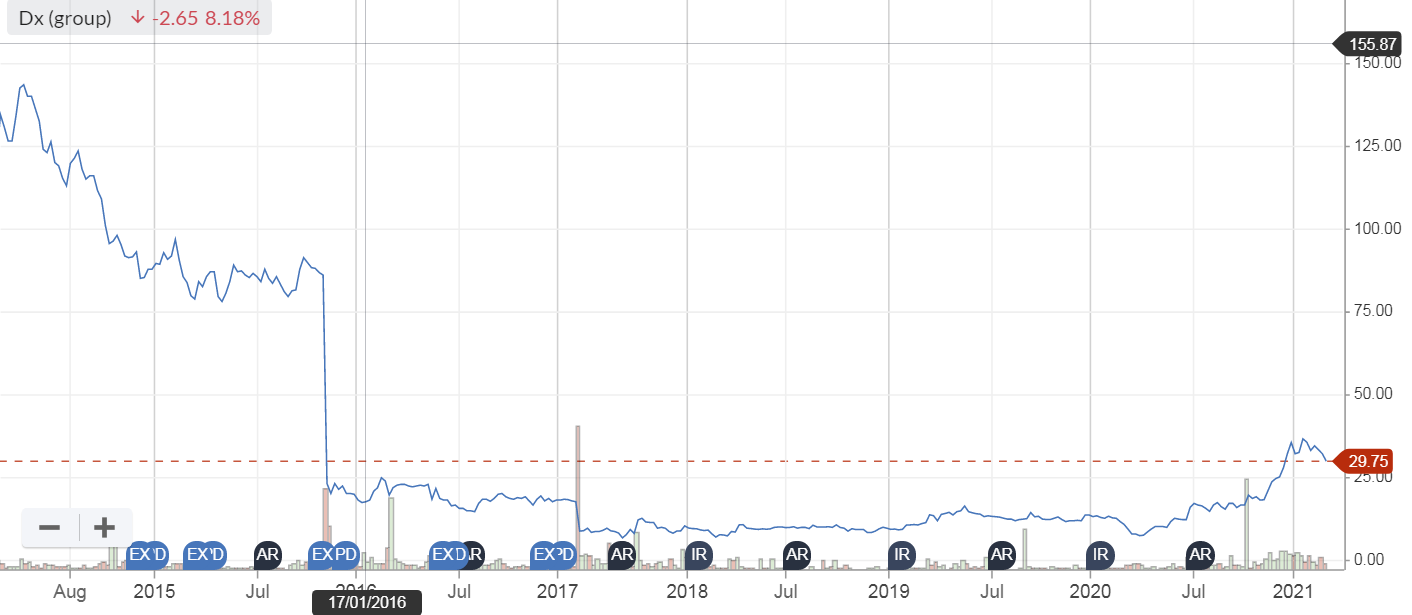
30p (down 7%, at 10:08) - mkt cap £173m
Here are my notes from 2 Feb 2021, where I covered the interim trading update for this freight & logistics company. In summary, I liked the positive trading (materially exceeding market expectations), but didn’t like the high valuation nor the weak balance sheet. My conclusion then was that the run up to 36p looked a good opportunity to bank some profits.
The price is down to 30p now, including a 7% drop today, so it looks as if the results have not impressed.
A leading provider of delivery solutions,including parcel freight, secure courier and logistics services
Interim Results For the 27 weeks ended 2 January 2021
Rebuilding Profitability
Key numbers -
- H1 revenue £182.7m (up 7.4%)
- Adjusted profit before tax £3.8m (LY H1: loss of £(1.7)m)
- Adj EPS 0.65p (loss of (0.35)p)
- Net cash £14.1m (LY: net debt of £(8.4)m) - boosted by creditor stretch.
Cash generation of £12.8m is much higher than profits, with creditor stretch being a major factor. VAT of £11.4m has been deferred, and other (unspecified & unquantified) agreed deferred payments. Also note that this £12.8m cash generation figure isn’t real. That’s because lease payments of £8.3m appear further down the cashflow statement, thanks to IFRS 16, a huge distortion.
The first thing that strikes me is that, whilst it’s good to see a return to profits, the margin is very low, at only 2.1%. Although I wouldn’t expect much more from a freight company, it’s a low margin sector, because there's lots of competition. A lot of effort & capital, for not much return, hence why I don’t invest in this sector.
Divisional profitability - the figures shown are not very useful, because such a lot of costs, at £12.4m for the half year, are classified as central costs.
Outlook - sounds upbeat -
· Healthy pipeline of opportunities in the parcels market, building on our new ETA technology and expanding network
The second half of the financial year typically generates a greater proportion of annual earnings and cash flow than the first. With the planned easing of the national coronavirus-related restrictions, we now have greater clarity over when we can expect more normal levels of activity to return. This is especially relevant for our non-essential retail customers, which affects DX Express in particular. Given the robust current volumes and anticipated levels of new business, we expect the Group to make further strong progress with improving the overall level of operating margin and rebuilding profitability.
· Trading to date in H2 is significantly ahead of the same period last year, in line with management expectations, and the Board expects further strong progress in rebuilding profitability this financial year. It views prospects further ahead with an increasing level of confidence.
Balance sheet - looks weak. NAV: £26.6m, but deducting £31.1m of intangibles results in negative NTAV of £(4.5)m. Not disastrous, but flimsier than I would like.
Working capital - current assets of £43.6m (including £14.1m cash), compares unfavourably with £(67.1)m current liabilities, a very weak current ratio of 0.65. I we adjust for the overdue VAT, then the current ratio worsens to 0.6
The IFRS 16 entries for leases are noticeably large, with the current liabilities (annual rent roll) being £15.8m, which seems a lot.
Forecasts - Finncap has kindly updated us, with adj EPS of 1.4p and 1.8p for FY 06/2021 and FY 06/2022. That’s a PER of 21.4 and 16.7 - that’s too expensive for a low margin freight company with a weak balance sheet.
My opinion - a turnaround does seem to be underway, but I think the share price has overshot on the upside, and still looks much too expensive.
Personally I would value this share at 10 times next year’s earnings, so 18p.
Therefore at 30p, there’s no attraction to this share, unless you think the company can out-perform against forecasts.
Note that it’s not in a position to pay divis, due to the weak balance sheet, although Finncap does pencil in small divis in 2022 & 2023.
My other concern, is the declining DX service for solicitors. This involves renting a large number of small sites. Customers are using it less & less, due to email substitution. This is probably why the IFRS 16 lease numbers look so high, suggesting that DX has a long, and expensive tail of sites that it might struggle to exit from. These could become an expensive millstone, as customers drift away from the DX service. This service used to be highly profitable, hence why the shares were floated at a much higher valuation than now. Clever sellers, not so clever buyers, who obviously didn't understand that the high profits were unsustainable as email replaced physical papers being moved about by solicitors.
I don’t recall DX ever properly splitting out the figures for the solicitors DX service, it’s buried within one of the divisions. Things could turn very ugly, if customer business dries up, but DX is forced to maintain this large & expensive network of small physical sites. For that reason, I think this share actually looks quite high risk. So risky, and expensive.
.
.
French Connection (LON:FCCN)
(I hold)
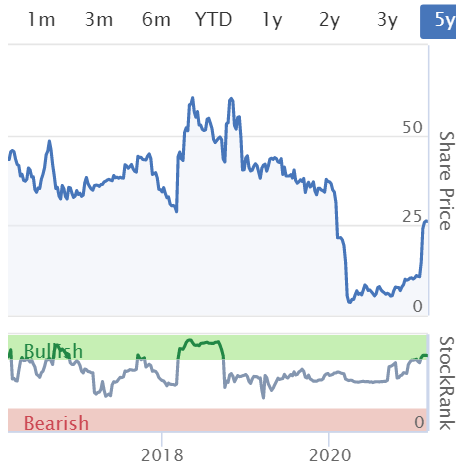
25p (down 6% at 14:52) - mkt cap £24m
Two announcements today, both issued at 12:30, suggesting they were co-ordinated.
Gordon Bros & Spotlight Brands
Announce they will not be making an offer for FCCN. This was one of two groups which had previously been identified as having approached FCCN about a possible bid.
FCCN announces that it has been approached by, and held talks with, three more potential bidders. So that makes 4 in total now.
FCCN has agreed with the Takeover Panel (see the full code here) to launch a formal sales process (FSP). This enables interested parties to talk to FCCN confidentially, without a requirement to be publicly identified. That could flush out even more potential bidders, who knows? It also gives more time for Go Global (the original interested party) to consider its options, without the previous 5 March 2021 deadline applying.
Anyone interested in bidding for FCCN should contact WH Ireland for further information.
My opinion - hopefully this could be the end game for FCCN shareholders.
I’m sitting tight on my shares, as I believe that this is an internationally recognised, long-standing brand that has considerable value. The wholesale & licensing divisions are profitable, and the loss-making retailing division could be wound down, perhaps more quickly under a new owner. Then there’s the potential to drive internet sales harder.
Someone who claimed to know Stephen Marks, commented on a bulletin board (so it must be true!) that he’s been rattled by the insolvency of Arcadia, hence is amenable to selling FCCN now. That sounds credible to me. I think this would make a nice management buy-in - i.e. bring in new management as part of a deal, with fresh ideas & internet knowledge.
In terms of price, personally I would be happy with anything north of 50p per share, but ultimately it's worth whatever the highest bidder is prepared to pay, and of course it has to satisfy Stephen Marks' expectations, as he has a blocking stake.
Fingers crossed!
.
.
Card Factory (LON:CARD)
68p (up 22% at 15:26) - mkt cap £232m
This is a high risk, financially distressed greetings card retailer. The share price was bombed out at about 35p until about a fortnight ago, when something very strange started happening - the share price has doubled!
Has the company successfully resolved its problem bank borrowings? No! That's what makes it so peculiar. The latest update (Friday last week) says (key part) -
... we continue to engage in constructive discussions with our banking syndicate, who remain supportive of the Company. The banks have provided further waivers in respect of anticipated covenant breaches through until 31 March 2021, taking account of the Company's cash flow projections, subject to certain conditions.
We are engaged on a plan to refinance the Company, and will provide a further update in due course. Coupled with the expected reopening of the vast majority of the store estate during April, the Board is confident the business is well placed to deliver for the benefit of all stakeholders.
So the business is lurching from one month to the next, getting short term covenant waivers from its banks - a highly precarious position to be in. It sounds as if a placing is probably underway as we speak. Therefore the risk to anyone buying in the open market now, is that you end up gtting diluted heavily in a discounted fundraising. Personally, I would never chase a share price up where a fundraising is being done, in financial distressed circumstances.
Big shareholders probably cannot sell in the open market because they're likely to have been made insiders, if I'm right about a fundraising probably happening behind closed doors (it couldn't be much clearer from what the company says above).
My opinion - we're in a very frothy stock market at the moment, and share prices are not being driven by fundamentals any more. A good story is all you need. It's exactly like 1998-99, in terms of sentiment & market froth, in my view. The danger with that, is a lot of new investors, who don't really know what they're doing, are learning all the wrong lessons in this type of market, e.g. chasing story stocks, ignoring valuation, ignoring balance sheet risk, bunching together into bulletin board (Reddit?!) story stocks, frothy IPOs going to instant premiums, and all sorts of nonsense in the US markets like Gamestop, Tesla, Bitcoin, SPACs, it's all absolutely classic bull market top type of behaviour.
In that context, who knows what story the bulls in CARD are getting excited by? Could it be that the Moonpig float has reawakened interest in greetings cards? A bear might think that CARD has missed the boat. But a bull might say that CARD has a great opportunity to up its game by becoming the next Moonpig, with a load of nicely cash generative shops too, and low production costs of cards.
Once the shops are allowed to re-open in April, then they should start generating cash again, but with a pile of debt & other deferred creditors to be repaid. So forget about divis for the foreseeable future - that was the main reason for owning this share previously.
It's frustrating for me, because I focus on fundamentals, which is how shares are usually valued! Right now though, weird & wonderful things are happening, and I cannot explain why CARD has just doubled in price, after putting out a wobbly update, confirming that it is financially distressed, and that a placing is very likely to be underway right now, at an unknown price.
In normal markets, any rational investor would steer clear. We're not in normal markets though. For me risk:reward is out of kilter here, so I'll leave it for the speculators, and wait to see how the refinancing goes.
.
(insert chart here)
Hotel Chocolat (LON:HOTC)
377p (up slightly today) - mkt cap c.£460m
I'll have to finish this later, as my eyes have gone, so can't look at the screen any more.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

119 comments
I have a very modest holding in Card Factory (LON:CARD) so when it fell, I wasn't much troubled and concentrated elsewhere. When I finally got round to it, before taking the loss and moving on, I decided to do some proper homework on it which included watching a video presentation from several key employees. The most impressive of these were the chaps that analysed the sales. I had no idea how complicated the business was, how aware they were of operating in a slowly dying market and how much attention they paid therefore to squeezing the last drop of cash out of the potential customer. I was immensely impressed. I liked the fact that they printed 75% of their cards too. This looks like a hard nosed, savvy organisation.
I could not see how any bank could benefit by pulling the plug right now, so decided to hold on. It was mainly indolence on my part but also a pure gamble on a 20% residue of equity. In addition, it did seem likely, as the vaccine programme appeared to take a grip, that High Street activity was about to rise and a massive release of pent-up frustration after a winter of enforced austerity might be more reflected in sentimental pocket money splurges rather than big ticket buying. Who knows? It would seem that I am not alone.
If French Connection (LON:FCCN) is a "is an internationally recognised, long-standing brand that has considerable value." do we know any UK companies with international aspirations, who may be interested in taking it on and introducing it to their ever growing marketplace?
Feels like a good fit to me and may move the news on.
I see McColl's Retail (LON:MCLS) shares are up 33% today, their stores are going to be rebranded as Morrison’s.
Only some (more) of the McColl's Retail (LON:MCLS) stores herbie and this was pretty much already known from previous disclosures.
They are actually up more than 50% over two days (announcement was on Monday). I bought back a small position a few weeks ago so I'm happy with the reaction, but my finger is hovering over the sell button now as it is not at all clear who makes the most money out of Morrisons Local - I suspect I know however.
Bromley, OK thanks, it was not clear from the announcement if it was all or just some as said 300. If it was already known then why are the shares up 50% this week?
It seems that this is just a name change on the 300 stores, so I’m not sure how much benefit it will do. I don’t have any McColl's Retail (LON:MCLS) near me. But it could be a possible takeover?
I' have followed the Morses Club (LON:MCL) story quite closely (investing off and on for a while) so I knew that this was about 1/3rd of their stores (the bigger ones - mostly I believe ex Somerfield, ex CooP .
It's more than just a name change, it changes the brand range and the operating model too, the rebranded stores reportedly outperform significantly; but I am still unclear who benefits most McColl's Retail (LON:MCLS) or WM Morrison Supermarkets (LON:MRW) .
When I said it was already known that was probably too strong. It was in the public domain that they were in discussions about more conversions and it was a no-brainer there would be some more and to be honest 300 is not IMHO a surprising number.
So why is the share price up 50%? Well I understand a couple of analysts have gone really positive on the "news" and substantially upped their guidance, Whenever I have taken a detailed interest in a company over a few years I have formed the opinion that the 'analysts' know next to nothing and understand even less. Maybe there was a lost opportunity here for me to better understand how they would react and reap the benefits?
It seems to me highly likely that McColl's Retail (LON:MCLS) will be bought out by WM Morrison Supermarkets (LON:MRW) at some point, but unless McColl's Retail (LON:MCLS) can actually prove their business model then there may not be too much of a premium. I suspect that WM Morrison Supermarkets (LON:MRW) will be quite cautious given that their last foray into convenience grocery was such a major disaster.
Currently long McColl's Retail (LON:MCLS) , but tempted to sell as I think this has been overblown.
I don't hold Boohoo (LON:BOO) but its a well run company and I think the financials look good. But when I think of £BOO and its current troubles I am reminded of the old Warren Buffet quote, “It takes 20 years to build a reputation and five minutes to ruin it. If you think about that, you'll do things differently.”
I believe Boohoo (LON:BOO) have been unfairly tarnished and regardless of the actions they have done to fix the issue, the perception remains. I hope in the medium term it gets resolved.
Hi Mr.Corbett,
What I'm focused on with Boohoo (LON:BOO) is the financial results. Ultimately over time, this will drive the share price, and overcome any worries about the supply chain, which is in any case being dealt with comprehensively.
The key thing is that none of the numerous press articles, and social media comments, have had any impact on BOO trading. The customers are clearly not concerned about ESG. Trading updates have been consistently strong, with expectations raised, not just during lockdowns, but also last summer when the shops could open.
I wonder if the alleged threat to its US operations could be overcome by creating a new US subsidiary, and operating from & distributing within the US, instead of fulfilling from the UK?
It's very easy to get deflected from a great investment, by background noise, which in this case can sometimes become deafening. But each time the share price plunges on this issue, it bounces back, because of the strong fundamentals.
I know a lot of people get frustrated, because so many private investors have such a short attention span, and want instant results. Whereas I think it's better to focus on the long term. BOO is going to be a much bigger, and much more profitable business in 5-10 years time. That's all that matters. Everything else is just a distraction, in my view.
Regards, Paul.
Afternoon Paul, I am afraid I am as lax as any other in not praising your efforts on the SCVR in words often enough (You do get the thumb daily especially now it is obvious I have voted) - Full blown Views and opinions from you in volume have made my annual subscription to Stocko for this year full value in just one days INVESTING EXPERIENCE from you and your report
As with any view not 100% will agree all the time - But keep up both your views and opinions please. Reading them even if I don't agree will at least make me think independently (I HOPE!).
PS - It might be my age but I am rather heavier than normal in cash at right now, always nice to have after a correction (NOT a prediction)
Sorry wrong board
Re Boohoo (LON:BOO)
Seems to me Boohoo might be well advised to engage with the lawyer & Liberty Shared, to invite them to share their evidence and discuss ways forward. This might result in a road-map for closure of this issue (edit: I.E. something Liberty Shares might suggest that is over and above all the steps Boohoo are already doing), by addressing some of their critics' concerns & proving they are serious about getting to grips with supply chain governance. A constructive dialogue is cheaper, faster and usually results in a better outcome. Worst case it is better to have your foes inside the tent peeing out, than the other way round.
(I hold).
has anyone else seen PensionCrafts latest video comparing the present situation to Japan in the 90s, its quite thought provoking
I like his videos, the man has no charisma, you wouldnt want to get stuck next to him at a party, but, he's extremely smart and well researched. Everyone i've recommended him to has ended up binge watching his videos
The Japan situation, albeit political driven asset value growth vs US current tech plus political driven asset value growth ended with the threat and increase in CB rates. Currently we are not close to CBs increasing rates, they are still spending like mad, so like for like (ignoring another catalyst) we have runway yet in asset value growth, both land/prop and equities.
not going to argue with that GInvestor, and with US planning another stimulus package in a few months, this bubble based on that video has further to run
Boohoo (LON:BOO), another own goal in my opinion. This is a £4bn market cap company, and yet they still fail to be on the front foot on PR issues. They have small company mentality and need to get used to playing with the grownups. They only have themselves to blame, whether true or not, this need not have happened.
Unimpressed
Roger - look at your post - if it has a blue "lightning flash" next to your name then you posted whilst logged onto the new site.
See - you get an Awesome badge AND a lightning flash.
Boohoo (LON:BOO) Liberty Shared seems to be a Hong Kong based charity but its VCMS program is funded by the US Department of State.
Boohoo (LON:BOO) British lawyers. You need to look at how British lawyers can target available revenue streams in order to enrich themselves. I use to work in an office block that had solicitors on the ground floor. There use to be queues of people hanging around outside everyday. They were migrants seeking legal advise. One Solicitor made so much money he turned up in a brand new Jaguar XJ that could barely fit in the parking bay.
Look at the solicitors that tried to prosecute British Solders in Iraq using tax payers money.
Cherie Blair and Shami Chakrabarti have both done it for various causes.
If a solicitor can target a pool of money available from government funds they will. Maybe there is money available to pursue modern day slavery cases.
Boohoo (LON:BOO)
From what I can see Liberty Shared have submitted a petition then announced to the world that they have. Has anyone seen any confirmation that the US authorities have opened an investigation. I can't find a definitive answer to this question anywhere.
It strikes me that Boohoo need to raise the anti by publicising what they have done to address the issues. Not sure an RNS on its own will cut the mustard in this day and age.
£AGY (I hold) has risen 8% today but the half year results aren't out until tomorrow is this a case of people guessing the results or am I missing some news somewhere??
insider trading I suspect. (I also hold Allergy Therapeutics (LON:AGY) )
In my view, these boohoo allegations will come to nothing. I also think that there is clearly an organised party that is behind these 'news' leaks. I mean for example, a British lawyer & charity complaining to the US? Why not complain to the UK authorities? Doesn't make sense.
I also think that there is clearly an organised party that is behind these 'news' leaks. I mean for example, a British lawyer & charity complaining to the US?
That's a very Boohoo (LON:BOO) centric viewpoint. Not everyone cares about our shareholdings as much as we do (I hold).
Liberty Shared is not an anti-Boohoo organisation. It's been around since 2012 and has developed a range of techniques for going after its targets. Using US forced labour tariffs is one such method - they used it on a Malaysian palm oil producer last year for instance.
Perhaps of most interest for shareholders here is the fact it worked:
The United States has banned imports of palm oil from Malaysian producer Sime Darby Plantation from Wednesday over allegations of forced labour during production, the U.S. Customs and Border Protection (CBP) said.
https://www.reuters.com/articl...
timarr
If it was the first time these allegations had been made then fair enough but it is constant. There is no doubt in my mind that this is orchestrated.
If it was the first time these allegations had been made then fair enough but it is constant. There is no doubt in my mind that this is orchestrated.
It makes no difference if the petitions are granted. If Liberty Shared have the data to support the allegations, regardless of source, then there's a good chance they'll succeed in getting Boohoo imports blocked. It looks like they have a data sharing relationship with the U.S. Customs and Border Protection.
Interestingly Liberty Shared have made two petitions - one is specific to Boohoo, the other one applies to all of Leicester bar a couple of ethical sourced suppliers.
timarr
Your evidence is - you must have some given your 100% certainty??
Boohoo (LON:BOO)
In my view, these boohoo allegations will come to nothing. I also think that there is clearly an organised party that is behind these 'news' leaks. I mean for example, a British lawyer & charity complaining to the US? Why not complain to the UK authorities? Doesn't make sense.
I went to the source of the story to see if i could garner any additional infromation as to whether the news is coming from the authorities or perhaps a "third party somewhat biased viewpoint" - ie possibly the people doing the complaining talking their own book so as to speak.
The article didn't really make it explicit who or what the source of info is
i will repeat the relevant text here
"US Customs and Border Protection has seen enough evidence to launch an investigation after petitions from a campaigning British lawyer."
The article writer did take the time to repond very promptly bearing in mind they have probably had a busy morning in this regard. The reponse was very non commital in that they advised they could not discuss sources of information - they did reiterate though that the story is accurate so it appears they are sticking to their guns hear journalistically speaking ref what they have quoted.
The middle ground here is there may be a very low hurdle to acheive to warrant an investigation - and it may be that investigations are very commonplace and normally result in none to little action so i am no further forward as to whether there is likely to be in the system that is to come out soon that would at such time it comes out materially affect the shareprice. Its annoying though that the uncertainty exists here as to whether there could be pending investigation.
It's probably all my fault as i only bought back into this share last week ! - only good news is that depsite this news i have the option to sell at the price i paid for the shares if i so choose. So if i do continue to hold i can only blame myself if things get much worse in the near future.
I think this later Guardian article sums up the situation rather well.
https://www.theguardian.com/bu...
Last year the CBP issued 13 such orders, more than in the previous four years.
Simon Bowler, an analyst at Numis, said: “Orders to prevent the import of product under these regulations look to be rare, and the nature of an investigation across a complicated supply chain that is in the process of being overhauled, for which no evidence of modern slavery has yet been found by current UK enforcement bodies, means that the direct risk arising from these letters feels remote.”
Clearly I'm no one's favourite Boohoo (LON:BOO) analyst ;) ....
And I'm not going to say I'm particularly expert. I have looked in a bit of detail and can summarise that I like some things and dislike some other about it.
IMO I thought the Debs transaction was perhaps a little odd. I see the opportunity in it....but focusing more broad spectrum UK seems a less good high margin high growth path than continued rapid internationalisation. Here's the note I wrote (see points 1, 5, 8, 10, 13 as most pertinent in connection with this)
https://www.stockopedia.com/co...
I've always been sceptical that the path to international growth is golden. Not due to legal issues but more taste and vibe and a belief that for a non super brand like the boo collective of brands there needs to be a lot of groundwork in country to fit commercially and style wise and get the customer attraction and acquisition process right and really humming like it does in the UK....
...and so this made me wonder whether the Debs platform acquisition and buildout plans were really a signal that growth is going to be much more UK centric going forward...which IMO will be capital intensive. This could be good or bad for the sp...all demands on how top line and investment meet.
A hiccup with the US legally would reinforce the above.
I'm providing questions not answers!
Good to have some more more balanced views on BOO. I personally think the ESG issues could have a lingering effect for quite some time so staying clear. Fixing the issues could prove very costly, but also need to consider that many fund managers will simply avoid this name on ESG grounds and that can keep the share price depressed for a long time (look at the tobacco stocks). Perhaps the biggest concern is that this seems to be have become a bit of a witch hunt and I'm sure there are a lot more journalists trying to uncover stories - could this eventually impact the brand?
On that point, I am mindful that fashion can be very fickle for the 18-24 age bracket. In a few years BooHoo and the related brands might have gone completely out of fashion. It's hardly a timeless brand that will be around in say 20 years. Yes they have other brands for older demographics, but I suspect all the growth has come from the original brands.
Yes Bouden...as is often said often on here, why take the risk? Especially with so many other quality stocks moving up so strongly. Unfortunately the company is under such a cloud at the moment (maybe unfairly).
What is the thinking behind awarding the title 'Awesome Stockopedia Subscriber' as marked by the gold rosette next to each and every name here?
Luckily I don't see that (old site effect?). Maybe they're trying to tell subscribers that Stockopedia is Awesome.
mercury61 - it's your reward for logging into the "new" site. Some of us don't worry about such things.
I suspect it dates from when non subscibers would access these boards. Since that's no longer the case it's obsolete. And might be best eliminated.
I quite like being called awesome. It happens rarely, if ever. .
I'm afraid that those of us still on the old site are not labelled as awesome.
Seems you are as far as those of us reading on the new site can see!
How do I tell if I am logging onto the old or the new site?
Once logged in, click on your profile button on the top right of the screen. A drop down menu will appear. One of the options will be to switch to either the old or the new site...
Only if you are an older subscriber, not sure of the exact date but I think anyone, who joined in the last year, will only have access to the new site.
I use the old site 99% of the time.
Here are my SCVR heat maps for today (prices as at ~10am).
Small Caps with RNS news today ("N!!" in bottom row of the heatmap tile means report / update today):
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
PS: See my main heat map thread for more (non-SCVR specific) heat maps, and keys to the heat maps contents
Cloudcall (LON:CALL)
Next!
Increased unemployment in Leicester seems an inevitable consequence of the continued press "interest". in BOO. Choppy share price in the meantime until press wear out the story and move on.
Boohoo (LON:BOO) (I hold) it only gets worse. Via Daily Express (owned by Reach (LON:RCH) I hold):
“Boohoo shopper's horror as she finds spider 'the size of her bulldog' in parcel “ https://www.express.co.uk/news...
Humour alert just in case.
Regards
Michael
The world's smallest Bulldog apparently...
:-)
"In a series of horrifying videos, she detailed her ordeal upon finding the spider"
Oh, good grief! It's a spider. In a sealed package, so it couldn't get out. I read this not long after watching some of the reporting from Yemen on the news and it certainly makes you think about people's bravery and resilience. 'Ordeal' indeed!
apropo of nothing in particular I ordered a headboard online yesterday and the chap I am dealing with said:
“...everyone seems to have gone completely mad kitting out their homes!
Our sales for January and February were double what they were last year and yesterday we had another record day.”
The bed it goes with I ordered on October 21st.
Certain sectors seem not to be suffering from Covid, indeed quite the opposite.
This is what makes me sceptical about the 'pent-up demand consumer savings to the rescue' hypothesis that is apparently going to turbocharge the economy.
We've been spending money on bigger ticket items for our homes all throughout lockdowns (I spent a grand on an office chair - my spine wept with relief, my wallet with pain), doing up houses, buying furniture etc, and yet somehow the herd-thought is that if only we can get to the hairdressers or the pub the economy will fly.
I'm not buying it. We aren't going to get twice as many haircuts to make up for lost time, and I won't be buying a new office chair (ever - if they cost this much). The modifications we've made to our homes are for the long-term and won't be repeated, whereas the service economy is not subject to inelastic demand. As David Rosenberg said: 'we aren't going to Disneyland every weekend'.
There's a gap somewhere.
There are whole sectors of the economy that have been shut down, their staff losing jobs or income, owners losing income or business. When they are allowed to restart they will generate income and demand. Yes it’s remarkable how much commerce has continued over t’internet, but a lot more will happen from shops when they open and we can freely enjoy looking around.
As for demand, things we can not do at present include: go out for a meal, a concert, a drive into the country, a short break, a holiday, a session in a bar or pub. We cannot hold or go to a party or any large celebration, we cannot play sports, we cannot attend sports, theatre, fairs, circus, conferences, classes, country shows, air shows, dog shows, etc, etc. The point is people, me included, are desperate to do many of these things and they will all engender significant spending.
You are talking about supply, I am talking about demand. The peloton standing bike, sofa, headboards for beds have all been bought, the conservatory has been built. What's left are haircuts, pints, weekend breaks, and theatre as you rightly identify. Not only are they relatively small ticket, the demand is not inelastic.
I can't wait to get back in the pub, but how many Sunday sessions before I'm all pub'd out? We're not going be going to the pub at double the rate that we normally would for six months straight, which is what we need to ensure the pub sector earnings stay flat for the year. How many air shows are you going to attend before your thirst for air shows is sated? How many trips to the circus?
Add in to this shortfall the fact that big ticket buys will decline, because they've already been bought through lockdown. So we'll switch from bigger ticket to smaller ticket purchases, except the yearly volume will be cut drastically due to lockdowns. So less of less.
How does that add up to a turbocharge?
IML
A few thoughts:
‘They are relatively small ticket’ - er I don’t think you have been to a concert, a test match, a Premier League football match, an Opera or similar. Tickets cost plenty, sometimes £100s, then there is travel, drinks and a meal out, maybe get your hair done, a new outfit, etc
‘How many trips?’ - Well who knows but at the moment there are zero! Eg PL football match has 30k - 60k attendance for 10 games a week, repeated 38 times....
Yes the turbo charge comes from the fact for so many sectors we starting from nothing!
But insolvencies were very low last year due to Govt. support. Unemployment is rising now and I see that continuing and insolvencies increasing when the support ends.
So football clubs will benefit, good for the high paid players.
I also suspect the "pent up demand" may underwhelm. The surplus savings have largely accumulated to the already well off and many millions of people have been pushed into financial difficulty. Without the helicopter money as seen in the USA I think a consumer recession is more likely after a short lived spike in spending.
I don't really agree with this. Whilst I do agree that all the talk of pent up demand and 'accidental savers' misses the fact that many people have been financially devastated I think it is more complex than that.
There is a risk of over-stereo-typing this, so I apologise in advance, but as it see it :
The two, financially, winning groups are :
On the other hand the , financial, losers are :
So on balance I do think there will be a strong bounce back economically. However, other than a short term pressure relief splurge, I cannot really see any reason for greater economic activity than before. So I'm cautious of companies now valued higher than pre the pandemic, unless there is a good reason.
How does that add up to a turbocharge?
I think the other issue is likely to be supply restrictions. Social distancing and capacity restrictions are likely to remain in place for a while - perhaps even through next winter. In theory prices would go up, but frankly there's only so much people are prepared to pay for a wilted lettuce and few breadsticks.
There are a few big ticket items that might get a boost though - holidays, cars and houses.
On holidays while I think it's entirely reasonable to expect to see a major boost to domestic tourism it's quite hard to see how you'll get a big overseas holiday season. Vaccine passports down specific corridors - to Greece and Spain mainly - seem like the best route forward.
You could also see a boost to car purchases - if people are travelling more and don't want to share personal space then a new car might make sense. And presumably Sunak's budget will try and boost house sales, as it always does. Post-lockdown last time saw lots of people in shared rented accommodation moving as soon as they could get away from their hideous housemates.
Other areas, where people have found suitable substitutes during lockdown, are unlikely to fully recover, at least for a while. Working from home won't disappear, so commuting will probably be permanently reduced impacting trains, buses and all of the ancillary services that supply them, as well as all of the casual businesses around commuting corridors. Business travel budgets have been slashed, at least for this year. And I'm unlikely to see the inside of a barbers again.
If you wanted a tangential play on reopened I'd look at medical technology companies who have seen revenues hit by non-critical (and some critical) treatments and surgery being cancelled. There's one hell of a backlog to get through, for those who survive long enough to benefit from it.
timarr
They are all British as well, few imports (apart from Premier League footballers)
Yes that is a good point. I suspect (but don’t know/am not sure) there will be an initial surge of holidays booked, meals taken and parties/weddings etc held but after that who can say? Everybody (apart from pensioners it seems) are going to be paying more tax, I cannot see how unemployment cannot go higher and remain so for quite sometime (but them I am by no means a macro economist) and if you are working you might want to take 6 weeks holiday to make up for the lost ones but don’t have the time.
Further a lot of these companies will be much more indebted and trying to rebuild balance sheets. I cannot see Easyjet (LON:EZJ) buying any more planes for a few years for example.
Another unknown is interest rates, if they rise at some point (which I would have thought they might have to sometime) then the consequent rise in mortgages will suck a lot money out of the economy.
Anyway there seems to be a lot of moving parts and it is certainly to complicated for me to get a handle on. Hence no investment in Saga (LON:SAGA) or Escape Hunt (LON:ESC) for me.
Regards
Michael
Hi IncredibleMosesLeroy
"we aren't going to Disneyland every weekend" true, but only because it's a long way away. We're definitely going to the pub, theatre, restaurant and cinema every weekend (and weekday evening for the first few months, if my work-mates are anything to go by).
In short I do buy into the pent-up demand/coiled spring theory. It seems to me a lot of it has been priced-in already, but it's real.
Congrats to your back! Would you mind telling us what you bought? Not entirely happy with mine.
A Herman Miller 'Aeron'
https://www.hermanmiller.com/e...
Thoroughly recommended but hand your wallet to someone else to order for you whilst you rock back and forth in a hot bath listening to whalesong.
If you don't mind buying reconditioned there are many on eBay at around £300
I'd imagine the supply will be good due to lots of offices closing.
I have the Aeron in France and the Mira (Mira is cheaper) in the UK and to be honest you can not tell the difference. Both picked up on eBay and because they are so well built the second hand ones are as good as a new one.
You can pick a Mira up on eBay for £300 delivered and it is worth every penny. Will decades literally. Worth the money.
I did a search on e-bay and found a site doing reviews for chairs that weren't as expensive but were as good as the Aeron. Paid £225 for an equivalent and its fab. I couldn't justify £1k+ for an office chair when the wife has an Ikea one...............
In my area a local tradesman said people he knew in construction and related trades had more work than they can handle.
The problem with Boohoo (LON:BOO) is that even if this is a rehash of the old issues, they've done serious medium term damage to their ESG reputation that leaves a lingering smell; one that is hard to shift, no matter how many judges you appoint or reviews you undertake. It is a continuing headwind that undermines what should otherwise be a compelling business case. I bought Boohoo and Asos at about the same time - the latter has all but doubled, while Boohoo is only now back to my buy price. (Well, it was yesterday). The opportunity cost of continuing to hold is becoming tedious, and even if significant changes have been made, the PR battle is still a long way from being won. Part of the issue is that they are seen as having sailed fairly close to the wind in terms of their practices for a long time and having cleaned up only when they had to - contrast this with Marks and Spencer who've faced a number of sweatshop scandals over the years but have been able to sound more convincing in terms of their position on these issues, and have been able to leave them behind. With Boohoo they can't shift the narrative. Not out yet, but in a market that is anything but dull, I'm beginning to wonder if there aren't better opportunities elsewhere.
Two thoughts on this Boohoo (LON:BOO) ESG issue:
Yes it’s having an effect, and it clearly is difficult to escape, but others beforehand have been successful in rehabilitating their reputation, and boo are taking the right measures for these issue to be left in the past. There are plenty of companies who have been here before and moved on, Tesco and Apple are two that come to mind (and remember the allegations re Apple were that workers at their suppliers were killing themselves because it was so grim working on Apple products!).
Secondly, I wonder is this a bit of a lockdown effect? At the moment so little is happening in the World compared to usual, news companies may be more determined than usual to hold on to stories and keep recycling them.
That said I do find it bizarre that the long term consequences of all this may be a reduction of employment in Leicester and an increase in a country with lower wages, standards, etc...Boo do seem determined to keep employment in this Country, good for them, but it seems many would be happy for the jobs to go elsewhere.
On a positive note, the senior management won’t need to work hard to reinforce to all their managers and staff how important following correct procedures are!
The next big ESG announcement will come along in a few weeks, including its full audit of U.K. producers and updates on its model factory in Leicester and its overseas producer audit, along with the results for 2021, it will be interesting to see how the share price looks then.
I hold.
£BOO. Yes indeed. As I understand it this is a man whose father came over from Kenya from nothing and started with a market stall. Who has made something from nothing. The drive, hard work and shear determination to succeed and to achieve what he has achieve is extraordinary and yet the press have found every excuse to try and destroy what is without doubt a success story.
Do I wish I didn’t hold it? Maybe but not because of ESG concerns but simply though I believe that the share price will be multiples higher in say three years time it is going to be a difficult ride and mentally I am not very good at handling that.
I am bot going to sell until the results in April or if there is an import ban from the states. That said it it has convinced me that overweight positions really are not worth the grief.
I hold.
Boohoo (LON:BOO)
The longer the share price underperforms, the cheaper it will be. Eventually it will rebound.
Which is fine, or an opportunity, for long-term holders, but not those looking for short-term outperformance. Seems to me that will be an apparently random roller-coaster unless you have inside info on when the next grenade will be chucked.
There's no sign of a significant impact on real world sales, though there must presumably be a cost to the work they're doing in Leicester. In the background, they must be looking at options to buy more from overseas. And at warehousing in the US and EU. Neither will be entirely straightforward given their business model.
£call
"...but the PrimaryBid offer has only raised £0.3m..."
That seems a little odd, when my perception is that most (all?) stocks offered to PrimaryBid's contact list over the last year have risen quite strongly after the placing has taken place.
Have PrimaryBid placed any stocks that have drastically fallen in price afterwards that might explain the lack of appetite for Cloudcall shares, or are investors getting more nervous lately?
Does anyone know if PrimaryBid does any due dilligence on the companies it does placings for, or is it just the modern day equivalent of the likes of City Equities etc that used to be infamous for placing shares in virtually any company they could profit from (allegedly)?
(I haven't bought any stock via PrimaryBid yet. I was on their mailing list, but I seem to have dropped off it as I don't recall any recent emails from them).
Hi gtrdave.
I’ve used Primary Bid as a a source of shares off and on for a few years. I’m not aware of them doing due diligence on any of the companies that they place shares for although most of their offers seem to piggy back on wider placements with the institutions coordinated through the more traditional brokers which can provide a bit of comfort.
In the early days many of the PB offerings did seem to come from pretty canine Sucker Stock beasts in the Oil & Gas and Mining sectors but they seem to be gaining a broader spectrum of sometimes higher quality companies now. Still tend to be a bit Parson’s egg - good in parts. In terms of yesterday’s Cloudcall offer, this may have suffered from there being an issue at the same time for Serabi Gold (LON:SRB) which looks to have been a success and probably swallowed up much of the available PI liquidity. I looked at both and used the offer to top up an existing holding in Serabi.
Hi gtrdave
I looked at the PrimaryBid offers yesterday, and decided not to participate. One of them at least was offering shares, but those who bought in the placing got a warrant as well. Not exactly equal treatment for the retail investor!
I do not think you should assume that shares offered on PrimaryBid necessarily go up. Look at Applied Graphene Materials (LON:AGM) which was offered at a 40% discount to the market price. I bought some (though got only 18% of what I asked for) and the share price immediately dropped by 40% where it has stayed!
ricardo
I think the PrimaryBid offer did poorly for Cloudcall (LON:CALL) because the fundraising was announced after market hours (so some investors might not have known) and was open just overnight.
Also the placing was done at no discount to the share price at the end of the day - so there were no tasty discount to lock in instant gains.
The more encouraging thing was that the bookbuild was well over-subscribed given no discount to prevailing market price.
Will be interesting to see who picked up more shares. A US Investor maybe?
Also telling, management did not dip into their own pockets to participate... and in fact are renegotiating themselves a better incentive scheme, for up to 15% of shares instead of the 10% before...
Many thanks to everyone who responded to my questions about PrimaryBid.
dahokolomoki said: "I think the PrimaryBid offer did poorly for Cloudcall (LON:CALL) because the fundraising was announced after market hours (so some investors might not have known) and was open just overnight".
I thought all PrimaryBid placings were announced after market hours giving investors quite limited time to research the company and make funds available, but I could be wrong on this.
"Also the placing was done at no discount to the share price at the end of the day - so there were no tasty discount to lock in instant gains".
"Also telling, management did not dip into their own pockets to participate... and in fact are renegotiating themselves a better incentive scheme, for up to 15% of shares instead of the 10% before..."
Your points provide a good explanation of the lack of interest in the Cloudcall (LON:CALL) offer from PrimaryBid.
.
No comment.
Good news.
Just used Stockopedia's "set up your own screen" system to track down Prime People (LON:PRP) [a very small cap], and snapped up some shares like an eager (and very hungry) crocodile.
Thanks to you brill people at Stocko!
.
Very unwelcome intervention on Boohoo (LON:BOO) (I hold). Either Duncan Jepson/ Liberty Shared know or think they know something we don't (new "evidence") or they have another motif. I can't believe he's not up to date on developments since the matter of labour conditions at Boohoo suppliers was first raised.
This isn't actually the bad news for Boohoo I was expecting this week, that's potentially yet to come in the Budget Statement. Double checking my seat belt...
It seems a little odd, considering Boohoo, as detailed in their response, are taking lots of positive action to tackle the issue. They're not just trying to shrug it off or pay lip service.
I expect there are many other high-profile brands who would be more deserving targets of a campaign to improve working conditions.
Re Boohoo (LON:BOO)
What I found interesting about the article was the use of the term 'campaigning lawyer'. I hadn't seen that before but it would explain the long series of attacks. The article seen previously were done under the name of journalist, or the paper or were anonymous. Presumably it's someone in Leicester.
Hi Paul - agree with your comments on CALL.
I think it's a good price (minimal discount, although the price clearly sold off due to insider dealing) and getting it away now means they won't be raising when the funds are running dry. That's a positive as companies often raise when they have to rather than when they could do.
I'm a holder but I'll set my alarm for another six months and check back then. There are better opportunities elsewhere at the moment.
Boohoo (LON:BOO) have just put out a response to the article this morning:
boohoo notes recent media commentary. The Group has not received any correspondence from, nor is it aware of any investigation by, US Customs and Border Protection ("CBP"). The Group is confident in the actions it is taking to ensure that all of its products meet the CBP criteria on preventing the product of forced labour entering the US (or any of its markets). boohoo continues to fulfil orders to customers in the US across all of its brands. The Group will work with any competent authority to provide assurance that products from its supply chain meet the required standard.
Over the past 8 months the Group has been working closely with UK enforcement bodies. If the Group were to discover any suggestion of modern day slavery it would immediately disclose this to the relevant authorities. In addition, Alison Levitt QC's independent review (the "Independent Review") into boohoo's Leicester supply chain, published in September 2020, stated that "there is no evidence that the company itself or its officers have committed any criminal offences."
As a result of changes already under way since 2019, and those initiated through the Agenda for Change programme, which includes implementing the Independent Review's recommendations in full, the Group's supply chain in Leicester, and oversight of it, has been significantly improved and strengthened. The Group has made significant progress in a number of areas, including:
● Appointing Sir Brian Leveson PC to provide independent oversight of the Group's Agenda for Change programme
● Appointing Bureau Veritas and Verisio to support the ethical audits of suppliers and subcontractors, together with enquiry and enforcement specialists headed by former Deputy Commissioner of the Metropolitan Police Tim Godwin OBE to support Sir Brian's independent enquiries
● Continuing to map and audit the Group's tier one and tier two supply base, in the UK and internationally, led by teams from Bureau Veritas and Verisio
● The completion of over 400 on-site audits on UK suppliers
● Removing 64 suppliers from the Group's UK supplier list, who did not meet the Group's standards on the levels of transparency required
● Committing to publish UK tier one and tier two supplier list by end of March, and global supplier list by the end of September, which will both be updated every 6 months
● Significantly investing in strengthening the Group's internal Responsible Sourcing, Compliance and Sustainability teams
● Establishing a Supply Chain Compliance Committee reporting to the Board, led by the Group's Director of Responsible Sourcing
● Appointing KPMG as consultants to advise and monitor the implementation of the Agenda for Change programme
The Group and Sir Brian Leveson will continue to provide stakeholders with further updates on its Agenda for Change programme, including publication of its first Annual Sustainability Report alongside its 2021 Annual Report and Accounts.
Never has Stocko ratings shown themselves to be more accurate than Cloudcall!! I have sold my holding on the grounds it is simply flogging a dead horse. I wish you luck Paul.
I miswrote the sale was of Oxford Genetics !
For those that did not notice Mercia Asset Management (LON:MERC) had a profit upgrade and a successful sale of Oxford Biogene yesterday afternoon.
Deegee Eff -> Mercia Asset Management (LON:MERC)
The reaction today and yesterday to the news is quite muted IMO. I think one pager from N+1 Singer summarises the under reaction so far (available on Research Tree). The OXGENE transaction 'emphatically' proves out their model.
This is snapshot of balance sheet VC portfolio at half year (30 Sept 2020):
The also had £25m cash at this time so an asset backed NAV of £126m. Add a net gain of £14m from OXGENE exit and get asset backed NAV of £140m. There will be gains and maybe some losses over 6 months to end of March 2021. I think gains given cycle, areas of focus and the fact that in March 2020 they took quite big covid write downs in some industrial assets (eg Warwick Acoustics which provides high end audio to high end cars and personal use -> more DJs and music professionals than punters). Nevertheless...
Market cap at beginning of today is £119m so near 20% to get to asset backed NAV and £50m of that NAV is in cash....
And this places zero value on the 3rd party asset management business that manages c.£750m (ex the balance sheet) and is growing. This is sticky and high fee as EIS, VC and VCT money. Brokers typically ascribe £25m value to that. That's conservative for a variety of reasons but lets stick with it and we get to tangible asset backed plus asset mgt biz of £165m...
Portfolio is mix of tech (biggest position is VR game co), technology, industrial (IP and tech backed) and healthcare. It focuses on the UK ex London and SE for investment believing they have less competition there, lower valuations for entry and that the regions ex London and SE are disproportionate providers of innovation success stories.
They've started paying a dividend. Its modest but its based on the asset management business and as that moves into positive operating cash flow (estimated £4m for fy21) its well supported and with room to grow. They need to clarify further on this as there are some acquisition contingent payments due in next couple of years and it depends how they meet them (from op cf or balance sheet cash) on how much is left for dividend (my preference is that they do from op cf).
Conclusion: A growth portfolio and a growing asset manager at a discount. I note that a not totally dissimilar but much trendier/viby Draper Esprit (LON:GROW) trades at considerable premium to asset value....
Note, its early stage VC so the journey per company can be lumpy and some companies will fail. An under appreciated strength IMO is that Mercia have taken their write downs well and early and also be able to exit businesses they no longer have confidence in through industry sales minimising loss.
Ex post addition: this fulsome note from Edison just out (obvs its paid for!)
https://www.edisongroup.com/pu...
Mercia Asset Management (LON:MERC) - yesterday's RNSs were a little dissonant though.
Profits after tax at the interims were £8m.
Realised gain on Oxgene: £15m.
So, that's the £23m forecast comprehensive income for the year, implying a net contribution from everything else in 2H of nothing.
Or have I missed something?
No, you're right IMO. I noted that yesterday here:
https://www.stockopedia.com/co...
A few reasons, Could be...
I think its a mix of all three. I'd guess that on 1 they will have a good feel across their portfolio but they cannot say anything at all until the formal end of year valuation process. My (100%) guess is that write-up is probably more likely than net write down as that is the normal direction of travel even allowing for the J-curve effect plus they took big write downs at 31 March 2020 due to covid hits (so the worst point in time too....right when everything was most uncertain, and the process even though completed in May-ish 2020 must be based upon end of March information). Add in the cyclical recovery in the mainly manufacturing-tech holdings they wrote down and the odds are good for an increase.
So on 3, I think there's a good chance of a 'surprise' in the bag. They would like to do this obvs as it helps keep the attention on positive news flow momentum.
Mojo - I should have been clearer.
The dissonance was with the comment that "the Group's full year adjusted operating profit* is expected to be materially ahead of current consensus forecasts" which then seems to wiped out by something not alluded to in the RNSs. I looked at it this morning and concluded that they just reported the good news - the sale of Oxgene and fund management profits, but there may be more write downs in their direct investment portfolio.
But the liquid asset backing provides a good margin of safety.
Adjusted operating profit is purely for income producing activities (fund and directorate fees, former much more significant) so not the change in value of investments and (I think) before non cash adjusting items such as amortisation of recent (and so sizeable) acquisition intangibles, share based payments, etc. So at a consolidated income level this may be closer to zero than >£2m of adj OP for fy2021. Interim illustrates:
Adj OP £1.048m is negated at consolidated level by £1.167m of amortisation....then both are overwhelmed by the asset value moves (£1.704+£6.730m).
Adj OP under states operating cf too which is £2.002m...or £2.743m if taken before working capital movements:
Note that the £1.704m of realised gain in the income statement is not in the op CF above as that is recognised in cash flow from investment activity (its a cash gain rather than a valuation gain).
So bit complex perhaps but I'd say that 'income' from the asset management business on an ongoing basis is looking something like £4m pa and that is what they pay dividend out of. £4m ongoing 'income' (its not accounting definition of it so that's why in quotes) supports £25m asset manager value very well! Jupiter Fund Management (LON:JUP) for example are 12x earnings and 9x cash flow. I'm not going to push this point hard though as we do need to see where the asset management profit levels out in coming years (and costs have been helpfully reduced due to covid short term) as the biz matures....but £25m is pretty conservative
One of the issues with Mercia Asset Management (LON:MERC) is that it can be a bit difficult to read the financials. Now, I believe that Mercia have been a bit guilty in the past of using a bit of complexity as obfuscation when they were loss making and establishing themselves etc. Maybe naughty...but also very common place and particularly in VC and growth business space. They could put some work into simplifying...
They are two businesses in one - an asset manager and effectively a closed end fund. The accounts blend costs, gains and incomes from both so need to unpick.
I hope the above answers your question. You're observation is correct...but hopefully this explains
Note, the N+1 Singer note today is wrong in how they treat valuation as they effectively double count the value of the asset management business in getting to their c.£195m value for the business as they give £25m value to asset manager and then also count the goodwill on the balance sheet as a separate asset but that goodwill is primarily for prior acquisition of asset management businesses! So my £165m is 'clean' in that cash + portfolio inv + £25m for asset management. £25m is low IMO as the assets are high fee and very sticky....plus I think the holding value of investments is on balance lowly marked...so mark ups not guaranteed but I do think the experience with OXGENE will be representative of exit mark ups (off course there are some failures so not everything marked up)
I can't see the table fully on my mobile but I note that Concepta is now renamed Myhealthchecked (LON:MHC) and is up five-fold in the past few months. It might be a ramp though.
.
HELP!!
.
Re the small caps, which are consultancies or software companies that install AI solutions for other companies? Ie they are the catalysts of change. And if they have prospects of a global customer base.
Indeed, if AIM and other indices are a database of small caps, how do you mine them for the type of company you want, with the type of dynamic management you want?
PS: Am also looking for companies that have taken AI on board (eg Computer Games companies) and are already using it to get and keep a competitive advantage.
Thanks
.
You might want to look at Renalytix Ai (LON:RENX) and Verici Dx (LON:VRCI) in the medical sector, and at Draper Esprit (LON:GROW) which is a private equity outfit with major holdings in what I think are some serious high tech companies.
I hold all three. Note that Verici Dx (LON:VRCI) only listed very recently as a spin out from Renalytix Ai (LON:RENX) .
Good luck.
Ricardo
£IQAI + £ DMTR also biotech , I think also £TERN , also Frontier Ip (LON:FIPP) , Blackbird (LON:BIRD) has interesting tech and IP
I remember wondering if the Stockopedia subscription would be worth the money. Paul, your insight into Saga (LON:SAGA) has repaid me many times over on it's own. It is a big thank you from me.
Even if you didn't share my enthusiasm for Naked Wines. :-)
The FT's Lex column today tries to pour cold (sea) water on cruise lines' shares, incl £SAGA. But the FT's grip on the UK small/midcap market is, as we know, slender.,
now theres a question...what is the return on investment on our stocko subs. without giving values away my first years return was only realistically measured in dB
I have not known investing without Stockopedia. I started in investing in 2012 and subscribed in 2012 after reading a David Stevenson article in the FT. But two spring to mind Boohoo (LON:BOO) 44% CAGR over five years and Globo got out with a small profit!!!
I also invested in Bioventix (LON:BVXP) (still hold) in October 2015 after watching Paul interview Leon Boros.
I got to know about Stockopedia because of Globo, was debating that on IC and looking for more information I came across Paul’s postings, I always felt there was something wrong with it, figures did not seem to add up to me.
Bioventix (LON:BVXP) was the first share I bought because of Stockopedia and the Leon Boris interview, I did sell out last year but have bought back in again fairly recently.
Paul’s insight into Saga has paid off half my outstanding mortgage....or it would do if I was minded to sell any shares which I am not.
I’ll be making a donation to Zane in April to say thanks.
Sky News article, at the top of the app about Boohoo (LON:BOO) (Boohoo) this morning. Facing US trading ban. Accounts for 40% of revenue. I know what the retorts to that will be but it's getting tough for Boohoo to escape this Leicester slave labour line.
Look at every item of clothes you own. Most will be made in Asia somewhere, even high quality brands. Are the media telling us that many of these products are produced in conditions far superior to those in Leicester ? I doubt it! I do have a small speculative holding in Boohoo (LON:BOO) but aside from that this is clearly a media witch hunt. Also on what basis can a government ban a seller of cheap clothing - national security?! If they ban Boohoo (LON:BOO) then there should be plenty of others who should be treated in the same way. The story is probably an attempt to force the price down and enable someone somewhere to make a fast buck!
A lot of if's in the article, this looks like a continuation of the slave labour issue that £boo seems to have a handle on, that said if Boo are taking US sales, then the US is likely to ban them on the basis that the US like to look after the US market first in the case of online gambling until the US companies catch up.
But , what about the Apples of the US economy getting the questionable Chinese labour to make their phones..... This is where the US market looks after itself ALWAYS.
What is clear , is that £boo needs to get its house in order and double quick, which it will and medium term this should be a non story, it is the first article on the skynews web site though, so likely to be a bumpy day for £boo
Boohoo (LON:BOO) should be able to demonstrate the action it has taken hopefully and reach out proactively to authorities, but I note that the US has banned some quite major suppliers on slavery grounds before so I wouldn't regard it as an entirely empty threat. E.g. two subsidiaries of one of the world's biggest medical glove companies although in this case I remember watching a video on Channel 4 of people living in crammed, basic hostel style rooms during the pandemic which looked like it was on a different scale of severity than anything Boohoo (LON:BOO) is alleged to have allowed in its suppliers.
a great opportunity to buy more. For about the sixth time in the last 5 months
This happens SO often to British Companies trading in the US. UK politicians so often refer to the UK’s special relationship with the US. Not when it comes to British Companies trading in the US it isn’t.
What about BP? Milked for all sorts of spurious claims including from people and Companies not affected at all by it, after the Gulf of Mexico disaster. And President Obama insisting in calling the BP BRITISH Petroleum.
Tesco tried to expand there. Failed miserably. Marks and Spencer with Brooks Brothers, and before that Dixons.
Up to now I’ve been relaxed about BOO events for reasons so well covered by Paul and many others here, but on this one the US is very likely to make sure BOO can’t trade in the US. Any excuse will do.
Best to assume that BOO will take a big US hit and then be relieved if it doesn’t rather than just dismiss it as another storm in a teacup. A question is how much BOO can make up for that lost trade with fast expansion elsewhere?
And how much further short term will the share price fall?
I don't think you can jump to that conclusion re BOO in the USA. Bear in mind that it's so small relative to the US market, that BOO wouldn't even move the dial over there. Worst case scenario they might have to re-brand within newco for US sales. That would be hugely disruptive, but recoverable, in the worst case scenario.
If you watched the Parliamentary appearance by Mahmud Kamani, founder & big boss at BOO, with his team, they've got chapter & verse on what's been done to fix the supply chain problems. They're taking it super-seriously, as was clear from the parliamentary hearing video. Hence a very strong case to defend themselves. I expect a few boxes of paperwork will be landing with the US authorities, detailing everything that's been done to sort this out.
I hope you are right Paul. Up till now I’ve agreed with nearly everything you’ve written about BOO, but I’m not convinced that because “Boo wouldn’t even move the dial there,” that it means it’s fairly unlikely to happen. There are plenty of UK small Companies that have come unstuck in the US.
I did watch the whole of the Parliamentary Committee BOO appearance and thought they were very impressive. It was the MPs and especially so Caroline Lucas, who were so unimpressive! Apart from the Committee Chairman they seemed to have very little understanding of the retail sector. And all Caroline Lucas could contribute was a repeated demand that Mahmoud Kamani must meet with the Unions, She just could not accept his very reasonable answer that he was happy to let his employees join a Union but he himself had no wish to meet with them. The questioning in general was poor.
But back to the US news. It is perhaps best not to write off the chance of your worst case scenario actually happening and to be relieved if it doesn’t, rather than the other way round! . Assuming the worst case scenario how hard would it hit BOO and the BOO share price?
Wow Liberty Shared have got it in for BooHoo https://libertyshared.org/appa...
It’s pure propaganda, talks about 10’s of thousands of people affected in Leicester!
Very bad news this. I cant imagine it is easy to get such a ban lifted either, if it were to be enforced.
I can only find reference to US Border Control being 'asked' to look into Boohoo - not that they ARE. Big difference if that's true. This comes from a different report from sky that was published before them in the US.
Oh and if you look at the Liberty Shared website where this started from it's a bloody petition for christs sake quoting all the same old stuff that's been going around for months.
Not saying you can trust the US but this looks like old dinner reheated for a third time and I suspect will end up being thrown in the bin.
Oh and are you sure it's 40% of revenue? I thought it was more like 20-25%
I agree, the whole crux of the news article and damning headline is centred on the below sentence:
'US Customs and Border Protection has seen enough evidence to launch an investigation after petitions from a campaigning British lawyer.'
It reads like it is directly taken from the US department but it could easily be a assumption by Liberty (the British lawyer) themselves e.g. they themselves feel the US has enough information to investigate. It doesn't mean that they will.
I think it's a very watery article until an official response is made or investigation is launched. The lack of substance in the article indicates that something may be at foot here but I'm sure an ethical organisation such a Liberty would be beyond market manipulations.
For those who are Boohoo (LON:BOO) holders or prospective holders I recommend flicking through the Liberty website/ petition as it gives an overview of manufacturing in Leicester and the issues at hand. It's obviously quite skewed in it's rhetoric but it does offer an interesting insight.
RE Boohoo (LON:BOO) . This is very out of the blue...and puts my holding in the red! However, irrespective of this, it is stark why this company is constantly targeted but nothing is said of its competitors. They all use the same suppliers!!!
Here is what Boohoo (LON:BOO) say on the US ban....
"We are confident in the actions that we are taking to ensure that all of our products meet and exceed the CBP (US Customs and Border Protection) criteria on preventing the product of forced labour entering the US (or any of our markets).
Will they also be banning companies like hershey, Nestle and Mars that are currently being sued for using child slaves to produce cocoa https://www.theguardian.com/gl...
RNS out now in response
That's certainly a comprehensive RNS in response this morning, well done BooHoo.
Boohoo (LON:BOO) . An absolutely spot on response, Paul. Yes we need to make sure that workers in Leicester are treated fairly. Killing Boohoo (LON:BOO) will only move clothes manufacturing to the Far East where wages and conditions are far worse and maybe deprive some of these workers of their livelihoods when Boohoo (LON:BOO) is already resolving these problems.
Hi PDiddy
On Boohoo (LON:BOO) (I hold) where did you get the “Accounts for 40% of revenue”. Sharepad gives the US as 20.4% but like all data providers that could be out of date.
Thx.
Michael.
My morning smallcap tweet: LOOK off the hook for sanctions
Nuformix (LON:NFX) Safestay (LON:SSTY) Mycelx Technologies (LON:MYX) Emmerson (LON:EML) Mobile Streams (LON:MOS) NAHL (LON:NAH) Amiad Water Systems (LON:AFS) Lookers (LON:LOOK) Cloudcall (LON:CALL)
Nuformix (NFX) positive result from preliminary preclinical study of NXP002 in treating idiopathic pulmonary fibrosis. [SP=2.84 Cap=15m]
Safestay (SSTY) sells a hostel for €900k = book value. [SP=19 Cap=12m]
MYCELX Technologies (MYX) project extensions, trial and capital sale total $3.5m in 2021. [SP=28 Cap=5m]
Emmerson (EML) propsed move from main list to AIM [SP=6 Cap=44m]
Mobile Streams (MOS) trading remain ahead of internal forecast. Chinese language version of Streams coming mid March. [SP=0.27 Cap=3m]
NAHL (NAH) re reforms to the personal injury sector from end May. Reforms could affect up to 90% of RTA personal injury claims. Changes are in line with mgmt expectations. [SP=43.1 Cap=21m]. I hold.
Amiad Water Systems (AFS) launches Spin Klin Nova filtration system after years of R&D. Offers "greater filtration efficiency and can process larger volumes of water per hour with a smaller system footprint than Amiad's existing products and, the Company believes, than competing solutions...The release of the Spin Klin™ Nova proves, once again, we are the Masters of Filtration." Masters of Filtration! Is there a movie coming? [SP=270 Cap=82m]
Lookers (LOOK) FCA closed investigation. No sanction - releases provision of £10.4m. [SP=40.4 Cap=158m]
CloudCall (CALL) [last night] yet another placing, £7.5m at 81.5p, a nil discount, to keep the lights on. [SP=81.5 Cap=32m]
In line: £