Small Cap Value Report (Tue 2 May 2023) - RTN, CARR, PHC, KITW, ADF, TRB, MTEC, VNET, TLY

Good morning from Paul & Graham!
Today's report is now finished at 13:13
My podcasts went up on Saturday, and my SCVR summary spreadsheet is also now up-to-date (links in the reader comments below), so we're starting the new week on the front foot!
Banking turmoil (again)
I see another troubled US bank, First Republic, has been put out of its misery this weekend, taken over by JP Morgan. First Republic's shareholders are wiped out. So far the system is holding together, and everyone knows what to do (and fast) with troubled banks. So I think this still ranks as "turmoil", rather than a "crisis". I've just seen a press report, saying that JP Morgan's longstanding boss Jamie Dimon has said that the collapse of SVB, Signature Bank, and and now First Republic, "pretty much resolves them all", in terms of problem banks. He also says the US banking system is "very stable". Let's hope he's right!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
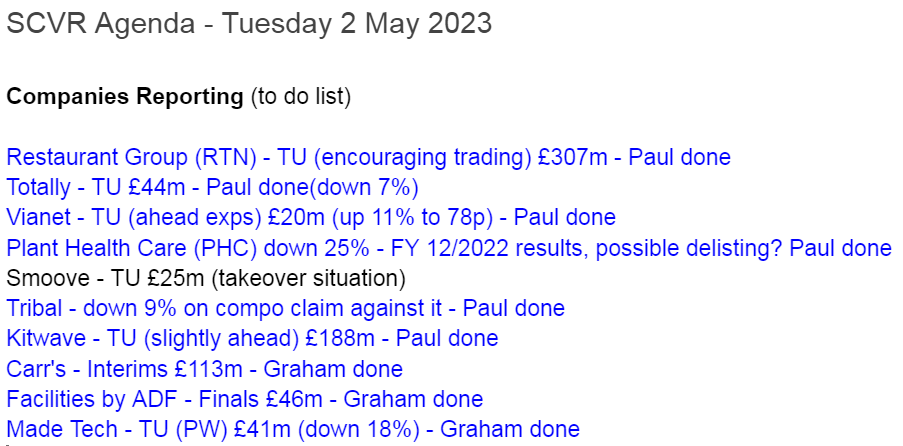
I did start to look at Smoove, but ran out of time. It's heavily cash burning, but has cash remaining, and is in bid talks. Actually, my initial impression is that this could be worth a closer look another time.
Summaries
(with main sections further down)
Restaurant (LON:RTN) - up 12% to 45.3p (£344m) - TU - Paul - AMBER
“Encouraging” trading in first 4 months of FY 12/2023. However, it uses weasel words to avoid saying whether or not it’s trading in line with expectations. Awful balance sheet and too much debt. But with decent sales growth, will the negatives matter?
Carr's (LON:CARR) - down 5% to 121p (£114m) - Interims - Graham - AMBER
A small profit warning from this specialty agricultural and engineering group. Much jam is promised in future periods but with auditors confused and few signs of quality, I am cautious.
Kitwave (LON:KITW) - up 1% to 271p (£190m) - H1 TU - Paul - GREEN
This wholesaler traded well in H1, and sees the FY 10/2023 being slightly ahead of expectations. It's a decent GARP share this one, thumbs up from Paul.
Facilities by ADF (LON:ADF) - up 3% to 60.5p (48m) - FY 12/2022 results - Graham - AMBER
I’m tempted to give this the thumbs up but need more time to monitor it. This rental company and service provider to film & TV studios is highly ambitious and already profitable.
Quick Comments
(no further detail below)
Plant Health Care (LON:PHC) - down 23% to 8.85p (£28m) - FY 12/2022 results - Paul - RED
I bargepoled this share here in 2015, and Graham confirmed his negative view in 2017 here. We haven't seen any reason to trouble you with any updates until now. PHC has made multi-million losses every year since, and the share count has tripled. FY 12/2022 results show revenues up, but continuing heavy losses. There was $5.7m net cash remaining, so no immediate worries over solvency (going concern note is clean), although the clock is ticking. Accumulated losses are now close to $100m!
Today it announces a consultation on whether to maintain its AIM listing. Management doesn’t take any responsibility for years of losses, instead blaming AIM for its lowly share price (I’d actually say the share price is generous!). 4 major shareholders own 50%, along with poor financial performance for years, so I’d say the de-listing and dilution risks are now very high, hence safest to steer well clear, in Paul’s opinion.
Tribal (LON:TRB) - up 5% to 41p (£87m) - Damages claim - Paul - RED
A short update on its major contractual dispute with a Singpaore university (NTU) which has rejected Tribal’s software. NTU has demanded £6.0m equivalent in damages from Tribal, which says it disputes, and will legally defend itself against this claim.
Paul’s view is unchanged - this seems an accident-prone company, that has gone nowhere in 22 years being a listed share - check out the long-term chart. This latest debacle just reinforces my negative view. Although the client relationships might be attractive to an acquirer possibly? Software companies, no matter how lousy their track record, do sometimes attract bids (look at Tungsten, and Proactis as examples).
Made Tech (LON:MTEC) - down 25% to 20.4p (£31m) - Trading update - Graham - RED
A nasty profit warning from this 2021 IPO (the words “2021 IPO” should strike fear into the hearts of investors). Previously, MTEC’s management suggested that profitability could improve in H2 (for FY May 2023). However, public sector spending is under pressure and consequently “several of the Group's clients have moved the start date of work packages, which had previously been scheduled for April and May 2023, into FY24”.
Revenues this year and next year were supposed to be £43m and £50m, respectively. Broker Cenkos has slashed these estimates to £40m and £43m.
Adjusted PBT was supposed to be £3.4m this year and £4.1m next year. These estimates are now £1m and £1.1m. The company’s fixed cost base was set up for higher revenues, which are now unlikely to materialise.
I’m going to give this stock the thumbs down because even if it has cash, its underlying quality appears to be unusually poor. In previous comments I noted its lack of profitability despite surging revenues. It now does not even have surging revenues and looks like just another opportunistic IPO from that annus horribilis.
Vianet (LON:VNET) - up 11% to 78p (£22m) - Trading Update FY 3/2023 - Paul - AMBER
Ahead of mkt expectations - operating profit to be £3.1m (up 30%). Revenues are 85% recurring. Renewals & new contracts “encouraging”. Good gross margin, despite semiconductor shortages. Hoping to shortly receive a £0.9m R&D tax refund. Improving products, and seeking to enter new markets.
Paul’s view - both broker notes out today seem to show operating profit almost completely disappearing, and only £0.5m adj PBT for FY 3/2023. So these numbers need close scrutiny. Capitalised R&D is a big number too, so ignore EBITDA. I’d like to see the full numbers, as this update looks to be cherry-picking an unrealistic profit measure, maybe? But at least it's ahead of expectations.
Totally (LON:TLY) - down 9% to 20.25p (£40m) - TU FY 3/2023 - Paul - AMBER
Provides outsourced health services. It says EBITDA of £6.3m is in line with consensus mkt exps. Net cash is £3.9m. Exceptional costs (no £ amount indicated) incurred, related to restructuring & cost inflation.
Paul’s view - an interesting company, although these seem large and complicated contracts, with wafer-thin margins. News today of restructuring costs & inflation worries me, as it implies that maybe contracts have not been set up sufficiently robustly to accommodate changing macro conditions? Shares are probably cheap for good reason, with several contracts not going smoothly, I worry what other potential problems might surface in future? Might be cheap enough to have a small punt on this, but I wouldn't want to risk a big position size here.
Paul’s Section:
Restaurant (LON:RTN)
45.3p (pre market)
Market cap £344m
The Restaurant Group plc operates approximately 410 restaurants and pub restaurants throughout the UK as at 02 May 2023. Its principal trading brands are Wagamama, Brunning & Price and Frankie & Benny's. It also operates a multi-brand Concessions business which trades principally in UK airports. In addition, the Wagamama business has a 20% stake in a JV operating seven Wagamama restaurants in the US and over 50 franchise restaurants operating across a number of territories.
The current financial year is FY 12/2023.
Encouraging trading momentum through the first four months of the year
The table below shows surprisingly good LFL (i.e. excl new , or closed sites) revenue performance - this is better than I would have imagined -
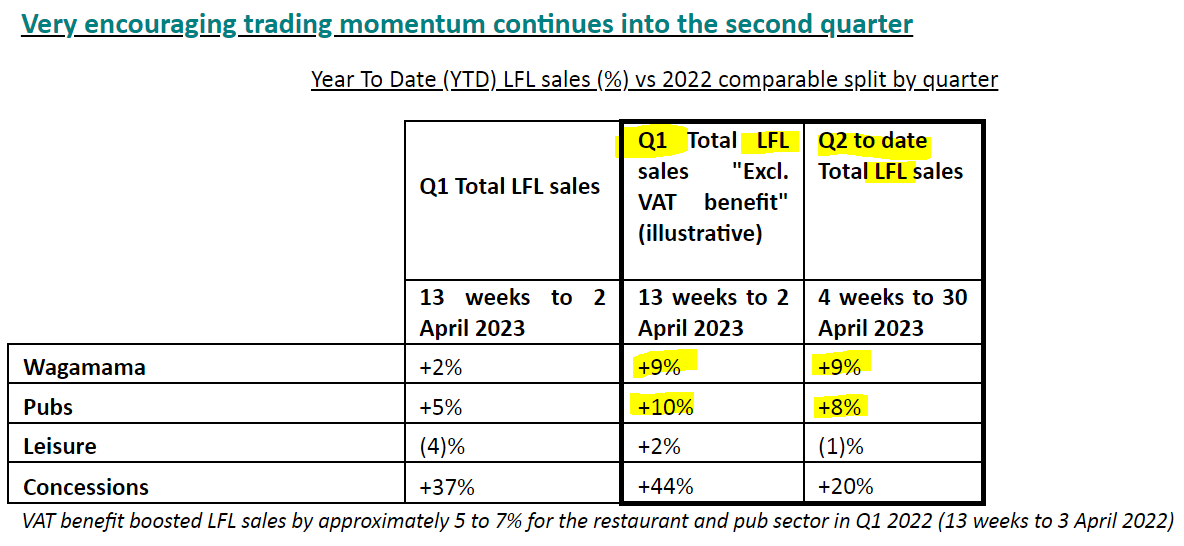
You could argue that this is only keeping up with inflation, and with many costs a lot higher, RTN needs to generate this sort of revenue growth, just to stand still. But even so, I’m impressed, given the headwind of the current cost of living squeeze on household spending.
Leisure division is under-performing, and is being restructured (23 sites closing shortly).
Concessions division is booming, due to a soft comparative when airports were depressed due to omicron in early 2022.
Note that column 1 above is impacted by last year’s VAT concessions, so it’s columns 2 & 3 that show the true underlying performance I would say.
Another table shows that there’s been a marked shift away from delivery/takeaway, in favour of people dining in the restaurants. Unsurprising I suppose, given decreased anxiety about covid these days.
Cost savings of £5m pa achieved.
UK property market still favourable, with new Wagamama sites available on attractive terms (7-8 new sites [previously 5] now planned for 2024).
How is it trading vs market expectations? - this is what investors need to know, and is the whole point of trading updates. We’re not told. Instead we have these weasel words (point 3) -
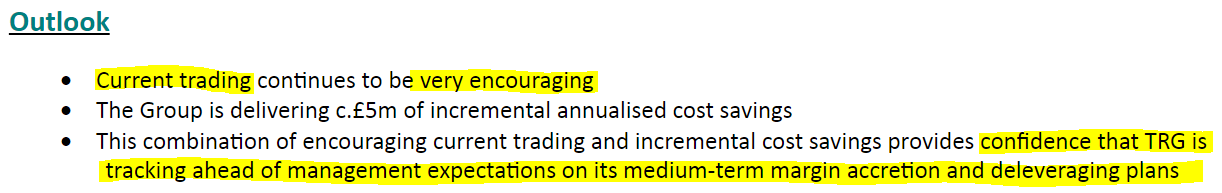
This is not good at all! It comes across as deception - they clearly don’t want to say if they’re trading in line with market expectations (which makes me wonder if they might be trading behind expectations?). Instead they invent a new definition - tracking ahead of medium-term margin accretion & deleveraging plans! An E-minus for whoever wrote this cobblers!
We like simplicity and clarity here at the SCVR. RTN’s update today has taken too long to pick through, trying to work out how the company is actually trading, and ends up being ambiguous.
To conclude, trading is first described as “encouraging”, then “very encouraging”, but it then dodges saying how it is trading vs market expectations! What to make of that? I’m not sure.
This bit also sounds vague -
TRG is pleased with the early progress in executing the plan to deliver significant EBITDA1 margin accretion over a three-year time horizon2 and the Board continues to consider long term strategic options.
My opinion - a really badly-written, unclear trading update. It should have been shorter, and just told us if they’re trading in line with market expectations, or not. That’s what everyone wants to know. A trading update that doesn’t disclose this, is not a trading update, it’s a PR release.
I can’t see any broker updates yet today. As you can see below, the existing forecasts have been reduced a lot, but have started edging up in recent months.
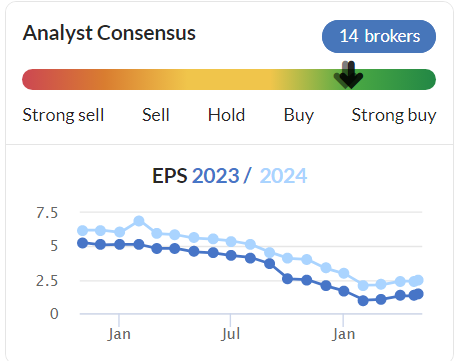
Casual dining is just a horrible sector right now, where it’s very difficult to make any profit at all. So the shares are only of interest if you think that there’s likely to be a decent consumer recovery, and that margins can be improved (e.g. from falling ingredients prices, lower energy costs, maybe?). The gross margins are high, so there’s considerable operational gearing, and a lot of competitors have closed.
RTN also has a horrible balance sheet, with too much debt. Graham reviewed the 2022 accounts here, which is a sobering read (how does NTAV of negative £(224)m strike you?!)
I can’t make up my mind between maintaining Graham’s RED view, or going AMBER on it, given the strong revenues reported today? Tricky one. As I’m not sure, it has to be AMBER from me. Although Graham’s probably right that at some stage RTN will probably need to raise fresh equity to repair its horrible balance sheet. Debt is a lot more expensive now too, so it would be worth checking the terms of RTN's debt pile.
It's also worth considering the long-term performance of RTN, which has been dire, for anyone who bought in the glory days of 2014-15. Also note that the share count has risen almost 3-fold in the last few years, from 277m to 765m. So in market cap terms, the 500p share price peak would equate to only about 170p now. I'd say it needs to increase that share count further, since the balance sheet remains weak and overly indebted.
Despite an upbeat-sounding update today, it's still only trading a little above breakeven, once you include finance costs.
Anyway, it doesn't matter what I think, the market likes the update, with RTN shares up 11% to 44.7p at 08:51 - so maybe it's a hold your nose share and ignore the problems, because momentum looks to be moving in the right direction?
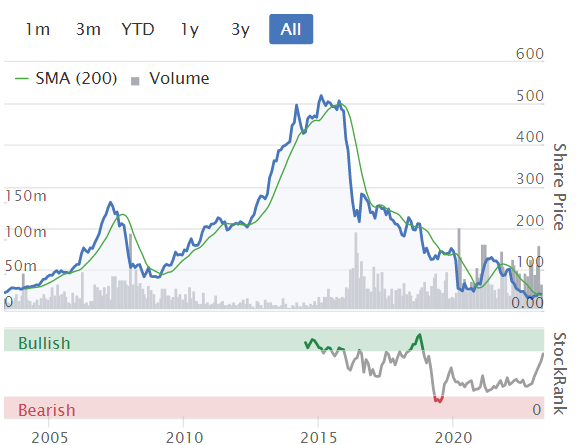
Kitwave (LON:KITW)
271p (up 1% at 10:13)
Market cap £190m
Kitwave Group plc (AIM: KITW), the delivered wholesale business, today announces a pre-close trading update for the six-month period ended 30 April 2023.
The current financial year is FY 10/2023.
This is pleasing -
The Board anticipates that the Group's results for the full financial year will be slightly ahead of market expectations.
All divisions traded well in H1.
Normal seasonality is an H2 weighting.
Well placed to mitigate macro & inflationary risks.
Recent acquisition (Westcountry Food) is going well, and performing as expected.
Outlook - sees “considerable opportunities” for organic growth, and more acquisitions.
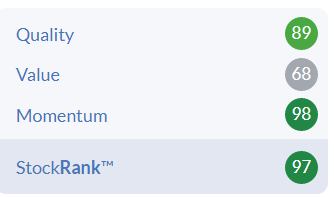
Paul’s opinion - I’ve commented favourably on this company before. Today’s update reinforces that positive view. It’s still reasonable value, on a fwd PER of about 10x, paying good divis of c.4.1%, and self-funding bolt on acquisitions. Experienced founder-CEO holds 15.6%. Thumbs up from me!
Thumbs up from the computer algorithms too -
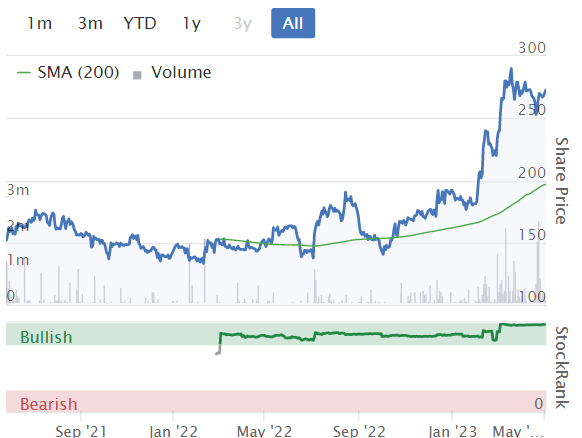
Behold! A most unusual thing - a recent float which has actually done well -
Graham’s Section:
Carr's (LON:CARR)
Share price: 121p (-5%)
Market cap: £114m
We have a small profit warning from Carr’s today:
Carr's (CARR.L), the Speciality Agriculture and Engineering Group, announces its Interim Results for the 26 weeks ended 4 March 2023.
In recent months, the company had a messy situation involving delayed accounts and the suspension of its shares, but hopefully that is all behind it now?
They sold the agricultural supplier Carr’s Billington and received a nice chunk of cash for it, so they now have a net cash position, as expected.
The remaining divisions are “Specialty Agriculture” and “Engineering”, each of which are made up of multiple specialist businesses.
Let’s take a look at these interim results:
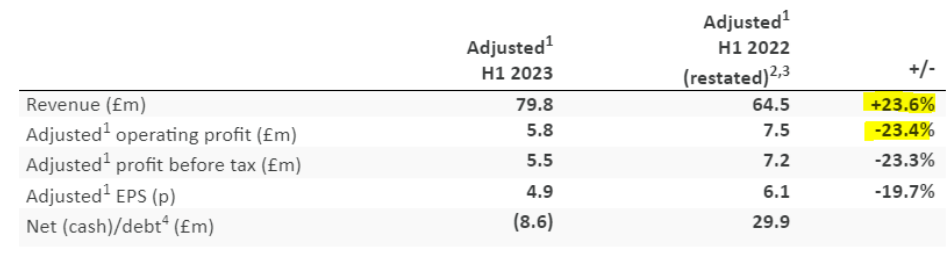
So we have nice growth in revenues (lots of inflation, I’m guessing), but unfortunately this has not translated into higher profits.
Also, I’ve had a look at the footnotes here and read about the prior period restatements: the new accountants at Grant Thornton have done a lot of work trying to make the numbers add up and conform with accounting standards.
Carr’s has been on the auditor merry-go-round: PwC held the role from 1909 (yes, really) to 2018. Then KPMG, of Carillion fame, had a go.
Last month, the Financial Reporting Council indicated that it was investigating KPMG’s audit work on Carr’s for FY August 2021.
Grant Thornton is now attempting to make sense of the company and its financials. Judging by the prior period restatements, it has been something of a clean-up job.
It can be hard to know exactly where blame lies in situations like this. For investors, I think the main conclusion should be that the underlying business is complicated. If it wasn’t so complicated, then surely it would have been much less likely to run into these problems in the first place?
At least Carr’s is marginally less complicated now that they have made the aforementioned disposal. Let’s read on and see how the two remaining divisions are doing.
Highlights (I’ve added the bold):
Revenue increased 24% on prior year, reflecting raw material cost recovery in Speciality Agriculture division
H1 profits impacted by volumes in Speciality Agriculture and contract timing in Engineering
Record Engineering order book of £57 million at 28 April, up by 30% from start of the period
Phasing in engineering work will be favourable in H2, with strong profit generation in the division expected
Outlook:
The outlook for Engineering in the second half of FY2023 is positive. The division has several key contracts coming through… These factors will offset the low summer season for Speciality Agriculture which also continues to manage historically high input costs.
Acknowledging the challenges ahead, the Board anticipates full year adjusted profit before tax of c.£10m and remains confident in the prospects of both divisions in the medium term.
According to the most recent Edison note, PBT of £10.5m was expected for the current financial year, so this is a slight profit warning.
Agriculture: the major theme here is inflation as the cost of molasses for making feed blocks has increased by 70% in three years.
Carr’s increased its average feed block selling prices by 35% this year and it’s not obvious that this was even enough. But of course there’s a limit to what their customers can bear: volumes fell 13% in H1.
In the US, there is inflation and a drought. Hard times! Volumes fell 10%.
More positively, Carr’s management do tell us that farm input prices are currently coming down and that the longer-term outlook is more positive, i.e. from FY 2024. We shall see.
Engineering: H1 adjusted profits in this division saw a much larger percentage fall to just £1.1m. But with a larger order book and “confirmed high value contracts continuing into FY2024 and FY2024”, there is much jam to look forward to in future periods.
My view
There is plenty to digest with this one but at the end of the day, I’m finding it difficult to come up with any reasons to treat this as a high-quality stock.
At the current time, its main attractions are probably the cash balance (£23m, though net cash is only c. £9m) and the £120m of net assets on the balance sheet (including nearly £30m of intangible assets).
Perhaps more disposals would make sense? Can anyone explain why it makes sense for the remaining agricultural and engineering businesses to stick together?
I’ll stay neutral on it because they are at least still profitable and not suffering from financial distress. However, the underlying quality is questionable to me. And if even the auditors are struggling to understand what is happening, that is one more reason for investors to tread carefully.
Facilities by ADF (LON:ADF)
Share price: 60.5p (+3%)
Market cap: £48m
Paul usually covers this one, but I’ll take a look at these full-year results for 2022. Trading in 2023 is in line and expectations are unchanged.
Facilities by ADF, the leading provider of premium serviced production facilities to the UK film and high-end television industry ("HETV"), is pleased to announce its audited final results for the year ended 31 December 2022.
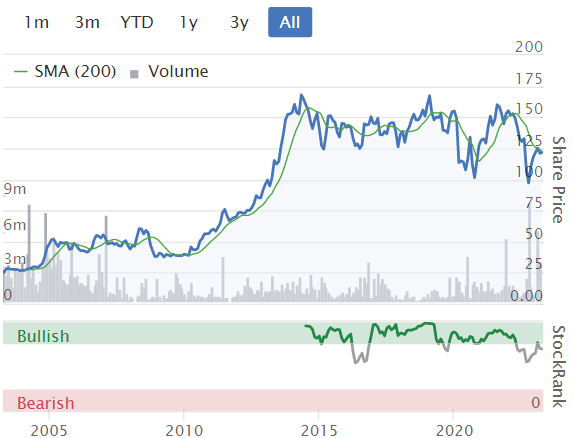
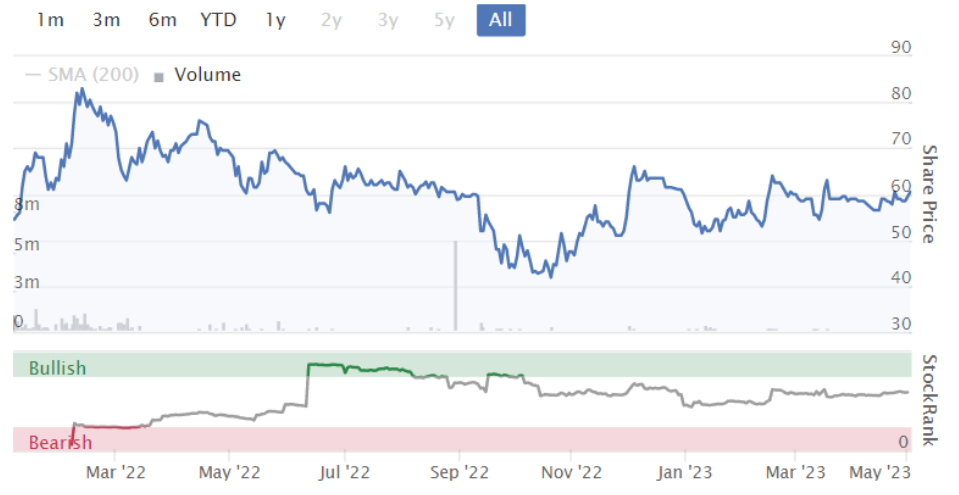
It’s a January 2022 IPO, and is currently trading higher than its IPO price of 50p. That’s impressive, considering how many IPOs have disappointed by this stage in their life on the stock market!
The headline numbers show year-on-year growth coming in as expected (see our coverage of the full-year trading update):
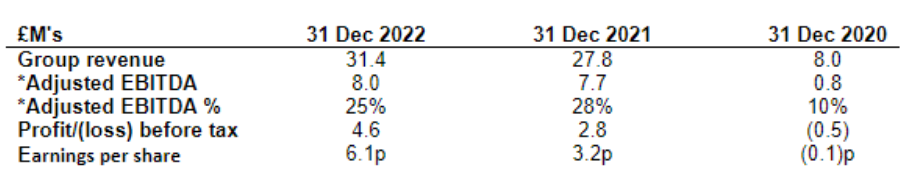
As noted by Paul, the EBITDA number is irrelevant, due to depreciation (£2.5m in 2022), so I would hone in the PBT result (£4.6m for 2022) and forget about EBITDA.
The 76 productions supported by ADF in 2022 include Netflix, Apple and BBC shows.
And H2 saw a nice improvement in trading with bigger projects:
H2 productions were larger and more clustered around London resulting in improved margins. The Group generated an average revenue value of £386k per production.
Expansion: the company added 136 vehicles during 2022, to bring the total fleet to 632 by year-end.
Other expansionary actions:
Acquired Location One (initial cash consideration £4.4m)
New office in Scotland
Doubled capacity at manufacturing facility in Wales
New operational hub in Surrey, “perfectly located to serve several major studios” including Apple, Disney, Netflix and Sky..
Outlook
A very confident outlook statement based on “underlying market drivers” that will ensure demand remains strong for ADF’s services. More acquisitions are on the cards.
The FY23 order book is strong, indicating a continuation of the H2-FY22 profile, with larger productions generating higher revenue per job. The Group is presently taking orders for Q1 and Q2 FY24 providing strong levels of revenue visibility for the year.
UK film/high-end TV spending certainly appears to be enjoying a boom period, especially, since Covid-impacted 2020:
CEO comment is similarly upbeat:
We have a growing addressable market, an expanding network of contacts and a high-quality business model driving growth in Group revenue. Alongside positive market drivers, where demand for film and HETV in the UK continues to accelerate, I am confident in the Group's ability to deliver on its strategy and plans in FY23."
The strategy is to treble revenues to over £100m (I’m not sure over what timeframe), with the help of acquisitions. They want to be a “one-stop shop” for film and TV producers. Sounds ambitious!
Cash flow statement shows lots of capex, so nothing to write home about in terms of free cash flow yet. Still at an early stage of development.
Balance sheet has tangible net assets of £18m, with £9.5m of cash.
Estimates from Cenkos are upgraded due to a tax boost relating to depreciation and FY 2023 after-tax profit is now estimated at £6m (up by £1m). However the estimated capex bill has also increased by £1.5m.
New forecasts are released for 2024, suggesting after-tax profits of £7.5m.
My view
I’m new to this share but it does look potentially quite investible. It’s profitable, ambitious and growing, and exposed to an industry that I believe is only going to go from strength to strength over time: domestic film and TV production.
As noted by Paul, it’s not an industry that you can bank on every single year. There will be bumps in the road, and ADF as a service provider will have to make do with whatever the large studios want to produce in any given year.
The ambition to be a “one-stop shop” is perhaps aggressive, but I think that’s what we should want from most small-caps: we should want them to have big aspirations to grow and to become larger companies.
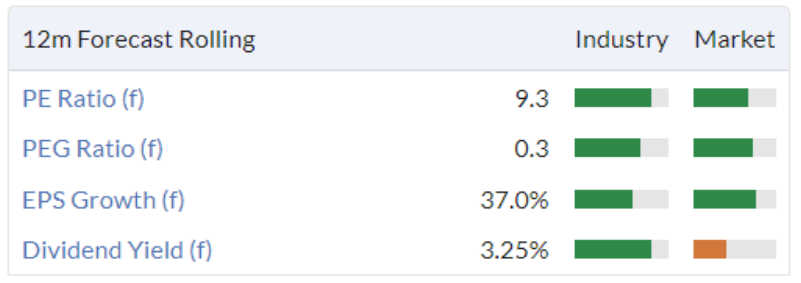
I’m going to stay neutral on this one purely because I’m new to it and would need more time to come up with a firmer view, but I do like what I’ve seen so far. It doesn’t hurt that the value metrics are already so good:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
Thanks to BnB and the Jayman for their comments on Videndum (LON:VID) . I went through the annual report last night. Too much debt is my concern , which too an extent has been eased. Covenant net debt to EBITDA is stated at 2.2 times at 31 December 22, with expectations for it to be slightly higher at June 2023
Yesterdays announcement states that
"An increased H2 weighting will slightly increase our covenant net debt to EBITDA ratio at 30 June 2023 from our previous expectations"."
The loan covenant taken from the last prelims is shown at 3.25, which should provide headroom.
The annual report also cited the going concern basis adopted by directors.
Much depends on how badly trading is impacted in the short term, but for the time being I shall sit on my hands. It had also occurred to me that Videndum (LON:VID) could pull the dividend. Sensible I suspect but unpopular?
Videndum (LON:VID) Just seen this afternoon's RNS. Doesn't look great. Trading is clearly not going well, but as is often the case, debt is the elephant in the room. I have a holding which fortunately is small and getting smaller, certainly in the short to medium term.
I think Videndum (LON:VID) operates in an attractive area, so I am unsure whether the current problems are due to management ineptness, an unfortunate confluence of events or a combination of both. To paraphrase the Clash "should I stay or should I go". Decision time!
I think Videndum (LON:VID) operates in an attractive area, so I am unsure whether the current problems are due to management ineptness, an unfortunate confluence of events or a combination of both. To paraphrase the Clash "should I stay or should I go". Decision time!
Is it not a confluence of pandemic hangover with macro uncertainty? I’m wary of anchoring to the chart but we are at levels last seen in the initial pandemic crash when the world was about to end. I don’t expect a swift turnaround - and the screenwriters’ strike is a further spanner in the works - but, long term, this looks an attractive entry to me rather than a valuation from which I’d be inclined to jump.
While lower debt levels would certainly be welcomed, I believe BnB is reading this in its proper context. I have a holding acquired from £5.5 to £11
Thank you for your comments on Carr's today Graham, I'd noted Paul's caution on the 24th March and started to sell our holding when the shares were relisted, we sold the remaining third today after reading your opinion. Good luck to the company and remaining holders but we are happier building holdings in Anpario and Wynnstay, the latter highlighted on here recently by planetx.
"Pretty much resolves them all". Hopefully not famous last words.
Here's Property Franchise (LON:TPFG) full year results webinar from 18.4.23 video & podcast. Between the day of results/this webinar and today the seller has cleared and the share price is up of over 20%. It's now on a PE of 12.5% and a divi yield of just over 4%. Not as cheap as it was at results but still a predictable stock with a nice dividend. It's not as liquid as Belvoir (LON:BLV) but has less exposure to Financial Services. TPFG believes 2023 total property sales (TAM) will go back to 2019 volume, around 1-1.2m completions but rental income is extremely strong. TPFG has an operating margin of 41%, a ROCE 20% and is looking to grow both organically and through acquisition.
Robert Forrester, CEO, Vertu Motors (LON:VTU) will hold one of his legendary webinars next Wednesday 10th May, 3.30pm. Register here. We know the automotive retailers have been doing extremely well and there's consolidation in the sector. Robert is always extremely generous with his time and answers all questions. Do join us with Robert and Karen Anderson, CFO for what is always an entertaining session.
1Spatial (LON:SPA) presented FY23 results last week. Claire Milverton, CEO was joined by the new CFO, Stuart Richie. Claire sounds very excited about 1Streetworks, the Traffic Management Plan Automation solution, which is illustrated via a video. Worth a watch to understand their offering and strategy. Video & podcast.
Macfarlane (LON:MACF) (my second largest holding) – Small acquisition
Macfarlanes second small acquisition of 2023 – a northwest regional protective packaging distributor - Gottlieb – for £2.75m (plus earnouts) with (historic) £4.5m sales and £0.7m ptp. The kind of small bolt-on that Macfarlane has excelled at now for years.
What is perhaps more remarkable – when added to the previous 2023 acquisition (on a pro-rata pro-forma basis) - Macfarlane (LON:MACF) has already achieved 2/3 of the forecast growth in revenue and 100% of the forecast increase in pre-tax profit for the current year. Leaving not very much to be achieved by the existing business – and Marfarlane do have a consistent record of improving revenue and profits over many years now.
Management forecasts are always cautious and have a record of under-promising and over-delivering. As there is an established seasonality to the results – this acquisition increases the likelihood of an upgrade towards the end of the year in my view.
The shares seem valued currently on the basis of a much less successful operation. As the company keeps doing what it does well I expect the shares to re-rate significantly. I just don’t know when.
Cheers
Mark
Vianet (LON:VNET) (I hold) Trading update for year to end Mar23
Here are the notes I've written this morning:
And I am left with more questions than answers. Though why that should be a surprise with Vianet’s history of almost but not quite delivering – I’m not sure. As always I read these kind of reports – more for what they don’t say than what they do say……..
Revenue is up 7% to circa £14m – but that’s a big miss on the £15.7m currently shown on the stockreport. Is that right? It’s even a slight miss on the ttm figure of £14.1m. So what happened in H2? We are told contract renewals and contract wins have been encouraging – but it looks to me like something expected did not occur, in H2 at least? I await the FY results to learn more (Ed - just seen Paul's quick comment and am in agreement with him. Something here doesn't seem to add up very well - though it's likely that the capex, capitalised development and increases in working capital (flagged by the semiconductor surcharge - and remember that VNET is primarily in the IoT PGA/controller fields where auto dominates) there won't be a lot left when it trickles down to ptp?)
So. Operating profit is up significantly to £3.1m – That’s adjusted operating profit mind you – adjusted primarily for the amortisation of capitalised software development which was running at around £2m in 2022. Nevertheless it is apparently ahead of market expectations. Except that there aren’t any on the stockreport. But good all the same although it leaves me with the question – how did they miss on revenue and end up so far ahead on adj operating profit? - probably they haven't and the adjustments need to be seen as already surmised?
Cashflow does look even better with the pre- working capital and capex at £3.5m. Looks like good management of the business operations – even if the revenue trajectory has yet to achieve take-off. Again. The cash will come in handy for paying down the debt accrued during the lockdown. But once its gone – it’s looking like a good cash generative business.
No information on new connections. Which rather makes me think that there is nothing particularly good to report here?
For me this is an OK report in terms of recovery of the pre-pandemic business – but once again it seems as if it might have kicked the jam roly-poly down the road again in terms of its growth trajectory for its data-analytics led smartvend and smartdraught products.
The problem for Vianet is that it needs serious revenue growth in new contracts to generate operating leverage and produce sensible eps figures. Without that its never going to achieve escape velocity. I'm still holding, but for how long......? It seems an attractive product, ahead of the competition and a very attractive market which is growing strongly - I'll likely give it another 6-12months to show some significant top-line growth......famous last words.......but it is testing my patience now.
Cheers
Mark
Well, we have results in June and AGM in July - hopefully with a trading update. If the new partnerships come to anything there a strong baseline to add profit. If it is £0.5m in FY 23 then hopefully the finance costs will also disappear if they have managed to generate the cash they say and tax refund they expect by the end of June.
Sigmaroc (LON:SRC) appears to be on a roll, up 9% at present, not aware of anything specific, possibly a delayed reaction to the recent positive AGM statement? I hold.
Hostmore (LON:MORE) I have just listened to the webinar.... I realise it's a sorry subject but if like me, you have some shares in the bottom draw....it was actually encouraging and worth a listen.
The plan... is to be debt free by 2025.... to generate £10m plus FCF ....to stop openings until finances are sound.... ie 2025... and debt covenants have been extended to cover this.
If this plan is achieved the share price will be well north of 17p. A debt free market cap of £17m with FCF £10m....leaves plenty of scope for recovery. Having said that they have guided to a small rise in net debt at half year....but have also said they are looking for more cost savings.
I think it's important that S Welker is Ch. as this plan is now classic Sherborne. In the past their track record of underpromising should serve them well. I would guess they squeeze another £1-2m cost savings and by 2025 are focussed on delivering £20m plus EBITDA.
I realise it's a sore point for many, but if you have held on until now then there would appear plenty of reason to continue to hold. I have been waiting for them to sound a little more on the front foot before averaging down.... today looks like a major step forward ... of course it's still risky .... but the debt reduction alone would accrue a 100% rise on the shares...for me it now looks interesting for recovery.
I agree - I listened to it and think Hostmore (LON:MORE) is a potential recovery multi-bagger.
The new strategy is much sounder. Capital allocation now positioned to eliminate debt over 2 years and then focus on shareholder returns, whilst at the same time not skimping on maintenance/makeover capex required to keep sites fresh. This is done from self help initiatives like no new roll outs until 2025 and around £6m of annual cost savings. Looking at the FCF waterfall chart they presented, which includes inflation drivers and conservative price increases (which are less than overall inflation) but no increase in sales that's more than achievable.
Gone back to TGI Friday brand as the "Fridays" initiative was clearly flawed and resulted in lower brand appreciation. Since new CEO came in net promoter scores and trip advisor reviews have gone up considerably. Utilisation of intelligent data to drive initiatives and enhance management of stores looks very effective. Even a very mild recovery from here will give a strong uplift. They mentioned circa 1% increase in covers adds £1m ebitda so that a useful metric to remember and compare in future.
Exec bonuses for this year don't kick in until ebitda hits £20m and the recovery plan only factors in £14m ebitda to generate the debt reduction so clearly management are more optimistic than they are guiding the market.
But if they achieve £20m ebitda free cash flow will come in around £14m (after interest and maintenance)
Use that as the potential recovery baseline and apply 5* (probably 8-10 in a good market) and we could see an EV of £75m -£125m which is multiples of current share price.
Might now be an interesting recovery story. No need for equity dilution either if debt is quickly reducing/eliminated, so that risk gets much diminished. Need to do some more analysis but am tempted in taking a 2 year view here.
If you had a choice of Carr's (LON:CARR) or Wynnstay (LON:WYN) , I think you’d choose the latter. I hold Wynnstay (LON:WYN) . They’ve shown the same projected downturn in agriculture profits this year, but have really solid asset backing and a decent strategy, in my opinion.
The impact of imported inflation and Brexit/currency movements is horrific; I’ve rarely seen inflation on this scale in any sector. It all feeds through into the cost of our food basket. It won’t be long before ministers are crying out for higher food production again.
US Banking system 'very stable'. That's a joke. All the problems always stem from them and some of these Banks having risky Business Models. Some of it sounds like Casino Banking to me. Nothing stable about it at all.
Worried about the banking turmoil, I picked up HSBC when it bought SVB last week and JPM when it bought FRB yesterday!
Restaurant (LON:RTN) I see limited possibilities with RTN. I used to love going to Wagamamas back in the late noughties, but for some reason, the prices went substantially higher before the cost of living crisis. Sitting elbow to elbow with other diners has never appealed.
Have to agree with the exception of ‘sitting elbow to elbow’ ! Whenever I pass F & B and Wag’s there always seems to be plenty of empty tables. How they cover their rental and staff costs alone at these sites must be a struggle.
Made Tech (LON:MTEC)'
"The recent rephasing of activity has, accordingly, disproportionately impacted the expected adjusted EBITDA3 outcome for FY23, which is now estimated to be at least £1.5 million."
Its bad enough that they miss revenue forecasts by 7%, big miss on EBITjunk and cash well down....but the use of "rephasing" is unforgivable.
The result of this "rephasing" is Singer have taken a chainsaw to 2024 forecasts.
Revenue reduced from 50m to 43m
PBT 4.1m to 1.1m
EPS 2.6p to 1p
Net cash £10.7 to £7
Share price at 21p (down 23%) is trading at 21x forecasts. Looks like this has further to fall to me. Hard to believe when they floated at 122p in 2021, and being talked of as a baby Kainos (LON:KNOS) brokers were forecasting EPS of 5.7p + PBT £10.9m for 2023
Facilities by ADF (LON:ADF) Haven't fully got to grips with the detail but on an initial quick read the final results look promising. A fairly recent IPO that is doing what it said it would and has remained above its listing price unlike most. I hold
Paul/Grahams thoughts, time permitting.
Anyone else using Investegate for monitoring RNS releases as it looks as though they've had a disaterous upgrade over the weekend. Used to be a brilliant service and it now looks unusable.
Why don't they consult with users before changing anything especially where the mantra "if it ain't broke, don't fix it" applies!
As you say problems with investegate, have used the London Stock Exchange this morning, which worked very well, although I prefer the former.
Also have no idea how Investigate now works. No link to my alerts and search facility is clunky. I use London Stock Exchange as an alternative but sometimes it won't let me view RNS's even though I'm logged in.
Or you can use Stocko itself, as your RNSs appear on the front page. But, irritatingly, the Stocko presentation makes YoY growth numbers very difficult to interpret. If Stocko management could sort that out please....
Click on the url for the printable format. It gives a readable version.
I'm getting lots of RNS for stocks that are not in my folios and lots I have no interest in. This issue has been raised with Stocko before.
I had to switch that function off, Oliver was not impressed. I now just use the RNS announcements on Stocko's front page to pick out the ones that I have an interest in as I was getting an avalanche in my mailbox.
Readers might find this link useful to bookmark.
I set it up to include, and exclude what I'm interested in, direct from the RNS feed at the London Stock Exchange.
Brilliant Paul, thanks for sharing, that will save some time.
Is there a way to set it up so that it will return only results from a selection of companies that one is interested in? I can add a filter to return the RNSes of just one company but can't see how to get those of a number of companies. That's what Investigate was good for by using "My list".
Problem with Stocko is the clunky presentation of both the lists and the content and the fact that RNSes are returned for everything that's in a Folio. Can't remember whether Stocko offers email alerts but Investegate allows one to select whether to receive them or not for each company.
Glad to see that I am not the only one having problems with RNS announcements that are not in my Folios nor requested. I get many iShares RNSs every day, but I have never invested in any iShare. I contacted Stockopedia and they suggested that it might be because some of my old holdings are showing in my Folios but this is not the reason. This has been going on for months and gradually getting worse. I guess the easy way out is to use a different provider for this facility.
I get many iShares RNSs every day, but I have never invested in any iShare. I contacted Stockopedia and they suggested that it might be because some of my old holdings are showing in my Folios but this is not the reason.
I see this problem too. I believe the annoying ETF NAV releases may relate to having London Stock Exchange (LON:LSEG) in one of your portfolios.
I completely agree. I use it everyday and this morning its an absolute disaster. What were they thinking? It worked perfectly ok until Friday, so why did these Clowns think they needed to change it. Just leave it as it was. It was perfectly ok as it was.
I use ResearchTree for RNS. You do not need to be a subscriber either and you can customise it. If you decide to subscribe, go to The Naked Traders website and get a 20% discount code off there. Thank you Robbie Burns.
https://www.nakedtrader.co.uk/
Subscribe direct to LSE direct, you can also get alerts and a watchlist(s)
Simplesss
You might also have seen "US Government risks running out of cash" FT online FT headline this morning Paul? Once more into the breach my friends!
Oh that debt ceiling thing has been going on for donkey's years with the US Govt. It just gets increased again every time.
US debt certainly has been increasing Paul the graph does however look a little scary
https://fred.stlouisfed.org/se...
Gone off gold, will wait till 2100. Silver is industrial (solar panels etc). But in small denominations so can exchange for the loaf of bread when the government denies access to your BritCoin.
Gold and silver very cheap at the moment. Good recession hedge.
Good physical hedge. Like watches, jewellery, this is wealth you can 'bling'.
No interest but some flash enjoyment and fundamental family wealth. All the easy stuff has been found, so scarcity and cost of mining increases.
Gold cannot be destroyed.
Governments know this so grabbing like mad to support their weak fiat currencies. Argentina anybody.
My morning smallcap tweet: MADE trade fade
Superdry (LON:SDRY) Restaurant (LON:RTN) Made Tech (LON:MTEC) Kromek (LON:KMK) Hostmore (LON:MORE) Tribal (LON:TRB) Genincode (LON:GENI) Synectics (LON:SNX) Kitwave (LON:KITW) Destiny Pharma (LON:DEST) Vianet (LON:VNET), Totally (LON:TLY), Smoove (LON:SMV)
◄Superdry (SDRY)► confirms talks on fundraising of up to c.20% of cap. [SP=86.1 Cap=71m]
◄The Restaurant Group (RTN)► trading encouraging. Ahead of mgmt expectations "on its medium-term margin accretion and deleveraging plans". [SP=40.08 Cap=307m]
◄Made Tech (MTEC)► warns FY-May rev c. £40m and adj EBITDA £1.5m+, a miss. Blames clients delaying project starts. [SP=27.2 Cap=41m]
◄Kromek (KMK)► $1.4m order from new customer, to be booked this FY. [SP=6.6 Cap=29m]
◄Hostmore (MORE)► plans further cost reductions of £4.1m PA. Substantially all affected employees and service providers have now left. [SP=13.55 Cap=18m]
◄Tribal (TRB)► gets an interim demand for $9.9m damages from Nanyang Technological University (which had purportedly terminated its contract). Co intends to dispute it. [SP=39.6 Cap=83m]
◄GENinCode (GENI)► NHS accelerates implementation of LIPID inCode testing of patients suffering with hypercholesterolemia and familial hypercholesterolemia. [SP=15.5 Cap=15m]
◄Synectics (SNX)► further $3m orders for surveillance system for Solaire Metro North casino. Delivery in Q4. [SP=106.3 Cap=19m]
◄Kitwave (KITW)► guides FY-Oct slightly ahead of market expectations. [SP=268 Cap=188m]
◄Destiny Pharma (DEST)► positive results from testing SPOR-COV in several COVID and flu research models. Supports potential as prophylactic nasal spray. [SP=32 Cap=30m]
◄Vianet (VNET)► guides FY rev up 7% and op profit up c.30%, ahead of market expectations. [SP=69 Cap=20m]
In line: TLY, SMV
Morning All,
Update this morning from Kitwave (LON:KITW), trading slightly ahead, strong performance. Only on ten times forward earnings, undervalued in my view!
I hold.
Morning JohnDoe2378!
Yes I also like Kitwave (LON:KITW) so I'll review that next.
Regards, Paul.
Muted reaction thus far!
My summary SCVR spreadsheet (pls don't share this link outside Stockopedia, it's intended for subscribers here) is now up-to-date - it's a quick reference tool, so you can see at a glance how we view about a month's work here (depending on your screen size!). It now contains 5 months SCVRs, all in one place, showing the colour-coding we've attributed to each share, and hovering over any cell brings up a very short summary of our view on that day (subject to change obviously, as the newsflow changes with time). Here's a screenshot -
I just put April and March greens into a FOLIO looks like Watkin Jones (LON:WJG) could be an opportunity. -62% from the years high, EV/Sales of 0.53 50% revenue growth target over the next two years, the relative strength is moving up and a 7% divi. I've just bought a few
Alphawave IP (LON:AWE) I know this company has been discussed here a fair bit with a temp supspension..........
RNS release this morning:
LONDON, United Kingdom and TORONTO, Ontario, Canada 2 May 2023 - Alphawave IP Group plc (LSE: AWE, the "Company" or "Alphawave Semi") notes the following typographical errors in its preliminary results for the year ended 31 December 2022 published on 28 April 2023:
- Capitalised R&D, pages 4,11 and 12, US$7.5m. Amended to US$7.2m.
- Operating expenses, page 11, US$88.6m. Amended to US$86.6m.
- Cash generated from operating activities before tax, page 28, US$'000 (2,857). Amended to US$'000 7,818.
- Revenue contribution from the acquisition of OpenFive, page 74, US$70,644,000. Amended to US$70,827,000.
- Accrued revenue from WiseWave, page 5, US$14.9m. Amended to US$20.2m.
- Accrued expenses, page 64, $US4.0m. Amended to US$4.0m.
For the avoidance of doubt, these are typographical errors only and not changes resulting from the completion of the audit work.