Small Cap Value Report (Tue 2 Oct 2018) - RBG, TET, SCS

Good morning,
This is what I intend reviewing today;
Revolution Bars (LON:RBG) (in which I hold a long position) - preliminary results
Treatt (LON:TET) - trading update
SCS (LON:SCS) - preliminary results
DX (Group) (LON:DX.) - preliminary results - sorry, I ran out of time, so didn't get round to looking at this after all.
Revolution Bars (LON:RBG)
Share price: 123p (down 1.7% today, at 10:16)
No. shares: 50.0m
Market cap: £61.5m
(at the time of writing, I hold a long position in this share)
Revolution Bars Group plc ("the Group"), a leading UK operator of 76 premium bars, trading under the Revolution and Revolución de Cuba brands, today announces its results for the 52 weeks ended 30 June 2018.
Where to start with this?! This is a classic case of a share where some investors will see negatives, and others (including me) see a turnaround opportunity, with the negatives already priced-in to the share price.
Larger competitor, Stonegate, tried to buy RBG last year, with a 203p recommended cash bid. Very unusually, RBG's larger shareholders then turned down this bid, as undervaluing the company. I'm struggling to think of that happening before, as recommended bids are not usually recommended, unless management has agreed the terms with major shareholders. So a very unusual turn of events.
Negatives
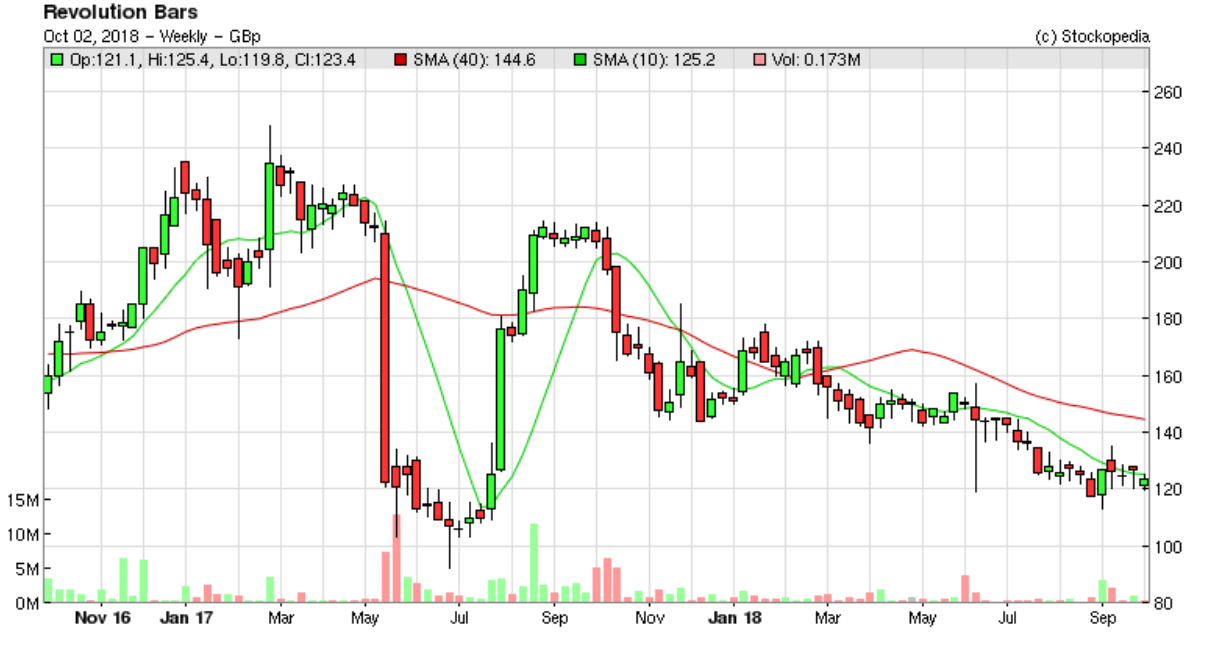
Why has the share price slipped so far down, from the 203p cash bid approach last year, to only 123p now? Partly it's the bid premium coming out of the price of course. But also, here is a list of the things that have gone wrong in the last year;
Management distraction from Stonegate (and Deltic) bid approaches - this is a perfectly valid point in my view - business is bound to suffer, if a small management team is spending a lot of time handling a takeover bid & other approaches.
Lack of leadership - the outgoing CEO (mark McQuater) left on 18 Oct 2017. The new CEO (Rob Pitcher) joined on 25 June 2018. So that's over 7 months without a proper CEO. Again, for a smallish business, that's bound to have a significant impact on performance. Linked to this, today's RNS also mentions the loss of some experienced senior managers, during this period of uncertainty. The "unsettled workforce" is also mentioned.
Extreme weather - this affected everyone in the sector. However, it's a valid point that most of RBG's sites do not have much outside space (just a small smoking area, mainly). Therefore, it makes sense that the extreme hot weather benefited bar operators with big outside space, but will have harmed RBG. Who wants to be indoors, when it's boiling hot, after all?
World Cup - again, I don't see this as an excuse, it's a genuine factor. My experience at the time, was that people were queuing up, in large numbers, to get into pubs with sports screens. RBG generally doesn't have sports screens, so it would have suffered reduced sales for this reason, as customers went elsewhere.
LFL sales deterioration - from +1.9% in H1 (July-Dec 2017), to -3.2% in H2. There's been a further deterioration to -5.0% in Q1 of the new year (July-Sept 2018). Some investors might be alarmed by this (although there's no sign of panic selling today). Other investors (myself included) had already factored in known negatives listed above, and a -5% recent LFL performance is not as bad as I feared it might have been (my most recent comments on RBG indicated that I thought the company could have one more profit warning in it, before the turnaround under new CEO gained traction)
Cost pressures - mainly staff-related, but these have been partially mitigated through better scheduling.
Exceptional provisions - of £11.1m announced today, seems very large. Of this, £3.3m is fees relating to the aborted takeover bid. This seems extremely high, but it's done now, and like other things above, is one-off in nature. Onerous lease provisions & asset impairments this year, of £7.8m is sizeable. Although note that there has been a considerable tightening-up of accounting procedures, reflected in prior year adjustments, etc. This seems like kitchen-sinking, to clear the decks, which you often find when a new CEO starts. Today's provisions are of course tomorrow's higher profits - as some cash outflows are charged against the provision on the balance sheet, instead of going through the P&L.
Increased bank debt - the bank facility is a £25m RCF, and note 13 indicates that the bank covenants were reset recently, to provide more headroom. The facility was drawn down by £19m at the time of signing the financial statements. That's quite a big increase from c.£5m a couple of years ago. Although it's gone up, I don't see bank debt being anywhere near dangerous levels. It's gone from almost nothing, to a level of about 1.27 EBITDA, which is fine.
Capex - the company is spending heavily on 5 large new sites (with heavy capex) in H1. Heavy capex is discretionary, so can be switched off fairly quickly, if necessary. Therefore, I don't have any worries over the increased bank debt, providing it doesn't continue rising considerably. The commentary indicates that a more cautious approach will be taken to future expansion, whilst they put their house in order, with operational improvements. That's absolutely the right thing to do, and it should see bank debt peak, then start reducing next year.
Overall then, there are lots of things to latch onto, if you want to take a negative view of this company. However, it's all in the price I reckon. If the above issues were not present, then the share price would probably be double what it currently is. So you get what you pay for.
Positives
Hands-on new CEO - it's too early to judge, but the commentary today from the new CEO is music to my ears. All this business needs is decent, hands-on management. It sounds like that's what we've now got;
Historically, the Group's brands have led their market segments but sustained success is delivered by focusing on the detail of our customer proposition - something that has waned due to management distractions and operational management change...
I view all the issues in the negatives section above as being temporary, or one-off factors, that should be relatively straightforward to fix (apart from ongoing upwards pressure on wage costs). Therefore, my view is that, given perhaps a year to mend the business, we could be looking at a much better picture (and hence share price too) this time next year.
New openings - this is a roll-out, with the estate continuing to expand, at an accelerating pace in Jul-Dec 2018, so the new CEO certainly has a lot on his plate. I'm impressed that he's already visited 50 of the company's sites, in his first 3 months.
Mention is made of a new site in Torquay having performed badly, but the rest seem to be doing well. Bear in mind that new sites take about 9 months to mature to full profitability. If I'm reading it correctly, the section about returns on capex seems to be saying that;
- last year's new sites have generated at 18% EBITDA return on capex (held back by Torquay under-performing), but
- this year's new sites are performing much better, at 30% EBITDA return on capex expected once maturity is reached
So not completely plain sailing, but the recent openings appear to be achieving a payback in the 3-4 year range, which is not bad at all. It's clearly a good investment, if the right sites are chosen. Management needs to avoid any more mistakes on site selection. Highly seasonal Torquay seems a strange choice of site.
Dividends - the final divi of 3.3p is maintained, as was the 1.65p interim divi. The total is 4.95p for the year, giving a yield of 4.0%.
Clearly though, paying decent divis, at the same time as a heavy, expansionary capex programme, is causing bank debt to rise (as mentioned above), although that's not a current concern to me. I don't see anything wrong in taking a previously ungeared balance sheet, and incurring new bank borrowings to fund a heavy capex programme - where the capex is delivering an excellent return. If you can get an 18-30% return on investment, then borrowing money at probably 3-4% makes a lot of sense. Providing the total bank debt doesn't become excessive, and result in insolvency in the next recession (as happened to Luminar in 2011).
If the bank debt reduces, once the current heavy capex programme is completed, then it would be fine to continue paying divis. However, if the company keeps ploughing on with new openings, then it would possibly be wise to reduce the divis, or suspend them for a year, perhaps?
Operational improvements - there's loads of stuff in the narrative about steps being taken to improve day-to-day execution. I won't regurgitate that all here - if you're interested, you can read the narrative with today's figures. It all seems excellent to me though, and exactly what is needed.
Outlook - there is some early indication of things improving, re Xmas bookings;
In the first quarter of FY19, like-for-like** sales are -5.0%. However, with many exciting initiatives planned or currently being implemented, as detailed in the CEO's statement, we are confident of improvement.
In addition, pre-booked revenue for the critically important Christmas trading period is currently up 20.3% on the same time last year (up 13.8% on a like-for-like** basis), which we expect to aid our performance.
Furthermore, we do not anticipate a recurrence of the same external circumstances experienced to date in 2018.
I think it's too early to get excited, but there seem to be good initiatives in place to rejuvenate trading over Christmas (Q2 contributes just under half of full year profit).
My opinion - I accept that opinions will differ on this share. It's a classic case of operational problems emerging, and performance declining somewhat as a result. All we have to decide, is whether these are signs of structural decline, or whether the business can recover from temporary problems? My view is firmly that this is probably a recovery situation, but we'll have to be patient to find out.
If the new CEO delivers solid Christmas trading, and it sounds to me as if that's a likely outcome, then I see this share price heading back up towards 200p.
The wild card is whether someone decides to bid for it. Stonegate aren't the only potential suitor. Something might happen with Deltic too, although I suspect probably not. It sounds to me as if the new CEO wants to prove himself by sorting out RBG's own operations. After that, who knows.
I think the turnaround at RBG could be fairly straightforward, and reasonably quick. The business doesn't have any major problems. It just needs a period of new ideas, and decent, hands-on management. They always say that "retail is detail", and it's exactly the same with the hospitality sector too. I like the report from the new CEO today - he seems to be focusing on the right things, and in time this should deliver improved performance. That's just my initial impression though, we'll have to wait and see what the future numbers look like.
Bottom line, if a competitor wanted to buy it at 203p, and nothing has fundamentally changed since then, why would it be worth a lot less now? In fact, it now has more sites, and the new sites are performing well overall. So logically, once the operational issues are sorted out, then the value of the business should be heading upwards of 203p in due course.
We should also consider the downside risks. With more bank debt, things are more highly leveraged to decent performance. If bank debt gets out of hand, and that combines with really bad Q2 trading, then things could get a bit sticky. Although, in the worst case scenario, the business could just shelve the new openings programme, and let the cashflow naturally reduce bank debt. So I'm not sure this is a big risk.
Treatt (LON:TET)
Share price: 473.5p (down 1.8% today, at 12:32)
No. shares: 58.4m
Market cap: £276.5m
Treatt Plc ('Treatt' or the 'Group'), the manufacturer and supplier of innovative ingredient solutions for the flavour, fragrance, beverage and consumer product industries today publishes a trading update for the year ended 30 September 2018.
Key point;
The Board is pleased to confirm that the Group has performed well in the second half of the financial year and despite some foreign exchange headwinds expects to report profit before tax and exceptional items for the year ended 30 September 2018 in line with the Board's earlier expectations.
I'm not sure why they've used this wording, instead of just saying in line with market expectations, which should be the default.
There's more detail, which I'll summarise below;
- Recap on the year - equity fundraising, and disposal of non-core business (Earthoil Plantations)
- US expansion going well - should be operational in H1 2019
- UK site relocation - plans progressing well
- LFL revenue up c.9% in 2018 vs 2017 - all product categories have grown
- Gross margins down a little, due to forex, raw materials & pricing pressures on new business
- Year end net cash £9-10m
- Year end receivables up
- Entering a key investment (capex) phase
- Board looks ahead with confidence
- Results will be published on 27 Nov 2018
Valuation - I can't find any broker updates today. I'll assume there are no changes, as the statement says in line with expectations.
Stockopedia regards it as a "high flyer" (one of the positive classifications), and it has an upper-middle StockRank of 64 - which reflects good quality & momentum, but poor value.
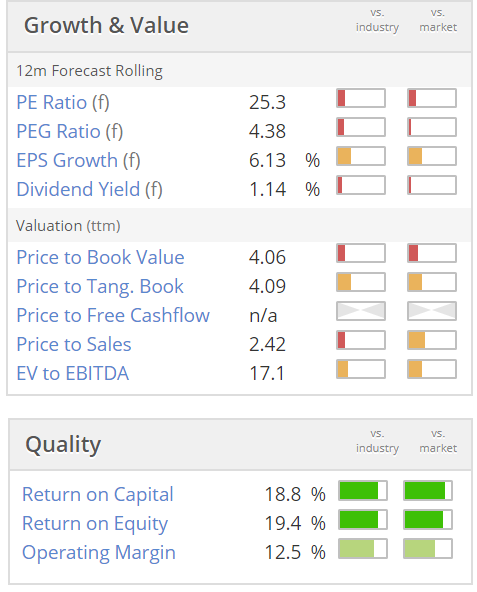
My opinion - this share is one I've held before, and have a positive view on fundamentally.
I'd like to buy back in at some point, but three things make me too nervous to do so now;
- High valuation, and
- Big expansion capex in the pipeline - whilst this seems positive, in that it should increase capacity to meet demand, it also introduces more execution risk than I'm comfortable with.
- I'm not confident enough about the macro/political picture, to want to add any new positions right now, unless they're complete no-brainers
Therefore, whilst today's update sounds OK, this doesn't feel like the right time for me personally, to buy back into this company. Fundamentally though, I have a positive view of this company, and am certainly interested in following its progress from the sidelines.
SCS (LON:SCS)
Share price: 215.5p (up 8.3% today, at 15:12)
No. shares: 40.0m
Market cap: £86.2m
ScS, one of the UK's largest retailers of upholstered furniture and floorings, is pleased to announce its Preliminary Results for the 52 weeks ended 28 July 2018.
The market clearly likes these numbers, with the share price up 8.3%. I can't get hold of any broker research, which is a nuisance, so that limits what I can say about the company. It looks like an earnings beat - with actual EPS of 26.8p comparing favourably with the consensus forecast shown on Stockopedia of 23.8p. This equates to a PER of 8.0 - attractively cheap, providing good performance continues.
So many retailers are complaining about poor footfall, low consumer confidence, etc, it's refreshing to see a company bucking the trend. ScS must be executing well, to be achieving good results.
Current trading - also looks impressive. To be achieving positive LFL sales growth right now, is pretty impressive - many other retailers are not doing so;
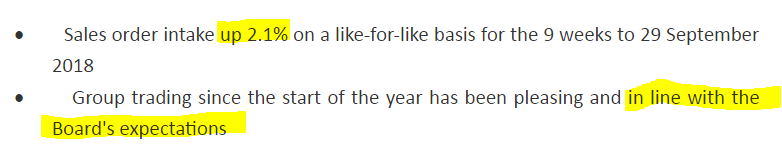
House of Fraser concessions are clearly a headache at present, but it doesn't sound too bad;
Due to the ongoing changes at House of Fraser, trading within our concessions, which represented 7.1% of FY18 gross sales, remains challenging and we are working with the new owners to address this as a priority. Performance in our core ScS business has been encouraging.
Flexible costs - I like this section below. It's a really good point, that I hadn't considered before;
The nature of the Group's business model, where almost all sales are made to order, results in the majority of costs being proportional to sales. This provides the Group with the ability to flex its cost base as revenue changes, protecting the business should there be wider economic pressures.
Lease exposure - this is the number one issue for most retailers. ScS reassures on this point today;
The Group has reduced the average remaining lease tenure of our store portfolio. This has been achieved by targeting lower tenures on existing lease renewals and on new stores. This provides the Group with increased flexibility to exit or relocate stores where required. The majority of recent leases entered into are 10 years in length.
Average remaining tenure length for the Group has dropped from 8.4 years at the end of FY16 to 6.8 years at the end of FY18 (FY17: 7.6 years).
Dividends - total divis of 16.2p are proposed, giving a very healthy yield of 7.5%.
Balance sheet - in the past I've not been terribly keen on this, as the cash pile comes from customers paying up-front. However, on reflection, I'm wondering whether my previous concerns were misplaced? Looking at the balance sheet fresh today, it looks fine to me. There's a £48.2m cash pile, and no bank debt.
Cashflow statement - looks excellent to me. This business is generating a lot of genuine cashflow, and has little capex requirement. So it can pay out big divis without putting any strain on the balance sheet.
My opinion - this business is performing much better than I imagined it would. Whatever they're doing, it's clearly working very well. If this strong performance (in tough conditions) continues, then this share would certainly look great value.
If all the political/macro stuff works out OK, then this share would certainly be on my buy list.
Sorry, I ran out of time before looking at DX (Group) (LON:DX.) results.
See you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
And a good thing - Deltic wanted to be bought then the would in turn run the company... No idea why the proposed merger with Stonegate was rejected.... Will be interesting to see what happens to the share price in the morning...
Deltic off :-
https://www.stockopedia.com/share-prices/revolution-bars-LON:RBG/news/revolution-bars-termination-of-discussions-urn:newsml:reuters.com:20181010:nRSJ6544Da/
Hardly a surprise.
Paul,
Thanks for the very in-depth review of Revolution Bars (LON:RBG)
I couldn't agree more with everything you wrote, eg:
Operating Cash flow (before changes in working capital) is c.£8.5m...which is great for a company valued at £67m and gives me confidence that the balance sheet is significantly protected, even if there were to be further LFL sales declines.
A further point to add is that I follow Revolution Bars (LON:RBG) on twitter. I did't realise I had been following them as they never actually posted anything. However, recently I started receiving tweets on their latest food offerings, which do indeed look appealing. Retweet and likes are still low, but I am seeing a clear improvement in these metrics over the last couple of months. Fingers crossed.
Yes, I hold
GLAH
The Revolution Bars (LON:RBG) summary is still that management - who know what is really going on - backed a sale at 203p.
The shareholders were wrong to reject the management advice, and getting back to 203p is going to be a prolonged struggle.
Hi Aislabie.
I don't mind prolonged struggles if I think the odds are stacked in my favour. A previous value of 203p per share means that currently the intrinsic value of the company could well be greater than the market cap, due to increased sites in-between times. The shareholders were, perhaps, wrong at the time to decline the offer, but the situation now looks like a buying opportunity, and with a revitalised exec team it could well go from strength to strength.
So I think the CURRENT summary is: was misguided, had a bad correction, now looks like value if the new management team can harness the potential.
Paul,
A great report on Revolution Bars (LON:RBG). Thanks.
I'm sorely tempted to take a holding, as I can see value at the current price and the new CEO seems to be making elbow room for a damn good shot at delivering results over the next 6 -12 months.
I'm watching for a good entry point.
Ref Tesla
production figures out today for 3 months ended sep and the numbers are bang on the money as far as the consensus estimates (50-55k model 3's slightly beaten) - model 3 deliveries in the period were double the level of all previous periods to date. so hopefully the extra sales will eat massively (but probably not entirely) into their ongoing cashflow negativity.
Interesting fact that the model 3 was the top grossing car in the US for August (and likely September too) - ignoring pickups - so the comments about the company not being able to mass produce cars will hopefully now slightly diminish.
finally they delivered more cars than they produced so the rumours about them not being able to sell the vehicles due to lack of buyers or the cars not being fit to be sold seem to be wide of the mark.
I guess none of the above will change the minds of the non believers one iota at present, in some respects till they are decently cashflow positive and profitable on sensible non adjusted silly adjustments profit and loss wise i would expect most bods not to be convinced the company justifies its premium rating.
Now if only Twitter would ban Musky then ..........
I am afraid I am not sure Paul is not looking at RBG as objectively as he does on other stocks. No criticism intended at all.....I just think there is much more downside risk here than is suggested. I think the business is not as robust as they say and resolving the dire food offer is not as simple as some think.
I did very well out of these on the bid...it roared well above the 203 price at one stage. I would def be a buyer towards the 100 pence level but I have a higher risk appetite than most.
Hi BarnetPeter,
I am afraid I am not sure Paul is not looking at RBG as objectively as he does on other stocks...
Well, I tried my best, by starting the section on Revolution Bars (LON:RBG) with a massive list of every negative point I could think of!!! Headed, "Negatives" in large font!
The new food offering has already been launched actually. I've not tried it yet, but this might be a good excuse for me to pop down to my local and have a meal & a couple of pornstar martinis!
When I met the (fairly) new CFO, formerly from WalkAbout, he commented in passing that RBG makes "staggering returns" from its bars. I find that people often form their view on RBG based on what their local bar is like. Some of them are starting to look like they need a refresh, which the CEO mentions in today's report (e.g. Bournemouth, Brighton). However, if you look at the new sites, e.g. Reading Rev de C, it's fantastic. They're doing £1m fit-outs on the new sites, so they look the absolute business. And with time, the new sites become a larger proportion of the total.
With decent management, there's every chance performance could return to growth, in my view. Remember this company has basically been rudderless, in terms of management, for 7 months. It's actually quite surprising that it's managed to perform as well as it has, without key management.
Anyway, time will tell, nothing's guaranteed. I think risk:reward is leaning towards reward, on a turnaround. You don't. That's fine, it's what makes a market! But I don't think your comment that I'm not being objective is fair. I wrote about both the negatives and the positives, then gave an opinion. Which may turn out to be right, or wrong, we'll have to wait & see!
Regards, Paul.
Hi Paul,
I had similar thoughts to BarnetPeter.. No criticism whatsoever of the way you very clearly laid out the pros and cons - excellent as ever, but when if came to your conclusion I was personally somewhat reminded of some of my own spirited defences of holding "value traps".
RBG escapes being given the value trap label by stock primarily because of the fantastic "Gross Profit to Assets ratio" contributing to the quality measure.(Although that might not be a great measure in this case given that the bar staff are really a variable cost rather than an overhead).
Perhaps though the thing that most struck me was your statement :
Somebody said yesterday (I think) that whenever they catch themselves using the word "hopefully" they realise it is time to sell in the current market - I have similar thoughts about the word "probably" at the moment.
As you say though we each reach different conclusions and yours and Graham's work here every day are a tremendous resource to help people make their own decisions, but they won't all be the same.
I'll keep my eye on RBG but I don't see the attraction right now.
on an apropos, notice that Funding Circle Holdings (LON:FCH) is down 10% today and below its IPO price: I have used them in the past as a bit of a bond proxy but wan't overly impressed with their practices and operations.... increasingly I don't opt into IPOs as price action in year one seems to follow a similar paths.
I prefer to see good signs of exits by the loose hands and bottoming of price action before taking positions.
One for the watchlist ... maybe
Paul
did you see one of the restatements at RBG is the uncleared debit/credit card payments from last few days trading have been moved to receivables, previously classified as cash. £1.3m one off reduction in cash. Good example of new CFO putting in place robust accounting policies.
Not familiar with the relevant standards myself, but I would have thought uncleared card payments should count as cash. Receivables surely is payments where you may not get paid if the debtor gets into trouble, while an uncleared card payment is one that has already been approved by the debtor's bank. Do Revolution Bars (LON:RBG) have a lot of card payments that the bank subsequently rejects?
I agree, a very high quality receivable as already authorised by card provider
on Revolution Bars I think the new CFO has been quite aggressive in adopting much harsher accounting policies which have resulted in a number of negative restatements to historic numbers but will give a tailwind to profits for the next few years. the new financial disclosure is very good. remains to be seen if new food director can make a difference. although I don't like management blaming the weather generally the extreme cold and extended heat wave (and World Cup) must have been a headwind for their type of bar and no CEO for 6 months won't have helped. All in all operating profits flat on last year not a bad result. Share reaction looks like the market is giving the new CEO a chance to fix things. Long and happy to hold as potential upside more than downside from here.
Regarding Revolution Bars (LON:RBG) I wonder if the new CEO has kitchen sinked the exceptionals whilst he has the chance of being called a new broom, and this may flatter future comparable periods, and allow him to give an upside on H1 18/19.
Its good that the Christmas bookings are up quite a bit. They still have a bit to do on the food side, and the staff rostering software does not appear to have been implemented well. But this may be down to a period of drift with now CEO.
Looking forward to Paul's take on things.
Any chance of a look at the National Milk Records (OFEX:NMRP) final results? Will their divorce from the pension fund leave a profitable and growing business?
National Milk Records National Milk Records (OFEX:NMRP) - irrespective of what one might think of the business, it's pretty academic as there is close to zero liquidity. It's just about the least liquid stock I've ever tried to buy!
Quite correct. I tried to purchase half a dozen times over the last two years. It is nearly impossible. (But a cracking niche business)
There's a certain irony in National Milk Records (OFEX:NMRP) having no liquidity.
Very good, EffortlessCool..........................!
On National Milk Records (OFEX:NMRP) ....
I read up on this company for first time today as seems a little odd and interesting. Does anyone know it a bit?
Underlying profit improvement this year despite falling revenue is driven by an even bigger cut in Admin expense. From the data given its hard to understand why. There's a hint the 2018 report that it could be through a cut in R&D...if so that would be hefty and perhaps as much as £3m suggesting projects shelved.
Any light from anyone that knows a bit more?
I'm very interested in your opinion on the finals from Revolution Bars (LON:RBG) Paul, as you hold (I don't).
To me these look terrible - they are blaming all kinds of things, including the weather and the world cup! That seems really odd, considering EI (LON:EIG) (which I do hold) reported very good figures boosted by the world cup. It has me all confused... and with a current lfl of -5.3% I won't be going anywhere near them. But perhaps the long-awaited predator will take the opportunity when the price drifts low enough to take them out. I found this statement quite amusing "This is a fundamentally good business which has seen significant disruption over the past year and factors outside of its control" - doesn't a business have to adapt to the environment?
Revolution Bars (LON:RBG)
This is morphing from a nice simple self funding rollout business to something more sketchy.
Lets look at the current and non current liabilities - at 31/7/16 the total was £26 mill at 31/7/2017 the total was £35 mill and at 31/7/2018 £52 mill - anything other than a self funding rollout. Ok there may be some legitimate reasons partly explaining the difference (onerous lease provisions) - but the trend is very poor factoring in the backward trend in profits and cash being generated.
There is nothing at present that would make me want to buy back in here despite the lowly shareprice.
Hopefully for holders the new CEO can work some magic and reverse the poor LFL's - having sampled the bars i would still have hope in the basic business plan if they can execute.
I can’t help feeling that Revolution Bars (LON:RBG) are still one of the lame ducks of the drinking venues. The class act for cocktail bars seems to be the unquoted Be At One chain that seem to have no problem growing in the current environment. No wonder Stonegate decided to buy them from their private equity owners earlier this year.
http://www.piper.co.uk/our-brands/be-at-one/
(No position long or short)
I'm not surprised to see Treatt (LON:TET) down 5% this morning.
There's nothing wrong with the TU, just inline. But the valuation was pretty full previously IMO.
Personally I can see the potential for the figures to take a wobble with all the investment going on, at which point the price may also wobble and I'll be there!
The market has marked Burford Capital (LON:BUR) down 7% to the oversubscribed placing price, which on an 11bps spread gives PIs a chance to participate. I shall do so.
I seriously don't know what to make of Revolution Bars (LON:RBG)
the LFL declines seem to be accelerating and yet we are told Christmas bookings are up 20%.
The adjustments made especially to opening costs are very questionable as presumably they will need to refurbish some of the older ones soon (does that come out as an adjustment also?) The acquisition costs are strange given they were the company being bid for and there doesn't seem to be a lot of detail around the nearly 7m of impairments on leases. We've been told about the food move now for over a year and there's a wonder whether that will ever happen.
I still hold but have less conviction than ever
My morning smallcap tweet: Revolution Bars serves mixed cocktail.
Pennant International (LON:PEN), Tekcapital (LON:TEK), SCS (LON:SCS), DX (Group) (LON:DX.), Revolution Bars (LON:RBG)
Pennant (PEN) wins £10.2m Middle East order. Performed over the 2018, 2019 and 2020 FYs.
Tekcapital (TEK) placing at 7.5p, a 12% discount. " significant amount of the Placing will be utilised to expand Tekcapital's commercialisation of their investment portfolio of businesses."
ScS (SCS) FY ahead of market expectations. Rev up 1%, EPS 26.8p up 14%.FY div 16.2 up 10%. Trading: Sales order intake up 2.1% LFL for the 9 weeks to 29 September. Group trading in line with the Board's expectations.
DX Group (DX.) FY slightly ahead of market expectations. Rev up 3%, EPS -8.1p (-40.3p). Net debt £1.1m (£19.1m), ahead of market expectations. Current trading encouraging.
Revolution Bars (RBG) FY as guided. LFL rev -0.6%. EPS -5.7p (+7.7p [restated]). Adj EPS 13.p (14.6p [restated]). Div 3.3p (3.3p). Recent LFL -5% "but benefits of new initiatives put in place by new CEO yet to work through". Pre-booked Christmas sales up 20.3% (LFL 14%). I hold.
I'd be interested in your view of DX (Group) (LON:DX.), Paul. Preliminary results this morning show a large, but much reduced, loss and a significant reduction in net debt. The outlook statement is relatively optimistic.
https://www.investegate.co.uk/dx--group--plc--dx--/rns/preliminary-results/201810020700045937C/
Turnaround opportunity or basket case?