Small Cap Value Report (Tue 21 April 2020) - Bankruptcies, SFR, JOUL, GOCO, FLO, LID

Morning! Graham here.
Bankruptcies
I'm sure you will all appreciate the cheery headline.
As a follow-up to yesterday's Covid-19 update, I thought I would spend a few minutes reflecting on the poor financial health of the travel & leisure industry, which is currently a fast-moving situation.
Airlines
Last night, it emerged that Virgin Australia entered into a voluntary administration (Sky, BBC), after the Australian government turned down its request for a loan.
It had already been struggling under a large pile of long-term debt (A$5 billion), and figured that this was the best way of restructuring.
Shortly before that news broke, Sir Richard Branson (who owns 10% of the company) published an open letter to employees. He wrote:
We are hopeful that Virgin Australia can emerge stronger than ever, as a more sustainable, financially viable airline.
With regards to Virgin Atlantic, he said:
...we will do everything we can to keep the airline going - but we will need government support to achieve that in the face of the severe uncertainty surrounding travel today and not knowing how long the planes will be grounded for. This would be in the form of a commercial loan – it wouldn’t be free money and the airline would pay it back (as easyJet will do for the £600m loan the government recently gave them).
The entire industry is facing calamity.
I've been doing some work on Easyjet (LON:EZJ) recently - that's a stock that I would consider selling short, to hedge against the risk of continued lockdown and/or to speculate on its cash burn accelerating via operating losses and too many Airbus orders.
The dispute at easyJet with its major shareholder adds to the controversy and the drama.
The general public shouldn't be overly concerned by any of this - as others have noted, it doesn't matter to them who owns the planes or the brand they are flying with.
For equity holders, it's a different story. There is a real risk of airlines changing hands, from their current owners to their lenders or to new investors.
Something I didn't mention about Berkshire Hathaway (BRK.B)* in yesterday's report: one of the few noteworthy trades it made recently was the sale of $400 million in airline stocks.
It still owns big stakes in the airlines, so I don't want to over-egg the importance of these trades, but I still thought it was interesting. It's not as if Berkshire has any particular need to raise money...
Hotels
Travelodge is in difficulty, though not currently in administration.
It didn't pay its landlords for this quarter, choosing instead to see what it could negotiate with them.
One of the landlords, Secure Income REIT (LON:SIR), made an RNS announcement yesterday:
Secure Income REIT plc has already reluctantly initiated actions to recover this debt, but remains hopeful that this matter can still be settled prior to those options being fully pursued.
The hotel group has hired Deloitte and Moelis to help it figure out what to do. Never a great sign.
Travelodge last got restructured in 2012 and is owned by its former lenders. It looks like the equity might get passed around again.
Restaurants
While there is plenty of domestic demand for restaurants, none of that matters when the doors are shut.
So far, I've noticed the collapse of Carluccio's, Chiquito (owned by Restaurant (LON:RTN) ). and Mark Hix. Many more are vulnerable
At the risk of sounding obvious, these sectors are likely to have a shared destiny: airlines, hotels, their landlords. And restaurants, to an extent.
And for companies which supply each other, the bankruptcy of one can lead to financial difficulties for another, as bills go unpaid.
Central banks will print like crazy to prevent this from happening, but what we are looking at is the classic spiral in a depression as financial failure creates knock-on effects across the economy.
Far from a V-shaped recovery, I see the future as a Nike "swoosh" - a quick financial collapse, followed by a gradual rebuilding.
Negative Oil
In other unusual news yesterday, which is related to the collapse of travel, the price of US oil for the May futures contract fell to minus $37.63.
I should probably mention that the May contract wasn't "front month". Almost nobody was trading it, and the open interest (number of outstanding contracts) was tiny - only about 3% of the June contract. This means that the "negative oil price" will have affected very few people.
In addition to the over-supply of oil, the negative price might have been driven by a technical factor such as the implosion of an oil trader.
So I wouldn't get too worked up about it. It's still highly unusual, of course - not something you see every day!
*Disclosure: Long BRK.B.
Ok, small-caps of interest today:
- Severfield (LON:SFR)
- Joules (LON:JOUL)
- Goco (LON:GOCO)
- Flowtech Fluidpower (LON:FLO)
- Lidco (LON:LID)
Severfield (LON:SFR)
- Share price: 66.4p (-2%)
- No. of shares: 306 million
- Market cap: £203 million
This is a structural steel manufacturer. Let's see how it's doing:
- "factories and sites are remaining operational where it is safe and practical to do so".
- Order book £293 million - this is down from November, still up compared to the same time last year (£274 million a year ago).
- No material impact to the result for FY March 2020.
Guidance is withdrawn, as almost all companies have done.
Balance sheet - gross cash at year-end is £44 million, and total headroom is in excess of £50 million.
This is after drawing down fully on its RCF. Net funds are £16 million.
Indian JV - no guidance for what this might achieve in the current financial year. The scenes from India have been frightening, as the lockdown pushes large numbers of people immediately into food poverty. I'm sure many of them feel that they would prefer to get the virus, than to go hungry.
The capacity of this JV has increased, but again the order book is down, compared to November.
My view
No strong view on this, as it's not a sector I know well.
I will say that the cash headroom looks more than sufficient - about six months of the operating expenses seen in prior years.
Some construction work is still taking place. That being the case, and with Severfield closely managing its costs, I think the bank should remain relaxed.
Joules (LON:JOUL)
- Share price: 84.4p (+12.5%)
- No. of shares: 108 million
- Market cap: £91 million
Joules has been fixing its balance sheet, first with a £15 million placing at 80p, and now with an increase in its RCF at Barclays.
The £15 million increase in the RCF brings it up to a new size of £40 million.
Net debt as of two days ago was £6.9 million, with available headroom of £43 million.
When we are looking at survival prospects in the very short-term, it's the headroom that counts, much more than the net debt position. Headroom going to zero means that the cash has literally run out.
In the case of Joules (and SFR), headroom is currently plentiful. So they are not at immediate risk of cash running out.
This changes if debt facilities are withdrawn, e.g. if covenants are tripped in an RCF or if an overdraft is called in. Barclays appears to be supportive of Joules, judging by its action today.
E-commerce - open for business and doing better than Joules expected it would, when lockdown began (I don't know how low those expectations were).
Historically, e-commerce was responsible for half of revenues.
My view - this appears capable of surviving the lockdown, having raised fresh funds. The available headroom represents c. five months of historic operating expenses, and current operating expenses should be running much lower than their historic levels.
Goco (LON:GOCO)
- Share price: 70.8p (-7%)
- No. of shares: 420 million
- Market cap: £297 million
Formerly known as Gocompare, I held Goco until January of this year. I don't like the new name at all (but that's not why I sold!)
This is a very confident RNS, despite withdrawing financial guidance for the current year:
- cash is £27 million and £22 million is undrawn from RCF, i.e. total headroom is £49 million.
- debt is 2.1x trailing adjusted EBITDA, below covenant (the covenant is 3.0x - more companies should say what their covenants are, when they discuss their RCF)
- expects to generate positive operational cash flow "even under multiple stress scenarios"
- will pay the 0.5p dividend previously announced. That costs only £2 million, no big deal.
Q1 (January to March) was quite good, revenues +6% year-on-year.
There is some serious growth happening in the "AutoSave" segment (comprised of Weflip and Look After My Bills).
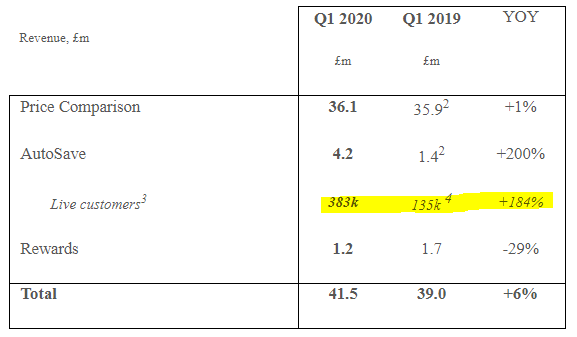
Those gains are offset by the large fall in revenue from MyVoucherCodes (the "Rewards" segment). GoCo says this is purely down to the C-19 crisis.
Media trends - people aren't searching for car insurance much these days. Why would they?
Search traffic via Google is lower. On the other hand, people are spending more time on Facebook, YouTube, etc.
People who were marginal drivers before now, are becoming non-drivers. More than half a million cars were taken off the road in March (double the number seen in February).
Additionally, young people will delay getting their first car (e.g. because they have no job and can't afford one, and/or because they aren't allowed to go anywhere).
These are very negative trends for the car insurance market. One of the few silver linings is that it's now much cheaper for Goco to buy TV advertising.
My view
I didn't particularly want to sell this share.
The new products are innovative and being received very well. And the core busines is holding its own, with a very well-known brand (maybe "well-liked" would be pushing it, as the ads are hated by many!)
Stocko gives it the thumbs up as far as Quality goes, with a QualityRank of 91.
Management strike me as reasonable, so I would take the dividend payment as a good sign that the business remains healthy, despite these extraordinary circumstances.
Flowtech Fluidpower (LON:FLO)
- Share price: 68.8p (+15.6%)
- No. of shares: 61 million
- Market cap: £42 million
Like almost everybody else, lockdown hurt the end of Q1 for Flowtech, a provider of components and services:
Many of our suppliers and customers suspended operations, although recent indications suggest that some have either already reopened or are planning to reopen in May, albeit with reduced capacity.
Whenever you hear about capex being cut back, there is a supplier somewhere who is missing out.
That supplier could be an equipment manufacturer, who in turn is supplied by someone like Flowtech Fluidpower. The ripples of spending decisions are felt all around the economy.
Outlook - no guidance is given. Customers in the manufacturing and construction sectors might get active again in May, or they might not be. Nobody knows.
The outlook statement is a blank. They don't know what is going to happen, and don't bother pretending that they do. They do say that more cost reductions might be needed, if the lockdown is extended.
My view
There seems little point in trying to guess what might happen here, since this is not an industry I know much about, and the company itself can't guide investors.
Prior to Covid-19, EPS was forecast to come in around 12p. A cheap multiple against pre-Covid earnings, then.
The company seems relaxed about cash flow/debt, and has up to £9 million - £10 million available in its banking facilities.
If you liked this company before the crisis, then you should probably like it even more at the current share price. Watch out, though - the end-markets are looking weak in the short and medium-term.
Lidco (LON:LID)
- Share price: 8.75p (-3%)
- No. of shares: 244 million
- Market cap: £21 million
From one type of flow to another. Lidco is in the business of cardiac monitoring.
FY January 2019 shows good growth in the revenue from Lidco's own products (19%), at the expense of third -party products. Total revenues are up just 3% to £7.55 million.
The boost in own-product sales helps to increase gross margin, and reduces the loss for the year.
This company seems to have been around for a long time, with a very patchy record of profitability. More often than not, it makes a loss.
The share count has increased significantly over time, with the most recent increase in 2017.
Year-end cash was £1.36 million.
Covid-19
Some big news was already priced in:
Significant increased demand as a result of COVID-19 with 195 monitors sold to date, predominantly to the UK market, compared with 219 monitors sold in the whole of FY20
Board expects that sales in the three months ending 30 April 2020 will significantly exceed total sales of £3.5m achieved in H1 FY20
The body's reactions to viral infection can cause sepsis (blood infection). While Lidco's products aren't specifically designed for Covid-19 treatment, they do apparently help to treat sepsis.
Recurring revenues
it's trying to improve visibility with long-term customer contracts, and appears to be making progress on that front (recurring revenue base now £2.2 million).
It hasn't cracked the US yet - is working on that.
Outlook
The company expects a large cash inflow in H1 on the back of the spike in demand.
My view
I can't express a strong view here, since I don't know enough about Lidco's markets and products. If it can use the windfall profits wisely, perhaps it can create a better future than its past?
Calling it a day there, thanks everyone.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
Goco (LON:GOCO) seems to me to be well worth hanging onto. It was spun out of Esure (LON:ESUR) , and like that company is effectively run by Sir Peter Wood. He founded both Esure (LON:ESUR) and Direct Line Insurance (LON:DLG) , and has made no secret of the fact he wants to sell the company up. He is now over 70 and there was a rejected bid a while back at 120. Should that, or anything near it, be offered again I am sure we will see a takeover. In the meantime there is an acceptable dividend.
Lidco (LON:LID) . I can't get excited about Lidco. The sales of monitors for FY20 raised £1.8m Assuming the surge in sales lasts two quarters a back of the envelope calculation gives them a np of £900k for FY21 which is relatively good after several years of losses but it does look like a one off to me. Plus of course, the sp is already well ahead.
Good results out from £RGBP today and it seems that business is pretty much unaffected by Covid19 other than a delay in a couple of Convex deals completing, Any comments Graham appreciated. I hold.
Sumo (LON:SUMO) FY19 analysts' presentation from this morning. It has a very positive tone.
Separately, do join the Thursday piworld webinar, this Thursday 23rd April at 1pm, where Leon Boros, ISA millionare, will be discussing current markets, and what he's buying or shorting. Register here.
Hello TamzinPiworld,
Proved impossible to register...may I suggest you post link here once webinar has completed, so subscribers on STOCKOPEDIA can see your excellent link.
I have just managed to register so it appears to have been fixed.
peter, my comment was really a tongue in cheek swipe at the Trust's choice of language - they made it sound as though they were now asking their staff to take a well earned couple of weeks off by the beach somewhere nice and sunny.
I'm sure many NHS staff could do with break but somehow describing it as a "holiday" seemed a bit crass (to me at least).
"in his Trust Medical Staff are now being "instructed to take their holidays" "
Given the current situation presumably that's the same as "stay at home".
Yes you are probably right Laughton. I would also interpret the NHS Trust asking their staff to take a holiday as indicating that, like the WHO, the Trust believes that the worst is still to come in this pandemic so they want to maximise the number of staff they available in the medium term future. In terms of absolute numbers, I would anticipate that the numbers of cases and deaths in the UK are near the peak in terms of rates per day. However, I am almost certain that we are at a relatively early stage of this pandemic which will rumble on with reduced but unacceptably high numbers of deaths for many months to come. This conclusion is based on the biology of the virus, notably the remarkably high infectivity, and the sad fact that we are nowhere near achieving herd immunity.
I saw an interesting theory on Twitter about the sale of airline holdings by Berkshire Hathaway and that was that Warren Buffet had previously openly admitted in a TV interview (which I later watched) that he had misjudged the level of his holdings which had taken him above the reporting threshold. Those disposals will now move him below the threshold. I'm not fully conversant with the reporting thresholds in the US from memory but, if correct, that would allow him to adjust his positions out of the public gaze and negate the "Warren Buffett effect" on his additions/disposals.
Interesting point Tom.
I do wonder whether famous hotel owner, Donald Trump, will let current hotel economics influence lockdown policy.
Graham - Pls could you take a look at Lidco (LON:LID)? Thx
Sure, taking a look at Lidco (LON:LID) shortly. G
"It's a slight shame this app hasn't had more plugged in the press and perhaps at an official goverment level"
It could be because it is a private Venture Capital backed project and not a formal government initiative.
A question on oil prices from a complete oil/gas novice, specifically with regards to producers who have hedged their sales for this year already.
With prices at ridiculously low level, is it not simpler (and easier?) to switch off production, and profit between their higher hedged sales price and the current futures price?
Looking at an update from Rockrose Energy (LON:RRE) (which I pick as I know it's a favourite here) I see that they hedged a chunk of their sales position for both 2020 and 2021. Surely a risk free opportunity for them?
I don't think it is that easy just to switch off production when a well is flowing. Normally you would not want to abandon the well. Having a hedge in place is very helpful of course in the short-term but I am afraid there will be always be a lot of costs involved. Also, the local political position will be important to oil companies. Creating local unemployment and stopping local payments in countries that rely on oil to feed their population ....in five years when oil may be high again and the company needs to apply for a new permit....memories are long.
Countries that rely on oil to feed their population tend to use oil to feed their autocratic politicians and their friends.
Thanks BarnetPeter
A few follow-ups if I may:
1 - Do you know how much it would cost to switch off production? I understand it might be difficult to stop and start-up production, but would companies really never choose this option?
2 - I wasn't implying stopping payments to workers. Simply pay the workers and then pocket the hedging difference as profit (see 3. below).
3 - From a previous announcement it looks like Rockrose Energy (LON:RRE) are hedged until 2022 (for gas at least), at what appear quite high prices. Given the environment I (perhaps naively) assumed the company might be able to shut down production, hedge out their positions for guaranteed profits, then restart once prices return to normal.
I have never really looked into oil and gas, so apologies if the above come across as very basic.
Cheers
A
"€0.53 per therm (49p/therm) for calendar 2020. Looking further ahead, an additional 54 million therms has been hedged in each of 2021 and 2022 at €0.41 and €0.45 per therm (38p and 42p) respectively."
Apparently Admiral (LON:ADM) will give a £25 rebate to all motor policy holders. This may have repercussions for other insurers.
I can imagine that with so little traffic on the roads there is less chance of collisions while I guess that with my car sat on my drive it balances out the idiot who manages not to negotiate a bend in the road.
I received a home insurance renewal quote from Admiral on Friday. About the same price as last year. I pressed the "cancellation button" as I felt I could shop around and I have the time to do so. Yesterday they wrote with a new offer; £80 discount on the Friday offer. That's fair.
Interesting item on Newsnight with a commentator saying we reached peak a few days back, and now we should be seeing the plans for lockdown being eased.
the most excellent covid symptom tracker app is showing a 71% decline in people with active symptoms from the peak levels which is a nicely promising stat , It's probably not a accurate stat as i suspect there was probably a spike of people signing up with symptoms when it was briefly very will advertised, but it's certainly most excellent at what it does due to its simplicity of use.
There are 2.5 mill people registered users too - so its a very large sample size albeit with a probably non representative sample of the population reporting. It's a slight shame this app hasn't had more plugged in the press and perhaps at an official goverment level (probably way more useful than standing outside ones house and clapping) - as the higher the number of users updating the more accuare the data is likely to be. Stats from apps like this should be particularly useful to get a handle on whether there are any spikes when the full lockdown is relaxed presume it retains a reasonably consistent user base.
https://covid.joinzoe.com/post/covid-cases-fall
I use this app to report and can endorse how easy it is to use. I am part of the Legion of people who think they've probably had Covid but with mild symptoms (in my case a top flight cough and mild loss of taste/smell). Their stats point to a 2-3% infection rate that varies by Region (though I am not sure how this is calculated). This, plus the official stats and a first hand update from a Registrar friend saying that in his Trust Medical Staff are now being "instructed to take their holidays" says to me that we may start easing up restrictions quicker than hoped.
Clearly there is a danger of a second wave and there is a danger of complacency - but this also needs to be balanced against the economic and associated impacts - which the ONS have started flagging.
My best guess at the moment is we are going to see a W type recovery - a rally when restrictions start to ease - followed by another dip when the impact in certain sectors is better understood - then a more gentle recovery.
Good luck to all - I have appreciated many of your wise inputs to date.
Hi Graham
Not worthy of much analysis on your part but it terms of the general economy I take it as a positive sign that Michelmersh Brick Holdings (LON:MBH), which shut down production on 25-Mar-20, has recommenced production at all plants from today.
I wonder if this is a precursor to an outbreak of common sense in the construction sector with work restarting wherever possible consistent with social distancing.
I cannot imagine Michelmersh Brick Holdings (LON:MBH) doing this unless it was pretty certain there would be demand for its output of bricks/pavers.
Shanklin - My reading of the RNS is that it is going to be a slow ramp-up. But I agree with you that it looks very odd, since their customers are presumably in near lockdown mode. Could be wrong.
Re: Michelmersh Brick Holdings (LON:MBH)
There's no lockdown on construction as long as they can maintain social distancing. Presumably on some sites that's very difficult, but not on all. I'd be more concerned about the longer term, the Knight Franks report and the figures out of Rightmove (LON:RMV) yesterday both made grim reading:
https://propertyindustryeye.co...
timarr
Michelmersh Brick Holdings (LON:MBH)
I am guessing (but may be completely wrong) it may be less of an evil to produce bricks that have no customer now and incur the maginal extra cost than let the facility sit idle. Presumably by building up a buffer of bricks that may come is useful if there is ever demand beyond capacity or it may give them more scope ref future shutdowns for refurbs etc. I am gessing pretty much any brick sold will be sold at profit - perhaps even making a more bog standard brick than they would nromally do if they can sell these quickly for a lower margin.
Hi Graham, could you comment on RBGP if you have time. Seems a positive report to me
Hi Graham
It really is heart-wrenching to see great British companies and their employees brought to their knees through no fault of theirs. I just hope that we have a government that can rise to the occasion and mitigate the disaster that is unfolding in front of our eyes.
On the topic of oil, Brent crude currently down 22% today to $21, and WTI June now only $12!
Yes I respectfully do not agree with Graham's views on the oil fall last night to minus $37. I think it has highlighted many issues and how dangerous this entire market has become. Brent crude continuous contract has today broken through $20 and I sense that the price is sitting on a piece of thinning ice. There are record numbers of tankers full of oil ....one analyst wrote today "When oil turns into a negative-yielding asset, that's a signal that the imbalance between supply and demand has reached a crescendo so great that producers are losing money to get oil off their books. And speculators are playing a game of 'musical chairs' to see who ends up holding those contracts at the end,"
"However, even though the damage to price isn’t likely the function of a “hedge-fund blowup,” and the June contracts are in comparatively good shape, the alternative reason for Monday’s oil collapse may be even less appetising, as it suggests an oil market that may be unravelling.
“That’s why pointing to more measured declines in out-month futures is whistling past the graveyard; it doesn’t change the message from the overall crude market that the industry is breaking,” analysts wrote.
Agreed. Stockmarkets are telling us one thing, the oil market another.
I believe this is the first time that oil in the US has ever traded negative.
Hi
Re Oil prices, I'm more with you that when you start to see really strange things with any asset, in a highly volatile market entering into recession, it indicates structural problems & the implications come later. This very much happened in 2008/9 and I think we are at the start of these behaviours & the outcomes are completely unpredictable, we'll only see them as things blowup. Then, quite likely we get the next phase of the down leg, unless that happens sooner given the potential for economic destrution.
The -$37 price related to WTI Crude which apparently is a physical delivery futures contract. I also understand that WTI cannot be exported from the US so that perhaps contributed to the sharp fall as the game of musical chairs came to an end.
Apparently you also have to take physical delivery in Cushing, Oklahoma. One person on Twitter commented “Not even people who live in Oklahoma willingly go to Cushing.”
Interesting item on Newsnight with a commentator saying we reached peak a few days back, and now we should be seeing the plans for lockdown being eased. Scotland are muttering about issuing plans imminently (there is always a sub-agenda with them of course).
So we can expect some developments in the coming days, with social distancing etc still playing its part
I just can't share your optimism.
Think of the pandemic like a fire. Those without immunity are the fuel, and social mixing is the oxygen. Lockdown has reduced the burn to a smoulder, but if the WHO are right and even the Stanford study suggests that they are, 98-97% of people in the UK are the pandemic equivalent of seasoned kindling.
These are the numbers with an unprecedented lockdown in place:
Easing lockdown would be like running up to a building pouring smoke and kicking all the doors open. I think we have to start thinking more along the lines, not of "When does this end?" but instead; "When does it begin?"
Very emotive and can see your view, but the one thing that encourages me to believe differently is that the data on your chart shows the awful situation 11 days ago - a massive amount of time when in a crisis situation.
I posted yesterday my discovery of the NHS daily statistics, and of using that to form my own view. And my view is that the red line will not continue that trajectory when it is published next week. I don't know it, and it feels almost perverse to do so, but I would back my view based on looking in depth at NHS England daily data, rather then taking the press reporting view.
Hi Graham, Please can you comment on today's RNS from Severfield ?
A.J.Bell: Part of a company statement "As a financially strong business, we have been able to assure every member of staff that their jobs are safe, no one will be furloughed and everyone will continue to be paid as normal throughout the crisis. Whilst we have identified a number of staff who could have been furloughed, we believe that the Government’s Job Retention Scheme should be preserved for those companies that need it most. Additionally, we will not be claiming benefits from any of the other financial support schemes available to employers – for example, we will be not be deferring our VAT bill. " Just think how supportive staff will be when things return to normal.
A reflection of how expensive for customers and lucrative for managers the UK asset management business remains; there is an implicit agreement not to compete on price.
Disclosure: A customer of AJ Bell and invested in too many UK based asset managers to list.
Bonitabeach
There are also barriers to competition in this sector.
For effective competition, we need a regime where customers can move from one broker to another, with no exit fees and a reasonable maximum time limit when they cannot access the portfolio (e.g. 2 hours).
The FCA seem to spend no end of time on bank accounts, where it is very easy to move provider and they do very little to fix the problems with brokers, where moving is difficult. This smells of regulatory capture.
Also, it would be much better if we had a Singapore style system, where people hold their shares directly on an electronic repository & can buy with one broker and sell with another. That improves competition and removes the risks with brokers holding our shares in a nominee account.
Another vote for Lidco (LON:LID) please, Graham. I don't hold, but today's prelims look encouraging and I'd welcome your view of the balance sheet strength.
Morning everyone,
I know it's far from a small cap but the Associated British Foods (LON:ABF) personal message from the Chief Exec. makes sobering and heartfelt reading https://www.investegate.co.uk/assoc-british-foods--abf-/rns/interim-results-announcement/202004210700022665K/ including:
"And when we are allowed to reopen we must make our Primark stores safe for our staff and our customers, even if that means ensuring there are fewer people shopping at any one time and so accepting lower sales at least until the remaining risk is minimal. In time we can rebuild the profits. We can't replace the people we lose."
"From making sales of £650m each month, since the last of our stores closed on 22 March, we have sold nothing. One of the world's great clothing retailers is entirely shut. We have paid for in full, and taken delivery of, very large amounts of completed stock which we can't sell for now ..."
Now this has had a much worse impact on Primark, since they don't do online shopping (will they rethink that now?), but this is quite some impact. It's worth pointing out that food businesses of Associated British Foods (LON:ABF) have been open and very busy.
Chris
I think it's worth quoting the end of the statement from the Associated British Foods (LON:ABF) CEO:
The willingness of thousands of our people to come to work whilst so many of the rest of us sit this disease out safely at home has been humbling; and the ingenuity, hard work and leadership of dozens and dozens of frontline managers has been amazing. Our factories are full of people who know how vital their work is and who are skilled and committed. Our success in keeping the nation fed is testament to the robustness of the modern food chain; it is also testament to the reality that you don't need to tell most people how to behave well, you just need to allow them to do so; and it is the finest thing I have seen in a career in business.
timarr
As the Associated British Foods (LON:ABF) personal statement has been mentioned already, and whilst it clearly isn't a small cap share, I think it goes some way to illustrating the quality of the management and the 'family company' nature of the holding structure. The Weston family hold 54.5% of the company.
I found this statement quite refreshing.
Hi Graham, please can you cover Joules (LON:JOUL) today? They have now raised £30m through an equity placing and matched bank facilities announced today. Director involvement in the recent placing was encouraging. An analysis of where you think they are would be helpful
Morning - yes, I'm looking at Joules (LON:JOUL).
Cheers
G
I see that in Nexus Infrastructure (LON:NEXS) senior management are taking large cuts to their salary, including 100% by the CEO. Highly commendable (I hold.)
Morning Graham
I hope that you are well. Your sanguine approach to the current economic turmoil is commendable. Churchill's quote "Never let a good crisis go to waste" comes to mind.
On to small caps; the update from £FLO this morning reads quite well. The company is clearly in a difficult place but management is continuing with self help measures and cash flow seems to be holding and debt is coming down. The share price suggests that the company may well go under. I don't think so. Much will depend on the on length of the lock down and severity of the aftermath. An equity raise may well be on the cards, but at such a depressed share price? I continue to hold...foolish perhaps, and may add if offered a really silly price..
All the best
No Issues today with the ever superb and humerous Mr Contrarians posting time - everything is NOW. Perhaps the link to individual personal settings timezone has been been changed in the programming?
Inspiration Healthcare (LON:IHC) has also reported full year results today in case you want to look at it, Graham.
I'd be interested in Inspiration Healthcare (LON:IHC) too, please, finals look in line and the rating doesn't look too demanding with underlying profit growth above 20% and a confident outlook
Any chance of a look at Severfield (LON:SFR) if you get time Graham some fund managers think the Indian business is (was now with covid) worth the price of the entire company alone.
Thanks Andy
Hi Andy, I'll take a quick look at that one for you.
Best
Graham
My morning smallcap tweet: MBH bricking it again
Dialight (LON:DIA) Nexus Infrastructure (LON:NEXS) Titon Holdings (LON:TON) Flowtech Fluidpower (LON:FLO) Michelmersh Brick Holdings (LON:MBH) Severfield (LON:SFR) Aptitude Software (LON:APTD) Joules (LON:JOUL) Lidco (LON:LID) Billington Holdings (LON:BILN) Equals (LON:EQLS) RBG Holdings (LON:RBGP)
Dialight (DIA) Mexico plant closed pending review of application for an "essential business" order. Q1 in line until end March saw softening in Lighting. Bank talks to arrange additional liquidity and covenant headroom, should that be required. Co's expectations for H1 and FY have significantly reduced.
Nexus Infrastructure (NEXS) H1(March) in line with rev up 18%. Tamdown has furloughed 97% of its employees, TriConnex 74% aND eSmart Networks 53%. Cash at hand £19.6m. No guidance.
Titon (TON) limited scale production will re-start but orders fulfilled will be a small proportion of normal sales.
Flowtech Fluidpower (FLO) Q1(March) was in line until lockdown. Rev down 10%. Net debt £15.6m, facilty is £25m. "The work undertaken as part of our restructuring activities over the past twelve months is helping our [lockdown] planning enormously."
Michelmersh Brick (MBH) factories are reopening.
Severfield (SFR) some disruption to its operations. Order book £293m (1 Nov £323m). The level of tendering and pipeline activity for the Group remains good. No material impact of covid on FY(March) but FY21 will be hit. Cash headroom exceeds £50m.
Aptitude Software (APTD) home working has not lead to service disruption to clients. Net cash £31.2m. Recurring revenue level over 50%. Q1 rev and profit slightly ahead of mgmt expectations. Sales cycles are lengthening. CO comfortably profitable and cash generative under covid scenarios, although below earlier expectations. Will pay div.
Joules Group (JOUL) £15m increase to revolving credit facility, has sufficient liquidity headroom to manage a COVID downside scenario. "Customer traffic and demand to Joules.com has been running ahead of the Group's revised expectations."
Lidco Group (LID) Significant increased demand as a result of COVID. "Although no clinical studies have been conducted involving patients with COVID-19, clinical studies have demonstrated that the use of LiDCO's technology in the treatment of sepsis significantly improves outcomes and reduces mortality."
Billington (BILN) majority of construction sites open and customer projects continuing after some temporary interruptions. Some reduction in volumes of certain products and services but "well placed to deal with the uncertain future ahead."
Equals Group (EQLS) Q1(March) rev up 32%. Q2 indications are within median expectations on co's scenario modelling.
RBG Holdings (RBGP) Rosenblatt has seen no change in existing instructions with work proceeding as planned across all practice areas and has had new instructions due to financial restructuring and employment-related issues.
Lidco (LON:LID) Prelims
· Significant increased demand as a result of COVID-19 with 195 monitors sold to date, predominantly to the UK market, compared with 219 monitors sold in the whole of FY20
· Board expects that sales in the three months ending 30 April 2020 will significantly exceed total sales of £3.5m achieved in H1 FY20