Small Cap Value Report (Tue 21 July 2020) - JDG, TED, SDI, BIDS, AO., BMY, CTO

Good morning, it's Paul here with the SCVR for Tuesday.
The news coming out of Oxford University sounds very encouraging, with talk of a possible covid vaccine by the end of this year, if further trials are successful. Wouldn't it be wonderful if a vaccine is successful, and is given to the world by British scientists? Let's keep everything crossed to hope it works. I suppose we mustn't jump the gun, but this surely increases the probability that we should be thinking in terms of a bullish outlook for sectors that have been smashed up so badly, such as hospitality, travel, etc.. Providing companies have the balance sheet strength to survive into 2021, then some of these shares could be very lucrative from this point onwards. Hence I've closed my shorts, and am now thinking in terms of economic recovery, and maybe things even returning to normal next year? If a viable vaccine is imminent, then investors are likely to look through poor 2020 results. This is a big opportunity I think, to snap up some bargains.
Please see the header for the company announcements I'll be looking at today.
Estimated timings - we'll see how I get on.
Optibiotix Health (LON:OPTI)
The CEO reached out to me, with a slightly ill-tempered reply to my negative article about his company yesterday. Bizarrely, he accused me of lying, and having an agenda against Tom Winnifrith! (who I've had no contact with for several years). Complete nonsense of course, but there we go. Whereas if he were a regular reader here, he'd know that I just give my opinions on shares, warts and all. I'll have a look at that later, and formulate a response.
It's absolutely fine for companies to have a right of reply, especially if I've been critical of the company & its track record, as in this case. So once today's news is out of the way, I'll take a look at what he says & publish something about it. Or it may be tomorrow, depending on timings.
Six years after listing, and having generated little meaningful revenues (let alone profits), it's no wonder the heat is on, and he wants to shoot the messenger.
Gattaca (LON:GATC)
I've had another snotty email, from the PR to this staffing company, demanding a correction re its net debt. Again, I'm happy to follow up on that when time permits, and give their side of the story. She makes an interesting point about non-recourse invoice discounting being excluded from net debt under IFRS, so I'll look into that. I think the point is that investors don't have to slavishly follow IFRS. We can adjust the accounts any way we like, to suit out personal view of things - e.g. I always write off intangible assets, and add back capitalised development spend. Also I ignore lease-related debt. It boils down to personal preference. As far as I'm concerned, non-recourse invoice discounting is a debt facility, which would cause problems were it to be withdrawn. Therefore, in my eyes, regardless of what accounting standards say, it's debt.
.
Judges Scientific (LON:JDG)
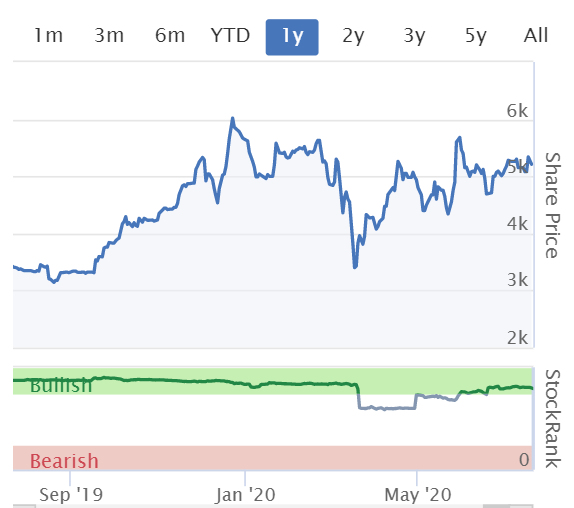
Share price: 4850p (down 7%)
No. shares: 6.27m
Market cap: £304.1m
The Directors of Judges Scientific (AIM: JDG), the group focused on acquiring and developing companies in the scientific instrument sector, provide the following update regarding the Group's trading performance for the six-month period ended 30 June 2020.
This group previously issued a cleverly worded profit warning, which I reported here on 20 May 2020. The house broker lowered forecast EPS by 30%, but nobody seemed to notice. That's encouraging I think, in that it seems to demonstrate that JDG has committed, long-term shareholders, who are not easily spooked.
Order intake - today it says this (which looks very similar to what was said on 20 May) -
The main adverse impact of COVID-19 has been, and continues to be, on order intake. Across the Group, Organic order intake for the 6 months to 30 June was down 17.3% compared to the same period in 2019, caused by the closure of universities, the cancellation of scientific conferences and our inability to travel....
In May, Organic order intake recovered, to an extent, from the trough of April and then progressed slowly in June.
The way I read that, conditions are not improving much.
It says the order book overall is satisfactory, at 10.8 weeks of budgeted revenue.
H1 sales - down 12%, which strikes me as a reasonable performance in a very turbulent environment.
The Group has operated profitably in each of the first six months of this year and generated positive operating cash-flow for the period. As a result, the Group has maintained a robust balance sheet with solid liquidity.
Again, that's similar to what it said in May.
Outlook - uncertain.
Valuation - it's looking expensive, as I noted last time. Forecast EPS is 151p this year, so the PER is 32 times. This seems to be pricing in a strong recovery in earnings next year. Forecast is 186p, dropping the 2021 PER to a still punchy 26 times.
My opinion - it's up to you to decide whether the premium valuation is worth it. I can see why this share justifies a toppy rating, because it has an excellent track record. Personally, it doesn't appeal to me, on valuation terms. I can remember buying this on a PER of 13 a few years ago. It's remarkable how PEs have expanded in the last couple of years. The big question is whether high PERs are the new normal, with interest rates seemingly permanently near-zero. Or whether we'll eventually get some reversion to the mean. Answers on a postcard please!
.
.
.
Ted Baker (LON:TED)
Share price: 77p (up 9%)
No. shares: 184.5m
Market cap: £142.1m
For the 11 week period from 3 May 2020 to 18 July 2020 ("the period")
This is a fashion brand, selling online, through stores, and wholesale.
If you recall, it was really struggling, even before covid closed its shops. It refinanced by selling off its London office freehold, and doing a deeply discounted placing. This has eliminated debt, and left it in a healthy net cash position;
Net cash as of July 11 was £56.7m, ahead of management expectations due to strong cash management.
It's vital to remember that Govt tax deferral schemes are artificially boosting many companies' cash positions. I think all companies should disclose how much they have deferred in taxes, otherwise it's highly misleading. Remember these back taxes have to be paid in early 2021, so if we're not told the amount, then we don't know what the real cash position actually is.
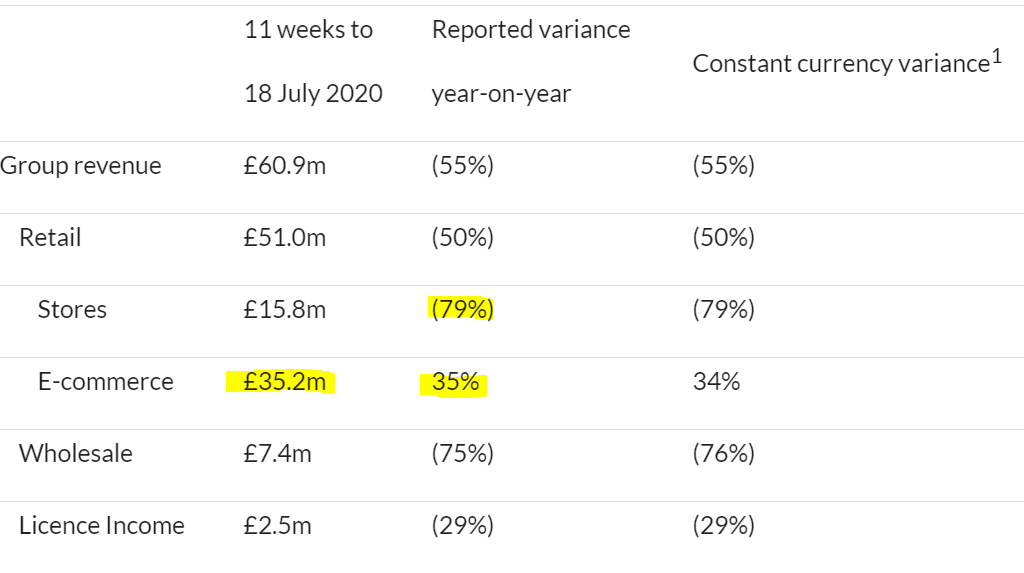
It says that trading is resilient, but that's not what these figures are saying to me;
.
.
I can understand the stores being well down on last year, because they've only recently re-opened. But is the +35% e-commerce sales growth a cause for celebration? I'm not particularly impressed, and have seen much higher growth from some other brands over this lockdown period.
Trading overall sounds as if it's better than expected;
Overall trading has been ahead of the base case scenario provided alongside the Preliminary Results announcement on 1 June 2020. The base case scenario was one of two ranges set at the time of the equity raise, along with the reasonable worst case scenario which was used for funding requirements.
I can't find any numbers forecasting profitability, so am in the dark somewhat. Ah, I've just found an update note on Research Tree, here we go;
Forecast EPS loss of (37.1p) this year FY 01/2021, a horrific loss before tax of £(66.5m)
Then a bounce back into profit of 6.1p EPS FY 01/2022, and 12.2p EPS FY 01/2023.
Current trading - from stores looks bad, and no doubt stores will be heavily loss-making at such greatly reduced revenues;
As at 18 July 2020, 95% of the store estate was open globally, and 75% of stores have been operational for the last four weeks. Like-for-like store sales were down 50% versus last year for the last four weeks of the trading period.
Wholesale and licensing are doing even worse;
Wholesale and licence revenue decreased 70% compared to 60% decline in the base case revenue scenario. The weaker performance reflects cautious ordering from store-based trustees since the early phase of the pandemic.
Guidance - I'm getting really sick of this. Companies should not be withholding guidance. This is wrong. They should be giving whatever information they have to investors, i.e. a range of possi ble outcomes - base case, upside, and downside cases.
In common with many other public companies, the Board will continue to withhold guidance for the current financial year ended 30 January 2021 given the unprecedented uncertainty around the severity and duration of the impact of Covid-19.
The rest of the announcement today sets out strategy and aspirations.
My opinion - the company has fixed its balance sheet in the short term. However, it's trading at a massive loss, which is likely to deplete that cash pile as this year progresses. Then there will be all those stretched creditors (e.g. VAT & payroll taxes) to catch up on in early 2021. It does have bank facilities available, but banks hate funding losses, so I wouldn't rely on those being available longer term, since there might be covenant breaches.
Retail turnarounds hardly ever work these days. It's all about being able to get out of the property leases, since rents are generally far too high to make stores viable these days. Therefore, I would only be interested in this share, if the company did a pre-pack administration to ditch all its lease liabilities. Another issue is what bad debts might occur in the wholesale receivables book?
On the upside, TED benefits from having Toscafund, and activist investor, holding just over 25% of the company. They might even bid for the whole company, which is what they did a few years ago to apparently remove a mistake from public view.
Is Ted Baker still a relevant brand? I don't know. When I was in Selfridges last year, looking for a leather bag, the Ted Baker offerings looked quite nice, but expensive. It's 50% off menswear is still about 3-4 times the price that I would be prepared to pay! But I'm probably not the target customer, judging by how thin the models are.
I categorise TED and SDRY in the same boat - rather tired brands that were seriously struggling (breakeven or loss-making) before covid struck. Therefore now heavily loss-making. Will they survive as standalone companies, or are these brands eventually destined to join BooHoo's (I'm long) growing stable of brands bought from an administrator?
Overall, I can't see any appeal to this share.
.
Sdi (LON:SDI)
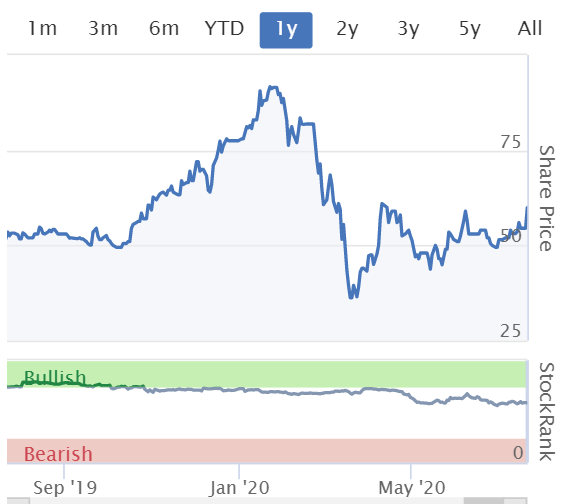
Share price: 59p (up 8%)
No. shares: 97.5m
Market cap: £57.5m
Investor presentation - this Friday, 24 July, at 4pm. Sign up link is here.
SDI Group plc, the AIM quoted Group focused on the design and manufacture of scientific and technology products for use in digital imaging and sensing and control applications, is pleased to announce its final audited results for the year ended 30 April 2020.
Revenues up 41% to £24.5m, but nearly all the growth is from 4 acquisitions. 4% organic revenues growth.
Adj diluted EPS up 23% to 3.43p - a PER of 17.2 - anything under 20 seems a bargain these days, comparatively. Bear in mind that covid would have only impacted about the last 6 weeks of FY 04/2020
Net debt seems fine, at £4.0m (ignores lease liabilities, which is fine by me). Note that gross bank debt is £9.4m, with £5.3m in offsetting cash. Note that most companies have a push to collect in cash for the year end date ("window-dressing") which is fine, it's not breaking any rules, but it's always worth bearing in mind that the balance sheet date might not be a typical position. I would much prefer if accounting standards required companies to publish the average daily net debt/cash, and a graph showing how this fluctuates throughout the year. That would give a much more meaningful view of reality. That is more a general point, than specific to SDI.
Outlook comments look mixed, but at last here's a company that gives investors some profit guidance;
SDI Group has started the new financial year in a strong financial position and a number of our companies have seen increased demand for medical products which are being used to address the COVID-19 challenges. Other companies within the Group face some uncertainty and a downturn in orders although all our manufacturing facilities remain in operation.
There are early signs of a return to normality in trading and overall SDI remains profitable and cash generative.
For the financial year ending 30 April 2021 the Group expects to report year on year revenue growth and profits at least in line with FY20.
That last bit is the most important. If we can anchor on profits being at least in line with FY 04/2020, then the valuation looks reasonable to me.
Acquisitions strategy sounds interesting. This reminds me a bit of Judges Scientific (LON:JDG) actually, with a similar strategy - acquiring niche companies and using new shares and the cashflows from them to repay debt fairly quickly. Note that SDI has increased its share count about 4 times in the last 6 years, which does somewhat cap the share price upside, if it keeps diluting shareholders to buy more companies. Over the same period, the share count at JDG has hardly changed, so actually they're not similar at all in that regard.
Balance sheet - not the best I've seen, so it gets an adequate rating from me. NAV is £20.1m, less intangibles of £21.65m, gives NTAV (the more conservative way of viewing a balance sheet) slightly negative, at £(1.55m). I wouldn't want to see the company raising more debt for acquisitions, personally. As the covid crisis has vividly demonstrated, nobody knows what the future holds, so having a buffer on the balance sheet (cash, and freehold property) is very valuable in times of crisis. Look at how many companies, large and small, overstretched their balance sheets on cheap debt, and then ended up being forced to raise equity at the worst time & price. Overly generous dividends are another policy that plenty of companies must now be regretting too.
Cashflow statement - very much as I was expecting. It's genuinely cash generative, and then spends that money, topped up with bank debt, on acquisitions.
Dividends - it's not paying any at the moment, which is fine for a company focused on growth.
My opinion - I've not ploughed through all the narrative, but it's there in the RNS for anyone interested.
My quick financial review has left me comfortable that this looks a decent investment proposition. Going forwards, it all depends on the quality of the acquisitions. With any acquisitive group, the danger is always that they buy something duff, and gear up too much. Providing those pitfalls can be avoided, then this share could do well. I'd like to see it get to a point where it can safely make acquisitions without issuing lots more equity - that's a key difference between SDI and JDG - where JDG has pulled off the remarkable feat of funding its acquisitions without dilution or excessive debt.
.
.
Bidstack (LON:BIDS)
Share price: 4.33p (up 1%)
No. shares: 387.4m
Market cap: £16.8m
Bidstack Group Plc (AIM: BIDS.L), the native in-game advertising group, is pleased to provide a trading update for the six months ended 30 June 2020.
I keep a vague eye on this speculative little share, because I like the concept - selling advertising space within computer games.
The good news - revenue in H1 2020 has gone up 10-fold!
The bad news - it was £27k last time, and is £270k this time. As the saying goes, 10 times f-all is still f-all!
Companies built on future expectations have to regularly stoke the fire with exciting narrative, and we get a decent helping of that today.
Cash looks fine for now, given the recent fundraising. Although the cash burn rates looks high, so this is probably only enough to last about a year or so;
The Company's significantly oversubscribed placing, the results of which were announced on 5 June 2020, raised gross proceeds of £5.7m for the Company leaving Bidstack in a healthy cash position to continue to pursue its business plans.
Outlook - I should hope so, that H2 revenues improve on the poor H1 revenues;
As announced on 28 May 2020, the Board continues to expect revenues for 2020 to be very significantly second half weighted and in line with market expectations for the year ending 31 December 2020.
My opinion - looks potentially interesting, if the company can increase sales further by a factor of about 100!
I'll watch from the sidelines for now. Very few speculative AIM shares actually deliver on their promoted potential. The usual route is a 45 degree downwards chart, with repeatedly lower fundraising prices, and massive dilution. Before eventually giving up, and turning the company into a shell to do something else similar, in order to utilise the tax losses.
.
Ao World (LON:AO.)
I despise value creation plans. To my mind they're cynical ways in which management want to be paid twice, or three times if you include existing share options and salary.
So I was ready to launch into a tirade against this, but actually it sounds quite good - focused on rewarding all employees, not just Directors (which are capped at a modest £20m!). The founder pledges his payout to a youth charity, a nice touch. His trademark gushing, slightly unhinged, style of expression comes through in this RNS, in particular this made me chuckle;
AO Founder and Chief Executive, John Roberts, said: "This is the AO Way of doing a Value Creation Plan. The decision to create an opportunity for every AO employee to receive a meaningful reward for the value they create is one that I'm proud to tell my mum about.
Good for him (and his Mum!) - I like a bit of quirkiness, not everyone has to be a boring grey suit!
The hurdle looks very high at 523p per share. Above that, 10% of the sustained share price gain is given to employees. I think shareholders would probably be very happy for the share price to get anywhere near that, since it looks too high currently at 164p, for a low margin box-shifting business.
... to realise the full benefit of the scheme, we would need to achieve a share price of at least £9.41 (equivalent to £4.5bn market cap) and that value must be maintained for at least two further years (March 2025 - March 2027).
My opinion - it's a nice idea actually, and I hope more companies come up with schemes to reward & lock in staff, as opposed to just Directors. In this case the hurdle looks unrealistically high to me. It then runs the risk of the scheme being ignored by staff, if they think it's unattainable. Then the hurdle would have to be lowered, leading potentially to reward for failure. Still, it's a nice idea for a business focused on customer service. Certainly that's needed, as in my sample size of 1, the delivery driver from AO who visited me, was a right grumpy git!
..
Bloomsbury Publishing (LON:BMY)
Share price: 224p (up 12%)
No. shares: 79.1m
Market cap: £177.2m
The market seems to like this, with the share up 12% today, so let's take a look. This company is a book publisher.
Bloomsbury announces its trading update for the four months ended 30 June 2020, ahead of the Company's Annual General Meeting ("AGM") at 12.00pm today.
Note the unusual 28/9 February financial year end.
This sounds good;
Bloomsbury experienced strong trading for the first four months of its financial year, ahead of the Board's expectations, with year-on-year sales growth of 18% during a period of unprecedented disruption caused by the coronavirus pandemic.
Our revenue and earnings are weighted towards the second-half, with sales of trade titles rising for Christmas and sales of academic titles being strongest at the beginning of the academic year in the Autumn.
More detail is given, with the stand-out items being 28% growth in consumer titles (helped by lockdown I imagine), and digital revenues up a vry impressive 63% (but unfortunately no absolute figures provided, so I I don't know how significant diigital is overall).
Liquidity - sounds fine;
At 30 June 2020, Bloomsbury held net cash of £35.5 million and in addition has an unsecured revolving facility with Lloyds Bank Plc of £8 million in the first half and an additional £4 million in the second half, totalling £12 million, to match Bloomsbury's cashflow cycle. With our strengthened liquidity, the Board believes that we have sufficient liquidity to weather the impact of the coronavirus pandemic and avoid damaging our business in the long-term.
Unsecured lending is great, as it demonstrates the bank is supremely relaxed, and sees no risk requiring security.
Outlook - there's more detail given, but the key part says;
Our good May and June performance in particular were unexpected, and historically demand for books has been resilient in times of economic downturns. However, our customers are unclear about what is to follow. Our outlook in the next eight months therefore remains uncertain as the pandemic continues.
Bloomsbury has a successful track record of acquisitions and we are considering opportunities in Academic publishing.
It did a fundraising in April, as by the sounds of it, the company was expecting conditions to be a lot worse that they have turned out.
My opinion - this looks an encouraging update. Hopefully divis should resume in future. This looks a nice steady company and it could put the cash pile to good use, if financially distressed acquisitions appear. So it gets a thumbs up from me. I've always liked the strong balance sheet here too.
(by the way, I'm writing this outside in strong sunlight on my laptop, so apologies for any typos, I'll edit it later)
.
Tclarke (LON:CTO)
93p (down 4%) - mkt cap £40m
TClarke plc ("the Group" or "TClarke"), the Building Services Group, announces its half year results for the six months ended 30th June 2020.
This company mainly does complicated electrical/computer fitting out for large buildings like office blocks, so the obvious worry is that work might partially dry up due to the work from home trend. On the other hand, public sector work may increase due to the Govt priority to increase infrastructure spending?
The order book looks healthy being up
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

107 comments
Here is the cnbc article I think Paul was referring to. It suggests people are now looking for cheaper alternatives. So one could argue people cancelling their expensive memberships may look for cheaper no contract alternatives. Pure gym and Gym (LON:GYM) could be a beneficiary of that https://www.cnbc.com/2020/07/2...
Re AO, I'd say a stroke of genius, what has this done, quite a few things actually :
1 - signaled to retail investors a share price target that could generate buying pressure on the stock, regardless of maybe more measured reasoning, it may get there, who knows.
2 - a lot of free publicity, eg air time on radio 4 this morning
3 - not cost the company a penny (yet)
4 - potentially incentives/retains its workforce, TBH time till tell on this
5 - gives AO a warm feeling of doing right by its staff
"The CEO reached out to me, with a slightly ill-tempered reply to my negative article about his company yesterday. Bizarrely, he accused me of lying, and having an agenda against Tom Winnifrith!"
Short indicator?
I expect Tom Winnifrith is not a friend of Pauls.
I'm pretty septical of most commentators and bloggers. It appears they are just as septical of each other.
BSV
I love the Freudian spelling mistake!
Without commenting too far, I think it is fair to say that Tom Winnifrith is Marmite double plus!
I know though that at times both Paul and Graham have said good things about Tom, not sure the reverse is true.
Re. Bloomsbury Publishing (LON:BMY) does anyone know:
a) What the gross margins for Digital revenue is, and/or
b) the investor relations contact email address? The website only appears to have phone numbers.
Ta
A
Bidstack is an interesting one. I hold a few shares, having been sucked in by some fervent ramping last year.
Reality then set in, and the shareprice tanked. I should be grateful, as it's one of the experiences that made me decide to overhaul my investment strategy to something more robust.
It could go either way with Bidstack. So far, they've developed the irritating habit of over-promising and under-delivering. This latest update is pretty much as expected. Revenues nowhere near enough to cover costs, but an improvement on last year.
The next update will be key. They have to start delivering on the promise. I'll keep some powder dry, because if they do start generating meaningful revenues, it could be a rapid ascent.
I hold a small position and really do want this to work! When I worked at an agency ten years ago I flagged up in-game advertising as a potential revenue generator. Bidstack (LON:BIDS) are putting the work in to make a lot of moving parts work seamlessly together, so I'm hoping they get this right and fly as you have said. Only other option is they run into financial problems and a big ad brand comes in, secures the IP at a cheap price.
Like Paul I think there are some sensible ideas baked into the £AO. Value Creation Plan, but the share price growth seems massively ambitious and unlikely to be achieved. AO is one of those companies whose services I've used and valued which led to look into them as a potential investment. All I can say is that it looks better to be a customer than a shareholder! Whilst the growth is solid, the margins are miserable, and the current valuation already looks high. The idea that this might rise a further 5x over the next 5 years seems hard to believe, but I've been wrong before, so what do I know! In it's current form it's a distribution business trading on razor thin margins. Any valuation or multiple should reflect this.
I like the business model, but not the valuation at either today's price or the aspiration set for the future. For me this is a shorting candidate, even at the current price...
re Covid - interesting and encouraging take on immunity and how long it might last from Dr John Campbell. For those who haven't come across him before, he's been following the course of this pandemic from the very early days. Of particular interest perhaps to those who've recovered (PS):-
https://www.youtube.com/watch?v=R3_wSU1JnTE
I think it is worth bearing in mind that SDI was in a poor position back in 2013 which triggered the first raise at a lowly level due to a previously aborted reverse takeover.
The second was also at executed at a low discounted price, but it did at least enable SDI to execute on the strategy, so I wouldn't have a problem with a small raise at current or higher levels.
Management has done a good job thus far, the acquisitions have been decent and importantly provide strong synergies which isn't always the case with Judges.
(That isn't a criticism just an observation).
The SDI board has also stated that it does not plan to embark on a large acquisition or overreach, rather, it is concentrating on smaller often niche players that throw off cash.
Happy holder and happy to continue with that.
On the subject of what companies do and don’t report, even though I have been investing for eight years, I am always amazed at the leeway companies on what figures they declare to the market.
I would not have thought it would be beyond the wit of FCA/BOE/Government to be more prescriptive on non sensitive information that is declared. To take Paul’s example how much of the cash on the balance sheet is not the companies.
Regards
Michael
It would be very helpful if companies were obliged to detail both revenue and profits in TSs, something that seems beyond the decency of many companies to provide. Generally, if its not pretty obvious that the numbers are strong, its just a sign of an unprincipled management team trying to keep the SP up until something favourable turns up... ...which is normally not the case anyway.
Panoply Holdings (LON:TPX) reported a record performance, CV19 seems to have really boosted their business.
For 2020 yr (end 31.3.20), revenue and EBITDA in line with expectations. Cash now £6.8m.
Looking forward to 2021, very positive: Q1 21,: Rev £10.1m (Q1 20: 6.3m), Adj EBITDA £1.7m (Q1 20: £0.5m). Organic revenue +10%. Contract wins in Q1: £14m. The Board believes the results reflect a structural change in public sector procurement. Momentum continuing into Q2 21. The Group expects revenue and adj EBITDA for 21 to be significantly above market expectations. (Albeit with a H2 weighting). Results 30th July 2020.
This morning's note from Progressive Equity Research includes an uplift in the forecasts for TPX for the next two years. YE2021 has EPS now showing at 4.9p and YE 2022 at 5.6p with PER reducing to 15.0 and 13.2 (up from YE2020 3.3p and 22.4). No staff have been furloughed.
Interview with the chief executive of Ten Entertainment (LON:TEG) here.
seems to talk sense. Shame he’s leaving the company at the end of the year!
Sthree (LON:STEM) presentation given to analysts yesterday, with Q&A, here. Mark Dorman, CEO & Alex Smith, CFO outline the half year, described as one of two quarters! A lot of coverag of CV-19, and how they are navigating the pandemic. Good coverage of financials and the group KPIs. Nicely embellishes yesterday's results statement, and gives an interesting insight to the recruitment sector across the STEM sectors, (Science, Tech, Engineering & Maths).
Separately, Mark Slater is the piworld guest on our webinar, this Friday 24th July, 1pm. Mark is Chairman and Chief Investment Officer at Slater Investments. Also, Mark did much of the research for his father's book, the Zulu Principle, focussed on the PEG ratio. We'll be discussing CV-19 markets, what Mark's been doing, what he thinks of short attacks, and much more. Plus, the opportunity to ask your question. Register here, for An Hour with Mark Slater.
Paul re the accounting. I would also adjust debt for invoice discounting. And so does anyone who wanted to lend to the company. Its a financing tool for companies that cant wait for invoices to settle and it costs quite a lot to do it.
It does show that the column is read by Financial PR companies who (seem to me) sometimes add a puffed up comment about the companies they cover in here. it would be nice, but expecting too much, for them to say so.
Thanks kgb.
I'm pretty robust in standing my ground when companies or their advisers complain to me about what I've written. If it's fair comment, or a genuine opinion, then it shouldn't be a problem. Equally, am more than happy to correct any factual mistakes. But some companies cannot seem to distinguish between facts, and opinions!
Usually most of the feedback I get is fine. Geoff Wilding of Victoria (LON:VCP) once said to me;
"Paul I may not always agree with what you write about us, but it's never boring!"
When I meet PRs, the conversation usually starts with me apologising for being rude about one of their clients. The usual reply is something like, don't worry about it, we agree with you! Or, "they deserved it!"
Most of the time it's quite fun slotting into the intersection between companies, the City, and private investors. Also I think that, if you dish it out (which I do) then you've got to have broad shoulders and take some criticism in return.
Regards, Paul.
Ted Baker (LON:TED) brand, this is an interesting survey and doesn't quite indicate a tired brand:
https://yougov.co.uk/topics/consumer/explore/brand/Ted_Baker
Thanks for the hard data - that's quite a useful website actually and some other interesting data there although I have always thought of Ted Baker (LON:TED) as more expensive mid-market rather than comparable to brands like Versace so I am not sure the comparisons are quite right. I do think Ted Baker (LON:TED) are better at adapting their styles and perform well across a range of products, whereas Superdry (LON:SDRY) on the other hand I think feels tired because it was all about Japanese writing and the high-collared coats which have gone a bit out of fashion. The YouGov data is less favourable about Superdry (LON:SDRY) mostly due to more negative opinion than Ted Baker (LON:TED) https://yougov.co.uk/ratings/c...
Worth noting Ted Baker (LON:TED) had a massive sale at the start of the pandemic which will have hit margins and profits - which is indicated here: 'Promotional activity has been elevated, but in line with peers, which has had some impact on Group gross margin as expected.'
The vast majority of Ted Baker sales are to Millennial women who want very nice quality business attire but not at Channel prices and smart outwear for events and I would say they are one of the best brands for it. Especially now that Karen Millen and LK Bennett have basically given up. Karen Millen has become Boohoo clothes since they bought it -not saying that is bad per say, but it has changed their market segment.
As a male, I don't buy much from Ted Baker other than their holdall bags but my wife does and when I'm normally working in the city in London, I see loads of women wearing their smarter dresses, coats (Ted Baker cashmere coats sold like crazy last year) and their shoes.
I bought shares in Ted Baker and sold, and then bought in again at the 75p placing because I do think it is a good brand in a market which is always needed and has lost some of its main competitors.
With people going back to the office, I think there will certainly be an increase in sales in this segment and Ted Baker (LON:TED) looks very cheap - even given the expected £30mio or so loss this year.
"When I was in Selfridges last year, looking for a leather bag, the Ted Baker offerings looked quite nice, but expensive. It's 50% off menswear is still about 3-4 times the price that I would be prepared to pay! But I'm probably not the target customer, judging by how thin the models are."
That sounds exactly like something I would say, lol ...!
Kape Technologies (LON:KAPE) the TU seems very reassuring and indicates they are on a low valuation. i'm not too familiar with company so a couple of questions please if anyone can help.
1 - think there is a shareholder loan of 40m. is there anything unusual about this loan - interest terms / warrants etc...?
2 - i think the ebitda guidance is the same as they gave with their final results in March, i.e. it doesn't seem that they have had a lockdown benefit, which seems surprising but i am wondering are they saving a little bit of good news until later n the year. thoughts welcome. many thanks.
disc: dont hold. type: downside risk adverse investor.
What are your thoughts on today's Kape Technologies trading update?
HiPaul - I know you dont normally cover Accsys Technologies (LON:AXS) - its still not making profits but its one of those coys worth watching and over the past months its beefed up the Board - today announcing another new appointment - Alex Wessels. Never heard of him before but his profile seems to me impressive and so intrigued he is interested to take on this new role - such a small company..... Any thoughts anyone..?
Hi bohenie,
re Accsys Technologies (LON:AXS), the new NED's background is European, not surprising since their main factory is in Belgium, and the larger part of sales is, and will continue to be, in Europe. Is a company with revenue around 90 million euro and growing fast all that "small"? To me it looks like just general beefing up of the board now that they have grown from being "jam tomorrow" to at least "jam post-COVID". I hold. Anyone got any other thoughts?
Accsys Technologies (LON:AXS) main product is a timber treatment that makes a low value pine into a premium harwood-like timber via a chemical process that is well known.
This makes a softwood into a sustainable source of architectural timber with a company guarantee of 50 years in normal usage and 25 years when immersed in water.
They have some big joint ventures which should materialise in the next few year, one in Hull, U.K. and some other early day projects in the U.S. and Asia.
I have used it in the manufacture of new sash windows as recommended by the joinery concerned.
I have followed the company for about the last 3 years in which time it has been "jam tomorrow"....I'm still watching.
John
In my previous life I owned a building and property company specialising in renovating old properties, Architects/designers always specified Accoya treated products. I hold a very small holding in Accsys the product is fantastic they can not match demand, various setback in upscaling production and capital intensive, maybe one day they will deliver the Jam!
Thanks for the input folks - I should have mentioned I have held this for some years - and one small correction - their main manufac base is Netherlands not Belgium and as has been pointed out - they are building a new factory in Hull - in conj with BP Ventures., which if I have understood correctly, uses a by-product of the BP facility based there, (bit like making marmite !) Yes, they have over the years suffered lots of delays and a dispute with a Far East 'partner' but I do get the impression that they are now on the right track - and they are Eco products so lots going for it..... The share register looks interesting too (thanks Stockopedia for this facility)......
Axs have lot of good credentials in carbon foot print area. I have been looking into the more practical sides of its use and comparisons with alternative timbers. I have known many architects and never once heard them mention Accoya and have never had it specified. Some claim it is as durable as teak and more stable than many hardwoods, less shrinkage or expansion. On the other hand it is still a soft wood and apparently more susceptible to damage from heavy use or traffic. I've always liked cedar it smells great and looks and ages beautifully and like Accoya it doesn't need treatment or a finish. It is comparable in price to many quality timbers. So not cheap. I can't say its the most naturally beautiful looking wood but would be interested to see how it ages left untreated to the elements. I can imagine it being most ideally suited to the construction of doors and windows for which there is obviously always going to be a huge market. Making windows and doors out of softwood can be a nightmare and not at all stable or durable in the long run. Cheapness not always being the best route in economy over a long period. Unfortunately I can't see this being of interest to major house builders as cheapness and lack of quality are indeed key ingredients to their criteria. I do remember when this came to market and rather bizarrely the then unadveturous Majedie Investment trust threw all caution to the wind and started investing in companies like this. Looking at their appalling investment record over the 20 years this might have been one of their slightly better investments but they have substantially reduced that investment which they seem to have the knack of doing just as a company is about to lift off. It takes a long time to get established in this industry. I would hope 15 years is long enough for this to appeal to the more discerning craft builders both in new builds on a wider scale and restorations where permissible. Very interested now but possibly glad I waited 15 years.
Simon - As I understand, the Accoya and Tri process changes softwood into very durable 'hardwood' and as such it needs virtually no treatment once installed - So it is used a lot in commercial applications - public bldgs where initial cost is not as important as savings in future maintenance.... See their website for examples.
With regard to the vaccine - the teams involved are doing amazing work and creating a solution in amazingly short timescales BUT on BBC R4 this morning a top Prof in the field said that they would NOT be able to do "Challenge" trials (ie trials where people are vaccinated then deliberately infected with CV19) as there is no effective treatment available. This will slow down the efficacy testing as they will have to rely on trials "in the field" and in many countries the infection rates are now very low so trials will be very slow and need large numbers of people. I do know the Oxford vaccine are going to be trialling in Brazil where the infection rates are still high currently.
Open Orphan (LON:ORPH) are gearing up to run human challenge studies for Covid-19 in their Whitechapel facility.
I would be amazed if the Chinese aren’t using “volunteer” prisoners to test their vaccines.
I thought that the Chinese had already said they were giving their vaccine to the military. I think that was a few weeks ago - not aware of any reports on how effective it has been.
Open Orphan try to keep up a constant newsflow, with frequent RNS's and investor presentations.
They have suggested COVID challenge trials, but nothing has been announced.
I'm certainly not an expert, but with approximately 5000 in the UK part of the phase 3 trial getting the Oxford vaccine, the numbers of these who will be exposed to the virus will probably be rather small. So to gather enough data, you would think they need either a challenge trial, or a much bigger phase 3B trial.
I know this is trialled in Brazil & South Africa as well, but wouldn't it make sense to increase sample sizes if a fast result is needed ?
Am very interested to hear what people who know something about this topic think.
they are testing 10000 in South Africa and Brazil now and plan another 10000 in the USA very shortly
Begbies Begbies Traynor (LON:BEG) results today, look a bit of a mixed bag though prospects are probably good. I don't really understand the huge difference between adjusted and basic EPS. Any help appreciated.
Adjusted basic EPS** (p)
5.7
4.8
Basic EPS (p)
0.7
2.0
Basically the adjusted figure ignores acquisition costs and amortisation of ‘goodwill’ paid on past acquisitions. Whether you agree with this approach or not, most companies do this although the list types of item in the ‘transaction costs’ in the notes is a bit longer than other companies have. ‘Deemed remuneration’ must be like earn out payments for employees who were former owners? There are some reconciliations in the report.
Sounds to me as if they're trying to have it both ways - stating a high book value,then reducing that and adjusting out the reduction. Why include the goodwill in the first place ?
Non-Standard Finance (LON:NSF)
Trading update ast Wednesday making some positive nosies about collections at "89% of the average level in January and February 2020" and "Lending in all three divisions is continuing to build using our revised scorecards and this is reducing the rate of decline in the overall loan book"
This has somewhat reduced my concerns they are liquidating their book faster than debt repayments thus ending up with no equity value. But it's still a high risk as debt covenants could be called in. Also NSF mentioned the equity raise again. I still puzzle over this as the share price is so low I don't see how they can raise a meaningful amount without massive dilution to force shareholders in.
Yesterday an RNS - HSBS has taken a 6.47% stake. At first I assumed this was a debt for equity swap but perhaps not as the last fund raise was not through them and RBS is their bank lender. So I'm not clear why HSBC are holding this.
Albeit this is an options play on either destruction or recovery. If they survive, NSF does throw off cash and competition is reduced with payday lenders out and Amigo down. If they survive then sub-prime usually does well on the other side of a recession.
Morning Paul,
If you have time, I would appreciate your views on what appears to be a very optimistic Trading Update from £ergo Ergomed.
The highlight for me is that they are successfully cross selling between their existing business and a recently acquired US business.
Regards,
Ricardo
Request seconded
Why don't you give us your thoughts on it instead of expecting Paul to do all the legwork? You'll likely find if you put more thoughts down other people will reply with their thoughts too :)
Obviously I can't promise they will but it usually works for me.
Morning Paul,
Very interesting about the contacts from Optibiotix Health (LON:OPTI) and £GATC. We absolutely prefer to hear your real opinions so keep it up!
Better grab the popcorn :)
I second that .... Pauls becoming the “Roy Keane” of Stocko and long may it continue.
(for those of us of a certain age) Roger Cook from The Cook Report springs to mind. They don't make them like they used to - proper journalism :).
Begbies Traynor (BEG) have released their final results today, would be great to hear your thoughts on this one!
Looking forward to Paul's comments in Sdi (LON:SDI)
What are your thoughts?
Good morning Paul and everyone.
Your optimism is good to hear but I am being much more cautious about prospects of a vaccine this year. There are well over 100 studies into a vaccine being conducted but none of them are predicting a vaccine this year, even though some have said it is 'possible' and the govt is forward buying hundreds of millions of doses.
I think it is much more likely there will be advances in methods of ICU treatments and drug combinations which could mitigate the effects of the disease until a vaccine is proved. This will certainly help lower the critical care rate but it will not remove the fear factor and save millions of jobs. One report suggests half a billion people globally being pushed into poverty. This is a terrible thought if true and will set the global economy back years and call a halt to the global expansion plans of many companies.
My feeling is that a reset switch has been flicked and it is far too early to judge how successful the reboot will be for many companies. To use myself as an example, I used to travel abroad about once every two months, eat out at least twice a month, visit cafes and go for weekends away. All that has stopped and I have no intention of going back to it until there is a vaccine. If I am typical of the older middle income type of person then I wouldn't be in a rush to by airlines, restaurants or luxury goods companies right now.
I am always optimistic. I think there will be a vaccine or at least a treatment that reduces the effects and number of deaths but how long would you wait to avoid travelling abroad, eating out, visiting cafes and going for weekends away? Without these things is it not a meaningless life? The young don't seem to care too much. Our large "village" was never so crowded as when the pubs reopened. I am told it was packed with young people practising no social distancing and hugging one another. We are at the other end of the spectrum and want to do all the things you mention and even go on our cruises again before it is too late. In fact, although I was not bothered by the restrictions for the first couple of months it is now coming to the point where I am getting quite angry about being tied down and am hoping we will be one of the first to be offered the vaccine once it has completed its next trials and is deemed to be reasonably safe. I know we can do some of these things now but the overall experience of staff wearing masks and the significant precautions are off-putting to an enjoyable experience. A vaccine even if not providing 100% certainty would make me more relaxed.
I don't personally think my life gets much meaning from my ability to be a consumer :)
I guess it depends on what you do with your life. Some people are happy to stay at home reading or gardening or even watching TV which I have never had much time for. Mine is based on hard work even at 75 advising a very large company and when not doing that going out to good restaurants at least twice a week, attending football and especially looking forward to our next cruise. Without the opportunity to do those things what is the point of having money and trying to make even more on shares?
On the other hand I've already been abroad, and my flight out from LCY was full. What we can say is that there will be a full spread of responses from individuals, and that those will vary over time. We can anticipate that age will be a significant factor so activities favoured by younger demographics will advance as rapidly as the law allows while the retired will be extremely cautious and behind regulations.
My observation on a vaccine is that one does not even need to work that well, it just needs to make a marginal improvement. It seems that only about 10% of those infected get any noticeable symptoms, so lets say rather than preventing the disease it just speeds up recovery by 25%. Asymptomatic cases shed for 1.5 days not 2 days, some people move from mild symptoms to no symptoms, some from serious to mild, from hospital to at home, from ICU to hospital bed etc. The herd gets much larger and the risk of death or complications reduced to a normal respiratory level. So long as that vaccine is quick and cheap to produce then many restrictions could be removed soon after immunisation was well under way. What we get left with is the results of the fiscal response and the increase in money supply and money circulation.
SDI (LON:SDI) have an investor meet presentation on friday
Zero chance I, or any of may family, will be taking any vaccine rushed through at such speed and bypassing so many testing protocols. And by all accounts, 25% of people in the UK think the same. Still, wish I'd held SNG....
Fair enough but I think you're in the minority who wouldn't want to take a vaccine. The rest of us are jumping at the chance!
That's very altruistic. Thanks!
If you are happy to sign a full disclaimer against any injury or death, there must be dozens of trials that would like to recruit you.
I'll sign up for the Oxford vaccine at the very first opportunity.
good luck with that. While you wait, maybe research what they put in many of these vaccines, including Mercury and other heavy metals, foetal RNA etc....And I won't mention the countless vax programmes which have caused widespread medical fallout. I'd rather risk the (now CDC acknowledged) very low fatality rate of COVID
This is one recent case where a vaccine did not work
https://en.wikipedia.org/wiki/Dengvaxia_controversy
Has a vaccine been produced for Respiratory Syncytial Virus (RSV), the answer is no
https://vk.ovg.ox.ac.uk/vk/rsv
I don't think you can say it didn't work - it's licensed in twenty countries and clearly works BUT it works better on those who have had previous exposure. As it stands there doesn't appear to be proof that the drug was responsible for the extra deaths mentioned in the wiki page but what was also clear that the net effect of people not inoculating for other diseases caused outbreaks including polio and measles.
As for mercury in vaccines. Thimerosal (a preservative that contained mercury) has not been used in the UK for over 10 years BUT even if it was used, it's a miniscule amount - the equivalent you'd get in a tin of tuna.
Please don't tell me we are getting anti bloody vaxxers on here too!!
Fair enough but I think you're in the minority who wouldn't want to take a vaccine.
Unless you live in America where the latest survey indicated only 49% would say yes - I don't like to call an entire nation stupid but it seems they do at least have a decent hardcore of non believers there - perhaps djokovic will now apply for us citizenship.
Vaccine damage
Please don't belittle the risk around vaccines. I watched my brother fight complications from the TB vaccine. Was spending two years in and out of hospital, having bone scraped from various bits of him to replace the bone that dissolved in his arm under the vaccine injection point a risk worth taking? Did those years of illness prevent his possible death from a disease that was still around (the mid 60s) where he was living? Who knows.
Admittedly, this was a rare side effect. It was also a provable side effect, but the extent and provability of damage are not always so obvious. Statistics are open to manipulation and the medical profession is not always scientific (i.e. the use of the scientific method to establish clear links between cause and effect), although such things have been improving quickly over decades. A working knowledge of medical history invites caution rather than an outright rejection of standard medical treatments. In the US, general trust in the medical profession is affected by a more obvious relationship between medical care and money. Trust is coloured by reports like this:
https://www.cnbc.com/2018/02/22/medical-errors-third-leading-cause-of-death-in-america.html
Vaccines have given us benefits, but there is a cost, and vaccine damage is not as rare as is assumed.
Would I be vaccinated against a dangerous disease that was prevalent in a place where I lived or visited? Yes, if the vaccine was deemed safe and effective. Would I have a COVID vaccination? I wouldn't be among the first to have it, but I am not in an obviously at-risk category (I'm Paul's vintage, with no health problems except a few extra pounds). I had the swine flu, and that wasn't a lot of fun, so maybe.
Do I think that most folk would be trying to get the vaccine as soon as possible? Yes, I do. That can be good for suffering companies, assuming that the debt that has accumulated is not too burdensome. For us, as consumers, it would be good to be able to go out into the world without the worry of COVID.
I think that laughing at the perceived non-rational rejection of certain vaccinations misses the point that many standard protocols in medicine may not be as safe or effective as they appear. If all objections to vaccines are deemed irrational, the impetus to improve safety and prove efficacy is much reduced.
https://www.gov.uk/vaccine-damage-payment/eligibility
https://www.hrsa.gov/vaccine-compensation/index.html
As it is now clear the people at risk of serious illness are overwhelmingly those with pre-existing health conditions, why would the healthy take the chance with a vaccine that is being rushed through?
I think many people have missed that the ONS has been publishing for some time the deaths with and without pre-existing health conditions and even in the older age groups the vast majority of deaths were in those already ill with something
On the one hand I agree that there is a tendency for some people to over emphasis the risk of catching covid-19. On the other hand, there is early research out there suggesting that people that have had the disease even asymptomatically may suffer lasting (permanent?) lung damage and also findings of damage to other organs. Until we know more about this it is hard to access the risk of virus vs vaccine.
As things stand though personally I would sway quite heavily in favour of being vaccinated; but each to their own.
Nick
That’s interesting to know. Please can you clarify. Which testing protocols have been bypassed?
I would also like to know about these bypassed testing protocols. If you have inside knowledge you are duty bound to report the Oxford trial to the FDA and EMA at a minimum.
Nick Tull
You have made extremely serious allegations that testing protocols have been by-passed.
Please respond to let us know what these are and the source for this information.
There is so much fake news and conspiracy theory scaremongering about vaccines that we need to know.
Why would you need to report it to foreign regulators? You surely mean the MHRA.
Good morning Paul, another request for Sdi (LON:SDI) and if you have time, Rps (LON:RPS) who announced their Q2 update today. Revenues down (£107m vs £130m prior year); debt significantly down from 3 months ago (£57.8m June 2020 vs £102.8 March 2020), £35m impairment charges (31m non cash); extra bank facilities undrawn, can't give guidance.
cheers
Francis
My morning smallcap tweet:
Ergomed (LON:ERGO) Ted Baker (LON:TED) Bidstack (LON:BIDS) Eleco (LON:ELCO) Bloomsbury Publishing (LON:BMY) Judges Scientific (LON:JDG) KRM22 (LON:KRM) Panoply Holdings (LON:TPX) Synairgen (LON:SNG) GSTechnologies (LON:GST) React (LON:REAT) Collagen Solutions (LON:COS) Kape Technologies (LON:KAPE), RPS (LON:RPS)
Ergomed (ERGO) guides H1(June) rev up 15%, order book up 22% since Jan. Expects FY EBITDA materially ahead of market expectations.
Ted Baker (TED) last 11 week rev down 55%, ahead of the base case lockdown scenario Net cash £56.7m, ahead of management expectations.
Bidstack (BIDS) guides H1(June) rev £0.275m. Co "confident that it is making material progress in its approach to building a strong foundation on which to grow and create value." Hmm.
Eleco (ELCO) has changed name from Elecosoft.
Bloomsbury (BMY) last 4 months rev up 18%, ahead of the Board's expectations. Lockdown boost IMO. No FY guidance.
Judges Scientific (JDG) guides H1(June) rev down 18% but orders down 17%. Blames closure of universities, the cancellation of scientific conferences and co's inability to travel. Organic order book 'satisfactory'. Co is in "a robust position to weather the impact of the pandemic."
KRM22 (KRM) guides H1(June) ARR (what is that?) £4m, excludes disputed contract with ARR of £0.3m. Confident of meeting FY management expectations.
Panoply (TPX) guides FY(Mar) rev up 49%, adj EBITDA in line with market expectations. Q1 rev up 60% and adj EBITDA £1.7m (0.5m). Guides FY significantly above market expectations.
Synairgen (SNG) clarifies that yesterday's impressive covid treatment trial result was a phase II.
GSTechnologies (GST) outline Singapore lockdown hit to subsidiary EMS Wiring Systems.
React (REAT) wins contracts worth c. £350k to rund for 5 weeks from Aug.
Collagen Solutions (COS) now has orders or contracted development milestones, together with revenue already recognised through the first three months of the financial year, worth c. £4.3m (108% of last FY rev).
Kape Technologies (KAPE) guides H1(June) in line. Integration of PIA has advanced ahead of management's projections. Confident of FY rev $120-$123m and adj EBITDA $35-$38m.
In line: RPS (LON:RPS)
KAPE smashed it. Glad I bought more stock before the news.
Second that
"Synairgen (SNG) clarifies that yesterday's impressive covid treatment trial result was a phase II."
Can you please tell us how many phases these treatments need before they go alive and the time they take.
Thanks in anticipation.
Phase I : small groups of people receive the trial vaccine
Phase II, the clinical study is expanded and vaccine is given to people who have characteristics (such as age and physical health) similar to those for whom the new vaccine is intended
Phase III, the vaccine is given to thousands of people and tested for efficacy and safety.
Many vaccines undergo Phase IV formal, ongoing studies after the vaccine is approved and licensed.
**********
The whole process takes years, even if measured from Phase II.
The media are igniting false hope by suggesting that a successful, rigourously approved vaccine will be widely available this Christmas.
https://www.cdc.gov/vaccines/basics/test-approve.html
Thank you, Howard, that's very interesting and it puts all the speculation into perspective. I will now go and read the link.
How wonderful is Stocko.
well the guy in charge of the project at Oxford University said it would probably be ready by end of the year . Speaking on CNN last night. Of course not ready for the public until maybe another 3 to 6 months after that as it takes that long to manufacture the 5 billion plus vaccines and distribute them.
well the guy in charge of the project at Oxford University said it would probably be ready by end of the year
And this is what Professor Sir John Bell, Regius Professor of Medicine at Oxford University told the House of Commons Health committee today:
"The reality is that this pathogen is here forever, it isn't going anywhere. Look at how much trouble they've had in eliminating, for example, polio, that eradication programme has been going on for 15 years and they're still not there.
"So this is going to come and go, and we're going to get winters where we get a lot of this virus back in action. The vaccine is unlikely to have a durable effect that'll last for a very long time, so we're going to have to have a continual cycle of vaccinations, and then more disease, and more vaccinations and more disease. "So I think the idea that we're going to eliminate it across the population, that's just not realistic".
Professor Sir Jeremy Farrar at the same committee was clear that "things will not be done by Christmas" and that we'll be living with the virus for decades.
Rather more positively, there's an article in the Guardian today about how the UK is leading the response for treatments for Covid-19:
https://www.theguardian.com/co...
timarr
well I prefer the opinion of the Professor leading the Oxford team . Of course I am an optimist
The Oxford University vaccine results are great news, but it is still early days. From the actual research:
The participants recruited in this study will be followed up for at least 1 year and further safety, tolerability, and immunogenicity (in addition to efficacy) results will be reported when data are available
https://www.thelancet.com/jour...
Clearly if the upcoming Phase 3 trial results are positive then there may be a choice ahead about whether to vaccinate high risk groups before we're 100% sure about its safety, but I wouldn't jump to conclusions about this being immediately available based on press reports. We also don't yet know if a vaccine can create long lasting immunity or quite how the T-cell response works.
There is lots of encouraging noise around, however - the study showing that an interferon beta nebuliser can significantly reduce severe infections is an indication of the type of therapeutic treatments that will become available long before a rigorously tested vaccine. As it stands, though, the winter is still likely to be difficult as respiratory infections absolutely love damp, cold conditions.
Beyond that, though, I'd say things look pretty hopeful.
timarr
I am always bearish on vaccine development, as discussed been in and around this industry since I left university. Take for example polio, a massive outbreak in 1916 New York and when the vaccine was eventually deployed in the early 50s there were numerous incidents, one being 'the cutter incident' of paralysis in the injected arm. Remember there are strains of C19. ok so the bulls will come out with "things have moved on since 1955" but as mentioned here a few times, from FT research:- normally of the hundreds of potential modern vaccines invented each year 10% make it to clinical trials and 2% get approved and get through trials. Total time on average from concept to approval = 10 years. With AstraZeneca having a PE ratio of something like 110 I would say it's worth shorting. It's a company laden with debt and smells of desperation born out of wider governmental economic destruction & desperation.
Pdiddy-
normally of the hundreds of potential modern vaccines invented each year 10% make it to clinical trials and 2% get approved and get through trials.
i think there well over 100 different trials up and running to a certain degree now so even by your own maths here that should "probably" be enough to find a solution (it may not be a 100% perfect solution to begin with anything that gives some resistence though is a start). the "it takes 10 years to get approved" issue isnt an issue if things are being fastracked and the 2 uk trials are proof that it can be done inside 12 months if nothing goes wrong. To me the main risk is that all the vaccines run into the same or similar issues that havent as yet been anticipated (ie covid maanges to mutate to avoid the chasers) - so no certainties but the bods who know their stuff seem reasonably optimistic here - i think one of the main comments i heard quite early on was that they did actually find it reasonably easy to find something that could "attach" itself (probably the wrong terminology used?) to this virus and that its was comparatively stable in some aspects which gave them hope it wouldnt be as difficult as some other viruses to come up with the potential solutions. They scientests would blow their own trumpets though wouldnt they if they need funding - so perhaps i could end up with egg on my face ref my hopes here.
AstraZeneca (LON:AZN)
With AstraZeneca having a PE ratio of something like 110
Stockopedia shows expected eps for 2020 of £4 and £5 for 2021 - i am not sure if forecasts have been suspended or not here - but if these numbers are real or can be acheived if any covid related issues subside the potential p/e may not be anythoing like 100 - £5 eps is pe * 25. I am not saying its a good investment if any increase in earnings is likely to be short lived but not sure its a complete headtheball case.
If anyone here invested in Immupharma (LON:IMM) after their great phase 2 results for treating Lupus, you'd have learned (the hard way) that phase 3 doesn't always work out... Ouch! Let's hope this one is a success :).
Another point of caution not mentioned above is that the "success" of the vaccine was in stimulating an immune response. But (a) we don't know how effective that will be in preventing the disease and (b) it was only tested in people aged under 55. Older people often respond less well to vaccines (produce much less immune response) and we know many of the issues around covid relate to older people.
I think the main point of optimisim is the number of different fronts on which progress is now being made and the variety of approaches being tried. Therapeutic drugs originally intended for totally different uses, that are already approved for use, are being shown (on limited testing) to be effective treatments. Never bet against human ingenuity!
Never bet against human ingenuity!
I don't, I fully expect that we'll be on top of this in 9 to 18 months. I just think the frantic seesawing of investors based on the latest PR is suboptimal. Science, especially medical science, takes time to be done safely. I'm about as far from an anti-vaxxer as you can get but there's no way I'll be accepting a fact tracked vaccine.
In all of this I'm reminded of my mother's story about how she suffered terribly from morning sickness while pregnant with me. She pleaded with her doctor for the latest wonder drug to relieve the symptoms but he, being thoroughly old school, wasn't willing to prescribe something he wasn't sure of for something he felt could be managed in other ways.
The drug, of course, was thalidomide.
timarr
Sorry timarr, I didn't mean to imply anything about you, I'd rambled off on to a more general point at that stage.
”I don't, I fully expect that we'll be on top of this in 9 to 18 months. I just think the frantic seesawing of investors based on the latest PR is suboptimal.”
I think you are right though I would have given a bigger spread of 9 to 36 months.
I think in this instant gratification world 24/7 news cycle that we now live many people have forgotten that things can take time and that simply willing for something to be over by Christmas doesn’t make it so.
Sounds like you were born the same time as me though I don’t think my other was offered thalidomide.
I think you are right though I would have given a bigger spread of 9 to 36 months.
For a vaccine, maybe. For therapeutic treatments it'll be quicker - we're already finding things that look like they reduce mortality and the length of hospital stays. Many of these treatments are well understood so they don't need the same amount of trials before they can be authorised for use. I'd take dexamethasone or remdesivir in a shot if needed.
This is why lockdown, masks, social distancing, etc are so important - every day takes us closer to getting effective treatments. To see people simply ignoring these measures because they're too self-important, selfish and impatient to wait a few months is disheartening in the extreme - but, frankly, given the confusing messages coming out of government it perhaps isn't too surprising.
"It'll be over by Christmas". Now, where have we heard that before?
timarr
Morning Paul
BEG released their final figures this morning. Revenue up but profit lower than I expected. Looks like they may have paid down some of their debt.?
Possibly a good outlook for 2021?
2020
2019
£m
£m
Revenue
70.5
60.1
Adjusted profit before tax*
9.2
7.0
Profit before tax
2.9
3.3
Adjusted basic EPS** (p)
5.7
4.8
Basic EPS (p)
0.7
2.0
Proposed total dividend (p)
2.8
2.6
Net debt
2.8
6.0
Tesla up another 10% last night, forbes thinks its the mother of short squeezes https://www.google.co.uk/amp/s/www.forbes.com/sites/danrunkevicius/2020/07/20/tesla-stock-may-be-rallying-for-this-absurd-reasonand-this-wont-end-well/amp/
At least thats one explanation of whats happening to the greatest company in the world.
Hoping Tesla price comes down so I can buy more stock! I'm a LTH, btw.
If you are you should listen to Bethany Mclean's podcasts on Solar City - which you unfortunately own - and Tesla. They will be spending $12bn Capex in the next three years. Good luck with it!
A love truth honour ????
"The greatest company in the world".
Have they finally got Wirecard's title. Good for them, it has been a long slog.
Seems that there is the prospect that they enter the S&P 500 forcing index funds to buy.
BOB seems to be subject to a takeover bid. If so, does anyone know what the terms of the offer are?
Assuming you mean Best Of The Best (LON:BOTB) see their June 17th announcement that they are reviewing their options as part of a formal sale process. I’ve not seen anything further.
A consequence of Best Of The Best (LON:BOTB) reviewing options including 'for sale' is that it repeatedly appears on the Takeover Panel's Disclosure Table RNS and that may have caused the question.
Morning Paul. Sdi (LON:SDI) gave their final results today. Some impressive numbers, though most of it seems to have come from acquisitions. Would be interested to know your thoughts on them
Revenue increased 41% to £24.5m (2019: £17.4m)
Revenue growth both organic (4%) and from acquisitions (36%)
Adjusted profit before tax* increased 44% to £4.3m (2019: £3.0m)
Reported profit before tax increased 54% to £3.3m (2019: £2.1m)
Thanks Martin, I'll review the figures from Sdi (LON:SDI) and report back later this morning.
morning, I was also going to ask about SDI, looks pretty good from what can I see.
regards
David
I like the SDI acquisition strategy. All their acquisitions contribute to profits. They acquire at 4-5X EBITDA multiples and the fact they are listed gives them an immediately higher multiple creating value. Great figures.
I had previously held Sdi (LON:SDI) but had sold at a loss earlier this year, I had been watching but had recently taken off the watch list, with my current sleep at night strategy, so missed the bounce in the last month which was typical of my old buy high sell low strategy.
I have a vague recollection of Paul's previous comments about debt and possible requirement for another equity raise later in the year, so the question is whether these results remove that risk?
I guess the big question for me is whether Sdi (LON:SDI) are moving to a longer term "shareholder growth" phase through the prudent use of positive cash flow to fund further acquisitions, or whether we are going to see continued issuance of new shares each time the bolt on?
Their latest acquisition was supported by HSBC by way of lending. This with retained profits bodes well for the future.