Small Cap Value Report (Tue 21 May 2024) - XPP, GNC

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Summaries
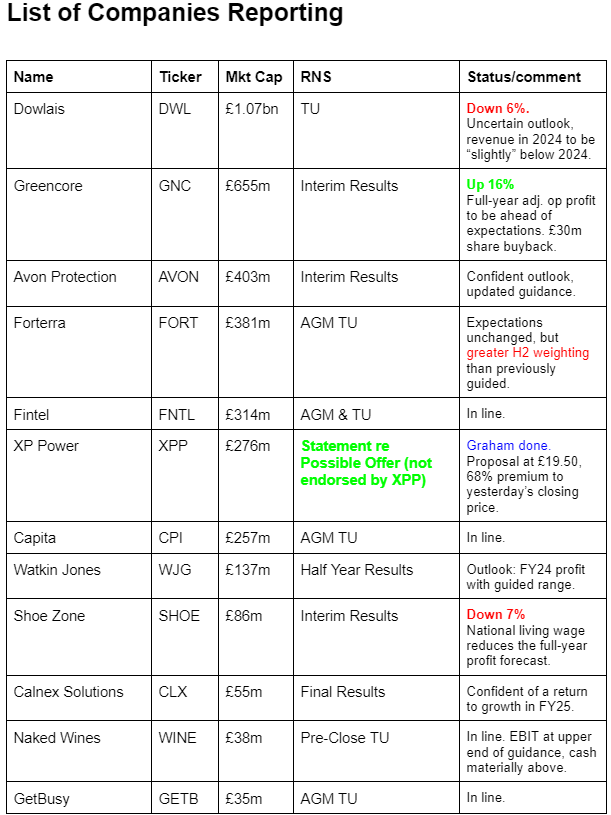
XP Power (LON:XPP) - up 47% to £17.07 (£404m) - Statement re Possible Offer - Graham - AMBER
Bombshell news as we learn that a US-based company wishes to take out XPP. However, three proposals were all rejected by the XPP board, so the potential buyer has decided to go public. I think it’s a generous and credible offer. With many different possible outcomes, I’d consider locking in some gains here.
Greencore (LON:GNC) - up 19% to 165.2p (£760m) - H1 FY24 Interim Results Statement - Graham - AMBER/GREEN
Excellent news from Greencore as profits for FY24 are trending to beat expectations. Broker EPS forecasts are raised by 5% and the company announces that a further £50m will be returned to shareholders, including at least £30m in new buybacks and the first dividend in several years.
Graham's Section
XP Power (LON:XPP)
Up 47% to £17.07 (£404m) - Statement re Possible Offer - Graham - AMBER
It’s an uncommon situation at XPP this morning as we do not yet have an announcement from XPP itself (as of 8am). Instead, we have an announcement from its suitor, the US-based Advanced Energy Industries ($AEIS).
AEIS is “a global leader in highly engineered, precision power conversion, measurement, and control solutions”.
It emerges that AEIS made three all-cash offers to buy XPP, all of which were rejected by the Board.
October 2023: £17 per share
November 2023: £18.50 per share
May 2024: £19.50 per share
It’s important to bear in mind that XPP increased its share count by 20% just after the November 2023 proposal, by raising new equity (covered by Paul here). It did this at £11.50 per share.
Now if I was AEIS, I’d be reluctant to pay £19.50 for shares that the company had just flogged off to investors at £11.50 six months previously. But they are clearly very interested in the acquisition.
It’s also worth reminding ourselves that XPP issued a serious profit warning in February (covered here).
The fact that these two events didn’t stop AEIS from putting in an even higher bid is remarkable to me.
A false market?
There is a point to be made here about the timing of the disclosure of offers to the stock market.
As things stand, market rules don’t require that all takeover proposals be made public in a timely manner, or at all. So XPP investors were in the dark about all of these AEIS offers until now.
Here I do have a slight difference of opinion with Paul. Personally, I don’t think that a company should have to disclose every proposal that it receives, if it would mean that every frivolous, non-binding suggestion had to be published to the stock market.
However, I do have a concern about XPP not disclosing the second offer it received from AEIS on November 5th 2023, at £18.50 per share. Around this time, the company was in covenant talks with its banks and appeared to be financially stressed (e.g. see our coverage in late October).
The very next day, after receiving that second offer from AEIS, XPP announced its funding plan to raise £44m in a placing and up to £1.5m in a retail offer, all priced at £11.50 per share.
Did any of XPP’s investors know that instead of buying more shares at £11.50, they could have potentially sold their existing shares for £18.50?
If they had known, is there a chance they might have preferred that option?
I don’t know what the solution is in terms of the rules, but perhaps XPP should have disclosed the second AEIS offer to its investors before announcing its fundraising.
Strategic rationale for the proposal
AEIS has a market cap of £3.1 billion (converted from USD) and is offering £468m for XPP’s equity: not a trivial amount for a company of its size.
AEIS says that the proposal would solve a range of problems.
XPP investors: they would exit at “a highly attractive valuation”, and no longer have to worry about the low liquidity of XPP’s shares.
XPP itself: the company would benefit from additional scale and resources, less cyclicality as part of a larger company, a more comprehensive product portfolio, broader R&D resources and technologies, etc.
AEIS: they have “over $1.0 billion of cash on hand and low-cost debt”. From their point of view:
Advanced Energy's proposed offer is consistent with the company's strategy to focus on precision power and deliver more value to customers in Industrial, Medical and Semiconductor applications. Advanced Energy's strategy is to grow revenue with highly engineered customized power conversion solutions. XP Power's engineering capabilities and product portfolio would complement Advanced Energy's existing technology and product base.
Graham’s view
We’ve followed XPP’s story with interest here at the SCVR, although it hasn’t been an easy one.
Most recently, in April, I took a neutral stance, arguing that the company “still appears troubled”. The order book was still falling, revenues were still falling, and net debt remained significant at £103m.
That net debt level was manageable to my eyes, but still not comfortable even after all the fundraising efforts.
What would I do? I’d probably take the £19.50 offer, if it turns into a firm offer.
XPP’s current problems may be temporary, but I think the 10-year chart tells the story. The company did pay out a useful dividend stream during this time, however in the end it took on too much financial risk given the cyclicality of demand for its products. I wouldn’t want to go through another ten years of this:
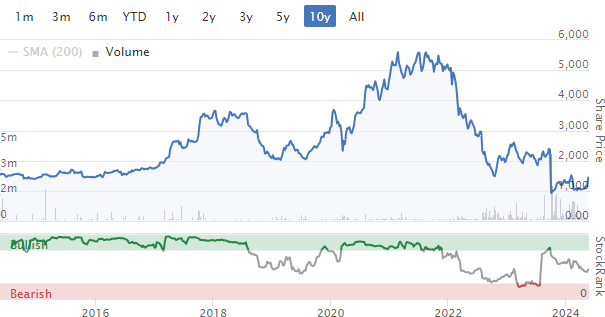
The latest potential offer from AEIS is at nearly 23x the consensus EPS forecast for 2025, with AEIS also taking on XPP’s debts. It’s a good deal, so personally I would take the money and run.
However, there is a strong chance that the XPP board will disagree. It could get complicated.
The current share price of about £17 reflects that it might not be straightforward for the deal to go ahead at £19.50. But it’s still a very nice price: 20x EPS for 2025.
Therefore, as with Keywords yesterday, I’d consider selling some XPP shares today, to lock in some value. But hopefully patient shareholders will ultimately get £19.50 or more.
Greencore (LON:GNC)
Up 19% to 165.2p (£760m) - H1 FY24 Interim Results Statement - Graham - AMBER/GREEN
We’ve not looked at this Irish convenience food manufacturer in the SCVR before but it made it onto Ed’s New Year NAPS for 2024.
Despite being headquartered in Ireland, its manufacturing and distribution sites are all in the UK (see here).
Today’s interim results show a surge in profitability, even though total revenue declined. Revenues fell due to a disposal and the “decision to exit a number of low margin contracts in FY23”.
(This is one of my favourite themes - when businesses transform their profitability simply by abandoning unprofitable activities. See IG Design and AO World.)
Some key bullet points from the announcement:
Volume growth ahead of the wider market, although LfL volume growth was only 0.5%.
ROIC up to 10.2%
Net debt to adj. EBITDA modest at 1.4x
FY24 adj. Operating profit to be £86-88m, ahead of current market expectations.
Shareholder returns: a new £30m buyback is announced, with a plan to return £50m in total to shareholders over the next 12 months. The first dividend since 2019 will be paid if trading continues as expected.
The company already made £50m of share buybacks between May 2022 and Feb 2024..
Balance sheet: new £350m five-year debt facility. Net debt (excluding leases) £244m.
Pension deficit: £22m. The pension scheme should be fully funded by September 2025. Contributions by Greencore of nearly £10m p.a. should cease then.
Outlook: a Greencore site in Sheffield has had excess capacity, but a new ready meals contract in Q4 (July-Sep) will improve its profitability and returns from FY25.
£6-7m is being spent in the current financial year on an IT transformation programme.
Graham’s view
It’s difficult for me to not take a positive view on this, considering that despite all of the good news, the valuation doesn't seem to have reached extraordinary levels.
As of last night, these were the value metrics:
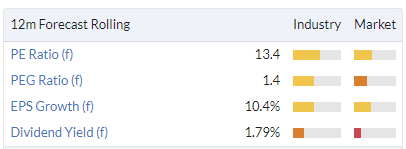
Latest EPS forecasts from Shore Capital (many thanks) suggest adj. EPS of 10.2p in the current financial year, putting the shares on a PER of 16x. Based on the 11.6p forecast for next year, the PER falls to 14x.
The StockRanks give it a big endorsement:
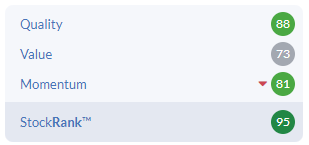
I’ll rein in my bullishness a little and take an AMBER/GREEN stance, since these earnings multiples are admittedly a little high for a food manufacturing business. And it's always slightly intimidating when you see a chart like this, combined with persistent share buybacks - is there a risk that the share price has got ahead of itself? It last reached these levels in 2021:
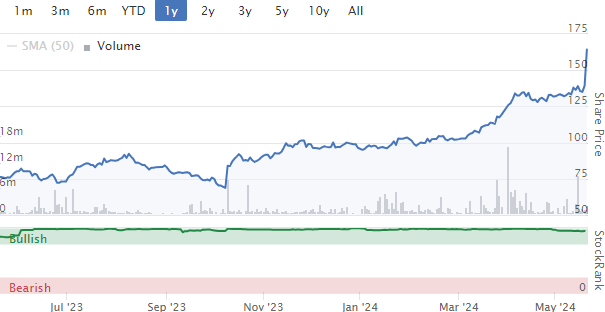
But there is a lot to like here. Greencore supplies both supermarkets and the foodservice sector so it offers broad-based consumer exposure - it’s not “just” food for consumption at home or “just” discretionary purchases on the go. And it’s thought to be the world’s largest sandwich maker!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
Polarean Imaging (LON:POLX) , cheeky £10 million placing announced after close as 1p per share, a discount of about 70% of the closing price today.
So glad I dumped that a while ago, kind of wish I had got out at £1 though.
dogs dinner that one.
To be fair I may buy a few if I can get around a penny, bottom feeding
Reminds me of Shield Therapeutics (LON:STX).Great fda approved product i would think as a layperson but burns money and can't get any real uptake at a sufficient rate to offset huge cash burn anyway.Not sure if it's just because taking on big pharma and their legions of embedded marketeers is impossible for a relatively tiny capitalised company going it alone or i'm missing something in the scientific detail and competitive landscape, which the company isn't mentioning to the layperson.Luckily i don't invest in these anymore.Enough red in the portfolio there.Although in the bull run they can do well.Naturally I wish i had invested in Renalytix (LON:RENX) on their huge bull run.Perhaps the strategy is to just ruthlessly sell when they achieve FDA approval always.
If paul or graham have time i would appreciate if you could pass comment on MicroSalt (LON:SALT)
was tipped at 70p a few weeks back in the shares magazine and has doubled in price since :(really regret not starting a position
You regret it because the price has doubled. A few weeks ago you saw a tip and decided not to buy which is usually the correct idea.
This is very sound advice.
Pass the salt
This was the previous comments, 19 February:
"MicroSalt (LON:SALT) - 114p (£49m) - Recent AIM float - Paul - AMBER
I review the AIM Admission Document below for this recent float, which has gone to an unusually large premium. Very much a jam tomorrow company, with negligible sales to date, but it's a nice story!"
XP Power (LON:XPP)
In the interest of balance the following small print is in the 6/11/23 RNS announcing the fundraise in which the directors participated:
My own disillusionment with the directors was crystallised in the profit warning at the beginning of August 2022 when I sold out at 2510p.
It's amazing isn't it: a board of directors, none of whom held a particularly large holding of shares at the time "has had no hesitation in unequivocally rejecting" the approaches. These, we now find out, were at a 50%+ premium to the then share price.
I'm sure all of this is absolutely fine and best corporate practice, and will tick all the ESG boxes. After all, the idea that a board, acting on behalf of shareholders, should even consider for a moment an offer at a substantial premium. Well, it is absurd isn't it? The best value for the shareholders is of course in paying the board nice salaries and giving them more share options, and that is so obvious that the shareholders don't even need to be asked.
But why would a company refuse to even consider selling shares to a purchaser for £18.50 and the next day offer to sell shares to anyone else for £11.50?
Mello at Chiswick
I would ordinarily attend both days but have another commitment this Wednesday, so if any one attends the presentation by the Property Franchise (LON:TPFG) who are there for the Wednesday only, I will happily reciprocate by providing feedback on Richard Staveley's presentation on Rockwood Strategic (LON:RKW)
Both are held in family ISAs.
All the best
I think there are at least two readers here who are doing very detailed reports on the visit to Mello2024 at Chiswick so you should get to read something on TPFG after the show.
Just a reminder to anyone who has not yet got their ticket readers can use Mark Simpson's discount code for half price tickets...It is Simpson50
Also
If you have never been to one of our two day conferences before then clearly you are missing a great opportunity to engage with management teams and also network with hundreds of likeminded investors so we are offering virgin tickets at just £30 for either of the days so that you can see what it is all about.....a big discount from £99.00 and if you do not agree having spent the day with us I will give you an annual pass to our virtual shows on top. I just want investors engaging with all these quality smaller companies. This offer is only if you have never attended before so please be fair to all those who pay much more.... Simply enter the code NEW2MELLO24 BUY NOW: https://www.tickettailor.com/events/melloeventslimited/1201351
Cheers David. Look forward to saying hello on the Thursday.
Today's news that Indonesia based zircon sands miner PYX Resources (LON:PYX) expects 80% energy cost reduction in energy costs after connecting to the grid was additional good news.
I bought a small position on last week's news that it had made it's first shipment, so moving towards the forecast first profit this year. Added today.
I am profoundly unhappy at 3 recent stories: the revaluation of wefox at Chrysalis Investments (LON:CHRY) and the bid action around XP Power (LON:XPP) and Keywords Studios (LON:KWS) and have written a substack piece about the same. Please read, share and comment. We need to have a market that feels fairer.
https://open.substack.com/pub/...
Wholeheartedly agree with the sentiments in your substack. How can it be right for a company (in this case XP Power (LON:XPP) ) not to disclose material and credible information about a takeover offer in a timely manner.
Non disclosure creates a false market and especially disadvantages smaller investors.
If rapid disclosure of possible takeover approaches (and equity fundraises) was implemented, the markets would soon adapt. For example discounting that many approaches don't progress to a bid, or that equity fundraises might justify a fall in share price.
Why can't we have that level of transparency! Much better than the acres of ESG horse manure that uslessly clutters listed company reports.
Nice read.Finally we all know why XP Power (LON:XPP) was a distinct anomaly and could raise equity at a lovely premium to recent profit warning lows when everyone else was needing to pretty much discount at an already discounted market cap.It all comes out in the wash eventually.Seems rather like a substantial portion of the non-retail market might have guessed at one point??What does surprise me is Sky News didn't seem to.
Greencore (LON:GNC) never been covered on SCVR?
It is a low margin business, though.
Greencore (LON:GNC) Cockney Rebel was waxing lyrical about Greencore several weeks ago. Seems he was right to.
Indeed, great stuff from GNC! Piece up on it now.
Although he sold down much of his position in the last week or two?
Wowser! Fidelity virtually double their stake in IG Design (LON:IGR) to 10%
https://newsfile.refinitiv.com...
12mth fcst p/e of 11.4 and a peg of 0.3!
StockRank 96 with strong momentum.
I was amused to see that, having soared some 17% yesterday and up 30% in the last months, Stocko’s algorithm has changed Kainos (LON:KNOS) from neutral to fallen star.
Kainos (LON:KNOS) but isn't that the value of Stocko? While qualitative assessment is taking Kainos higher, a purely quantitative approach, unencumbered by any emotions, is giving a different result. That's why I love Stocko anyway!
Absolutely loving the detail of when the offers were made/how much etc. for XP Power (LON:XPP).
So for those lucky enough to be able to go to Mello, a cracking question for Christopher Mills would be to ask straight if Harwood knew of the offers before Odyssean Investment Trust (LON:OIT) subscribed to the placing in November. Maybe other funds in the Harwood stable also subscribed but that's the one that jumps out at me first.
I felt like a bit of a lone voice yesterday challenging the insider buying during the bid period for Keywords Studios (LON:KWS). Probably my point was badly made, and I can see why technically you can argue there was no abuse, I just knew I'd have been fuming if I'd have been selling while an insider was buying during that period.
However for anyone subscribing to the XP Power (LON:XPP) raise in November with that insider knowledge, I'm really struggling to see why technically there is no abuse.
Edit: to qualify my point, the knowledge the market was I think missing was an offer at a specific price/substantial premium to the then current price from a credible buyer.
Keywords Studios (LON:KWS)
M48
I felt like a bit of a lone voice yesterday challenging the insider buying during the bid period for Keywords Studios (LON:KWS). Probably my point was badly made, and I can see why technically you can argue there was no abuse, I just knew I'd have been fuming if I'd have been selling while an insider was buying during that period.
If you were told this was a prior to bid(s) pre planned future set of buys would that change your mind?
for example Don Roberts buy in may has the following relevant note - so i wouldnt presume he has taken advantage of inside knwledge here like you seem to be saying he did
Market purchase of ordinary shares as a personal investment, pursuant to the Investment Programme.
Any comments on Watkin Jones's (LON:WJG) earning call? it looks in line but share is giving up some of the recent gain it made.
WJG (I hold) suspension of divi I suspect
Watkin Jones (LON:WJG) RNS states
"Continuing the approach adopted at the FY23 year end, the Board is prioritising the maintenance of financial flexibility during this period of market disruption and consequently is not declaring an interim dividend; the Board will keep this approach under review."
Positive is that the building safety works seem to be within the provision
"We continue to focus on the delivery of our building safety rectification obligations and have completed works on three buildings in the period with cash spend in line with expectations."
Negative is that, other than a slight improvement in the build to rent segment, margins were lower in the other three.
I hold.
If inflation comes in lower than expected at 7am tomorrow morning , a rate cut in June looks nailed on . Which UK junk companies will rally the hardest ? My personal favourites
Eurocell (LON:ECEL)
Mission (LON:TMG)
Liontrust Asset Management (LON:LIO)
Cavendish Financial (LON:CAV)
Saga (LON:SAGA)
Inflation in the media is based on annual cpi over a 12 month period. The figure for april 2023 was 1.2% (works out over 12% annually) - the figure for april 2024 will definitely be lower than this hence the reported cpi figure will drop
Eurocell (LON:ECEL)
i thought this company has net cash - if thats the case whats the direct benefit of lower rates other than perhaps enhanced consumer spending?
Presumably Jesse is expecting the multiplier effect of a rate cut on the housing market?
Graham, XP Power (LON:XPP) Have just RNS’d to announced they have rejected the latest bid.
Thanks Jeremy! G
XP Power (LON:XPP) - great piece on XPP Graham.
Cheers Peter!
Looks like another busy day on SCVR and looking forward to seeing some of the write ups.
If you have time it would be good to see your thoughts on Dowlais (LONDowlais (LON:DWL. It looks like a mildish profit warning to me but do you think it is a good recovery play?
Many thanks for your excellemt daily reports, very much enjoy.
Dowlais (LON:DWL) I had a very quick look at this over the weekend as a few respected investors I follow have mentioned this. Certainly looks cheap but perhaps less so on an EV basis when factoring in both the debt and the pension deficit. Also, I generally avoid ex-private equity companies (I would class Melrose as private equity in the way they operate) - nevertheless I do want to take a closer look and would be interested in others thoughts as they seem to be genuine market leaders. Also worth mentioning that there has been some director buying and the company is also buying back its shares.
I sold my Dowlais (LON:DWL) this morning. The statement read poorly in my view, and gave little confidence in forecasts. Destined to remain (ostensibly) cheap for a while longer I fear.
Shoe Zone (LON:SHOE) In freefall over the past few months, 2 mild profit warnings and today maintain the divi, increased EPS, but slight miss on full year profit forecast, blamed on higher living wage and freight costs (which seem reasonable). I'm a bit annoyed given I bought at £0.50 and could have sold at £2.75; however, kept it for the divi which worked out at circa 26%.
Given that the divis are being kept and also the owners are heavily incentivised, I will be looking to top up today I think as this now does look oversold.
Shoe Zone (LON:SHOE) Apparently the Houthi hijack problem and some other issues caused an unexpected spike up in freight rates, but the feeling is that there is an oversupply of capacity about to hit the market so freight rates trajectory should shortly be downwards. This was info I gleaned from a podcast about the shipping industry.
Found the opposite last week
Freight rates up from to 2k to 3k for a 20 footer
No reason for the raise apart from “What are you going to do about it “
Viz - Shoe Zone (LON:SHOE) has not had 2 mild profit warnings. It has had 1. As per the broker the £13.8m PBT (down from £15.3m) was in the previous trading update and so broker forecasts have stayed the same today. You could see people who hadn’t read the statement properly bailing first thing only for more canny investors buying back as it dipped.
Most of the £1.3m downgrade is from one offs that should reverse - only £0.5m is persistent (as min wage inflation) so I see normalised as around £14.8m pbt. That puts this stock on a slightly bizarre PER of 7 ish given its net cash position and dividends of 5%+
Fair point David, felt like a 2nd warning, perhaps the broker could have phrased it better.
Yes - Viz
Communication not great I agree - I think Shoe Zone (LON:SHOE) management were trying to be genuine and point out that they had, during H1, downgraded expectations for the 3 reasons provided. Unfortunately they failed to mention that this downgrade had already been incorporated into broker forecasts at the time of the trading update. So trading now in line with previous expectations but lower than forecast at full year by about 8%.
I find too many investors either don’t bother with access to research (and in my view they should) and/or don’t read results statements properly before reaching for the buy/sell button. If you are a holder of the stock you should know the broker forecast (it is on Research Tree) and correlate that back to the numbers in the statement.
Instead several investors clearly read downgrade commentary assumed a mild profit warning and bailed. One suspects with that kind of lax attitude to reading financial statements they also probably don’t make much money over time!
Dowlais (LON:DWL)
A FTSE 250 constituent.
AGM statement; broadly in line, which means a small miss on current consensus due to weakness in fully electric vehicles (BEV -battery electric vehicles). Second half weighting reiterated. Revenue decline of 6.6% including £90m FX headwind. On the positive side operating margins increased by 30 basis points to 6.1%.
Margin expansion and increased free cash flow expected over the full year.
Difficult call! The shares remain absolutely unloved and very cheap, perhaps in the short term rightly so, but whatever one thinks about EVs the move towards electrification is inexorable. The company is a global leader in its space. I am not looking to double my money over 12 months, but can I remain sufficiently patient or could I better deploy the money elsewhere?
re Capita (LON:CPI) (I sold) report inline but a headline grabbing -9% Revenue in the first 4 months doesn't do much to help. To be honest I could argue it looks ok from a contract win rate perspective and they took all the bad news by dumping enough cost into the exceptional line at the year end. However I told myself Id give them one more statement, and this isnt cutting it. The capital markets day will be fine, with positive margin chat and long term stable growth. Always easy to cut a starter position so Ive moved on.... and will wait for some better news from them.
Excellent interims from Greencore (LON:GNC) this morning. Not a sector that I would usually get involved with (supplying retailers) but they seem to be making some sensible decisions and it appears to be paying off. Exiting low margin business and seeing turnover reduce must be painful, but it's transforming the bottom line. Outperforming current estimates, buying back shares and reinstating a dividend. Q V and M ranks all good and an overall stock rank of 95.
Begbies Traynor (LON:BEG) - Update extends long record of growth (link to research: https://www.equitydevelopment....)
A positive FY24 update reiterates the inherent reliability of its business. Both revenues (up 12% at c £136m) and EBITDA are expected to come in ahead of market expectations, adj. PBT in line. The latter reflects relatively subdued corporate finance M&A volumes and expenses related to investment in its teams and IT support.
According to the update both divisions grew materially y-o-y on the back of acquisitions and organic growth. Business recovery and advisory was c 7% up, property advisory and transactional services by c 25%. The latter saw all its core disciplines - valuation, asset sales and consultancy - pick up pace. The c 13% expected revenue growth by business recovery reflects higher activity levels across all case sizes and that operation is well placed to capitalise on market growth.
The four acquisitions completed in FY24 added c £5m to FY24 revenues (£9m+ pa on an ongoing, pro-forma basis), and built insolvency and property advisory operational capacity and geographical profile. Their integration is progressing well and all trade in line with expectations.
We expect more acquisition led and organic growth which has driven the last 3 years, with BEG to add capacity, geographical reach, and market share in its core disciplines. The rating of BEG shares appears to have lagged events and we retain our 175p/share fair value.
A very much of a "meh" update IMO from Begbies Traynor (LON:BEG) . Organic growth seems rather pedestrian, compared to Frp Advisory (LON:FRP) .
Would have preferred if they had cleanly broken out a set of like-for-like numbers, stripping out the acquisitions. But now have to try to work out a split of the acquisition (+£5m cumulative in FY23) across the two divisions... IMO when things are omitted which could have been easily put in, likely because the numbers/facts don't tell a good story...
I've been holding Begbies for several years now, probably coming up to 5. I'm probably the least enthusiastic I've ever been after reading these results...
I wrote a long post on Begbies in early April when I topped up around 107p. My estimate for the FY Apr24 EPS was 10p (£21m PBT) and it looks like it has come in at that, maybe a bit higher. I posited that this could go back to 150p share price (15x historic PE) if there was a good solid outlook statement of growth in both insolvencies and property services for the year ahead.
I don't think today's update really makes a convincing case for that growth (unless they do some further meaningful acquisitions). I think this might settle around 12-13x PE, which would be back to around the 120-130p share price in the next few weeks.
(I hold in the Boon Fund)
Not sure what to make of the Avon Protection (LON:AVON) update. Looks good on the surface. Are they upgrading forecasts for the year with this statement?
Confident in the outlook for H2, issuing updated FY 2024 guidance:
· Revenue growth c.10%
· Adjusted operating profit margin 10%
· Transformation investment c.$15m
· Cash conversion over 100%
· Net debt: EBITDA <1.5x, new $137m financing facility successfully agreed
I hope Avon Protection (LON:AVON) will get covered today
They are saying their previous predictions for rev were high single digit and they have delivered 10% increases. Equally previously predicted adj profit margin approaching 10%, they have delivered 10%. So marginally higher in both cases or top end of however you define their predictions.
Slightly more upbeat RNS from Naked Wines (LON:WINE) this morning. At £20m of net cash, you're getting the business (£290m of revenue, big inventory to unwind) for £19m. That seems cheap
Time to fill your boots? Liontrust Asset Management (LON:LIO) , Premier Miton (LON:PMI) , Jupiter Fund Management (LON:JUP)
British stocks represent a golden buying opportunity, HSBC has said.
The investment bank has told clients to buy UK-listed stocks, arguing that downward pressure on share prices from pension funds selling almost £2 trillion of assets has ended.
https://www.telegraph.co.uk/bu...
eParo, thanks for posting this link. Liontrust Asset Management (LON:LIO) for me out of those three and Stocko's compare tool seems to agree.
I personally think Premier Miton (LON:PMI) looks a better bet than Liontrust Asset Management (LON:LIO) - LIO still seeing pretty heavy outflows at last update while PMI only a marginal outflow. Fund performance also looks slightly better at PMI, with many of LIO's bigger funds still struggling a bit.
Hi Bouden54. Premier Miton (LON:PMI) up 4.96% today, Liontrust Asset Management (LON:LIO) only up 4.64%. You win round one lol. I'm off to research PMI a bit further.
The brokers also look promising in this environment, with companies like Cavendish Financial (LON:CAV), which I hold, rising strongly off the back of IPO speculation but still trading far, far below previous IPO peak seasons. (I know Cavendish merged but essentially the share count doubled along with revenue & profits so previous share price peaks should be a good guide as to what's achievable here).
My morning smallcap tweet: Producing a worth certificate
XP Power (LON:XPP) Cirata (LON:CRTA) Judges Scientific (LON:JDG) Gore Street Energy Storage Fund (LON:GSF) Begbies Traynor (LON:BEG) Shoe Zone (LON:SHOE) Comptoir (LON:COM), Works co uk (LON:WRKS), Getbusy (LON:GETB), Fintel (LON:FNTL), Forterra (LON:FORT), Epwin (LON:EPWN), Naked Wines (LON:WINE), Capita (LON:CPI), Watkin Jones (LON:WJG), Diaceutics (LON:DXRX)
◄XP Power (XPP)► gets hostile bid at 1950p. [SP=1164 Cap=276m]
◄Cirata (CRTA)► wins $592k three year contract renewal. [SP=61 Cap=70m]
◄Judges Scientific (JDG)► AGM stmt - trading subdued but "H2 looks more promising which would result in a performance that is second half weighted and lead to a full year result in line with market expectations". F/C is £34m pretax and adj EPS 384.6p. Also "Next Geotek contract is now in negotiation, and specifies an expedition starting at the very end of 2024, implying no recognisable revenue in the current financial year." [SP=11700 Cap=777m]
◄Gore Street Energy Storage Fund (GSF)► guides FY-Mar rev up 5%, EBITDA up 2% and estimated average revenue of £15.1 per MW/hr, down 1%. In line? Says 'strong results'. GB weak. [SP=65.3 Cap=330m]. I hold.
◄Begbies Traynor (BEG)► guides FY-Apr rev up c.12% and adj EBITDA up c.9% to c.£29m, ahead of market expectations of £27.7m-£28.4m. [SP=105 Cap=167m]
◄Shoe Zone (SHOE)► H1-Mar rev up 1.5%, adj pretax in line. FY pretax F/C was £15.2m "which has been revised down to £13.8m". Blames higher National Living Wage rise, container rates and store dilapidations. [SP=185.23 Cap=86m]
◄Comptoir (COM)► FY -Dec. Outlook confident. [SP=6.99 Cap=9m]
In line: WRKS, GETB, FNTL, FORT, EPWN, WINE, CPI, WJG, DXRX
XP Power (LON:XPP) another one goes! Plenty of rebound trades on this one over the past two years but I seem only to have caught the falls!!
XP Power (LON:XPP) "another one goes" Has it gone or has the XPP board rejected the offers/hostile bids?
XP Board have rejected three bids, so bidder (Advance Energy Industries) have gone public. Will be interesting to see if this flushes out other bidders. I hold XP - has not been great to say the least.
As someone who has never held XPP I am uncomfortable with multiple bids at significant premiums being rejected by the board out of hand, without being announced. It doesn’t seem right. Board members take a nice salary, and so may be happy to wait years for the market to “fairly” value a company. But shareholders don’t have the luxury of getting paid six figures a year to wait.
Even worse, like at Keywords Studios KWS, the chairman has been filling his boots with the stock while no announcement of the approaches!!!
Yes, though at XPP, if online comments are correct, the directors all participated in a placing at a price miles below an offer they had received.
Keywords Studios (LON:KWS)
EdmondJ
Even worse, like at Keywords Studios KWS, the chairman has been filling his boots with the stock while no announcement of the approaches!!!
do you have any evidence these buys were not pre planned event that he did yonks ago and has to stick now on basis that it was all agreed back then when there were no bid approaches. Its easy to throw mud - but you should probably not do so if you are in danger of being factually wrong or misleading ref his intent - ie if it was mechanical pre setup decision to make these buys before approach he hasnt make any active decision to fill his boots whatsoever.
i dont know what the facts are here i must admit - i am simply happy the bid is here at decemt level so to me its great job done by the board - great chance now for anyone to exit who has slightest uncertainty as to whether this deal will complete.
As with my comment on yesterday's SCVR. It appears the chairman buys ~£50k each quarter. Assuming it was a proposed regular purchase, what do you propose he does when a bid comes in? Stops buying (which in itself may send another, conflicting message)?
I'm just curious to what you think he should have done, rather than ranting about the fact he continued buying shares which incentivized him to get a better price.
It's clearly not a perfect situation, but the only clear solution to this scenario is all directors involved don't own any equity, which has other weaknesses. Or do they announce the first bid and risk not maximising the value for shareholders?
You announce bids as and when they come in. Simple as that. You can say that you disagree with them and have rejected them. But I am extremely uncomfortable with a director buying shares at a time he knows that there is a bidder lurking likely to bid more than double the current share price.
That was rather the point of my substack: I am sure that he has followed the rules. But to most people it feels wrong. And if the effect of compliance, with its huge cost, is to make people think that the system is rotten, then that is something that should worry everyone.
(Admittedly just one party albeit has raised possible offer terms, three or four times.)
XP Power (LON:XPP) did a share placing in november 23 knowing full well they had received higher bid offer(s) and not telling investors that not right.
XP Power (LON:XPP) It will be interesting to see how the corporate broker feels about that. Plus how will the FCA react? No wonder the directors subscribed for shares in the placing. with a cash bid on the table.
XP Power (LON:XPP) To think it was as much of 5000p a few years ago. If only the company did not have so much debt, it would have a fair chance of fighting off the hostile bid and returning to former glories. As it is, I'd imagine most shareholders will gratefully accept an offer of just under 2000p.
@XPP It's 2.5% less than 2000, hardly 'just under' to most investors, which is a big discount to true value as assessed at the time of the capital raise in a detailed note by Harwood/Mills who are big shareholders I think. But I sold half v. reluctantly as Paul and Graham are on a bit of a roll!
Cranswick (LON:CWK) reporting prelims today. Not a small-cap, though, at £2.4b. I thought it deserved a mention. Revenues up 11.9% (11.6% on like-for-like). Statutory PBT 13.5% higher. Net debt lower. Operating margins up a little. CWK has a Quality score of 91, and an average ROCE of 15%. Net profits have been growing at a rate of 10%pa over the last 5 years.
What a high quality business this is! I've owned shares in the company since Sep 2022. Too bad I didn't buy 20 years ago. They have 10-bagged since then. The shares aren't in the bargain bucket, and trade on a forward PE of 17.9. I will continue to hold, though, as flogging off your quality compounders because the price seems a little bit high is usually a mistake.
Gamma Communications (LON:GAMA) gives a trading update today, It's one I've added to in my new ISA. They say they expect adjusted EBITDA to be within the range of expected forecasts. The point I wanted to draw your attention to is that the announcement gives the expected range of what they consider to be analyst forecasts. I'm sure Paul would approve of that. Maybe he's having an effect, who knows? Now, if only we could convince everyone that EBIT instead of EBITDA is the preferred measure.