Small Cap Value Report (Tue 22 Mar 2022) - BKS, SCS, LUCE, KGH

Good morning, it's Paul & Jack here with the SCVR for Tuesday.
Agenda -
Paul's Section:
Beeks Financial Cloud (LON:BKS) (I hold) - I review its interim results to 12/2021. Very strong organic growth, and lots of recent contract wins, suggests the future is bright. At this stage though, it's little above breakeven, so tricky to value.
Scs (LON:SCS) (I hold) - poor H1 results, but that's against unusually strong, distorted prior year comps. Outlook comments seem confident about recouping backed up orders into revenue in H2, with an in line with expectations guidance. Balance sheet laden with cash. Looks interesting, and I'm tempted to average down.
Luceco (LON:LUCE) - 2021 results look solid. The big question, is how much the doubling of profits from 2019 to 2021 was lockdown-fuelled? A PER of 12 looks attractive, but we could have just seen peak earnings maybe? At this stage it's tricky to value, and really depends on your personal view of the macro outlook.
Knights Group (LON:KGH) - profit warning from this legal services group has collapsed the share price by an astonishing 50%. Is this an over-reaction? Possibly, but I don't know the share well enough to be sure. I don't see solvency risk, and it remains decently profitable. So there could be a trade here for a rebound, maybe? I'm more worried about the read across to the whole sector, with corporate work slowing.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Beeks Financial Cloud (LON:BKS) (I hold)
144.5p (down 1% yesterday) - market cap £81m
21 March 2022 - Beeks Financial Cloud Group Plc (AIM: BKS), a cloud computing and connectivity provider for financial markets, is pleased to announce its unaudited results for the six months ended 31 December 2021.
These figures came out yesterday. They seem neutral, as the share price barely moved, on only 100k shares traded.
The main attraction with this share, is an acceleration in organic growth, now looking rapid, with continued momentum in order intake. There was a flurry of big orders (c. $6m total) received and RNS’d in Feb 2022 alone. The total market opportunity is large, and global. That’s why I think this is a very interesting share, although as mentioned before it’s difficult to value at this stage. Also bear in mind growth/tech shares have borne the brunt of the recent market sell-off and de-rating, as investors prepare for higher interest rates (which puts downward pressure on PERs generally).
Another key point is that growth investors generally want growth companies to maximise that growth, rather than maximising profits during the rapid growth phase. Hence BKS strategy is to do exactly that - with out-performance & upgrades to revenue being utilised in increased spending.
Tech companies are facing skills shortages & higher salaries, so they need to be delivering strong organic growth just to absorb higher costs. Thankfully BKS is doing more than fine in terms of growth.
This is all reflected in the half year highlights below - strong top line growth, but not much above breakeven on an underlying basis, and a £(266)k loss before tax on a statutory basis -

Gross margin is a lot lower - it’s come down from 49% to 40.5%. The explanation provided sounds reasonable to me, but we need to check future results to ensure gross margin does indeed move back up -
Underlying gross profit in the period, which is calculated by deducting amortisation on acquired assets and grant income increased by 21% to £3.14m (H1 2021: £2.59m) with gross margin down at 41% (H1 2021: 49%), in line with expectations. The expansion of our asset base across our growing data centre estate has led to an increase in depreciation and data centre costs at a faster rate than our revenue growth during the period.
The gross margin percentage has also been impacted by a higher proportion of hardware sales during the period which are at a lower gross margin than our typical infrastructure sales. As we deliver the material signed contracts over the second half of the year, we expect gross margins to increase in percentage terms as the cost of the infrastructure investment has already been made.
Outlook - continues to sound really good -
The prospects for Beeks have never been more promising, as demonstrated by the record third quarter trading, with over $8.3m to date in Total Contracted Value, resulting in ACMRR increasing to £17.7m as at end of February 2022.
Even excluding the potential contribution from Exchange Cloud, the Board are confident in achieving results for the year in line with market expectations, having already upgraded FY22 revenue expectations three times in the last six months.
Our position as an established technology provider to financial markets, provides us with a strong foundation to drive our business forward. Most financial institutions now see the cloud as a fundamental pillar of their business strategy and cloud adoption is already well underway for financial services. We will continue to invest into the development of our offering and increased sales and marketing activities to capitalise on our early successes in this significant market. We have a considerable and growing pipeline and look to the future with confidence.
Note that the new “proximity cloud” service has only generated negligible revenues of £17k so far, to end Dec 2021. That should grow considerably in future, as new announced contracts are implemented.
Taxation - is low at 9%, due to favourable effects of R&D tax credits, and the new super-deduction.
Balance sheet - the most noteworthy point is a rapid increase in property plant & equipment, as the company has been spending heavily on IT kit for its expansion.
Bank debt has increased to around £4.8m, less cash of £1.1m, so net debt of £3.7m - that looks fine to me, in the context of very rapid expansion, and a growing stream of mostly recurring revenues.
NAV is £14.0m, less £6.3m intangible assets, gives NTAV of £7.7m, which looks OK.
Going concern - I’m a little concerned that this note discloses that there was a covenant breach in Dec 2021, but it was “discussed and agreed beforehand” with the bank, which provided a waiver. That’s sailing a bit too close to the wind for my liking, so I would prefer to see the company do a small placing (say 5-10%, which would be £4-8m) to strengthen the balance sheet. Although now is probably not the right time.
My opinion - I occasionally buy growth companies, but only if they are reasonably priced, and display exceptional organic growth, which this is.
There’s a strong headwind at the moment, in that growth shares are out of favour currently. That’s fine by me, as it means I can buy more, and relatively cheaply.
BKS seems to have an outstanding market opportunity, and this is showing all the signs of becoming a much larger, and more profitable company, in a few years. Hence I like it very much as a long-term hold.
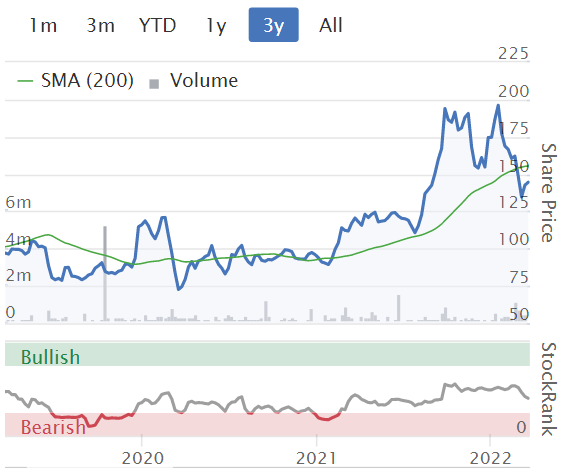
Given how much progress the company has made in the last 3 years, this looks a relatively good entry point to me - strong fundamentals, but weak sector market sentiment, could be giving us an opportunity maybe? Either that, or people just overpaid in the past?
Incidentally, I like the tweaks to the charts, which now show a moving average, and volume bars, both useful additions, without cluttering it up -
.
.
Scs (LON:SCS) (I hold)
182p (pre market open) - market cap £69m
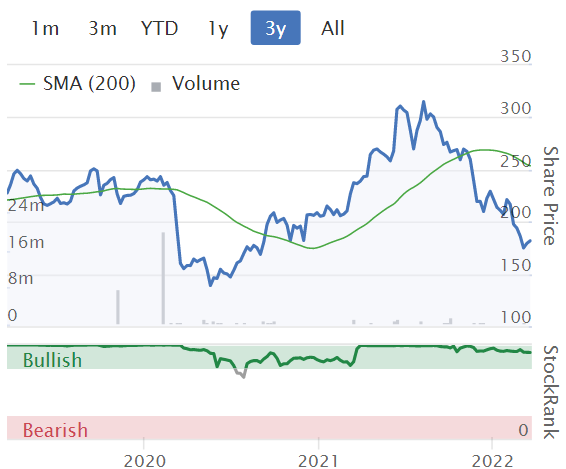
The background here is that SCS shares have performed badly since last summer’s peak, as indeed have many consumer stocks, and lots of small caps generally.
We’ve got general market worries (higher inflation & interest rates, supply chain problems, Ukraine war, energy crisis). SCS has also been hit with a slowdown in order intake previously announced, and supply chain delays causing its order book to extend to such a point that delivery times may be too slow for customers.
Hence I’ve been expecting poor interim results, with hopefully a recovery in supply chains subsequently happening. For that reason I’ve held back on increasing my position size here, until the scale of the damage in H1 became apparent.
This is tricky to analyse, because the H1 comparatives for last year were unusually strong, benefiting from the first re-opening after phase 1 of the pandemic last summer. This results in H1 this year -
Revenue down 16% at £145.9m
Profit before tax of £(3.6)m, down from a (one-off) profit of £17.7m in H1 last year.
Clearly a poor result.
However, the pre-pandemic H1 comps (26 weeks to 25 Jan 2020) are more meaningful, and show only a slight deterioration, with revenue down 4%, and the loss this time of £(3.6)m comparing with a pre-pandemic H1 loss of £(0.6)m.
The company thinks it can catch up in H2 - and has good visibility from the bulging order book. The key question for me, is whether the supply chain can actually deliver the backlog in time for year end (July 2022), or if some of the backlog might run into the new financial year FY 7/2023 - there’s got to be a risk of an H2 profit warning, if they don’t catch up -
During the period increased lead times for product due to supply chain disruption impacted delivered gross sales*, revenue and profitability but has enabled the Group to build a strong order book. This supports the Group's expectation of delivering profitable full year results in line with market expectations…
The Group has returned to a profile more in line with prior traditional financial years, whereby the investment in advertising to support order intake over the key winter trading period results in costs in the first half of the year which support delivered sales in the second half of the year. These costs have led to the Group making a loss before tax of £3.6m for the period, although positive underlying trading has ensured cash generation remained strong, with free cash flow* of £4.4m. The Group expects that the strong order book will support a profitable second half of the year and a full year result in line with current market expectations…
The Group's order book at the end of January 2022 was £148.0m (including VAT), which is £57.5m larger than at the end of January 2021 and double the size it was at 25 January 2020. The Group therefore expect delivered sales in the second half of the period to benefit from delivery of this order book.
Pricing power - absolutely key in this time of higher inflation. Can companies pass on higher input costs is the no.1 question we need to ask when considering buying or holding any share.
SCS makes positive-sounding comments on this -
As we forecast at the start of the year, gross margin* was 44.6% (44.8% in H1 FY20) despite significant rises in product material and shipping costs, as the Group has been successful in managing these pressures. The Group is working closely with existing suppliers, and is also actively engaging with new suppliers, to maximise our value offering and to improve lead times for our customers. Our tight control of margin extends to other costs, which we have managed closely. Our promising strategic progress and growth in key teams has come whilst ensuring a lower overall headcount than at the same point in the prior year.
Retailers do have an advantage, in that they set the selling prices directly. There’s no negotiation with customers, or contractual supply agreements which might need to be amended. So whilst many investors seem to be eschewing retailers, they could actually turn out to be quite good investments in an inflationary environment, who knows? I suppose the main drawback, is that we don’t currently know how customers will react to higher prices. What is the elasticity of demand for various products? I don’t have the answer to that, we’ll find out. Conventional thinking is that people keep spending on essentials, but cut back on discretionary items, when incomes are squeezed by inflation. However, SCS sofas are quite cheap, and there is an interest-free credit offer, so perhaps some sales might shift from outright sales, onto credit sales? I don’t know, we’ll have to wait and see.
Balance sheet - very healthy. NAV is £37.7m, less £2.2m intangibles = NTAV £35.5m.
A key point is that furniture retailing as a sector, has negative working capital - i.e. customers pay the cash before suppliers are paid for manufacturing it, and almost everything is made specifically to order.
Therefore, on a rolling basis, furniture retailers sit on a big cash pile. This can either be hoarded, and do nothing with it (which is what SCS has done), or it can be distributed to shareholders, which is what DFS has done.
I explain this point, with the numbers, in this video, which compares the balance sheets of SCS & DFS. This is factual, not an opinion, so people who dispute the point that SCS is sitting on huge surplus cash, are just factually wrong, as my video explains -
If that link doesn't work, try this link.
Distribution of cash - I’m pleased to see that SCS management has listened to shareholders, I know many have been nagging them to do something with the excess cash.
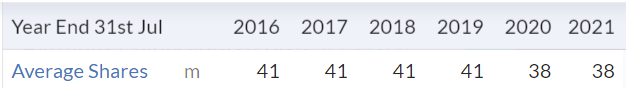
Today it announces a useful share buyback, of up to £7m (about 10% of the company) over the next 12 months. Hopefully that should soak up some selling overhang, and of course enhances future EPS and dividends. At the current market cap, it’s a no-brainer, and very pleasing. The company has done share buybacks before. It also didn’t need to raise cash in the pandemic, so unusually the share count is in a long-term downward trend - excellent for shareholder value on a low PER share.
.
.
There’s also a 50% rise in interim divi to 4.5p.
These measures barely put a dent in the massive cash pile, which reached £91m recently.
The cash will reduce, as order book backlogs are reduced over time.
Valuation - Stocko shows 28.5p for FY 7/2022, and 21.4p for FY 7/2023 - presumably brokers are being cautious due to the squeeze on household incomes, which is bound to have some downward impact on order intake I imagine.
At 180p per share, that gives us a PER of 8.4 times next year’s forecast EPS, and 6.3 times this year’s forecast. In other words, very cheap.
Given the immense balance sheet strength, and cash pile bigger than the market cap currently, then you couldn’t really ask for more downside protection.
My opinion - I thought it was cheap at 300p, so probably best ignore my opinion! That said, the consumer is facing a tight squeeze this year and probably well into next year, a lot worse than was expected this time last year. An article this weekend said that people need a 10% pay rise, just to keep up with inflation and tax rises.
We should find out imminently what the Chancellor is going to do, to alleviate household incomes, but I think his reputation for competence is already slipping, seemingly asleep at the wheel as the economy faces the risk of slipping back into recession.
SCS has a more variable cost base than some other retailers, as a lot of staff pay is performance related, i.e. sales bonuses for achieving targets. Another big cost is marketing, which can be dialled up or down to reflect the circumstances.
Overall, the H1 numbers look poor, but the commentary and outlook sound confident about H2. Therefore I’m tempted to average down. Valuation remains remarkably cheap. EPS should return to c.30p in due course, and take the share price back up to c.300p. I’ve no idea how long that might take though? Maybe 1-2 years? Who knows, my crystal ball is in for recalibration at the moment, after a period of underperformance.
I’d like to see more firm evidence that deliveries to customers in H2 are recovering. The trouble is, if we wait for that evidence, then the share price could have already anticipated it, and be higher than now. Tricky one. It is tempting to trickle feed some money into SCS, starting now, whilst accepting there is a risk of an H2 profit warning, so maybe keeping some powder dry to buy more on any future falls.
The cash pile remains a beacon for takeover bids, although maybe the company is too small for private equity players?
Stocko shows a 7.5% forecast dividend yield too.
SCS seems a strong candidate for a value investing portfolio.
.
Luceco (LON:LUCE)
240p (up 3%, at 09:59) - market cap £386m
Luceco plc ("Luceco", or the "Group" or the "Company"), a manufacturer and distributor of high quality and innovative wiring accessories, LED lighting, and portable power products, today announces its audited results for the year ended 31 December 2021 ("2021" or "the year").
These figures look pretty good, and ahead of the consensus forecast shown on the StockReport: 20.2p adj EPS actual, vs. 19.3p forecast.
Liberum’s update note today (many thanks for this) says 2021 is in line with their expectations, and forecasts EPS essentially flat for the next 2 years.
Luceo makes a strong profit margin, with a 15.5% operating profit margin, demonstrating decent pricing power. So the products must be good.
Pricing power - “mitigate” suggests not all cost increases have been passed on, due to a time lag, but overall this sounds encouraging to me -
Successfully implemented selling price increases to mitigate cost price inflation…
Gross margins came under pressure for all manufacturers given inflation in raw materials and freight costs. Cost inflation increased progressively through the year, costing £13.6m in 2021 and expected to cost £25.0m on an annualised basis. We swiftly and successfully implemented selling price updates designed to offset the £25.0m annualised impact in full, albeit with an inevitable modest lag due to notice periods and order lead times.
Temporary gross margin compression from the implementation lag was mitigated by hedging arrangements, further manufacturing efficiency gains from automation, and solid operating leverage on strong sales growth. The latter is illustrated by the fact that in the last two years the Group has added no extra overheads despite £52.5m of organic revenue growth. ..
Inflationary trends stabilised in the final quarter of 2021 compared to the second and third quarters but have resumed in the wake of recent tragic events in Ukraine. We are mindful of the impact that real wage deflation could have on consumer spending, including home improvement, and therefore remain vigilant.
Note that gross margin was 38.5% in H1, and 37.1% for the full year, which implies a fall to just under 36% in H2 - not a disaster, but it’s worth noting that margins are under a bit of pressure.
Lockdown benefit - profitability doubled over the pandemic 2 years, from the 2019 base figures. So the question is, to what extent has LUCE benefited from the surge in demand for home improvements during the pandemic? Or how much of the increased profit is due to self-help, e.g. moving production to lower cost facilities in China? The group has also made acquisitions, including a small electric vehicle charging point business announced today, called EVCP, for £10m (previously 20% owned by LUCE, now 100%).
It’s this question about lockdown benefit, which has held me back from buying LUCE shares so far, despite the financials & valuation looking attractive, after big recent falls.
Hence it’s a difficult share to value, because future profits might go up or down, we don’t know at this stage. That’s why it’s priced on a low PER though.
Balance sheet - looks reasonable. NAV is £87.7m. Take off intangible assets of £32.9m, and NTAV is £54.8m.
Working capital is healthy, with a current ratio of 1.9 (for this type of business I regard anything above 1.5 as being good).
Note there is £36.8m of interest bearing debt in long-term creditors - that’s not a problem whilst the business is strongly profitable, but could become an issue if we go into a recession and future profits tumble.
Net debt (excl. leases) is £30.6m. Personally, I wouldn’t want to see that get much bigger, because profits could fall if there’s an economic slowdown, so this is really not a time to be running up more debt. Buying the remaining 80% of Sync EV, announced today, looks to be adding £8m to net debt. Maybe not such a good idea?
There doesn’t appear to be a pension scheme, I’m pleased to report.
Outlook -
"Luceco has a long history of market outperformance. The accelerated progress we have made over the last two years, in which our profit has doubled, is the product of our market focus and business model. We favour RMI construction markets because of their resilience in uncertain times, and undoubtedly benefited from that focus in 2021. But it was our advantaged business model, with its inbuilt resilience and agility, combined with our "can-do" culture, that allowed us to prosper more than most. We moved quickly, won new business and saw growth opportunities across our diversified customer base.
Such strong progress in 2021 naturally creates a tough comparative, particularly in the first half when UK residential RMI activity was at a lockdown-driven peak. We therefore expect revenue in the first half of 2022 to be broadly in line with last year. We are mindful that recent geopolitical developments, and their associated impact on inflation, may make progress harder during the year.
We have strong positions in attractive markets with an advantaged business model and a clear strategy. We have a well-funded business with clear growth opportunities, particularly from our recent entry into the electrical vehicle charger market. We face the future better prepared than ever and I am confident we have what it takes to continue to outperform our market."
My opinion - there’s no doubt that LUCE has performed very well indeed in recent years. The guidance (H1 2022 revenues flat, tough comps) suggests to me that it’s probably best to regard c.20p EPS in 2021 as being peak earnings for the time being.
Hence at 240p per share, the PER is 12 - probably about right, for a company which might be around peak earnings, coming up against tough comparatives, and with some net debt (about 8% of the market cap, so not excessive).
However, as a long-term proposition, if earnings growth resumes, then this could end up looking a good entry point.
Overall then, the uncertainty over future earnings makes this difficult to value, because there’s a fairly wide range of possible performance over the next year or two, depending on how macro factors unfold. That said, I’m tempted to take a small, initial stake, dipping my toe in, and then see what happens. There’s also a reasonable dividend yield, about 3.4%, which is worth having.
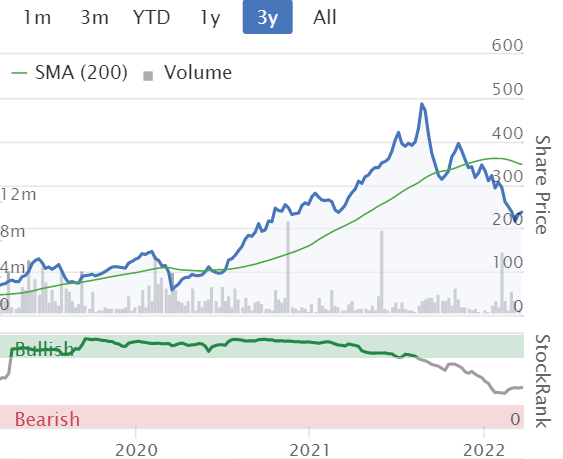
As you can see from the chart, the market has scrubbed off growth expectations, halving in price since the Aug 2021 peak. That could re-rate back up again once we’re through this current wobbly macro patch maybe? Even if profits fall by a third, the PER would still be under 20. So there seems a fair bit of downside protection at 240p per share. So it really all depends on how you see the outlook for the economy, and future earnings at LUCE. Dust down your crystal balls!
EDIT: check out the Director dealing - some multi-million selling has occurred.
.
.
Knights Group (LON:KGH)
186p (down 50% at 12:44) - market cap £154m
Trading Update (profit warning)
This is one of the flurry of acquisitive legal services groups which listed a few years ago, this one in 2018. Jack normally covers this sub-sector, but he’s been carrying me recently, so I’ve told him I’ll do today’s report solo. No harm in having 2 opinions on any share, we like to do that, to compare notes.
Jack sounds sceptical here on 12 Jan 2022, when he reviewed KGH’s interim results. At the time, the group thought it would experience the usual H2 seasonal weighting and achieve market forecasts.
That’s gone out of the window today, with a profit warning for FY 4/2022 which I’ll summarise, with my comments -
Slower than expected H2, especially Q4
Reasons? Staff sickness due to omicron, slower benefit from return to office working, slowdown in corporate work due to downturn in business confidence. The only one that sounds credible to me is the last one.
Some improvement recently, but not enough.
No loss of significant clients or staff.
Revised guidance: £126m revenue, £18m underlying PBT - so it’s still a decently profitable business, and H2 is better than H1 (which was £7.6m underlying PBT. I’m not sure what previous guidance was as no broker notes are available.
Guidance for 2023 - organic growth of 5% in revenues is all it says.
Margins “rebuilding to historic levels over time” - doesn’t sound too good, suggesting to me there’s something wrong here.
Cash conversion robust.
Balance sheet - when a share plunges 50% on a profit warning, that tends to mean there’s something serious wrong. Is there solvency risk? Not that I can see (on a review of last, interim balance sheet). It’s not great, mainly being goodwill from acquisitions, but NTAV is almost £10m, which is OK.
Receivables & unbilled work are high at almost 6 months revenues.
Net debt looks OK at £23.3m, not excessive for a firm expected to make c.£18m annual profit.
My opinion - this looks an extreme market reaction, but that can often be because brokers have slashed forecasts brutally. I don’t have access to any forecasts. Is the business really worth half what it was worth yesterday? It did look over-priced to begin with, and could now have overshot on the downside? So if you like the sector, and the company, then it could make sense to buy it at half price today, I don’t know.
This could have read-across for other listed legal firms. If business confidence is declining, and new work is reducing, then that’s likely to have at least some impact on other firms too.
Or the problems could be confined to KGH, which doesn’t strike me as likely.
Maybe work will recover, who knows?
I’m not keen on this sector, for the fundamental conflict there is between shareholders and fee earners personal interests. If they get fed up with paying divis to outside shareholders, then the talent could drift away to set up in competition, it’s all about personal relationships with clients & lawyers after all.
All the share price gains in the last 4 years have gone out of the window, in one day.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

60 comments
Hi Paul
Looking at Scs (LON:SCS) I also think as JonBirdy advises below, that the quality is not as bad as some may suspect and I think potentially as consumers tighten the purse strings, those who shop at more expensive retailers may end up buying from Scs (LON:SCS) as an alternative.
It is always hard to predict but for some retailers, a squeeze on consumer spending may benefit them.
Hi Paul
Thanks for your comments on Scs (LON:SCS) (I hold).
I recently used SCS to re-carpet my house. They were cheap and contrary to common opinion, they don’t just sell tat! John Lewis sell the same carpets I bought but costing a lot more.
One aspect of the Scs (LON:SCS) business model is ‘free fitting’ but only IF you buy their overpriced underlay. I bought my own underlay (a small hassle) and saved money overall. Many busy people won’t be bothered, so as an investor I applaud their model!
Customer service was great and with four years interest free credit my carpets feel basically free, costing me the same as a few cups of coffee each month
There were initial supply chain issues with my fitting delayed. But Scs (LON:SCS) then came good with getting my carpets in over a month earlier than they first said.
I would use them again for price, customer service and interest free credit alone.
I know you like to sample your hospitality shares. So I thought sharing my Scs (LON:SCS) customer experience might be useful.
Some stonking trades gone through in the last hour on Supreme (SUP) .
1.1 million shares traded today, normal daily volume is 20-50k shares .
240k shares at £462k value twice
280k shares at £539k value twice
Thats someone just spent 2 million quid so around 1% of the company which actually isn't that much I guess .
But someone like it, price is starting to creep up to £2 level which it has made several attempts to clear previously , looked like it had made it until Ukraine invasion torpedoed (excuse the wording) that .
A lot of people like it due to the entrepreneurial CEO and it looks a decent business with a CEO who loves his company and is not in it for a quick buck.
Since someone sold, you could also say that someone doesn't like it :)
Fortunately I did sell 1/3 of my holding in June 2021 at just shy of £20 so did manage 50% profit on that tranche. Sadly should probably have sold the balance as now effectively at break even on my original investment. However, past experience tells me as soon as I sell the share price will rocket! Guess we will have to see if your analysis proves correct and I should also have got out sooner.
I know strictly speaking that Gamma Communications (LON:GAMA) isn't in the SCVR universe but I wondered whether anyone had any views on why the share price is down c. 12% today. I have read the results announcement and in my view there appear to be very few negatives - just some difficulty in recruitment perhaps. The adjustments to the accounts seem reasonable noting the exceptional item recorded in 2020 (profit on a sale of business) meaning that the true comparator is up 25% at Adjusted PBT level. Cash generation is excellent and after major expenditures on Capex, acquisitions, etc. during 2021 there is still nearly £50m at the bank. Consequently the balance sheet looks healthy with a decent NTAV despite significant intangibles (attributable to acquisitions). Management comments on the outlook are positive and the business is performing well so far in 2022. Results appear to be in line with analyst consensus expectations. Despite all this after today's fall the share price is down c. 50% since September 2021. Maybe some of the fall is attributable to a rerating from a fairly toppy valuation but prospects and growth appear strong and in line with historical growth rates. What am I missing!
Gamma Communications (LON:GAMA)
What am I missing!
I sold today because:
a) the rate of growth is slowing
b) the runway for adoption in the UK ends fairly soon as traditional phone lines are phased out
c) the anticipated European growth is not coming through
d) this is a very competitive market globally and I hold a faster growing international alternative
e) taking into account the above and the general rerating of growth stocks, the reduced valuation is still not compelling
f) should I have sold last summer? too bloody right!!
Fortunately I did sell 1/3 of my holding in June 2021 at just shy of £20 so did manage 50% profit on that tranche. Sadly should probably have sold the balance as now effectively at break even on my original investment. However, past experience tells me as soon as I sell the share price will rocket! Guess we will have to see if your analysis proves correct and I should also have got out sooner.
hi BnB, just out of interest what’s the faster growing international alternative?
Sad to see Gamma falling so far today. Fundamentally still a solid business still growing at a fine pace. The market is brutal at the moment and is taking no prisoners. I believe in 3 years times the share price will be substantially higher again. The partnership with Microsoft and European expansion will prove crucial
Circassia (LON:CIR) (no position)
Brief comments on this one in response to some of the comments below:
On listening to a previous Chris Mills interview I was initially under the impression that approval was a given, but after the x2 2021 delays I am more wary.
If I held I would conservatively assume the $10.5m + $6m potential royalty uplift here is zero for now.
a)a £0.7m PPP uplift, which will not repeat;
b) £4.4m tax benefit due to prior losses from a Swedish subsidiary.
I know there are lots of historical losses on the balance sheet, but for me it was unclear how much of these could be used in the future.
If these China revenues were booked in March-June 2021, then perhaps the comparatives will get harder for the rest of H1 2022?
Of course if this is +24% on top of the £0.6m China revenues, that would be most impressive.
I think it's also worth adding that Clinical revenues are +24% vs Jan/Feb last year, with no mention of Research revenues (which are c 16% of group revenues for completeness.)
I also don't know why they didn't give a YOY% value up to 20th/21st March?
Playing devil's advocate I can't work out where their 3rd party distributor costs are now?
Gross Margins have barely changed in the last 2 years, which is where I would expect these presumably quite significant costs to sit.
Where are they?
I continue to remain tentatively interested. It still looks expensive to me at the moment, but if growth can kick in then I would certainly be more interested.
GL to all holders.
A
Scs (LON:SCS) are tighter with money than me. At this rate theyll be able to spin the buyback out until 2023
On buybacks they say - "The maximum daily number of Ordinary Shares that will be purchased is 18,733, which is 25% of the average daily volume traded in February 2022, the month prior to this announcement. The Programme is currently expected to end no later than 12 months from the date of this announcement."
Rock solid Wynnstay, looks like they will get a one hit bump due to spike in fertiliser prices (effectively their incumbent stock will get a higher price).
I hold (but not as much as I’d like) , been waiting for a dip to add but doesn’t happen .
Cracking company, bulletproof and a real great anchor share for any portfolio with long term robustness and a management that is there to serve its shareholders.
Talking myself into adding .
Are you talking about £WYN ?
The reason for my query is that I have held for a while and topped up twice when it has dipped to around 500p recently where there seems to be support !!
Richard
yes Wynnstay , WYN - well done for topping up at 500 level , can’t see it going there again .
Wynnstay (LON:WYN) I love their CEO's & CFo's presentation. they come across as really straight guys with no pretensions whatsoever. The sort of rock-solid persons you want to be running a Company.
Just a reminder that the monthly Mello show for Trusts and Funds is free to join and starts in one hour..... https://www.stockopedia.com/co...
I've just looked at the top fallers list today, and see that;
Diurnal (LON:DNL) is down 43%, and
Knights Group (LON:KGH) is down 48%
So I'll prioritise those to look at next. Commiserations to anyone here holding either share.
Regards, Paul.
Hi Paul, did you have a chance to review LON: DNL diurnal, although I may have missed it, please?
best, Neil.
Diurnal (LON:DNL) some signs of life today. Any views whether this has bottomed out?
Knights Group (LON:KGH) down very sharply on profit warning, which from what I can read is mainly driven by staff not coming back to the office, which is hitting productivity. Sounds rather odd as it didn't seem to effect them (or the wider sector) until now. Several of its legal peers are also down in sympathy.
I read and tried to get a short on (down 35% from AU) it read rather fishy IMO.
Knights Group: It's an odd profit warning; I don't buy the excuse of lower productivity being caused by "the business not benefitting from a faster return to office working and the consequent advantages of our team-based culture."
It's far more likely to be caused by the next sentence "We have also seen a softening in business confidence, possibly due to concerns around the strength of the economy, such that there has been a slowdown in corporate work". It's odd to me that they decide to place the importance on the first aspect than the second. Work not coming in the door is more important to me than teams being able to have an in person chat. Plus, offices are open and people are going in, just not five days a week.
I am a lawyer who used to work in law firms, and productivity isn't affected that much by not being physically present with other people. Law firm work is the perfect example of work that can be done nearly as well remotely. It's a (digital) paperwork job essentially, with networking required from the partners/senior associates, to keep relationships with clients. I don't believe believe partners aren't networking, as this is their lifeline to the high salaries. It's possible that networking has become more rigid/less effective because people are out-of-town more.
The way lawyers at law firms record their time is by charging minutes/hours of work to client matters during a working day. So you can't just dodge work by being at home. The work has to get done, and the mgt. can track, on a daily basis, who is doing what.
If the work is coming in, it gets done; if the work isn't coming in, you can't do it, no matter how productive you are.
Whatever the reason, mgt. saw it coming and some decided to offload shares in advance; CFO sold off over GBP 700k in Feb (from options, not personal money invested); the co-sec/general counsel sold GBP 40k eleven days ago (! - is that legal??).
For any shareholders in Keystone Law, beware: whilst a materially different business model, with a positive trading update in Jan, there were big share sales in late 2021, coming in at just shy of GBP 10m.
I like Keystone, and it acknowledged that Omicrom affected their business positively (lower socialising costs in December, and therefore more time to do work), so this will reverse at some point, and they will undoubtedly see pressure for chunky pay rises, as their money earning assets are highly mobile, well paid professionals, in a buoyant market.
Cheers
Chris
Deleted. I had postulated a circumstance that I now read in the RMS did not prevail
Chris, Re Keystone my take is that they are the nearest thing to a franchise model for lawyers that the regulations allow. Their lawyers set their own billing rates with their clients so if they want to charge more that has to come from the clients, not from Keystone. Happy to be corrected.
Hi John,
Yes, correct on both points. I think of them as a hairdresser: the lawyer is self-employed, and pays Keystone a % of their takings for a seat in a shop (central offices, PI insurance, technology, a brand, admin team and Keystone's profit margin).
If you go in to Keystone as a partner, you get a very high % of the fees you bring in yourself, and get a smaller % of fees for work you do which was brought in by someone else. In theory, still much more money than you would earn in a law firm, no (or certainly much less) politics, and no one really cares if you down tools for 12 months because they don't owe you a base salary.
Similar for junior lawyers, you can still go in and do work brought in by the partners, and collect a decent % of the fees, although you don't have as much job/income security should work dry up for a bit.
If the lawyer chooses to have their own office, which some lawyers do, Keystone doesn't pay for that. I'm guessing rent for Keystone is a much lower % cost than any comparable law firm. Keystone has a central office for Keystone's overhead staff and some office/meetings space, but it's not big enough to accommodate the amount of lawyers they have, and it's not intended to.
I like the company and the business model, I was pondering buying in before seeing the gigantic director share sales. Will watch from here.
Cheers
Chris
Re Knights Group (LON:KGH) , (I don't hold) I believe 'the staff not returning to the office' loss of productivity mitigation. During the lockdowns and restrictions I was designated as a key worker by my employer and was one of the very few who had to go to the office every day. As time went on it became clear that many (not all) of the Working From Home crew were taking the wotsit and doing very little work at all. I think it's something that companies will need to address.
As ChrisFarrell21 says above taking the mickey isn't possible for lawyers in firms who have to record every minute of their work. If anything the lawyers I know say they are more productive working from home, certainly compared with working in an open plan office with all the distractions they bring. Two days a week in the office is the sweet spot for them.
So I suspect there must be something about the Knights culture that is different and not necessarily for the good. Keystone Law would be my pick in the sector.
I know a couple of lawyers that TUPEd over to Knights when their firms got taken over. A year later and these lawyers have left for other firms.
The success of a law firm is dependent on keeping fee-earning talent. When lawyers move, often so do the clients. This is a big risk and warning sign, for me.
Hi Paul, I know Staffline (LON:STAF) (I hold) is not your preferred choice of recruitment company, but wondered if it's one you can cover? They have announced results today plus two contract wins - maybe that changes the picture somewhat?
Hi RajanP,
I've got Staffline (LON:STAF) on my list, but there's a lot else to cover today, so will try to include STAF but can't guarantee it.
Regards, Paul.
Circassia released interim results this morning. The results are all as stated in the year end trading update from January. The two positive indicators that stood out to me are:
The story is intact, mgt. is on target for the c.62p share incentives, and presumably the intention is still to sell the company once the turnaround is further down the road.
Thanks
Chris
Circassia (LON:CIR) looks good. The fact that is has £12m+ of net cash with £6m to come and is now strongly cash generative on a month by month basis is one heck of a turnaround !
Mgmt Incentives kick in at 64p
The key to this share though is the value to a buyer. A global player with a strong distribution network can basically strip out a large chunk of cost very easily, so the profitability to a purchaser is probably £10m+ better than to Circassia (LON:CIR)
So what we really want is for them to get to £6-10m of profitability organically then make a sale. Valuation to a buyer could then be north of £340m inc cash, or roughly 80p+
The CEO has done the sale before and is well connected to the right buyers. Harwood own a bunch and they are backing the sale strategy so I expect 12-24 months is probably the right timescale.
£SCS The 2021 annual report provides a wealth of market and marketing information. I suggest its worth a re-read, if only to allow the reader to understand the background and overlay the interim results and your own views on the possible environment for furniture and floor covering sales over the coming months.
Wynnstay (LON:WYN) An inline with management expectations AGM statement today. Shore Capital (house broker) note released said it was a strong update, inline with their expectations pre acquisition. They have upgraded forecasts for 22 and 23 by 3% and 7% for PBT.
Thanks Paul for your analysis on £SCS. I bought around the 260p mark originally and averaged down a couple of weeks ago. What I hear is a lot of positivity based on the numbers, more alignment between company and shareholder and a bit of heightened uncertainty as to what the future holds. On balance it feels like a classic value situation where everything looks good, objectively, in the present, but the price is depressed due to the inflationary uncertainty. Given it seems a lot of that is priced in, it feels to me like a good time to take advantage of the share price. By the way I agree with you that it was cheap at 300p!
On the averaging down dilemma - I often find it helpful to ask myself the question "if I didn't have this share in my portfolio, would I buy it now?" if the answer is yes then I invariably go ahead and average down.
Pebble (LON:PEBB) (promotional products like 4imprint). FY21 released today, in line, rev £115m, EBITDA £15.4m. Facilisgroup has ARR+40%, it's scaleable with strong margins. This is the most exciting part of the business in my opinion. Brand Addition ahead of pre-pandemic. They are confident for the year ahead. There's a management webinar Thurs 24.3.22, 1pm Register here. The SP is already up 19% today! We have Pebble (LON:PEBB) last two results presentations here. (NOTE nothing to do with PEB, they are completely different!)
Some other results webinars coming up, register for any of them here:
Personal Group (LON:PGH) Full Year 2021 results: Friday 1st April, 12 noon. A bit more detail. Results next Tuesday. January's TU in line w expectations. February they announced the Sage agreement has been extended. This provides £1.6m ARR. Again in February, Royal London took a 4.96% stake. Personal Group (LON:PGH) benefits from the current talent war, with employers focus to support employees.
Property Franchise (LON:TPFG) Full Year 2021 results: Wednesday 6th April, 12.30pm
Tracsis (LON:TRCS) Interim results: Friday 8th April, 1pm
And, the Stockopedi/PIWORLD StockSlam: Wednesday 6th April, 6pm. Where private investors 'slam' their best stock idea in 3 minutes, followed by Q&A. We still have a couple of places left if you'd like to pitch your favourite stock. This may be your last chance since we'll be taking a break with these StockSlam events after this one. To take part contact me here. Or, register to attend live, here.
Paul, I have provided a response here to your challenge regarding Empresaria (LON:EMR)
BnB's write up is well worth a read for context on recruitment stocks, not just Empresaria (LON:EMR)
Great, thanks BnB, I shall take a look once the SCVR is finished :-)
Always interested in your views on the staffing sector.
Regards, Paul.
Results from Harworth (LON:HWG) looks good. NAV per share increased from 160p to 198p over the year. This is land developer which prepares residential plots which are sold on to housebuilders, it also has a big industrial portfolio. Very under the radar but has excellent track record, trading well below NAV and gives exposure to real asset which has to be a good thing in a more inflationary environment.
https://www.theguardian.com/fo...
A tad blunt but hospitality providers may have a rosy future after all
Hi colin,
Thanks for this, interesting.
This echoes a point I've made previously, that the juggernaut of negatives which is about to hit the hospitality sector, is sadly likely to see large numbers of independent restaurant/bars go bust in the coming months. Reasons are -
Put all that together, and it's likely to be absolute carnage.
All of which clears a lot of weaker operators out of the market, leaving more market share for hospitality companies which have survived.
Also it means loads of good sites coming onto the market, already fitted out, with lower rents and landlord incentives.
Therefore, companies in this sector which are expanding, e.g. Hostmore (LON:MORE) (I hold), £FUL , Various Eateries (LON:VARE) and Nightcap (LON:NGHT) could be interesting, and may do better than expected, with highly profitable new sites offsetting some or all of the decline in profits from existing sites.
Plus of course much less competition as the zombie competitors disappear throughout 2022.
The bottom line is that hospitality companies offering good products & services, at attractive prices, always do well.
Regards, Paul.
Mti Wireless Edge (LON:MWE) which I hold announced today the sale of their Russian business for a nominal value to their GM there. This is not a significant business to them and will impact about 5% of their revenue but clearly seeing much smaller companies pulling out of Russia is desperate news for the Russian economy. I read yesterday that 25% of airport staff at the main russian airports have been put on leave as there's obviously very few international planes running now. It's economy is crazily small for such a huge country (they can thank Putin for that) but is very concentrated in a few key industries. Russia though is clearly off grounds for investment for a long time now and will only present an opportunity if Putin is taken out and replaced by someone very different. (Again I am not commenting on the war just the impact to the economy)
Economics and politics are strongly intertwined unfortunately - Russian economy is shrinking and will continue to shrink at least in the very near future but commanding such an incredible wealth of resources and people resolve I doubt any sanctions will bring it to its knees and the change of the leadership unfortunately. I also think that the problem with its tiny economy compared to its size and resources is exactly the leadership and the prevailing system which does not promote free thinking, entrepreneurship, creativity, its a state authoritarian capitalism at best. Sorry for digressing here on the matters not really to do with any shares whatsoever, I shut up!
Mti Wireless Edge, an Israeli company.
Sold them all profitably in July 2020 at 31 pence / share, regretted it almost immediately, having sold on a whim. That whim being my objection the supply of automated crop irrigation controls to Red China.
I no longer hold.
Today the share price is 67 pence……
Moral of the story is; don't let politics get in the way of profits.
Silver
That’s not the moral of the story.
The moral of the story is that there’s a lot of people out there who couldn’t give a fig about human rights so long as they’re making a few quid.
Mtl Instruments Ord (LON:MTI) doing the right thing, and quite quickly.
If, as I suspect, they provide the antennae to the Iron Dome system, they should encourage their mother nation to supply it to the Ukraine government pronto.
Good morning Paul and Jack,
would Luceco (LON:LUCE) be on your agenda today, 2021 FY results out this morning look excellent, 30% increase in EPS to 20.2p , they look cheap to me.
Richard
#LUCE might appear cheap on the surface, but it is wise to be aware that it is one of only six companies in the Stockopedia UK Universe to score a maximum Montier Earnings Manipulation Score of '6'.
https://www.stockopedia.com/ra...
Very good point re Luceco (LUCE). It will be interesting to see if the score remains the same after STOCKO updates for todays final results. To be fair to them, they appear a pretty genuine outfit to me and I am impressed by the level of information provided in todays presentation. There may be an opportunity to get some answers from the Investors presentation scheduled for next week.
Just to add, my main concern here is the dependancy the company may have on B & Q. I know a few years ago it was 40% of sales - I assume that has reduced since then, possibly considerably. I see Kingfisher shares got a hammering today despite pretty good results, presumably because of their reference to a slow down in current trading.
I see LUCE as part of a bigger trend..
Have electricity prices gone up? - Yes
Are businesses/consumers wanting to switch to more efficient LED lighting to save money/do good? - Yes
Will LUCE benefit from that? - It has good products, competitively priced, good place in the market, so on balance probably yes.
Comments on Luceco's results would be much appreciated Paul and Jack if you get time.
interesting update from Pci- Pal (LON:PCIP) this morning about a patent being granted in the US - is there read across for a positive outcome in the lawsuit I wonder?
From Finncap via research tree Pci- Pal (LON:PCIP)
"We note that a number of competitor systems were reviewed – including Semafone, with whom PCIP currently has a patent dispute – and the US Patent Office is sufficiently satisfied of PCIP’s innovation to grant the patent. This decision has no direct bearing on the outcome of the Semafone dispute – which is expected to be heard in the US courts in 2024 – but in our view it is a positive indication
Has anyone else noticed that after a STOCKO software upgrade, any ALERTS you have set up go back to zero, meaning that you have to go through all your holding and set them up again?
Good morning, it looks like £SCS have released their interim results :)
Finally the company is coming around to starting share buybacks.
Thanks for flagging this Harry, I'll look at Scs (LON:SCS) (I hold) next.
Thankyou for your thoughts on SCS Paul, keep your eyes out for final results from COG any day now. I'm also keen to hear if they've found a replacement for former CFO Michael Holton, who was relieved of his duties in November. Hopefully positive news soon. (May accompany their results). This has probably been a contributing factor in helping to keep a lid on the current share price.....
Scs (LON:SCS) does that annoying thing of saying their full year will be in line with market expectations but then doesn't tell us what they actually are...The Stocko consensus figures look out of date to me because the broker consensus doesn't seem to reflect a less than satisfactory H1 revenue performance.
Hi Harry, I understand your frustration regarding waiting for share buybacks, but I am also conscious of the fact that the company needed to be mindful and sensitive to HMG financial handouts in the way of furlough money, so I'm not surprised at all at the delay. I don't have an issue with this.
ATB DH2.