Small Cap Value Report (Tue 22 Nov 2022) - FORT, VANL, AO., OSI, CARR, WINK, ALT

Good morning from Paul & Graham!
Agenda
Paul's Section:
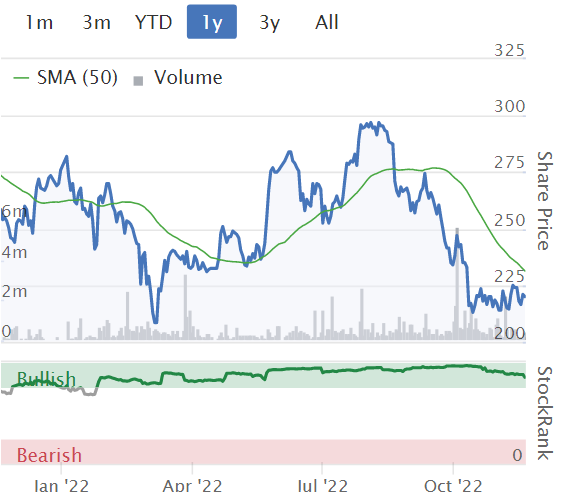
Forterra (LON:FORT) - an in line with expectations update for FY 12/2022. There are some interesting dynamics here, which suggest FORT could be set up well for any forthcoming downturn in housebuilding. The finances look good too, with an almost ungeared balance sheet. I think this is starting to look interesting, after the big recent fall in share price.
Van Elle Holdings (LON:VANL) - a solid trading update today for its H1 to end Oct 2022. I like the strong, largely ungeared balance sheet here. Outlook for the rest of FY 4/2023 sounds encouraging, but I'm worried about the outlook beyond that, given macro negatives. Will larger building projects be quite so plentiful, now that interest rates are higher, and the economy going into recession? I suspect not. For that reason, risk:reward doesn't seem attractive enough to tempt me into this share right now.
Osirium Technologies (LON:OSI) [quick comment] - a tiny, speculative nanocap. We discussed it here on 1 Nov 2022, concluding that whilst it looked an interesting speculation, it clearly had a desperate need to raise fresh funding. Today it announces a small placing, raising £1.36m net of fees. Heavy dilution, and a 50% discount for the fresh money, coming in at 2.0p per share. Cost-savings being implemented. CEO moving to become part-time Chairman, and Sales Director becoming new CEO. The product looks intriguing, but super-speculative share. A bit better now it's raised some fresh cash though. [no section below]
Graham's Section:
AO World (LON:AO.) (345m) - H1 sales are down 17% at this online appliance retailer. However, it still manages to increase market share since the overall market has declined at an even faster pace. More importantly, the company has cut costs and is working on many more ways of cutting costs in the months ahead. This encompasses headcount reduction, products being pulled, and unprofitable sales channels being shut down. Even the operations in Germany have been closed in the name of improving the company’s bottom line. I’m impressed by the vigour with which it’s pursuing a reasonable EBITDA margin and so I’d no longer want to short this stock or give it the bargepole treatment: it’s now acting like a proper company, being run on behalf of its customers and its shareholders. I guess that’s what nearly running out of money will do to a management team.
Carr's (LON:CARR) (£100m) - an unpleasant RNS with news that results at Carr’s for FY August 2022 won’t be ready until mid-January, and trading in its shares will need to be suspended. It’s not clear who is to blame. One of Carr’s companies - which it has already sold - needs to be audited, and its existing audit arrangements can’t be used for reasons of “independence”. I speculate that this is because the auditor was hired by a related party of Carr’s (there is a complicated web of company relationships involving Carr’s and the division it has sold off). It doesn’t look like a serious problem to me, based on the information in the RNS, but it’s certainly going to be inconvenient for Carr’s shareholders and I can understand some investors choosing to get out instead of waiting for the problem to be resolved.
Altitude (LON:ALT) (£17m) (+9%) [no section below] - excellent news here as Altitude says FY March 2023 is trading “materially ahead of current market expectations”. These expectations are for revenue of £13.9m and adj. EBITDA of £1.2m. Further growth is anticipated in the next financial year. I covered this stock in October, when it revealed that it was on track for results “at least in line with expectations”.
New forecasts from Zeus now suggest FY 2023 revenues of £16.5m and adj. EBITDA of £1.5m. The corresponding forecasts for FY 2024 are £23.7m and £1.8m. It’s a short update from Altitude today and I haven’t got more to add except to reiterate that I believe this stock has interesting potential as a trusted marketplace, while acknowledging that it’s still at an early stage. [no section below]
M Winkworth (LON:WINK) (£20m) (unch.) [no section below] - this franchisor of real estate agencies announces that revenues for FY Dec 2022 are expected to exceed management forecasts, and full-year PBT will also be “ahead of the current market forecast of £2.1m”. This reflects a very strong Q3 performance (+38% network sales vs. Q3 last year) which included “an overhang of uncompleted transactions in Q2”. The September mini-budget and rising interest rates caused some nervousness for buyers but property sales did progress and October was fine. In his comments, the CEO mentions strong levels of UK employment as underpinning the economy: with exposure to both sales and lettings, Winkworth appears confident that it can do well even in a higher-rate environment. I like the franchise estate agency model and consider all of the companies in this sector to be worth researching. [no section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Forterra (LON:FORT)
220p (pre market open)
Market cap £468m
New CEO found - Neil Ash, who has relevant sector experience. Handover not until Q2 2023, as previously announced, so looks amicable.
Forterra plc (the 'Group'), a leading UK producer of manufactured masonry products, provides this trading update for the ten-month period ended 31 October 2022 (the 'period').
This falls within FY 12/2022.
Robust trading, FY22 expectations confirmed
Sales volumes in line with LY.
Revenue up 23%, driven by selling price increases - this looks very strong - although it obviously hinges on what the extent of cost price increases are -
Group revenue in the period was 23% ahead of the prior year driven by selling price increases implemented on 1 January, 1 April and, most recently, 1 October when we raised the majority of our brick prices by a further 16.5%. We continue to act decisively to recover ongoing cost inflation and we have notified customers of further necessary price increases effective 1 January 2023.
Production capacity constraints & “record low inventory levels”.
FY 12/2022 in line with mgt expectations.
Energy costs - probably the main concern (along with potentially weakening demand) for this type of share - but we’re not told anything about energy costs here, just that supply has been negotiated (but not on what terms) -
We have secured almost 90% of our energy requirement for the remainder of 2022. We have recently secured further 2023 positions and have now fixed approximately 60% of our full year 2023 gas requirement, (increased from c45% at the time of our last announcement) with Q1 currently c85% covered.
Factories - new brick factory at Desford is starting up, with first customer orders to be fulfilled in early 2023, then production scaling up during 2023. Capex budget of £95m expected to be met. Wilnecote factory closed in Sept 2022 as planned, for a 13 month refurbishment. Intended to diversify product offerings away from volume housebuilding.
Share buyback - quite significant, £40m has been spent, reducing share count by 15.8m to 212.8m.
Net bank debt of £23m at end Oct 2022 - this is very modest for the size, and profitability of the business.
Outlook -
"Trading remains robust although we are watchful of the impact of the recent instability in financial markets and the reported negative impact this is currently having on the housing market. The Group enters this uncertain time in a position of strength having a strong balance sheet with low levels of debt and high levels of cash generation. Inventories remain at record low levels and despite the current uncertainties we remain well-placed to mitigate the effects of a softening of demand by substituting imported bricks with domestically manufactured product."
The last sentence could have been better explained, I’m not sure what that means. Is FORT currently importing bricks due to shortages? Or does it mean displacing competition from imported bricks brought in by other companies? This is clarified by looking back at the commentary with the last interim results, which said this (sounds good to me) -
Despite recent and ongoing capacity investments, UK brick manufacturers presently lack the capacity required to meet demand, with current domestic production capacity of c.2.1bn clay bricks per annum still lower than the pre-financial crisis figure of 2.6bn. Brick imports have increased to record levels being c.25% of UK consumption in the five month period to May 2022 compared with c.19% in the whole of 2021 with bricks being imported from greater distances with increasing transport costs in order to satisfy demand.
The UK's island geography, coupled with similar cost bases and inflationary pressures in continental Europe, also provides an economic barrier to entry with the increasing cost of transportation ensuring that imported products continue to stand at a significant cost disadvantage to those manufactured domestically.
Our customers regularly inform us that they would prefer to buy UK manufactured bricks with assured provenance and quality from stock without reliance on long and fragile supply chains.
These market dynamics leave us ideally placed to substitute imports with bricks from the new Desford brick factory which, upon commissioning at the end of this year, will be the largest brick factory in Europe offering market leading efficiency.
Balance sheet - as usual, I always like to check financial strength, especially at the moment, as we go into a recession of unknown severity & duration.
The last balance sheet was reported as at 30 June 2022, and looks good. NAV of £231m turns into NTAV of £215m if we deduct £16m of intangible assets. NTAV is almost entirely made up of fixed assets, of £219m (PPE), which the company essentially owns outright, with only modest net debt noted above.
Overall then, this looks a very soundly financed business, so I have no solvency or dilution worries at all, even in a recession.
Also bear in mind its main customers are volume housebuilders, which are extremely well financed generally, with little to no debt. Hence the risk of customer insolvencies is close to zero, even in a downturn, in my view. Hence all good. This is very different to some previous recessions, where housebuilders were on their knees, due to debt, and write-downs.
My opinion - this company looks very interesting. It looks to be in a good position, with a shortage of bricks, and imports being more expensive, so could be displaced if demand overall declines in a housing downturn which is looking increasingly likely (housebuilders are reporting softening of demand, as I would expect given the macro picture). There’s obviously then a lag between a housing market downturn, and builders possibly slowing down production. Or they might carry on, and just reduce prices, who knows? They’re so well funded this time around, that I don’t necessarily see any imperative for builders to stop or delay projects, as I can remember happening in the past, but it depends on lots of macro factors.
The balance sheet is strong. I also like that it has been able to pass on cost increases with a series of quite large price rises.
I suppose the main downside risks might be demand falling more than expected, prices softening, and energy costs remaining a problem. These negative factors seem already priced-in to a forward PER of only 9.0, and a forecast divi yield of 6.3%.
Overall, it’s starting to look tempting, for investors prepared to ride out a recession, or at least to monitor more closely, so it’s going on my watch list.
The recent sharp dip could be the start of a buying opportunity possibly, for the brave!
.
Van Elle Holdings (LON:VANL)
45.5p (up c.2% at 08:42)
Market cap £48m
Van Elle Holdings plc (AIM: VANL), the UK's largest ground engineering contractor, today provides a trading update for the six months ended 31 October 2022 (the 'Period').
The current financial year is FY 4/2023.
This is encouraging, although note the profit margin is quite low -
The strong momentum in trading achieved from the start of the year through to the update at the time of the Company's AGM, continued through the remainder of the first half of the year. All divisions operated at high activity levels, with significantly increased revenues delivered in Housing and General Piling. As a result, the Group expects to report record revenues for the period of approximately £81m, representing an increase of 35% on the prior year comparative (HY2022: £60.1m).
Profit before tax is expected to exceed £3.0m for the Period (HY2022: £1.9m).
Increased costs - this sounds reasonable, and similar to what lots of companies are saying at the moment. Also, VANL has previously flagged cost pressures, so nothing new here -
Although there has been some easing in supply chain disruption during the Period, inflation, and in particular wage, fuel and materials costs have continued to impact the Group's cost base. These are substantially mitigated through contract price mechanisms as far as possible, however in some cases there is a lag in recovery.
Order book - up 26% to £49m. A big £13m contract win was previously announced on 10 Oct 2022.
Net cash of £3.5m (excl. lease liabilities)
Balance sheet - looks solid, with NAV of £46.6m when last reported at end April 2022. Deducting £3.8m intangible assets, gives NTAV of £42.8m. This is nearly all property, plant & equipment, as I would expect for this type of business. The rest of the balance sheet looks fine to me, so no issues, and little to no dilution or insolvency risk, in my opinion.
I suppose that, in a severe recession, business could dry up, so that might be an issue. So if you’re taking a very negative macro view, then this type of share is probably best avoided right now.
Outlook - this sounds reassuring -
Whilst recognising the current economic uncertainty in the UK, strong activity levels are expected to be sustained through the second half of the year, despite the winter months which traditionally deliver lower activity levels due to weather disruptions.
The Board is pleased with the progress made in the first half of the year and anticipates trading for the full year to be slightly ahead of market expectations.
Forecasts - there’s no footnote to say what market expectations are. I see Peel Hunt is the NOMAD, who are private investor unhelpful, in my experience. The buyers of these small cap shares are going to be private investors - we create the liquidity & set the price. So having a NOMAD that actively prevents PIs getting hold of their forecasts, seems to be a NOMAD that is not doing their job properly. Thankfully Zeus have issued an update note today, to keep us informed, so many thanks to them for filling that gap.
Zeus has upgraded forecast Adj PBT from £4.8m to £5.2m for FY 4/2023.
That is 3.9p diluted adj EPS, giving a PER of 11.7 - that looks fair.
My opinion - this looks a decent business, not madly exciting, sensibly priced.
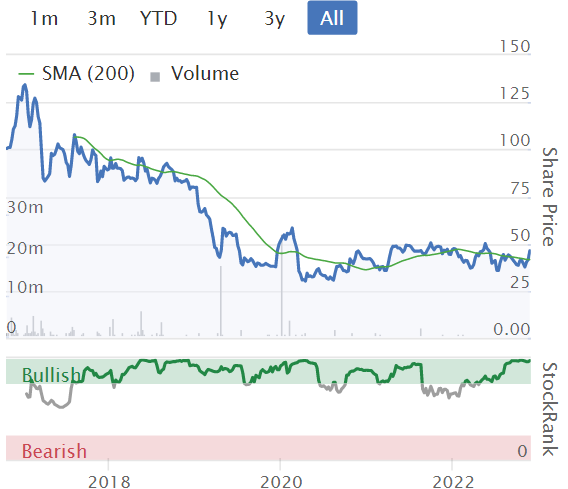
As with so many floats, it seemed to list on AIM (in Oct 2016) at a bloated valuation, after a couple of good years, then profits subsequently plunged (before the pandemic created further turmoil). Hence overall it’s been a disappointing listed share, generating a negative total shareholder return to date.
The current valuation looks about right to me, which isn’t good enough at this stage of the economic cycle (going into a recession). I’m looking for cyclical companies/sectors to be dirt cheap (e.g. housebuilders), to reflect the uncertain/negative outlook. My worry is that, whilst current trading & outlook might sound fine, there could be a time lag before new projects begin to reduce. After all, higher interest rates mean that new building projects have more challenging economics, and in times of uncertainty, some companies defer or cancel big property projects.
On balance then, VANL looks an OK company, but I cannot see any compelling reason to get involved with its shares.
Note that the StockRank score has been high since VANL listed, so the computers obviously see something good here.
.
Graham’s Section:
AO World (LON:AO.)
Share price: 59.9p (+14%)
Market cap: £345m
This is a stock I’ve loved to hate over the years: a profitless box-shifting business with an evangelistic CEO who describes his employees as “AOers” and talks about the “One AO” model and “the AO Way”.
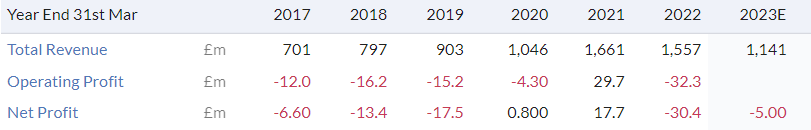
Profits have been a rare event, despite soaring revenues:
But today’s interim results are unusually positive:
The six months to September 2022 represented solid progress in the plan to pivot the business to focus on profit and cash generation. As a result, FY23 sales are forecast to be within the range guided, FY23 profit is now expected to be around the top end of previous guidance, and guidance for FY24 has been set above current consensus.
It may not sound like it is a radical plan - to focus on profit and cash generation - but in an AO context, it is!
Paul covered the company’s £40m equity placing in July. The new strategy, as announced at the time, was to cut costs and simplify the UK business, for an estimated £25m in benefits by FY 2025. This would enable an EBITDA margin of 5%+ (still very low) and a modest capex bill of c. £5m.
Key points from today’s interim results:
- Revenues down 17% (the combination of a smaller overall market and AO World no longer selling items at a loss, and removing non-core channels).
- £17m reduction in SG&A. Now looking for £30m in total cost savings by FY 2024.
- Adjusted EBITDA margin 1.6%, still unacceptably low, and a pre-tax loss of £12m.
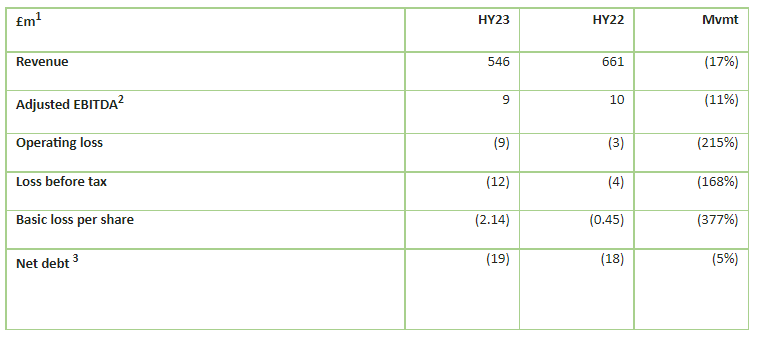
Net debt reduces to £19m (from £33m) but don’t forget that the company raised £40m (gross) from an equity placing in July. It’s clear now that if the company hadn’t raised new equity, it would have been in a perilous situation.
Going concern: the company has available liquidity - cash plus RCF headroom - of about £70m and therefore believes that it’s a going concern, even in “severe but plausible” downside scenarios.
The going concern note acknowledges that the company has net current liabilities (current assets minus current liabilities) of £71m. This is traditionally considered to be a source of danger.
Operationally, the key points are:
- The German operation is shut down at last, and the cash costs of doing this have fortunately turned out to be none.
- No longer working with Tesco or housebuilders.
- Eliminated 158,000 square feet of warehouse and storage space!
- Reduced headcount in middle management and senior management.
With respect to customers:
- AO is now charging for delivery for all orders, and has reduced cashback incentives.
- Net promoter score unchanged at 86, Trustpilot rating unchanged at 4.6/5.
- AO’s market share in appliances is unchanged at 18%, and its online market share increases by 2% to 34%.
It might be surprising that AO’s market share went up despite its revenues going down by 17%.
It turns out that the online appliances market shrank by 18%, I guess due to post-Covid shopping patterns and economic conditions. Therefore AO can grow its market share even while its sales are shrinking.
Note that sales are still up considerably compared to pre-Covid: revenues for H1 in FY March 2020 were £470m (versus £546m announced today).
Outlook
It’s a fascinating outlook statement: the company has finally decided to stop selling pound coins for 50p.
The whole of the electricals market is down year on year and in light of this we continue to have a laser focus on profit and cash which will see us driving only profitable sales and channels. We have initiated a number of cost reduction initiatives during the first half of the year which will see the cost base of the business reduce, giving an annualised run rate saving of at least £30m in FY24 vs FY22. We will continue to ' right size ' our cost base to market conditions and outlook.
The consumer environment is “challenging and uncertain”, and there are “ongoing supply chain issues”. But, thanks to the new strategy, AO is now looking for full-year adjusted EBITDA around the top end of the range of previous guidance, £20-30m.
With faster and larger cost cuts than previously anticipated, AO wants to hit its 5% adj. EBITDA margin target in FY March 2024. That would produce adj. EBITDA of up to £60m.
How much of that will feed through to reported net income? I’m unsure.
My view
Like Paul, my view on AO has changed with its change of strategy.
In the past, I viewed it as a company that was being run ideologically, primarily for the benefit of customers and with zero regard for shareholders (which was unsustainable, because it was eventually going to run out of money).
The new strategy seeks to make a profit on every sale (!). The non-profitable sales channels have been abandoned. The international operations are shut down. Products that generate no margin are gone. Middle managers have been let go. In short, this is now an investable business. It’s now a company that we can take seriously.
What hasn’t changed is that it’s still very much a low-margin box-shifter, but at least it’s working very hard on improving its margins. An adj. EBITDA margin of 5% would still be very low but at least it would be something to work with.
At the same time, we must bear in mind the lack of current profitability and the likelihood that even at a 5% adj. EBITDA margin, the reported net profit margin would be much lower.
Additionally the balance sheet could be stronger, despite the £40m fundraising that helped to plug a hole this year.
Therefore, the path from where AO is now, to justifying a market capitalisation of £300-350m, still looks like a long one to me. But it’s at least possible, under the current strategy, that it could do it.
In the past, I’ve been a short-seller of AO. I wouldn’t dream of short-selling it now. Not when it’s actually being run to make a profit and already has tangible achievements on the way towards sustainable profitability.
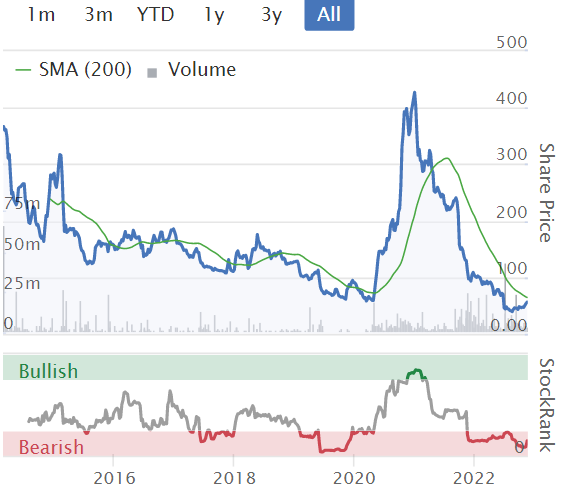
Carr's (LON:CARR)
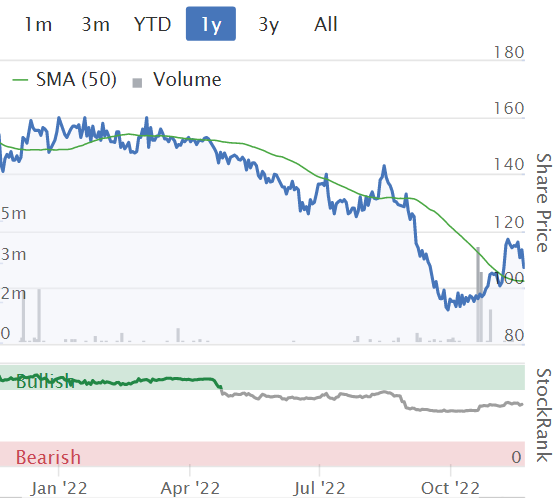
Share price: 106.5p (-6%)
Market cap: £100m
Two parts to today’s announcement.
1. Trading update
Performance since the last update in early August has been strong and the results for FY August 2022 are in line with expectations. Likewise, the performance in the new financial year is in line with expectations.
The company should be in a net cash position now, having received nearly £25m for selling its shares in Carr’s Billington. This disposal was covered by Paul here.
2. Audit status
This audit problem relates to one of the companies forming part of Carr’s Billington. This company is referred to as “CBAO”.
The problem relates to who should audit CBAO, from the perspective of Carr’s Group.
Grant Thornton, the new auditors for Carr’s Group, wanted to rely on the work done by CBAO’s statutory auditors.
But it turns out that they can’t do this:
While the audit undertaken by CBAO's statutory auditors is near completion, it has been determined that, for independence reasons, GT can no longer place reliance on that audit. As a result, a separate audit of CBAO is now required for the purposes of completing the Group's FY22 audit process…
I don’t fully understand why this has suddenly become an issue now. Why did the previous auditors at Carr’s not also face this problem? I’m guessing that it’s because of the disposal, and because the buyer of CBAO is a related party.
As the group results will now be very late, shares in Carr’s will have to be suspended from 4th January. Publication of the results is expected in mid-January, when Carr’s will request that trading in its shares is restored.
My view
Even though Carr’s Billington is no longer part of Carr’s, and CBAO was not a particularly large part of Carr’s in the first place, I can understand why some shareholders would want to get out of this stock today.
Firstly, this problem hints at a lack of organisation (although it’s not clear who, if anybody, is at fault - Carr’s management, their auditors, their previous auditors, or someone else).
Secondly, it means that shareholders will have to wait an unusually long time to get audited results for FY 3 September 2022 (i.e. almost FY 8/2022). That’s inconvenient, and potentially creates an information gap.
Thirdly, the prospect of being unable to trade Carr’s shares is an unpleasant one. There is always the possibility of further delays, so that investors who want to get out in the short-term are unable to do so.
I assume that nothing nefarious has taken place. It looks like a mildly annoying case of delayed results, and nothing more serious than that. It’s reasonable for CARR shares to sell off by a few percentage points today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
I appreciate Digital 9 Infrastructure (LON:DGI9) the digital infrastructure Investment Trust is a bit large for the SCVR but as it is an interesting area for the future I wondered if anyone had any views on today's 10% fall in share price. It seems to be related to the postponement of a Capital markets day following the departure of two members of the digital infrastructure team within the investment manager Triple Point. The people involved have only been with Triple Point for less than a year and just over a year so this could be an over-reaction unless something lurking in the background. May be an opportunity to buy more shares at decent discount to NAV?
Sorry its a little late Guys....I caught this Director buy a little late in the day but thought I would flag it in as its the million pound mark.
Knights group (LON:KGH) I was on the fence about the turnaround happening with Knights when reading the RNS his morning, but that's some serious skin in the game from the CEO, so that's tipped me in to this one. If only other CEO's would but there hands in there pockets and get behind the shareholders, instead of all these bloody handouts!
Debt a bit high for me (£35.6m) but if the predicted profits flow through then its much less of a worry. Forward P/E of 4ish with an EPS growth predicted 45.4%, looks excellent. It would appear that the EPS got hacked earlier in the year which sparked a big sell off, but I can see a good bit of upside from here.
Alliance news reports
'Knights Group Holdings PLC - Newcastle-under-Lyme, Staffordshire-based legal and professional services - Chief Executive David Beech buys 1.2 million shares at 83.9 pence, worth £995,024, on Tuesday.
Knights Group earlier Tuesday said profit and revenue increased in the first half of financial 2022, as its prior year acquisitions are ‘performing well’. Pretax profit was £https://www.stockopedia.com/#9.0 million in the six months that ended October 31, up 18% from £7.6 million a year before. Revenue increased to £71 million, up 18% from £60 million.
Current stock price: 81.00 pence, up 0.3% on Tuesday'
12-month change: down 80%
EDIT
The share price has already quiet rightly responded to this News.
(I now Hold)
Hi Floating Investor - well done, that's a good spot! I'm taking a closer look as we speak, re £1m purchase by Knights group (LON:KGH) CEO
Floating Investor, Thanks for flagging this one up. It does show a significant vote of confidence from the CEO and I'm tempted to follow him in. It's worth pointing out though that the same director cashed in shares to the value of £61m last year. Now that is a lot of money!
Hi Gnome2,
Yes I've just spotted that too, about the previous £61m CEO share sale. Looks like he's a shrewd judge of whether the share price at Knights group (LON:KGH) is priced to buy or sell!
I'e mentioned this briefly in tomorrow's (i.e. Weds) SCVR.
Regards, Paul.
Stocko shows him buying a £million worth back in May too
Intercede (LON:IGP) released HY results today. In-line with market expectations, and already flagged in an earlier trading update.
However, there is an interesting FX play here. Intercede's cost base (mainly headcount) is in GBP. But 86% of its revenues are from the USA (assumption is they charge in USD?)
If they do the same revenues in H2 as in H1 (£6.1m) but get a 7% FX benefit that falls straight to PBT, that is an extra £367k PBT. H1 reported PBT was only £620k, so an extra 59% PBT growth, HYoHY!
However, my quick skim of the HY results, my initial impressions is that they haven't made much progress in securing many new contracts, and it looks like organic growth in H2 is likely to be muted. Management are busy/distracted with the new Authlogic acquisition, and they seem to see that as the magic bullet for growth, and not pushing organic growth of their existing products. So am skeptical of the growth prospects. But the pricing at the moment still seems fair, given the highly recurring nature of their revenues, the FX benefit to come, and the solid balance sheet backing it, as well as a potential growth engine in the Authlogic acquisition.
But those are just initial thoughts based on a skim.
(I hold in the Boon Fund)
Mulberry (LON:MUL) could be in play. Had a big run-up recently.
BUSINESS
Burberry Taps Heritage to Become a British LVMH
https://www.washingtonpost.com/business/burberry-taps-heritage-to-become-a-british-lvmh/2022/11/17/9e25fb1c-666a-11ed-b08c-3ce222607059_story.html
Trifast (LON:TRI) Paul wrote about this a month ago, here. H1 figures published today, and as expected not good. Paul said starting to look cheap. Cheaper now. Operating profit% catches my eye. A pity, I like companies that make things (a weakness of mine).
change
Hi MichaelC,
That's strange, £TRI interims didn't come up on mine or Graham's newsfeed this morning.
I've just done a quick skim of the H1 numbers, as you say they're not great, but it's still profitable. Balance sheet & cashflow - I do have a concern here that inventories seem to be relentlessly growing and now seem excessive - with the balance sheet showing £102.8m inventories (at cost), which is more than 6 months cost of sales (£90.7m), a red flag I think that it might have problem levels of inventories, with possible write-offs being required at year end? It's only a risk, I don't know if that will happen or not.
Outlook comments sound reasonable - expecting an improvement in recovery of cost increases, so better H2 margins. Oct & Nov 2022 trading said to be in line. Short term uncertainty.
Could be getting decent value in a long-term view, but who knows where the short-term bottom is likely to be? Same with lots of shares right now.
Regards, Paul.
Interesting comments re Forterra (LON:FORT).
I also had a quick look at CRH (LON:CRH) this morning. Its down on what I thought was an OK statement. I do remember getting interested in Ferguson (LON:FERG) ( was Wolseley at the time) a bit early in the 01-03 recession but it was on 11--12x at the time....and did well enough until GFC. These stocks have the repair and maintenance exposure that helps in a downturn.... if indeed we have a volume downturn? This is the Q IMO...clearly house prices will be affected by the interest rate rises that are passing through the system. The builders have stepped off land purchases and reservations are down. Obviously the banks pulling fixed mortgage deals in Autumn hasn't helped. I can see a world where volumes hold up actually.... but I think the market will be nervous. Also Ukraine rebuild could further tighten supply chain. The US stocks are cheaper than these EU counterparts and have a similar structural demand story around housing. Mortgage rates are higher though and the market under more pressure. Ironically in CRH (LON:CRH) the US numbers are much better ... showing no signs of stress compared to Europe which is weak. What do we make of all that.... ? Its a bit of a dogs dinner and doesn't tell us much about UK bricks but on balance... despite attractive PEs do you need to be early? probably not.
I supported Ibstock (LON:IBST) at IPO and we liked UK bricks at the time mainly due to lack of capacity ....although this is slightly double edged since their growth options are somewhat limited which has always held back the ratings. Personally I prefer building materials for a broader infrastructure exposure over bricks... and so Breedon (LON:BREE) is also worthy. Im happy to keep them all on the list... guessing its still a tad early.
Crestchic .
Had a quick visit yesterday to see progress with the new facility.
Met by the FD quick blast round . Quick summary below
1/ Asked if he was up for engaging with PI in small groups (ie any Stockopedia) and said “absolutely that would be great”
2/ Asked if leadtimes had come down and were now market leasing due to the increased capacity - said they came down at first but orders as so strong that lesdtime is back to normal (4-6 months )
3/. Asked which markets doing well says US very strong and bulk of sales export to USA
4/. Asked about what is the actual value of loadbanks on the asset register over 10 years (they are written down to zero) but didn’t get a vakue but I think it is quite significant
5/ “old” facility looked much improved as bigger units are now processed over fhe road in new unit .
6/. Asked about some recently heavy share sales and who was selling down and he said it was Camacord who have been reducing from 10% over the past year. Both surprised no RNS
7/ Asked about Harwood having a high holding and if they had a seat on board, said Nick Mills on board and they were very supportive .
8/ Asked about disposal of Middle East Tasman operation, still dragging on but days away and Middle East red tape
9/ Talked about new facility , it’s current capacity , and staffing . They are at 50% efficiency , to get to 100% need to recruit and train 10 more -which does take time . But facility looks very efficient and there were 8 big koad backs in production (think these are 300k each and going to usa ?)
10/ Talked about this years operational improvements and the COO recruited from rolls Royce in January seems to having a huge impact .
11 /. Asked when next update would be said probably February but could be one early December .
12/. Asked about top company structure as no CEO which I though unusual but Peter Harris is a very active chairman who send to fill part this role very ably and is very committed .
Finally the little things sometimes tell you the most and the few staff I spoke to including the lady at reception all seemed very happy to be there and the “feel” was a good company in a good place with good people .
Nice one, a December update would be nice...
Thanks for the report Dave.
Excellent work.
Very interesting planetx thankyou.
Thank you - very interesting. I consider Crestchic one of my absolute core holdings given its in a strong upgrade cycle, pretty cheap for the growth on offer in a structural growth industry.
Hi PlanetX
Sounds very positive. Thank you for the insight into the company's on-site operations. Such 'nuggets' are not usually available to the private investor. I made a reasonable investment recently and my impression from watching the company presentation on VOX markets and generally from the imperative of ensuring the integrity of back-up power supplies is that there is a reasonable prospect of a further upgrade, possibly in December.
I admit to a bias and try to temper this by acknowledging that things can go wrong, but I believe the balance is towards the upside. Time will tell.
Planetx - £LOAD - Interesting site visit update with a number of positives. Also curious to hear that Crestchic could issue a trading update in December, because last year this was in mid-January.
There is research to suggest that companies beating analysts expectations, like to get news/results out earlier than the previous year, (and conversely later with bad news). Its human nature I suppose. I hold.
Surprised nobody is talking about AO World (LON:AO.) today :)
AO World (LON:AO.) I'm not buying the SP increase and management waffle, they could hardly make money with the COVID boom and prior to that were loss making, and the next year or two is going to be very different in terms of a white goods squeeze (sounds a bit naughty :D).....I like the logo, but that's about it...(I'm short)
I also like the logo, and their customer experience from website to delivery to aftercare, having shopped with them several times now. By far the best online retail experience I've had. Long term I can see them continuing to take market share and becoming number one in electricals plus appliances.
If they hit their target of 5% EBIDTA at current revenue levels and £300m market cap they're trading at a 20% EBIDTA yield. I suspect revenue will be much higher by that point too. Looks very promising to me if they can execute, and if so, it's onwards and upwards from that point.
Whatever AO World (LON:AO.) are achieving, wouldn't you rather Marks Electrical (LON:MRK) with nearly double the margin and free delivery built into that margin (a nice customer incentive) and a market share which is growing even faster?
No because of the red flag from their employee reviews
Thought it was Tuesday today..... but thanks Paul for the write-up on Forterra (LON:FORT) which I hold and may well add to now.
Hi Silver Moon,
Thought it was Tuesday today.....
I was wondering who would be the first to spot that! ;-)
Regards, Paul.
exciting stuff if we get tomorrows trading updates before close of play today - that would be handy.
Any predictions for updates tomorrow should be detailed in comments no later that 4.29 pm today - lets see who really can read them tealeaves.
over 500 reads already!
CentralNic (LON:CNIC) another great set of results today with continued growth and technology that seems to put this company in a sweet spot, trading inline with recent upgraded guidance (upgraded six times since 2021), revenue up 88%, Net revenue/gross profit up 53%. EBITDA doubled.
'Its unique cookie-less marketing platforms are taking market share, the company’s scalable business model is converting high growth to strong margin expansion and its recently negotiated debt facility and strong cash conversion support further earnings accretive acquisitions.'
No dividend all growth this one but the P/E seems very low IMHO (FWD P/E 8.1). Well worth a look at the technology here and a good update from Zeus on research tree.
These privacy laws on cookies are the driver behind this companies current success.
Should rerate today, maybe its the lack of dividend in the current market conditions, or perhaps doubt that the significant upgrade could be achieved, but appears to be performing well.
(I Hold)
The only problem with CentralNic (LON:CNIC) is they do not have any equity, in fact they have huge negative equity. So you're not actually buying anything tangible. They will need to do a big write-down at some point to get them intangibles down.
I would love one day to hear Graham or Paul's thoughts on a CentralNic (LON:CNIC) update and the company more generally to understand if we are all missing something re the low valuation and high growth.
Debt is an issue here and the current ratio was less than 1x recently, and maybe there is market scepticism about the outlook for marketing and advertising which tends to be the first thing cut by companies in a recession. Another "negative" is the broker estimates for next year look fairly modest (single digit percentage growth) against current year so they are also sceptical about whether the fast growth can continue (maybe this will re-rate the share if Q1 of FY23 is strong?)
I remember someone on Twitter selling up because they felt there were too many adjustments to the profit figure and the actual profit was far below the adjusted level. However, when i tried to go through the adjustments most seemed OK to me although I did do it pretty quickly and meant to go back and have another go.
Edit: I see Zeus have lowered their EPS expectation for this year from 20.9c to 19.1c 'largely due to higher tax resulting from the growth of the Online Marketing division in Germany, where the company has limited tax losses but is pursuing additional tax planning' so that may weigh on sentiment today. Even with this change it's still on a p/e of 8!
Further edit: I am sharing this sceptical comment on Twitter this morning from @F15JCM in case it's helpful food for thought. i'll try and look at this in more detail later on: 'Accounting loss has more than doubled in 3 months. Increased from £8.1m at interims to £17.6m at 9m, driven by FX movement. Shareholder equity down £8.2m in 3m period'
Hi Patrick
Jack at the time held this share and wrote a favourable report about CentralNic (LON:CNIC) back in May this year, with a share price back then above where it is now, which pretty much sums up sentiment.
I think you could well be right about the marketing aspect with a looming recession, holding back the SP.
Am happy to hold bar a major fall in share price.
I for one would prefer to keep Twitter off of SCVR if possible, because that just opens the floodgates to all sorts of s%%t getting put on here, but I do appreciate your own valued input.
I've never known what to make of CentralNic (LON:CNIC) - poor results for years, then suddenly enormous profits seem to have appeared out of thin air. Although taking all costs into account, including high tax charge, there's very little profit left at the bottom of the P&L.
Balance sheet looks awful, highly geared under new facilities, and dominated by intangible assets, big negative NTAV.
Lots of acquisitions.
Not sure I can add much by doing more digging on this one, it makes me nervous, so not something I would want to invest in personally. Also I don't understand the business model.
Good update from Van Elle Holdings (LON:VANL) (I hold) . Record half year numbers and full year to be slightly ahead of market expectations.
Seems to be on target for my personal FY 2022 forecasts.
Telecom Plus (LON:TEP) pre tax profit £95m previous forecast £84m dividend 80p previous forecast 74.7p.
are we nesting peak profits with this one?
nearing I mean!
I think it's all to do with their customer base, if they keep increasing their signups then they increase their profit. When energy prices go down they might lose customers as their energy rates are not the cheapest. The comparison sites are showing Telecom Plus (LON:TEP) as an option (which may explain their increase in customers) not because they have cheaper rates, but because you can save money on their other offers.
CML Microsystems (LON:CML)
Interim results out. Not cheap with a PE of 26 but trading ahead of forecasts with a 24% increase in profits, cash of 22m and no debt.
Very positive statement which in todays climate is a nice change.
“The strong progress made in the six months to 30 September 2022, coupled with the increasing opportunities within the market for organic and acquisitive growth, gives the Board a great deal of confidence as we continue to deliver value to our shareholders.”
Morning all,
Excellent Q3 update from £CNIC. Whether finally the positive news flow may finally be reflected in a rising share price !
I hold.
Probably up and then flat on the day, like most good updates
It all looks really good from what I can see. Significant revenue growth and profitability allowing acquisitions to fuel more growth alongside organic growth. What am I missing?
I worked a while back for a unicorn/decacorn software company who had lower revenue/profitability and growth compared to CentralNic (LON:CNIC) but was valued at $13bn. I am not suggesting thats the valuation of this but it does seem hugely undervalued
its because they have negative equity.
CentralNic (LON:CNIC)
It’s because they have negative equity
This certainly, but it is massively outperforming both tech and adtech sectors, where every other company seems to fall on each TU. By contrast CNIC has held steady all year. Holders need to be patient.
Paul... it's Tuesday (not Wednesday)
In these woke times it could easily be Tuesday for Paul and Wednesday for the rest of us!?!