Small Cap Value Report (Tue 23 Jan 2024) - AWE, BMK, ELCO, HAT, MARS, BOOT

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Agenda
Companies reporting today -
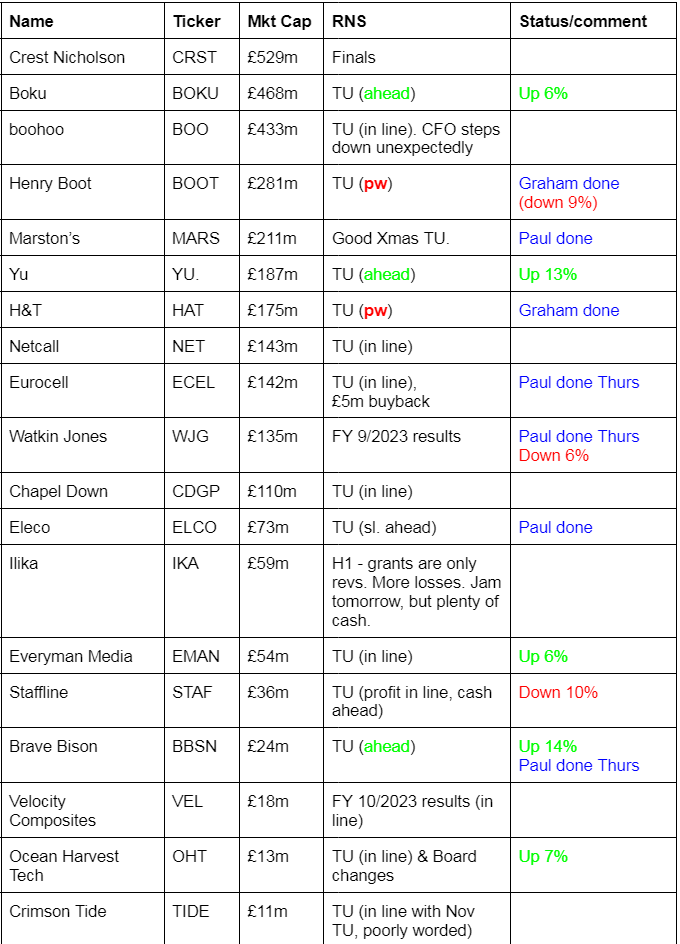
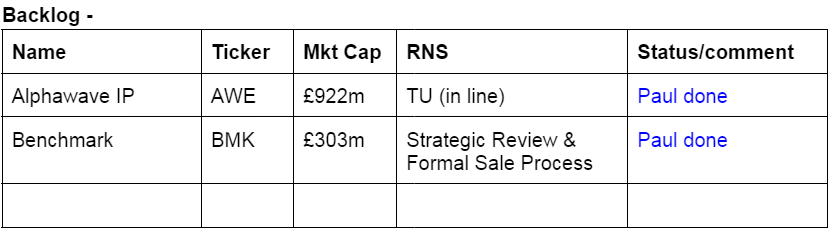
Other mid-morning movers (with news) at 10:25 -
Cornerstone FS (LON:CSFS) - up 9% to 38p - deal with Mastercard to launch corporate cards in Q3 2024.
Big Technologies (LON:BIG) - up 9% to 114.5p - CEO buys 300k at 106.5p, total held 73.4m (25.3%), recent PW.
Esken (LON:ESKN) - down 48% to 48% - serious dispute over £194m conv loan. Equity worthless possibly?
Summaries
Alphawave IP (LON:AWE) - up 16% y'day to 134p (£961m) - Trading Update - Paul - RED
My first review of this (one of many) disastrous 2021 floats. I don't understand its products or tech, but I can see plenty of flaws in the figures. So it's not for me. I think this chip designer needs to establish a more reliable track record of profit/cashflow before it can be viewed positively here. Shares bounced strongly yesterday on an in line 2023 trading update. Will any of the $87m EBITDA turn into cash though? It didn't in H1, which was heavily cash consuming.
Benchmark Holdings (LON:BMK) - up 17% y’day to 41p (£303m) - Strategic Review & FSP - Paul - AMBER/RED
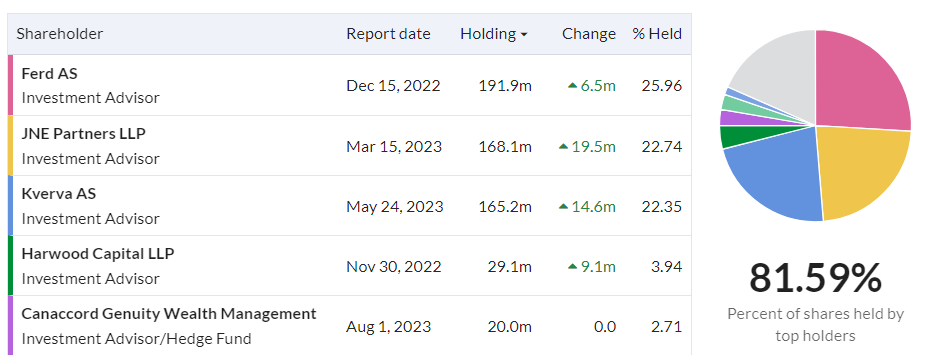
Puts itself up for sale, as management think shares are undervalued. I'm struggling to justify a valuation anywhere near the existing high price, given its years of losses, and indebted balance sheet. So it will be interesting to see how this pans out. 3 major shareholders hold almost 3/4 of the equity, so it's quite illiquid.
Eleco (LON:ELCO) - up 5% to 91p (£76m) - Year-end trading update (slight beat) - Paul - AMBER
Slightly beats 2023 forecast, but that's come from trimming costs, as revenue is slightly below forecast. About half the growth is coming from acquisitions. Balance sheet has plenty of cash thanks to favourable up-front payments by customers, but balance sheet overall is slightly negative NTAV. Overall I think it looks a nice enough business, but as mentioned before, fully priced for now, hence me sticking at amber. Could grow into the valuation though, if forecast growth is achieved or beaten.
H & T (LON:HAT) - down 15% to 339p (£149m) - Trading Update (profit warning) - Graham - GREEN on fundamentals, BLACK (profit warning flag) for spreadsheet
H&T reveals that December was a tough month for it from a retailing perspective, as buyers chose cheap, low-margin new items over more expensive pre-owned items. I remain a fan of this company and see an opportunity here at 6x earnings that warrants further investigation.
Marston's (LON:MARS) - unch 33.3p (£211m) - Trading Update (AGM) - Paul - AMBER/RED
A laggard whilst sector peers have rerated up. However I soon discover why, as this is a special situation with a debt mountain that consumes all the cashflows. Hence no divis, and worries over refinancings. That said, trading in 2023 and YTD FY 9/2024 has been good, with decent +8% LFL so far this year. The equity is only a fraction of the debt, but it has a big estate of property assets. I think somebody might bid for it. Elevated risk from the debt mountain though, so a tricky one - special situation really.
Henry Boot (LON:BOOT) - down 10% to 190p (£255m) - Trading Update (profit warning) - Graham - GREEN on fundamentals, BLACK (profit warning flag) for spreadsheet
It’s a dose of bad news for Henry Boot investors as the company now expects its end markets to take longer to recover. It’s frustrating as the macro indicators have been moving the right way. But the stock may still offer a decent proposition over the medium-term.
Paul’s Section:
Alphawave IP (LON:AWE)
Up 16% y'day to 134p (£961m) - Trading Update - Paul - RED
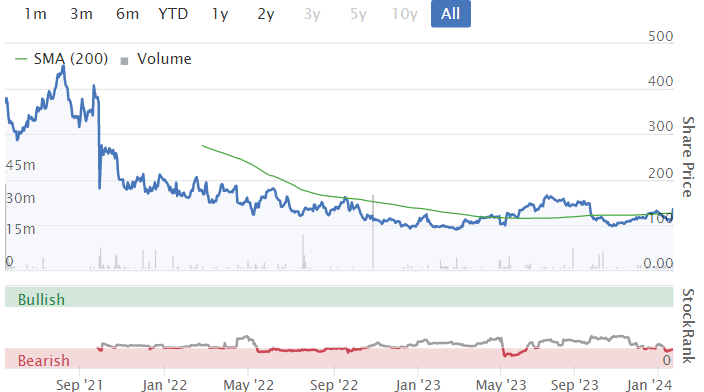
This is a new company for the SCVR, so it will be good to get something into our system here. It was a £3bn 2021 tech float at 410p/share, so obviously the shares have plummeted since. Note the prospectus says selling shareholders took out £495m in the IPO. Still, it doesn’t seem to want to go below 100p more recently, maybe a base forming here?
Note that the rot seemed to set in after the FT published a critical article in Sept 2023 about alleged undisclosed related party deals, which the company denied here.
What does it do? Search me! Press articles describe it as a “chip designer”. This is the company’s self description today -
Alphawave Semi is a global leader in high-speed connectivity for the world's technology infrastructure. Faced with the exponential growth of data, Alphawave Semi's technology services a critical need: enabling data to travel faster, more reliably and with higher performance at lower power. We are a vertically integrated semiconductor company, and our IP, custom silicon, and connectivity products are deployed by global tier-one customers in data centers, compute, networking, AI, 5G, autonomous vehicles, and storage. Founded in 2017 by an expert technical team with a proven track record in licensing semiconductor IP, our mission is to accelerate the critical data infrastructure at the heart of our digital world. To find out more about Alphawave Semi, visit: awavesemi.com
I don’t understand what the company does, and today’s update very much blinds me with science. So I’m going to purely look at the figures, which I can understand.
I have to get almost to the end of the update today to find something I can lock onto, this bit -
The outlook for 2023 remains unchanged. Alphawave Semi expects 2023 revenue of US$340m to US$360m and adjusted EBITDA of approximately US$87m (or approximately 25% of revenue), which is at the mid-point of the revenue guidance range.
Despite the uncertain macroeconomic environment, our growing pipeline reflects positive secular growth trends in data infrastructure markets and the continued investment in next-generation AI- centric connectivity solutions. This, combined with our talented team and strong balance sheet, give us confidence in our future.
Broker update - I don’t have access to anything, so instead will have a look at the last interim results to get a flavour & compare with the FY guidance above.
H1 Results to 30 June 2023 -
Profit & loss account -
Revenue $187m (up 228% due to substantial “Royalties and silicon” starting - from China)
Adj EBITDA $32.4m
Massive share-based payment of $18.5m in H1, which causes the losses below:
Operating loss $(2.6)m
H1 Loss before tax of $(11.2)m - after $7.6m H1 finance charge due to net debt, plus a $2.7m charge for a loss-making JV.
Balance sheet - at 30 June 2023 -
NAV $487m, includes goodwill $332m and intangible assets $180m, so NTAV is $(24)m.
Net debt of $100m at 30/6/2023 compares with net cash of $452m a year earlier, so where did all the cash go?
Receivables $100m + Accrued revenue (same thing) $67m is equivalent to almost all of H1 revenues, and a lot of those revenues originate in China, so this makes me very uneasy.
Cash of $123m is more than offset by $223m “Loans and borrowings”, so net debt of $100m. Note 18 in H1 results shows this is a $100m 5-year term loan plus an RCF from a banking syndicate.
NB it breached a banking covenant in June 2023, with an amended agreement signed in Sept 2023 relaxing the covenants. Still not a good look. In the going concern statement it blames this on customers paying slowly (higher deferred revenue) and high R&D spending. It gave itself a clean going concern review in June 2023.
Cashflow statement - for H1 2023 is poor, showing it consuming cash. One half year isn’t enough to draw a firm conclusion, but I don’t like the look of this.
Cash generation in H1 was $29m, but then $(60)m was absorbed by working capital, mainly “deferred revenue” creditor which shrank from $92m to $42m.
So operating cashflow was negative $(31)m vs positive $32m in H1 LY. Swings and roundabouts maybe, but it nets off to almost zero, suggesting to me this is not a cash generative business yet.
Then there are further H1 cash outflows, $5m in tax, $13m capex, $25m in capitalised development spending (just in H1), and $4m invested in a JV.
Overall, cash was considerably depleted from $186m to $123m, and borrowings increased a little too. Not a pretty picture, so an amber warning from me here on negative cashflow.
Paul’s opinion - all I’m talking about here are the numbers, as I don’t have any understanding of what the company does, or its competitive position.
My concerns are -
EBITDA does not turn into cashflow, so far anyway. Note that $32m adj EBITDA in H1 was more than exceeded by capex & capitalised development spend.
Also working capital absorbed a lot of cash, and it seems the Chinese customers are slow payers, quelle surprise! Anything that relies heavily on selling things into China is something I would rather avoid, for a variety of reasons, it often seems to cause problems for UK companies and investors.
The balance sheet is weak, and heavily reliant on bank facilities.
Breaching covenants in June 2023 suggests weak financial controls, and performance not going to plan. So although it was resolved with amendments, it’s a warning I think.
Shareholders took cash out in the float, but it’s still dominated by 2 shareholders with a combined 50.7%, which is too much, especially combined with the China connections.
On the upside, the products/services could be the best thing since sliced bread walked through the door, I have no idea on that. But the numbers alone don’t give me the confidence to want to dig any deeper.
So overall I’m going to view this as RED, based on the facts & figures at this point in time.
Once it’s established a better financial track record of real profits and cashflow, which it hasn’t yet, then I’ll be happy to look at it with fresh eyes in future.
Stockopedia's computers share my unease -
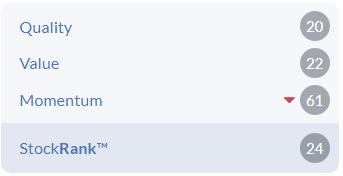
It qualifies for 2 short selling screens, and only 1 long screen -
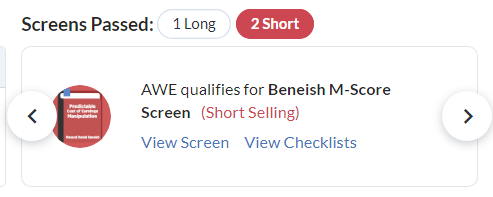
So I think it's clear that both man and machine want to see a longer track record from AWE before getting keen on the shares. The trouble is, we might miss out on a bull run if we sit on the sidelines, so that's the trade off isn't it.
Benchmark Holdings (LON:BMK)
Up 17% y’day to 41p (£303m) - Strategic Review & FSP - Paul - AMBER/RED
Benchmark Holdings plc ("Benchmark" or the "Company"), is a market leading aquaculture genetics, nutrition, and health business, delivering advanced biotechnology products and solutions that enable the aquaculture industry to improve its productivity and sustainability, helping address the need for sustainable aquatic food to feed a growing global population.
The Company is a supplier of choice for aquaculture producers worldwide with market leading positions in genetics, early-stage nutrition and sea lice solutions and well invested infrastructure to support growth. The Company's specialised mission critical products and solutions reflect decades of invested capital, IP and expertise, which the Board believes are very difficult to replicate.
BMK management seem to think its shares are undervalued, and so has put itself up for sale, through the Formal Sale Process under the Takeover Panel rules. So expect a deluge of announcements each day as the disclosure obligations move down to 1% holdings, and changes to positions above that size. I often have to take companies off my email RNS alerts watchlist once offer periods begin, due to the volume of trivial announcements.
It claims a successful financial track record -
Management actions over the last three years have delivered substantial revenue growth and improvement in profitability and cash conversion. Since FY20, Benchmark's revenue from continuing operations has grown from £105.4m to £169.5m in FY23 and Adjusted EBITDA has increased from £15.5m to £35.5m. The Company is well positioned with a strong balance sheet and significant headroom to grow within its existing markets, as well as multiple potential avenues for expansion.
Although it doesn’t actually make any real profits - so I’d say the financial track record has been lousy, and doesn’t even come close to justifying a £300m market cap.
The £35.5m adj EBITDA mentioned above turned into a £12.7m loss before tax. The same thing happens every year - statutory losses, not profits.
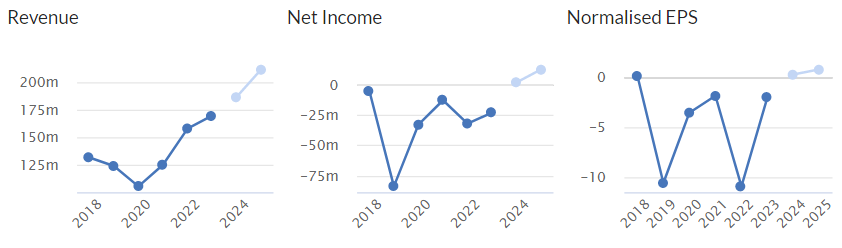
The company says it has a strong balance sheet, but it doesn’t! Net debt was £65.5m at 30/9/2023, which brings hefty finance costs to the P&L.
I don’t understand why it pays heavy taxation, considering it’s loss-making?
Paul’s opinion - this has always been a jam tomorrow company, and I’m amazed investors have been so patient with years of continuing losses, cash outflows, and several equity fundraisings.
It must boil down to investors believing that the company has special know-how that might eventually result in it making some profit, perhaps?
As I say above, the existing valuation doesn’t make any sense whatsoever to me, so why would anyone be prepared to pay even more for it, in a sale process?
There’s not much liquidity in this share, due to 3 dominant shareholders, so maybe taking it private might make some sense? I’d be worried that could happen at a discount, rather than a premium though.
I see Harwood increased in Nov 2022, and they're certainly not fools, so there must be something interesting at BMK that is not obvious from the numbers -
On the upside, sometimes companies with unique technology attract high valuations that are not necessarily linked to financial performance. Maybe this could turn out to be such a case?
Time will tell, I don’t know how this situation will end up, your guess is as good as mine!
Given that it’s so overvalued on poor fundamentals, I have to go AMBER/RED.
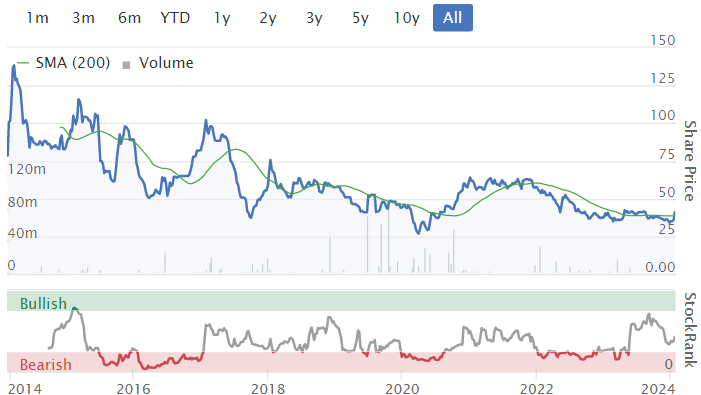
10-years as a listed company, and it's gone nowhere -
Eleco (LON:ELCO)
Up 5% to 91p (£76m) - Year-end trading update (slight beat) - Paul - AMBER
The Board of Eleco plc (AIM: ELCO), the specialist software provider for the built environment, is pleased to provide a trading update for the year ended 31 December 2023, based on unaudited management accounts for the period.
I have a generally favourable impression of this software business, having followed it for years. It bombed out after the 2008 GFC (great financial crisis), bottoming out around 7p, so has been a lovely 10+ bagger since then (not far off a 20-bagger during the peak 2021 valuation of c.132p).
Eleco seems a good company, churning out pretty reliable profits. Although I’ve often placed a question mark over its high valuation, eg when reviewing here on 11/5/2023, I could only go to amber then because any higher didn’t seem justified since profit had only gone sideways in the last 5 years.
The bull case is that a long transition to more reliable SaaS recurring revenues (now up to 74% of total revenues) has suppressed short term profits in return for more reliable long-term recurring revenues. Lots of software companies have done a similar thing, but 5-years is a long time for investors to wait.
On to today’s trading update for FY 12/2023.
Record Recurring Revenue Growth
ARR at 31 December 2023 was approximately £22.6m (at 31 December 2022: £18.2m) an increase of 24%.
That is good, and gives nice visibility. Although almost half the growth has come from an acquisition of BestOutcome.
Total revenue for FY 12/2023 is now £28.0m.
What about profitability? The CEO says -
…profitability is expected to be ahead of consensus. This reflects our strategic switch to a SaaS business model and our focus on higher margin core products, and the discontinuation of products that were not contributing to the future of the Group.
Cavendish updates us (many thanks), and its revised FY 12/2023 actually show a reduction in forecast revenues from £28.7m to £28.0m (6% Y-on-Y growth instead of 8% previously forecast). This revenue shortfall is recouped only through lower costs. The table shown by Cavendish shows an increase in forecast adj EBITDA from £5.8m to £6.0m, but actually both figures arrive at £5.9m, flat. So there must be some rounding differences in the table, or a formula is wrong in their spreadsheet!
I hope Cavendish don't mind me including the excerpt below, and of course I'll remove it if they complain -
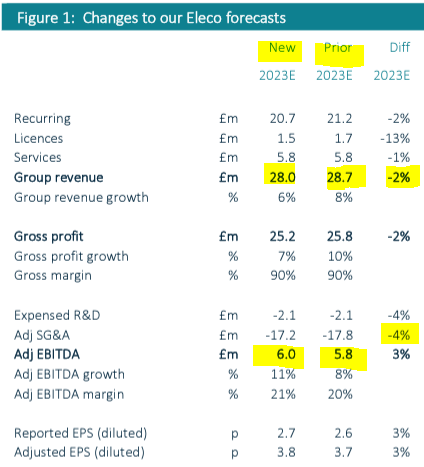
Adj EPS is revised from 3.7p to 3.8p, and given that this has been achieved by lower costs, on lower revenue than forecast, I don’t really see this as ahead of expectations - it’s more realistic to see this as in line, thanks to some costs coming in a bit lower than expected.
I’ll call it a “slight beat” so I don’t have a riot on my hands from ELCO shareholders!
Forecasts for 2024 and 2025 are actually slightly trimmed today for revenue (down 3% in both years compared with previous forecasts). EBITDA is unchanged in the 2024 & 2025 forecasts, but that’s only been achieved by cutting forecast costs by 4%. So it looks a rather defensive minor move on forecasts, although to be fair, the numbers are still showing decent earnings growth year-on-year, with this forecast progression -
FY 12/2023: 3.8p adj dil EPS
FY 12/2024: 4.6p
FY 12/2025: 6.0p
I don’t think there’s any point in looking any further forward into the future, although since ELCO has c.74% recurring revenues, it’s easier & safer to forecast than for many other shares. So even if a profit warning were to happen, it probably wouldn’t be a major miss.
Cash looks healthy -
Cash as at 31 December 2023 was £10.9m reflecting strong cash generation outside of an acquisition payment and related costs of £3.8m and increased Interim, Final and Special Dividends.
However, bear in mind that more than all the cash all comes from favourable working capital cycle - getting paid up-front by customers. Eg at 30 June 2023, cash was £9.4m, but deferred income creditor was £(12.0)m.
Overall NTAV was slightly negative, at £(1.3)m. So it’s not actually a strong balance sheet, it’s adequate thanks to a favourable working capital cycle.
We really need to know the average daily net cash figure, plus the annual peak and trough, to be able to properly assess the validity of its cash position. That’s true for all companies. Are the period end cash figures untypical seasonal highs, or are they normal at that level throughout the year? We don't know, it's a big gap in current financial reporting requirements.
My worry is that if ELCO keeps making acquisitions using cash paid up-front by customers, it would reduce NTAV further into negative territory, thus potentially making the share more risky if something bad happened.
Expansion into the USA sounds very interesting, with >40 new clients. That’s something I’d be interested in hearing more about when the full results are published. Obviously a huge market, so if ELCO can succeed there, very tough to do of course for overseas companies, then it might be transformative long-term.
Outlook -
"We continue to see exciting opportunities with the long-term market growth trends and drivers in the geographies we operate in. Given our established positioning and cash-generative SaaS business model, we are confident of another year of strong organic growth, supplemented by further acquisitions, to widen our international reach and customer-focused capabilities."
Paul’s opinion - this looks quite good. There are some nice positives covered above, but as before, valuation seems up with events. Hence I’ll stick with AMBER. Just to emphasise, I don’t see anything wrong with ELCO’s numbers, my only quibble is paying a high-ish multiple for relatively modest organic growth - remember that acquisitions are boosting the growth numbers.
Although taking a 2-year view, if it hits 2024 & 2025 forecasts, then the share would probably have decent upside, as it grows into the valuation. So maybe something to consider as a long-term investment, if your own research makes you feel positive about it meeting or hopefully beating forecasts in future.
Marston's (LON:MARS)
Unch 33.3p (£211m) - Trading Update (AGM) - Paul - AMBER/RED
· Marston's is a leading pub operator with a 40% holding in Carlsberg Marston's Brewing Company
· It operates an estate of 1,408 pubs situated nationally, comprising managed, franchised and leased pubs
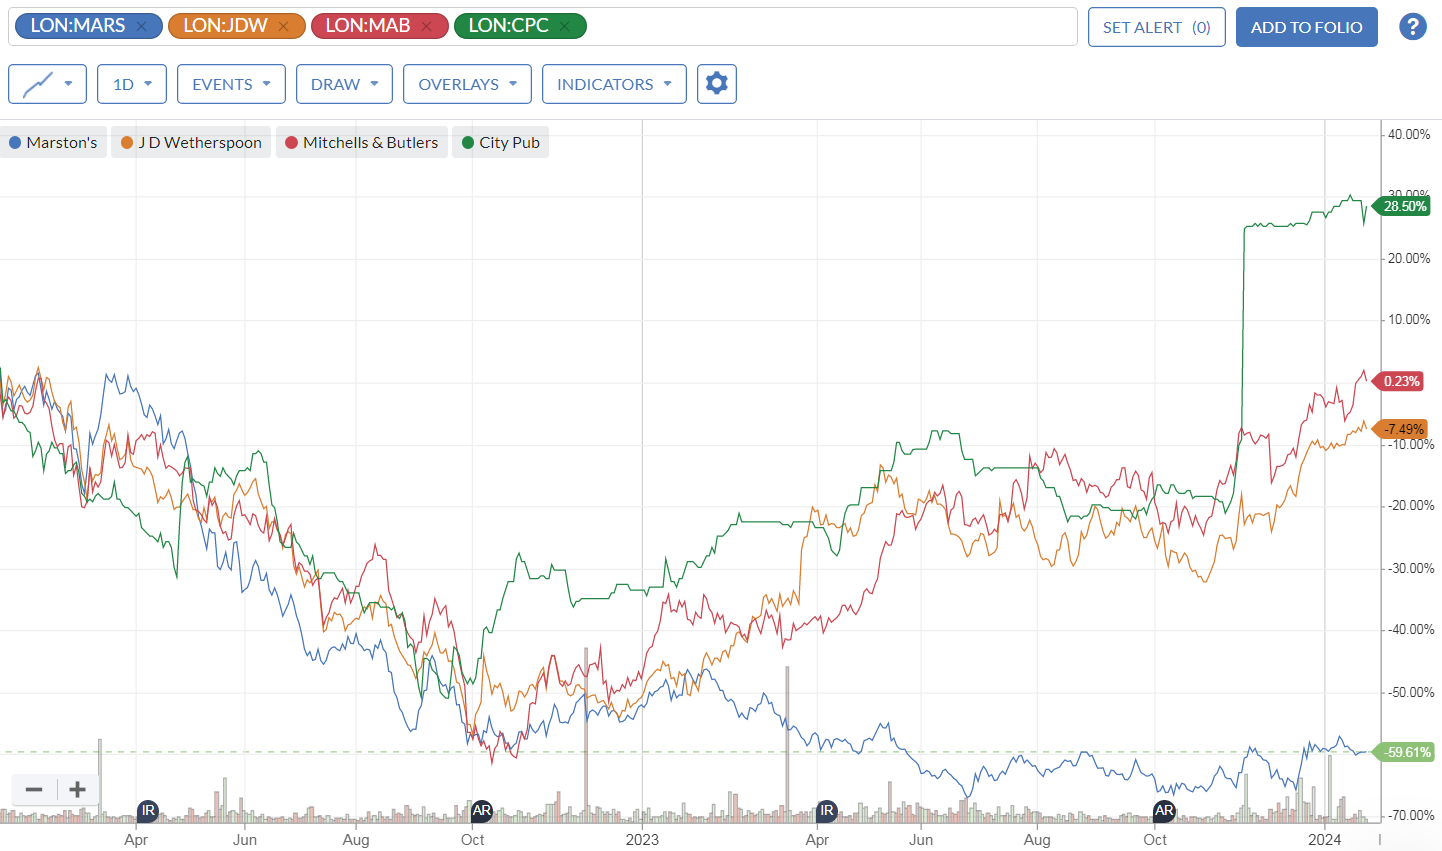
I’ve been meaning to look at Marstons for a while, as the shares have been a sector laggard. The chart below shows MARS at the bottom, down 60% in the last 2 years, whilst larger sector peers J D Wetherspoon (LON:JDW) and Mitchells & Butlers (LON:MAB) dropped about 50% in 2022, then recovered nearly all of that in 2023. Whilst MARS only went sideways in 2023.
This makes me wonder whether MARS could be a laggard for a recovery in share price? Either that, or there’s something wrong that is putting off investors from MARS?
The stand out top performer is City Pubs, which attracted a takeover bid - the green line at the top, below -
Current trading -
MARS tells us today it did well over Christmas, with YTD (16 weeks to 20 Jan 2024) showing LFL revenues up a healthy +8.1%, a slight acceleration from previously reported growth of +7.4%.
Outlook - brief, but encouraging comments here from its very new CEO -
"I am pleased to report a strong trading performance with like-for-likes up 8.4% over the festive period. It has been an encouraging start to the year.
This, together with an improving outlook in which inflationary headwinds are broadly abating, and the actions we are taking to operate more efficiently and rebuild margins, position Marston's well for the year ahead."
The financial year is FY 9/2024.
I find that all reassuring, but the market doesn’t, with no change in share price so far today.
We didn’t look at MARS last year, so I’m flying blind here, with no recent notes to refer to, only some old notes here during the pandemic, but nothing before or after.
I’ll quickly review its FY 9/2023 results from here -
The company’s own headline was -
IMPROVED UNDERLYING PROFITABILITY, POSITIVE CASH FLOW AND CONTINUED STRATEGIC MOMENTUM
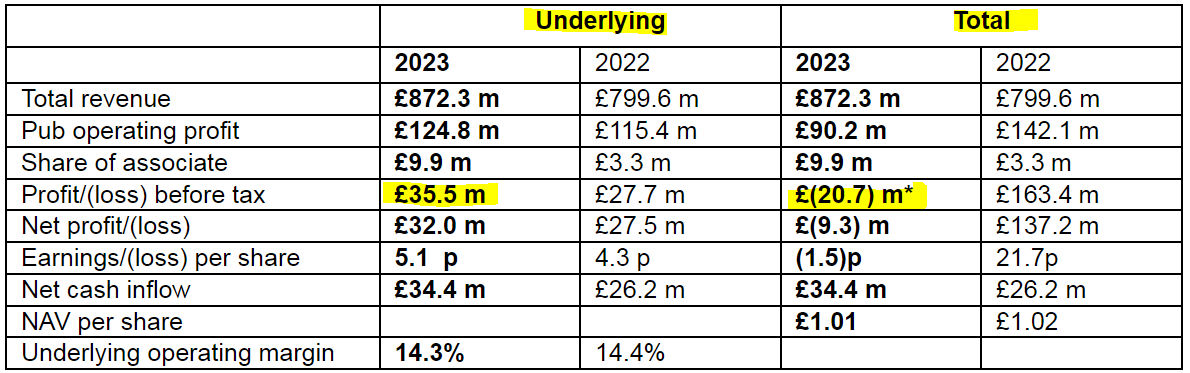
This table below shows an u/l PBT of £35.5m, up 28% on FY 9/2022.
Note the large adjs of £56m, and the £(20.7)m statutory loss - probably asset write-offs I imagine. Yes here we are for the adjustments -
*Includes a £21.6 million net loss in respect of interest rate swap movements, a partial reversal of the £109.2 million net gain reported in FY2022, and £31.2 million of charges in respect of the impairment of freehold and leasehold properties.
Pensions - bit of a drag on cashflow, but doesn’t sound serious -
The net annual cash contribution is c.£6m and is only expected to continue for the short term. The results of the next triennial valuation are expected in early 2024.
Debt - this is the big issue. It had £1,185m of debt (excl. leases, which are future operating costs, not debt), dwarfing the £211m market cap. So properly studying & understanding the debt is the crucial research work here, which I won’t have time to do properly today.
This excerpt below gives you an idea of the complexity, and things that need researching more -
As set out in our Interim Results, we successfully secured an amendment and extension ('A&E') to our banking facility and private placement to the end of January 2025. The revised £340 million facilities are comprised of a £300 million Revolving Credit Facility (the 'RCF') with the continued support of all of our existing banks and with two new banks keen to join the syndicate, together with a restatement of our current £40 million private placement. The RCF replaces the Group's existing £280 million facility. The facility cost is variable: to be determined by the level of leverage or drawings from time to time alongside changes in the SONIA rate, together with issue costs. As previously reported, £120 million of the facility is hedged.
During the period and prior to the A&E, we secured the covenant amendments that we required, as reported in our 2022 financial results, again demonstrating the good relationship and support we continue to have with our banking group and private placement provider. No further covenant amendments have been required.
The Group anticipates commencing formal discussions with the RCF banks and private placement holder in early 2024 in order to secure the refinancing of these facilities to beyond January 2025. Whilst there is no guarantee, based on the successful A&E to the RCF and private placement during the period, and the positive conversations held to date, the Directors are confident that they would expect to be able to secure refinancing on similar terms.
The vast majority of our borrowings are long-dated and asset-backed, including the securitisation debt of c.£611 million, which has low interest rates in the current environment and a payment structure that reduces debt. The weighted average fixed interest rate payable by the Group on its securitised debt at 30 September 2023 was 5.1%. The Group has confidence in the loan to value of its debt, which is improving year on year and is currently 68% for debt excluding IFRS 16 lease liabilities and 53% for the securitisation debt.
The Group's financing, providing an appropriate level of flexibility and liquidity for the medium term, comprises:
· £300 million bank facility to January 2025 - at the year end £229 million was drawn providing headroom of £71 million and non-securitised cash balances of £10 million
· £40 million private placement in place until January 2025
· Seasonal overdraft of £5-£20 million, depending on dates - which was not used at the period end
· Long-term securitisation debt of approximately £611 million - at the year end £10 million of the £120 million securitisation liquidity facility had been utilised, which was repaid in October 2023.
Going concern - says it can manage the debt facilities, but this is obviously a concern -
Accordingly, the financial statements continue to be prepared on the going concern basis, but with a material uncertainty arising from the current macroeconomic environment. Full details are included in Note 1.
Discount to NTAV - is huge with a price to NTAV of just 0.35, which obviously casts doubt on the property asset values - PPE is £2.06bn. It stands by its total property values here -
The Group has performed a market capital gap analysis to determine whether an impairment of the asset values is required. The analysis showed that there is sufficient headroom between the total asset value and enterprise value such that no impairment is required.
Cashflow statement for FY 9/2023 clearly shows that the cash generation from the pubs is all consumed by maintenance capex, and finance costs. So that means unless performance improves, there’s not going to be any prospect of reducing debt significantly other than from selling off properties.
Paul’s opinion - this is special situation, where the c.£211m equity is dwarfed by debt (non-leases) of almost £1.2bn. It would take an enormous improvement in performance to start even making a small dent in the debt mountain, which seems unlikely. So the probability is that debt would have to be rolled over in future, and the terms of such refinancings would be crucial to whether any value returns to equity or not.
I doubt insolvency would happen, as that’s not in anybody’s interests. The main concern is that equity doesn’t see any cashflows at all (no divis have been paid since early 2020), and it might require a substantial equity raise to persuade lenders to refinance at a more affordable cost perhaps? So equity holders would probably have to put more money in, before they’re likely to get much (or any) share of future cashflows.
Asset disposals is another possible direction to take, but buyers would probably be mainly interested in the best performing pubs, so sales would then mean losing profits. Alternative use might be helpful in realising some asset values maybe, after all lots of pubs in London have been turned into fancy flats. Although I see from its website that Marston’s doesn’t have many sites in London. They’re mostly concentrated in the Midlands and Northern England. There’s also its brewery partial holding, which could be sold.
What about a takeover? That looks a distinct possibility to me. If a bidder offered a say 50% premium, it would only cost about £300m, to take control of 1,400 pubs, and maybe negotiate upside on the borrowings?
So I think the main attraction of this share is for a potential takeover bid.
The heavy debt burden could make it higher risk, so a lot of detail needs to be checked before proceeding here I think. I’ve got to flag the elevated debt risk, so have to view this AMBER/RED, but I can also see upside potential in a consumer recovery that’s probably in the pipeline. Decent LFLs last year, and so far this year, probably make the risk in this share tolerable.
Graham’s Section:
H & T (LON:HAT)
Share price: 339p (-15%)
Market cap: £149m
H&T Group Plc ("H&T" or "the Group"), the UK's largest pawnbroker and a leading retailer of high quality new and pre-owned jewellery and watches, today provides an update following completion of the financial year ended 31 December 2023.
This is a surprising (to me) profit warning from the UK’s largest pawnbroker.
2023 profits are up 40% compared to the prior year, but retail conditions pre-Christmas were “challenging”, particularly in December. So despite strong year-on-year growth, the profit result is still 10% below market forecasts.
With thanks to Research Tree and Shore Capital: the old PBT forecast for 2023 was £29.5m, whereas the new forecast is £26.6m.
Shore Capital have also reduced their PBT forecasts for 2024 (by 9%) and for 2025 (by 10%).
Let’s explore the trading update a bit more:
Pawnbroking: continues to go from strength to strength. The pledge book is up 30% year-on-year to £131m, ahead of expectations. The characteristics and performance of loans are unchanged, i.e. average loan size £201, redemption rates 85%, loan to value 65%.
As an aside, perhaps the warnings in recent months from HAT on problems in the luxury watch market should have been taken as a bad omen for Watches of Switzerland (LON:WOSG) investors? HAT is now more cautious when it comes to lending on watches, and watches are now just 15% of the pledge book (previously 17%).
Retail: Q4 was “challenging”, due to the pressures on disposable income. More items were sold than the previous year, but “customers displayed caution in their spending, with a significant shift towards lower priced items”. Customers favoured cheap, new items over more expensive pre-owned items, and Q4 revenues fell 3% year-on-year.
FX/Holiday Money: revenues are up 11% and a “click and collect” service launched in June 2023. It seems to be making good progress, but “it is taking longer than anticipated to achieve forecast volumes and revenues.”
Gold purchasing: up 18% at consistent margins.
Costs: the 10% rise in minimum wage from April 2024 is flagged.
CEO comment: addresses the challenging retail conditions
We believe, despite this challenging backdrop, that we have the right product offering and have continued to invest in our store estate and our technology platforms.
Graham’s view
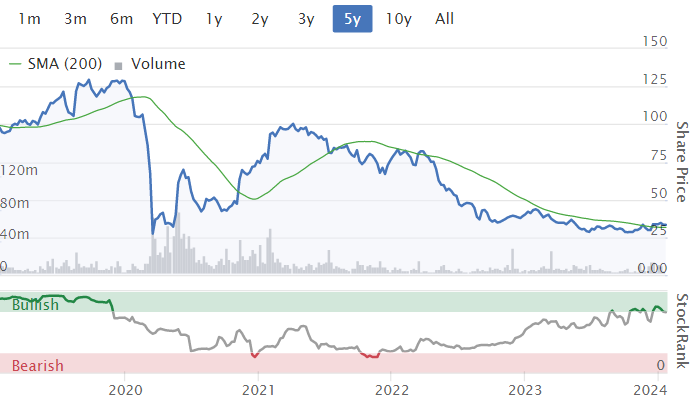
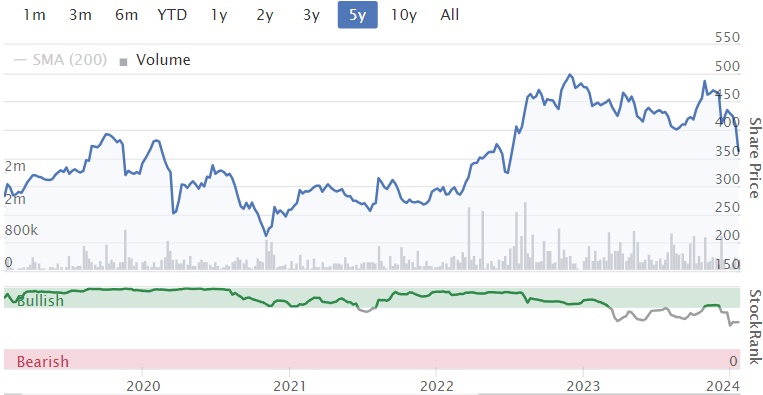
I’m a long-term fan of this business and I’m disappointed for shareholders that they’ve seen such limited share price progress. At 326p, the shares are back at levels they first reached in September 2017.
Here’s a 5-year chart:
I used to hold this as my largest position. One of the reasons I no longer felt compelled to continue holding it was a belief that it was struggling to do well in terms of ROCE/ROE. Here are those latest quality metrics according to Stockopedia:
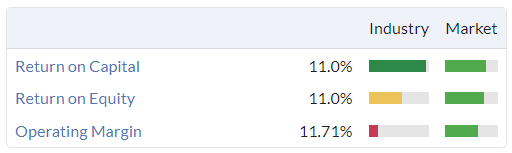
As you can see, returns have been good but not “great”.
However, I still view this as a really solid business and am struggling to understand this valuation. Even after today’s downgrades, the company is still forecast to generate an adjusted PBT of £33.5m in the current year, vs. a market cap of less than £150m.
At a 25% corporate tax rate, we have an adjusted PAT of £25m, meaning that the shares are trading at 6x adjusted earnings (note that adjustments were ZERO in 2022, i.e. adjusted profits were the same as actual profits).
At 6x earnings, how can I not give this stock the thumbs up?
To summarise, the bear points are:
Exposed to retailing sentiment which has been difficult.
Cost inflation, particularly minimum wage.
Unexciting return metrics.
Against that, you have:
The biggest pawnbroking book in the country, by a mile.
A very long track record of responsible and profitable operations.
An earnings multiple of 6x.
(Paul adds: the first profit warning from my top 20 ideas for 2024, drat! Still, it's fairly mild, and as readers have commented below, why did the company guide brokers to set forecasts so high in the first place? The reduced outcome announced today is still an excellent improvement on last year's profits. We also have a bulletproof balance sheet, with nearly the whole market cap now supported by NTAV. The share price has fallen from 490p peak in the last 3 months, to just 344p today. I think that actually makes it more appealing overall as a value share. So for me, this profit warning is very much glass half full, not half empty. I don't see anything wrong with the core business, it's more a case of overly ambitious forecasting, creating the illusion of under-performance, in what has actually proven to be a good year in 2023. So I very much agree with Graham's view that it's GREEN on fundamentals)
Henry Boot (LON:BOOT)
Share price: 190p (-10%)
Market cap: £255m
And now for my second profit warning to look at today, it’s Sheffield-based Henry Boot:
Henry Boot PLC, a Company engaged in land promotion, property investment and development, and construction, is today issuing a trading update for the year ended 31 December 2023 ahead of the announcement of its full year results on 25 March 2024.
CEO comment
The CEO describes it as a “resilient performance” in 2023, in line with market consensus.
However, he also says that 2024 results will be “impacted” by inflation and interest rates, even if those two factors are now on a path lower.
He says the company is “well placed to achieve its medium term growth and return objectives”. This sort of phrase is often used when short term objectives are impossible to meet…
Trading update for 2023
Key points:
“Robust sales” despite activity reducing in three key markets (Industrial & Logistics, Residential and Urban Development).
PBT in line with consensus (£37.2m)
Net debt increases to £77m, gearing “towards the top end of the optimum stated range of 10-20%”.
Boot’s subsidiary Hallam Land Management has grown its land portfolio to nearly 101,000 plots.
Developer HBD has beaten expectations, completing on a range of schemes and nearly doubling the value of its development programme year-on-year.
Stonebridge Homes - a premium home builder based in Leeds - completed 251 homes (2022: 175), working its way towards a target of 600 homes. As mortgage rates stabilised towards the end of the year, reservations picked up. Supply chain/cost pressures also moderated.
Henry Boot Construction “traded below expectations but remained profitable”. Two projects were impacted by “the availability of materials and the resultant delays”.
A bit of a mixed bag for 2023, then, although mostly positive and ended up meeting expectations.
Unfortunately, the 2024 outlook is less positive.
Despite the company’s optimism around inflation and mortgage interest rates, they say the following:
The Group is well positioned to benefit when our end markets recover, however we expect there will be a lag in performance due to the time it takes for projects and sales to complete… we are now more conservative with our estimates of completions for 2024 and anticipate the impact from a recovery in residential sales will be more weighted to 2025.
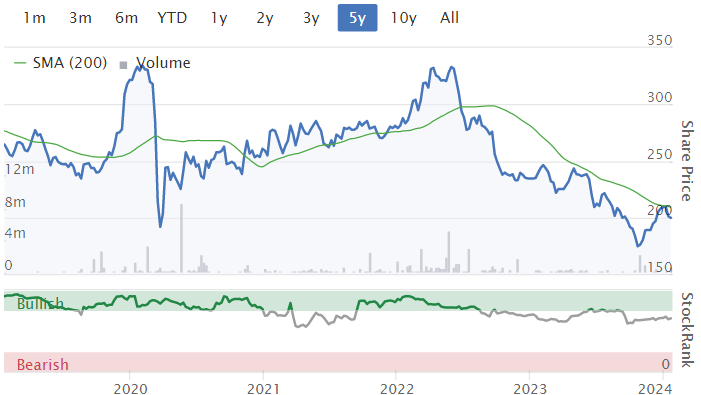
Perhaps this is another case where the company might have been more careful with its estimates in the first place, and might have avoided this profit warning? After all, as the company itself points out, the outlook for inflation and rates has improved. But it seems that Boot’s forecasts assumed these macro factors would improve and would boost performance even faster than they already have.
Additionally, Boot’s level of gearing is going to remain at the high end of the range through 2024, as they have agreed to extended payment profiles with housebuilders on strategic land sales (I wonder why? Why not let the housebuilders use up their own cash or borrow to invest?). The result is that Boot’s interest bill will be higher than anticipated and this will also impact profitability.
As a result, profitability for 2024 will be significantly below current market consensus.
That consensus, according to the company, is PBT of £37.2m, the same as 2023.
Graham’s view
I looked at this stock last March and liked it. Paul also liked it in May.
Interim results posted in September showed NAV rising to 303p and net assets of £405m, almost entirely tangible.
However, ROCE fell to 6.3%, below the target of 10%-15%. I do give the company points for keeping shareholders updated on this important metric.
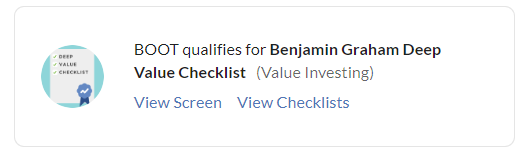
On balance, I think I’ll continue to give this one the thumbs up. It’s probably on a single-digit earnings multiple against the earnings that it could achieve in a “good” year, it’s at a discount to NAV, it has a long track record of profitability, and it passes a nice screen:
Against that, investors are going to have to be more patient while they wait for a full recovery in the company’s end markets - I look forward to finding out the new earnings estimates from Peel Hunt and Panmure. I also note that the debt position is less comfortable than it ought to be, and ROCE is likely to be underwhelming in the short-term (less than or around 10%). But for patient investors who want to benefit from land development and construction, this could be a reasonable choice and one that’s worth investigating further.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

102 comments
Had been considering Henry Boot (LON:BOOT) for a while, took the plunge and bought with the drop in price after today's profit warning. Graham sums up the situation well:
"It’s a dose of bad news for Henry Boot investors as the company now expects its end markets to take longer to recover. It’s frustrating as the macro indicators have been moving the right way. But the stock may still offer a decent proposition over the medium-term."
Not sure if I have bought too early, as many stocks continue to fall the next day after a profit warning.
Luceco (LON:LUCE) decent jump on some volume - one giant bid - this afternoon following a couple of decent sized buys this am. Probably come straight back down tomorrow.
Luceco (LON:LUCE) - Could this be related to the concert party split RNS yesterday?
Hi, interested why Marston's (LON:MARS) scores a 96 on Stocko valuation metric? I note on Stockreport it lists 4 "Price to" and only one "EV to" metric. Given that the company has roughly 6 times as much net debt as it has market cap, using any "Price to" metric is giving a very false measure of cheapness!
Marston's (LON:MARS)
any "Price to" metric is giving a very false measure of cheapness!
Have you read the value caveats that the notes page advsises on? the warning is there
It should though be noted that 'cheap' stocks are often distressed, junk or low quality stocks and can often be highly volatile as a result - so one should be careful in the very highest ValueRank companies.
to me the system rightly points out the value here - its up to us the to risk assess that value- as we have done with red flags. Note its probably trading at 1/3 of the book value here so you cant argue its "value" its just very risky value with all the debt that could wipe out equity holders in a heartbeat.
When you owe the banks that amount of money, they take you to lunch with champagne...
Indeed - it is slightly frustraing also that Stocko opts for the Price/Sales metric on the front page ratios, rather than the much more useful EV/Sales.
Yu. ? !!!
What do Yu (LON:YU.) mean?
DYOR. Sorry if that is too challenging for you !
I don’t understand your posts.
You just posted Yu?!!!
Perhaps others that understood can explain since you are not willing to.
I have done my own research 15 months ago and if I am not mistaken it was Davidjhill that mentioned this (yet again and thanks again David!) when the price was still around 300p.
Thanks
'The US is on to the next big innovation (AI) and we are still discussing the prospects of a teapot maker!'
I couldn't resist the opportunity to ask the AI to discuss the prospects of a teapot maker!
And this is what I learned:
The prospects of a tea pot maker would depend on various factors such as market trends, consumer preferences, competition, and the ability of the tea pot maker to adapt and innovate. Here are some key considerations:
*************************************************
9. Customer Engagement and Feedback:
In conclusion, the prospects of a tea pot maker depend on a combination of factors including innovation, quality, marketing strategies, and adaptability to changing consumer preferences. By staying attuned to market trends and continuously improving products, a tea pot maker can position itself for long-term success.
I'm so impressed I've bought a few (more) shares in a teapot maker :-)
Check back here in a couple of years time to find out which of us is about as much use as a chocolate teapot :-)
cheers
Mark
Hi Mark
What does the AI think about AI?
Just curious
Haha, very good Yiannos! Top marks.
Since you've asked me to look it up for you. I asked the AI to discuss the prospects for AI and teapot makers :-) Here's the reply:
The prospects for Artificial Intelligence (AI) and teapot makers might seem like an unconventional pairing, but the integration of technology in various industries can bring about unexpected opportunities and enhancements. Here's a discussion on how AI could impact teapot makers:
Are you sure that you want me to jam the message board up with thoughts on AI and teapot makers? Well you did ask:
AI algorithms can be employed to optimize the teapot supply chain. Predictive analytics can help forecast demand, manage inventory levels, and enhance logistics, ensuring that teapot makers can meet market demands efficiently while minimizing excess inventory.
While the integration of AI in the teapot industry presents exciting prospects, it's essential for teapot makers to approach technology adoption thoughtfully. Consideration of factors such as cost, consumer acceptance, and maintaining the traditional craftsmanship associated with teapot making will be crucial for successful implementation and sustained growth.
OK. The AI may have lied a little bit towards the end. But that's the problem with AI isn't it? A teapot never lies?
Oh this is so much fun?
Made a note to buy more shares in a teapot maker on the basis of AI enhancements ........ Whose a smart teapot? :-)
For the avoidance of doubt - that's the last word from AI&I on teapots, smart teapots, chocolate teapots and all,
cheers
Mark
Must be lovely to have that much time to waste....
£350k director buy Quartix Technologies (LON:QTX)
Afternoon Paul, I just wanted to say I'm loving the new agenda and mid morning movers sections, they are a fantastic addition and allow for readers to get a solid overview of how the day is unfolding with just a quick read. How you are able to churn out so much content in such a short period of time blows my mind. If I sat at my laptop just typing out the dictionary for 8 hours I wouldn't get half as much written down as what you and Graham produce. That's not even accounting for the pre reading, balance sheet analysis and hinterland you both provide for each stock! Don't work too late today chaps, I get the impression tomorrow could be a monster day for reporting!
'Quite Remarkable' as David Coleman would have said! #ImLovinIt
That's nice, thanks BenHazz! I'm just about keeping on top of things by starting work before 5:00 am each weekday! Glad you like the new agenda format. It's really helping me & Graham focus rather than being completely overwhelmed, so a good innovation!
I've got a hard stop at 10:30 tomorrow due to an investor lunch, so will make sure we get off to a flying start with some sections from today done by 7am tomorrow morning.
Best wishes, Paul.
Re: AWE. I used to work as a programmer, and even I can't work out what they do. I'm not a hardware guy, though, although I know a little.
Their website says "Alphawave Semi’s chiplet solutions build upon our industry-leading wired connectivity IP portfolio combined with our custom silicon and advanced packaging capabilities." To be honest, that sounds like it was generated either by AI or a marketing department.
Reading here: https://awavesemi.com/chiplets...
A SOC is a System on a Chip. On your typical PC you will have a CPU mounted onto a motherboard, which is like a PCB. There are lots of other chips that go onto the motherboard, like memory cards, graphics cards, and so on. When you buy a PC with Windows on it it will typically have either an Intel or AMD CPU.
A SoC on a chip is, like, "hey, why don't we just combine all these various components onto one small chip and have done with it?" If you've ever bought something like a Raspberry Pi, that uses a SoC. Those don't have Intel CPU architecture on them, but Arm.
Phones are also based on SoCs. SoCs offer a combination of price, low power consumption (vital for mobile devices) and small size. They tend to be slower and less expandable, however.
So I think what these chiplet things are is saying that they provide an efficient design for getting the different "blocks" on a SoC (i.e. CPU, graphics, memory, etc.) to communicate faster internally, which is of of course advantageous. The page also seems to be implying that they are a way for SoC designers to modularise their designs rather than performing more complex integration.
I take it that the company doesn't manufacture of this stuff, but licenses the design, which is like Arm, but unlike Intel (who actually manufacture chips).
AWE also seem to have other offering, but I can't be bothered wading through it.
I could be wrong, though. If anyone has greater insight into the matter, I'm sure we'd all be interested.
Having been on my watchlist for a while I bought a starter position in Alphawave IP (LON:AWE) on yesterday’s positive update - it confirmed to me that they were successfully migrating to their new business model after a serious of acquisitions.
In addition, they state 99% of new bookings are ex China as they actively pivot.
I found the H1 results presentation below very helpful in terms of understanding what they do their market position, strategy and opportunity. They answer some good analyst questions too!
https://awavesemi.com/interim-results-2023/
The Chinese revenue generated is legacy, older tech, lower margin business inherited with a recent acquisition and rolling off. This helped drive negative working capital as upfront Chinese customer payments left the balance sheet for the P&L as goods were shipped to customers.
The new business model is focussed on advanced chip design, development and production. Revenues in this part of the business are currently from design and development – what they categorise as Licence or Non Recurring Engineering (NRE) revenue.
Alphawave IP (LON:AWE)’s focus is on connectivity e.g. connections within and between data centres or cars etc.. They see Marvell Tech as their main competitor. They differentiate themselves by offering either the IP, or design, or complete chiplet product. So, if you’re Microsoft and you want to make your own chiplets you might prefer to use Alphawave IP (LON:AWE)’s design versus Marvell Tech’s chips.
The change in capability/focus has generated significant revenue growth, but the transformational revenue/profit shift occurs when these designs enter production. This is due to start in 2024 and ramp through to 2026.
In the last 12 months or so they’ve signed contracts “with all the major hyperscalers”.
Although its cash consuming at the moment, it is profitable (albeit helped by the capitalisation of significant costs) and the analyst forecasts mean Alphawave IP (LON:AWE) is very cheap compared to competitors in an industry where consolidation appears ever present.
In addition, the forecasts are from 4 analyst/brokers: Barclays, DB, Jefferies and JPM which, for me, makes them more credible than the standard AIM jam tomorrow forecast from the house broker and 1 analyst at best.
In the semi conductor and tech world, bookings are a great indication of future revenue due to the time lag, depending on the project and development/manufacturing timeline. Reporting revenue would certainly help the credibility of trading updates - though they are implementing a new ERP system which I always see as a risk.
Overall, I think this is a more interesting watch than tea pots :) and sits in the high risk part of my portfolio.
Anyone know why Ramsdens Holdings (LON:RFX) has fallen on no news?
HAT read across.
hi James
Ramsdens Holdings (LON:RFX)
Shares have fallen due to read across from H & T (LON:HAT) results today.
Snazzy
I looked at Ramsdens Holdings (LON:RFX) this morning and all I could see was poor technicals for the fall. Fallen below all the main MA lines. With no news out to lift it, it does not look good from a chart prospective.
I see it has recovered a little from its low. It may bounce back from here, but if it hangs around this price for bit then my guess is it will drop further. Need to wait a few days to see.
FWIW interesting news re Norcros (LON:NXR) - completely major new 9.9% holder just disclosed today, (Perpetual Ltd, AU) on a business with a stock rank of 98 and a rising trend.
I've held Norcros for some time as - absent a trade war with China - I think it it is a boring but increasingly good business. It has good customers, makes small, close -in and adjacent-markets acquisitions to its core Bathrooms niche and in the UK/South Africa markets it knows well. It then regularly generates cash to pay down the acquisition debt debt. In fragmented markets, this is an easily repeatable model. Vs a few years ago, its much better diversified by channel/ brand/ product and the pension scheme less of a risk as the overall business grows. New mgt is knitting the group closer together with a well covered 5% forecast divi as we wait.
I'm also of the the view that we are close to the bottom for housing suppliers as the UK desperately needs more homes and new infrastructure and Labour are promising to 'bulldoze' local opposition. Housing starts for instance have fallen for the last 2 years. I think they must start going up soon! In SA, the roll out of House of Plumbing seems an obvious success in the making.
(I'm less bullish on housebuilders as the 'landbanks' on balance sheets, historic excess profits and habit of making massive donations to the Conservative Party make them visible and easy targets politically.)
Abrdn to axe hundreds of jobs
https://news.sky.com/story/fun...
First they come for your vowels, next they come for your jobs...
Brilliant!
The SCVR summary spreadsheets are a great idea. Really useful if you are doing a quick review of a particular stock or quickly want to sort the wheat from the chaff. I also like the summary box if you are searching a particular ticker. A nice resource I will use going forward. Thanks Paul & Graham.
Thanks rick! Glad you're finding my spreadsheet useful. I find it's the quickest way of getting up to speed on any stock I look at. A few hours updating it each weekend is worth the effort!
Ridiculous volatility ?
Anyone else noticing sone quite bonkers share price fluctuations on virtual no volume .
Inducates some small caps are still extremely thinly traded with minimal volume .
Creating some opportunity if fleet footed .
Eg Centaur media which I have been buying a few in the past month ago sudden drop down to 37p from a spike of 46p a few weeks ago .
Filled what I could in the 37s and swiftly heading back to 40p.
Think key not to get flushed out on downward spikes unless “the story has changed” and also keep a float or cash to catch these waves on the lows .
Just an observation, market seems really undecided right now whether to carry on the rally or take a turn downwards, plenty of issues on shipping, poor sales, house prices, dog feeling unwell to make for a sideways period with a possible slip down .
Yes and if no or few trades the spreads are very wide, even on some normally tight spreads. Often I can't even a quote on many small caps to buy even small amounts, I was looking to buy Good Energy (LON:GOOD) yesterday. Market has been going down all year, after a good rally in November and December. PIs have left the market and fund managers are having to sell as money is withdrawn from the funds.
Who are you using Rusty? Out of coincidence I bought 2400 shares of Good Energy (LON:GOOD) yesterday afternoon at 360p through IG. Looks like I would have been better off waiting until today as it's down to 350.7p for a quote for the same amount!
I'm using IG group (LON:IGG) as well, sometimes can't buy anything, not even 20. Yes falling today, looking to buy under 350p.
Are you using the "request quote" system, I find I almost always get an offer through that, although I have to play around with the share amounts and refresh it a few times to check I'm not paying over the odds.
Hi planetX
I have a reasonable holding in Centaur Media (LON:CAU) bought over a year ago around 39/40p so have received some handsome dividends. I have been musing over this mornings share price volatility and wondering whether I have missed something? I am no chartist, but the direction of travel is unimpressive.
Was thinking of adding to Brickability (LON:BRCK) but need funds to do so
Jonno
Just think there had been a pullback and a few sales
Seemed too good to be true at 37 just can’t see any downside and that’s the very bottom of trading range past 6 months
I had no funds akso but decided to cut my position on Trifast last night as it looks a long turnaround and I had a good holding, big negative was also non Aim share so no IHT cover inn my trading account .
Not a big fan of brick ability and growth by acquisition comes with risks, acquisitions rarely deliver what you think (at PX I did a few and was 2 good , 2 bad , 1 disaster ) .
I’m liking Pennant and Transense but pennant has made its first step up, so that’s missed . Transense you might catch o. A 98p dip if your lucky .
And of course Filtronic who I suspect will have a few upcoming RNS orders .
HI planetX
Point taken regarding acquisitions, they don't always work out as you say, but when they do they can be very rewarding.
I posted my reasons for buying Brickability (LON:BRCK) in mid December when they were trading at around 50p, which I have cut and pasted below. I could be wrong, but hopefully not?
"Researched this after it was referred to by Paul Jourdan in his recent Vox market interview with Paul Hill. Watched the presentation of the recent interims on investor meet company and went through the accounts.
Whichever way I look at it, it just seems too cheap and that is despite the fact that UK small caps are cheap across the the board. It operates a capex light model and unless one thinks that the housing market is never going to recover the shares appear to be a steal.
I naively thought that the company's product range was confined to bricks but this is far from the truth. With the recent acquisition of Topek, a cladding specialist to add to the other two cladding businesses within the group, roughly 50% of revenue is now derived from bricks, down from 80% at the time of listing. After the terrible disaster that was Grenfell there will be a long term demand for cladding remediation works.
Brickability (LON:BRCK) operates 4 divisions:
The acquisition of Topek is forecast to offset the current revenue decline in bricks and building products going forward. The current and forward PE is around 5 for earnings of around 9.5p/10p. The dividend was increased at the interims to give a yield close to 7%. Management have plenty of skin in the game and as far as I can see the balance sheet is in decent shape and to cap it all the shares trade at less than book value. Seems like a no brainer. There is a broker note freely available from Finncap or Cavendish as they are now known.
What could go wrong? Two obvious potential banana skins, although there are no doubt more that don't come to mind as I write
I have bought a starter position in one of the family portfolios and would have bought more but am currently fully invested.
I could go. These are just my views and will leave others to make their minds up.
All the best."
The recent acquisitions of two cladding businesses look timely and on balance the purchase prices look reasonable. The prelims from Watkin Jones (LON:WJG) this morning reinforced my view on the prescience of the acquisitions when it reported that it had set aside a further £35m as an exceptional charge for building remediation works.
"£35.0 million further provision for building safety remedial works. Costs expect to be incurred over a period of up to five years"
According to Cavendish, Brickability (LON:BRCK) financial position remains satisfactory post the most recent acquisition of TSL Assets Limited
"The impact of the cash payment on our net debt forecast, all other things being equal, would increase our FY24E net debt from £44.3m to £61.6m which remains a comfortable and prudent level."
As ever good luck with your investments.
Brickability (LON:BRCK)
planetx does have a good point whatever way yuou lok at it for a £150 mill market cap company in the last 4 months they have spent £100 mill on these 2 cladding companies - that has to be a big leap of faith. No one is denying that at face value the cladding market looks busy at present - could it all be a bit of a short term boom though perhaps? as in the end all historical issues wil eventually be sorted. I would also slightly worry about guarantees etc it must be somewhat risky ensuring the work you do is fit for purpose long term. The acquisitions need to be delivering good profits in 5-7 years time for what they have paid - at the end of the day they are predicted to be making decent prfoits for 2024 and 2025 as things stand so i can see the attraction here but with acquisitions the reality is its all a leap of faith at times.
Agree....Smiths News (LON:SNWS) up 7% today no news.
Smiths News (LON:SNWS) has not been 'up' 7% at any time today, in reality it has improved by 1p so about 2-2.5% at best. Depending on where you get your data the Uncrossing Trade has a lot to answer for . Sometimes a stock will be marked up by a few % or pence on a single figure share trade in the UT after 4.30pm , this will unwind the following morning and give the impression that a stock is down .This is the reason that Stocko's numbers look to be at odds with others price providers. Over the last few day (apart from today when it has actually moved) Zotefoams (LON:ZTF) has been showing as a top riser when in fact it hasnt moved at all. For smaller cap lesser volume shares the only way to find a true price is to do a dummy trade.
EDIT Smiths News (LON:SNWS) is NOW up 5% at 50p to sell ;-))
...the only way to find a true price is to do a dummy trade.
And then unintentionally click on the "Accept" button rather than "Cancel". Don't laugh...
I am sure we have all done it, if I am thinking of adding to a holding I often try a dummy sell trade just to gauge the markets appetite for a stock and have even accepted the SELL when I really wanted to BUY.
FFS
Smiths News (LON:SNWS) was on Stocko at +6.5% ( I rounded up ) when I was typing! I was just commenting in agreement with apparent volatility on no news....
DD
I hope you didnt take my post the wrong way. A lot of people have been criticising Stocko's pricing lately so I thought I would help explain why this happens. In addition to my post often the price quoted will be the bid and then change to the offer and if the spread is wide this can mean a change of a few percent when in fact there has been no change at all.
I see Smiths News are moving into offering office accommodation, presumably as an addition revenue stream. Looks interesting, no details as yet, from what I can see.
https://twitter.com/hashtag/Mo...
That sounds alarming. 200 years of newspapers and then office rentals all of a sudden.
Eleco (LON:ELCO) From today's update "Despite challenging macroeconomic climates and geopolitical uncertainties, Eleco has continued to deliver a robust performance with its underlying revenue growth, and profitability is expected to be ahead of consensus. This reflects our strategic switch to a SaaS business model and our focus on higher margin core products, and the discontinuation of products that were not contributing to the future of the Group." The previously announced interim results informs us that one of the differences between underlying and actual revenue relates to "The profitable disposal of non-core German architectural CAD business" which has already taken place. I have bought on this mornings update.
Just received a nice marketing email from Sanderson Design (LON:SDG) , showcasing their latest fabric and wallpaper designs.
This reminded me a bit of Giles & Mary ("nutty") from Gogglebox, where Mary seems to blend in with the wallpaper.
Hopefully the office won't mind me including a bit of humour on the same topic -
?si=RlfmZzcvYUvMVScGAlphawave IP (LON:AWE)
Thanks for the coverage today Paul. I found it very interesting to witness your analysis of the numbers, given your candid admission that you don’t understand the product set. As it happens, the technology is gaining decent traction within the industry. Essentially AWE designs networking chiplets. A chiplet is a semiconductor module that performs part of the function of a full (monolithic) system chip, leading to the creation of customisable and modular semiconductors that save development time and reduce power consumption. A good comparison in terms of application area is networking chip giant Marvell Technology (NSQ:MRVL) and one of the largest shareholders in AWE is associated with the founders of Marvell. AWE sells IP, not chips, and it’s their ambition to join the likes of Synopsys (NSQ:SNPS) and Cadence Design Systems (NSQ:CDNS) as providers of the raw IP for semiconductor design. When you look at the astonishing charts and valuations of the latter two you can see the appeal!!
Your analysis ably highlights the delicate financial status of the business and the unconvincing cash generation. I like the tech and I’ve had several meetings with the IT analyst at my bank in which we’ve discussed, inter alia, AWE. He likes their product set and thinks they have a good chance of success, in which case, today’s price will look very cheap in a few years. I’m more cautious and am not buying on yesterday’s update. But part of that is my existing interest in multiple well established, cash generating semi stocks already, many of which have doubled this year. Do I need another? Probably not.
The notorious shorter Carson Block of Muddy Waters recently had a dig at some tech companies on the LSE, the the intent that "if they are proper companies, why would they not list on Nasdaq where their valuation would be many multiples of the UK valuation"? That is always my nagging doubt with any relatively newly UK tech company with global aspirations: why are you here? Because the only advantage I can see is the lack of scrutiny if it all ends up being worth nothing.
If you are a floor covering company or a lightbulb stockist, yes, AIM is your natural home. But a global competitor to the likes of the companies you mention: it does not make sense.
Alphawave IP (LON:AWE)
Very good point, Donald
Thanks for those posts BnB and donald pond - I think they help me crystallise a view I have been contemplating for a long time and which was recently reflected in a comment (by BnB or Yiannos) 'The US is on to the next big innovation (AI) and we are still discussing the prospects of a teapot maker!' (I think that share was Portmeirion).
I was thinking of buying H&T today for the reasons Graham and Paul have given, but does the future belong to a UK pawnbroker? Hmmm. No.
Question for BnB - do you use Stockopedia for snapshot financial summaries of US shares, or something else?
Question for BnB - do you use Stockopedia for snapshot financial summaries of US shares, or something else?
I use Sharepad. It's a personal thing but I find it presents the data with more clarity - greatly helped by having a customisable financial fundamentals view that gives me everything I need in one carefully personalised page. Charts are more customisable too.
Sharepad, not Sharescope?
Sharepad, not Sharescope?
Yes. Works best across Windows and iPad for me.
‘Will the last person leaving Seattle , turn out the lights!’.
deleted, off topic
and empty the teapot
The question surely, isn’t whether you chase the next innovation but whether you might make a decent turn out of the butcher, baker, candlestick or teapot maker listed on the UK market.
I set some money aside to chase those innovations but the rest is invested in the butchers, bakers, candlestick and teapot makers that I think will make me a decent turn within my investment window.
I stand more chance of understanding those businesses than I do businesses that are intent on providing functions and services that I never knew I needed.
I therefore saw the fall in the H & T (LON:HAT) as an opportunity and bought.
Fair enough.
But since you claim to understand them , I am interested to know where is the growth coming from in order for your capital to appreciate?
About 3000 companies listed on AIM a few years back we are left with 600-700 now and most foreign investors are doing a Usain Bolt.
Thanks
Looking at the forecasts in Sharepad and factoring in the downgrades in today's estimates I reckon I am looking at PBT of £26.6m 2023 for H & T (LON:HAT) , 2024 £33.9m and 2025 £38m. It may not shoot the lights out, but then I am not aiming to shoot the lights out. If I can make a consistent 9 to 10% a year in my portfolio, I'll be a reasonably happy camper.
I am no expert on H & T (LON:HAT. It's not my industry sector but I stand more of a chance of understanding their business model than I do that of Alphawave IP (LON:AWE).
Not sure that I agree that foreign investors are doing a Usain Bolt as it seems to be mainly foreign investors that are buying up British businesses and delisting them. In my own industry sector all the hot money is from overseas. It has been for the past 20 or 30 years.
I claim no expertise in the macro picture [I envy those who are able to comment meaningfully on it in this forum] but isn't some of the problem with the UK market due to UK investment institutions choosing to invest overseas rather than in the UK?
Valid points but I was referring to the UK small cap market in general and not to any particular share and not to FTSE250 companies. For the buyouts though the directors seem eager to offload them on a 50-60% premium so one can assume they see no real growth in them.
UK financial institutions are investing overseas for growth and liquidity issues.
A 5-7% spread plus on top the commission is one of the issues that drives investors away. The FCA should do something about this before it’s too late (although looks like it is).
Thanks
It's a shame we let Arm Holdings (NSQ:ARM) be delisted more than a few years back.An Arm Holdings (NSQ:ARM) or similar couple have encouraged more IPOs in a similar tech basket to give the LSE a shot.
Alphawave IP (LON:AWE)
from memeory i think they deserve rough treatment - anyone trying to defend the companies presentation of facts is mising the fact the company have brought these woes on themselves.
what particualrly irks me is that bookings are the only figure they quote in trading updates wtf.
correct me if i am wrong but my understanding is bookings are not actual sales income - why dont they quote actual sales like any normal company - you can add in bookings figure as extra info but if it aint sales why "pretend it is"
I think books this year as anniunced are 390 mill which will exclude soem sales - yet sales are only expected to be 340-360 mill. Oh we are 20 days past year end and we still dont have an idea what actual sales we did for the year what financial systems do they have in place.
Utterly incomprehensible that a company can think its ok to live in such afantasy land - if they are real an genuine its annoying that they have done their best to ensure that no sensible numbers based investors would go near this with bargepole. Fair play to those that understand the industy understand the need to pay millions on behalf of chinese partner and can see the wood for the trees - i cant.
one question are the numbers below poor to be expected or not relevant ? to be expected ? are they saying these previously big areas ref income are bringing in didly squat ? Bearing in mind startup costs ref china if its not bringing in anything its not exactly a great advert.
In Q4 2023, there were US$nil Flexible Spending Accounts[5] ("FSA") drawdowns (Q4 2022: US$nil) and US$0.4m China (VeriSilicon) reseller deals[6] (Q4 2022: US$nil). Both FSA and reseller deals represent the conversion of customer commitments to design wins.
Hi rmillarree,
Good point on how Alphawave IP (LON:AWE) makes such a song & dance about "bookings" in its trading update. I had to wade through almost the entire update before I arrived at any information that told us how they are actually trading!
I didn't like to say, but it reminded me very much of WANdisco, blinding us with bookings numbers that always sounded positive, but then followed by awful actual financial results every time. Plus of course in the end they just made up the bookings figures completely! So that's a lesson seared on my memory - to only trust audited results (mind you they can be wrong too! Look at Globo, Quindell, Pat Val, and all the other frauds & semi-frauds we've had in the UK market over the years)
To be clear, I'm not suggesting there's anything wrong at AWE, just that I don't like their focus on bookings as a KPI, as it's so easy to manipulate KPIs like that. It will certainly be interesting to see how it evolves. But personally I'd rather buy a teapot maker when it's oversold, and bank a 50% gain a few months later, which worked quite nicely for me last year! And at least I can mystery shop it without needing a PhD.
Regards, Paul.
But personally I'd rather buy a teapot maker when it's oversold, and bank a 50% gain a few months later
As the original source of the teapot comment, I need to point out that Americans aren’t feeling compelled to buy AWE either. They’re buying NVDA which has 4-bagged in not much more time and is still much cheaper than you’d expect. Most forum members would be shocked to learn that this “massively overpriced” revenue-doubling leader of the Mag7 has a CY24 PER beginning with a 2!
"if they are proper companies, why would they not list on Nasdaq where their valuation would be many multiples of the UK valuation"
Having worked in UK Finance Teams before (most notably Auto Trader (LON:AUTO) before it was listed), I feel that being listed in the USA would be a nightmare.
Internal Monthly reporting in the UK was arduous enough and it seemed that as soon as we finished one report it was time to start prepping for the next one. Most importantly it meant less time on actual analysis and improving the business itself.
In the USA, detailed reports (10-Q's) - similar to Annual Reports - are required every 3 months.
As a PI they're fantastic and I would greatly appreciate a similar system in the UK, or at least compulsory Trading Updates every 3 months.
But if I was personally compiling 10-Q's together every 3 months, it would be a nightmare and I imagine take much more time than the monthly reporting that I was used to. This would leave even less time to work on the juicy analysis that is meant to help drive the business forward.
As for valuations...I see plenty of expensive looking valuations of UK-based companies. Cerillion (LON:CER) and IQGeo (LON:IQG) immediately come to mind.
Abtan. I think compulsory trading updates for all UK listed companies every three months is a great idea. I can't see it being arduous for them to produce. And it seems like quite a reasonable expectation for the owners of the company to regularly receive such an update. Personally I tend to steer clear of companies that leave it much longer than 3 months because I feel that, if the company was on track, or ahead of expectations, then they would normally be quite happy to tell us about it. So if they tell us nothing, then it's fairly likely that they are not doing well.
I worked in a finance role for US public companies for many years and absolutely reject the notion that quarterly reporting is “not arduous”. It is a nightmare, and I don’t believe it is good for corporate management. It might not be so hellacious if shareholders were a level headed bunch who could be relied on not to have knee-jerk reactions to the inevitable quarterly variations but such holders do not exist in the US ( and absolutely do not exist in the UK). As a result a lot of pointless time has to spent on not surprising shareholders or at least asking them to think about short term cycles of supply and sales. Inevitably this leads to non-optimal management decisions. As you read the transcripts from quarterly announcements and see managements forced to go through painful arguments as to why their eps forecast was off by a penny you know that the company is wasting its time and (your) money on this exercise.
Aislabie, I made it quite clear in my comment that I was NOT asking for quarterly reports, I was asking for quarterly trading updates which are obviously far less time consuming to produce. It could be as short and as simple as "The company is trading in line with expectations." Management might not like it, but it should be the owners of the business that call the shots.
Essentially AWE designs networking chiplets. A chiplet is a semiconductor module that performs part of the function of a full (monolithic) system chip, leading to the creation of customisable and modular semiconductors that save development time and reduce power consumption. A good comparison in terms of application area is networking chip giant Marvell Technology (NSQ:MRVL) and one of the largest shareholders in AWE is associated with the founders of Marvell. AWE sells IP, not chips, and it’s their ambition to join the likes of Synopsys (NSQ:SNPS) and Cadence Design Systems(NSQ:CDNS) as providers of the raw IP for semiconductor design. When you look at the astonishing charts and valuations of the latter two you can see the appeal!!
This used to be my day job, so for clarity, comparisons with Synopsys and Cadence are not valid. They are very different companies whose main business is developing and licensing software used for chip design and verification. Yes, they also license some IP, but last time I looked this is a relatively small part of their sales. Their main profitable business is recurring revenue from software subscriptions in which between them they have pretty much the entire global market tied up.
There are so many red flags waving for me about Alphawave that it’s really not funny. I wish anyone invested luck, because you’re going to need it.
They (SNPS and CDNS) also license semiconductor IP but comparisons are not valid? I think you're nit-picking. Synopsys is one of my largest positions and I'm fully versed in its SaaS based EDA revenue stream. I was trying to explain the bull case for AWE in simple but necessarily un-nuanced fashion to less tech-y readers and, when professional analysts look at the bull case, they use Synopsys as the mature comparison on fundamentals.
What we can agree on is the number of red flags. I've already lost money on this one in '21 and I don't care to risk the same again
Article in Times on why to invest in Japan. There are Investments Trusts that invest just in Japan (and Japanese small companies) as well as ETF. I hold Nippon Active Value Fund (LON:NAVF) https://www.thetimes.co.uk/art...
In Discuss under Investment Trusts- there is quite a lot on Japanese Investment trusts- if you can locate in what is a lengthy thread now- browser search of the page should find it.
hedge for currency risk if you are a long term investor. I have lost my shirt in the past.
Bit of a miss for H & T (LON:HAT) usually reliable, downward trend ? (I hold but top sliced some months back)
Profits +40% but still below expectations. Management can't manage the analysts?
I've said this before but I don't understand why H & T (LON:HAT) had such aggressive forecasts. If they meet them then it's only in line and if they fall short, like today, the price gets whacked.
Much better to hold back a little for the odd beat to be included, and if things slow then it's still in line. Pretty amateurish I think.
Exactly, no forecasts and +40% on profit would probably be seen quite positively!
H & T (LON:HAT) Strong results, but agree very poor guidance. If they'd guided say 10% EPS growth and then delivered 40% the share price would probably go through the roof. They need to sort this out.
I've held this stock for a long time and don't plan to sell any based good results that have only missed some expectation.
Fully expect it to recover in the medium term and will enjoy the 4% +yield in the meantime
Impressive "ahead" TA from Brave Bison (LON:BBSN) this morning.
They've presented at Mello a couple of times and impressed (me at least!). Interesting shareholder register & net cash.
It's beginning to look like Oliver and Theo Green have something of substance here, and the ability to grow it?
Reader and esteemed writer comments welcome. I hold.
Why does Stocko have Henry Boot (LON:BOOT) as one of the biggest risers +5%, when it is down 10%?
Henry Boot (LON:BOOT) It says 10% down now. Quite often when there is selling I've noticed they seem to get the buys out of the way upon open then put the sells through, so it can quite often be a little misleading on the bell.
Yes it changed around 8.30am. Really confusing mixing yesterdays prices with todays. Prices should be zeroed before the market opens. I have noticed that some big fallers are updated later, even though the prices are down at opening,
For what its worth- I never look at prices on Stocko before 08.45 - and even then I often check elsewhere....
Henry Boot (LON:BOOT)
Why does Stocko have Henry Boot (LON:BOOT) as one of the biggest risers +5%, when it is down 10%?
to stick the BOOT into us holders - happy holder here despite current woes ref shareprice.
Henry Boot (LON:BOOT) yes pretty comfortable too - just short term trading weakness but the long term demand for their housing plots should be strong. Balance sheet is rock solid so shouldn't be a problem for them if trading a bit weak for the next year or so.
Henry Boot (LON:BOOT)
the thing with shares like this is one has a chance to sell when newsflow is good - in hindsight if i realised it was gonna drop over 33% from peek i woudl have sold but the long term sotory aint really changed and back then i wasnt really expecting contruction activity to slow down in genral (its really bad for everyone when their line of work dries up)
What i like about boot is that they are safe pair of hands - so i expect that these new expectations are very conservatively drawn up (thats not to say things cant get worse) - so no need to panic - the reasons for vanishing of earnings make sense. In some respects the fact that they have delivered £20 mill plus profits every year other than 2020 is somewhat better than i may have expected. With their lumpy stuff and prices acheived being subject to factors outside their control if they made nil profit in one year that woulndt bother me in ten slightest if the progress is still being made ref current/future projects. It helps thats the acounts are ultra conservative - the only slight blip on the radar is the higher debt levels - if the business is there and will make money though their gearing is still pretty sensible so no brainer to be using soem debt to drive business forward. What the current weakness does though is perhaps give me a chance to topup here as i wouldnt mind having a bit more of this company - so at least i should probably reinvest all the dividends i have had and spent elsewhere now when the price is at a lower point
I'm pretty sure Stocko prices are delayed 20mins or thereabouts.
Yes but some are delayed 15 minutes, some 30 minutes or so, it is a right mix up. If they reset the prices at the market open, at least any changes, would be todays.
Great numbers from Yu (LON:YU.) :
Record financial performance
· Full year revenue expected to exceed £450m (FY22: £279m), with organic revenue growth of over 60%.
· EBITDA expected to be significantly ahead of current market expectations, with expansion of adjusted EBITDA margin for the year, driven by strict controls and operating leverage.
· Average monthly bookings grew over 120% to above £55.0m (FY22: £24.5m, H1 23: £51.3m).
· Strong net cash position of £31.9m as at 31 December 2023 (FY22: £18.8m). A further £49.8m of cash was also held on deposit with our trading counterparty to support our hedging strategy and is due to flow back in the coming months.
https://www.investegate.co.uk/...
£80m in cash, Mtk cap £187m. Hope Paul/Graham cover the update. tia
Paul, I love reading your reports and listening to your Podcasts, they have greatly improved my ability to evaluate shares - well done and keep up the good work! It would be great if you could review Yu (LON:YU.) which I think is one of Ed's favourite shares.
A few broker changes this morning
Yu group ahead. EPS increased 23% and 24% for '23/'24
H&T profit 10% below. Cut EPS 10% '23 and 9% '24
Eleco 3% EPS increase 2023
Staffline - 2024 EPS cut 29% 2025 cut 25% tho wouldn't know reading the company update.
My morning smallcap tweet: Housebuilder gives holders the order of the BOOT
Henry Boot (LON:BOOT) Chapel Down (LON:CDGP) Brave Bison (LON:BBSN) Eleco (LON:ELCO) Everyman Media (LON:EMAN) Netscientific (LON:NSCI) Esken (LON:ESKN) Crimson Tide (LON:TIDE) Boku (LON:BOKU) H & T (LON:HAT) Cornerstone FS (LON:CSFS) Tristel (LON:TSTL) Yu (LON:YU.) World Chess (LON:CHSS), Quiz (LON:QUIZ), Ocean Harvest Technology (LON:OHT), Eurocell (LON:ECEL), Staffline (LON:STAF), Netcall (LON:NET)
◄Henry Boot (BOOT)► guides FY-Dec in line but warns FY24 profit significantly below mkt exp. [SP=209.5 Cap=281m]
◄Chapel Down (CDGP)► guides FY-Dec rev up 13%. In line? Outlook bullish. [SP=65 Cap=111m]
◄Brave Bison (BBSN)► guides FY-Dec ahead of market expectations with rev up 12%, net rev £20.8m up 23% and adj pretax £3.6m, up 38%. [SP=1.86 Cap=24m]
◄Eleco (ELCO)► guides FY-Dec rev £28m up 11% in 'underlying and constant currency terms', ahead of consensus. ARR up 24%. Underlying rev? Profit also ahead of consensus but no number. [SP=89.5 Cap=74m]
◄Everyman Media (EMAN)► guides FY-Dec rev up 17% and EBITDA up 19%. Figs are compared to FY22 with VAT benefit removed. Performance in H2 was marginally affected by the Hollywood strikes. Guides FY24 in line however. Slate of forthcoming films includes a film of a musical, a sequel, a sequel, a sequel, a sequel, etc etc. [SP=58.69 Cap=54m]
◄NetScientific (NSCI)► portfolio company Glycotest has closed a $1m follow-on investment. [SP=59.24 Cap=14m]
◄Esken (ESKN)► dispute with Carlyle Global Infrastructure Fund worsens, as it demand repayment of £194m convertible by 16 Feb citing technical breaches. "There have been no payment defaults by LSA in relation to the convertible loan agreement and LSA cashflow has been in line with expectations." ESKN and London Southend Airport investigating the validity of the claims. ESKN still seeking a buyer for the airport. [SP=0.85 Cap=9m]. I hold.
◄Crimson Tide (TIDE)► guides FY-Dec rev up 15%. EBITDA £0.4m+, above mgmt exp at the time of H1 results. Outlook positive. [SP=172.26 Cap=11m]
◄Boku (BOKU)► guides FY-Dec rev up 30%+. Adj EBITDA at least $27.3m, up 33%, ahead of market expectations. [SP=157 Cap=466m]
◄H&T (HAT)► warns FY-Dec pretax c.10% below market forecasts due to weak ending to year. Q4 volmes up 3% but with lower av ticket price. [edit] Rival Ramsdens guided in line on Jan 15, broker left FY24 U/C. [SP=398 Cap=175m]. I hold.
◄Cornerstone FS (CSFS)► has signed an agreement with Mastercard to launch a corporate card scheme to launch Q3 2024. [SP=35 Cap=20m]
◄Tristel (TSTL)► Canada has approved Tristel ULT as a Class II Medical Device for endocavity ultrasound probes and skin surface transducers. [SP=430 Cap=204m]
◄Yü (YU.)► guides FY-Dec ahead of expectations with organic rev up 60% and EBITDA significantly ahead of market expectations. Guides operational cash inflow substantially ahead of market expectations in FY24. [SP=1115 Cap=187m]
◄World Chess (CHSS)► launches Women's Wednesday Online Tournament Series, the "Swiss Queens Wednesday". [SP=6.6 Cap=40m]
In line: QUIZ, OHT, ECEL, STAF, NET
Appreciated the weekend Podcast Paul - pleasing your market perspectives and acuity weren't dimmed by the customary sojourn to Gozo.
Impossible to judge market movements looking into 2024. So why bother? I'm focussed purely on company risk and inherent value and am prepared to wait years for the market to recognise this or a welcome liquidity event.
Wincanton a recent example, where the value offered became even clearer after a mild profit warning took down the market cap a great deal further and then the news to follow of the fully-funded pension.
My only regret? I only had a normal sized position, but that happens when there are so many candidates with funds needed to back them.
Overall:
You and Graham keep up the sterling efforts!
Boohoo (LON:BOO) CFO steps down with immediate effect, new CFO in place.
Rats leaving a sinking ship ?
or the influence of Frasers?