Small Cap Value Report (Tue 23 July 2019) - IDOX, TUNG, BKS, NXR

Good evening/morning, it's Paul here.
Let's start off with a couple of stragglers left over from Monday's RNS.
Idox (LON:IDOX)
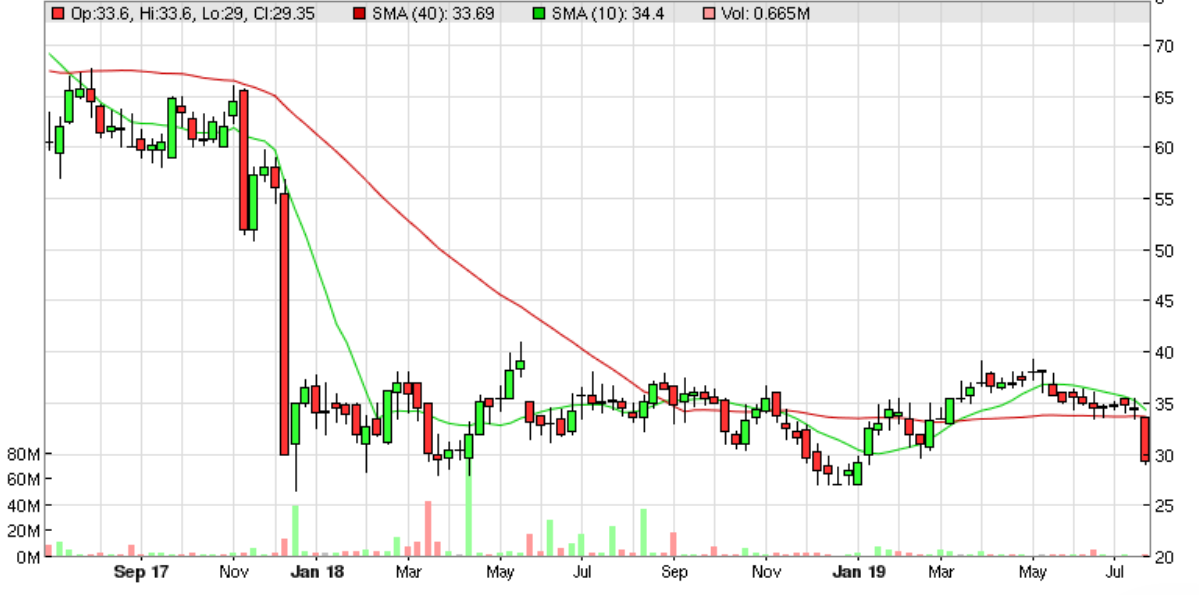
Share price: 29.4p (down c.14% yesterday, at market close)
No. shares: 415.5m
Market cap: £122.2m
IDOX plc (AIM: IDOX, "Idox", "the Company" or "the Group"), a leadingsupplier of specialist information management solutions and services, today announces its unaudited half year results for the six months ended 30 April 2019.
This software group seems to be permanently restructuring. The heavily loss-making digital division is now gone.
Forecast reductions - there's not a lot of point in analysing the interim results, as there seems to be an H2-weighting. So we cannot just double the interim profits, to arrive at an estimate for the full year. In this case it's easiest to rely on the house broker's forecast, updated today on Research Tree. This shows EBITDA reduced by 10%, and EPS by 20%, for the full year ending 10/2019.
The company likes to talk about EBITDA, but in my view that number is not reliable for valuation purposes, because the company looks set to capitalise costs of over £4m into intangibles (£2.2m in H1), which note 8 shows is mostly development costs - which in my view is ongoing payroll costs, which is part of running the business, so it cannot be ignored for valuation purposes. This is mitigated by a useful £832k tax credit last year.
Also, as it has material borrowings, we cannot ignore the interest charges either, another reason why EBITDA is not a good measure here.
There are lots of other things I don't like about these figures, so I'll keep this brief & move on;
Balance sheet - is too weak, making this share high risk, in my opinion.
Net debt - looks uncomfortably high to me, at £25.4m - bank facility expires in Feb 2020, so is classified as a current liability - which makes the current ratio look very bad. That won't be a problem if the bank facility is renewed, but it does reinforce the reality that this group is heavily dependent on the confidence of its lenders.
Going concern note - reinforces this point by emphasising that the group is reliant on renewal of its bank facilities, in 7 months' time.
Dividends - not being resumed at this stage, which is wise given the stretched balance sheet.
Accounting irregularities - sounds like some former staff fiddled the figures historically - on a smallish scale, but it doesn't inspire confidence in the financial controls.
Acquisition - currently assessing a bolt-on acquisition. Is that wise? It would need an equity raise to do this safely.
My opinion - as you've probably gathered, I'm steering well clear of this one. There are too many things that have gone wrong, combined with a really weak balance sheet (negative NTAV of £-41.4m), which makes this share uninvestable for me.
Risk:reward looks unfavourable. If problems were to arise with the bank facility, and if combined with weak H2 trading, then the risk is that shareholders could face an emergency fundraising. We've seen recently with Staffline (LON:STAF) (in which I hold a recently opened long position) that the price of an emergency equity fundraising can be ruinous for existing shareholders (and PIs often don't get access to emergency fundraisings, so can get diluted heavily).
Given that I don't know how likely the IDOX business is to turn around, and improve trading, nor the likelihood of it renewing bank facilities in a few months, then why would I want to risk it? Especially when we have so much macro uncertainty around. It strikes me as a complete punt at the moment, unless you know the business inside-out - which would enable you to make a more informed decision perhaps.
Tungsten (LON:TUNG)
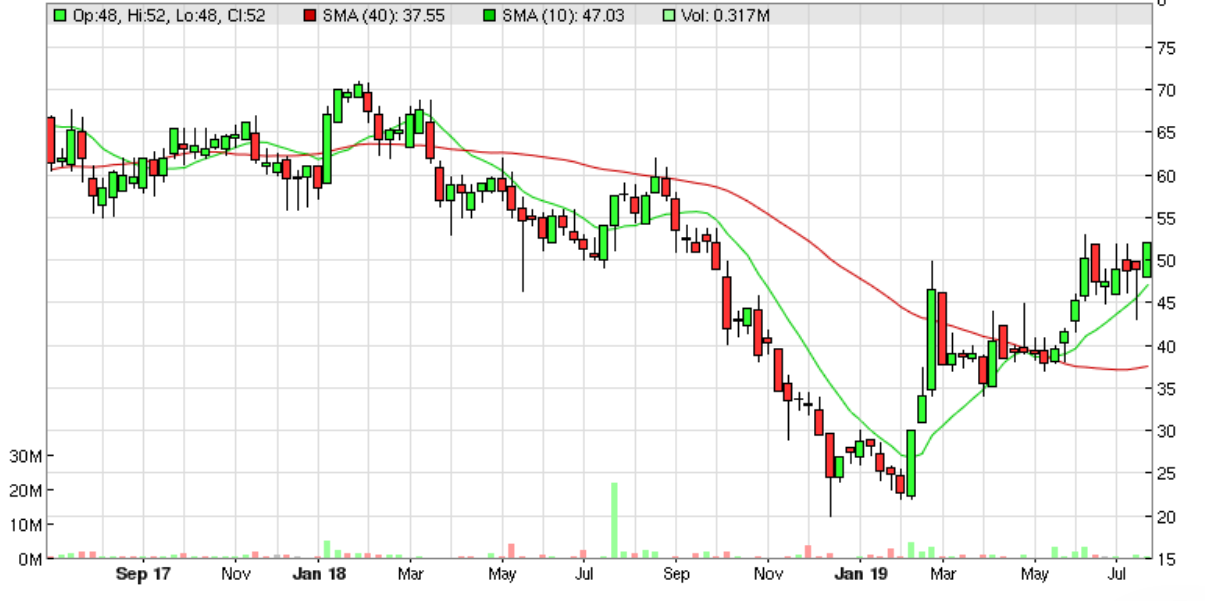
Share price: 52p (up 6% at market close yesterday)
No. shares: 126.1m
Market cap: £65.6m
From one struggling software company to another. This is an accounting software company, focused on eInvoicing, mainly for large companies. Its shares were a shooting star originally, with wildly exaggerated claims made by former boss, Edi Truell, which subsequently failed to be achieved.
- Results for FY 04/2019 don't look much good to me;
- Revenue growth of only 6.7% to £36.0m
- Operating loss of £5.2m (reduced from loss of £12.1m prior year)
- Cost-cutting has reduced operating expenses by 10% - a saving of £3.3m against last year. The overheads have looked top-heavy here for a long time, so progress has been made.
- Tungsten Network Finance to be divested (as previously announced on 30 April 2019), which said;
The Board has concluded that, whilst Trade Finance is an important service to be able to offer to our clients, its provision is non-core. Accordingly, Tungsten has appointed an M&A corporate finance firm to advise and handle this divestment. An information Memorandum will be finalised shortly and a list of interested parties has been prepared.
Balance sheet - it's no secret that Tungsten needs more cash. In the restructuring RNS of 30 April 2019, Directors even agree to having their remuneration more focused on deferred share, than cash. I like that - it shows decent commitment to turning around the company. But it also shows that the company is pretty near the last chance saloon.
Its balance sheet is dominated by nearly £121m in intangibles (mainly goodwill). Write off all of that, to be prudent, and NTAV goes negative, at £-4.5m - not good, but not a disaster either.
I spot an unusual liability called "contract liabilities" within current liabilities, of £6.8m. What is this? Note 1 explains that this is deferred income - i.e. where cash has been received up-front, but no services yet provided. Therefore the real cash position is actually worse than the net cash of £2.8m suggests.
Tungsten is clearly getting very close to running out of cash. Note 1 contains a going concern comment, saying that Directors believe it can continue trading without needing to draw down any more on bank facilities (which only seems to be £1m drawn at 30 Apr 2019). I don't know what the terms of the bank facility are - anyone considering a purchase of this share would need to find out this, as it could be critical to whether the group can survive or not.
I think another equity fundraising looks almost a certainty. That's not necessarily a disaster though - if the company can get investors excited enough (again) to pay around the current share price, then £6m-ish would only be 10% dilution, and would probably be enough to secure the company's future. The massive cash burning days are over now, so a modest placing should be do-able.
Capitalisation of development spend has been greatly reduced, from £7.2m last year, to £2.9m this year - a good sign, as the company has focused its activities more to reflect the reality that the coffers are nearly empty.
My opinion - the business model has considerably changed, and looks a lot more sensible now. Cash burn has been brought under control, and there's a much clearer focus. The product is used by lots of large companies, so it must be pretty good.
Overall then, despite the lamentable track record, I think there might be a chance of a turnaround working. If sales really start to take off, and it moves into genuine profitability, then the valuation could re-rate higher. How likely is that to happen? I have no idea!
At this stage then, this one is really just for punters. But I'll keep it on my radar, as something that might be potentially interesting in future. Also, I'd want to see a placing successfully completed before investing here, so that solvency is not an issue.
The chart looks a lot like many other companies - the indiscriminate sell-off in Q4 of last year, has now been recovered, now that the USA & other Govts have kept the cheap money taps running, and any idea of normalising interest rates seems to have disappeared again. Equity markets are clearly addicted to cheap money, maybe this is the new normal? It is for now, or at least until the banking system shakes itself to pieces again - which looks inevitable eventually, given the huge gearing that's building up all around us again.
Could TUNG attract interest from a Venture Capital, or Private Equity buyer? Actually, it wouldn't surprise me. The size & quality of its client relationships, and the potential acceleration in growth if more cash is thrown at the new strategy, might be of interest to one of the many well-funded VC/PE companies. I saw some astonishing stats today, and just how much spare cash these VC/PE companies have got, and they're paying some astonishing high, insane valuations, for growth/loss-making companies with a big idea. What could possibly go wrong?! But in this type of bull market, TUNG might attract some interest perhaps?
Beeks Financial Cloud (LON:BKS)
Share price: 91p (up 17% today, at 12:22)
No. shares: 50.9m
Market cap: £46.3m
(at the time of writing, I hold a long position in this share)
Tier 1 Client Wins & Trading Update
A cleverly worded RNS title there, by including the phrase "Tier 1" in the title, more people will click on it and read it!
Introduction - Beeks is a Glasgow-based IT company, which provides a connectivity service through the cloud, for financial organisations & traders. It's a very interesting little growth company, in my view. The company came about by accident! An ex-IBM man, the CEO Gordon McArthur had his own automated trading algorithms, but was frustrated by the latency between him, and the exchanges in e.g. America. So he persuaded several exchanges to let him put his server physically in the same room as theirs, thus cutting down the connection distance from thousands of miles, to a few feet. That way the automated algorithms had almost instant execution. Exchanges then passed on queries from other traders to McArthur, so he began allowing others onto his server, thus building a business which has grown into Beeks, and connects to over 100 different exchanges worldwide, allowing customers to pick & choose which ones they want to connect to, and with instant self-setup.
The videos from my friends at PI World are most informative, here.
Client wins - these don't sound particularly game-changing in terms of money (e.g. one is £500k over 2 years), but it does provide further evidence that the company's services appeal to large new clients. It's really all about future upside, at very high gross margins, just
The other contract win is described as;
The global bank has contracted with Beeks' via a partner for the delivery of an initial proof of concept for a fixed income implementation. This proof of concept is revenue generating and is currently live with the bank. It is anticipated to be a pre-cursor to an extensive deployment with the client.
Trading update - this is for the year recently ended, on 30 June 2019.
The Board is pleased to confirm the Group traded in line with expectations for the year ended 30 June 2019 and looks forward to providing a further update at the time of the Final Results, to be released in late August.
If it's in line, why is the share price up 17% today? I think that's partly due to the contract wins making investor sentiment more bullish. But also because the share price has been drifting down for most of the last year. People inevitably then start to assume that trading must be weak.
Whereas actually, with illiquid micro caps like this, the share price can move all over the place, on very little volume. Hence the share price movements can often be considerably detached from the reality of how a company is trading. This is one aspect of micro cap investing that makes it considerably difficult, and indeed at times very frustrating.
Most of us find it dispiriting to have heavy paper losses. Yet the big multibaggers nearly always involve having to ride out significant losses along the way. This problem obviously doesn't affect the many social media punters who always seem to have miraculously sold at the top, and bought at the bottom, repeatedly!
Valuation - there's an update note on Research Tree today, leaving forecasts unchanged, at 2.9p underlying EPS for FY 06/2019. That puts it on a PER of just over 31 - a punchy rating you might say, but not when you consider that the company is producing strong organic growth.
Forecast EPS for FY 06/2020 is 4.0p, which if achieved would drop the PER to 22.8 - much more palatable. Given that FY 06/2020 is now the current financial year, and the outlook seems positive, then I think it's OK to use this as the valuation measure. Providing nothing goes wrong, then I think that valuation is justified.
Outlook comments sound upbeat:
"We are pleased to announce a strong second half and successful outcome to the year, in which we delivered continued revenue and profit growth, while expanding our offering.
"Beeks Financial Cloud is growing the services we can provide and therefore the variety of customers we can serve, as reflected by these exciting Tier 1 client wins.
We are seeing growing interest from financial services organisations in managed cloud computing and connectivity.
The resilience and scalability of our network, combined with our specialist financial services expertise, means we are increasingly well positioned to benefit from the growth of this market and we look to the future with confidence."
OK, the above is mostly generic positive stuff, but I feel there is good reason for management to be confident - e.g. positive results for 06/2019, growing markets, new customers, new services, high recurring revenues, high gross margin, and not much direct competition.
My opinion - it's been a bumpy road in terms of share price, but I'm pleased with the way the company is performing, and the current share price looks reasonable - neither cheap, nor expensive, the way I see it.
As with most of my micro cap investments, it's all about backing strong management. What's most impressive about Beeks, is that it created its own niche, and has historically done very little actually selling - customers sought it out. What does that tell you?! I see that as a remarkably strong position.
There's an argument that Beeks doesn't charge enough - its self-service cloud service seems remarkably cheap, if you look on its website. I see that as an opportunity - once it's bigger, there could be scope to increase charges, and hence dial up a much bigger profit.
In my view this share is too illiquid to try to time the ups & downs. It's more a buy & hold share, for say, the next 5 years. I reckon it could pay off nicely over that sort of timeframe, but only for investors who can tolerate stomach-churning volatility along the way.
I'll crunch the numbers in more detail, when results come out in late August. In particular, I want to check that it doesn't need more cash. The last interim results looked OK in that regard. The CEO has a huge personal shareholding, so we're in his hands. Those of us who met him at Mello were left very impressed. If micro cap investing is all about backing smart entrepreneurs, then this one fits the bill, I reckon.
Norcros (LON:NXR)
Share price: 218p (up c.2% today, at 14:00)
No. shares: 80.4m
Market cap: £175.3m
Trading statement (AGM)
Norcros plc ("Norcros" or the "Group"), a market leading supplier of high quality and innovative bathroom and kitchen products, issues the following trading update covering the 13 week trading period to 30 June 2019...
The year end is 31 March, so today we're getting a Q1 update.
Graham published an excellent review of the FY 03/2019 results here, which I've just read to get me up to speed. To summarise - the group was trading well, and shares look very cheap on a PER basis. The reasons are: worries about exposure to South Africa, and the large pension scheme.
Today's update - it's in line;
The Group continues to win share in our two main markets with the Board's expectations for the full year remaining unchanged...
You can read the RNS yourself, if you're interested in the additional detail given about revenues.
Outlook comments - this sounds encouraging, given the wobbly macro backdrop;
"We have delivered a resilient first quarter performance against an uncertain economic and political environment, which is a testament to our leading market positions, our portfolio of well-established brands, the strength of our offer and our strong financial position.
The Board remains confident that the Group will continue to win market share and make progress in line with its expectations for the current year."
So, whatever they're doing, it seems to be working!
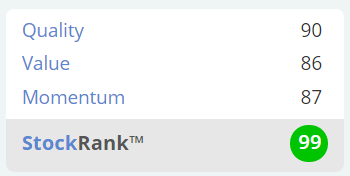
Valuation - Stockopedia sums it up well, as usual - a high quality business, that's dirt cheap (although I don't know whether the Stockopedia algorithms factor in pension deficits?)
My opinion - Graham mentioned in his last report that he's leaning towards seeing this share as under-priced. I agree. Management seems to be doing a good job in gradually growing the group through decent quality acquisitions, without stretching the bank borrowings too much.
The strategy is to grow the business, so that the pension scheme is diluted as a lesser issue, once the group is bigger. So far, it seems to be working.
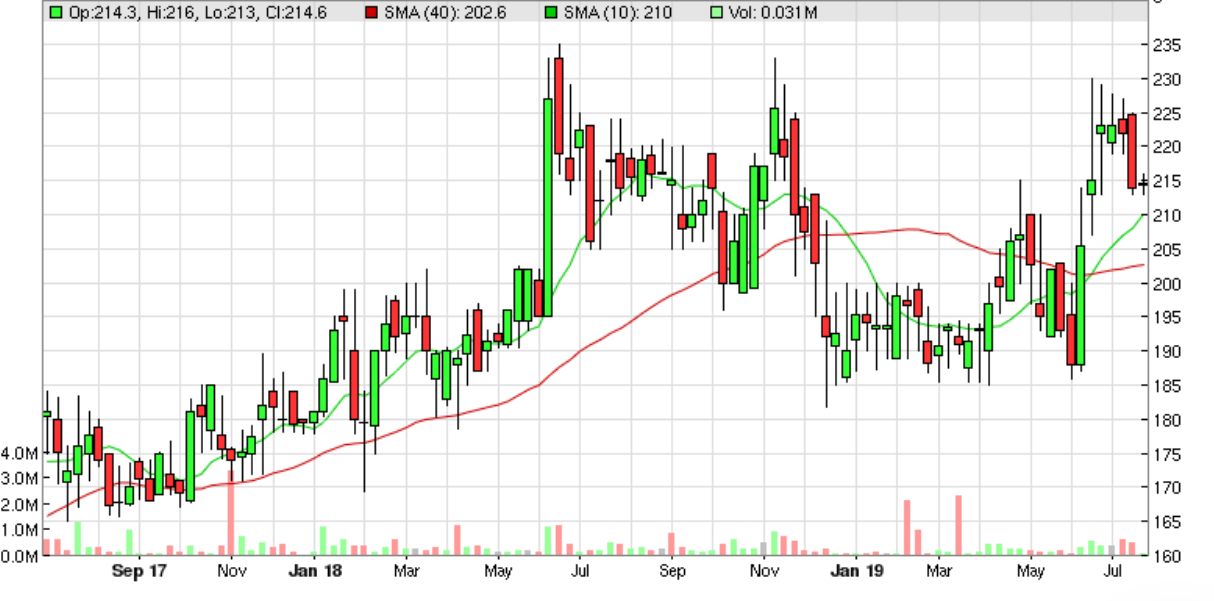
I'm not sure what's likely to change here though? Every time the share tries to break out upwards, it seems to be stifled by stale bulls trying to exit.
The best thing might be if someone comes along and bids for Norcros. But who would want to take on that massive pension fund?
I'm succumbing to the heat, as it's 28oC here inside my flat, so will have to park this until it's a bit cooler.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
I suspect the Tier 1 non bank addition is Fidelity. If so it would be interesting to know if it is their international or US division. Could leave room for upscale although Fidelity are primarily an equities house which BKS don't do.
Very interesting goings on today with Scapa (LON:SCPA) on their AGM day.
A quite positive AGM statement released early doors but which made no mention of the lost Convatec business nor the upcoming litigation.
There was a modest rise this morning on the back of this.
The AGM was due to kick off at 10:30am and the results of AGM statement was issued after market close this evening.
However at around 2:45pm the blue touch paper was lit and the shares rocketed to finish up 20%.
I wonder what time the AGM and/or any post AGM meetings actually finished?
Was anyone here in attendance?
Hello. I don't usually make analysis requests...but how about GetBusy (LON:GETB) ?
Its been covered a bit in SCVR in the past. I did some cursory research into company when they announced about month ago that they were tidying up their reporting format into product verticals rather than by country. Yesterday I decided to look again ahead of interims today and took a small position. IMO its got too much to prove to be a big position but here's why I thought it probably mispriced and worth a bit of risk:
1) It has been successfully growing revenue and margin
2) It was spun out of a successful business in Australia (Reckon Ltd - accounting software) owned by GetBusy's CEO's father - who has a 20% stake in GETB
3) CEO is relatively young (31?) and unproven although has had startup experience so has some wear and scares....plus some fatherly mentoring. Not necessarily all positive but potentially positive
4) After listing they seem to have gotten themselves an experienced FD sort as CFO who has tidied up reporting
5) I tendency to expense R&D rather than capitalise
6) Most established product 'Virtual Cabinet' is most of revenue (c. £8m pa I think) and cash flow positive.
7) Second earning product is called 'Smart Vault' and was acquired just before IPO. Its been growing at 30-40% rate I think and is approaching cash flow breakeven. I think it had a bit of sketchy rep with customers sometimes in the past and GETB have been repointing the product since taking over with what seems like improvement in perf
8) 3rd product is live beta. They have given out free and don't charge. Its called GetBusy and is B2B communication and productivity software. They admit they need to work out how to commercialise but the live free beta with their installed 65k+ business and 400k ish global users is the right move. Once they find way to fee for it its pure $ to bottom line. There's high but unknown optionality in this
9) on 8, they've put in about £1m pa to develop the beta. If they hadn't they would be cash flow positive today
10) Recurring revenue is very high - >90% I think.
11) Once you start using their product there is a very high inertia re moving. Their client loss rate is less than 1% pa
12) The rate of earnings growth as revenue surpass costs base should be high
Negatives
1) Some very heavy options incentives of about 10m shares (if I recall correctly) The strike is around 50-100p range so distance to travel. From my cursory reading I recall 2m to CEO, 1m ish to CFO so I assume quite a lot going to the broader team (in true tech start-up style)
2) Could be more economic cyclicality than think as little businesses go under or cut costs (though inexpensive so not likely first)
3) Competition...but they are growing fairly rapidly suggesting that that product has desirability and perhaps that users are good promoters for them in business networks
Its a small position for me relative to higher conviction and stuff that can be analysed with more clarity...but I think quite high upside potential and perhaps quite long duration and durable
£TRMR We had a lot of discussion on here about over last few months so I know there are several interested posters.
Whilst not a specific news item today I've noticed several integration announcements recently and the share price has had a bit of a relentless rise from the 75p nadir up to 170p+ . It appears as though the market is gradually coming to the conclusion that the business is not a fraud and therefore pretty cheap. New CEO seems to be doing a decent job with the market messaging and the share buy backs seem to be doing their job of mopping up any excess stock. Also feels a bit like the inevitable merger stock overhang has cleared and there are less stale bulls left of the two old entities hanging around looking for a reason to sell.
Appreciate this is a marmite stock - does anyone have any other views on reasons for the rise as wondering if I've missed something specific?
Shhhhh! I'd I've kept quiet until above 250p at least ;) ...who knows what randomness is afoot and with a share price that sketchy and a company so disparaged (much of it correct from rearview mirror perspective) where the SP might end up
£TRMR is up over 20% today on high volume.
...Nearly 10% of the market in Tremor International (LON:TRMR) traded today...something surely going down and RNS reveal coming...
(LON:TRMR) we spoke too soon............
It's interesting on Tremor International (LON:TRMR) - I've no idea what moved it up over 2 prior days and down today so much. Volume yesterday for >20% move up was 10m whereas today -12.5% is on about 600k which is about half average volume. Yesterday there seemed to be a very big crowd of mainly buyers. Today there as a fairly small crowd of mainly sellers. Beyond those banal observations there's a lot to fill in....
Agree that DOTD should be covered here although this is, after all, just a detailed trading update. I mean between them and TUNG there is a gap as wide as the Cheddar Gorge. I no longer have either but wish I had held my DOTD.
Re Revolution Bars (LON:RBG)
I notice that unlike prior years there has been no Trading statement in June, prior to the releasing of preliminary results, usually in Sept., unless I have missed something?
They have stopped the dividend to allocate capital to refurbs of some of the bars, and to reducing the borrowings.
However, they said in March some other refurbs impacted on the results for December, when like-for-likes stats were down.
The silence on trading is a bit worrying, because if its good/OK, usually there is an impetus to tell the market. So, I am expecting some disappointment.
I am a holder.
Revolution Bars (LON:RBG)
I guess that the norm is that they update in trading late july - this was the case in 2017 and 2016.
The june 2018 update i am presuming was a forced profit warning rather than the norm.
so i would be surprised if something is not scheduled to be released in the next 7-9 days - it should be easy enough to confirm with the company though.
i would say the silence should be good news in that they haven't had to warn again on profits as they are prone to do - unless they cobble together an excuse that the reasons are such that they are only finding out now.
One slight anomaly is that the forecasts for 19 and 20 have been reduced again in the last month according to stockopedia.
Is this just late feeding through of numbers from March or are the company slightly lowering expectations behind the scenes without advising the market explicitly that this is the case ? Note 0.9 mill reduction on 5.6p EPS expected previously is over 10% - so i would hope this is slow broker update based on what they said March rather than anything untoward.
Revolution Bars (LON:RBG)
If I am interpreting the Stocko data correctly then the consensus is made up from 5 analysts, so the markdown might just be an update from one of them?
There could be an element of "read-across" here from other results (both of pubcos and other related companies).
I note that £
Hi Trident,
Re Revolution Bars (LON:RBG) (in which I have a long position) - we'll have to see what the next update says.
Last year they warned on profits on 14 June 2018, just before the year end of 30 June 2018.
The way I see it, the fact that we have not had a profit warning this year, suggests it should have traded in line with expectations - otherwise they would have had to inform the market. Also, they're up against soft comparatives for last year. Therefore, I'm quietly hopeful that the next update might be better than the bombed-out share price suggests.
Interim results to 29 Dec 2018 were not good, but it's still generating a ton of EBITDA - which should enable it to self-fund refurbishment of the tatty sites which are pulling down group performance. Other issues, mainly a loss of key area managers, who took their best site managers with them, should be fixable, with no distractions from new site openings.
The market cap looks amazingly cheap to me, but that's because there's little liquidity, so drip drip selling from stale bulls results in long periods of the share price being bombed out. We've seen this before, then it shot up when Stonegate bid for it at 203p. I reckon, at the current valuation of c.65p, it's only a matter of time before another bidder turns up. We saw a recent (much larger) deal with EI (LON:EIG) at a reasonable premium, so there are bidders out there, despite macro uncertainty.
If you compare the valuation of RBG with Loungers (LON:LGRS) it's unbelievably cheap - especially as RBG has very little debt compared with LGRS. And the EBITDA performance isn't actually that different, although there is a widespread view the LGRS management are very good, and newish RBG management yet to prove themselves, but seem determined to fix the problems when I last saw them.
Anyway, let's see what happens!
Best wishes, Paul.
Hi Paul
Thanks for your reading of the Revolution Bars (LON:RBG) situation
Probably, I am just preparing myself for disappointment. I did buy some a little while back to average down a little but then the price dropped again. So I have the occasional outbreak of bullishness which has not been rewarded thus far, but fingers crossed.
Just on another subject I note that UP Global Sourcing Holdings (LON:UPGS) have been buying quite a lot of shares for their Employee Share Trust.
This is a more honourable, and equitable strategy for supporting option awards, than just issuing new dilutive shares. It might also suggest the Directors see the stock as under priced and are taking advantage of an opportunity
However, being of the Eeyore tendency, I can also see this as a means of playing Keepy Uppy with the share price for short term benefit in relatively low volume markets, and also using up quite a bit of working cash.
Of course it gives a nice dividend yield, and has a trading statement that suggests it will exceed market expectations - so there is no pleasing some people like me.
However, this is one of my few stock choices where I have averaged down quite a bit, that has paid off - for once!
Good morning Paul
Lots of interesting announcements today though I am not sure if they are all in your areas of interest:
Beeks Financial Cloud (LON:BKS):
* they now have 3 tier 1 clients which should give them good reference clients to help them to add more
* winning new clients at the end of the year gives good committed revenues for next year
dotDigital (LON:DOTD)
* more steady growth
* GDPR does not seem to have caused them any problems
Franchise Brands (LON:FRAN)
* forecast beating H1 results
* I wish the names of their franchises were not so off-putting
* management have a good track record in building franchise businesses - if I am right they were the original founders / builders of Domino's Pizza (LON:DOM)
Fevertree Drinks (LON:FEVR):
* nothing much happening this year
* justification of their high price will depend on the success of their US and international expansions
Your thoughts on any / all of these would be much appreciated
Interim results out this morning from McColl's Retail (LON:MCLS)
This was covered in some detail back in February both by Graham and in the comments, so not worth revisiting all of that.
They key take outs from this morning for me are :
Over the full year I still think they are about cash-flow neutral prior to any of the planned improvements.
Fairly much steady as she goes here then. Still in my view an interesting potential investment, but perhaps still a little early. Share price down slightly this morning, but still up nearly 20% on when discussed in February. (Possibly in part because of an expectation that there might be a deeper tie up with WM Morrison Supermarkets (LON:MRW) in future - although nothing much to support that in today's announcement)
IG Group (LON:IGG)
I don't think there is much to say here - one has to be prepared for the long haul with this one - presumably the quality of the company and its core earnings is setting some base in the shareprice despite the ever worsening tend in earnings. 63p 43p and 41p eps for 2018 2019 2020 est.
I bailed out of these as i though 888 Holdings (LON:888) looked a better medium term bet IMHO as i have more confidence that they will be able to churn out reasonable numbers although i have to admit both companies have similar regulatory and other similar obstacles that make things hard to predict.
Perhaps the chomping dividend yield makes the IGG shares still worth holding - at present they are paying out close to 100% of their earnings as dividends and presuming the company doesn't need the cash - that's not bad bang for your buck when the shareprice is going nowhere (cue a bit of Therapy)
After reading an Animalcare (LON:ANCR) trading statement, I checked their website to see what they do. A first step on the way to understanding the business.
Something to do with animals appears to be the answer, but there doesn't appear to be a picture or a mention of a single specific product or service on the entire website. Much BS, very little fact.
I did notice they have an LTIP and they can get the first 25% of this for as little as 3% EPS growth (to me it is not 100% clear if this is 3% PA or 3% total over 3 years).
Already gone in the "too difficult" pile. Most good businesses manage to explain what they do on the website.
£ANCR went on my blacklist following the Ecupharma reverse takeover which was covered here in June 2017.
Also on a dedicated thread at https://app.stockopedia.com/content/animal-care-reverse-takeover-195959
I was puzzled by your reference to their website because I remembered it being fairly clear. I see they in fact have two sites, a corporate group one that Stocko links to, and a more consumer facing one at animalcare.co.uk
Thanks JohnEustace! I was looking at the corporate website. All that's missing is a big clear link from the ANCR corporate website to the consumer one, or perhaps a lack of curiosity & nous on my part ! A little more visibility on how they are evolving the product portfolio would help too.
Norcros (LON:NXR)
In line trading statement for Norcoss this morning, that's all i ever hope for with this company as delivering on forecasts forecasts for the next couple of years will massively improve the balance sheet (acquisitions ignored and there will probably be more !) - in 2 years the pension deficit will likely be less of an issue and - and in my mind the business becomes less risky as recent acquisitions prove they can add the cash to the bottom line that was expected when they were bought never a given as we all know.
As one would expect as they have met expectations the shareprice has returned to near historical highs - to me the risk of holding would be that profits would not meet market expectations.
Despite the share price appreciation and trading as expected the p/e is still a pretty undemanding 6.5 - although i expect at least a 20% discount to be given to this company down to the south african slant to their earnings.
I will continue to hold in the hope they continue to deliver as expected.
Re Norcros (LON:NXR) I recently sold off, and am happy enough to have done so on this update, as I consider that revenue growth is weaker than usual and the zero lfl growth is also off
Norcros (LON:NXR)
I recently sold off, and am happy enough to have done so on this update, as I consider that revenue growth is weaker than usual and the zero lfl growth is also off
The way i look at at is that while the pe is 6.5 the business doesn't need any growth to generate sufficient cash over the short/medium term so that shareholders should do well..
If you look at current years net profit 29 mill - that should be giving them £10 mill + warchest available to buy a new business (for cash if they wanted) - say buying at pe of 10 - that's £1 mill extra profits going forward or a 3.3% increase in earnings they can expect from utilising that spare cash. So that is an added benefit of a low pe company with decent cashflow that they do have this added weapon at their disposal. the one issue at present is that as debt is quite high they may choose to repay debt rather than acquire added on business.
So i continue to hold in the hope that one day the market will agree with me that this company is worth more that the current shareprice gives it credit for. I would say the market deffo disagrees with my stance here as this share is pretty much eternally cheap as chips on pe.
Fevertree Drinks (LON:FEVR)
Pretty anemic growth announced today (i hold) and shares are down 6%.
The good news is that they are on track to meet market expectations so one may think its a surprise that the shares are down 6% but they have often exceeded prior expectations at this time of year - so not what the fanboys and fangirls where hoping for.
Growth is expected to be back up to 15% next year so perhaps if there is bad news next years expectations may be lowered somewhat?
Note next years EPs is expected to be 67.3p and price of 2167 gives pe of 32 - not outrageous for a good brand with growth something in double digits with worldwide market to grow into - lets hope the current gin craze lasts as long as te one in the 1600's
United Carpets (LON:UCG) reported today. A fairly flat year and the receivables are up sharply but with an impairment of about half a million because of the introduction of an installment payment option. UCG seem to be a long-term survivor but I can't see any significant growth here until the housing market takes off again, if it ever does.
I'd be very interested in your view of the results from Fevertree Drinks (LON:FEVR) which look very weak considering the valuation
IG results arent the best,
I know Graham is a holder and theres quite a few other holders on the forum
Paul, in addition to favourites Beeks (£BKS) with its exciting announcement and Joules (£JOUL) good figures, could you please comment on dotDigital's results please? (£DOTD).
Thanks
£BKS share price moved down sharply the other week off the back of some PI selling when a blog mentioned concerns around hitting their numbers and lack of tier 1 new orders. Todays announcement does two things.
(1) trading is in line so the expected strong H2 has materialised as expected (this is a fairly normal pattern with this business so nothing new). It also means ARR going in to next year is around £1.75m higher than actual 2019 revenues due to recurring nature of the business. Thus to hit next years numbers requires circa £3m of new business.
(2) Todays Tier 1 announcement reduces risk around this as it probably adds circa £1m of those revenues so even if the core business only generates 15-20% growth it should hit targets. Therefore, I now see upside risk to forecasts.
My morning smallcap tweet: Scabby dog RM2 asks for last scraps
£RM2, GetBusy (LON:GETB), dotDigital (LON:DOTD), Seeing Machines (LON:SEE)
RM2 International (RM2) $6m rescue placing at 2c (why in US$?). Pre-suspension SP was 8.5p. Will go bust if placing not approved. Remains suspended due to late accounts. Last placing in Nov at 105. 99.9% down in 5y.
Getbusy (GETB) H1 rev up 20%, guides FY rev beat.
Dotdigital Group (DOTD) FY trading. Guides adj EBITDA and op profit lightly ahead of market expectations. Outlook: "Momentum has continued into the new financial year...confident."
Seeing Machines (SEE) wins driver monitoring order, from a German mfr, worth total A$11m and A$30m from 2021.
Franchise Brands (LON:FRAN) please. Looks like 2019 sales will exceed £40M with an earnings beat, thanks to the Metrorod 5 year growth strategy. Happy holder. Ian
Interested to hear thoughts on £CHRT results announced this morning. Significant difference between Adjusted figures (indicate growth in PBT & EPS ) and statutory numbers which show significant decline! Note explains what is adjusted for but is this another example of a business not doing as well as the headline numbers suggest.
Second this on Cohort (LON:CHRT) - I sold out at a profit, lower down than this, but still not sure I didn't make the right decision. There are regularly large adjustments for acquired goodwill, so although trading is good, ROCE is poor. Unfortunately you have to pay for quality of earnings.
[Formatting screwed in Beta site]