Small Cap Value Report (Tue 23 June 2020) - SHOE, G4M, SCPA, RMV/OTMP

Good morning, it's Paul here with Tuesday's SCVR.
Estimated timings - let's try for 1pm. I've started before 7am, and feel unusually perky this morning, so that should be do-able!
Edit at 12:03 - as usual, everything is taking longer than expected. How can 5 hours go by in the blink of an eye? It's looking more like 4pm finish time, as I need to do more work on G4M & Scapa.
Update at 15:57 - today's report is now finished.
.
Covid treatment/vaccine
Given that I have no medical knowledge, I've tended not to think about the likelihood of a vaccine appearing any time soon. Experts in the field told me a few months ago that a vaccine would probably be late 2021 (at best), and maybe not at all. This is similar to what the UK Govt said in its document about the lockdown a few months ago.
However, much more promising signs seem to be appearing. An article in the Telegraph today really gave me a jolt (in a positive way). This suggests that, admittedly only in a best case scenario, the Oxford/AstraZeneca vaccine could be ready by this October. In a similar vein, Jim Cramer keeps saying on CNBC that the tone he's hearing direct from top US pharma company CEOs has become much more positive of late.
If effective treatments to suppress covid are only months away, then this changes everything. It means that humanity could get back to something like normal maybe by early 2021? That means travel, holidays, hospitality, retail, and every other sector can ramp back up to normal. Therefore I'm wondering if I should be pushing the boat out a bit more with some shares that could rise strongly if that scenario plays out. The key factor is whether companies have enough liquidity to survive into 2021? If they do, then the future for such shares could be much more positive than currently expected. Plus they could see pent-up demand, and less competition.
I appreciate it must be a bit frustrating for readers, because I change my mind on this topic more often than I change my socks!
We've got to balance up optimism over treatments/vaccines, with the negative of current resurgence in cases in some states in the USA, in Germany, and other places. It's certainly not under control yet, but if that's only months away, then as investors we should probably be positioning ourselves for recovery, not armageddon. Therefore I'm going to go on a spending spree when the market opens, and buy some shares that I previously thought too risky.
.
UK mortgages
Press reports are suggesting that lenders are (understandably) worried about house prices falling, and new borrowers going into negative equity. This seems overblown to me (at least outside London). With such low interest rates, probably/possibly for a long time, then personally I cannot see any reason why house prices would fall much. Mortgage monthly payments are so cheap now, if you can stump up a decent sized deposit.
Although there could be some short-term problems, as apparently the big lenders are withdrawing the low deposit mortgage deals. Pity, as that hurts younger people keen to buy their own home.
We could see the housing market struggle for some time to come. Hardly surprising though, is it?
For this reason, I've decided not to revisit the housebuilders' shares just yet. They don't look cheap enough to tempt me back in.
.
Quote of the week
I’m very much enjoying the superb emails from John Authors, from Bloomberg (highly recommended). Several people have forwarded them to me, but I’m already on the list, so thanks, but no need to send them on to me!
This comment from him seems very pertinent right now;
In a bubble, you’re not investing in a company, you’re instead placing a bet on the collective behaviour of other investors. That behaviour reveals itself in chart patterns rather than in balance sheets or valuations.
Thought-provoking, and undeniably true, in the short term.
.
Volex (LON:VLX)
A reminder that there is a results presentation online at 10:30 this morning. It's on Investor Meet Company, an excellent new platform to connect investors with listed companies.
I'll be attending this event, and will reflect back any interesting points.
I like Volex, it's a very good turnaround, and has a strong balance sheet. Although obviously covid will have some impact on this year's results. I covered it here last week, and think this is a good share, with a medium to long term view. Not one I currently hold, but as always I reserve the right to buy some if I like the results presentation.
EDIT: Actually, I've got more important shares to focus on this morning, so will watch the video recording of Volex's results webinar this evening. End of edit.
.
Shoe Zone (LON:SHOE)
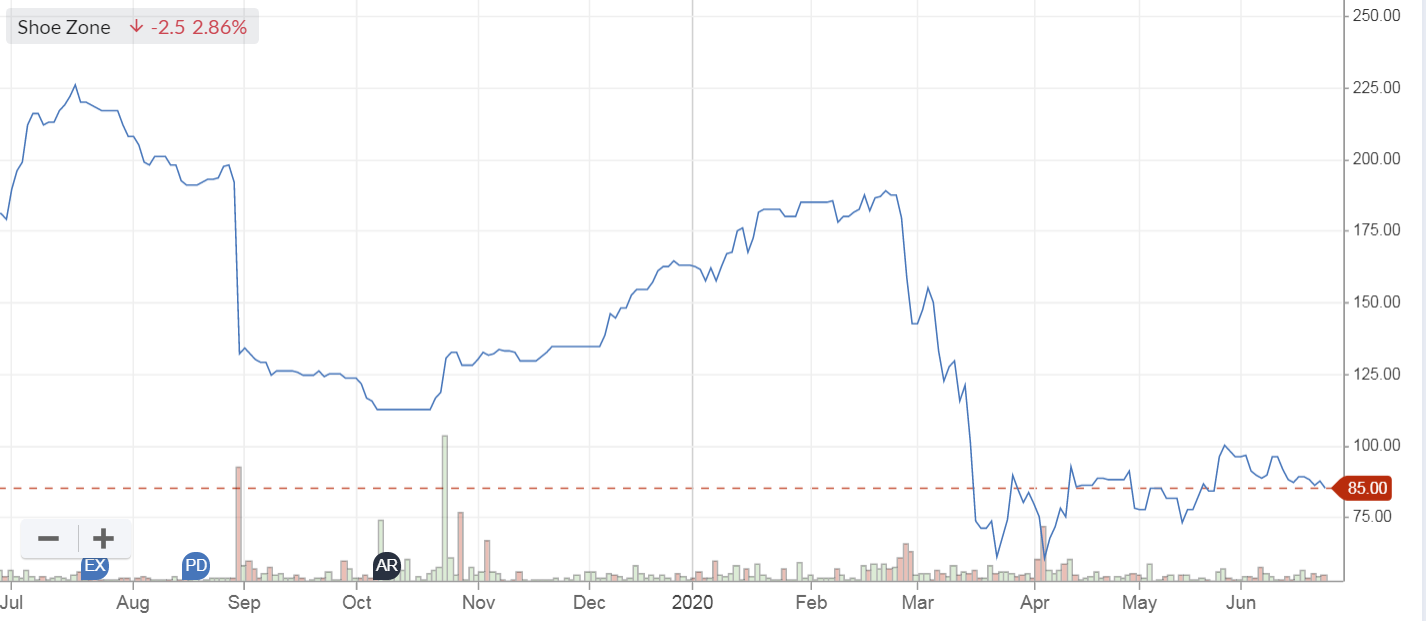
Share price: 85.0p (down 3% today, at 08:37)
No. shares: 50.0m
Market cap: £42.5m
This is a retailer of cheap, Chinese-made shoes., from 490 shops.
Shoe Zone plc ("Shoe Zone", the "Company" or the "Group") is pleased to announce its Interim Results for the six months to 4 April 2020.
I won't dwell on the interim numbers, because;
- SHOE has a heavy H2 seasonal bias, hence interims don't really matter that much
- Lockdown caught the tail end of the interim period, and will have obviously changed everything for the last 3 months
- Outlook for re-starting trade, and the liquidity position (will it survive or go bust?) are the key issues that I need to focus on, as with everything at the moment
In short though, interims (Oct 2019 to Mar 2020 + 4 days in April) say;
Revenue down 5.6% to £68.9m (was up 2.6% for the 5 months to end Feb, before lockdown hit the figures in March)
Digital sales small at £6.5m (9.4% of total sales), but rising strongly (up 31.9% in H1). However, excellent growth during lockdown, reaching 17% of previously budgeted (pre covid) total sales - this is encouraging. Driven by aggressive discounting, to turn inventories into cash - a smart move, but obviously damaging to profit margins.
Loss of £(2.5m) in H1 (LY: H1 profit of £1.0m) - not a good performance
Balance sheet - I'm a bit taken aback by the IFRS 16 lease asset/liabilities, which are larger than I expected. Previously the company has emphasised that it have flexibility due to very short leases. That doesn't actually seem to be the case. Of course lease commitments don't matter if a retailer is trading profitably from sites. Leases are only a problem if trading is deteriorating, loss-making, and that is combined with a long lease commitment.
Note there is a £9.95m pension deficit, not a disaster, but an unwelcome line on the balance sheet. It is a cash drain of c.£0.9m p.a. (see cashflow statement)
Liquidity - net cash of £3.6m at end March 2020. As previously notified, divi was scrapped, Drawn down £10m of £15m facility under CBILS Govt backed loan scheme, so liquidity should be OK.
Outlook & covid - Shops closed on 24 Mar 2020, and re-opened on 15 June 2020. I can't find any comments or figures on how the resumption of physical stores has gone, so I imagine not very well - otherwise they would have told us! This doesn't sound encouraging;
Whilst the group has taken all possible steps to ensure that the business will survive through the crisis and continue into the future, the impact is likely to continue to be felt for several years.
The Board remain confident that the Group's current level of funding will be sufficient to secure the future of the business, assuming that sales return to a high proportion of previous sales during the next year.
I think it looks fine for now, so shareholders have no need to worry about SHOE going bust any time soon. That could change though, if retail footfall & spending doesn't improve as 2020 progresses.
No V-shaped recovery for the High Street then, it seems. Although I do think it's too early to judge. With distancing now being relaxed, and nicer weather coming, plus re-opening of bars & restaurants soon, then town centres could start to come alive again, possibly? Time will tell. I don't have a strong view on this either way, we don't really know yet.
There's more detail in the announcement, but I've seen enough to make up my mind.
My opinion - this business should survive, as it has adequate liquidity for the foreseeable future.
Given that management have very large shareholdings, then they won't want to dilute themselves or anyone else, with an equity fundraising. So far go good on that front. Although we have seen with other companies, that sometimes bank support comes with an (often undisclosed) side agreement that the company will raise fresh equity when it can.
The lease liabilities look higher than I was expecting, so it would be useful to have an update on that from the company.
I like the fact that online sales are growing. The company needs to increase the proportion of its sales that are made online, which it is doing. Driving growth through heavy discounting is fine, because once a customer has made an initial purchase, then the company can communicate & drive offers free by email. SHOE is doing BOGOFs (buy one, get one free) online, to drive growth & clear inventories - a good idea.
Overall, I think the current valuation looks about right, given the difficult circumstances. There should be some upside if the economy returns to normal, if covid is tamed with treatment/vaccines. I can't see any particular appeal to rush out and buy the shares now at 85p - that's not a cheap enough valuation to tempt me in.
Ignore the outdated broker forecast & dividend yield.
It currently seems as if the retail sector recovery is likely to be a long & painful journey, with many falling by the wayside. A lot of smaller retailers don't seem to be re-opening now, even though they can. Why would they? With staff on furlough, and not paying rents or business rates, then it's cheaper to remain closed whilst footfall is low.
I suspect there are likely to be many empty units in the High Street after Xmas. Maybe some retailers might re-open for Nov & Dec, to generate some cash from stock clearance, and then close for good in Jan 2021?
The more I think about it, the more bearish I'm becoming on property REITs with exposure to retailing, and am going off the idea of revisiting that sector.
.
.
Gear4Music
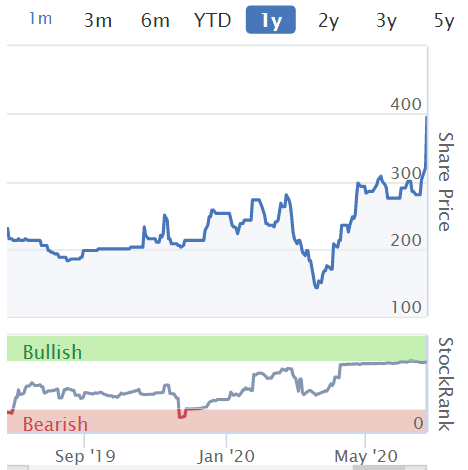
Share price: 390p (up 22% today, at 10:29)
No. shares: 20.95m
Market cap: £81.7m
(at the time of writing, I hold a long position)
Gear4music (Holdings) plc, ("Gear4music" or "the Group") (LSE: G4M), the largest UK based online retailer of musical instruments and music equipment, today announces its financial results for the year ended 31 March 2020.
The company gave a year end trading update, which I reported on here on 23 April 2020. Comparing the actual results today, with the previous trading update goes as follows;
Revenue: as expected at £120.3m (NB. this is up 2% against prior year, which was a 13-month period. It's actually up 9% on a properly comparable 12-month time frame)
Gross margin: as expected at 25.9% (up 310bps on LY, as the company's stated strategy is to increase margins, rather than chasing low margin sales growth - this strategy has clearly worked well, kudos to the team!). Note from the commentary that G4M absorbs £8.8m of delivery costs into cost of sales. By my calculations, stripping out delivery costs means that the product margin rises to a more respectable 33.3%. Average basket size is quite high too (compared with, say higher margin online fashion), at £117.
EBITDA: looks like a beat, with £7.8m reported today, versus "not less than £7.0m" expected.
Current trading & outlook - this is probably the main reason for today's sharp share price rise. This sounds excellent;
... we have experienced exceptionally strong trading at the beginning of the current financial year.
With the shift from high street to online consumer shopping continuing to accelerate, we remain confident that our business is appropriately configured to achieve long term profitable growth, and that we are in a strong position to build upon the excellent progress we have made during FY20.
Management at G4M are not given to hyperbole, having a good track record of telling it like it is. Hence when they describe current trading as "exceptionally strong", then I sit up & take notice, and so has the market by the looks of it.
Broker upgrade - many thanks to a friend who flagged up a large increase in forecasts this morning from the house broker, very helpful. The existing forecast for FY 03/2021 is 10.6p. This has been almost doubled today, to 20.4p
EBITDA comparisons - the only thing I don't like about these figures, is how the EBITDA comparison doesn't compare like with like. The impressive-sounding £7.8m EBITDA for FY 03/2020 isn't comparable with the £2.3m last year number, because this year is boosted by IFRS 16, and last year suppressed by IAS 17. The real comparison (as shown in a footnote, to be fair) is £7.8m TY, £3.7m LY. Still good, but as a general rule, I feel that tables should only ever be presented with truly comparable numbers, not numbers distorted by anything.
My opinion - this is very pleasing indeed, to hear that the company is trading so well. The only potential issue, is that trading may not remain quite so exceptional once schools go back, it must have benefited from kids being stuck at home during lockdown. that said, I hope the surge in interest in making music continues. We severely undervalue the big social benefits from teaching music to children. Making music gives people (adults and children) pleasure, self-esteem & a sense of achievement, better mental health (hence better behaviour), confidence (from performing in front of audiences), and cooperation/teamwork (from playing in a band or orchestra). Hence I really hope this trend continues, not just for selfish share-price-related reasons!
I've printed off the full results, and will read them in the sunshine now, so will post any further bullet points below once I return.
Some time later: this isn't working, I've got completely bogged down in the detail. The best thing to do is just read the note from N+1 Singer, which is available on Research Tree. It makes many excellent points. I think the bull case has got much stronger today, because of the broker forecast EPS doubling. Therefore I shall probably be increasing my position size here. Obvioously DYOR, this is only one person's opinion, and I may have missed something important.
It's one of only a few shares where we can actually rely on the latest broker forecasts. Also note that the 100% rise in forecast EPS, combined with today's 22% rise in share price, means that the forward PER will actually come down substantially, from 30 to about 20. For that reason, I think this is a bullish development, and am happy to continue holding, and increase my position size. It's good to see the sceptics proven wrong!
.
.
Scapa (LON:SCPA)
Share price: 103p (down 14% today, at 15:01)
No. shares: 186.5m
Market cap: £192.1m
(I hold a long position in this share)
Chairman resigns - he's leaving at the next AGM, replaced by Chris Brinsmead.
Scapa Group plc (AIM: SCPA), the diversified Healthcare and Industrial company focused on bringing best-in-class innovation, design and manufacturing solutions to its customers, today announces its preliminary results for the 12 months ended 31 March 2020.
I bought some shares in this after the equity fundraising, which I reported on here on 18 May 2020.
The sharp fall in share price today seems a bit perplexing, as the FY 03/2020 figures are as expected. The balance sheet was shored up with a recent placing at 105p, and look fine once you add on the placing proceeds (which happened post year end). All the bad news, about losing a big contract with Convatec last year, was already known.
Current trading/outlook - this is a bit of a muddle, and seems contradictory;
Year-to-date trading better than initially forecast under Scapa's COVID-19 scenario, but recovery is at a slower pace
How can it be better, but slower? That doesn't make sense to me. Maybe the slower pace of recovery refers to the forward order book? It should have been explained more clearly.
It then goes on to say;
Continue to execute against the COVID-19 scenario and expect trading to be in line with the outlook provided at the time of the placing
There's something for everyone in those outlook comments - we're up, but we're slower, but we're in line!
Forecasts - a fresh forecast has come out today with 5.4p EPS forecast for this year, FY 03/2021. Obviously that's a long way down on prior year (which was itself down on prior year), due to covid and the loss of its major customer. Still nobody is valuing companies on their 2020 earnings, the market is looking ahead to recovery in 2021 and beyond. I haven't seen any forecasts for FY 03/2022, so am a bit in the dark on this.
My opinion - it's refinanced, and remains profitable even in the year of covid. Profit margins look strong normally, and the turnaround plan sounds sensible. It looks an obvious takeover target too. However, despite that, something is clearly bothering the market, with more sellers than buyers today.
The chart is also suggesting that there are persistent sellers in the market, feeding out stock whenever buyers come in. Looking at the most recent "Holding in company" announcements, Octopus and Allianz IARD are both selling, with 8.5% and 5.0% remaining. Whilst Blackrock is a buyer, with 6.25% when last disclosed.
I'm not confident enough in my knowledge of the company to increase my position size, so I'll just sit tight with a medium-sized position, and see what happens.
.
Residential Property portals
Rightmove (LON:RMV)
(I am currently shorting this share)
By far the market leader in the UK. It has a market cap of £4.89bn, after today's 5% fall in share price.
Today's update says it gave a 75% discount to all its estate agent customers in April-July. Today it is offering a 60% discount for August, and 40% discount for September, to assist estate agents as they rebuild their sales pipelines. The total lost revenues for this will be £82-95m. That's going to hit profits very hard, since incremental sales are 100% profit (or loss, in reverse).
The platform is now very busy, indicating considerable consumer interest in moving house, perhaps? Plenty of people like browsing though, with no intention of moving. Or just to have a virtual nose around local properties!
Customer numbers are down 3.8% since the end of 2019. Unwilling to provide guidance.
My opinion - I really dislike this business. It's unethical, because it price gouges its customers, abusing a near-monopoly position, to effectively be a tax on estate agents. Hmmm, okay I don't think there's likely to be much public sympathy for that line!
.
OnTheMarket (OTMP)
(I am currently long of this share)
This challenger portal also updates today. It's a minnow compared with Rightmove, with a market cap of only £56m, which is not much more than one-hundredth of Rightmove's value! However, it has a large stock of listings, achieved by allowing agents to start with a free trial. It is also majority owned by estate agents, who funded it initially, before the launch on AIM. Free shares are available to "reward" agents that sign up to full price deals. The concept is that, if estate agents are incentivised to do so, they might hopefully help topple Rightmove. That's not happening yet, but who knows what the future holds?
Rightmove is having to give away massive discounts to keep its customers. Will it really be able to crank the fees back up again to the previous (outrageously high) level? I have my doubts. There's a clear opportunity for OTMP to drive sweeping change in the current circumstances, but it's running low on cash, and is searching for a new CEO. I hope it doesn't miss the big opportunity.
OTMP is also offering discounts, but a much lower % than Rightmove, at 33% in month 1 & 20% in month 2. Bear in mind that OTMP's standard fees are about a quarter of RMV's - because it has far lower traffic to its website than RMV has.
OTMP also says it is seeing strong growth in website visitors, despite spending less on marketing.
My opinion - obviously OTMP is a complete punt. If it was valued at say one fifth, to one tenth of the market cap of RMV, then I wouldn't be interested. What makes it interesting, is that it's valued at almost one-hundredth of the value of RMV. Imagine if a 100:1 bet were to pay off. I think those odds are quite interesting. I only have a tiny long position in OTMP, because I'm waiting for the next placing to take a bigger stake. It's got enough cash to tick along for now, but a proper resumption of growth (in particular heavy advertising to drive more traffic to its website) would need a fresh fundraising.
.
That's me done for today. See you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

97 comments
Scapa (LON:SCPA) - bought into this shortly after the placing but got cold feet and sold. CEO is well regarded but very highly paid for the size of company and in the past has rarely spent his own money on buying the shares. He participated in the recent placing but relative to his net worth probably a modest amount. I thought the healthcare dressings business was interesting but couldn’t see the competitive advantage with which to win market share. Considering that healthcare stocks have rallied strongly, the market is not keen on Scapa (LON:SCPA)
Thanks Paul for yet another superb effort today. I don’t know how you find the stamina to do it day after day!
I was especially interested in your take on OTMP. I reckoned it was worth a small punt after your previous update and going well so far. Seems that a fund raising is inevitable. Just hope that like Revolution Bars it includes an open offer for ordinary shareholders too. Hate it when they are (as so often happens) excluded in dilutive placings.
I find it difficult to believe that Onthemarket (LON:OTMP) will manage to supplant £RMV. As someone who is currently selling their house and looking to buy a new house I find RMV's website use-ability and functionality to be far superior to OTMP. RMV also has more properties listed on it. I cannot find any reason to visit OTMP - everything and more is offered by RMV. From a consumer perspective RMV wins hands down. I can see why estate agents resent them, but that's something different.
Unlike Paul, I love RMVs business model. There have essentially followed Peter Theil's mantra of creating a legal monopoly. OTMP is the plucky challenger trying to get in on the action late in the day. Unless they can create some innovative functionality or get a large number of estate agents to leave RMV enmasse then it's difficult to see them succeeding. The 100:1 market cap differential seems to me to imply overly optimistic odds of them succeeding - I would give them longer odds. In this digital age we have a large number of companies that have succeeded in maintaining similar monopolies (Amazon, Google, eBay etc.), so unless RMV bugger this up I can't see them losing their dominant market position any time soon.
My issue with RMV is a different one; growth and valuation. I can't see where the growth will come from as they already dominate the UK market and charge a "full" price for the services they offer. If they try to increase prices they run the risk of opening the door to OTMP. I don't follow the company in detail, so perhaps they have some grand ideas for developing other revenue streams. The valuation prices in significant growth expectations (no other way to justify a 30x PE ratio, even for a virtual monopoly) which I can't comprehend.
I don't hold either share, but find myself tempted to dip into RMV when the share falls during market down-turns or on bad short-term trading news, which is all externally driven and has nothing to do with the viability of the underlying business model.
I agree it's unlikely that OTMP will supplant RMV. Highly unlikely. But not 100:1 unlikely, which is what the respective market caps are saying.
Paul, if it is of any help, in respect of Scapa Group Berenberg is forecasting earnings of 11.6p and Numis is forecasting earnings of 12p both for the year ending March 2022. They are both brokers to the company.
Regards
Phillip
Very helpful, thanks Phillip! :-)
To my mind, that probably justifies a share price for Scapa (LON:SCPA) of about 150-200p, with a bit of patience.
Also liked what I saw today Paul and enjoyed a good chat with management for a write up.
Hopefully following Covid-19 most Tattoo parlours will shut down forever. Surely one of the most egregious fashion trends of our times. At least with most fashion trends you can in retrospect laugh at your old photos.
Already got two booked in for when they reopen. The artists are working away as we speak!
Hopefully following Covid-19 most Tattoo parlours will shut down forever ... Already got two booked in for when they reopen. The artists are working away as we speak!
:-)
When Denmark started reopening two of the immediate businesses that were permitted were hairdressers and tattoo parlours. The former were swamped, the latter ... not so :-)
Denmark is close to being fully reopened but borders with Sweden still closed. The former's had 200 excess deaths, Sweden (double the population) 4,800. According to friends in Copenhagen retail business is quiet, a lot of people are still working from home.
Denmark has handled the pandemic well, Sweden not so and the UK terribly - but everyone's economy has been trashed. In the end it's never been a choice between lives and the economy, the economy was always going to be hammered, it was just a choice about how many people were sacrificed along the way.
timarr
Timarr, given it was a choice and you feel the UK sat down and decided on 60k+ excess deaths. How many would you have sacrificed? I wish I could empathise with your eternal pessimism but even after the decision to sacrifice 60k+ lives, mortality rate within the UK for 2020 will remain comparable with Denmark and significantly lower than in Germany. Happy to continue taking my chances in he UK. It's not to say mistakes were not made, I just struggle to believe anyone made the choice to sacrifice lives.
No one sat down and "decided on 60k excess deaths". The issue is that the govt has handled the outbreak badly, and continues to do so. If they had paid real attention to what was happeing elsewhere, from Jan onwards, we would have locked down earlier, had fewer deaths and almost certainly have been able to relax restrictions earlier, with less damage to the economy. We had the advantage of being behind several other places when this started, and it was pretty much thrown away.
The key to relaxing now is clear messaging, effective testing and tracing, and powers to local authorities to impose local restrictions where new outbreaks occur. None of those are being handled well.
The key to relaxing now is clear messaging, effective testing and tracing, and powers to local authorities to impose local restrictions where new outbreaks occur.
Bold words indeed Peterg!
Give me an example of clear messaging that the media won't misrepresent and that everyone will understand and observe? That the Scottish Government will use if suggested by a UK Government.
What Powers would you give to local authorities that the media and everyone impacted won't claim are an abuse when used. Powers that will stop hundreds of thousands of people heading to a beach in Bournemouth on a gloriously sunny day when the rest of the country can. What does a local lockdown entail?
What constitutes effective testing and tracing? What does it look like? If the UK released a Tracking App with a 15%, take up, would you agree that that was a success?
I look forward to your answers.
I just struggle to believe anyone made the choice to sacrifice lives.
No? We have nearly ten times the number of excess deaths as in Germany. Don't you think that requires explanation? Boris likes to compare himself with Churchill. Well, Churchill didn't choose to sacrifice Australia's finest on the beaches of Gallipoli, but he did it anyway, because he was pigheaded and ignored the advice he was given. Sacrifices aren't about choices, they're about decisions.Anyway, I'm not a pessimist - the most likely trajectory of Covid-19 is predictable. We'll see cases rise during the winter, fall back next year and death rates will fall because vulnerable groups will take preventitive measures, treatments will improve and, eventually, we'll get a vaccine. If we get a lot of flu in the winter we may be back into lockdown to protect the NHS but that would be unlucky.
Investing is about seeing the world for what it is, not what we'd like it to be.
timarr
No? We have nearly ten times the number of excess deaths as in Germany.
But a 20% lower mortality rate than in Germany.
Surely if Investing is your game, Which company are you investing in?
A company that outperforms by 20% with the occasional blip or the company that underperforms year on year by 20% but with no blip.
In respect of mortality rates, UK is the place to be even taking Covid-19 into account.
Maybe excess deaths could have been lower with different decisions, I'm just glad I didn't have to make those decisions because I am sure I would have got them wrong too.
That’s my business (employing others), my career and the career of literally thousands in the country. But sure, maybe we should all go bust because you don’t like them and think it’s a trend.
By the way, the oldest preserved body ever found, over 5,000 years old, had tattoos. It’s an art form with a long long history.
So, as expected, Boris confirms pubs and some other hospitality, can re-open on July 4th. Awaiting further details but one heavily fancied "condition" is that:
Pub-goers will have to give up personal details to get a pint
I open this up to those far more knowledgeable than I - does this mean landlords/operators will now have to register under the data protection legislation?
I assume that it might well mean that, in which case is this another "rule" that is being instigated without full consideration of all the consequences?
As for the reduction in the social distancing "rule" from 2m to 1m:-
Even a 1m “rule” is going to be a joke once premises do open – give it five minutes and nobody’s going to take much notice and if it was enforceable then a lot of licensed premises are going to go out of business.
But, as it’s not a law, what could be the comeback if some official calls in and sees that it's not being implemented, what could be the comeback?
Could the licensing authority revoke the license and if so on what basis? No law has been broken.
Could the business insurer cancel cover and if so on what basis? No law has been broken.
OK, the clientele might decide that they don’t want to enter a premises without enforced social distancing but that’s a risk many operators might be prepared to take becasue it's unenforeable and in a way this would be good as it would help keep numbers below capacity..
Looking at what’s happening generally. I think a lot of people, especially the younger generation, don’t care all that much, they just want to go out and have a good time and are fed up with being told what they can and can't do by politicians who seem to have completely lost the plot.
But, as it’s not a law, what could be the comeback if some official calls in and sees that it's not being implemented, what could be the comeback?
I was under the impression that the government could change the law if they saw fit?
timarr
I was under the impression that the government could change the law if they saw fit?
Indeed - but they haven't chosen to make this a law and it's been quite a while.
Indeed - but they haven't chosen to make this a law and it's been quite a while.I
I haven't noticed many people out boozing recently :-)
The point is they can insist on what they want. If businesses choose to ignore the "advice" then it'll depend on whether they're serious or not. If I were a big chain I'd probably take it seriously, law or no law. Independents may choose to take the risk.
timarr
Might you be overthinking this a tad ? i would happily give my name and contact details if it meant I could have a life a little more normal by going to the pub. Publicans are more interested in selling drinks and food than selling a contact list or GDPR - Personally I dont think the pubs will be full to the brim on day one or day 30 for that matter.
well I was astonished to see the queue outside a local pub in Richmond yesterday evening. People prepared to wait at least 30 minutes to take out a pint or two .
Agree, the 1m social distancing rule will be a legal fig leaf for the government; we will have (sensibly) moved de facto to everyone decides for themselves based on their own perception and understanding of their own risk/risk tolerance ie same as choosing to take up sky diving!
One thought - will the "fig leaf" approach favour independents vs national chains who have much greater risk of negative PR consequences if they are seen to be flouting a 1m rule. So whilst Revolution Bars (LON:RBG) or Tr European Growth Trust (LON:TRG) might need to scan temperatures on doors and move tables etc, individual owner operators may feel less need to incur extra cost - especially if they have a young customer base eg bars and fast food places.
Can people please stop asking me to look at more things, I'm absolutely snowed under already!!! Thanks :-)
Maybe look at Autotrader. You could part/ex the XJS
RA International (LON:RAI)
would be interested to know if anyone has any thoughts on how long the sharebuyback plan of action may carry on for this company and practicably speaking what the max price they can pay for the shares they are buying. - is this just simply the current market price ish unless the price drops below the averaged amount around the time of the announcement +5% in which case they can pay that higher price?
they did say the follow which might as well be written in treble dutch.
the maximum price (exclusive of expenses) which may be paid for any ordinary share does not exceed the higher of: (a) 5% above the average middle market prices of the ordinary shares on the London Stock Exchange Daily Official List for the five business days immediate preceding the date on which the Company agrees to buy the shares concerned; and (b) the higher of the price of the last independent trade of any ordinary share and the highest independent current bid for an ordinary share derived from the London Stock Exchange at the time the purchase is carried out.
They have only announced that they have bought back 100k sofar - so ignoring the part filled orders that presumably dont need to be notified - it looks like they have hardly scratched the surface yet.
If the price continues to rise much more i may certainly be tempted to sell - but it probably doesnt make sense to do that if there is a ready willing buyer at a price higher than i would be selling at.
Hi Paul, Given how you are feeling - any chance of a few words on Fih (LON:FIH)? Their results seem as perky as you you - but are only up until 31/3.
I don't what you're thinking Paul, but I liked £VLX. I don't know the company well but all they said re cash, management ownership, dividends, margin focus, ticked lots of boxes for me. More work to be done but an excellent presentation i thought
Yes, I also liked the Volex (LON:VLX) presentation. It came across as more honest than slicker ones I have seen and unlike here not all management addressing shareholders refer to 'your company', which they should. I particularly liked their attitude to acquisitions, which cropped up several times, including not wasting money on paying external advisers and incentivising management to keep the company improving rather than sacking them to cut costs.
Paul by the sound of it I suspect you won't have time but circling back to Best Of The Best (LON:BOTB), which I have taken a small starter position in, on the Stockopedia page against the "Earnings Manipulation Risk(M-Score)" Stockopedia shows as High.
Do you look at these sort of signals when assessing a company and check in to the figures to ensure that that the formula is throwing out a false positive or do you ignore M score etc?
Thx.
Kind regards
Michael
Looking at the drivers of the M score, it seems to be reduced depreciation expense and increased days receivables.
On the former, they sold a bunch of fixed assets and on the latter increased advertising expenses are often pre-paid, especially TV advertising.
On the other hand, I have come up with explanations to look the other way on what has been a successful holding. I added yesterday
Sorry - I know I am not Paul!
Interesting but somewhat strange statement today from £intu today. They confirm that the administrators are standing by but also say that without pre funding (and we are talking many millions of £) the centres will have to close, at least for a while. Intu owns and manages 17 shopping centres including 9 of the top 20 in the UK. They include Metro Centre, Trafford Centre and Lakeside. These employ many thousands of staff.
Rent day is tomorrow; can the majority of tenants expect to continue to refuse to pay rent yet expect the commercial centres to continue to fund security, safety, cleaning, car parking, maintenance, welfare and many other services? What if Intu and the others at risk simply closed their doors from Friday? They cannot evict the tenants or take enforcement action but there is nothing the Government can do to make them stay open. Would closing almost every major shopping centre in the UK detonate a bomb under the economy? I don't know. It might help the High Street a bit I guess (and Amazon) but probably at the cost of a vast number of jobs.
Even if you do not own shares in Intu (disclosure; I have a few as a mad punt) it seems to me this is an important scenario. Will anyone buy these huge centres if Intu goes or has their time gone? Who would want to put up hundreds of millions at a time when the Government is allowing many major companies (many of whom can afford to pay the rent) to refuse to honour contracts? I personally think that has set a dangerous precedent. Many say that Lakeside could be redeveloped into residential housing. So is that it for physical retail? I suspect this is going to be a defining time even after covid is long gone.
I wonder whether lining up administrators is aimed at scaring the tenants into paying their rent and the banks into supporting a re-financing ...?
Exactly right I'd guess. Even under administration I'm sure there's enough rent coming in to cover service costs, so the administrator would keep the actual shopping centres open.
There are tenants like Next who are paying their rent in full and on time. Closing the doors and stopping access to their stores would give the lawyers more work. It's a busy time for them already.
The Intu announcement contains a bit of everything, possibly designed to chivvy lenders and creditors into more action. Shareholders now know (officially) that things are bad and hence softened up for any outcome.
My best guess would be that Peel Holdings, possibly with a third party pick this up
Tp (LON:TPG) anyone got any thoughts? Looks like a cracking little company in a GARP style. Has navigated Covid very well and been announcing new contracts with what seems to be increasing regularity with a recent €18m deal. Todays announcement looks interesting which is its first AI contract signed. Only £300k but bodes well.
At a financial level has net cash of £6m or 10% of market cap so well funded. Has a £7m facility if required so balance sheet looks good. Had an order book of £64m at y/e and with the new contracts this should be more like £80m now which is more than 1 years worth of revenue visibility with a current year PE of 12 and what looks like room for upgrades.
The new on-site oxygen modulator system and the data/AI business also looks well positioned and could add some jam to the existing business.
Thanks for mentioning this company, my best winners have been companies mentioned in the comments. This has strong GARP characteristics.
One interesting point about TP is that 13 million of the 58 million ye 12/19 revenue came from an acquisition made in May 2019. The full year equivalent of the 13 would be 22 million or thereabouts without any growth. As it happens, organic revenue growth in the year was 16%, so ye 12/20 revenue could be quite a bit higher.
Hello Paul & members. In the Mail 'health' today. Given that the virus affects the lungs you might think those with allergy & asthma would be amongst the worst affected. Indeed researchers sifting through the statistics expected the same thing. 'But when data started emerging about cases in the U.S. & China, we weren't seeing what we expected.'
In fact, the numbers of allergy & asthma patients who were severely affected by the virus were lower than in the general population. 'It led us to ask if something about the treatment used by people with these conditions is affecting their response to the virus, or does something about the immune system of those with asthma & allergies protect against the virus? If we can find out the reason, it would be a significant breakthrough.'
Both could be true and it will take some work to disentangle, looking at the different treatments that asthma patients are using.
Asthma is caused by an overactive immune system triggering an allergic reaction to everyday irritants such as pollen, airborne pollutants, etc. That might mean patients naturally have immune systems that are better at seeing off the coronavirus though I'm not aware of any such benefits against colds or flu. Treatments include regular use of low dose inhaled corticosteroids. They suppress the allergic reactions. Perhaps they protect against the virus by suppressing a cytokine storm.
If people with asthma are taking steroid inhalers, and I know at least one person who does, then perhaps lung inflammation is suppressed, in the same way the newly announced use of a fairly cheap steroid is proposed for use for people on ventilators or having more severe symptoms.
Steroids are generally an anti-inflammatory drug, and in asthma will be used to modify ongoing asthma issues.
Hello Paul - Can anyone subscribe to the John Authers e mail and if so it would be much appreciated if you (or anybody else who has it) could provide the link. Thanks very much.
Mike Elkin
Mikeelklin
You can sign up to Auther's daily email by clicking on the link beneath the article photo:
https://www.bloomberg.com/opinion/articles/2020-06-23/a-weaker-dollar-is-just-what-the-world-needs-kbrffirm?sref=wORX77mh
Thanks for the helpful and quick response Howard - Just Signed Up. I look forward to reading them.
Paul, I always find I am in a different place than you re Shoe. For me there is a guaranteed demand for cheap shoes which will always underpin a business like shoe. The risk to this type of business is management. If the business is run sensibly and progressively I cannot see how they will get into trouble. This management team have some wood in the fire and seem very conservative. I think the business will probably move to online although the market for these shoes isn't necessarily likely to be too IT savvy, so the boxes make sense. I have to admit I am a Churchs man and maybe that is why I see the value in shoes!! Anyway it goes without saying I am a buyer.
I don't disagree with any of that. It looks like you've misunderstood what I wrote in the main article, or maybe I expressed myself badly?
SHOE is a survivor for sure, and its business model seems OK. It just doesn't appeal to me at the current valuation, which I see as being maybe about right (hence not cheap enough to tempt me to buy). Also I have reservations about how long it might take (if at all) for High Streets to be busy enough for retailers to become decently profitable again.
Hi Paul, I took a small stake in Shoe Zone (LON:SHOE) sometime last year after I used their online shop to buy a pair of slippers. Mine were a safety hazard and I was too busy to travel to the nearest large town, supermarkets only seem to stock slippers at Christmas. I had been reading your thoughts on Next's online offering and was impressed by how user-friendly Shoe's site was. Fast forward and after a year the slippers failed their MOT and I revisited to find a large expansion in their product range and not just the range of cheap imports you might find in their shops. https://www.shoezone.com/Brand...
Cracking outlook statement from G4M. Re-rate coming imo.. future looks very bright :)
Hi Paul. Would love to hear your view on Beximco Pharmaceuticals (LON:BXP) if you get time
Thanks!
Sorry, I don't cover the pharmaceuticals sector, as it's a sector that really needs specialist knowledge/experience, hence I cannot add any value by commenting on things such as that.
Regards, Paul.
Its worth noting that current S&P futures see the biggest net short position in 9 years.... And we were wondering why stocks keep going up.
Macro and shizzle here...
https://foreignpolicy.com/2020/06/22/the-great-pause-was-an-economic-revolution%e2%80%a8/
Profound dudes. We live a revolution
I thought the negative votes a bit harsh and the article makes an interesting point albeit not entirely convincing.
The future is always told by wingnuts...I don't agree wholly with article either however I felt its main point was good and a very important reminder that backwards facing analysis is prone to problems right now. I am naturally sceptical and can see bearish side often but bears at the moment may be in a cognitive-behavioural trap...that doesn't mean I think its moonshots all the way...it just means I don't think the major bear arguments hold water
As for red thumbs...I welcome them warmly ;)
Interesting and thought provoking Paul.
Paul, Do you have any views on Bushveld Minerals (LON:BMN) ? Would be great to hear your opinion given financials we published today
Sorry no, I don't cover the natural resources sector at all, because it needs specialist knowledge which I don't have.
I think you might some stuff over at Graham's site Cube Investments on £BMN. Not 100% certain but it rings a bell.
Kind regards
Michael
"For this reason, I've decided not to revisit the housebuilders' shares just yet. They don't look cheap enough to tempt me back in."
I hold Countryside Properties (LON:CSP) (as capital light model and a £1.5b order book as at 31 March) and Berkeley Group (LON:BKG) (as £1.1b in cash on hand). Neither are rock-bottom cheap but not expensive either so prepared to sit on them and see what happens.
"in a bubble, you’re not investing in a company, you’re instead placing a bet on the collective behaviour of other investors. That behaviour reveals itself in chart patterns rather than in balance sheets or valuations."
Yes. I have been trading the US tech and bio stocks recently, following the momentum. PER are off the scale many have no earnings yet market caps in the $ billions. It's just money flow now, not fundamentals. Not surprising Buffett has not participated.
Can someone answer me this question - why would Silence Therapeutics (LON:SLN) want to be listed on NASDAQ as well as AIM as per today's RNS? (Disc: I hold - in my gamble category). It seems to me that this is just adding to costs. I think it says that there is no dilution on the way - should we believe them?
Biotech valuations tend to be significantly higher in the US with far greater pools of funding. I would expect them to raise money again but I assume they will hope to do so from a higher valuation.
US listed biotechs are more highly rated (valuation) vs their UK listed counterparts. IE they probably think their shares are under appreciated here. Another reason is that nearly all the big specialist biotech investors are based in the US. There should be no dilution because they will create an ADS which will be based on a ratio of UK to US shares, but DYOR in case they do a secondary offering at the same time.
Noticed Renalytix also said they were dual listing on NASDAQ about a month ago. Factor in a couple of Covid RNS's and they are up 45% in that time.
Paul, you commented on Scapa (LON:SCPA) after the placement. Please will you cast an eye over the results today?
Thanks.
Second for Scapa please!
Yes, Scapa (LON:SCPA) is on the list! So I'll add a section later this morning.
Decent update from Ncc (LON:NCC) today:
https://www.investegate.co.uk/...
The Board expects Revenue and Adjusted EBIT 1(subject to audit) to be comfortably ahead of latest FY20 analysts' consensus expectations of £243m and £22.3m respectively. Revenue will be higher than in FY19 and Adjusted EBIT 1 will be lower, owing to our decision to preserve the capability and capacity of our business in readiness for the economic recovery.
Net debt down to £5m from £20m too.
The main value here is in the escrow business which is a cash cow. However, if they can sort out (or flog off) the remaining bits of the company then it's got decent growth potential. And given the broader situation anything around "cybersecurity" is always likely to bounce given a smidgen of news.
timar
I can't see how the Telegraph article is encouraging. The new bit is that the earliest availability of the Oxford vaccine has been pushed back from September to October. Also repeats what we already know, that they are having difficulty with the trial because the rate of infection is now low anyway in the UK so it's difficult to prove the vaccine is effective - they are looking to test it in higher infection rate jurisdictions which surely will push back the date further.
It seems to be the "re-opening trade" is a question of buying a story - you could get lucky, but chances are you won't. I'd rather wait for some figures. Anecdotally, I ventured into Guildford yesterday for an afternoon's shopping: with social distancing in place it is a tense experience (and won't be much different with a 1 metre rule) and I don't think it is going to catch on.
Interesting comments on the mortgage market and housing sector.
Certainly true that lenders are cautious about going to 90% with any meaningful deals, except Accord and HSBC as we speak.
But there is certainly the demand there.Whether this is pent up from before lockdown or new I am not quite sure yet. Estate agent activity and mortgage activity is currently surprisingly high.
"Certainly true that lenders are cautious about going to 90% with any meaningful deals, except Accord and HSBC as we speak"
Curious, I just had a look at the HSBC site. Yes, 90% LTV still listed but max loan size is £400k compare to 70% LTV where the max loan size is £3 million. So effectively they have knocked the London properties on the head for high LTV through loan size restrictions.
At present millions of people are living in a fool's paradise. They're getting 80% of their wages without having to do any work or incur any of the expenses associated with work. Over a million have stopped paying their mortgages / credit cards / car leases, so they're sitting on a pile of cash while having a great time in the sunshine.
So many people can't see beyond next week, let alone next year, and will assume that all this rather pleasant existence will just carry on, so with interest rates at absurdly and damagingly low levels why not jump on the bandwagon and move to a bigger house?
But the taxpayer-funded gravy train is going to hit the buffers very hard within a couple of months as the cash dries up. I know that many of my clients are planning redundancies once the furlough stops, but haven't yet told their workforce. There will be mass unemployment and widespread, very genuine hardship.
Apart from the simple fact that many people will have no money and be forced sellers of houses the general public mood will deteriorate rapidly, and pessimism is disastrous for the housing market.
I wouldn't touch house builders with a bargepole.
It's not all bad news. There are reports as well of people saving more and repaying debt (credit cards, etc) more than before the pandemic. So there will be some spare cash for consumers to use when (if?) the pandemic emergency comes to an end and business resumes as usual.
John Authors is spot on. It`s all about the precise timing of entries rather than wishful thinking.
Reuters:
ENTERTAINMENT: Cinemas, museums and galleries in England can reopen from July 4, Prime Minister Boris Johnson will say on Tuesday.
No pubs :(
"Pubs, restaurants, hotels and hairdressers will also be given approval to reopen their doors with coronavirus precautions in place on July 4." https://www.ft.com/content/4db0e676-072a-4dd1-878c-fd9e51d1b06c
I topped up Newriver Reit (LON:NRR) at the open since it has a 'hidden' pub chain. High risk of course - pubs and shopping centers, but it's low-geared (compared to many peers) and PBV is 0.34.
Hi Mr C,
I see that now in the telegraph ‘pubs etc to open’ but Reuters are not running that yet.
I change my emoji then. Pubs open :) - of course some may never set foot in one again but we’ll see if those who did, do again.
To my earlier point, reversals still a real threat ‘The more we open up, the more important it is that everyone follows the social distancing guidelines. We will not hesitate to reverse these steps if it is necessary to stop the virus running out of control,” a source in Johnson’s office said.’ or maybe this is just more rhetoric.
Muted response to Newriver Reit (LON:NRR) where i hope to recover some losses.
As usual, there is absolutely no consistency, and HMG is floundering around. Why is it OK to sit a few inches away from someone on an aircraft for several hours but not in a cinema or a restaurant?
There's no need at all for social distancing measures outside, and as trying to enforce the rules inside when the social distance is only a metre will be utterly impossible they may as well scrap all social distancing rules.
Instead, people must now be allowed to decide for themselves what level of risk they will accept. If you aren't happy going to cinemas or restaurants then don't go - but your reluctance shouldn't prevent the rest of us going if we want to.
HMG are still giving far too much priority to the health risks, which for most people are now quite clearly much less serious than originally anticipated. The emphasis must now be shifted to the economic risks, which are likely to be far more serious than anticipated.
Yes Pro Bono I think HMG is floundering around but I would suggest that they have caved in to economic pressures and have thrown caution to the wind in the comprehensive list of measures they have announced today, some of which fly in the face of some scientific opinion. For example, reducing social distancing to one metre is similar to no social distancing at all as, according to the BBC News, people have always stood about a metre apart when interacting in social situations so as you rightly say, they may as well scrap the social distancing rules. I think people realise that responding effectively to this pandemic is beyond the government's abilities, scientific advisers or not, and will behave according to how much risk they perceive they are causing to themselves and, I hope, other people.
I just read the rather lengthy summary of the new rules on the BBC website and I wouldn’t fancy my chances of scoring much above 60% if I had to sit a test on them. I doubt any of our political leaders would do better.
I think we are all using our own common sense at this point and the politicians are rushing to catch up and maintain the fiction that they are in control.
I think to flip between optimism & pessimism is quite right in this market, i’m still very wary, not of a second wave (and of course the media love this) but of governments reaction to this. The worlds governments are still
on the playbook of partial lockdowns & restrictions for a flare up, this is not a long way from where we were.
The US numbers are starting to look a worry, not from c19 being an infectious virus, but what the authorities will do. So as a look through 2021 i think generally positive as a lot of news on ‘this drug helps a lot’, but any move to shut leisure down on the continent is like to heavily influence Boris and co safety first mentality. As an example, here in spain the Chevez style state of emergency ended Sunday & nearly everyone in phase 3 of de-escalation,on monday a region was put back from phase 3 to phase 2 because a number tested positive in a factory.
This type of news and implications are the big downside to the recovery plays, but feeling this uncomfortable they could be very profitable. I have Loungers (LON:LGRS) Foxtons (LON:FOXT) On The Beach (LON:OTB) with OTB being now a long term hold with the others purely a trade. I wouldn’t buy either loungers or foxtons other than for a short term bounce.
Id be very interested in other short term ideas from others and of cause what you are buying Paul ( i know lots of comments & shared previously but this is a fluid time!)
All that said, for all the long term small caps i still hold i have low resting orders in as i can easily see another momentum driven lurch down. This is also a good way to play them evil market makers, damn them vultures, as when the market turns in a small cap a very low resting buy order can easily be hit, i picked up a few in the march/april slump this way. I also have out the money puts on the indices. So i guess that highlights my thinking, could go up & equally fall a lot, but 2 years out up, why not. Any other strategies out there?
Help to buy should really be renamed Help to make profits for housing companies. There has been long term suspicion that it inflates prices beyond normal market prices and therefore at some stage in a downturn will leverage participants negative equity.
I think that mortgage companies are cautious about such a downturn and therefore withdrawing 10% deposit products.
Is MrContrarian having a sleep in today? :)
No. Mr C should be renamed Mr Consistency for consistently providing such an excellent potted summary of the morning’s RNSs.
You are right and he literally posted at the same time as I did. I'm always used to seeing it first thing in the morning, but I guess today I'm up a bit earlier than normal. Nevertheless, I don't always get the time to read the full SCVR, but I always at least read MrContrarian's Smallcap tweet. Keep up the good work!
My morning smallcap tweet: Top GEAR
Fox Marble Holdings (LON:FOX) Frontier IP (LON:FIPP) AFC Energy (LON:AFC) TP (LON:TPG) SIMEC Atlantis Energy (LON:SAE) Clear Leisure (LON:CLP) Intu Properties (LON:INTU) Trackwise Designs (LON:TWD) Velocity Composites (LON:VEL) Pressure Technologies (LON:PRES) 1pm (LON:OPM) Gama Aviation (LON:GMAA) £G4M
Fox Marble (FOX) wins €600k contract for delivery in 2021.
Frontier IP (FIPP) posrtfolio holding The Vaccine Group has 2 covid vaccine candidates succeed in vitro.
AFC Energy (AFC) some progress with its AlkaMem anion exchange membrane for fuel cells.
TP Group (TPG) wins initial contract worth £0.3m to develop Artificial Intelligence tools for use in the oil and gas industry.
SIMEC Atlantis Energy (SAE) successful completion of industrial-scale combustion testing of the waste derived fuel pellets to be used at the Uskmouth Conversion Project. "The test conclusively proves that a pulverised fuel burner based on MHPS's DS® Ultra Low NOx burner can be used to stably combust the waste derived fuel unsupported (i.e. without any oil or gas support firing)."
Clear Leisure (CLP) settlement agreement has been reached with the Mediapolis Receiver regarding the transfer of the Mediapolis auction funds from the Receiver. €1.7m.
Intu (INTU) staring into the abyss. Still no areement with creditors ahead of the revolving credit facility covenant waiver deadline of 26 June. Has appointed KPMG to contingency plan for administration.
Trackwise Designs (TWD) FY(Dec) looks in line with Dec's trading stmt. Current trading - vague. Are all their computers on furlough?
Velocity Composites (VEL) H1 in line. "Velocity is resetting its cost structure." Ugh.
Pressure Technologies (PRES) H1(Mar) rev down 4%. Chesterfield Special Cylinders in line but Precision Machined Components (PMC) Q2 weak and and gross margin reduced to 25% (31%). PMC order intake in H2 lower than run rate, but "encouraged by recent levels of enquiry."
1Pm (OPM) FY(May) trading 'satisfactory'. Rev down 8%. Pretax £3.0m (£8.1m) after a 'one-off' increase in the bad debt provision of £2.1m. No material increase in bad debt write-offs at YE but increased bad debt provision as 'a prudent governance measure'. Gets £3.1m 5 year loan from its bank. New and/or reallocated existing facilities of £6.3m to lend to UK SMEs in the form of CBILS loans and leases.
Gama Aviation (GMAA) FY19 results expected July. Inc bad debt of $2.5-$3m. $1m inventory write-off. Errors found in 2018 inventory and receivables: $1.2m reduction to restated 2018 EBIT. Covid impact: US maintenance activity stabilised at c. 50% of budgeted level in April, increased slightly since. Special mission contract activity continued broadly as budgeted for UK government customers but charter sales continue to be heavily impacted. In the ME pressure on aircraft management charges and the lack of charter sales have been mitigated by cost reduction measures. Asia business has had to reduce pricing. $29m undrawn credit available.
Gear4Music (G4M) FY(Mar) rev up 9%, pretax £3.1m (-£0.6m), ahead of mgmt exp. Exceptionally strong trading in April and May.
Hi Paul,
I hope you have a chance to cover £G4M.
Gear4music Holdings (LON:G4M) reported today. Improvided gross margins, exceptional high trading in April, May, and June.
Assuming growth continues shares likely to be re-rated according to my model see graph below. (Note I have a long position here.)
DYOR.
BSV
G4M look in great shape. Re-rare on the cards for sure imo.
Of course, I always cover Gear4Music when it releases results or trading updates!
Thanks, Paul,
Always appreciate your company coverage both informative and entertaining.
BSV
Any more thoughts on the future of (£WDI) ? as an observer it's a fascinating case. Better than half the dramas on TV. I see on IG index lots of retail investors piling in on the short side. This looks dangerous to me.
Was referring to Wirecard. Not got to grips with inserting tickers yet...
Any more thoughts on the future of (£WDI)?
Wirecard is bust, the only thing keeping it going is the systemic risk to the payments system of letting it go under. That may mean there's some value there, but who knows? Ascribing any value to the equity is pure guesswork.
Decent article on it here, but anyone who's been following the FT on this won't be surprised:
https://blog.argonautcapital.c...
timarrThis is rather like the old Keynesian beauty contest idea I think:
Morning Paul. Re housebuilders, surely the governments help to buy scheme will go some way to maintaining demand for new houses? Mortgages are still available for new builds at 75% (5% deposit plus the governments 20% equity loan).
Morning Greg,
Good point, thanks. Do we know how long Help To Buy is continuing for?
I suppose my point about withdrawal of mortgage offers might impact the secondhand market, more than new build, possibly?
Regards, Paul.
Hi Paul,
According to a quick Google search, it will be reduced to first time buyers in 2021 and then removed all together in March 2023.
Another point worth mentioning is that whilst many lenders will have cut LTV's back over fears around house price falls, I believe for others it will have at least been partly to handle demand. Most lenders have a backlog of applications to get through due to lockdown stopping physical valuations. Many lenders are still focusing on automated computer based valuations to speed up applications/ reduce virus risk and obviously they deem it too risky to do automated valuations for high LTV cases.
Thanks,
Greg