Small Cap Value Report (Tue 23 March 2021) - LOOP, COG, PMP, TMO, LUCE, WYN, BOOT, ERGO

Good morning, it’s Paul & Jack here with the SCVR for Tuesday.
Timing - it's an all day job, with a deluge of results/trading updates out today. Update at 15:57 - today's report is now finished.
Agenda -
Paul -
Loopup (LON:LOOP) (I hold) - delayed accounts & NOMAD appointed
Cambridge Cognition Holdings (LON:COG) (I hold) - results in line with Jan 2021 trading update. Almost reached breakeven, strong order book, looks very good to me, and still cheap.
Portmeirion (LON:PMP) (I hold) - brief update from webinar last weeks, some interesting points I jotted down.
Time Out (LON:TMO) - Pulls out of a London development site, and confirms it is reviewing another fundraising proposal. Looks an awful investment to me, very high risk.
Luceco (LON:LUCE) - impressive results for FY 12/2020, in line with January's trading update. Still looks reasonably priced.
Jack -
Wynnstay (LON:WYN) - 'in line' trading update, 3.2% dividend confirmed, and two bolt-on acquisitions
Henry Boot (LON:BOOT) - improving outlook for this prudently run construction company
Ergomed (LON:ERGO) - great results from this high flying pharmaceutical services provider, but the shares might be too expensive for some.
.
Paul's Section
Loopup (LON:LOOP)
(I hold)
78p (pre market open) - mkt cap £43m
FY 12/2020 results are delayed. A very specific reason has been given - that a “routine technical review” has not been completed in time by the auditor, Grant Thornton. This relates to the amortisation treatment of intangible assets from an acquisition.
I’m surprised at the reason given. I would have thought it was very simple to decide whether goodwill has to be amortised or not. You just look at how much profit is being made by the subsidiary in question, and if that supports the goodwill on the balance sheet or not. If not, then you write it down. Why that would cause a delay to the accounts, I’m not sure. Is there some other reason, I wonder? (e.g. auditors not being happy with going concern?)
This bit is positive though - the RNS specifically re-confirms the 2020 results given in a previous trading update -
For the avoidance of doubt, this is a non-cash, technical accounting review and the Group reconfirms in line FY2020 results: revenue of £50.2 million (FY2019: £42.5 million); EBITDA of £15.3 million (FY2019: £6.4 million); year-end gross cash of £12.1 million (FY2019: £3.0 million); and net debt of £0.7 million (FY2019: £11.5 million).
That is reassuring. I don’t mind writedowns of intangibles, because I write them off completely when I analyse all accounts anyway.
My opinion - on balance, this update probably shouldn’t be price sensitive, if we take it at face value. It must be very difficult to audit company accounts during lockdown, as you would have to rely on the company emailing you everything. That’s the not the same as being on site, and rummaging around through filing cabinets, and observing the body language of staff you interview. It struck me as odd that training for auditors (when I did it in the early 1990s) didn’t include anything on reading body language, or how to phrase questions. Maybe they do that these days, as it was a yawning gap in the skill set of people who were supposed to be investigating the accounts. There’s a very good book on this, called Spy the Lie - written by former CIA operatives, if you’re interested in how to tell if people are lying, and how to tease the truth out of them with carefully structured questions - useful for our company meetings!
NOMAD - a separate announcement today, saying that Panmure Gordon will service as its NOMAD and sole corporate broker with immediate effect. It’s not clear if this is linked to the delay in the accounts or not.
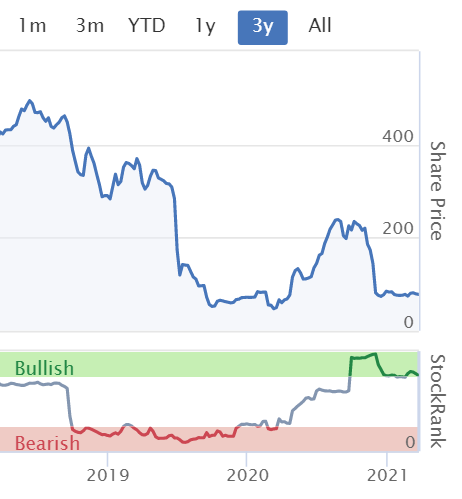
LOOP shares are almost unique in having had no bounce at all in the last 6 months. Either there’s an opportunity, or things are going really badly. It had a really good H1, when lockdown 1 started, but then seemed to hit a brick wall in H2. Maybe customers switched to using Microsoft Teams instead? We’ll find out in due course.
I've got little confidence in the company or its management, due to erratic decisions & performance in the past, so have resisted the urge to average down on my existing (thankfully smallish) holding. I'm too stubborn to sell.
.
.
Cambridge Cognition Holdings (LON:COG)
(I hold)
78.5p (up 5% at 10:00) - mkt cap £24m
Cambridge Cognition Holdings plc, which develops and markets digital technology to deliver customer-focused solutions to assess brain health, announces its unaudited preliminary results for the year ended 31 December 2020.
I’ve followed this company since it floated in 2013. The product sounded very interesting, and I attended a demo in the City a few years ago, lured by free beer and canapes. The key point is that, whilst its product looks simple (cognitive tests on an iPad, to detect & measure things like dementia, or the mental impact when taking a drug trial), there’s decades of data and experience backing it up - hence a proper moat, and high gross margin.
Despite this, revenues never seemed to gain traction, seemingly stuck between £5-7m p.a., and it seemed to generate losses, and burn cash nearly every year, as you can see -

.
Positive trading update - I reported here on 19 Jan 2021 that the FY 12/2020 update looked good, with a 34% rise in revenue to £6.74m, and the £(2.9)m loss in 2019 having been largely eliminated, with only £(0.44)m loss for 2020.
Key factors were: 2 large one-off orders of £3.1m in 2020, and a reduction in overheads.
Probably of more importance though, was the very strong order book, which almost doubled to £11.17m as at 31 Dec 2020, of which “at least” £6.0m expected to be recognised as revenue in 2021 - meaning that nearly all of forecast 2021 revenues are already contracted, and making further growth look very likely. It’s a very high gross margin business too, therefore it only needs a small increase in 2021 revenues, to move into profits at long last. Hence why I concluded in Jan 2021 that this share is starting to look interesting.
.
Investor presentation - is today at 18:00 - open to all - details here.
.
Preliminary Results - this is out today.
Key points -
Revenue up 34% to £6.74m - as expected
Record sales intake of £12.7m (up 159% on a year earlier - highly significant)
Almost at breakeven, loss after tax credit, of £(438)k greatly reduced from £(2.9)m loss in 2019 - again as expected, in line with the Jan 2021 update mentioned above.
Operational gearing - looks exciting, with a gross margin of 80% - meaning that the record sales intake is mainly gross profit - that’s what I look for, when searching for growth companies - a highly profitable niche, combined with strong order book growth, can have a transformative boost to profitability, if it can be sustained.
Balance sheet - not great, it only has £57k in NAV, but that’s probably adequate. However it looks as if COG has a favourable working capital cycle, probably receiving customer stage payments up-front I imagine, because it’s sitting on net cash of £3.05m - probably adequate, especially as it should be profitable from now on. Hence I’d say the risk of another placing looks low, and would probably only be small anyway, so low risk of further dilution.
Accounting looks conservative - it seems that development costs are written off as incurred, rather than being capitalised, which is good.
Retained earnings, in reserves, is negative £(17.4)m - suggesting that COG should have plenty of tax losses to offset against future profits.
Cashflow statement - very simple figures. Note 5 shows that the positive operating cashflow of £1.0m all came from favourable working capital movements (creditors rising more than debtors). There was £1.4m from a placing. Those were the main causes of the cash pile rising from £901k to £3047k in the year.
Overall, I can’t see any funnies in the numbers, these look simple & clean accounts.
Outlook - all important in turnaround situations.
Subjectively, the commentary today sounds more upbeat than last time, some examples;
We expect the business to continue to grow strongly through 2021 and beyond…
We have a strong pipeline of opportunities that we aim to convert into orders and revenues in 2021 to add to the £6.0m of contracted order backlog we expect to realise this year…
We were pleased to be profitable in the last quarter of 2020 and would expect that to continue into 2021. We are anticipating further revenue growth and plan to continue careful financial management and targeted investment in research and development…..
With a strategy focused on commercial execution, substantial value anticipated from newer eCOA and Digital Health solutions in attractive, high growth markets, together with the established CANTAB™ product and the commercial launch of NeuroVocalix™ planned for 2021, we believe that we are well placed to continue to build substantial, sustainable shareholder value. We look forward to reporting further exciting progress in 2021….
My opinion - this looks really good.
Although the share price has risen a lot in the last year, the market cap is only £24m. For a niche growth company that’s just moved into quarterly profitability, and has a bulging order book, that valuation still looks modest to me, especially in a bull market like this. £50-100m looks more realistic to me.
As a serial disappointer in the past, I wonder if it might take the market time to recognise that a sustainable turnaround appears to be happening here?
My broker told me last week that there’s a seller in the market, so that could be an opportunity to pick up some more stock before a potentially big re-rating occurs? I think all the signs are looking good here.
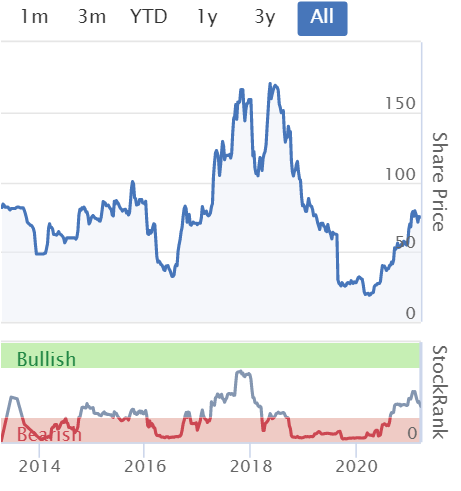
The only negative I can think of, is that revenues don't seem to be recurring, so there's always a risk that the order book could dry up again. But with 2 years' revenues already in the bag, contracted, that risk doesn't seem imminent. Also, as you can see from the chart below, since it listed there have been some false dawns before. Which might make people hesitant in trusting the strong recovery underway now, perhaps?
.
.
Portmeirion (LON:PMP)
(I hold)
Just a few quick points from the recent InvestorMeetCompany webinar from last week. The recording is now available here.
Key points that I jotted down are worth noting, as subjectively it felt more upbeat than the RNS itself, or maybe I didn’t read the RNS carefully enough - I have so many companies to cover, that I rarely have enough time to read all the commentary -
- Big new range of Sophie Conran designed products to be launched, which is a popular, strong selling part of the business
- Outlook - “real momentum going into the next couple of years”
- Reducing factory costs by 10% - e.g. automation projects £1.5m capex, payback 2-3 years
- Increasing factory capacity also
- Procurement cost savings of c.£1m by end 2022 in the pipeline
- Factories currently running at close to full capacity - sounds encouraging
After watching the webinar, I feel there are more reasons to be cheerful about holding this share, than when I wrote a section about it earlier.
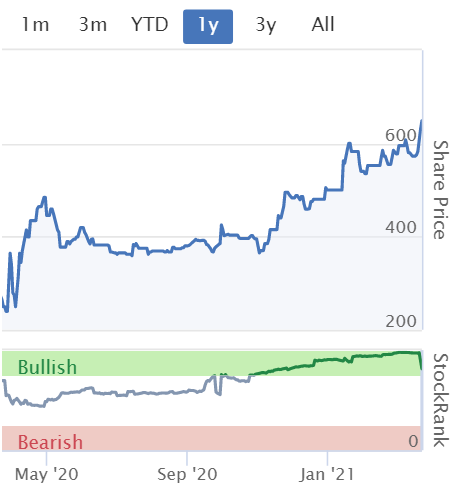
It’s not a shoot the lights out type of share, but a decent recovery in earnings from poor 2020 figures, looks underway. Also, I’ve always been convinced there’s hidden value in its many brands, and their heritage. Similar to Sanderson Design (LON:SDG) (I hold). These brands could appeal to a takeover bidder, and be broadened into more lifestyle brands with much broader product categories, and sold internationally. Hence I like both PMP and SDG for the long-term potential. Although as with most things, the prices have risen a lot in the last 6 months, so you do wonder at what price the market is up with events?
.
.
Time Out (LON:TMO)
37p (down 20% at 11:50) - mkt cap £106m
Time Out Market London (Waterloo) & funding update
This caught my eye on the top risers & fallers list. The update which came out at 10:05 seems to have triggered a sharp fall in price.
Time Out has pulled out of a development project at Waterloo, due to the impact of covid (and presumably not having the money to proceed with it either?).
Fundraising -
This decision does not change the Company's need to secure additional funding, as a result of the financial impact of repeated periods of pandemic-related containment as previously stated in its interim results on 30 September 2020.
Consequently, the Company is currently reviewing an equity funding proposal that would ensure the Group has financial and operational flexibility. It is anticipated that an update will be provided at the time of the Company's interim results announcement on or around 30 March.
Looking back through the previous RNSs, this company raised c.£47m in a 35p placing & small open offer, in June 2020.
I’ve checked back, and the interim results (6m to 30 June 2020) published on 30 Sept 2020 did indeed mention that more funding might be needed. Remember that this company was heavily loss-making & cash burning before covid, so it started off in a ropey position, before covid lockdowns clobbered its whole sector. Very unfortunate, and not the company's fault of course, it's operating in probably the worst sector for covid impact - a magazine for leisure/events, and food markets.
Last time it needed more cash, TMO benefited from having major shareholders who seemed happy to back the company, at a not unreasonable price discount of c.15% with fresh funding at 35p.
.

.
This is a wider point worth noting - I’ve seen in several other cases, having supportive, dominant major shareholders, seems to have generally worked out very well for companies needing cash injections over the last year. Whereas companies with a fragmented shareholder base can maybe find it more difficult to raise money at a sensible price. New investors aren't bothered about diluting the existing holders, indeed are incentivised to demand a deep discount on pricing of a placing.
Each situation is unique I suppose, but my general feeling is that it’s probably best to have a cornerstone, deep-pocketed investor, or several, who are prepared to stand their corner in a crisis & put in more funding, which is what happened before at TMO.
My opinion - I’ve never understood that appeal of this share.
Look at this historic performance - it’s terrible! Obviously the light blue forecast blobs are pie-in-the-sky now, so should be ignored.

.
That said, clever and shrewd people, are big shareholders here, so they must see something good in the future potential.
Smaller shareholders are now completely at the mercy of the major shareholders, and if, and on what terms, they are prepared to keep pouring money in, to keep TMO afloat. For this reason, I think this share needs to be seen as currently very high risk.
Major shareholders are stuck in it. Whereas little people like us, can go in & out at will. Therefore, I cannot see why anyone would want to buy or hold a potentially insolvent company, and hope that the major shareholders will put in more money at a favourable price? It seems a lot of risk, for not much upside.
.
Luceco (LON:LUCE)
265p (up 5%, at 14:38) - mkt cap £426m
Luceco plc ("Luceco", or the "Group" or the "Company"), a manufacturer and distributor of high quality and innovative wiring accessories, LED lighting , and portable power products, today announces its audited results for the year ended 31 December 2020 ("FY 2020" or "the period").
I covered Luceco’s FY 12/2020 trading update here on 22 Jan 2021. It had a highly successful year, with a series of positive updates.
These numbers look bang in line with the update in Jan 2021.
Revenue of £176.2m, up 2.4% on 2019
Adj EPS of 15.5p (up 101% on 2019) is slightly higher than 15.0p forecast from Liberum.
Adj operating profit is up from £18.0m in 2019, to £30.0m in 2020, yet revenues only rose 2.4%, how come? The answer is margin improvement (profit up £8m), and cost cutting (profit up £4m). That’s great, but companies generally cannot keep raising margins and lowering costs forever. So I see this large increase in profits as a bit of a one-off in 2020. Future profit growth is likely to be more modest in % terms. Ultimately top line (revenues) growth is needed to drive continued profit growth.
Valuation - at 265p per share, and 15.5p adj EPS, the 2020 PER is 17.1 - which looks reasonable.
Balance sheet - the number that jumps out at me is £71.8m in receivables, up 65% on a year ago. That doesn’t look right, it’s too high relative to annual revenues of £176.2m, and why would receivables have risen 65%, when revenues are only up 2.4%?
There’s a similar large increase in trade payables. Why do customers take so long to pay?
I’ve found an explanation in the commentary, it says -
The Group once again converted all its Adjusted Operating Profit into Adjusted Operating Cash Flow. Rapid sales growth and associated industry-wide supply chain constraints in the fourth quarter resulted in a temporary increase in working capital towards the end of the year. Widely reported port delays in China and in the UK due to Brexit meant some finished goods were not delivered until early 2021 and there were delays in the issuance of port documents required to collect payments from customers. This temporarily increased year-end inventory days to 107 days (2019: 105 days) and receivable days to 105 (2019: 89 days). Port delays are now reducing, and I expect working capital levels to normalise in 2021. Trade payable days also increased, due to the increased activity in Q4, from 75 days to 95 days.
Outlook comments - sound positive -
"We have started 2021 with strong momentum despite tighter social distancing measures in some markets. Revenue growth has accelerated from the high levels achieved at the end of last year as new business wins, increased home improvement spending, superior access to high growth channels and product availability combine to sustain further market share gains.
"We have seen inflation in raw material and freight costs in 2021 as economies recover from COVID-19. These can be expected to create some temporary gross margin pressures for all manufacturers until they are passed through the value chain or otherwise subside. However, we expect our strong sales momentum and tight control of overheads to mitigate the impact of inflation on operating margins, which should be similar to those achieved in 2020. We therefore remain confident of further revenue and profit progression in 2021."
Investor presentation is on 29 March at 11:00 - details here.
Dividends - are becoming more generous -
As previously announced, the Board has therefore approved a new dividend policy with the payout ratio increased from 20-30% to 40-60% of Adjusted Profit After Tax. It is recommending a final dividend of 4.7p per share, which with the interim dividend of 1.5p, is consistent with a 40% payout
My opinion - Luceco continues to look good. A company that has performed remarkably well in 2020, and sounds upbeat about the future as well, at a reasonable price.
The commentary explains the working capital increase, so hopefully that would unwind in H1 of 2021 - I’ve just submitted the question: has working capital now normalised? for the forthcoming webinar on InvestorMeetCompany.
Overall, it looks a good company, at a still-reasonable price, despite the big rise in share price. The rise looks justified.
Jack's section
Wynnstay (LON:WYN)
Share price: 467.5p (pre-open)
Shares in issue: 20,051,043
Market cap: £93.7m
(I hold)
Wynnstay (LON:WYN) is an often neglected agricultural business that splits its operations into two divisions: Agriculture (covering the manufacture and supply of agricultural inputs to farmers), and Specialist Agricultural Merchanting (which supplies specialist agricultural and retail products to customers).
The share price spiked up to 532p earlier in March - a clear break out to a 52-week high - so sentiment does appear to be improving. With shares now back down to 467.5p, a forecast PE ratio of 13.6x, and a forecast dividend yield of 3.3%, I would argue the shares still offer value but that the shorter term rerate opportunity has reduced.
That said, and while the company is unlikely to generate tech or healthcare levels of growth, its dividend track record is terrific, its business model is resilient (but cyclical), and its medium to longer term growth opportunities are understated in my view.
The key takeaway is that trading in the first four months of the financial year ending 31 October 2021 has been in line with management expectations.
Farmer sentiment has continued to improve, buoyed by higher farmgate prices and greater clarity over the future direction of UK farming, following the Trade Agreement with the European Union and the passage into law of the Agriculture Bill.
Feed sales and sales in the Specialist Agricultural Merchanting division in the period were ahead of last year but Arable sales were down due to lower winter cereal seed volumes.
Wynnstay has expanded its presence in the east of the UK with the two bolt-on acquisitions (previously reported) and the group remains an essential service provider with full operations.
A final dividend of 10p will be paid on the 30th April, so the total dividend will be 14.60p. That’s a yield of 3.2% and is a 4.3% year-on-year increase.
Chairman Jim McCarthy is stepping down as chairman after eight years and will remain on the board as a Non-executive Director until 31 July 2021. He will be succeeded by Steve Ellwood. It looks like a predictably steady and sensible transition.
Conclusion
The last two months of the first half are important trading months in the seasonal calendar, so an ‘in-line’ update for the first four months is encouraging, particularly when coupled with the improving farmer sentiment.
Even though Wynnstay’s shares are not as cheap as they have been over the past year, this remains a sensibly run operation with a long term outlook and steady, if unexciting, growth potential. And its StockRank remains very strong, with a Value Rank of 92 particularly impressive given the recent rerate.

It’s fair to say that when the shares were at between 300p and 350p, as they were for most of last year, there was a more obvious shorter term rerate opportunity.
But, while trading can be volatile here, I continue to think there is a longer term investment case to be made for stable, income-producing, cash-generative growth as Wynnstay consolidates via bolt-on acquisitions in a fragmented UK agriculture industry.
Henry Boot (LON:BOOT)
Share price: 285.9p (+0.66%)
Shares in issue: 133,208,931
Market cap: £380.8m
Henry Boot (LON:BOOT) has been successfully operating in land, property and development for over 130 years and comprises three segments. Running through these quickly, we have:
Land promotion
- Hallam Land Management - strategic land and planning promotion, well into its third decade of acquiring, promoting, developing and trading in land,
Construction
- Henry Boot Construction - construction contractor to public and private clients,
- Road Link (A69) - which has a 30 year contract to operate and maintain the A69 trunk road between Carlisle and Newcastle.
Development
- Henry Boot Development - dealing with more ambitious developments,
- Stonebridge Homes - builds and sells family homes in Yorkshire,
The group also has Banner Plant, which offers a range of products and services for sale and hire.
It strikes me as a sensibly run operation that considers its shareholder base. In fact we can see the Major Shareholders list is dominated by Boot and Reiss family members and trusts. But the share price performance has been fairly pedestrian over the past five years - is that a lack of progress, or a sign of undervaluation?

Final Results for the year to 31 December
A little further down these results is perhaps the key sentence for a construction company given that the past year has inevitably been impacted by Covid-19:
Good start to year, ahead of expectations on activity, order book and forward sales in land, development and housebuilding
Full year highlights include:
- Revenue -41% to £222.4m,
- Profit before tax -65% to £17.1m, ‘ahead of expectations’ due to land disposals and a resilient second half,
- Earnings per share -68% to 9p,
- Net asset value per share of 235p (2019: 239p),
- Net cash position steady at £27m,
- Final dividend of 3.3p and total dividend of 5.5p, up 10%.
That puts the group’s shares on an FY20 PE ratio of 31.6x with an FY20 dividend yield of 1.9%. It’s an historically conservative and well-covered dividend though and, if we expect business to fully recover, then assuming a return to FY19’s 27.6p of earnings would see a much more appealing earnings multiple of 10.5x.
The group’s resilient net asset value per share of 235p should provide further reassurance.
Boot also touts an evolved strategy focusing on three long-term markets: industrial & logistics, residential, and urban development, ‘all of which are driven by positive long-term trends’.
The land promotion business sold 2,000 plots and its interest in a major JV in the Midlands. This capital was then recycled into growing the landbank to 16,607 acres (2019:14,898 acres). There’s a £1.4bn development pipeline (HB share - £1.1bn) with 78% in industrial and logistics.
Stonebridge Homes performed ahead of target after completing on 115 sales in 2020 and secured 57% of their sales target for 2021. The land bank increased to 1,119 plots including a site in Wakefield secured for 149 plots.
Boot’s construction business recovered well in H2, performing ahead of expectations with a turnover of £86.2m. Encouraging demand, led by public sector customers, has created a full order book for 2021.
All in all, it sounds fairly encouraging.
Conclusion
The good thing about Henry Boot is that it looks to be prudently run and, reading through the detail, it’s clear that the group has managed its way through Covid with minimal lasting impacts for shareholders.
Boot initially utilised the Government's CJRS but only ever had a minority of people on furlough, with the business topping their pay up to 100%. It stopped using the CJRS in August 2020 and paid back all furlough grants claimed under the scheme in February 2021 as confidence levels stabilised.
The group has a strong balance sheet as well, with net cash of £38.5m as at 28 February 2021, committed debt facilities of £75m, and material retained earnings, so it’s in a good position going forward.
And now the group observes encouraging signs of recovery, which has translated into a good start to the new year. Meanwhile, Boot’s three key markets of Industrial & Logistics, residential, and urban development, all benefit from structural tail winds.
The group believes this strategy can generate an average ROCE between 10-15% p.a., without high levels of financial gearing, and so fully intends to grow profits to beyond pre pandemic levels.
Perhaps Boot is not a clear bargain in the same way so many companies have been over the past twelve months, but I would argue the valuation is undemanding given that it is a quality operator with a shareholder-friendly culture that is well placed to capitalise on an encouraging outlook. It’s probably suited to longer-term investors.
Ergomed (LON:ERGO)
Share price: 1,237p (+3.08%)
Shares in issue: 48,746,109
Market cap: £603m
(I hold)
Ergomed (LON:ERGO) provides specialist services to the pharmaceutical industry across all phases of clinical development, post-approval pharmacovigilance and medical information.
Its fast-growing services business includes an industry-leading suite of pharmacovigilance (PV) solutions under the PrimeVigilance brand, as well as high-quality clinical research and trial management services under the Ergomed brand (CRO).
This is an impressive healthcare growth stock with some excellent CAGRs, so well worth revisiting in my view.

As an aside, it is one of the Stockopedia Investment Club’s best performers. You can see Ben’s original write up here.
Highlights:
- Revenue +26.5% to £86.4m,
- Gross profit +34.6% to £39.7m and gross margin up 2.6ppts to 45.9%,
- Adjusted EBITDA +55.2% to £19.4m,
- Net cash +32.9% to £19m,
- Order book +55.5% to £193m,
- Basic adjusted EPS +29.6% to 25.8p. Basic statutory EPS +67% to 20p.
It’s an excellent set of results on the face of it and, predictably, the main sticking point is valuation.
Based on these results, Ergomed shares trade at 48.5x FY20 earnings per share. FY21 is forecast to see earnings per share rise to 30.5p for a forecast PE ratio of 40.1x - so yes there’s exciting growth here, but the shares are quite expensive. Stockopedia shows the forecast PEG to be 2.4, which is high.
That said, Ergomed operates in large and growing markets so there is plenty of room for future growth. The gross margin expansion bodes well, too.
There are a fair amount of adjustments in the accounts, detailed in note 8 but none of them jump out as particularly aggressive.
Goodwill and intangibles have grown significantly, up from £13.38m to £24.65m and £2.76m to £9.62m respectively, but the group does have nearly £47m of current assets and no debt on the balance sheet. So it’s asset-light but not risky, with net tangible assets of c£18.6m.
The growth in revenue and profitability led to strong operating cash generation and cash conversion of 99% to adjusted EBITDA. Cash and cash equivalents grew by £4.7m to £19.0m at the year-end even after net cash outflows on the acquisitions of Ashfield Pharmacovigilance in January 2020 of £7.6m and MedSource in December of £4.4m.
Net cash from operations is up 53% and, with less than £1m of capex, free cash flows look robust.
Furthermore, consolidated retained earnings now stand at £45.4m (up by £50.9m) following a capital reduction and the generation of distributable reserves.
PrimeVigilance
Looking at the 26.5% revenue increase in more detail, it looks like pharmacovigilance has delivered the growth. The division is up 55.6% to £55.1m after the Ashfield Pharmacovigilance acquisition, and up 30% on a like-for-like basis.
There is an increasing global requirement for pharmacovigilance services and an ongoing drive to improve drug safety through regulation. These are good tailwinds for Ergomed’s pharmacovigilance business and its position as an outsourced specialist.
In Europe, the implementation of Good Pharmacovigilance Practice ('GPvP') in 2012 and subsequent mandatory compliance has led to an increased demand for outsourced PV services and been a consistent driver for Ergomed's growth.
In the US, the existing stringent PV regulatory regime continues to be regularly strengthened on an ongoing basis.
Similarly, PV regulation continues to be rolled out in the Middle East, China and South East Asia, providing further growth opportunities for Ergomed's PV business. It can leverage existing partnerships here to facilitate growth.
Interestingly, the group says that Brexit will add regulatory complexity and ‘drive further demand for specialist outsourced PV services’.
This division has acquired and integrated Ashfield Pharmacovigilance
This is an established PV provider in North America, that has been rebranded as PrimeVigilance USA Inc. ('PV USA') and significantly expands Ergomed's PV offering in North America.
Ergomed CRO
Revenue in Clinical Research Services (CRO) was flat at £31.3m despite COVID-19, with service fee revenue returning to growth in H2 (up 13.5% over H1).
The CRO market has experienced significant expansion with high annual growth in oncology and rare disease research expected to continue over the coming years. More general tailwinds include increased investment in drug development by pharma-biotech companies, a shift towards clinical trial outsourcing, and strong growth in the number of trials in markets such as Asia.
There has been an acquisition here, too: MedSource. This is a US-based CRO business with over 20 years' experience in delivering specialist oncology and rare disease clinical trial services.
It further strengthens Ergomed's position as a high-quality oncology and rare disease CRO provider in the strategically important North American market.
Conclusion
Ergomed continues to make great progress despite the COVID-19 pandemic. In fact, the pandemic is spurring innovation and investment in infrastructure, technology and digital transformation.
It’s been a great year for the company, with two key strategic acquisitions in the US. The group looks well positioned for further organic and acquisitive growth as it seeks its goal of achieving ‘global leadership in specialised pharmaceutical services addressing unmet medical needs and patient safety’.
Ergomed says it has finished its transition to a fully services-based business model, which was originally announced in 2018, freeing it up to focus on the services-based model in both PV and CRO and allowing it to reduce R&D expenditure from £0.5m in 2019 to £0.2m in 2020.
Yes, the shares are expensive based on earnings and cash flow multiples, but this might be one of those instances where you pay up for a high quality, rapidly expanding company and just let it compound over time. The order book to start 2021 looks particularly strong.
Ergomed has so far achieved a compound annual revenue growth rate of over 20% since the IPO in 2014 and there are no signs of this slowing.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
Luceco (LON:LUCE). Promising snippet at the end of the results presentation where they mentioned entry into the EV charging market. This will be huge and even if they only get a small share it will contribute to growth. They certainly have the manufacturing capability and infrastructure to do well in this area.
Time Out (LON:TMO) If this link from morningstarworks, it explains the prospects, albeit now held back by covid. This ought to help Paul understand the appeal of this share and help explain it's interest from the 'clever and shrewd people' involved.
https://lt.morningstar.com/e4e...
That's it....no more from me onthis !
Time Out... (why doesn't this £ in front of ticker wiork ? )
Finally : re: your 'lot of risk, not much upside' comment. Pre Covid price was 125...current price apart from this week's blip...35. hmmmmm
Time Out (LON:TMO)
It does.
oops.. presses Enter...I'll continue...
The time out market Lisbon is a fantastic atmospheric open experience. It is scaleable all over the World. They are next moving into the middle East. London will be a temporary hold because Dubai is better. It is about how they can expand within the constraints of cash. So covid means they have to rein themselves in a bit.
So why have these big boys funded it... no mystery really, they envisage a scaleable very popular product.
Sometimes the opportunities are beyond the immediate numbers. Of course the immediate numbers are terrible. But this is a 10 year development. Why are investors involved.?they see an opportunity.
My advice: as soon as one re-opens go there and you will understand, it ticks all the boxes for modern, cash rich, 20-50 year olds.
It will tootle along with the occasional upward blip, but when lockdown finishess, despite the need for more funding, this will press ahead. It's a Market opportunity. !
End of part 2
Time Out (LON:TMO)
"The time out market Lisbon is a fantastic atmospheric open experience. It is scaleable all over the World"
I completely agree. Lisbon was the first Time Out market I saw and (in normal times) I can certainly see it being popular in other countries too.
Re : Time out £TMO
Firstly: forget about the publishing business. This is all about the Time Out Markets. Ultimately businesses are all about the product. Of course you have to get everything else right, but if you don't have good products you are sunk.
Time Out markets are a great product. When you are allowed, have a weekend break in Lisbon...apart from being one of the great cities of the world, the T
Well the long-awaited 'Tax Day' has gone down like a wet cod https://www.telegraph.co.uk/ta... (for once, not hiding behind a paywall). Opportunity missed to do much radical stuff. No CGT changes so far and no on-line sales tax (awaiting international initiatives?). Not clear if expediting tax from 'freelancers' will impact those who earn a few bob from investments but have no regular income.
The second largest shareholder in Checkit (LON:CKT), D & A Income, Ltd has just notified the sale of almost all of their 19% holding.
But you failed to mention the flip side, that the 19% stake in Checkit (LON:CKT) was picked up by a company called Montoya Investments Limited.
The trade was also done at a decent price compared to the prevaling bid-ask that day too.
Haven't been able to find out who the eventual owners are, although news articles say they also have owned declarable stakes in Elektron and Pressure Technologies before.
Thank you for the FULL picture as the first post caused me a slight heart flutter ( I hold)
"The second largest shareholder in Checkit (LON:CKT) D & A Income, Ltd has just notified the sale of almost all of their 19% holding".
With all due respect that is only half the story - the purchaser was Montoya Investments Limited.
We know little of D&A as it hides behind a Jersey registration and that it picked up most of its stake in an emergency "cashbox" placing in 2014: https://investegate.co.uk/elek... . Montoya hides behind a BVI registration but does name the final holder as Graham Edwards. Google leads us from this https://londonminingnetwork.or... to this https://www.telerealtrillium.c... Make of it what you will.
Edit - dahokolomoki - you beat me to it!
Re Time Out (LON:TMO) my wife worked there for many years and she told me that they were a basket case that never made any money in the twenty years she did work for them. The model was. obviously, based on advertising. So I was surprised to see Oakley Capital Investments (LON:OCI) as the major investor as I knew the CEO there and he was a sharp cookie which put me off ever investing in Oakley Capital Investments (LON:OCI). That has been a mistake because their other investments have done well. But, frankly, Time Out (LON:TMO) was an absolute howler of an investment from the outset that shows that even good outfits can make super-sized mistakes.
Worth noting that Timeout is now very small part of the Oakley Capital Investments (LON:OCI) portfolio so wouldn't be too concerned about that. It seems a bit of an outlier as the rest of their companies have done very well and mainly focused on the digital economy.
Ah, but when the facts change you should also re-evaluate your investment opinion :)
Time Out (LON:TMO) is no longer banking on magazines, content, and advertising revenues.
The play now is whether they can execute a global network of food halls under their brand, and make money from it.
To be honest, I'm skeptical and barge-poling their new business model having looked at it.. But some of the best multi-baggers have come from former basket-cases who manage to pivot and create a successful new business. Many investors put companies on permanent bargepole lists. But when management, strategy, and market changes.... so should our opinions.
A recent post says "The present CEO is called Matthew Stork...". The CEO of which company?
Apologies for repetition but will people please say what company they are writing about. There are 7 different settings for reading these comments - 6 on the new site and 1 on the old and only 3 of these are threaded which would give a clue to which company it is.
Thanks
Hello sharw.
Matthew Stork is the CEO of Cambridge Cognition ( COG) . It is my post was written in reply to a post about this company by mammyoko. My post is a 'tabs width to the right from Mammyoko so you can tell it is in reply. He/she said the directors at COG had no medical experience amongst other comments which I do not agree with.
Hope this gives you clarity.
Michael
It is my post was written in reply to a post about this company by mammyoko. My post is a 'tabs width to the right from Mammyoko so you can tell it is in reply.
You are clearly reading with a different screen layount to the one I'm using here. It was not a "tabs width" away.
Please just follow the advice and quote the company.
@peterg
Happy to write the name of company each time.
Had no idea that some could not see clearly that a response corresponded to a particular post.
--presentation of comments--and why EPIC codes are important
I don't see the tabs width. Neither, apparently, does sharw. If half of readers do not, that would be c. 3500 readers.
When I first read SCVR, I read it threaded (with the tabs width). As it is difficult to find comments added after my initial reading if I view the threaded version, I switch to unthreaded (without the tabs width) where I find all unread comments in a red box. By not mentioning the name of the company, you are denying me and perhaps c. 3500 readers with similar reading strategies the fruits of your wisdom.
When I am looking back at readers' comments in old SCVRs during research, I only look for the specific EPIC code in question; it is easy to spot in blue. If the EPIC is included in the comment, I can easily find what could be essential information.
If you feel that you are writing something important that you want to share and that you feel others would find beneficial, it really is important to remember to supply the EPIC code.
Duplicate post
Cambridge Cognition Holdings (LON:COG)
Thanks for everyone's thoughts on this company. I don't hold but to add a couple of observations:
I'm not sure it matters given the enlarged order book, but I thought it worth highlighting.
No holding yet, but if the growth story continues and the company can return to being at least cash flow neutral, then I will certainly be more interested.
GLAH
A
Agreed Abtan. Cambridge Cognition Holdings (LON:COG) may be a winner....but so far its only shown its not a perennial loser
Today's move is spectacular for results that are not. £30m for £7m of revenue that is highly growth and margin uncertain.
Clearly the guys promoting this stock have a huge amount of understanding of its advantage and scalability and its not just another hope and hype to the crowd thing...
Re Cambridge Cognition Holdings (LON:COG)
I listened to the presentation (I've looked at and watched presentation before too). CEO Stork is good and sensible and executed well since coming in. He's got a plan that's cut to COG's cloth...herein lies the stock's valuation problem...what price a modest growth stock with middling rather than high software biz margins?...
IMO this is a stock to buy at a moderate valuation for its cash generation and some element of growth option. However, today it is priced as a high growth option company. This means that investors are likely to be disappointed. I guess that a price up 2/3 current is an entry point.
Management are being 'too honest and diligent' if they don't take advantage of the current high price to raise cash. A nice round £6m more sets them up to invest in growth including product development in way they are currently restricted in due to cash and resource
Of course theme/narrative speculators are selling the software-healthcare dream nexus....be wary.
Afternoon Paul
Portmeirion (LON:PMP) and Sanderson Design (LON:SDG) share many similarities as you indicate and I liked the direction and strategy for the former outlined in the recent investor meet presentation.
I have held Sanderson Design (LON:SDG) for close to three years and was fortunate to add when the pandemic hit. My reason for doing so was the value of its archives, especially William Morris and Sanderson. At the time I paid 39p versus analyst's value of the company's historic archive of 92p or thereabouts. I am also impressed by the new management team under Lisa Montague and how they have set about optimising the value of the company's brands.
Hopefully Portmeirion (LON:PMP) will be equally successful. However what deters me from investing in Portmeirion (LON:PMP) are the paltry holdings of senior management. As far as I can tell Mike Raybould, CEO and David Sproston hold 2631 and 1315 shares respectively, acquired last summer when the company raised £11.8m by the issue of 3,096,604 shares, about 25% of the equity. Admittedly Lisa Montague does not have a substantial holding in Sanderson Design (LON:SDG), but it is decidedly greater than Messrs Raybould and Sproston holdings in £PMP.
Just my view. Also I am happy to be corrected if my numbers for senior management's holdings in Portmeirion are out of date.
duplicate, ignore
....or its a good way to ensure you control the narrative as much as possible
https://order-order.com/2021/03/23/hancock-warns-eu-third-wave-can-hit-uk/
No no no... not anymore!
"Matt Hancock told the Today Programme this morning that a “third wave appears to be taking hold” in Europe, with a rising number of cases, hospitalisations, and new lockdown measures reimposed in countries like France and Germany. The Health Secretary said that rising cases on the continent has led to rising cases at home before, acknowledging that “This time we have as a defence our very extensive vaccine programme”, insisting caution is still necessary to “protect” that success. Hancock explained that:
“In fact this is all about how we stick to our roadmap out. Because we have got out vaccination programme, we’ve got hope on the horizon, we can see our way out. The roadmap guides us on that route out, following the data all the way through checking that things are going well.
But there are two concerns. One is the sheer number of cases if international travel brings home more cases, but the other is the risk of a new variant that the vaccine can’t deal with as effectively. Both of those are unknowns… therefore it’s reasonable for us to take a precautionary careful approach, which is what we are doing at the borders.”"
This ("the third wave") is a bad bad signal, if it turns out as badly as the last 3 Lockdowns / waves.
Dont believe a word of it any more I am afraid.
As of today I am a holder of Saga (LON:SAGA) after following Paul Scott in, somewhat delayed but well below today's price. However, I have been disturbed by the sequential falls in SP from a high of over 400p no more than a week ago. That hurts. I fully accept the argument that it is a several year hold, but I think that the 'several' is becoming more than I had originally planned.
Additionally, there is stronger rhetoric coming not only from the Heath Minister but also from across the Channel frorm the likes of Mrs Merkel (who I do listen to) as distinct from President En Marche (who I dont). I foresee the UK government wanting to stick to its promises for the road map out of lockdown as far as possible within our borders. If that means sacrificing the overseas sector this year, then I would guess the attitude is 'so be it'. I do not see that cruising from and to our shores will receive special treatment, unless it is controlled rigorously, and does not include any port visits to countries outside the UK (possibly ROE excluded, because of the Common Travel Area, but even then......
Thinking back to the radio interview with Hays Travel over the weekend, if any cruises are likely to benefit, then it will be the 'specials' like hastily arranged P&O vessels traveling around Britain. I dont see Saga (LON:SAGA) making any such changes to their original plans other than to delay them - see their website, and tell us here if you can find any.. IMHO, their best bet is to make money out of the late autumn period, assuming eg Continental European ports are accepting vessels by then; after all October cruises-are largely focused on France,Spain,Croatia and the rest of the Med. That isn't going to do much for this financial year, where I could see forecasts going down and down.
For next year, there are some big bets by Saga (LON:SAGA) on Caribbean and South America, after what should be a good Canaries period over Christmas.
I really would welcome other views, and especially persuasive more positive views.
As a holder I'm inclined to believe that the longer-term outlook for SAGA remains unchanged, so I will continue to hold without losing too much sleep. Might be worth revisiting previous write-ups on Stockopedia to remind oneself why we invested in the first place. I am of the view that nothing has really changed, although the timescales may have changed a bit.
Many vaccinated holidaymakers (and buyers of travel shares) in the UK are getting too excited too early about resuming adventures abroad. Successful mass vaccination programmes in much of the rest of the world is by no means certain this year or next and there are the unknown consequences of new variants. My feeling is that travel companies will be burning cash for a fair bit longer than investors currently expect.
I have written to Saga to enquire why they are not doing UK centric cruises?
Other cruise lines are seeing the opportunity why cant Saga?
Hello manbre. I will be interested to hear what Saga (LON:SAGA) have to say. The way I see it is that £SAGA's apparent advantage of UK back to UK could turn out to be their short term weakness. As I say, they seem to be just pushing back their cruises (or presumably cancelling some?) to non UK destinations, whereas the P&O's of this world werent going anywhere and so can switch to UK only cruises almost at a moment's notice.
Some of their ships are here already. P&O and Princess have short cruises on offer now - 3 and 4 days at this stage, in June, July to Sept. P&O are also offering non stop (apparently) cruises for up to 7 days too in Aug and Sept on a choice of a couple of ships, Britannia and Iona. Great value, special drinks packages included. What's not to like? Have a look at the P&O website
Fred Olsen are doing the same, though they seem to have some stopping cruises in the UK already planned in.
Ridavies Saga (LON:SAGA)
I really would welcome other views, and especially persuasive more positive views
Sorry, but I can’t offer any more positive views and Momoko Miyamoto has just written most of my response. I don’t hold Saga (LON:SAGA) but I do know we hold another share in common and whilst it’s now coming good the money could have been put to better use in the meantime. We have a (rescheduled) river cruise booked for May 2022 but I’m not convinced we’ll risk it even then.
On Saga (LON:SAGA) I wouldn't get too upset of the decline from 400p. The run-up to that was just all hot air, full of speculators and punters looking for quick profits. Fair play for anyone that spotted it and cashed out. But if you're in it for the long term, the only question you need to ask is if your personal valuation has changed, and whether 320p still is below your expectation of where the share price will be in a few years.
If you're not a long term type holder, then you really shouldn't have gone into this share based on rationale that it will be higher "in a few years". It's like buying Wagyu Steak because a credible expert said it has the best marbling and taste, but you're actually a vegetarian.
For me, the key modeling any SAGA holders need to do now is - if first cruises are delayed till Aug/Sep, does the company have enough cash? Does it need to raise more equity? The earnings from FY23 are unaffected. However, there might be a higher risk of further fundraising or taking on more debt, which changes the EV and share count.
Time Finance (LON:TIME) not wasting any today. Why the interest? I’m back in the black...got another 300% to go before thinking about selling :)
Like you, I have followed Cambridge Cognition Holdings (LON:COG) for several years waiting for the moment to invest. Until now there hasn't been one because they have been serial disappointers never reaching breakeven. I don't know whether it is still applicable but a few years ago they were a medical solutions company without a single medically-qualified Director which, I seem to remember, had serious consequences for their sales efforts. Perhaps that has now been remedied?
I think the following from the annual report is sinificant
It should be noted that the 2020 performance was accentuated by two large one-off orders that, together, totalled £3.1 million. Such large single orders are outside of the scope of normal business and may not be repeated every year.
However, I do think that the numbers now suggest that they may have a decent couple of years and on that basis I took a position today but I will be running a pretty tight stop based on their previous performance.
The present CEO is called Matthew Stork. He joined Feb 2019.
Dr Matthew Stork
Chief Executive Officer
Dr Stork has twenty-five years’ experience of managing companies in the med tech sector and expertise in AI, IT, diagnostics, medical equipment, and pharmaceuticals. He has a degree in pharmacy from the University of Bath, a PhD in Artificial Intelligence in Medicine from King’s College London, and an MBA from London Business School. Before becoming CEO of Cambridge Cognition in 2019, he held managing director and divisional leadership roles within GE Healthcare Digital, InHealth Group, ArjoHuntleigh, Canon Medical Systems (formerly Toshiba) and Smith & Nephew.
He has also rationalised the sales team with a focus on commercialisation which has culminated in this turnaround.
I take your point about the large contracts but the fact that they were booked is positive. It means this can happen again or maybe larger contracts can be won?
Without these one-off larger contracts, the order book already stands at £6m for year ending 31st December 2021 which was originally targeted at £7m. Target now increased to £8.5m. In 2020 the value of additional contracts booked during 2020 far exceeded the amount in the order book at the start of the year. If this repeated this year, there would be a massive beat. If COG booked the same number as in the order book at the beginning on the year, revenues for this year would be £12m (target £8.5m).
I hold (obvs biased)
Good morning gents, might it be possible for you to comment this week on H & T (LON:HAT) (I hold) preliminary full year results announced today? It apprears to me that the gold price has been a prop in 2020. Thanks
Loopup (LON:LOOP) has been my worst performer these last 12 months and disposed of 50% last year after it showed little sign of starting to recover. I await the disclosure of the interims with baited breath. If they don’t shift the sentiment in a northerly direction then they will go. I agree with Paul, Goodwill in my view can be a reflection (in my opinion) of the coy paying over the odds for acquisitions . The damage to cash was done when it was bought and in my view the auditors if they were of that view should have expressed it in the last audited accounts. (I used to be one many many years ago!)
Other than the odd legal Eagle Eagle not much of a moat. Pumped by IC etc. With MSM to compete with a hard play.
Morning Paul
I am interested to read your comment on Cambridge Cognition FY results as I also hold.
Yesterday another company in the Life Science / IT sector called Instem announced a 'transformative' acquisition of D-Wise for $31m following hot on the heels of another acquisition on 1st March of The Edge for $8.5m. I wrote about it on SCVR yesterday with more details but I think Ben may have run out of time.
These acquisitions form part of Intem's strategy. Funds were raised last Summer to cover a number of acquisitions as the plan was to grow this 'highly scalable' business. Instem has an excellent track record for acquisitions.
Maybe you might take a look?
Obvs I am biased as I hold.
Michael
Henry Boot (LON:BOOT) seems to have avoided being given the boot by Mr C this morning (profits down 65%!)
Earnings well down on last year - largely covid related -they do construction services by the way.
Boot come across as an extremley safe pair of hands with their ultra conservative approach to most things - they have made the decsion to repay all furlough funds they were eligible too - they have paid all staff 100% of salaries too so that the covid hit has been fully taken by the bottom line of the company and no one else (as far as i can see) - i applaud the company for this act of fairness of despite this fairness coming direct from my pocket prqacticably speaking - if all people / organisations and the powers that be acted with fairness life would be better overall IMHO.
The shareprice has only slightly creeped upwards for boot - so they have probably well underpeformed compared to shares that have bounced back more stongly recently. With the decent NAV (235p) reasonable outlook - 2% dividend and modest pe if they can get back to EPS of 30p ish per share i am more than happy to continue to hold here. Are they at risk if recession hits in construction ? - probably but their strong balance sheet and minimal gearing (nil!) mean they should come through tough times with ease.
There is always the execution risk with lumpy contracts but they seem to manage to avoid these banana skins genrally spekaing.
Its pleasing to see they have plans to expand the housebuilding side of things to 600 units per year - they only did 160 units at stonbridge in 2019 so thats great news as long as they don't expand at the peak of the property boom - hmmmmm
So overall i agree with the company when they say the outlook is encouraging.
Hello millaree re Henry Boot (LON:BOOT) I think that the decision to maintain their employees' pay and repay the government is the right thing to do with the former and the moral thing to do for the latter. As for their employees, maintaining a strong, experienced workforce (trade-wise and company loyalty-wise) is long sighted IMHO. Ready to get up and go when the doors are opened again fully.
Today's results with webinars coming up over next few days:
Personal Group (LON:PGH) FY20 results webinar with Q&A next Tuesday 30.3.21, 11.30am. Register here.
Announced today: Rev of £71.5m w EBITDA of £10.1m. Pipeline of opportunities with direct & partners. Sage Employee Benefits currently delivering >£1m recurring revenue pa. Insurance sales impacted by lockdown.
Pebble (LON:PEBB) FY results webinar with Q&A this Thurs 25.3.21 at 12.45pm. Register here.
Group revenue and adj EBITDA ahead of expectations. New year started well, in line.
On Personal Group (LON:PGH) anyone knows why no RNS shows up on Stocko? I've raised a ticket on this a few weeks back but still doesn't look like its fixed.
There seems to be a problem with some RNSs, I reported TM17 results missing.
That is still not fixed either.
Does Luceco (LON:LUCE) still fit in SCVR?
YES
Paul (&Jack if he’s there), credit to how much I appreciate your work that I missed you yesterday!
My morning smallcap tweet:
Panther Securities P L C (LON:PNS) Dev Clever Holdings (LON:DEV) Biome Technologies (LON:BIOM) Oxford Biodynamics (LON:OBD) Symphony International Holdings (LON:SIHL) Iconic Labs (LON:ICON) accesso Technology (LON:ACSO), Quartix Holdings (LON:QTX), Wynnstay (LON:WYN)
Panther Securities (PNS) loan facilities extended to July 2021, as expected. "The refinance of our term loans is now expected to receive full credit approval and complete within the Extension Period." [SP=205 Cap=36m]
Dev Clever (DEV) how do you get a member of the Lords to be your paid mouthpiece? Make him chair of a Business Advisory and Intelligence Group. "I am delighted to become the Chairman of the BAIG. Dev Clever instantly aligned with my personal passion to ensure the youth of today are given the best start through effective careers advice and professionals are supported on their journeys..." [SP=37.5 Cap=192m]
Biome Technologies (BIOM) wins expected contractual commitment with a second US end-customer "to accelerate the commercialisation of its proprietary compostable filtration material. This important customer's business will support a significant portion of the Group's expected revenue growth in 2021 and beyond." Buys another $70k of equipment. It's all in current market f/c though. [SP=279 Cap=10m]
Oxford BioDynamics (OBD) US launch of its EpiSwitch COVID Severity Test. It identifies high-risk individuals by detecting genomic biomarkers so that they can manager their risk. Sounds genuinely useful. Next test to launch will be "a predictive immune response profile for immuno-oncology checkpoint inhibitor treatments in 2021." No idea how improtant that is but personalised medicine is a big step forward. [SP=69.9 Cap=65m]
Symphony (SIHL) Dec NAV/sh $0.7384, up from $0.653 in Sept. Rise mainly due to 28% increase in the share price of Minor International. Discount to NAV 51%. [SP=0.38 Cap=187m]
Iconic Labs (ICON) troubled media tinpot sees more directors scarpering: NED and CEO. They are thanked. [SP=0.01 Cap=3m]
Accesso Technology (ACSO) FY(Dec) rev $56m ($117m), ahead of expectations set out at the onset of the pandemic. Adj EPS -60.64c(+30.78c). Cautiously optimistic for 2021, expecting pent up demand. [SP=520.2 Cap=214m]
In line: Quartix Holdings (LON:QTX) Wynnstay (LON:WYN)
PS I greatly enjoyed my spot on the Mello investor show yesterday.
Re your comments on Oxford Biodynamics (LON:OBD) - the Covid Severity Test is important and helps prove the Episwitch technology but the the immuno-oncology test could be signficantly larger
Good Morning Paul,
would very much appreciate your thoughts on Cambridge Cognition Holdings (LON:COG) who published results this morning:
Financial summary
· Record sales order intake of £12.7m (2019: £4.9m)
· Revenue up 34% to £6.7m (2019: £5.0m)
· Gross profit up 39% to £5.4m (2019: £3.9m)
· Loss for the year £0.4m, a £2.5m improvement (2019: £2.9m loss)
· Loss per share 1.5 pence (2019: 12.4 pence loss per share)
· Cash balance at 31 December 2020 £3.0m (31 December 2019: £0.9m)
Looks like quite a step change to me?
many thanks
Sure, I'll look at Cambridge Cognition Holdings (LON:COG) next (I hold)
The company is giving a presentation this evening - registering is a bit cumbersome (compared to something like InvestorMeetCompany), but details are here: https://otp.investis.com/clien...
Yes, a tiny bit more complicated but it saves COG around £2000 if they organise the presentation themselves. I consider this a good sign of cost management, particularly important for a small company.
thanks Michael - that is interesting information. I have often wondered about this, so great to have a hard number as a frame of reference.
£2000 !? Investor Meet Company actually charges nearly double that whereas companies can come and present to 600 in live audience at Mello as part of an evening investor show for just £850 as we do not want to put companies off and we guarantee huge audiences. ShareSoc also offer single company webinars at a much lower cost than IMC
Investors speaking to companies should get them to consider a Mello or ShareSoc appearance
IMC is a good service and I am certainly not knocking it but there are lots of options out there.
Thanks for the clarity on prices David.
"Investors speaking to companies should get them to consider a Mello {...} appearance".
This might be fine for supplementary investor PR, but investors should be able to interact with companies at least once a year, without having to pay a third party.
I would therefore encourage investors speaking to companies to request that they primarily use Investor Meet Company or other free to investor alternatives such as Tamzin's PI World.
Good point gtrdave, shareholders shouldn't have to pay a gate- keeper to see management present their company progress.
My understanding is that InvestorMeetCompany charges £3,500 p.a. for unlimited numbers of online presentations.
More power to everyone creating great content, and connecting private investors with companies, I'm a fan of everyone doing this, as it's incredibly helpful.
If I'm aware of a company webinar coming up, then I'll always try to remember to include a link in the relevant section here, with no favours given to any particular organiser, they're all doing a great job, long may it continue :-)
Also, I encourage people to post links in the comments here, for company webinars, as Tamzin & David do. Similarly, if people find links to company presentation slides, then feel free to post them here too, as often I won't know they're available, so it helps me too.
Regards, Paul.
Neither investors or companies should have to pay, it is market information. RNS should have an upload presentation option.
Well ... providing that service comes with a (significant) cost. Somebody has to pay. If it's not companies and it's not investors, who should it be?
US companies have earnings calls that all can join and put the slides on their websites. Same with the German shares I hold. Simple.
Loopup (LON:LOOP) were supposed to announce results today, amortisation issue has delayed them.... is this share being on purposely driven down for takeover? Either that or LOOP management completely inept on not letting this strap being hit and no decent news for 3 months! H & T (LON:HAT) seemed like good results to me with a decent divi and good figures considering store closures, with good eCommerce sales.
A takeover is a distinct possibility....
On H & T (LON:HAT) one KPI to look at is the pledge book. This is a forward looking indicator correlated to future pawnbroking revenues within the next 6-12 months.
After hours announcement from Medica (LON:MGP) last night of an acquisition and accompanying placing. Hidden at the back of that was a trading update, which reiterates in line but also notes that the NHS appears to be moving off a CV-19 war footing and is starting to resume elective procedures:
https://www.investegate.co.uk/medica-group-plc--mgp-/rns/proposed-acquisition-of-us-based-radmd/202103221707090897T/
My thesis is that the private sector healthcare providers like Medica and Emis (LON:EMIS) would see a strong earnings uplift as we come out of the pandemic and elective procedures resume. I don’t think that’s reflected in the prices yet unlike other, perhaps more visible, sectors like hospitality and travel.
Healthcare providers will be dealing with a backlog of work for months if not years, NHS waiting lists are estimated to be at 10 million cases, reflecting the impact of the pandemic on non CV-19 treatments.
timarr
I hold Medica which seems attractive. Had EMIS on my watchlist for ages. It seems attractive on financial metrics but also low growth and tied into essentially one customer- the NHS. Is there something that could lead to EMIS having higher turnover once the Covid crisis ends?
Is there something that could lead to EMIS having higher turnover once the Covid crisis ends?
Hi Mark
The growth in earnings has been pedestrian but a glance at the quality figures shows that this is very decent business. They gave a PI World presentation on their recent results which is well worth listening to:
https://www.piworld.co.uk/2021...
They didn't take any Q&A and it felt a bit staged but I thought it was a good explanation of the strategy. They're now extending their offer out into life sciences companies.
Ultimately this is a big data business and their integrated architecture lowers their cost of execution - so it'll be a lower cost business. They're also expecting 5% to 9% growth in revenues going forward.
It's a very nice business. Maybe not one that will shoot the lights out, but it's more likely to surprise on the upside than the down.
timarr
I hold Medica (LON:MGP) as well. However, I am thinking whether they've overstretched themselves - Ireland acquisition last year, JV in Australia, and now an acquisition in USA.
There's only so many hours in a day for the C-suite and having to then do 3 different time zones is a big stretch. Not to mention their core UK operations will see a surge in demand this year, which they'll need to make sure they can cope operationally.
Hoping they've not bitten off more than they can chew, in their ambition to accelerate EPS growth...
In a similar vein w.r.t hospital backlogs, £TRX (I hold) is all funded up with £9.5mn per latest TU, with new U.S CEO, additional manufacturing facilities + new white label products growth area.