Small Cap Value Report (Tue 24 May 2022) - RTN, RWI, MEAL, AVON, LORD, EPWN

Good morning, Paul & Jack here today.
Agenda -
Paul's Section:
Restaurant (LON:RTN) - a surprisingly upbeat trading update, with no slowdown in demand evident. In line with expectations. Concessions (airport) business is recovering well. Other divisions also trading well, and coping with higher costs. Encouraging, but will demand remain as robust in future?
Parsley Box (LON:MEAL) - talk about rewards for failure! New share options give failed Directors 9% of the upside from any recovery, after they've destroyed 90% of the share price from a float only a year ago. Ridiculous, but sadly, this is one of many examples of executive greed, at the expense of private investors.
Lords Trading (LON:LORD) - my first review of this building products distributor, doing multiple acquisitions, which listed on AIM last year. I think it looks quite good!
Epwin (LON:EPWN) - today's trading update seems reassuring. Looks cheap, but that depends on your macro view.
Jack's section:
Renewi (LON:RWI) - FY23 expectations upgraded thanks to a helpful recyclate pricing environment. Renewi is managing cost inflation well and its business is exposed to some positive trends, so there are signs of promise. But regulation has been an issue before, contingent liabilities remain, and the financial health is not the strongest. Assuming trends continue though, the company could be one to look at.
Avon Protection (LON:AVON) - the CEO departs, which is important for restoring credibility here. Events in Ukraine may also have materially improved the medium term demand outlook. But the group is cautious on the second half and has embarked on an £18.5m buyback, while maintaining its dividend despite net debt shooting up. That means leverage of 2.6x is getting close to the 3.0x debt covenant. In light of recent performance, I view this as too risky.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Restaurant (LON:RTN)
54p (yesterday’s close)
Market cap £416m
Trading Update (AGM)
The Restaurant Group plc operates approximately 400 restaurants and pub restaurants throughout the UK as at 24 May 2022. Its principal trading brands are Wagamama, Frankie & Benny's and Brunning & Price. It also operates a multi-brand Concessions business which trades principally in UK airports. In addition, the Wagamama business has a 20% stake in a JV operating five Wagamama restaurants in the US and over 50 franchise restaurants operating across a number of territories.
TRG provides an update today for the Group's year-to-date trading performance comprising the 19 weeks ending 15 May 2022 ("YTD").
I thought this would be an interesting share to look at, since the much-publicised cost of living squeeze must, one imagines, be impacting the whole hospitality sector - given that it’s discretionary spending. Although anecdotally I’ve seen no evidence at all of that, both in London and Bournemouth, where people seem to be out in bars & restaurants, and spending freely. Mind you, it’s better to rely on data, rather than personal impressions.
The other point which might help the sector, is that so many zombie companies are now facing winding up petitions, and eviction from sites with unpaid rents (renot moratorium having now ended, I believe). Hence expect the sector to considerably contract, leaving more market share for those that have stronger finances.
Hence I’m scrutinising RTN’s update today for signs of a slowdown.
This table looks encouraging. Although there seems a slowdown in growth from Q1 to Q2, the footnotes (I’ve highlighted) are key, and explain this difference being down to the ending of the temporary reduction in VAT, which boosted Q1 sales. VAT returned to 20% in Q2.
.

.
The other query I had was over the impact of lockdown on the prior year figure. It’s easy to forget when the lockdowns happened, so this is a handy timeline to bookmark, when queries arise. This shows that the UK was in lockdown in the prior year, but then I realised that RTN is using 2019 pre-pandemic as the comparator year. Hence being 6-15% ahead is really rather good, but necessary I would say, to absorb the higher costs (esp. wages, which would probably be 10-15% higher over that 2 year period).
The concessions business is mainly airports, which seem to be strongly improving as travel returns to near-normal.
New sites - 8+ new Wagamamas planned. Plus 3 new delivery kitchens. That’s a key point actually - the pandemic seems to have triggered a step change in customers ordering online for delivery. So successful restaurants now have to also be good at delivery/takeaway.
3 new pubs also planned.
Inflation - food/drink cost prices are expected to rise 9-10% (previous guidance was 5%).
Finances - net debt down £6m since year-end, and cash headroom >£220m. Planning on reducing debt, and funding expansion.
However, as I explained here in March 2022, RTN has a weak balance sheet, with negative NTAV. Therefore it is heavily reliant on debt, not something I would want to see if a recession is on the way. Mgt glosses over this fact today, saying that it is in a “Strong financial position”, which is clearly not correct, given that NTAV is negative £(160)m. It worries me that management is so blase about the debt pile.
Outlook - this is very encouraging, and exactly what I would want to hear in the current challenging macro environment -
Management's current expectations for FY22 remain unchanged, with continued robust trading in our Wagamama and Pubs businesses and the stronger recovery in Concession sales offsetting the increased food and drink inflationary impact in FY22.
My opinion - a very impressive update, and better than I was expecting.
It just shows, the best businesses manage well in tough macro conditions, whereas weaker businesses blame inflation, Ukraine, consumer caution, etc.! Anyone but themselves, for not being good enough!
Checking the key Stockopedia graph on broker expectations, there’s been a profit warning by stealth, with brokers steadily reducing forecast EPS for FY 12/2022 by more than half the original expectations, as you can see below. This is a key point right now - I want to see this graph heading downwards, to reflect the tougher economic conditions. If forecasts remain high, then that probably means a profit warning is on the way, with the stomach churning 30% plunge in share price that tends to accompany profit warnings. It's much better when done like this (below), i.e. broker expectations managed down gradually. Then the company can report in line trading -

.
This is a very tough sector, facing multiple headwinds, so I would want a strikingly cheap entry price to open a new position here. Overall, I’d say that RTN looks priced about right. The key positive, is that it’s coping with higher inflation. Therefore once inflation subsides again, the business should be in good shape to grow profits again.
Could be interesting as a longer term investment. I wonder whether it will be able to continue offsetting higher costs? Indications seem to be that food inflation could get worse, due to the big rise in fertiliser prices, and supply constraints from Ukraine. So I wouldn’t want to bank on food/drink inflation easing any time soon, which might prove a struggle for RTN to handle. Although so far, it’s doing well.
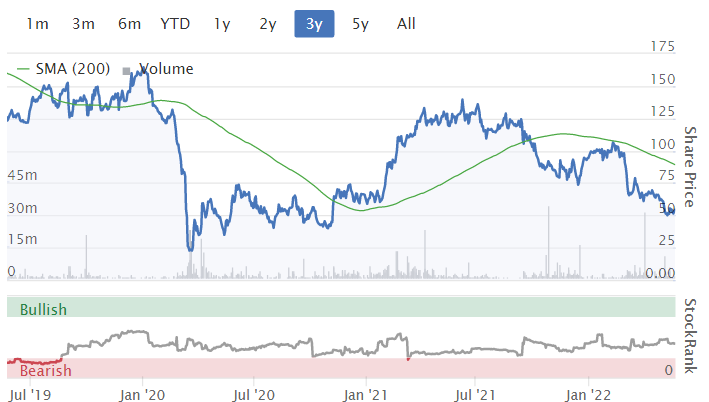
As you can see below, the share price is back down to summer 2020 levels. Although note that there's been a lot of dilution here, with the share count now up to 765m, with 2 fundraisings, one to buy Wagamama, and the other to prop up the balance sheet during the pandemic.
.
.
Share Options
We often complain here about excessive remuneration for listed company Directors.
Not only excessive salaries, but also bonus schemes that pay out when the economy is doing well, rather than anything to do with the actions of Directors. Plus other incentive schemes, that often rely on soft targets, or incentivise Directors to take risks, like making acquisitions and taking on too much debt, due to chasing performance targets for personal enrichment.
By far the worst schemes are so-called value creation plans, which in my view are nothing more than legalised theft - inserting an intermediary holding company, so that Directors can hive off partial ownership of the company.
Not far behind that, is nil-cost options.
I don’t particularly mind standard share options, to lock in a genuinely strong CEO, with a strike price set at the current share price level. Then the CEO benefits from a rising share price, and it’s a good way for a hired hand to build up a meaningful stake in the company they manage. All too often though, they’re cashed in early, being treated like a bonus.
The last form of reward which aggravates me, is resetting or replacing share options at a low level, after a period of lamentable performance. For example -
Parsley Box (LON:MEAL) - today announces new share options for 3 Directors, priced at 20.5p. Remember this is the team that has run the company into the ground, delivering a 90% share price fall in its first year as a listed company, and burning through the cash pile, requiring a 20p fund raise recently.
Today’s 6.6m in newly granted 20.5p share options is 9.1% of the company! Giving Directors options over 9% of the company would be stretching things, if they had done a great job. But having presided over 90% shareholder value destruction, why on earth would shareholders want to lock in these Directors?! Let alone reward them if they manage to claw back some of the losses. It’s just beyond the pale, and makes me reach for my even longer bargepole.
Sometimes, Directors, and their advisors, just seem to be living on a different planet to private investors.
.
Lords Trading (LON:LORD)
88p (up 5% at 08:54)
Market cap £139m
Lords, a leading distributor of building materials in the UK, announces its annual results for the year ended 31 December 2021 ('FY21' or the 'period').
This is our first look at LORD, which floated on AIM in July 2021. Is it yet another opportunistic, over-priced float, from major shareholders cashing out in the pandemic boom? (like so many other recent floats). We’ve been correct to be highly wary of recent floats, so many of which have been awful, and/or overpriced. Although there could be bargains emerging now prices have dropped so much, possibly? I do wonder how the brokers managed to get so many floats away at such inflated prices! Why were so many fund managers happy to drastically overpay in 2020 & 2021? Just a bull market I suppose.
Slow reporting - The reporting schedule for LORD is way too slow. It’s not far from the 2022 half year now, so to be getting FY 12/2021 results in late May 2022, is way too slow.
There was a FY 12/2021 trading update, but even that wasn’t published until 26 April 2022. If the CFO is on top of the figures, then a FY 12/2021 update should be issued some time in January! Not late April.
April 2022 trading update - covering FY 12/2021, I’ve summarised the key points, so we can compare with today’s actual results further down -
- Revenues in line with expectations at £363m
- Profits in line or above: £21.5m adj EBITDA, adj EPS >5.4p
- 7 businesses acquired - seems a lot.
- 2022 Q1 - LFL revenues down 4%, total revenues up 13.5% due to acquisitions.
- Supply constraints for boilers - expected to worsen in April/May 2022, then improve.
- Underlying demand remains strong.
- Performance “Largely in line” for Q1 2022, expecting £438m FY 12/2022 revenues, and PBT £16.0m.
Good clear guidance there. I’m a bit concerned at the rapid pace of acquisitions. Let’s see what LORD says today.
FY 12/2021 actual results
- Revenue £363.3m - fine, that’s in line with guidance.
- Gross profit £62.7m (17.3% margin is low, but up from 16.4% in FY 12/2020)
- Adj EBITDA of £22.3m, above guidance (of £21.5m)
- Adj PBT £10.2m (up 149% on LY) - note this is less than half EBITDA.
- Adj EPS 5.48p - fine, slightly ahead of 5.4p guidance.
- Dividend of 1.89p.
No surprises there, so all OK re profitability.
Balance sheet - looks OK to me.
£50.7m NAV, less intangible assets and deferred tax liability, comes to NTAV of £30.9m.
Inventories & receivables look about right for the size of business.
Gross interest-bearing debt has greatly reduced, from IPO proceeds, and is now only £4.9m, which is exceeded by cash of £11.4m, hence net cash of £6.5m. That’s good, but I always assume a bit of year-end window-dressing, so a more normal figure would probably be around cash neutral, possibly?
I think this balance sheet does have scope to fund more acquisitions. 4 more have been done since the year end. Does management have the bandwidth to integrate so many acquisitions I wonder? Note 2.2 shows that there are substantial bank facilities available, although the IPO document says mgt want to be prudent re debt, and limit it to 1x EBITDA, which reassures. I also see that they've done a lot of acquisitions so far, and claim to be a well-known consolidator in the sector, so target companies come to them. I like the sound of that.
Cashflow statement - looks good in both 2020 and 2021, although remember to take off the lease-related payment of £6.75m, which is now in financing activities, and reduces operating cashflows of £19.5m by about a third.
The biggest entries relate to the IPO - £28.5m (net of fees in fresh equity raised), and £35.2m (net) of interest-bearing debt paid down.
Overall then, this looks a genuinely cash generative business (although the track record as a listed company is only brief), that is using cashflow to acquire other businesses, and paying divis. That looks quite appealing to value investors - providing mgt know what it’s doing re acquisitions, I’d want to know what their track record on acquisitions is like before investing.
Mopping up smaller competitors could be good, or it could create a can of worms.
So far, pretty good. Now let’s look at the important outlook comments -
Outlook - this (below) sounds fine to me, as it uses the same wording as the April 2022 trading update.

.
My opinion - this is only my first look at LORD, so please bear that in mind. With all companies, we gradually learn more about them as time passes, and multiple results/updates are digested.
So far though,I quite like the look of LORD shares.
There’s an obvious risk from supply constraints for boilers, its largest division. Although that might allow it to jack up prices, and make more profit on reduced revenues?
The balance sheet & cashflows look solid to me, so no issues there.
I see its founder family controlled still, which I generally like, providing they treat outside shareholders decently.
Time to do some more research on this share, as it has passed my initial review, as looking a decent share, and sensibly priced.
There’s an InvestorMeetCompany at 1pm today, so I’ll tune in & report back if there’s anything useful to add. Whilst, as always, bearing in mind that mgt will give the positives primarily, that's their job!
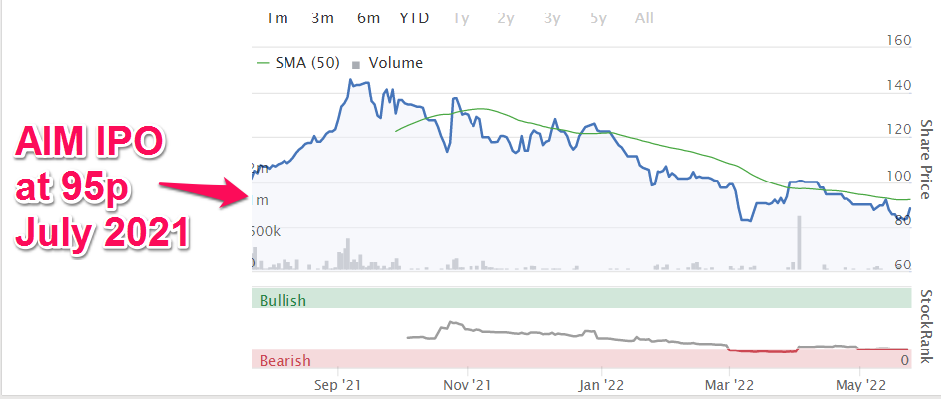
The AIM Admission Document is here. The key bits can be read in about an hour or two, so worth checking before putting money at risk. It floated at 95p, and is currently 88p, so not a bad performance in a falling market, so far.
Overall, this is going on my watch list, as something to potentially sniff around once macro conditions become clearer. Meanwhile I’ll do more research - this is the perfect time, because as my broker said to me, there’s a buyers’ strike in UK small caps. So we can research at our leisure, ready to pounce once sentiment turns up.
.
.
Epwin (LON:EPWN)
82p (up 2.5% at 11:59)
Market cap £119m
It’s interesting to see that the last year’s share price of EPWN looks so similar to LORD - a timely reminder that so many share price movements are actually sector moves, and it doesn’t necessarily mean you’ve picked a good, or bad, company to invest in.
We can see below that LORD ran to a premium after its IPO, which has since scrubbed off, and it’s since tracked EPWN down -
.

.
Epwin Group Plc (AIM: EPWN) ("Epwin" or the "Group"), the leading manufacturer of energy efficient and low maintenance building products, supplying the Repair, Maintenance and Improvement ("RMI"), new build and social housing sectors … in respect of current trading
This relates to FY 12/2022.
Jack reviewed its 2021 results here, and sounded “fairly positive” about them.
Positive trading -
"I am pleased to report a continued strong trading performance in the first four months of the year, with revenues to 30 April 2022 15% ahead of a strong comparative period in 2021.
Demand remains robust, particularly from the key RMI market.
Inflation - this sounds reassuring -
"Material costs, particularly PVC resin, have continued to increase during the year, mainly as a result of the tragic events in Ukraine. The Group's strong relationships with its PVC resin suppliers have ensured it has been able to secure material supply. The Group continues to work with its customers to pass these costs on equitably through price increases and surcharges and remains confident in its ability to manage further cost inflation.
Liquidity - >£55m headroom on bank facilities.
The last balance sheet looks OK to me, with about £20m NTAV. I wouldn’t want to see EPWN actually use anything like that £55m headroom, given the size of the business & the macro uncertainty.
Acquisitions - similar to LORD, EPWN is looking at making further acquisitions. Also it expects market share gains. Maybe this is an interesting sector to consolidate? That depends on what prices are paid.
Outlook - confident in medium & long term growth drivers. Nothing said about the short term though!
My opinion - this looks obviously good value, providing you don’t expect demand to fall off a cliff. So it depends very much on your macro view.
Low PER, big divi yield, and a decent StockRank are positives, providing we don’t end up in a recession, which of course could result in a dip in demand.
.
Jack's section
Renewi (LON:RWI)
Share price: 700p (+8.19%)
Shares in issue: 80,059,937
Market cap: £560.4m
Final results for the 12 months to 31 March 2022 and acquisition of Paro
Outlook for FY23 ahead of management’s previous expectations
This is a leading European waste-to-product business, recycling waste into specified industrial materials.
- Revenue +10% to €1,869m,
- Underlying EBIT1 +83% to €133.6m,
- Underlying EBIT1 up 77% compared with the pre-Covid FY20 reference period,
- Underlying EPS1 up 118% to 98 cents, basic EPS increased from 7 cents to 93 cents,
- Statutory profit of €75.4m (FY21: €5.5m#)
- Core net debt* reduced to €303m (FY21: €344m) and net debt to EBITDA reduced to 1.4x from 2.2x
Underlying EBIT has been helped by customer pricing measures, a favourable recyclate pricing trends, and cost inflation delivering a year-on-year benefit of €45m. It seems as though this recyclate environment is set to remain positive.
Although recyclate prices are expected to moderate in FY23, we expect prices to stabilise above pre-Covid levels for the medium term, reflecting the structural growth of the circular economy.
General demand is good, too. The group put 8.4m tonnes of materials back into reuse, up 5% on the prior year, with a recycling rate of over 67%, up 1.4pps.
The group’s Commercial Division (which represents over 70% of group revenues) increased underlying EBIT margins by 380bps to 10.0%. Revenue in this segment was up 10% to €1,360.5m and underlying EBIT rose 77% to €135.7m. Of the group’s smaller segments, Mineralz & Water revenue rose 6% to €193.9m and underlying EBIT increased from €0.3m to €5.8m, while Specialities revenue grew 16% to €350.1m and underlying EBIT improved 71% to €4.1m.
Progress has been made on key strategic initiatives to deliver €60m of additional EBIT in FY26, with €10m delivered in FY22:
- Over €100m of capital investment now committed to increasing the group’s recycling capacity at attractive rates of return,
- Mineralz & Water recovery underway, with further improvements to follow over the next 3 years,
- Renewi 2.0 programme on track to conclude next year and deliver full benefits from FY24.
Today brings a conditional agreement to acquire Paro too, an Amsterdam based commercial waste and recycling business, for an enterprise value of €67m.
Conclusion
FY23 is expected to be ahead of expectations, something that the company has set up in previous statements.
Renewi’s end markets continue to grow, driven by legislative changes. The commercial business has performed strongly despite Covid shutdowns and inflationary pressures - in fact this division, which is the bulk of the business as things stand ‘has been able to accelerate its journey towards double digit margins’.
I think the market here could be worth spending more time on. It seems to have some strong multi-year trends in its favour. Regulation has been an issue in the past though, at least partly responsible for a sharp fall in share price a few years back.

These issues have been resolved and the net impact is that today, Renewi trades on a single-digit forecast PER.
There are some provisions and contingent liabilities that introduce uncertainty, I’m just flagging that for now as another point to look more closely at. The group is changing its accounting here:
From 1 April 2022, the company will apply the Amendments to IAS 37, "Onerous contracts - costs of fulfilling a contract." Consequently, all costs required for the fulfilment of a contract should be included when assessing the onerous contract provision, including an allocation of divisional central overheads.
The retirement scheme is in surplus but the group has a negative net asset value and the current ratio is poor. So I think financial health is a concern, as flagged in the Z Score.

Renewi is generating lots of cash though - I make it roughly 75m of free cash flow after another 75m of capex, although this has been volatile in the past.

Things have clearly gone wrong here before, and the financial position is not the most robust, so it’s not a clean bill of health. Earnings and cash flow are dependent at least in part by recyclate pricing. But Renewi looks like it is positioned in a long term growth area with favourable pricing trends, so if it can put past issues to bed then I think there could be potential here.
Avon Protection (LON:AVON)
Share price: 1,023.10p (-14.53%)
Shares in issue: 30,449,775
Market cap: £311.5m
Perhaps Avon’s recovery can begin in earnest now? The group CEO is stepping down after a disastrous period for the share price.

Today, we are announcing that, after 5 years as CEO and 19 years with the company, Paul McDonald will be stepping down as CEO at the end of this financial year. Beyond this date, he has agreed to make himself available to support the transition to a new CEO.
But I’ve also been slightly concerned about what I perceive to be poor communications with the market, including quite a lot of spin. If I was a shareholder I would not feel well treated over the course of this unfortunate episode, and the departure of the CEO is not a cure-all.
The group says the first six months of the year have been ‘both an opportunity and a challenge’. An opportunity, insofar as recent global events have heightened focus on security, is hard to argue with. Avon itself comments:
Active engagement with European and North American customers following the start of hostilities in Ukraine… We expect to see a significant shift in demand in the short, medium and longer term
But there are company-specific challenges to deal with, and the results today don’t make for good reading.
- Orders received -33.8% to $113.6m,
- Closing order book -15.3% to $110.7m,
- Adjusted EBITDA -47.6% to $12.5m,
- Adjusted operating profit -72.6% to $5.1m,
- Adjusted profit before tax -80% to $3.6m,
- Adjusted earnings per share -80.6% to 9.1 cents,
- Net debt +338.8% to $56.6m.
Solid order intake of $113.6m in the first half, a reduction as expected against the strong prior year comparable, and with continued delays in U.S. DOD ordering
Given recent performance, I'm going to be skeptical in my interpretation and view that as a risk. There have been a couple of contract wins, but more important is the following:
Corrective actions underway to address identified operational challenges:
* Improved forward ordering to anticipate future demand, now possible in higher demand environment
* Implementation of the announced $15m overhead reduction programme on track and additional $6m reduction now planned
However, the group goes on to say:
A very strong macro demand environment drives medium-term confidence, but volatility of funding and timing of customer orders gives rise to risk to the H2 outlook on revenue mix.
This sounds like Avon is setting things up for a poor second half, and it adds that inflation will be another headwind. It does expect some sequential improvement on EBITDA margin though, from this period’s 10.5%, which has declined as a result of product mix shift and operational challenges, including supply chain issues.
So, while the general outlook might be favourable, the near-term outlook specific to Avon sounds notably less positive.
Leverage of 2.6x EBITDA (on a bank covenant basis) is under the 3.0x covenant but not by a lot. Avon expects leverage to reduce as profit recovers but, given the state of the covenant and the fact that net debt is up 338.5%, I question the prudence of an $18.5m share buyback and maintained dividend. Particularly given the H2 guidance.
Conclusion
It’s quite possible that recent events in Ukraine have fundamentally changed the medium term demand picture in Avon’s industry. But it’s a shame the company has managed to so comprehensively shoot itself in the foot months before this important shift.
Due to the company-specific concerns I’m going to pass but I see how a changing demand environment could help the company recover.
Following the events in Ukraine, there has been a significant increase in expression of interest in our products. We continue to work proactively and at pace with our customers to confirm orders and maximise the utilisation of our facilities.
On the other hand though, the fact that a military supplier is making a loss in this environment is notable. I’m skeptical of not just the original acquisition that caused the share price to crash here, but the ongoing capital allocation of the management team and I would want to see more proof of rehabilitation before considering an investment.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
Hi Jack, Real useful write up on LON:AVON. I too wonder about the share buy back given debt levels. Maybe it's a sign of confidence - but then again they were equally confident about their investment in the Body Armour Business.
Long term I am a big fan. Their main product is seeing a sustainable surge in demand , which may take sometime to turn cash but will come good provided they don't screw it up.
If I was a candidate for CEO I'd think its a good time to take over. I don't even think it needs someone that special.
Is Calnex Solutions (LON:CLX) not being covered by SCVR anymore?
Hi Flame007 - we normally cover an average of 5 companies' trading updates/results each day. So if there are more companies reporting, we can't cover everything. Yesterday there were 10 companies reporting, so we had to pick the ones that looked the most interesting, and moved share prices the most.
Calnex dropped 4% on publication of final results. I'm just looking at the highlights now, and the figures look good - v good gross and net profit margins.Net cash. EPS Fell though, even though profit rose - a much higher tax charge, and exceptionals last year but not this year, seem to be the culprit.
Overall, I quite like the look of Calnex. By all means post your thoughts on it here, and sorry we didn't get round to having a proper look at it.
FYI, here's (below) yesterday's list of companies that Jack & I decided to cover, and the ones we didn't get round to. As I say, we can't cover everything, and would need a team of maybe 4-5 people to cover everything!
Regards, Paul.
Re Parsley Box (LON:MEAL) , I think these director incentives are disgraceful. Since the IPO the shares have fallen by about 90%, so what are they being rewarded for? I hope a certain potty-mouthed financial journalist might have something to say about this.
Positive update from Frontier IP (LON:FIPP) as they announce that one of their portfolio companies, Cambridge Raman Imaging, has raised £1.1m in a new funding round at 4x the valuation of the last funding round in July 2020. I estimate that adds on around 2p to the NAV to bring it to 70p using the last price for listed holding Exscientia and means the company sits at a 5% discount to NAV despite numerous positive updates recently. Also positive to see Exscientia reversing some of the recent losses and is up 15% in the last week as it has been caught up in the global biotech selloff.
thanks for replies on £VTU. Query is really for my Dad who is 99 this year. His GP told him he was only dying slowly so he's optimistic he'll make the 2 year threshold so I suggested VTU but was worried if he makes the 2 years and then finds out they don't qualify which really would be a killer. PS He refuses to pay the £5 to check on Investors Champion
If Paul or Jack get time, I would value a viewpoint on Lords Trading (LON:LORD) results and progress announced today. I am 15% down on my buy price from earlier this year (that is not bad compared to some stocks I hold) but I like the potential for this 'buy and build' consolidator in a fragmented sector. Only a 4% bounce today despite strong results, including announcement of maiden dividend. All views appreciated.
Hi BritishExpat70,
Yes, I've been looking at Lords Trading (LON:LORD) this morning, the section is already up!
IMC webinar is at 1pm today, imminently, so I'll check that out too.
It looks quite good, and has gone on my watch list.
Regards, Paul.
Thanks Paul. Appreciated.
I too am scratching my head at the mixed messages coming out of £AVON. I keep looking at this one but have yet to overcome my many doubts.
Order book down (admittedly from an elevated prior year number so not as bad as it looks), but then later the talk about "elevated demand".
One thing to add to Paul's good write up above is that they have now paused the share buy-back:
Having executed the first half of the share buy-back, announced in January, the Board have decided to put the second half on hold to enable further organic investment to meet elevated demand levels and to ensure leverage stability
The less charitable may interpret "ensure leverage stability" as "we bought back our shares too early, and now we are getting too close to our covenants"?
The losses on the armour business (which will continue through H2) are more than eating up the profits from the much bigger continuing respiratory/helmet business which is probably why they remain subdued about the near term, which also highlights the margins in the ongoing business are quite slim. Which is perhaps what you get if you are supplying one dominant customer?
A new CEO will probably resort to the kitchen sink to try and set a low base from which to proceed. On the other hand once the discontinued armour losses roll off it could be a very sharp bounce back in earnings.
It's just a shame they split off the dairy business as we can't make jokes about spilt milk.
May I correct the above....it was Jack's good write-up, not Paul. Apologies
Parsley Box Parsley Box (LON:MEAL) I too take a dim view of director share options but I am wondering, when a business is foundering and issues options maybe we should see it as a not-very-descrete capital raising exercise; tapping up their leadership team for cash. Was their recent funds raising operation undersubscribed by any chance?
Gravy Train comments .
Well said Paul your comments are spot on regarding the self righteous boot filling mentality that pervades some boardrooms .
Guaranteed Nil cost options are bad, and arguably a bit of a tax dodge as if it’s not subject to NI income tax etc is sometimes just used to boost executive pay.
The only true value f significance is skin in the game directors buying with cold hard cash .
Everything else is just financial engineering and self enrichment.
I once had a great few hours with Sir Hugh Facey who build Gripple into one of Sheffield’s most anazing companies and his employee ownership scheme involved every single member of staff buying share with their own money .
He told me a story about the time he realised it was going to be a game changer .
After a particularly bad month of trading he as CEO and head of the company was heading to the toilet when he sad he followed in by both cleaners who both gave off to him about his underperformance and that he needed to book his ideas up .
At that point he knew it was going to be a success .
Skin in the game works .
As investors we should not stand by but give management both barrels .
I was at the Holders AGM recently a pretty small affair and I asked about zero cost options and that it is morally repugnant and asked the CEO and chairman directjy if they would ever do it , because if the did I considered it theft and I would rather just give them sone cash there and then.
Yesterday Driver (LON:DRV) announced a shake-up of its Middle East business involving moving certain parts to a third party. Mr. C flagged it up but there were no other comments here. Today Equity Development has issued a note describing the move as a "masterstroke" making me think there are more positives than I first thought. Worth reading if you are interested in this company: https://www.equitydevelopment....
Hi sharw,
Thanks for flagging. IIRC, I quite liked Driver when last looking at it, as a credible, cheap turnaround. So I'll have another look.
Regards, Paul.
Problem for the day...Would Vertu Motors (LON:VTU) qualify as a Inheritance Exempt Share if it is basically a property company with a sideline in selling cars?
Yes I’m pretty certain vertu motors is IHT qualifying you can check on investors champion they have a search tool.
hi colin1862 - re any potential IHT on Vertu Motors (LON:VTU) is only a problem if you're dead. I'd suggest you stay happy being alive and ignore it.
I'd suggest you stay happy being alive and ignore it
There are investors with problematic conditions who are very conscious of the need to get their portfolios in shape for the next generation - sometimes with great urgency. Your comment is very valid for the rest of the community but is it maybe a good idea to tone it down a bit out of consideration for the unfortunate few?
Vertu Motors (LON:VTU) Latest Research by Investors Champion suggests it is Qualiying for BPR so IHT exempt
Calnex Solutions (LON:CLX) (I hold) announces FY results today.
Calnex Solutions plc (AIM: CLX) provides test and measurement solutions for the global telecommunications sector and is pleased to announce its audited results for the 12 months ended 31 March 2022 ("FY22" or the "Year"). I cannot copy the sumary table into this post, but statutory measures look good:
Profit before tax +64%
Basic EPS (pence) +11%
Diluted EPS (pence) +20%
The adjusted figures look less good:
Adjusted profit before tax +18%
Adjusted basic EPS (pence) -11%
Adjusted diluted EPS (pence) -4%
I do not have the time or the skill to reconcile the statutory and adjusted results, but it is clear that by bothn measures EPS has grown much less than pre-tax profit. I would appreciate it if someone with more knowhow could assess the figures.
Richard
Hello Richard, no expert but I believe the significant differences with regards to their eps numbers is due to there being circa 14m and 9m more shares (post IPO) for basic and diluted share weightings respectively. Thus reducing the actual reported earnings per share/s.
Thanks, Dave. Re Calnex Solutions (LON:CLX) I don't think I would have picked that up. There remains a big gap between statutory pre-tax (+64%) and adjusted pre-tax (+18%) which I will try to unravel this evening.
Richard
Good update from Epwin (LON:EPWN) today:
"I am pleased to report a continued strong trading performance in the first four months of the year, with revenues to 30 April 2022 15% ahead of a strong comparative period in 2021. Demand remains robust, particularly from the key RMI market.
Having been involved in the restaurant trade my entire life, I was more than surprised at the level of service during a visit to Frankie & Benny's Lincoln recently. The food was probably on par with this type of chain restaurant, however the attentiveness of the staff, the professional way they handled my kids and the way they managed to process takeaway orders without impacting the ambiance of the restaurant impressed me and is obviously the result of extensive staff training. If this is replicated throughout all the brands, Restaurant (LON:RTN) should be in a stong position.
I had a similar experience recently and left the staff a 20% tip as a result. In my case, as well as the kids, it was my wife who is gluten & dairy free.
Good Morning Paul and Jack, nice to Forterra (LON:FORT) issuing a positive update, and reassuring to see much of its forward energy costs already fixed in advance. Even the delay to refurbishing the existing factory in Wilnecote seems to have a positive effect on the bottom line.
I'm beginning to wish I held more of this stock.
Re Forterra (LON:FORT) - AGM trading update today. Positive statement with volumes ahead of Mgt plan and 6% ahead of 2019 despite "brick selling price increases of 12% implemented from 1 April in addition to the 16% applied
in January." Benefits of a highly concentrated oligopolistic market structure - top 3 players have >80% prodn from memory.
Demand strong, UK brick capacity fully used and imports at a record level with a 19% share. Pressing ahead with big investments in new capacity (like Ibstock) that will reduce energy and increase product range.
Dividend of >5% looks secure plus a share in a business that is unlikely to go away. Good place to park cash for the less adventurous. (Disc I hold Ibstock which is similarly blessed)
Zipman - Forterra (LON:FORT) price increases at this regularity and size might then be a challenge for the house builders to absorb don't you think?
i remember hearing Phil Oakley discussing Forterra (LON:FORT) a few years back - i believe bricks represent low-mid single digit % of the overall build cost so price increases don't impact the housebuilders as much as you might expect
"price increases at this regularity (16% Jan 22, 12% April '22) might then be a challenge for the house builders to absorb don't you think"
The brick builders say bricks are only 2% of the total cost of building a house and house builder margins are huge since they are selling land they bought several years ago. As long as all the highly concentrated brick builders price up, then yes, I think they can!
Trinity Exploration and Production (LON:TRIN)
Good results for the full year with this oil producer.
Aiming to double production over the next few years with drills funded from existing funds. 6 drills per year are expected until 2028 is expected to produce a step change to its production. Looks to be an exciting few years to come for this company.
Cenkos have released a detailed report this morning with a target price of 360p. Current price is 126p.
On Beach group (LON:OTB) half year update sounds promising this morning, as it appears people aren't holding back from holidays this summer despite cost of living pressures: '...group sales returned to 2019 levels in mid-January and now at 22 May ‘22 summer sales were 22% ahead of pre-COVID levels'. There are a couple of other figures used in the report but I like that one because some of the others might be distorted by catch-up bookings post recent Omicron waves.
Remember that with Thomas Cook in its previous form knocked out the market, On Beach group (LON:OTB) should be able to pick up some of their old business (depending on how well the new Thomas Cook is performing) and it also sounds like On Beach group (LON:OTB) is benefiting from dealing with the more premium end of the market now noting that ‘early bookings for summer 2022 have been stronger into higher value, more premium hotels.’
It also notes people are booking later this year, partly driven by recent relaxation on Spanish COVID rules, so summer revenues may go even higher yet.
Fingers crossed travel doesn't shut down over monkeypox...
In the memo to staffers, (Snap) chief executive Evan Spiegel said that while the fundamentals of the business remained “strong”, the company faced “rising inflation and interest rates, supply chain shortages and labour disruptions, platform policy changes, the impact of the war in Ukraine, and more”.
Almost fell out of my chair laughing. Describing one's business operations as strong but then throwing every single external factor put there as reasons to blame for poor performance. Sounds like to me that management have never had a proper trading environment challenge to deal with so far in their careers , which is probably the case for almost all tech companies.
Good to see that some companies are still trading well. On Beach group (LON:OTB) and Topps Tiles (LON:TPT) and Harworth (LON:HWG) ony watchlist all releasing decent, positive trading updates today. Albeit, of course, with the usual cloudy outlook statements.
Good update this morning from Warehouse Reit (LON:WHR) who are now looking to move to the main markets from AIM. Results continue to be strong for now as they have been riding on the wave of online shopping. I continue to hold and have done well from this share over the last few years but am a little concerned when I read the likes of Amazon are looking to close 5-10% of their warehouse space.