Small Cap Value Report (Tue 24 Sept 2024) - STEM, CARD, FNX, YU

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
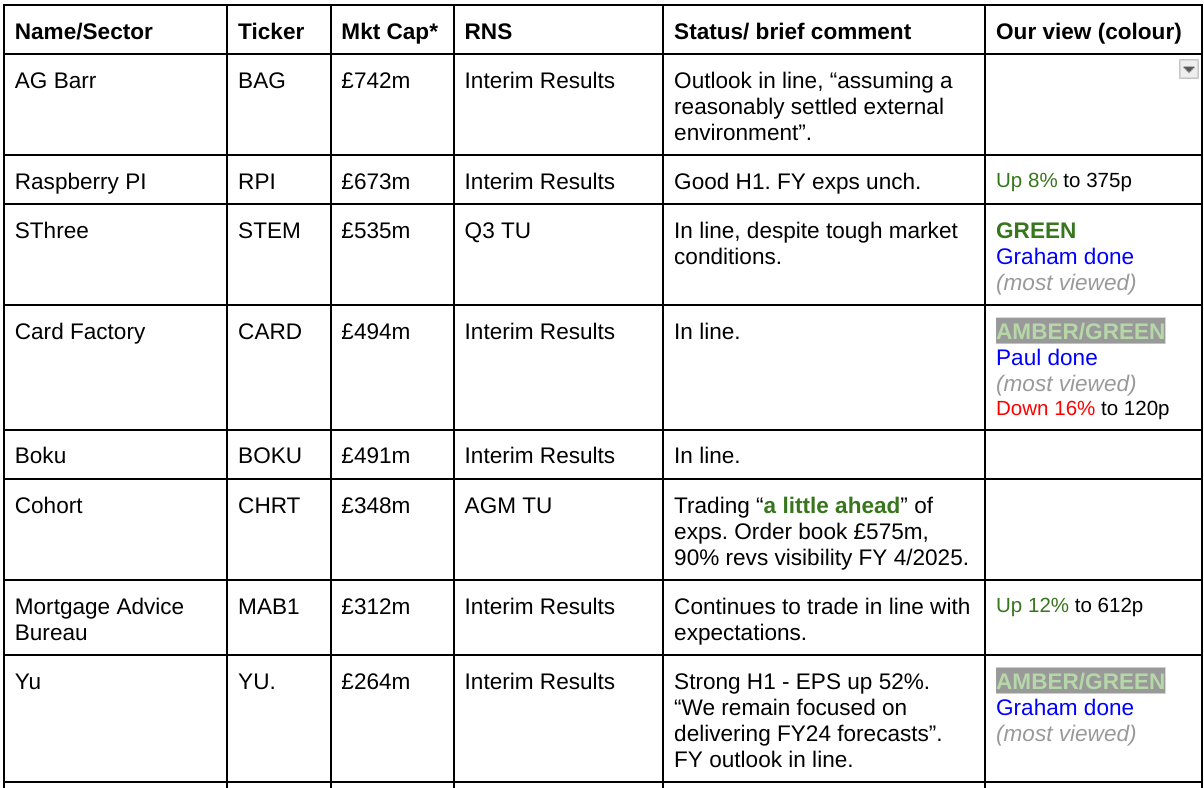
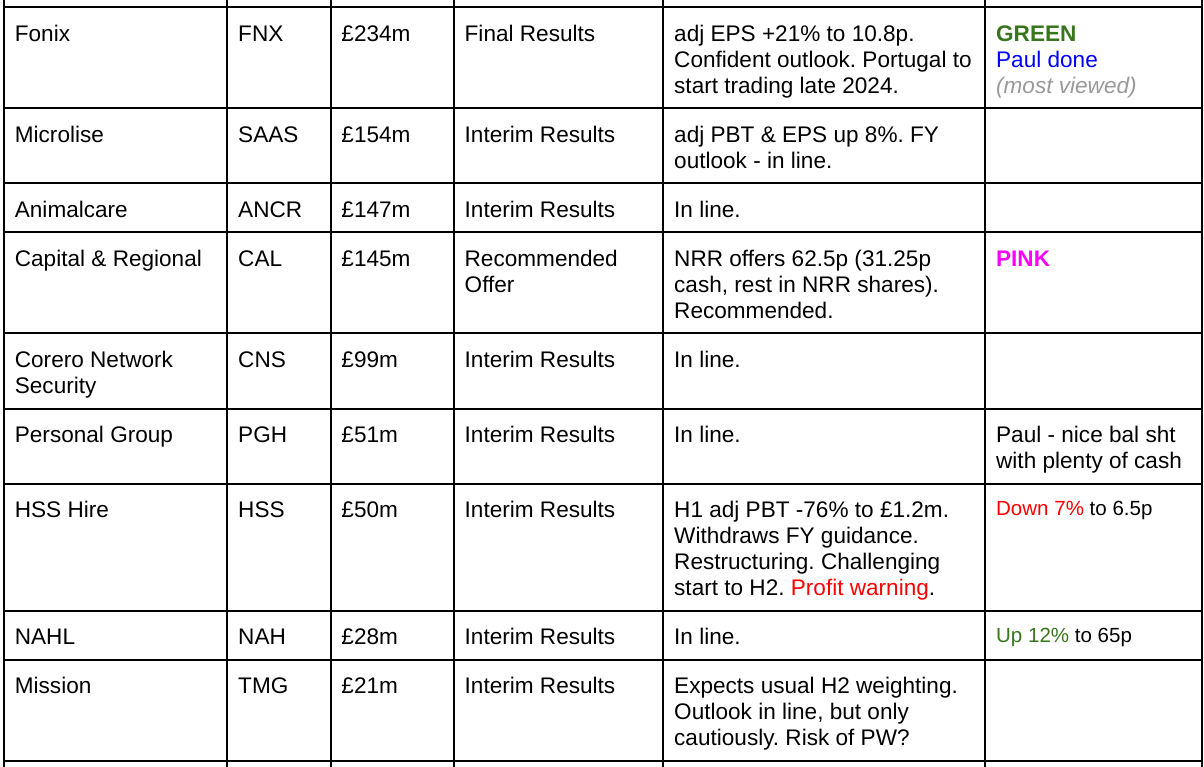
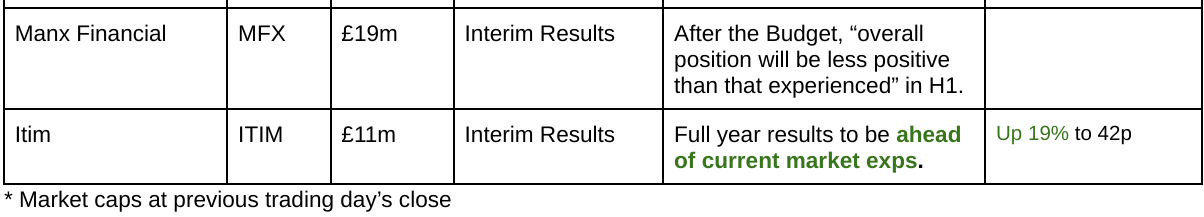
Summaries
SThree (LON:STEM) - down 2% to 388p (£524m) - Q3 Trading Update - Graham - GREEN
Tough market conditions for recruiters continue and STEM is not immune, posting an 8% reduction in net fees. The market may be a little disappointed that there has been no improvement yet, but I continue to rate this company highly both against its peers and as a standalone investment idea.
Card Factory (LON:CARD) - down 17% to 119p (£413m) - Interim Results - Paul - AMBER/GREEN
Weak H1 results, hit by higher wages costs, but it reiterates full year guidance, which will require a particularly strong H2 weighting, so some doubt has crept in. That said, the forward PER of c.8x allows room for some doubt. Good divis now, and the balance sheet has been sorted out without fresh equity being needed. Looks pretty good, but not as compelling risk:reward as it was earlier this year, so I moderate from green to AMBER/GREEN.
Fonix (LON:FNX) - down 1% to 235p (£232m) - FY 6/2024 Results - Paul - GREEN
Smashing numbers again from this quality company. Sticky clients, good cashflow, and a capital-light model means it pays out decent, and growing divis - quite unusual for a small tech company. I like the international growth continuing, with a fresh launch into Portugal imminent. Valuation looks reasonable, and broker forecasts set low, and likely to be beaten. A keen GREEN from me again!
Yu (LON:YU.). - up 3% to £15.90.50 (£267m) - Interim Results - Graham - AMBER/GREEN
I’ve upgraded my stance here as I find the organic growth in revenues (+60%) and profits (+122%) too good to ignore. The good news probably can’t last forever as margins are bound to fluctuate, but I have to sit up and take notice when a company posts numbers like this. The CEO (and largest shareholder) appears frustrated with the lack of share price momentum - and maybe he has a point?
Paul’s Section:
Fonix (LON:FNX)
Down 1% to 235p (£232m) - FY 6/2024 Results - Paul - GREEN
One of our favourite shares here at the SCVR. Fonix provides the IT/telecoms services for TV viewer voting, eg charity things like Children In Need, and eviction type reality TV shows. Also Eurovision for the first time in 2024.
It’s lucrative work, with very sticky clients who stay with Fonix because it always works, hence clients are not interested in taking the risk of switching supplier for their mission-critical revenues. I think that’s a decent moat.
My previous notes show we’ve been GREEN 3 times this year: 24/1/2024 - marginally ahead TU, 19/4/2024 Directors sell in secondary placing, and 22/7/2024 ahead exps TU.
The only question marks with FNX have been how to value the shares (they tend to be on a fairly punchy rating of 20-30x PER), and if the growth can continue.
As you can see below, +27% growth in adj PBT ticks the growth box! -
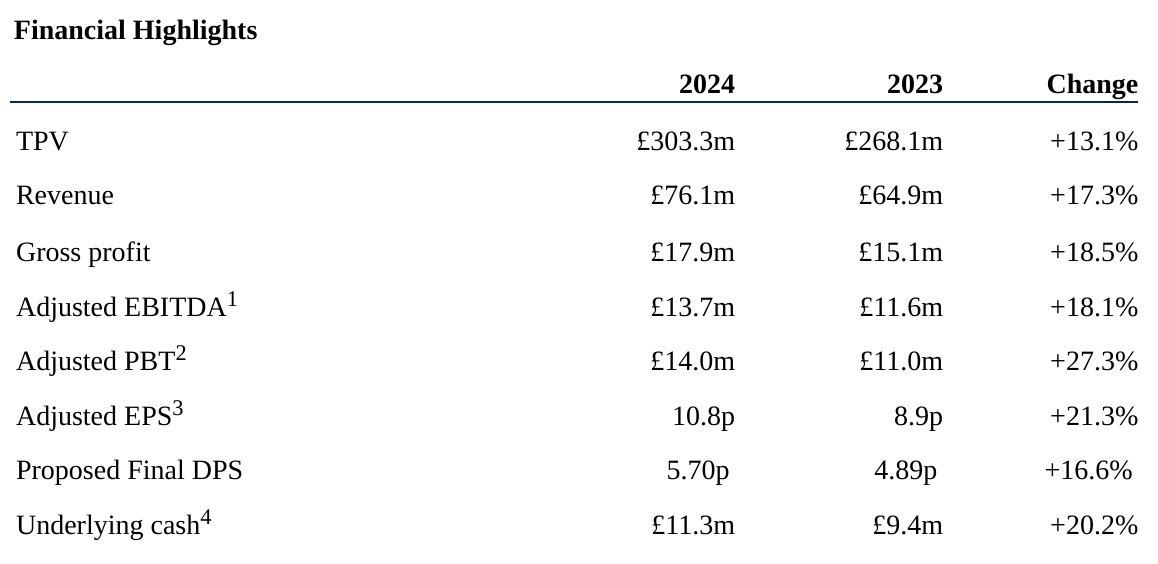
Adj EPS of 10.8p gives a PER of 21.8x, which I think is justified by the growth. That's likely to drop into the high teens by this time next year, from higher earnings.
Dividends - 2.6p interim already paid, plus 5.7p final = 8.3p total, a 3.5% growing) yield. Not bad. Note that 77% of earnings are paid out in divis, as this is a capital-light business model that doesn’t need cash for any other purposes, the ideal scenario for investors.
Note that higher interest received on cash balances boosted profit by about £0.8m vs LY (last year).
Outlook -
“The business maintains a robust pipeline of prospects going into the next financial year…”
“The Board remains confident in Fonix's growth potential for FY25 and beyond, supported by high levels of recurring revenue with a strong run-rate, an expanded commercial offering, and significant opportunities for further international expansion.”
It’s keeping things updated with new payment methods and features, eg -
“Significant investment in new product features in the Year, including live broadcaster voting, online payment portals, new payment integrations, new mobile network operator connections and advanced campaign scheduling.”
International - at present Fonix is mainly UK, but has also done well in the smaller Ireland market. This is exciting - Portugal is the next market it’s hoping to crack -
"We have made significant strides in our growth strategy this year, expanding our commercial offering and capitalising on a client-driven opportunity to build a substantial sales pipeline in a third geographical market, together underpinning our growth expectations for the year ahead.
In the next 12 months, we plan to further enhance our products, building on the strong progress achieved in FY24. Our serviceable market is expanding significantly with new direct network connectivity in Portugal, and we will explore additional direct connectivity opportunities in other territories in FY25 as we determine the most effective routes to market.
With a fair wind, we hope to begin transacting in Portugal before the Christmas trading period commences. By achieving this and continuing to nurture growth from our existing clients, we believe we have a strong opportunity to further build on our outstanding record since IPO."
Forecasts from Cavendish (many thanks) are modestly set, so FNX looks well set up to publish “ahead of expectations” updates as FY 6/2025 progresses, so very little risk of a profit warning, given the sticky repeating clients.
Balance sheet - is quite modest, as there’s not much in fixed assets, and no inventories. NTAV is c.£9m, which is enough.
Net cash of £26.5m is not quite as good as it looks, as some of that cash is passing through. Net current assets are £9.2m, which I would use as effectively the company’s own surplus cash. I imagine cash balances would be quite erratic, depending on when large amounts come in suddenly from a popular show, but then large remittances have to be paid over to the TV companies some time later. Anyway, it’s all fine, so nothing to worry about.
Finance income of £1,127k on the P&L suggests to me that Fonix probably sits on an average cash balance of c.£28m, assuming it earns c.4% on cash. That’s very close to the year end £26.5m cash, giving me comfort that the cash is real, and not a spike up for window-dressing purposes.
Paul’s opinion - this is a lovely business, with sticky revenues generating good margins and plenty of free cashflow. It hasn’t put a foot wrong since listing. I’m impressed at the continuing growth, and entering a new market, Portugal, sounds intriguing. It would be interesting to hear from management as to why they’re going into Portugal? Presumably each country has its own incumbent competition? Maybe FNX can win business by offering better features?
This strikes me as the type of share that you could just buy and forget, enjoying a steady stream of growing divis, and in say 5 years’ time the shares would probably be usefully higher. Who knows though, I wonder what direction technology might take this in future? Are there any potential risks on the horizon? The main short term risk would be a catastrophic meltdown in its IT, say if hackers went for it & got through, because it only has a short window of time to take in large amounts of viewer calls.
It has to be GREEN again.
If brokers would float more things like Fonix, then AIM would be a much healthier market!
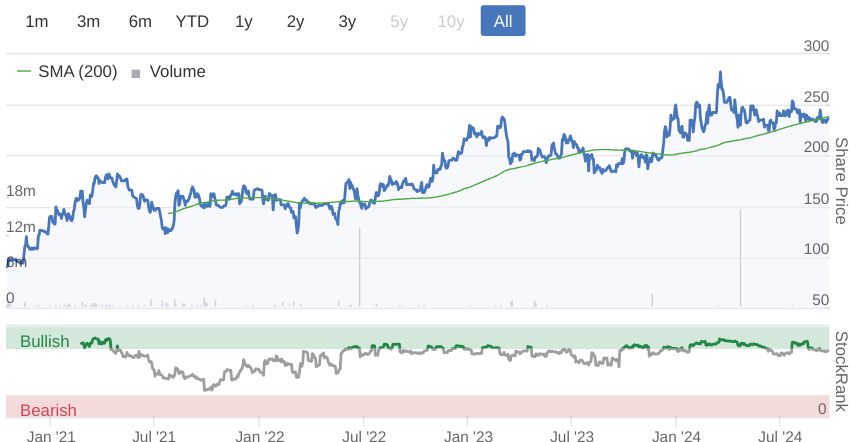
Card Factory (LON:CARD)
Down 17% to 119p (£413m) - Interim Results - Paul - AMBER/GREEN
cardfactory, the UK's leading specialist retailer of greeting cards, gifts and celebration essentials, announces its interim results for the six months ended 31 July 2024 ('HY25').
Quite a sharp correction this morning, with the recent gains being given back. That’s quite surprising given that it reiterates FY Jan 2025 expectations in the headline -
“Resilient revenue performance with further strategic progress achieved including successful partnerships expansion. Full year expectations unchanged.”
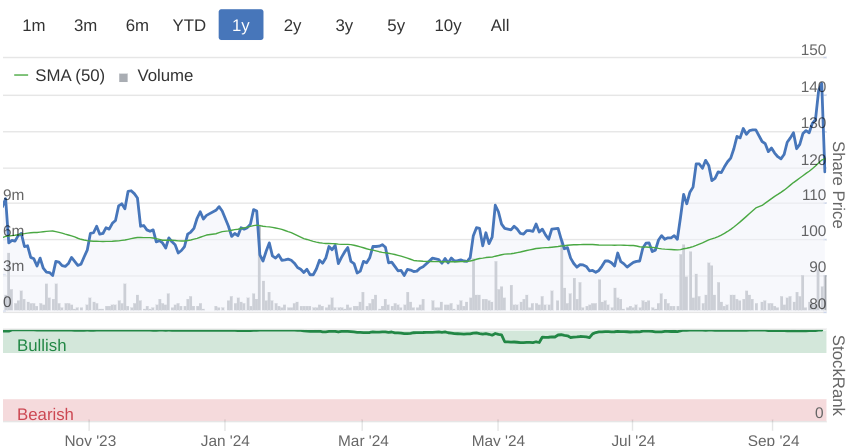
However, once I looked at the H1 highlights table, I can see why the shares have fallen today - due to poor H1 profits, being well down on H1 LY -
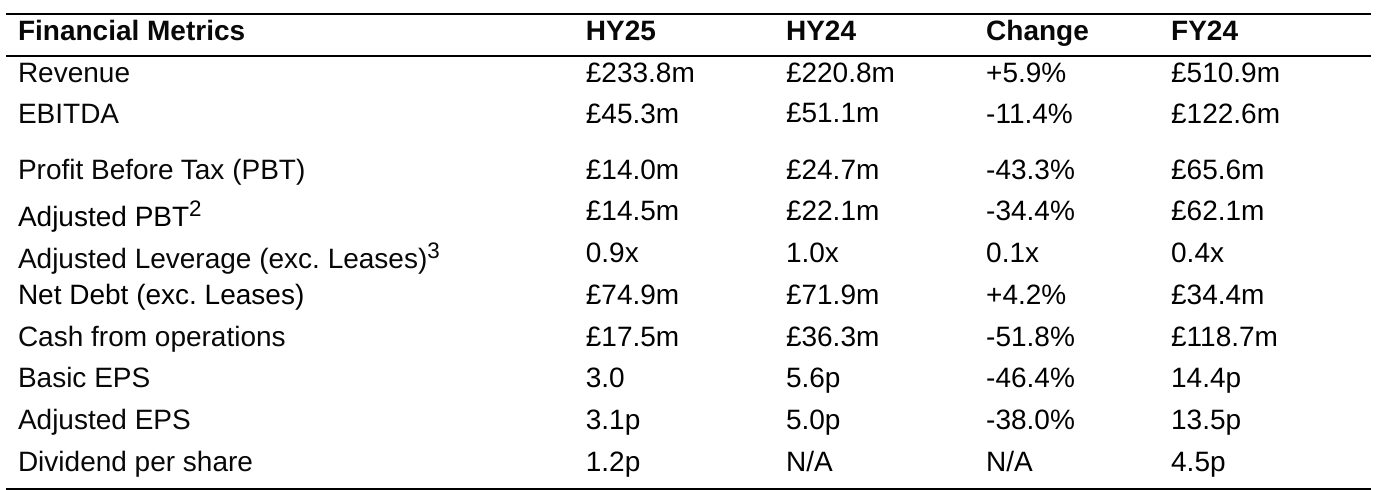
This is the explanation for profit being down 34% -
“HY25 Adjusted PBT was down £7.6 million to £14.5 million, reflecting substantial increases in National Living Wage, plus freight inflation and phasing of strategic investments. As previously guided, the benefit of our strategic investments and robust programme of productivity measures and efficiency savings in FY25 are weighted to the second half of the year and we have already seen these positively impact the cost base.”
Outlook comments - start off with this rather ambiguous point -
“Trading since the period end has been in line with the first half…”
Is that good or bad? The commentary talks as if H1 was good, but it wasn’t - profit was sharply down.
Cost pressures sound like they’re still an issue -
“Whilst macro-inflationary pressures have started to ease in the second half, we continue to manage specific retail impacts.”
It does provide good reasons for expecting an improvement in H2 -
“There are several factors that are supporting our profit margin performance going into the second half of the year. Approximately half of the margin growth in the second half will be driven by the seasonality of sales. Our robust programme of productivity and efficiency savings will also make a material contribution. In addition, we expect to benefit from margin-enhancing range development and prudent management of operating costs. “
Unchanged full year expectations, but obviously with a particularly heavy H2 weighting, and the risk that brings with it -
“Albeit we are yet to trade through the key Christmas period, the strong topline performance in the first half, combined with our robust actions to mitigate inflationary pressures, means that our expectations for the full year are unchanged.”
Broker forecasts have been edging up, which sits oddly with the weak H1 profit performance -
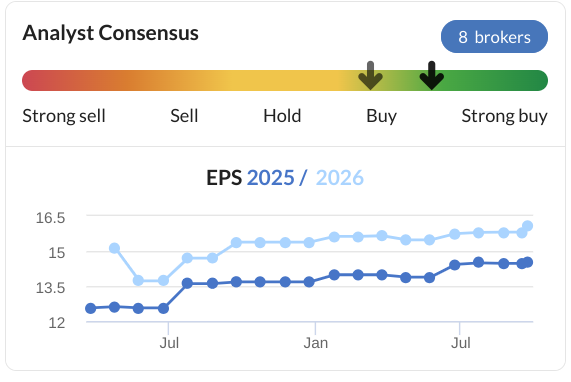
H1 actual adj EPS is 3.1p (down from 5.0p in H1 LY).
H2 LY was 8.5p (calculated as 13.5p adj EPS for FY 1/2024, less 5.0p H1)
The StockReport has 14.5p adj EPS forecast for FY 1/2025, so this implies a substantial increase to 11.4p (up 34% on H2 LY) in H2 performance. It’s quite unusual to see such a big improvement in H2 performance after H1 was sharply down. Hence I think there has to be an element of doubt about how realistic the 14.5p EPS forecast is? That could be what motivated sellers early today perhaps?
As I have some doubt over the 14.5p forecast, I’d be happier with a lower PER. Let’s say 8x, to allow wiggle room if H2 is not the barnstormer that is forecast, gives me a 116p valuation - pretty much bang on what the current price actually is, after a sharp fall today.
I see the word “resilient” is used by management to describe performance. I had to chuckle at the excellent Small Caps Live blog, which humorously (but actually quite accurately) says whenever they see the word “resilient”, they know things are really bad! Management have slipped in one instance of the deliberately vague phrase “profitable growth” too.
For balance though, there’s plenty of positive-sounding stuff in the commentary too.
Balance sheet - has been nicely repaired, from retained profits, with negligible dilution over the last 6 years. That’s a considerable achievement, as remember this company teetered on the edge of going bust since it went into the pandemic with excessive bank borrowings.
NAV is £312m, of which £332m is intangible assets (goodwill mainly), so NTAV is still negative, but only £(20)m, which is not a worry at all, given that inventories and receivables are fairly low, and property is mostly leased (there is £17m in freehold property too), so it’s an asset-light business model that generates plenty of cash, so it can comfortably carry some debt. I don’t have any remaining concerns at all about the balance sheet, as mentioned before, it’s fine now.
Let’s hope management learn from the mistakes of the past, and don’t gear it up again at the top of the cycle.
Going concern is clean, and with bank facilities renewed, and covenants comfortably complied with, there’s nothing to worry about.
Cashflow looks poor in H1, but given the H2 seasonality, I think we need to see the full year numbers before making a judgement.
Dividends are now being paid again. The StockReport shows broker consensus divis of 5.22p this year, and 5.83p next year, so on today’s reduced share price (down 15% at 122p at 09:46) gives a healthy (well-covered almost 3x) between 4.3% and 4.8%. Given that the divis are in a rising trend, then this looks attractive to me.
Paul’s opinion - I can see why some holders might see the H1 results as disappointing. It’s now relying on a particularly strong H2 weighting to meet forecasts, which does make me a little uneasy. That said, the valuation now reflects this risk I think.
It’s a pretty good business, trading on an undemanding multiple of about 8x, paying good divis, and with its financial risk now resolved.
I was green twice earlier this year, at 100p and 107p. We’re now at 122p, and H1 results have underwhelmed, putting more pressure on the H2 upturn to be particularly strong. Therefore I think risk:reward is not as good as it was when Teleios selling was suppressing the price (since gone).
Overall then, I’ll moderate to AMBER/GREEN today.
Graham’s Section:
SThree (LON:STEM)
Down 2% to 388p (£524m) - Q3 Trading Update - Graham - GREEN
We have an in line Q3 update from my favourite recruitment stock.
However, expectations were modest and the growth numbers are as follows:
Net fees down 7%.
Contractor order book down 6%.
Net cash fell to £45m (a year ago: £83m), “reflective of the timing of certain client payments, with net cash expected to return towards normalised levels over the coming months”.
At first glance, that might seem to be an alarming fall in the cash balance. But in my management Q&A with the company, I was told that SThree needs about £60m to fund “business as usual” along with planned contractor growth. In other words, swings in the cash balance are expected - let’s hope that it swings back towards the previous, higher level by the end of the year.
CEO comment:
Despite the challenging conditions in the market, which have extended beyond our industry's expectations, our strategic focus on Contract continues to underpin the Group's competitive positioning. The Contract order book, down 6%, reflects protracted soft new placement activity partially offset by ongoing strong Contract extensions.
The “Technology Improvement Programme” remains on track - one other interesting thing I learned from my Q&A was that SThree might be more open to doing acquisitions, when this is complete. The idea is that acquired companies would run more efficiently when they can be plugged into SThree’s new technological framework.
Revenue breakdown: geographically all regions are down except for the smallest one, “Middle East & Asia”.
As usual, Life Sciences had the sharpest fall, down 14% year-on-year as the post-Covid slump continues for now. The larger categories, Engineering and Technology, were down 7% each.
Graham’s view
The ongoing decline in fees is a disappointment but I think there are two points to bear in mind against that.
Firstly, this is an industry-wide issue and other recruiters are doing worse than SThree. For one example, Hays (LON:HAS) recently reported net fees down 14% in the twelve months to June 2024.
Secondly, despite the pressure on fees, SThree has remained highly profitable and protected its bottom line (so far). See our coverage of the interim results in July.
Therefore, I’m going to leave my positive stance on this one unchanged. I appreciate many things about it: the focus on Contract recruitment in scientific sectors, its technological efficiency, and its geographic diversification.
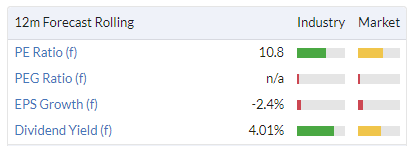
It continues to trade at attractive earnings multiples, in my view, making no adjustment for the cash balance:
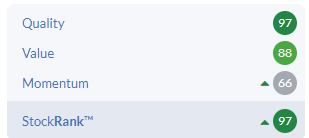
The StockRanks love it, and it passes seven bullish stock screens.
None of this guarantees success, of course. As someone who likes the business, I just like to see when the stock screens agree with me!
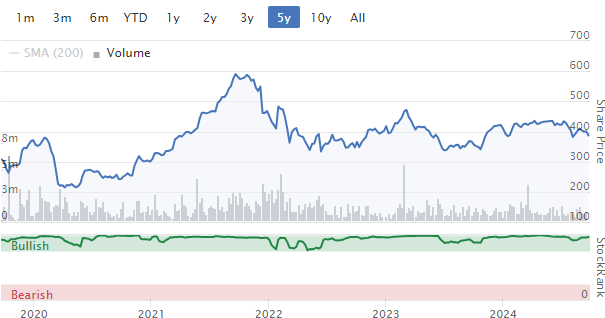
Share price performance has been flat in recent years - it’s a slow burner, but a company I believe in.
Yu (LON:YU.).
Up 3% to £15.90.50 (£267m) - Interim Results - Graham - AMBER/GREEN
Yü Group (AIM: YU.), the independent supplier of gas and electricity, meter asset owner, and installer of smart meters to the UK corporate sector, is pleased to announce its unaudited half-year results for the six months to 30 June 2024.
These are fabulous numbers, which I believe are in line with expectations.
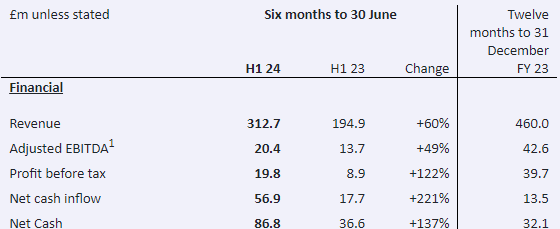
The growth is all organic. There was a remarkable 110% growth in the volume of energy supplied, leading to the following financial results.
Lower down, in their operational KPIs, they include their Trustpilot (LON:TRST) score! I think this is the first time I’ve ever seen a company do this. Their score is up from 3.5 to 4.3 (out of 5) over 12 months. Cynics may wonder if this coincides with Yu upgrading their Trustpilot subscription!
Getting back to Yu’s tangible achievements. They have seen an 80% increase in meter points supplied, and a 125% increase in smart meter installations.
Net cash, as shown in the table above, has more than doubled to £87m. The company has also cancelled its share premium account (an accounting item, on the balance sheet). This gives them the flexibility to return more cash to shareholders, if they choose to.
Outlook: EPS will increase in H2 vs H1, in line with expectations (adj. EPS in H1 was 88p).
CEO comment: starts out positively.
Yü Smart continues to go from strength to strength. Like all new startups, we've experienced growing pains and building teams who share our values and habits has required management attention. However, I'm satisfied good progress has been made and we have positioned ourselves for significant meter installation growth. Smart meter installations are up by 125% and engineering headcount is up 300%.
It ends with some more critical comments which I guess may reflect frustration with the company’s share price. Note that the CEO is the majority shareholder here:
The lack of Institutional engagement has been disappointing, despite management delivering colossal value year on year. Many AIM companies are questioning the market's future and the desirability of remaining listed. This has been reflected in the reduction of quoted companies. The AIM market's future is delicately balanced and won't be helped if the current government further punishes and disincentivises entrepreneurial high growth companies. This lack of recognition is frustrating; however, we remain focussed on delivering FY24 forecasts and positioning the Group for another record-breaking performance in 2025.
I’m completely speculating here but one interpretation is that he may have wished to sell a portion of his holdings, and expected that he would be able to do so at a higher share price.
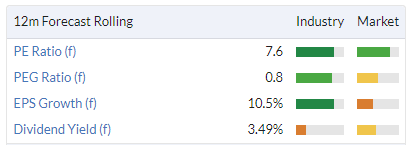
The value metrics are indeed on the cheaper end of the spectrum:
Strategy - a five year agreement with Shell is underpinning Yu’s long-term supply. Market share has grown from 1.4% to 1.8% and organic growth remains the focus.
Graham’s view
I’m intrigued by the statement that mild Spring temperatures, and lower commodity prices, held back these results. YU could have done even better than this!
Roland was neutral on this in July when he covered the H1 trading update.
The share price is a touch lower than it was then, and I’m tempted to give the stance an upgrade to AMBER/GREEN.
It comes down to your view on the sustainability of profit margins - when all is said and done, YU is a supplier of commodities to extraordinarily price-conscious customers (small and medium sized business).
We’ve also seen YU struggle in the past, as it did from 2018 to 2020, partly due to accounting problems.
It’s a much bigger business now, however. With scale comes certain advantages and the tie-up with Shell could be an example of this. Perhaps it is now a safer investment proposition, having reached this size? Revenues are forecast at £668m this year, versus only £279m in 2022 (source: SP Angel).
This may be generous but I’ll tentatively give this an AMBER/GREEN. When a company posts organic growth like this, it has to be worth looking at in closer detail. Like my co-writers, I suspect that current profit margins may be unsustainable - but if its customer numbers keep growing quickly, maybe that isn’t the most important thing?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

137 comments
Somebody else, respected, is flagging Card Factory (LON:CARD) so when drops like a 'sack of potatoes' then 'hello' lets have a look. Chart says just over-exuberance after a nice rise and reverting to mean. Sorry changing my moniker to 'tea leaves'. Don't hate.
It's broken out of a range on the weekly. large spikes (doji candles) today so lots of bulls and bears in battle, and a draw. Now fair value and should settle down and with a SR99 and all four green then a good punt for those that like retail.
At 111p this seems a good place to start the journey if you like the sector.
I think that stockopedia is really superb. I stopped subscribing for a year, then missed it so much I resubscribed a few months ago and am really glad I did.
Can any subscribers recommend any of the other additional sources of analysis and share information ?
I used to subscribe to Investors Chronicle, but there appeared to be things going on behind the scenes and there was a big turnover in their journalists ? Didn't feel a steady ship or with much credible and consistently winning advice. Has it got any better ?
And does subscribing to Adfvn give any benefits ? I can get the childish bickering for free but is there any real insight there that is worth paying for ?
Would appreciate any advice out there on these two plus others I may not have come across, many thanks
Hi Lockinver, Some good sites are:
(Free) InvestorMeetsCompany where you can see videos of CEOs / CFOs of companies you are interested in.
(About £10 per month)Research Tree is quite good if you want broker reports etc.
(About £25 per month): I use Share Pad for the RNS news and it has decent charting and financial info. Some good screeners.
(About £20 per month): Trading View, I think it’s better than. Share Pad.
Also use some for USA.
Obviously Stockopedia is the best one……
Cheers,
Colin
Thank you so much Mr Moon , very much appreciated
TradingView is a chartist (tea leaf) tool and down to 15 minute charts.
City Index uses TV for their spread betting charts which I find essential if that is of interest.
If into US shares then IBKR are as liquid as water (small bets) and their mobile offering is good, but need a smart brain for their web version.
Totally agree i was just thinking the same.Cheers Paul, Graham, Roland, the rest of the team and the big bosses for all your hard work and output.My investing has definitely improved and i enjoy the challenge and hobby much more now, even though i don't always follow what i should!
The scvr and other interactive content really brings the screens to life for someone like me who isn't the most bookish academic and methodical.If you're interested in the us market too, i like seeking alpha as they have a variety of subscirber analysts too posting who will run you through their ideas, methodology behind them and you can take what you want from each one like here, both bullish and bearish. (and other subscribers can post comments and questions and interact like me on each analyst's post).That's the main reason i like it as well as Stockopedia.
I think Stockopedia is great too. The main complementary resource I subscribe to is Research Tree. There are two other free resources I use extensively - Investor Meet Company and https://www.theaic.co.uk/ for investment trusts. Hope that helps!
Many thanks BL !
IC went 'woke' so 'broke' imo along with there masters the FT.
If into the yanks (silly not to) and Seeking Alpha is very informative.
FT may now have 'woken up' so may dip back in (hope lives eternal). We need the Macro, for the Micro.
Have I missed the memo? 1Spatial (LON:SPA) seems to have gone down relentlessly for several months, with the collapse accelerating since August. I can see no reason for this, although as a microcap not much reason is required. It is highly rated but appears to deserve it on performance thus far. Maybe it is caught up in profit taking before the CGT change, do any others here have thoughts or, better still, actual news?
Hi Aislabie
Following the excitement of 1Streetworks in March, the was a steep rise in share price for 1Spatial (LON:SPA) . Since there has barely been any contract news. The share price became highly rated, maybe unjustifiably?
Lots of budget fear about BPR for AIM shares and CGT.
Not a great mix.
Yup, also got some extra juice from the IQGeo acquisition which has now fizzled.
Mortgage Advice Bureau (Holdings) (LON:MAB1) LSL Property Services (LON:LSL)
Mortgage lending stats for MAB and LSL below for any interested.
I don't have any actual insight to provide, though I find the comparison interesting.
Treatt (LON:TET) ( I hold).
Personally I find the whole psychology of Directors share dealings fascinating and have learnt to closely follow them.
It was interesting to see that it was announced today that the new CEO at Treatt (joined June this year I believe) has just made an initial purchase of £10k worth of shares.
On the one hand its a start and nobody throws money away , but its not a huge display of confidence in the business’ future after he has done his first one hundred days imo. It equates to about 10 days salary.
Should have learned my own lesson from this same company when the previous FD unexpectedly (imo) announced in Dec 2021 that he would be retiring after nearly 20 years with the business, part way through a “transformational” factory relocation and business reset. And promptly sold the vast majority of his shareholding worth several million. Well done to him though - absolutely nothing wrong in doing that from his point of view, especially after all that service.
Shares are down 50% in the last 3 years ( 20% down this year). Given there has been no trading news flow from the company since mid May (understandable I guess whilst the new CEO gets his feet under the table) I just found todays announcement a little underwhelming.
Thank you so much for your replies re Treatt (LON:TET)
The more I think about it, the more I think this is a pixx take by the ceo and the board
If the bloke really thought the prospects looked mega, he would have gone all in and invested a six figure number minimum . After spending 4 months looking intensively at the business. This guy is no mug, very good cv for this business.
And yet he has done his dd on the job and , having done that is only prepared to risk £10k of his own money on it.
Wow !
Time to sell I think
Nexus Infrastructure (LON:NEXS), I hold.
The price was boosted back in May when Peter Gyllenhammar took a ~5% stake, but has since fallen back slightly. This week has seen a series of announcements, resulting in that stake now being just shy of 28%.
I hold with renewed interest... could a bid be coming?
Mortgage Advice Bureau (Holdings) (LON:MAB1) looking to pimp their numbers by not fully expensing system development in future. [I hold]
Technology, Automation and AI
Whilst others move away from in-house solutions, technology remains central to our strategy and our investment in our MIDAS Platform, our proprietary technology platform, will continue at the levels required to ensure we are always in the strongest possible position to optimise operational efficiency and drive revenue growth from new lead flow, lead nurture, customer retention, adviser productivity and customer lifetime value.
Our strategy is to continue developing our system, to provide a best-in-class experience for our firms and improve the customer journey. To this end, management is currently reviewing whether the historic accounting policy to fully expense these costs appropriately reflects the expected future economic benefit associated with the ongoing investment.
Noticed that Kitwave (LON:KITW) fallen quite sharply last few days - not aware of anything to cause this, and last trading update looked more positive than earlier in the year.
Selling ahead of the budget with potential CGT, IHT and AIM reliefs getting hit? I have started to cash up quite a bit now.
Will also take 25% tax free cash from SIPP before that gets capped to a much smaller amount (£100k max mooted).
You have to make your own choice but when pension changes have happended in the past there has always been protection regimes put in place to protect anyone affected at the point of change.
Given their lack of protection for pensioners since coming into power, it seems unlikely that they would start now ...
This is a different thing from the pensioner issue though Cancun, whenever changes have been made to private/company pensions the last 15 years plus ,protection regimes have been put in place every time. Its normally people over a set monetary limit protection applies to if your below the threshold you will be the one's caught in the new rules.
I hope that you're reading the room correctly Phoenix ( and you're usually highly perceptive ), but I haven't seen much evidence of pro growth or protective policies so far...
I totally agree re the anti growth part of things but I do think we are generally in check mate whoever is in charge, the £2.7 tillion national debt is now costing tad under £100 billion a year in interest costs alone.
More and more of the UK population don't want to work any more hence wage inflation still north of 5% per annum rolling which isn't great.
We have an ageing population, most of the boomers are now retiring and will stop paying in and add to the need to pay more monies out in state pensions and NHS costs.
We are all living longer but generally are not getting healthier again putting more pressure on the NHS from time and costs point of view.
The benefits bill is totally out of control, the thing is 99.9% of the population don't realise quite how bad things are financially from UK plc's point of view re countries debt, Europe is in the same trap, US also but they can probably keep going longer as worlds reserve currency.
When SKY & BBC drill down on the budget in 4 weeks they never ever cover the £2.7 trillion issue which is the elephant in the room I do wonder sometimes if word comes down from above not to highlight it.
Anyway my friend after writing all that i'm feeling depressed , hopefully I will be proved wrong and Reeves will manage to get the growth all politicians want but none seem able to deliver.
I'm always bullish stocks to a fault unfortunately, but I genuinely think that this economy is like a super tanker... thinking back to Greenspan in the 90's, when he speculated that the US economy was so strong, that at that current pace of debt repayment, there would be a total elimination of US debt :)....
If we could get some less anaemic growth, combined with the consequently better tax receipts, then with the help of minor inflation , the debt mountain could be reduced in real terms ...
But, I'm always too bullish :)
Bouden54- just announced fund raising for an acquisition. News leaks. which affect share prices really should. be able to be stopped in this day and age- an institution no doubt selling to buy back in the placing.
Just spotted that Kitwave (LON:KITW) have announced a placing to raise an additional £31m at a small discount to the closing price: https://www.stockopedia.com/sh... I just sold out today, to take up a position in Warpaint London (LON:W7L) instead, as I think the fundamentals are better and I think Warpaint London (LON:W7L) also is set up for bigger / quicker growth than Kitwave (LON:KITW) . I still think Kitwave (LON:KITW) is a good company, but I'm a bit unsettled with a fundraise at cost of dilution to complete an acquisition
Kitwave (LON:KITW) are and always have been a Buy and Build business so it's always likely that new capital will be wanted, But I'm not convinced by the figures for this acquisition https://www.londonstockexchang... .
Seems an expensive buy to me. The business being acquired, Creed, is family-owned, started in 1972, and it's tempting to assume the sellers are cashing in pre CGT increase as already suggested. But why is Kitwave paying so much? Are there any competing buyers?Is anyone else buying local and regional foodservice distributors in the current climate?
£31m placing and just £0.5m for retail investors on Primary Bid. I used to hold Kitwave and did quite well with it (I bought after the founder retired when I thought the shares had been hammered excessively). I would buy again at 250p, but not at the 305p placing.
Agree the acquisition looks a to be on a similar multiple to Kitwave itself so not sure it's worth diluting shareholders and racking up £30m additional debt for this. Huge amount of director selling too which at the very least has to be an amber flag.
Kitwave (LON:KITW)
An 8% drop over 4 days and then a placing - seriously!
The sooner we adopt the Australian system the better. Does anyone actually believe the "City" did not know about this and was selling knowing they could replace at a cheaper price. It stinks. There are no Chinese walls.
Institutional placing £30.5 m - for the great unwashed £0.5m - reminding us all once again that nobody can be trusted look after their own finances and needs to pay a fee to the great and good for advice.
London is dying, and its happening due to its own actions.
Apologies but this happens continually and really p****s me off.
Excellent write up on CARD, thanks guys
I used to buy greeting cards at Sainsburys paying around £2 to £3 per card. Then came the pandemic and switched to Moonpig again paying around the same until I discovered Card Factory. Couldn’t believe how cheap the cards were for the quality. Same or better cards at 79p 99p and 129p so bought shares in Card. Submitted a couple of questions for the webinar today but they were not answered. First was on pricing and asking why they could not increase prices by 10per cent each year for the next 2 years as they will still probably be the cheapest in the market. Although this was not answered I was pleased that a number of the analyst questions were on pricing so maybe they also feel there is room to increase prices.
The second question was on their online. I have tried to use it instead of Moonpig when you want to send a card quickly or send it abroad where it will involve a trip to the post office to get the postage correct. Card don’t do fulfillment and I can’t see how they can compete with Moonpig if they don’t. With Card you either pick up the cards in store or they post it to you. I can’t see how they can compete with Moonpig if they don’t do fulillment. Maybe they don’t want to or need to compete with Moonpig at this stage as they are looking to expand partnerships and gifting but it would have been nice to know.
They got a lot of catching up to do to hit full year targets but sounded pretty confident. I wonder if the reason for this is they know they can raise prices before the busy Christmas/New year period. Would be interested to hear what others think.
I really dont know about this
I get your investment theory
Its not for me though, trying to save 50p or a pound when buying cards for your nearest and dearest - but each to their own. They know where they come from !
I really love ideas to slash your own spending . Just me but this one goes too far .
But good luck to you TC, look after the pennies and the pounds look after themselves
You're right Lochinver , that works for you... but as you allude, not everyone buying cards has the income of a Stockopedia subscriber... and not everyone that one buys cards for are ' nearest and dearest '...
Great points re price they are miles cheaper than the competitors. Room to bring back their margin and possible on line business. They haven’t changed their guidance so management must be confident to land the year.
With regard to MPAC (LON:MPAC) , does anyone know who or what James G Laverdiere is? They now own nearly 5% of the company and did not previously have a notifiable position. RNS from this morning.
I googled but nothing obvious came up.
I hold and it seems positive to me that some would take such a significant position.
Just answered my own question, he was the owner of BCA, which mpac have just bought, partly with shares. So nothing to see here!
Card Factory (LON:CARD) a few blushes and explainers needed in UBS offices today. Friday sees an upgrade to "buy" with a target of 180p. A few days later a 20% fall on lower profits. Seems overdone but the schadenfreude is good value ( I hold).
Anyone invested in BOKU might want to check out the Edison forecasts... in their updated forecasts for 2024 they have revised profit figures down by >60%... I stagger to think how they could be this far out in their forecasts during the year end itself, massive red flag for me.
Who are you trying to kid? They are unchanged, I have just checked them on Research Tree...
look for yourself here: https://www.edisongroup.com/re... Exhibit 4. reported PBT 67% LOWER than was previously estimated... seriously if the forecasts are this wrong not sure how anyone can take the forward numbers seriously at all. EPS 62% DOWN
Why not try and understand what they are doing before making such OTT statements? The changes appear to be due to share based payments being higher than forecast + £4.8m of FX losses.
Forecasts in the market are based on normalised basic EPS, nor reported basic EPS, so neither changes effects these forecasts (as they are not cash based costs)
It’s not OTT it’s just facts. The fact you’re so emotional shows you need to calm down and stop falling in love with your holdings. You can dress it up however you want using different financial terms but the facts are that Edison are so close to the business and working with them yet have had to alter their forecasts hugely due to fx and share based payments which would have been known about. So looking to 2025 the actual profit produced could be just as much out but console yourself with your normalized measure… take a look at the chart as well as it don’t look great. Don’t get so emotionally it’s just a stock lol
I don't hold shares in BOKU, however your type of post needs to be countered before anyone makes uninformed decisions.
'I stagger to think', 'massive red flag' and your use of caps lock suggests you are the one with emotional issues (or you are trying to influence the emotions of others).
Edison's headline is "With FY24 outlook maintained, our revenue and adjusted EBITDA forecasts are unchanged."
You cannot forecast FX hedging losses, it is what it is. With SBC they had simply rolled forward the previous years actual result.
I suspect you have a short based on the above & would hope that the moderators remove your comments in due course as they are misleading in my opinion.
lol I have no short. I think your imagination is just inventing things now. All I have presented is facts which is that their forecasts for actual profit were 67% out. Obviously Edison don’t want to lead with this because they are paid by Boku. If anyone’s comments should be removed it’s yours. I note you attacked Roland in the comments before and others claiming they hadn’t done their research, so that makes you a troll in my book, one who should be banned from this site.
Boku (LON:BOKU)
Its not complicated and all out in the open with the linked article.
There is no inconsistency here - you can concentrate on your measure amd they can concentrate on their measure - its clear with regard to core trading there is no change so your initial post was completely ignoring that fact.
Fair enough flag up discrepancy/different update ref bottom line numbers and that info wasnt in prior forecasts but i dont see that in any manner anything is being hidden here by anyone and its clear why the adjustments are present. You cant get more transparent than that info being made available in broker notes during the year and ikts clear they they are concentrating on their chosen metric.
Ps thanks for your post always very useful to know if there are "below the line" adjusts that syphon profits away.
In all regard the numbers speak for themselves from my point of view
It is a good point for others to note that looking at the bottom line can sometimes come up completely different position than underlying numbers will present - that a (often ugly) fact of life
Oh you are a delightful piece of work aren't you? You clearly don't understand FX or SBC estimates or you wouldn't have tried to make what is a moot point.
Ps. I didn't attack Roland, I disagreed with his negativity (and reasoned with financial facts) on Hotel Chocolat back in July 2022 when it had just warned on profits and shares had fallen to 135p.
Since then it has been acquired by Mars for 375p - so yes, I'll stand by my comments that Roland's article was overly negative, a 200% return is hard to argue with I'm sure you'll agree?
Not sure I agree. The FX revaluation would have been calculated when they last updated their forecasts and the US$ has weakened considerably since then. Also, since Boku (LON:BOKU) is growing faster than expectations, their cash balance is also higher than expected so the FX impact is greater than previously estimated. The SBP charge has increased because the share price has gone up. In fact the only thing within the company's control is the increased amortisation of a legacy platform that has reached end of life.
In fact Edison, raised the underlying forecasts as they're performing a bit ahead of expectations so not sure why you think this is a red flag?
I suspect the main reason the chart has fallen is the threat of IHT removal for AIM stocks as Boku (LON:BOKU) is a mainstay of those portfolios (Octopus is the biggest shareholder).
Not strictly stock related but I came across a link to this long form essay referenced both in the FT’s Alphaville and in John Stepek’s excellent daily Bloomberg e-mail. I must admit that I haven’t researched the background of the authors but to me at least it makes for compelling reading on what is holding the UK back. It’s less capital market focused and more real economy. In any case very thought provoking for anyone long the UK, which I presume most of us are…
https://ukfoundations.co
Excellent, long but well worthwhile
One of the first things I do in the morning is fire up market watch and check Asia over night.... I have no particular positions in theory that would benefit from a lift but generally, if Asia is positive this suggests to me, rightly or wrongly, the market is positive towards the cycle.
Last night HK and China were up strongly... for now, what are obvious reasons. I sold my Weir Gp a while back because ISM / PMI data was weak and trading statements from industrial stocks were subdued. Caterpillar had also given back gains and the Oil price was weak. Recently both stocks have picked up ... kind of a surprise really....since there seems little fundamentally to get them going.... unless you believe US monetary policy and Chinese stimulus will actually work/help.
The oil price is up 2.5%... Copper is up, Steel is up, Silver is up .... the Dollar is down ... US futures haven't moved much..... but the FTSE 100 is only up 0.3% and so you could just shrug and go and play golf. But a look at the top of the leader board paints a rather different picture.... with all the usual commodity type stocks on the move....
For me, I tend to think why fight it? When the Fed cut it seemed like an opportune time to stimulate for China and here we are...which gives everyone an excuse to push more towards value....a reverse of what has worked this year. Admittedly it suits me so I won't be fighting it.... but the Yen carry unwind, Fed policy and now Chinese policy all point the same way IMO It will be months before we have the data to judge how well things are working out so for now, the risk is money ends up chasing an unloved part of the market. Since the Uk falls in this bucket I think this is positive.
Paul - any new thoughts on hVIVO (LON:HVO) ? Yet more positive news today that Octopus have once more increased their holding to 11.3% and rising. This follows their superb recent results, and the election of a govt committed to investing in prevention rather than cure of our ailments, which is music to the ears of Hvivo. 7 brokers, all BUY or STRONG BUY. Broker forecasting >40p which is a 33% increase on today. So, what the devil is holding back their SP?
2% of my portfolio but sorely tempted to wade in deeper.
Loving the daily updates and the weekly podcast. Many thanks.
Hi Andrew, in answer to your question of what is holding back the share price of hVIVO my answer is that I'm not sure. If you want my personal reason for avoiding hVIVO it is principally that the chairman is a "wheeler dealer" type who previously founded and ran an oil and gas company as well as a range of other companies more similar to hVIVO. Nothing wrong in this, but I'm just not attracted to this type of approach and I wonder if there might be others, particularly institutional investors, with similar views?
Completely the opposite Peter
hVIVO (LON:HVO) some retail investors love Cathal (rightly or wrongly) and the fact that he sold all his shares to institutions has held the share price back as they exit. As he is no longer a shareholder his Chairman role holds much less sway. However, Mo Khan (CEO) has stated that the company want to do some M&A, and given Cathal’s experience in this space it makes sense to continue to use him.
The people who bought Cathal’s stake were the institutional investors - after buying some from Cathal, Octopus Investments (a good manager in my view) has continued to buy in the open market - and now gone over 10%. So the institutional ownership is growing quite rapidly.
The holding back of the share price is merely a period of consolidation in my experience. It trades on c. 15* PER when cash adjusted. One year forward that drops to maybe 12*. As this happens and assuming growth continues and/or earnings enhancing M&A the price will react accordingly. Right now it is just treading water.
@card I'm out. Nice ride just wish I had sold yesterday.
What really scares me is this:
*Entry into the US market secured through a nationwide wholesale retail partnership which will roll out in time for Christmas."
1/The US greetings market is huge. Dominated by Hallmark and American Greetings (at least when Iast looked).
2/ They have Holidays not Christmas. Thanksgiving, Hanukkah etc.
why are you scared ?
Probably because most retailers who expand into the US usually end up regretting it - it's a tough market with a lot of competition.
"2/ They have Holidays not Christmas. Thanksgiving, Hanukkah etc."
Aren't they still card events?
Calling it Christmas shows a misunderstanding of the US greetings business. The business that invented, Mother's Day, Fathers Day, Halloween and greetings around religious holidays.
But the largest market is Christmas, from Hallmarks site:
Christmas is the largest card-sending holiday in the United States,with approximately 1.3 billion cards sent to friends and loved ones every year.
According to Hallmark research, consumers say they always participate in the following activities during the holiday season: 98%wrap presents, 90% decorate inside their homes, 88% decorate a Christmas tree, and 85% send Christmas cards, letters or photos.
It’s a wholesale retail partnership with a US business selling cards. It’s not as if Card Factory (LON:CARD) are entering the US market themselves and will incur significant costs. This is same capital light model they use in other international territories. Plus, as others point out Americans are actually quite a card hungry country both at Christmas and others.
A wholesale partnership in the US wouldn’t be the reason I’d sell. If they were going to be setting up their own stores there I’d be more concerned.
Today’s update was actually relatively well flagged, so not unexpected. However, when I looked at the results initially I realised I had indeed forgotten the H1 narrative, so I expect many others have too and are perhaps selling as a consequence.
CT Automotive (LON:CTA) will publish interim results on Thursday 26.9.24 with a webinar by CEO & CFO at 11am Thursday. Register here.
From the July 2024 Trading Update. In line with expectations. The margin improvement initiatives should benefit Gross Margin beyond 22% for the Full Year. Expect stronger demand in the second half with new launches from Tier 1 customers.
To join us on Friday (27 September) and receive the joining link please use the register button below.
The event starts at 10:00 and lasts for 45 minutes. If you can't attend it live you can watch on-demand providing you register.
This exclusive pre-event for Showcase attendees and will include dedicated Q&A time for audience questions. We hope you will join us.
We'll cover the following topics:
Very interesting on China. US$18 trillion is a big number. China = Japan 40 year ago in my view. If we did have a 50% US stock market crash caused by a recession/technology bubble burst then the size of that hit would be cUS$60trillion / 2 = US$30trillion on equities alone. Huge numbers. The Fed would have a problem bailing that out! Are we going to end up in the next few years with Japan, China and the US all > 200% debt to GDP?
Dialight (LON:DIA). I agree it was a fairly unclear RNS today but I see the shares have bounced back a bit. I bought the shares several times over the last couple of months but didn't buy because of the US Court Case, I bought because of their impressive new management team and new strategy to return the company to decent profitability after years in the doldrums.
Oh man, some sort of weird spike in Team17 (LON:TM17) - I thought it was up 40% today for a minute there ..
Paul / Graham, grateful for your thoughts on Mortgage Advice Bureau (Holdings) (LON:MAB1)'s interims this morning.
They were first on Paul's list from Friday of possible bargain shares to investigate and there was discussion last week by readers (including me) about the large fall following the "in line" TU which seems to have followed the FCA publishing its draft terms of reference for the pure protection market study at the end of August.
Trading is said to be in line. Adjusted EPS in H1 was up 25.8% to 14.8p. Trading so far in H2 has seen a pick up with "written new case numbers ... 11% up in July and August compared to last year" and adviser numbers also up since the end of H1. The accompanying slide deck adds "New activity has increased post-election
and BoE rate cut" and "Pipeline larger than this time in 2023. Record level of mortgages available (23.5k v. 17k in 2023)". Since the forecasts are for 4.6% EPS growth in FY24, there seems some chance of an upgrade. (The main attraction of the share to me is not so much its accounting earnings as its strong cash generation, which continues.)
The interims have a section on the FCA's “Pure Protection – Market Study” which emphasises that MAB1 has always been focused on good customer outcomes and thinks that raising standards is a good thing and will create acquisition opportunities. More interesting IMO is MAB1's explanation of why there is (said to be) no consumer duty problem with the use of loaded commissions which is in the slide deck on slides 9 and 25. Essentially, because advisers do not earn more by recommending products with higher commissions the advice they give is not distorted by variations in the commissions offered; the commissions that are charged are made clear to customers; and the payout rate from the insurance products customers buy is in the top quartile of general insurance products.
Thanks for your excellent analysis over the last week or so. Not sure where you are getting the EPS forecasts from though? 2023 Adj. EPS was 29.7p, sharepad forecasts currently show 36.1p pencilled in for FY24, so +21.5% YoY.
To hit these numbers MAB1 needs to earn 21.3p in H2 vs the 17.8p achieved last year, which is +19.7%. Comparing that to the +11% new case numbers and there is no obvious reason to expect a beat, rather they will do well to meet expectations?
Stat du jour.
Barclays estimates that the Chinese property crash (eg Evergrande) since 2021 has destroyed $18 trillion of household wealth (vs UK GDP = $3.4trn), equivalent to around $60,000 per family.
I saw a vid in which half-completed high-rise buildings were demolished because the developer ran out of money. Shocking.
Then you had things like a large domestic property developer defaulting on a loan that was denominated in a foreign currency. Taking out foreign loans for domestic production is a recipe for disaster.
Then, what, property development accounted for something like 30% of GDP? That's a very skewed sector weighting.
This has a lot of echoes of Japan back in the day, which experienced a lost generation. I think China is in much deeper water than most suspect.
Maybe they could offer Evette Cooper or Angela Rayner some of that lovely housing.
Are these not micky mouse stats? if we take the viewpoint that there were unbooked gains that perhaps were somewhat never realiseable is the reality that these so called assets were pimped up wherever they were sat (presumably aided by balance sheets of evergrand and people doing buisness with them) - that frowth is now gone. What it ever a real tangible number where people could have sold at the? perhaps they could have sold even then preumably it was like a bubble of the tech boom back in the 90's where stocks were over inflated temporarily.
Good news is if everything is now reset at more realistic levels without having triggered a crash than thats good in that there are less likely to be ongoing contagion? - i am not saying there is no fall out here - obviously soem will have invested and be stuck ion negative equity or paying for stuff that they cant afford.
It is difficult to read China as it somewhat of a Black Box, and to an extent the Govt intends it to be that way.
However, the general signals are not good. Unemployment is growing amongst the young. They are trying to provision for a growing elderly population by pushing back pension provision to later ages (this was inevitable). The replacement of population by young people having babies is both damaged by the cost of property and the fact that properties have lost quite a bit of their value. Discretionary shopping except for restaurants is down.
They have probably massively overproduced electric cars, and in trying to dump the surplus onto foreign markets are facing tariff barriers going up everywhere.
Unless Govt policy starts to change foreign investment will be retreating back home, and there is strong evidence of this happening.
The party have tried to put the brake on this and so the full effects have not been felt yet. It is a tremendous blow to personal wealth that is only going to get larger because prices have further to fall.
China pulled the world out of the GFC by huge infrastructure spending. It is likely they will push the world into the next slump.
I have see the miles upon miles of unoccupied and half finished apartment blocks on several visits to China. It is insane and makes the Japan property bubble look like a minnow.
A couple of stories that come off the top of my head ...
Hedgie Hugh Hendry did a fact-finding tour of China quite a few years ago. He reported that there were plenty of empty office blocks. I thought to myself "Yeah, that ain't good". I have sceptical about that aspect for years. Legendary investor Bill Rogers said some time ago that he thought there was "some" overheating on the periphery. When I heard that I reckoned he was well understating the case.
Another example: some company rented office space on the lower floors of a building. They used to play basketball on the floor above. The rest of the building was basically an empty shell.
There must dozens of other such examples.
I've always been sceptical of the Chinese push towards growth, particularly exports. We've been lapping up Chinese goods. The big problem from China's viewpoint as I see it is that they having been manufacturing goods at low profit. Sure you'll win customers, but you're not earning a decent profit. No wonder the West is buying whatever China is selling. It's not a great business model.
China is mulling the idea of encouraging internal consumption. I think this is actually a good idea. In my view, you want a balance between consumption and production. Consumption without production leads to bankruptcy. Production without any consumption, well what's the point? I heard an economist challenge the doctrine of being a net exporter. He argued that as long as external trade was balanced is there really much benefit to it?
In theory are China not progressing nicely to uk standards - from investment point of view the excess property building is probably poor for returns - but if they are upscaling the quality of cities/housing stock and the like then the reality is they can probably move to a more service based economy perhaps. The only problem i perhaps see is the declining population due to lack of young uns - they have time to turn that around. Surely if there is over production of stuff like electric vehicles thats good as it keeps price down to buy. I ssupect all the real astatsh that matter - what % have decent home - what % have some sort of vehicle and what % are doing some sort of semi skilled work amust all be increaisng on ongoing basis.
I have heard that the Chinese are not only building excess office blocks, but actually building entire cities large enough for 500,000 people in the hope that people will move into them. The collapse of Evergrande was the logical consequence of this situation.
The communist party has set a goal of reaching peak CO2 emissions by 2030, which is the reason why so many EVs are being manufactured in the country. It all seems reminiscent of the attempts to predict and control manufacturing volumes in the Soviet Union, which is not an encouraging precedent.
I have heard that the Chinese are not only building excess office blocks, but actually building entire cities large enough for 500,000 people in the hope that people will move into them. The collapse of Evergrande was the logical consequence of this situation.
Yep pretty sure this is true - note it might not be as bad as it sounds i think i have also heard that it can take years for these ready built locations to be filleds up with people. There has to be a danger though that they have built too much i would certainly agree - its not as if they have lots of kids coming through needing homes - i suspect there is probbaly a huge amount of people living in rural areas or in poverty who could/will benefit from upgdrages given the chance.
The communist party has set a goal of reaching peak CO2 emissions by 2030, which is the reason why so many EVs are being manufactured in the country. It all seems reminiscent of the attempts to predict and control manufacturing volumes in the Soviet Union, which is not an encouraging precedent.
I have been following the coal situation for a few years i thought 6 years ago it would have been peak consumption by now - they arent quite there but i would say progress has been pretty solid so increases are pretty negigible - its not as if they havent invested in renewables too so i for one wont criticise their progress. I think any comparison with soviet union is probabably like comparing a porsche to an 1980's skoda made in the easetern block.
To quote from the Centre for Research on Energy and Clean Air,
'In the first half of 2024, construction began on over 41 GW of coal projects, nearly equaling the total that started construction during all of 2022 and constituting more than 90% of global new coal construction activities. Moreover, the government’s goal of bringing 80 GW of coal-fired capacity online in 2024 indicates a potential increase in project completions in the latter half of the year, from 8 GW commissioned in H1 2024'.
a levelling of consumption doesnt mean that existing facilities either past their best or suitable for upgrading will not be replaced. Everything has a finite life after all.
Here is the evidence that they are near to peak conmsuption - one may choose not to believe it but
https://www.mining-technology....
if you look at the following table thats in google that will evidence that - there hasnt been rampant increase in coal consumption since say 2013 onwards - albeit deffo a recent uptick. I think they have done pretty well in that regard bearing in mind the improvements in their citizens quality of life towards western standards.
Consumption of coal in China from 1998 to 2023
a levelling of consumption doesnt mean that existing facilities either past their best or suitable for upgrading will not be replaced.
On that theme I understand that while Chinese coal fired capacity has grown and may continue to grow the utilisation factor has fallen from 70% to 50% now - and forecast (S&P commodities forecast) to fall to 30%.
There might be a plan or not? It seems that increased coal-fired capacity is being used less often - to provide backup generation capacity for when the wind don't blow, the sun don't shine and the three gorges run dry? Using gas-fired capacity is more the norm elsewhere - China doesn't have gas reserves but does have large thermal coal reserves?
Quite the experiment? Will be interesting to see how well this turns out for them?
ref https://www.sustainabilitybynu...
cheers
Mark
Who knows the secret of the black magic box - if nothing else having the extra capacity might come in handy if ............
Cohort plc (LON:CHRT) another pleasing update at the AGM: H1 25 is seen significantly ahead year-on-year, with FY revs and adj operating profit slightly above Board expectations ✔️
We raise some forecasts and retain Fair Value at 910p/share for now, as you can read in new research note here (free access):
https://www.equitydevelopment....
Dialight (LON:DIA)
Decided to sell this one today, took a bit of a punt on it a month ago or so.
Didn't think the RNS read like the legal decision went in their favour:
"The Company is currently reviewing the detailed jury verdict and judicial rulings in conjunction with its legal advisers and will release a further announcement as soon as there is greater certainty over the implications of the verdict."
To me that does not sound like the verdict went their way.
Not a great week so far having owned Oxford Metrics (LON:OMG) and Card Factory (LON:CARD) as well, with all three shares dropping 20% plus. Investing is great, but need to take the rough with the smooth......
Yes, the market is reading it the same way as you with Dialight (LON:DIA) . What a ridiculous announcement making investors guess rather than just showing them a transcript summary. You have my sympathies for your triple whammy this week. I also took a hit on Oxford Metrics (LON:OMG) but fortunately I haven't held Dialight since the days when the share price only used to go up (i.e. a long time ago!)
Dialight (LON:DIA) I assume it is a "deliver bad news in stages" kind of announcement, paving the way for a later clarification, but I'm rather surprised they are allowed to do this. Some shareholders clearly know the ruling whereas the rest of us shmucks are in the dark.
Dialight (LON:DIA)
These should be suspended or the full ruling should be disclosed to the market, it's clearly material.
If I were a shareholder, and some people knew the decision while I was left to second guess, I would be livid.
Housebuilding picking up
Van Elle Van Elle Holdings (LON:VANL) mentioned in their online presentation yesterday that they were seeing an early pick up in housebuilding activity. I would like to get a toehold in the sector but don't have a good knowledge of the various UK builders. Does anyone have any strong views on the best way to play this?
As an aside I thought the Van Elle presentation well worth watching. They made the point quite clearly why they are not subject to the same major risk that other primary contractors are. Primarily lots of small quick jobs and they are always at the very beginning of a project and finish and get paid early in the lifecycle.
I would like to get a toehold in the sector but don't have a good knowledge of the various UK builders
You could do worse than stick with Van Elle Holdings (LON:VANL. In contrast to all the house builders, who have been on a strong run, the name is barely off the floor. I like MJ GLEESON (LON:GLE) but don’t expect it to continue rising in pace with the last year.
Thanks for your thoughts BnB, BO and JASVS
Hi Peter,
I thought the Van Elle presentation was good as well, for what it's worth I have only two cyclicals exposed to the sector Van Elle Holdings (LON:VANL) and Eurocell (LON:ECEL) both have very solid balance sheets, excellent management and have traded through the bottom of the cycle very well, in short i see minimal downside with these two.
I don't own housebuilders but if i did I would probably go for Cairn Homes (LON:CRN) MJ GLEESON (LON:GLE) Vistry (LON:VTY), however the optimum time to buy these has now past in my opinion.
Imo you could do worse than research Michelmersch Brick PeterW, we hold and expect it to benefit from any pick up. We also hold Cairn the Irish builder. Crest Nicholson might be worth studying, we no longer hold but might buy in again.
Hi Peter, Roland Head wrote a very interesting article on builders materials, https://www.stockopedia.com/co...
which is a good place to start, you could also use the Screens (lots of articles on how to use these , most recently one done by Paul "mic on" Scott. :-) ).
Talking mine own book , i'm in Cairn Homes (LON:CRN) ,Morgan Sindall (LON:MGNS) ,Forterra (LON:FORT) , looking for a RE entry point for Michelmersh Brick Holdings (LON:MBH) . REITS are also worth a look at , now the interest rate is moving in the right direction (down!). There are a lot of high dividend, discounted property trusts out there too..... Check out Charles Mitchell and Co's contributions on investment trusts, lots of valuable ideas on that thread. ( Great resource Charles M and Co.... many thanks)
https://www.stockopedia.com/co..
happy researching!
Thx v much..
Warpaint London (LON:W7L) - worth looking at Barclays' research published in press release today which mentins 'Dupes' the category of cosmetics that Warpaint focuses on - see the press releae under this link: https://home.barclays/news/press-releases/
do you have direct url pls as I can't find it
do you have direct url pls as I can't find it
Possibly this: https://home.barclays/news/press-releases/2024/09/digital-beauty-boom--new-barclays-data-reveals-growing-demand-fo/
Thanks for this.. Super interesting! Who knew 50% growth of LipsTIK Tok de-influencing was a thing.?? Also with 32% of consumers buying dupes vs 18% buying the OG product I think the trick is to make the original AND the dupe...(I've often had my doubts...)
Strong results from Yu (LON:YU.)
Financial performance
· Revenue increased 60% to £312.7m (H1 23: £194.9m) with strong organic growth in meter points.
· Adjusted EBITDA increased 49% to £20.4m (H1 23: £13.7m)
· Strong net cash position of £86.8m (H1 23: £36.6m). Net cash inflow of £56.9m (H1 23: £17.7m), including return of £49.8m cash on deposit (H1 23: £16.5m outflow) from previous hedging counterparty, and after £10.2m of capital payments through share buy-back and dividends.
· EPS grew 52% to 88p (H1 23: 58p) (adjusted, fully diluted basis).
· In line with our progressive dividend policy, a materially increased interim dividend of 19p per ordinary share (H1 23: 3p) to be paid in December 2024.
https://www.investegate.co.uk/...
ZIGUP (LON:ZIG)
Agm update today not a trading update as such but confident tone. Current year broker forecasts average in the company website. It makes sense that currently 2026 forecasts are lower than 2025 as normalisation in van prices mean that the temporary benefit from historical prices is replaced by normal conditions. Note they also changed depreciation rates such that earlier years benefitted (necessary to resilient values) - even on 2026 forecasts or is something like 8 ish with confident outlook here I am happy holder and am increasingly confident that 2026 level of earnings looks sustainable and hopefully factors in more tailwinds that headwinds. Hey ho quite a few moving parts here and we will have to wait for future trading updates to see the score - I take comfort from management confidence here they have not failed me as of yet.
My morning smallcap tweet: Going the extra trial
Dialight (LON:DIA) Niox (LON:NIOX) MTI Wireless Edge (LON:MWE) Cohort (LON:CHRT) Blackbird (LON:BIRD) Galliford Try Holdings (LON:GFRD) Knights group (LON:KGH) Ra International (LON:RAI) Capital & Regional (LON:CAL) HSS Hire (LON:HSS) ITIM (LON:ITIM), ZIGUP (LON:ZIG), Card Factory (LON:CARD), Microlise (LON:SAAS), Animalcare (LON:ANCR), Corero Network Security (LON:CNS), Personal group (LON:PGH), NAHL (LON:NAH), Mission (LON:TMG), Mycelx Technologies (LON:MYX), Digitalbox (LON:DBOX)
◄Dialight (DIA)► the re-trial in relation to the litigation with its former manufacturing partner, Sanmina, has ended. Co is reviewing the detailed jury verdict and judicial rulings. The judgments will be fully released by the court in due course. [SP=250 Cap=100m]
◄Niox (NIOX)► £21m tender offer at 80p, a 21% premium. That's 6% of shares max. Trading in line. [SP=66 Cap=278m]
◄MTI Wireless Edge (MWE)► wins initial $0.7m order in India for 5G backhaul antenna solution. Any further orders will be considerably larger. [SP=49.42 Cap=43m]
◄Cohort (CHRT)► guides FY-Apr rev and profit a little ahead of mgmt expectations. [SP=832 Cap=348m]
◄Blackbird (BIRD)► elevate online video editing and content creation platform now has over 10k verified users. [SP=7.13 Cap=28m]
◄Galliford Try (GFRD)► wins £88.9m road contract. [SP=296 Cap=308m]. I hold.
◄Knights (KGH)► AGM stmt - board has confidence in the current year. [SP=132 Cap=113m]
◄RA International (RAI)► wins $32m three year contract in Somalia. Two option years worth £4m max total. [SP=7.4 Cap=13m]
◄Capital & Regional (CAL)► rec offer from NewRiver REIT of 31.25p + 0.41946 NewRiver shares. That's worth 57.4p at NRR's closing price of 62.4p. [SP=62.4 Cap=145m]
◄HSS Hire (HSS)► H1-June. Removes guidance for the foreseeable future due to "a period of significant transition over the next 6-12 months as we implement change". [SP=6.98 Cap=50m]
◄itim (ITIM)► H1-June. Guides FY ahead of market expectations. [SP=33.08 Cap=11m]
In line: ZIG, CARD, SAAS, ANCR, CNS, PGH, NAH, TMG, MYX, DBOX
There has not been much mention of the yield curve inversion as markets hit new highs. Just drawing a line under the disinversion that took place earlier this month its interesting to note that the US yield curve was inverted (i.e 2yr more expensive than 10yr) for 795 days or 26 months which is the same length of time as prior to the great depression (i.e. 5 July 2022 to 6 September 2024 = 795 days). US equities are priced for perfection. Personally, I think the US ecomony is in the 'twilight zone' where things are not quite what they seem, with the Fed reliant on inaccurate data that is subsequently being revised down. Think we could well have a blow-off top in the S&P500 and Nasdaq first, but we might be in for something spectacular as this bull run comes to an end.
Anyway, back to small caps - it would be good if City of London Investment (LON:CLIG) and Personal group (LON:PGH) could be covered today.
Buffett is 45% in cash. Nuff said.
Buffet also bought Tesco just before all the problems emerged....
Buffett has held a high % of cash relative to his stocks since the financial crisis 2008/9. He would have done better to be fully invested. He's not always right.
Re: Wazza The Great - its hard to go shopping though when all you have are billion dollar notes.
Buffett also bought Tesco just before all the problems emerged....
He also bought a dog of a textile company called Berkshire Hathaway and gets to remind himself about it every day. Humility in investing is important. Everyone makes mistakes is the only take away from a tiny investment loss he once took on Tesco and only time will tell if he is right or wrong on holding so much cash. He is more often right than wrong with such calls which is all you need to be to make good money.
I am not sure what to make of the vice-chair, Ajit Jain, selling more than half his stake in Berkshire Hathaway (NYQ:BRK.A) though. I hold and am scratching my head. Maybe there is a change of succession plan; maybe Mr Jain is departing for his own venture ... who knows, but the optics are not good.
Berkshire Hathaway vice-chair Ajit Jain sells more than half of his stake in company (ft.com)
I am not sure what to make of the vice-chair, Ajit Jain, selling more than half his stake in Berkshire Hathaway (NYQ:BRK.A) though. I hold and am scratching my head. Maybe there is a change of succession plan; maybe Mr Jain is departing for his own venture ... who knows, but the optics are not good.
Sorry, I don't follow the company but have read "The Snowball" - one of the best biographies I have ever read. It does seem strange for a key high-level employee to offload that much stock but my understanding is that he was passed over to become Buffett's successor, so maybe not surprising that he may have other long term plans of his own.
Mr Jain is head of Berkshire Hathaway (NYQ:BRK.A) insurance business and Mr Buffet is on record saying Mr Jain "probably made more money for Berkshire than I have". Mr Buffer wrote in the 2017 newsletter: “If there were ever to be another Ajit and you could swap me for him, don’t hesitate. Make the trade!”
Mr Buffet said in 2021 that Greg Abel, who heads up Berkshire's energy business, will succeed him.
If Mr Jain does walk, it will be a serious loss for Berkshire Hathaway.
Thanks for the heads up on snowball ... I have ordered a copy. I should have read it years ago!
Niox (LON:NIOX) interims a pleasure to read and tracking ahead of expectations IMHO. They also state: "Tender offer announced today to repurchase approximately 26.25 million shares at 80 pence per share, returning £21.0 million to shareholders if fully taken up" - that's a ~21% premium to today's price. The ultimate end goal is a sale of the business. I hold & have done for some time now. Tough call on what to do for sure :-)
MGinvestor at the least it would seem to be a good idea to take the 80p per share for 6.2% of your holdings, after you have bought that number of shares today for c70p.
RPI Very brief (Frist post) H1 update ... revenues +61%, gross profit +47%, unit volume +31%, adjusted EPS +27% but Basic EPS -11%. Net cash +9%.
Statutory figures (i.e. the "real" ones): operating profit +9.6%, PAT -10.6% (they had higher taxation rate and increased interest costs on lease of new office)
Potted highlights: Completed recovery from pandemic related shortages ... introduction of Pi5 ... launch of AI hardware product ... debut of cloud product (50k users since May 2024) ... performance weighting no longer expected to be in H2 as H1 was ahead of internal expectations ... higher unit volumes expected in H2 ... customer/channel inventory levels expected to normalise from higher than usual level .. full year expectations remain unchanged.
Engineering staff increased from 46 to 61. That seems to bode well for future product development.
Seems pretty good, although I guess we'll have to see what the market makes of it given its fairly lofty valuation. Shout-out of Monty Carlo an his son.
Excellent progress on value realisation at NAHL (LON:NAH) announced in their interims this morning.
Sale of Bush (likely for £40m+ or 85p/share+) progressing well with several parties being taken through to the negotiation stage. And finally announced the strategic review of the PI division alongside. Feels like we are finally into the endgame here and shareholders should receive at least 100p of value over the coming months (versus stock price of 60p)
An uninspiring set of results from Card Factory (LON:CARD) this morning. I can't see the recent upturn continuing.
I agree, profit down, EPS down, hopefully Paul or Graham will pour over the rather detailed RNS
I would add that these results were expected and I do think the explanation for the YoY profit reduction is clear (primarily increased wage/freight costs). Interesting to see where it goes now. Restoration of interim dividend a positive.
Uninspiring and yet a 18% fall in share price as I write. I think that is way over done. They have clearly been stung by the National Living Wage and they haven't managed to reduce the debt (in fact it has grown a little bit). But on the positive side they are introducing a dividend and the outlook is reasonable. There is no profits warning and they trade around 8 to 9 times. I cannot see how that warrants such the size of the fall. The problem is as much as I like and applaud commentators like Paul and Cockney Rebel they do encourage (not deliberately I know) traders into the share and this adds volatility. I still think this share should be trading 10 to 12 times and the price should be near £1.60 for what it is worth.
The problem for me is that revenue is up, but profit before tax is down substantially. It's difficult to see a strong recovery from that position.
Hi Camtab - on the debt issue:
1. £15m in dividends were paid in the period so for comparison's sake to HQ23 implied debt in H124 is £15m lower than reported.
2. Stocking up for the main trading period in H2 means higher inventory. As this unwinds through H2 expect to see debt level reduced.
Thanks Gimmers.
The presentation slides are on the card factory website which give a bit more detail. Full Aldi store rollout to 1,200 stores from the end of September 2024 (are they already in half)?
The boss of the clothing chain Superdry says its rival Shein is being allowed to "dodge tax", and is urging the government to take action.
Julian Dunkerton told the BBC the fast fashion giant was enjoying an unfair advantage because import duties are not charged on the low-value parcels it sends direct to customers from overseas.
Shein declined to comment, but has previously said that its success was due to its "efficient supply chain", not tax exemptions.
The Treasury said tax policies had to balance the interests of consumers and retailers.
However, Mr Dunkerton said it would be in the UK's interests to get rid of this tax "loophole".
“The rules weren’t made for a company sending individual parcels [and] having a billion-pound turnover in the UK without paying any tax,” said Mr Dunkerton, founder and chief executive of Superdry
https://www.google.com/amp/s/w...
This is an ongoing issue in the uk we allow cash to flow directly out of the uk with little taxes being paid - unbelievable - if those sales had gone to boohoo or super dry or other uk retailer proper taxes would have been paid and money kept in uk to be spent in uk (uk jobs - payroll taxes) - crazy we make it easier for cash to depart the uk than stay here when it should clearly be the other way round - and we say people need to spend more , that’s hard to achieve when cash has departed the building. Toriss actively encouraged this situation current government need to change things
Don't buy the crap they sell, then.
Re: Don't buy the crap they sell, then.
Agree, but sadly my nieces can't resist the temptation of shiny things at ultra-low prices (they're not thinking of the long-term costs and consequences at all).
Re: The rules weren’t made for a company sending individual parcels [and] having a billion-pound turnover in the UK without paying any tax,” said Mr Dunkerton, founder and chief executive of Superdry.
- Incredible that UK Treasury & HMG should need to have this explained to them.
Ed_miller.....I can only assume you haven't dealt with HMRC recently. Lol
https://www.independent.co.uk/...
look at this example as to how clued up head of hmrc is - unbelievable the niavety of the head of hmrc
HMRC has found “no evidence of fraud” in a case where 12,000 Chinese companies changed their addresses to a flat in Cardiff.
Flat owner Dylan Davies has received thousands of tax bills for the companies since November 2021, including letters from debt collection agencies.
But while Jim Harra, the permanent secretary at HMRC, told MPs on Thursday that it was an “odd” and “curious” incident, he said there has been “no fraud perpetrated on HMRC as a result of this and it’s not clear that it was an attempt to defraud us”.
Appearing before the Public Accounts Committee, Mr Harra said: “If this was an attempt at fraud, it would be very unusual for fraudsters to use an address that is not under their control because what actually happened in this case would happen, which is that the real occupier of the address starts to get correspondence and they contact the authorities.”
What are contrarian investor Michael Burry's (re Big Short) stock picking & portfolio management strategies?
Key messages include:
1) Buy shares of unpopular companies when they look like road kill, and sell them when they've been polished up a bit (ie Blood on the street).
2) Stock picking is 100% based on the concept of a margin of safety (ie downside protection).
3) Fish from an unconstrained pond of opportunities.
4) Hold 12 to 18 stocks , diversified among various depressed industries, and typically be fully invested.
5) Wrt timing, use 'Bowl' style formations on charts to highlight possible turnarounds (re Richard Crow ). But cut losses fast if wrong.
Cockney Rebel loves a bowl
Thanks Paul, great post.
EV/EBITDA & Free cash flow yields are for me by far the two most important valuation metrics I use and on that basis I own McBride (LON:MCB) GYM (LON:GYM) IG Design (LON:IGR) Billington Holdings (LON:BILN) Gulf Marine Services (LON:GMS) Serica Energy (LON:SQZ)
If anybody has any other stock ideas that fit the bill please post, or indeed what parameters you use to screen for low ev/ebitda and high free cash flow yields, I would love to hear and have a conversation about it.
Thanks
PS> I have sold out of my Learning Technologies (LON:LTG) which would have fulfilled my usual criteria as there are just too many unknown variables that stop me from making this a conviction hold
William Tamworth of Artemis Fund Managers on recent Vox Markets video beleives Future (LON:FUTR) is good value as a growth share on a free cash flow yeild of aproximately 12%. I hold
The trouble with Mr Burry is he has been a permanent bear since the GFC. Being years too early is no different to being plain wrong. Scion's returns have also been a mediocre: 43.21% over 3 years. I do however think his perma bear view might be more relevant now. Still, I suppose 16 years too late is better than not arriving at all.
Would like to keep that by me, Paul. Could you tell me where the quotation comes from (can't lift it from here...) Thanks