Small Cap Value Report (Tue 25 April 2023) - JUP, SMV, ABDP

Good morning from Paul & Graham!
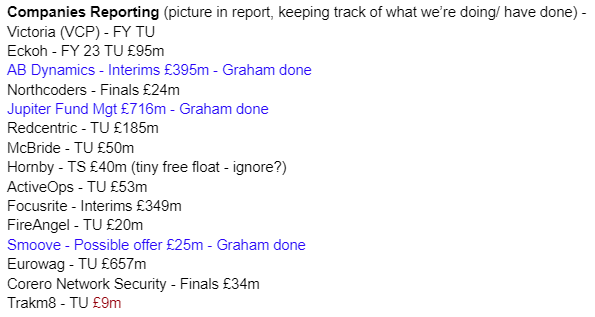
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Jupiter Fund Management (LON:JUP) - down 2% to 129p (£703m) - Graham - GREEN
I continue to take the contrarian view that these shares are underpriced. Retail outflows continued in Q1 but institutions stayed flat and market movements boosted AUM. Remains very cheap by historic standards.
Smoove (LON:SMV) - up 28% since Friday (£24m) - Graham - AMBER
Smoove’s assets may have strategic value, as a large Australian group is currently in talks to buy the entire company. After poor results released last year, this could be a nice way for shareholders to exit.
Ab Dynamics (LON:ABDP) - up 1.8% to £17.30 (£396m) - Graham - AMBER
Interim results are in line and full-year expectations are unchanged. Good visibility for H2 and acquisition integrating as planned. But valuation remains high even if you give the benefit of the doubt re: adjustments.
Graham's Section
Jupiter Fund Management (LON:JUP)
- Share price: 132p (pre-market)
- Market cap: £719m
This is one of the pure-play fund managers I’ve taken an interest in since late last year, when I noticed that valuations in the sector had become (in my opinion) excessively depressed.
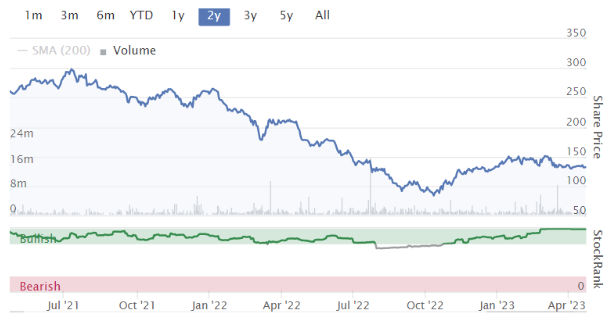
As a consequence, I started to make positive noises even - or especially - about fund managers which I did not consider to be best-in-class, as their valuations looked far too low.
Jupiter is up by 36% since the last time we covered it in the SCVR. Let’s have a look at this morning’s Q1 update.
Assets under management are up by £0.6 billion to £50.8 billion.
The improvement is broken down as follows:
Market returns positive £1.5 billion
Net flows negative £0.9 billion, due to retail outflows (more than 80% of Jupiter’s AUM is retail money).
Institutional money was static: there was a slight £0.1 billion positive flow from institutions.
Company comment:
…the 'risk off' environment we saw through 2022 continued into the first quarter of 2023. Client demand for UK and European equities remained muted, although this was partially offset by continued positive net inflows into global equity strategies. Outflows from Fixed Income continued to slow, but market uncertainty remains.
Positive momentum was maintained in the institutional channel as we again generated net positive flows. This was primarily driven by mandates funding into global equity strategies managed by NZS Capital. Our pipeline of late stage opportunities remains strong and we look forward to increasing scale in this channel over the medium term.
Graham's view
This is just a brief quarterly update, and so I’ll try to keep my comments brief.
One of the exercises I did last year, when studying this stock, was to provide my own spin on the “EV/AUM” multiple that gets used when studying companies in the fund management sector.
I called it the “AUM multiplier”, and it asked the question “for every pound that I spend buying shares in this fund manager, how many pounds of AUM do I get”?
This was the result I got when studying Jupiter last October, and comparing it to prior years:
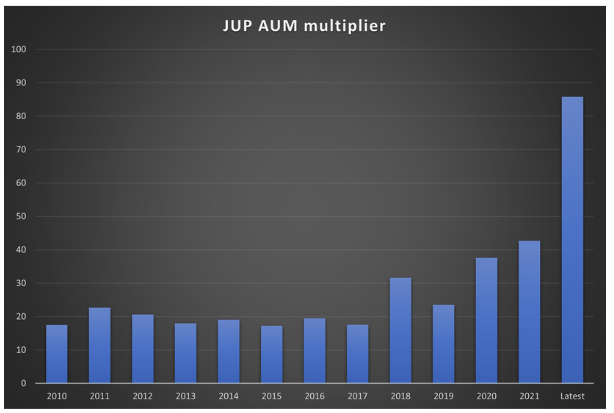
The AUM multiplier had grown from a “normal” reading of about £20, to what I thought was a silly reading of £86.
That number today is £72, still an extraordinary reading by historical standards.
Of course it will not be very easy for Jupiter to win the hearts of minds of retail investors, but I suspect that the new CEO at Jupiter understands this. Still in his first year, I look forward to tracking his various initiatives to improve performance.
With the share at this valuation, I have to remain positive on the prospects for shareholders from here.
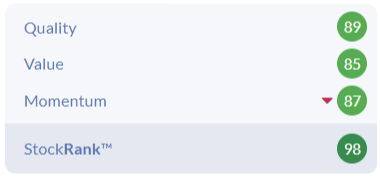
This share also enjoys a stunning StockRank of 98.
Smoove (LON:SMV)
- Share price: 41.4p (+28% since Friday)
- Market cap: £24m
This company owns eConveyancer, DigitalMove and Legal Eye.
I’ve found this one interesting over the past year, due to its large (but shrinking) cash pile, last seen at £17m in September 2022.
In a positive sign of shareholder orientation (and hopefully not a sign of overconfidence), they returned £5m to shareholders in January via a tender offer, buying back shares at a price of 40p.
Results have been poor, including a £3m underlying loss in H1 of the most recent financial year, with very little revenue growth. I remained open to the possibility that the company could cut costs and get itself onto a steadier financial footing.
Today’s news: stock market investors might not see the final outcome here, as there are talks around a possible offer. Thanks to sharw for flagging this in the comments this morning.
The unofficial stock exchange announcement service at Sky News broke the story, followed by an RNS:
The Board of the Company notes recent press speculation and confirms that it is in early discussions with PEXA Group Limited ("PEXA"), regarding a possible cash offer for the entire issued and to be issued ordinary share capital of the Company. Discussions with PEXA remain at an early stage.
PEXA is an Australian property settlements platform, providing similar and complimentary services to Smoove.
PEXA is worth £1.3 billion according to its StockReport, so this deal, if it goes ahead, will be peanuts to them.
There was also some kind of an “alternative potential transaction” that Smoove was working on, instead of the possible PEXA deal. But in a separate RNS today, Smoove says that discussions around this alternative transaction have ended.
My view
Sky News said there were “several takeover approaches from unnamed suitors”. Doesn’t several mean three or more? So I’m wondering if PEXA might still face some competition in its efforts to buy Smoove.
It’s difficult to comment on this proposed deal without more information around the terms (which may not be agreed yet) and on Smoove’s current trading We still don’t have results for FY March 2023.
Based on the FY 2022 results and the H1 results for H1 2023, I do think that Smoove will be negotiating from a position of relative weakness, i.e. the argument that it will be able to succeed as an independent company is not as strong as it might have been. Those H1 results really were very poor.
Perhaps Smoove’s openness to discussing takeover offers reflects a difficult H2? Maybe they realise that turning the corner to profitability is going to take longer than anticipated? If that’s true then a cash offer from PEXA would be a nice way for shareholders to gracefully exit their positions.
I should mention that one of the NEDs at Smoove owns 19% of the shares (the largest shareholding), and he has a background in corporate finance. Harwood Capital (the company managed by Christopher Mills) owns 15%.
Ab Dynamics (LON:ABDP)
- Share price: £17.30 (+1.8%)
- Market cap: £396m
Today we have H1 results from this company, described as a:
“designer, manufacturer and supplier of advanced testing, simulation and measurement products to the global transport market”.
Key points:
Revenue +30% to £49m (organic growth is 14%)
Adjusted op. profit +37% to £7.8m
Actual op. profit + 16% to £2.9m
“Recurring and service based revenues” continue to represent 41% of the total - not bad.
Net cash remains strong at £21m after £11m was spent on acquisitions during H1 (this is part of the upfront cash payment for Ansible Motion).
The integration of Ansible is “continuing as planned”. Note that the maximum price of this deal is £31m, so they may need an additional £12m to pay this.
There is “a promising pipeline of potential acquisition opportunities”.
If more cash is needed, they also have a £15m RCF with NatWest (partially drawn).
Outlook
As noted previously, they have good visibility for H2 this year. Expectations are unchanged.
Looking further ahead:
Future growth prospects remain supported by long-term structural and regulatory growth drivers in active safety, autonomous systems and the automation of vehicle applications
My view
This remains a very solid business, and the exposure to ADAS testing (advanced driver assistance systems) is an attractive niche to be involved in. These systems are surely only going to become more popular and more advanced over time, and ABDP can hopefully play a big role in developing them.
As for the merits of the shares, well, I’m going to risk repeating myself by saying that they are very expensive.
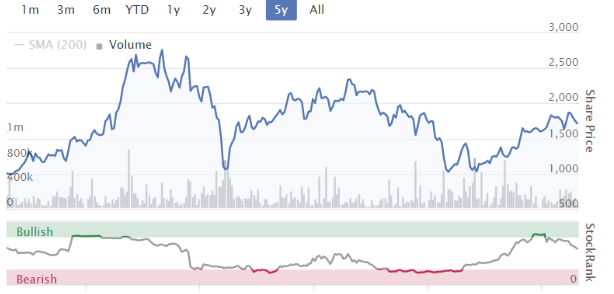
Over the past five years, only the investors who were price-sensitive have done well. Caution has worked well in the past:
Is it possible to justify their current rating?
One way to do it would be to use the company’s “adjusted cash flow from operations”, which was £9.5m in H1. Double that and we are nearly at £20m of adjusted cash flow for the year.
The adjustments to cash flow include £0.8m for ERP (enterprise resource planning) software development, £0.4m for acquisition costs, and £2.1m for “a bonus paid to employees of the acquired entity for pre-acquisition service”.
It may be possible to justify all of this, although I have major doubts about treating ERP spending as “exceptional”.
You then also have to ignore capex and capitalised development costs.
And even then, the pre-tax cash flow yield is still only around 5% annualised.
I like the stock but I can’t give it the thumbs up at this price,
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

62 comments
It looks like the US banking troubles are back on with the First Republic Bank (NYQ:FRC) share price collapsing by over 40% today. Looking at its Q1 financials it lost x5 its equity in deposits in Q1 which was replaced by short-term borrowings. Banks are truly scary when they have a run!
I see the hope of putting Unbound (LON:UBG) shareholders out of their misery (myself included) has gone with Woolovers saying no longer interested. Obviously they didn't like what they saw so guess the management of Unbound (LON:UBG) couldn't manage to hide their dire position from the aptly named interested party!!
??? Woolovers has pulled out because Unbound (LON:UBG) management said they instead supported an injection of equity at 10.5p a share by another investor.
Someone prepared to ‘throw good money after bad’ I fear. Surely Unbound (LON:UBG) has demonstrated it cannot extract itself from the hole it was left in by the private equity outfit that sold the market a complete disaster!
Bid targets, where would you like me to start! to add to Vertu Motors (LON:VTU) Somero Enterprises (LON:SOM) and Sanderson Design (LON:SDG)
Headlam (LON:HEAD) Portmeirion (LON:PMP) Videndum (LON:VID) Watkin Jones (LON:WJG) Palace Capital (LON:PCA) Real Estate Investors (LON:RLE) Forterra (LON:FORT) Centaur Media (LON:CAU) Harworth (LON:HWG) Flowtech Fluidpower (LON:FLO) Galliford Try Holdings (LON:GFRD) TT electronics (LON:TTG) Belvoir (LON:BLV) Hargreaves Services (LON:HSP)
With the exception of Sanderson Design (LON:SDG) all of the above are held in family portfolios and in my opinion are underappreciated and depending on which metric one uses undervalued.
A few have faced particular challenges caused by the rise in interest rates, notably the two REITS, Palace Capital (LON:PCA) and Real Estate Investors (LON:RLE), similarly I would mention Watkin Jones and Harworth (LON:HWG) (LON:WJG) but these are fully reflected in the share prices. I will leave you to do the homework.
Harworth (LON:HWG) Portmeirion (LON:PMP) despite the recent share price rise, Headlam (LON:HEAD) and Forterra (LON:FORT) stand out as especially vulnerable at current prices.
Appreciate it isn’t a typical small cap share but is anyone following the Thomaslloyd Energy Impact Trust (LON:TLEI) situation. I hold having bought at the IPO last year as focused on the renewable sector with a decent pipeline of projects in Asia & Far East where renewables are sorely needed to reduce dependence on fossil fuels (coal specifically). Yesterday’s RNS and the follow up one today don’t look good to me. I fear Thomaslloyd Energy Impact Trust (LON:TLEI) could turn out to be an absolute dud. Relatively unusual for an IT but the omens are not good. If it comes back from suspension at anyway near 30% below the IPO price I will exit but I fear a complete loss. One problem tends to be a forerunner of a lot worse!
Will you be covering Anglo-Eastern Plantations (LON: AEP) ? I believe they put out a TU last Friday 21st April
hVIVO (LON:HVO)
Good set of results as expected from the recent TU. Net cash up a bit more than I thought at £28.5m - now makes up 20% of the market cap (remember this is own funds - any cancelled contracts forfeit the deposit).
Guiding towards £55m revenues (100% visibility/contracted) so around £10-11m profits. Paying £3m dividend but still expected to have closing net cash of between £30 & £35m (30%+ of market cap) at Y/E.
Given the 100% visibility I suspect the £55m revenue guidance is being set up for a beat too.
Brokers think it's worth somewhere between 26p & 35p given global leading position, expansion of margins and growth in challenge study models and Asia expansion. My own calcs give me something north of 30p target. I reckon a sale achieves circa £200m+cash so around twice current price or 34p equiv, so that also fits my model.
Not unsurprising to see them write down non core assets. You can be pretty certain that if and when the market turns both Disease in motion and Imutex spin outs will be revived but I have those discounted to zero in my own models anyway, so neither here nor there.
Petrotal (LON:PTAL) excellent update again from these guys and still look cheap as chips to me.
Sticking with guidance but suspect a beat is on the way later in the year given update. Mar and Apr were consistently above 20k bopd (well in excess of guidance) and more wells coming on stream. Add to that the reopening of the pipeline and that gives them two routes of delivery (barging + pipeline) which mitigates risk of low river flow/logistics etc.
They basically now have net $100m of net cash (after receivables/payables unwind over next month or so) are paying a cash dividend of over 10% and are buying back 10% of the company shares.
Even after that they are expected to have a net cash position of $200m by y/e. (current market cap is $500m)
Free cash flow looks like $160-180m p/a after capex and probably going higher (given they are $30m ahead of consensus in the first 3 months). So even with effective yields of 13%+ we get a company with net $200m on its balance sheet, trading on 2* FCF (adjusted for net cash on balance sheet).
Produces 21,500 bopd with wells constrained due to delivery constraints, so it's not a declining production profile either, and more than 10 years of production left with reserves increasing.
Have to say I'm surprised they are not trading higher. Broker has 150p target for what that's worth but to be fair I am struggling not to get well over 100p myself. Happy to wait though now I'm paid 10% a year in the interim.
Micro cap battery recycling and bettery minerals miner Technology Minerals (LON:TM1) are ticking up on news (I hold). On Stocko it has shares in issue numbers falling by c33% in the TTM. Any ideas why? How can you predict this number without news of consolidation of the shares?
Bid Targets
Feels like the private equity boys are moving in for the kill now on companies that the market is undervaluing .
Sureserve was a no brainer for a buyer with make making profits and a huge order book .
Few of mine I reckon bid targets based on a “would you buy them if you had the money” question .
Vertu motors - total no brainer as the anomaly of freehold more than valuation plus cash plus profits plus good business .
Somero - probably bid target , cash , good business , it would pay for itself in 6-7 years , and great IP , plus there’s possibility to grow .
Sanderson Design group - literally has a “licence” to print money as it’s license deals are proving .
Any other no brainer bid targets out there ?
I like to think that if VTU gets an offer it will finally raise thd SP to its truer value and Robert F would still refuse it. Recent acquisitions are just the start of the sector consolidation.
The takeover which hasn't happened that surprises me is Angle (LON:AGL) . I would have thought a company like Agilent Technologies (NYQ:A) would have been a good fit, but there are others too. Agilent's been shifting more and more into diagnostics and their own PL-1 test could be compromised by Angle's tech. Guess Angle's just too small to be noticed State side.
Nice post - I think National Express (LON:NEX) is one that is beaten down and could be snapped up. Likely by a larger European travel company or even a Chinese state owned company looking to gain a foothold in the UK coach market
How about GB Group?
PE have lots of money and there is a chase to find assets, so in a lot of cases bids are becoming competitive. Usually PE plays in the private space but the level of competition for private company assets means that deals are becoming expensive. Counter that with complete lack of liquidity in the UK market means PE find they can purchase good public companies cheaper than it will cost them in the private market. Therefore I suspect there will be multiple take outs of companies over the coming year unless sentiment/liquidity changes quickly.
It's a bad situation for the UK public market to find itself in medium to longer term though. You can see this playing out in the fact that since 2003 the number of UK premium/standard listings has shrunk from about 2k to 1k. LSE and Govt. feel a bit like they are asleep at the wheel on this topic.
Agree fully .
The valuations of private sector acquisitions are basically much higher than stock market valuations .
If you are a PE or private buyers with cash in the bank you pretty much are paid to deploy it, so prime undervalued assets are going to get snapped up especially for PE who will hold for 5 years plus .
Tandem group another one that is just a silly price, real estate alone probably worth more than market cap and has a huge new warehouse that can be used if you wanted to merge in existing operations .
Market price of tandem probably going sideways / down as they are going to have a tough year. But real business owners with a 5-10 year view would get hold of a cracking new facility and an ok business .
Strip out the board of directors and top management and replace with sensible salaries and you add another million quid profit right away .
I was with a large PE house the other day and the senior guys were complaining about the competitiveness in the bidding process. Valuations in the private sector have got more realistic but at the same time there are too many players chasing the same companies. As a result companies may give a PE preferred bidder status but whereas that previously led to a transaction now they are getting gazumped!
No real wonder they are turning more to public markets as the valuation difference is now stark enough to offset revealing their hand in a public environment.
But would you want your best investments to be taken out for a quick 30%? And then they come back onto the market a few years later at the top of the cycle and loaded down with debt. This already happened to Somero Enterprises (LON:SOM) a few years back and the business almost went under as a result.
For me the answer is no. What I actually want is to buy a business that gives me long term structural growth in its market of 10-12% p/a at a relatively low/reasonable valuation and sit on it for several years and get a double effect of growth plus a bit of a re-rating to achieve my 15%pa target. I'd like to get an income of at least 3% whilst I wait.
With these businesses getting taken out at low points in the cycle I'm left with a much smaller pool to choose from and of lower medium term quality, so I have to trade in and out and try and move with the hot money, which doesn't suit my style really.
Not great but not terminal yet for the UK market but something needs to be done quickly.
I would happily sell my whole portfolio for quick 30% profit and start over from scratch !!! hmmm being over 50 perhaps i would say better off putting all the proceeeds in premium bonds and going down the pub.
I'm 100% with you. I always struggle with the sell decision, so it's nice to have the decision made for me, then I get the fun of looking for the next buy. Or as you say, invest them wisely in a real asset down the pub!
Todays rumour is Watches of Switzerland (LON:WOSG)
I’d be very careful, NT mentioned it in his latest blog then Baron Investments tweeted today rumours of a bid…..but nothing to support that. Do think there’s a lot of P&D strategies in play atm due to very low volumes and liquidity, be careful out there!.
Bid rumours regarding Watches of Switzerland (LON:WOSG)
Good morning Paul, hope you had a good rest last week, there's certainly a lot for Graham and Paul to plought through today. I'm wondering about CMC Markets (LON:CMCX) , something for Wednesday perhaps, as it is another of those tiny float AIM companies. The Founder has a lot of skin in the game and this may be a reason for the share performance, would this be typical? Peter Crudas has an interesting CV, https://www.celebritynetworth.... this is a link for those who want to learn more.
Silver
CMCX - main market , market cap £495m
Oops! Guessed it was an AIM without thinking. Still has a tiny float though, a bit of a worry when one is underwater.
I watched a management webinar a few years back and sold my shares immediately. Let us just say they did not impress me.
CMC and Ig Index both make incredibly high profit margins. In a way good but it also means they are very vulnerable to new entrants.
I contribute to IG group (LON:IGG) profits by 'over trading' and losing 'spread bets', but at least hold so might get some peanuts back.
Seems to be clawing back recent 100p drop.
Finally some positive news from Eckoh (LON:ECK) ahead of expectations and rolling out a new call recording upgrade to their customers...
Also good to see that they define their understanding of current expectations in the RNS
this one is a competitor of PCI- PAL (LON:PCIP) which has been reviewed here a few times
I hold Eckoh (LON:ECK)
A strong set of results from Iofina (LON:IOF) today. Revenue up 8%, gross profit up 47%, net debt down, by the end of Q2 a new production facility is scheduled to be open leading to a "significant step change in production". This is the 5th successive year of record revenue and EBITDA. The bear case is that it is reliant on the spot price of iodine. Would be interested in thoughts from Paul or Graham if you have time.
I second that request. Although it’s in the Basic Materials sector that I know the guys lean away from, it’s quite specialised and an interesting company and so would be useful to read any thoughts they have on it.
Iofina (LON:IOF) - iodine used in many products - including radiation tablets - which I was looking for on Sunday when the phone shook me out of my nap.
Is that a 'cup and handle' I see before me - albeit an old one. Perhaps wait for 35p.
Hi Caduceus
Here is the link you asked for yesterday, I posted last night but appreciate that you might not have seen
https://www.dividenddata.co.uk...
Tommy
Interesting goings on at Sulnox (OFEX:SNOX) today with one of its shareholders ‘RemNOx’ demanding a general meeting. I saw Sulnox (OFEX:SNOX) present at Mello in Chiswick last year and have a very small position ( even smaller than when I first started I might add). The idea behind the product is a great one but the company does not seem to have been able to capitalise on it, which is a pity. The work they were doing in Africa would have had great benefit for the population there too.
“The Requisition requires the directors of the Company to convene a GM to consider ordinary shareholder resolutions to remove Chairman, Radu Florescu, as a director of the Company and appoint three new directors to the Board. In addition, the Requisition includes a special shareholder resolution to remove CEO, Ben Richardson, from his position with the Company. In accordance with the Act, the Company is required to call a GM to consider this resolution within 21 days of receipt of the Requisition and to provide for the GM to be held not more than 28 days after the date of the notice of such meeting.”
I spoke to Sulnox (OFEX:SNOX) at Mello. I like events like Mello for speaking to companies that I wouldn't normally consider and seeing if I learn something interesting or even find something I could be invested in (as an aside, and as topic of conversation today, hVIVO (LON:HVO) is such a realisation...I like new CEO Mo too...thought Open Orphan was a Cathal nonsense crapshoot...however I think hvivo is overvalued and lacks a clear enough expansion plan to justify high expectations so its a wait and see for me...my guess is this turns into a good yield stock if Mo is sensible as going for high growth ain't possible).
Let me give the Sulnox product the benefit of the doubt. Tho that still makes it uncertain that they can make a market in the product...again let's give them the benefit of the doubt that they will...
I would still be worried that shareholders today may not see the benefit. Even before the RemNOx options nonsense stuff unfolded the corporate identity/jacket of the company was a bit thin. Its just a layer in a multi-layer venture with a number of people and cos floating around it. The people in the background could commit/source funding to Sulnox if they wanted to. I'd worry that the current jacket is flimsy and easily discarded (even intended to be) if commerciality comes into sight...and the returns from shedding accrue to nearby insiders rather than current shareholders. Maybe one of those annoying delisting or just a cheap takeout.
Hi Mojomogoz. I don't agree with you about hVIVO (LON:HVO) and have just bought some. As far as their expansions goes, they have already taken multiple actions to increase profits such as 1) Increase capacity for higher numbers of trial patents per clinical trial as requested by their customers. 2) Increase capacity so as to be able to run multiple different clinical trials at the same time. 3) New testing services. 4) Introduced ability to do trials for types of infection that they were previously unable to carry out. I expect forecast upgrades in due course.
On a lighter note, please can you enlighten us all by informing us what "A Cathal nonsense crapshoot" is?
Hi WarrantStar, re "Cathal nonsense crapshoot' -> I didn't like old CEO of Open Orphan. I believe he's a total huckster and hype guy. IMO Open Orphan progressed very differently from what he sold would happen. Some might say that was navigational skill...maybe...I think it was probably more luck. A lot of people like the guy so I'm not expecting agreement. Maybe I just don't see the genius!
But I do (to my surprise based on origin) like hVIVO (LON:HVO) and its CEO. My reservation is around valuation and growth. I'm a little out of date and need to catch up with news today so consider my comment here as a bit drive by rather than informed...
IMO hVIVO can earn really well from established infrastructure and capabilities and once the capability is physically established it will have a fairly long enduring and low cost to maintain moat around the capability -> nice high RoC and can support high div payout and earnings growth thro price inflation (likely higher in testing services than broad economy) and share buybacks.
But I see expanding capability has quite high degree of difficulty. It's not the basic cost of facilities but sourcing the 'resources' needed to support expansion and by that I mean mostly the pure and non exposed humans needed for testing (i've forgotten the technical terms they use for their 'guinea pigs')...and solving that difficulty likely feeds back to high hurdles to expansion and relatively high initial capital costs as they can't just incrementally expand infrastructure they have but need to set up new geographically specific hVIVO ecosystems.
So the above may be well off beam...but that is the nature of my hesitation on price and growth. I see modest growth and high capital return as the right route for this company. Its a nice business now...but I would want to buy (based on my views) at lower price
Agree with you entirely about Cathal Friel…. His last one I recall was Fastnet O&G, on which he shafted investors with his jam tomorrow Friel Spiel.
Hi Mojo
"But I see expanding capability has quite high degree of difficulty."
Fundamentally this is where I think you are wrong in your thinking.
1) Their strategy around capacity has been done as a hub and spoke model. This means that once they run out of room they can add a spoke at relatively little cost and in a few months. That in turn means they can first sign the contract and collect the 20% non refundable deposit and then commit the capex to increasing scale. It's quite neat. The hub is the really expensive bit and that would be hard to replicate, but there is no need.
2) Expansion of resources : hVIVO (LON:HVO) already have many thousands of signed up volunteers. You are correct that when your business is operating on a single challenge study this resource collection is expensive and eats margins because many of those volunteers have already been exposed and can't be used. However, when you expand into multiple challenge study types those already signed but redundant resources can be used in the new challenge studies. Again not all will qualify but some will and there will be no volunteer recruitment cost.
So actually the expansion into multiple challenge study types does two things. (1) It provides good future growth for the business and (2) it lowers the cost of resources so margins go up.
So in essence, no you don't need to set up geographically specific hVIVO ecosystems to expand. Hub and Spoke model - done from UK and actually resource costs are margin enhancing via expansion of study types.
Thus the business is scalable and at increasing margins, though I'd say margins will cap out in the early 20%'s medium term (as you still have to pay the volunteers for the actual study).
We've seen this effect already with margins rising to around 17%. Current capacity supports revenue of around £70m so plenty of room. Net cash should be around £33m.
Edit : I'd also note that the very same dynamics provide a moat to the business against competitors. Pharma want certainty about volunteer recruitment quality and hVIVO (LON:HVO) can provide that. Expensive for someone to come in from scratch and replicate. Plus the hub is expensive to replicate and would need full regulatory certification etc.
Just thought I would add an FY TA from Activeops (LON:AOM) to the mix this morning. It's a £42m EV ssas based "management process automation (MPA) software company", and it says it's ahead and has managed to make an ebitda profit & secure a positive ebitda run rate.
Paul S last (rightly) commented that it floated recently at a gross overvaluation (around 185p) and was loss making. It's a lot cheaper now, and hasn't diluted. It's a bit of Paul Hill fav.
I don't hold but it sneaked onto my radar recently. Thoughts welcome.
Hmm - Activeops (LON:AOM) look quite good value actually. As you say heavily overpriced at IPO but strip out £18m of cash and you're paying £40m for £22m of ARR so less than 2* sales, which given the product (looks to have a strong reputation) and market sector looks pretty decent value.
A large chunk of that cash belongs to customers though in the form of advance payments (not disclosed in the TU) - and after stripping out the intangibles, the balance sheet is not as strong as that headline cash number implies.
They don't capitalise as much internal development cost as some others in fairness, but they do capitalise a growing chunk (massive judgment within their control, and not disclosed in the TU). Throw in the share option dilution, this company is not really profitable at all. I see the share price fading when we get the proper year end accounts, this trading update is just the sugar coating in my view.
I like the concept of this business, I just am to be persuaded yet there is a potential return on investment.
Associated British Foods (LON:ABF) - too big for this forum, but some good read across, looks like a decent set of results to me. Primark still growing and in the US. Looks promising to me from a growth perspective and even more importantly, looks very resilient given current market conditions.
Yes that was my reading too - yet the market doesn't agree! big movement down this morning. Nothing makes sense anymore....
ABF is down 5% and WTE is up 4%.
customers prefer cutting on clothing rather than travelling. Except in luxury goods.
LVMH became the biggest European company at 500 billion.
Hope hVIVO (LON:HVO) gets covered today. 0.45p special dividend. Non core assets kitchen sinked. Is the Co. being prepared for a sale or a US listing? Liberum have raised tp to 26.3p
Strikes me a serious CEO and CFO leading the turnaround and clearly the pipeline looks attractive- all be it USA lead.
Agreed it’s positive they concentrate on the core business. Writing down the non core assets now will allow for positive updates in the future hopefully
My morning smallcap tweet: It's the words that MrC rejects that makes Smallcap Sweep the best
Hornby (LON:HRN) Guild Esports (LON:GILD) McBride (LON:MCB) Activeops (LON:AOM) NAHL (LON:NAH) Sigmaroc (LON:SRC) Deltex Medical (LON:DEMG) Fireangel Safety Technology (LON:FA.) Smoove (LON:SMV) Mobile Tornado (LON:MBT) Redcentric (LON:RCN) Loungers (LON:LGRS) Superdry (LON:SDRY) Eckoh (LON:ECK) Spectra Systems (LON:SPSY), Iwg (LON:IWG), Trakm8 Holdings (LON:TRAK)
◄Hornby (HRN)► guides FY-Mar behind internal budgets. Expects modest underlying pretax loss. Outlook cautious. [SP=25 Cap=42m]
◄Guild Esports (GILD)► £4.5m three-year global sponsorship deal with Bitstamp will end in Jan, a year early by 'mutual agreement'. Really? [SP=1.05 Cap=5m]
◄McBride (MCB)► guides FY-June adj operating profit and pretax loss to be between £5m and £10m ahead of market expectations. Cites new business wins combined with favourable demand levels for private label products. [SP=28.2 Cap=49m]
◄ActiveOps (AOM)► guides FY-Mar ahead of market expectations with rev £25m+ and positive adj EBITDA. F/C are £24.6-25.1m and -£0.5m resp. Cites "good uptake of the newly launched CaseWorkiQ solution, as well as securing multiple new wins and contract expansions for its existing software solutions, ControliQ and WorkiQ". [SP=74 Cap=53m]
◄NAHL (NAH)► sells Homeward Legal for £150k = book value. Gets only £30k up front and rest over 2 years! Homeward rev was £1.2m and op profit £13k. [SP=47.16 Cap=22m]. I hold.
◄SigmaRoc (SRC)► AGM stmt: Q1 slightly ahead of management expectations but guides FY in line. [SP=54.2 Cap=376m]. I hold.
◄Deltex Medical (DEMG)► £0.25m bridging loan from chmn to help fund working capital associated with accelerated production of new monitor to be launched in June. [SP=1.29 Cap=9m]
◄FireAngel Safety Technology (FA.)► returns to form with warning of FY-Dec 2023 rev slightly below F/C but EBITDA materially below market expectations. Blames component shortages and an expected contract not gained yet. [SP=11.5 Cap=21m]
◄Smoove (SMV)► the alternative to PEXA's bid approach announced yesterday not proceeding. [SP=44 Cap=25m]
◄Mobile Tornado (MBT)► reseller get order for 200 (initially) user licences for push-to-talk over cellular comms. [SP=1.95 Cap=8m]
◄Redcentric (RCN)► guides FY-Mar rev up 52% and adj EBITDA £24.8m (£23.7m). Implies latter is a miss due to higher electricity costs (by of c.£1.7m) and higher than expected software license costs (by £0.7m). [SP=121.42 Cap=190m]
◄Loungers (LGRS)► guides FY-Apr rev up 20% and LFL up 7%. EBITDA broadly in line with market expectations. "New roadside concept, Brightside, has opened well". [SP=206 Cap=213m]
◄Superdry (SDRY)► lender to increase the borrowing availability level until completion of the previously announced sale of the APAC business. [SP=85.7 Cap=70m]
◄Eckoh (ECK)► guides FY-Mar adj op profit at least £7.6m, slightly ahead of market expectations of £7.5m. [SP=33 Cap=96m]
◄Spectra Systems (SPSY)► $885k of additional, high margin revenue for currently in-use sensors with a central bank contract. Mostly in 2025-2027. [SP=165.2 Cap=74m]. I hold.
In line: IWG, TRAK
great work as usual, always appreciated!
Comprehensive update from Sigmaroc (LON:SRC).
Headwinds in some areas notably housing construction offset by operations in industrial minerals with continued growth in demand across chemical, environmental, and agricultural markets, as well as metals & mining. LFL volumes currently ahead of last year, albeit marginally. Confident outlook.
I am an admirer of the entrepreneurial management team that is making good progress in growing what I believe will be a substantial pan northern European aggregates business.
I hold.
Excellent podcast from SRC this morning re trading update. Very impressed with management who have good shareholdings and full knowledge of business. I hold
Focusrite (LON:TUNE)
Half year results in line with March TU and margins holding up before a promised stronger H2. I couldn’t escape the feeling that confidence in the full year outlook was not absolute - revenue growth expected to be in line with expectations but no word on profit, while costs remain elevated to support promotion of new lines, on which revenue growth depends. Grateful for the thoughts of others, including Paul or Graham.
Valuation is supportive at 13x PER for a high margin, high return compounder.
Yes. My concern here is that they are putting a lot of faith in new product launches in H2 to make up for slow sales in first half. Even though revenues were down only 7.2%, they were actually down 19% on a constant currency basis and taking acquisitions into account and operating profits down about 30%. I am a long term holder because of the quality of the products and the management and culture, but it has been a trying share to hold. I think it will get punished, but who knows in these markets,
Trading update out from City of London Investment (LON:CLIG) . I hold. Steady as she goes update. Unexciting as usual. However the projected outcome is considerably higher than the forecast on this website, giving a P/E of a bit less than 10. Divi forecast still good. Will never shoot the lights out but I continue to hold.
CTY is a good long term.
I hold MRCH which is similar.
Today there’s a Mello Investment Trust session at 2pm.. always informative and interesting.
City of London Investment (LON:CLIG) and City of London Investment Trust (LON:CTY) are very different propositions.
I do wish one of them would gracefully swallow their pride and amend their name slightly.
I suspect this one is responsible for a few entries in various broker error accounts, although perhaps not in the league of the BA./BAY debacle when it came to compliance having to trawl through hours of recorded phone lines.
Smoove (LON:SMV)
It looks as if we were all so busy discussing the Medica (LON:MGP) bid yesterday that we didn't notice the announcement of the RNS at 11 38 regarding a possible offer for Smoove following news of it at 11 03 from Sky.
It was the Sky readers that had the advantage:
Once again the question of the point at which a company should tell the market of an approach is raised,