Small Cap Value Report (Tue 25 June 2024) - VTU, IGR, PRES. Briefs: FCH, SAE, ORCH, G4M, SAGA, CDGP, ANP, WYN, HUD

Good morning from Paul!
That's it for today, sorry my brain now needs a rest!
I caught up with my backlog of updates for my SCVR summary spreadsheet last night, it's now fully up-to-date. I'm pleased to say we've reported on 537 unique companies here so far in calendar 2024. That rises to almost 650 on a rolling 12-month basis, so really extensive coverage, and I'm always pushing harder to do more!
Here's a screenshot below, for about the last 6 weeks. It's notable how much takeover activity there is (I colour-code takeover approaches in PINK and put them on the left). Also not many profit warnings (in black), other than a recent flurry of five of them. Remember that on the Google Sheet you can hover over any cell and a pop up box appears giving a short summary of the SCVR comment on that company on that day. It's a very useful quick reference tool, to quickly get up to speed on any share we cover here, using CTRL+F and ticker.
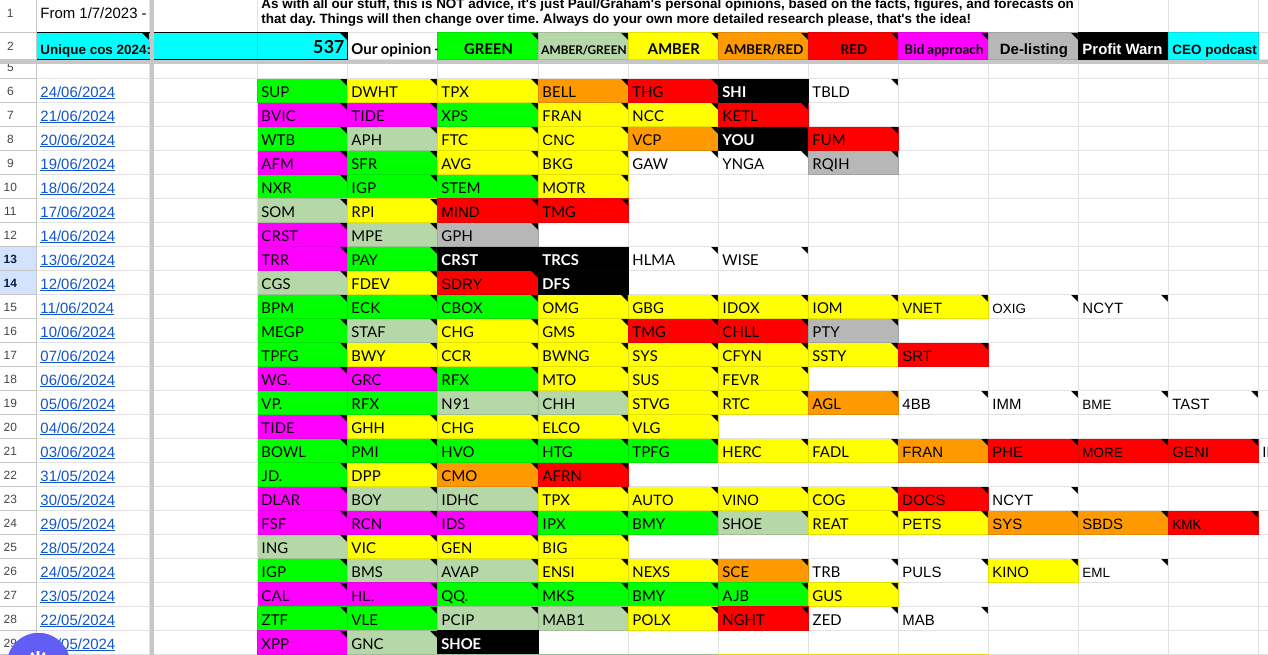
[Note that for the colour-challenged, I now arrange the companies in a left to right, good to bad format. Also if you open the spreadsheet, hovering over each item shows text which includes the colour as a word. I hope that makes it accessible to almost everyone].
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
A manageable workload today, so I'm hoping (not promising!) to catch up on CMCX too - sorry, too tired now, so that will have to wait.
I'm taking my lead from the "most viewed" widget on the home page, so am planning on writing up sections in this order -
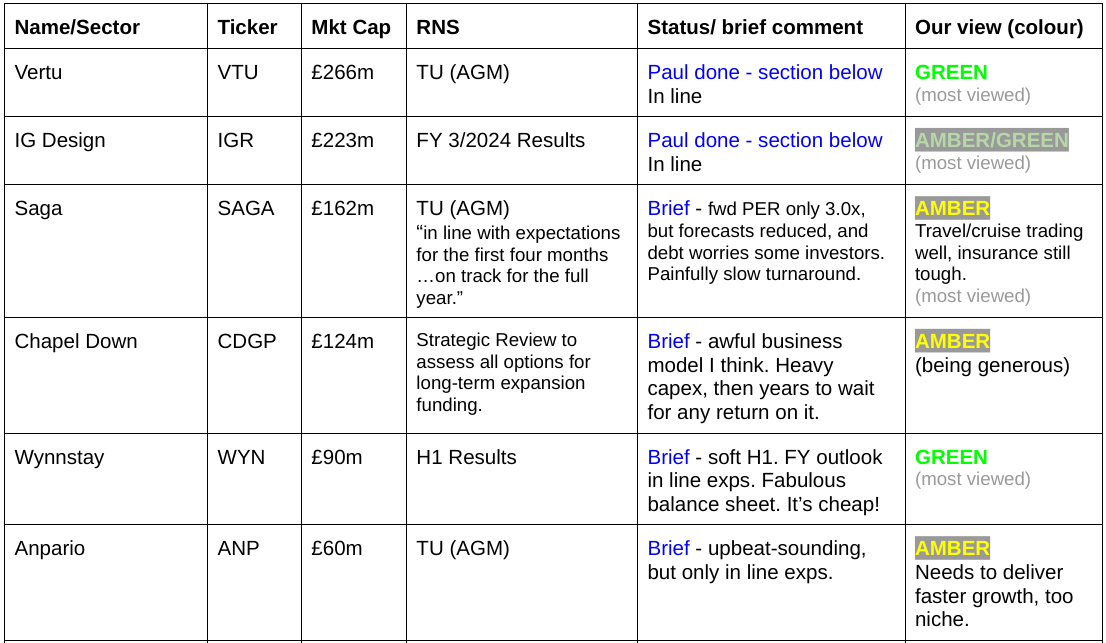
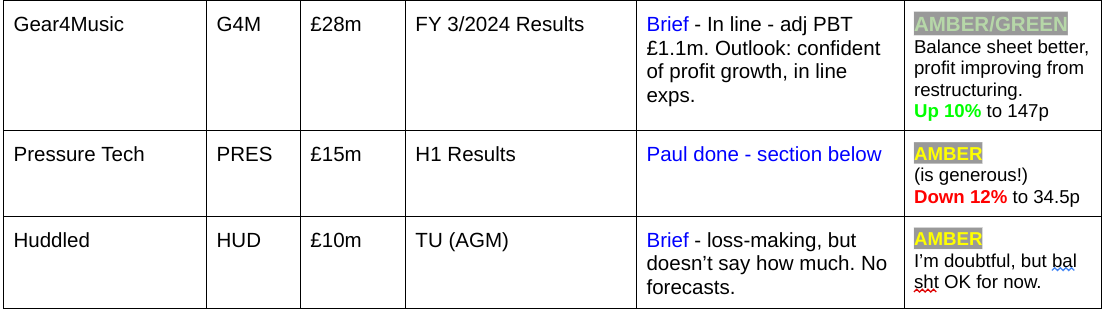
Other mid-morning movers (with news)
Funding Circle Holdings (LON:FCH) - up 10% to 93.4p (£327m) - The newswire says -
British small- and mid-sized enterprises lender agrees to sell its U.S. business for 33 mln pounds ($41.9 mln).
Confusingly it also says -
“The US business contributed losses of £(23)m to the overall Group in 2023, although reported a statutory profit before tax of £7m for the year ended 31 December 2023.”
Says UK ops on track to attain profitability in H2
“The UK business is on track to be profitable in H2, in line with our guidance. Over the medium term we expect net income growth of 15-20% CAGR with PBT margins of >15%.”
If those targets are hit, it would be a massive turnaround from heavily loss-making historical numbers. How credible is a >15% PBT margin?
Readers are discussing this in the comments below, noting that shrewd investors Harwood seem to like it.
Checking through the RNSs this year, its stated strategy is to focus on profitable UK business. It’s doing share buybacks almost every day (£25m total). Interesting balance sheet, with large amounts of net cash.
Paul’s view - it’s a special situation, so needs properly thorough research, but on a quick skim, I can see that this might be interesting to research in more detail, due to the big cash pile, disposing of the loss-making US business, and an indication that the UK business will be moving into profit shortly. So potentially worth you taking a closer look! Let me know what you think.
SIMEC Atlantis Energy (LON:SAE) - up a remarkable +107% to 2.2p (£15m) on publication of (quite late) FY 12/2023 results. A large profit has come entirely from upward revaluation of one of its renewable energy projects. Full accounts reveal accumulated losses of £190m, and a lot more debt (c.£50m) than is revealed in the shorter version issued on the RNS. Care needed here, it looks a special situation that needs thorough research. See reader comments below here.
Orchard Funding (LON:ORCH) - up 14% to 32p (£7m) - initial spike up to 36p this morning has moderated to 32p. Trading update today says;
“management now expect that earnings will exceed current market guidance by over 20%.”
That sounds good, but bear in mind this specialist financing company has a chequered history with various mishaps and a key RNS on 17/5/2024 stated that it intends to de-list because the costs & hassle outweigh the benefits. Shares trade at only a third of NTAV. It also stated in May that dividends would be stopped, so ignore the supposed 11% yield. Very unsatisfactory, looks like the majority shareholder wants to take it private on the cheap. There might be a tender offer, but not stated on what terms. Personally I’m steering clear, as there’s too much uncertainty, and a controlling shareholder at 54% can do whatever he wants.
Summaries
Vertu Motors (LON:VTU) - 79p (pre market) £265m - Trading Update (AGM) [in line] - Paul - GREEN
A reassuring update, in line with expectations so far in FY 2/2025, and for the full year outlook. Valuation remains reasonable, and the tangible asset backing (loads of freehold property) is a stand-out positive, that protects downside risk for investors. Takeover bid the likely outcome, but nothing so far.
IG Design (LON:IGR) - down 2% to 225p (£218m) - FY 3/2024 Results - Paul - AMBER/GREEN
Smashing figures, as expected as its turnaround gathers pace. Further margin improvement is anticipated, although I think the big rise in share price has now factored in a fair bit of the upside, so it might be more tricky for the bull run to continue, at least in the short term maybe? Super balance sheet with plenty of net cash. I'm shifting down from green to AMBER/GREEN, to reflect the very strong share price rise, so it's not as obviously undervalued now, as it was last year.
Pressure Technologies (LON:PRES) - down 13% to 34p (£13m) - Interim Results - Paul - AMBER
Underwhelming H1 results and outlook. Fund managers are trying to engineer a turnaround & restructuring, but it looks hard going. Balance sheet needs more liquidity I think. Risk:reward just doesn't appeal to me, as there's too much guesswork. Also I'm puzzled as to why they want to sell off the division that's performing better, and keep the problem bit?
Paul’s Section:
Vertu Motors (LON:VTU)
79p (pre market) £265m - Trading Update (AGM) [in line] - Paul - GREEN
Vertu Motors, a leading UK automotive retailer with a network of 189 sales and aftersales outlets, is pleased to announce the following update with regards to the three-month period to 31 May 2024 (the "Period"). The Board anticipates that full year results for FY25 will be in line with current market expectations.
I won’t regurgitate all the detail, see the RNS for that.
This bit below caught my eye, and is an interesting point, as it becomes increasingly clear that a lot of the public do not want electric vehicles (EVs), and the interesting unintended consequences that could boost used values of conventional cars maybe -
“The Board has been encouraged by the trading results for the Period. The Zero Emission Mandate to force the uptake of zero emission vehicles sold in the UK has the potential to create volatility in the new car market. This may include reduced supply of new petrol and diesel cars in the coming periods and would lead to a strengthening of petrol and diesel used car values.”
Aftersales (servicing and warranty repairs) stands out as the area management sound most upbeat about, eg -
“The Group's high margin aftersales businesses have strong growth potential due to additional resource levels and Group strategies around customer retention and increased average invoice value per customer.”
More acquisitions on the way, I wonder? -
“A number of growth opportunities are being evaluated against the Group's capital allocation metrics. The franchised retail market remains very fragmented with the Group representing around 5% of the sector.”
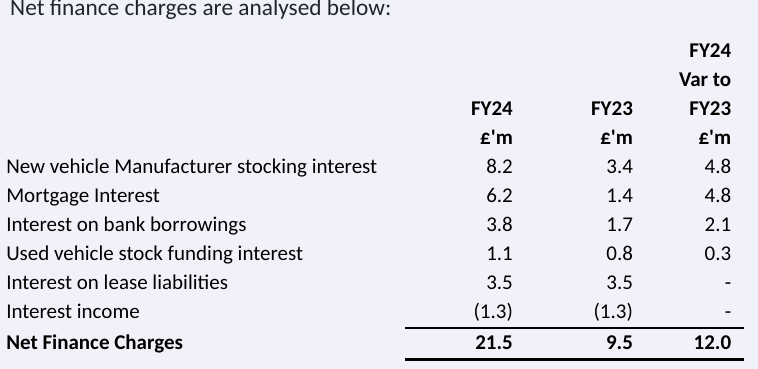
Stocking loans - are not mentioned in today’s update, but I always flag this point when talking about car dealers. Higher interest rates means everyone in the sector is now paying much more in finance costs, to fund their inventories through stocking loans. Eg this table below comes from VTU’s FY 2/2024 results, illustrating the point, with finance costs having more than doubled -
Paul’s opinion - this is a reassuring update. I’m amazed that nobody has bid for VTU, as so many others in the sector have been taken over. Investors have the added reassurance of a very strong balance sheet at VTU, it’s a property company as well as a car dealers, which should mean this share is strongly underpinned.
Management seem good, and on top of the detail, which is essential in a low margin, competitive sector. Although as with any company, none of us really know what's going on behind the scenes.
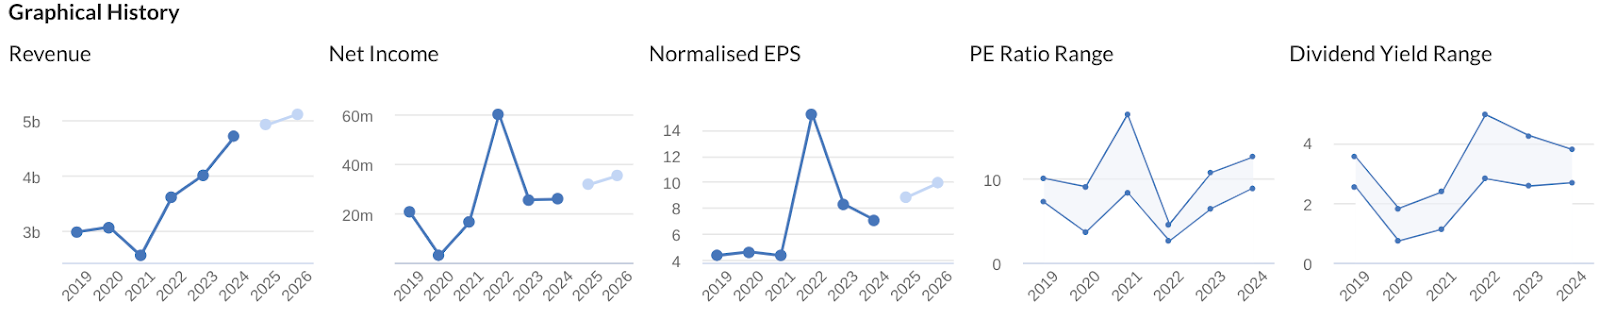
You can see from the graphs below how the pandemic distorted trading, but it looks as if we might now be back at a steady state where EPS is almost double pre-pandemic.
I can’t decide whether to stick with amber/green from last time, or just go with green? I think given the balance sheet strength, and a reassuring update today, combined with a fairly modest valuation and takeover bid potential, it should probably be GREEN.
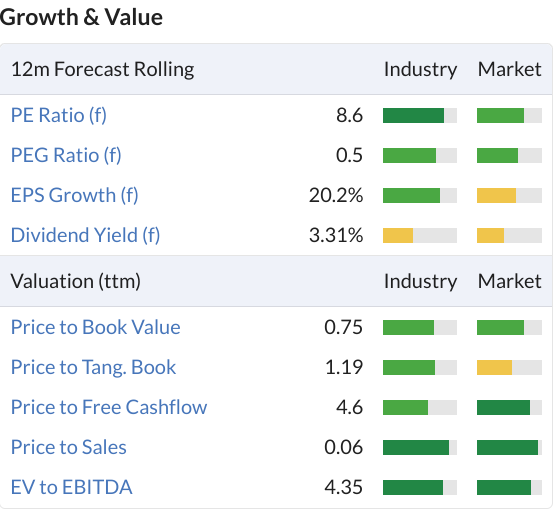
Attractive valuation scores below, but this sector tends not to achieve valuations above a PER of c.10x most of the time -
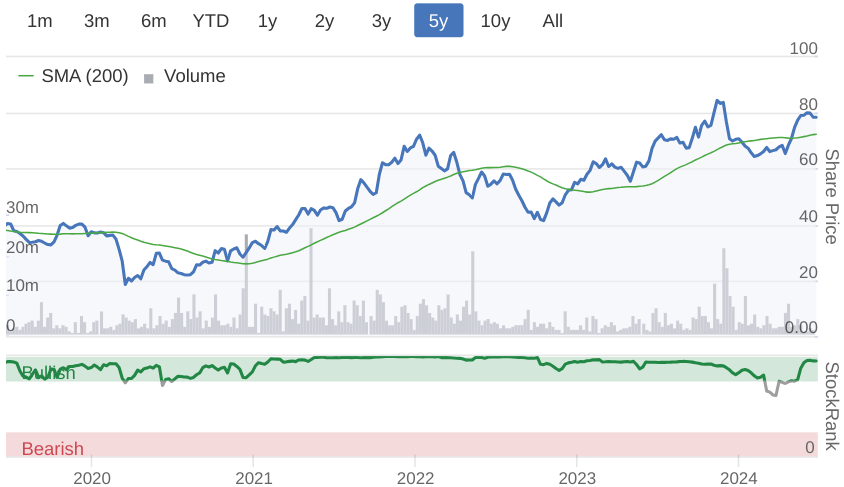
Share price over 5 years has been resilient, given that 2021-23 in particular was a nasty bear market for small caps -
IG Design (LON:IGR)
Down 2% to 225p (£218m) - FY 3/2024 Results - Paul - AMBER/GREEN
IG Design Group plc, one of the world's leading designers, innovators and manufacturers across various celebration and creative categories announces its audited results for the year ended 31 March 2024.
Second successful year in the three-year turnaround journey, with improving operational efficiency and simplification of the business
Impressive adj profit growth, although note the adjustments to EPS seem very large, I’ll look into that - OK it’s due to a large taxation credit, so we need to adjust that out and hence ignore the 36.6c statutory EPS figure, since the 16.3c adj EPS is more realistic on a normalised tax charge -
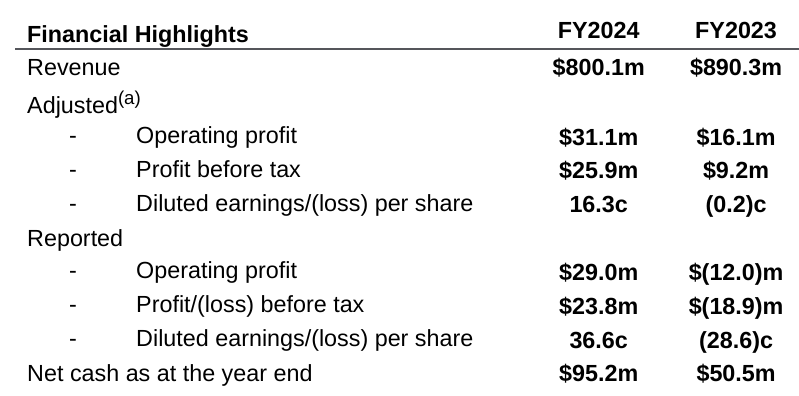
Dividing the 16.3c by 1.27, to get from US dollars to sterling, gives 12.8p, so at 225p the PER is 17.6x, which looks up with events. Maybe that’s why the share price has slipped slightly so far this morning on a bit of profit-taking by the looks of it. Although not much volume has been printed so far today, only about £600k-worth of shares traded (plus whatever orders are being worked in the background - larger trades get printed later, with a delay).
Margin improvement is what the strategy is all about, and it’s working. Although this operating margin is still very low, and I imagine things like wrapping paper are never going to achieve good profit margins. Also as we’ve seen in the past with IGR, it doesn’t take much to go wrong (eg delays & costs in the supply chain) to cause havoc & ruin profitability - since seasonal products are worthless if they’re not delivered to customers well in advance of say Christmas, Easter, etc. So it’s not a very good business model in my opinion, so I would never pay a high PER for this share.
“Adjusted operating profit margin rose to 3.9%, up 210 bps on prior year”
Outlook - if IGR achieves the step up in operating margin set out here to 4.5%, then 6%, then I think this bull run in the shares could continue -
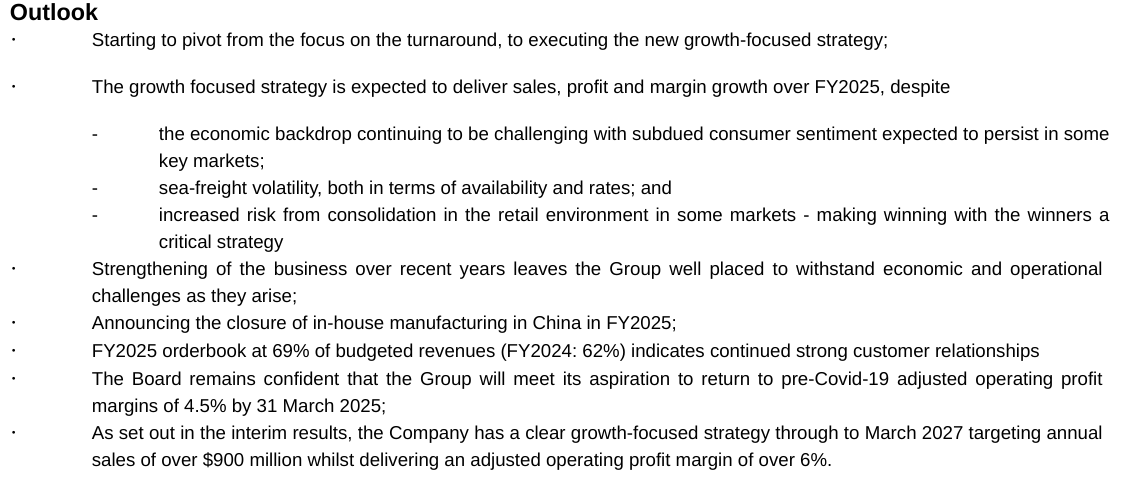
Crunching the numbers, for FY 3/2024 IGR achieved a 3.9% operating margin at $31m.
It’s guiding 4.5% for this year, FY 3/2025, so that would raise operating profit from $31m to $36m (assuming unchanged revenues).
The medium term guidance of $900m revenues and operating margin of at least 6% would be $54m adj operating profit, up 74% on FY 3/2024 actual - pretty good.
In EPS terms, I calculate it like this - $54m adj operating profit target, less say $5m finance charges = $49m adj PBT. Take off 25% corporation tax = $36.8m PAT target. Divide by 97m shares = 37.9 cents, divide by 1.27 = 29.8p. Put that on a PER of say 10-15, gives me a future share price target (if things go well, and targets are achieved) of 298p - 447p. That compares with a current share price of 225p. Hence I get an upside case of 32% to 99% over a two year period. Not bad, but I would want to discount that upside, to allow for any mishaps. There’s no guarantee it will get to 6% operating margin, as it’s struggled in the past to get to, let alone exceed, 5%.
Finance costs are below the operating profit line. Here, finance costs were $5.2m, fairly significant, as it has to use bank facilities to finance peak working capital periods.
Balance sheet - the considerable balance sheet strength, combined with the good chance of a trading turnaround, is why I chose IGR for my 2024 top 20 shares ideas list. IGR only uses bank debt at seasonal working capital peaks, and the year end 3/2024 position was a tremendous $95m net cash.
NAV was $369m at 3/2024, less intangible assets of $75m, gives a healthy NTAV of $294m.
Overall, I'm very happy with the balance sheet, and I reckon dilution or insolvency risks are very low.
Dividends - none declared. I think dividends could be reinstated, as IGR has the financial capacity to resume divis.
Sure enough, Canaccord is forecasting divis resuming this new year FY 3/2025, with 5p, rising to 10p by 3/2027.
That’s an OK yield nothing special, at 2.2% rising to 4.4%.
Cashflow statement - looks great at first sight, but remember there are hefty lease payments further down. The $43m increase in the cash pile has almost all come from a favourable reduction in inventories of $40m. That’s a one-off, and could even reverse a bit if revenues start rising again.
So I’m putting a question mark over cash generation, which doesn’t actually look as good as I was expecting.
Going concern statement is clean, as I would expect given the balance sheet strength.
Paul’s opinion - this is a good turnaround, and that’s been reflected in an excellent move up in the share price.
Outlook also looks good, with further increases in operating margins anticipated - which, if that is successfully achieved, could propel this share higher.
We’ve been green on this share on the previous 3 occasions it’s been reviewed here. However, given the big rise in share price, I feel the value is less compelling now. Hence I’m shifting down a gear to AMBER/GREEN due to the share price having gone up a lot. It feels to me as if the low-hanging fruit has now been enjoyed by shareholders, and further gains might require more patience, but who knows, anything could happen to share prices, as you know!
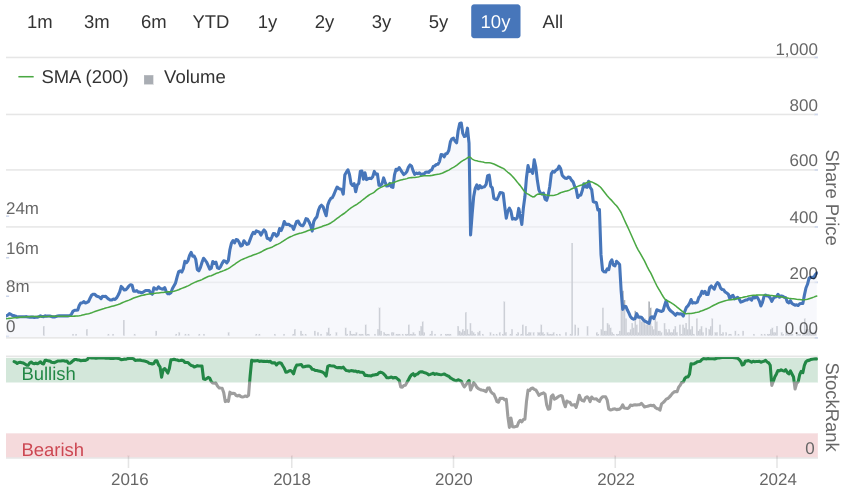
Looking at the 10-year chart below, it was de-rated from a growth company to a value share, when all the company-specific problems hit in late 2021. Now that recovery is well progressed, logically this share could have further to run upwards. Although I think supply chain problems in 2021 and 2022 showed the vulnerabilities in the business model. I'm not convinced it will get back to a growth company valuation any time soon. Also note that the number of shares in issue has steadily risen from c.66m in 2018 to 97m now, so that needs to be taken into account when looking at long-term charts.
Anyway, all told, I think there's probably more upside on this share over time, so I'm moderately positive at AMBER/GREEN. I might add it to my buy the dips list, if it drifts down to make risk:reward more attractive, possibly. Anyway, I'm glad we spotted the valuation anomaly last year, which has produced a good gain so far.
Pressure Technologies (LON:PRES)
Down 13% to 34p (£13m) - Interim Results - Paul - AMBER
This is another special situation, where Harwood, Schroders, and Peter Gyllenhammar combined control 57%. They rescued it financially, and are hoping to encourage a turnaround and disposal. Harwood have talked about this one in webinars, it’s quite interesting, and could have upside maybe. Although I always bear in mind that these guys are high & dry, with big illiquid positions, so they have to try and resolve the problems, whereas you and I can just hit the sell button any time we like (providing its not too large a position) and walk away. That’s a massive advantage for private investors vs fund managers, and it’s one of the reasons I never put money in small cap funds - because fund managers can’t ditch their mistakes, whereas on my own, I can. Also I get much better results than any small caps fund! (roughly 19% pa compounded since 2012). And I enjoy picking the stocks myself, and learning from the whole process continually. That said, I’m a great admirer of Harwood, who are seriously good at what they do, hence it’s always worth sitting up and paying attention to what they’re buying. Anyway, back to PRES.
H1 results to 3/2024 - the quick version is, not very good. Adj operating loss of £(0.7)m, worse by £200k than H1 LY. And they’ll be finance costs to come off that, of £238k, so the adj PBT in H1 is just over £(0.9)m.
Balance sheet looks tight for cash, I think it has too much tied up in inventories & receivables, and probably inadequate liquidity. It needs to be better funded, so I’d say dilution risk is probably quite high. Although on the plus side, it does own freehold property.
There’s potentially 5% dilution at 32p per share from warrants, which doesn’t worry me.
Outlook - sounds rather poor for the Chesterfield Cylinders business, better for the other part, which they’re trying to sell -
“During FY24, CSC expects to pass the peak of activity on current high-value defence contract milestones and will seek to re-balance its revenue profile across global defence programmes and the hydrogen energy market, with each of these markets presenting significant opportunities over the medium-term. During this transitional period, CSC revenue is expected to decline on FY23 levels with a consequent reduction in divisional profitability in FY24.
Whilst we expect significantly stronger performance from CSC in the second half of the year, the shortfall in first-half performance will not be fully recovered in the second half, while full-year performance will be further impacted by delayed order placement for new hydrogen storage contracts due to the UK general election, now expected later in FY24.
PMC continues to see increasing demand from its global OEM customers and improving operational performance. The strong first-half result and robust order book provides high confidence in a much-improved full-year FY24 performance for the division. As previously announced, this improved trading environment underpins the Board's decision to divest PMC.
Order books in CSC and PMC underpin the outlook for the Group in the second half of FY24. Given the current divisional trends and performance outlook, we now expect full-year FY24* Adjusted EBITDA to be not less than £1.0 million.
* FY24 outlook includes CSC and PMC, on the basis that PMC is not sold in FY24 and remains a continuing operation”
Paul’s opinion - for me, there’s too much guesswork in trying to assess the value of this share. There doesn’t seem to be anything particularly positive happening, indeed H1 figures look poor. It mentions £1m EBITDA for FY 9/2024, but bear in mind the physical assets depreciation charge is about £1.5m pa, and after interest costs, I reckon that could be a loss of c.£(1)m for FY 9/2024 at the PBT level.
The PMC division has now moved into a modest profit, so why are they trying to sell it? Surely PRES should be hanging on to the better-performing division, not selling it?!
For me this looks like a difficult turnaround, where fund managers are trying to get something done with deals, etc, to extricate themselves from a tricky situation. They might pull it off, and I certainly wouldn’t bet against them, but for me I want better risk:reward to put my own money into speculative turnarounds, and this doesn’t make the grade. As always good luck to holders, I hope it does well for you. The Chesterfield Cylinders business does look interesting, but its track record is so patchy, due to large lumpy contracts. There’s no reason for it to be listed now either.
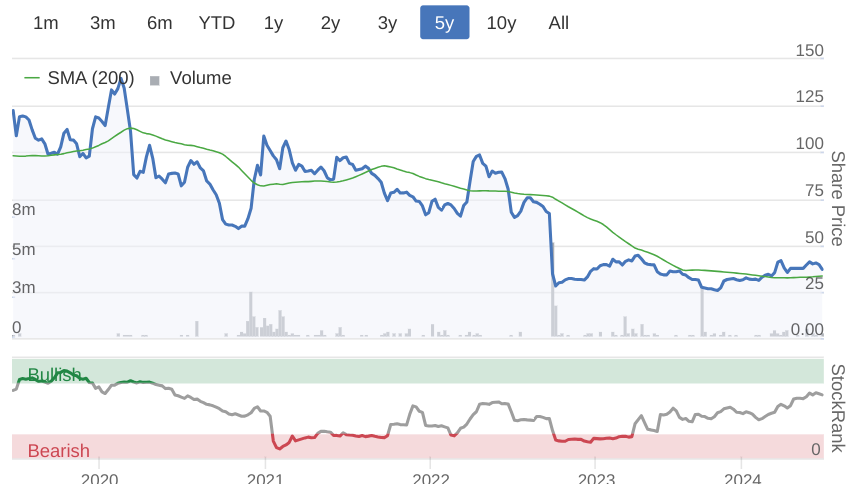
Note the share count has doubled over this 5-year period below, so less upside on the share price -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
Saga (LON:SAGA) - From Grok (AI) - Review for technical patterns
Updated Technical Review of Saga plc (SAGA.L) - October 16, 2025 (Live Data)
Current Date and Time: 04:10 PM BST, October 16, 2025. Live Price: 282.00 GBp (last traded 20 minutes ago) Day’s Change: +9.50 GBp (+3.49%) Volume: 237,931 (vs. Avg 286,587) Bid/Ask: 296.00p / 250.00p (spread 18bps) Day Range: Open 260.50p | High 282.00p | Low 260.50p 52-Week Range: 105.40p – 289.50p Beta: 3.063 | 1Y Volatility: 57.44%
1. LIVE CONFIRMATION: CUP AND HANDLE BREAKOUT FULLY ACTIVATED
2. LIVE INTRADAY BULLISH FLAG (Short-Term)
3. LIVE SUPPORT & RESISTANCE
4. LIVE INDICATORS (Estimated from Price Action)
5. ACCUMULATION PHASE? → NO — MARKUP PHASE
6. FINAL VERDICT: STRONG BULLISH BREAKOUT
ACTION PLAN FOR YOUR 23,231 SHARES
This is one of the strongest technical setups in the FTSE SmallCap — Cup and Handle breakout + insider buying + earnings momentum.
This is not financial advice. Consult a professional advisor.
Anyone any insight into this one?
I just dont see this company surviving
sae, i just dont see it making more revenue that it takes on in debt
Alert triggered on Anpario (LON:ANP) - thought RFK and general fight back against processed foods particularly wheat treatment and sugar maybe a tailwind. Then read Grahams quick summary:
"needs to deliver faster growth, too niche" - and at a market cap of 87m have no argument with that. If a yank wants to buy it go ahead will be happy with 'one that got away' - or not.
Burn't from 2021 which will take a long time to clear from the brain.
They aren't making enough money to cover costs and debt is going up, I cant see how they can survive
Which stock are you talking about?
SIMEC Atlantis Energy (LON:SAE)
Paul many thanks for your SCVR Spread sheets , really useful
Much appreciated
Thank you Darei
No comment on G4M ?
Good news re pension deficits.
"It’s not often that you hear the terms “good news” and “pensions” in the same sentence together, but today I bring you some good news on pensions. Britain’s corporate pension funds have just recorded their biggest surplus ever, according to actuarial consultancy Mercer.
As of last month, if you look at them in aggregate (the state of individual funds will vary), the FTSE 350 defined benefit (DB) pension funds have £79 billion more than they need in order to pay the pensions of their remaining members. That’s the biggest surplus on record, says Mercer."
Source: Bloomberg https://www.bloomberg.com/news...
A subscription site but I believe there are three free article views per month.
Should be good for the insurance companies as these schemes take the opportunity to transfer out while in surplus - Legal & General (LON:LGEN) recently mentioned the huge volume of buyouts expected to take place over next few years.
If DB pension schemes in corporates are recording increasing surpluses... this should also be good for pension consolidators like Legal & General (LON:LGEN) and Phoenix group (LON:PHNX) in their existing portfolio of DBs right? Possibly more surplus cash/assets can be released?
(I hold PHNX in the Boon Fund)
Tortilla Mexican Grill (LON:MEX) : a late RNS today - they are buying an equivalent (smaller) French outfit. Intended to be a springboard for European expansion. My worry is the difficulty of running a French business from a staff standpoint..based on hearsay not personal experience. Be great if you could comment on the deal Paul, especially as its one of your 2024 picks
Cancelled post. Egg on face.
Supreme (LON:SUP)
That was up 10% yesterday on the announcement….. :-)
All the best
Drat. I have been offline for 2 days - got the email this morning and only looked on this morning's SCVR, didn't realise it had been discussed yesterday.
Nightmare being offline these days.
Re Harwood, It was announced yesterday that they have bought Downing's 4% odd stake in National World (LON:NWOR) .
Syncona (LON:SYNC) Currently 112p
Syncona's strategy is to deliver value for shareholders by investing in high-growth potential portfolio companies. Currently, Syncona has seven clinical-stage companies valued at £350.3 million, with seven clinical data read-outs expected this year.
To address what they believe is an undervalued share price, the Board launched a £40 million share buyback on 29 November 2023. This buyback is funded from Syncona's £613.1 million capital pool and will not impact planned investments in clinical-stage assets over the next 24 months. Chair Melanie Gee emphasizes the Board's confidence in the portfolio and the decision to balance capital allocation between investment and the buyback.
The buyback meets Pauls criteria of shares being undervalued on fundamentals, and a strong balance sheet so the company can easily afford the buybacks.
Based on the latest reports, the company has bought back approximately £30 million in shares and is likely to complete the buyback in the next 2-3 months. On checking a recent RNS, the company reports that it has allocated a further £20 million to the programme. So it may take the rest of 2024 to complete the buyback.
Ken Mitchel recently commented on share buybacks, noting that he often uses them as a reason to exit, as the share price often falls afterward. Since Syncona started the buyback 9 months ago, the share price has fluctuated between 110-130p with no positive effect so far.
I'm thinking this could be a decent proposition if one is prepared to hold for medium to long term, but not sure if now is a good entry point. What do others think?
Syncona Final Results 20 June 2024
Wynnstay (LON:WYN) H124 webinar on Friday, Register here.
Results today: guiding in line for the full year, albeit with a H2 weighting.
Challenging trading conditions due to weather, falling commodity prices & weaker farmer sentiment has hit H1 but April and May are ahead of last year & weather deferred sales will come in H2. Milk prices are also favourable.
Dewhurst (LON:DWHT) and Dewhurst (LON:DWHA) - Paul, you mentioned the 2 classes of share yesterday and previously you have said the non-voting share is better value - the stockopedia metrics look the same for both classes. Could you (or someone else) explain a bit further?
DWHT 1190p, DWHA 620p. They have exactly the same rights, inc dividends, as each other except DWHA cannot vote. So the non voting DWHA shareholders have minimal say in what happens to the business, despite owning >50% of the company.
For the voting DWHT shares, large shareholders with surname Dewhurst own around 47% - and there may be other family holders with small shareholdings / different surnames.
So the Dewhurst family dictate what happens. If you're happy with this, the DWHA shares are much better value. If you're not happy with this, I'd suggest buying another company!
Similar setup with Youngs.
It can be worth watching the relationship between voting / non voting shares as pricing anomalies do occur. However with Dewhurst, there's little liquidity.
I hold DWHA
thanks for the explanation - much appreciated
Gear4music (HOLDINGS) (LON:G4M) looking potentially interesting medium term.
Profitability growing, debt halved to £7m which now looks much more manageable at0.6* ebitda. Return to growth and second hand market doing well.
The AV business could be operationally geared to consumer spending in Europe too so one to watch for signs of material pickup.
Interesting NED appointment - she is also a NED at Warpaint London (LON:W7L) so maybe some valuable lessons to impart to Gear4music (HOLDINGS) (LON:G4M) management
All in all looks like good progress and becoming interesting again imv
My thoughts immediately jumped to Michael Spencer, who joined the Chapel Down (LON:CDGP) board himself (last year?). Previously, he's sent a subordinate to oversee his investment.
He also has some other wine-related investments. And has the pockets (and/or connections) to orchestrate a take-private.
FWIW it is a very sorry state of affairs, that Chapel Down feels that they can't just raise money through equity fundraising, and/or bank debt as a public listed company, to fund expansion. That they have to consider other options like private equity or selling to a bigger strategic player. What does this say about the bad state of UK public markets?
Boon- maybe the major shareholder's (Spencer and Wray) does not want to fund any more ? I emailed them a few months ago re the new winery suggesting they have a rights issue rather than stuff the company with debt.
Chapel Down (LON:CDGP) i hold.
Not sure what has changed. Got my initial holding in an eis raise back about 2010. There have been other normal capital raises since then. They probably cannot do an eis raise again but surely raising capital is the point of a listing.
Tortilla Mexican Grill (LON:MEX) interesting acquistion of European competitor for around €4m + small update of trading in line (RNS came at 10am).
I am increasingly positive on Tortilla Mexican Grill (LON:MEX) . There is a clear growth strategy and a cash positive business model with modest capex. Operating cash flow of £3.8m pre-acquisition which could increase to ~£5.8m assuming they hit the £2.5m EBITDA from the acquired business and assuming no growth in the core. Obviously the plan is for significant organic growth therefore they should do better than this. Currently much of the op cash flow is absorbed by new store CAPEX but it shows what a cash generative business this is. It feels very cheap for a £20m market cap, virtually no net debt (maybe £3m after this deal which will quickly unwind) and an increasingly proven operating model in prime sites within a fast growing food segment where they have a clear lead. With a fair wind I can see this being a true multi-bagger from current levels.
Interesting move at Tortilla Mexican Grill (LON:MEX) buying Fresh Burritos a decent sized European operator https://newsfile.refinitiv.com.... First step in overseas expansion. 4.95mn Euros inc 2.7mn of its own cash. FB currently slightly loss making but seems a good fit and a logical step.
Hi Paul, you had mentioned SIMEC Atlantis Energy (LON:SAE) sometime ago here https://www.stockopedia.com/co.... What do you think of its results today?
I see you have replied to another request. Please ignore this one.
Fantastic balanced review of IG Design (LON:IGR) Paul. Thank you.
Fantastic balanced review of IG Design (LON:IGR) Paul. Thank you.
Thanks Wolf, from someone of your calibre that's praise indeed! :-)
Best wishes, Paul.
Yes that was a vey well balanced and detailed analysis on IG Design (LON:IGR) and on Pressure Technologies (LON:PRES) as well.
I have exited now completely on my IG Design (LON:IGR) and McBride (LON:MCB) positions.
All these weekly billions and billions and more billions of bond auctions in the USA are starting to make me more and more nervous. Elections in France as well will probably unsettle the European markets if Le Pen gets in.
All the best
Thanks yiannos1, appreciated :-)
SIMEC Atlantis Energy (LON:SAE) up 100% and flying this morning on results. Renewables with new gov could see more develpment. Paul could you nose test this one?
Hi Zorbatheleek,
SIMEC Atlantis Energy (LON:SAE) up 100% and flying this morning on results. Renewables with new gov could see more develpment. Paul could you nose test this one?
Yes indeed, a remarkable move up today in this nanocap green energy company. Up 133% today (!) to 2.45p, which takes the market cap from £8m to £18m today.
The excitement is its FY 12/2023 results, published today, which show a large profit from revaluing assets upwards -
The Group reported a profit of £23.2m, compared with a 2022 loss of £11.1m.
· Increase of 292% in Group revenue to £15.3m (2022: £3.9m).
· Revenues available to the Group, which excludes ring-fenced revenue earned by the MeyGen tidal array, rose to £10.7 million (2022: £nil) . The sale, at Uskmouth, of a ready-to-build 230MW BESS project with a grid connection for £10.0 million accounted for the majority of 2023 revenues, with the balance of £0.7 million being rental income from the Uskmouth site.
· Net Assets increased 678% to £44.2m (2022: £5.7m). The major increase in the valuation of the Group arises from the reassessment of the value and size of our battery storage projects.
Unfortunately, I've only occasionally looked at anything like this before, and find them complicated and very time-consuming to research.
I've had a quick look at the 2023 Annual Report here, and it shows large accumulated losses of £190m in the reserves section of the balance sheet. Also the debt on its balance sheet is multiples of the figure quoted in today's RNS, at around £50m.
Overall, on just a 15 minute quick look, I'd say a lot of care is needed here. The historical track record looks awful, and a one-off upward revaluation of an asset has created the big 2023 profit.
Good luck whatever you decide, but I can't give a view on this, as it would take me a whole day to properly research it all. It's very much a special situation though, so needs a careful, thorough look.
Regards, Paul.
Thank you Paul for running the numbers. I agree, it's very much a special situation but with todays news and new gov committed to net zero and job creation the risk may have been reduced.
Directors Pay is also quite hefty, First time we have seen them speak in a couple of years! Not much "skin in the game" here either
Directors pay as always...but today, 4 x directors put some skin in the game with purchases
A paltry amount though compared to salaries!
LUCE any thoughts on the recently constant drop in this share price? Feels a very similar drop to the RNO price discussed yesterday.
Luceco (LON:LUCE) I asked for views in yesterday's SCVR as freight costs are rising sharply. If plantex is looking in, please can you comment on any updates you have from your forwarder? tia
Eurocell (LON:ECEL) big volume yesterday and holding rns, Alantra down 5% to 4.98 and Wellcome trust picks up another 1% (4% to be accounted for still). Does anyone know who/what the Wellcome Trust is?
I believe it’s a major UK charitable foundation which focuses on medical research and is funded by an endowment originally seeded by the founder of the Welcome pharmaceutical business.
It is one of, if not the largest, endowments in the UK. More details here >>>>> https://wellcome.org/who-we-ar...
interesting, thanks
Hi Newtarrow,
"Does anyone know who/what the Wellcome Trust is?"
I find that a quick google search is the best bet whenever an unfamiliar company name crops up. I do this every time there's a takeover approach, just looking up the name of the potential bidder provides an immediate guide as to their size, financial clout, etc.
Regards, Paul.
Solid set of results from Augmentum Fintech (LON:AUGM) - NAV per share up 5% to 167p puts this on a c.32% discount. Cash balance of £38.5m – this is around 20% of market cap. This seems very cheap given portfolio seems to be performing well - they mention average revenue growth of 65% this year across their top 10 holdings, and since inception the company has delivered an IRR of 16%. Can see a decent recovery here once general sentiment improves.
Agree that Augmentum Fintech (LON:AUGM) is at a stunning bargain price, with the only obvious problem being investors, as is the case with too many Investment Trusts on big discounts to NAV, still not recognising this.
Note the first bit of their Portfolio highlights update today; their top 3 holdings plus cash covers almost all the current market cap with all the other often quality holdings doing well, in the share price for free.
Also all exits from the portfolio so far have all been above the last reported value and have realised £89.6 million proceeds compared with about £34 million originally invested in them.
AND NAV is up again to 167p, yet Augmentum Fintech (LON:AUGM) can be bought for just 115p. Don’t know how long before investors wake up or before it attracts a bid or amalgamation, but it looks a steal as a lockaway buy. I hold but only with modest 5% gain ….so far.
Portfolio highlights
Here’s a Citywire write up on Augmentum Fintech (LON:AUGM) after their update yesterday:-
https://citywire.com/investmen...
It’s worth registering for Citywire articles but for any not registered here’s the text:-
“Shares in venture capital fund Augmentum Fintech (AUGM) jumped 5.5% on Tuesday after annual results showed the resilience of the portfolio despite the challenges of a rising interest rate environment.
Over the year to the end of March, the largest 10 positions, which represent 81% of the portfolio, delivered revenue growth of 65%, driving the trust’s total underlying returns of 5.4%. Half of these companies are now cash-generative, while the other half have a 20-month cash runway.
Manager Tim Levene said it had been a year of milestones, as the £271m trust of European challenger banks and financial services disrupters saw its fifth and sixth realisations since launch in March 2018, while the largest holding, business banking group Tide, saw its value surpass £50m.
The trust’s valuations were validated, as NatWest acquired pensions provider Cushon at a 44% uplift, while in April, post the period-end, the US-listed provider of digital identity solutions Entrust acquired digital identity verification business Onfido at a 5% premium.
Chair Neil England said a chunk of the £32.9m realisation proceeds will be distributed to shareholders via a tender offer or special dividend, depending on the preference of shareholders, but could include share buybacks as it has done in the past.
‘The average premium to the last reported value is 30%,’ Levene (pictured below) told Citywire. ‘That demonstrates that not only should there be confidence in the underlying valuations, but actually as and when you exit, they’re exiting north of the holding value. The market’s the market, but I hope the discount starts to bridge as we’ve made a little bit of progress over the last couple of days.’
He pointed out that the extent of the current 31% discount is highlighted by the three largest holdings – Tide, Zopa and Grover – plus cash almost equating to the £187m market capitalisation of the company, implying that no value is given to the portfolio’s remaining 22 holdings.
The majority of the portfolio, or 21 positions, have downside protections such as liquidation preference and anti-dilution provisions in place, which shield the value of the fund’s position if there’s a fall in the value of the company from the price paid.
Now that the European Central Bank has started cutting interest rates and the Bank of England is poised to, Levene said improved sentiment could bridge the gap between the shares and net asset value.
The deployment of cash will likely return to longer-term averages in the coming year as valuations return to normal following the departure of ‘tourist capital’ in fintechs.
At the same time as announcing its annual results, Augmentum Fintech revealed a £2.6m investment in LoopFX following the period end. The fund is the first institutional investor in the spot exchange rate trading platform, which Levene said is a textbook example of a fintech operating in the capital markets in partnership with blue-chip financial institutions.
The investment manager invested £16m in one new company and six existing holdings during the year, a reduction from the previous year as valuations looked expensive. This included £4m in new position Artificial, an emerging leader in the ‘insurtech’ (insurance technology) space, as part of an £8m Series A funding round, and a further £5.3m in existing holding Volt, a real-time payment provider.
The board bought back 4.7 million shares over the period to narrow the discount, which widened from 39% to 40% over the year. Since then it has come in slightly as the shares have rallied 8% during the past three months.
Since launch six years ago, the portfolio has delivered underlying returns of 69%, while the shares have gained only 8.4%, according to data from Morningstar. The shares peaked at 173p in September 2021 and were trading at 116p on Tuesday afternoon.
Deutsche Numis analyst Gavin Trodd said the fund could be an ‘attractive’ long-term investment but noted that the early-stage portfolio could make for a bumpy ride for investors.
‘The fund has a strong record of realisations, all six of which have been above carry value and we would expect this track record to continue, particularly as wider market conditions begin to ease,’ he said.“
Be grateful if you could cast your eye over Funding Circle Holdings (LON:FCH) . It's a Rockwood favourite, has a lot of cash on its balance sheet, and announced today it has sold its US business, at a price better than many expected. If the underlying business is good (which Richard Staveley was confident about) it could be a bargain, but its not the easiest business to get a grip on.
Richard Crow is very vocal in his interest too
I have a starter position
Funding Circle Holdings (LON:FCH) - just looked at the list of major shareholders - quite a few names Ive never heard of and worthy of investigating out of interest
I don't know much about the business but I am a 'historic' retail investor on its books. I say 'historic' because they have been closed to retail investors for a number of years now. See here: https://www.fundingcircle.com/...
Double check but as far as I am aware it now receives all or most investor money from government via the British Business Bank - at least for its UK operations. Therefore there might be a risk associated with dependence on this model and perhaps it puts a ceiling on growth?
The other thing to check is exposure to the COVID loans scheme which has caused problems for some banks like Starling.
Strange RNS from Chapel Down (LON:CDGP) today. The big event which will require some serious finance is the planned new winery, yet as far as I can see they have not yet received final consent for that (there has been a plethora of appeals from NIMBYS). A rights issue is quite possible. Yet today's announcement mentions a sale of the company as being a possible option - clever, it mitigates any weakness in the share price. So I am not quite sure what has changed to warrant this RNS. I Hold.
I assume they had to as so many leaks at the moment re takeovers- even if a bid is a remote option. I have held for a bit and always thought it would be the likely outcome. But equally would be happy to fund in a rights issue- like my 33% discount and as I bought in low 40p's in profit as well.
CM, I am in the same (happy) boat.
Half year results out of Wynnstay (LON:WYN) today, I hold
Backdrop has been terrible; awful spring weather and post Brexit shambolic changes to agricultural grants, well meaning but don't help production.
I expected pretty grim results but actually they weren't too bad:
EPS 13.9p v 18.9p
Divi 5.6p v 5.5p, a bit mean, I think.
Outllok is unchanged but I struggle to believe this.
I will continue to hold. My biggest fear is the effects of climate change on farm production, and the awful new trade agreements. OK, we all get to buy decent NZ food at keener prices (no food miles there), but we also get to eat Australian feed-lot produce. Still a modestly priced, asset backed business. Some risk that the retail side will struggle, and Welsh hill farmers are having a really rough time (until wind farms bail them out).
I sold Wynnstay (LON:WYN) yesterday as given the comments about the weather this year, it made sense that there would be a negative TU so sold for a modest profit and used it to top up Kier. Whilst the balance sheet is holding up, there are clear clues that may change given the delayed sales on what already is revenue in decline. Whilst these may iron themselves out with April-May above normal prices coming through, a weakened farmer sentiment (which I read quite a lot of yesterday) is my main concern. Whilst they have a strong market position, this area is prone to shocks, so I'm waiting from the sidelines. It's a shame as it was one of my portfolio which was boring and didn't move at all (safe).
AGM statement from Huddled (LON:HUD) this morning shows Discount Dragon continuing to grow well.
It is important to point out that this is a tiny, early stage business based on buying discounted items very cheaply (instances cited around an eighth of the retail price and selling them at approximately double the cost). This means the buyer is saving about 50% of the normal retail price while simultaneously providing generous margins to DD. Management say there is a glut of unsold products in the market which would otherwise go to landfill. All items are delivered direct to customers' homes.
There are no forecasts in the market as they are at the forming and storming stage. Management, who are very experienced at buying and selling businesses know the dangers of missing targets and will provide sensible forecasts when the picture is clearer. As DD is growing quickly, a larger warehouse has been found. They plan to move in shortly.
Q2 24 rev expected no less than £2.7m from DD, £3m including the recent acquisition of Food Circle (Nutricircle) in April for a snip.
Revenue progression has been impressive: Q3 23 £1.3m, Q4 23 £1.8m, Q1 24 £2.1m, so Q2 24 rev at £2.7m is more than double the revenue 9 months ago not including Applied Foods.
The MCap of approx. £10m and is approximately 50% cash so they have the money to grow the business. This is the remaining cash after the sale of the location based Immotion business when a large proportion of the proceeds was returned to shareholders, so they have a history of looking after shareholders. Management own a lot of shares so are aligned with us.
Although this looks 'blue sky', the management team are clever proven winners at buying and selling businesses. I have spoken to them several times. They are confident and excited for the prospects of the business and the niche they operate in, which has given me the confidence to own shares.
Saga (LON:SAGA)
I notice earnings projections per stocky have taken material hit over the last month - current year eps forecasts have been trending downward consistently with few blips up and are now at the lowest point of the year - confirming the consistent trend in lower expected numbers.
So today’s update that trading is in line imho is pretty meaningless - forecasts have continually worsened with this news presumably being drip fed in advance by brokers continually lowering the numbers. Can they really say this is them being on track ??
This is the problem with saga they have consistently being lowering numbers they start the year with for sustained period of time.
Next year earnings expectations are also in decline too already (albeit currently higher than this year)
Are market conditions in insurance still grim or are they just bad for saga ?
If one wants to take a positive next years earnings now are expected to be better than this - but well they would be now wouldn’t they with their ability to provide realistic stuff in advance being worse than useless.
Agree re Saga (LON:SAGA) rmillaree
I’ve emailed management this morning and have asked them precisely which expectations they are managing to…….
Are they treating shareholders like the proverbial frog in hot water and hoping we dont notice a 20% profit warning or are they genuinely trading strongly in line with the expectations set in January
Given I have so far got no response I suspect its the former and that’s starting to make me quite cross ;-)
The 26 bonds now say zero chance of default trading at 95p and given gross cash exceeds the De Hahn facility I suspect the debt situation now has multiple outcomes including a bond refinancing in about 12 months………..the trading and shareholder communication is beginning to leave a lot to be desired……
A while ago Paul did a video of him visiting a ME International (LON:MEGP) site. At the time, the food machine was out of order and he didnt get the opportunity to test it out. On visiting my local Co-Op in Lichfield I noticed this little site (pics below). Pizzas were listed as half price so I decided to do a bit of market research. It took 5mins 20secs to prepare my picante pizza (they advertise 4 mins) and I got charged £4.98, rather than the 'usual' £9.95. Overall the topping was tasty but i felt the dough was a little undercooked for me personally. No way to adjust the cook time unfortunately. My 3 year old was a bigger fan than me which I think is a fair summary.
The laundry was all in use and had few people waiting for machines to free up sat on a well placed bench. Im not currently a holder.
BenHazz
Very interesting post re ME International (LON:MEGP) , thank you.
FWIW, the company has sold off its food offering, as per https://www.investegate.co.uk/...
The more recent TS makes no mention of food.
I think the pizza machine has good roll-out potential for organisations with lots of night workers like hospitals where there is a shortage of hot food available during the night. In fact I saw a pizza machine at Queen's Hospital in Romford although I am not sure if it was a ME International (LON:MEGP)
Also on the subject of ME International (LON:MEGP) , I note that Stocko reports that Peel Hunt initiates coverage with buy rating; PT 350p. I'd be interested to hear how Peel Hunt get to such a valuation. I hold and have a lower target price in the 200s
Also on the subject of ME International(LON:MEGP) , I note that Stocko reports that Peel Hunt initiates coverage with buy rating; PT 350p. I'd be interested to hear how Peel Hunt get to such a valuation.
Typical small cap broker BS. They just looked at the current price and doubled it. Maybe it’s the AI connection ;-)
My morning smallcap tweet: The Exit Factor
Funding Circle Holdings (LON:FCH) Trakm8 Holdings (LON:TRAK) Chapel Down (LON:CDGP) Orchard Funding (LON:ORCH) Proton Motor Power Systems (LON:PPS) Pressure Technologies (LON:PRES), Vertu Motors (LON:VTU), Saga (LON:SAGA), Anpario (LON:ANP), Aurrigo International (LON:AURR), Gear4music (HOLDINGS) (LON:G4M), Wynnstay (LON:WYN)
◄Funding Circle (FCH)► agrees to sell co's US business for £33m including all loan portfolios. [SP=85 Cap=298m]
◄Trakm8 (TRAK)► new contract and a contract extension with Iceland Foods. No £££. [SP=7.5 Cap=4m]
◄Chapel Down (CDGP)► strategic review of the options to fund its plan to continue driving strong and profitable growth. Includes possible sale of co. [SP=66 Cap=113m]
◄Orchard Funding (ORCH)► guides FY earnings (pretax?) more than 20% above F/C. [SP=27.23 Cap=6m]
◄Proton Motor Power Systems (PPS)► wins follow-up order from from DB Bahnbau Gruppe. No £££. [SP=2.17 Cap=36m]
◄Pressure Technologies (PRES)► H1-Mar. Outlook - CSC weak but PMC OK. Guides FY adj EBITDA over £1m. Not clear if this is a warning. [SP=39 Cap=15m]
In line: VTU, SAGA, ANP, AURR, G4M, WYN
Hi Paul,
Thanks on behalf of many of us for your lively views, and spirited delivery, of this weekend’s podcast.
These are always keenly anticipated and much appreciated.
How kind, thanks The Jayman!
I really enjoy doing the podcasts each weekend. It's a good way to recap on the week's activities and remind you/me of the most interesting companies, which I otherwise quickly forget. It's also a safety valve which helps me let off steam, as you've probably gathered :-)
Best wishes, Paul.
Most welcome Paul
The real value-add is the look-back and taking stock, exploring emerging themes, shifting risks etc.
My non-investing wife also listens in and particularly likes your moments of “exasperation”. Recently she came into the room where I was listening to Lord John Lee and she said “Who’s that? Paul S is much better”. I hope he’s not reading this post.
Definitely agree. I just took out a regular DDM to Zane by way of a thank you Paul - but why aren't you mentioned in the "where did you hear about us" box on the sign up page???
Jim
A big thank you for Zane DD, you will help people literally starving in Zim. Paul introduced me to Zane c 5years ago and I am now a trustee as I have become close to Zane. It is an extremely effective charity. Nothingventured, your help is much appreciated. Charles