Small Cap Value Report (Tue 25 Oct 2022) - SDRY, SDI, SHOE, SYS1, ALT, DVRG, THG

Good morning from Paul & Graham! Today's report is now finished.
Energy crisis - here are a couple of useful links, which I bookmarked, so I can follow what's going on with energy prices. You might also find them useful -
Trading Economics - this page gives a chart of the UK price of natural gas, plus an excellent short summary at the top, explaining factors behind price movements. As you can see, the price of gas has absolutely plunged recently. I think this is just a spot price though, so might not be reflected in bills, if the supplier has agreed different contracted terms.
Clifford Talbot - this page gives a useful chart (change timeframe to year-to-date) showing the spot wholesale prices for UK electricity & gas. Note the colour coding determines whether the Y-axis is on the left, or the right hand side of the page. This is also encouraging, as the price of electricity for example now looks well below the Govt's price cap. If it stays at that level, or below, then the Govt support measures could end up costing a lot less than initially feared.
Marketwatch - this page is useful, giving the current yield of benchmark 10-year Govt debt (Gilts). They've risen almost in lockstep with US Treasuries, so it's important to remember that the trend is being dictated by international factors (as with so many things right now). The recent mini-budget kerfuffle caused a spike up to c.4.5% yield, which seems to be the level where big margin calls hit pension schemes due to their LDI derivatives. In recent days, the yield has dropped significantly as UK Govt policy has changed from increasing the deficit (hence more bond issuance) with tax cuts, to cancelling most of the mini-budget, and talk of more spending discipline (hence less issuance of new debt). Plus remember the key buyer was the Bank of England, using QE, but that's now stopped.
Do add any interesting links you use (and why you use them) to the reader comments section, I see a couple of people already have, thank you!
Agenda
Paul's Section:
Superdry (LON:SDRY) - thank you and well done to an eagle-eyed reader, Albm7, who spotted yesterday that Superdry's auditor had resigned, leaving a letter that is critical of internal controls. This is very unusual (the last case I recall was Cake Box Holdings (LON:CBOX) ) and once the news leaks out, it tends to be very bad for the share price. I discuss it further below, but have taken SDRY off my potential buys list, as this is a serious matter.
Shoe Zone (LON:SHOE) - delivers a decent FY 9/2022 trading update - the year ended with a flourish, with profit 4.5% ahead of Zeus's forecast. It's been highly cash generative too, with the cash pile now over a quarter of the market cap. I remain positive on this company.
Deepverge (LON:DVRG) [no section below] - I flagged up the nasties at this company here in June 2022, since when the price has fallen by 3/4. Today the price has bounced up 20% to 2.5p on news that strikes me as negative. It's trying to raise fresh equity through Turner Pope (a broker very much at the speculative end of the market!). The big risk here is that the price of the (seemingly imminent) placing could be disadvantageous to existing holders. After all, there aren't many people around with cash to deploy on highly speculative companies that have run out of money! So they can name their price. Also, both the CEO and CFO are stepping down, admitting that they've been stretched, as well as the balance sheet. Looks super high risk until a refinancing has been done, so I'm steering well clear. We can always revisit it, once funding has been secured. Buying or holding now looks too high risk to me. Just for gamblers at this stage. [no section below]
THG (LON:THG) - a solid Q3 trading update, no change to guidance, and it says customer behaviour is stable. It's not a value share, and I don't like the heavy losses & cash burn. But with raw material prices now falling, it reckons margins can be improved. It's not for me overall though, but might interest shorter term traders maybe? [much more detail below]
Graham's Section:
SDI (LON:SDI) (£186m) (+6% on Monday) [no section below] - this acquisitive group has spent £13m to purchase “a UK manufacturer of anti-static equipment”. The acquired company’s website can be viewed here. Deal terms appear reasonable: SDI is paying less than twice revenues, or an adjusted EBIT multiple of 8x, and also receives ownership of freehold property.
SDI is smaller than Judges Scientific (JDG), but they both face the challenge that comes with success: how to deploy larger amounts of capital? SDI’s last three acquisitions had price tags of £4.9m, £7.7m and £4.2m. Hopefully they can make slightly larger deals, such as the one just announced, and still find the same level of success that they have in the past. Management are highly credible although it is worth noting that they elected to sell 1.3 million shares in January at 195p, after exercising options. There tends to be less dilution and more insider ownership at JDG, so I do prefer JDG, but SDI also has an excellent overall track record. [no section below]
System1 (LON:SYS1) (£27m) - this marketing company updates for H1. Revenues are down 15% as its declining consultancy sales more than offset the growth in its data products. I was very supportive of System1’s plans to replace a labour-intensive, contract-driven business model with an automated, subscription-based service. However, it appears that the company itself is unsure about what to do. The results of a major strategic review will be announced at the end of November, and this will hopefully bring clarity to both existing and prospective investors. But for now, the company’s financial numbers are significantly worse than they were before, and it’s not even clear what form this business will take a year from now. With so much uncertainty and with a transition underway, I think the market is correct to price these shares at a modest level and perhaps should even let them drift lower from here.
Altitude (LON:ALT) (£15m) - this owner of a US-based marketplace for promotional products says that it is on track to be “at least in line” with market expectations for FY March 2023. I remain intrigued by the possibility that this could turn out to be a high-quality, valuable business. As the host of vast quantities of transactions between thousands of buyers and sellers, it seems that it should be possible to turn this into a success. For now, however, revenues and profitability are modest. Its cash balance is lower than it used to be, and the company opened a borrowing facility earlier this year. This looks finely balanced but I do see potentially very large upside for shareholders if the company succeeds in its goals.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Superdry (LON:SDRY)
119p
Market cap £98m
(Long section, with lengthy quotes, so [as with everything here] just skip to the "My Opinion" bit for a summary, if you're not particularly interested in the detail. I'll tidy up the formatting later, but want to check out SHOE before the opening bell at 8am).
Many thanks, and well done to one subscriber, Albm7, who spotted that Superdry's auditor has resigned. This was buried in an announcement which looked harmless, so I ignored it originally. The title was "NOG - Notice of GM" - sounds trivial. But when you open the link, the internal title is "Notification of General Meeting and Auditor Resignation" - a completely different, and much more serious matter. How deceptive is this, awful! They've obviously tried to bury the bad news and hope nobody spots it.
Superdry also announces that Deloitte LLP has resigned as the Company’s auditor...
A copy of the Statement of Circumstances which details reasons behind this resignation has today been sent to all shareholders alongside the Annual Report and Accounts for the year ended 30 April 2022 and the Notice of General Meeting.
This is the same thing that Cake Box Holdings (LON:CBOX) did when its auditor resigned, with a critical letter. The bad news was buried in the Annual Report, and not published to the market in a clear way.
I'm reviewing the FY 4/2022 Annual Report now, and on page 104 (Audit Committee Report) there's a section entitled "Review of the effectiveness of internal controls" which discussed this issue. Interestingly, it says that the auditor raised similar concerns about poor internal controls in FY 4/2020, and remediation work was implemented. Areas of concern cropped up again in FY 4/2021, causing a delay in the accounts being published.
The Annual Report goes on to say (sorry this is quite detailed, but it's all interesting, and pretty damning I think -
Current position – effectiveness of the Group’s controls in FY22
Deloitte has continued to identify significant weaknesses in the Group’s control environment during the course of the FY22 audit, highlighting a significant number of audit adjustments as a result. Their audit report continues to explain weaknesses in the Group’s transactional processing controls, month end close the books process, management review controls and general IT controls.
Unfortunately, particular issues have been identified in the accounts payable and inventory business processes (specifically inventory cost variance accounting) during the current year external audit, indicating a deterioration of controls in these areas. This has been exacerbated by high employee turnover within the Finance team resulting in the loss of knowledge of the Group’s processes in these areas which, in lieu of effective systems, is essential for the adequate maintenance of controls. Despite the implementation of IFRS 16 accounting software, the process continues to be complex especially as the IFRS 16 accounting is maintained outside of the underlying general ledger and recorded as an overlay adjustment through the consolidation process.
Consistent with FY20 and FY21, the deferral of the announcement of the FY22 results has again been necessary to allow more time for the Finance team, the Board and Audit Committee, and the external auditors to undertake the additional work required to respond to the control weaknesses identified and ensure there is no risk of material error. The additional work performed has included performing detailed, transaction verification testing in certain areas. Further details are set out in the Independent Auditor’s Report on page 132.
Finance Transformation Plan and future actions
A finance transformation plan (the ‘Plan’) was developed by the new finance leadership team following the completion of the FY21 audit in order to address the Group’s control deficiencies. The Plan is establishing a framework for the improvements required across the Group, focusing on the four pillars of people, processes, policies and systems.
As part of the transformation plan, an internal control questionnaire (ICQ) has been implemented. This requires control owners to attest on a quarterly basis that the controls in their areas are being operated as designed. Consistent with the findings of internal and external audit referred to above and in the Independent Auditor’s Report on pages 132 to 147, the results of the ICQ indicate that there remain control deficiencies that need to be addressed.
It is clear that significant further work and focus is needed to improve the effectiveness of the Group’s internal controls and the pace of change is not as originally planned. The deterioration in controls in inventory and accounts payable in particular is disappointing. Recruitment activity in FY22 has sought to build the strength and depth of the finance team and although some progress has been made, further work is needed to increase the technical competencies and seniority of the finance team across both financial reporting and tax and establish a solid foundation on which the transformation plan can be built.
The Group plans to implement a number of new systems in FY23 including Blackline, a new reconciliation tool; SoftCo, a new AP automation system, and an upgrade to the Group’s accounting system. The new systems will help increase the level of automation and standardisation in the Group’s processes helping to ensure the control environment is sustainable in the long term. However, it will take time to implement the system changes needed to ensure the Group has an effective internal control environment and until then, the Group will continue be reliant on a number of manual review and reconciliation controls, which as set out above need to be improved as a matter of urgency.
Auditor resignation - worryingly, this was advised to the company "During the year", referring to FY 4/2022, but doesn't seem to have been notified to the market (maybe it's not required, but this is important information) -
During the year, Deloitte LLP advised the Company that they intended to step down as its auditor, following the completion of the audit of the Group’s results for the 53 weeks ended 30 April 2022.
Indeed, on 9 May 2022 the main Board had a meeting which is described as "Potential new auditor presentation (RSM)" (page 89 of Annual Report), so this issue of auditor resignation has been known about for a long time, but it's the first I've heard of it.
The audit report has a "material uncertainty" statement, re the bank facility, saying -
The Directors’ base case forecast indicates that a financing facility of up to £70m will be required during the going concern period. The ability of the Group to continue to trade as a going concern is therefore dependent on the availability of sufficient, committed bank facilities. Current projections using the Directors’ base case together with a reasonable downside scenario indicate that the October 2022 covenant requirement of the existing ABL facility will be met. The going concern material uncertainty is therefore specifically in relation to the expiry of the existing ABL facility in January 2023 and, currently, the absence of a sufficient committed facility throughout the remainder of the going concern period.
I've already flagged up this issue previously - renewal of the bank facilities is essential, which expire in Jan 2023. As things stand, I feel reasonably comfortable that the bank is likely to renew them, because it has security over the wholesale receivables book. Although a damning criticism of internal financial controls from the auditor, is bound to make the bank question whether the security is adequate. Poor internal controls can often hide black holes in the accounts. So I'm less sure than I was that the bank funding would necessarily be renewed. It probably will, but we can't be 100% sure about that, which in a downside scenario might lead to an emergency equity fund raise, maybe at a deep discount, or worse. The clock is ticking, with Jan 2023 not being far away. that said, the auditors still gave the FY 4/2023 accounts a clean audit opinion.
The audit report itself includes some unusual items, including this -
Significant changes in our approach
We have designed our audit in light of the deficiencies within the Group’s control environment and our
findings from previous audits. The nature, extent and timing of our audit procedures continue to be
modified in order to respond to the pervasive risks arising from the control deficiencies. More details on
the impact the Group’s ongoing control deficiencies and associated finance transformation plan have had
on our audit approach are set out in the ‘impact of control deficiencies’ key audit matter below.
Also, see section 5.1 of the audit report, gives more detail on the control deficiencies, including this bit -
Furthermore, we have identified the deterioration of controls
compared to the prior year in inventory and accounts payable. In inventory in particular, controls around
inventory costing and accounting for price and quantity variances were found to be deficient resulting in
management having to perform significant additional investigations to evidence and rationalise the
accounting entries and year end inventory balance. Correcting adjustments were recorded as a result of
these investigations. A lack of controls around matching payments to suppliers to the outstanding liability
means management has had to perform additional work to match unallocated debit balances on the
accounts payable (“AP”) ledger and in the AP suspense account at year end and record correcting journal
entries as necessary to clear down the balances. In all of these areas, there continues to be a need to
improve management review controls.
I recognise that issue from my CFO days! It's where supplier accounts are not reconciled, so you just pay them round sum amounts of cash, to stop them nagging you for late payment. This builds up a large, unreconciled account, which can mean that some invoices have not been input onto the ledger (meaning profits are overstated). It's a basic control that is lacking - supplier accounts should be reconciled every month to the statement from the supplier.
Adjustments to the accounts -
Consistent with previous years, a significant number of misstatements have been identified during the
FY22 audit, that in aggregate were material. The majority of these (net impact to the Income Statement
£4.9m) have subsequently been corrected by management. The misstatements identified are indicative of
the ongoing control issues within the Group as highlighted above. The control environment will continue to
be a significant area of focus for the Audit Committee in the forthcoming year as discussed in their Report
on pages 104 to 105.
My opinion - there's loads more detail in the audit report, and it just shows (as with Cakebox) that we as investors should download the Annual Reports as soon as they're published, and go straight to the audit report, and read it carefully. In this case, SDRY has had ongoing sloppy financial controls for the last 3 years, all disclosed in the audit reports, but it's the first time I've become aware of it!
I think this issue leaves SDRY shares wide open to a critical dossier, of the type that short sellers use to make money on a falling share price, often exaggerating the problems.
Maynard Paton issued a critical report on CBOX not long ago, which also had a crushing impact on the share price, from which it's never recovered. I don't think he was shorting it though.
The same sort of issues seem relevant at SDRY, and this issue has had almost no publicity so far as far as I know. Therefore, I think SDRY shares are probably best avoided for now, due to the depth of the problems in its finance department. This is a damning indictment of the CFO, although he's only been in the role since 2021, and raised eyebrows as he had previously been sacked from the role in 2015 due to being made bankrupt by HMRC (since overturned).
This all looks a bit of a mess, so for now, I think SDRY shares are probably best avoided.
Shoe Zone (LON:SHOE)
180p (pre market open)
Market cap £88m
We’ve been enthusiastically reporting on SHOE this year, as it has repeatedly raised expectations. Its low priced Chinese-made footwear obviously strikes a chord with cash-strapped consumers. Also, with supply chains now easing, and sea container freight plunging in cost, the margins could improve further in future (although the strong dollar could be a negative factor).
With results statements or trading updates, to get a quick view early on (if you’re intending to buy or sell on the opening bell, for example), then I find it’s best to check for updates on Research Tree. In this case, many thanks to Zeus, which confirms that these flash figures for FY 9/2022 are 4.5% ahead of its forecast - this is now the 5th upgrade this year, really impressive stuff.
Forecast for FY 9/2023 has been raised by Zeus, up 20% to £8.5m Adj PBT, and Adj fd (fully diluted) EPS of 13.4p. Note that the forecast for FY 9/2023 looks modestly set - well down on actual results for FY 9/2022 announced today of 17.6p adj EPS. This gives me comfort that SHOE seems at low risk of profit warnings in future, indeed we might see it beat these modest forecasts. Although I do think it’s sensible to err on the side of caution, given the fragility of consumer confidence right now.
There again, there is an argument that I find quite persuasive, that SHOE’s customers are making essential purchases, not discretionary - e.g. kids needing new shoes for school due to their feet having grown over the summer holidays. Plus, the shoes are going to get trashed anyway, so might as well buy the cheapest option.
Key numbers - this is quite detailed for a trading update, so it looks as if the finance department has a good handle on things (unlike at Superdry!) -
FY 9/2022 -
Revenue £156.2m (prior year figure of £119.1m is not comparable, due to covid closures)
Digital revenues dropped from 26% to 17% of total revenues. So this is mainly a physical stores business, with covid having boosted the prior year’s online sales.
Gross margin is maintained at 61.3% - note this is a very good margin for a retailer, and shoes tend to have a low returns rate too.
Adj PBT “not less than £11.0m” - given the company’s cautious track record, the actual figure is likely to come in a little above this.
Adjustments look reasonable - re forex, and profit on freehold property sales.
Store numbers - a striking reduction, 410 down to 360 now, but remember the strategy is to close smaller stores, in favour of the better economics of bigger units on retail parks. So this is a good thing.
Net cash - striking here, at £24.4m (up £9.8m on a year ago’s £14.6m) - at a guess though, there might be some favourable working capital movements helping this a bit, possibly? It’s all the more impressive given that capex was £4.7m and a £4.4m CLBILS loan having been repaid. Yet still, even after those big cash outflows, the bank balance has risen £9.8m.
Growing divis, and a share buyback programme, reinforces that this is a nicely cash generative business, now generating surplus cash.
Management comment - there’s nothing said on current trading or outlook, but this sentence reassures in current macro uncertainty -
Shoe Zone continues to show how resilient it is, with a proven track record of delivering robust results during times of economic uncertainty.
My opinion - we remain fans of Shoezone here at the SCVR. It’s performed so well this year, and the valuation still looks modest, despite the share price having been a rare riser this year.
Selling cheap shoes, at high margins, from a low overheads base, looks an excellent business model.
In current conditions though, I personally wouldn’t be interested in chasing the share price higher. But for existing holders, I think there’s an obvious, and strong case, for just locking away the shares, collecting in the divis, and let management (owner managers with large stakes) carry on working their magic!
A very unusual chart below, but justified by repeated upgrades. Note also the StockRank - it's stuck on maximum, but I've tapped the StockRanks dial, and it's not jammed, that is the real score, currently 98!


THG (LON:THG)
53p (up 15% at 11:46)
Market cap £704m
Graham looked at the interim results & profit warning here in Sept 2022, from this quite big eCommerce company (main product categories are beauty, and nutrition, plus it does outsourcing for external brands).
I’ve also done my own quick review of the interim results, to familiarise myself before looking at today’s Q3 update, which has given the share price a nice 15% boost today. Is it getting into bargain territory maybe, after dropping almost 90% from a vastly overpriced IPO (at 500p, £5.4bn market cap, in Sept 2020)?
Based on the interim results to 6/2022, I’d say no, it’s not a bargain. It’s heavily loss-making, and the balance sheet looks a bit flimsy for the size of business (over £2bn p.a. revenues), once you delete the intangible assets, NTAV is only about £200m. A big cash pile previously, has now turned into net debt (excl. leases) of £226m, with the business now being reliant on borrowings. So the terms & covenants of debt is the key thing to research carefully.
THG PLC ("THG" or the "Group"), the proprietary technology platform specialising in taking brands direct to consumers ("D2C") globally, announces its third quarter trading update for the period ended 30 September 2022 ("third quarter" or "Q3 2022").
This sounds fine, I could have saved myself some time by reading this bit first!
Full year revenue, adjusted EBITDA and cash guidance unchanged
A few key points (not comprehensive) -
Consumer behaviour remains “stable & consistent”
Positive start to Q4 (Oct-Dec 2022)
Additional £156m bank facility agreed.
Bank facilities are “covenant light”, long-dated (not really, more medium dated I would say, at 2025-26, but that’s fine for now), and with fixed/hedged interest rates thankfully.
“Stock levels are normalising” - good because they looked too high at the interims.
Guidance is for £500m gross cash at year end. But bear in mind this is more than offset by bank debt. Net debt was £226m at the interims (excl. leases). So whilst it has plenty of liquidity, it’s still got a lot of gross debt.
EBITDA guidance -
Full year adjusted EBITDA guidance is maintained between a range of £100 to £130 million pre Software-as-a-Service ("SaaS") cost reclassification.
That’s very nice, but bear in mind the depreciation & amortisation charges were about £100m just in H1, so in reality, this level of EBITDA “profit” is actually a real world loss.
Take a look at the H1 cashflow statement, for a dose of reality! It ran a big operational cashflow loss, even before heavy capex, and is capitalising a lot of internal IT costs onto the balance sheet. For this reason, EBITDA is totally meaningless for this company.
CEO comments sound quite upbeat, and note that he jointly took out Softbank’s stake with the Qataris recently, at 39p, which is already looking a canny deal!
Matthew Moulding, CEO commented:
"Another strong quarter of delivery across our Beauty and Nutrition divisions has enabled market share growth in our key global territories. We remain committed to our strategy of supporting our customers around the globe through investment in price protection, without compromising on quality or choice.
As commodity prices ease further, we remain well positioned to grow margins into 2023, whilst reducing pricing to consumers. This positions the Group well in continuing to expand market share. As cost of living pressures rise, customers are continuing to prioritise beauty, health and wellness categories and, through investing in bringing them into and retaining them within the THG ecosystem, we are laying the foundations for our future growth.
"The fourth quarter has started positively, and we are well positioned from a logistics and supply perspective to meet the significant uplift in demand anticipated during the cyber period, whilst continuing to deliver a high-quality customer experience.
My opinion - it doesn’t make any money, and has been dashing for growth maybe too fast? However, the talk of better margins in 2023 sounds encouraging. It’s clearly not a share that would interest value investors, so I’m looking at it more in the context of a possible candidate in a possible wider sector re-rating, from current bombed out levels.
Similar to ASOS (LON:ASC) (covered recently here), Boohoo (LON:BOO) [I hold], THG is a big revenues business. So with supply pressures & costs maybe now easing, it wouldn’t take much to turn the struggling P&L performances from these companies into profits. Then, in a recovering stock market (at some point, no idea when!) the forecasts might be upped, and investors might start to re-rate them upwards as growth companies again. That could be a powerful mix of positive factors, hence why I’m looking ahead, not getting bogged down in current market gloom.
I don’t think THG would be my first choice in this sector though. It's not a charity, so why is it holding back on price rises, to help customers? I don't like that.
Another worry I have, is the CEO, who seems still locked into la-la-land, where growth companies think they can ignore commercial realities, and run up big losses & cash burn with impunity. Those days are over, for now anyway, so he could be a bit of a loose cannon perhaps? I prefer more commercially grounded management. That said, he has built a sizeable business, fast. What a pity then that it doesn’t make any profit! So probably not for me, but it could be an interesting share for traders possibly?
.
Graham’s Section:
System1 (LON:SYS1)
Share price: 213.5p (+2%)
Market cap: £27m
This marketing specialist announces an H1 update (for the period ending September 2022).
Key points:
- Data revenue +38% to £6.2m. Now 59% of total revenue.
The “data” revenue is the high-quality income stream System1 has been building for the last few years. It’s high-quality because it’s a subscription-based, automated service, rather than a labour-intensive contract with a customer.
- Consultancy revenue is down 46% to £4.3m.
The consultancy revenue stream is being allowed to shrink, as the company pursues its new strategy of focusing on data services.
Total revenues are therefore down 15% to £10.5m, in line with expectations.
Profitability: gross profit is down 18% to £8.5m and the company did not make an overall profit in H1, either on a statutory or adjusted basis.
Cash: the cash position is thankfully still good, but has reduced to £6.6m.
US litigation: the company’s efforts to sue an American business with a similar name continue. I believe that the American business being sued is this one.
Outlook: this is the closest we get to an outlook statement in this update:
The Board is encouraged by the strong growth in "Test Your" Data products… It is clear that the transition from bespoke research consultancy to platform-based "Test Your" data is well underway, and the Board expects the drag from declining bespoke research consultancy to reduce progressively.
My view
There’s great uncertainty hanging over these shares while the Board conducts a strategic review.
On 31st August, less than two months after announcing a share buyback and tender offer, it postponed these actions, saying that it needed time to consider alternatives to its existing strategic plans:
Whilst the Company can continue with its current strategy, the Board believes that it is important to ensure that it has explored all strategic options to capitalise on System1's current market opportunity to deliver shareholder value, including considering the value it can create in its current form, the options for increasing organic growth through forming partnerships, and external or internal investment to grow revenue by leveraging the significant investment made in automated predictions technology.
This creates a problem for prospective investors in the company: it’s difficult to know what we might be buying into. It might just go back to its original strategy, or it might do something very different - a merger, a takeover by a larger company, a fundraising? Anything is possible.
The strategic review is being “supported” by the company’s Nomad/Broker. These things often do wind up with some sort of a transaction.
The other point is that there isn’t much current profitability to get excited about. Much of this is to do with the transition from one type of business to another, but it still leaves the share price vulnerable, when the numbers currently being printed in the financial reports are so much weaker than they used to be.
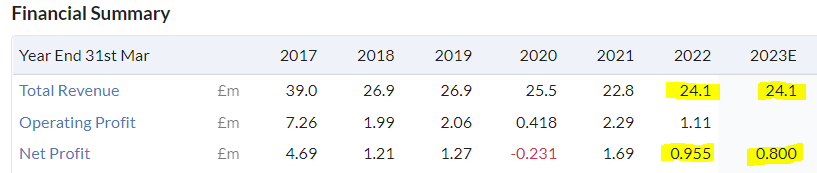
In July, I presented a list of bull and bear points around this company. Unfortunately, it looks as if the bearish arguments are winning. While it’s too soon to say that the company’s current strategy - or the strategy it eventually settles on - is doomed to failure, it does need to settle on a strategic direction as soon as possible.
Altitude (LON:ALT)
Share price: 21p (-2%)
Market cap: £15m
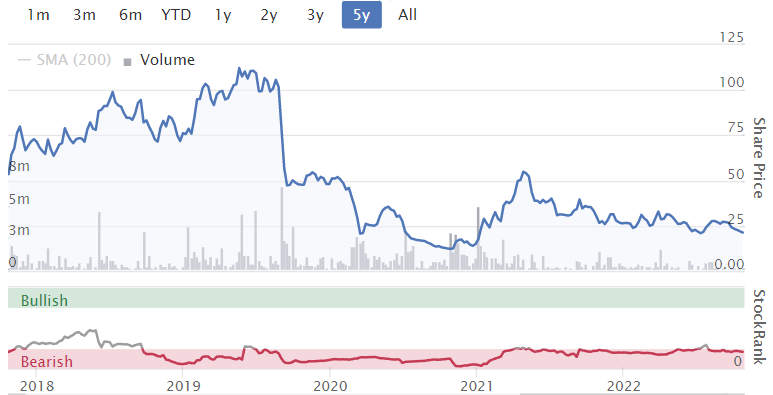
This share captured investors’ imagination a few years ago, before coming back to earth:
It operates a marketplace for promotional products - here’s the link. Based in the United States, this is described as “the largest organization of experienced and qualified promotional product distributors in the global promotional products industry”.
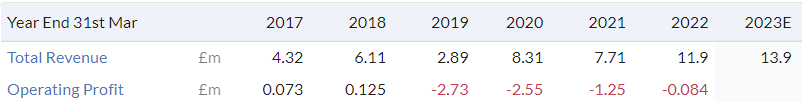
While the platform has supposedly hosted $2.1 billion of sales so far, this hasn’t translated into huge results for Altitude yet:
Let’s read this update for H1 (to September 2022):
The Board is pleased to report the Group has delivered another excellent period of growth, driven by successes across all key Services and Merchanting programmes.
Unaudited revenue for H1 23 is expected to be no less than c. £7.6 million (H1 22: £5.9 million) an increase of c.30%. As a result of the strong underlying business performance, an advantageous exchange rate and having not experienced any negative impact to date from the current macro-economic turbulence, we continue to trade well and expect to be at least in line with market expectations for the financial year to 31 March 2023*.
The company helpfully discloses market expectations: revenues of £13.9m (as seen on the StockReport) and adjusted EBITDA of £1.2 million.
My view
I think there is good encouragement to be had from this announcement. Many companies do blame the macro environment for their current performance, but Altitude appears to be doing fine.
I always like a “marketplace” type of business - something that connects buyers and suppliers. For me, this has the potential to be a high-quality business, even if it hasn’t shown up yet in the financials.
Management say that their “systems and people infrastructure have been developed and designed for continued scalable growth”. I do believe that they are thinking and acting with long-term success in mind.
Of course it’s still rather speculative at this stage but I don’t think the market cap of just £15m gives the company much credit for what it has done and for what it might do in future. The price to sales ratio is only at a small premium to 1x.
One possible issue is the cash balance, which fell to £900k as of March 2022. It will be unfortunate if the company ends up indebted to a bank: it needs to be very careful with its spending until it turns the corner to profitability, to avoid any need for an equity raise.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
BrilliantLeader, Thank You for your link to the Bond Guru Paul Hawkins; Very Timely as i am currently considering getting back into them within the next couple of months ; just finished enjoying his excellent interview. Also look forward to an update if Paul can arrange it.
I think that Pauls warning on Made.Com (LON:MADE) was timely, looks like they didnt find a bidder.
As usual, nothing on Tristel, although quite good results declared today.
Hi kendal,
We've followed Tristel (LON:TSTL) here for many years, indeed I've written about it here 37 times!
Strange though, it didn't come up on my newsfeed this morning, I've just seen that it issued prelims. We didn't ignore it intentionally. Our usual conclusion is - nice company, shares are too expensive. So that probably saves me a job!
If you disagree, then do flag up why, and I'll take a fresh look.
Sorry we missed it.
Regards, Paul.
Thanks for the interesting links. I will certainly bookmark them. In fact what I do is use Chrome as my day to day browser (non investing stuff) and then use multiple browsers for my investing sites, so:
- Firefox: Stockopedia
- Edge: Sharepad
- Opera; Tikr
- Brave: other sites such as koyfin, Rhodium price on Trading Economics (I hold Sylvania Platinum (LON:SLP) indeed last time I looked, which was a while ago, it was my largest holding), quickfs, Dataroma, Freightos data (container freight index) etc etc
I have then written a batch file that opens these and outlook, so with one click I can have these loaded easily. And no I don’t have six screens just two and I don’t sit in front of them eight hours day but find in useful not to have to remember which data was sourced from which web site.
Regards
Michael
PS Any thoughts Paul ASOS (LON:ASC) and Ashley’s stake and the read across to Boohoo (LON:BOO) (I hold smallest, was largest, position). I hope he doesn’t pickup Boohoo for 60p and think he has done shareholders a favour. Though I would have thought Kanani et al would ensure that doesn’t happen?
Hi Michael,
That sounds terribly complicated, and I fear would overwhelm the processing power of my aged PC.
I just use Chrome, and have saved a list of websites that it opens automatically when I turn the computer on.
Regards, Paul.
Very interesting movements in FTSE small and mid caps this afternoon...seems like the robots are at work, seeing the real value in these shares now. Short lived probably but makes me feel these low levels are a good buy and hold strategy from here on out, adding slowly but surely.
The Spectator data site has many useful charts, including spot and futures gas prices https://data.spectator.co.uk/c... and I should add that it is UK centric
But not the NBP gas price, I.e. the price being received by gas producers
Trading Economics is a great resource for charts, all kinds of useful metrics on there.
I'm interested in the trend for UK bankruptcies, as I hold Begbies Traynor (LON:BEG)
The chart here paints a fairly grim picture, on a sharp upwards trajectory at the moment. Begbies reports half year results (through to October) on December 12th.
Edit: Select '25Y' to see a line chart which illustrates the upwards trajectory
https://tradingeconomics.com/u...
When looking at insolvencies, the key question to ask (when evaluating for Begbies Traynor (LON:BEG) ) is whether they were voluntary or involuntary insolvencies. The former, isn't in the space that Begbies works in.
For Sep 2022, the gov's insolvency stats say:
"Numbers for other types of company insolvencies, such as compulsory liquidations, remained lower than before the coronavirus (COVID-19) pandemic, although there were over 6 times as many compulsory liquidations in September 2022 compared to September 2021"
However, looking at the monthly trend, compulsory liquidations look like they are at an inflection point, potentially poised to explode higher from Oct onwards (or maybe not). We will have to wait another month to see the numbers!
Hi Boon,
When looking at insolvencies, the key question to ask (when evaluating for Begbies Traynor (LON:BEG) ) is whether they were voluntary or involuntary insolvencies. The former, isn't in the space that Begbies works in.
That sounds a bit strange to me. When I worked in the insolvency dept of Price Waterhouse (one of the biggest firms of accountants), about 30 years ago, they covered all sorts of insolvencies, and didn't discriminate between types of cases - they would take any insolvency work if there were enough assets to cover the (hefty) fees!
Could you elaborate, if you have time, as to why (and the source) you think BEG don't do some types of insolvency work mentioned?
I'm quite surprised that BEG shares have softened from 150p to 131p recently, given that there's likely to be a big surge in corporate insolvencies over the next few years, for well-known macro reasons. Could be a buying opportunity, and it seems decent value right now for a counter-cyclical business.
.
.
.
Paul - I inferred as I remember reading in a Begbies Traynor (LON:BEG) trading update very early on this year, that they make most of their money in being appointed as administrators.
My understanding is that a company going into administration is more likely when creditors are pressing a company, or already filed winding up petitions in court? Therefore, I assumed, the level of administration activity is more correlated to Compulsory Liquidation levels, than Voluntary Liquidation levels.
Happy to be corrected in my assumption and thinking here!
re Gas Prices ..... I also use https://www.theice.com/product... to watch the fwd prices. Although near prices are falling ...its not til 2024 pressure really eases. Also - if you click 5Y on the trading economics page you can see prices remain elevated even though they have fallen a lot.
Broadly speaking (I don't own), this remains a positive picture for Serica Energy (LON:SQZ) since short term gas will be hedged and longer term prices remain high. The shares have been very weak .... and have dipped below their 200 day.... -30% .... so in the zone for sure.
Re Altitude (LON:ALT) - I looked and agree could be interesting. However, my opinion is that they persistently employ an element of opaqueness in how they describe and report their business and this leads me to feel there is something at least unconfident about them...and of course it could be more sinister. I bias to the former and think its as they have scrabbled around for years trying to find their thing and they are never very sure whether they have a good thing...
Paul
For the real price being received by North Sea gas producers, you would be better advised to look at https://www.marex.com/services...
The relevant line, under the "UK Natural Gas" header, is "NBP All Day D.A", which as of yesterday was an average of 41.169p/therm.
Apparently cause by a combination of the mild weather, fairly full storage facilities in Western Europe and a fair few LNG tankers looking to unload. On a snapshot basis, does make the WFT seem completly farcical albeit when winter kicks in presumably prices will go a lot higher.
RNS just out confirming press reports that Frasers (LON:FRAS) has bought 5.1% of ASOS (LON:ASC)
What are his intentions? Well apart from putting his sticky mitts into every pie available, I'd say it's probably to get some leverage for doing stock supply deals with Asos.
Although with ASC mkt cap now down to only £543m (taking into account today's 5% rise), and Frasers at £3bn, a takeover bid for Asos by Frasers is within the realms of the possible.
Although Bestseller seem to have what looks like a potentially blocking stake -
I'm interested in the statement from On Beach group (LON:OTB) this morning. FY trading update. I think their fortunes are rather more positive gong forward than I had otherwise thought. The Stockopedia predicted revenue was 130; the 2019 revenue was 148; the CEO says sales were 16% ahead of that! I make that around near 170? That's a big difference and of course shows nothing about the financials which we will see in due course.
The SP is below 100p (close to the year low), and the Stock Rank is pretty dire, but I would be interested in comments from others and from Paul/Graham on their prospects for a recovery in SP in the future, especially on the strength of the balance sheet which as ever is relatively unknown territory to me!
I have cherry picked quite a lot from the report and highlighted some key points in bold.
In H2FY22, Group Sales were 25% ahead of H2FY19, despite the indirect consequences of the war in Ukraine and ongoing disruption across the travel supply chain as the sector continued to recover from the pandemic. Over the full year, FY22 Group Sales were 16% ahead of FY19.
All booked Sales over the year relate to new bookings. The sales of many other operators over the same period will be flattered by a proportion of their bookings rolled over from previous periods or booked using vouchers or refund credit notes ("RCNs").
The Group has never issued vouchers or RCNs in lieu of refunds. Where customers have been refunded using vouchers or RCNs from other operators, they are then captive to that operator, narrowing our addressable audience this year. The Group believes that our enhanced proposition and reputation will allow us to target these customers in FY23 when the playing field is levelled.
My comment: They have had to work very hard to differentiate themselves and look for new opportunities in the last 2 years. 5* holidays is one of them.
The Group has materially invested in its brand, technology, and customer proposition throughout the year. This includes offering a differentiated customer experience with premium lounges and fast track security, increasing headcount in technology and customer service areas, and investing in above the line media to drive awareness of the brand. These investments, combined with improved access to a broader hotel portfolio have resulted in FY22 growth in 5* holiday sales of 83% vs FY19, contributing to total FY22 ABV growth of 31% versus FY19.
My comment: this is another - B2B and long haul. Together they will be small compared with the bread and butter 3* holidays (see their decline below in 2022 vs 2019, but we will see their financial impact when the prelims come out on 8th Dec.
On the Beach also continues to make good progress in B2B and Long Haul. B2B sales were 45% ahead of FY19. Long Haul sales were 257% up vs FY19.
Partly due to continued rising costs of living, the lates market for value holidays has remained subdued in H2FY22 and as a result, sales of 3* holidays for FY22 were 18% below FY19. The Group is committed to maintaining its focus on this important segment and growing its share of value holidays.
Despite heavily disrupted trading throughout the financial year, and the Group continuing to strategically invest ahead of full market recovery, the Board expects underlying PBT performance for the period to be in line with market expectations. OTB exits the year with a strong cash position and balance sheet flexibility.
The Board is confident that the strategic actions taken during the pandemic, together with continued investment made in FY22, ensures the Group exits the year in the best possible position to grow market share across its core addressable market and expansion areas in FY23.
Re: On Beach group (LON:OTB)
Does anyone know the latest Peel Hunt or Numis forecasts? Was told they've cut estimates but us plebs are none the wiser.
Im actually thinking of refusing to buy any company using brokes who don't make research available, its a real disadvantage not to have it and shows a certain arrogance by management.
On Beach group (LON:OTB)
2022 year end net cash forecast >£60 million.
Peel Hunt 2023 PBT forecast today £26 million. Numis £29 million. 20% cut to prior forecasts.
If you believe them still very cheap.
Thanks Robbie
Several months ago I requested Paul's comment on On Beach Group (LON:OTB), and promised he will look into it when update comes. when you have time I will appreciate if you give us your take on this please.
Hi Eesha,
"Several months ago I requested Paul's comment on On Beach Group (LON:OTB), and promised he will look into it when update comes. when you have time I will appreciate if you give us your take on this please."
I think we looked at On Beach group (LON:OTB) recently, and thought it looked interesting. Yes, here we are - I reviewed the interim results here on 1 June 2022. this was my conclusion back then -
On Beach group (LON:OTB) - I check out its interims to 3/2022. Still impacted by omicron, it only reached breakeven in H1. The future's looking more bright though. Could be quite good, but lots of travel shares look cheap now, so I'd be inclined to look at a few, and maybe buy small positions in several? Balance sheet is adequate, but it's good to see customer deposits ring-fenced in a trust account. [SCVR 1 June 2022]
Ah! I've just twigged what you mean, I said I'd look at it again today.
Looking at the update today for FY 9/2022, it's just in line, so not of any significance - the key bit says -
"Group underlying PBT performance for the year is in line with market expectations. OTB exits the year with a strong cash position and balance sheet flexibility"
The pandemic impacted the early part of FY 9/2022.
Cash refunds were given, instead of vouchers, which has caused a short term headwind vs competitors, but enhanced the brand.
Tougher trading conditions more recently.
Claims a strong balance sheet, but no figures given. I concluded that the balance sheet was actually not particularly strong, when I reviewed the interim results.
Good grief, I've just noticed that the share price has more than halved since I last looked at it in June! (95p now, 204p on 1 June, when I wasn't enamoured by the fundamentals, but thought the chart looked like it might bounce LOL! I shall definitely stop trying to be an amateur chartist!)
Conclusion - pre-pandemic this was a good growth stock, with nice margins. Earnings, and the share price, have really come down. This could be worth investigating further, as a recovery share, maybe? It's starting to look cheap I think.
Regards, Paul.
Thanks for cherry picking all the positive points, but missing out the big outlook statement by the On Beach group (LON:OTB) CEO at the end?
"Despite the tougher trading conditions at the end of the year...."
Big shout out and thanks to Paul and the member Albm7 who flagged up the Superdry (LON:SDRY) shenanigans.
For once I got out in the nick of time. Even made a profit! Off to blow it all on a packet of Pringles
Made me chuckle.
I will make a brief comment re Whitbread (LON:WTB) and the backdrop. I spent yesterday looking at corporate bonds...save to say you can get 7% in blue chip short to mid dated bonds. Why mention this... well its pretty important for lots of things, why have the hassle of B2L property if you can get 7% in BATS Corporate Bond? and the link to dear old Whitbread (LON:WTB) .... well its too expensive isn't it? 20x on a 2% dividend....with a UK recession looming. I don't mind Whitbread, nice company, good environment to increase the platform... difficult cost backdrop though. For me this isn't GARP.
Whilst I'm positive about the backdrop for equity investing.... these Bond yields are a significant hurdle to equities delivering little growth. When assessing value its worth bearing in mind low risk 7% is available. Strikes me as rather positive for the wealth management sector.
Where can I see a list of Corporate Bonds?
Try Hargreaves Lansdowne’s website.
Try Hargreaves Lansdowne’s website.
https://www.hl.co.uk/shares/co...
The Tesco 2042 or the HSBC 2040 are yielding over 7% if held to redemption. Whether that's good value is dependent on your view on inflation and your tax status.
timarr
Hi, can I ask how that's worked out ? I see they're for sale at 89p to buy, and they're showing a yield of 4.875, I appreciate that in 2042 they'll give you a pound back for your 89[ and in the meantime they'l pay you 4.875% of what you pay for them, but it's 20 years, and you're only getting 11p extra, that'd be maybe 15 % max ? I've never bought bonds, so this is a genuine question , feel free to add, stupid boy in a captain mannering kind of way !) thanks !
G
Hi kenobi
Well, I use a yield to maturity calculator, rather than trying to work it out myself :-)
But if you take the Tesco 2042 (and I haven't looked at any of the details, including the spread) then you currently have a price of £83.5 on a face value of £100 with a yield of 4.875%. It's bounced a bit since I posted originally.
Logically if the yield is 4.875% at £100 then it must be greater at £83.5. And it is, it's about 5.8%.
And then you add on the extra £16.5 you get at the end - so the yield to maturity is obviously over 5.8%, roughly around 6%.
But in reality you have to take the spread into account and how often the coupon is paid, so it's easier to use a YTM calculator than do it yourself.
timarr
wisealpha (a marketplace for fractional corp bonds)
Some of the yields are a massive bargain or an indication of impending company failure. I dont know which either.
I use Saxo.... on the left under explore select bonds and you can filter by currency and geography. There are also bank FRNs you can look at . decent cash returns available now without going too far out in maturity.
Thanks RDHowarth,
I agree very much, and have mentioned bonds a couple of times in my podcasts. They're looking attractive, for the first time in many years. Especially if you think that inflation is likely to come back down again in 2023, which is credible given that the big inflationary input cost prices are now easing, and in some cases, even going into reverse. Although wages & energy are a big concern still, but these are going to annualise in the not-too-distant future.
Also, locking in a bond yield of 7% now, could end up giving you a nice capital gain on top, as yields reduce, once inflation is falling.
As you say, if cash is being sucked into the bond market, then it puts pressure on equities valuations, and makes it more likely that fund managers might have to sell some of their equities to meet redemptions from investors who want to switch from equities into bonds.
So yes, I agree, bonds look an attractive area to research.
We did have a subscriber here who is a bond expert, and he posted a superb podcast a couple of years ago. I can't remember his name, annoyingly. If he's still around, I'd like to invite him to do an audio interview with me! So please do get in touch if you're reading this.
Best wishes, Paul.
Hi Paul, I believe it was Paul Hawkins @Hawkeye_74 on Twitter - a PI World 2020 special iirc.
EDIT - this link should take you to his interview https://www.piworld.co.uk/educ...
Thanks Brilliant Leader, I've reached out to bond expert Paul Hawkins, and we're trying to sort out a podcast for later this week :-) I'll come up with some basic questions, and then invite readers here to submit your (succinct please!) questions as well.
Cool well done... on one level a complex subject....but on another, Lloyds 7.625% 2025... trades at 102 now so a 2% guaranteed loss! Maybe it goes sub 100 next week after MPC... my unsophisticated approach is as short as possible, blue chip quoted Co., below or v close to par. Some of these bonds have min £100k investment level but not all... Lloyds is 1k. I'm also less keen on v low coupon since the path to redemption is less certain.
Thats not a rec. these are just the facts .... you have to decide for yourself if that's interesting. It illustrates the importance of growth in equity valuations. A lot of equities aren't very interesting if growth is getting more difficult unless yields come back down to force us back up the risk curve.
Lloyds 7.625% 2025... trades at 102 now so a 2% guaranteed loss! Maybe it goes sub 100 next week after MPC...
This isn’t how you should view it. Forget the coupon of the bond. All you should consider is the Yield To Maturity in 2025. Work out what it is at 102p including any dealing costs and accrued interest. Bond investing is not as easy as it first appears to newbies.
Not quite, because the coupon shortens duration and therefore if the inflation / interest rate environment pans out against current investors (both rise) ....you are protected from drawdown. In a low coupon bond you may have to hold to maturity...since your return is tied up in the redemption value. You have more flexibility and as the above bond illustrates to me, plenty to go for in decent coupons and short duration. I know what YTM is thanks..
Not quite, because the coupon shortens duration and therefore if the inflation / interest rate environment pans out against current investors (both rise) ....you are protected from drawdown. In a low coupon bond you may have to hold to maturity...since your return is tied up in the redemption value. You have more flexibility and as the above bond illustrates to me, plenty to go for in decent coupons and short duration. I know what YTM is thanks..
Yes, this is true. But you wrote:
Lloyds 7.625% 2025... trades at 102 now so a 2% guaranteed loss!
Which sounds a bit naive on the face of it, with the clear indication you intended to hold to maturity.
apologies but actually that's kinda my point.
I can hold to maturity and lose 2p in the 100.... taking the income as return ... and even if Lloyds were downgraded etc ... I can hold for 2.5 years and get a 7% return to maturity with my 100 back. So the fact you are guaranteed to lose is another way of saying you get your 100 back.... which is harder to argue in longer dated securities.
Now in some respects the risk to me, as I can hold to maturity is only mark to market. ie interest rate impact and a credit downgrade. The high coupon offers some protection. Now some might say its not the bottom etc... and I agree but I guess my thinking is .... I think 7% is pretty good.
Don't get me wrong, I don't see this as sell some equities buy some bonds... more, if like me you are running high cash levels, then there are interesting things to do.
can anyone recommend a 'bonds for dummies' resource ? as I'd like to learn more !!
the Paul Hawkins video will be a good place to start by the looks of things, thanks for posting @brilliant leader
I can hold to maturity and lose 2p in the 100.... taking the income as return ... and even if Lloyds were downgraded etc ... I can hold for 2.5 years and get a 7% return to maturity with my 100 back. So the fact you are guaranteed to lose is another way of saying you get your 100 back.... which is harder to argue in longer dated securities.
Trouble is I'm being quoted 106.295p which makes it a no-go because the YTM is nothing like 7% at that price, so I'm not sure who quoted you 102p yesterday? Also this issue was tendered for in August and the original 750m nominal is now down to only about 270m left in circulation, so liquidity may not be so good.
Thanks. I’ve had similar thoughts (prompted by the 30 gilt going over 5% a few weeks ago but which I was too slow to execute). However, there are now plenty of stocks out there yielding 8%+, which offer the potential for capital growth as well as the dividends over a medium term view. Having said that, it still feels brave to be buying stocks… decisions, decisions!
Dare I says that the problems within Superdry (LON:SDRY) stem from WFH? I don't hold as I sold my shares at 479 pence well before Covid broke out, not being able to stand the stress of the Big Dipper.
Well that's guesswork, because we don't know if working from home (WFH) has been a contributory factor or not in the accounting problems at Superdry (LON:SDRY)
Since the problems actually pre-date covid, and have been reported in Annual Reports going back to 2019/20, then it seemed more deep-rooted.
Problems like this are a damning indictment of SDRY's CFOs, and clearly they are totally incompetent.
I find in situations like this, the reported problems can often be the tip of the iceberg, and accounting problems always seem to over-state profits & assets, funny that!!
Paul, I may have to take that back about WFH but I'm sure there are none in regular employment so keen as youself ;-) Here's a Stock graph:
It shows the last 11 years of performance and being wet behind the ears in 2019 I thought the dip I bought into would behave as before. Realising my mistake in time for a change, the 11 grand I put in was reversed out with half a grand in profit in my hands. How could things go so bad especially with Julian Dunkerton the co-founder putting so much trust and cash into the business I can only guess at.
Silver
Shoe Zone (LON:SHOE) I would welcome your thoughts on todays results please Paul & Graeme
Shoe look to be shining ;-)
Particularly good to see net cash up at £24.4m
Share buyback to continue
Second 3p interim dividend welcome
I hold
Hi AstonGirl ,
But there is no cash flow statement to see where this big jump of net cash comes from.
Working capital adjustments and/or sale of freehold properties?
Thanks
Is it such a ‘big jump’ though?
At the interims back in May the cash was £13.9 million
Today it’s £24.4 million. This isn’t even double the half year cash (which was boosted by property sales) so seems about right
And let’s not forget that £24.4 million is approximately a quarter of their £88.2 million market cap which has to be a good thing in my book
I think my post was very clear.
There is no cash flow statement to come to a safe conclusion where this increase in net cash comes from. My assumption is that most of it is from favourable working capital movements and/or sale of freehold properties.
A similar case in net cash ( that made no sense at all ) was promoted through twitter and other social media platforms for TheWorks.co.uk plc and we all know where its share price has ended.
However I have to say that Shoe Zone is a good company returning cash to shareholders through buybacks and dividends. It’s just its current net cash is boosted by favourable working capital movements.
Perhaps Paul can give us his expert opinion on this.
Hi yiannos1,
I think that's a fair query to raise, and I did the same in the section above about Shoe Zone (LON:SHOE) - net cash/debt figures on the balance sheet date are just a snapshot, and can move around all over the place, due to timing of things like payment runs to suppliers, payroll, VAT & other large tax outflows.
Hence we only really get the full picture when we see all the numbers when the accounts are published.
SHOE does look a cracking business, but I agree that there might, stress might, be some temporary factors boosting year end cash a bit.
This doesn't alter the fundamental investment case for SHOE, which I think looks excellent. But to be fair, yiannos1 does make a valid point too, I think. We can check it all out when the full figures are released.
Best wishes, Paul.
Some firmness in UK small caps today. Does the combination of falling gilt yields, low valuations, still weak sterling, the installation of a smart, competent, untainted (except by his wife's money) PM and the prospect of fiscal rectitude signal a turning point for UK small caps? Add in easing supply chains in some areas and lower shipping costs and there seems to be potential for greater risk appetite. All provided there are n more shocks out of the Ukraine conflict, I guess.
Of these, the fall in the 10-year gilt yield seems to me the clearest indication that we may have formed a bottom. Where the bond market leads the equity market follows.