Small Cap Value Report (Tue 26 June 2018) - CRL, CRPR, CPR, DSG, RDT, VEL, PRSM

Good morning, all.
Today I am interested in:
- Creightons (LON:CRL)
- James Cropper (LON:CRPR)
- Carpetright (LON:CPR)
- Dillistone (LON:DSG)
- Rosslyn Data Technologies (LON:RDT)
- Velocity Composites (LON:VEL)
- Blue Prism (LON:PRSM)
Lots of updates today, let's see how far I can get!
Cheers
Graham
Creightons (LON:CRL)
- Share price: 27.75p (+7%)
- No. of shares: 60.6 million
- Market cap: £17 million
Please note that I currently own shares in CRL.
Creightons Plc (the "Group" or "Creightons") is pleased to announce its preliminary results for the year ended 31 March 2018.
This is a small company in the sector often referred to as "FMCG" - fast moving consumer goods. It makes haircare, skincare and beauty products.
I bought into it after its "good" profit warning a few months ago. I've topped up my holding today
The issue was that Creightons couldn't handle all of the demands upon its manufacturing capacity. So as not to let down external customers, it outsourced the manufacture of its own branded products.
Unfortunately, manufacturing own-branded products is where it makes its highest margin.
As a consequence, gross and operating margin were reduced by £229k in these results.
Even without this problem, gross margin would have fallen due to rising raw material costs and other input prices.
By my maths, even without the capacity shortage, the gross profit margin would have fallen to 41.3%, from 42.5%.
From a more positive point of view, we can say that on an absolute basis, the gross margin contribution still rose rather impressively, due to rising sales:
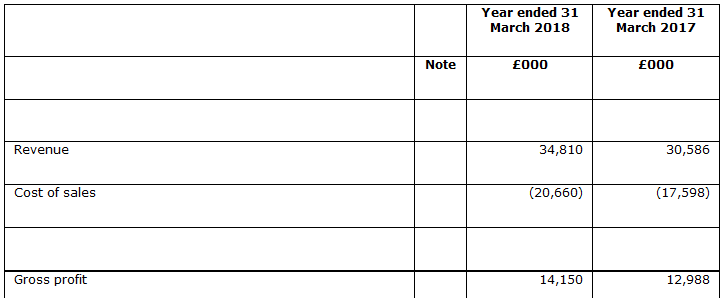
The capacity shortage increased Creighton's distribution costs, too - an operating expense.
The operating profit margin reduces by 0.2% to 4.7%. In the absence of capacity issues, operating profit margin would have increased to c. 5.6%.
So the quality of the performance clearly deteriorated from an operating margin point of view, due to this problem.
But again, on an absolute level, operating profit increased, due to the higher sales throughput.
I believe the capacity issue has now been addressed, to meet recent levels of demand:
The Group chose to outsource some manufacturing for a period while we invested in personnel and equipment to meet unexpectedly high growth in demand. This has been successful with all previously outsourced manufacturing brought back in house by the end of May 2018.
Of course, it is possible that demand will once again outstrip supply in the months and year ahead. If that happens, profit growth will not be as rich as it might otherwise be.
But this is a nice problem to have, I feel. I'd rather own shares in a business which has under-invested relative to its growth, than one which has over-invested.
If you add back the £299k of capacity-related costs, operating profit for the year was £1.9 million.
The company's cash position has been significantly reduced (to support its growth, according to management). Nevertheless, it retained a small net cash position at year-end. The dividend for the year is unchanged, offering a token yield of c. 1.5% for investors at the current share price.
In the absence of any material finance costs, my adjusted profit number of £1.9 million only needs to be reduced by a normalised tax charge. Applying 19% gives me a net income figure of £1.57 million.
This is the normalised net income figure I am using to determine the present valuation, so at a market cap of £17 million I get an adjusted trailing P/E ratio of 11x.
Looking at the quality of the performance from a balance sheet point of view, according to my calculations the company employed average fixed assets plus net working capital during the year of £8.7 million (ignoring intangibles).
Using the actual operating profit generated of £1.6 million, that suggests a return on tangible capital employed of c. 18.9%.
This is in the same ballpark as Stocko's calculations for Return on Capital, probably using last year's numbers:
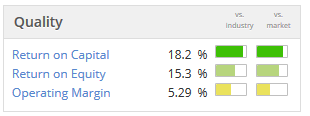
I would like to see this metric improve, as own-brand sales continue to grow and are manufactured in-house.
Note how the company generates a strong return on capital, despite a low-ish operating margin. That's only made possible by running a very efficient balance sheet, such that you generate a large quantity of sales using very little capital.
Creightons reckons that its balance sheet efficiency has actually improved, at least on the basis of stock turn:
Higher forecast sales in the first quarter of 2018-19 have driven increases in inventories with underlying ratios significantly improved. Stock turn, based on cost of sales in the months prior to the yearend, improved to 4.5 times compared to 3.5 times in 2017.
My view
I am cautiously optimistic. I like "good" profit warnings, as they can be a great time to buy a good stock at a discount (this is not easy to find, however - most profit warnings lead to future under-performance).
I also like quality companies trading at reasonable prices. That's the essence of Greenblatt's Magic Formula, according to which Creightons almost has a top rating:
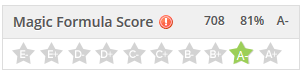
The Magic Formula does not take the stock's Momentum into account.
Given that Creighton shares had been trading up at 45p last year, it's clear that the stock doesn't enjoy a lot of momentum right now.
Indeed, momentum is what's holding back its StockRank at the moment:
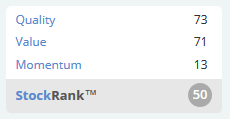
Personally, I don't mind waiting for Momentum to return to this stock.
Something else worth mentioning: I've been impressed by management presentations I've seen online. They strike me as knowledgeable, disciplined and realistic, while also harbouring significant ambitions for the long-term development of the business.
So I'm holding this stock and will hopefully participate in its future progress.
James Cropper (LON:CRPR)
- Share price: 1422.5p (+2%)
- No. of shares: 9.5 million
- Market cap: £135 million
This "advanced materials and paper products group" has hit a bump in the road, as anticipated:
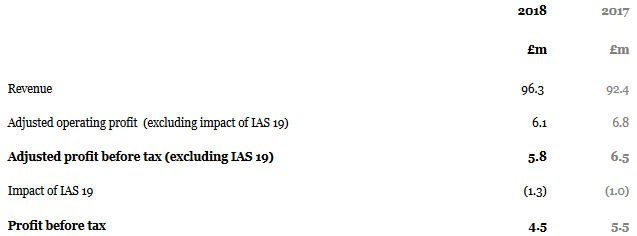
IAS 19 is the accounting standard that governs how pension costs should be measured.
Personally, I don't believe that the accounting standards concerning pensions are unnecessarily harsh on companies. So I would be inclined to use the actual PBT figures shown above, not those which use the company's own version of its pension costs. Like many accounting issues, this is a matter of opinion.
Paper
Getting back to simpler matters, the basic cause of Cropper's reduction in profitability is the increase in pulp prices. These increased costs by £3.5 million - very significant, relative to total pre-tax profit of £4.5 million.
It's very easy to miss a company's sensitivity to commodity prices, until things go wrong. Accrol Group (LON:ACRL) mentioned that pulp prices were an important factor in its admission document. But if you weren't watching these prices, or hadn't read the admission document, then it was easy to be caught off guard when its financials collapsed. I had written about it a few times, and failed to spot this sensitivity.
3D Products
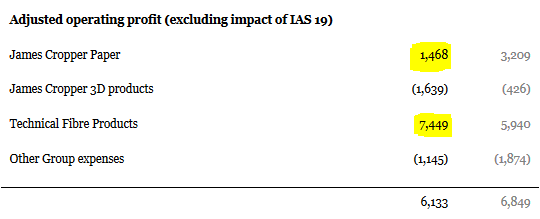
Besides the Paper division, another division called "3D products" has generated a small amount of revenue. It's taking longer to commercialise than previously anticipated. Increased losses were seen in this division, also significantly affecting Cropper's operating profit result.
Technical Fibre Products
By far, Cropper's most profitable division this year was TFP (Technical Fibre Products). This sounds more high-tech:
We work with a broad range of specialist fibres including, but not limited to; carbon, aramid, metal coated carbon, glass, polyester and thermoplastics, and convert these into high quality nonwoven mats and veils. We can tailor the properties of these to fulfil our customers' specific technical or aesthetic requirements through fibre-type & binder selection as well as the addition of particulates to the structure.
TFP is achieving double digit organic growth, sales up 17%.
This division has similar challenges to Creightons:
Recently installed capacity is ensuring demand is met.
Additional capacity is being planned to support continued volume growth.
Add it all up, and this is the summary of each division:
Outlook remains very positive for the long-term:
As intimated by the recommended final dividend increase, the Board and I continue to be excited about the prospects of the Group. We recognise there are significant challenges in recovering the margins lost in Paper to pulp costs and that continued research, innovation and investment will be vital to maintaining our position and creating future value.
My opinion
Overall, I have a positive impression of the company.
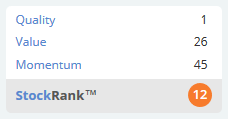
The StockRank isn't too high (27), as it doesn't appear to offer much value at the current level.
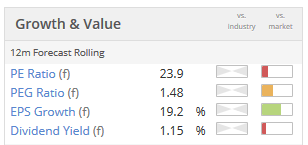
I also can't see why it deserves such a high rating as this. I'll leave it on the watchlist.
Carpetright (LON:CPR)
- Share price: 28.4p (-5.5%)
- No. of shares: 304 million
- Market cap: £86 million
Paul and I covered this stock several times in recent months.
Most recently, I noted the successful completion of its Placing and Open Offer.
232 million shares were issued at 28p, i.e. more than 3/4 of total shares outstanding today were issued.
The placing price can act like a magnet for subsequent share price action. Today's weak results have helped see the shares slip back toward that 28p level.
We have a dramatic reduction in EBITDA, and an underlying loss:
- Group revenue decreased by 3.0% to £443.8m
- Underlying EBITDA of £6.4m (2017: £28.6m)
- Underlying loss before tax of £8.7m (2017: profit of £14.4m), in-line with previous guidance
Net debt ballooned to over £50 million as supplier credit was withdrawn.
The equity financing took place after period-end, so we can't see it in these statements.
It raised £65 million, enabling the CVA proposal to go ahead with the approval of landlords.
Under the CVA, about 200 sites will either be closed or have their rent reduced by 30%-50%.
That's about half of the original estate.
Meanwhile, the entire estate is being refurbished with new branding a fresh fit-out.
So as I said last time, there is potential for a really significant improvement over the next 12-24 months. Although the trading update provided today is mixed:
In more recent weeks, following the approval of the CVA and completion of the recapitalisation, the Group has begun to see the benefits of stock replenishment by suppliers and less negative publicity, although UK like-for-like sales remained negative.
Factors contributing to the decline in EBITDA last year were as follows:
The margin was impacted by higher product costs in the UK as a result of the depreciation of Sterling against the euro, promotional measures taken to address competition and the inevitable disruption to trade resulting from the adverse publicity surrounding the restructuring.
The highlighted factor is the one which bothers me the most - increased competition.
Can carpet retailers differentiate themselves at all, or is it a fully commoditised product set?
Market valuations are saying that they are commoditised. Which is unfortunate for me, as I currently continue to hold United Carpets (LON:UCG).
I'm not planning to go bottom-fishing with Carpetright. While I think the company has a good chance of making a financial recovery in the short-term, I worry that competition will remain too tough to make it a comfortable long-term hold.
3pm: Time is getting away from me - I will need to speed up coverage of the remaining stocks!
Dillistone (LON:DSG)
- Share price: 64p (-18%)
- No. of shares: 20 million
- Market cap: £13 million
Dillistone Group Plc, the AIM quoted supplier of software for the international recruitment industry, is pleased to announce a trading update ahead of its Annual General Meeting
It's a dour update in reality.
Recurring revenues are down for its existing systems and its new product, GatedTalent, has not achieved the take-up that the company was looking for.
GatedTalent is a tool enabling high-level executives to chat with recruiters.
The update concludes as follows:
We had anticipated that GatedTalent would be loss making in 2018 and this remains the case. The lower than anticipated initial number of profiles and subsequent delay to profile monetisation will impact further on revenue. As stated above, the Board is aiming to deliver a growth in profits year on year, prior to the impact of the anticipated GatedTalent loss, acquisition related items and the impact of IFRS15 adjustments.
I have looked at this stock once before, and didn't see it having many attractions the first time, either.
It still has £1 million of cash but doesn't look particularly cheap relative to earnings or fundamental quality.
Good luck to holders but this one is not for me.
Rosslyn Data Technologies (LON:RDT)
- Share price: 4.65p (-3%)
- No. of shares: 188 million
- Market cap: £9 million
Rosslyn Data Technologies plc (AIM: RDT), the provider of a leading cloud-based enterprise data analytics platform today announces a trading update for the year ended 30 April 2018.
I intended to cover this in a little bit of detail but have quickly concluded that it is not something I can contemplate investing in.
It has made a significant loss in FY 2018 and is down to less than a million in cash. It says it is on track to achieve cash-flow breakeven "during the current fiscal year".
But it has been loss-making for its entire existence, and accumulated losses have grown to £15 million. This could be the point at which it finally turns around but it remains too speculative for me.
Stocko algorithms also provide a warning:
Velocity Composites (LON:VEL)
- Share price: 67.5p (+5.5%)
- No. of shares: 35.8 million
- Market cap: £24 million
Velocity Composites plc, the leading supplier of advanced composite material kits, providing engineering value-solutions for the global aerospace industry, is pleased to announce its interim results for the six months ended 30 April 2018.
A couple of things jumping out at me from these results.
- Gross margin rather low, at 15.2%. Suggests there is not much "value-add" being performed by Velocity. The company is conscious of this, and points to higher gross margin of 18.2% in April (performance over a single month is not too important, however).
- Visibility over revenues appears low. If you scroll back to the April trading update, you find a very long and complicated explanation as to why contracts were delayed and revenues and profitability for FY 2018 were set to be lower than originally anticipated.
This appears to be the nature of the business that it is in, delivering kits for the production of aircraft parts. Aircraft is a lumpy business that depends on oil prices, upgrade cycles, etc. While it should grow over time, it will never be predictable.
The outlook statement today reflects the unpredictable nature of results:
Board remains confident of meeting the market's revised full year expectations, subject to customer demand fluctuations
Customer and programme pipeline remains strong with over 60% of FY19 revenue market expectations and over £60m of business for the remainder of FY18 through to FY20 under contract
So there is still some uncertainty over FY 2018, and up to 40% of FY 2019 revenues are still up for grabs.
The explanation for the operating loss is that there was "continued investment arising from the Company's listing, additional sites and growth strategy."
It doesn't strike me as a particularly helpful explanation, and I'm left without any particular reason to believe that things are set to dramatically improve.
It is priced at a trailing price/sales ratio of approximately 1x but given the low gross margins, losses and lack of visibility, that strikes me as generous.
Blue Prism (LON:PRSM)
- Share price: 1834p (-1%)
- No. of shares: 67 million
- Market cap: £1,223 million
This is a massively high-flying robotics company.
It is creating a new workforce of software robots to take over mundane human chores.
The key sales number is now as follows:
Exit run-rate (recurring licence revenue) increased to £4.4m per month at 30 April 2018 (30 April 2017: £1.7m per month)
So if it stood still from the April 2018 level, it would generate £53 million of revenue per annum.
Stocko is showing a forecast sales figure of £52.6 million for FY 2018.
Compare that to the market cap of over £1.2 billion.
It's impossible for me to value this company. I just think it's worth mentioning, as investors are obviously willing to pay up for it. We don't often see price/sales ratios like this!
Made it through the entire list!
Have a good evening.
Cheers,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
£D4T4
FAO PTG/DVQS
Interesting that the big customer is SAS. I saw the list of partners in the last Annual Report and was impressed to see the more familiar Microsoft and Adobe in there (the others mentioned being Teradata, SAS and Pegasystems).
I still don't understand why GM% has gone up though. Have they lost sales through other partners? I notice that there were x2 customer who contributed >10% of revenues in 2017, reduced down to just the x1 in 2018.
I certainly agree that risks will be mitigated if partnerships are with sub-groups within a larger organisation.
My understanding is that the cross-selling of SAS solutions by D4T4 will be included within the £232k "agency" revenue that was in the screenshot in my previous post.
Cheers
by low risk I mean if the entry is around the current price of 1860 with a stop at say 2020 so a defined loss of 180p depending on spread ..assumes Blue Prism (LON:PRSM) isn't acquired or gaps up over one's stop (and if it does you get out and suck it up).. that is controlled by stake size with a scaling in on positions (i.e trade management).
I also have rules on ATR and liquidity so Blue Prism (LON:PRSM) simply isn't liquid enough for me to short (I need min daily volume of 800K in "normal" trading so not distorted by price dislocations).
Technically one has to use price action and chart analysis to identify shorting opportunities. Particularly volume behaviour around price changes. I never short on a principle or a hunch but always based on analysis and with rule for when my shorting hypothesis is violated (So I am wrong)
Finally, I build stakes in a short so start small and scale-in if the short is working , I use staggered stops which shadow each other to maintain risk/reward and stake sizes. I also analyse and follow short interest to make sure I am aligned but not too late as short squeezes can be spectacular.
£PRISM has only a 1.9% opn interest atm which is low when one considers IQE (LON:IQE) is at 9.7%
Need rules, discipline, process, structure and above all else, consistency. The right risk:reward ratios outdoes the percentage of right: wrong shorts if managed correctly
£D4T4
Hi peterthegreat
The reply function doesn't seem to be working so I'm re-posting my response here. Apologies for any duplication.
Evening
62%
The 62% figure came from near the top of the Notes section within the results released today.
£12.4m from x1 customer, out of total revenue of £20.1m (62%)
Screenshot here:
Third-Party/Reseller
A reseller could make sense, however, the following makes me doubt this is the case:
If a reseller was this #1 customer I would have expected gross margin to go down in 2018 if that same seller contributed proportionally more to the top line. Unless of course D4T4 sell their own product at a lower price than their partners, but I find this highly unlikely.
I could be wrong, or possibly even over-thinking it. Either way, this was a short-term punt based on the trading update in April. I generally don't like companies making most of their profits from project work as they can be lumpy (see * below), but I thought there might be something in the recurring revenues. However, 6% recurring revenue growth YOY doesn't give me enough conviction to continue to hold.
Good luck!
A
*
H1 2017 sales = £10.0m
H2 2017 sales = £7.7m
H1 2018 sales = £4.8m
H2 2018 sales = £15.3m
D4T4's major customer is SAS whom they have worked with since 2006.
https://www.sas.com/en_us/partners/find-a-partner/alliance-partners/us-partners/d4t4.html
https://www.sas.com/content/dam/SAS/en_us/doc/partners/sas-grid-appliance-powered-by-d4t4-solutions.pdf
At a previous AGM there was a discussion concerning this reliance on one customer and the Board noted that they were acutely aware of this, however, they noted that SAS are a multi-headed Client (they sell into various parts of the SAS organisation) and thereby the risks are mitigated to a degree.
I will raise this again at the upcoming AGM.
Thanks very much drvodkaquickstep for your reply to my query about D4T4's big customer. It sounds as though SAS is more of a commercial partner than a customer. As the relationship between these two companies has been going since 2006 I guess it must be quite a successful arrangement so perhaps it will continue well into the future. I note that the SAS web site indicates that they both have input into the same SAS product so I guess these two companies must be working quite closely together. However. I guess SAS is the senior partner in this relationship as it is much bigger that D4T4.
Thanks very much abtan for answering my query about D4T4's biggest customer. I have also received help from drvodkaquickstep who indicated that SAS is this biggest customer and sales are to various parts of SAS. Assuming this to be so, it sounds more like a partnership agreement with SAS as the SAS web site describes D4T4 as a partner and they have been working together since 2006, including both providing input for SAS products. The web site also suggests that D4T4 is actually a reseller of some SAS products, although the much larger size of SAS suggests to me that it is likely to be the senior partner in its relationship with D4T4. Nevertheless, this is arrangement is likely to be more durable than a simple customer/client relationship (at least I hope it is). I agree about the lumpiness of the profits at D4T4 and more recurring revenues would certainly increase the attractiveness of the company.
Graham, thanks for the excellent piece of analysis on Creightons (LON:CRL). I think Paul might have some competition for "Journalist of Year" next year!
willhampson,
This year's AGM is on 18th July as per https://www.ramsdensplc.com/investor-relations/financial-calendar
anyone following Ramsdens (LON:RFX). CEO has just sold 25% of his shares to raise £900k. salary and bonus of £175,000 so the shares are a substantial amount relative. first sale since IPO. seems not unreasonable thing to do. shares marked down 8%. great buying opportunity. just topped up
Hi HornBlower, thanks for this. The coordinated sale of three PMDRs at Ramsdens Holdings (LON:RFX) all yesterday is a little strange. My hunch is perhaps yesterday was the final day before the beginning of a closed period. It may well be about 30 days until the AGM and they may intend to give a trading update at that time; a TU was given last year a few days before the AGM so as to coincide with the data breach announcement, but I suspect - but for - that data breach the TU would have been given at the AGM.
I can understand why this has spooked some people, particularly large CEO sales, but I intend to hold for now. I still find the valuation compelling and the growing dividends are worth having.
willhampson, This year's AGM is on 18th July as per https://www.ramsdensplc.com/investor-relations/financial-calendar
and two of the other senior management have sold too, halving their stakes.
The price of 180p for all 3 was around half of the SP fall on Tuesday. The total of nearly 1m shares must have found a home though, and I wold guess they have gone to an institution. (It is unusual for 3 top managers to sell so much at the same time, unless there has been a request from an institution to do so or unless the company news is doubtful) Not surprising really, after the great prelims.
I'm not sure that this is bad news - often director selling is, indicating that the SP has reached a peak - though there are one or two hints of caution about trends in the retail sector. Then they counter that by saying they intend to continue to extend their estate.
I have been an enthusiastic holder here and can understand why one would want to ones holding. I will maintain my stake at its current substantial level for now.and see whether an RNS comes out about where the near 1m shares have gone.
Thanks for flagging Hornblower. I have been pondering this since I saw it. I decided this morning to add to my already very small holding. The reasons I decided are:
1, It probably was the last day before the closed period before the AGM,
2, This is the key point for me. These are likely to be material sums for each individual, though I do not know that for a fact. However, I assumed they are and I mostly focused on the CEO sale. We are all working for a purpose and to take out £900k is probably a life changing amount of money, so is not unreasonable to do. This then becomes a point of timing. If he really is signalling the top, why not sell them all? I am probably being naive but am taking the view that he is entitled to take some profits and that his fellow directors may have simply followed him. If the next update is poor then it will certainly be (another) lesson learnt but I am hopeful that the sales weren't the warning shot that many fear.
3, The CEO still has a material stake and I can't believe he won't be working extremely hard to at least maintain its value, but ideally increase it.
Finally, what I don't know (or perhaps been too lazy to figure out) is how much cash they may have taken out at IPO and whether this amount is material in that context. Compared to £175k salary £900k is substantial but not if he took out a greater figure earlier.
One final scuttlebut point that is an amber flag to me. I emailed the IR email address some time ago to ask about their status as regards BPR and IHT. I have yet to receive a reply. This kind of thing does make me wonder about the professionalism at the organisation. Its not hard to reply even if its 'we don't know'.
For now I'm holding.
Regards
Hi Graham,
I see you have VEL on your list - woudl be really interested to hear your views, the sp seems to have moved up a little today (I hold).
Roger
Re Blue Prism (LON:PRSM) - An egg or a tennis ball?
I sold out on Blue Prism (LON:PRSM) a bit early (if very profitably), it is a real tricky one to value but their channel and GTM is super and having huge outsourcers like Accenture selling your products into incumbent clients is no mean source of scaleable low cost sales .
Added to this both Gartner and Forrester really rate this from a vendor PoV so it has pedigree. No doubt it is stretched (he says having sold early ;P) but I would be a reluctant short unless I saw some real volume conviction selling from a blow-off top. Blue Prism (LON:PRSM) hasn't even gone near its 200MA since July 2016 when it was 110p
That said it did double top yesterday and rejected the previous high, price action today is fascinating with a real bull-bear fight going on . It will be interesting to see how this finishes the day as the bulls seem to have it for now (13:40): 10% of today's volume went through off-book at 12:20 in a couple of big trades ...we will see who and what later I suspect ( if there is a TR-1) but price is holding for now just flat on the day having been down over 10%) .
In any case a short from here should be relatively low risk - just set a stop at above 2000p and sit back albeit the 10 day average volume is just 210K so it is relatively easily pushed around
I also work in IT, I am a very experienced developer, like someone else said. I came across Blue Prism when dumb management were telling everybody how great it is. So I was intrigued at the claims. But we couldn't find a single use case for it, a single case where you couldn't do it better with existing free software. And so were left scratching our heads at the hype.
So I have to give it to the BP marketing though. They have marketed it brilliantly calling it a Software Robot. But there is nothing Robotic about it. The Product or Robot (chuckle it's not) does not 'learn' the Process, and breaks when the process changes. It also needs to be configured by a Developer which is a very expensive cost on top of the licenses. There is also fierce competition in this space, there is no way imho that BluePrism will ever grow into it's current crazy valuation.
Thanks for this. I have not seen BP software myself, but have seen other tools with similar claims, and similar limitations, so I suspected this was the position. There are situations where tools of this sort prove useful, but using them always requires expensive skilled effort. It is plausible that BP's software might be better than the competition, but not that it can add anything like the value to justify the BP share price.
Marketing never lets facts get in the way of a good story. There are many similar technical arguments made against Apple but they do ok: Betamax was technically better than VHS, that didn't help the use cases ...the list goes on ..
£PRISM has a lot of backers and is well positioned by Gartner and Forrester who do influence a lot of CIOs and budget holders: see below, Blue Prism (LON:PRSM) is positioned as a market leader.. you may call this BS marketing even but I wouldn't underestimate their influence, (and I have transformation consulting background).
A likely exit for £PRISM is acquisition ...that could hurt if one is short
I'm not defending their technical prowess but in this case price is the only truth ..for now.
Re Blue Prism (LON:PRSM)
I do not think I can agree with the "relatively low risk" description.I have been doing quite a lot of navel gazing over shorting recently given that as discussed elsewhere I'm moving to becoming market neutral(ish) by using a diversified short portfolio.
My (very limited) past experience from memory in the past I think I have had maybe half a dozen short positions. The two most memorable (both over a decade ago) were Carpetright (LON:CPR) & Countrywide (LON:CWD).
Countrywide subsequently delisted and relisted whereas Carpetright is still with us (for the time being anyway.)
Countrywide (LON:CWD) was quite horrible (although thankfully quite a small exposure) given that despite being "ludicrously overvalued" it actually got acquired for a premium, IIRC by Private Equity.
Carpetright (LON:CPR) wasn't quite so dramatic, but despite also being "ludicrously overvalued" the price just would not go down, in fact it continued going up. This wasn't so much a case of the market staying irrational longer than I could stay solvent, but more a case of longer than I could remain confident.
Without checking my records I think I was probably "about even" on the other smaller short positions, there were certainly no memorable winners.
In actual fact though, these past misadventures should have no bearing whatever on what I am undertaking now. As mentioned above what I am now looking at is a diversified portfolio of shorts. These are mostly companies I know very little about, but that on the SRs statistically should under-perform. This does not totally stop me from "price watching" and flinching at each little tick up in any of them, but so far I am being good and not trading outside of plan.
My past failures, however, were "conviction shorts" I went short because I was convinced they were grossly over-valued.
Let me repeat that "over-valued". Now I cannot go back in time and prove it, but I know that both Countrywide and Carpertright had "momentum", I suspect that they also had a degree of "quality". They were I suspect "high flyers" in Stockopedia parlance.
Guess what? so is Blue Prism (LON:PRSM)
This dear readers is a winning style - you are statistically more likely to do better long than short.
It may well be a bubble (I'm inclined to think so) but the thing about "bubbles" is that the killer play is to be 'long' in the early phase and 'short' at or around the peak. Sadly most of us will either go short too early in the stratospheric rise or go long near the top (maybe even both).
Certainly I cannot think of a reason to invest here (other than the winning style) but that doesn't mean on should automatically consider a short.
You may strike gold shorting at these levels, but that is only similar to the chances of picking the correct sucker stock to go long.
Good luck to anyone that is short here, but for me, I'm more than happy to leave the tempting half volley outside off-stump.
By low risk I mean the entry is around the current price of 1860 with a stop at say 2020 so a defined loss of 180p depending on spread ..assumes Blue Prism (LON:PRSM) isn't acquired or gaps up over one's stop (and if it does you get out and suck it up).. that is controlled by stake size with a scaling in on positions (i.e trade management)
I also have rules on ATR and liquidity so Blue Prism (LON:PRSM) simply isn't liquid enough for me to short (I need min daily volume of 800K in "normal" trading so not distorted by price dislocations).
Technically one has to use price action and chart analysis to identify shorting opportunities. Particularly volume behaviour around price changes. I never short on a principle or a hunch but always based on analysis and with rule for when my shorting hypothesis is violated (So I am wrong)
Finally, I build stakes in a short so start small and scale-in if the short is working , I use staggered stops which shadow each other to maintain risk/reward and stake sizes. I also analyse and follow short interest to make sure I am aligned but not too late as short squeezes can be spectacular.
£PRISM has only a 1.9% opn interest atm which is low when one considers IQE (LON:IQE) is at 9.7%
Need rules, discipline, process, structure and above all else, consistency. The right risk:reward ratios outdoes the percentage of right: wrong shorts if managed correctly
Blue Prism: I wouldn't buy the stock at these levels but agree with Grahams comments above and certainly woundn't short it. I work in the IT sector and Blue Prism is the most common RPA software that large blue chips i come across are starting to use.
Regarding Blue Prism (LON:PRSM)
They are in a land grab, spending large amounts on expansion to ensure that they have a major presence in the rapidly expanding robotic process automation market. Additionally, they don’t capitalise development costs and revenues are deferred from their licenses to spread the revenues over the full duration of the license while commission payments etc are paid upfront. So, this means that they are unlikely to show profits soon.
However, cash flow is positive, there’s no debt and a placing to fund expansion has already been done.
Some people have poo-pood their product. Some of those people are IT professionals. But note that the emphasis is on some. It is clear from their rapidly increasing sales, their increasing list of Blue Chip clients, the attendance at their conferences and surveys from HfS analysts of this market that their product is highly rated by those that use it and that the product clearly fits well with the needs of a huge array of large corporations and public sector bodies. So, who are you going to believe as to the value of the product? I don’t believe you can dismiss the body of evidence that the product has substantial market acceptance in its particular niche.
So is this niche market set to expand rapidly? Yes.
https://www.interquestgroup.com/iq-hub/infographics/2018/robotic-process-automation-industry-forecast
The difficulty is that the company is very hard to value at this stage, but note that Old Mutual doubled their stake late last year and the recent (January) placing was at only 1.1% discount so there is significant institutional support.
I believe that they’ve barely scratched the surface of this potential market; the large investment in expansion will tail off in due course; profits will be forthcoming at that time. It is a stock for the patient investor.
You may have guessed by now that I hold!
Brief thoughts on £D4T4:
The Good
The Bad
I took a punt on this over the last few months and sold out this morning
Thanks abtan for your post about D4T4. 62% of total revenues from one customer does indeed sound worrying and I was wondering if you could tell me where this figure came from as I have seen it suggested on another board that this large customer is actually a reseller who sells to a range of other customers. Do you think this might be the case? Thanks.
Evening
62%
The 62% figure came from near the top of the Notes section within the results released today.
£12.4m from x1 customer, out of total revenue of £20.1m (62%)
Screenshot here:
Third-Party/Reseller
A reseller could make sense, however, the following makes me doubt this is the case:
If a reseller was this #1 customer I would have expected gross margin to go down in 2018 if that same seller contributed proportionally more to the top line. Unless of course D4T4 sell their own product at a lower price than their partners, but I find this highly unlikely.
I could be wrong, or possibly even over-thinking it. Either way, this was a short-term punt based on the trading update in April. I generally don't like companies making most of their profits from project work as they can be lumpy (see * below), but thought there might be something in the recurring revenues. However, 6% recurring revenue growth YOY doesn't give me enough conviction to continue to hold.
Good luck!
A
*
H1 2017 sales = £10.0m
H2 2017 sales = £7.7m
H1 2018 sales = £4.8m
H2 2018 sales = £15.3m
Blue Prism , could you have a look, simply because of the insane valuation, and yet still no prospect of a profit. Good software makes profits from the early stages, but BPs doesn't.
Please check out the Trade receivables in the account and give your thoughts. Very strange.
James Cropper (LON:CRPR) please. Solid family company, Lord Lee is an investor I believe. Finals today. Looks a very high PE (23+) for a low growth pulp and paper business but the juice seems to come from its Technical Fibre Products and early stage 3D printed paper products that they see as an alternative to plastic. There is a broker note from Stockdale on Research Hub with a target price of 1750p (1433p today).
Thanks for the James Cropper (LON:CRPR) suggestion and for your comment - it was worth a look! G
What's the special interest in D4T4 compared with other software houses? The Stocko computers seem unenthusiastic.
Morning Graham,
Can I request you take a look at Blue Prism (LON:PRSM). Paul has commented on this in the past (as crazily over valued) - interims out today, lots of good sales talk but it's still racking up the losses, management appear to have used to lofty share price to both raise more funds and sell their shares. I don't hold but have been short in the past and would consider it again...
Stocko saying it is still estimated to loose nearly £14m on £79m of sales in 2019 (although this could be revised).
I just can't see how this company can be valued at £500m let alone £1.2 BILLION. Maybe I just lack the vision thing!
I went short Blue Prism (LON:PRSM) yesterday. I agree that whilst it is not a small cap it certainly should be. Anybody can sell pound coins for 90p, but it doesn't make for a viable business in the long term.
There was a good discussion on here in the past with somebody who had actually seen or used the Blue Prism "robots" which really reinforced the short case. It's just been a matter of waiting for a good entry point. I don't think the market is in the mood to blithely ignore the P&L of companies like this as much as it has been recently.
I don't see that much has changed since Paul's analysis here:
https://www.stockopedia.com/content/small-cap-value-report-wed-22-feb-2017-hotc-prsm-mcb-tmmg-lgt-ncc-172456/
Well other than the small matter of the market cap. It was about £300m then and Paul felt it was overvalued. It's about 4x that now and it isn't in much better shape than it was then.
I'm in no hurry to close my short.
Perennial jam (albeit non-calorific, no sugar) tomorrow stock OptiBiotix Health (LON:OPTI) announced another manufacture and distribution license with an unnamed counter-party this morning for their sweetbiotix product.
https://www.investegate.co.uk/optibiotix-health--opti-/rns/agreement-with-global-corporate-for-sweetbiotix-/201806260700015010S/
Perhaps unusually the counter-party is “big” (global £100bn t/o food and agri co) and they will be paid a 6 figure retainer during the duration of the license. Share price seems to like it so far, up about 6% this morning.
Gus.
Hi Graham
It would be interesting to get your interpretation of the latest trading update from Dillistone Group (DSG) as this business is both a mix of technology and recruitment.
Kind Regards
Emmett
Dillistone (LON:DSG) have a really good product, but the new data protection regulations seem to be giving it a massive hit. Their announcement this morning tries to put a good spin on this by saying that CEOs are signing up, even though lesser grades are not. Perhaps this is because they have secretaries to wade through all the correspondence. Profitability is bound to be hit in the shorter and medium terms. I sold out this morning, but will keep a good watching eye. The company has money in the bank, great connections, and a smart product. It is just stubbornly refusing to make a profit at the moment. (Sub 60 would be a bit of a bargain for the longer term, but it is closely held and very illiquid, so not for the trader or the feint hearted)
Emmett. I used to hold Dillistone (LON:DSG) but sold out near the lows at the end of Q3 2017 (which turned out to be awful timing). The management are personable but I got fed up with management talking up metrics of certain products (in 2016 it was file finder new orders) which ultimately had little financial relevance. I worry if the “hype” around Gated Talent will be similar. Also, while understandable, I was also put off by the directors funding themselves the 8.15% loan notes in Sep 17. While the reported cash position looks strong - there are quite a bit of pre-payments in there.
Hi Emmett, Dillistone (LON:DSG) is in the report now. I am struggling to find positive features of the stock but admittedly it is not one that I have studied in massive detail.
Best,
Graham
£D4T4 finals were underwhelming, sold out most of my position in the early liquidity, mind you they have rallied over 50% in the past 2 months so pleased with the short term profitability. Trouble is that any share that rallies that hard in such a short period needs to delight the market with results and guidance (which was woolly and vague) or suffer the profit taking.
Also interested in £D4T4 - thought the update was fairly good myself. Mind you this looks to me an essentially "software house" business model, so not sure how much room there is for a re-rating.
big increases in trade debtors and last year's back-end weighting of results looks like they have pulled forward revenue to make the numbers. That's fine if their pipeline is very strong but guidance doesn't support this.
Graham. Interested in your views on Creightons (LON:CRL) which I hold as a reasonably priced company given management's ambitious growth targets. Full year (to end-March) results out today, which look better than advertised in the profit warning of 8 Feb. On 8 Feb, company had said that sales had exceeded expectations (likely to be up 12% in FY, following only 7% in H1) and this had caused manufacturing capacity problems and the need to outsource production at higher cost - and as a result full year pre-tax profit would be "marginally below" prior year. Today, company says that sales were even stronger (up 13.8%) and pre-tax profit in fact rose 8%. Going forward, the manufacturing capacity issues appear to be sorted as chairman states that all previously outsourced manufacturing was brought back in house by end of May 2018.
What is worrying, apart from the company's ability to forecast its sales, manufacturing needs and financials accurately, is that cash flow conversion (which is normally good) was poor in both H1 (when sales growth was moderate) and in H2 (when it was strong), as working capital has consumed cash. Free cash flow for the year was negative £1.6million, compared to a post tax profit of £1.2 million.
The company is ambitious with the previously stated "ambition" to reach £60m of sales by FY2020 (partly through acquisitions) and an £800k capex requirement to boost manufacturing capacity to permit this level of sales.
Another vote for Creightons (LON:CRL) Graham. The results appear to be encouraging, although I would like to have seen a more specific outlook statement. Like Dave and Mercury I hold, albeit it is one of my smaller holdings; however tempted to add, but may let the dust settle first.
All the best
Jonno
Rosslyn Data Technology (RDT) warns on FY. Accepted some lower margin business in relation to a larger contract. Guides adjusted pretax (excluding one off costs associated with the Integritie acquisition) -£1.3m" but "We are extremely excited about the year ahead."
Excited perhaps in the Chinese sense,as in 'may you live in exciting times' !
re: Rosslyn Data Technologies (LON:RDT)
MrC
Are you excited, too?
Graham,
Another request for Creightons (LON:CRL) my largest holding where after a year of too much business (chose to temporarily outsource rather than drop customers) they have increased capacity so all now back in house. With new equipment, increasing percentage of own products and dropping lower margin stuff should result in hike in eps for current year.
Dave
Dave, Mercury, et al. Creightons (LON:CRL) now written up. Let me know what I've missed! G
Creightons (LON:CRL) a Speculative, Micro Cap, Contrarian, which has been commented on before in this year,says FY Operating Profit Up 8.1 Pct To 1.6 Mln Pounds
FY REVENUE INCREASED BY 13.8% TO £34.8M (2017: £30.6M)
FY OPERATING PROFIT INCREASED BY 8.1% TO £1,635,000 (2017: £1,513,000)
I hold.