Small Cap Value Report (Tue 27 April 2021) - STAF, TUNE, GMR, WATR, IHC

Good morning, it's Paul & Jack here with the SCVR for Tuesday.
Mello online investment show - today, free tickets here, starts at 11am until about 15:00. Feel free to dip in & out. All the companies presenting look interesting to me. I've got to think of something clever to say in my slot at 14:50!
Timing - TBC
Agenda -
Paul:
Staffline (LON:STAF) - quick comment re 2nd largest shareholder buying more shares yesterday. Augurs well for refinancing perhaps?
Focusrite (LON:TUNE) - sparkling interim results. How much is caused by lockdown? Not sure, but I think the higher share price here does stack up on fundamentals. This share gets a thumbs up from me.
Gaming Realms (LON:GMR) - quick review of its 2020 results & 2021 outlook. I continue to believe there could be good potential here, but unfortunately I can't fathom how to value the shares.
Jack:
Water Intelligence (LON:WATR) - great growth figures from this water leak detection specialist with corporate and franchise operations, but trading at a premium valuation.
Inspiration Healthcare (LON:IHC) - in line update from this ventilator provider that has seen a Covid-related boost in demand
Paul’s Section
Staffline (LON:STAF)
73p - mkt cap £51m
Holding in company - we looked at Staffline yesterday, so as a postscript, I see there’s an RNS today, saying that major shareholder Henry Spain Investment Services (a stockbroker based in Market Harborough) increased its stake in Staffline from 19.4% to 21.4% yesterday (on publication of a trading update).
Given that Staffline urgently needs an equity fundraising to repair its weak balance sheet, then I think it’s encouraging to see the 2nd largest shareholder buying more shares in the market. That suggests to me that the shareholder is probably going to be supporting in a fundraising.
HRnet owns 29.95% of Staffline, so these 2 shareholders put together have over 50%. Therefore if both are supportive, then a fundraising should be no trouble to get away, although they’ll also be heavily influencing the price. The danger is if they decide to heavily dilute small shareholders. Although I find that’s rare, since often big shareholders want to preserve the value of their own stake, as much as anyone else.
It will be interesting to see how this pans out, and it’s probably best seen as a special situation until the funding situation has been fixed.
.
Focusrite (LON:TUNE)
1,195p (up 7%, at 08:31) - mkt cap £700m
I’ve followed this share here since it floated in late 2014, with the share price since having multi-bagged (about 8 times).
Results today stand out as very strong, so I’m going to take a look at them, despite the market cap now having grown beyond my usual cut-off point of c.£400-500m. It seems a pity, and rather illogical, to stop covering the best companies, because they grow beyond an arbitrary market cap limit!
Acquisition - the third acquisition since listing in 2014 is announced. It’s a high end synthesiser company based in San Francisco, called “Sequential”. The price is £18m, of which £15m is being paid up-front. This is being funded from Focusrite’s existing cash resources, and a partial drawdown on its facilities from Nat West.
In the FY 12/2020 (unaudited), Sequential was profitable with both EBITDA and EBIT at $3.5m (strange that they’re the same figure, which implies it has no depreciation charge - so it must have little, or very old fixed assets!), on revenues of $18.3m.
It looks like a founder selling prior to retirement, perhaps?
This looks a good deal, and it’s going to be earnings enhancing (because cash on the balance sheet earns nothing, so better to buy something that is profitable instead), with other interesting aspects to the deal - e.g. co-developing new products.
Owner-managed businesses like Focusrite (Philip Dudderidge still owns 33% of the group) tend to make good acquisitions in my opinion, because it’s their own money they’re risking. Whereas hired hands, keen to empire build, often make a hash of acquisitions - look at how often we see “non-cash” impairment charges of goodwill, due to botched acquisitions at other companies.
Focusrite plc, the global music and audio products company supplying hardware and software used by professional and amateur musicians and the entertainment industry, today announces its half year results for the six months ended 28 February 2021.
H1 figures look stunningly good against the pre-covid prior year H1 comparatives. Although note that Focusrite seems to have been a beneficiary from the pandemic, much like Gear4music Holdings (LON:G4M) (I hold), since the lockdowns fuelled demand for their products from people developing hobbies in music, and other audio. Although in both cases, I think there’s also evidence that they are gaining sales from structural, long-term growth. We just don’t yet know the split of one-off, vs permanent growth.
Look at these highlights - pretty spectacular, including 64.3% organic growth in the top bullet point -

.
Amazing as those figures are, it’s worth noting that if you split last year into H1 and H2, then H2 was very strong (benefiting from lockdown 1). So sequentially the half year performance (i.e. H1 this year, vs H2 last year) is not quite so striking, but still very good.
Component shortages are mentioned, as causing supply problems, and is a global issue, likely to “affect supply for some time”.
Earnings - adj EPS is 36.3p for H1. I’m happy with the adjustments, which is almost all goodwill amortisation, which is fine to adjust out.
I can’t find any broker research, but Stockopedia shows the broker consensus for FY 08/2021 being 38.8p. Therefore, having achieved almost all of that in H1 alone, clearly the full year forecasts need to be greatly increased.
The difficulty is predicting whether, and by how much, sales/profits might reverse once lockdowns end fully? Some product lines (e.g. Martin Audio) are likely to benefit from re-opening, as live gigs and venues open up again & want to upgrade their speakers.
Also, the main product lines at Focusrite (61% of group sales) could continue to see strong demand, from the digitisation of music, and people creating music content & podcasts, etc, at home. I can’t see that trend reversing at all, although this is not my area of expertise. I’ll ask my family, who are musicians & report back.
Just spoken to the family, who told me: Focusrite products are excellent. Over lockdown, a lot of music teaching moved online, so musicians needed to buy a decent quality microphone & that usually needs a Focusrite interface. Although once bought, the setup will last years, so repeat business might be an issue. Any readers with knowledge of this sector, do please leave a comment in the comments.
Forecasts & Valuation - bearing in mind the above, I’m leaning towards assuming there’s some one-off boost to H1 from lockdowns. With 36.3p in the bag for H1, I might assume H2 could be a bit softer, maybe 30p? That gives 66.3p for the full year. Then maybe a step back to 50p EPS next year? At 1185p the PER is 23.7 times my guess of 50p future earnings. That looks reasonable, and based on what seem to me quite conservative assumptions. I haven’t factored in any extra earnings from the acquisition of Sequential either.
Based on this simple back of the envelope stuff, I think the valuation seems reasonable.
Hopefully there could be upside on my 50p EPS estimate?
Outlook - in H1 the group performed “exceptionally well” - which might be hinting that lockdowns brought a benefit which may not necessarily be ongoing?
Although the next bit suggests that growth could be permanent -
… revenue for the period being slightly ahead of our revised expectations as announced on 19 February 2021. As previously discussed, we believe the customer base has materially grown, with more people utilising these solutions for music creation, podcasting, social media broadcasts and other streaming workflows. The digitisation of almost every facet of modern life continues unabated, and audio is no exception…
We expect demand to remain higher than pre-COVID-19 levels for our ADAM Audio and Focusrite businesses, but recognise the uncertainty that the end of lockdown will bring.
While demand for Martin Audio products continues to be constrained by the shutdown of live events, we are now seeing the pipeline increase for both installed and tour sound business.
As always, we remain appropriately cautious given the unique global circumstances, but also optimistic about the future prospects for the Group."
Cautious and optimistic. What are we supposed to make of that?!
Balance sheet - looks healthy, no issues here.
My opinion - these are really impressive numbers.
I don’t know how much lockdowns have benefited TUNE, there must have been some benefit.
It’s difficult to buy a share that I’ve been observing for years, and has 8-bagged, but I’m happy that the current valuation can indeed be justified, even on fairly cautious assumptions, as demonstrated above.
Combine that with another good acquisition announced today, and the owner-manager model with the founder still holding 33% of the equity (much like Gear4music Holdings (LON:G4M) which I hold), and I think this share looks attractive.
Obviously I don’t have any idea what the future holds, that’s the problem. But based on the excellent track record, and that it’s selling into a large, global market, with products that do seem to have a competitive edge, then I imagine it’s more likely to do well in future, than badly.
Overall then, a thumbs up from me.
.
.
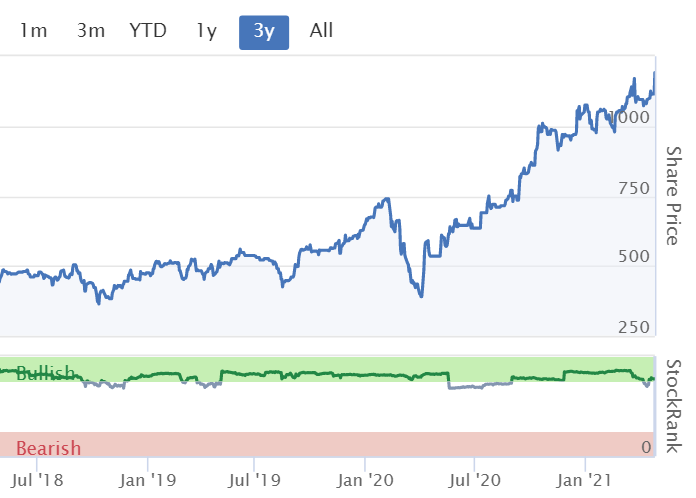
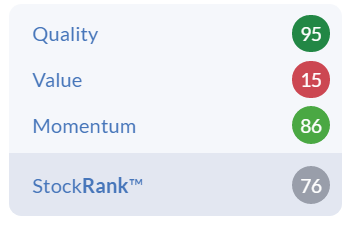
Note the StockRank below shows a poor value score. However, this is based on existing broker consensus earnings forecasts which are way too low. Therefore, I think we can manually adjust that to a higher figure, which should feed through if/when revised broker forecasts appear - although this share seems under-researched, and we don't have access to any notes, being insignificant little pipsqueak private investors! Bloody annoying isn't it.
.
.
Gaming Realms (LON:GMR)
40.3p (down 9%, at 11:51) - mkt cap £116m
This share has done phenomenally in the last year - it’s 8-bagged from the covid crash low in March 2020. It’s been on my radar for a while, as potentially interesting, but I haven’t got a clue how to value it, that’s the trouble with companies that are historically loss-making.
The share price has reacted negatively to today’s update, but as you can see below, that looks like a blip on a very positive chart.
.

.
Gaming Realms plc (AIM: GMR), the developer and licensor of mobile focused gaming content, announces its annual results for the year ended 31 December 2020 and Q1 highlights for 2021.
Impressive revenue growth of 66% to £11.4m
Profitability - pick a number which you prefer! Here are the options:
- Adj EBITDA (continuing) £2.94m
- EBITDA (continuing) £2.02m (after £468k restructuring costs, and £449k impairment)
- Loss before tax £(1.53)m - why such a big difference? The main costs are £2.82m amortisation of intangibles, and a heavy finance expense of £882k
Balance sheet - quite weak, NTAV is slightly negative at £(0.2)m. I cannot understand why the company hasn’t raised a bit more cash, given that it has a £116m market cap. In their shoes, I’d do a £5-10m placing, to make the balance sheet bulletproof, which wouldn’t be much dilution. Strike whilst the iron’s hot! There is no charge for this sage guidance!
Cashflow statement - the key number is £2.44m of capitalised development costs. This is perfectly normal for a software company, but it renders EBITDA meaningless. In the real world, this is not a profitable company, it’s trading at a small loss, once you take into account development spend.
Current trading -
… the Board has every confidence in the strategy being pursued and in the Group's prospects for the year ahead. The Company is trading marginally ahead of Board expectations.
Outlook - upbeat, but non-specific -
… strong pipeline of new and exciting branded Slingo games, the Board is confident in the future prospects of the business and looks forward to keeping its shareholders updated on progress."
My opinion - neutral. I like the growth, and the products are clearly well-established, and Slingo looks a fun game, with an impressive client list, especially in the USA. So there’s lots to like here, I completely understand why some investors are excited by the growth potential.
High gross margins mean that there’s exciting operational gearing, if growth continues to be very strong.
My problem is, it’s impossible for me to value, because I don’t know what the future growth is likely to be. Good luck to holders, it looks an interesting share.
I’ve been listening to the company’s presentation on Mello, whilst typing this. I like the combination of the calm Chairman, and the younger CEO, it works well. For anyone who missed it, worth watching on the recording.
There is something interesting with Gaming Realms, I just don’t know what it’s worth. Sorry if that is unsatisfactory!
.
Jack’s section
Water Intelligence (LON:WATR)
Share price: 838.5p (+3.52%)
Shares in issue: 15,492,443
Market cap: £129.9m
(I hold)
I’ve been looking into Water Intelligence (LON:WATR) and will actually have something more detailed out next week.
It’s a bit of an oddity and is off the radars of most investors and brokers. But this is a high Quality-Momentum small cap that has been growing very strongly, and the group’s global addressable market is vast.

WATR is a leading multinational provider of precision, minimally-invasive water leak detection and remediation solutions. It provides its corporate and franchisee plumbers with proprietary equipment that allows them to locate leaks without breaking down walls or floors.
This helps to reduce costs and enhance water conservation.
The company started as Qonnectis, but things went wrong here a decade or more ago and this prompted a reverse acquisition of American Leak Detection (ALD), which has been the core business ever since. ALD was established in 1974 and operates primarily in the United States as a blend of corporate and franchised operations but it is steadily expanding internationally.
Liquidity is an issue here: with a share price of 806p and an exchange market size of 500, only about £4k worth of stock can be reliably traded but sometimes less in practice. Aside from that, the obvious catch is relative valuation.
There’s no two ways about it: you’re paying up for this growth and you want it to continue, or even accelerate.

Thankfully for the shares, this looks like an ‘ahead of expectations’ update or (as Mr C points out) a ‘quadruple outstanding’ statement...
Highlights:
- Water Intelligence revenue +38% reaching $11.4m (1Q 2020: $8.3m),
- Implied total annualized sales to customers (franchise system sales plus direct sales from corporate locations) would surpass $140m ‘providing critical mass’,
- Both businesses (ALD and Water Intelligence International, WII) grew business across residential, commercial, and municipal customers,
- ALD revenue grew by 36% to $10.2m (1Q 2020: $7.5m),
- WII revenue grew 63% to $1.3m (1Q 2020: $0.8m),
- Water Intelligence profits before tax (PBT) adjusted for non-cash amortisation expense and share-based payments +115% to $1.78m (1Q 2020: $0.83m)
Reporting segments:
- Royalty income grew by 3% to $1.84m (1Q 2020: $1.78m), despite eight franchise reacquisitions during 2020,
- Franchise-related sales (national accounts; parts and equipment; franchise territory sales) grew 15% to $2.4m (1Q 2020: $2.1m)
- Key insurance business-to-business channel grew 19% to $2.3m (1Q 2020: $1.9m)
- Corporate location sales grew 64% to $5.9m (1Q 2020: $3.6m);
The group has had an outstanding first quarter and has built upon its consistently strong compounded annual growth (CAGR) trajectory. Revenue and PBT growth rates are an eye-catching 30%+.
Water Intelligence has been busy buying back select franchise operations and buying back its own shares this quarter. Commenting on the good performance, executive chairman and major shareholder, Dr. Patrick DeSouza said:
Once again we are reporting outstanding results. We are racing ahead as an 'essential service provider' offering valuable water-related solutions to our residential, commercial and municipal customers during this late-Covid period. As noted in a recent release, even as we move beyond Covid, we expect that market demand for our solutions will only increase as a result of the Biden Administration's American Jobs Plan and its anticipated $100 billion investment in water infrastructure.
Conclusion
These first quarter results continue the impressive 2020 trading momentum which, despite Covid, produced 17% growth in revenue to $37.9m and 78% growth in statutory profits before tax to $4.2m.
Since 2016, Water Intelligence has achieved a CAGR of 33% in terms of revenue and 53% in terms of profits before tax.
Audited results for 2020 are expected during the second half of May.
The results are very good, but we come back to the relative valuation. A forecast PE ratio of 42.5x and a forecast PEG of 5.4x. Solely in terms of price multiples, there are more attractively valued growth opportunities out there.
Are we looking at the future of global water conservation, or an expensively valued network of plumbers? It’s possibly a mixture of both, and the global opportunity for the group is promising. As is the optionality created in its hybrid corporate/franchise structure.
It could be a good ‘buy and forget’ candidate, but there’s no doubt we would be paying a premium for the privilege, and that makes for precious little margin for error. The group is putting quite a lot of capital into its International corporate store segment at the moment, and there is execution risk here.
It is notable, though, that the company has bought back shares recently, but only in small amounts. Either management understands those shares are cheap on a longer term view, or this is a poor use of capital that could be more profitably allocated elsewhere.
On the point of spending, the group says:
As our profits increase, we are committed to reinvest not only in more execution capabilities for current market capture but also in leading technologies that reinforce our brand and our growth throughout this decade. We have a strong matrix of clean water and wastewater solutions and we aim to be market leaders with respect to the world's most precious resource.
For now, momentum continues across the group’s key performance indicators as it passes the mid-point of the second quarter. Water Intelligence is scaling its operations and it could be one to watch on a longer term view.
On the other hand, in the shorter term, a lot of good performance is priced in.
Inspiration Healthcare (LON:IHC)
Share price: 116.7p (-4.73%)
Shares in issue: 68,121,447
Market cap: £79.5m
Another company, and another share price up by 50% or so over the past six months. It’s been a very strong period in the market and you can see the All Share is up by some 26.44%.

Unlike Water Intelligence, though, IHC’s valuation metrics actually compare favourably to its Healthcare equipment & supplies peers.

We’re afforded a more forgiving price multiple here.
In fact, Inspiration Healthcare (LON:IHC) qualifies for the Neglected Firms Screen. This screen compares companies to their industry peer group’s across EPS growth, PE ratio, net margin, price to book, and five-year returns on equity.
IHC is a global supplier of medical equipment with a range of products for neonatal intensive care and patient warming. The group provides customer service and technical support around these products and supports the work done ‘to save and improve the lives of some of the world’s most fragile patients.’
Highlights:
- Group Revenue up to £37m (FY2020: £17.8m) including 'one time' Covid-19 related orders and contribution from SLE Limited,
- Adjusted Operating Profit up to £4.3m (FY2020: £1.5m),
- Net cash position up to £10.7m (FY2020: £4.5m)
- Gross Margin up to 48.7% (FY2020: 48.2%)
Adjusted operating profit excludes £579k of acquisition expenses and a £435k final settlement of contingent consideration.
On 7 July 2020 the group acquired the entire issued share capital of SLE, which is a leader in the design and manufacture of ventilators and capital equipment for neonatal intensive care, treating premature and sick babies.
It looks like this was a good opportunity for funds to initiate or increase stakes.
The year-on-year adjusted operating profit increase is primarily due to the increase in underlying revenue plus contributions from Viomedex, SLE and the 'one off' Covid-19 related revenue; offset in part by increased administrative expenses.
Shares are down on this in line update.
It’s better to journey than to arrive, as they say, and another phrase: the markets are forward-looking. So perhaps investors are getting off this train and entering the overheated reflation trade.
Conclusion
It’s an in line statement with revenue for the year up 108% and adjusted EBITDA up 150%. That looks attractive, but the share price has already rerated.
It’s a bull market and today’s drop might just be profit taking from shorter term holders who have found them with a very respectable six-month performance.
I’m more interested in whether or not this could be a long term investment and on that note it looks potentially of interest given the markets it operates in and the revenue growth over the years.
Returns on equity have been falling though, so there are questions around whether this growth is actually particularly profitable.

On that note, net profits have been small but they are forecast to pick up so it could be worth digging into the investment case a little more.

Diluted earnings per share of 5.07p, up considerably from 2.15p and underlying diluted EPS of 6.89p (vs. 2020 of 3.62p), values IHC at 16.7x FY21 underlying diluted earnings. Not bad, but it looks like the group has had a bit of a Covid windfall, which may explain the share price fall this morning.
Inspiration announced its first NHS Covid orders in March 2020, and delivered £7.3m of equipment to the NHS over the period.
That’s about 20% of the revenue figure that, presumably, will not be repeated. If you deduct 20% from the underlying EPS that would make for underlying EPS of 5.5p and an adjusted FY21 PE ratio 21.2x.
If there’s a really good longer term opportunity then that could be a decent entry point, but I’m slightly skeptical given the group’s historic lack of net profit growth. Barring this year’s Covid affected results, why haven’t net profits grown in line with revenue?

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
Hi, gather there was a Mello Event last night. Gather SWG, Shearwater was briefly discussed. Did anyone hear what the outcome was? Thanks
Focusrite (LON:TUNE) Paul thanks for looking at this one. I have a Focusrite at home as I have a sideline in the music world so I understand a bit about what they do I am just still very much learning about deciphering company statements!
Martin Audio have in the past been very much known for operating at the higher end so nightclubs, festivals etc (which of course have all been shut down). Void and Funktion One I would say would be there main competitors in this market. Void you may well know as they are HQ in Poole, which is just down the road from you isn't it? Many of these manufacturers have pivoted a bit over the years to produce mid range products to broaden their market.
I had a look at Gear4music Holdings (LON:G4M) website the other day. I cannot speak for the instrument side but from a DJ side they are expensive, I am not quite sure why DJs would buy their DJ equipment from them. I compared a few prices of theirs on some of the most popular DJ equipment with DJkit.com who are one of the biggest and well known DJ sites in the UK:
- Pioneer CDJ 3000 £2,299 (G4M) vs £2,169 (DJ Kit)
- Pioneer XDJ-XZ £2,107 (G4M) vs £1,999 (DJ Kit)
- Denon DJ Prime 4 £1,699 (G4M) vs £1,649 (DJ Kit)
- DenonDJ SC6000 £1,324 (G4M) vs £1,259 (DJKit)
Pioneer and Denon are the leaders in the DJ world and set strict rules about pricing. I have just placed an order for some kit through my long term supplier and they've told me there are delays as a result of the microchip shortage so worth keeping in mind for all companies that depend on these chips.
I've bought one or two things from Gear4music Holdings (LON:G4M) and not been terribly impressed. I doubt that a serious musician would buy a big ticket item from them. But the share price keeps on rising so they are clearly doing something right. I think they have a good chance of establishing themselves as the go to place for cheaper musical equipment and a lot of smaller sales are better than a few big ones. I also suspect they got an awful lot of lockdown impulse buys. And I am not sure that this will be enough to keep the business expanding especially once lockdown finishes.
Hi Jeff,
Thanks for posting that info about Gear4music Holdings (LON:G4M) (I hold) prices vs DJ Kit. Quick query if I may - are those prices like-for-like including similar delivery options? I understand that G4M major on next day delivery for most things, and top notch, no quibble customer service. Maybe that's why they charge a little more?
My brother & sister-in-law are both professional musicians & composers, and they say that G4M isn't really much good for the specialist instruments & equipment they need, but that it's fine for the mass market. My brother now recommends schools he works with, to just buy everything from G4M, because it's quick, usually cheap, and no problems with importing, and good customer service if anything goes wrong.
The chips thing really worries me. What an incredibly short-sighted policy, for Western economies to become so reliant on chips made in Taiwan, when it looks as if China is limbering up to eventually invading & absorbing Taiwan, which it sees as a rebel, breakaway island. Yet so many essential computer chips are made there. Madness.
Regards, Paul.
Yes I agree about microchips and this shortage has been affecting many businesses, here is one report about car manufacturers in the US: https://www.nytimes.com/2021/04/23/business/auto-semiconductors-general-motors-mercedes.html
Avoiding Chinese or Taiwan components, in the music industry is very difficult.
Hi Paul,
DJkit includes free next working day delivery in UK for orders over £50 otherwise it’s £5.50 charge m.
DJkit offers price match and finance - including 0% option (G4M offers finance but I couldn’t see a 0% option)
DJkit has 6,377 Trust Pilot reviews at 4.9 vs G4M 98,436 at 4.8
G4M offer 2 year warranty as standard which is better but I suppose you could argue you are actually paying for that upfront with the increased price.
DJkit were established in 1999 so have been around a while.
Margins on DJ equipment over the years have become more squeezed with some brands as they been acquired. The more lucrative market is equipment hire.
Pioneer and Denon are the leaders in the DJ world and set strict rules about pricing.
Would that not be against competition law?
https://www.pinsentmasons.com/...
I am afraid law is a field I am not versed in. I am not sure of the detail but the prices across their resellers are pretty consistent in terms of a minimum price. My aim was to point out that G4M charge more for DJ equipment
Thanks Jack for a very balanced review of WATR
It's a big problem for me that we are looking into the first quarter results for 2021 for Water Intelligence (LON:WATR) and yet the Stockreport is still not yet up to date for the full year to Dec 2020. So this would make a proper analysis far more difficult & time consuming to such an extent that I just will not bother with it.
I agree with WarrantStar that this is a major frustration - I so often find that the numbers are miles out of date especially amongst the small mining companies, where their cash balances are regularly replenished by exercise of warrants. The trouble is that this distorts many of Stocko’s clever analysis tools.
For my part, I would much prefer Stocko to focus on getting the basic numbers up to date rather than on new features.
This is not to say that I don’t find Stocko a valuable tool. It just could be a much better one.
ricardo
Hi WarrantStar,
This is the company's fault, not Stockopedia. Water Intelligence (LON:WATR) do not publish prelims, just final audited results, which obviously take longer (expected second half of May 2021 for the year to December 2020). This was behind my comment about a weak finance function earlier.
It's was perhaps excusable when the company was a tiddler, but now it is valued at over £150m and really needs to grow up. I have raised this with management previously, although clearly with no effect.
Effortless Cool. Thank you for your explanation. If Water Intelligence (LON:WATR) were to fix the problem, I would probably be a share holder. But as things are at the moment, I will not.
Carclo (LON:CAR) - Returning to Growth.
I revised my evaluation with the trading update.
https://www.stockopedia.com/co...
BSV
Mello has arranged a Results Roadshow for April which runs today from 11am and it is completely free to register and join the webinar.
https://melloevents.com/tuesday-27th-april-2021/
Here is the full programme and Paul Scott will be reviewing the results and updates of a number of the companies that have reported during the month live on the show too.
Programme for Tuesday 27th April
11.00am Mello Welcome & Company presentation by Avation
11.30am RBG Holdings
12.10pm Company presentation by Gaming Realms
12.40pm Results round up (Part 1) with Richard Crow
1.00pm Company presentation by Belvoir Group
2.00pm Company presentation by Trident Royalties
2.50pm Results round up (Part 2) with Paul Scott
Do not forget to register and it is completely free so do come and join us. There will be a Q&A for you to participate in after each company presentation.
David
I really enjoyed the "fireside chat" between yourself and Paul at the end of the Mello show today. Just listening to the 2 of you chat about shares is time well spent.
Many thanks for all of your hard work David.
Focusrite (LON:TUNE)
Some set of results. I don't think it's unreasonable to just assume a doubling of these results to get a full year figure, there's no large seasonal effect in the last couple of years.
An EPS of 66p for the full year gives a PE of 18 which looks cheap to me for this company, which has just acquired another related company and still has net cash.
It has gone from looking expensive for a couple of years to cheap overnight IMO.
I hold but have no cash to top up.
I'm with you, I bought a few today, if they can keep this up the company looks like good value.
I've read your reports for many years but don't often comment! 2 comments from me this week for G4M and TUNE! I'm a Professional Live Sound Engineer, The results from Focusrite do look great and I can say that they are well respected in the Industry as their products are reliable and sound great, I think coming out of lockdown we are gearing up for a busy Summer in the Industry. They should benefit from an increased professional spend although the Industry has been quite badly beaten up with none of us being able to trade. The Martin brand is very well respected as one of the big 4 Manufacturers of professional PA systems for Arena and big festival type systems. The recent acquisition of Sequential also looks a perfect bolt on for the business. Again, I need to put my money where my mouth is and invest!
Good morning Paul & Jack. I'd be interested in your thoughts on Carclo (LON:CAR) news today if you have time please?
Good morning Paul, any thoughts on Inspiration Healthcare (LON:IHC) - results out this morning. In line figures but I wonder whether the rating isn’t now a bit stretched given the likely unrepeatable Covid revenue boost in 2020-21? Grateful for your thoughts.
Focusrite (LON:TUNE) for a relative newbie like myself it would be great to hear your views on this one following interims.
My morning smallcap tweet: Abingdon Health sickly
LSL Property Services (LON:LSL) Abingdon Health (LON:ABDX) Water Intelligence (LON:WATR) Immotion (LON:IMMO) Synectics (LON:SNX) Gaming Realms (LON:GMR) Chamberlin (LON:CMH), Tribal (LON:TRB), Xaar (LON:XAR), Inspiration Healthcare (LON:IHC)
LSL Property Services (LSL) contract to provide mortgage and protection advice to The Property Franchise Group's 430 estate agency offices. [SP=358 Cap=376m]
Abingdon Health (ABDX) warns FY(June) substantially below market expectations. Blames orders for covid rapid tests is taking longer than expected. Guides rev £11.4m to £17m and adj EBITDA -£3.3m to zero. No sign of Gov't paying £6.7m owed for tests. [SP=79.7 Cap=76m]
Water Intelligence (WATR) Q1 rev up 38% and pretax up 152%. Uses 'outstanding' four times. Outstanding! [SP=800 Cap=124m]
Immotion (IMMO) its flagship VR Theatre installation in Nevada has capacity limit raised from 50% to 80%. Nevada intends to allow 100% from June. [SP=6.18 Cap=26m]
Synectics (SNX) trading, as expected, carried on at similar levels to prev FY. Sees some early signs of increased customer activity in the gaming sector. [SP=138.5 Cap=25m]
Gaming Realms (GMR) FY(Dec). Recent trading marginally ahead of Board expectations. [SP=44.4 Cap=128m]
Chamberlin (CMH) CEO resigns, remains as director. New CEO chosen. [SP=8.35 Cap=6m]
In line: Tribal (LON:TRB) Xaar (LON:XAR) Inspiration Healthcare (LON:IHC)
Property Franchise (LON:TPFG) Full Year 2020 results overview video/podcast. Profit before tax up 20% to £4.8m, operating margin 42% (19: 35%), cash £8.8m, dividend 8.7p (19: 2.6p). Here, Gareth Samples, CEO gives more detail, with an update on the Hunters acquisition, and he talks more about the strategic partnership announced with LSL (financial services) today. Video & Podcast.
A full presentation will be given by Gareth Samples, CEO and David Raggett, CFO followed by Q&A, tomorrow Wednesday 28th April 11.30am. Register here.
Thanks Tamzin. Sounds like everything is rosy in the Property Franchise (LON:TPFG) garden
One note to say I think the CEO should cut down on the 'really really' effusiveness of everything otherwise he will end up sounding like the character in the Fast Show who said everything was 'Brilliant!'
https://www.youtube.com/result...
Gaming Realms (LON:GMR) - Gaming Realms results out today and it hails a 'transformational' year posting a 'maiden adjusted EBITDA profit of 3.3m'. Revenue is up 66%, launched with 26 new partners, blah, blah, blah, touts EBITDA result about a dozen times more before revealing company actually made a loss of 1.5m.
I'd appreciate if the SCVR chaps could run the rule over Gaming Realms (LON:GMR) as I'm thinking of selling up given high p/e, another year of loss, however, company seems to be moving in the right direction- do I need to hold on?
I second a look at Gaming Realms (LON:GMR)
What I’m seeing is that development costs are still large and consuming the cash flow. They are capitalised so to my mind the “profit” is not a particularly useful number here at present.
However, the revenue from the expansion in Michigan should start to kick in by the end of this quarter with a further state coming on board later on this year. So, to my mind this is the transformational year. If these US expansions go well in particular there will likely be further states coming on board in 2022 onwards which will give a great growth ramp with out much additional cost. Well, that’s the theory!
Gaming Realms are presenting at 12.10pm lunchtime at the Mello Results Roadshow event today.
It is completely free to register and watch all the companies present plus Paul Scott reviewing a number of companies live on the show. The show starts at 11am
https://melloevents.com/tuesday-27th-april-2021/
Just click on the registration tab and you will also be sent a recording.
thanks registered - also interested in RBG who are presenting
Yes thoughts on Gaming Realms (LON:GMR) would be very much appreciated - the results in some ways are good BUT still not profit making overall, growth seems sluggish despite many new partners.
I am trying to slim down the number of shares I own at the moment and I think this is a candidate for selling perhaps.....
Focusrite (LON:TUNE) seems to be posting good headline results!
Yes Focusrite (LON:TUNE) has posted half year basic EPS of 33.2p against Stocko's full year forecast of 38.8p. What previously looked very expensive is suddenly looking less so. They have also announced another acquisition this morning as well as half year results. I hold.
Water Intelligence (LON:WATR) released its Q1 results this morning showing revenue growth of 38% and statutory profits increases of 166%. This share continues to be expensive but continues to go up like others based on its continued expansion and buy back of franchises. It talks about a sizeable opportunity in the increased infrastructure spending by the biden government.
I am an happy holder of this and see further appreciation of its results over the next few years. It is very capital intensive which eats up a lot of its cashflow and I do wonder long term whether it'll ever be in a position to deliver dividends. For now though I am enjoying the ride.
Hi Brookeda,
Thanks for your post on Water Intelligence (LON:WATR) [I hold]. I agree with it, apart from where you say it is capital intensive - in my opinion it is actually a capital light business.
By way of supporting this, I would suggest looking at the last published cash flow statement, from the 2020 interims. You can see there that PBT of $2.0m converts to operating cash flows before working capital of $3.2m and after working capital of $2.7m.
The cash leaves the balance sheet further down the cash flow statement, which shows $2.4m spend on reacquisition of franchises. This is discretionary spend and, as and when the company stops or reduces this level of reinvestment, it could easily afford to pay a dividend. In fact, the franchise model underpinning the business is particularly supportive of dividends, since it produces an annuity-like flow of income driven by relatively stable and secure franchisee revenues.
Outstanding!
I hope you are right, I refer to the comments in todays announcement which say.
"As our profits increase, we are committed to reinvest not only in more execution capabilities for current market capture but also in leading technologies that reinforce our brand and our growth throughout this decade."
I am always looking for the bear points on a stock that's gone up 150% in the last 9 months and I guess that my concern.
I would like to think they continue to buy back the franchises at it clearly seems to be a way of maximizing profit across the entire end to end process. Additionally whilst I understand the current focus on the US with the biden bounty I'd like to hear a bit more on their plans outside of their current countries.
I am not suggesting that Water Intelligence (LON:WATR) will start paying a dividend any time soon, I am saying that it could. However, given the returns they are achieving from (re)investing in the business, I am more than happy for them to keep doing that, rather than have them return capital for me and for me to try and achieve those returns through investment elsewhere.
There are genuine bear points with Water Intelligence, the most prominent being a weak governance framework, and I also consider the business to have a sub-standard finance function. Further, it is now priced at a level where it can't afford a mis-step. However, there is immense potential in its market and, so long as it keeps meeting/beating expectations, I do believe there could be a lot further to go.
Water Intelligence (LON:WATR) .........liquidity is an issue. I'll get my coat.
Nicely done.
Liquidity isn't as big an issue as potential insider knowledge given their history of leaks, although I believe they are trying to fix them.
Only those who are wet behind the ears would buy without doing further investigation. Heard there was a flood of orders being mopped up earlier. Could all be a damp squib though. I'll pipe down now.