Small Cap Value Report (Tue 27 Feb 2024) - ITX, MCB, VIC, ITIM, SBDS, OPTI, SNX, OTB, MEX, SND, PPS, BRCK

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
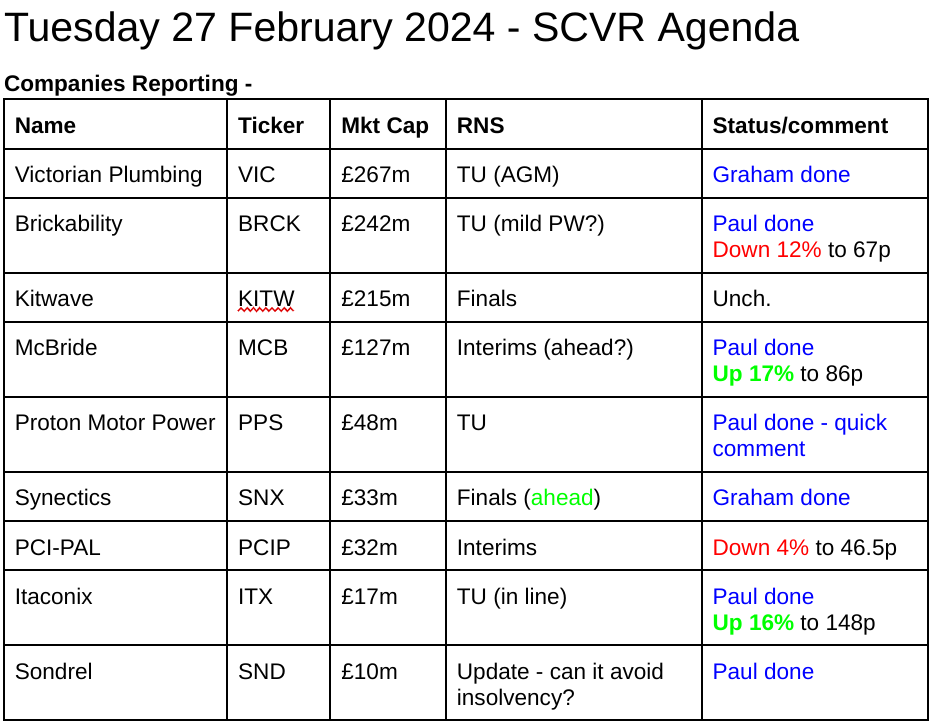
Other mid-morning movers (with news) -
ITIM (LON:ITIM) - up 58% to 34p (£11m) - Contract win from QUIZ - “five year multi-million-pound contract”. Quiz is the first retailer to take its full end-to-end software package, including wholesale. FY 12/2023 TU update coming “shortly”.
ITIM floated June 2021 (WH Ireland, 154p, now down 78%!) not covered in SCVR before. H1 saw £(1.1)m loss on £7.4m revenues. Cash-burning, and balance sheet only just OK at £1m NTAV. Paul’s view - potentially interesting, worth a closer look for higher risk investors. Founder owns 38%.
Silver Bullet Data Services (LON:SBDS) - up 13% to 180p (£31m) - Extends $2.3m contract for a third consecutive year, with Mars Petcare in US. Historically loss-making. Did £1m placing in Nov 2023 at 70p. Reckons it can achieve positive EBITDA in early 2024. No forecasts. H1 results showed revenue almost doubled to £4.2m, and loss before tax halved to £(1.8)m. Threadbare balance sheet with debt. Will almost certainly need another fundraise in my view. But, this looks an interesting business, in a hot area (data, AI), with impressive clients (eg Heineken, Mars, Sony and Omnicom) - I’m intrigued, and tempted to have a little speculative punt on it once it’s properly refinanced.
OptiBiotix Health (LON:OPTI) - up 11% to 25p (£23m) - Strategic & Commercial Update - listed 13 years, and has achieved nothing in commercial success, apart from profitably selling shares in similar spin-off Skinbiotherapeutics (LON:SBTX) . It says “ the last three quarters of 2023 have seen a gradual return to strong sales growth.” The rest of this update seems to me more of the same that I’m used to from OPTI - a mixture of cherry-picked percentages, and hot air. The only updates that matter from OPTI are the results statements, which always disappoint. I’ll be happy to change my mind if OPTI actually produces some decent trading results at some point in the future. For me, it’s still a firm RED.
On Beach group (LON:OTB) - up 13% to 159p - Partnership with Ryanair. A “transformational shift” in their relationship. OTB customers will be able to book Ryanair flights through OTB as part of a package holiday, with transparent pricing, and no additional overcharges. So presumably OTB gets commission from Ryanair? Seems to suggest (not directly stated though) that litigation has been settled - “this agreement enables both parties to move on from outstanding litigation”. Paul’s view - I’m already GREEN on OTB, and think the shares still look good value, even after the recent re-rating. Ryanair partnership sounds intriguing, although financial effect unknown. Good to see litigation settled in a constructive way.
Tortilla Mexican Grill (LON:MEX) [Paul holds] - up 5% to 44p (£17m) - awaiting RNSs to see who the buyer(s) and seller(s) are from yesterday's flurry of very large trades, in this normally very illiquid share. Hopefully this might have cleared an overhang of persistent selling? Andy Naylor moved up from CFO to COO recently, then last week was promoted again to CEO, replacing Richard Morris who held the role for 10 years. Mild profit warning on 20/12/2023 - adj PBT forecast now is only £0.3m FY 12/2023. Plan is to increase margins gradually, as energy & food inflation recede. However, sector-wide problem of 10% living wage increase in April 2024 will be a fresh headwind. Will be interesting to see how it pans out. Biggest & best UK burrito chain, in my view, and also has successful & growing franchising activities through SSP. I think it's too cheap, as a recovery situation, and possible bid target. UPDATE: Luke Johnson has popped up with 1.4m shares (one of the big trades yesterday) at 3.6% just announced by RNS.
Sondrel (Holdings) (LON:SND) - down 3% to 10.75p (£10m) - contract wins and negotiations with suppliers (presumably over onerous software rental charges) pale into insignificance compared with this latest bombshell - it needs additional financing by TOMORROW! -
“the Group will now require additional capital by the end of February 2024, in order to inter alia, meet payroll and other short-term working capital requirements. The Company is in advanced discussions with a potential provider of capital which would serve to extend this working capital runway.”
Paul’s view - you can’t get much higher risk than this, but good luck to everyone involved. It seems an interesting company, but woefully under-resourced - the same pitiful story with so many smaller UK companies. I've been RED since the profit warning in Aug 2023, and remain so due to ultra high risk. We can review it fresh if it successfully manages to refinance, fingers crossed.
Summaries of main sections
Itaconix (LON:ITX) - 128p pre-market (£17m) - Trading Update [in line] - Paul - AMBER
Trading update only talks about revenues. Rapid revenue growth, but loss-making still. Its saving grace is an ample cash pile of about half the market cap, and moderate cash burn so no need to raise more in these very tough markets. Worth a closer look I think, it's going on my watchlist.
McBride (LON:MCB) - 74p pre-market (£128m) - H1 Results [ahead] - Paul - AMBER/GREEN
An excellent H1 report from this supermarket supplier of personal/cleaning products. FY profit guidance is raised again. The balance sheet is still weak, but decent debt reduction is demonstrated, so excessive gearing is no longer an emergency, but is a drag on valuation. No divis for the time being. It looks cheap, and has pulled off a remarkable turnaround, so I'm moderately positive now risk has receded somewhat.
Victorian Plumbing (LON:VIC) - 82p pre-market (£268m) - AGM Trading Update - Graham - AMBER
An “in line with expectations” update when it comes to EBITDA, but I’m guessing that revenue will struggle to hit forecasts as consumers prioritise value over luxury. My overall impressions here are positive as VIC does tend to chuck out a low-margin profit every year.
Synectics (LON:SNX) - up 1% to 187.4p (£33m) - Final Results - Graham - GREEN
This security and surveillance company’s end markets (particularly oil and gas but also casinos) have recovered strongly and enabled it to beat forecasts, although broker estimates for FY24 and FY25 are unchanged. Looking ahead the valuation should still allow for upside.
Brickability (LON:BRCK) - down 12% to 67p (£214m) - Trading Update (PW) - Paul - BLACK (profit warning) - on fundamentals: AMBER/GREEN
Forecasts have once again proven a bit too optimistic, so it's another mild profit warning (last one was 11/10/2023). Also, recovery is now expected later than its original view. I think it's right that BRCK shares have given up some of the recent big % gains. Medium term, this share should do fine I think, but for now it's had a wobble, but far from disastrous.
Quick comments -
Proton Motor Power Systems (LON:PPS) - Unch 3.0p (£48m) - FY 12/2023 Trading Update - Paul - RED
Nothing much going on here, with revenue unchanged at only £2.1m, selling some hydrogen fuel cells. Nothing said about profit or cash. H1 results showed £6.1m operating loss (FY 12/2022: loss £(10.5)m). Utterly bonkers balance sheet, with borrowings of £109m! So clearly there will have to be a debt for equity swap at some stage to straighten out this insolvent balance sheet at NAV of £(105)m. 2 major shareholders together hold 82%. I’m steering well clear, as existing equity looks worthless to me. RED.
Paul’s Section:
Itaconix (LON:ITX)
Up 16% to 148p (£20m) - Trading Update [in line] - Paul - AMBER
Why on earth is he starting today’s SCVR with this loss-making minnow, you might justifiably ask?! It’s because I read the update first, and it’s quick & easy to summarise. For background, Roland reviewed it here in June 2023.
Itaconix (AIM: ITX) (OTCQB: ITXXF), a leading innovator in sustainable plant-based polymers used to decarbonise everyday consumer products, is pleased to provide a trading update and report that trading is in line with current expectations.
This isn’t really a trading update, because it only talks about revenues and not profit (or rather losses) -
Itaconix achieved another record year with unaudited revenues of $7.9 million, a substantial increase of 40.6% over FY22 of $5.6 million. The Company has now grown revenues at a compound annual growth rate of 54.9% since 2018. Europe led this year's growth rate, with revenues increasing by 89.3% to $1.0 million, while North America continued to generate significant increases, with revenues growing by 35.6% to $6.9 million.
Obviously if it had broken through into profit, then the company would be shouting about it, so the silence must mean continuing losses to add to the historical losses - although I do like the impressive revenue growth, so there might be something here worth further investigation -
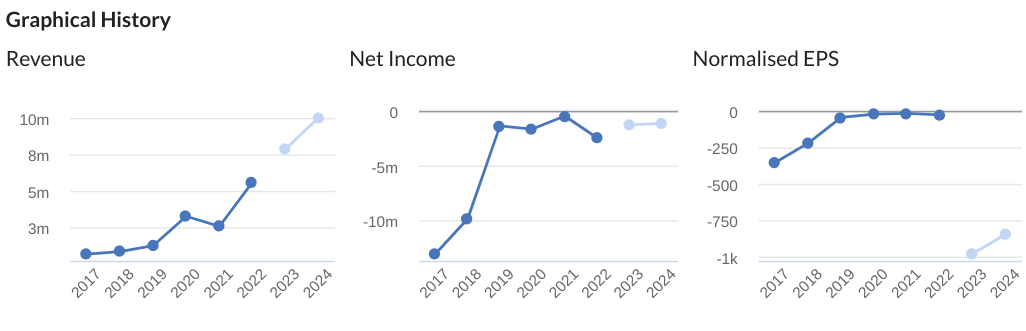
Almost all revenue comes from the cleaning sector, ingredients for detergent.
It’s quite impressive that sales are global, not just UK.
ITX makes these claims for its products, so getting third-party verification of this would be a key area to research -
Although Itaconix ingredients increase sustainability, the Company's key competitive advantage is in delivering both performance and affordability, which remain major concerns for brands, retailers, and consumers alike.
Cash - interesting, as it’s got plenty, following a placing at 5p (pre 50:1 share consolidation, so 250p in new money) early in 2023 -
Unaudited net cash and investments as at 31 December 2023 was $10.0 million (2022: $0.6 million).
That’s about £8.0m in sterling, almost half the market cap, which means most of the £10.5m (before costs) raised last year is still in the bank, suggesting a moderate level of cash burn relative to the funds available, which I like.
Outlook - all very nice, but these are mostly aspirations rather than facts -
"We have completed another record-setting year with revenues again growing substantially. This is being driven by both new customer wins and an expanding base of recurring revenues from existing customers. Our strong balance sheet is enabling us to target new customers and product innovation to underpin our growth objectives. With our commercial advancements and the development of new revenue opportunities, we are well placed to fulfil our strategy of becoming a large, profitable specialty ingredient company, distinguished by our commitment to safer chemicals, superior performance, cost-efficiency, and sustainability."
Paul’s opinion - I like the compound revenue growth over several years. Also I like the cash pile being about half the market cap. So this is worth further investigation, for people who absolutely have to invest in loss-making, cash-burning companies - which is usually a total disaster because they run out of cash, often repeatedly. ITX seems to have done that already, and is now nicely cashed up, providing management don’t squander the funds raised last year, as I doubt more would be forthcoming from investors in current market conditions.
Key areas to research are the track record of management, and whether the products are any good. I’ll put it on my watchlist, and await further details with its results due in early April.
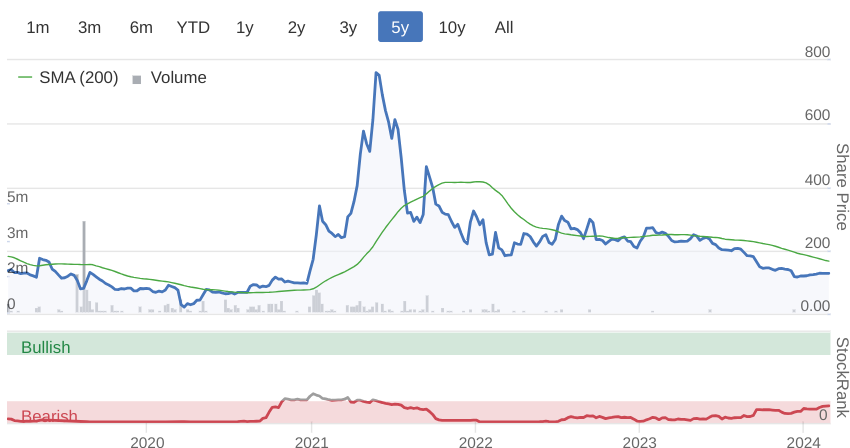
McBride (LON:MCB)
Up 17% to 86p (£150m) - H1 Results [ahead] - Paul - AMBER/GREEN
McBride, the leading European manufacturer and supplier of private label and contract manufactured products for the domestic household and professional cleaning/hygiene markets, announces its unaudited interim results for the six months ended 31 December 2023 (the 'period').
I like the headlines -
Strong first half performance underpinned by continued consumer shift to private label
Full year profit expectations raised
H1 key numbers - a fantastic turnaround vs last year -
· Group revenue of £468.0m (2022: £426.3m), up 9.8% (9.9% at constant currency(1))
· Adjusted operating profit(2) of £30.5m (2022: loss of £1.3m)
· Adjusted profit before taxation(2) of £22.4m (2022: loss of £7.9m)
Adj EPS in H1 was 9.1p.
Net debt - is coming down nicely, so no longer looks a major problem (although it’s still above the market cap, so is clearly still excessive, and needs to be taken into account when valuing the shares) -
Net debt(2) decreased to £145.7m (30 June 2023: £166.5m), liquidity increased to £85.0m (30 June 2023: £59.3m)
Pension deficit is consuming £4m pa in deficit recovery payments, plus potential top-ups up to £1.7m if profits exceed a benchmark.
Going concern - gives a clean bill of health, although I see the severe downside scenario as having quite soft assumptions.
Balance sheet - is clearly still stretched, with only £17m NTAV, and far too much debt for me to be comfortable. The restrictions on divis is further evidence that the bank wants its exposure reduced, and I don’t blame them after sailing so close to the wind in the last few years.
However, things are clearly moving in the right direction, so the weak balance sheet is no longer an emergency, and if MCB continues performing so well, should gradually repair itself from retained profits.
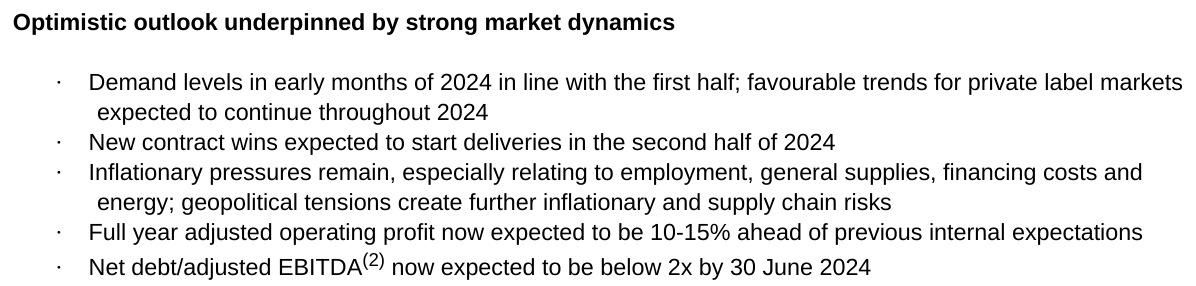
Outlook - great to see guidance being raised, and the debt EBITDA multiple coming into more acceptable territory -
Valuation - looks incredibly cheap on a PER basis even before today’s news of guidance being raised. So I imagine this update should propel shares higher (I haven’t looked at opening trades yet).
There are no broker updates available to me. Stockopedia has existing broker consensus for FY 6/2024 at 16.5p, so if we assume that might be raised to perhaps 18-20p, then the PER is only about 4! Obviously there’s a mountain of debt which will have to be reduced further, although probably won’t need to be fully repaid. So I doubt generous divis will be on the agenda for some time, and are still currently restricted by the terms of the bank facility - see the section titled “Payments to shareholders”.
My opinion - MCB has been a tremendously impressive turnaround, from a position that looked highly precarious back in the summer of 2022. The bank gave it a generous lifeline (suspending covenant testing), which we commented on here at the time, taking away insolvency risk. With hindsight, that was a great time to take a punt on this share, and well done to subscribers who saw the opportunity. I didn't imagine that earnings would recover to anything like the extent they have, it's been tremendously impressive.
I think today’s positive update justifies a resumption of the bullish share price trend. Maybe 100p might be achievable now? I’ve not yet looked at the share price, but imagine it’s likely to be usefully higher this morning.
EDIT: MCB shares are up 17% to 86p at 9:00, well done to holders!
It remains to be seen if the aggressive supermarket buyers will allow MCB to continue making decent profits, or if as in the past, they’ll squeeze it out again?
Brickability (LON:BRCK)
Down 12% to 67p (£214m) - Trading Update (PW) - Paul - BLACK (profit warning) - on fundamentals: AMBER/GREEN
Construction materials distributor. Today it says -
Bricks demand down on last year (but it already expected that)
“Pricing is becoming increasingly competitive given the softer demand.”
Non-bricks “traded well” and “gross margins remained strong”
Overall - it’s a mild profit warning for FY 3/2024 -
FY24 adjusted EBITDA is expected to be towards the lower end of current market expectations.1
1 Complied analyst consensus for the Company, prior to this announcement, is for FY24 adjusted EBITDA of £46.2m with a range of £44.8m to £47.2m.
That’s a tight range anyway, so being at the lower end is neither here nor there to me. However, shares have had a strong run since the Oct 2023 low, and are still up c.50% since then. So I can see why the market has been unimpressed with today’s mild profit warning.
Outlook comments are not good -
Whilst it is encouraging that the rate of inflation is trending down favourably and the widely expected fall in interest rates will benefit the wider market, trading conditions are expected to remain challenging for longer than initially anticipated.
As a result, the Board now considers it appropriate to assume a more conservative profile for the Group's recovery over the next twelve months. The underlying long-term demand for UK housing remains robust, and the Group is well placed to benefit significantly as the market and volumes recover.
Revised forecasts - thanks to Cavendish for updating us. It lops a fair bit off revenue, but only slightly reduces profit expectations for FY 3/2024 and FY 3/2025. I’m struggling to understand that, but it might be because recent acquisitions have masked the underlying fall, possibly?
I vaguely recall that in the past the company has said its business model is not particularly highly operationally geared, since it’s a distributor, as opposed to a manufacturer with high fixed costs.
EPS is now expected at 8.3p FY 3/2024, and similar at 8.4p for FY 3/2025, then a recovery anticipated in FY 3/2026 to 11.3p. So the PER looks reasonable, and this may be at or near low of the cycle earnings?
Paul’s opinion - broker forecasts had already been reduced in several stages since last July, so to miss these reduced numbers does suggest that BRCK isn’t forecasting very well - they’re clearly being too optimistic. I think that often happens when management are fairly new to public markets, and they need to learn to under-promise and over-deliver. BRCK has been listed nearly 5 years, so this should have been handled better.
That said they’re not responsible for macro factors, which is what has caused a deeper downturn than previously anticipated.
We know a recovery is likely, from what the housebuilders are saying, so that should feed through in due course and see earnings recover.
Overall, I think this share remains attractive as a medium term recovery investment, like many other building supplies shares. I like several in this sector, but don’t know where the low point will be, or has been? It’s tempting to buy a basket of the better quality/cheap building supplies company, then just wait 2 years or so, and the basket is likely to be worth more I reckon, and would collect in some decent divis along the way too.
I’m happy to stick with AMBER/GREEN, same as last time it warned on profits on 11/10/2023. In both cases, these are not huge misses, just fairly modest profit warnings.
Graham’s Section:
Victorian Plumbing (LON:VIC)
82p pre-market (£268m) - AGM Trading Update - Graham - AMBER
Let’s briefly review today’s trading update from “the UK’s leading bathroom retailer”.
Full-year adjusted EBITDA is still expected in line with expectations.
Today’s update relates to the first 21 weeks of FY September 2024, which is not intuitive at all! Let’s instead say that it covers the five-month period beginning last October and continuing until now.
Key points:
Revenue growth 1%
Average order value is down 3%, but order volumes are up 4%. This is considered to represent market share gains.
It’s not a surprise given what we know about cost of living conditions, but “customers are continuing to seek value and are purchasing proportionately more own brand products”.
This “continues to improve the Group’s gross margin” and is one of the reasons, along with “stable marketing spend efficiency” for VIC’s confidence in meeting EBITDA expectations.
They only mention hitting EBITDA expectations, not hitting revenue expectations. There is a cynical voice whispering in my ear that revenue expectations (£305m, according to Stocko) will be very difficult to meet. After all, the revenue estimate from the StockReport suggests a 7% gain on last year, whereas today’s update says that revenues are only up 1% on last year.
Their new distribution centre, “which will address current capacity constraints”, is expected to be operational in H2.
Graham’s view
I’m new to studying this one, but overall impressions are positive. See Paul’s summary of their full-year results in November.
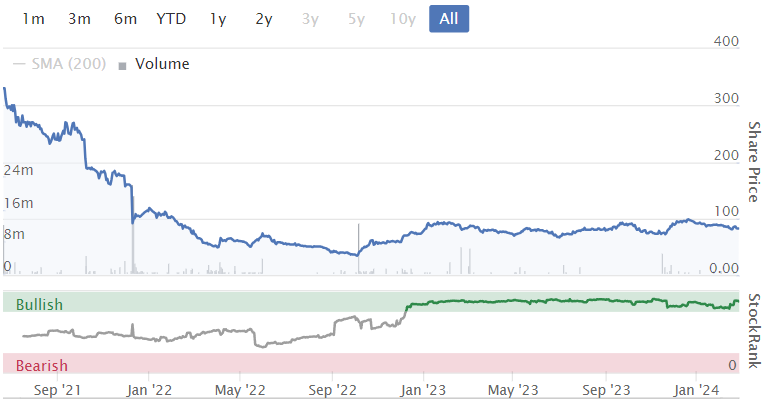
For a bit of financial history, I feel obliged to mention that this was the largest ever IPO on AIM. Shares hit the market during that terrible vintage year of 2021, priced at 3x their current level. Nearly £300m of shares changed hands at that level:
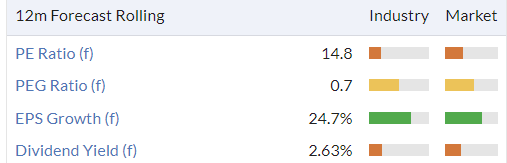
Looking ahead, from the current valuation, this might be priced sensibly:
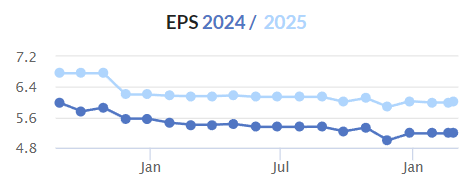
There has been pressure on estimates:
And I expect that quality is limited, e.g. operating margin struggles to ever break into double digits. But it could be a reasonable company offering reasonable value at the current level. Until I’ve studied it in more detail, I’ll be staying neutral.
Synectics (LON:SNX)
Share price: 187.4p (+1%)
Market cap: £33m
Synectics plc (AIM: SNX), a leader in advanced security and surveillance systems, announces its audited final results for the year ended 30 November 2023 ("FY 2023").
Congratulations to Paul for his positive coverage of this one in December (share price at the time: 105p), when he said “risk:reward is probably as good as it’s likely to get”.
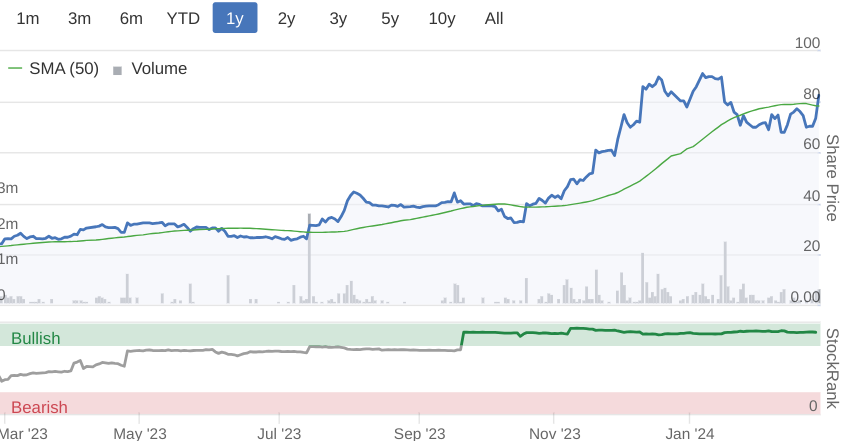
It has been a remarkable few months:
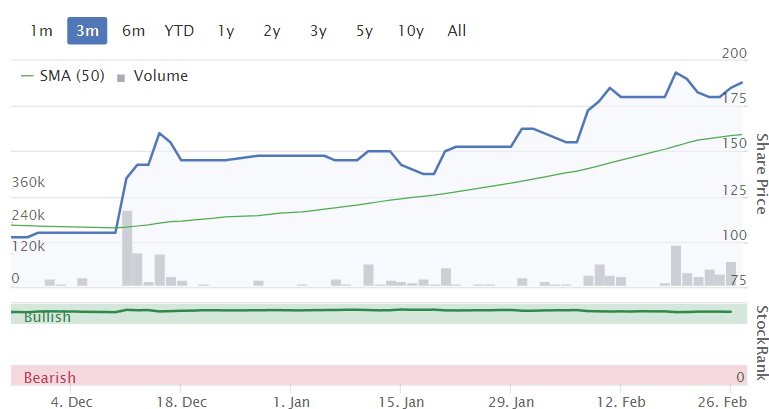
Here are the full-year highlights:
Revenue +26% to £49m
Underlying operating profit up to £3.1m (last year: £1.2m)
These are “strong results, exceeding market expectations, underpinned by growing demand from the oil and gas sector”.
Synectics provides security and surveillance products (e.g. camera systems) used by casinos, airports, railways, cities and towns, and oil and gas.
Net cash is £4.6m.
Order book finished the financial year at £29m (last year: £24m).
The dividend gets a substantial increase; the dividend record is quite good here:
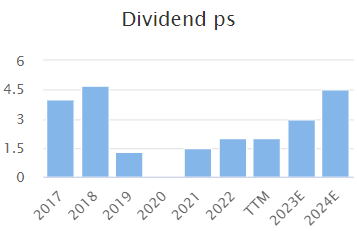
The 3p final dividend (the only dividend for the year) is well-covered by 14p of underlying EPS.
Estimates: many thanks to Shore Capital for publishing a new note on the company. While today’s results are slightly ahead of forecast, they leave FY Nov 2024 and FY Nov 2025 estimates unchanged.
Estimates suggest revenue growth of 8% in the current year (to £52.9m) and then a further 13% in the following year (to £60m).
Adjusted PBT is seen rising to £5m by FY November 2025.
Outlook in the company’s words:
Extended agreement with National Grid, with contracts of £4.0 million signed to upgrade more sites across its estate
Key end markets continue to recover, and we are seeing opportunities for both new projects and the renewal of existing infrastructure and systems in all sectors
Strong new business momentum delivered at the end of FY 2023 has continued into H1 2024, underpinning the Board's confidence in the Company's outlook for the medium term.
Management and shareholders: the CEO has been with the company for over 20 years, which I take as a positive sign. However, he’s not really an owner-CEO or a founder-CEO, having a 3% stake in the business.
The shareholder register shows that SNX also has a 30% investor - an offshore, anonymised entity that also has a decent stake in First Property (LON:FPO). Perhaps it’s someone we know in the value investor community!
Interim Chair’s statement is reassuring:
In 2020, we initiated a comprehensive restructuring programme whilst focusing on maintaining our core market insight and technology skills in response to a slowdown in our key end markets.
Continued progress and investment since then have ensured that we have advanced our proposition and knowledge, positioning us well to capitalise on the recovery in our core markets, which returned to growth in FY 2023.
Building on these foundations, the Company is ideally placed to capitalise further on its specialist end markets…
Adjustments: I’m reassured to see that there are only £300k of non-underlying items for the year, which makes this quite a clean set of accounts. The company spent £200k on “a confidential legal matter in the US which has now been settled”. Ok!
After all taxes and without making any adjustments, the net income for the year is £2.2m (last year: net income £1.5m, including discontinued operations).
It’s true that £1m of technology development spending was capitalised, instead of going through the income statement. But the company also wrote down (amortised) £0.7m of previously capitalised spending. So when you net these out, the decision to capitalise development spending didn’t make a big difference to reported profits.
Graham’s view
I feel as though I’m late to the party here, with the share price rising by 80p in a few months. Perhaps it has already reached fair value but I’m going to respect momentum and maintain the positive stance here.
If they hit the target of £5m adj. PBT over the next two years, then the current market cap (£33m) will, I suspect, be seen as having offered good value. Especially considering that the company has a net cash position.
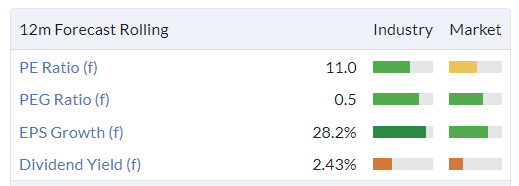
I haven’t seen anything to suggest that SNX has any revolutionary technology or an extraordinary competitive advantage, but it does appear to be well-run and a solid performer.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
It is nearly five years since Brickability (Brickability (LON:BRCK)) was floated on the market at 65p a share and its revenues have more than quadrupled to over £600m a year. However, following today’s profit warning its shares, after a recent strong run, have fallen back to close to their IPO price.
Brickability scores highly on the Stockopedia rankings, which is often a good sign. But there are a couple of warning lights. Much of BRCK’s post-IPO growth has been driven by acquisitions, and Alan Simpson, BRCK’s second biggest shareholder with a 10.8% stake and the architect of its recent acquisitive growth strategy, is about to stand down as chief executive.
He is being replaced by Frank Hanna, joint ceo of Michelmersh Brick (Michelmersh Brick Holdings (LON:MBH)), who has spent over 30 years in the brick industry. It is nine months since the management changes were announced and he is not going to take up his post until April which seems a long time to wait.
Mr Hanna is a well respected figure in the brick business. But BRCK’s recent growth has been driven by a need to reduce its heavy reliance on brick sales, which are now probably under half total revenues following the £48m acquisition of Topek Southern, a cladding installation and remediation business.
So when Mr Hanna eventually takes over he will be responsible for a much more complicated operation than a typical brick manufacturer, and a business which is several times bigger than Michelmersh both in sales and market value.
BRCK says that “trading conditions are expected to remain challenging for longer than initially anticipated” and its board “now considers it appropriate to assume a more conservative profile for the Group's recovery over the next twelve months”.
It will be up to Mr Hanna to prove over the next few years that BRCK deserves its current 99 Stockopedia rating as a “Super Stock”.
My understanding of Brickability (LON:BRCK) was its a distributor for er bricks from the likes of Ibstock (LON:IBST) Forterra (LON:FORT) Michelmersh Brick Holdings (LON:MBH).
Essential for our 'English' vernacular and they are the middleman for the builders Persimmon (LON:PSN) etc. So a tough market following cyclicality but perhaps not the next NVIDIA (NSQ:NVDA).
Ok but a labour govt needs to focus on housing delivery so 'bricks and mortar' will be top of the agenda - so demand long term not an issue. Cost to whom though is, but another story.
Mega Report today , thanks to both of you I don’t know how you manage to review so much albeit briefly in some instances. Much appreciated. I hold Synectics (LON:SNX) and was reassured by the update and am hoping that although the broker update was cautious there could be upgrades later.
Thanks richardho! We work hard on these reports, so it's great when readers give us nice feedback :-)
As an aside, I want to stress that I do properly research every share, even if it's only in the mid-morning movers section. I look through not just today's RNS, but also the last 6-month's RNSs, to check if there have been any fundraisings, last interim results, or any other material things. They may be short sections, but I check out the detail properly.
Best wishes, Paul.
Thanks Paul. Despite the workload yours and Graham's posts are delivered with freshness and enthusiasm.
Obviously a big report today but it would be great if Kitwave (LON:KITW) could be covered after their results this morning. Thanks in anticipation.
Hi David, I'll try to take a look at Kitwave later this week. It was in line I think, and price fell a little, so it was a low priority today, and I couldnt manage any more today once we'd covered 12 companies already. Its a good business I reckon, so am happy to cover KITW when theres time. Regards, Paul.
That would be great - thank you. I can see why it was low priority. I hold KITW and am considering some more. I am new to Stockopedia (previously with Vector Vest before they ditched the UK) and really appreciate the effort that goes into the daily SCVR which is a great read and resource.
That's kind, thanks David! Welcome to Stockopedia :-)
KITW has just moved up my priority list, I might even look at it now, seeing as you asked nicely!
Made Tech (LON:MTEC) - biggest volume since company listed!
Market gossip : Hot off the City AM press,(now owned by THG (LON:THG, whose CEO hates the market of late/shortsellers naturally), for those who don't read the rags perhaps :
'Shein muils London IPO after pressure from US regulators'!
It would definitely be a boon for London and the LSE.Although i do wonder why the US don't want them or why they can't comply with regulations there.It's reported to be political, but there are still a bunch of Chinese listed companies on the US exchanges obviously...
Given we are all wanderers through the wastelands of UK small caps, I thought Verdad's latest research might be of interest to some. Please: this is not political, although the period under analysis covers the Brexit period. I am an avid consumer of research and Verdad publish a lot of free and extremely interesting statistical-based research which can be accessed here:
https://verdadcap.com/weekly-r...
Anyway, to quote some pithy sections from their report, which does not yet appear on their website:
"Using a difference-in-differences technique, Verdad compared the UK’s corporate earnings to Europe’s corporate earnings in the three years prior to the finalization of the UK’s separation from the European Union (12/31/2020) and the three years after".
In the table below, margin spreads are defined as UK profit margins minus European profit margins, and valuation spreads are measured as UK Price/Book minus European Price/Book. To isolate the Brexit effect on domestic economies, the analysis is based on small-cap companies in both regions, since small-cap firms primarily generate earnings in their domestic markets.
Companies in the UK used to earn higher profit margins—and trade at higher valuations—than companies in continental Europe. But, post-Brexit, the spread in margins has almost entirely disappeared, and UK stocks now trade at a discount, as shown in the table below".
Figure 1: Brexit Effect, as Measured by Change in Margin Spread and Valuation Spread
Source: S&P Capital IQ and Verdad analysis. Small caps are defined as firms above $25M of market cap and below the 80th percentile of market cap (~$2.5B) within each year.
Profit margins have compressed meaningfully in the UK, post-Brexit, whereas European margins have been broadly flat.
Figure 2: Small-Cap Profit Margins in the UK and Continental Europe
Source: S&P Capital IQ and Verdad analysis. Small caps are defined as firms above $25M of market cap and below the 80th percentile of market cap (~$2.5B) within each year.
"Investors have sold UK equities as fundamentals have deteriorated. Morningstar estimates that equity funds domiciled in the UK have experienced net outflows in six out of the past eight years, most recently recording 12 consecutive months of net outflows in 2023".
Figure 3: Net Fund Flows in Billions for UK-Domiciled Equity Funds (January 2024)
Source: Morningstar.
"While it’s important to note that the fund flow estimates from Morningstar include a wide range of UK-domiciled funds, from international strategies to domestic strategies, we believe the big picture is that UK equity funds have bled assets since the Brexit referendum, leading to the deeply discounted valuations we see today among UK small caps".
...which is PlanetX's point further down in the comments.
"With the UK’s valuation premium turning into a discount, it appears the bad news around Brexit has already been priced in. In our opinion, what’s not priced in are the potential levers for upside in the UK going forward. For example, with UK small caps trading at a 25% discount to the US in terms of P/E and generating enough cash flow to offer dividend yields that are 2.5x higher than the US, it seems the UK small-cap market is ripe for private equity firms that are sitting on a record $2.6 trillion of dry powder. In 2022 and 2023 there were over 27 acquisitions of companies in the UK’s Numis Smaller Companies Index, and half of these firms were taken private by PE acquirers. The median acquisition premium was 51% among all of these transactions, and the 2023 deals were done at an estimated purchase multiple of 11.5x EV/EBITDA. For private equity, this compares favorably against the average US purchase multiple of 15.7x EV/EBITDA. Simply put, today’s discounted valuations of UK small caps provide enough room for a healthy acquisition premium of 51% while still offering better relative valuations for private equity acquirers."
Apologies for the length of post, but I thought it might be of interest to some despondent aficionados of UK small caps and provide a modicum of hope!
Have a nice day folks.
xxx
Tortilla Mexican Grill (LON:MEX) (I hold)
This was the catalyst I have been waiting for, seller taken out and Luke Johnson declaring a stake.
He has the means and the connections, Mex are now in play IMHO.
He holds a 27% stake in Brighton Pier (LON:PIER) as well and the SP has never done anything.
All the best to shareholders.
Tortilla Mexican Grill (LON:MEX) Of course Yiannos no guarantees, but you can't deny he is an industry heavyweight and he is not passive. So I think it's a reasonable bet he either activates for positive change or buys it himself, either way an operator of that experience sees value or potential or both, and so do I.
We shall see what happens.....
Tortilla Mexican Grill (LON:MEX) I would take Mr Johnson's money and run, but not sure I would invest if he was in charge. History......etc.
Luke Johnson the former chairman of patisserie Valerie .
mmmm
win some lose sone I guess , maybe this time better
Thanks planetx for mentioning this……
Hi Burnt Onions,
The gulf is gigantic between the relative valuation metrics of Tortilla Mexican Grill (LON:MEX) [I hold] and larger US competitors, Chipotle Mexican Grill (NYQ:CMG) and Cava (NYQ:CAVA) [great ticker, it's one of my favourites].
Therefore I suspect MEX could well be a tasty morsel for the larger, and enormously higher rated US competition - on about 5x sales! Put MEX on that rating, and it's about 20x the current share price!
Regards, PAul.
Am I missing something re the large bank debt MEX has ?
Tortilla Mexican Grill (LON:MEX) ..the debt thing on Stockopedia looks odd... Last October's presentation by the now CEO said:
Net debt of £1.6m, with debt of £2.9m drawn from a total available facility of
£10m (at 2 July 2023).
• Strong liquidity provides platform for future growth.
• The Group’s efforts to recover profitability this year and going forward will
enable the business to get back to the aim of funding expansion capital
requirements from operationally generated cash.
So are the Stocko figures wrong or is it some accounting quirk I wonder? (I hold)
Tortilla Mexican Grill (LON:MEX)
So are the Stocko figures wrong or is it some accounting quirk I wonder? (I hold)
as ever a look at the accounts and check of the lease liabilities will answer your question - so quirk of acounting it is albeit - its pretty "standard quirk" so hardly even quirky really,
per the interims their quoted net debt has the followung caveat.
defined as net debt / cash before lease liabilities arising from application of IFRS 16.
per last year end acounts lease liabilities in debt per note 14 of the acounts was £36 million.
Tortilla Mexican Grill (LON:MEX) - Thanks for the explanation...
I completely agree Paul, indeed I believe the Liberum analyst quipped in her latest report the entire mkt cap of Tortilla Mexican Grill (LON:MEX) was worth less than 1 branch of Chipotle!
I think the numbers are messy at Tortilla and costs and remunerations are far too high relative to the size of the business but with a top line of £70m+ and negligible debt there is undoubtedly a business there ripe for new management to turn around OR an easy and cheap way for estate expansion for the likes of Chipotle who I believe are now up to 19 branches in the UK (as oppose to 3500 in USA).
I think the departure of the current CEO and emergence of Luke Johnson adds to the investment case. Certainly with a mkt cap of now £19m and an EV/EBITDA ratio of circa 3.5 I see limited downside and enough for me to take a position but each to their own.
Not sure I get it. The two brands aren’t really comparable. Chipotle has a specific store brand format so other than a vague connection to Mexican food why would they want to buy Tortilla Mexican Grill (LON:MEX) ? They could almost certainly negotiate better leasehold deals with landlords than Tortilla Mexican Grill (LON:MEX) and it would cost pretty much the same to fit out a new branch as it would to re-fit a Mex branch. So what would be the benefit other than eliminating the competition?
If you believe Mexican fast food has the same appeal in the UK as it does in the US (I seriously doubt that myself) then I can understand an argument that the business can be turned around and made profitable but “in play” for Chipotle to take over - really?
And as for comparing market cap of the two companies and relative valuations - well surely thats just bonkers…….. one operates in a US market with a heavy Mexican cultural influence and customer base whilst the other is playing on a recent UK trend that has almost no similar characteristics and is loss making hoping for a turnaround. Not only that but it now needs to compete with Chipotle expansion who have far better buying power so prices can be lower, the branches will be new and shiny and as a corporate machine have bigger marketing budgets.
Doesn’t feel like an obvious recipe for success to me and Luke Johnson isn’t exactly a poster child after the Patisserie Valerie debacle. I’m surprised the shares went up on that news.
Anyway I’m probably missing something.
David you make fair & reasoned points and obviously I can only postulate as an investor as to why they would be a takeover target for another Mexican operator.
But I am (amongst many things) a commercial property landlord and I come from a family of restaurateurs. So some reasons as to why a takeover might work here...
First of all Chipotle have no commercial advantage in securing more favourable lease terms, it just doesn't work like that. A higher quality covenant against an independent trader then yes you would be right but one national chain against another then the landlord will just opt for whoever agrees the most favourable terms.
Yes rebranding restaurants costs but not as much as fitting out from new plus you have the added advantage of having established A3/A4/A5 use, planning for extraction etc
Scale, you immediately are buying a decent footprint of sales, sites take time to build up to maturity, if somebody has already done the leg work for you it's easier just to take that over, rebrand and you are away.
Competition removal is massive. If a landlord controls a particular site such as a train station or a shopping centre the he will not want to have too many similar types of operators but will instead mix it up to enhance the offering. Yes you might have a Mcdonalds and a Burger King but two Mexican restaurants in the same food court? unlikely...
Finally the last and probably best reason for a takeover would be the proof of established sales. If I know I can sell £1m pa of Mexican food in a particular area then I know the concept works, after that I'm just applying my operational skills/marketing etc to a proven concept.
Yes Mexican food is not as popular is the UK as US they are still selling £70m of burritos pa so somebody is buying them. And there are more chains coming Taco Bell, Boojum, Zambrero, Chipotle immediately come to mind but there are more, so yes the demand is there and establishing itself.
Finally nobody is comparing mkt caps, that would be ridiculous, a typical Chipotle site in US turns over $3m pa, they have thousands of stores and are worth billions. I merely mentioned the entire estate of Tortilla was worth less than 1 Chipotle store, I just thought the juxtaposition of the two valuations was interesting, a dinner party commentary piece, no more than that.
So it might happen might not, probably my 'in play' was too loose so you're right to pick up on that but Luke Johnson is no fool, he is an industry heavyweight and people sit up and take notice of what he does. Indeed only today in Propel (the industry newsletter) he is talking about how much more sector M&A there will be this year. Might not be Tortilla Mexican Grill (LON:MEX) , maybe this is a turn around, I don't know, but I believe there is more than fair risk reward numbers at these levels so I have bought into it.
I hope that addresses your raised points and thanks for raising them, they were totally valid.
hi Burnt Onions
Yes, thanks for your reasoning and maybe the turnaround works but personally I'd want to see that starting to happen rather than placing all my trust in a guy who just sat as Chairman of Patisserie Valerie, which turned out to be a massive fraud. At a minimum it suggests poor oversight over management. Not sure what his role is here though other than having taken a stake.
I don't disagree that taking over a chain of sites can be a bit cheaper for all the reasons you note but that applies to any restaurant chain. ie they could buy anyone and achieve a similar benefit, it doesn't have to be Tortilla Mexican Grill (LON:MEX). Chipotle has a very specific layout and brand so they usually rip out the entire place, remodel and refurbish irrespective of it having previously been a restaurant. In fact I know this because they have just opened one near me and done exactly that.
So it is clear that they are taking end of lease / bust leases where presumably they can get a good price in the right location. Buying a chain that is struggling means you also end up with a bunch of under performing, poorly chosen located leases you have to try and negotiate out of as well as the few that are great. So again I'd be highly reluctant to buy Tortilla Mexican Grill (LON:MEX) on the basis that Chipotle may decide to buy them. Perhaps they will anyway just to kill the competition but not something I'd personally be prepared to bet on as an investment thesis.
So really that leaves me with a hospitality business that has seriously struggled to generate meaningful returns on its chosen site locations, that is now facing serious competition from a couple of big US machines who are rolling out another US fast food brand to the UK with all the marketing/pricing power they have at their disposal. Tortilla Mexican Grill (LON:MEX) Balance sheet is ok - small net debt and reasonable headroom but very likely capex restricted - so can they afford to expand and as the decor gets tired can they afford to refurb?
Perhaps the valuation is already low enough that any sort of turnaround will raise the share price but it doesn't feel that way to me. Perhaps I am missing something and perhaps a rising tide of consumer spending will float all boats and we see a resurgence in profitability in hospitality.
Franchise Brands (LON:FRAN) Capital Markets Day given last week. Video and podcast. Outlining their vision to take the FY27 EBITDAa to £60m and EPSa to 20.5p (FY23e: EBITDAa 29.8m EPSa 8.64p).
Each of the divisions spoke about their strategy to grow sales and the Maximum Potential Model - each of their total addressable markets.
Mello have a presentation by Ocean Dial and India Capital Growth Fund (LON:IGC) at 13:00 today. Plus River and Mercantile River and Mercantile UK Micro Cap Investment (LON:RMMC) . It is free . https://us06web.zoom.us/webina...
Thanks for write up Graham. Paul was spot on!
What I liked about Synectics (LON:SNX) was when Covid happened they struggled big time but did an amazing job in pulling in the purse strings and keeping the company alive. They have many different sides to the business and have the potential to pull off some big contracts for large cities in the future. Never a given but there is the possibility of a lot of growth over the next few years.
Kitwave (LON:KITW)
I hold a modest position and am contemplating adding a few but there is competition for limited funds. Have read this morning's prelims announcement, which I need to revisit, but operating margin increasing from 4.3% to 5.3% looks very positive, especially accompanied by the selective buy and build approach in food services, which will increase revenue. Increase in revenue and operating margin, all things being equal is a winning combination. Also distribution costs although increased by 0.4% are being well contained in an inflationary environment.
Just need to get up to speed on the finances, debt, covenants etc, but all in all it looks like a buy at the present level with little in the share price for future and all being well prudent acquisitions.
Will wait to hear the views of the dynamic duo, aka Paul and Graham.
Kitwave (LON:KITW)
Thanks Jonno. Do you have a view on how cooling food inflation may impact the figures? They reference cost inflation quite consistently - which presumably is indeed a big headwind given low gross / operating margin - but it sounds like this has been offset by manufacturer-led price increases. I'm wondering whether there's potential for a profit squeeze as manufacturers drop prices whilst KITW's costs remain high.
“Investing in Britain is safest bet, minister”
I read a statistic last week concerning the the Hoses of Parliament / Mp pension fund .
Less than 1.5% of the value is invested in UK equities .
if true it is a national scandal and total disgrace .
As per usual my due diligence does extend no further than a chat with my mate Tim at the Fat Cat so treat with caution this statement before calling a bye election .
if true it is a national scandal and total disgrace .
hey ho make policies that allow google/meta to extract cash out the uk without paying vat or copr tax and then buy shares in google and meta. Oh and pretend for 7 years that uber dont provide taxi services and when after 7 years they do agree they are a taxi company allow them to treat all their sales as being "tour operator magin scheme" so minimal vat is paid - lets buy shares in uber too. On while they are at it google/meta et al will employ your family members on huge salary and have a nice position waiting for you when you lose your seat at the next election.
Sir Nick Clegg still does work @ Meta Platforms (NSQ:META) doing something.Popped up on the uk radio the other day too.And for balance, Osborne has apparently just gone to Coinbase Global (NSQ:COIN) to do something very important too i'm sure.
Hi planetx,
Look at this in a positive way; At least we will not have to fund the tax bill (pension deficit)!
I think it might be true ... see post above.
AIM down for a 7th day in a row. Hoping for an uplift soon in the run up to Easter!
Kitwave (LON:KITW) good results, share price had run up a fair bit recently though.
McBride (LON:MCB) (just bought a starter position).
I'm late to the party here but these are extraordinary numbers. Potential cash flow of £100m this year? If they throw say £40m of it at debt every year for the next 2/3 years then this just becomes a dividend machine.
Management looks top draw and I can't see people switching back from white label to branded once they realise it's all the same....No need to reinvent the wheel here, just carry on doing what they are doing.
Don't know what valuation is fair but seems to me anything under a £1 is a bargain.
McBride (LON:MCB) always has been a bargain ; still is.
Kier (LON:KIE) as well ; same situation cutting down debt.
I hold both.
Solid half year results from Alternative Income REIT (LON:AIRE). Slightly different from the average small cap - but held by a few here I think as a result of it's stability and fantastic yield (also was tipped by IC a few months back). They own 20 odd properties dotted round the country (a mix of care homes, health clubs, car dealerships etc). Nice geographic and sector mix so they aren't over exposed to problems in one particular area of the economy. Over 90% of the portfolio is on index linked rent reviews and rent collection is 100% (this half year and as far back as I can remember... I think there were deals done around Covid times to help people out). I was alerted to it by a post here on Stockopedia a few years back and I've held it ever since. I'd love to hear the small cap view and it might provide you with a change from the usual. It's a fairly straightforward business with no smoke and mirrors.
EDIT: I forgot to mention that sadly the Stocko figures for dividends and yield are all wrong. I've raised it many times (as have others) but nothing seems to change - probably a data supplier issue. The figures considerably understate dividends - so yield doesn't look as good as it is in reality.
Agree dfs12 (I hold) Good yield, dividend is covered and at a substantial discount to NAV. Given recent consolidation in the sector that must also be a possibility- though I hold for yield rather than any Corporate Activity.
dfs, i too have raised the dividend issue, even quoting from the notes in the Interim Report and the yearly R&A. The response was poor to put it mildly. When i further complained to Lawrence i received a meaningless standardized reply which didn't address the issue at all.
It is bizarre how they can treat their subscribers with such contempt.
AIRE is a great little company, were the income should rise steadily at about 3% to 4% for years. Currently yielding about 9%.
But there is one wrinkle. Just be aware that they have a £41m loan facility from Canada Life at about 3.2% which expires in Oct 25. They are unlikely to be able to refinance at that rate.
When i did some back of the envelope sums and assumed that the refinancing would be at about twice that interest rate, it seemed they would have to cut the dividend back to about 5.7p.
So maybe think of the stock as a stock paying 5.7p div from 2026, then growing at 3% to 4%.
Any extra you get beforehand is a bonus.
But one of my biggest ISA holdings.
Alternative Income REIT (LON:AIRE) ChrisW fair flag on debt renewing by Oct 25 but is assuming it doubles realistic? I expect to see Interest Rates start to fall in H2 with further drips in H1 2025. Would expect if they are refinancing early 25 they'd pay no more than 5%. Am I being too optimistic?
Appreciate your guidance on moderating longer term dividend and expectations. Just hope rates drop quicker!
Ditto.
I have very limited interest in AIM/small/micro-cap/penny stocks, but I have a significant interest in companies such as Alternative Income REIT (LON:AIRE). Unfortunately, most of the discussions are centered on those small/micro caps. I don't know why, because the analysis of companies such as AIRE is much simpler than the typical penny stock.
I like Stocko, but there are far too many data quality issues. I currently pay them for 5 regions, which makes it my most expensive data platform out of many that I use. I mainly use Seeking Alpha now for US stocks instead of Stocko.
And yes - I also reported the wrong dividend info and got some nonsense answer that they don't really support Investment Trusts.
You will probably enjoy the Trusts and Funds show this afternoon....
FREE Investment Trusts and Funds Event on Tuesday 27th February at 1pm Mello Investment Trusts & Funds 27th February 2024 – Mello Events
1:00pm Keynote presentation from Edmund Shing
1:30pm Company presentation from Ocean Dial and the India Capital Growth Fund
2:00pm Company presentation from River and Mercantile UK Micro Cap
2:30pm Andrew Latto presents ‘Fundsmith – Thirteen Years On’
Register for FREE here: Webinar Registration - Zoom
Up to 60% OFF Annual Passes:
Spring Annual Pass (1st May 2023 - 30th April 2024) - £49 (RRP £125)DISCOUNT CODE: MAYAP49
Buy Annual Pass – MelloMonday Annual Pass 1st May 2023 - 30th April 2024 – Zoom, Mon 1 May 2023 6:00 PM - Tue 30 Apr 2024 10:30 PM (tickettailor.com)
Autumn Annual Pass (1st November 2023 - 31st October 2024) - £99 (RRP £125)DISCOUNT CODE: NOVAP99
Renew/Buy Annual Pass – MelloMonday Annual Pass November 2023- October 2024 – Zoom, Wed 1 Nov 2023 6:00 PM - Thu 31 Oct 2024 10:30 PM (tickettailor.com)
We hope you can join us,
David
Partnership with Ryanair
On Beach group (LON:OTB) is delighted to announce that it has signed a long-term distribution agreement with Ryanair Holdings ("Ryanair").
The agreement represents a transformational shift in OTB's relationship with its most significant low cost carrier. It enables OTB customers to seamlessly access Ryanair's low fare flights as part of their holiday packages with full price transparency, whilst continuing to benefit from OTB's flexible payment plans, customer perks (including free lounge and fast track), and ATOL protection.
https://www.investegate.co.uk/...
My morning smallcap tweet: Spotting turkeys at the absurd sanctuary
Brickability (LON:BRCK) Sondrel (Holdings) (LON:SND) On Beach group (LON:OTB) Proton Motor Power Systems (LON:PPS) Fusion Antibodies (LON:FAB) OptiBiotix Health (LON:OPTI) Silver Bullet Data Services (LON:SBDS) Ocean Harvest Technology (LON:OHT) World Chess (LON:CHSS) ITIM (LON:ITIM) Skinbiotherapeutics (LON:SBTX) PCI- PAL (LON:PCIP) McBride (LON:MCB) Synectics (LON:SNX) Diaceutics (LON:DXRX) Aptamer (LON:APTA), Itaconix (LON:ITX), Victorian Plumbing (LON:VIC)
◄Brickability (BRCK)► warns FY-Mar adj EBITDA towards the lower end of market expectations of £44.8m to £47.2m. Also expects weaker FY25. [SP=76.4 Cap=243m]
◄Sondrel (SND)► sweet & sour: wins $9m contract for a chip design. Guides production revenue $14m over 10 to 15 years from 2026. Also other orders worth $0.9m this FY. But needs additional capital by the end of Feb. "Advanced discussions with a potential provider of capital which would serve to extend this working capital runway." [SP=13.5 Cap=12m]
◄On the Beach (OTB)► customers will be able to book Ryanair flights though OTB's website. Resolves outstanding litigation. [SP=141.4 Cap=236m]
◄Proton Motor Power Systems (PPS)► guides FY-Dec rev flat. In line? Order intake down at £2.5m (£2.7m). [SP=3 Cap=48m]
◄Fusion Antibodies (FAB)► gets first purchase order (c. £60k) under the master services agreement announced 14 Feb. Most will be booked next FY. [SP=3.8 Cap=2m]
◄OptiBiotix Health (OPTI)► strategic overview that seems to have nothing new. Long and bullish progress update. [SP=22.5 Cap=21m]
◄Silver Bullet Data Services (SBDS)► another order from Mars Petcare, for $2.3m, to be booked through cal 2024. [SP=155.25 Cap=27m]
◄Ocean Harvest Technology (OHT)► get a second patent, "covering a wide range of claims about the benefits of using its OceanFeed product in the diets of a range of animals". [SP=11.62 Cap=15m]
◄World Chess (CHSS)► announces some moves which don't amount to much. [SP=3.5 Cap=22m]
◄itim (ITIM)► wins 5 year multi-million contract for its Omni channel retail platform from QUIZ clothing. [SP=22 Cap=7m]
◄SkinBioTherapeutics (SBTX)► positive interim data from acne treatment tests. "The supplement containing the lead formulation, being supplied to participants in powder-form." Lead? Oh, not the poisonous metal. [SP=9.5 Cap=18m]
◄PCI-PAL (PCIP)► H1-Dec rev up 20% . Pretax -£1.3m (-£1.9m). Says "KPIs continue to show performance better than expectations" but doesn't guide FY ahead of exp. [SP=48.39 Cap=32m]. I hold.
◄McBride (MCB)► H1-Dec. Guides FY adj op profit 10-15% ahead of mgmt expectations. Net debt/(adjusted EBITDA) now expected to be below 2x by 30 June. [SP=73.6 Cap=128m]
◄Synectics (SNX)► FY-Nov exceeding market expectations. Rev up 26%. U/L EPS 14.2p (6.9p). Final div 3p up 50%. Outlook confident. [SP=181 Cap=32m]
◄Diaceutics (DXRX)► significantly increases the number of labs through which it's sourcing data in Europe. [SP=96.1 Cap=81m]
◄Aptamer (APTA)► progress update for new Optimer+ platform. Tests show it's better than existing aptamer-based approaches. [SP=0.84 Cap=4m]
In line: ITX, VIC
“World Chess announces some moves which don't amount to much” - Very good sir!
Kitwave (LON:KITW) Strong results but the CEO retiring, who holds 15% of the shares may be an overhang going forward. as it would seem to be an obvious choice for him to diversify his wealth
Kitwave (LON:KITW) seems to be doing well. And EPS went up from 20 to 27. nice margin increase
· Revenues increased by 20% to £602.2 million (FY22: £503.1 million)
· Gross profit margin increased to 22% during the year (FY22: 20%)
· Adjusted operating profit increased by 49% to £32.0 million (FY22: £21.5 million)*
· Profit before tax increased by 40% to £24.9 million (FY22: £17.8 million)
· £30.3 million net cash generated from operations (FY22: £26.5 million)*
· Pre-tax operational cash conversion of 90% (FY22: 105%)*
Hopefully enough to see the stock start to re-rate upwards.
Kitwave (LON:KITW)
I thought the outlook statement was a little coy:
"FY24 has started satisfactorily and, subject to successful management of the continued inflationary headwinds referred to above, we expect a positive outcome for the year and to continue to deliver value to our shareholders."
I think it was a relatively similar message last year so perhaps nothing to fret about, but you'd think 4 months into the new FY they'd be in a place to comment directly on market expectations. Does anyone know if brokers have updated their guidance for this year? Stocko summary suggests profit will be flat. I'm curious what impact lower food inflation (and deflation in areas?) may have.
Silver Bullet Data Services has extended its partnership with Mars for the third consecutive
year, for a value of US$2.3 million, from January to December 2024. This is a substantial deal given total revenues last year were only £5.82M. This repeat business at a time when marketing spend is rather depressed in general is impressive and shows they are really adding value. I wonder if there are plans to expand their services beyond pet care business to other parts of the Mars business.
Looks good doesn't it!certainly material. I'd expect a big rise today. Managed to get some small limit orders in that got executed, hard to find stock
That's some endorsement of their 4D AI technology in the post cookie world. I've mentioned previously about some huge corporations using this tech. Sadly too illiquid to add shares in size Silver Bullet Data Services (LON:SBDS) but prospects look good imo.
Synectics (LON:SNX) results out today.
Very strong results out, with revenue up 26%, profits up to 3.1m from £1.2m. EPS increased to 14.2p from 6.9p. Dividend increased by 50%. Looking through the report I can not see any negative comments.
"In the year to date, the Company has seen continued sales momentum, driven by a robust order book and a strong pipeline of new business opportunities, underpinning the Board's confidence in the Company's outlook for the medium term."
Still looks too cheap to me. It will be interesting to see if Shore Capital increase their valuation or not.
Brickability (LON:BRCK) Mar24 EBITDA towards the lower end of expectations, meaning approx 3% down on mid-point. FY Mar25 expected to be tougher than originally expected and Cavendish sees eps 16% down on current forecast before recovering energetically and in line with expectations the following year. So a middling PW - what will the market make of it, especially after a hard run up? I trimmed 20% last week (should have trimmed harder!) and will likely repurchase if there’s an overreaction.
Shout out to Eparo for flagging this up a few weeks back:
I sold out on this news, so thanks Eparo. I am surprised to see quite a muted reaction today, only 10-12% down. I was expecting closer to 20% like you suggested BnB when I read the RNS. I have moved out of a few of the building suppliers in recent days/weeks and gone into retail stocks that look very unloved - Pets at Home (LON:PETS) , Card Factory (LON:CARD) , JD Sports Fashion (LON:JD.) and whilst not in the unloved category Marks and Spencer (LON:MKS).
I have moved out of a few of the building suppliers in recent days/weeks and gone into retail stocks that look very unloved - Pets at Home (LON:PETS) , Card Factory (LON:CARD) , JD Sports Fashion(LON:JD.) and whilst not in the unloved category Marks and Spencer (LON:MKS).
I wonder if you’re being a bit impatient with the building stocks. They’ll possibly move up on the same drivers as the retail stocks. But I do like (and own three of) your retail choices. I’d hope all will do well.
I agree - patience is at times something I struggle with and can be a little trigger happy at times. I hold around 15-20 stocks, of which about 10 are they are just mid-long term holds. This leaves around 5 or 10 to trade over shorter to medium durations. I know you run a much larger portfolio. I do have my eye on TT electronics (LON:TTG) still, one you highlighted previously as that has been drifting down, I have an alert at 140p which is fast approaching. Brickability (LON:BRCK) and Headlam (LON:HEAD) got the chop before. The other which overlaps the two sectors discussed is Topps Tiles (LON:TPT) which could both be a bid target and a nice recovery play. I would like to enter here but hoping it might pull back to 40p mark. As for your comments Zippmanpeter, again valid points, there will be a recovery at some point, that is certain. I am just banking on the fact it might happen a few months later that then retail space recovery and then I can rotate back into the cyclicals. Of course, I could be totally wrong and have made a howler!
Further to discussion above about £Brickability - this is what makes a market! I am a buyer of building suppliers because of the data. The latest stats from the ONS show the short term news on bricks is indeed grim......and the trend since 2019 has also been bad. But unless you believe that we don't need to be building more houses/infrastructure or that bricks are going out fashion, we surely must be close to the bottom. Deliveries of bricks are BELOW the average for the 2008-2010 period!
The brick making triopoly (Ibstock (LON:IBST), Forterra (LON:FORT)) have generally protected margins and cut costs/sites and have mostly paid for new energy- (& carbon-) efficient plants and capacity. This will let them compete more effectively vs the importers including £Brickability.
The political backdrop is very likely to shift to be much more supportive of large scale building quite soon. Good for Labour's younger voter base and strong growth multiplier effects for the economy. Chance for some nods towards building greener homes and other green themes. So in my mind, one more bad year maybe (with a divi, generally they are not distressed!), then they should boom.
I am not a trader and don't want to miss out. The market looks forward 6-12 months. So time to buy brick-makers (& drainage pipes, roofing & ground work materials, insulation makers?)