Small Cap Value Report (Tue 27 June 2023) - SCE, PZC, CREO, CML

Good morning! It's Graham and Roland here with today's report.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or
serious problems, so anyone looking at the share needs to be aware of
the high risk.
Summaries
Surface Transforms (LON:SCE) - 31p (pre market) (£76m) - AGM TU - Roland - AMBER
Production issues are gradually receding at this manufacturer of high-performance carbon brake discs, but H1 revenue appears to be a little behind expectations. This still looks speculative to me, but I’m encouraged by the quality of recent boardroom hires.
PZ Cussons (LON:PZC) - down 4% to 167.6p (£719m) - FY update - Graham - AMBER
This update for FY 2023 looks weak in terms of revenue but the company also faces a significant currency headwind to performance for FY 2024, following a devaluation in Nigeria. I like this company but as an investment I think there are superior alternatives.
Creo Medical (LON:CREO) - up 1% to 36p (£126m) - AGM Statement - Graham - RED
This company issues a bullish AGM statement and announces a succession plan for the Chair. Regardless of the value of their technology, they only seem to have a modest chance of getting to profitability without raising more cash. I therefore give it the thumbs down.
CML Microsystems (LON:CML) - up 4% to 464p (£71m) - FY results - Roland - AMBER
This well-established semiconductor design group delivered strong revenue growth last year and has a cash-laden balance sheet. But while profits rose sharply, returns on capital remained very low. On balance, I think the shares are up with events.
Graham's section
PZ Cussons (LON:PZC)
- Share price: 167.6p (-4%)
- Market cap: £719m
Let’s get up to speed with the latest news for this owner of brands including Carex, Imperial Leather and St Tropez. The company has issued a trading statement for FY May 2023.
Key points:
Like-for-like revenue growth of 6.7% in Q4, 6.1% in the full financial year.
Full-year revenue £655m (N.B. this is below the estimate I can see on the StockReport of £669m).
Adjusted PBT at least £70m.
Nigeria
As of FY 2022, PZC generated over a third of its revenues from Africa, with Nigeria being the key location.
Today’s update includes a major section devoted to foreign exchange policy in Nigeria, following a 36% devaluation of the Nigerian currency (“NGN”) earlier this month. About a third of PZC’s revenues are denominated in NGN.
The devaluation will not affect FY May 2023 results. Unfortunately, I think it does mean that the FY May 2023 results are unreliable, as they use the previous exchange rates.
The rates used in PZC’s results are between 536 and 577 NGN to the US dollar, whereas the new rate is a far weaker 750 NGN to the dollar.
It’s a devaluation in the region of 30%. PZC say that every 10% reduction in the value of this currency hits adjusted operating profits to the tune of about £3 million, and reduces the cash balance by £20m.
The company reported a total cash balance (in all currencies) of £196m as of December 2022. A very large chunk of their current cash balance must be in the form of NGN.
I would also note that as of December 2022, their cash balance was offset by £232m of non-current borrowings, so they did have a net debt position.
More positively, they say their Nigerian business has recovered from an operating loss in FY 2020 to a positive operating margin of more than 10% in FY 2023, and they consider themselves well-placed “to withstand any macro-economic volatility”.
CEO comment:
While the Naira devaluation will have a one-off impact to the Group's near-term reported financial performance, we believe the medium to long term prospects for our Nigerian business will be much improved by the economic reforms, currently being introduced by the new government, the likes of which have not been seen for decades.
More widely, PZ Cussons has delivered another year of progress against a challenging economic backdrop. We have continued to transform the business and build brands for the long term, while responding to the day-to-day challenges of cost inflation and meeting the needs of the cost-conscious shopper. This has resulted in a third consecutive year of like for like revenue growth in FY23.
Graham’s view
I have read comments online suggesting that the new NGN exchange rate is now about right, or even undervalues the currency, compared to the previous rate.
That would be good news, as it would undermine the black market and allow legitimate businesses such as PZC to trade the currency at fair prices.
However, my understanding is that the currency remains tightly controlled, so there is nothing to stop a disparity between the official rate and unofficial rates from materialising again.
I wrote previously that I was between Green and Amber on this stock. Today, after reading about these difficulties in Nigeria, I’m going to sit firmly within the Amber (or neutral) camp.
I want to like it, as the brands strike me as being fundamentally sound, but like-for-like revenue growth remains slightly too pedestrian for my taste, especially considering the inflationary environment.
Additionally, the risks in Nigeria are perhaps bigger than I previously understood. And the balance sheet is not exactly overflowing with riches.

The stock isn’t expensive according to the metrics and as a long-term hold it may have some merit. But I suspect that investors can find better options than this, particularly in the branded consumer goods sector.
Creo Medical (LON:CREO)
- Share price: 36p (+1%)
- Market cap: £126m
We have an AGM statement from the Chair of this medical devices company.
Excerpt:
"Creo Medical continues its evolution from UK medical device innovator into an international group focused on the clinical and commercial adoption of a full suite of electrosurgical products. Having reported revenues in 2022 of in excess of £27m, we continue to experience growing demand for both our core technology and our complementary range of endotherapy devices."
As noted by Paul, this company raised £34m in March at 20p per share, so it has been a pleasant few months for shareholders since then.
Funds are being used “to enable world-leading clinicians to develop new ways to treat a growing number of indications with our devices and technology with the intention of driving the business through to cash flow break even, and, ultimately, profitability”.
Later in the statement, the Chair announces a succession plan for himself::
I have agreed with my fellow directors that we should seek to recruit an experienced international medtech executive as an additional independent non-executive director who would be suitable to succeed me as Chair and for those changes to take effect no later than the 2024 annual general meeting of shareholders.
Graham’s view
Creo clearly believes that it needs new Board leadership for the next stage of its growth. Fair enough if that’s what it wants.
The bigger issue here is that adjusted pre-tax losses are forecast to come in at £24m for the current year, and £15m for 2024. I don’t think we have forecasts for 2025 yet, but they would have little predictive value anyway.
According to an analyst note published last week, “we estimate the company is funded to operational profitability into H1 2026”.
However, it looks very tight to me. The company had cash of £13m at the end of 2022. It then raised £33.7m (gross) with net proceeds of I believe c. £32m. So that’s about £45m in total cash resources.
With the official forecasts suggesting £39m of adjusted pre-tax losses across 2023 and 2024, and with those forecasts most likely being on the optimistic side, and with more losses likely in 2025, the cash runway here does not look long enough for comfort. I therefore have no choice but to give this share the thumbs down.
Roland's section
Surface Transforms (LON:SCE)
- 31p (pre-market)
- Market cap: £76m
- AGM Trading Statement
I last commented on this manufacturer of high-performance car brake discs in April, when I speculated that problems ramping up production might still leave the business short of cash. Today’s AGM statement reports that manufacturing output has improved, but still hasn’t reached target levels.
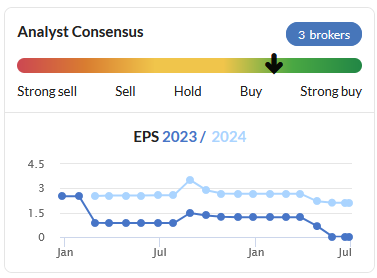
Sales for the half year to 30 June are expected to be £3.3m (H1 2022: £2.9m). However, the volume of production discs manufactured during the period has increased by more than 80%, reflecting production improvements.
According to a note from broker Zeus this morning (available on Research Tree), this level of revenue is below their analysts’ H1 forecast of £5m.
However, the company has reiterated its guidance for 2023 and 2024 and broker FinnCap has also left full-year forecasts unchanged.
The company says it lacks the capacity to make up for disruptions to production but is continuing to add capacity. By the end of this year, management expects to have surplus capacity over current demand.
Separately, I notice Surface Transforms has just hired a very experienced-sounding new CFO from James Cropper (LON:CRPR) and a new COO with carbon fibre manufacturing experience. I’ll be interested to see if these appointments prompt any changes over the coming weeks.
I think Surface Transforms is a good example of a recurring issue that growth investors sometimes overlook – rapidly ramping up to commercial levels of production can be very difficult, even when you have contracts in the bag and a good product.

Roland's view: This business is still a little too speculative for me and I continue to think there’s a risk cash could run short -- there's no update in today's statement on cash levels.
However, I think there’s a credible story here and am impressed by the apparent quality of recent boardroom appointments. If the company can deliver on 2023 and 2024 guidance, the shares might not be too expensive at current levels. I’ll be watching progress with interest and have tentatively gone to amber on this one.
CML Microsystems (LON:CML)
- Share price: 446p
- Market cap: £69m
Full-year results y/e 31 March 2023
"This has been a strong performance for CML with trading for the period ahead of initial expectations.”
Today’s results cover the year to 31 March and appear to show solid growth in revenue and profits. Cash remains a dominant feature of the balance sheet, providing significant downside protection.
This AIM-listed semiconductor design group operates in areas such as microwave communications and RF technology.
CML has been listed on the London markets since 1986 and appears to have been a solid investment over the last 20 years, at least for investors who’ve caught the periodic lows:

Let’s take a look at today’s results.
Financial highlights: profits for last year were boosted by a £2.1m profit from the sale of surplus property owned by the group. To provide a clearer view of the performance of the operating business, I’ve stripped property profits out of the results below:
Revenue up 22% to £20.6m
Operating profit up 142% to £2.93m
Pre-tax profit up 77% to £3.2m
Earnings per share up 161% to 19.2p
Full-year dividend up 22% to 11p per share
Net cash of £22.3m (FY22: £25.0m)
CML’s profitability increased dramatically last year, with the group’s operating margin doubling from 7% to 14% – the highest since 2017:

This increase in margins appears to be the result of operating leverage – a feature of businesses with high fixed costs and low variable costs.
In this example, we can see CML’s staffing and overhead costs only rose by 9% last year, whereas revenue rose by 22%. With gross margin unchanged at 75%, much of the extra revenue dropped through to the bottom line, providing a big boost to profits.
This is nice to see, but I still have some concerns about the profitability of this business. Even if we include the property gain, CML only generated a return on capital employed of 8.8% last year. Excluding property, my sums suggest ROCE was just 5.2%.
I think that one reason for this is that CML appears to capitalise quite a lot of its development expenditure onto its balance sheet. This means that associated costs, such as staffing, may not be fully reflected in operating expenses.
Today’s balance sheet shows £13.8m of development costs listed under non-current assets, up from £11.2m last year:

Scrolling down to the cash flow statement, we can see the amortisation and cash costs associated with these assets:
Amortisation of development costs: £1.8m (FY22: £1.5m)
Investment in development costs (i.e. cash expenditure): £4.5m (FY22: £3.5m)
Capitalising development expenditure in this way is perfectly legitimate when the products being developed are expected to deliver commercial revenue over a number of years.
But this approach can also flatter reported profits. Last year’s amortisation charge of £1.8m was subtracted from reported profits, but the £4.5m “investment in development costs” will have been excluded from operating costs.
The effect of this is that CML’s operating profit last year was £2.7m higher (£4.5m - £1.8m) than it would have been if the company had expensed all of its development costs in the year they occurred.
As always, I think free cash flow tells the real story. Looking at today’s accounts, I estimate underlying free cash flow (excluding property and acquisitions) of just £182k, compared to a reported net profit of £3.1m before property gains.
Looking at these numbers, I think it’s reasonable to argue that CML’s low returns on capital employed may provide a more accurate reflection of the group’s true profitability than its operating margin.
In fairness, another reason for low ROCE is the £22m cash balance, which represents about one-third of total assets. My sums suggest that reducing net cash to £5m would increase ROCE by about 2%.
Trading commentary: CEO (and 8% shareholder) Chris Gurry reports “broad based” revenue growth last year across “resilient end-markets”.
Seven new products were released and the company entered the broadcast sector with a low-power DRM receiver solution (a digital radio product).
The company says it invested 25% of revenue into research and development last year, reflecting my comments above.
The acquisition of US firm Microwave Technology, Inc. for $18m that was announced in January remains underway, subject to certain approvals.
Further property disposals are planned, with another £2m sale expected this year.
Outlook: the company says its confident the current strategy will “yield the sustainable long-term growth we are looking to achieve”.
Expansion into the microwave sector is now said to be delivering “tangible results”, with good growth expected.
The Board expects to report “solid growth in revenues and operational profitability” for the year to 31 March 2024.
There doesn’t seem to be any change to existing expectations today. Existing consensus forecasts shown on Stockopedia suggest adjusted earnings could rise by 19% to 23.2p per share, putting the stock on a forecast P/E of 19.
A further increase in the dividend is expected to 13p per share, giving a prospective 3% yield.
Roland’s view: I’ve only taken a brief look at CML’s activities today. My impressions are that this is a decent business, but it’s having to invest heavily in new products in order to generate growth.
While the balance sheet looks bulletproof to me and is being further bolstered by cash proceeds from property sales, the accounts for recent years suggest to me that CML may not be generating very attractive returns on its operating assets.
The bull case here would be that current investment will yield attractive returns in the future, as revenue scales up. That may be possible.
However, as far as I can see, ROCE has been below 10% every year since at least 2017. I think that merits a degree of caution, in terms of pricing in future growth.

On balance, I’m neutral here. I think the valuation is up with events, but this business does have some attractive features and a reassuringly low track record of operation as a listed business.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
Just trying to think where UK markets are in the cycle right now. Im wavering between having a second capitulation and a grinding despondency. Maybe fund redemptions and earnings misses will grind values lower for a little longer yet?
Personally I've traded almost everything last year and this but will likely come a time to buy and hold for a sustained rally at some point. Can't remember seeing such accross the board value in many a year, It's all about timing now I reckon. Twitter/ADVFN/comments here are quiet, if inflation starts to meaningfully fall next month/energy cost fall...earnings probably trough out before year end unless there's a bad recession, we can look out 6-8 months to better prospects.
UK Food prices finally looking to have topped
I do not agree with your conclusion. What the graph is actually saying is that the rate of increase of food prices has declined. But what is actually happening is that food prices are continuing to increase. So food prices have not topped.
Although I don't disagree with analysis of the graph suggesting rate of increase has declined I actually think this is seriously lagging. Looking at supermarket prices on a lot of fast moving foods the prices are actually falling on hundreds of products. Butter as an example in the last month has fallen by 5% across the board and so on.
So the graph above is lagging a bit but I suspect will go negative in the coming months.
Services/flights on the other hand are trying to go the other way so we'll have to see how that plays out in the overall figures.
Yes butter down 10p, is the only fall I have seen. Potatoes shot up, cheap bread up 25%, sugar up again now 105p, eggs up again, these are in Aldi. Recently beer, biscuits, yoghurt and porridge all gone up. Some prices seem to be peaking. I'm finding the quality of veg. to be poor, certainly seems to have gone down recently. Some products are out of stock, quite a few gaps on shelves.
Wholesale milk prices have fallen considerably but potatoes are up around 100% On last year.
Some media commentators seem to misunderstand that if inflation falls, they think prices are falling.
Yes, I should have said UK Food prices (y-o-y % increase) finally looking to have topped. Didnt mean £
Who is Granimator?
I bought @cml February this year at 582p so far it's only gone one way as it's now 460p. Just waiting for these final results before I decide to cut my losses.
PROCOOK (LON:PROC) - Fackelmann GmbH have amassed a near 12% holding. Could they be interested in acquiring the company?
Like Mr Contrarian I hold Unbound (LON:UBG) probably along with many Stockopedia subscribers unless they had the good sense to get out of this disaster with some small return! Today’s announcement pretty much confirms their demise. Who is going to put £1.5 - £2.0m in this disaster of a company. I expect Hostmore (LON:MORE) will go the same way before too much longer. Remind me never to invest in a business that is an IPO from a private equity outfit. Electra really sold investors down the river and convinced many investors and commentators on Stockopedia that there was a good business here. It has proved anything but!
Hi Roland, I respect your view on Creo Medical (LON:CREO), the financials and cash burn (c £2m / month) are not flattering. I would like to suggest there may be significant upside in Creo Medical (LON:CREO) over the next few years.
Last week the received CE approval for upper GI procedures (Throat to Stomach) via their Speedboat inject product. Such procedures accounted for 40% of all procedures performed in the US and APAC so they have significantly added to the European obtainable market.
On June 1st they received notification that there speedboat inject product has been selected by NICE for assessment. "The guidance, if favourable, often results in improved adoption of the device or technology. NICE guidance, though not binding, is followed by the NHS, the UK’s public-funded healthcare system, for optimising its resources."
Creo Medical (LON:CREO) are currently in 23 NHS sites out of a possible 350. If NICE produce a positive assessment, Creo Medical (LON:CREO) Obtainable Market is significantly expanded by a factor of 10 in the UK. The NICE process takes up to 38 weeks.
Stupidity of North Sea windfall tax there for all to see. I did hold Shell for a couple of years but Id never buy another European oil share, next time oil drops towards $30 much better looking at an US oil etf in my opinion.
From FT
"In November, when chancellor Jeremy Hunt increased an existing windfall tax on the profits of oil and gas companies and extended it until 2028, the government predicted the so-called energy profits levy would raise as much as £41.6bn with a headline tax rate on the sector of 75 per cent.
But in the Treasury’s most recent forecasts from March the estimated tax take has dropped almost 40 per cent to £26bn, reflecting a sharp fall in the price paid for oil and gas in wholesale energy markets."
Surely someone will see sense? Maybe not.
"The main opposition Labour party, which is leading in the polls ahead of an expected general election next year, has vowed to extend the windfall tax by backdating it to the start of 2022 and scrapping its generous investment allowance."
I shouldn’t worry too much about Shell (LON:SHEL) & BP (LON:BP.) as North Sea operations are a small part of their worldwide operations and profitability. Also if the likes of Ed Miliband & Ed Davey (yes he is Labour in disguise!) who are the promotors of this ideologically motivated retrospective tax succeed we may see the multinationals seek domicile in a more enlightened regulatory environment. Unfortunately the independent operators in the North Sea are already cutting jobs and reducing investment. So much for energy independence and yes we are getting more from renewables (wind & solar) but what happens when the wind doesn’t blow and the sun doesn’t shine - not to mention the endless delays and high costs of Nuclear power.
Indeed. Relying so much on the wind fairies for cheap green energy has taken a knock this week
https://www.reuters.com/busine...
I think that these are such big beasts and so hard to understand that one might as well invest instead in a global O&G exploration and production ETF. This is what I've gone for... https://www.ishares.com/uk/ind...
Pity it's not more up to date but useful information nonetheless
https://bmbi.co.uk/the-index/#
"The latest Builders Merchant Building Index (BMBI) report shows builders’ merchants’ value sales down by -9.0% in April compared to the same month in 2022. Volume fell -20.2% with price inflation of +14.0%. Taking trading day differences into account, like-for-like sales were -4.0% lower as April 2023 had one less trading day than the same month in the previous year.
Seven of the twelve categories sold more this year than in April 2022. Renewables & Water Saving (+55.4%) was the strongest performing category by some margin, followed by Decorating (+8.3%) and Plumbing, Heating & Electrical (+5.3%). Timber & Joinery Products (-20.6%) and Landscaping (-23.3%) were the weakest.
Month-on-month, total merchant sales were down -12.7% in April compared to March 2023. Volume sales were down -11.9% with prices registering a small decline (-0.9%). But with five less trading days in April, like-for-like value sales were up +11.6%. Landscaping (+3.3%) was the only category to sell more, while Plumbing, Heating & Electrical (-22.6%) and Workwear and Safetywear (-26.7%) were the worst performing categories.
Total merchant sales in the twelve months from May 2022 to April 2023 were +1.5% higher than the same period a year ago. Volumes fell -12.5% with price inflation of +16.0%. With two less trading days in the most recent period, like-for-like sales were +2.4% higher. Ten of the twelve categories sold more with Renewables & Water Saving (+39.9%) well ahead of Plumbing, Heating & Electrical (+13.6%), Kitchens & Bathrooms (+13.3%), Decorating (+12.2%) and Heavy Building Materials (+7.7%). Landscaping (-8.5%) and Timber & Joinery Products (-11.6%) both sold less."
Hi
Not a small cap, but good to see a UK-listed quite recent IPO Wise (LON:WISE) capturing impressive growth.
SP up +18.46% as I type. It has fallen quite a lot in recent past, was 622p 13/06, then fell to 525.40 26/06. Today 617.40 as I type.
Some Stocko fin-tech growth investors might be interested to take a look.
Headline from RNS .....
Our strong growth and continued profitability are a direct result of our focus on our mission and our customers. This year approximately 10 million people and businesses chose Wise to move and manage their money internationally, an increase of 34% YoY. And in total, we helped these customers move c.£105bn across borders, up 37% YoY. This growth drove a 51% increase in revenue and a 73% increase in income[1] for FY2023.
RNS here ....
https://www.investegate.co.uk/...
I hold very small amount.
Regards
Howard
Wise may turn out to be a fintech success. I have an indirect holding through Scottish Mortgage 3% interest.
Slight fall in shop price inflation. Everyone seems so negative that any surprise inflation figures next month will likely be a big boost to the market.
Mind you with all the media seamlessly switched from inflation forecasting experts to Russian military command chain experts they might not have time to notice.
Period Covered: 01 – 07 June 2023
Helen Dickinson, OBE, Chief Executive of the British Retail Consortium, said:
“Households up and down the country will welcome the easing of shop price inflation in June. Food inflation slowed for the second consecutive month, particularly for fresh products, as retailers cut the price of many staples including milk, cheese and eggs. Clothing and electrical goods also saw falling prices, helping customers to pick up a bargain ahead of the summer holidays.
“If the current situation continues, food inflation should drop to single digits later this year. However, it is imperative that Government does not hamper this progress by introducing costly new policies. Reforms to the packaging Levy (Extended Producer Responsibility) and a new deposit return scheme, could create an additional £4bn burden on retailers and their customers. Along with a rise in business rates, and the introduction of border controls in October, these policies could hinder the Government’s efforts to combat inflation.”
Surface Transforms (LON:SCE) This is going to sound horrible, especially as Surface Transforms seems like a great little British business with great technology; however, the chances of the company achieving £16.2m of revenue this calendar year (Finncap forecast) after achieving £3.3m in the first half is zero.
In addition, the company is already forecast to have negative free cash flow of over £10m this year, even if it does achieve those revenue targets. With those targets net cash would be around £3m at the end of the year..... however, if they miss the revenue targets considerably (which seems incredibly likely) then they will likely be in the red.
I would think that they will come back to the market for more cash by this time next year and therefore unfortunately, this stock has to be marked "Red" in the short term in my opinion.
Surface Transforms (LON:SCE) I dont think you're being horrible, just truthful.
Going back 20 years free cashflow has been negative every year, as will this year . Sharecount has ballooned from 9 million to 240million. I suspect it will grow again later this year.
Sales were 3.3m in H1. Zeus forecasts Q4 sales of 8m. Good luck with that. If they hit targets then good luck to them but it looks a long shot. In a market with quality companies trading on 8-12 x multiples why buy this?
I agree going from £3.3m to £16m is impossible now for the FY23. But it would be close, as their max capacity at the moment is c£20m per year. If they solve all the teething issues. If one assumes maybe possible to hit 85% of capacity in H2, then that's £8.5m in H2, giving a FY revenue of £11.8m.
But really, as share investment is forward looking, the number to focus on is that in H2 this year, they will probably get to c£17m revenue run-rate.
Cell Two, which adds another £15m capacity, will come on-line in Q3. Lets give a buffer and say Q4 commissioning. And only reaching 85% of capacity in H1 next year.
That means, over the next 12 months, the run-rate is going to be £8.5m (H2-23) + £14.8m (H1-24) = c£23m revenues run-rate.
My back of the envelope calcs:
Which is not bad given the current market cap of £73m. As we should then expect rev in 12-month to Dec24 to grow further to around £30m....
Disappointing update today. Would have thought they now ironed out all production issues, given that its now been up and running for >6 months.
(I hold in the Boon Fund)
I hope that you are right as it would be good to see a small British engineering company doing well. I will be keeping my cynical hat on until I can see that the business model definitely works and they can be cash generative. As they have never managed to hit their target numbers before, I have to remain sceptical that they will get close to any of your numbers above.
As a recap, here are Finncap's Surface Transforms predictions from 2016. Needless to say, I doubt that anybody thought that 2022 revenues (£5.1m) would be just over half of the predicted 2019 revenues:
Accsys Technologies (LON:AXS) - Has anyone had the patience to go through the 51 page 'preliminary' results report ? Seems still a standstill and a mess over the Hull Tricoya plant
How is a +34% in revenues YoY a standstill at Accsys Technologies (LON:AXS) ?
And pleasingly, it is driven by pricing power. Only +6% increase in volumes sold.
Frustratingly, they still seem to have factory building issues, which is their achilles heel throughout the years. USA factory timelines keep slipping and slipping. No doubt there might be a cash call at some point for extra funds to complete it.
Also outlook statement, they have given themselves scope for a profit warning later this year, mentioning that there is a softening of demand.
No comment on Accsys Technologies (LON:AXS) , but generally I disagree that rev growth driven by price increases is better than rev growth driven by increased volume sold. Pricing power is important, especially in an inflationary environment, but over the longer term, a bigger market for your product is generally a much more important driver of growth. There is only so much you can increase prices.
That is true, volume growth is more important than pricing growth long-term.
And this is where the investment case for Accsys Technologies (LON:AXS) comes in. Their volume growth is currently constrained due to existing factory capacity. The demand is there (Demand > Supply , albeit their outlook statement for H2-23 puts that into uncertainty).
Therefore volume growth is just dependent on getting the USA factory up and running, and also the Hull plant construction back on track. And potentially a JV/licensing agreed with an Asian partner (mentioned in the past). Demand, apparently, was far above supply at the moment to not worry (until now).
re Accsys Technologies (LON:AXS), I don't see anything much new from the previous update. My own feeling is that they are concentrating management effort on getting the US Accoya plant up and running. It looks like fixing Hull will need a lot of the detailed engineering design work to be done, which must have been missing originally, and that is going to take time. I hold.
Pressure Technologies (LON:PRES) the turnaround appears to be on track, albeit the company needs to refinance its debt as the current RCF expires at the end of the year and the amount available steps down at the end of September.
Having said that the company has adopted the 'Going concern' basis, which reassures and Rockwood Strategic (LON:RKW) have a significant holding with manager Richard Staveley on the board of Pressure Technologies (LON:PRES) as a non executive director. I hold.
Over to you Roland
I see that RBG Holdings (LON:RBGP) changed its name to RevolvingBoardGambit Holdings at the latest AGM
My morning smallcap tweet: The Muppet Show
Unbound (LON:UBG) Bango (LON:BGO) Arecor Therapeutics (LON:AREC) Surgical Innovations (LON:SUN) Surface Transforms (LON:SCE), Inspiration Healthcare (LON:IHC)
◄Unbound (UBG)► ends formal sale process - no acceptable offers. Still trying to sell main op subsidiary but may result in little or nothing for holders, Also looking at placing of £1.5-2m to support implementation of a formal restructuring plan. Trading continue to be impacted by lack of cash. Profitability in line. [SP=2.5 Cap=2m]. I hold.
◄Bango (BGO)► 3 yr $8m loan at 6% with warrants at 202p. [SP=187 Cap=144m]
◄Arecor Therapeutics (AREC)► granted key patents in EU and China. Protects its Arestat technology and innovative insulin products. [SP=244 Cap=75m]
◄Surgical Innovations (SUN)► AGM stmt - "orderbook is extremely positive, providing confidence in management forecasts for 2023". [SP=2.01 Cap=19m]
◄Surface Transforms (SCE)► AGM stmt- Q1 production probs have not recurred, but still getting "individually small production disruptions that have slowed the ramp up in output". Nevertheless reiterates guidance for 2023 and 2024. [SP=31 Cap=75m]. I hold.
In line: IHC
re: Unbound (LON:UBG) would you care to explain why you hold. you paint the summary so poorly, it seems odd to conclude with 'I hold' ? have you spotted something?
CML Microsystems (LON:CML) excellent results even excluding sale of land which I assume is exceptional item
The shares have drifted down over the past 3 months but this should show a rebound but you never know with the market
Morning richardho, CML Microsystems (LON:CML) is on my list for this morning.
Roland
Thanks Roland much appreciated
Thanks Roland, also interested on your thoughts here. I was a little surprised that the SP has not moved following the RNS, which to me seems well written and clear, it notes trading and revenues above initial expectations. There are positive noises in the RNS around further land sales and the outlook comments are reassuring, PER now seems more reasonable for a company in this sector and the divi has continued to be increased. Maybe some early morning profit taking with a gradual rise up later in the day?
More Unbound (LON:UBG) misery.