Small Cap Value Report (Tue 28 April 2020) - LOOK, SNX, SYS1, MKS, IQE, PLUS, MKS

Hi, it's Paul here, with the SCVR for Tuesday.
Estimated timings - most of the report is ready for the 1pm email, but I'll keep going until about 4pm with extra sections.
Today's report is now finished.
Market thoughts
As always the macro/virus picture is very uncertain, and I'm constantly grappling with this, as I'm sure you are too. How do we balance up catastrophic short term economic damage, offset by unprecedented Govt support & stimulus? Lockdown is far too expensive (in economic & human costs) to continue, as shown in the recent OBR report.
There's big potential upside if/when an effective treatment, and then probably later, a vaccine, is created.
There's big downside potential, if/when subsequent waves of the virus happen before there's a treatment for it.
It's all down to timing really. Nobody knows with any accuracy how this is going to pan out, hence why I am wary of anyone that expresses their views/predictions with too much certainty. It's not "will", it's "might".
In the shorter term, now that the virus seems to be peaking & starting to reduce in many countries, then that is increasing demands for lockdown to at least be eased in stages. I'll be closely monitoring how that goes, as it's likely to be a key driver of share prices. It's also important to look at data, as this very often gives a different true picture, compared with the media attention given to tragic, but often atypical, cases.
Taking all that into account, I'm trying to position myself in shares where I see good recovery potential that hasn't yet been fully baked into the current price.
Recent purchases have been housebuilders (done well), car dealerships (only a small recovery in price so far), on the basis that they're likely to get back to business very soon. I foresee pent up demand for both.
Property REITS are another area I've bought, but made a loss, having jumped the gun.
These are more trades than investments, and I'm trying to buy liquid mid caps in those sectors, so I can ditch them any time, as the facts change.
Looking forwards, I think H1 company results could be so dire, that we might see another move downwards in the markets in the summer, once people see the full enormity of many companies' losses. Or investors might look through short term losses, I don't know. Remember that at the moment, some company liabilities are just being deferred, but still have to be paid at a later date (e.g. rents, VAT, payroll taxes, etc). The furlough scheme could get very complicated, as in many cases, it's likely to be cheaper for e.g. shops & bars to remain shut. Once furlough stops, then expect vast numbers of people to be made redundant. That could get very sticky, if handled badly.
I'm also looking at most refinancing situations. I did well on Joules (LON:JOUL) - but have now sold them, as the surge in price recently looks to have baked in the upside for now. I've also gone long of Foxtons (LON:FOXT) as I liked its refinancing (de-risked for now), and the lettings side of the business should keep it ticking along. Also, what it said about doing virtual viewings, etc, puts it in the category of companies which are innovating effectively, and continuing to do business with staff working from home, and using technology - another important theme.
I used Zoom last night for the first time, and found it enjoyable & it worked well. A valuation of c.$35bn is now attached to the company! I'm not sure how that makes sense, given competing products from Microsoft Teams, and Facebook, and that most people are using Zoom for free. On this topic, it's really good to see lots of initiatives in the shares world, with a big increase in webinars, etc on the internet, to enable companies to communicate with shareholders. I've not had any meetings in London for a while, which has saved lots of time. Mind you, I am looking forward to sinking a few pints in the Lord Aberconway (opposite Finncap's offices) with my investing friends, once meetings resume. Web-based meetings will have to suffice for now, but you can't beat a proper face-to-face meeting & subsequently comparing notes in the pub with other investors that you like & respect. Also, the staff in the Lord Aberconway are great - they retrieved, held & returned my suit jacket (with passport in pocket) once, as I tottered off into the balmy summer evening in 2019 or 2018, having completely forgotten that I had earlier been wearing a suit jacket at all, let alone that my passport was in the pocket. Good eggs, which I rewarded with a generous donation to their staff party.
Another point to consider, is that the indices are not the economy. US indices in particular are very tech heavy, and people see those companies as beneficiaries from the current crisis. Healthcare is also doing well, for obvious reasons. Whereas travel companies and others which are being hurt by the crisis, have seen their share prices rightly smashed downwards, then more recently some recovery as reduced lockdown is priced in. Markets look forwards.
Therefore, by looking at just the benchmark index (Dow Jones, or S&P 500), we're not seeing the detail that perhaps makes more sense than the headline index figure alone? Maybe it's not as incongruous as many of us thought that US markets have recovered about half the losses? I don't know the answers, but am thinking about this stuff all the time, and absorbing/processing views from many sources.
My hedges (shorts) worked extremely well from late January (as disclosed in the SCVR for 27 Jan 2020 which is interesting to revisit), but became too expensive (i.e. losses) more recently, so I closed my shorts on the Dow & most other things. My only (smallish) short currently is Rightmove (LON:RMV) . I don't really like shorting, and am not very good at it, but it's saved my skin in the last 3 months, more than covering all the heavy losses on my longs- many of my speculative small caps have been really whacked hard by Covid-19.
To summarise my current thinking (subject to change at any time), I'm long reasonably-priced companies where I see recovery potential, but am keeping a close eye on the exit. If specific shares recover to a point where they look fully valued (e.g. Joules) then I'm selling, and looking out for better value opportunities elsewhere. By July/August, I'm intending to sell more things, and have a higher proportion of cash, because I'm worried that H1 results statements could look a lot worse than currently imagined (people sometimes forget about operational gearing in downturns). But that depends entirely on how the big situation has developed by then.
Overall, I'm looking at things on an individual, share by share basis, rather than forming any particular view on the indices.
This is a time to be very flexible in our thinking, rather than sticking rigidly to a preconceived viewpoint. Isn't that always the case though?!
Lookers (LON:LOOK)
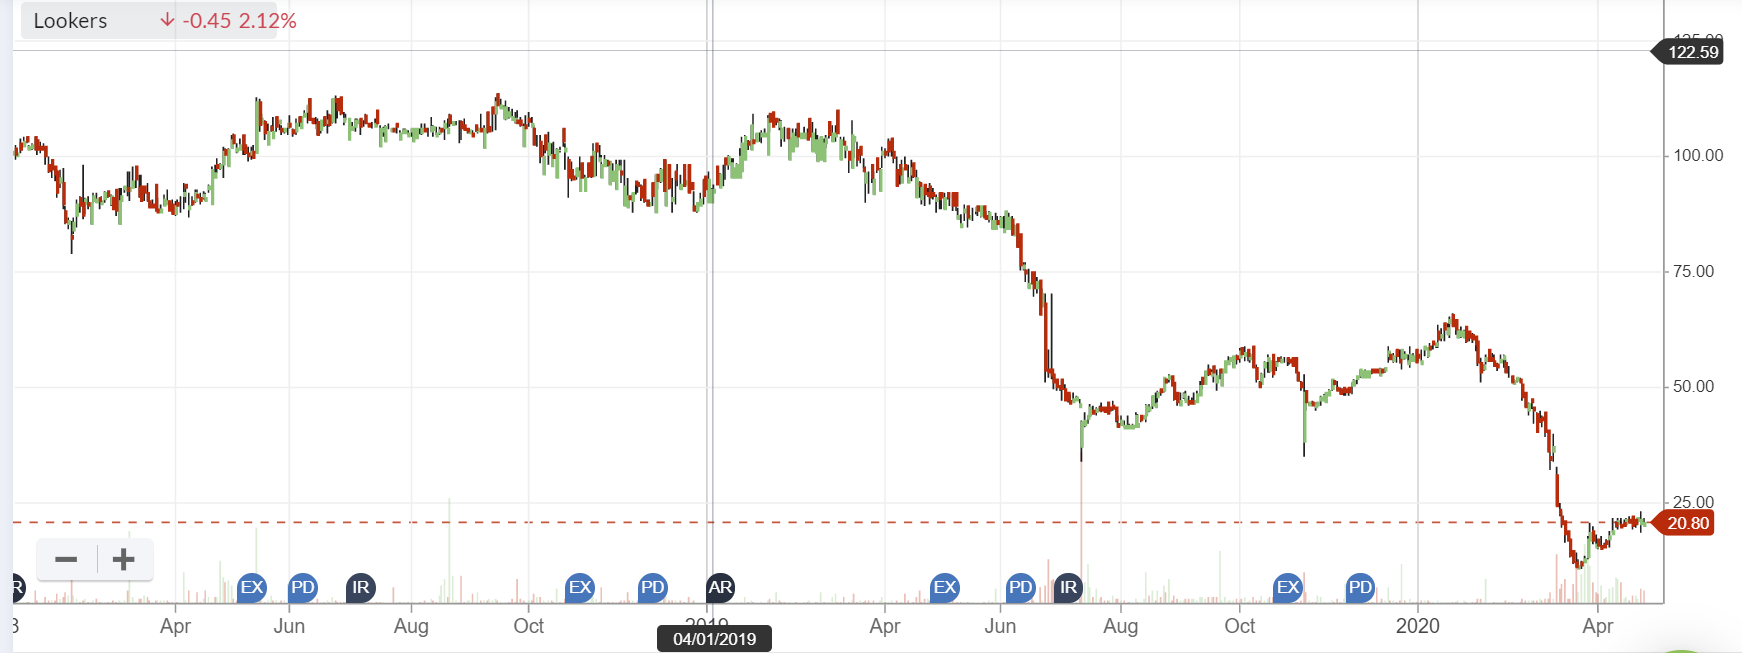
Share price: 20.8p
No. shares: 390.1m
Market cap: £81.1m
Recap - I reported here on 11 Mar 2020, when this car dealership chain announced it had found possible fraud in its accounts. The share price fell 30% to 26p on the day.
I reported here on 26 Mar 2020 on its Covid-19 update, which seemed to reassure the market.
Latest update (28 Apr 2020) - note that it has a 31 Dec 2020 year end.
Things were not great even before Covid-19 struck, with negative LFL sales of new & used vehicles, and margin pressure, in the 2 months to 29 Feb 2020. Cost-cutting measures were taken in Nov 2019.
As we already know, all its sites were closed on 23 Mar 2020. Since then 31 sites have been partially re-opened for repairs/maintenance of key workers vehicles.
Property disposals - 7 freehold sites sold (proceeds of £17.6m raised in 2019). More disposals planned in 2020.
Furloughed 7,000 staff. Board & senior mgt taken temporary 30% pay cuts.
Net debt - was £62.0m at 31 Dec 2019. Barely changed at c.£65m as of now. Bank facility is £250m RCF, expiring in Mar 2022, which seems to give LOOK lots of headroom.
Fraud investigation - Grant Thornton were brought in, the "initial phase" is now complete;
The initial phase of the investigation focused on the operating division concerned and identified certain misrepresented debtor balances in respect of bonus receivables together with a number of fraudulent expenses claims. These items are expected to give rise to a one-off, non-cash charge, in the 2019 financial statements of circa £4m.
I would have preferred a much clearer explanation. Fraudulent expenses claims is straightforward - that's employees stealing money via expenses. I'm not sure what the other bit relates to. Possibly fake invoicing, in order to trigger staff bonuses? It's not clear. But anyway, person(s) unknown with the company have been on the fiddle. That means previous profits were over-stated. £4m is a fair bit, not minor fraud.
Phase 2 is underway, looking at all other operating divisions within the group. This has unearthed what sounds like sloppy bookkeeping (being generous there), but again this would have meant previous profits were over-stated;
Initial indications have identified some operating divisions where certain non-cash balance sheet accounts have not been fully reconciled, in accordance with Group policy. These items are expected to give rise to a one-off, non-cash charge, however this part of the investigation is still ongoing...
Outlook - clearly Covid-19 is bound to have a major impact;
The Board is contemplating a range of post covid-19 reopening scenarios and is considering the challenge of managing the Group's cost base against what the Board considers will be materially lower volumes, as a consequence of continued social distancing measures.
It declines to give us any more detail, or any figures, which is a cop out in my view. Other companies are publishing base case, and downside case estimates. We really need this information. There again, financial control doesn't seem to be a strength at LOOK, so it's hardly a surprise it's vague on this issue.
My opinion - I wouldn't invest in anything with an ongoing fraud/accounts investigation underway, because they usually turn out to be worse (sometimes disastrously worse) than originally thought.
We're also not given enough information on likely current/future trading.
On the upside, it has a treasure trove of freehold property. I wonder if the inventories of vehicles might need a provision made against them, if dealers are forced to discount heavily once business resumes?
I'll be happy to stay on the sidelines until the accounting investigation is concluded & published. Hence not for me.
Valuations are so low in this sector, I do wonder if sector consolidation could be on the cards? Private equity could be attracted by the freeholds, maybe?
.
.
Synectics (LON:SNX)
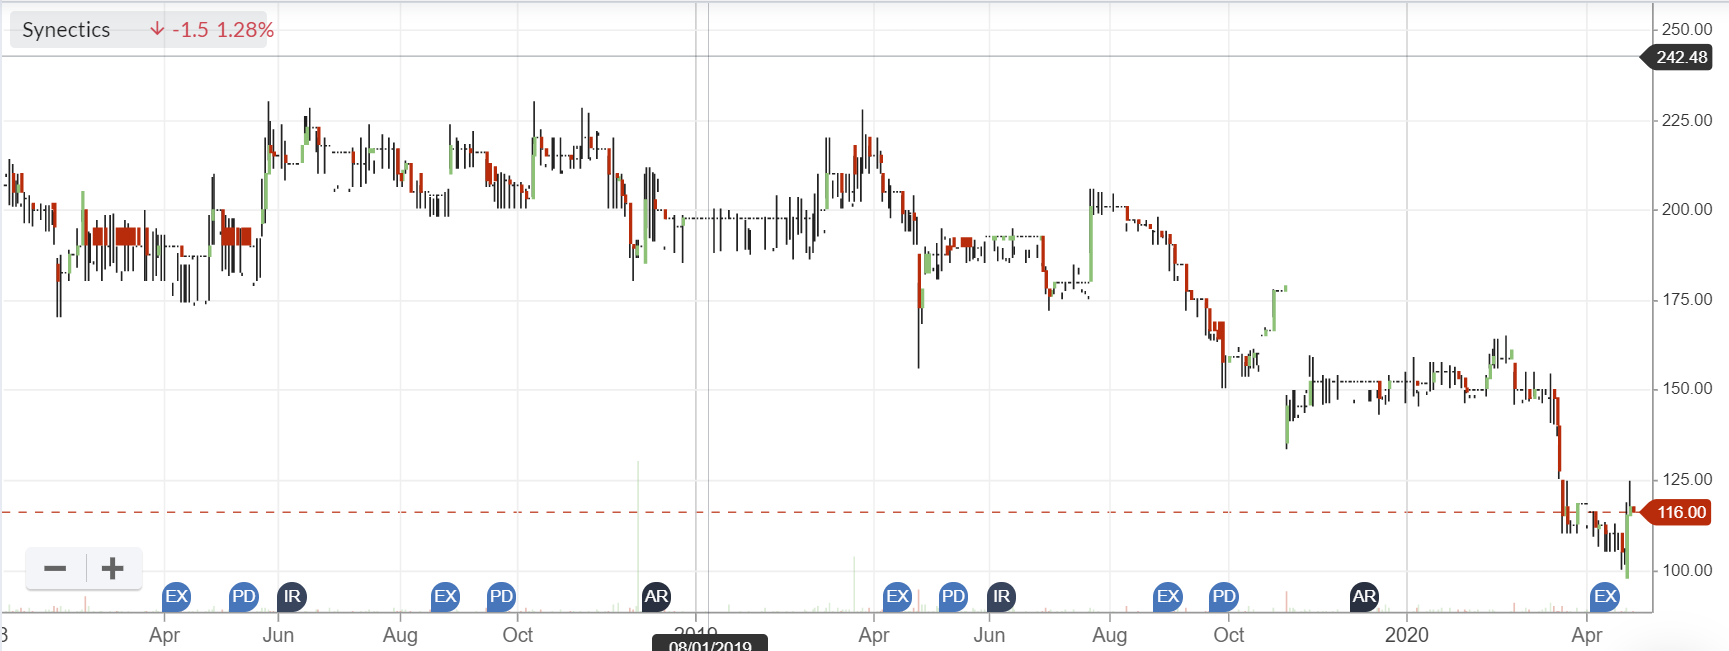
Share price: 116p
No. shares: 16.9m
Market cap: £19.6m
Synectics plc (AIM: SNX), a leader in the design, integration and support of advanced security and surveillance systems, provides the following update ahead of its Annual General Meeting ("AGM")...
This company has an unusual 30 Nov 2020 year end date.
I've not looked at this company for a while, but must have liked it last year (BC) as it's still on my watchlist.
Latest update - it's monitoring & reacting to the situation.
Liquidity - this sounds reassuring. As it was already on my watchlist, then the balance sheet must have been OK last year;
The Company has a solid cash position and measures in place to ensure that it remains financially sound during this period of uncertainty and beyond. The Group's available consolidated net cash balance was £3.3 million as of 20 April 2020, with confirmed facilities of £5.0 million in place if required.
Actions taken - looking very similar to what we're hearing from so many companies;
- Furloughed 30% of staff, and applied for similar Govt schemes overseas. Others working from home
- Director & senior mgt - temporary pay cuts - why no mention of the percentage, a glaring omission?
- Conserving cash by cost & capex cuts, and cancelling divi
- Guidance remains suspended for this year (was withdrawn on 23 Mar 2020)
Operations - not good, but not surprising either. It's not quantified, but this sounds like it's going to be a big impact on profitability this year;
All the Company's business units are currently operating, but at significantly reduced levels of activity in every sector and geography. Reasonable levels of design and planning work are continuing for projects now expected to proceed later in the year than originally anticipated.
My opinion - it's impossible to value at the moment. The point is that losses this year could blow a big hole in the balance sheet. When last reported, as at 30 Nov 2019, it had about £19m in NTAV. However, if you look at last year's P&L, it made £23.3m gross profit, less £20.7m operating expenses, for an operating profit of £2.6m - that was on revenues of £68.5m.
So, if revenues drop by, say half this year (remember its products are capex for its customers, and so many companies are slashing capex), then gross profit could drop to say £10,0m (more than half, as customers would no doubt try to negotiate discounts to proceed with purchases in the pipeline).
On fixed operating expenses of £20.7m, that would turn into an operating loss of -£10.7m, compared with a £2.6m profit in 2019. If my estimates there are right, then the company would no longer have a strong balance sheet. The cash would be gone, and it would probably be using most of its bank facility. It would then need a decent upturn in 2021 to keep going. Bank covenants could be breached (I haven't checked) at that level of losses.
In practice, the company would be forced to drastically cut its £20.7m operating expenses, to reduce the losses. If those costs were cut by say a quarter, then we'd still be looking at an operating loss inn 2020 of about £5m.
Since I have absolutely no idea what the 2020 figures would look like, then how could I even consider buying the shares? I think investors who assume everything gets back to normal in 2021 might be overlooking the balance sheet damage caused by one diabolical year in 2020.
Hence risk:reward has changed a lot, for the worse. I don't think I would want to invest in anything that sells products which are capex to the buyer. I got caught out by that mistake in 2008, and it was a disaster. Overall then, SNX looks too uncertain, and is becoming much higher risk than it was in 2019. Time will tell how bad 2020 turns out to be, but I don't feel the current price has adequately factored in the risk.
Obviously, at this stage we have to completely ignore valuation metrics such as forward PER and divi yield, because broker forecasts are pie in the sky for now, mostly. Reality is likely to be far worse than current estimates, in my experience.
We can afford to be very picky at the moment, and only buy the best risk:reward situations. Hence anything uncertain is just best ignored, in my view. We can always buy at some point in the future, when the facts are clearer. Why take the risk now? There are no prizes for being loyal to a share.
.
.
System1 (LON:SYS1)
Share price: 97p
No. shares: 12.6m
Market cap: £12.2m
System1 Group, the international online market research agency, is today providing the following Trading Update for its financial year to the end of March 2020, together with updates on the impact so far of the Covid-19 pandemic and related matters.
This is another share that was on my watch list last year, as showing possible signs of something interesting happening, but that's likely to have been clobbered by Covid-19 & its economic effects. Marketing-type spend is an obvious thing to cut, as it's discretionary spending for SYS1's customers.
Anyway, let's have a look at what it says today, which is likely to be on a scale starting at bad, and ending at awful.
Actually before we do that, do have a look at my notes in the SCVR for 6 Feb 2020. It was clear at that stage, things were going wrong - poor trading, and loss of staff. That's BC (before covid-19) remember. Also the company annoyed me by apparently trying to gloss over the extent of its profit warning, with an update that left us to do the maths to work out it was likely to be running at around breakeven.
Today's update seems somewhat better than that, saying;
The modestly reduced sales for the full year, together with a 1% increase in overhead expenditure, is expected to result in a 2019/20 Profit Before Tax figure (excluding AdRatings and share-based payments) of approximately £2.9m, compared with £3.6m in the prior year. Whilst we acknowledge this was a disappointing result, it does exceed our previous expectations.
AdRatings is its startup, loss-making business.
Investment in AdRatings continued during the year, with expenditure of £1.8m recognised in the income statement, compared with £2.2m in 2018/19.
What that means, is the £2.9m PBT figure mentioned in the previous paragraph above, needs to be reduced to £1.1m to arrive at the total group profit for FY 03/2020. Moreover, the phrase "recognised in the income statement" rings alarm bells with me, in that it could mean more of AdRatings costs might have been capitalised onto the balance sheet, in order to massage profit upwards? Given that we've established in the past that this company's investor communications can be misleading at times, then I wouldn't put it past them to pull another trick this time.
AdRatings revenues are de minimis. Given the current crisis, this raises the question of whether AdRatings is worth pursuing at this time, given that its operations are consuming about two thirds of the profits (maybe more, in cashflow terms?) of the rest of the group? Maybe it should be shelved, given radically worse macro conditions? -
...an impairment charge of £0.9m has been taken in relation to AdRatings development costs in light of the continuing modest AdRatings revenues in the year (£0.05m).
[Paul: that's £50k annual revenues. For a £1.8m loss]
ITV - a glimmer of hope here, or just a shrewd client recognising that SYS1 is prepared to provide a service at way below cost price?
On the strength of the industry attention received by AdRatings, we have announced a strategic commercial partnership with ITV, the UK's largest seller of advertising space, to support its customers in creating ever more innovative and effective advertising. We expect to enjoy revenues from these arrangements although it is hard to quantify this while the Covid-19 pandemic continues.
It just feels the wrong time to be doing this. I imagine management must be agonising over this issue, and it's very unlucky timing. To be fair, it's easy for me to criticise, perched on a piano stool (to avoid slouching), in front of a computer screen/keyboard, but many highly successful businesses would never have got off the ground, unless entrepreneurs were prepared to take risks, and burn shareholders' cash in the startup stage.
Covid-19 update - unsurprisingly perhaps, this falls into the bad, but we're not telling you how bad category, which I find unacceptable at this stage. There again, SYS1 has repeatedly said in the past, that it has limited visibility, even in good times. So it probably doesn't know how things are likely to pan out;
Since the end of the 2019/20 financial year, System1's trading has inevitably been adversely affected by the global economic situation. The Board has concluded that it is difficult at this stage to provide guidance on the financial performance for the current year until a clearer outlook emerges. The Board will keep investors updated as the impact on the Group's performance becomes clearer.
I would have liked some scenario analysis, combined with what actions could be taken to handle each scenario. But maybe that's too dangerous to put into the public domain? After all, for a people business, mooting the idea of sacking staff, wouldn't go down too well (although people tend to work that out for themselves).
Actually, to be fair, they do say this;
...we are monitoring the trends in forward sales, evaluating a variety of plausible revenue scenarios, and taking decisions on our cost base when agreed trigger points are reached.
Mitigating actions to date include deferring employment costs, reducing the number of hours paid for where the volume of work has fallen, and taking advantage of government-backed business support and furloughing schemes in the countries where we operate. The Board and other senior executives of System1 have agreed to defer 20% of their salaries until further notice.
It's difficult to criticise that, as it sounds like common sense stuff, and must be very hard to manage, making potentially tough decisions. As investors it's probably not something we take into account enough, but at times like this, management of any organisation under pressure (be it private or public sector), it must be incredibly tough on a personal level for everyone involved. I certainly wouldn't want to be taking life or death decisions in Govt or civil service, nor having to agonise over which employees to furlough or make redundant within any business. Still, that's what the big salaries are for.
Liquidity - again, sensible actions taken, to give what looks like some headroom;
Given the emphasis on retaining cash in the current circumstances, the Board has decided to suspend both the proposed buyback programme of up to £1.5m of System1 shares as well as the payment of a final dividend for the 2019/20 financial year. Future returns of capital will be kept under review as the economic situation develops.
In addition, the Company arranged and drew down a £2.5m revolving credit facility in March 2020, ending the year with a gross cash balance of £6.6m (2019: £4.3m) and debt of £2.5m.
That all looks pretty smart to me. Survival first, then worry about recovery later.
Outlook - this offers some hope maybe;
At this difficult time we are working as closely as possible with our clients, sharing the latest insights on how Covid-19 has impacted consumer feelings and behaviour around the world and strengthening our relationships with them. We believe this will stand us in good stead and benefit our business when conditions improve.
Maybe, but how many clients are really going to have spare cash to do this? Maybe some big consumer brands?
My opinion - everything has a price, and with this market cap down to only £12m, combined with what looks like adequate liquidity for now, and a cost base that's flexible (people), I'm quite tempted to have a punt-sized dabble here. Potential upside could come from a future decision to put AdRatings on hold, for reduced cash burn, for a temporary period?
This type of business could maybe survive a severe downturn, by slashing its mainly variable costs (people). Maybe we should take a fresh look at people businesses for this reason. In the past, the issue has been that the talent walks out of the door every day and can get paid more elsewhere. Right now, I think the talent is probably working from home, and grateful to still have a job.
Incidentally, what's to stop employers furloughing staff, i.e. getting the Govt to pay 80% of salary up to £2,500 per month, with a quiet agreement on the side that the employee continues working from home, off the radar, and is rewarded in future? Surely that's better than twiddling thumbs and doing nothing of economic value whilst furloughed?
In terms of its investor communications, this needs a complete overhaul at SYS1. The commentary is often disarmingly honest - e.g. telling us repeatedly that it has no real visibility on revenues & hence profits. Yet in other places, it seems to create a maze of distractions & minor deceptions, to obscure bad news. Memo to John Kearon, CEO - Honesty is the best policy. Get rid of any advisers who encourage you to deceive investors - it destroys trust - e.g. publishing % changes in some metrics, in order to conceal the overall picture (a plunge in profits).
Overall - I'll put my paperwork on SYS1 into my "looks potentially interesting, unlikely to go bust, but risky" tray. Let's see how things pan out in 2020.
.
Iqe (LON:IQE)
Share price: 39.4p (up 1% today)
No. shares: 796.5m
Market cap: £313.8m
IQE plc (AIM: IQE) the leading supplier of advanced wafer products and material solutions to the semiconductor industry, announces its full year results for the year ended 31 December 2019...
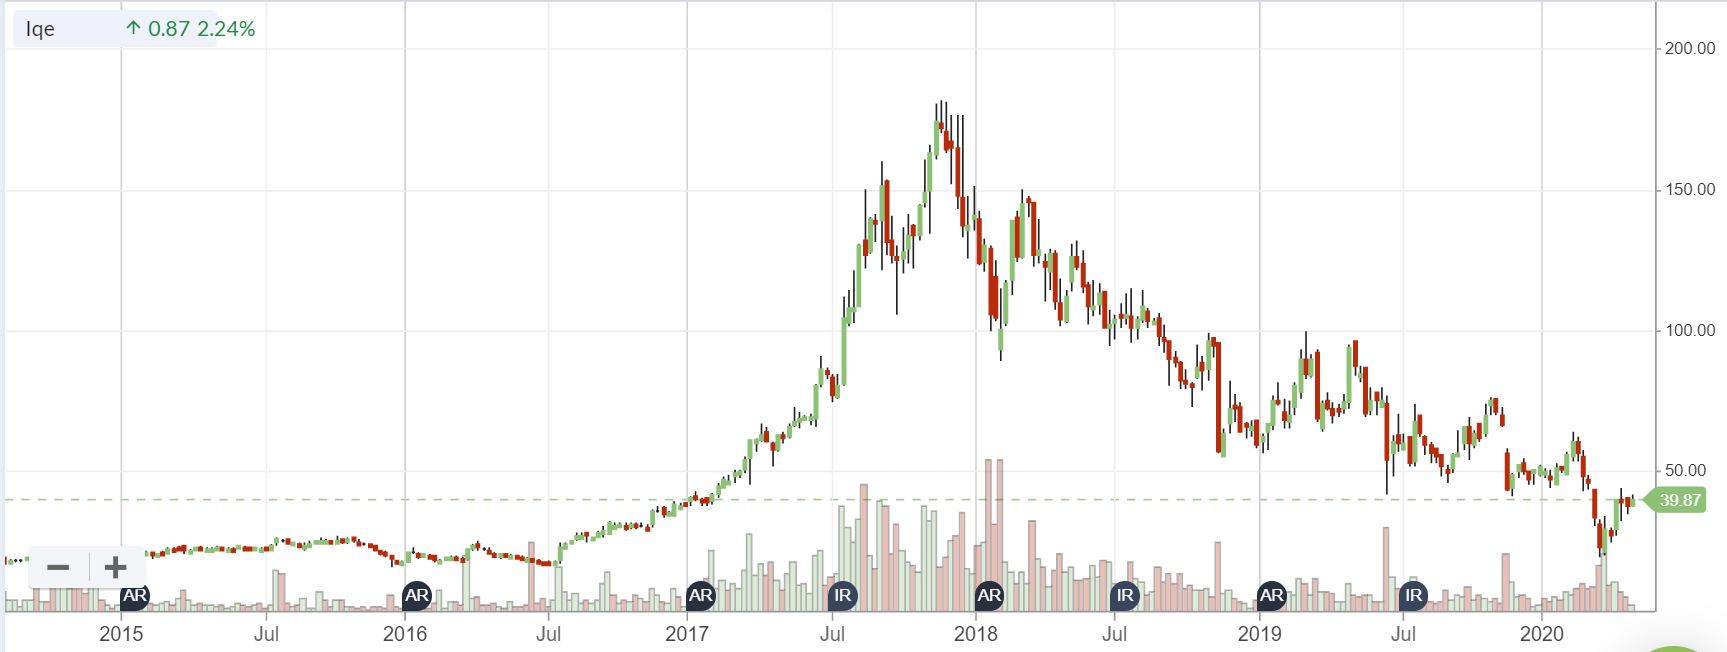
This was a wonder stock a few years ago, popular amongst private investors. As you can see from the 5-year chart below, it multi-bagged, but has since come most of the way back down again, as the company failed to deliver on all the hype. That often seems to happen with fashionable shares!
.
.
The company says that its 2019 numbers are in line with the figures previously given in its trading update on 24 Mar 2020. I'll take that as read, rather than checking, as I don't intend spending long on this share.
Revenue down 10.4% to £140.0m
Adjusted operating profit down from £16.0m in 2018, to a loss of -£4.7m in 2019
Heavy capex again, of £31.9m - the big problem with this company is that it's capex hungry, but is not generating a decent return from that investment
Outlook comments seem quite good -
“Looking at this year, I am pleased to report that Q1 2020 trading was slightly higher than our internal expectations and the outlook for Q2 remains positive at this time. IQE remains well positioned to withstand the near-term uncertainty, and we are confident our technology will be a critical part of the world’s technologically driven future.”
Liquidity - this reassures -
"Increase to credit facilities to support navigation of challenging market conditions:
- £30m asset financing facility put in place, increasing total available facilities to ~£57m (£25m drawn down at 31st December 2019)
- Formal agreement in place to relax debt covenants in December 2020 and June 2021, as a precaution, to ensure continued access to debt facilities in severe downside scenarios"
Cashflow statement - is revealing. This shows that the company has been spending far more on capex in the last 2 years, than it has generated in cashflow. Even if capex now reduces, that suggests to me that it's really not a very good business.
My opinion - this company has disappointed over several years. The pattern is that it promises wonderful things from new products in the pipeline, but then nothing much happens with those either.
Overall then, I am deeply sceptical about this share. Why is it valued at £313m, given poor performance in recent years?
There's not much of interest in small caps, so here are a couple of noteworthy announcements which caught my eye from larger companies;
Plus500 (LON:PLUS)
A cracking update from this controversial CFD/Spread Bet company.
Everything seems to be going well, leading to another upgrade to expectations;
...the full year is expected to be substantially ahead of current consensus expectations, as revised following the Q1 trading update on 7 April.
Spread Bet/CFD companies thrive in times of market volatility. Memo to self - when markets go haywire, buy this sector. Ig Group (LON:IGG) and £CMD have also issued positive updates recently. PLUS is the riskiest out of these, as it has run into multiple regulatory, accounting, and ethical problems in the past. That said, these concerns are reflected in the valuation multiple, which looks cheap.
Personally, I think the boat has set sail in share price terms, so I'm not interested in chasing it up any further. Of course, as volatility subsides, then customer activity is likely to reduce back down to more normal levels.
This sector has been great of late, something to remember for the future.
Marks And Spencer (LON:MKS)
(I'm long)
There's a reassuring update out today.
- Banking covenants have been relaxed through to Sept 2021.
- Confirmed as able to borrow under Govt CCFF scheme - providing extra liquidity if needed.
- Has enough liquidity for next 18 months - removing any concerns about solvency. Last man standing in its sector, so should gain market share once it can re-open, in my view.
- Given a daft name to its restructuring: "Never the same again". Give me strength.
- No divis for 2020/21 - saving cash of £210m
- Food delivery via Ocado on track to start in Sept 2020. This is quite exciting in my view, and the main reason I want to hold this share.
My opinion - it's definitely going to survive, and I could see possibly 100% upside from the current level of 97p. However, figures are probably going to look dire in 2020, but everyone knows that - it's in the price already.
All done, thanks for reading & commenting.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

70 comments
Burford Capital (LON:BUR)
Hi Bruce,
You need to learn to not take everything you read or are told at face value. If you believe that Jim Kilman is the real CFO of Burford and it makes you happy, that's fine with me.
Bonitabeach
But if you state:
"Elizabeth O'Connell is still the CFO of Burford"
that is a fact that is demonstrably false. https://www.burfordcapital.com...
If you then state "oh you shouldn't take that at face value, I didn't mean she was the CFO, what I really meant was she is the 'real CFO' "
it does rather undermine the rest of your arguments.
Brilliant article, very much enjoyed the read. Thanks Paul
Marks And Spencer (LON:MKS) is of interest - last man standing IMO. Furthermore, grandparents in lockdown could mean more of the offspring have to run errands to good old M&S, and maybe get a pleasant surprise.
I agree 2020 is a write off now but the debt is ok .... with a decent tailwind MKS should make at least 3x todays profits announced from Games Workshop (LON:GAW) yet they trade on the same market value, give or take. Surely that aint right?
Venture Life (LON:VLG)
I've actually been looking at this company over the previous weeks and delved a little further after yesterday's announcement.
My conclusion was that it was perhaps not as impressive as it might initially seem.
Building in:
Gives me FY20 revenue of £28.6m vs £26.3m Stockopedia forecast.
It's a nice "beat" no doubt, but this forecast looks a little outdated, at least for FY20 as most of these figures would/should be known.
Also note the materially lower operating profit margins for Venture Life, where Dentyl currently is accounted for.
Where I could be materially wrong is if FY20 Dentyl China revenue is greater than £7.8m/9m EUR already expected.
FY20 aside, the other thing that stood out for me was the the the €168m over the 15 year term is not in fact guaranteed.
"The Directors believe that this minimum value commitment, which the partner is required to purchase in order to retain the exclusive distribution rights, demonstrates our partner's long term intention and support for these important brands."
So if the partner decides they no longer want to sell Dentyl they simply stop ordering from £VLG.
No doubt I'm probably missing a trick here and it's a screaming bargain, but I'll sadly wait on the sidelines for this one.
GLAH
A
Hi Abtan, thanks for picking up the Venture Life (LON:VLG) discussion. You make some interesting points, particularly the observation that c.£7.8m of Chinese sales to this partner is already baked in to the 2020 forecasts.
However, I think there are additional points that you could take into account.
I don't necessarily see Venture Life (LON:VLG) as a screaming bargain either, but I do see a great deal of what I consider to be underpriced potential, hence my enthusiasm for it.
Venture Life (LON:VLG)
Hi Effortless Cool
Thanks for continuing the discussion.
You make some good points. Some counterpoints if I may:
Thanks again and best of luck.
Cheers
A
Paul, I wouldn’t hold out too much hope in Ocado delivering much for £MKS. From my own anecdotal experience in trying to get groceries delivered for my elderly mother, a more useless delivery / fulfillment company you are unlikely to encounter...
Non-existent slots and not taking on new customers - who would have thought it, from a company who specializes in this?! Utter shambles.
They probably didn't build a pandemic into their business model. Much like everybody else.
Whereas someone like Tesco did? They’ve been much more resilient and have had slot availability...
Sorry, if fulfillment is your business and you can’t do it , you’ve no business being in business, pandemic or not.
i think this might depend where you are based - Tesco/Sainsbury's dont (didnt a few weeks back) have slots available at all for a month whereas Ocado did
Another fabulous markets/coronavirus update today Paul (ditto the Company updates as usual). Thanks.
My main market concern (and it’s a big worry on health grounds too) is the high chance of Covid-19 returning in much more virulent form. Have Governments made a big mistake in throwing the kitchen sink at this first outbreak? And what weapons, if any, will they have left to tackle it? So as Paul says, unless a vaccine or another solution by then, the outlook on health and investment grounds looks worrying. So maybe another big sell off triggered as soon as Covid returns?
Another big concern hardly getting a mention at present is very fast rising inflation. Pubs, restaurants, airlines etc etc will have to put prices up if far fewer customers because of social distancing. Can interest rates be kept low if inflation takes off? And interest rate rises along with much higher mortgage payments would not be good for economies. And this sort of worry along with high unemployment just leads to one further negative after another.
Yet markets continue to soar. It seems illogical....or could it be that markets have spotted the inflation risk? And are equities a good place to be when inflation is high?
Yet markets continue to soar. It seems illogical....or could it be that markets have spotted the inflation risk? And are equities a good place to be when inflation is high?
Hi Ken
You want to be in capital light companies. If you have to buy equipment to maintain or grow the business then the company is exposed to inflationary costs which negates the inflationary profits. Same is true of businesses that need a lot of manpower, as wages will tend to grow as well.
Businesses that can mainly operate online tend to fall into that category, so they should firstly survive and should then be relatively inflation proof. That's my theory anyway.
A lot of the stocks that are going up a lot are those that went down a hell of a lot. As the panic fades it should start to become possible to differentiate between those businesses that may not survive, those that will survive but may face reduced demand and those that will recover to former highs.
The tricky bit is in the middle - for instance, I'm seeing increasing suggestions that companies that can work from home are actually seeing improved performance and better communications. If that follows through then commercial property looks like a risky place to be. If commuting falls due to more home working then patterns of consumption also change - so less takeaway coffee, less drinking and eating near work, more home delivery and consumption of digital content at home. Etc, etc.
Vaccine - probably 18 months away, so best hope are that some existing drugs alleviate the worst of the symptoms and make it survivable for most people. If we can staff them then the Nightingale hospitals probably give us surge protection for a combination of flu and coronavirus next winter. My worst case guess is social distancing until end Q1 next year, which will be a disaster for restaurants and bars plus high footfall stores.
I'd say this was fascinating from an investment perspective were it not that 40,000 of our fellow citizens have died with more to come. Grim.
timarr
Hi timarr
Thanks for replying. I agree with nearly all of it but am more optimistic on a vaccine available sooner than you fear or one or more of alternative solutions (some remarkably simple) working well and becoming widely available.
One sector you don’t mention is oil (which is not covered here). Share price falls were remarkable. e.g Shell fell to £9, which was £4 below previous 20 year low,! And some smaller cash rich producers are down 90%. Short term the World is awash with oil and with nowhere left to put it. But sector is certain to recover in time as there will be demand for oil for many more years.
It might take a while, but I can see a scenario once coronavirus is history, and quite likely even before it is,as markets look ahead, where when demand returns to normal, the lack of production now, along with Saudi Arabia and other oil Countries needing a much higher oil price leading to a much higher oil price if they agree production cuts. . Then the likes of Shell and BP could easily double from current prices Shell now back to £13) and some of the smaller fry could well multibag. Indeed a higher oil price could be another trigger for fast rising inflation.
Hi Ken
I agree with nearly all of it but am more optimistic on a vaccine available sooner than you fear or one or more of alternative solutions (some remarkably simple) working well and becoming widely available.
I try to look where the actual evidence points rather than relying on what I hope for (which, roughly, is that this will end tomorrow). Sadly all authoritative sources I can find say that a vaccine in 18 months would be remarkable. There's no way a vaccine will be rolled out without proper trials, it's too risky. Two years would be a triumph.
Drug treatments are more likely - there are over 150 trials going on. However, those need to go through clinical trials too. Roughly you're looking at end of calendar year earliest. Most drugs have side effects that only become apparent over time - remember thalidomide. We don't want the cure to be worse than the disease. Say end of Q1 next year as a reasonable target, anything sooner would be a bonus.
I agree that the major oil companies are a fair bet going forward. However, it's not a sector I'm particularly interested in, it's going to face a lot of headwinds in terms of sustainability. And you also need to think about the US response to its shale producers collapsing - do they really want to end up dependent on Russia and Opec again? We could be awash with cheap oil for a while. But there's value there.
Personally I want to invest in capital light businesses that generate high operating margins and which are at no risk of going bust. I work in financial technology so unsurprisingly I'm attracted to technology and financial businesses which often meet those criteria. I'm spending a lot of time researching the healthcare sector too, for obvious reasons.
International Consolidated Airlines Sa (LON:IAG) has just announced it's making 12,000 staff redundant. None of them have a hope in hell of finding another job in the foreseeable future. The next two quarters are going to be difficult, we all need to have a plan to deal with that.
timarr
Hi Tim
I am amazed on a daily basis by the soaring stockmarket on a background of forthcoming economic Armageddon for significant sections of the economy and the future tax burden we will all have to pay.
Drug treatments are unlikely to be effective in the near to medium term as the virus will evolve due to hostile pressures ie treatment . The best that can be hoped for is treatment that will help survival to some extent in those most seriously affected.
A vaccine holds more hope but is likely to provide partial temporary protection - remember also the large numbers of narcolepsy cases after the swine flu vaccine . Again the virus will evolve to avoid the protective effect of the vaccine and thus the vaccine will have to be adjusted each year.
What I see is a rise in the indices as lockdown ends and the population feel its over then a fall with a second minor spike and then a big drop with the inevitable winter surge in cases. By March 2021 we will be over the worst of it and live with covid as just one of the many pathogens that circulate through our population.
Hi timarr -
There is a lot in your post that makes sense.
My investment approach is split into two pots. The first has companies that present immediate opportunities that will not last for long. The second has stocks which are the likely winners in the medium to long term.
In the first group, the pharma, biotech and health care sectors have presented a number of excellent opportunities. I ran a program to identify the top risers since 2/1/2020 and in the top slots I found these kinds of stocks, most of them having multibagged. I think their runaway share price growth is running out of steam and the best opportunities are probably behind us.
The second group is more challenging, to say the least. My focus is on:
- asset light businesses
- platform businesses with network effects
- sectors : software and computer services, pharma, biotech and healthcare, consumer durables
But nothing is set in stone. I think it will be some time before we can peer through the fog and catch a glimpse of the new world order.
For me the main clue to how this market develops will be provided by the banks.
In 1929 the Dow fell 48% in 2 months, then rose 48% over the next 4 months. This year, the Dow fell 38% in 1 month and has so far risen 33% from that low, with other markets following similar patterns.
From 1930-32 there then followed a series of banking crises until the markets bottomed for a total loss of 89%. Thousands of banks were allowed to go bust and there was no deposit protection in place.
It won't get as bad as that this time around, because we now have larger banks which will be backed by the government, and in the UK for example you have the £85k FSCS deposit protection in place per banking licence.
However, banks on both sides of the atlantic are currently making bad debt provisions in the $billions, and it will still take several months for loan defaults to work through the system. We're still only one month in, since the lockdown began.
2007-09 was also a banking crisis, the bear market was 18 months long and produced a total drawdown of -58%. It then led to years of austerity.
Looking at the charts, Lloyds Banking (LON:LLOY), Hsbc Holdings (LON:HSBA) and Barclays (LON:BARC) are all pretty much stuck at their lows for the year, and not far off their lows from 2009. This isn't exactly a positive indicator.
I bought Plus500 (LON:PLUS) at 900p-ish as I thought they would rally on the market volatility but sold above 1200p as the CEO left, never a good sign to me.
Yesterday was a boom day for small and micro caps and today is looking just as good with dozens of stocks moving up ten per cent and much more. Many miners are soaring with tiny gold stocks in demand. Some health stocks are up hundreds of per cent since the beginning of the month. DDDD and HEMO for instance. Will it last as Ftse approaches 6000 and the Dow.....that seems to go up almost daily even as unemployment soars and Covid cases exceed three million (and the rest I hear you say)? I don't really understand it myself and the markets seem to be ignoring most of the risk it seems to me but this seems to be an exciting time for equities without a cloud in the sky and the sun shining away. I cannot see that lasting and perhaps people smarter than me can explain.....but it might last for a good while yet so I am fully invested albeit not averse to cashing in after some of these monster rallies on individual stocks.
Judges Scientific (LON:JDG) analyst presentation FY19 results, given on 18.3.20 here. Although rather belatedly published, it coincides with the AGM announcement today, that invites questions, which will be answered in a video, since attendees are not invited, because of lockdown. So a useful prompt for that.
CV19 investor communication: Don't waste the opportunity to give your feedback on company CV19 updates. Alma PR are running this anonymous suvery, (no data collection, not commercial). This is to help the PRs to give us investors the information we want. It will take a minute. Please complete it here.
Finally, do join the piworld Thursday webinar, 30th March, 1pm. When we're delighted to host David Buik for his Macro Market Commentary. David will share his experience and knowledge of bear markets, he'll consider the CV19 effects on the economy, Government fiscal and monetary intervention, and what that means for the economic future, and for investors. As always, you will be able to ask David your questions. David is a seasoned commentator for BBC, Bloomberg, Sky, etc, and has a wealth of insight to share. It should be a fabulous session. Register via the link here.
Tamzin - just a word of thanks for extending (I think) your webinars into podcast format. Perfect for my newish anti-lockdown daily walk.
Hey Paul.
No disrespect to your colleagues on Stockopedia but ‘ You Is The Man ‘.
Your daily analysis is brilliant, simply brilliant.
Very kind, thank you Tony :-)
Paul...You deserve it and everyone here should give you the credit you deserve, in light of what you, John and I think Muriel all suffered.
You give a totally different insight into the world of investing, and I do not care if your view is right or wrong, it’s a view that gives me insight and that in itself is a priceless commodity, for readers here to absorb.
Thank you
Yes indeed , my thanks for the time and trouble you take , Paul.
Terrific analysis, Paul. I wish I could learn from my mistakes so clearly!
I know its not one that Paul will comment on, but I understand a few of us own Sylvania Platinum (LON:SLP) and I see no harm in discussing in amongst ourselves.
The 3rd quarter results are out and to me seem fairly positive.
It appears to be a well run company with plenty of cash in the bank. Big jump in the share price yesterday, not much movement on these results today.
Any other Sylvania Platinum (LON:SLP) holders have a view on its outlook.
My only concern Bob is "provided operations are able to resume as planned". There is such a question of doubt about so much at the moment why risk it.
An FT article this morning reported low death rates for COVID in Africa, suggesting it might be spared the worst effects. The other concern is the ZAR devaluation.
Africa is a weird one ! How can so much poverty etc lead to so few cases , great if it lasts !
Indeed it is. I am living in Cape Town and we are all amazed how low the numbers here after over 4 weeks of total lockdown . After all it’s impossible to have an effective social distancing in the townships which have up to a million people !! Many of these disadvantaged have HIV,TB or diabetes. .
I added to my Sylvannia holding this morning first thing. Easy to get them despite expectations that MM would read the price a lot higher at open after such good results. Stockrank is 98, p/e low and plenty of cash. I am hoping some institutional money might start to find its way in to support the share price.
On Feb 24th, Premier Miton bought 5% of the company at a price around 57p, so hopefully at least one expert investor has faith.
I found the company using the slater screen, tweaked slightly and added some extra criteria using stockranks. Only two companies meet that criteria still, SLP and Polymetal (too russian owned for my liking).
The price does seem to surge ahead in spurts, and looks like the market mid morning has taken a shine to it - fingers crossed.
Surprised not more mention of Venture Life (LON:VLG) after what looked to me like stunning contract news yesterday. Looks like a classic STOCKO stock imo.
I agree on Venture Life (LON:VLG). The deal announced yesterday was for a minimum of EUR168m revenue from a Chinese partner over 15 years. That is about £10m per annum, compared to total revenue of £20.2m in 2019. According to the finnCap note, they can satisfy this increased demand through existing production facilities.
Venture Life (LON:VLG) was already looking interesting, given that it seemed to have recently transitioned from being persistently loss-making to being consistently profitable. Now it stands to add massive benefit from the operational gearing effect from this additional revenue stream. They are also successfully continuing their buy-and build strategy, with another smallish acquisition completed in January, also with consequent benefits for operational gearing.
I missed the boat a little, having originally bought in early April, but yesterday's news prompted me to double up.
I don't recall ever having looked at Venture Life (LON:VLG) - probably because having the word "Life" in the name, I'd just assumed it was a biotech type of stock. It's impossible for one person to cover the entire small caps market! So sometimes things do slip through the net.
That wasn't intended as a complaint, Paul - I hadn't heard of it a month ago myself. Perhaps just bear Venture Life (LON:VLG) in mind in the future, however - always interested in your views.
Sure, I'll try to find a minute to circle back to Venture Life (LON:VLG) at some point :-)
Venture Life (LON:VLG) came out with a cracking RNS yesterday, very much small cap, very much under the radar.
Universe (LON:UNG) seem to have fallen more (+65%) from pre Covid level than would be justified by the TU this morning (on track + major new contract). The presentation at MELLO was very informative + impressive.
They have generated CASH during the year and net CASH is now 2.6m (1.0p a share). CASH profits (pre development expenditure) were 3.6m vs MC of 7m!!
They are a Gvt approved supplier to get critical retailers going (food+petrol), so trading during lockdown has seen some resilience but impacted by discretionary projects and lack of new sales. Still they indicate revenue for the year could be close to last year and then right at the end of the RNS talk of a significant new and recurring contract.
EPS for the current year are likely to be 0.4p (so a CASH adj P/E of 4times)
disc: I bgt post Mello and bgt further since
Paul
Therefore, by looking at just the benchmark index (Dow Jones, or S&P 500), we're not seeing the detail that perhaps makes more sense than the headline index figure alone?
The rally in U.S markets is very narrow. The big five tech stocks make up 20% of the S&P now.
Lookers (LON:LOOK)
Initial indications have identified some operating divisions where certain non-cash balance sheet accounts have not been fully reconciled, in accordance with Group policy. These items are expected to give rise to a one-off, non-cash charge, however this part of the investigation is still ongoing...
Call me old school when it comes to stuff like this but checking balance sheet items is the number 1 starting point for anyone doing anything to do with accounts ? - how can a CFO earning their top whack pay preside over a business that doesn't even do the basics right? is it any surprise with a lack of basic controls that employees have been on the fiddle. It's often a double whammy here where it suits bosses and employees for stated profits to be top max high every reporting period bonuses acheived all round - look how this ended up at Tesco. Forget reality close your eyes and just present some decent numbers no questions asked.
Note specifically with companies like Lookers they nearly all have potentially self destructing balance sheets to start with that are living on the edge - if we presume they are in control of what they report. If the numbers aren't materially correct that is truly poor.
Last 6 monthly net reported profit £18 mill
Look at the balance sheet numbers
inventories 990 mill
Receivables 302 mill
asset value of rental fleet vehicles 64 mill
Trade payables £1,340 mill !
strewth where does one start looking in those figures for minor 5-10% w/offs if the quoted reported numbrers havent all been "checked" and stated correctly.
I know the car companies have some decent tangible freehold proiperty (248 mill at last interims but if the reported numbers are anything other that 99% materially accurate (higher for debtors) it makes a ridiculous mockery of the previously reported wafer thin profits.
Hopefully for holders the end result here is a manageable transition to doing what should have been done all along ref these aco####ing basics.
Rmillaree - I think there's a simpler metric to identify that a minuscule margin of error can turn profit to loss and going concern to bankruptcy and that's the profit margin. At Lookers it's about 1%.
Just looking at that tells you that very little needs to go wrong for a nasty outcome.
Lookers (LON:LOOK)
that's the profit margin. At Lookers it's about 1%.
Just looking at that tells you that very little needs to go wrong for a nasty outcome.
I would agree 100% - that's the ridiculous thing here though - one would expect with such enormous numbers on the balance sheet they would not be asleep at the wheel as they can't afford to be - for them to be exactly that (asleep) with such enormous numbers involved is really a slap in the face to shareholders.
Burford Capital (LON:BUR):
1. Accounts signed off without qualifications or restatements by Ernst & Young. SP had been marked-down following the short attack and again when the accounts were delayed.
2. Positive first quarter update, continuing the trend reported in the 3 February RNS.
3. Bullish on COVID in creating litigation opportunities and potentially weakening access to capital for rivals.
Burford Capital (LON:BUR) Annual Accounts 2019 extend to 160 pages compared to 108 in 2018 and are extremely detailed and informative.
The detail proves beyond doubt in my mind that much of Muddy Waters allegations were completely false and cost many private investors including me very large sums of money.
The Accounts cover extensively the issue of cash generation.
The stand out number for me is that between January and late April this year 2020 Burford received $800 million showing what we all knew that revenue is extremely lumpy.
I shall be listening to their on line presentation at 2 pm today with great interest.
The big risk with Burford Capital (LON:BUR) is that the litigation they're financing may not produce any hard cash.
This is because as a lawyer I'm all too conscious that getting a court judgment is very different to getting paid. Enforcing a judgment is often 90% of the work.
There are inevitably going to be many cases where a company that was highly creditworthy at the time litigation was launched, say a year ago, is now a very different proposition. The CV19 crisis will mean that many good and well-run companies will suddenly find themselves insolvent, and you can’t get blood out of a stone.
I've no idea who the companies are that Burford Capital (LON:BUR) are involved with, and hopefully they will all survive to satisfy any judgment, but the one certainty is that this very substantial element of risk would never have been built into their original decision to finance the claim.
Burford Capital (LON:BUR) Clissoldkid I hear what you say but Burford reject 93 out of every 100 cases put to them and you can bet that getting paid is paramount in their process.
Just look at their track record over 10 years.
Burford Capital (LON:BUR)
Hi Clissoldkid
As a holder I too was concerned by the current situation and the ability of court payments to be made in the near future.
Burford's Annual Report published today states the following:
"The ultimate payor in much of Burford’s litigation is either (i) a government or a state-owned entity; (ii) an insurer; or (iii) a large company in an industry less likely to be rendered
insolvent by this economic disruption. For example, Burford does not have material cases against defendants in the travel and hospitality industries; we provide a breakdown of the
industries relevant to our litigation matters on page 46 of this annual report"
I haven't had time to read through the report today but I did immediately check out a few things, including mentions of Covid. The company has compiled a relatively thorough section on this risk if anyone wishes to check it out.
Cheers
A
Burford Capital (LON:BUR)
I do not understand the attraction of this company.
My perspective is that it has all the signs of a PONZI scheme. I do not say or know that it is a PONZI scheme but it quacks and waddles.
1-1-2013 to 31-12-2018
Operating Cash Flow - a negative £412.8M
Net Cash From Financing a positive £753.6M
1-1-2014 to 31-12-2018
Increase in "value" of "Long-Term Investments" £1,389.7M - of which £772.1M is accounted for by a "Fair Value Adjustment".
Increase in "Retained Earnings" £693.1M. (see "Fair Value Adjustment"!)
Update On Liquidity Strength And COVID-19 Impact - issued 2 April 2020.
Your dvidend is being utilised to maximise "future opprtunity" and hardly a convincing endorsement of liquidity strength.The chairman is 86 years old and the CEO's wife does all those fair value adjustments.
Muddy Waters indeed.
Bonitabeach
Burford Capital (LON:BUR)
Hi Bontiabeach
Just to pick you up on the last points:
1) The Chairman is 86 years old but I'm not sure what that is supposed to mean. Warren Buffet is nearly 90!
2) The CFO is Jim Kilman, who is not the "wife" of the CEO.
A
Burford Capital (LON:BUR)
Company Chairman: agreed, age of itself does not disqualify but he has been in post since 2009 and has been told he will be retired next year: not somebody with the energy or inclination to rock the boat.
CFO: Is actually called Elizabeth O'Connell, aka Mrs Bogart, aka "Chief Strategy Officer", as disclosed in the Muddy Waters short attack. When a company changes its CFO there is usually a perceptible recognition of a new set of hands on the wheel; Jim Kilman has had no such effect.
Investors in Burford Capital will believe: we all only invest where we believe. I don't know but I know I don't believe.
Bonitabeach
bonitabeach - your information is out of date. CFO was Elizabeth O'Connell, but now Jim Kilman as abtan correctly states.
If you can't get this basic fact correct, it suggests you ought to do more research before calling the stock a ponzi scheme.
Hi Paul,
Are you still long card factory? The share price has been hammered along with most other retailers but it makes most of its money November/December. Assuming things go back to normal it could emerge from the crisis relatively ok? Still highly profitable although the debt is too high.
No, I sold Card Factory (LON:CARD) for a nasty loss a while back (didn't hold for long), as part of a general portfolio clear-out back in Jan-Feb. My feeling is that the starting level of debt was OK for normal circumstances, but too high in the post Covid-19 world. Hence I see several years of balance sheet repair, de-gearing needed, before dividends likely to resume.
But if Card Factory (LON:CARD) can survive it might be OK. Look at Captain Tom - 65,000 birthday cards! People do still like to give cards and you can't really buy a single birthday card from Amazon. And retail rents are going to be much, much less for the foreseeable future,
Can you think of a worse location to spread the virus than a card shop?
What do shoppers do?
They pick up cards and put them down again. Touch their face as they laugh at the card. Pick up the next card.
#germfest
I can't help but feel this year the old adage sell in May and go away will work.
Not as good as the new adage - sell in Feb and stay in bed. Which I failed to heed!
Mark Minervini tweeted this earlier today:
The market has defied gravity and leading stocks are acting great. While a pullback is certain to come, the lockout rally has left many disbelievers on the sidelines missing out. Fortunately, I don't trade my opinion and added a bunch of names on the long side starting on Apr 6.
In an earlier tweet he mentioned that he is long with at least 10 stocks and all bar 1 are profitable.
DYOR.
Fortunately, I don't trade my opinion and added a bunch of names on the long side starting on Apr 6.
How anyone could continue to follow this guy after such a statement! "The market is definitely pulling back, but I'm going long! Don't do as I say, do as I do, unless of course what I did was wrong, then you should have done what I say."
How anyone could continue to follow this guy after such a statement! "The market is definitely pulling back, but I'm going long! Don't do as I say, do as I do, unless of course what I did was wrong, then you should have done what I say."
Yes. This is brilliant. A global pandemic, crappy weather, but at least humour is not dead! LMFAO. Si
James I could not agree more. I have never followed him (Minervini) and never done or not done what he says partly because I am not a trader, partly because I dont like his manner. I think there is a strong possibility it is all bluster.
I suggest to him, politely IMO, that he might not want to express how clever he was by going to cash on Feb 20th (assuming of course he did what he said) and rather show a bit of empathy with PI’s who had got clobbered. He blocked me!!
My advice would be to stay well clear of him, listen to what other more humble (Paul) people have to say and then DYOR.
Games Workshop (LON:GAW)
Interested in your take on this if you have time - realise its hardly small cap.
First TU I've come across that put actual figures on the effect of shut-down. Seems to be a 20% miss on down-graded forecasts if I'm reading correctly.
Phil
(No holding)
My morning smallcap tweet: SFO to do SFA re Rob Terry et al.
Distribution Finance Capital Holdings (LON:DFCH) EKF Diagnostics Holdings (LON:EKF) RTC (LON:RTC) Renalytix AI (LON:RENX) Universe (LON:UNG) Angle (LON:AGL) STM (LON:STM) Fusion Antibodies (LON:FAB) Watchstone (LON:WTG)
Distribution Finance (DFCH) loan book continues to perform well and remains stable but near-term demand likely to be curtailed whilst the majority of the Company's dealer networks and manufacturers remain closed. Believes its main lending sectors of caravans, recreational vehicles, small motorboats and motorbikes will perform strongly after lockdown lifts. Pulls guidance.
EKF Diagnostics (EKF) building a UK production line which could produce 12,500 sample collection tubes a day from id May.
RTC Group (RTC) general UK recruitment and smart-meter installation activities have been significantly impacted by the lockdown. Q1 has been largely unaffected. The majority of RTC's activities are in public and regulated sectors. Passing div.
Renalytix AI (RENX) preliminary steps in preparation for a potential spin-out of FractalDx, as mooted.
Universe Group (UNG) guides FY(Dec) in line with rev up 13% and adj EBITDA up 50%. Assuming that some non-critical work planned for customers in this financial year will be delayed and no sales to new retail customers expected. We take some comfort from the fact that our customers provide essential, daily required goods, that we entered this year with sound cash resources and that we have a material pipeline of recurring and on order revenues to execute."
Angle (AGL) Covid: "Guildford UK laboratories are now operating with a skeleton crew." Ovarian cancer test: may be able to generate clinical results mid year to assist in the negotiations with clinical laboratory partners. Pharma services cancer drug trials: "taking advantage of the increased accessibility of key executives during lock down, to establish dialogue with prospective customers and collaborators for the deployment of PDL1 analysis capabilities". Reminds us that co has sufficient cash for planned operations until mid-2021.
STM Group (STM) FY(Dec) U/L pretax £2.6m (£3.7m). Div 1.5p (2p). Operational Highlights include 'Redefined Purpose and Vision' and a new slogan for the Carey brand: 'Options, for your tomorrow'. BS merchants working 247 there. Co confident that its fixed recurring fees structure (rather than a % of Assets Under Administration) gives high visibility for the majority of our rev. Only £0.4m of 2019 £18m recurring revenue is at risk.
Fusion Antibodies (FAB) £3m placing at 90p, a 26% discount, was substantially oversubscribed. So it was too cheap then! 13% dilution. Cash to expand existing proof-of-concept work on Mammalian Antibody Library to include COVID, the existing oncology targets and for working capital. Co "well positioned to continue to trade with limited impact on its service provision."
Watchstone Group (WTG) SFO will not prosecute after investigating shenanigans under Rob Terry.
Hsbc Holdings (LON:HSBA) is very atypical of shares examined here, but it is perhaps interesting as it is today reporting a quarter that has been fundamentally impacted by the virus:
https://www.londonstockexchange.com/exchange/news/market-news/market-news-detail/HSBA/14518717.html
Profit down 48%
Revenue down 5%
Prospects have "substantially worsened in the last two months"
They are reviewing their "medium term financial targets"
This situation is much worse than I had expected.
And yet the Hang Seng rises 1%!!!
To be expected - on a more positive note, deposits and loans up.
Some estimates to have lost as much as $3bn when oil trader OK Lim was wiped out last week! bad lending = bad losses.
I have long worried about who they are ultimately relying on for loans to be repaid in the far east. Of course they are 100% independent of all political pressure out there.
- yeah right.
a great long term buy. I continue to acquire on weakness and believe the share price will at least be double in 3 years . Mind you,it has been a highly lucrative investment for me over the last 30 years,and I have no intention of selling now. Disclosure—-my son is a senior executive in the Bank :)