Small Cap Value Report (Tue 28 May 2024) - VIC, ING, GEN, BIG

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting Today
Quiet today, presumably lots of people on holiday this week. We've had to pad out the list a bit -
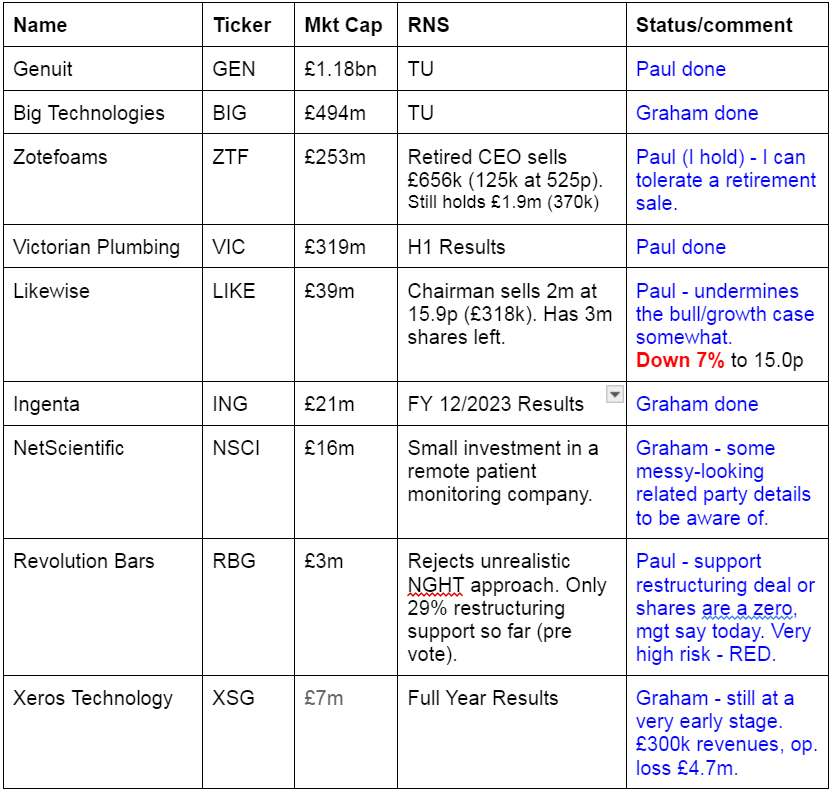
Summaries
Victorian Plumbing (LON:VIC) - down 3% to 94p (£309m) - Half Year Results - Paul - AMBER
Good H1 results, with adj PBT up 40%. However the full year outlook is only broadly in line, with some hesitant-sounding comments about current trading. I think this is a good business, but overall shares seem priced about right for now.
Ingenta (LON:ING) - up 4% to 152.5p (£22m) - Final Results - Graham - AMBER/GREEN
Decent results from this small software company/consultancy that serves the publishing industry. It stands out as a conservatively-run small-cap with cash on the balance sheet, no debt and a stream of dividends. Due to its lack of growth (historically and in the forecasts), I prefer AMBER/GREEN to GREEN.
Genuit (LON:GEN) - down 1% to 468p (£1.16bn) - Trading Update [in line] - Paul - AMBER
AGM update is only in line with expectations, and based on cost-cutting and margin improvements, offsetting revenue declines. Looks well set up for a cyclical recovery, but no longer a bargain after a c.50% rise from last autumn's lows. So I'm shifting down from amber/green to AMBER, to reflect the forecast PER having gone up from 12x to 18x.
Big Technologies (LON:BIG) - down 2% to 167p (£485m) - AGM Statement - Graham - AMBER
It’s an in-line update from this provider of electronic tags to the justice sector and fall alarms for the elderly. This share offers an enormous net cash position (£86m, Dec 2023) and healthy profitability. However, I do have one or two concerns, which includes a demanding valuation at this level.
Paul’s Section:
Victorian Plumbing (LON:VIC)
Down 3% to 94p (£309m) - Half Year Results - Paul - AMBER
Victorian Plumbing Group plc ("Victorian Plumbing", the "Group"), the UK's leading bathroom retailer(1), announces its half year results for the six months ended 31 March 2024 ("H1 2024").
(1) Mintel (2023) Bathrooms & Bathrooms Accessories UK.
The highlights table below for H1 looks good to me - with revenue slightly down, but a good improvement in gross margin from 46% to 50% (helped by own brand sales, and lower shipping costs) resulting in an impressive 40% rise in H1 adj PBT -
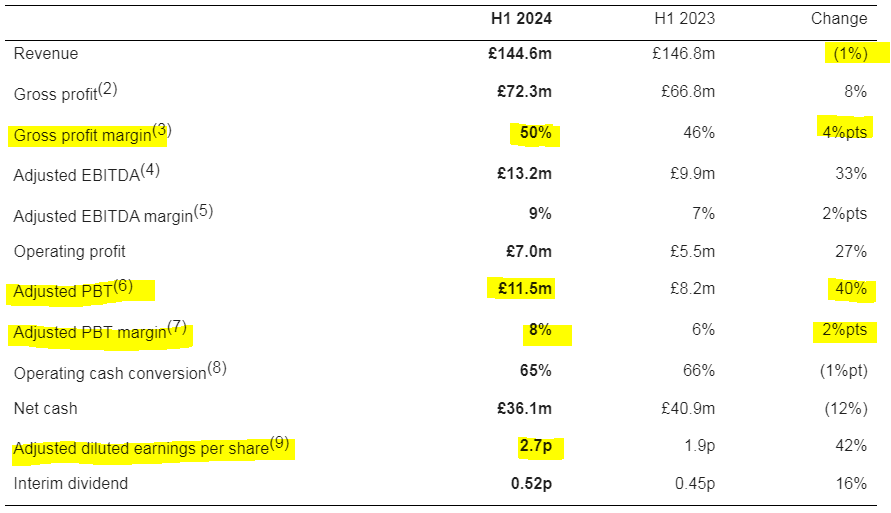
Marketing spend is still massive, at 29% of revenue. If only they could figure out a way of building customer loyalty, so they don’t need to spend so much to attract each customer order?
Outlook - sounds a little hesitant to me (below), so I can see why some punters might have decided to bank their recent profits this morning. I think a forward PER of 17.8x (per the StockReport) needs a more upbeat commentary than this -
Current trading and outlook
As customers continue to seek value, demand for 'big ticket' discretionary items is unchanged. The Group has continued to take market share organically; LFL revenue in April and the early part of May 2024 has been in line with H1 2024 trends, with order volume growth offset by lower AOVs.
The decline in AOV has shown early signs of levelling off, indicative of a slowdown in the shift by consumers to buy more of our own brand product range. Additionally, comparative shipping cost tailwinds have diminished over recent weeks, with both factors stabilising gross margin.
Looking forward, the Group will benefit from revenue growth as a result of further market share gains from the acquisition of Victoria Plum, albeit tempered by a continuation of recent trading trends in the market. While the ongoing Victoria Plum cost reduction programme is finalised, losses from the business will have a marginal impact on Group profitability in H2 2024, therefore adjusted EBITDA in FY 2024 is expected to be broadly in line with current consensus. The Acquisition is expected to be EPS accretive from FY 2025. Net cash (excluding IFRS 16) at the full year is expected to be in the range of £5m to £7m, reflecting the impact of the Acquisition and investment in the DC.
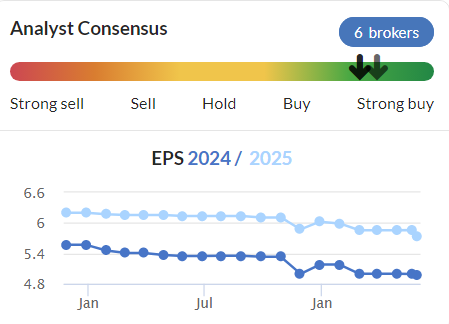
Broker forecasts - nothing available for us plebs! Given that the trend for consensus forecast (data we do have available to us, on the StockReport) is clearly downwards, and that today’s outlook is only broadly in line (slightly below), then I’d say the likelihood of the premium brokers slipping out a further small decrease in forecasts is probably >50%, but that’s just educated guesswork -
Balance sheet - note that fixed assets are rising fast (from a small base) which is due to building a new, large distribution centre, which it says will remove capacity constraints. Hence the “assets under construction” line in note 10 now has net book value of £15.5m. I wonder if this is freehold or leasehold? Maybe someone could ask, if they do a webinar? Ah I think I’ve answered my own question, as the lease entries on the balance sheet have shot up (RoU assets up from £4.1m a year ago to £48.5m at 31/3/2024), which suggests the new dist centre must be leasehold. Pity, but never mind.
The rest of the balance sheet looks fine, but bear in mind the £36m cash pile will be mainly gone by 9/2024 year end, since they spent £22.5m on buying Victoria Plum. If I make manual adjustments for that acquisition, the balance sheet will still look OK, although with the surplus cash moved up into intangible assets (goodwill) and increased stockholdings probably. No cause for alarm though, it should be fine.
Cashflow statement - looks OK, although note that it’s capitalising increased amounts of IT spend into intangible assets, £2.0m in H1. That’s c.22% of operating cashflow. The main cash outflow was £12.4m spent on physical capex, being the fit-out of the new dist centre, so let’s hope they generate a decent enough return from this capex to make it worthwhile. The size of the capex suggests to me it’s not just a shed with racking and forklifts in it, they must be spending on automated systems to hopefully make it more efficient. That would be an interesting area to hear management give us more colour. It’s on time, and on budget they say, to commence operations fairly soon. Sorry, I’ve just found the detail on it - so yes a 20-year leased site, and “semi-automated”.
Dividends are now only small, as the surplus cash has been spent on the big new distribution centre capex, and acquiring Victoria Plum. That’s fine, investors are looking for growth more than income at this type of share I think.
Paul’s opinion - I think this is a fundamentally good business. However the shares look priced up with events, hence I’m comfortable at AMBER for now. It’s almost amber/green though. After many years of attributing very high valuations to eCommerce businesses, that era now seems over, and they’re being valued like normal companies. Hence I think a forward PER of 17.8x looks about right for VIC. Why pay more? That said, once the economy is recovering more strongly, and they’ve bolted on Victoria Plum, maybe there’s upside on FY 9/2025 forecast numbers and beyond? I’ll keep an eye on it. A dip, maybe on a mild profit warning in future, could be a buying opportunity maybe, but I don’t see the current price as being attractive enough to tempt me in.
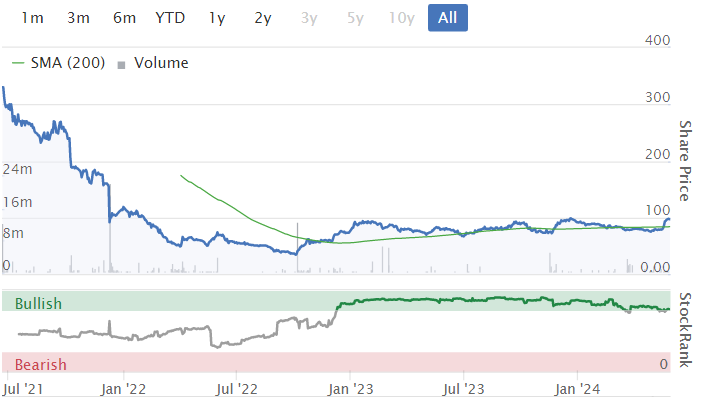
A seriously over-priced 2021 float, but finding its feet now at a more sensible valuation -
Genuit (LON:GEN)
Down 1% to 468p (£1.16bn) - Trading Update [in line] - Paul - AMBER
Genuit, the UK's largest provider of sustainable water, climate and ventilation solutions for the built environment, today issues an update on trading for the four months ended 30 April 2024 ahead of its Annual General Meeting ("AGM")...
Genuit used to be called Polypipe. I recall being moderately positive on this share with AMBER/GREEN here on 17/11/2023 at 315p, flagging the value at 12.3x PER, 3.9% divis, and a “marginally ahead” trading update.
It’s since risen c.49% in share price, so is it still good value?
Today’s update strikes me as lacklustre, given that GEN shares have considerably re-rated. I’d be looking for an ahead of expectations update to support a forward PER which is now 18.0x.
Instead we’re told for FY 12/2024 -
No change to management's full year earnings expectations
4 month revenue to end April 2024 is down 8.6% vs LY, blamed on soft markets.
It seems to be compensating for lower demand through costs & margins -
We are continuing to benefit from our focus on business simplification, continuous operational improvement and product innovation which is driving an improved operating margin.
Markets seem very relaxed about this, and seem to be anticipating recovery -
Genuit is in a strong position to benefit from the normalisation of volumes as markets recover, and we continue to see growth potential in our markets due to the structural sustainability drivers to which we are exposed."
… Genuit is on track to deliver the previously announced £15m of annualised savings from this programme, and will realise further productivity gains through the ongoing rollout of the GBS.
Upgrade cycle? This is the big question generally for construction, and related cyclical companies. Numerous companies are telling us that markets should improve in 2025. Although broker forecasts often lag behind these recoveries, presenting good opportunities for us at this stage in the cycle. That seems to be very much what the GEN share price has done, anticipating a not-yet-forecast recovery.
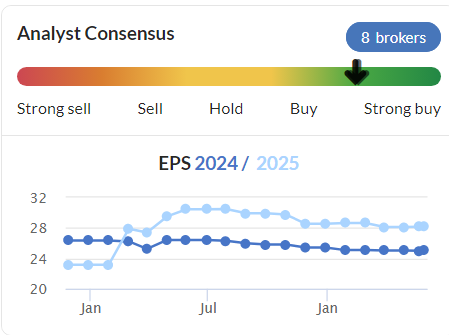
Paul’s opinion - the forward PER could turn out to be less than 18.0x, once brokers begin raising forecasts. But we need to see ahead of expectations updates, instead of the in line one provided by GEN today.
I think there are possibly better bargains at the smaller cap end of this sector, where you can still find some good potential recovery shares on much lower forward PERs than this.
Genuit looks a decent quality business, making a decent operating profit margin, suggesting it has some pricing power. For me though, the obvious value last time at 315p has been recognised by a share price rise to 468p, so I can’t see value here any more. For that reason I’m reducing from amber/green to AMBER.
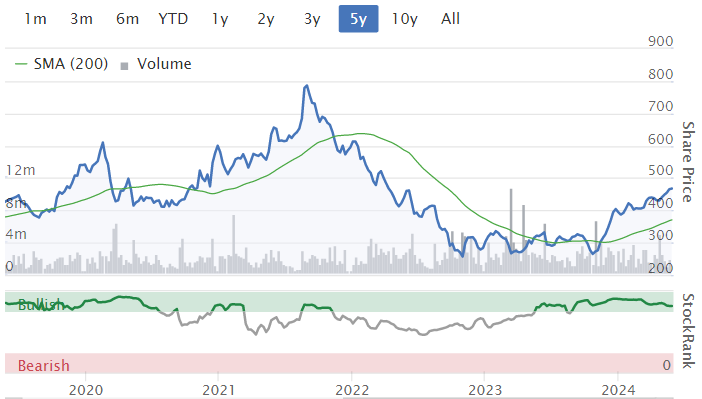
Note also that the share count has risen from 202m to 249m over the chart period below -
Graham’s Section:
Ingenta (LON:ING)
Up 4% to 152.5p (£22m) - Final Results - Graham - AMBER/GREEN
Ingenta plc (AIM: ING) a leading software and services provider to the publishing and media industries, announces its final audited results for the year ended 31 December 2023.
We haven’t covered this one since 2022, when the company again published its annual results at a considerable delay: results to December 2021 were not published until nearly the end of June 2022!
It seems that the company is on a slightly tighter schedule this year, publishing 2023 results at the end of May 2024.
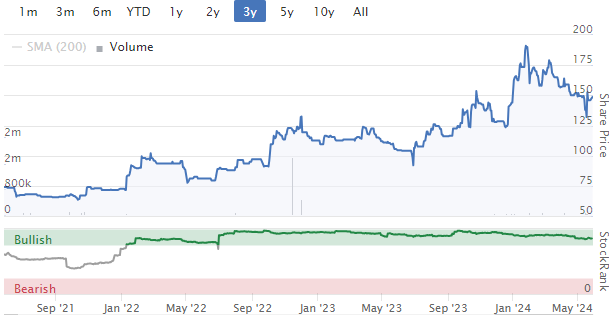
The share price has done well over the past two years:
Here are today’s full-year results highlights:
Revenue +3% to £10.8m
Annual recurring revenue £8.7m (last year: £9m)
Adj. EBITDA £2.2m (last year: £2.3m)
Net profit £2.3m (last year: £1.8m)
You may notice that the net profit figure is surprisingly large vs. adj. EBITDA. This is due to modest depreciation/amortisation charges and the company benefiting from tax credits.
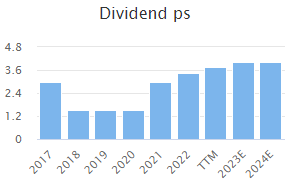
Dividend: the full-year dividend is 4.1p. Ingenta has an impressive track record for dividends, for a company of this size:
Cash increased slightly during the year to £2.7m. Speaking of the balance sheet, Ingenta has tangible equity of £3m, approximately matching the cash balance, and zero borrowings.
Operational highlights: the company highlights a couple of new customers and “go-lives”. This is a B2B company and so the numbers of new customers can seem alarmingly small but I suppose it goes with the territory.
Current trading: in line with expectations. A very important piece of information, as we are already five months into 2024! But it all sounds fine, with “a strong pipeline of project work being built for later in the year”. The outlook section also mentions that the company will consider potential acquisitions, although they do expect to see opportunities for organic growth.
CEO’s comment:
"It is pleasing to see the Company continuing its progression on an upward trajectory. The expansion of our web-based content platform has been critical to driving growth, and the continued expansion of our IP product into new markets which is now in use in five countries has demonstrated the offering and the adaptability of our Commercial product to meet new markets.
Continued growth and expansion of our customer base will be the primary focus in 2024. Having won a number of key new customer accounts, and demonstrated that with our streamlined operating structure we can deliver new business more profitably, we are expecting any new future revenues to make a substantial contribution to our profits and cash flows."
Graham’s view
The financials are all very reasonable, as they were when I studied the company two years ago. I noted then that the company had been around for many years, but had failed to make much progress in terms of market cap.
Important context here is that the company has a 28% shareholder in the form of its Chairman:
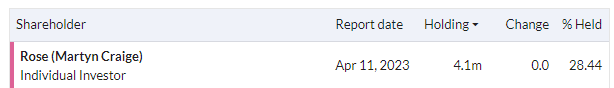
Judging by his CV, Mr. Rose appears to be involved with a number of different businesses but Ingenta is one that he has been involved with since 1999.
Ingenta has rarely increased its share count, pays a dividend and has a solid balance sheet - all signs of a business where management are heavily aligned with existing shareholders and are eager to earn a return from the business itself, instead of earning a living through fundraisings.
It’s tempting to give this one the green light but the lack of growth over the long-term is holding me back. The StockReport forecasts suggest that muted revenue growth (4%) is expected again this year.
In summary: this seems to be a successful business in the content management space with good financials, a decent long-term track record, a sound balance sheet and well-aligned management. If I could get excited about growth prospects I’d be willing to pay a high multiple for it. However, it’s been around for a long time and has experienced only very limited growth during most of its life, and that remains the case currently. Therefore, I’m AMBER/GREEN at this level.
Big Technologies (LON:BIG)
Down 2% to 167p (£485m) - AGM Statement - Graham - AMBER
Big Technologies plc, the UK-based, remote people monitoring technology company provides the following trading update ahead of its Annual General Meeting ("AGM") in London later today.
This is a 2021 IPO that issued a profit warning in January (covered by Paul), on the loss of a major contract.
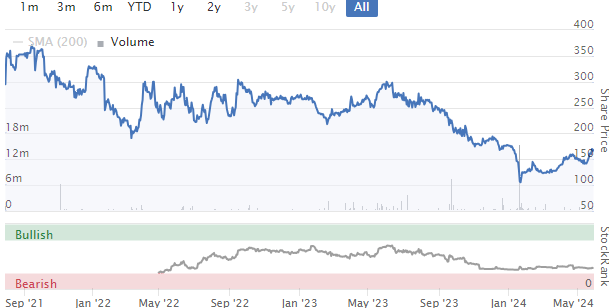
As you would expect from stocks of the 2021 vintage, BIG has been a poor share to hold since IPO.
However, it is up about 60% from the low it hit on the day of the January profit warning, so perhaps it may have hit the bottom already?
Here is the latest from today’s AGM update, which is in line with expectations.
Revenue £18.5m in first four months of the year (2023: same).
H2 revenues will be lower due to the loss of the contract announced in January.
“Overall, the forward visibility from our core global customer base remains excellent - 86% of the revenue from our largest customers is contracted beyond the end of 2026.”
Forecasts: the 2024 revenue forecast is £51.4m, down from last year.
The 2024 adj. EBITDA forecast is £27m to £29.5m (last year: £33m), implying healthy profit margins on sales.
Actual operating profit last year was £16.8m; I’d expect another wide gulf this year between adj. EBITDA and operating profit.
As an aside, I feel compelled to point out that share-based payments have been huge in each of the past two years (the cost of these payments is excluded from adj. EBITDA).
2023 is on the left, 2022 on the right:
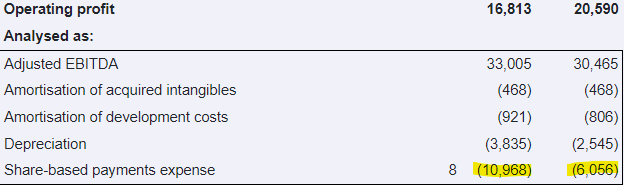
The share-based bonus schemes “were established to reward and incentivise the senior management team and employees to deliver share price growth”.
If the share price had soared in 2022 and 2023, it would be a little easier to defend these payments. This is how the share has actually performed:
Medium-term outlook:
Drivers for continued growth across both sectors remain strong in the medium-term. With our clear strategy and market-leading products, we are well positioned to generate strong cash flow and expect a return to growth in 2025 and beyond.
Here “both sectors” refers to the criminal justice sector (tagging offenders) and remote care (fall alarms for the elderly).
Graham’s view
I’m neutral on this. The company itself is profitable and should have some growth prospects again next year when the contract it lost is less influential in the comparatives. Electronic tags and fall alarms strike me as highly investable products.
I also note that the company finished 2023 with an extraordinary net cash position of £86m, covering nearly a fifth of the market cap.
However, the size of the share-based payments has spooked me, and the earnings-based valuation multiples are rather demanding.
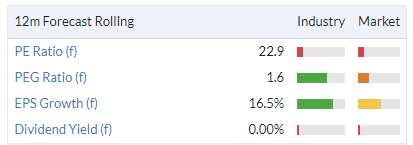
Price to sales is 9x, or about 7.5x if you adjust for the cash balance.
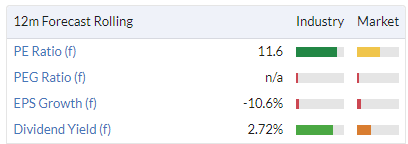
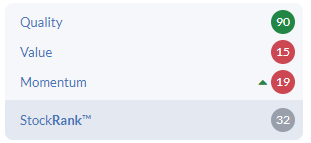
The StockRanks see a high-quality company but with little value on offer:
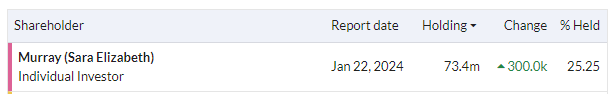
I should note in passing that the CEO is a 25% shareholder, and she was buying shares outright (not exercising options) in January this year, with a £300k+ purchase. Her business dealings and certain legal claims have been scrutinised by journalists at The Times this year (1, 2)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
One way in which Labour might follow Tory taxation policy would be to take on Hunt & Sunal's plan to freeze income tax thresholds till 2029. That's a pretty effective stealth tax route they could follow.
Gulf Keystone Petroleum (LON:GKP)
Genel Energy (LON:GENL)
Breaking News :
The Iraqi oil minister has invited the KRG’s natural resources ministry and the IOC’s for an urgent meeting in Baghdad to discuss an agreement to accelerate the resumption of the Kurdistan Region’s oil exports.
All the best
Not smallcap obviously with a 'complex' balance sheet and difficult valation.But Ocado (LON:OCDO) is on the move today (a top riser on hargreaves i think for once).Can't find out why but someone said on one of the puntier online bulletin boards there (so probably total rubbish!!), might be wind of another bid or perhaps the much anticipated possible Nasdaq listing??hey also moved according to their Kroger relationship news a fair bit before.Or perhaps just sentiment at all time lows being somewhat unwound and/or money coming back into puntier things again?
Pure rumours naturally and it's still quite shorted and a fair bit of bad news built in including with their Marks and Spencer (LON:MKS) partnership litigation and the CEO's multimillion pound bonus.I'm in for a trade.So will probably tank tomorrow and everyday the rest of the year and followed by massive diution!
Some huge trades going through at Seplat Energy (LON:SEPL) right now. 1.5million shares showing on LSE which is over 15 times daily average. (However, the value is 3.5million shares according to Google, so not sure if more will come through shortly).
General Election 2024: Labour backs British ISA plans but Natwest share sale under ‘review’
https://www.cityam.com/general...
I am reading through What Works on Wall Street, and found something interesting in chapter 23, which I thought worth sharing. There are 10 sectors. Of those, consumer staples had the highest annual compound return of all sectors. information technology offered the lowest average annual return.
That could well have something to do with when it was published (4th edition available on Amazon was published in 2011). I think technology has moved along a lot since then. I bought my first position in NVIDIA (NSQ:NVDA) back in 2016 and that has been my best performer ever by a very large margin.
A thank you to eParo for highlighting the article b y Nat Rothschild in City AM. Needless to say I agree with the views expressed.
On the subject of Volex (LON:VLX) and I am biased as it is my largest holding, there is a view, expressed by Judith Mackenzie at Downing that operating margins could hit 10%. I agree and this is also my view. The following is an extract from my post of the the 9th April last that give my reasons.
"In medical and complex industrials the company's customers have been able to increase production due better availability of key components, resulting in these end markets experiencing strong demand. In medical, Volex mainly works as a contract manufacturer with the result that production tends to be supported by corresponding orders.
Business continues to be strong in complex industrials with increased demand for the company's high speed 800Gbps cables by data centres, driven by the growth of cloud computing and AI.
Regarding the off Highway sector, the integration of Murat Ticaret is proceeding well with according to the company a multi-disciplinary team engaged in the delivery of integration plans. Murat Ticaret enjoys higher margins than the other sectors in which Volex operates and I anticipate that once fully integrated operating margins will be much closer to 10% that the 9.4% reported at the interims. The aim is to internationalise Murat Ticaret sales
The company does not provide operating margins for the individual areas of operation, but complex industrials, medical and off highway have the highest margins. These activities are lower volume and specialist manufacturing. On this basis it is reasonable to conclude that the higher margin specialist manufacturing capabilities of these sectors will offset the current demand softness in consumer electricals and EVs. I would add however that whatever one thinks of electric vehicles the trend towards electrification is in my view inexorable."
I could off course be wrong as could Judith Mackenzie. Hopefully not, we will find out shortly.
Off topic I have opened a starter position in Van Elle Holdings (LON:VANL) . I will post my reasons and thinking later as I am currently pushed for time. Taking a leaf from Cockney Rebel's play book, could they double in 12 months? If interest rates head down and the housing market picks up possibly. More later.
All the best
Hi Jonno, Van Elle Holdings (LON:VANL) I also bought a few of these the other day following their latest trading statement. I like the balance sheet strength given where we are in the cycle and net cash gives them the firepower for further bolt on acquisitions.
For anyone else interested I would point you in the direction of the most recent IMC presentation and Zeus note on Research Tree, it really is a high quality specialised niche operator.
WOSS if you see this, you know I value your TA skills, what do you think of the chart?
I think like all these things, patience required, the CEO has been buying shares and he comes across as pretty sharp, as they say if you want to invest in an ice cream van, you've got to buy it in February not July...
Hi Burnt Onions
Van Elle Holdings (LON:VANL) In line with my thoughts that I will post later. I believe that Richard Staveley at Rockwood Strategic (LON:RKW) has a position, but not sure of the size.
Yes I thought that the recent trading statement was pretty good given the sectors the company operates in. Also I like the tie up with Galliford Try (LON:GFRD) through the acquisition of its specialist piling subsidiary Rock and Alluvium .
Love the reference to ice cream vans; buy something of worth/value when nobody is interested. As you say patience required.
Still in a downtrend, volume picking up, if I owned it Id hold, if I wanted to buy now Id wait for a close above the red 200d and a higher high.
Price just where you'd expect it to find some sellers, below 200d and right on the blue VWAP low from 19 July '23.
Weekly chart.
Thanks Wolf, what an asset you are to the Stockopedia community, hopefully I can get to thank you in person one day, maybe at Mello or one of those things....
I also own Volex (LON:VLX. It will be interesting to see how well they have hedged their copper position as I believe Copper will move towards USD10/llb over the next two years, despite the problems in the Chinese real estate market (China accounts for 50% of global copper demand and they are sitting on huge stockpiles at a time COMEX is short). It is currently up 34% over the past 12 months and currently trades around USD4.85/llb. My largest position is Sprott Copper Miners ESG Screened UCITS ETF Acc (LON:COPP).
I am not a believer that the FED and other CBs have kicked inflation into the long grass. I think we will see a second wave later in the year. I believe it will be agricultural commodities and metals that drive inflation higher together with FED incompetence. Zinc, copper, aluminium, wheat and coffee are all set to drive higher fast I reckon.
Saga (LON:SAGA) shares are up 30% in the last month. There was some discussion in a previous SCVR about investors taking on a bit more risk in a bull market which seems to have happened here. Mkt cap is £187m, p/e(f) 3.7and peg(f) 0.1. Price crossed 200d SMA recently. £150m bond repaid recently as well. Stocko rates it as a 'Turnaround'
Don’t forget that South African elections happen tomorrow. I know that a lot of people hold mining stocks with exposure.
Braemar (LON:BMS) FY24 results webinar today 28th May at 1pm. Register here.
Redcentric (LON:RCN)
Further increase in sp this morning. For those of you who left early on Friday I posted this:
On a quiet Friday afternoon before a Bank Holiday weekend the share price jumps at 15 17 and then 10 minutes before close we have "The board of directors of Redcentric (the "Board") notes the recent press speculation and confirms that it is in the early stages of discussions with Wiit SpA, regarding a possible offer for the entire issued and to be issued share capital of Redcentric".
Watch this space!
(RCN provides in-demand cloud storage but the sp is still recovering from an accounting scandal in 2016 for which the then CFO was jailed for five and a half years).
I expected Zotefoams (LON:ZTF) to be down on the news today.... must be the Paul Scott impact from his podcast (I hold) :)
Disruptive Mono-material Aseptic HDPE Carton Tech Takes Aim at LPB | Packaging World (packworld.com)
Zotefoams (LON:ZTF)
Maybe this article in Packaging World has something to do with it, Neil Acort Johnston the president of Mucell Extrusion which is part of Zotefoams is quoted as saying he thinks that the Rezorce packaging will be on the shelves in the next financial quarter which is probably a lot quicker than most folk are assuming.
Over the weekend I noted both Paul and Cockney Rebel mentioned they were buying Zotefoams (LON:ZTF) . Pretty unusual to see an overlap in the shares they hold. I must say as one of my largest holdings I was pretty chuffed. Then of course David Sterling comes and spoils then fun. Although on reflection, only selling 1/4 of his shares on retirement doesn't seem unreasonable at all. He's still choosing to have a significant portion of his wealth invested in Zotefoams (LON:ZTF) even after he steps back from the company. He certainly deserves to enjoy a bit of the success he's brought the company.
Hi BenHazz,
Actually I often like some of the shares that CockneyRebel highlights, so nothing unusual about us converging on the same share in ZTF. He's a fine stockpicker, and often has interesting angles on turnarounds, etc.
Regards, Paul.
PS - I think it was someone here who made another interesting point, that the likely new Govt has boxed itself in already by saying no increases in PAYE, NICs, and no wealth taxes. That leaves very few options other than a multitude of stealth taxes, and maybe an increase in CGT, also to close the loophole highlighted in the Times this weekend that "carried interest" is being used as a way to achieve lower taxes for some high earners. Hence these considerations re higher taxes (esp CGT) might be why we're seeing some Director selling now, to bank their gains whilst the tax bill is reasonable?
Couldn't agree more, he is excellent. I was more highlighting that as you have both built a position in Zotefoams (LON:ZTF), that to me is a great vote of confidence. Here's hoping it's as successful as CMC Markets (LON:CMCX) when both you and Graham selected it in your top lists!
The smart money has been crystallising some of their gains for the last year or so, particularly while certain roll-over reliefs remain available. Alternatively they have been creating and claiming losses to be carried forward and relieved against future more highly taxed gains.
There is already an observable trend of the burden of taxation starting to switch from income more onto capital - that has advanced at a pace recently under the current administration who don’t have Labour’s ideological leaning, and observable antipathy towards, “unearned” income and returns. Expect to see a rush towards abolishing a range of IHT and CGT exemptions and reliefs, although that will hit the reality of working against other well-signalled intentions, given it may undermine capital raising for early stage companies and investment in “green” outcomes.
Other investors are no doubt reflecting on this, although I can’t see how abolishing IHT relief on holding many AIM-listed shared can do anything but fatally undermining the functioning of that market in both terms of capital raising and liquidity in the secondary market.
Let’s all see
Fair point. I sold my investment property last year given that CGT relief was being tapered to nil soon. Others surely would also consider this
The problem is that in many cases "the gaIn" is not a true gain but a result of inflation so if CGT rates are increased they need to bring back indexation.
Spot on The Skier.
Annual CGT exemption on shares soon to be down to £3K per annum. Inflation been in double figures recently . Not a good background for holding shares .
Good ramble Jayman I agree both the main parties seem to be moving towards taxing assets and the income they produce rather than raising income tax.
The problem is magnified by the fact that since covid a lot of people in the UK have given up/don't want to work I think furlough created a sense of entitlement to get paid for doing nothing.
From memory 20% of the 16-67 age group don't work, part of that group is students who hopefully will work in the future and it also includes carer's.
I have friends who run pubs and they struggle to get staff, a lot of the staff they have don't want overtime as it then starts to reduce their universal credit.
We have engineered a situation where for the poorer part of society if you have two children or more aged 16 or under and in your in rented property there is really no financial incentive to work more than 16 hours per week (30 if your a couple) as you end up about a £1 an hour better off best case.
I don't know what the answer is but can only see this issue growing and more benefits needing to be paid and labour will certainly look to soak assets as a way of paying for the every growing financial mountain.
Interesting thoughts Phoenix. A friend of mine has suggested to take the freezing of thresholds as a given - possibly apart from when it starts to draw State Pensions into the net - and watch out for an increase in VAT, as several EU countries at 22%+.
Your point on Carers very topical as Carers Allowance is one of these daft cliff edge schemes. Perhaps they will look to make that a little more balanced, increasing incrementally above a threshold. If it is more cost effective, and humane, for those that need support to be cared for at home surely we should find a way to encourage it without the dreadful optics of HMRC plunging those that also go out to work, probably for their own sanity as much as economic necessity, into substantial debt if they go over the proscribed limits.
The clawback on Universal Credit may be a little too aggressive to encourage taking on extra hours as well. Only a sample of one but a chap I assist loses 55% of each pound over a given level. So he's minded to mitigate earnings over the threshold particularly as his earnings are variable. Again layering it might might change behaviours for a mutual benefit.
KBR - A sound argument for using all Tax Efficient investing options asap! For those beyond that I guess it will just be part of the price of success. Another home business I work with was pleased not to reach the threshold for payment of tax this year - I've suggested she regard paying tax as an achievement and strive for it every year. Amazing that so many people expect all our public services and pot holes to be sorted without contributing. Be proud of being a taxpayer - but don't pay more than you have to!
I'm not keen on this "Paul Scott effect/impact" thing, as it makes me sound like some spivvy tipster. What we're actually doing is just reporting on each day's news (that's what moves the share prices, not my opinions).
“Infamous stock market plunger known as The Maltese Falcon has built a stake in Zotefoams (LON:ZTF) . The darling of tip sheets and thousands of small punters, The Maltese Falcon whose real name is Paul Scott is hated in equal measure by the market making community!”
Very droll! Maltese Falcon has a nice ring to it. Or how about the Gozo Ghost?!
Spivvy tipster. I don't know why this came into my head but it did!
I think you'd look good in the stockbrokers bowler hat Paul.
Sorry Paul won't say it again :(
Hi Nanotrader09,
Sorry Paul won't say it again :(
It's fine, don't worry, I wasn't fishing for an apology, you can say what you want within reason! ;-)
Best wishes, Paul.
Hi Paul,
Many years ago I was an inexperienced writer covering the biotech sector for a financial web site and I was aware that my articles could move share prices if the company was small enough. That was certainly not the intention, I think it was just a reflection of the fact that some companies receive so little coverage that comments online have a disproportionate effect. As you are relatively well known by the investment community (unlike me) I am sure your opinions do move share prices, at least for the smallest companies, even though that is not the aim of your news coverage, it is just a side effect which can be a nuisance.
Hi peterthegreat,
I take your point. However, it's impossible to determine, since we cover opinions here on the daily news, driven by trading updates & results statements. To me it seems obvious - the market reacts to results & trading updates, then we write about the movers here.
Anyway, we've gone round in circles on this point many times before, and there's nothing new to talk about, so I'll leave it there.
P.
If supply > demand, then good for travel companies and airlines. So why the drift?
Sometimes the flow of money just goes elsewhere. It’s not necessarily a comment on the operational progress of the neglected sector.
Likewise (LON:LIKE)
Undermines the bull/growth case somewhat is an understatement. No follow up explanation!
Agree; as far as I am concerned, selling straight after giving a 'everything is Roses' presentation the other week, completely stuffs buying LIKE until audited accounts show a pretty picture. That's likely to take 12+ months.
Victorian Plumbing (LON:VIC) Was anyone else like me confused as a retail customer between Victorian Plumbing and Victoria Plum. Maybe that's why VIC purchased their struggling competitor, so that on-line traffic no longer goes to Victoria Plum instead of Victorian Plumbing.
Yes, I was once confused by the names. Though I have to say, having previously used Victorian Plumbing (LON:VIC) the difference was immediately apparent as soon as I opened V Plumb's site, and I left and didn't look back!
There had been a legal case between the two companies - case revolved around the similarity of the names - and the impact on sales. Judge found it difficult to make a decision. He finally made Victorian Plumbing pay Victoria Plum £1.5million - loss of profits. I suppose that Victorian Plumbing feared that a new owner of Plum would see an opportunity to continue to get financial compensation - more legal cases etc, so worthwhile for VIC to get permanently rid of the issue.
"Higher interest rates have caused off-plan home sales to tumble in the UK, prompting the nation’s housebuilders to scale back development.
Some 32% of new homes were sold before they were built in England and Wales last year, down from 39% in 2022 and the lowest level in ten years, according to Hamptons International. That’s bad news for developers, which have been slowing build rates to preserve capital and ensure they’re not left with large numbers of unsold homes, the broker said.
“With more homes only sold after they’re finished, it means developers are borrowing money for longer and at higher interest rates,” said David Fell, lead analyst at Hamptons. “This means the government is unlikely to get close to hitting its housebuilding targets until interest rates drop back
considerably.”
Source: Bloomberg May 27, 2024
https://www.bloomberg.com/news...
A subscription site but I believe they offer three free article reads per month.
Thanks for the info.
My morning smallcap tweet: NIghtcap 'forgot its wallet' as it tries to buy RBG
Revolution Bars (LON:RBG) Quadrise (LON:QED) EQTEC (LON:EQT) Infrastructure India (LON:IIP) STM (LON:STM) Graft Polymer (UK) (LON:GPL) SIMEC Atlantis Energy (LON:SAE) CEL AI (LON:CLAI) Victorian Plumbing (LON:VIC), Big Technologies (LON:BIG), Ingenta (LON:ING), Theracryf (LON:TCF)
◄Revolution Bars (RBG)► Nightcap made a takeover proposal but co says it's "incapable of being delivered" since it would require two fundraises, plus due dil time. [SP=1.43 Cap=6m]
◄Quadrise (QED)► Commercial Framework Agreement with its client in Morocco, OCP. They will commence commercial discussions with third parties for MSAR supply to OCP and work together on a paid-for commercial trial. [SP=1.47 Cap=26m]
◄EQTEC (EQT)► £850k placing at 1.4p, an 18% discount, for working cap and to fund its strategic pivot. [SP=1.7 Cap=3m]
◄Infrastructure India (IIP)► terminates sale of Indian Energy (Mauritius) because the buyer has failed to cough up. [SP=0.1 Cap=m]
◄STM (STM)► regulatory approvals slow in coming so Long Stop Date extended to 28 June. [SP=57.5 Cap=34m]
◄Graft Polymer (GPL)► makes US patent application "for the use of its proprietary and patented self-nanoemulsifying drug delivery systems (SNEDDS) platform for the delivery of drugs for the treatment of substance use disorders". [SP=0.13 Cap=m]
◄SIMEC Atlantis Energy (SAE)► gets next milestone payment of £2m for its Battery Energy Storage System project. [SP=1 Cap=7m]
◄Cel AI (CLAI)► H1-Feb. Outlook - cost cuts to eke out cash plus "it's important to note that tangible results may require additional time to materialize". [SP=0.16 Cap=1m]
◄Victorian Plumbing (VIC)► FY-Mar. Outlook- guides FY24 adj EBITDA only broadly in line as it's weighed down by its lossmaking Victorian Plum acquisition. [SP=96.3 Cap=314m]
In line: BIG, ING, TCF
Ingenta (LON:ING) Final Results might be an interesting one to look at today, although a tiddler. Revenue up 3%, Net Profit up 30% and some adjustments to unpick. There is a Cavendish note out this morning as well with FY24 forecasts unchanged.
Great weekend podcast Paul, thanks
Thanks TJ! Hopefully the birds didn't put you off too much.
As someone who listens to a lot of podcasts, I actually think they enhanced it
I likes the birds too!
Paul you covered Whitbread (LON:WTB) back in January and liked it but not at region 3600p, plainly out of favour now down in the 2900p range, any thoughts ? I'm always looking back at past reviews you have done so you get a better understanding of business cycles. Keep up the great work.
There seems to be weakness in consumer discretionary and travel stocks and my bank has just downgraded the sector - although they are often slow with the downgrades. Whitbread is one out of favour and I picked up a position a couple of percent higher, WH Smith is another that I like with a great estate of outlets in airports. Increase in minimum wage is clearly an additional cost for many consumer stocks. But if we’re going into a cyclical upturn - obvs not guaranteed - then a rebound may reward holders.
Have the same issue with Dalata Hotel (LON:DAL) which despite increasing revenue and profit seems to continue trading lower. I run the travel team in my company and all I see is increasing prices of flights and hotels globally and supply seems to be struggling with demand.
If supply > demand, then good for travel companies and airlines. So why the drift?
I mean Demand > Supply. Sorry, can't edit post on an Andriod mobile.
Morning mike!
Yes I'm quite surprised to see Whitbread (LON:WTB) shares very much out of favour at present. That's despite strong results for FY 2/2024, with adj EPS up 27% to 206.9p (PER 14.1x). Bear in mind also it has a superb balance sheet, stuffed full of freeholds. Doing buybacks as well as an unremarkable 3.3% divi yield.
Living wage increase is bound to be a headwind, but I would expect that to already be baked into the forecasts.
Slight drop in recent broker consensus I see, but that's after a good trend upwards in forecasts previously.
Maybe the recent news of it restructuring some of its food & beverage outlets into more hotel rooms might have spooked some investors about performance in that division?
As a long-term investment I think WTB looks very attractive, because there are so few branded, good value hotel chains in the UK, and Premier Inn has an excellent brand, and market position I think, and its numbers speak for themselves. Lots of expansion potential (including Germany), and less competition as so many independents exited the market during the pandemic, and have repurposed their properties apparently.
As always, I've no idea what the share price will do, but I still regard WTB shares as an attractive option to consider as a long-term investment. It's on my watchlist. With a fragmented shareholder register, it could be a bid target too maybe?
Regards, Paul.
Whitbread (LON:WTB) - Have looked at this myself and tempted but the £4.4b debt figure put me off though I have gone with J D Wetherspoon (LON:JDW) which also has debt but sentiment seems to be with them.
Whitbread (LON:WTB) - Have looked at this myself and tempted but the £4.4b debt figure put me off.
Balance sheet is beyond fine. Have a look at Paul‘s previous coverage of the name
Thanks BnB. Indeed that £4.4bn debt figure re Whitbread (LON:WTB) is a red herring. I went through & explained all the figures & balance sheet here in Jan 2024 so that's a good starting point. If I get time I'll update it for the more recent results. Bottom line though, as BnB says, WTB's balance sheet is more than fine, it's rock solid!
Thanks BnB - I appreciate its a great business Whitbread (LON:WTB) - and Paul's write-up back in Jan was spot-on - warning not to buy at that time/price. Q now is whether to buy today or wait a bit longer. Trading update due next month so will hang on for now.
Why would anyone want to buy into a tough retail business at PE 14 and 3.3% yield? I don't understand why anyone finds these types of business attractive. BT for example, has a PE of 7 and yields in excess of 6%.
I know you only used it as an example but as a counter to your argument: BT has huge negative tangible asset value, massive debt and rev/profit going backwards. So is cheap on a PE basis for very good reason. It should be paying down debt, not paying out divis.
Whitbread (LON:WTB) I don't know anything about BT but for WTB I'd say a PE of 13 looks decent value given its growth prospects and leading market position. Also the yield is quite a bit higher than 3.3% if you factor in share buybacks - probably more like 6%.
Hi RCTurner,
Re Whitbread (LON:WTB)
Why would anyone want to buy into a tough retail business at PE 14 and 3.3% yield?
Maybe because it isn't a "tough retail business"?! It's actually a high margin, highly cash generative hotels business. Check the numbers out, and you'll see the attraction - eg, PBT margin of a superb 19% last year -
Balance sheet is bulletproof, with £3,519m NAV. Includes intangibles of only £185m.
Cash £697m, less borrowings of £995m (cheap bonds) - they could be earning more interest on the cash deposits than paying on their bonds -
Fixed assets contains £3,669m of freehold property!
The supposed £4.4bn debt is a complete red herring, it's IFRS 16 lease entries, which are future years rents payable (a future operating cost), not debt.
WTB is very much a situation where you have to dig into the numbers. I nearly fell off my chair when I saw how strong the balance sheet is. Hence why I think private equity might bid for it, as they could pay a premium out of re-gearing WTB's own assets.
Regards, Paul.
Thanks Paul - Its all about understanding the balance sheet - and I had not appreciated the leasehold commitments being shown as debt. thanks for pointing this out - think I have been caught on this one before!
Whitbread
perfect timing for me to buy some. I only need to own 67 shares to qualify for a 10% discount at Premier inn. Shareholders perks are not available if you buy within your SIPP.
I only need to own 67 shares to qualify for a 10% discount at Premier inn.
I’ve got quite a lot more than that. How do I claim my discount?!!!
Whitbread (LON:WTB) Get your broker to apply for the discount card for you.....
I heard there were free breakfasts too for shareholders!
Whitbread (LON:WTB)
Shareholder benefits are not as you describe.
Minimum holding is 64 shares.
The 10% is for food in restaurants.
Free breakfast if you stay in a hotel.
Full details https://www.whitbread.co.uk/in...
Not so many companies do shareholders perks as far as i know anymore than used to. Carnival (LON:CCL) is the only other one i can think of off the top of my head, although maybe i'm missing some?Don't think J D Wetherspoon (LON:JDW) 's does.Shame on you Tim Martin!
P.S. Just found this on shareholder perks on Hargreaves Lansdown (LON:HL.) dated 2023 for anyone interested.And just discovered a company with shareholders' perks that i've never heard of Adnams (OFEX:ADB).You only need 1 share there for the perks 'You’ll get a privilege card giving a 15% discount on Adnams store
purchases and on meals and accommodation at Adnams hotels.'
https://www.hl.co.uk/shares/sh...
Bloomsbury Publishing (LON:BMY) I believe do discounts on their books for shareholders.
Marston's (LON:MARS) 25% off food in all their pubs and they sent me c20 coupons when I requested via AJ Bell. Not sure I'll ever use them but some comp shopping is always good
I believe if you own 1 x BMY share it entitles you to a 35% discount off its books.
Tempted by Whitbread (LON:WTB) , so just looking over the FY results, which do look good, but put off by:
1. Loss making in Germany - very difficult market for British consumer companies to make money. I guess that this performance is not in line with their original plans when they decided to open in Germany.
2. Great operating profit margin % as Paul notes but then in the cashflow there is £253m of non-expansionary capex, which in my experience usually gets a very low return if any. You could regard this as a P&L item, generally just maintaining the estate at the required standard.
3. One of P&L adjusting items are imo at the more aggressive end is the £27.1m (PY:£13.8m) of "Strategic IT costs", plus a load of impairment provisions around the Strategic plan.
4. Is this a good time to buying into a business where 100% of profits are coming from the UK?
Having said that after adding back expansionary capex, I get to a FCF return of 10% on the current share price, which when you look at the growing and well run business looks quite attractive.
I stay in Premier Inn and think they are great at focusing on the important customer requirements in a budget hotel business.
Also you do wonder what the group would look like on a hotel model split into property returns and management fees, so could well be a takeover target.
I'll be interested in others' views?
AIM high: Why the London Stock Exchange still matters
Urgent reforms are needed to prevent the flow of companies exiting the London Stock Exchange becoming a flood – and AIM is a great place to start, says Lord Rothschild -Volex (LON:VLX)
https://www.cityam.com/aim-hig...
Understandably Nat has offered quite a company and regulatory focused solution.
I would love to see investing made more accessible for us retail investors including by releasing RNS results the night before after the market closes so we don't have 1 hour to digest key information in the morning and by improving the availability of company research so we aren't left in the dark about what a company's expectations are.
Why noy make it clearer which shares qualify for IHT relief on AIM instead of HMRC being so covert?
Contacting companies direct for their view it worth it sometimes
KBR
- too much capital tied up in unproductive assets e.g property & associated rent-seeking
- stock-market is culturally viewed as 'gambling', 'something you won't win at', 'may as well go to the casino' and so on
- anecdotally: a chap i know recently sold his stake in a private business to his co-founder and a larger company (and now does freelancing as and when he chooses for the larger company)
- he wasn't specific about the amount, but from the figures he has revealed in conversation before (e.g turnover/revenue, dividend tax rates etc.), i estimated it at low 7 figures
- his immediate response? 'look around the banks for the best rates and see what they're offering'
sums it up really...