Small Cap Value Report (Tue 3 Apr 2018) - AIR, RNWH, FLYB, HRN,

Good morning, it's Paul here!
I'm back from a week's holiday on the west coast of America, which was interesting & enjoyable. If you think we've got a homelessness problem in the UK, then you should visit San Francisco - where the scale of the problem is unbelievably bad, and very sad to observe. All that wealth, yet thousands of people have just been abandoned, to live miserable & squalid lives on the streets.
Many thanks to Graham for doing a sterling job last week, which gave me a chance to have a rest from the markets.
It looks to be a quiet day today. So far I have the following on my list to review;
Air Partner (LON:AIR) - accounting issues
Renew Holdings (LON:RNWH) - trading update
Flybe (LON:FLYB) - trading update
Hornby (LON:HRN) - trading update
So I'll get cracking on those now.
IQE (LON:IQE) - I've just seen the tragic news that its Finance Director, Phillip Rasmussen, has died following a cycling accident abroad. He presented at a Mello evening a couple of years ago. His presentation was an absolute masterclass in how to explain complex subject matter with amazing clarity. Our condolences go to his family, friends & colleagues.
Air Partner (LON:AIR)
Share price: 113.25p (down 21.1% today, at 08:39)
No. shares: 52.2m
Market cap: £59.1m
Year end update (accounting problem)
A reader has asked me to try to explain today's announcement in plain English.
A problem has emerged during the audit of its figures for year ended 31 Jan 2018;
The Board of Air Partner has identified, during the course of its year-end review process, an issue predominantly relating to its accounting for receivables and deferred income.
Following preliminary investigations, the issue principally relates to the collection of receivables from customers and accounting for uncollected amounts since financial year 2010/11.
Certain uncollected receivables were inappropriately offset against deferred income rather than being expensed to the income statement in the appropriate financial year.
This is a non-cash item and has no bearing on the Company's cash balances.
This seems to be saying that bad debts (i.e. amounts which had been invoiced to customers, but were not paid by the customer) were not written off through the P&L. Instead they were offset against a balance sheet creditor (deferred income).
This appears to be indirectly saying that prior year profits were overstated. Although I cannot be sure about that, as it depends on the nature of the deferred income. If bad debts were dumped into the (very large) deferred income creditor account, with no specific reason, or matching of related items, then that just sounds like false accounting to me - very concerning. However, we cannot be sure of this, as today's announcement doesn't give enough detail. It also refers to preliminary investigations.
The size of the problem is fairly small, and spread over several years;
Whilst the investigation continues, the Board presently understands that the cumulative amount between financial year ended 31 July 2011 and the financial year ended 31 January 2018 is approximately £3.3 million and a significant proportion of this relates back to 2011.
My opinion - this is a tricky one, as we don't yet have full information.
If you are happy to give the company the benefit of the doubt, then it could be argued that a drop of about £15m in market cap today, for a £3.3m historic accounting issue, could be an over-reaction, and hence perhaps presents a buying opportunity?
However, following on so soon from the calamitous turn of events at Conviviality (in which I have [now worthless] long position, bought 1 day before the shares were suspended, as a falling knife purchase), the timing could hardly be worse.
Maybe this disclosure could be the thin end of the wedge? Who knows?
Looking at the last reported balance sheet, at the interims as at 31 July 2017, it looks OK to me, although not particularly strong. As with many travel companies, it relies heavily on customers paying up-front, in advance of using the service. Some key numbers;
NAV: £16.1m
NTAV: £7.4m
Current ratio: 1.1
The stand-out figure on the balance sheet, is £43.8m of deferred income - i.e. the opposite side of the double entry from cash received from customers. Total cash is £28.8m, so the whole business is financed by customer up-front payments. That's not unusual in this sector - airlines, and cruise ship operators typically finance operations in the same way.
Overall, my feeling is that share price drop of around 20% today looks about right. It's very concerning that the company appears to be admitting today to having falsely accounted for bad debts, and hence boosted cumulative reported profits by £3.3m.
There again, that's a relatively minor amount, and I don't see any signs that this issue alone would affect the viability of the business at all.
The company has more explaining to do, and perhaps a change of FD is now needed? Based on today's announcement, I don't see any reason to panic. It doesn't look like another Conviviality. Let's hope those are not famous last words on the matter.
Renew Holdings (LON:RNWH)
Share price: 386.5p (up 1.7% today, at 09:46)
No. shares: 62.59m
Market cap: £241.9m
Renew (AIM: RNWH), the Engineering Services Group supporting UK infrastructure, announces an update on trading in advance of the interim results for the half year ended 31 March 2018.
This all sounds reassuring;
The performance of the Group continues to be strong. Trading for the first half of the year is in line with the Board's expectations and we anticipate reporting an increased forward order book at the interim results.
This has been driven by Engineering Services where order flow across our Infrastructure and Environmental sectors has been good.
The Group expects to report a modest net debt position at the half year in line with expectations. Our year end net cash forecast remains unchanged.
What is less reassuring however, is (as I have flagged many times before), this group has a very weak balance sheet. To date, this doesn't seem to have caused any problems. However, it's a potential major risk, that investors need to be aware of.
Consider the following key figures, from the last reported balance sheet of 30 Sept 2017;
NAV: £28.1m
NTAV: -£32.6m - a significantly negative position. I don't normally invest in anything with negative NTAV.
Usually, this would indicate that a company was laden with debt. However, in this case, there's very little in interest-bearing debt. The elephant in the room is the enormous trade creditors debt of £173.2m. I looked into this before, and a lot of this non-interest-bearing debt is deferred income - i.e. the other side of the double entry to cash received up-front from customers.
So, coincidentally, in a similar way to my comments on Air Partner (LON:AIR) above, Renew Holdings (LON:RNWH) is also funded by its customers up-front cash payments. This is fine if the receipts keep flowing, however it could spell disaster if, for any reason, customers decide they don't want to pay up-front. In that scenario, RNWH would need to strengthen its balance sheet with an equity raise (I'm surprised they haven't already done this, given the fairly strong share price in recent years).
In a nutshell, RNWH's business model hinges on it being paid by its customers before it has to pay its sub-contractors & other suppliers.
The problem is, in this sector, a weak balance sheet means that a contractor is only one bad contract away from disaster. We've seen how numerous contracting businesses have run into contract problems - often terminal, as with Carillion.
Pension scheme - this needs more investigation. There is a £9.7m asset for pension schemes, within non-current assets. However the last cashflow statement shows a £5.3m cash outflow for contributions to defined benefit pensions. Therefore it looks like there might be a significant actuarial deficit, but an accounting surplus. I don't have time to look into that now, but am just flagging it as an issue which readers might wish to investigate if considering a purchase (or hold) here.
On the upside, Renew seems to be well-managed, and focused on niche projects, with improving margins (up to 4.6% at the last full year accounts).
Another positive point is that a loss-making subsidiary has been disposed of, which should boost group profits by £2.8m p.a..
Valuation - seems reasonable, but wouldn't look this cheap if you adjust for the black hole in the balance sheet;
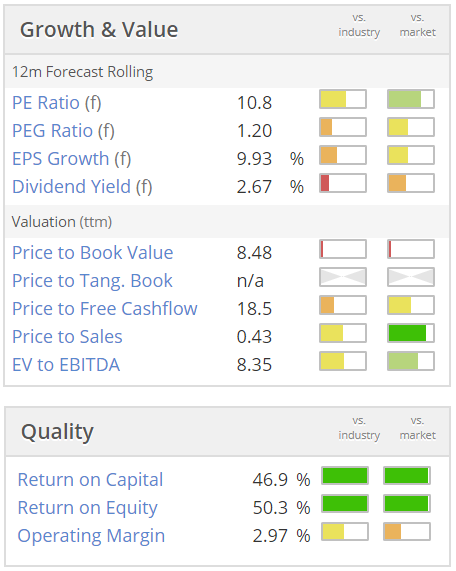
My opinion - the company has a good track record. However, this sector is fraught with risk, so I cannot understand why anyone would want to invest in this sector at all. Let alone in a company with a negative NTAV balance sheet.
Flybe (LON:FLYB)
Share price: 34.25p (up 2.2% today, at 11:09)
No. shares: 216.7m
Market cap: £74.2m
This reads as a mixed update today, from this UK-based regional airline.
Load factor & revenue per seat in Q4 (Jan-Mar 2018) have improved;
Flybe's turnaround continues with a further improvement in load factors as we reduce capacity1. In Q4, load factors2 were up by 6.8 ppts to 73.5%, a strong performance for the winter season.
As a result, estimated passenger revenue4 per seat was up by 9.0% to £50.84. Passenger numbers3 rose by 3.7%, even though capacity was reduced by 6.0%.
On the negative side, the very poor weather this year has hurt profits, as you would expect;
We had to cancel 994 flights due to weather in Q4 compared to 372 in Q4 last year. As a result, we anticipate this to have an impact of around £4m from lost revenue and additional care and assistance costs on cancelled and delayed flights.
The company can't be blamed for that.
The legacy problem of excess leased aircraft seems to be drawing to a close, which is good news;
At 31 March 2018, Flybe has returned five of the planned six end-of-lease aircraft with the final one to be returned in early April. At the year end, Flybe will have a total fleet size of 80 aircraft (31 March 2017: 83) which will fall to 79 once the final handback is completed.
Net debt;
We expect net debt at 31 March 2018 to be broadly flat year on year.
Looking back at last year's results, net debt was £64.0m at 31 Mar 2017. Previously the company had a lot of net cash, but it used this to buy 10 Bombardier Q400 aircraft, which were previously on leases. This gives me a good excuse to put a picture of a plane below.
Early indications of summer trading;
Our strategy to reduce capacity to focus on profitable flying will continue into the new financial year. Very early indications of our summer trading are encouraging with an estimated 7.5% increase in passenger revenue per seat offsetting an expected 7.9% decrease in capacity.
So far, we have sold 21% of our H1 capacity, against 20% sold at the same time last year.
Outlook - sounds a bit mixed. Some positives, but also mentions cost headwinds;
"The Flybe strategy as set out in our business plan to reduce the fleet size is delivering higher load factors and revenue per seat. The drive to reduce costs is continuing, given added impetus by the rise in fuel prices and lower value of sterling.
Despite these headwinds, the foundations are being put in place to strengthen the business and we remain confident that our strategy will continue to improve performance as we go into the new financial year."
My opinion - I'm not the best person to judge, as I've been wrong about this share in the past. It has always seemed a good turnaround, if you believe broker forecasts. However, the company seems to repeatedly disappoint, missing forecasts.
That said, it's a lot of company for the money (just a £74m market cap). A bear might point out that the company isn't really viable - historically failing to put enough bums on seats to make its routes profitable overall. The company also seems to be tying up a huge amount of capital, to generate no return for shareholders. So what is the point in it existing at all, other than to provide employment for Directors and staff?
On the plus side, the company does seem to be gradually working through its historic problems. Maybe the much vaunted turnaround could be finally emerging?
I can't help wondering whether there might be value in FLYB to an acquirer? There was a recent flurry of announcements from Stobart (LON:STOB) and FLYB which seem to suggest that STOB made an offer for FLYB, which it declined. I can't find any mention of a mooted price for the possible bid.
Overall, I wonder if FLYB might make an interesting punt at the moment? There's a possibility its long-standing turnaround could begin to work. Also, the takeover potential looks interesting, particularly if an acquirer could somehow utilise its fleet in a more profitable way - maybe reducing passenger capacity, and increasing freight, on routes with low load factors?
FLYB looks financially stable, so it's not a completely ridiculous idea to look at it as a possible punt. It would be very interesting to find out what price Stobart were willing to pay for Flybe. Has anyone seen any detail on this? If so, please leave a comment below.
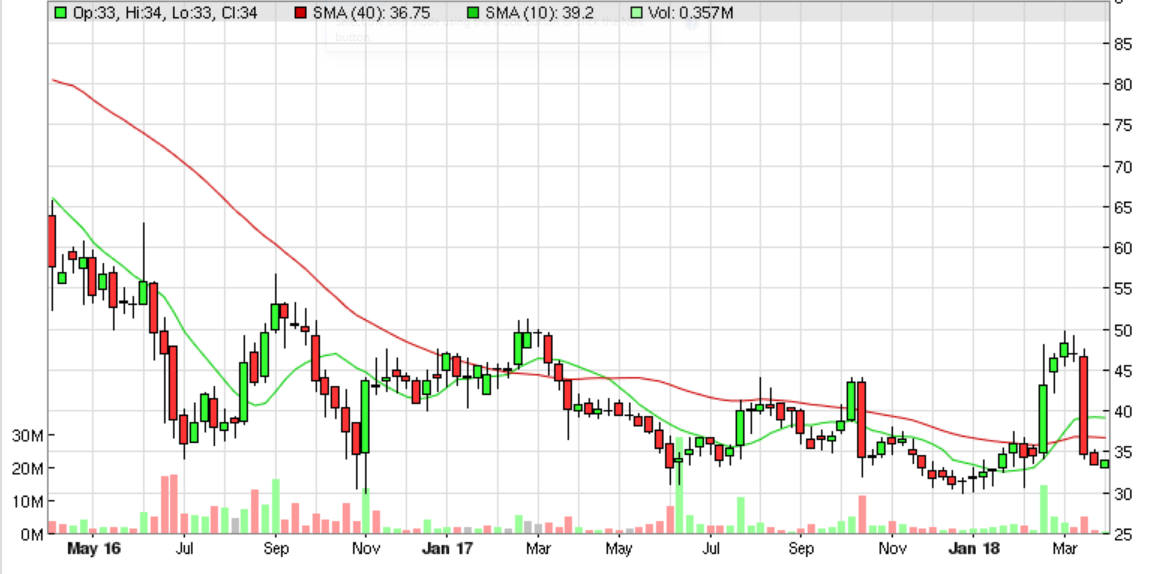
Hornby (LON:HRN)
Share price: 23p (down 6.1% today, at market close)
No. shares: 125.3m
Market cap: £28.8m
Hornby Plc, the international hobby products Group, provides an update to shareholders on the progress of the new strategy.
I'm a bit rusty on this share, so have been reading through the recent RNSs.
25 Jan 2018 - profit warning, due to a refusal to discount prices, and late deliveries. Underlying loss after tax (for y/e 03/2018) likely to be larger than expected.
Interim results to 30 Sept 2017 look very poor - a £4.5m pre-exceptional loss, on revenues of £17.0m. Bank debt rising, to £5.3m. Receivables & inventories look too high.
Placing - in Nov 2017 - relatively big, raising £12m gross, at 29.5p - should have more than wiped out all bank debt.
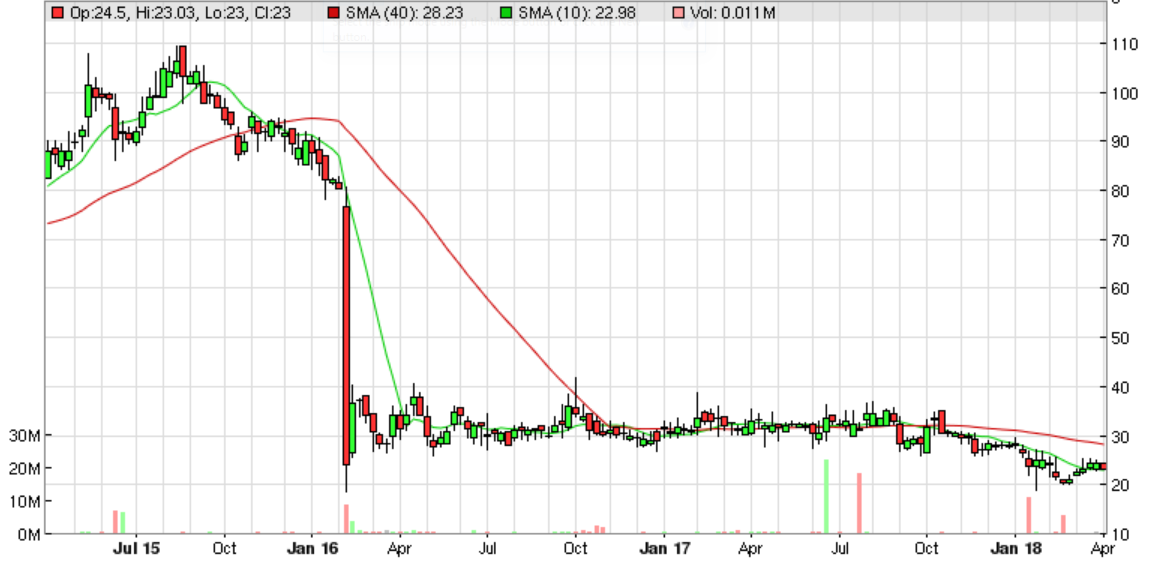
Key shareholder, Phoenix Asset Management Partners supported the fundraising, and had previously tried to buy all of Hornby, in a takeover offer in July 2017, which didn't complete. This is the current major shareholder list (taken from Hornby's website);
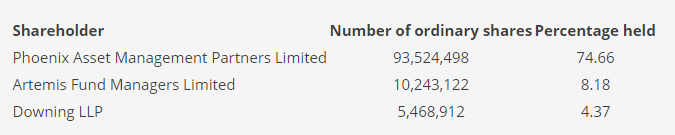
Clearly then, the big issue is what are the intentions of the major shareholder, Phoenix? Could another bid approach from them be forthcoming? I don't like overly dominant shareholdings like this, as minorities are at the mercy of whatever the big shareholder wants to do.
Today the trading update says;
As reported in the January update, the lack of discounting coupled with late deliveries of product has continued to affect our sales rate. There was an improvement in sales towards the end of the financial year as some of the European product started to arrive, but as expected, the Group sales and profits were lower than last year.
Clearly then, there's still some way to go, with this turnaround.
Lending update - this isn't as bad as it sounds, because the company had net cash of £4m at year end of 31 Mar 2018;
The Board has now refined its strategy to enable the business to return to profitability. The investment needed to support this strategy will require a larger facility than the one currently available to the Group.
Hornby is in the final stages of discussions regarding a new financing facility with new lenders and expects to have the facilities in place ahead of the Group's full year results, which are expected to be announced in mid-June 2018.
To support these discussions, the Board has engaged with Barclays and it has been agreed that they will support the Group with a covenant waiver in relation to the Group's EBITDA covenant in respect of the quarter to 31 March 2018, which is required due to the reduced sales volumes.
This covenant waiver sounds purely technical in nature, since the group was in a net cash position.
Outlook;
"As the dust settles on the changes to the strategy and we start to put together the line plans for 2019 and beyond, morale is starting to build in our hardworking staff and some trust is coming back with our retailers and customers; both in the UK and abroad.
Whilst we have managed to make a lot of progress in the first few months, there is still much more to do in terms of reducing costs, streamlining processes and adding routes to market."
My opinion - this is quite an interesting special situation. It seems obvious that the company would have gone bust, were it not for the deep & supportive pockets of its largest shareholder. Minority shareholders are really just along for the ride, and should be very grateful to Phoenix - as indeed should the staff & Directors.
I wish them all well with the turnaround, but it seems to be a company that is still heavily loss-making & cash-burning, with plenty more turnaround work needed to make it viable. The risk for small shareholders is that, if the turnaround works, then the upside could easily be whipped away by the majority shareholder taking it private.
Therefore, I don't see much upside potential on the current share price. Or rather, there's too much risk associated with any potential upside. It's not for me. It's difficult to see why this share is still listed. The only reason I can see to maintain the listing, is to provide Phoenix with an eventual exit, by placing its shares.
There haven't been any divis since 2012, and are not likely to be for some time to come. Note also that the share count has risen more than 3-fold in recent years, so the share price is unlikely to recover fully back to previous levels, unless there's a spectacularly good turnaround in trading.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
By 9.15 the Air Partner (LON:AIR) shares are up about 24% suggesting the market is giving them the benefit of the doubt for now.
Gus.
Update from Air Partner (LON:AIR) this morning on their accounts review.
https://www.investegate.co.uk/air-partner-plc--air-/rns/further-update-on-accounting-review/201804110700045025K/
PWC have been going through the books. Interim finding confirms the “hole” is not more than £4m and that prior to any related adjustments at the conclusion of the review the current trading period numbers are as previously indicated. At face value seems to have ring fenced the issue. Has the knife stopped falling? Remains to be seen if a nervous market gives them the benefit of the doubt.
Gus.
Wow, Air Partner (LON:AIR) just keeps on falling. Always worth reminding yourself about buying in too soon after profit warnings, which can be a temptation. Especially in small caps where it doesn't take much PI selling to move the price massively and not everyone sees the news on day one, which can lead to a continued drift lower.
Watching from the side-lines but wondering when it will be worth catching the falling knife !
I can't help but think this is a serious overreaction. Nothing new has come out since the update, but the price has been clobbered. Perhaps it's a worst case scenario and Air Partner is rotten to the core, but I doubt it.
Yes, glad I got out - I just wonder has it anything to do with Russia sanctions - Perhaps there will be a bit less spending from that area, on private jets. All I could think of.
re Air Partner (LON:AIR) precipitous drop in SP. It's just as well that its aircraft don't fall out of the sky on a trajectory like this!
I too think that the drop is overdone, based on what was contained in the RNS. With some other holdings, I managed to sell at the bottom when the SP was dropping when the company was fundamentally sound; my opportunity cost of missing out on the subsequent recovery was huge. But the question remains: is the SP drop an overreaction, or is there something else going on in Air Partner (LON:AIR) that has not been released?
Note: I have been a holder since 2006, so this isn't the first period of low-flying I have experienced with Air Partner (LON:AIR) . I hope this patch of turbulence doesn't make me sick
Air Partner (LON:AIR) Sell off.
Back2Value and Nicobus
I have held Air Partner (LON:AIR) since October 2012 (I have not sold any in the recent sell off; I thought the first day sell off was overdone, let alone what has happened since) and saw it as a sound well run company, which delivered steady growth and great divis (I have had £4,000 since 2012).
I am struggling to understand the scale of the sell off. I suppose one possibility is that the market is believes that this will cause Air Partner (LON:AIR) customers to lose trust in the company and not renew membership/charter them, or that this is the thin end of the wedge of accounting problems.
But assuming neither of these Stockopedia is showing £4.15m net profit for current year. If Air Partner (LON:AIR) has to restate previous years profits against this then profit for the year will be reduced to £850k. But this will not change the long term profitability to the company or cash flow/ability to pay dividends. (edit according to Torygraph article the company gave guidance of £6.4m on Jan18th, which be an increase of 26.5% on last year https://www.telegraph.co.uk/bu...
That said the lack of information from the company is frustrating and is not likely to engender shareholder loyalty.
So for now I am sitting tight but if the next news out of the company is not unequivocally positive I will sell out (if market conditions permit i.e. the shares aren't suspended).
Further edit the so called "scoop" by Shareprophets at https://www.shareprophets.com/... does not really shed any more light on it.
Michael
Hi Michael
If that piece is true it would explain some of the sell-off - if their internal accounting controls were so weak that they couldn't spot this debt for 8 years then you have to wonder what else was missed. On the face of it this is far from a disaster - essentially they failed to invoice for £3.3 million they should have and presumably they overstated profits at some point. It shouldn't affect current business. If I was a customer I'd be quite happy that they weren't invoicing me ...
No cash has actually left the business - i.e. there's no direct fraud involved - so there isn't a black hole in the books. However, there'll likely be an official investigation and presumably fines levied for misreporting. I wouldn't want to be Deloittes here, this is exactly the thing that auditors are supposed to spot.
Bah, still holding. Still not tempted to top-up.
timarr
Re: AIR PARTNER (LON:AIR)
I held on at UTILITYWISE (LON:UTW) another company that didn't know its deferred income from its elbow. It proved expensive.
It has been a long silence from Air Partner which is not good news. Too many red flags here among the acquisitions.
At least Mr Briffa still looks cheerful - but then he has cause to be:
Thu, 19th October 2017
Mark Briffa, Chief Executive Officer, sold post-exercise 179,935 shares in the company on the 19th October 2017 at a price of 132.46p. The Director now holds 97,511 shares
No position & DYOR.
Bonitabeach
The problem that Utilitywise (LON:UTW) had with its deferred income was obvious to anyone who cared to look at the accounts. The problem with Air Partner (LON:AIR) isn't the business model, it's the financial management. I'm not saying that's less of an issue, but it's comparing apples with eggs, really.
Given the issues if there was a known serious hole in the accounts then the company would have announced and/or suspended. The failure to do either, or make any announcement at all, suggests that the analysis is ongoing but hasn't uncovered anything.
This, of course, may simply be the equivalent of the man falling past the 50th floor window shouting "OK so far" :)
timarr
Hi Matylda
The RNS was confusing particularly re cash impact which reflects either their own confusion or a drip feeding of news. As I dislike confusion I am like you out for now and will just keep under review as and when clarification is forthcoming.
Paul, Phoenix Asset Management have recently rescued Stanley Gibbons (LON:SGI) in a similar way as Hornby (LON:HRN).
Taken over £10m of debt from RBS, with interest accruing for next five years then becoming payable. They also took a 58% shareholding for £6m at 2.5p (current SP has recovered to 4.75p). Although not ideal for existing shareholders, the most likely alternative was liquidation.
Disc: Bought a few as a recovery punt a while back, but approx. 50% down at present. Would be pleased to get investment back, but could be a while !
Re Flybe (LON:FLYB), the share price went up to around 50p and the market is rarely wrong....but on the other hand, Stobart pulled out after having had a good look at the figures. I do think that the company can do better than they have, and they are improving. Whilst I agree that the company cannot be blamed for the weather, if that starts to happen frequently, year by year, then it is a fact to be taken into account in how investors view the business model. Also, if things get a bit tighter for the European market, then the bigger boys - easyJet (LON:EZJ), Ryanair Holdings (LON:RYA) and Wizz Air Holdings (LON:WIZZ) can afford to take deeper cuts than Flybe (LON:FLYB) and we know what happened to other smaller airlines in the last 1-2 years. All IMHO of course and I would like to be argued out of my at best sit on the fence position.
Re Air Partner (LON:AIR) Thanks to Paul, Timarr and jdnthomas for your suggestions on what may have happened here. I did top up earlier at 112.4 giving the company "the benefit of the doubt" but wish I had seen more of the comments above beforehand. I do like the way the company is moving forward and hopefully this only relates to issues 5+years ago. Perhaps we will get a better answer on April 26th when results are due out.
For Air Partners (LON:£AIR) the original accounting entries would presumably have been:
1)
Dr Accounts receivable £3m
Cr Deferred income £3m
This would have been in anticipation that when the cash was received the entries would be
2)
Dr Cash £3m
Cr Accounts receivable £3m
and when the services were performed and thus the income earned the entries would be:
3)
Dr Deferred Income £3m
Cr Revenue £3m
If as soon as they passed the initial entry 1) above they discovered the accounts were not to be collected then I would have thought it would be quite OK simply to reverse entry (1):
4)
Dr Deferred income £3m
Cr Accounts receivable £3m
This is apparently what they did.
If there is a problem it is presumably that they either had already passed some of entry 3 above or that they continued to pass entry 3) (because the systems were set up to do so) after they has decided that the accounts would not be received and the revenue would never be earned. So deferred income would have been understated and revenue overstated. But that should have been picked up on analysing what was in the deferred income account on the balance sheet at the year end. Either it was, and so there should now be no further adjustments to make and everyone can relax, or it was not, which suggests the deferred income balance has never been proven for the last 7 years which would be appalling negligence by both the finance department and the auditors, and raise the possibility of the whole balance being overstated (or even understated) by much larger amounts. (everybody can make mistakes and it is only by analysing the balance between specific (live) contracts that such errors get picked up).
It does seem today’s announcement was rushed out before they really understood the nature of the problem and it may be that the benign scenario is the correct one. But the share price upside is surely limited in the short term - it’s not suddenly going to bounce back to the pre-announcement level. And the alternative is that deferred income could be a whole can of worms, and then the downside would be considerable.
If the share price had dropped 40% then a purchase now might be a reasonable gamble, but at the current price there seems to me to be more possibility of downside than upside in the short term.
But worth keeping an eye on in case it turns to be a storm in a teacup.
Incidentally I find the 2011 announcement (which may be related or may simply involve a coincidentally similar sum) totally incomprehensible.
The Air Partner (LON:AIR) announcement today suggested that the problems go back to 2011 and that a "significant proportion of this relates back to 2011". So I thought I'd have a look back to 2011. The interims back then contain the following:
That happened in the first set of results after the appointment of a new CFO - the one before the current incumbent - and during a change of auditors from Mazars to Deloitte. So one hypothesis is that something screwed up at this point, when presumably they were trying to kitchen sink past problems.
As it stands this doesn't look like a problem, but when the forensic accountants start trawling over the books there's always the chance something else might come out. I hold, but I'm not tempted to add. The Z score here is hovering on the edge of safety, so a degree of caution is indicated.
timarr
Flybe (LON:FLYB) my understanding is the bid was low balled at around 50p, just gossip so take it with a pinch of salt.
I know that Stobart are now restricted from making another bid for 6 months and cannot buy shares for 3 months in Flybe (LON:FLYB)
However, they did state that they reserve the right to set the restriction of rebidding aside in case of a 3rd party making an intention to bid. So could get hostile?
My sketchy number crunching has NAV at around 70p
Air Partner (LON:AIR) Thank you Paul for your analysis though I think the company has not been as clear as I think they could be or should have been.
The question also arises was this deliberate and therefore done to mislead the owners (us the shareholders)?
To me this is basic (I am only part trained accountant having dropped out of Middlesex Poly 35 years ago) accounting and expenses should not have gone through the balance sheet. But maybe somebody can correct me?
So the questions now are:
- can we trust the management, a key for any investment I make?
- should I dump the stock in part, the whole lot or not at all?
- or is it a buying opportunity as the market has over done it?
Tricky.
Sanderson (LON:SND)
Hello Paul,
If you have time, would you please comment on the grant of options to the directors on 29th March? I thought they we overly generous, but perhaps I'm being unfair?
Hi Paul
Any additional comments to add to Graham's ?SOS write up last week? I notice you have a position in it in BMUS.
Not currently a holder but it's on my watchlist!
Hi Ajay,
Re Sosandar (LON:SOS) - I'm perfectly happy with progress to date. This is an early-stage company, so for me it's all about backing management & the concept, both of which I think are excellent.
As regards the numbers, they're in the right ballpark (compared with the Turner Pope note from Aug 2017), although the year end was changed, so we can't directly compare the 9 month figures, with 12 month forecasts.
The operating loss for the 9 month reported figures was a bit higher than I was expecting, but not enough to cause concern. However, revenue is growing nicely (from a start-up), and the gross margin is excellent for such small revenues - suggesting that there's likely to be good upside on gross margin once turnover has risen considerably more.
There's plenty of cash in the bank for anticipated losses in 2018 & 2019, by my reckoning. So it's just a question of sitting back and waiting to see how things develop over the next 2 years. I'm trying to ignore the share price, as it's not relevant to my point of view, as I am treating this as a buy & hold forever situation (providing the growth continues to be strong).
The market has sold off most small caps, especially more speculative stuff, by 30%+ in recent weeks, so SOS has just followed that trend. I don't think the recent share price fall here has anything to do with fundamentals & outlook, which both look positive to me.
Taking a long-term view, if SOS does work out, then this could be a serious multi-bagger. That's why I think it's pretty exciting. Short term, the share price could go up or down, I have no idea!
Regards, Paul.
Air Partner (LON:AIR) - Thanks, much appreciated Paul.
I continue to hold for now in the hope some clarity is forth coming.
Thanks again.
Thanks for that on Air Partner (LON:AIR) - my initial reaction was the same. Recognising bad debts in the balance sheet, rather than expensing immediately though the p&l ought to be just a timing issue. Air Partner (LON:AIR) would have overstated profits in the early years, but eventually the deferred income on the balance sheet would be recognised through the p&l, so current or future profits would be understated if they had kept the same accounting treatment.
Anyway good to have a second opinion (even if it is confirmation bias :-) )
For clarity, I have subsequently decided to sell (as updated on my morning post)...
"My reckoning being the FD probably has to go now which is more bad news and then there's the further investigation to come. If the further investigation is worse, well that's more bad news.
Decided - Better out wishing you were in than in wishing you were out!"
A recent one missed that you have commented on before is PTSG, Paul.
Interestingly difficult accounts to interpret.
Any chance of a backwards look?
Hi apad,
In my opinion, Premier Technical Services (LON:PTSG) looks superficially attractive. However, I don't like the unexplained high debtors, nor do I like the Bob Morton connection. So not one that I plan on revisiting.
Regards, Paul.
Very sad news.
IQE (LON:IQE)
Twitter posting from FT just now.
The chief financial officer of IQE, which supplies chips to Apple, died in a cycling accident while on holiday abroad over the Easter weekend, the British company said on Tuesday.
https://www.ft.com/content/0d768110-3715-11e8-8eee-e06bde01c544
I have been to San Francisco twice. Once in the mid 1990's when it clearly had it's rough'ish areas but was generally free of people living on the streets. I loved the place. On the next visit in 2008 the rough areas had turned into extremely run down areas and there were lots of people on the streets. It sounds like that trend has continued. I wonder if it says something about income distribution in the US? I heard on the radio the other day (Radio 4 I think) that income distribution in the UK is pretty good and this is the first recession (post 2008) where the gap between the rich and poor has actually declined. And the reason for the decline? Changes to the UK tax system to benefit the poorest and lowest earners. Their incomes haven't gone up significantly but the disposable income has risen significantly due to changes in tax thresholds and rates. Probably doesn't help those who are totally outside the working world but its still quite heartening to hear.
Hi dfs12,
Interesting comments. The latest figures from the ONS are quite revealing. This showed that, after taking into account income redistribution through taxes & benefits, the UK has a remarkably low differential between the top & bottom earners.
From memory, the differential between the top quintile & the bottom quintile was only about 4-5 times. This surprised me, as I would have imagined it was over 10 times, but apparently not.
I suppose our perception is different because so much publicity surrounds the super-rich, who are relatively small in number.
Regards, Paul.
Quarterly dividends on AIM? Never !
Diversified Gas & Oil (LON:DGOC) has announced this is what its going to do - which was a surprise this morning. Guess it makes up for taking 4 months to prepare its accounts.
Phil
My morning smallcap tweet:
1Spatial (LON:SPA), Ukrproduct (LON:UKR), Hornby (LON:HRN), Flybe (LON:FLYB), Air Partner (LON:AIR), IG Design (LON:IGR)
1Spatial (SPA) wins £1.6m contract over 5 years. Current T/O is £22m.
UKRproduct Group (UKR) expects to report increased FY revenue and gross margin. An overall loss for the year is expected, due to the negative impact of exchange rate differences. No forecasts.
Hornby (HRN) has stopped shooting itself in the foot after the supply debacle: "some trust is coming back with our retailers and customers." "There was an improvement in sales towards the end of the financial year as some of the European product started to arrive, but as expected, the Group sales and profits were lower than last year." Seeking a larger financing facility with new lender. Barclays gives covenant waiver. "Whilst we have managed to make a lot of progress in the first few months, there is still much more to do in terms of reducing costs, streamlining processes and adding routes to market."
Flybe Group (FLYB) Q4 load factors were up by 6.8 ppts to 73.5%. But weather in February and March led to airport closures and flight cancellations. Estimates hit of £4m rev inc. additional care and assistance costs. Very early indications of summer trading encouraging.
Air Partner (AIR) has overstated profit in last 8 years by failing to account for bad debts correctly. "Principally relates to the collection of receivables from customers and accounting for uncollected amounts since financial year 2010/11. Certain uncollected receivables were inappropriately offset against deferred income rather than being expensed to the income statement in the appropriate financial year. This is a non-cash item and has no bearing on the Company's cash balances." Total £3.3m. "At no point was a customer, operator or supplier impacted or disadvantaged. Further, the Group continues to maintain a strong net cash position."
IG Design Group (IGR) sells property for £2.5m for a gain of £1.1 - £1.3m.
Morning Paul!
Welcome back, hope the trip was great.
Is there any chance you could put the Air Partner (LON:AIR) update into plain English ?
Year End Update – My initial thought is it's some kind of accounting balls up to the tune of £3.3m. The last Trading Update For The 12 Months To End January 2018 mentioned expectations of PBT of at least £6.4m. Does this mean PBT will be halved?
Would be much appreciated - I hold at present.
On air partners is it bound not to have a cash flow impact as deferred income by definition represents monies already received but where services are to be provided in the future. On the other hand debtors represent cash that is expected to be received in the future but which will not if the debt is bad.
Hi Paul,
Not a question I am qualified to answer and way above my simple standing (perhaps others more qualified can comment). The price action seems to be indicating an impact at present so I am happy being out for now.