Small Cap Value Report (Tue 3 Jan 2023) - HOTC, BIDS, APTA, CINE

Good morning from Paul & Graham, and a very happy new year!
There's little news today, so Graham's going to be writing a year end roundup type section today, and I might cover something similar but not overlapping. So we should have something interesting up by 13:00. Leave it with us!
Agenda
Paul’s Section:
Hotel Chocolat (LON:HOTC) (156p pre-market, mkt cap £214m) [quick comment] - we had previously been told that HOTC was trying to salvage something from its disastrous Japanese joint venture. A new arrangement for 21 Japanese stores is announced today, with HOTC owning a reduced 20% stake, but set to receive brand royalty revenues (not specified at what rate). There’s not enough information for me to assess how good this deal is, but anything is better than what looked previously like it might be a total write-off. As yet, there doesn’t seem to be any information from brokers. I reviewed its FY 6/2022 results here, and remain of the view that the investment story looks stale, the product tastes completely ordinary to me (and seems overpriced), and aggressive forecast profit growth for FY 6/2024 and beyond doesn’t look credible. Which leaves us with a share that’s probably over-priced, and vulnerable to more profit warnings in the current climate. Solvency/liquidity look fine though, with a sturdy balance sheet. For me, overall it’s an avoid, based on current information. (no section below)
Bidstack (LON:BIDS) (2.8p pre-market, mkt cap £36m) [quick comment] - another worrying announcement from this speculative, jam tomorrow, in-game advertising company. There were previous signs that its key relationship with partner Azerion was going wrong. Today we’re told it’s now become a legal dispute, with Azerion withholding payment for invoices from BIDS, and terminating the agreement. This is clearly a major blow for BIDS, however they try to gloss over it today. The interim accounts commentary showed how significant this $30m 2-year deal was for a company with previously negligible revenues. Without it, BIDS shares look too high risk, as it looks like the wheels are coming off. I don’t imagine FY 12/2022 results will be out any time soon, due to disputed invoicing, and how long will the last £10m fundraise keep it funded for? I’d vigorously avoid this share now, to be on the safe side, and salvage whatever you can. (no section below)
Here's the link to my New Years Eve podcast. As usual it was a run through the SCVRs, and also some wider thoughts about the market generally. I see a lot of small caps being very attractively priced right now, so am long-term bullish for decent companies on bombed out valuations. Shorter term? Who knows? It looks like a minefield of profit warnings, and also dilution/solvency issues for companies with too much debt, and/or cash burning junk that needs to raise more cash, so it's very clear what we should be avoiding in the meantime. There's one mystery share, my best idea for the week, which is a micro cap special situation called Rotala (LON:ROL) which I covered here on Weds 28 Dec. It needs deeper research, but the refinancing from sale of a large freehold has greatly improved its financial position. Very small and illiquid though, with a wide bid/offer spread, so this one will only appeal to special situations micro caps investors.
Aptamer (LON:APTA) (47p, down 8% - mkt cap £32m) [quick comment] - a life sciences business that floated in Dec 2021, raising £9.6m. Lost £(2.6)m PBT on £4.0m revenues for FY 6/2022. Today it says H1 (to Dec 2022) is only £1.0m revenues, and with expanded overheads, I expect to see cash considerably depleted from the £6.7m held at 6/2022. Says bullish things about the outlook for H2, but I reckon there’s not enough cash headroom to make this a safe investment. Very concentrated shareholder register, with little market liquidity. I’d steer clear of this, as risk:reward strikes me as unappealing at this stage.
Cineworld (LON:CINE) (3.4p - mkt cap £46m) [quick comment] - the extended death of this company continues. It's obviously bust, with a vast debt pile, created by reckless acquisitions. I don't understand how the shares continue to trade, despite the company repeatedly telling the market that there's little to no value in the shares, as it confirms today - "As previously announced, it is expected that any restructuring or sale transaction agreed with stakeholders will result in a very significant dilution of existing equity interests in Cineworld and there is no guarantee of any recovery for holders of Cineworld's existing equity interests." It looks to be an almost certain 0p in my view, so people gambling with the shares now are taking on a lot of risk.
Graham's Section:
Year-end review of Indices - see section below.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Graham’s Section:
Index Review
Good morning, and Happy New Year!
Today, since there isn’t much company news to cover, I’d like to give you an overview of some of the most relevant UK stock indexes: their performance in 2022, their current valuations, and their top components. Hopefully we’ll be able to draw some useful conclusions when we’re done!
Let’s start with the AIM All Share Index (AXX), since it includes so many of the small companies which we cover in the Small-Cap Value Report.
AIM All Share Index (AXX)

Price change in 2022: minus 32%
Components above their 200-day moving average: 26%

Largest components:
HUTCHMED (China) (LON:HCM)
Keywords Studios (LON:KWS)
Jet2 (LON:JET2)
RWS Holdings (LON:RWS)
Burford Capital (LON:BUR)
An unusual feature of this index is that it has a very long tail of tiny companies, so it can sometimes feel like there is a mismatch between the average performance of an AIM stock and the performance of the index as a whole, whose performance is guided by its largest components.
But this index fell 32% in 2022 and that seems to resonate, unfortunately, with the performance of many AIM portfolios held by private investors.
What I find surprising is that its median trailing P/E ratio is still in the mid-teens at 16.6x, according to the IndexReport. After a 32% fall, I would love to see a very cheap trailing P/E ratio on offer, to give me confidence that the index has fallen into value territory.
More positively, the median forward P/E ratio is only 12.7x, and forecast EPS growth is strong at 15%.
Is that unrealistic? Probably - analyst earnings forecasts do tend to overshoot in terms of optimism. Any EPS increase at all for AIM stocks in 2023 would, I am sure, do wonders for sentiment and for this index.
The companies in this index are some of the most sensitive to economic conditions: many of them are effectively binary bets on success or failure, and their smaller, weaker balance sheets make them especially vulnerable to difficult financing conditions. 2022 saw the IPO market close up completely and placings were also much more limited, compared to prior years. Companies needing cash had few places to turn.
So where do we go from here? As usual, I expect that the AIM Index as a whole will, on average, perform poorly compared to other indexes. This is a structural issue: AIM simply has too many poor-quality companies to do well. Think of the junior miners and all of the blue-sky enterprises, many of which eventually wind up worthless.
That makes AIM a stockpicker’s market requiring individual stock selection and I do expect we have now reached a point where many of its quality and value shares are severely undervalued. We have talked about many of these candidates in this report. Sorting the wheat from the chaff, and having the patience to wait for recovery, as always, is the challenge.
Smallcap Ex Investment Trusts Index (SMXX)
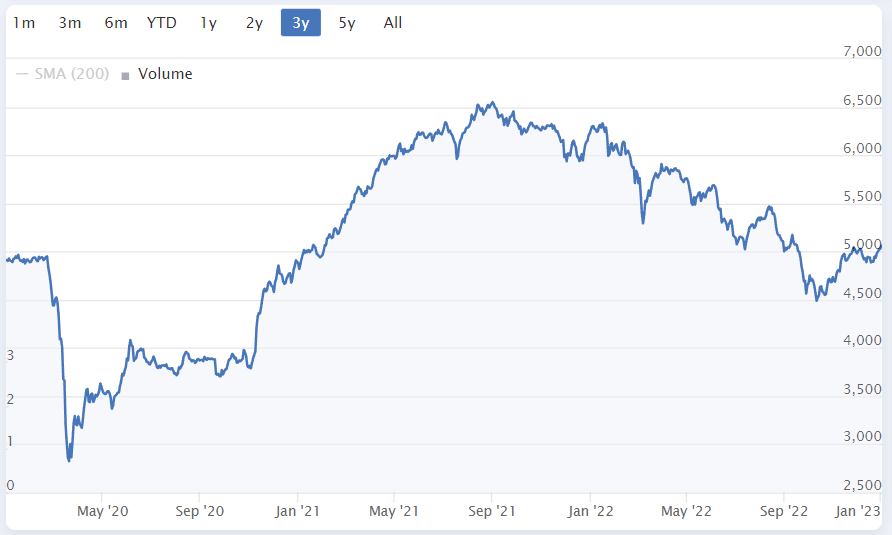
Price change in 2022: minus 20%
Components above their 200-day moving average: 30%
Largest components:
Fuller Smith & Turner (LON:FSTA)
A G Barr (LON:BAG)
Keller (LON:KLR)
Bakkavor (LON:BAKK)
Hunting (LON:HTG)
The performance numbers above show that this index performed significantly better than the AIM All-Share.
That shouldn’t be too surprising: this index consists of much safer, more “respectable” and well-known companies, who tend to have stronger balance sheets and more financing and strategic options than their AIM brethren.
It includes some ambitious small companies who want access to the larger pool of institutional investors on the main market. It also includes some larger companies who, perhaps temporarily, have fallen on hard times and fallen out of the FTSE-250 Index. The market caps in this index range from £30m up to around £600-700m.
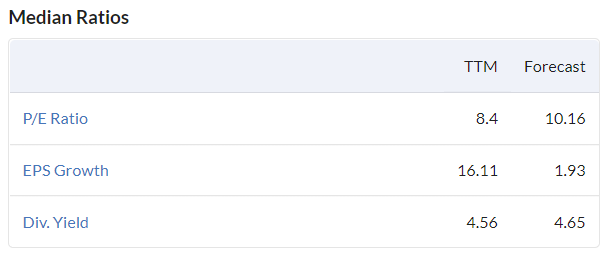
Valuation: the trailing (8.4x) and forecast (10.16x) median P/E ratios here jump out at me, screaming value!
Scrolling through the list, I see that many of the cheapest stocks are financials and property stocks, and of course there are good arguments to be made that the outlook for lenders and for the property sector are bleak. There is almost no EPS growth pencilled in for this index in 2023.
As a contrarian and a value investor, however, I can’t help but think that a trailing P/E ratio of only 8x for this entire index may be excessively pessimistic, for long-term investors, and that many of the components here are likely to be undervalued. This has always been one of my favourite indexes, and I like the pricing it offers here. Note that the dividend yield is also very chunky, and in value territory, at 4.6%.
FTSE 250 Index (MCX)
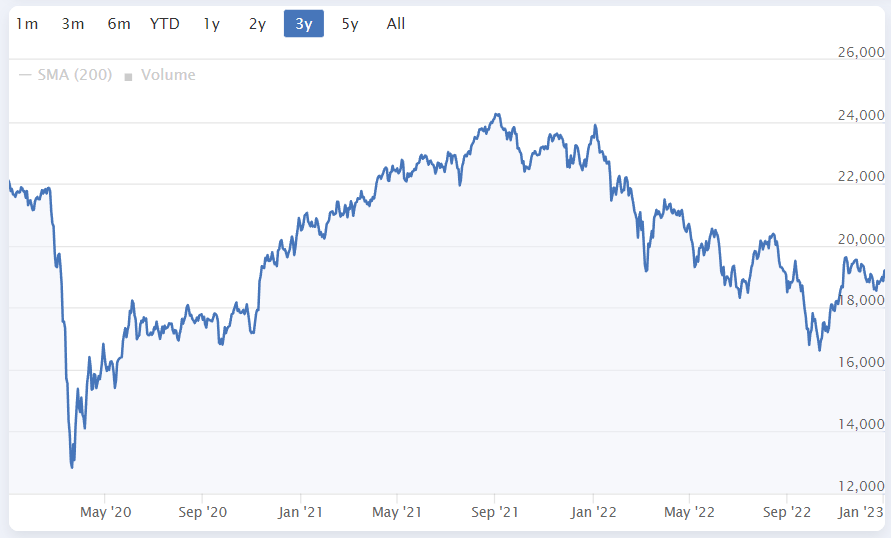
Price change in 2022: minus 20%
Components above their 200-day moving average: 39%

Largest components:
Carnival (LON:CCL)
Investec (LON:INVP)
Beazley (LON:BEZ)
Weir (LON:WEIR)
Johnson Matthey (LON:JMAT)
We are firmly in mid-cap territory with this index. This index includes some large global companies, including some that are leaders in their specific niche.
As with the small-cap index, this one significantly outperformed AIM in 2022.
Also, I note this index is showing signs of broad stabilisation with 39% of components currently trading above their 200-day moving average.
Valuation: this one is not offering the same low P/E ratio as the small-cap index SMXX, which I expect is fair since there are many excellent and unique stocks included here: think of the likes of PZ Cussons (LON:PZC) and Cranswick (LON:CWK) and Games Workshop (LON:GAW) .
At a forecast P/E ratio of 13x, for a quality index, I think this also looks very interesting.
Consistent with offering more quality and less value than the small-cap index SMXX, this offers higher forecast EPS growth (5% instead of 2%) and a lower dividend yield (4% instead of 4.6%).
So for investors who are willing to pay a slightly higher earnings multiple, and accept a lower yield, this index probably offers a safer and better set of companies in which to invest.
FTSE 100 Index (UKX)

Price change in 2022: plus 1%
Components above their 200-day moving average: 49%

Largest components:
AstraZeneca (LON:AZN)
Shell (LON:SHEL)
Unilever (LON:ULVR)
HSBC Holdings (LON:HSBA)
Rio Tinto (LON:RIO)
Wow! As Ed noted in his latest New Year NAPS article, 2022 was a year in which UK stocks seemed to perform better, the bigger they were. And the largest stocks performed best of all.
FTSE-100 Investors finished 2022 higher than they started it, and also collected the dividends for which this index is famous.
AstraZeneca had a good year, with strong contributions expected from its cancer and diabetes drugs.
The large banking groups muddled through a period of rising interest rates.
And large resource companies did very well as broad inflation saw many commodity prices increasing. Oil and gas producer Shell is back near the top of the FTSE-100 league.
Valuation: after a year of sturdy performance, the forecast P/E ratio here is steady at 13x.
This index is seen as low-quality by many investors - myself included - but perhaps we should give it more respect? It trounced many other indexes and asset classes in 2022, proving its worth as a defensive basket of stocks.
I would still expect the FTSE-250 and other indexes to outperform it over longer time periods, but perhaps the FTSE-100 remains an attractive asset for risk-averse investors who still want some equity exposure.
Conclusions
In summary, I think this analysis helps to prove what an unusual year 2022 was. It was very much “risk-off” with the largest companies holding up well and the smallest companies struggling badly.
Even the “quality” small companies performed badly in 2022, but I think this may now provide opportunities in both the Smallcap and FTSE-250 indexes, where valuation multiples and dividend yields have in many, many cases fallen into value territory, especially in small-caps.
There are also undoubtedly opportunities in AIM too, but the large concentration of low-quality companies there makes it harder to discern that from the index metrics.
Of course the more pessimistic you are on the economy, the less enthused you’ll be by the value on offer. Investing is at the end of the day a matter of opinion, as it concerns the future and the future is uncertain! But I hope this article has helped to clarify some of the big-picture issues for you, and leave you with some hope that 2023 performance could be significantly better! Cheers.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
Happy new year Paul and Graham and all readers too.
Andrew
Thanks Andrew. Happy New Year to you too! G
Thankyou Graham an interesting overall take. In normal years I measure myself to AIM as I like to think I am an ace stock picker!! (Ha ha ha). But at the beginning of 2022 I just felt it was going to be more complex this year for a number of reasons which I won't waste time on now. But ended up shorting 10 year gilts and buying an index linked gilt for the first time in my life. (Putting aside the NS&I Index linked certificates which you can no longer buy but when you can grab em!!) I am about 30% cash now as well. Also invested 10% in Ruffer Absolute return fund and Gold. It left me about 30% in Avacta, Spectra Systems, SRT Marine, Rolls Royce and Record. Anyway 3% down on the year which adding inflation is a double figures loss, but it could have been a lot worse. It is interesting in investing you can sometimes make one decision at the asset allocation level and it is more important than all your stock selection decisions. Diversification works on many levels. Anyway all the best to you all and to be honest I am far more nervous about this year because I simply have no idea what is going to happen in the year ahead. I know I never do, but sometimes I think I do.
Wow, well done Camtab! Some serious outperformance there compared to what could have happened. Congrats. G
Graham,
At a forecast P/E ratio of 13x, for a quality index, I think this also looks very interesting.
IMO you have to be very careful looking at the FTSE250 index in these terms. Yes, it contains some good companies but it also contains 77 Closed End/Investment Trusts and 21 REITs. How on earth you can meaningfully calculate a P/E for the index given 40% of the constituents are not "normal" operating companies, is beyond me.
All the best, Si
Thanks Si - good point.
Please see my previous comments on HOTC when I said it was insanely overpriced at 400+p. It's still overpriced: poor product (and I make chocolate so I know !), saturated market in the UK in a falling "luxury goods" market, failed Japanese and US expansion. For chocolate makers and retailers, everything depends on ability to sell in the USA and Japan/China. Without this, HOTC is just another high street shop with a poor product.
I wonder if a large part of the forecasts for Hotel Chocolat (LON:HOTC) are in their velvetiser range, which they are maketing quite hard. Popped in a shop towards xmas and the machine is knocked down from over £200 to about £90..
I reckon they will warn on profits this year.
I totally agree with all that hotel choc chocs are awful! I'd rather take a twix any day. Or a Freddo. In 2020 after a hip op I got boxfuls of sympathy Hotel C chocs from friends. Hampers and hampers of the stuff. I could have opened my own Hotel C pop up shop. My son and Mrs didn't like them either. Nor did our 80-year-old neighbour who prefers the inside of creme eggs as she only has three teeth left. We stuffed the cupboards with them. Then came Xmas. Loads more arrived.
Just when we thought there wouldn't be any more a package arrived from Marriott Hotels on Xmas Eve thanking me for all the business. Guess what? More Hotel C. Finally that afternoon a package from my publisher. Yep, you guessed it. Two larder shelves were now packed with HC.
Worse, I had a short in HC on the silly valuation grounds. But after all the deliveries I thought "Bloody hell they must be selling s-loads!". I closed the short - what a mistake!
We spent the next year re-gifting. And handing them out to anyone we could find, postman, delivery drivers, anyone that came to the door. "Thanks a lot, have some chocolate on us!" T
Five months later we had cleared them all. I worried about my birthday and Xmas in 2021 and getting more HC. As I'm a terrible people pleaser I didn't want to upset friends and say "no more HC". But the mrs came up with a plan and I sent a round robin message saying I was ordered to give up chocolate on health grounds. This worked but I now have 25 packs of salted caramel biscuits.
From time to time I have ranted about how micro cap prices are ludicrously adjusted for ridiculously small sells, so it’s only fair to note one going the other way.
Crimson Tide (LON:TIDE) (I hold, no sniggering please) today is showing a 4.2% rise on a purchase of 200 shares - an amount of £5 ! So for a fiver someone has increased the market cap by over £600,000. Crazy
Crimson Tide (LON:TIDE) Are you going by Stockopedia figures? If so, don't, they go on the last trade which was a buy. My broker with live prices has this as a non mover. If someone sells then will probably be negative on Stockopedia. This is really annoying.
Thanks for the review Graham. I keep telling myself that finishing less than 20% down in 2022 was a pretty good result. I finished down 19.1%, so I am going to keep telling myself that! Without Boohoo (LON:BOO) Tremor International (LON:TRMR) and Reach (LON:RCH) I would have had a reasonable year, probably in the region of negative 2% or 3%. Unfortunately I held them and still do except £BOO.
Q4 was a very kind to me with above 20% gains in Games Workshop (LON:GAW) Anglo Asian Mining (LON:AAZ) Reach (LON:RCH) Bioventix (LON:BVXP) Netflix (NSQ:NFLX) (very small holding) Sylvania Platinum (LON:SLP. These represent 56% of the portfolio. So I am glad I did what did and sat tight, looked little and barely traded. If I had been “clever” enough to sell at the beginning of April would I have been clever enough to get back in at the beginning of October. I doubt it.
Who knows what 2023 will bring. It seems that almost every commentator from Mr Roubini (I am not a fan) down, is full of doom and gloom on whatever front you look (recession, inflation, interest rates, Ukraine war, gas prices, climate change, etc etc etc) so maybe markets will get a nice surprise to the upside.
Here’s to a good 2023.
Regards
Michael
Happy New Year Paul & Graham. Nice sign off to 2022 on your last podcast Paul.
Happy new year Paul and Graham. Thank you very much for all your insight during 2022. I was a bit less active on here last year as I was really busy with work, which made your contributions even more valuable for helping me to keep abreast of small caps and macro-level economic news.
For lessons learnt and community sharing I thought I'd post my lessons from 2022 and 2023 look ahead which I compiled over the Christmas period.
2022 lessons:
I ended the year -14% which was my worst performance since investing in 2014. I know lots of others have had worse results than that so won't complain too much but it's still frustrating especially when you spend time and energy managing your portfolio and researching. Since investing in 2014 my cumulative gain is 142.67% (though last year I was at 182%) and average annual performance is 11.37% - although again last year's performance was such that I was over 14% average. Hopefully 2023 improves that!
Lessons from 2022:
So what about my strategy for 2023?
I feel reasonably positive about 2023 as markets usually bounce back and I think inflation will start to come down which will drive positive market reaction. At this moment in time I am positive on:
I still feel negative about retailers and similar cyclicals. I think their worst results are yet to come and so plan to stay out of them for Q1 but think Spring might be a good time to re-invest given markets tend to anticipate news and work 6+ months ahead. However, maybe I will be too late - this winter has been largely quite mild so far so that's surely good for reducing energy demand and therefore inflation?
Would love to know others' thoughts on what you're positive on for 2023! Happy new year and I look forward to continuing to read this fantastic SCVR and making a contribution where I can.
ps. I am on Twitter as @InvestTortoise if there are any other investors active on Twitter
Thanks for a useful analysis of your performance.
My own losses on my SIPP stand at 12.58% excluding pension income taken. I have made virtually no trading decisions this year.
My more significant holdings above 3% of the portfolio are:
Begbies Traynor, BHP, H&T Group, Northgate and Somero.
A further layer above 2% consist of:
CLIG, IG Group, Plus550, Sylvania Platinum, Wisdom Tree Physical Gold, and Wynnstay Group.
Like MichaelFBS I should have done better not to have held BOO and Tremor throughout the year. Nor has Saga done me any favours. A number of takeovers and fixed interest (Inflation indexed) provided a cash influx that has not yet been invested.
Ironically I have a momentum investment screen that had I followed it I should have done much better.
What is more depressing is to contemplate one’s losses of capital against any of the cost of living indices that nearly doubles my losses in percentage terms although over a three year period my returns merely return to track the RPI index from having been comfortably above it.
Anyone notice the interesting announcement from Bank of Georgia (LON:BGEO)? Appears to be one off and no share price reaction which is probably right. But it is large ($137m gain). Just wondering if there are any other legal claims still to be resolved?
£NYCT Novacyt Anyone aware of the reason for the 40% jump in the last two trading days? No RNS's that I can see
Combination of supposed new C19 variants out of China, the announcements of testing required of people from China into certain countries, the recent approval of new tests for new strains means they are best placed if C19 causes havoc again. It's also listed on French stock market and what we see now is what happened on their market recently due to them being ahead and trading when we were closed.
Galiford Try (GFRD)
Anyone holding or any feedback .
Been looking over it and looks a good company literally stuffed with cash (has more cash than market cap ).
Tiny margins but makes profits and pays dividends .
Am I missing anything other than sector negativity ?
It is a good company I'd say now, with a very strong management team, who have very strict risk criteria in assessing new bids. Formally it had built up a lot of debt having been engaged on a number of projects that went south and left it struggling and had to sell of some of its business, eg Linden Homes, to maintain solvency.
I think it's incredible it trades at a discount to cash, but it has done for some while. That looks to be driven my negative sentiment rather than business strength. One of my bigger holdings, as the downside now looks marginal, the dividends are attractive, and if sentiment changes then a re-rate is long overdue. I've held this shares since the early days when it was Try, but added over the last few years on that cash underpin basis.
I added it to my watchlist recently for the reasons you state above, however one concern i have is the working capital / liquidity situation (negative). Although they should be able to take on more long term debt (they have none/little currently) to solve the problem if needs be.
I've put it in my list to do more research on because I'm always a bit wary of companies that fly close to the wind with their balance sheets.
Agree with Paul about the taste of Hotel Chocolat (LON:HOTC) chocolate, Way overpriced too and not a patch on the delicious and cheap Moser Roth chocolate available in Aldi. E.g if still on their shelves, the Moser Roth Dark Selection Box at just £4.99 really does match the description of “an indulgent selection of filled dark chocolate made with Belgian chocolate.”
We’ve bought and enjoyed luxury Belgian chocolate in Belgium but the Aldi dark selection is every bit as good for a fraction of the price, as are their individual chocolate bars.
I have never tried Hotel Chocolat (LON:HOTC) chocolate but I used to have Aldi Mosser Dark chocolate, I thought it was quite good but it had a high sugar content, I don't know how it compares with others.
£RBGP Good to see that Robert Parker has gone as CFO and surrendered the 1 million nil cost options he was inexplicably given less than a year ago.
RBG holdings
Sorry todays announcement made me smile .
So much for the free share options that were given to the FD just for turning up to work.
Just goes to show that this daylight robbery from shareholders was not the incentive that some even considered acceptable .
I’m sure the incoming CFO will have a similar package in due course but with a bit of luck at least they might be at market rate .
Happy New Year and the best of Luck for 2023!
Interesting read...available on AJ Bell News feed for free.
Deloitte analyst Ian Stewart said: ‘The most aggressive tightening of monetary policy in more than 30 years is reshaping corporate attitudes to debt. Not since the credit crunch have CFOs rated debt as being less attractive as a source of finance for their businesses than they do today. When interest rates were at very low levels, debt finance easily eclipsed equity as a source of finance. CFOs now see them as being roughly on par.’
The survey features a panel of 53 CFOs, 17 from FTSE 100 constituents and 32 from the FTSE 250. Together, the firms they represent are worth £363 billion, some 15% of the UK quoted equity market.
By Eric Cunha, Alliance News news editor
Morning Paul and Graham, I'm interested to see that Hotel Chocolat (LON:HOTC) has resuscitated operations in Japan. Paul wasn't blown away by his mystery shop but as I remain a holder here I'm hoping you have time for a quick comment - especially if you you have a view on todays RNS in light of board changes that were announced in December.
(edit) I have just seen your QC above - thank you
Japan is where many Western companies slip up, thinking they can do the same business model there which worked so well in Western countries. So I am encouraged that Hotel Chocolat (LON:HOTC) has now gone the licensing route, allowing a local player to do all the strategy and execution. Could be big, if they crack it. Its a huge economy in terms of consumer consumption.
My morning smallcap tweet: New Year, New Fear
Aptamer (LON:APTA) MGC Pharmaceuticals (LON:MXC) RBG Holdings (LON:RBGP) Hotel Chocolat (LON:HOTC) Cineworld (LON:CINE) Bidstack (LON:BIDS) Genincode (LON:GENI) ReNeuron (LON:RENE)
◄Aptamer (APTA)► warns FY-June may fall below market expectations, after slow H1. Guides H1 rev c.£1m due to customer delays and general economic conditions. £1 of current signed orders going into H2, "as well as contracts in negotiation and strong expressions of interest across all three business units". [SP=52 Cap=35m]
◄MGC Pharmaceuticals (MXC)► further cost reductions: ~35% reduction in director fees; key executive officer team take 1-20% pay cut. [SP=0.6 Cap=38m]
◄RBG Holdings (RBGP)► FD scarpers "to pursue other interests but will remain as an adviser to the Group for a short period". He is thanked. New FD appointed. [SP=65.03 Cap=61m]. I hold.
◄Hotel Chocolat (HOTC)► strategic partnership agreement with Tokyo-based Eat Creator. "Eat Creator will be providing growth capital, new supply side know-how and proven expertise in food brand development for the Japanese consume." HOTC to have 20% of JC and get 'brand royalty' rev. [SP=158 Cap=217m]
◄Cineworld (CINE)► chaper 11 update. Will focus on selling the Group as a whole. "Any sale transaction for the Group as a whole would not include the sale of Cineworld itself." Huh? Reminds that there is no guarantee of any recovery for shareholders. [SP=3.64 Cap=50m]. I'm short.
◄Bidstack (BIDS)► co suing client Azerion for payment. Azerion has sent a notice of termination. "Bidstack has improving visibility of FY23 revenue and the Board is pleased with the Company's significant commercial progress independent of the Azerion relationship." [SP=2.77 Cap=36m]
◄GENinCode (GENI)► California state licensing approval and CLIA certification of its Irvine lab "enabling the provision of its products for the risk assessment of CVD to patients across 49 states in the United States....marks a major milestone in the commercialisation of the Company's 'first in class' polygenic CVD products CARDIO inCode". [SP=7.43 Cap=7m]
◄ReNeuron (RENE)► CEO scarpers. She is thanked. [SP=8.79 Cap=5m]
You're a braver man than me still holding onto RBGP - I cracked when they lost the 2 cases.....