Small Cap Value Report (Tue 3 Sep 2019) - SYN, XAR, SOLI, MBH

Good morning, it's Paul here.
Estimated timings today - late morning start time, should be finished by mid to late afternoon.
Synnovia (LON:SYN)
Share price: 122.5p (up 40% today, at 10:57)
No. shares: 39.0m
Market cap: £47.8m
This small group was previously called Plastics Capital.
There's an agreed takeover bid announced today, at 125p in cash. That's a healthy 42.9% premium to the share price on the "last practicable date". This phrase is used 29 times in the announcement. At the end, in the definitions section, we are told that the last practicable date is yesterday. They could have saved a lot of ink.
The bidder is a Californian investment group, so here's another example of American investors finding UK listed companies attractive bid targets, due to the weak pound no doubt.
This looks a done deal, with 57.7% of shares already lined up to support the bid.
In my view this looks a fair price. Synnovia was going nowhere as a listed company, in my view. Cash generation was poor, hence it was not able to generate enough cashflow to both pay divis and fund acquisitions. I agree with the announcement today, that the group would be better off being privately owned, rather than being an illiquid listed company.
Well done to shareholders, this is a good deal, at a fair price.
Xaar (LON:XAR)
Share price: 64p (down 27% today, at 11:16)
No. shares: 78.2m
Market cap: £50.0m
Trading update (profit warning)
Bad news from this advanced printheads maker;
Revenue in the first half year to 30 June 2019 was £22.5 million, as previously announced, including the impact of a £4.3 million revenue reversal relating to Xaar 1201 Thin Film printhead inventory being returned to the business.
As part of the interim results process, a review of the Group's holding of Xaar 1201 printhead inventory and near term prospects for sale has taken place which has resulted in a reassessment of realisable value. We now consider it prudent to make a provision of £5.7 million which will be reflected in our first half results.
Trading in H2 is also set to be poor;
Trading for the remainder of the year is expected to be weaker than previously anticipated. This is principally due to lower sales volumes of Xaar 1201 and Xaar 2001 printheads as a result of slower than expected new printer installs by OEMs and credit and sales channel issues on Xaar 1201. As a result, the Board now expects sales in the second half of the year to be similar to those in the first half.
Forecasts - there is a one-page update note available on Research Tree, but it says that forecasts won't be revised until the interim results are available at the end of Sept.
Looking at the existing (now outdated) forecast for FY 12/2019, it pencilled in revenues of £63.3m, and an adjusted pre-tax loss of -£10.6m.
Revenues are now set to be a lower, at c.£45m (H1 revenues of £22.5m times two). Who knows where that would leave losses? Allowing for the £5.7m inventories provision, plus operational gearing in reverse, Xaar must be heading for a loss of perhaps £20m or more in 2019, at a rough guess?
Net cash - at 30 June 2019 was £21.6m, which suggests there is some breathing space for maybe another year of survival?
Interim results - delayed from 10 Sept to 26 Sept.
My opinion - this situation is looking worrying. Is there a viable business here any more? I'd say the jury is out. As regards solvency, it had a very strong balance sheet when last reported at 31 Dec 2018. Therefore I think management has some time to fix things - further restructuring, and maybe a disposal of some or all of the group?
With no earnings now, it's very difficult to value this share.
Solid State (LON:SOLI)
Share price: 485p (up 13% today, at 11:39)
No. shares: 8.5m
Market cap: £41.2m
Solid State plc (AIM: SOLI), the AIM listed manufacturer of computing, power and communications products, and value added distributor of electronic components...
As the +13% share price movement today suggests, this update is a positive one (relating to FY 03/2020);
... is pleased to announce a positive trading update.
As a result of a strong start to the year, the Board is confident that profits for the year ending 31 March 2020 will be significantly ahead of expectations.
Revenue for the year is expected to be in line with current consensus forecasts, albeit the Directors consider there may be opportunities to generate further incremental sales later in the year...
Trading in the first four months of the year has been very strong and is well ahead of budget.
Generally, revenues across the Group have been in line with management's expectations however there has been an acceleration of certain project work into H1 that had been expected in H2 which will benefit reported revenue and profits in H1.
It's usually the other way around with many companies, of work slipping from H1 into H2, so it's great to see a company that is achieving positive timing.
As revenues are in line, but profits are "well ahead" of budget, then clearly margins have improved, as explained;
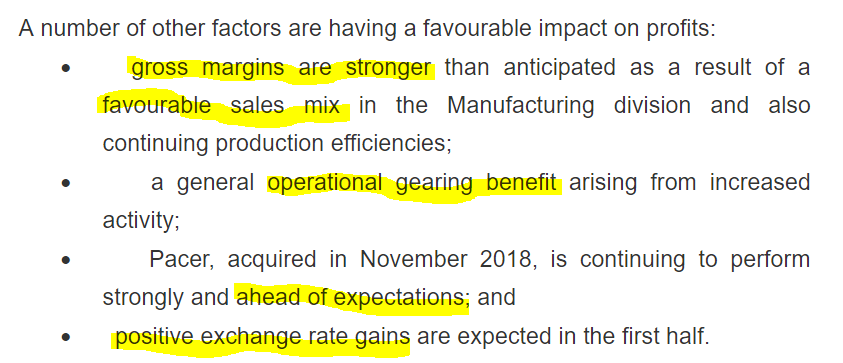
Forecasts - there's an update note out today. Forecast EPS for FY 03/2020 has been increased by nearly 14%, to 41.5p (LY adj EPS was 35.9p). This gives a PER of 11.7
My opinion - given that the group is performing well (this is one in a series of forecast upgrades), and that it has a decent balance sheet with not much debt, then I think this share still looks good value, even after today's share price rise.
Weak sterling should be a significant benefit for export sales.
I'm not sure that this sector is something I'd want to invest in, as the share price tends to go through good patches, then slips back down again. This reflects the project nature of some work - i.e. lack of recurring revenues.
Still, whatever those concerns, the group seems to be humming along nicely.
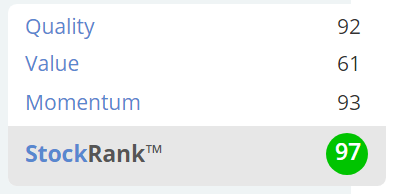
Stockopedia likes it;
Michelmersh Brick Holdings (LON:MBH)
Share price: 92.5p (up 6% today, at 12:26)
No. shares: 92.5m
Market cap: £85.6m
Michelmersh Brick Holdings Plc (AIM:MBH), the specialist brick manufacturer, is pleased to report its half year results for the six months ended 30 June 2019.
These figures look good, and with a positive outlook too.
Take your pick from the highlights below -
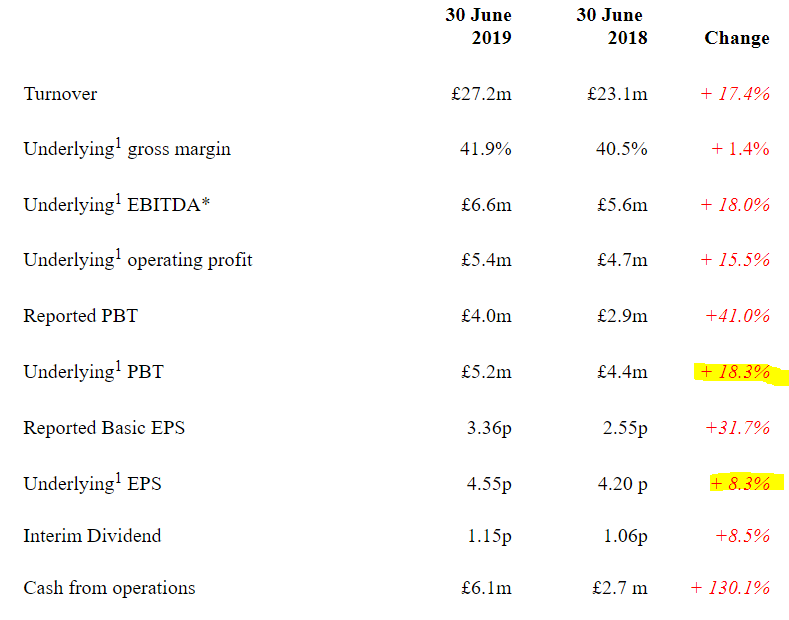
Note the yellow highlighter I've added above. Adjusted EPS growth is lower at +8.3%, than underlying profit growth of +18.3%. This suggests that either the tax charge is much higher (as EPS is post-tax), and/or that the share count might have risen. Yes, there was a placing of 5.56m shares at 90p in Feb 2019 to fund an acquisition in Belgium.
The adjustments to profit look reasonable to me.
Outlook - sounds good -
Following a very strong first half in 2019, and with a robust order book, Michelmersh can look forward to steady trading for the remainder of the year. Stocks across the industry remain at historically low levels and the volume of imported products are increasing.
The Group's performance in the first half of 2019 has continued into the second half and, with the positive backdrop to our markets, the Board expects to exceed market expectations for the full year.
There's more commentary on the sector, which I won't repeat here.
Balance sheet - looks good to me. There's some debt, but substantial property assets too, so not a concern.
There doesn't seem to be a pension fund, which is good news for shareholders.
Forecasts - unfortunately, I can't find any forecasts, updated or not.
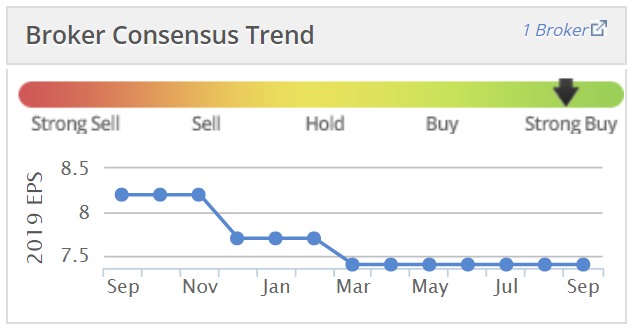
The usual Stockopedia graph shows falling forecast EPS. So maybe today's beat against softer forecast isn't quite as good as it looks?!
At a guess, I'd say the group might be heading for perhaps 8-9p full year EPS, which would value it on a PER of 10-11 - which looks good value in a low interest rate environment.
The dividend yield is just under 4%, which again is pretty decent.
My opinion - the Help To Buy scheme may be propping up housebuilders profitability, but even once it's withdrawn, that shouldn't affect the actual number of new houses being built. Therefore I imagine Michelmersh should continue to see decent demand.
Weaker sterling should make it more competitive versus more expensive imports, in the UK market.
Overall, this gets a thumbs up from me. It looks a decent company, at a reasonable valuation. It's also reassuring that management seems to have made a successful acquisition - with more to come maybe?
(I'm taking a break for lunch now. Will add a couple more sections later this afternoon)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
I wasn't going to comment on IQE (LON:IQE), no position currently but watching with interest, as the results were pretty much as expected. However, given that IQE (like Burford perhaps) has some little understood and complex items that can be subject to misunderstanding, both deliberate and otherwise, I thought I would address one point from this thread.
It is categorically NOT "a sale pretending to be something else"; in fact it is really a complexly constructed loan.So whilst the deal done by Drew Nelson takes a little bit of effort to understand, it is definately not a covert sale, in fact he has retained a significantly greater exposure to IQE's fate than the other more conventional approaches would allow.
All this said, and despite the fact I do still have faith that the 'bull case' still looks credible I have no interest in owning the shares currently. Someone commented today at ADVFN that IQE have been "unlucky" - this is probably true IMV, however there is plenty of bad luck out there waiting to kick companies and I would rather wait to invest in a company with a degree of insulation against "random chance", for me IQE is not there yet.
History has taught me not to hold my breath on upsides for IQE (LON:IQE)
Also the President/CEO has used again a strange complex device which effectively is selling shares subject to a buy back at a later date to apparently satisfy NI on a substantial options exercise.
This is legal, but as it is really a sale pretending to be something else as far as I can see, based on a complex instrument. You can say this reward for generally poor historic performance, is based on an over generous options machine working against the interests of shareholders, but others may be sanguine?
paul any thoughts on EKT
Paul Would be interested in your take on Gamma Communications (LON:GAMA) results if you get time. I think results look good and I have taken an initial position this morning.
My Buy In notes: Acquisition and operational gearing has boosted H1 EPS by +45%. New EPS broker upgrades over the next 3 years of between 11 and 19%/annum. 97QM score. Expensive, but high quality with price now near 52Wk High.
Another vote for your thoughts on Gamma Communications where half year results look robust and should lead to broker upgrades for the full year. Interim eps of 19.2p v current broker estimate of 36.7p for full year.
Return on equity and return on capital both around 25% and net cash around £30m.
As highlighted by iwright 7 not cheap but that reflects the quality ranking of 91.
The trading update from Xaar (LON:XAR) suggests a business in terminal decline with yet another share price fall approaching 30%. It would seem that they are struggling to find a strategic partner to provide some form of cash injection. They will need it as their cash balance is falling at about the rate of £7m + per half year and stock write downs in the millions won’t help. At this rate of decline it will be exhausted by end 2020. It would seem that their technology/IP is no longer a strength and most probably has been superseded by developments elsewhere. If this wasn’t the case it would surely have been acquired at these share price levels. Sadly, as a holder, I should have heeded Stockopedia advice and sold at the 1st profit warning!. I fear now that it will be a complete loss.
Serial dissappointer £IQE has slipped into 1H loss and the cash pile has gone completely. Still a BB favourite on a rediculously high PER given its history. Am short...
IQE (LON:IQE)
Still a BB favourite on a ridiculously high PER given its history
Agreed in most respects although one never knows with the future may bring - i am pretty sure Public Enemy would never have bought shares in IQE though.
IQE (LON:IQE) are priced based on future potential. It would be very strange to base the price on history for a small company that can potentially be completely transformed by the emerging technologies of VCSELs and 5G.
Of course, if one believes that neither VCSELs nor 5G will ever take off, or one believes that even if they do the company will never make any profitable growth from them, then go short as much as you like. If on the other hand.....
I hold.
Trouble is the jam has always been just around the corner. My fear for them is that by the time 5G does come round the world will have moved on and whatever edge they have (if any) will have disappeared.
At the end of the day its a low margin, high capex industry that's at the whim of much bigger players - ie, they have no pricing power. So even if the market does explode they're going to have to spend a fortune on more plants and people just to keep up with demand... with all the risks that those entail in any economic downturn.
Re:IQE
It is very clear that 5G is coming over the next 3 years. Trade wars between US and China may slow it down but it is definitely coming. I don’t see how the “world will have moved on”. What is this tech that the world will have moved on to that will mean that compound semiconductors will not be needed for 5G? (If we haven’t already heard something about it, it must be at least five years away).
Regarding margins, VCSELs are higher margin than the historic wireless products and newer products like their DFB products will also be higher. Once the customer base has diversified some more (e.g. many more android phone manufacturers will have adopted the technologies) the pricing power of individual large customers will be diluted, reducing margin pressure too.
High capex? The vast majority of capex investment needed is complete and they thus have considerable capacity to increase production without adding any additional tools. The Newport foundry infrastructure they have put in place means that when volume gets to the point where investment in additional tools becomes necessary it will be proportionally lower relative to the additional new volume than has been the case recently. The pay back on a new tool is around 18 months, so very reasonable. That’s far preferable to my mind than companies that are reliant on spending equally large sums on internet advertising etc. to win new customers and support the brand where as soon as you start to dial that back your sales suffer.
So, the idea that this will be a low margin business with constantly high and excessive capex seems wrong to me.
I remember being invested in GEO Interactive/Emblaze back in the early 2000's. They had the best mobile video technology around at the time, 3G and mobile video was just around the corner and we were promised that the market was going to be huge and the jam was coming.... but it never happened.
Sure 3G and mobile video happened, but years after the initial trials, mainly due to a slowdown in global growth / global recession - and here we are in very similar macro circumstances, and also because of a lack of consumer appetite for it at the time. Again, i don't see any evidence that consumers are waiting anxiously for 5G.
I think by the time that 5G and VCSEL's take off in a big way then the big chip companies will have come in and taken over and IQE will remain a small, niche player, possibly bought out. At least they do have a business - unlike GEO/Emblaze - just don't think it will ever take off the way some people do.
Hello Martin
I appreciate what you are saying. There is always a doubt around the speed of uptake of new technologies.
In this particular case we need to understand that IQE have key technologies that serve multiple growing end applications; this is not dependent on consumer demand in a single application.
For example, the photonics technologies are finding application in LiDAR, facial recognition, augmented reality, telecom infrastructure etc. It is not so much the desire of consumers for any one end application that makes this a success or failure.
To take telecom infrastructure as an example. The growing need to transmit ever higher quantities of data means that the telecom infrastructure industry has to invest in these capabilities. So, the consumer doesn’t care two hoots how the Netflix pictures arrived on his screen but you can be certain that as more and more people use streaming TV they are not going to be satisfied if their HD pictures start to freeze. Meanwhile cloud computing growth rates are high. (Have you seen how much Amazon make from AWS?). So, business demands ever more data capacity too. We may not think “photonics” when we think about streaming TV or cloud computing but that’s what’s coming.
Now one thing to be absolutely clear about is that IQE do not manufacture chips. Component manufacturers buy wafers from IQE. No one can say whether or not these component manufacturers will want to take the wafer fabrication in house or set up in competition to IQE. But why would they? Some businesses vertically integrate others don’t, but one thing is for sure and that is that it is harder to bring something in house that is already protected by IP, trade secrets, economies of experience and know how not to mention having to justify the capex and risk involved in doing so. IQE are far better protected from their customers backwards integrating than companies in less technical fields.
The uptake of 5G handsets will obviously take time and we know the replacement cycles for smart phones have already slowed but replaced they will be. Neither you nor I may watch much video on our tablets and phones. And neither you nor I may play online video games on our mobiles. But there are plenty of people that do and will not settle for the old technology when they next replace their devices. It is going to happen. It is only a matter of when.
Photonics and 5G wireless comms will be key enabling technologies in the 2020s. IQE are well placed to take advantage of that.
Great results from £BLV (LON:BLV) this morning. I am also pleased the already high dividend isn't being increased as that might provide an opportunity to pare down debt. This is looking like a decent value play. It's the balance sheet, housing market, and the fear of impact from the lettings fees ban that has put some investors off.
Two things to pull out from the detail I spotted:
Firstly growth in the underlying business minus the acquisition is 10% which is pretty good going for an estate agent in the current environment.
Secondly, these are the first set of results since the lettings fee ban came into place. It looks like the ban hasn't had a huge impact but in the whole of 2018 the like for like growth in lettings fees was 2.6% and this is now at 0.5%. So a bit of a slowdown but not a disaster like some investors were expecting.
Within our property franchise division, MSF increased by 5% to £4,201,000 (H1 2018: £4,015,000) with the lettings element growing by 4%. The introduction of the tenant fee ban on 1 June 2019 reduced organic growth in the period to around 0.5% with the balance arising from franchisee-led acquisitions under the Belvoir Assisted Acquisitions programme.
As I understand it, the fee ban might take a bit longer to fully drop in, as fees are still allowed on existing contracts, until 31st May 2020.
I wonder if in a years time that price competition would become pretty fierce in this sector..... in the past charging tenants could subsidise a lower landlord fee, but now it seems that all firms will be directly comparable.
I think short-term the fees will end up at the feet of landlords, in longer-term the margins will end up declining in the industry due to competition..... assuming a rental for 2 years on an average London flat on a non-managed deal, current agents commission might be in the region of £3k-£5k for their efforts which is a Rightmove ad, showing clients around, and administrative chores.
Personally I think the lettings sector is ripe for disruption if a technology based product could manage to get the scale required.
Just looking at the IHS Market Report, which gives a snapshot of UK manufacturing. "Highlights" are that PMI has fallen to its lowest level since 2012 and that the pace of decline is quickening. There's a double whammy here, as Brexit and Trump's trade wars have their impact:
https://www.markiteconomics.com/Public/Home/PressRelease/a683a7987184497cba5e01b52a7f99ab?s=1
No surprise that UK manufacturing is a poor place to be, there's only so much slack that the decline in sterling can take up. Having said that, 40% of manufacturers are still forecasting expansion in the next year.
To put this in context, the Eurozone PMI is worse than the UK's, although it's actually improved this month. OTOH, as that's 40% of our exports I'm not sure it's particularly good news. The notable difference is that UK manufacturers are putting domestic prices up, while their Eurozone equivalents are reducing theirs.
A time for sitting on one's hands, I feel.
timarr
My morning smallcap tweet: No cigar for Xaar
Xaar (LON:XAR), Solid State (LON:SOLI), Synnovia (LON:SYN), Newriver Reit (LON:NRR), Real Good Food (LON:RGD), Stirling Industries (LON:STRL), Qannas Investments (LON:QIL), Michelmersh Brick Holdings (LON:MBH)
Xaar (XAR) warns FY trading expected to be weaker than previously anticipated with H2 rev similar to H1. £5.7m stock write-down. "Management continues to focus on its strategic negotiations [for investing partner, RNS March] and expects that some additional time could enable the Board to provide a more meaningful update on progress" so interims delayed to 26 Sept.
Solid State (SOLI) guides FY profit significantly ahead of expectations but rev in line. Credits stronger margins, weak £ and the Pacer acquisition performing better than expected.
Synnovia (SYN) rec offer of 125p, a 43% premium.
NewRiver REIT (NRR) £58m disposals so far this FY at 1.2% above book value.
Real Good Food (RGD) CEO will leave end Sept. CEO role has become part time due to creation of two autonomous business units with their own separate strategies.
Stirling Industries (STRL) the cash shell shares are suspended pending an RTO.
Qannas Investments (QIL) suspended pending an RTO of portfolio includes shareholdings in a number of publicly traded GCC-focussed companies, in sectors such as real estate, maritime shipping services and insurance.
Michelmersh Brick (MBH) H1 rev up 17%, guides FY ahead of market expectations.