Small Cap Value Report (Tue 3 Sept 2024) - ALU, CRW, KITW, WOSG, MBH

Good morning from Graham & Paul!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 26/8/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
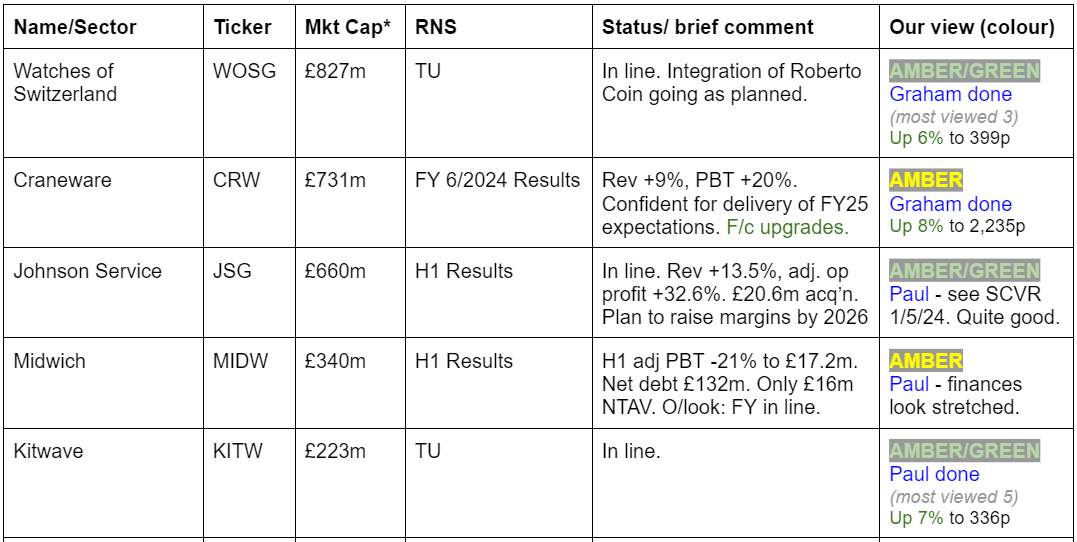
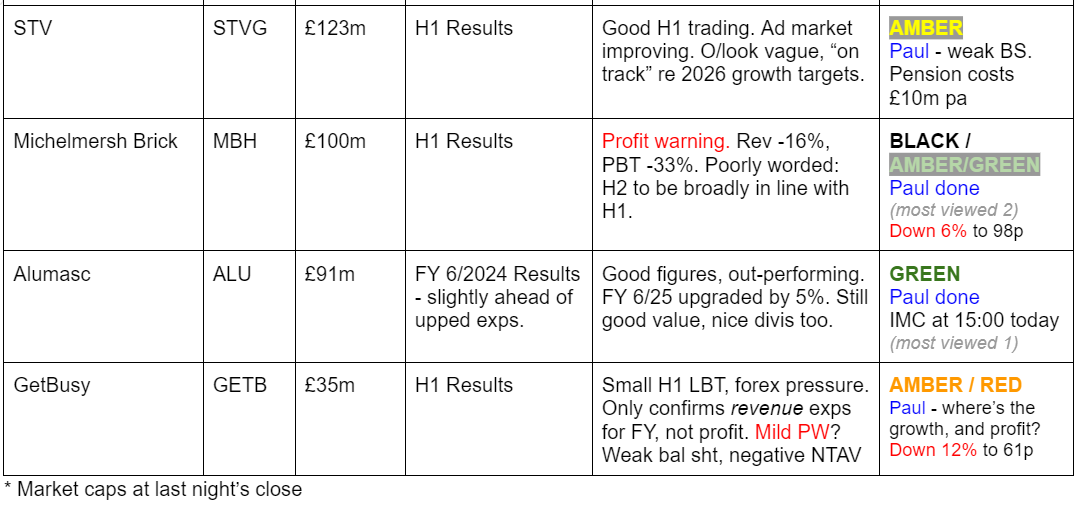
Summaries
Alumasc (LON:ALU) - up 5% to 265p (£96m) - Final Results - Paul - GREEN
Strong results, slightly ahead of forecasts that were raised in July. Everything looks good to me, with a decent balance sheet, and strong cashflows. This is a quality group of companies, with specialist environmentally good products, with pricing power. I think shares remain cheap on a PER of only 9x raised FY 6/25 forecasts. There should be a cyclical recovery to come too, so it might beat forecasts, as it did in FY 6/2024.
Craneware (LON:CRW) - up 8.5% to £22.46 (£793m / $1,041m) - FY24 Final Results - Graham - AMBER
A great set of results from Craneware and the analysts have updated their spreadsheets with higher revenues forecasts for the years ahead. The company is close to achieving the symbolically important “double digit growth” which I think could power the valuation to higher levels. For now, the valuation seems about right to me for a promising, high-performing software provider in the US healthcare space.
Kitwave (LON:KITW) - up 6% to 335p (£234m) - Trading Update - Paul - AMBER/GREEN
Decent summer trading seems to have eliminated the risk of an H2 profit warning, as it reiterates confidence in achieving FY 10/2024 profit expectations. It's an OK business at a fair price, although I can't get excited about it, due to pedestrian profit growth and rising debt from acquisitions.
Watches of Switzerland (LON:WOSG) - up 4% to 394p (£943m) - Trading Update - Graham - AMBER/GREEN
A sigh of relief for investors in this lowly-valued watch and jewellery retailer as it reports that trading has been in line in the first few months of the new financial year. Visibility over the rest of the year has improved and a large US-based acquisition is working out as planned. I was AMBER/GREEN on this earlier in the year and am happy to leave my position unchanged, as the company is executing well.
Michelmersh Brick Holdings (LON:MBH) - down 6% to 97p (£94m) - H1 Results - Paul - BLACK / On fundamentals: AMBER/GREEN
A 28% cut to FY 12/2024 forecasts does remarkably little damage to the share price of this premium brick maker. Despite today's disappointment, I like its balance sheet, generous divis, improving order book (which seems to contradict the H2 profit warning), and modest valuation on what could turn out to be bottom of the cycle earnings. I would pencil in c.25-50% share price upside in a recovering housebuilding market (maybe in 2025), as a distinct possibility.
Paul’s Section:
Michelmersh Brick Holdings (LON:MBH)
Down 6% to 97p (£94m) - H1 Results - Paul - BLACK / On fundamentals: AMBER/GREEN
Michelmersh Brick Holdings PLC (AIM: MBH), the specialist brick manufacturer and brick-fabricator, is pleased to report its half year results for the six months ended 30 June 2024.
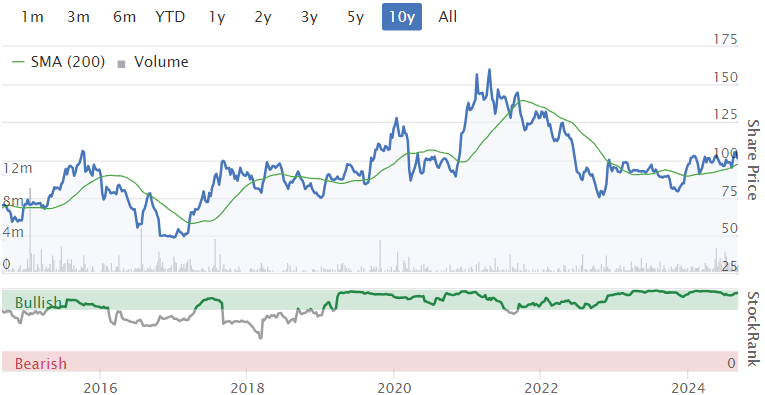
We’re overdue a look at MBH, having not covered it so far in 2024, but we did 5 times in 2023, mostly favourably. Shares have been in a sideways trend for 2 years now. Actually it’s been in a broadly sideways trend for the last 10 years, with c.100p per share seemingly acting like a magnet on the shares, if they were made of metal.
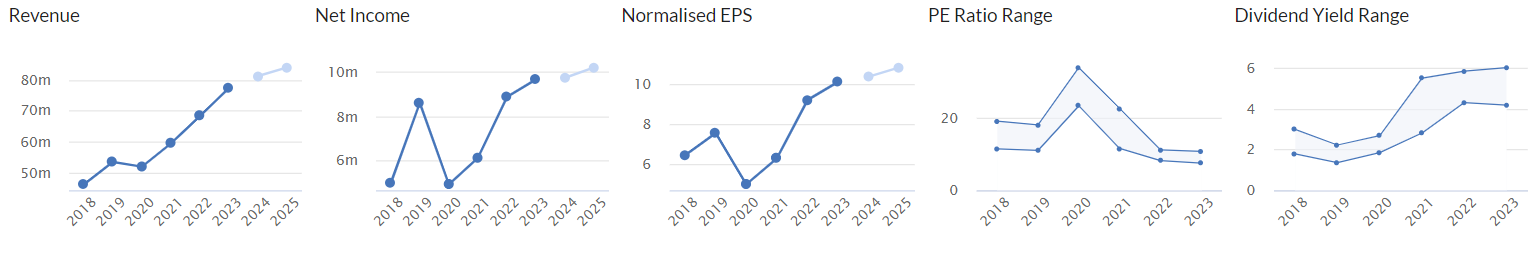
The Stockopedia fundamentals graphs below show a healthy picture, but a share which has de-rated onto a lower PER, and with a very nicely growing dividend yield, which has got my value antennae twitching!
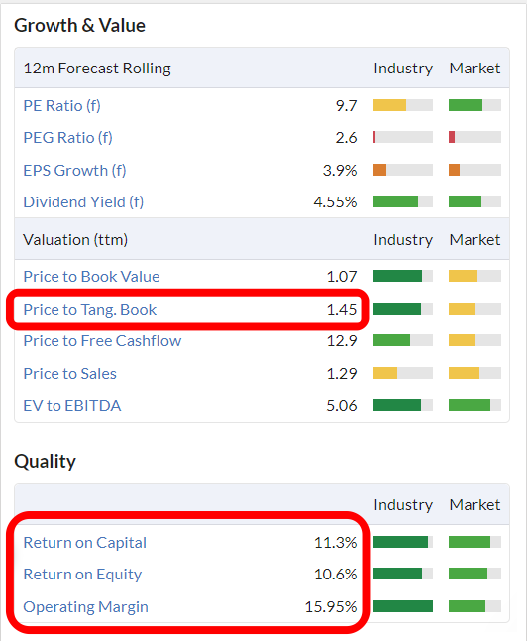
I’m also liking the signs of a strong balance sheet, with a low price to tangible book, and good quality scores shown here -
H1 Results -
Revenue down 16% to £35.4m (it says this is as expected, and out-performs a market down 40%)
Adj PBT down 22% to £5.3m (not bad at all, as I would have expected an operationally geared, much larger % fall in profit)
Adj EPS down 25% to 4.28p.
Interim divi up 7% to 1.6p, “underlines the Board’s confidence in the outlook…”
Outlook - some quite good things in here - but a sting in the tail, with the final point amounting to a FY 12/2024 profit warning -
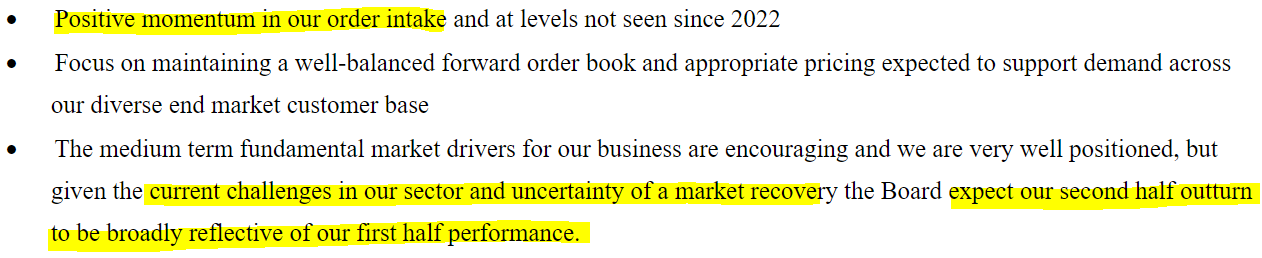
“Across the Group, current order intake is running ahead of our manufacturing capacity which is contributing to a growing quality forward order book underpinning our second half revenue expectations.”
Surely that last quote contradicts the profit warning for H2? Rather confusing.
The above implies something like 8.0p EPS for FY 12/2024 maybe?
Canaccord comes to a similar view, taking an axe to its 10.7p previous adj EPS forecast, and revising it down 28% to 7.7p - actually quite a nasty profit warning, despite the attempt by MBH to PR their way out of a tight spot in the announcement.
That said, at 97p/share, after today’s surprisingly modest 6% fall in share price, the PER of 12.6x is hardly demanding, considering this could turn out to be bottom of the cycle earnings, as housebuilders are saying they expect a recovery in 2025, so logically MBH should benefit from that. Although it does make speciality bricks, so I’d be interested to know what proportion go to mainstream housebuilders, and how much to private, or smaller builders?
The new Govt supposedly wants to increase the number of new houses being built, so there should be a tailwind there, with hopefully lower interest rates also being a much needed catalyst for the sector.
MBH should be benefiting from lower energy costs now too, which it says are hedged (80% 2024, 40% for 2025).
Balance sheet - the stand out number is inventories, which has almost doubled vs a year ago to £19.5m, which is the opposite of what I would have expected in a sector recession with lower sales. They must be stockpiling for a recovery. The commentary says they’ve built up stocks to cover a 2-month factory shutdown for planned maintenance. It also says the industry as a whole has higher than usual inventories. So that could be a drag on prices in future maybe, if there's a glut of bricks?
Overall the balance sheet looks excellent, with £91m NAV, less £23m intangible assets, giving NTAV of £68m - supporting 72% of the market cap.
An unusual item is a £15.4m deferred tax liability - what’s caused that, and what significance is it? I never properly understood deferred tax, which is probably why I failed my ACA finals exams. Let someone else worry about deferred tax, was my attitude - not ideal for passing exams arguably, but it worked out fine as that’s exactly what I did when I was an FD not long afterwards in the 1990s - letting Ernst & Young do the deferred tax calculations, and to this day I still don’t understand it. Something to do with timing differences?
Anyway, the balance sheet is smashing. Net cash has fallen sharply, due to the inventory build. So there’s only £4.1m net cash remaining from £11.8m a year earlier, but it has a £20m bank facility available, so liquidity is fine.
Cashflow statement - is poor, because of the big inventory buildup. Let’s hope that reverses in H2, which seems to be what the commentary is pointing {geddit?!} towards.
Paul’s opinion - I think MBH shares got off lightly today with only a 6% fall, despite a 28% reduction in current year forecast EPS.
That said, we could be at or near the low point of the earnings cycle, and it’s still reasonably priced. So people might quite reasonably now be factoring in improving earnings in 2025 and beyond.
With a cracking balance sheet, and a 4.6% yield, with divis increasing, I think patient investors could do quite well on this one, on a tuck away and forget basis. Although the lesson from the long-term chart is maybe to sell the big surges, and wait for it to come back down again!
Kitwave (LON:KITW)
Up 6% to 335p (£234m) - Trading Update - Paul - AMBER/GREEN
Checking my previous notes in 2024 for this food/drink wholesaler -
28/2/2024 - GREEN at 297p - in line FY 10/2023 results, all looks fine. A decent GARP share.
2/5/2024 - AMBER/GREEN at 407p - in line FY 10/24, but H1 demand soft due to bad spring weather. Price up with events now.
2/7/2024 - AMBER/GREEN at 316p - lacklustre H1 results. Risk of PW if H2 weighting doesn’t happen. Balance sheet has a bit too much debt. Valuation more reasonable after recent falls.
Latest trading update today -
“Kitwave Group plc (AIM: KITW), the delivered wholesale business, today provides a trading update covering the four months to 31 August 2024.”
It’s good news, key summer trading has been robust -
“The Board is pleased to report that trading over the summer, traditionally the busiest period for the Group, has been robust. As such, the Group remains confident of delivering financial results in line with expectations for the full year ending 31 October 2024. “
That removes my main worry, of the H2 weighting not happening enough to offset the soft H1 (when operating profit was down 8% vs LY).
More details -
- Customer demand strong.
- Efficiency gains, eg voice-picking technology at a distribution centre.
- 2 acquisitions helped growth, integrating as planned.
Broker update - thanks to Canaccord for its update. Forecasts are unchanged today, at £29.0m adj PBT (up 5% on LY). That’s 29.9p adj EPS, giving a PER of 11.2x, which doesn’t look demanding, although a business of this type wouldn’t usually command a PER much higher than that anyway. Profit only growing 5% Y-on-Y, despite 2 acquisitions is not exactly stellar is it?
Paul’s opinion - this looks a decent enough business, shifting a lot of other people's products, for a 5% operating margin. It’s done a lot of bolt-on acquisitions, so the strategy is to be an industry consolidator, which might possibly allow it to increase margins a bit over time?
Finance costs are creeping up, as it loads up on debt, which was a tad too high for my liking at 30/4/2024 at £53m interest-bearing debt (excl. leases) gross, with £5m cash that’s net debt of £48m, or c.21% of the market cap in net debt.
Overall I think it’s OK, not madly exciting, and there could be maybe 10-20% upside on the current valuation - not enough to get me excited.
You are getting a c.4.2% dividend yield, but I don’t think the company should be paying such generous divis, at the same time as it’s accumulating debt to fund acquisitions. The cashflow statements do show that it could comfortably pay divis if it wasn’t also spending c.£20m pa on acquisitions.
The £78m goodwill on the balance sheet leaves only c.£7m in NTAV when it’s eliminated, which I think is getting a bit stretched given this is a significant sized business.
Is it worth sticking at AMBER/GREEN? Just about I’d say, as the risk of an H2 profit warning seems to have gone now, after a strong summer trading. Valuation looks reasonable, but I can’t get excited about the pedestrian profit growth, and rising net debt. Although note that Canaccord assumes it can pay off nearly all the bank debt over the next two years, which would be impressive if achieved. Put it like this, I can’t find anything particularly wrong in the numbers, and it’s an OK business at a fairly reasonable price, so let’s stick with AMBER/GREEN.
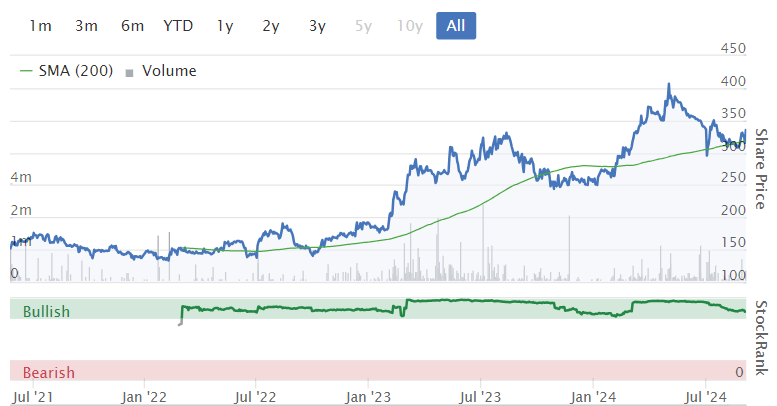
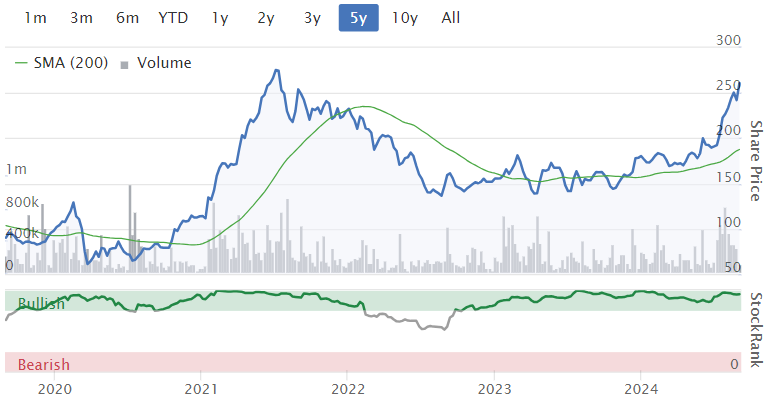
Good performance since listing, and note the high StockRank -
Alumasc (LON:ALU)
Up 5% to 265p (£96m) - Final Results - Paul - GREEN
Alumasc (ALU.L), the premium sustainable building products, systems and solutions Group, announces results for the year ended 30 June 2024.
One of our favourite shares here at the SCVR, which readers flagged to me on 9/2/2024 as looking interesting. I gave it an enthusiastic thumbs up at 179p, on in line H1 results and a bargain valuation. Broker consensus forecasts have been rising gradually this year, and we next looked at it here again on 18/7/2024, with another thumbs up (green) at 221p on an ahead of expectations trading update.
Today we get strong results for FY 6/2024, with this headline -
“DELIVERY OF STRATEGIC PRIORITIES DRIVING MARKET OUTPERFORMANCE WITH FURTHER UPGRADE TO 2024 PROFIT”
How much of an upgrade? Cavendish says it’s beaten FY 6/2024 EPS forecast by 2.3%, so a slight beat. Cavendish re-works the numbers to report a 26.6p adj diluted EPS (close to the underlying EPS of 26.9p in the results announcement), giving a PER of 10.0x based on this morning’s higher 265p share price. Not expensive, despite the strong rise in share price this year.
It’s notable that ALU is bucking the trend, out-performing a sector which has generally been struggling this year. Could that be lucky one-off orders, or possibly a sign that its innovative products are in demand, despite soft sector fundamentals (which could point to even stronger performance once markets are more buoyant).
I had a very good call with management earlier this year, and it struck me what a good job they’re doing in particular with product innovation, which is offsetting weakness elsewhere. The strategy to innovate, and command higher margins, is clearly working. The market is gradually waking up to the quiet transformation that seems to be underway at ALU - this is a quality business, with pricing power (and well-established brands/reputation), not just a distributor of generic products -
“Group underlying operating margin* of 14.1% (2023: 13.6%), progressing towards 15-20% target margin range, with all divisions contributing to the improvement”
Adjustments to profit are only small, and look acceptable to me.
Dividends are an attractive feature of this share, and are growing - the yield is a handy 4.1% -
“Progressive dividend policy reflects Board's continued confidence in outlook. Final dividend proposed at 7.3p (2023: 6.9p) per share, contributing to a total dividend of 10.75p (2023: 10.3p) per share, within our medium term objective of 2.5-3.0 times earnings cover”
Outlook comments are general, but optimistic in tone - eg
“While demand headwinds in Alumasc's commercial markets are likely to persist for the remainder of 2024, we are encouraged by early indicators of easing in planning, improving consumer confidence and the interest rate outlook which suggests an improved trading outlook in due course. With the positive trading momentum Alumasc has carried into the new financial year, and the improving economic environment, the Board is optimistic for another year of growth.”...
“While we still expect market headwinds to persist in the near term before commercial conditions strengthen materially, including anticipated further interest rate reductions, Alumasc is confident in its future prospects. Our recent track record of consistently delivering profitable growth; investments in people/processes/new products/ARP; the evolving regulatory/environmental and construction/housebuilding landscape; and our self help measures cause us to be optimistic about the delivery of our medium term aspirations, as market conditions improve.”
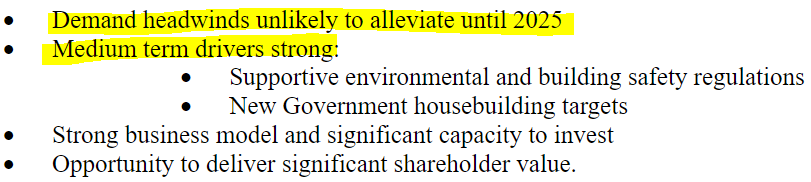
Cavendish has raised forecasts today for the new year, FY 6/2025 - raising forecast adj EPS by 5% from 28.0p to 29.4p (PER 9.0x).
Hopefully these numbers might be beaten, as the sector sees a macro recovery in 205 maybe?
Acquisitions - ALU seems good at these, and doesn’t rush into lots of deals. ARP has gone well -
“Since we completed the strategic acquisition of ARP Group and welcomed our new colleagues, the business has performed extremely well, bringing exciting synergies and opportunities for cross-selling to the business.”
Balance sheet - note the pension scheme consumes £1.2m pa in cash contributions towards the actuarial deficit. It has moved into a small accounting surplus of £0.8m, so hopefully in due course the actuarial-based contributions might subside somewhat. I’m working on the basis the £1.2m pa is likely to continue for several more years (next actuarial assessment is 2025, and they often take a year or more to agree).
Bank debt is modest, and has risen due to the cost of acquisitions. I ignore leases, as it’s not debt, it’s future years’ operating costs, and there are no covenants or risk of withdrawal. Leases are only a problem if they are onerous. So the old accounting method was far superior and reflected commercial reality, whereas IFRS 16 has screwed up all the numbers and needs to be adjusted out for the accounts to make sense. Maybe the new Govt could have a clear-out of the accounting standards bodies too, as not fit for purpose?!
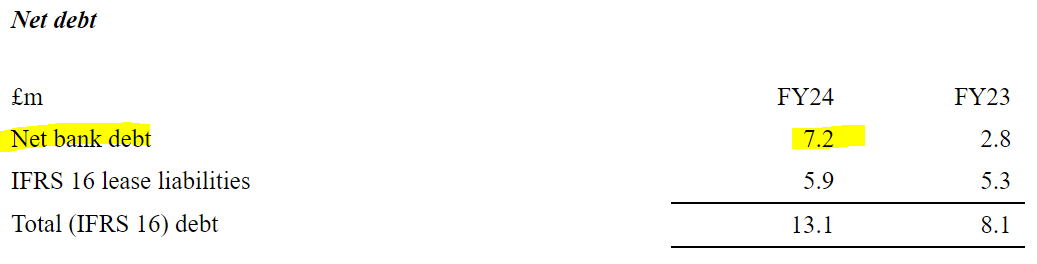
Overall the balance sheet looks fine to me, with c.£14m NTAV. Nothing untoward in there.
Cashflow statement - again, very clean numbers. It generated £14.1m in post-tax operating cashflow. About a quarter of that was spent on capex. The biggest item is £8.5m outflow (net of cash acquired) for an acquisition - this is why net debt went up as noted above.
Bank interest was nearly £1m, and dividends cost £3.7m. Plus £0.6m spent on buying back its own shares.
All very good - it’s able to pay out good shareholder returns, and self-fund an acquisition, with only a modest increase in net debt.
Paul’s opinion - I think this is an excellent business, and still reasonably priced.
Therefore it has to be another GREEN. I think it could be short-sighted to be banking profits below 300p. If a cyclical recovery starts in the sector, earnings could increase to well over 30p. Put that on a PER of say 12-13, and I’m thinking 360p - 390p looks possible with a say 1-2 year view. Plus a 4% divi whilst you wait. That makes this share remain attractive to me at 265p. Of course, something could go wrong, that’s the risk we take with all equities, but I’d much rather buy or hold something where risk:reward seems to be in my favour, as it looks to be here.
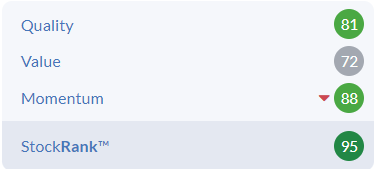
Stockopedia loves it too, so it gets the man+machine thumbs up!
Graham’s Section:
Watches of Switzerland (LON:WOSG)
Up 4% to 394p (£943m) - Trading Update - Graham - AMBER/GREEN
I’ve been mildly positive on this one, given the lower valuation on offer vs. 2022 and the interesting acquisition it made in the United States (see coverage in May 2024).
As a reminder, here is a chart of the company’s share price performance since IPO in 2019:
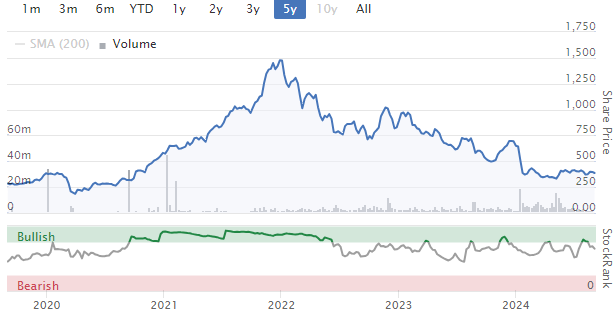
The bursting of the watch bubble has seen it drop back to cheap multiples:
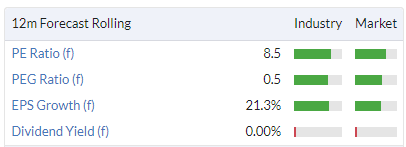
Today’s update is in line, after the first 18 weeks of the financial year (FY April 2025), and WOSG is confident in the delivery of FY25 guidance.
Key points:
Stabilisation of the UK market in luxury watches and jewellery.
US: performance will be second half weighted (amber flag?).
US: increasing inventory to enhance displays (probably fine, but it will drag on cash).
The acquisition of Roberto Coin is “progressing to plan”. This was an important and large ($130m) acquisition of a jewellery distributor that was already being used by WOSG. So I’m pleased to hear that everything is fine with the integration so far.
Some of the detail on future plans:
Looking ahead, we are working closely with our new colleagues on exciting growth plans for the US market. We intend to grow and develop the Roberto Coin brand and are actively negotiating new mono-brand boutiques in the US, alongside concession models with department store partners. In addition, luxury branded jewellery has also performed well globally, and we are pleased to announce the exclusive launches of David Yurman and Repossi in the UK…
Graham’s view
My mildly positive stance here seems to be working out, in the sense that the company is delivering on its plans and uncertainty is receding. Today they mention “increased certainty on the timing of key showroom projects, and visibility of new product launches”.
All we need now is for Roberto Coin to make a meaningful contribution to profitability, and shareholders should have a pleasant few years to look forward to.
I’ll be watching out for news on the company’s debt levels, as it borrowed to fund the Roberto Coin takeover, and its inventory position in the next results statement.
The company doesn’t pay a dividend (correctly, in my view) and does need to carefully manage its risks as it has financial debt, lease liabilities and a volatile retail market to contend with. But currently, everything is under control.
I’ll leave my stance here unchanged, looking forward to more of the same with the interim results.
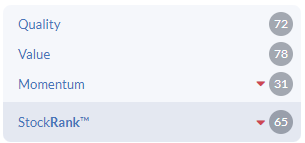
Stockopedia’s calculations share my view that this stock potentially offers some value and is worth a second look:
Craneware (LON:CRW)
Up 8.5% to £22.46 (£793m / $1,041m) - FY24 Final Results - Graham - AMBER
Craneware (AIM: CRW.L), the market leader in Value Cycle software solutions for the US healthcare market, announces its audited results for the year ended 30 June 2024.
We covered Craneware’s full-year update in July, when we learned that revenue would beat expectations for the year, and that EBITDA was towards the top end of expectations.
Today we have the complete full-year results statement.
Let’s take a look at some of the key bullet points:
Rev +9% to $189m (slightly higher than the growth suggested in the trading update).
Adj. EBITDA +6% to $58m.
Small increase in ARR to $172m.
PBT +20% to $15.7m.
It was a fine year (and I look forward to chatting with management later this morning); the only stumbling block I’ve had when it comes to the investment proposition here has been valuation. More on that later.
Operational highlights - one of the standout elements here is the strategic alliance with Microsoft, involving collaboration and the sale of Trisus on Microsoft’s Azure Marketplace.
Outlook
Increasing opportunity ahead, including accelerated innovation via the alliance with Microsoft
Momentum has continued post-year end, with good levels of trading and customer confidence, providing the Board with confidence in continued growth momentum for FY25, delivering on current expectations and the sustainable return to double digit growth rates.
In previous reports, I’ve been suggesting that double-digit growth was needed to help support the valuation of this one, and so it’s interesting to see the company specifically mention this as something they are working towards.
Estimates have been published this morning by Capital Access on Research Tree, and they have raised their forecasts on the back of the strong revenue performance and outlook.
Revenue growth was previously estimated at an average of 6% p.a. (from FY24 to FY27), and this is raised to an average of 8.5% p.a. This also flows through to increases in profit estimates; their adj. EBITDA forecast for FY June 2025 is $62.5m.
Peel Hunt have also pushed through some small revenue upgrades.
CEO comment:
"The strong financial results during the year demonstrates the strength of the Trisus platform, our increasing platform partnership successes and the role we play in helping healthcare providers drive for better value in the US healthcare market.
We see increased opportunity ahead. Our alliance with Microsoft will allow us to accelerate innovation and explore new AI-based applications in an efficient manner which, alongside the breadth of the Trisus platform, our unique data assets and our considerable and extensive customer base provides significant scope for expansion in the size of our addressable market…
We have commenced FY25 with a good level of trading, and remain confident in achieving another positive year ahead, growth acceleration over the near term, and our ability to create further long-term value for all stakeholders."
Cash/Debt: I should mention that the company finished the financial year with cash of $34.6m offset by bank debt of $35.4m.
Graham’s view
I’m wondering if I can upgrade my stance here to AMBER/GREEN, on the back of higher revenue growth forecasts.
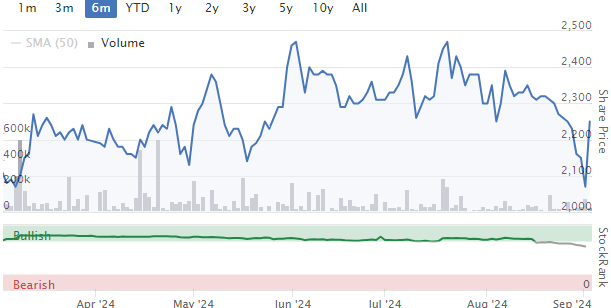
The share price was soft going into today’s results, but has found some bidding interest this morning:
On valuation, the market cap (which in this instance is the same thing as the enterprise value) gives us the following multiples based on FY25 forecasts:
Price to sales: 5.1x
EV/current ARR (annualised recurring revenue): 6.1x
EV/EBITDA: 16.4x
Adj. PER: 28x
You may agree with me that none of these multiples are screaming “value” but if you do a comparison against the US tech sector/healthcare sector you may find that the valuation starts to make more sense.
I still think that Craneware’s valuation is quite normal for its sector, and that it does have the possibility to outperform given its enormous data set, the potential for 3rd parties to want to work with this data, and the alliance with Microsoft.
If the share price hadn’t jumped higher this morning, I might have switched to AMBER/GREEN, but for now I remain comfortable with AMBER.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

108 comments
Kitwave (LON:KITW) I thought the update looked pretty encouraging and decided to reinstate a small position. Easy to understand, well-established business with long track record, and plenty of scope to consolidate a very fragmented market.
The modest 5% growth rate that Paul notes may appear a bit lacklustre, but historically EPS have grown at a much faster pace and would expect it to continue to grow by at least double digits over next few years. Indeed, by my calculations H2 growth must have already picked up quite a lot in order to have offset a weak H1. Admittedly, the growth story is based on acquisitions rather than organic growth, but I see this as rather low risk given they must have very good knowledge of the sector and generally avoid very large acquisitions.
For anyone interested I thought this research piece on Watches of Switzerland (LON:WOSG) - which I now hold - was excellent.
https://static1.squarespace.co...
Thinking about Eurocell (LON:ECEL) - i hold. The cfo confirmed that going forward we wont have a TU in between the AGM and results, while that makes sense it does raise the risk as to exactly why and I was thinking maybe a slight profit warning etc after a not quite so fantastic AGM update.
But there's been a profit warning by stealth as far as i can see already. The forecasts for 24 were cut 10% at the start of June after the AGM update that raised some headwinds. One of which was resin prices which appear to have increased in may/June but reduced to below Mays rate now. So, if the market compares results with current market consensus then it should reduce any risk of a profit warning (unless worse than a 10% miss!). Also interesting that the breakout happened after forecasts were cut.
So, all in all difficult to see how it will go tomorrow!
Auction Technology (LON:ATG) the slump pushes relentlessly on. Is it out of lack of newsflow - last TU was in May and saw a big jump over 600p (currently under 400p)? Or is it the selling down by private equity? Chart is a horror show but shares should easily be 50% higher if forecasts are sound.
I don't know much about the sector/stock BnB but just not interested in companies where Goodwill and Intangibles make up nearly all the assets. (According to Stocko end 2023 £886m total assets Goodwill £579m and Net Intangibles £270m). Some pretty big calls on cashflow last 2 years as well. On the upside it could be a turnaround (or crap management!)? I saw the Stuart Widdowson video, he likes it.
Been lurking around Auction Technology (LON:ATG) for a while.
I have the feeling that though it looks cheap now, that won't stop it getting cheaper.
The broker price chart mirrors the sp fall. I am not aware of any good moat. They do serve europe and the us but I wonder how much cross border business they actually do.
And it looks like there may be a seller.
There was a note in the scvr 1 July 24 that ended
"This might be controversial, but I think I’ll shift down to AMBER/RED, which will be too harsh if it achieves current forecasts, as the forward PER is only 14.5x. But why would it be higher valued, given that the business looks ex-growth, has a lousy over-geared balance sheet, is seeing broker forecasts reduced, and now its original financial backer is selling?"
I do think the business model has potential but will just watch until there is evidence.
Ashtead (LON:AHT) It's a large-cap, but since it's one of the most-viewed shares today, I thought I'd give it a mention.
Shares are up nearly 5% today on the back of its 2024Q1 results. AHT is an equipment rentals company, mostly to the US construction industry. Revenues were up 2%, operating profit down 2% and EPS down 9% (yuk).
I'll note that EBITDA was $1288m whilst operating profit was $688m. So it seems that depreciation and amortisation are colossal expenses, as one might expect for an equipment rental company. As Paul might say, in a capital-intensive business, EBITDA is meaningless, and perhaps shouldn't be quoted. Scrolling down a bit, I see that depreciation accounted for a whopping $571m, and amortisation $29m.
It's worth mentioning that AHT is a top 10 holding of Baillie Gifford UK Growth Trust (LON:BGUK). You can check out their other holdings here: https://www.hl.co.uk/shares/sh... It's a good source for quality growth companies ideas. I do, for example, hold Howden Joinery (LON:HWDN) and 4imprint (LON:FOUR) in my portfolio (but not AHT).
IIRC they had a recent shareholder presentation (check Youtube for Baillie Gifford), stating that hey had held the shares for a number of years (over 10, I think), and think that AHT is in a better position now than it was then,
Looking at the stock report, revenues has been growing at 13%pa, EPS by 11%, and its ROE is 13.8%. Those are the kinds of numbers that interest me. Fwd PE is 17.2, which is OK for a quality growth stock, I think. Interest cover is 4.9. If I were to make it a new buy, I think I'd prefer that to be above 7. I see that net debt has been growing faster than operating profits, which is not ideal. Others may decide differently.
This company reminds me a bit of Somero Enterprises (LON:SOM, which also operates largely in the US and does laser-guided floor levelling, of all things. Growth hasn't been as impressive as AHT, and it seems the market has been spooked out of the shares the last few weeks. Its returns on equity are pretty impressive, though, and it has net cash.
Make of all that what you will. I'm nowhere near in the same league as Paul, Graham or Roland when it comes to "analysis", so caveat emptor.
I don't hold either AHT or SOM.
I haven't looked at it for a while but on depreciation, they have traditionally been quite conservative and booked handy profits against carrying value when disposing of equipment. They break out growth vs maintenance capex in their reporting and presentations so you can get a decent handle on the 'real' or owner earnings here. Basically if they stopped doing acquisitions and refreshing the fleet and went into maintenance mode the numbers would look much more impressive.
More growth on offer than Somero as they have plenty of bolt on acquisitions to go after in the US. The plant hire market there is consolidating and Ashtead (LON:AHT) and United Rentals (NYQ:URI) are the dominant players still with a decent runway.
You maybe interested in this write up on Ashtead:
https://hollandadvisors.co.uk/...
Very nice find. Thanks for sharing.
I really must compile a list of "quality investors" at some point and share it with these boards.
I'm sure we'd all welcome whatever recommendations people have.
Very helpful analysis thank you
Both Ashtead (LON:AHT) and Somero Enterprises (LON:SOM) had terrible periods where they hit a recession with too much debt and came near to going bust.
Both recovered with AHT going over 20 years from a few pence to £50/£60 let share and Soon also going up many multiple times.
Since its turnaround AHT has taken acquisition options to continue to grow. however SOM hasn't found a sustainable growth strategy.
Very good write up on Alumasc (LON:ALU) Paul. You were a shareholder when you reviewed the July update. Just curious to know your reason for selling as future looks bright here.
Hi eParo,
Yes I did hold ALU personally for a while, but the usual problem arose - something more exciting caught my eye, and I needed to raise money from selling something. So not a judgement on ALU, wish I still had some actually, as I think there's nice upside on it.
There's no room in my small trading account either, as that's gone on a small margin call this morning.
Regards, Paul.
Ticket and Hotel booked for Mello Derby. Exciting.
Places like Derby and Chesterfield really need compelling reasons like Mello to visit.
Chesterfield's got the twisted spire. Better than the leaning tower of Pisa IMO.
The area in between them is pretty nice though
tic-tac-toe,
Re your question last night, try signup.stockprophet.chat
thank you
I don't know who brucie5 is but on ADVFN Spectra Systems chat billboard he seems to have printed verbatim Paul's write up on the Company. Bit naughty in my opinion.
Hi Camtab,
Yes people shouldn't copy anything from Stockopedia onto free websites, so whoever is doing it, please stop! The whole point is that this is a subscription website, so if people paste our stuff all over the internet, then it undermines Stocko and means they won't be able to pay Graham & I to create the content!
Thanks, Paul.
Apologies - it was me. I thought since it was a historic comment, from July, this would not be sensitive; and that by adding a link it was being fully attributed and of course, accessible in its full form only by sub. I also imagine that by referencing such excellent coverage as is offered here that it would actually serve the interests of Stocko in drawing extra interest to what you do. Perhaps you can clarify what is acceptable practice and I will gladly comply. In the meantime I will edit out the paste on the SPSY board.
Kind regards,
B5
Sorry to be a bit "arsy" Brucie clearly i got out of the wrong side of my bed this morning. My initial comment was driven out of the hasty thought "what the 'ell am I paying for if I can read it here". But after some reflection I get much more from this site than a comment on Spectrum so probably unnecessary that I raised it. But there is perhaps a principle involved.
No problems Camt. In future I will simply reference a view and supply a link accessible subscribers only. But I would never cooy/paste time sensitive content from a subscriber forum or newsletter.
Very kind Brucie5, thanks for your replies.
Best wishes, Paul.
Kitwave (LON:KITW) in case it's of interest, here's a detailed piece,
https://sohrapeakcapital.com/w...
Cheers Gmjs
A significant piece of research.
I do like Kitwave (LON:KITW) , a business that is easy to understand and well managed. I have owned it before buying around 270p and exiting at 315p, after the previous update. I am tempted to buy back in after this morning's announcement.
No worries Jonno- I thought it gives a decent overview. I like Kitwave (LON:KITW) on a long term basis and have been chipping away at it over the last 6 months or so, I don't think the valuation is at all demanding and could see it rerate to a P/E of 15+ over time. Often takes a while for the market to cotton on to these kinds of businesses- moderate organic growth and low margins put people off but if the acquisition strategy is executed well the results over time win out. Shades of Booker and Bunzl (LON:BNZL).
Have decided to buy back in; a modest opening position. Modest investment metrics and reasonable yield. In a bull market I could see it reaching a PE of 15, given the valuation Booker commanded, but a PE of 12 or thereabouts should be readily attainable in a decent market given a share price of around 400p.
It is such as easy business to understand and provided the management team execute well, it should continue to be successful.
All the best
I agree, my only quibble is that if I were running the business I'd probably pay smaller divis and pay down the debt a bit more aggressively. Not that I think the debt is excessive but I lean to the conservative side when thinking about balance sheets.
Yep, that's the approach I would take also.
Good piece of research - worth noting that Kitwave (LON:KITW) was trading at around 380p when this research was published back in May, and they make a pretty convincing case that it was undervalued even at those levels. So arguably looks a bargain at current price (335p at time of typing)
Bear in mind that it was written by an American, I think some of the multiples on the comps are a bit bullish for a UK smallcap. But on a long term view I think it looks decent value on a forward P/E around 10, should be able to grow earnings at 10% or so for several years.
Thank you.
Firering Strategic Minerals (LON:FRG)
Slightly off topic given this is resources - but caught my eye (so I own a few). Tiny market cap at sub £6m so clearly will be volatile and illiquid so probably not for most people.
CEO/Founder has a successful track record having built and sold mid size plays before so knows what he is doing.
This is a Quicklime project - used in Copper smelting. They are starting to produce in Q4 of this year and should be doing 600-800 tonnes daily when at capacity. Prices have ranged $160-218 p/tonne over last few years so this looks like a business able to generate $35m+ (the project has had over $100m spent on it in Capex as well historically). So even if they make a 15% margin this could be very significant compared to market cap.
Not often I see something in this space that peaks my interest but this looks like it has a good risk/reward to me. Today they were awarded an extra licence but the bit that I noticed was that their ancillary revenue streams are already generating positive operational cash flow and the quicklime hasn’t even started yet!!
Interesting. Wonder why the price/cap is so low - anyone any ideas?
I haven't looked at Firering Strategic Minerals (LON:FRG) in a long time so I could be way off the mark here but I think they used to be focussed on a v early lithium explo play in Ivory Coast and have now switched to Quicklime in Zimbabwe. Bit of a red flag imo when a mining co switches like that. I think the key mgt & funders were Israeli, don't know if they still are. Some people are sceptical whenever they see Israeli involvement. There's obvious jurisdiction risk in Zim. Key for any pre-revenue miner is funding. I don't know if they've sorted that but heavy dilution is the obvious risk but with such a low mkt cap they might look at debt funding but v difficult to source that on reasonable terms. Quicklime is not a common mining investment for most retail punters so there's that as well. Maybe it's a great investment, who knows.
Hi Joe
They are not in Zim - they are in Zambia which is one of the largest copper belts in the world so quicklime is key to that smelting.
Fully funded as far as I am aware as they did a placing recently, are operating cash flow positive according to the rns and starting quicklime production in Q4 - so very imminent and Capex requirements already taken care of.
I think historically the strategy they set was multi-mineral - ie strong cash flow generating projects coupled with early stage plays. Don’t think they’ve deviated from that.
Not sure of nationality or residence status of management - haven’t looked at that, only the previous cv.
I like that quicklime is not a retail punters mining delight. I avoid those like the plague, so I am intrigued by this one as it looks to me like it could be a seemingly “boring” stock that retail has not got excited about that could throw off more cash than its market cap very quickly, hence my risk/reward comment at just a £5 or 6m market cap.
The market cap is £6m for very good reason.
The key piece of information is contained in the circular linked to the May placing;
https://www.fireringplc.com/ul...
"In addition to the shareholdings referred to above, at the time the shareholdings are acquired, Firering (and/or Clearglass) will acquire the same proportion of shareholder debt (“Shareholder Debt”) which is currently owed by Limeco to the Vendor. As at 31 December 2022, the most recent published audited
accounts for Limeco, the Shareholder Debt amounted to $104,509,835."
So on the next set of accounts they will have over $10m of debt, which will increase to $20m if they find the extra money to get to 20%, as the £2m net raised in May will only cover the first of 3 payments required by next April;
"US$1,500,000 being payable no later than 30 June 2024 to acquire an initial 10% interest;
• US$1,016,667 payable no later than 31 December 2024 to acquire a further 6.7% interest; and
• US$1,033,333 payable no later than 30 April 2025 to acquire an additional 3.9% interest."
So it looks odds on there will be another placing needed later this year to pay for the second instalment & then goodness knows how much more they will require to get the plant going.
All in all it reminds me of PREM, it's certainly a deal that George Roach could have put together! Avoid at all costs, unless you want your pants pulled down.
Hmm - thanks for that AimingHigher : I hadn’t seen the debt structure in that memo which certainly would explain the market cap.
The plant is basically ready to go judging by the rns today since they start producing in the next 2 months so I wouldn’t expect large plant capex costs.
But presumably the business plan then expects the cashflow from commencing operations to pay the debt and funding, with all the inherent operational risks that brings. And irrespective, of whether they can/can’t do that the debt transfer changes the risk/reward profile considerably.
Meh!! This is why I usually steer clear of small resource companies ; there’s always something!!!
Good spot - much appreciated.
The update from Watches of Switzerland (LON:WOSG) , extract below, echoes the commentary from Ramsdens Holdings (LON:RFX) , which remains cheap and I expect to do better than the market is currently given it credit for.
"Over the period, we have seen continued stabilisation of the UK market in both luxury watches and jewellery following a period of challenging macroeconomic conditions in the prior financial year."
I hold Ramsdens Holdings (LON:RFX) and have been adding recently. Just my view.
Michelmersh Brick Holdings (LON:MBH)
Pleasantly muted market reaction thus far. Trading around 96p/97, bid/offer. I have a reasonable holding and sold a few at 96p, which was my original purchase price to raise money for another share that has caught my eye. However I have retained close to 70% of my holding as it must be close to the bottom of the cycle and Michelmersh Brick Holdings (LON:MBH) remains cheap on fundamentals relative to Forterra (LON:FORT) and Ibstock (LON:IBST) plus is cash positive.
Maybe its the market collective taking a somewhat more sensible view and recognising that the demand for bricks has hit basement level rather than rushing for the exit. Bricks remain essential to house construction, which according to the government's mantra is one of it's priorities.
Incidentally broker forecasts are for 7.7p of earnings this year rising to 10.3p for FY 2025.
We're holding MBH too jonno, we have a government determined to increase house building so we'll wait patiently for the cyclical upturn. Macfarlane and MBH are our top two Green holdings by number of shares held, I'm hoping MBH remains green today! Cairn Homes tomorrow reporting on a much better outlook for builders in Ireland.
Pennant International (LON:PEN) (I hold)
Further signalling of ambition with the appointment of the Intercede CEO to the Board.
No doubt these moves will take time before they are reflected in performance but it's undoubtedly positive, I'm sure the Staveley pitch here is influential and I watch and wait with interest...
Pretty tough economy and entrepreneurs on the slide and labour is the death blow .
Got my negative head on today .
Have to say Michelmiirsh brick is a warning flag that the economy is subdued / on the back foot and there just isnt any buzz just a grind along / down .
What has occurred to me is that the breed of entrepeneurship. Kickstarted in the 80s by the maggie thatcher “build your own business” bandwagon has come to an end with that generation now all retiring or packing in because of the woke mental health lifestyle brigade .
In my albeit tiny circle of Sheffield business group I see wiithout exception everyone literally packing in / selling up / exiting . Its untenable for most to continue with staff issues and now Starmer is the last straw no point building a business of value when the value just “plugs a black hole”
The issue is there is no grand sweep to follow through, who on earth would start a business in this economy, with this government , and this labour force .
What is even more noticeable is how society now sees zero value in a “trading” business .
I had a debate last week with one of my staff who “wanted yo go travelling” about how marco polo was a great trader and a great traveller , and that travel does not always have to be about the need for self but is actually part of journey .
Shes off to South America , I then said
“Tell you what we will pay all your trip and you can go buy 20 grand of coffee and do it aa a sourcing trip”
May as well have been speaking Chinese .
Big problems ahead me thinks in the next 20 years , a generational shift has happened .
So very true planetx. As a shareholder in Michelmersh Brick Holdings (LON:MBH) I am disappointed in their results, but not really surprised bearing in mind the state of the country and economy . Business confidence at an all time low and it’s reflected in the wine merchant I own . It’s a long standing business based in London , but the young don’t appear to buy wine ( or at least not decent wine ) and our older customers are cutting right back . So a business that has been in existence for over 40 years , will almost certainly not last the end of this decade .
I am selling most of my U.K. portfolio and switching to mainly US and selected European , with about 25% cash .
Hi Planetx - but why are you only buying enough coffee to keep me going for a month or so ;)
We’ve already seen how stupid labour can be, so everyone is scared stiff of the damage their October budget will do. Scary times.
I've got too much respect for your experience planetx to pick a fight over politics but here's a more positive comment on the future. Last night one of our grandsons brought us up to date on his life between Oxford and London. He's 24 with energy and brain power to spare, he loves the science and engineering research he's doing and the department will fund a Phd if he stays. He works out, runs, and competes in salsa teams for relaxation. None of his large group of friends get wasted or spend much time on social media, most don't drink at all, they all work hard and are excited about the future. Re trading, I've still got some Del Boy in me, if your staff member takes you up on the coffee deal, can I go half in?
When the Prime Minister and Chancellor portray such a gloomy message about the UK purely to suit their own purposes of wanting to raise taxes by blaming the opposition, that has the potential of a real economy doom loop. Business confidence has plummeted in the latest surveys meaning that businesses are investing less which leads to lower GDP growth. That feels like a very naive pair of politicians to me given the manifesto pledges around growth. A tax grab then further reduces spending, and a grab on CGT etc. will reduce entrepreneurship even further as well as damaging the stock market.
Half of the so called black hole was actually made up of the bumper pay rises to the public sector as recently announced (c £10bn before the future pension requirements), so this sleight of hand only really goes to show the level of contempt politicians are showing to the British public and voters. Unfortunately, in my view this lot is just as bad as the last lot which depresses me. Cronyism is as rife as it was under the Conservatives and wealth flows are already starting to move abroad. The Government is quite clearly showing themselves as a command and control party with the likes of the outdoor smoking restrictions that threaten an already beleaguered hospitality sector, threats of very large fines to companies who breach their idea of worker rights, potential mandatory 4 day working weeks.
I can’t see how any of the actions taken so far match up with any of the manifesto - business friendly, growth orientated, no tax grabs, reset of politics, supporting the UK capital markets. Everything being proposed is the opposite.
You really need to question the ability of the advisors and the quality civil service economists, combined with the lunacy of net zero policy, economic decline is inevitable. Surely they are not advocating an economic blowout?
Hi JASVFS,
Yes I also think a more positive view on younger people is justified. I've spoken to some, and it has surprised me how entrepreneurial they can be. Many have "side hustles" on the go, where they e.g. buy & sell vintage clothing on Vinted, some sourced from charity shops in posh areas just a bus ride away, etc. Or they make videos and try to become influencers, and earn money online from ads. Some do zero hours contracts work in several pubs, and cherry pick the shifts they want, flatly refusing anything they don't, unless a sweetener is added. Many of them don't drink alcohol, whereas my generation got/gets wasted at every opportunity.
I suspect there's a lot more potential out there than us lot of old crumblies here might imagine! ;-)
Regards, Paul.
Paul
My point is where is the “push” to help them along ?
How about the government incentivises, motivates, encourages and champions this.
Tony Blair did a huge dis service “everyone should be able to get a university education” .
I see regularly a steady flow of entrepeneurs working away but they are not supported or championed .
Had a young lady in today making dog harnesses etc all hand made in uk, cant quite go full tIme bit ever so close .
If she had support to go full time pretty soon she would need her first employee , she said as much .
Its just not actively encouraged, anyone in the 80s who “started their own business” was perceived positively by all.
Instead lets soend 10 billion on health service and we can all pay for it .
No problem on the coffee deal , ill send my bank details later for the 20k
Reminds me last year I was in java with the guy im doing business with .
I said “could do with sourcing sone coffee we used to sell a bit at banana industries”.
Next day were up early and i ask where are we heading. “To view the coffee plantation, dave is good deal 80 hectares can make 8000 kg of best java coffee “
I said “i only meant a few 100kg not a bloody plantation”
We then spent the entire day there and in the evening I worked out it was only 250k usd which seemed a good deal so i said “ok lets go for it”
Next day they request 20% deposit and send invoice for 500k
Turns out price was 2.5 million not 250k Id lost a zero somewhere in the calculation.
Didnt buy the coffee plantation .
Interesting thoughts Planetx my two penneth as there are indeed interesting times coming down the pipe.
I work in wealth management industry if your prepared to put 3-5 years of graft in to learn the basics and can tolerate over regulation there is still a decent living to be made.
At the moment there is roughly 31k (ish) financial planners country wide with a third of these anticipated to retire next 3-7 years.
When I go to regional learning days where roughly 150-200 people will attend I am still in the youngest 20% of the room at 55 with most people in sixties or early seventies.
There are a handful of younger people in the room so hardly anyone coming through the ranks.
Some of my friends have their own businesses they tell me when they advertise for staff half of the people applying don't even turn up.
I have said to my two young son's look smart, learn how to engage people in an interesting conversation and you will be ahead of 50% of the applicants before you walk through the door.
I do think covid changed the UK mindset a lot of people after furlough don't want to work anymore or just want 2/3 days per week hence huge numbers of economically inactive.
Also if you are young in a couple and have no hope of getting on the housing ladder and assuming you have three or more children financially you are way better off to both work two days per week each and then max out on universal credit.
The above situation won't change anytime soon as the UK Government knows we don't have enough young people being born so benefits are in place to encourage big families.
If your young and prepared to put a shift in there will be huge opportunities if your young with lots of children and don't want a put a shift in you will be okay for as long as the UK can keep racking up the three trillion national debt.
Sadly we live in a benefit based society where the incentive to be self reliant is seriously eroded. No wonder Stammer took down Maggie portrait, she was flowering at him!
I agree that some of the generational attitudes may end up having long-term repercussions for the UK economy. I would particularly highlight your reference to 'going off travelling' as having potentially significant consequences for the future.
A couple of years ago, a school friend of my daughter's who was in his final year at university, was trying to get into the city. He asked me to look at his cv and said that if he couldn't get a job as a trader with a merchant bank (he was studying Economics at a Russell Group so this wasn't an entirely unrealistic proposition) he thought his best 'option' was to go off travelling. I pointed out that going off travelling was actually not a plan, should not even really be regarded as an 'option', it was actually just an admission of defeat. I pointed out that said travelling was unlikely to make him appeal more to merchant banks on his return - he would just be a year older and competing with younger candidates who didn't have to explain what they had been doing for the last year. I advised him to get a job on the periphery of banking, get some experience and apply a couple of years later to the companies he was getting rejections from. That's what he did and two years later has just started working at Goldman.
The point of that story is that many of my contemporaries forty years ago who didn't have what it took then (which, to be fair to this generation, was far less than they're required to have now) to get into their careers of choice, didn't regard that option of 'travelling' as a substitute. Instead, they set up an estate agency, or an import-export business, or a bar or multiple other activities that not only taught them valuable, transferable life lessons but also, in the process, created thousands of small businesses, out of which emerged some much larger businesses that still exist today. They contributed to a thriving base of small businesses and created a generation of risk-takers. Risk taking now seems to be all about zip-lining or bungee-jumping while off travelling which doesn't really contribute to the UK economy unless you consider 'influencing' as contributing to the economy (which I sadly have to concede it probably does).
Setting up a small business in the 1980s was all about the prospect of potentially making lots of money, albeit it was also usually accepted that success would come slowly. It wasn't necessarily about doing something that you loved or about making a fortune quickly. Small companies weren't overwhelmed with compliance issues and administration was a sensible proportion of a business-owner's time commitments. It's partly understandable that young people are put off starting small businesses in the face of all the costs and headaches of compliance which is much more burdensome now. There's also huge social media pressure now to emulate other people who seem to be making money quickly rather than gradually - hence the huge rise in gambling whether that's bitcoin or punting on GameStop.
Young people's prospects of being able to earn enough from a small business to pay a mortgage on a house in the south of England are vanishingly small. Yes, I can hear you say that it's perfectly possible to do so in Sheffield, but there's a whole swathe of people brought up in the south who might previously have opened up businesses in that area who now are deterred from doing so because there's no real prospect it will provide a livelihood. And, consequently, they go off travelling ignoring the consequences for their future. Each year they take out of the conventional workplace makes them that little bit less employable, doesn't really add much to their skillset and, ultimately, only increases their anxiety over ever being able to earn enough money to join mainstream society. In the meantime, thousands of small businesses - the bedrock of a thriving economy - don't get set up. It's noticeable that in the world's biggest economy, the US, the concept of travelling as a substitute for setting up a small business doesn't really exist. And the bureaucracy around doing so is far less than in the UK.
So, if we want to avoid multiple generations of non-starters with the consequent impact on their mental health, the government could try doing a couple of things. Firstly, it needs to make setting up and running a small business for young people less daunting either through relaxing regulations or through teaching the basics of doing so in the education system. Then it could be clearer about the dangers of treating travelling as a substitute for working (unless we want a whole economy based on 'influencers'). Finally, until we help young people aspire to be able to own a property in the south of England, it's going top be very difficult to persuade them that industry is worth forgoing hedonism. Some attempt has to also be made to show that 'influencing' is not, realistically, a long-term or even (in most cases) a lucrative occupation.
This is spoken from observations of my children's friends (almost exclusively from what would be regarded as the privileged upper middle class, so a frighteningly irrelevant demographic) rather than personal experience. These are lessons that I passed on to my two daughters who absolutely love travelling but regard it as something they do as downtime from their professional jobs not as a potential substitute for those jobs if they get bored.
My only observation on the above is that many affluent children don't have the need to actually get up and do a days work as it won't affect them.
I can't ever remember mental health issues being a malaise of the working class, if you didn't go to work, you didn't get paid and then you didn't eat.
Young people love to moan these days, but they seriously do not know how easy they have it in reality. OK, house prices have risen, but I grew up in London and had to move to afford to buy my house (in SOUTH London!)
The amount of tech, govt assistance (childcare / right to buy / shared ownership) instant access to infirmation and knowledge, I know would have given me a massive help up.
Perhaps one thing I would say is the 'ambition'. Growing up in the 80's you knew you had to work hard, move up the ladder and then good things will come. The youth of today are expecting £100 trainers, 50k jobs and a first home worth 500k+ and if they can't get it, they view it as not worth it.
It was drilled into a generation over a good few years by Mrs Thatcher specifically that the future of the UK would be built by its own people building businesses and working hard .
That generation is now gone .
I was brought up in a mining village ripped to pieces by the same Thatcher and saw the steelworkers slowly lose their industry .
Even I actually started planet x on the back of getting “enterprise allowance” of 40 quid a week for 2 years .
I wonder what the input /costs output benefits were into this scheme .
Anyway got to pack some orders .
I agree with you that, in many respects, the government has provided financial assistance to help people of all ages start new businesses or own property. And I totally agree that the internet has created a frictionless, transparent and, potentially, level playing field for people from different backgrounds. There's also far more schemes to level up people from different parts of the country than forty years ago.
However, what the internet has also done is led to vast numbers of young people either living their lives in the public gaze or obsessing with other people's lives (both known and unknown) that they see on social media. This has led to huge social pressure on young people to be 'successful' (whatever that means). Huge pressure on young men, for example, to work out at the gym (a 20s friend of my daughter says that he sees boys as young as twelve working out in his local gym) and huge pressure on young girls in all kinds of directions I won't go into but which we read about all the time. Unfortunately, many young people feel that they simply can't compete with what they see on social media and, so, opt out of leading their own perfectly normal but (to them) less interesting lives than the ones they're looking at. And - if they can't see how they're going to earn a living wage from doing so - where's the incentive to take the risk of setting up their own business?
When they realise their educational achievements aren't good enough to get a conventional job that enables them to survive in the south of England and that even if they had been they would still have to wait for their parents to die to have enough to put down as a deposit on a two bed flat, they say, 'oh well, I'll do something more interesting with my life". Hence, the growth in people doing portfolio gig jobs and other far less productive activities which they console themselves they will just do to fill in until that big break drops into their lap - the classic actor working as a barista who's 'filling in time'. Then they wake up at 30 and realise that, well, perhaps they have actually become a career barista as they haven't had an acting job for eighteen months. And, of course, unscrupulous companies (answerable to shareholders, who can blame them?) have exploited this ever-growing army of young, dissatisfied and indigent people, giving them zero-hours contracts and no/the bare minimum of benefits..
And this hollowing out of generations of young people's potential careers is only going to get worse - much, much worse - with AI. Even (possibly, especially?) moderately complicated jobs that were previously done by people with degrees - particularly in professions involving data analysis like audit, law and finance - disappearing. So, more than ever, we need to create a generation of fighters, not quitters. People who set up businesses rather than go travelling.
We need to help young people build resilience and realise that what they see on social media is pure fantasy. It's okay not to be driving a Ferrari in Dubai at the age of 28.
There's a lot of wisdom in your comment mammyoko. Imo no matter what educational level you reach, success in life is mostly about work ethic, you either have it, or you don't.
While I agree that work ethic is the key to leading a purposeful life, it's easy to understand why many young people in the south of England have decided that the equation doesn't work for them. They look at the sacrifices and risks that they're going to have to make/take and the likely rewards that will flow from their choice and have come to what they believe is the logical conclusion that the risk/reward is not in their favour. In the absence of family assistance, why work fifteen years to save enough for the deposit on a flat in London? When the alternative is to enjoy their twenties (then thirties, etc) in spells of administrative roles followed by travelling the world and posting to all their mates what a great time they're having?
Within three years of leaving university in the 1980s, I was able to buy a two-bed flat in a nice square in SW1 on a 90% mortgage for GBP120k. Now my daughter, three years out of university and in a similar earning role has no prospect of buying that flat which sold a few years ago for GBP1m. The property market in the south of England id the greatest deterrent to ambition possible.
I don't think the problem is solely about having or not having a work ethic. I think it's also about incentives. We had them (not just a functioning property market but other things like the tail-end of DB pensions) so it was, arguably, much easier for us to have a work ethic than it is for our children.
Wow. I work in a sixth form college and this resonates hard with me. Please can I copy and paste your post and send it some of my colleagues who teach business?
Of course. If it stops one young person from throwing the towel in and saying 'I'm off travelling' when what would have been best for them is to get someone to help them build a career/start a business then I would be very happy.
A good work ethic was always a quality to be admired but now it would seem that hard work is seen as foolish and naive in a get rich quick world of self gratification. This is a Western disease. Lazy, entitled people. Asia is the engine of future economic growth where hard work is still admired.
Having lived in Japan and traveled all over China, I wouldn't think there is much chance of the west ever being able to compete with the east in terms of work ethic. I love the safety, security predictability and considerateness of life in the east but it entails huge social problems for non-conformists. Japan is the only country in the world where suicide is the major cause of death in under-18s.
However creative the east is and however much more globally competitive it is becoming in that area, where our youth and the companies they set up or the companies they work for can hope to compete is in creativity and, paradoxically, non-conformist thinking. If you're a young person in Japan brought up in the Japanese educational and social system, thinking creatively and making unconventional links that lead to progress, does not come as easily as it does to those brought up in the west.
Hi mammyoko
I too spent many years in Japan, where low interest rates distorted society long before we experienced something similar.
What I observe in the UK now does have some parallels with the "akirame richi", young folk in their 20s who spent a small fortune on their cars because they had given up on the prospect of property ownership.
And I have been very careful to keep my children away from anything like the "juku"!
It's an interesting post including some of the sub-posts. I'm not particularly anti- labour or the public sector and I think some of the points you raise are probably more cultural than political. Cultures emerge over many years under various regimes. Some aspects of modern Bohemian culture I despise. The travel generation a strange quirk of this modern world but equally so are the modern independence movement who strive to cut their budgets to achieve early retirement as long as we spend our money to pay their dividends. We can criticise the big public sector but there are also big company bosses in the private sector getting massive remuneration far beyond the value they add. Benjamin Graham highlighted this many times. The focus, however, on small business is totally right. That is where the jobs of the future will be as big companies largely automate everything. Anyway a great post especially the paragraph about the state of the economy. Hargreaves Lansdowne made the same point. If construction is struggling like Michelmersh it doesn't really augur well for the economy whatever the stock market is doing.
Read this to my son; We live in Malvern; he fancies a trip to Brazil. Better carnival. He said he'll get 4.6MT of arabica coffee for £19K CIF. October half term ok? He's 15... :)
29k for 4600kg is very good provided of course its great coffee
Lets book him a flight
At 29K he's all in! BTW if you like coffee & business this Starbucks/Schultz interview by the Acquired podast crew is V good. Like a triple espresso. Incredible journey. Did not know that Bill Gates Snr and Sinegal Costco were the earliest investors.. https://open.spotify.com/episo...
This thread reminds me a bit of the old Monty Python/ Tim Brooke Taylor ‘ Yorkshiremen’ sketch - “ In my day”, “ You were lucky”, “ A cardboard box in the middle of the M1 - luxury ,” ! !
I wonder if, perhaps like many generations, we are underestimating the next generations. Seems to me that they seem much more switched on about the environment, racism, sexism, the dangers of alcohol, homophobia, awareness of world affairs and lots of other things. Which cannot be anything other than good.
I agree that, back in the day, there was much more support available for small businesses and entrepreneurs, even as recently as 15 years ago ( eg Business Link) .
But there may be another side to the coin of how Thatcher encouraged entrepreneurship . Perhaps it went way too far. A huge focus on self, and a reduction in care for the rest of society. Maybe some younger people are simply dissatisfied with the notion that they should spend all their time trying to get rich. And in fact perhaps they are completely turned off from the business world when they see the excesses of big business, the fat cats, the immorality of excessive profit making and the constant wrong doing and even deliberate exploitation and fraud by many businesses and business people which are reported every single week in the press.
Work/Life balance has truly got a hold. Maybe many young people just don't want to slog their guts out for 50+ hours a week in the hope that they become very rich. Maybe they don't care about becoming rich. Maybe other things are more important to them now and they are just satisfied to have a reasonable standard of living alongside a fulfilling and enriching personal and social life.
Surely, going to the gym, keeping in good shape and eating carefully are good things ? And if that behaviour encourages their peer group to do the same , then isn't that a good thing too ?
Similarly, taking a year out to go travelling seems to me to be an immensely beneficial thing to do. To have the confidence to do that, to have those experiences and to see people who do it leave as a boy or girl but come back a woman or man is such an impressive thing to witness. As a job recruiter in the businesses that I helped to run, I was always impressed by youngsters who had the gumption to spend a year travelling and it gave them an edge over their competitors for the role, in my mind.
Im over 60 now, I left university with 8 close friends in the early 1980s. Only one is still working now. Its absolutely natural that people of my age are looking to get out now, realise the fruits of their hard work by selling their businesses and looking forward to spending a very active and fulfilling retirement for many years to come in any way that they wish to choose.
Getting rich was never the motivation for me to start my own business. Getting rich can only ever happen if the business is successful. It is the journey to getting there that is the real reward. I was determined to be the master of my own destiny, to build something meaningful and valued. The most important and challenging part of growing a business is creating motivated teams through a continuous process of learning and development. I look back with pride on the dozens of people I helped develop who are now running their own businesses or in management positions. IMO that is the real value of developing a business.
Totally agree SC120
Cavendish note - Alumasc (LON:ALU)
FY24 results were £0.4m ahead of forecast at the adj PBT line and 2.3% ahead at the EPS level. All three divisions saw sales growth and profit advances. Results illustrate a strong performance against challenging underlying market conditions.
This was generated by strong export sales, new product launches and the ARP acquisition. Management efficiency programmes continue to drive margins despite the tough underlying UK construction market. We upgrade FY25 EPS expectations by 5.0%.
Outperforming most of its sector peers, the shares have appreciated, helped by a more positive construction and infrastructure government agenda and expectation of further interest rate reductions.
We raise our TP from 315p to 330p, which offers decent upside for the rerating to continue, with the shares at a compelling FY26E P/E valuation of 8.0 x with a dividend yield of 4.5% and FCF yield of 10.7%
From FY results comments- Watches of Switzerland (LON:WOSG)
"The Group is exposed to movements in the £/$ exchange rate when translating the results of its US operations into Sterling. The Actual average exchange rate for FY24 was $1.26. FY25 guidance assumes a £/$1.25 exchange rate, with a five cent move resulting in an adjustment of c.£30 million to full year Group revenue and c.£4 million on full year Adjusted EBIT, on a pre-IFRS 16 basis"
£ = $1.31 now
Good spot eParo. That’s useful to know. Don’t own Watches of Switzerland (LON:WOSG) but have been watching and didn’t notice quite how profound $ level is for them.
Don’t own Watches of Switzerland(LON:WOSG) but have been watching and didn’t notice quite how profound $ level is for them.
Certainly a short term headwind relative to forecasts but I see the US (and USD) exposure as a long term opportunity.
I do hold as part of my luxury theme, alongside Ferrari NV (NYQ:RACE, Hermes International SCA (EPA:RMS), LVMH Moet Hennessy Louis Vuitton SE (EPA:MC) , COMPAGNIE FINANCIERE RICHEMONT SA (SWX:CFR) , ironically because it has the potential to prove to have been very cheap at my entry earlier this year.
Yes - slightly kicked myself that I didn’t pick some up around the 350p level tbh BnB
Not keen on chasing Watches of Switzerland (LON:WOSG) here though as I can see usd/gbp going higher - maybe back towards $1.4 and if that does transpire it will be a £12m headwind on profits in FY25.
But on my “watch” list……sorry couldn’t help myself…
Ultimate Products (LON:ULTP) - New Board appointments support growth potential - link to new note: https://www.equitydevelopment....
Strong relations with UK retailers and the potential to build on European expansion are important components of the value proposition and growth case for Ultimate Products plc.
The owner of the Beldray and Salter brands today announced two important Board appointments that are consistent with those objectives. As a brand manager with clearly prioritised distribution channels, we retain our 200p Fair Value for UP’s shares.
UP is to appoint two new Non-Executive Directors, both of which have pertinent experience and strong track records, to its Board with effect from 28th October this year. Andrew Milne, the current CEO of diversified and international soft drinks group Nichols plc, and José Carlos González-Hurtado, who holds Senior Advisor roles at global private equity firm Advent International and Roland Berger, an international management consultancy. We view these appointments positively.
Today’s announcement is consistent with UP’s growth strategy, which is driven by a twin commitment to its brands and distribution channels.
We reiterate the case for a 200p fair value, at which the company’s FY2025 EV/EBITDA would be 8.9x and its prospective P/E ratio an undemanding 13.8x.
My morning smallcap tweet: Mastering the market's three-cups game
Ondo InsurTech (LON:ONDO) Petards (LON:PEG) Amati AIM VCT (LON:AMAT) Aptamer (LON:APTA) EnSilica (LON:ENSI) RM Infrastructure Income (LON:RMII) Inspiration Healthcare (LON:IHC) First Property (LON:FPO) Michelmersh Brick Holdings (LON:MBH) Alumasc (LON:ALU) Manolete Partners (LON:MANO), Midwich (LON:MIDW)
◄Ondo Insurtech (ONDO)► LeakBot contract with National Farmers Union Mutual which has 900k customers. LeakBot "will be rolled out across its members". I'm sure they'll be flattened. [SP=14.5 Cap=17m]
◄Petards (PEG)► wins contracts worth £0.75m for delivery this FY and next. [SP=7.22 Cap=4m]
◄Amati AIM VCT (AMAT)► strategic review update: co has received a number of credible indications of interest, including proposals for a change of manager and proposals to combine its investment portfolio with an existing VCT. "eceived a number of credible indications of interest, including proposals for a change of manager and proposals to combine its investment portfolio with an existing VCT." [SP=80.01 Cap=119m]
◄Aptamer (APTA)► extends contract with Unilever to progress Optimer for deodorant development after successful lab-based tests. [SP=0.23 Cap=4m]
◄EnSilica (ENSI)► wins production orders worth an estimated $30m+ over seven years for an Arm-based Industrial Controller ASIC. [SP=45 Cap=43m]
◄RM Infrastructure Income (RMII)► £20m max tender offer at NAV. [SP=72 Cap=86m]
◄Inspiration Healthcare (IHC)► guides H1-July rev £17m, in line. Gross margin c.44.5% due to sales mix with increased sales of lower margin product. A warning? [SP=25 Cap=22m]
◄First Property (FPO)► £3m 1 for 3 OO at 8p, a 52.4% discount, to pay deferred consideration payment due on the Blue Tower property and working cap. [SP=16.25 Cap=18m]. I hold.
◄Michelmersh Brick Holdings (MBH)► H1-June rev down 16% and adj pretax down 22%. Outlook sounds in line. [SP=104 Cap=97m]
◄Alumasc (ALU)► FY-June U/L pretax up 16%, ahead of recently upgraded expectations. Outlook - "encouraged by early indicators of easing in planning, improving consumer confidence and the interest rate outlook which suggests an improved trading outlook in due course". [SP=255.6 Cap=92m]
◄Manolete Partners (MANO)► FY-Mar. Outlook - YTD new case enquiries up 22%. [SP=144.99 Cap=63m]. I hold.
In line: MIDW
Gulf Marine Services (LON:GMS) should be reporting soon (August 31st last year), and I look forward to an update on the debt reduction.
Any news about share sale overhangs would be great!
I’ve got no idea how that gets policed, but assume that in the longer term it just encourages these businesses to prioritise their manufacturing elsewhere. All are multinational companies after all.
Michelmersh Brick Holdings (LON:MBH) ’s results just show how well Alumasc (LON:ALU) is doing, with good growth from the same sector with PBT up 16%
Half year results out of Michelmersh Brick Holdings (LON:MBH) today. I used to hold, but sold out because of concerns about the market and the company building bricks for stock.
Results summary:
Revenue (15.7%) - not too bad but they had a decent forward order book
EPS (32.8%) - worse than I expected
DPS 1.6p v 1.5p
Big jump in inventories and drop in payables. Not so good.
Cash £4m v £11.8m. Cash flow not looking great to me.
Lots of share options settled over last two years.
I would really appreciate a thorough look at these fairly clear accounts. I think the company is exaggerating the brick downturn. Government numbers aren't so bad, although total brick sales are well down.
I like the company, but the cash flow looks weak to me. Perhaps ready for a cyclical upturn.
I'm assuming that there will be a decent drop in the share price today, but who knows....
Michelmersh Brick Holdings (LON:MBH) (no position)
On your point about "fairly clear accounts" I stopped my research this morning when I realised that they had excluded half the cash flow statement - they've never done that before, so it's a red flag for me. Why exclude working capital movements?
A
Having been a holder of Michelmersh Brick Holdings (LON:MBH) since March 2022 I sold this morning for a mere £100 profit. Time will tell if it was a good choice or not. My reasons for selling were: profit warning, despite the report sounding bullish it was a fair hefty profit warning imo. Secondly, it sounded like the company does not expect to pick up in the next 6 months which makes me believe it will go sideways for a while. Thirdly cash level has dropped significantly which makes me wonder what level the cash will be at come the next report. Fourthly, I was worried a while back when the joint ceo was leaving to join Brickability (LON:BRCK) and any possible implications that may cause or if he saw it as a time to leave because the business might not do as well.
I will continue to watch and see what happens, but there are plenty of other good companies around atm I can buy into.
Michelmersh Brick Holdings (LON:MBH) looks like a profit warning to me. "We expect our second half performance to be broadly in line with our interim results" would leave them far off Stocko full year estimates. There's a new broker note out this morning which might confirm this but I don't have access.
I don't hold but I am keeping a close eye as might be a nice opportunity to buy in at the cyclical low.
Looks like about 6.6p of EPS for the full year, well below forecasts. No idea what the brokers are saying.......
Michelmersh Brick Holdings (LON:MBH)
Canaccord:-
Forecast EPS 2024 reduced to 7.7p from 10.7p
Forecast EPS 2025 reduced to 10.3p from 11.2p
A.
Alumasc (LON:ALU) on track with a small upgrade to recent profits. Confident tone.
Watches of Switzerland (LON:WOSG) also bullish, albeit H2 weighted in the US.
Given the slow current state of our building industry I think the results from Alumasc (LON:ALU) are great. CEO comments;
“We are extremely pleased to report a further upgrade to our 2024 profit, with underlying profit before tax* of £13.0m, 16% ahead of the prior year. All three divisions saw organic revenue and strong profit growth, a result of continued delivery on our strategic priorities and Alumasc's position as a market leader in the provision of sustainable products, which provide efficient solutions to the challenges presented by our changing climate.”
Hopefully more to come as building sector picks up.
Given the slow current state of our building industry I think the results from Alumasc(LON:ALU) are great
Certainly. But it also underlines the importance of regulatory drivers. Compare to Marshals or the brick makers which are waiting for demand to return.
ALU is part of my Water theme, which includes Genuit (LON:GEN, Advanced Drainage Systems (NYQ:WMS, Xylem (NYQ:XYL) and Veolia Environnement SA (EPA:VIE).
BnB - Thanks for Water-themed stock list to look at - have you also looked at Water Intelligence (LON:WATR)?
BnB - Thanks for Water-themed stock list to look at - have you also looked at Water Intelligence (LON:WATR)?
Yes. I concluded that it is run for the benefit of management, not the wider shareholders.
Thanks for those suggestions BNB
I've been put off by Veolia Environnement SA (EPA:VIE) in the past due the share dilution + rising debt, although you can't argue with the share price over the last 10 years.
But the other 2 look interesting - thank you.
I also own some Hawkins (NSQ:HWKN) which is pushing into the water treatment segment if that is of interest.
I've been put off by Veolia Environnement SA (EPA:VIE) in the past due the share dilution + rising debt, although you can't argue with the share price over the last 10 years.
Debt is lower than peers and valuation well below, yet this is the largest water utility in the world. Good yield, although French tax doesn’t help.
Has anyone have any views on whether yesterday's UK ban on arms sales to Israel will have any material impact wrt defence stocks such as Rolls-Royce Holdings (LON:RR.), Chemring (LON:CHG) & BAe Systems?
Apparently among the items that will come under the suspension will be components for military aircraft including fighter jets, helicopters and drones.
https://www.bbc.co.uk/news/art...
Did you notice that Cathay Pacific are suspending flights on RR powered Airbuses of one model, due to component failure?
yes I think that was more the reason for the drop GreyInvestor ?
Rolls-Royce Holdings (LON:RR.)
Just read that the Rolls Royce (LON:RR.) engine ‘failure’ is due to a fuel line constriction problem……So to my mind that doesn’t make it an ‘ Engine failure’ ….Now obviously I know that for an engine to work it needs a constant reliable fuel feed but whether the piping concerned is supplied by RR for their engines and therefore their responsibility or the problem of the piping manufacturer or even a technical maintenance inspection oversight I have absolutely no idea
Re: Rolls-Royce Holdings (LON:RR.) Engine Component Failure
News feed here on Stockopedia indicates that the engine component failure that has led Cathay Pacific to inspect all engines for its Airbus A350 airliner fleet concerns a fuel injector nozzle (there are many injectors in each engine - their job obviously being to spray fuel into the combustion chamber and thoroughly mix it with air). This is (or always was) a Rolls-Royce-produced part, but regardless, Rolls-Royce has ultimate responsibility and liability for all components in its engines.
I worked as a metallurgist for Rolls-Royce for over 15 years and took voluntary severance in spring 2015.
Maybe restricted by green fuel?
It only represents 8% of UK arms sales to Israel, so would expect the impact to be tiny.
Anything to do with F35s aren't covered by the ban as that is covered by an open licence.
It's only come about after 5 FCDO legal advisors threatened to resign, so it seems like it's the minimum they needed do to prevent that embarrassment.
Hello Paul,
sensible question.
With UK export licences to Israel <£50m in 2022 - No I don't expect the suspension of a small portion of that to affect the share price of mult-national companies like Rolls-Royce Holdings (LON:RR.) and BAE Systems (LON:BA.). Chemring (LON:CHG) is an interesting question - I don't know the answer but the most likely chemring exports to Israel are most likely defensive (countermeasures and decoys) so quite possibly won't be affected?
It's all about the politics?
Six British governments have restricted arms supplies to Israel - including Thatchers Government.
In the commons David Lammy noted 'noted that he had not gone as far as Thatcher when justifying his decision to suspend just 30 arms exports out of around 350. '
This kind of suspension or delay in the approval of export licences is nothing unusual. In my experience as a non-NATO country and with plenty of history Israel is always in the 'difficult' box. The Israeli industries will be prepared for it and UK companies are also used to coping with changes and delays. As I understand it the affected licences are UK produced components on large systems used by multiple countries uncluding the US - eg the F-35. There are a number of ways around the suspension.
[1] In the short term Israel is likely to have a stock of any parts needed
[2] In the longterm it may be simpler for Israel to buy the components from stock of another country that uses the same system rather than directly from the UK.
That's not going affect the volume of shouting from all sides though,
cheers
Mark
Vance will love this as he already described "Britain an Islamist nuclear-armed country"
The UK sells under £100 million of arms to Israel. In 2023, it was a mere £42 million. Not all arms sales are banned ... my understanding is that of the 350 export licences in issue, thirty have been suspended. 79 UK companies currently hold licences for arms exports to Israel.
The question of course is which companies will be impacted by this ban and will it be material to financial performance?
The biggest impact will be on components supplied for jets, helicopters, drones, and items which facilitate ground targeting. By far the biggest area within that will be components for the F-35. BAE Systems (LON:BA.) supply approximately 15% of the value of each F-35 produced and is likely the most impacted company.
However, in the context of BAE's global business, the sums are miniscule. Any impact will be reputational rather than immediately materially financial,