Small Cap Value Report (Tue 30 August 2022) - DNL, REVB, JOUL, BMS, RQIH, UPR

Good morning from Paul & Graham!
Podcasts - good news, I've managed to publish my weekly summary podcasts on the main podcasting services now. Just search for "Paul Scott small caps" and it should come up (e.g. on Apple, Google, Spotify, Amazon Music), and hopefully it'll filter through to others too. I've used a free publishing service called Acast, and had to figure out what an RSS feed was, and how to use it, which took some time! I'll still be publishing them on my own website, with the latest episode here (warning includes a rant about energy prices, and bitcoin, and I don't expect everyone to agree with me, it's just one person's opinions, as usual!)
Agenda -
Paul's Section:
Diurnal (LON:DNL) - a takeover bid at an amazing 144% premium from a larger US bioscience group.
Revolution Beauty (LON:REVB) - confirms (as expected) that it won't meet the deadline for publishing FY 2/2022 results. So its shares will be suspended from close of play tomorrow. It's currently impossible to value this share without knowing the extent of the accounting problems.
Joules (LON:JOUL) - Sky reckons that talks with Next for a "rescue" refinancing have stumbled. Joules says that discussions continue.
Braemar Shipping Services (LON:BMS) - I have a good rummage through the (late) results for FY 2/2022, raising quite a few issues over balance sheet items. Current trading (in a separate RNS today) looks highly impressive, albeit the big upgrade is mostly due to favourable forex. Overall, Braemar looks to be making hay, in a buoyant sector. Shares look cheap, if current strong performance can be maintained longer term.
Graham's Section:
R&Q Insurance Holdings (LON:RQIH) (£386m) - Boardroom drama is heating up as a special general meeting approaches. Major shareholders want the Executive Chairman removed and replaced by one of the founders who gave the company its name. In this section, I discuss the background to the story which includes a collapsed takeover bid and an emergency fundraising. It looks to me as if bridges have been burned and there is no going back: I don’t think these relationships are going to be mended. As for the shares, they are an interesting speculation and offer cheapness versus the rate of profitability which the Chairman aspires to. Whether or not he will be around to implement his strategic plans is another matter.
Uniphar (LON:UPR) (£761m) (-4%) [no section below] - We’ve never looked at this “diversified healthcare services business” before. It joined the AIM market in 2019 and share price performance has been positive. Its three divisions are involved in 1) the sale, marketing and distribution of specialty medical products, 2) supplying early-stage, high-tech or otherwise difficult to source medicines, and 3) supply chain and retail (i.e. pharmacies).
Today’s interim results show single-digit growth in revenues and in various profit measures. Adjusted PBT increases by 9.9% to €26.1m, and net bank debt climbs to €73.8m. Post period end, the company increased its bank syndicate to include seven banks and they more than doubled the RCF to €400m, plus an extra €150m. Trading in H2 is in line with expectations despite “unprecedented inflation in all markets”, including “continued cost inflationary challenges which the management team are focused on mitigating”. There is no profit warning but the outlook statement comes with a disclaimer that maintaining margins will be a focus for the rest of this year and for 2023. Overall, there’s not much to dislike here but it’s far from cheap, the RCF-driven acquisition strategy is ambitious, and for followers of the IPO avoidance rule, it remains out of bounds.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Diurnal (LON:DNL)
11.25p (pre market open)
Market cap £19m
It’s another takeover bid, at a huge % premium - Diurnal has agreed to sell itself to Neurocrine Biosciences Inc, for 27.5p cash per share, an amazing 144% premium.
Neurocrine is listed on the US market under the ticker NBIX. Looking at its StockReport here, this has been a stellar share, rising 40-fold since the low of 2010. Its current market cap is £8.5bn, so buying Diurnal is a tiny morsel.
It has to be said that Diurnal’s track record since listing in late 2015 has been dire, as you can see from the share price -

.
The last trading update shows that Diurnal was well funded, with £16.5m cash in the bank at end June 2022. Therefore the takeover market cap of £48m is about a third self-funded.
Sales were starting to take off, with revenues up 104% to £4.7m for FY 6/2022, although Diurnal remains heavily loss-making.
So it looks like UK investors have funded the heavy losses over the last 7 years, and now the upside is being taken away with a takeover bid. Arguably not very satisfactory, although a 144% gain today is a nice way to start the week.
I wonder if the mainly institutional shareholder base will support this bid? The largest shareholder is listed IP (LON:IPO) which owns 29.3%, so it’s just made a profit of £8.1m this morning, but that’s only just over 1% of its market cap, so not madly exciting.
Personally I never touch biosciences shares, because they're impossible to value, unless you have expertise in the relevant science. And this is a good example of how the upside gets whipped away, if they do develop something interesting. Meanwhile the usual pattern is a plummeting share price, and repeated fundraisings. I see the share count at Diurnal has risen c. 4x since it listed. Still, at least it's not been a complete write-off, with the bid being 27.5p, being 81% below the 144p IPO price in Dec 2015.
.
Revolution Beauty (LON:REVB)
17.5p (pre market open)
Market cap £54m
Update on Publication of Final Results
The saga here continues. It has previously announced accounting problems, and that the deadline for filing accounts of 31 August for FY 2/2022 was not expected to be met (announced on 19 August 2022).
Today’s update just confirms this, and accordingly (again, as previously indicated) the shares would have to be suspended temporarily, under AIM rule 19 -
19. An AIM company must publish annual audited accounts which must be sent to its shareholders without delay and in any event not later than six months after the end of the financial year to which they relate.
REVB shares will be suspended before the market opens on 1 Sept, so if shareholders want to sell (or buy) then you’ve only got today & tomorrow.
After that, who knows what happens?
Timing - nice and vague -
The Company aims to complete its audit and publish its annual report within a matter of weeks of this announcement, post which trading in the Company's ordinary shares is expected to recommence.
My opinion - it’s just a gambling share at the moment. Since we don’t know the extent of the accounting problems, then the company is impossible to value accurately. Although of course investors could guess, and calculate a range of scenarios, then decide what seems most probable outcome, and go from there.
Although it is interesting that Boohoo (LON:BOO) (I hold) has bought up 12.85% of REVB in the open market, so clearly sees value here. There’s an obvious fit with BOO’s mostly young, female core customer base. REVB targets the same customers, with affordable make up.
So it’ll be interesting to see how this pans out. Expect more share price volatility today & tomorrow, before a nerve-wracking wait for more news, with the shares suspended.
Joules (LON:JOUL) (I no longer hold)
23.5p (down 8% at 08:09)
Market cap £27m
Sky News seems to be the go to place if you want to leak any company news for whatever reason! It reported on Sunday (28 Aug) that “rescue talks with Next stumble…” .
“The two companies are not close to agreeing the terms of an investment from Next…”, Sky tells us.
City sources said this weekend that Next had not received sufficient financial information to enable it to make a formal proposal to the Joules board.
There were also doubts that the clothing retail giant would be prepared to proceed with a deal at 33p-a-share or more - Joules' valuation when the talks were revealed by Sky News earlier this month.
Response to media reporting - Joules has issued a bland update this morning, just saying that “positive discussions” are continuing with Next, and the usual statement that there can be no certainty that agreement will be reached.
My opinion - obviously this share has been a disaster, with a series of (is it 4 now?) profit warnings. As mentioned last time I reported on it, the risk is now too high for me, given that it’s generating losses, and the clock is ticking re bank facilities, where the bank have been helpful in giving leeway, but only for about 3 months from now.
The risk is obviously that a discounted placing might be needed, diluting existing holders. Or worst case scenario, it might even end up in administration. Against that backdrop, it’s difficult to see why Next would be in a rush to do a deal, when it can let them sweat. Although there’s also the possibility Joules might do a deal with someone else.
I should have sat on the sidelines, and waited for a turnaround to become established, and the financial situation resolved, rather than jumping the gun and hoping everything would be alright. That’s my current stance, very belatedly - I’ll sit this one out, and only look to go back in once the funding situation is resolved, and a credible turnaround strategy in place. It should be salvageable, but I think they’ve done a lot of damage to the brand by being in constant sale, and I even saw a lamentable hour of TV shopping dedicated to clearing half price Joules stock - and it was grim, the product I mean. Hideous stuff, being sold on a tacky TV shopping channel. How on earth will they get back to selling at full price? So unfortunately, I think the brand’s pricing power has gone, and that’s a key thing right now.
My apologies that this one went so badly wrong, the sceptics were right as it turns out.
Braemar Shipping Services (LON:BMS)
332p (up 16% at 08:38)
Market cap £107m
These are very late numbers, for FY 2/2022.
Company’s headline -
Strong trading performance, balance sheet built for growth, and achievement of key strategic objectives.
Braemar Shipping Services Plc (LSE: BMS), a leading international shipbroker and provider of expert advice in shipping investment, chartering, and risk management, today announces its preliminary results for the year ended 28 February 2022.
The board is delighted with the performance of the business for the financial year and looks to the future with confidence.
Some key numbers -
Revenue up 21% to £101.3m
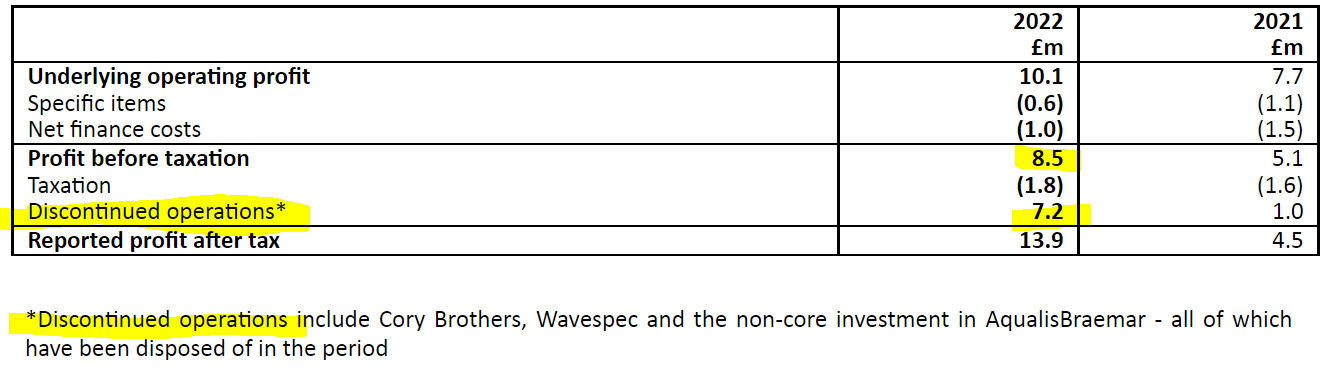
There’s a useful table showing how underlying operating profit of £10.1m turns into reported profit after tax of £7.2m (typo, sorry ) £13.9m , due to profit from disposals (which it says are to simplify the business) -
.
Increasing scale, and “generally favourable market conditions” are mentioned.
Underlying EPS is 27.95p (up a very impressive 100% on LY).
Although there are a variety of EPS figures given, and the most relevant one seems “Underlying continuing operations” of 23.06p (up 48% - much less of an increase than the number above).
Dilution - normally, diluted (i.e. allowing for share options yet to be exercised) EPS is similar to basic EPS, and a worse case scenario would normally be 10% dilution maximum from share options. I’m waving an amber flag here, because underlying EPS (cont ops) drops from 23.06p to 18.79p, due to 4.27p dilution effect from share options. That’s 18.5% potential dilution from share options, which seems horribly excessive. Note 11 says there are 6.94m share options issued. Why is this so high?
Note 28 has a section on share options. It’s too complicated for me to plough through it all here, with our time constraints.
There seem to be 3 distinct share option schemes, with by far the largest being a “Deferred Bonus Plan” with 6.45m share options (which seem to be nil cost) granted as at 28 Feb 2022. The shares seem to be acquired in the open market, and are held in an employee shares ownership trust, for granting share options.
To further complicate things, note 28 c) i) says this -
No option may be granted under any scheme which would result in the total number of shares issued or remaining issuable under all of the schemes (or any other Group share schemes), in the ten-year period ending on the date of grant of the option, exceeding 10% of the Company's issued share capital (calculated at the date of grant of the relevant option). Options are granted at a 20% discount to the prevailing market price.
What's the point is having share option schemes which could result in more shares being issued, but then not being allowed to issue them under this rule? All rather confusing, but this is a key area to get your head around if you’re thinking of buying or holding this share, I’m just flagging it up. But it does make me wonder whose benefit this company exists for - its shareholders, or its management? Is the balance right, or too generous to management?
Pension deficit - looks small, with note 27 providing more detail. Deficit recovery payments are £450k p.a., and expected to be eradicated by Jan 2023. So that looks OK.
Balance sheet - has about £81m intangible assets (nearly all is goodwill), so if we lop those off, NAV of £75.1m becomes NTAV of £(5.9)m - not very good.
There seem to be lots of unusual items on the balance sheet, e.g. long-term receivables of £5.6m, a deferred tax asset of £3.7m, investments, and an associate, convertible loan notes, derivatives (re forex forward contracts), provisions, warrants, the list goes on & on. I’m not sure management have simplified the business as much as they think! The more complexity there is, generally that can mean there are more things that could go wrong, in my view. It's unusual to find all this in a small cap.
It held cash of £14.0m, but debt of £28.3m (of which £5.1m is leases) so £23.3m bank debt.
Note 24 shows a very high accruals figure of £31.1m, which it says includes “accrued bonuses and other general accruals” - as the number is so large, I think this needs further explanation. How much is bonuses, in particular?
Receivables are covered in note 21, and look high at £38.8m. Although £6.5m is disposal proceeds, received 2 days after the year end date. It mentions employee loans (no number provided) - why is the company lending money to its staff? How much?
Note 21 also shows the ageing of receivables, which concerns me. It has £4.0m that is 3-6 months outstanding, and another £4.0m 6-12 months outstanding. Smallish provisions have been made against these numbers, but why are these customers taking so long to pay? Why is Braemar incurring bad debts at all? There’s another £2.4m more than 12 months overdue, but that has been largely provided for. But again, why are bad debts arising? If customers can’t pay, why do business with them? Why isn’t it requiring cash up-front from wobbly customers? I’m not sure the financial controls here are adequate.
Outlook - this all sounds very encouraging -
OUTLOOK
We have seen strong trading at the start of this financial year, and activity has been particularly high in the derivatives, sale and purchase, and corporate finance markets. The simplification of our business and our ambitious strategy to double our annual underlying operating profit is yielding strong trading results.
Our team has seen elevated numbers of newbuilding orders, principally in the container and gas carrier sectors. As a result, capacity at many shipyards is now unavailable well into 2025. For shipowners in other sectors this is making it challenging for them to renew their fleets and they're turning instead to the second-hand market. These dual factors have created significant opportunities for our Sale and Purchase desk, and they have capitalised on them. Over the next couple of years, these factors are likely to prove positive for our chartering desks too, as reduced ability to replace retiring ships is expected to constrict vessel supply and consequently create a higher floor on future charter rates.
We believe our ability to seize the opportunities available over the last year and maintain our high levels of activity are due to our investments in people, technology, and new offices. I look forward to another strong year of trading as these benefits continue to compound.
Trading Update - this is a separate announcement, presumably to draw attention to how good current trading is. Usually companies just include a trading update within the outlook section of their results.
This sounds fantastic, but note that favourable currency is a major positive factor (which could stop, or reverse in future periods possibly) -
Trading during the first five months of the new financial year has been exceptionally strong. The Group continues to benefit from the increasing scale and breadth of its broking operations, which have yielded a strong rise in transaction volumes across its diversified portfolio of shipbroking services. The board believes that these increased activity levels, combined with generally favourable market conditions will yield an outturn for the current financial year ending 28 February 2023 of not less than £20m (2022: £10.1m) of underlying operating profit, very materially ahead of the board's previously upgraded expectations of £12m.
In addition to the Group's increased scale, this year's trading is also benefitting from the strength of the US Dollar in which the majority of the Group's revenues are denominated. The strength of the US Dollar is expected to contribute approximately £5m to the growth in underlying operating profit over the previous year.
My opinion - there are lots of issues here that need further, careful research. But providing you can get comfortable with those points, then Braemar seems well worth considering.
It’s obviously in a sweet spot, and raising current year guidance from £12m to £20m u/l operating profit is remarkable, even if most of this increase is due to favourable forex movements.
I can certainly understand why bulls are happy with this company’s performance! These are impressive results, and an even more impressive current trading & outlook.
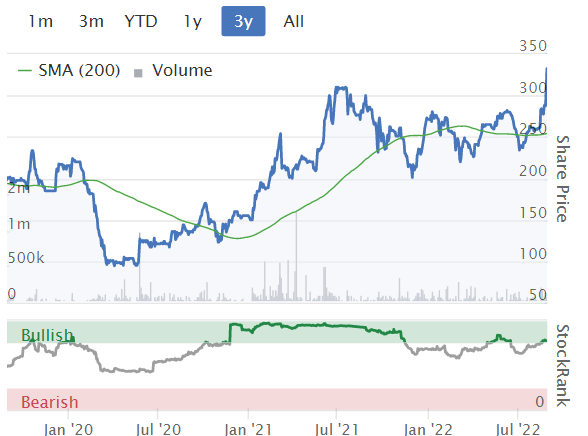
Stockopedia likes it too, with a StockRank of 77 - likely to rise shortly, as the big rise in guidance today filters through to broker notes - see Research Tree, for notes from Cenkos and Edison. Cenkos is forecasting 51p EPS this year! That would make the PER less than 7, although it might not be possible to maintain such a high level of profits longer term, time will tell.
.
Graham’s Section:
R&Q Insurance Holdings (LON:RQIH)
Share price: 102.25p
Market cap: £387m ($452m)
This is a Bermuda-based owner of run-off insurance portfolios (i.e. portfolios that are winding down, as new policies aren’t being added to them).
It sounds like it should be a sleepy business with little controversy attached. But somehow, it has ended up as the venue for a boardroom battle involving the Chairman, a founder of the business, and a well-known fund manager.
Chairman William Spiegel gave a presentation to Investor Meet Company in September 2021: here’s the link.
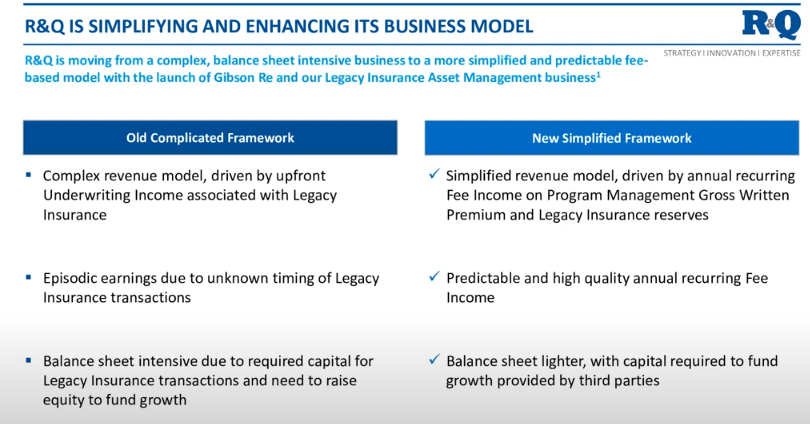
Spiegel has been spearheading a new strategy that will see R&Q adopt a fee-based, capital-light business model. Here is a key slide from his presentation that describes the change:
On April Fool’s Day of this year, R&Q recommended that it be acquired by its major shareholder Brickell, who would also inject £100m of fresh equity into the business. The new money was needed to cover losses associated with an old reinsurance contract.
However, that deal fell through and it looks like R&Q managed to annoy all of their major shareholders as a result of this episode.
Brickell pulled out of the deal, alleging that R&Q was “in breach of certain obligations under the implementation agreement [related to] the proposed transaction” (details not given).
But fellow shareholders Slater Investments and Phoenix weren’t happy with the proposed deal, either.
Phoenix CIO Gary Channon has written a new letter to R&Q shareholders.
In it, he details how Slater contacted him back in April about the proposed takeover. Slater wanted help to block the deal.
But Phoenix were concerned that if the deal didn’t go through, R&Q might breach its banking covenants, and had initially voted in favour of it.
In the end, the deal collapsed. The company raised the funds it needed in a $125m placing in June. But the top shareholders weren’t willing to just forgive and forget. It looks like they’ve had enough of the William Spiegel era at R&Q.
Phoenix Investments certainly has. In his latest missive, Gary Channon writes:
We and other investors have seen the performance of the business deteriorate under the leadership of William Spiegel… William Spiegel is not the right person to be leading the company…
From what we have heard, if there is a difference of opinion with other shareholders it is not about whether William Spiegel should go, it’s about how his exit should be achieved…
At Phoenix we think of these assessments in three categories: competence, alignment and integrity in ascending order. We find William wanting in all three.
According to Mr. Channon, William Spiegel “struggled with intelligent capital allocation at a company level”.
It’s a damning letter, and includes allegations of excessive pay and extremely poor communications with shareholders.
It includes the claim that R&Q accepted Brickell’s initial bid for the company and only the next day, informed Brickell that it needed £100m of emergency funding to avoid breaching its covenants.
Channon wants Spiegel out and they want him replaced by Ken Randall, one of the founders who gave the company its name.
Brickell, perhaps unsurprisingly, also want Spiegel to go.
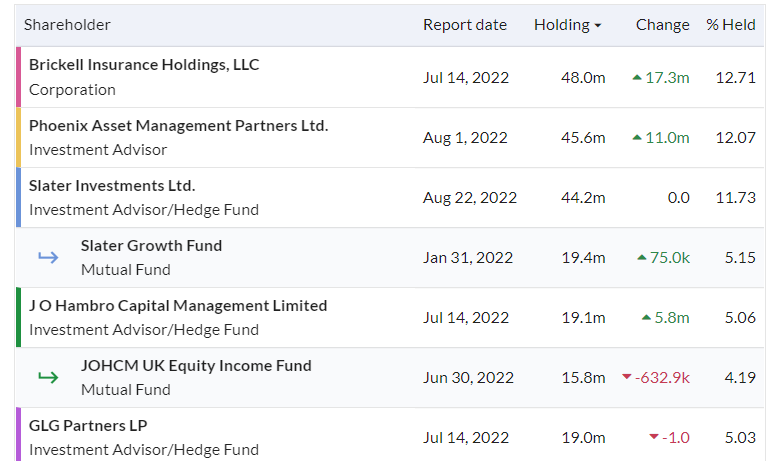
Slater are presumably enthusiastic for change, too. This suggests that the top three shareholders are all in agreement on the matter:
In its response published via RNS today, the board of R&Q “reiterates its unanimous support for William, its respect for him, and confidence in the strategy he and his management team are executing”.
They also take collective responsibility for the company’s actions and decisions, which is fair enough. The Executive Chairman can only do so much without the support of his fellow directors.
My view
What makes this episode remarkable to me is that Phoenix was never previously an activist investor. Instead, they are a long-term value investor with certain idiosyncrasies, such as a “reading room” on their website. For certain job openings, they will not accept email applications and ask for handwritten letters to be posted to them.
They always struck me as a place where people spent their time reading obscure industry journals (in the style of Buffett) and made a trade once every two years. In other words, they did not strike me as the type of people to get involved in Bill Ackman-style conflict.
But maybe that has changed?
After all, Gary Channon became the interim CEO of Dignity (LON:DTY) last year.
Maybe they feel they’ve reached a point where they can reluctantly add value by getting more actively involved, when necessary?
I say “reluctantly” because they’d clearly prefer if Dignity hadn’t needed a turnaround, and if R&Q’s management did not need to be replaced.
Indeed, Gary Channon says that his original plan was to simply sell out of R&Q and move on:
…we decided to sell our entire holding in R&Q… If shareholders should choose to keep William Spiegel, then we will respect that and go back to where we were, disengaging from the company. We didn’t seek the role of activist here, it found us. We were quietly on our way, exiting stage left, before this came along and that is why our initial reaction was to just accept the Brickell bid.
My view on Phoenix and on the Phoenix UK Fund is that they are proven to be capable of beating the FTSE All-Share Index (see their long-term returns - past results are no guarantee of future performance).
If they are engaged in activism from time to time, I see no problem with that, as I expect they will be able to add value in situations involving companies which they have been studying and have owned for a long time.
The major risk with activism is that it can be time-consuming and can use up energies that would have been better spent studying companies that didn’t require any intervention at all. So hopefully Phoenix don’t allow themselves to get too distracted!
As for R&Q, the situation looks finely balanced in terms of whether William Spiegel will be forced out, and the co-founder brought back in.
R&Q’s board say that shareholders representing 40% of the votes have already stated that they intend to oppose the resolutions brought by Phoenix to the special meeting.
On the other hand, according to the Stockopedia graphic, Brickell, Phoenix and Slater add up to 36.5% of votes.
So I don’t know which way it will go.
Since I’m inclined to trust that Brickell, Phoenix and Slater are correct in their view of management, I think it would be bullish for R&Q if the resolutions are passed.
However, if the resolutions are not passed, then in addition to the management issue there would also be a technical overhang with the shares, as I expect that Phoenix would start selling again. Maybe another shareholder would mop up that liquidity?
These shares are superficially quite cheap, and remember that it has recently been refinanced so the balance sheet should be fixed for the time being at least:

But in the words of Phoenix, R&Q is “very opaque”. It’s not easy to look under the hood and see what is happening with the underlying policies and contracts. That might change with the new fee-based strategy but even that strategy might be revised if new management is installed.
In other words, there is a great deal of uncertainty at play here. If I put my bullish hat on, I would note the company’s stated ambition to earn $90m in “run-rate” pre-tax operating profit by the end of 2023. That’s the goal of the current Chairman.
Either he will be given a shot at achieving that, or a (hopefully better) Chairman will be installed to replace him. Either way, at a market cap of around $450m and with some excellent investors working on it, perhaps it’s worth a second look?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
Interesting that Revolution Beauty (LON:REVB) is up 7% today - lots of gamblers out there it seems.
You can find Paul’s podcast on Spotify at:
https://open.spotify.com/show/...
Yet to listen but will binge at some point especially if there is a “a rant about energy prices, and bitcoin”!
I do wonder if the general media's view of the Energy pricing 'crisis' will turn out to be like the Pandemic 'crisis', as something we look back on shake our heads at being steamrollered by Fear Mongering headlines into some dubious policy decisions?
This could have the side effect of driving Stock Market prices into further irrational lows.
As I'm sitting outside the UK at the moment and I'm getting news from varied sources it seems quite apparent that the UK media do seem to be trying to talk the UK into a recession, when the energy crisis is actually a bigger problem in continental Europe. A conversation last week at work around a facility in Spain, for example, included the snippet that their electricity costs have increased seven-fold.
I agree that the media do love to sensationalise things .
But having children at university with little disposable income now let alone before the energy price hikes, having family members earning less than £20k gross working in hospitality , and having worked with SMEs for over 30 years, this time I am genuinely scared about the future .
And i mean pretty petrified.
Not for me personally, although my clever idea three years ago to set up a share portfolio to have some fun and beat the market , is being slaughtered into oblivion. But for the young people who face the prospect of going to work purely to pay their bills, if they can even manage that. And I have family members with very young children in just that predicament.
‘Riots in the streets’ is another often abused phrase, but I can genuinely envisage this this winter if something isn't done pretty soon.
hi Paul
I've listened to most of your weekly podcasts and found them very useful. Your efforts are much appreciated and your off piste ramblings most welcome too, even if not everyone agrees with all your opinions. You can't please everyone all the time.
I don't use a podcast host (wouldn't know how to nor why I might need to use one) so will continue to access it via your weekly website link.
Snazzy
Thanks for the podcast Paul. I’m now a follower via Spotify. You’ll get a better idea how many people listen to your articles.
Yes so much more convenient as now can listen on my Apple podcast whilst in the gym .:)
Quarto (LON:QRT) half year results out today, RNS was at 10am, so some may have missed it. Look ok to me but shares are down over 7%, no forecasts on Stockopedia, so not much to go on, debt has been reduced further.
Outlook for next half year looks challenging.
Hey Rustbucket,
Just read the Quarto (LON:QRT) results and they show a good first half performance, particularly vs. 2021. H1 is normally the weaker half as well. Also nice reduction in net debt (as you say).
Usual suspects of supply chain, inflation / cost of living feature as likely to impact H2, but 8% drop seems overdone - but pretty much the same for everything at the minute!
hi Graham
re Uniphar (LON:UPR)
'........and for followers of the IPO avoidance rule, it remains out of bounds.'
So what does the IPO avoidance rule state?
Snazzy
Hi Snazzy, it's the rule to avoid IPOs until they are trading at a discount to their IPO price! G
Thanks Graham
Very sensible.
I think I'd add a timeline too. Personally I'd also wait until they have been listed for at least 12/18 months to allow the market to settle down and to be able to see a full set of post IPO numbers.
Snazzy
In fairness Uniphar ( I do not hold )has been quoted in Dublin for many years and has performed well since its London quote in 2019. They appear to be following the strategy which brought success to UDG now in private equity hands.
Thank you for your quick scrutiny re Braemar Shipping Services Paul, you make some very important points on their balance sheet, options and accounting. I did try to buy early but thought the initial mark up overdone, it's gone higher since but I'll wait. We did buy Centralnic as they also seem to be on a high growth path, TS highlighted by Revs8 at 7.22am.
Hi Paul
You mentioned signing up to Acast for your podcast.
Acast are actually listed - the Stock Report is here: https://www.stockopedia.com/sh...
Despite the prolonged share price drop, it still looks terribly expensive, and I've remained sceptical due to recent negative growth in the US.
Having said that, I'm still following their progress as they have a large cash pile and I see them mentioned more and more when listening to podcasts on Spotify - it does makes me wonder whether they will grow into a much larger company.
I hope you don't mind me asking, but why did you choose to go with them?
Cheers
A
Morning chaps. I was wondering if you have time to cast an eye over LON:BYOT (I hold). Results look solid enough to me having calmed down from the Covid Blip (super-positive for them). I am encouraged by the growth in licensing deals even if they take a while to covert into cash in the Bank.
Good Morning Paul,
I do hope that you continue to do your Small Cap Podcasts, I find them useful as a catch up on last weeks reviews but mainly I enjoy your macro thoughts and general ramblings. Whether i agree or not, it is good to consider other peoples views.
Richard
Excellent news on your podcast being available on Apple now Paul, thank you. A great listen.
Anyone subscribe to shareprophets.com? Boohoo (LON:BOO) bearcast yesterday:
Tom Winnifrith Bearcast - could or should Boohoo.com go bust?
https://www.shareprophets.com/views/63989/tom-winnifrith-bearcast-could-or-should-boohoocom-go-bust
Boohoo (LON:BOO) is still the most shorted UK listed business according to the shorttracker website with short positions increasing in recent weeks even at these lows.
I wonder if the SP is headed to 22p?
You have to subscribe to listen to it ... what does it say? I can't figure out why Boo is shorted to the extent it is. Does anyone know?
Hi 55555,
I think the bear case for Boohoo (LON:BOO) goes something along the lines of;
Tiny Operating Margin, reducing sales, increasing debt (including a number of bank-loans that need paying off soon (and could lead to a discounted share issue), poor governance (family owned with lots of inter-party deals eg. purchase of PLT from family member), family members running slave-labour manufacturing warehouses so that Boohoo (LON:BOO) profit, returns costing huge amounts of ££ (now charging so maybe less of an issue), lack of global distribution system leading to poor customer experience outside of UK, crooked governance eg. purchasing shares in Revolution Beauty (LON:REVB) using shareholders money without approval (this was a personal investment by the Chairman at IPO but now using shareholders cash), massive bail-out of a lot of institutional money when the SP was around £3-4 a couple of years ago when the ESG issues first landed and little confirmation yet that things have really changed, competitors (Shein) doing far better, cost-of-living crisis likely to impact their customer base significantly........I could go on.
Apart from that everything is fine. I am sure someone has the bull case.
Regards
Kevin
Many thanks Kevin. Being bull'ish, many of the points you raise are either old news, dealt with or being dealt with. Unlike Shein, Boohoo have the brands and their target market loves brands and of course make up. Maybe cash will be short, but Boohoo have made some big investments into gearing up for massive US growth, which must be their biggest opportunity going forwards. I hold and am tempted to buy more at these levels.
Well, didn't expect FTSE100 to be up 1.3% this morning! Never try and second guess the markets...
Me neither. Irrational exuberance? Very clear lots of uk biz will now struggle deeply over next 6 months (and beyond). Which companies / sectors will benefit?
The US markets appear to be showing a bearish pennant after the significant drop last week. All other markets follow to some degree although the FTSE100 seems to be holding up better than those with more growth stocks.
I'd be vary wary of thinking that the US markets have bottomed at this point (I'm increasing my short position).
I concur that the indices could have further to fall
FTSE100 was up because the £ is down, which benefits oil companies and others that have revenue in foreign currencies.
I would welcome your comments on CentralNic (LON:CNIC) half year results Paul and Graham. Strong revenue growth including v high organic growth. Main downside is probably the debt pipe and potential for marketing spend slowdown in wider economy. I want to be challenged with the bear case on the share as it is only trading about 10x despite the growth.
One thing that bugs me about this share is the management talk the company up a lot and it oddly spends money advertising the shares on Twitter which is unconventional. I suppose they have had to increase the share count a lot over the years but it sometimes feels like it behaves like a junior oil exploration company albeit with actual revenue and profits to show!
£CNIC. They present on InvestorMeetsCompany at 1300hrs today.
CentralNic (LON:CNIC) is one of my largest holdings - and recently profitable and cash +ve too, which, being a smallish cap tech stock, makes it very interesting in today's market. It is beginning to hit the financial media's focus and is growing like topsy - the PEG is 0.3!!
Quite a lot of their business is esoteric and thus hard to understand but I think the financials are beginning to make the argument. Management have a very clear view of what they are setting out to achieve - they are ambitious, which can add risk but they really haven't put a foot wrong so far.
Kestrell Partners and Slater Investments are holders at 21.84% and 9.11% respectively.
Yet the market remains completely unimpressed - one for the biscuit tin perhaps.
Braemar Shipping Services (LON:BMS) punchy trading update upgrading forecasts significantly. Is there a read across to other sectors? Complex area to analyse.
I'm feeling light headed at reading so much good news on their report Revs8. I hope Paul or Graham cover Braemar Shipping Services today. It looks like an add to our current holding but I often miss something important.
Hey Paul, I have the Monday Morning feeling too!
I've just realised it's Tuesday, so refresh your page and it should be OK now! :-)
you can still have a Monday morning feeling on a Tuesday, or every day the stock market is open for business.
£ Tuesday Paul