Small Cap Value Report (Tue 30 June 2020) - VNET, D4T4, SOLI, DRV, COG, STAF, WGB, TRAK, SYS1, TST

Good morning, it's Paul here with the placeholder for Tuesday's SCVR, for you to leave your comments on the RNS from 7 am.
Please see the header for company results and trading updates that I'll be looking at today. Quite a lot, 10 companies, so it's doubtful I'll have time/energy to do any reader requests, sorry about that.
Estimated timing - I've started early at 7am, so there should be plenty of material up by official finish time of 1pm. I'll leave a note here if I need more time to cover everything, which is looking likely, due to lots of trading updates & results being published today.
Update at 13:00 - I've done 5 companies so far, and will add some more later this afternoon, after lunch.
Update at 17:40 - today's report is now finished.
.
Mello Virtual
David Stredder and his team have been busily working on an online version of the UK’s highest quality & friendliest investor show, Mello.
It’s on 10-11 July, so quite soon. Tickets are amazingly cheap, so I’ve already bought mine here. As usual, there will be some brilliant speakers, and decent quality companies giving presentations.
I’ll miss holding court in the bar afterwards, but never mind!
.
Company webinars
I must admit that I’m finding it wonderful to “attend” meetings online. Last week there was another really useful company webinar, from Warpaint (W7L). Thanks to Equity Development for arranging that. It gives a nice flavour for what management are like, and how they interact. W7L management made a good impression on me, with open/honest answers to the questions, and a good presentation. It doesn’t matter if there are minor technical glitches, as this stuff is all quite new at the moment.
If I find any webinar useful, then I'll publish a link here. Also, I encourage readers to post comments including links to useful webinars.
Here's the recording of the W7L webinar;
.
That's all I've got in pre-prepared stuff, as I used up most of it yesterday.
Vianet (LON:VNET)
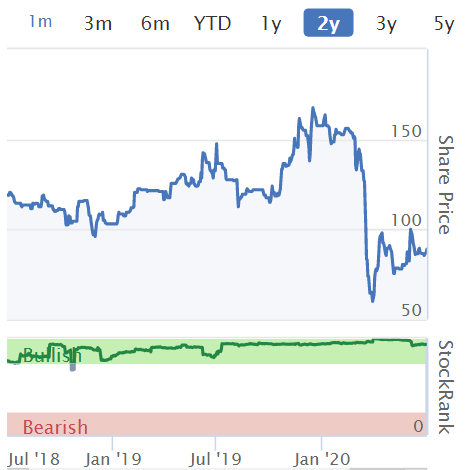
Share price: 94.5p (up 8.6% today, at 08:52)
No. shares: 28.95m
Market cap: £27.4m
Vianet Group plc (AIM: VNET), the international provider of actionable data and business insight through devices connected to its Internet of Things platform ("IOT")
I'm just reading my notes here on 2 June 2020, when I briefly covered its results for FY 03/2020. The current trading update was positive.
Today's update confirms that trading is OK;
"Thanks to our proactive response to management of C19, the Group's performance in the first two months of the financial year has been very encouraging, with losses comfortably lower than anticipated.
That's alright as far as it goes, but if you're expecting dire figures, and they're better than expected, they might still be pretty awful! I'd have preferred some hard numbers, compared with last year. That would be more meaningful.
Pubs division (Brulines) - majority of pub clients will start re-opening from 4 July. Clients seeking increased data, to help with re-opening. Giving customers 30% discount on weekly support services until 31 Oct 2020, when pricing will return to normal. So this will be a hit to revenues & profit, but hopefully one-off in nature.
Smart Shield - I hadn't heard of this before, but VNET has jumped on the bandwagon, offering anti-covid cleaning services. Too early to determine demand, but has received first orders.
Smart machines (vending machines) - strong momentum, new customers including Tchibo & Lavazza. Encouraging pipeline. Trend towards contact payment (instead of cash) is helping.
These strong trends will continue to gain momentum post lockdown,...
Outlook - bear in mind that VNET has a long history of over-promising about growth, whilst delivering only very modest growth, hence I would take the following with a pinch of salt;
"Whilst we recognise that the C19 situation is still unpredictable and uncertain, we remain confident that the Group is in a very good position to resume its strong earnings growth, continue the solid momentum that was building into FY2021 and deliver on the exciting growth opportunities that we see ahead of us."
My opinion - neutral. The main (probably only) attraction of this share were the generous divis. This year's impact from covid is likely to have damaged its balance sheet somewhat, which combined with companies probably being more prudent in future, means that investors may have to forget about divis for a year or two.
Pubs re-opening is likely to give some positive newsflow for a while, but that needs to be seen in the context that pub numbers are likely to continue falling, maybe at an accelerated pace?
There is some interesting growth potential, but there always has been. I've learned from experience that growth at Vianet happens at glacial speed, so the shareholder list tends to be a revolving door of people buying into the growth potential, then gradually losing interest as nothing much happens for several years.
It's not a bad company, and is profitable. I just don't see enough growth potential to get me excited enough to want to own this share.
.
.
D4T4
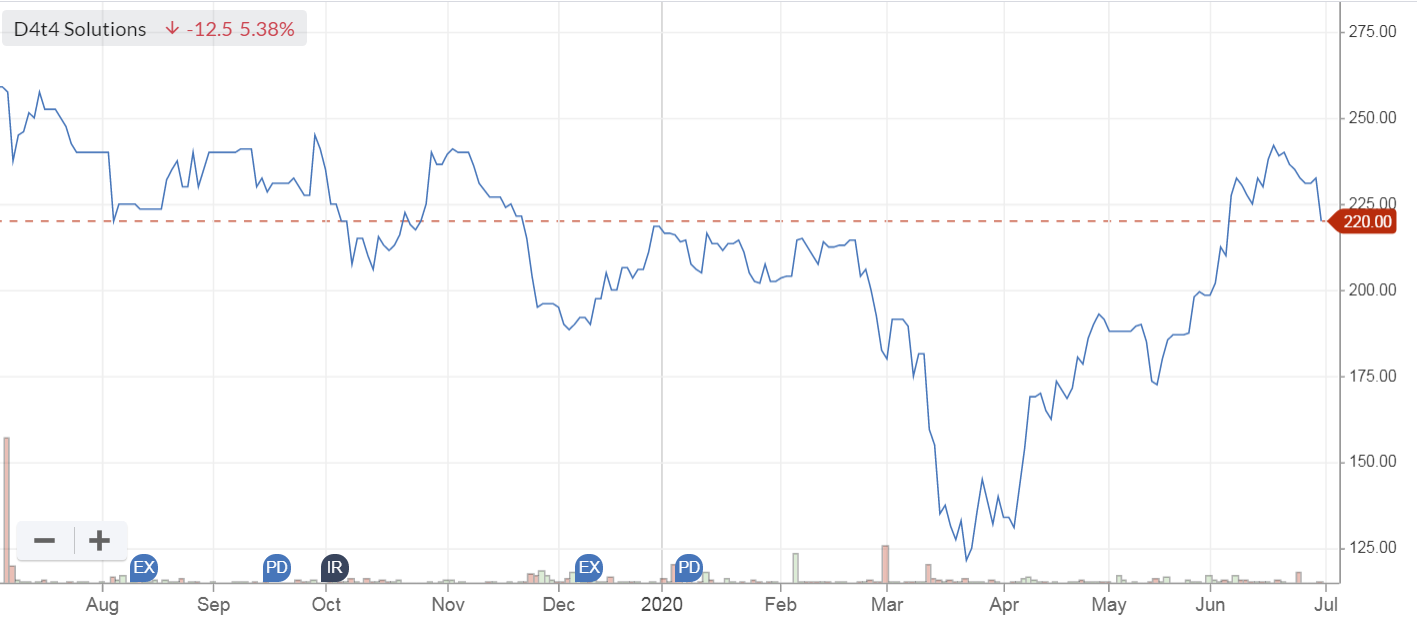
Share price: 223p (down 4% today, at 09:24)
No. shares: 40.26m
Market cap: £89.8m
D4t4 Solutions Plc (AIM: D4T4, "the Group", "D4t4"), the data solutions provider, today announces its Audited final results for the year ended 31 March 2020.
Results are down on prior year (both revenue and profit), which is blamed on transtitioning from one-off licence sales, to a higher quality recurring revenues SaaS model.
High profit margin - it achieved £5.05m adj PBT (down 16% on LY) on revenues of £21.75m (down 14% on LY), which is a profit margin of a very high 23.2%
Adj fully diluted EPS is 11.19p (down 19% on LY) - PER is 19.9 times - seems a lot, considering profits fell, and would have had little impact of covid in the FY 03/2020 figures. Although the big question is whether a PER of 20 is expensive, or could be seen as cheap, if you think interest rates are likely to be near zero forever.
Dividends - as Graham mentioned recently, this is an interesting indicator of how confident & solvent companies are. There's a 1.9p final dividend proposed here, down on 2.3p LY.
Balance sheet - receivables looks very high, at £10.1m. The commentary says this was due to "particularly strong sales" in Q4. that's fairly normal for software companies, but is an amber flag, that I would want to check the next interim results to see receivables have indeed turned into cash. Excessive receivables can be a precursor to accounting problems, in my experience, so I watch this area carefully.
In all other respects, the balance sheet looks excellent. There's a £12.8m cash pile.
Net current assets look lovely, at 2.64. Anything over about 1.5 is strong, in my eyes.
This company is very financially secure, so shareholders don't have to worry about solvency at all, even in a period of bad trading, which could be absorbed by a balance sheet this strong.
Outlook - rather long-winded, so I'll summarise the main points;
- Uncertain outlook this year, due to covid
- Low customer churn, and strong recurring revenues, mitigate covid impact
- Mixed impact on different customer sectors
- D4T4 operates in a sweet spot, of digital transformation
- Sales pipeline, for "major new contracts" remains strong, most should be signed this year, FY 03/2021
- Some contracts deferred or slower to close, but not being cancelled
- Transition to SaaS continuing - this year will be key
- Strong cash reserves & no debt (confirmed by me above)
- Upbeat final comments;
Taking these factors into account, including some very positive initiatives with our existing strategic partners and the excellent progress with product development, the Board remains upbeat about the future prospects for the business through 2020/21 and beyond. ..
2020 has started promisingly and in line with the Board's expectations, with strong levels of both existing and new client activity.
Overall that sounds positive to me.
My opinion - I've got a positive impression of this company.
It operates in a growth area, has a strong balance sheet, pays (small) divis, and over time revenue/profit should get less lumpy as the SaaS transition continues.
Overall, the company gets a thumbs up from me, although I'd say the share price of 230p probably looks about right at the moment, rather than cheap or expensive.
.
.
Solid State (LON:SOLI)
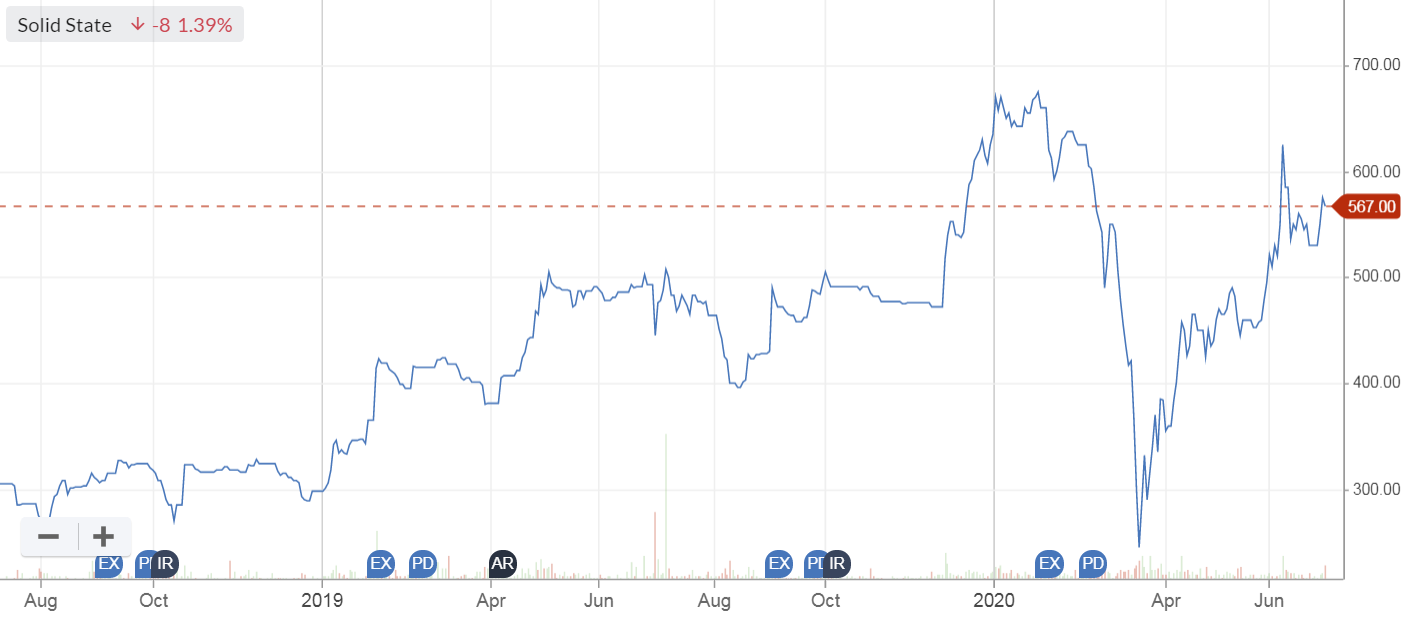
Share price: 555p (down 3.5% today, at 10:16)
No. shares: 8.54m
Market cap: £47.4m
Solid State plc (AIM: SOLI), the AIM listed manufacturer of computing, power and communications products, and value added distributor of electronic components, announces its Final Results for the 12 months to 31 March 2020.
Here are my notes from the 8 June trading update. The business was performing well, but there were signs of a softening in the order pipeline.
There is a results presentation, open to everyone, on InvestorMeetCompany at 16:30 today.
Results out today look good - with adj diluted EPS up 29% to 46.3p - a PER of 12.0
Outlook - hesitant again, for the current year, so it's fairly clear the company is signalling profits likely to fall in FY 03/2021, as I would expect given the ravages of covid/lockdown on the economy;
Although the Group is seeing and expecting some slowdown in order intake during this financial year, its diverse sector exposure and strong open order book will provide some resilience.
Bear in mind that a lot of its growth has come from acquisitions.
Order intake has softened in Q1 of FY 03/2021;
Entering the year with the strong open order book has meant trading in the first quarter has been broadly in-line with prior year and ahead of management expectations.
While we have been able to maintain a good open order book the Q1 order intake is down just under 15% compared to prior year, as a result of COVID-19.
Balance sheet - looks good to me, quite strong, hence there shouldn't be any solvency concerns.
Cashflow statement - looks good. Has generated plenty of cashflow (helped a bit by favourable working capital movements). This was used mainly to reduce debt by an impressive £5.3m, and also pay well-covered divis costing £1.15m.
My opinion - these figures look quite good actually, and the valuation seems undemanding.
The issue is all about future earnings, as with many/most companies right now, we don't know how bad 2020 is going to be, nor what level of recovery there might be in 2021 and beyond. Hence I think it's generally sensible to regard 2019 earnings as the peak, hence only be willing to pay a fairly low multiple for peak earnings.
Is a PER of 12 times (probably) peak earnings cheap enough? Not for me it isn't. I'd rather wait and see how current year results pan out, and look at it again once the outlook is clearer. Mind you, I'm really not looking to open new positions at the moment, because I feel worried about the short term economic outlook.
Both brokers that cover SOLI do not have current forecasts for FY 03/2021, hence we cannot currently rely on forecast PER and divi yields shown on the StockReport, which are likely to be too optimistic. This point is important to keep in mind for all companies at the moment.
.
.
Driver (LON:DRV)
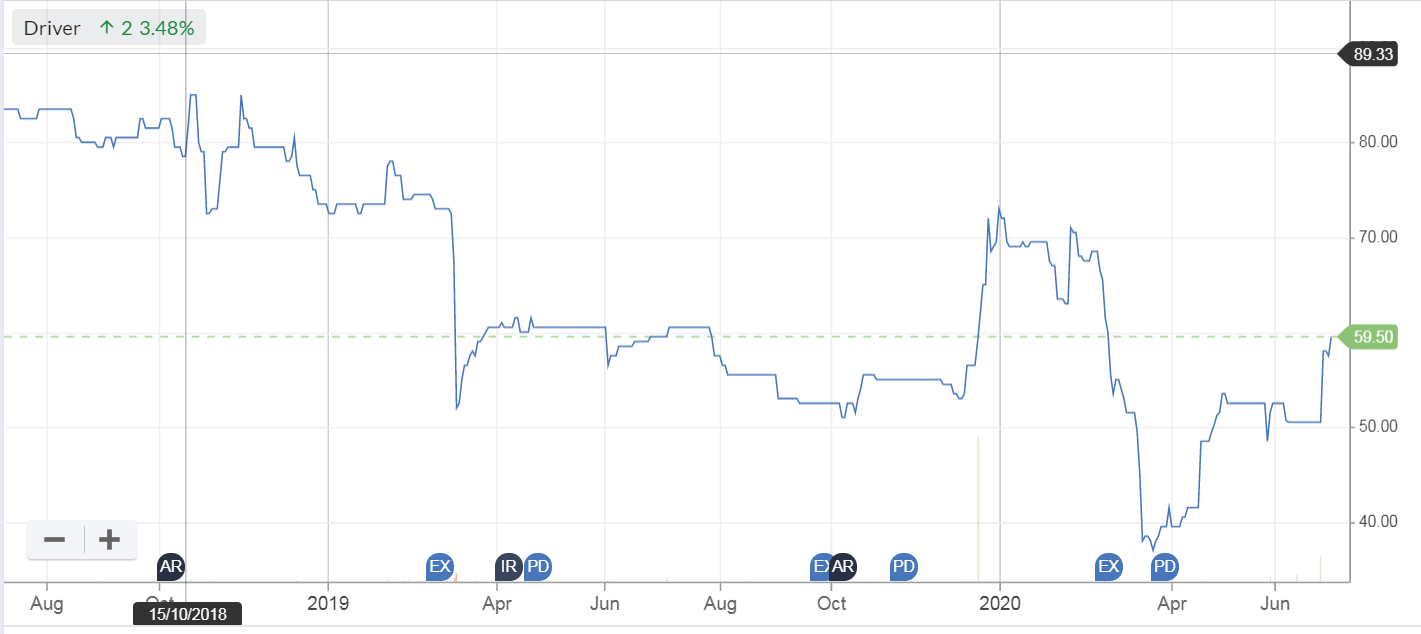
Share price: 57.5p (unchanged at 11:23)
No. shares: 52.2m
Market cap: £30.0m
This is a small consultancy business
The highlights section looks positive, with H1 underlying PBT up 64% to £1.25m
Driver has done a results webinar today, I'll put up a link to the recording, when it becomes available (from BRR Media) - if anyone spots this, please do put up a comment here, with the link.
The Chairman summarises H1;
"Driver have had a good first half year to 31 March 2020 with only limited impact on performance from Covid-19 related issues. There were strong results in the Europe & Americas (EuAm) and Asia Pacific (APAC) regions offset by a weaker performance in the Middle East (ME) region"
Action taken re covid -
- Home-working for employees
- No interim divi
- Postponed non-essential capex & discretionary spending
- Drawn down £3m RCF in full to sit on cash pile as a contingency reserve
- Board salaries reduced by 20% from 1/4/2020 for foreseeable future [good, I like this]
- Pay cuts for under-utilised staff, and "small number" furloughed
- HSBC has relaxed covenants & extended borrowing facilities by £4m
- Stress tests confirm company has adequate liquidity for >12 months (hence going concern basis is OK)
That all sounds sensible & reassuring.
Outlook -
... I am pleased to report that the Group's current net cash balance stands at £5.5m.
In more normal times, Driver is conditioned to operating with relatively low forward revenue visibility and, as a consequence of the Covid-19 pandemic there is heightened uncertainty over client behaviours and their impact on our business.
However, with current trading holding up well and with recently increased debt facilities the directors believe that the Group is well placed to trade through this current uncertain market environment and to take advantage of the opportunities afforded as a consequence of the disruption of Covid-19 in the Group's target market.
Balance sheet - receivables stands out as very high, at £21.8m. Are there any potential bad debts in that total, I wonder? It would be worthwhile to ask the question.
Overall, this balance sheet is strong. NAV of £20.1m, less £3.0m intangibles (all goodwill), leaves NTAV at a healthy £17.1m - this is good, for the size of company.
Therefore, I don't see any solvency risk here, providing the receivables book doesn't contain any big potential bad debts, that's the main risk here.
My opinion - if you want to invest in a small consultancy business, then this looks fairly decent. The strong balance sheet is particularly important at the moment, as I doubt it needs to do a placing, so hopefully no dilution for existing shareholders.
It could possibly become a takeover target at some stage? I seem to recall there was a flurry of takeovers at good prices in this sector a while ago.
The uncertain outlook is obviously a risk that H2 might slow down & result in a profit warning.
.
.
Cambridge Cognition Holdings (LON:COG)
Share price: 43.5p (up 14% today, at 12:03)
No. shares: 31.2m
Market cap: £13.6m
This is a very small, illiquid share, so I'll keep this brief.
Cambridge Cognition Holdings plc (AIM: COG), which develops and markets digital solutions to assess brain health...
This reads very well;
... pleased to announce further contract wins in the first half of 2020, taking the order intake to £4.9m for the year to date, compared with £2.6m for the first half of 2019. [Paul: up 88% - impressive]
To date in 2020, the Company has signed contracts for four large orders of over £500k and ten for between £50k and £500k, as well as taking many smaller orders. The contracted order book for the company is now at £7.5m compared to £5.7m at 31 December 2019.
In the last 5 years, annual revenues have been between £5-7m. Therefore the order book numbers above are quite significant, although it depends on what period they are delivered over - e.g. if these are multi-year contracts, that wouldn't be as positive as contracts to be delivered in the next year alone.
More details are in the RNS about product development.
However...
Until all clinical trial sites are open again, we remain cautious around the extent to which these increased order levels will have a favourable impact on recognised revenues this year.
However, as a number of clients have already indicated that they are now restarting trials that had been paused, the current prospects are encouraging.
Hedging their bets there a bit!
Directorspeak - some nice nuggets in this bit, although I don't know how the current CEO ranks in terms of delivering what he promises. The company hasn't done at all well on that front historically, but the newish CEO might be different hopefully?
"These order wins are pleasing to see and confirm that the strategy we set last year is succeeding.
"We are seeing unprecedented demand for the breadth of solutions we are able to offer clients: CANTAB™ cognitive assessments, electronic Clinical Outcomes Assessment solutions, digital solutions and also our new voice-based assessments for cognition. What is particularly pleasing is that many companies are ordering more than one solution, increasing sales per client.
"We are looking forward to delivering these new orders in the second half of the year and securing further orders from our strong order pipeline."
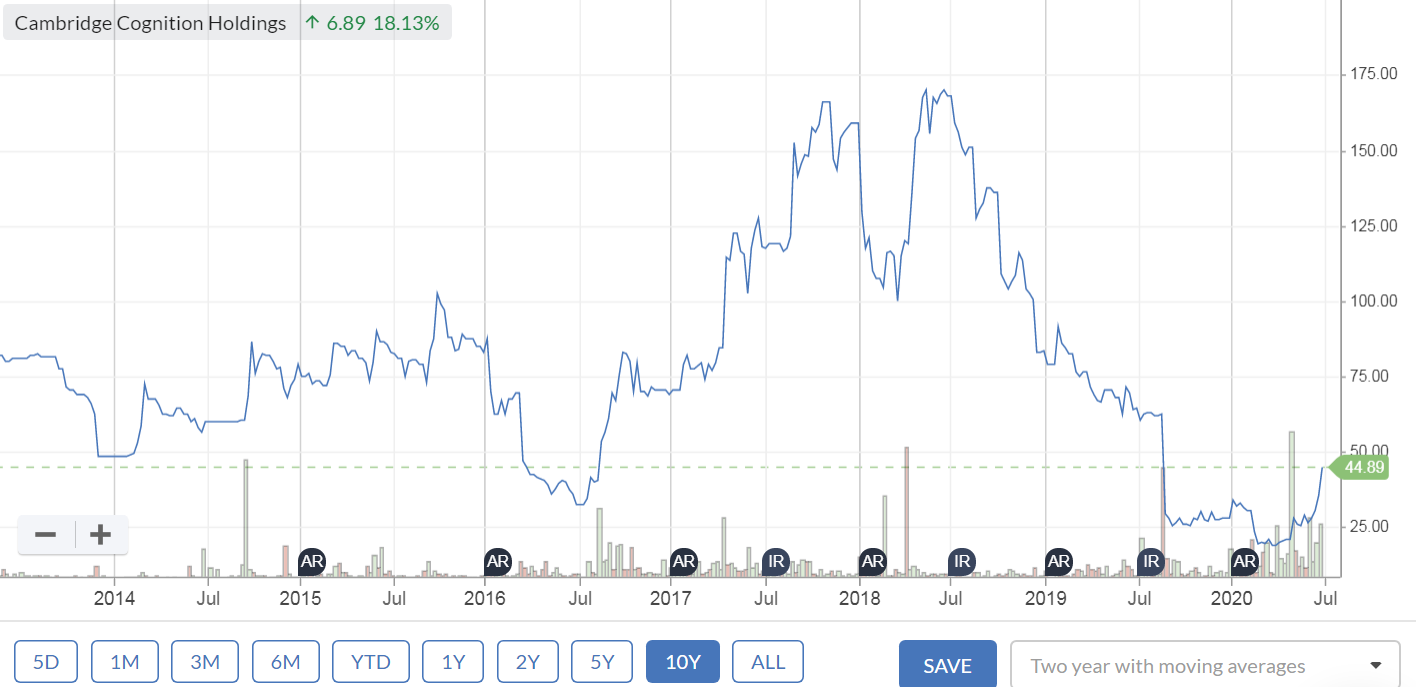
My opinion - there have been repeated false dawns here before, in the 7 years it has been listed on AIM.
I met the company a few years ago, and saw the product, and I've always thought it has an interesting niche. If sales can be scaled up, then we could see a highly operationally geared move into profit.
Overall, I think there might be speculative potential here. It sounds more than just hot air. The strategy was revised, to be more commercially focused, and a strongly rising order book suggests that it might be working. Clearly not for widows & orphans, given the track record.
Here is the long term chart since it listed;
.
Naked Wines (LON:WINE)
We had an interesting discussion here recently about this online wine club.
Here's the link for its results webinar recording. I shall check it out later.
I'm taking a break for lunch now, but will add some more sections later this afternoon.
Staffline (LON:STAF)
Share price: 37.8p (down <1% today, at 14:57)
No. shares: 68.9m
Market cap: £26.0m
Staffline Group plc, the recruitment and training group, today announces its audited preliminary results for the year ended 31 December 2019.
I reported here yesterday on the revised agreed banking facilities. I'm guessing that, with bank facilities newly confirmed, the auditors have now signed off the 2019 accounts, hence them being published today.
There's not a lot of point in poring over the 2019 accounts.
Revenue of £1,076.7m, down 3.9%. This number is inflated by pass-through revenue, being the wages paid to temps. Hence gross profit is a more realistic figure for STAF's real world revenues, at £86.5m.
The business is effectively trading around breakeven on an underlying basis, but there are lots of exceptionals, due to a series of accounting problems & mishaps. After taking account of those problems, the reported PBT is a loss of £(48.1m).
Going Concern - these disclosures are very important. As I concluded yesterday, the group is benefiting hugely from deferring its VAT payments, up to £45.7m. The crunch is coming in March 2021, with the company yesterday indicating that at present, i.e. remedial actions, it would not have enough cash/headroom by March 2021.
This is a really important point to emphasise. Many companies are building up large balance sheet liabilities, which are not included within disclosed net debt figures, because net debt is defined as interest-bearing, usually bank debt. Hence it's more important than ever to properly scrutinise every balance sheet, and determine what the total debts are, including backed up rent and tax liabilities, which will have to be paid later this, or early next year.
Note 3 gives more details about the going concern situation, much of which is repetition from yesterday's announcement. I don't like the sound of this bit - which sounds like it gives the bank scope to pull its lending facilities. With security over the receivables book, the bank would be in a good position to pull the rug out if it wanted to;
The amended revolving credit facility and receivables financing facility now include a cross-default clause that is triggered if there is a withdrawal, or reduction in the facility size and/or advance rate, of the £25.0m uncommitted (non-recourse) invoice discounting facility. The Group has a 28-day cure period in relation to the cross-default clause.
We're not given a full enough explanation of this to work out if it's dangerous or not for shareholders.
Material uncertainty - this confirms my previous comments, that STAF is definitely not yet out of the woods, and hence has to be seen as remaining financially distressed, until it does another equity fundraising.
... the Directors consider that the outlook presents significant challenges in terms of sales volumes over the coming months. The unprecedented and ever-changing impact of COVID-19, uncertainties specifically related to post-Brexit transition arrangements, well documented issues within the non-food sectors (including retail, manufacturing and automotive) and a slowdown in new contracts and apprenticeship starts are all impacting on sales volumes.
Whilst the Directors have instigated measures to manage liquidity (described below), these circumstances create material uncertainties over future trading results and cash flows.
...the Group's liquidity forecast (considering its available financing facilities) for this period is sufficient to cover the Group's and the Company's commitments during that period with the exception of a portion of the deferred VAT falling due on or before 31 March 2021, which represents a material uncertainty in relation to the Group's liquidity, although the Directors are working on options to mitigate this liquidity risk.
Not good at all.
Balance sheet - at end 2019, NAV was £75.8m. Deduct intangibles of £128.9m, and NTAV is heavily negative, at £(53.1m). At some point I think the group will have to do another equity fundraising, in order to fix this large hole in the balance sheet. It did an equity fundraising in 2019, so those funds are included within this. Another big fundraising is obviously required, which would likely lead to a doubling or tripling (maybe more) of the share count.
My opinion - there's loads more stuff in the results announcement. You could spend the whole day going through it all.
I've seen enough to make me not want to spend any more time on this. It's been a mess for a while now, and the company clearly needs to raise substantially more equity between now and March 2021 cashflow crunch time.
Therefore, for me this share is too risky, hence uninvestable.
.
Quick sections now;
Walker Greenbank (LON:WGB)
(I'm long)
Market cap £28.3m, at 39.9p per share
FY 01/2020 results show revenues down slightly to £111.5m, with adj EPS down 14% to 9.26p - a PER of just 4.3
Pension deficit - is a nasty drain on cash, with recovery contributions of £1.7 to £1.9m p.a. Hopefully this can be renegotiated.
Going Concern - short and sweet! The group has enough liquidity to continue trading for the foreseeable future. That's strong.
Balance Sheet - looks strong, with NTAV of £35.0m. Although there's a lot of capital tied up in receivables & inventories.
Divis - nothing for now, will be reinstated when conditions allow. Fair enough.
Outlook - the most important bit of every announcement these days.
Significant impact from covid. Trade is improving now, but below last year. First 5 months (to 30 June 2020), sales are 35% below last year. That's pretty bad. Slowly improving trend since April. No full year guidance.
Forecasts - how on earth are we able to value the shares, when there is no full year guidance, and no broker forecasts? It's ridiculous. The trouble is, we don't have enough information to be able to construct our own accurate forecasts. I'll have a stab at something rough & ready:
Revenues assume full year down 20% on FY 01/2020, gives £89.2m revenues for FY 01/2021
Gross profit margin of 61.1% feeds through to gross profit of £54.5, down £13.6m on last year.
Assuming no cost cutting, that would reduce the £6.4m profit before tax (PBT) to a £(7.2m) loss before tax.
Given the furlough schemes, and other possible cost cutting, then I would have thought the company could shave several million off its costs this year.
Therefore, my best guess is that we're probably looking at a loss of around £3-4m this year - that's not a disaster, and the balance sheet is strong enough to be able to absorb a knock of that size.
My opinion - I'm reassured by my very rough figures above. Combined with the confident going concern statement, I think there's very little insolvency risk here. So why is the market cap of £28.3m so low? That strikes me as an unnecessarily gloomy valuation, giving good upside if the business can return to profits next year, FY 01/2022.
The back catalogue of fabric prints, has considerable value, as is shown by the (somewhat erratic) licensing revenues.
This share look cheap to me. I already hold some, just a small position. It's rather illiquid, so I'm happy to keep this as a small position in my portfolio.
.
Trakm8 Holdings (LON:TRAK)
Market cap £7.9m, at 15.7p per share (up 21% today)
This telematics company seemed to have a lot of potential a few years ago, but it's flopped in recent years.
FY 03/2020 results are out today. Revenues up 2% to £19.6m, and it almost got to breakeven, with a £(0.2m) adjusted loss before tax (improved from a £(1.5m) adjusted loss prior year).
Net debt of £5.6m rules it out for me.
Outlook - no guidance for the year.
My opinion - it's just not a very good business in my view. Insurance telematics is a waste of time, because the only people who would tolerate their own car spying on them, are 18 year olds who cannot get conventional insurance. Then after 1 year of trouble-free motoring, they get conventional insurance & rip out the telematics box.
Why get involved?
.
System1 (LON:SYS1)
Market cap: £12.5m, at 98.5p per share (up 4% today)
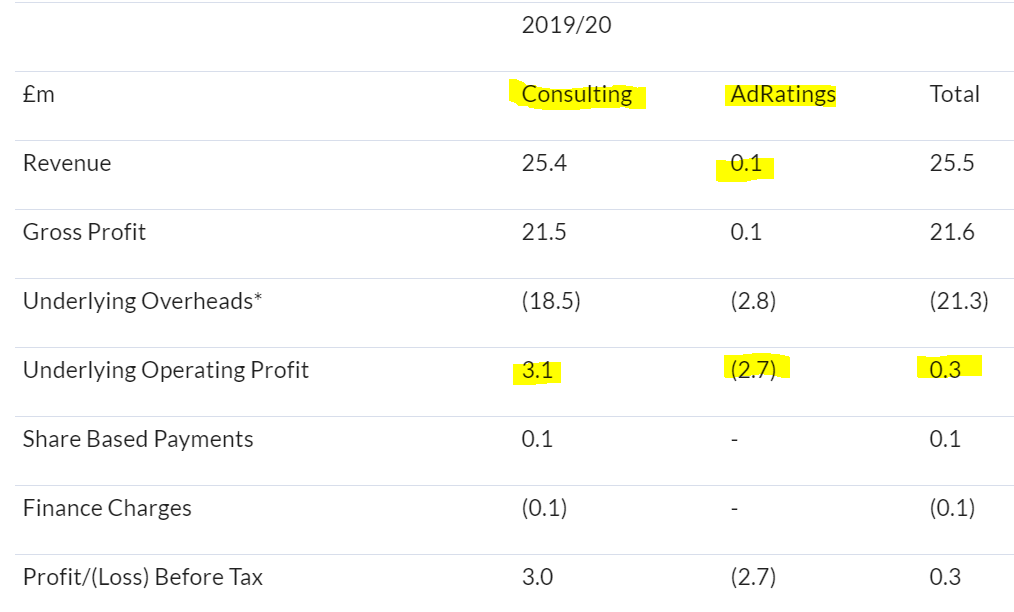
It splits out the core business results, from its loss-making startup, called AdRatings. I do wonder if AdRatings' losses are now too large for the overall group? AdRatings hardly generates any revenues, but burns up nearly all the profit made by the core business;
.
.
Of course, if AdRatings does work, then the upside on a £12.5m mkt cap could be interesting.
Outlook & current trading - a mixed bag here;
In the Trading Update issued on 27th April we said that given the impact of the Covid-19 pandemic it was difficult to provide financial guidance for the 2020/21 year, and this remains the case.
In the two months to end May, Revenue and Gross Profit were 36% and 38% respectively below the same period of last year.
Over these months the business as a whole incurred a Pre-Tax loss of some £0.7m as we pursued our short-term objectives of continuing to develop our new automated product set, while conserving cash by shrinking the cost base to offset lower sales.
Cash net of debt facilities ended May at £3.9m compared with £4.1m at 31 March.
In June, the sales pipeline has shown early signs of recovering towards pre-pandemic levels, and our cost base was in line with our targets.
Balance Sheet - looks OK to me. No solvency issues, and the company has flexible overheads, so could reduce costs relatively easily.
My opinion - something about this company intrigues me. However, when companies left right & centre are slashing non-essential costs, then I feel this is probably not the right time to be buying shares in this sector.
.
Touchstar (LON:TST)
(I'm long)
Market cap: £4.7m, at 55p per share (up 20% today)
AGM Statement. Here are my notes from first thing this morning, when I had a quick skim;
- Momentum has continued
- Strong interim result for H1 expected
- Greatly improved cashflow
- Order book >£500k at end June 2020
- £150k CBIL borrowing, plus unutilised £300k bank facility available
- No guidance due to uncertainty
My opinion - I'm quite pleased with that. It's a tiny business, but with interesting products. It looks solvent. I'm not sure why the stock market ascribes it such a lowly valuation, when there's interesting potential here. Am happy to continue holding.
Well, I'm surprised I got to the end of that list of 10 companies!
See you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
For those looking to attend MelloVirtual and wanting to see which companies are coming then here is a list with about six still to be added...
https://melloevents.com/mellovirtual-event-exhibitors/
The programme schedule should go live tonight and you will be able to buy one of the 60 or so remaining tickets here...
https://melloevents.com
I wrote a piece over at Cube a couple of weeks ago and also un-paused my Why I will be selling Walker Greenbank experiment over here.
I'm mostly pleased by today's update.
On the one hand my investment thesis is still intact and whilst we previously knew that they had been continuing to sell during the lockdown I had presumed this to be quite a minimal amount so to find out revenues for the first 5 months (3 & a bit of which were during lockdown) were 65% of last years is pleasing.
On the other hand whilst they report a "steadily improving trend" - sales still being down 31% over the last four weeks is weaker than I would have hoped.
This years numbers don't really matter so much as the exit rate and how quickly things get back to "normal". However I do like Paul's back of fag packet profitability calculation for the current year - but I do think it is overly pessimistic.
A 20% (£13.6m) reduction in Gross Profit is a reasonable guess based on what we know , but Operating costs will be down by much more than the £3-4m Paul suggests.
When I tested their ability to survive the lockdown one important point was that the "vast majority" of their staff were furloughed and all staff had agreed a temporary 20% pay cut.
The staff cost is close to £2.5m / month so three months of lockdown will have saved them at £6m I expect, plus the annualised cost efficiencies (£1m incremental I think) dropping through from last year and then other operating cost reductions (including marketing)
There will of course be some exceptional Covid expenses as well, but overall I expect they should turn a small profit this year (ending Jan-21). For the year ending Jan-22 there is no reason (at this stage) to assume earnings should not recover to at least an EPS of 8p - so at a forward PE of 5 and taking into account the quality of the business I think this looks very good value still.
We probably need to see news of sales picking up further though for the market to get to excited. The AGM is scheduled for the end of July so there will be further news then.
Hi Gromley,
That's really helpful, thanks. I had so many companies to cover today, that I could only spend a very brief time on my very crude forecast for WGB. Your logic on staff costs is very good, so it sounds like you're thinking in terms of around breakeven for the current year? I would be pleased with that.
Decorating should be something that people want to do more of, having been stuck indoors for 3 months.
Regards, Paul.
Thanks Paul,
I couldn't achieve the breadth of coverage you do - so I've cultivated a (rather long) watchlist on which I've already done some research, so I already had the staff costs figure at my fingertips.
Yes, I think around breakeven (maybe a small profit even). My main point is though that having remained solvent I think they should get back to "normal" relatively quickly - I was a holder at twice the price towards the end of last year.
As I said my main disappointment was that the YoY figures haven't recovered as much as I hoped - I understand a lot of DIY has gone on already in the last couple of months. One possible theory is that buyers of WGB products are more likely to "get someone in" than DIY and I don't think people have been too keen to have trades in their houses so far.
Walker Greenbank (LON:WGB) may or may not set the world on fire in the near term (they have always been "cheap") , but at the very least I think they are low risk.
Anyway thanks for the Mello prompt - it reminded me to book out Friday as well as the Saturday. I hope David has been creative in re-creating the evening "sessions" ;-0
Nice addendum Gromley, I hold and have added recently, albeit still down on my original purchase price. My reasoning being that the company will survive and the share price significantly discounts the value of the brands. However I am somewhat surprised and bemused by the insignificant holdings of the management team. This together with the pension deficit were the main counter arguments to buying.
All the best
See the RNS - the Directors must have been reading your post.
Solid State (LON:SOLI)
1 - CASH GENERATION
I no longer hold, but something to point out that worryingly wasn't mentioned today, but was in the last update:
"Net cash at 31 March 2020 stood at circa £3.0m as a result of continued strong cash generation and proactive cash management with clients and suppliers (2019: net debt £2.0m). Cash generation has also benefitted from a number of advanced payments totalling approximately £2.5m which will unwind across the course of the financial year ending 31 March 2021."
If one excludes this £2.5m advanced payment + working capital movements + debt repayments + dividends, the underlying cash flow was c.£2.4m.
A company worth £50m generating £2.4m of underlying cash a year seems overvalued to me, and I would only be interested if revenue and margins were on the up. Which leads me to...
2 - WEAK H2 MANUFACTURING PERFORMANCE
Manufacturing Revenue in H2 actually decreased Year-on-Year by -1.8%.
So the Full Year +8.8% looks great, but this was all driven by the +22% revenue growth in H1.
Note that the year end is March, so this H2 revenue drop should not be Covid-related.
A
What a monster report - good effort today Paul!
I'm only half way through - just had lunch, a nap, and now about to have a coffee and add some more sections! :-)
Great effort indeed. And thanks to everyone! I find the reports, comments and discussions on Stockopedia one of the most valuable elements of the site.
I have a question, if I may ask you learned Ladies and Gentlemen
I have just sold short a company called #BCPT BMO Commercial Property Trust. When I went to check the dividend payment, Stocko shows me that this company has been paying a dividend every month from 2012, can this be right? Divs are usually paid half-yearly or at the most Quartly. I have never seen a company paying divs monthly.
Please educate me.
Stocko shows me that this company has been paying a dividend every month from 2012, can this be right?
Yep. Nothing inherently strange in this - if cashflow permits then a company can pay whatever dividends it wants. However BMO Commercial Property Trust (LON:BCPT) have suspended payments due to the current issues with collecting rents.
timarr
Thanks timarr you lean something every day
In terms of D4t4 Solutions (LON:D4T4), think this is pretty significant from today's results...
"In the short term there is a well-known consequence of transitioning from perpetual to recurring licence models in that revenues recognised in the year are lower, hence the reported revenues fell from £25.2m to £21.7m in the period. If the majority of new contracts had closed on a perpetual licence basis then there would have been significant top line revenue growth in the year.
Several large contracts that probably would have closed on the existing perpetual licence basis were deferred into 2020/21 as a result of multiple stakeholders in client and partner organisations needing to review and approve new recurring revenue based contractual terms."
Given the backdrop, I am sure we would all have been happy with significant top line growth... ...and this is despite perpetual deals sometimes being more difficult to get over the line.
Great point, thanks for posting it.
I believe moving to SaaS is like hiding profitability in plain sight. Hiding it from the impatient, who don't look behind the numbers, and want short-term growth.
If you believe in the product, and trust the management, the transition phase is a real investment opportunity. I went through it with Proactis a decade ago and it ten-bagged before over-reaching with an acquisition.
D4T4 is in a market sweet-spot with a best-in-class product, and it's growth disguised by moving to recurring revenues. It is one of my biggest holdings.
Jon
As Paul (I hope!) correctly points out one of the major advantages of the change should, over time, be a smoother revenue pattern. Severe changes in six month sales reported have not been helpful.
No. That's where trust in management comes in. When they miss HY by a mile and say, don't worry we'll still hit the FY number, a lot of sceptics exited, understandably.
But it also meant their shares were available at half price for a while.
Paul could you please take a look at Sysgroup £SYS results? Thank you
Creightons (LON:CRL)
On one of the more infamous message boards, someone posted that Creightons (LON:CRL) would have to be suspended today because they main market shares get 3 months to release results. Could one of the more enlightened posters here give a comment on the veracity of that statement please? Thanks in advance
I don't know about the regulatory requirements, but I find ti difficult to believe that the management of Creightons who I have met and in my view are very sharp and have sizeable holdings would have overlooked such a fundamental issue. I was expecting the prelims at the end of last week, but we will have to wait and see.
I hold.
Yeah, that was my thinking too, but the complete lack of a trading update and even an announcement of when results will be presented is starting to spook me.
I hold to. Big thanks to Paul for flagging these when they had the "we've got too many customers" profit warning. Well in profit here.
For a main market company ( Creightons (LON:CRL) is) it is 3 months for interims and 4 months for prelims but there is currently a 2 month extension to these to allow for production of figures taking longer due to lockdown so they have until the end of September. Lots of companies have delayed their results recently
https://www.handbook.fca.org.uk/handbook/DTR/4/2.html
https://www.handbook.fca.org.uk/handbook/DTR/4/?view=chapter
https://www.fca.org.uk/firms/regulatory-reporting/changes-regulatory-reporting-during-coronavirus
Thanks, that's good to know. I'll stop worrying for now.
Hi Paul, thanks for the Mello heads-up. I’ve always fancied going but have never been able to - but can in this new virtual world. (I would not have known about it had you not flagged it). And really enjoying your macro / small-cap report mash ups :)
Jon
Interesting small cap stock CLCO out with interim results today. Far better than expected and the market likes them. This caught my eye
3-year cyber security management deal with major online fashion retailer, boohoo
Highly speculative and very risky. They have little cash but a potential turnaround (disclosure: I hold a few).
£D4T4 looks a good update, increased cash, no need for gov help due to c19, increased margins and move towards recurring revenue. The product ‘celebrus’ seems to be in a sweet spot given it provides online realtime data on customer web useage/transaction optimisation. Complex area but customer & partners seems to like the product. Report also mentions a number of contract renewals delayed as they are working through the detail on how to make them recurring. This is the third time d4t4 have stated this, in previous years the contracts delivered.
I had an email conversation with the ceo last year about move to recurring revenue and what they were doing, he was very non committal but i think he actually came across as very steady eddie and not over promise. I decided to hold then but these results look good to me so third request for your view Paul please.
Morning Paul
I agree with the comments below on £WGB. This morning's prelims on initial reading appear positive overall. While the share price may reflect current trading, it fails in my view to take account of the valuable archives held by the company, which it is progressively monetising via its licensing activities. On the downside there is a deficit of about £5.5m on the closed defined benefit pension schemes, which has given rise to a £1.9m annual contribution to reduce the funding shortfall by 2026. One of several take over candidates in the small cap arena I would suggest. I hold.
D4t4 Solutions (LON:D4T4), which I also hold reported prelims that are encouraging, although one has to look through the hit to profit and revenue resulting from transitioning the business from one based on the sale perpetual licences to one offering a fully fledged SaaS, with the resulting improvement in margins and quality of earnings this brings.
Your thoughts on either or both would be appreciated.
Keep up the good work.
Update reference the EY audit of wirecard
According to the FT, Wirecard claimed it had almost £1bn in cash contained within Singapore’s OCBC Bank, which the accountancy firm failed to request information from. The FT’s report also claims that, instead, EY relied on filings from Wirecard and screenshots from a third-party trustee.
This just about sums up worldwide auditing standars in a nice simple paragraph - note this was over a 3 year period too!
Wirecard
I am always very surprised when I see (up to now here) allegations that auditors did not seek direct 3rd party confirmation with banks - some of which, from memory, prove to be correct.
Global accouuting governing bodies are, as far as I'm aware, as one on their Auditing Standards that a 3rd party confirmation is required for each and every bank account/loan. This is needed not just to prove the quantum of the cash or loan but also provides valuable confirmation of security, charges given and contingent liabilities.
When I was an auditor I spent several hours on the phone chasing up bank letters with banks/clients. Far more recently on the other side of the fence I had to spend quite a lot of time getting access to a small subsidiary's minuscule bank deposit account (both signatories left) to ensure the group's consolidated statements were not qualified - the auditor (large firm but not big 4) explained it was mandatory in his firm and a colleague was no longer allowed to run audits when he/she did not pursue on the grounds of materiallity (similar situation).
Phil
Second any chance of a rambel on Redrow (LON:RDW) for read across building sector and the On The Beach (LON:OTB) Paul capital light model risky but papers seem to say massive demand for hols abroad against risk of more international lock downs.
Thanks Andy
Would you comment on D4T4 Solutions (LON:D4T4) and Solid State (LON:SOLI) please Paul. Thank you.
Walker Greenbank (LON:WGB)
I hold some of these and have added a little recently- current marekt cap of £26 mill - i see the potential for decent upside if they can get away without dilution to current shareholders.
They can make £6 mill profit a year based on pre covid estimates - so potential for over 100% upside if they can trade their way through the current issues.
sales seem to be running at 65% of normal - they need to keep upping that and hopopefully they can breakeven (ignoring exceptional - lol) or so this year - although unhelpfully they give no forecasts themselves so my breakeven is fantasy back of the envelope stuff.
Will the balance sheet suffice to avoid dilution?
at 31/1/20 - pre covid
inventories £28 mill - not really much use this stuff if one needs cash but it kinda is an extra comfort blanket for lenders perhaps.
Receivables 20 mill - trade and other payables 22 mill
Deficit here which isnt a great start and the numbers are high compared to annual profits. there must be some debtor isolvency risk at present and the creditors will never go away without bieng paid.
cash 3 mill - borrowing £1.7 mill - note near end of march they had moved into net debt due to seasonal cashflow reasons!
adding up all of the above roughly neutral
Leases £3 mill under 12 months and £5.6 mill over 12 months - not really material either way
Pension deficit £5.7 mill - probably not ashort term problem.
Lots of property plant and equipment which i will mostly diso#### but they do have freehold land and bulding at cost price of £5.7 mill - so presuming it hasnt gone without me noticing i would say this is anice little brucie bonus to have at time like now.
Overall score C - it seems to be the fashion to raise funds at the cheapest possible price shafting current shareholders at present - if they can kinda be near breakeven without a silly amount of exceptionals this year i don;t see the need to raise fund s- however i dont know tje score and the paranoia will likely be setting in in the board as they see the obvedraft creep up and the future headroom dwindling. Heres hoping they bumble along without dilution.
As an aside is anyone else slightly annoyed by the tendancy to give absolutely zip guidance - kudos to the companies that at least gives us something however sketchy - why not say range of breakeven to £4 mill loss - ignoring exceptionals which we expect to be no less than £2 mill of which £1 mill is cash related - is that too hard to do? - add in your covid related things could be materially differeent. Not surprised the shareprice is languishing when we have less than bob hope chances of knowing what the score is - ooooh good news agm is next month so hopefully forecasts will be restored.
Is the market negative reaction to Redrow (LON:RDW) seemingly reasonable results a good chance to buy? I am puzzled when there is a sell off... what were investors expecting?
I suspect the negative reaction to Redrow (LON:RDW) comes from their statement "the profit for 2020 will be substantially below 2019" without any attempt to quantify that 2 months after the year end.
The interesting bit, confirming what estate agents have been saying, is that they are scaling back on London operations (resulting in costs and impairments) to concentrate on building homes elsewhere with gardens and home workspace.
My take is that RDW was among the first to cancel its interim dividend this year and the reaction of most may be to expect more tardiness. On the other hand a Contrarian might see a bountiful final dividend on the horizon similar or better than last year's.
Silver Moon
Interims from Driver (LON:DRV) this morning - another one with excellent extension of the previous closed doors analysts meeting to private investors now Covid has forced it online.
This one is at 9 30 here: https://webcasting.brrmedia.co.uk/broadcast/5edf76215e278421d0696f87
Hi Paul - would be really happy to hear your views on £WGB's results. They seemed pretty reasonable to me, but share price is down.
Could you comment on On The Beach (LON:OTB) interims please Paul.
Nothing too surprising it seems in their interim update where profits have inevitably taken a big hit from coronavirus. Their business model does not rely on forward bookings payments for them to trade successfully, unlike so many other travel Companies, which seems a big plus in current environment.
CFO is going but it seems on good terms.
Two of mine reporting today D4t4 and £SOLI
Mixed bag for both. D4T4 announce a fall in revenue and profit but say it can be explained away as they are shifting to a recurring revenue model and the the early indications are this year will be one of growth.
Soli are the other way around, an uplift of revenue and profit for last year (reported profit up 42%) but the order book is 15% down in Q1. All the smart advice on this site is sell the profit warning early, so I think I’m going to be out of this one shortly.
As you say, the report from Solid State (LON:SOLI) is one to mull over. The negative is a big drop in new orders from the oil and aviation sectors, the positives are that all factories have stayed open and prospects continue to look good in other sectors. They are maintaining, but not increasing, the dividend for the year. There is a pay freeze for senior staff and some capex is deferred. I purchased because I think it is extending its reach to more strongly growing business, and I don't think that has changed.
I hold Solid State (LON:SOLI) and have viewed this as a long term buy and hold purchase. I have removed my automatic stop loss following a varied performance of them over the last couple of months with general volatility and intra-day price fluctuations triggering them, and then having to watch the value bouncing right back or higher again often.
I have to be honest and say that I have a day job, my wife is frontline NHS, children to home school (or in three weeks work out how to entertain for 6 weeks) and elderly parents to support. So whilst I do have more access to things like home email and internet currently than I would in the office I am an investor more than a trader.
So there was an opportunity for me to sell (for a small profit) and buy back in again after the initial management view of results a few weeks back on which Paul commented - but I was not quick enough to take it and it was not part of my plan at that point. By the looks of this mornings price spike and drop back the same thing happened again today, so I hope that you were able to sell at a £profit within that early spike.
There is a hard choice facing a lot of us this year, which Paul has been regularly flagging, that there are going to be some good, bad and VERY BAD results coming out throughout the year and the question we each have to answer for ourselves is what is priced in within the current valuation and what your personal profile is.
The other risk which I personally cannot quantify is how jittery other investors are as it only takes a few buyers or sellers with something like £SOLI to create a large movement upwards or downwards with price. So as of 10:42 this morning I think that my head continues to be Hold (~4% of portfolio) with a possible add if it does spike down later this year. But then I might change my mind as soon as I have posted this.
T.
My morning smallcap tweet: 18 summaries. Phew.
Staffline (LON:STAF) Syncona (LON:SYNC) On The Beach (LON:OTB) IDE Group (LON:IDE) Inspired Energy (LON:INSE) Redx Pharma (LON:REDX) Filtronic (LON:FTC) Vianet (LON:VNET) M&C Saatchi (LON:SAA) Good Energy (LON:GOOD) Cambridge Cognition Holdings (LON:COG) Yourgene Health (LON:YGEN) Touchstar (LON:TST) Comptoir (LON:COM Immunodiagnostic Systems (LON:IDH) Robinson (LON:RBN) ECSC (LON:ECSC) Fireangel Safety Technology (LON:FA.)
Staffline (STAF) FY19 results. Trading: "cautiously optimistic that each of the three operating divisions will achieve a positive result in 2020 on an underlying operating profit basis." Gov't expected to launch new funding for training and retraining schemes, which PeoplePlus is well-positioned to benefit from. I hold.
Syncona (SYNC) portfolio company, Freeline, expects to consider additional capital raising options this year, which could include a US IPO.
On the Beach (OTB) CFO leaves in July. He is thanked.
IDE (IDE) delays FY19 accounts by up to a month. Guides rev down 31%, adj EBITDA 'profit' £1.1m (-3.9m) boosted by £0.9m due to IFRS16. Current financial year remains broadly in line. New project wins offset new project delays into H2.
Inspired Energy (INSE) AGM stmt. Order book £61.1m up £1m in a month. "Group has remained both strongly cash generative and delivered profits ahead of management's prudent downside scenario."
Redx Pharma (REDX) to issue $29m of convertibles and $1m placing to keep the lights on and "progress our exciting pipeline of drug development projects" ie continue business.
Filtronic (FTC) H2(May) broadly in line with market guidance. Guides FY rev-cont £17.2m up 8%, adj EBITDA £1.2m (£0.7m). "Whilst we have entered FY2021 with a good order book, it would be imprudent to be anything other than cautious on the outlook."
Vianet (VNET) AGM stmt. Smart Machines: "Contracts have been finalised with several new customers, including Tchibo and Lavazza, and there is an encouraging pipeline of new contracts under discussion that are pending customers returning to more normal operations....confident that the Group is in a very good position to resume its strong earnings growth."
M&C Saatchi (SAA) April and May not quite as severe as co first expected. Seeking covenant relaxation and covid loan. FY19 accounts delayed.
Good Energy (GOOD) AGM stmt. YTD U/L profitability in line. Co remains cash generative and profitable.
Cambridge Cognition (COG) contract wins take YTD order intake to £4.9m (prev H1 £2.6m). Unless there is a second wave, expects that most, if not all, clinical trial sites will be open during Q3 2020.
Yourgene Health (YGEN) launches Clarigene covid test for research use only.
Touchstar (TST) AGM stmt - continuess to outperform against the expectations contained in covid roadmap. Guides 'strong' H1.
Comptoir (COM) will open restaurants in phases from 4 July.
Immunodiagnostic Systems (IDH) 25 minute IgG covid antibody test goes on sale. Has sensitivity of 100% and a specificity of 99.4%.
Robinson (RBN) expect delays of at least 6 months in selling surplus properties.
ECSC (ECSC) AGM stmt - target of operating on a break-even Adjusted EBITDA basis achieved in May and will be exceeded in June. Some furloughed employees returning.
FireAngel Safety Technology (FA.) AGM stmt - recent 6 month rev over 70% of the pre-covid budget. June has seen demand returning and sales team returned from furlough. Retail sales in June are expected to be up YoY. Wins initial £1m+ order for connected home from a local authority, delivered over 12 months.
On Staffline (LON:STAF) ( small holding), I was struck that the company currently has £41m of available liquidity (nearly all cash) and virtually all of it (£38m) is due to delaying VAT payments to March 2021. There is a long and very helpful section on the various refinancings and how the banks’ grip on the business has tightened. Very clearly it is the banks now calling the shots.
The lengthy notes on the assumed mitigating actions the board will be able to take to allow the business to continue as a going concern (note 3) include (as well as the usual further cost cuts and potential further equity raise), “if required” negotiating with HMRC to defer some of the already deferred VAT, which now falls due in March 2021”. This is the first time, I have seen a company write this in a statement and shows the pressure that HM Treasury will be under to support struggling businesses in the years ahead.