Small Cap Value Report (Tue 31 Oct 2017) - EPO, ULS, WEY

Good morning, it's Paul here.
Apologies, I forgot to put up a placeholder article last night, so here it is.
It's a quiet day for results & trading updates today.
Earthport (LON:EPO)
Share price: 18.5p (down 4.5% today)
No. shares: 630m
Market cap: £116.6m
Final results - for the year ended 30 Jun 2017.
This is an international payments company, which has been listed on AIM since Jan 2001, with an utterly dismal track record. Over that time it has accumulated total post-tax losses of £152m.
Profitability (or rather, losses) have either got better, or got worse compared with last year, depending on whether you focus on adjusted, or statutory operating profit, as shown in the P&L excerpt below;
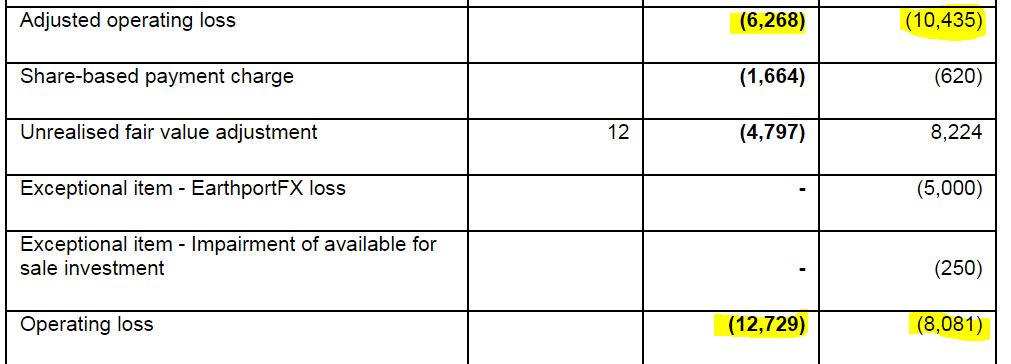
The cheerful narrative obviously focuses on the adjusted operating loss, which shows an improvement from -£10.435m loss last year, to £-£6.268m loss this year. Only in the bonkers alternative reality world of Earthport, can this be seen as a "positive year.."
That said, there is some impressive growth reported in revenues & transaction volumes;
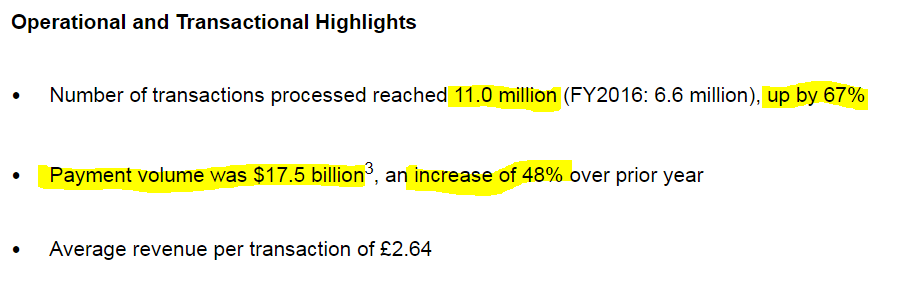
11m transactions processed is actually quite impressive. So how come the company cannot make any profit on that? It reports gross margin of 67%, but of course it depends how costs are classified. A big gross margin can be reported if most costs are reported lower down the P&L, in administrative costs. Although note that, despite good top line growth, admin costs only rose marginally, which does support the idea that there could be good operational gearing here, maybe;
Administrative expenses marginally increased by £0.6 million to £26.4 million (FY2016: £25.8 million). Administrative expenses as a percentage of revenue were 87%, compared to 113% for the previous year, mainly due to increase in revenues and cost efficiency.
This supports the idea that if big increases in revenues continue, then the trading performance could transform. I'm starting to warm to this company a little.
Balance sheet - this is already out of date, as the company raised £24m (after fees) in a placing priced at 20p, on 4 Oct 2017. When you adjust the balance sheet for this recent fundraising, it looks fine. Net cash of £11.9m would rise to a pro forma basis of £35.9m, which seems ample, in relation to cash burn.
I'm not madly keen on the "derivative financial instruments" of £7.3m shown within current assets, and £3.3m shown within current liabilities. Note 13 gives more detail - these are forex hedging instruments. I don't like that - it introduces risk of something going wrong, if poorly managed.
Outlook comments can usually be safely ignored with this company. The pattern in the past has been unrelenting optimism, despite continued trading losses. The company has not reached its target of cashflow breakeven.
On current trading it says;
Current trading, including core operational metrics in the first quarter of FY 2018, are broadly in-line with management's expectations and ahead of the same period in FY 2017.
The progress made in FY2017 has established a solid platform from which we can continue to grow, and we look forward to FY2018 with confidence in both our operational and financial performance.
EU passporting rights is a key issue for financial services companies;
...The Brexit vote, followed by the hung parliament result following the general election in May complicates the negotiating stance that the UK has with the European Union (EU). We continuously monitor the progress made at the EU negotiating table, to assess the lasting impact for Earthport.
We must plan for all eventualities in order to maintain our ability to transact within the Single Euro Payments Area (SEPA). If we were to lose our intra-country ability to passport our regulatory status across all the countries within the European Economic Area (EEA), Earthport and other cross-border payment providers would need to have some form of physical licenced operation in an EU member country in order to operate effectively. These uncertainties will continue to play out over the coming years, and we remain vigilant of any significant change.
That sounds like it could be costly, for this relatively small company.
My opinion - I've been bearish on this stock for many years, due to its lamentable financial performance. However, when the facts change, we should change our minds. In my view, there is a glimmer of light here. If the company can continue strong growth in transactions, and then benefit from operational gearing of a 67% gross margin, then the picture could improve considerably.
Overall, I wouldn't consider buying shares in this serial disappointer. However, I certainly wouldn't want to be short of this share either, now that it's reporting decent revenue growth.
ULS Technology (LON:ULS)
Share price: 141.7p (up 8.7% today)
No. shares: 64.8m
Market cap: £91.8m
Trading update - covering the 6 months to 30 Sep 2017.
ULS Technology plc (AIM:ULS), the provider of online B2B platforms for the UK conveyancing and financial intermediary markets...
I've not written about this company here before. Although it did crop up on a screen a while ago. I remember considering it for investment, but decided against. Pity, as the share price has done a very nice stair step move upwards;
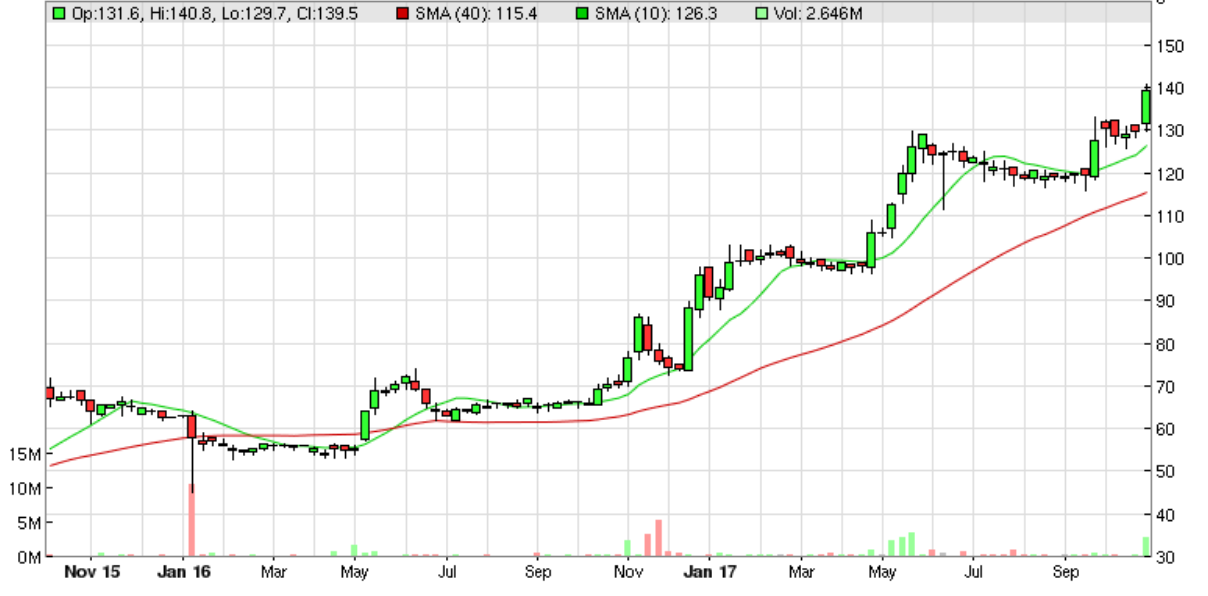
I was reading a chapter about charts in my favourite investing book, by Mark Minervini, the other day. He favours charts like the one above. This stair step move up is a sign of investors accumulating the stock (obviously), and is one of the most positive charts you can have. The danger with this type of movement, is that shares can run to over-valuations, and then suddenly plunge when reality bites.
Also, as I mentioned recently, we're seeing a general move up in PE multiples. So stocks which used to trade on a PER of 14, now seem to be moving up to a PER of 20. Sure enough, that is the case here. Stockopedia shows a forward PER of 20.3. If you use the "Print" button, and drop down menu to look back at the StockReport a year ago, from Oct 2016, this share was indeed on a forward PER of 13.9 .
The company has also been beating broker forecasts. A year ago broker consensus was 4.6 EPS for y/e 31 Mar 2017. The company actually achieved 5.06p - usefully ahead.
Forecast for the current year is 6.13p, whereas a year ago the forecast was 4.9p - that works out at a 25% increase in forecast EPS in the space of a year - impressive. I very much like companies where forecasts are rising, and earnings beats occur. In that type of scenario a company which initially looks expensive, might turn out to have been good value, because it was set up to beat forecasts.
That's why I think it's very important to always remember that broker forecasts are usually wrong - companies over, or under shoot, often by very considerable amounts. Hence why it pays to look for companies that seem to be well set up to beat forecasts. The flipside being to avoid companies where the broker forecasts look too optimistic.
Anyway, this is what the company says today;
The Group has continued to trade well during the first half of the financial year with revenue and profit before tax ahead of the Board's expectations for the period...
Helpfully, the company gives us its forecast for H1 performance;
Revenue for the period is expected to be approximately 56% up on last year at £15.28m (H1 2017: £9.78m), with underlying profit before tax up approximately 42% to £2.74m (H1 2017: £1.95m).
These increases are partly due to the acquisition of Conveyancing Alliance Holdings Limited ("CAL") in December 2016 but also due to organic growth in the remainder of the Group.
This growth was achieved against the backdrop of a housing market where overall transaction numbers continue to remain markedly below long-term averages.
Cash generation continues to be strong and net debt has been reduced.
Since it was acquired in Dec 2016, CAL will have contributed a full 6 months trading in H1 this year, but nothing in H1 last year. It's a pity the company didn't specify how much profit growth is organic, and how much due to the acquisition.
Referring back to my point previously, this acquisition is probably what drove the broker forecast increases, or some of it anyway. Therefore the growth in earnings is less impressive than if it had been just down to organic growth.
Outlook - sounds positive, despite a slow housing market;
The Group continues to win new contracts and has a healthy pipeline of new business which the Board believes will enable the Group to continue its strong performance during the second half of the current year and increase its conveyancing market share...
...Although we have had success in pretty much all our market segments over the period, it is especially pleasing that we are gathering good momentum with mortgage lenders, a market segment that we are focused on achieving further success in."
Valuation - this table will update overnight, to reflect the higher share price, and should update again after that for increased broker forecasts. I imagine that those 2 changes would roughly offset, leaving the PER about the same;
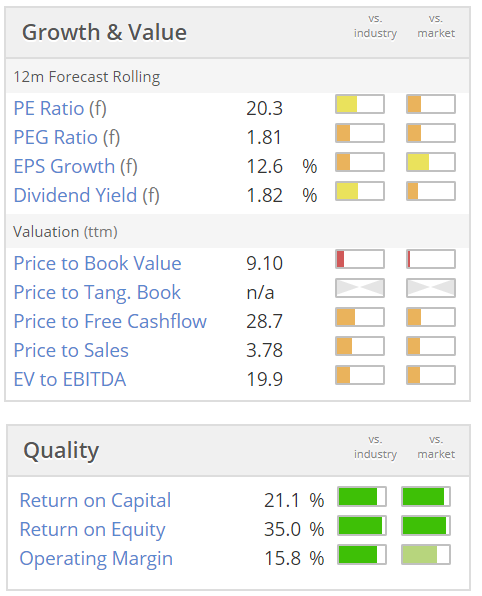
Note the excellent quality scores above.
My opinion - I've had a quick look at the last reported accounts, for year ended 31 Mar 2017, and I'm impressed. This is a strongly profitable, and cash generative business. As such, the weakish balance sheet doesn't really matter. Although it does restrict the company's ability to pay dividends.
Overall, I quite like this company. It's not cheap, but seems to be carving out market share in the UK conveyancing market. It seems to offer niche services, like conveyancing price comparison websites, etc.
I probably won't invest here, because I'm not sure how scalable this business model is? With internet disrupters, generally I look for something that could scale up 5-10 fold long-term, or more, to justify paying a high price. I'm not sure if that is likely here or not. Having said that, a PER of about 20 isn't actually a high price these days.
Overall, it looks quite a nice business, and might be worth some deeper research maybe?
Wey Education (LON:WEY)
Share price: 24.4p (up 28.3% today)
No. shares: 104.0m
Market cap: £25.4m
Preliminary results - for the year ended 31 Aug 2017.
...the education group operating the UK's only online fee paying secondary school...
This is an online education business, which operates an online secondary school, plus a consultancy business. What an interesting idea - running a school online. I've never looked at this company before, but Graham mentioned it here on 31 Aug 2017. Graham was sceptical about the valuation, at 22p per share then. He also pointed out the small free float. On the positive side, the company flagged strong revenue growth of 60%, and a maiden profit).
I like online disrupters, and 60% top line growth is enough to make me want to take a closer look. Unfortunately, I wasn't paying attention on 31 Aug, so I didn't see Graham's report linked to above.
Here are the highlights, with my highlighting added;
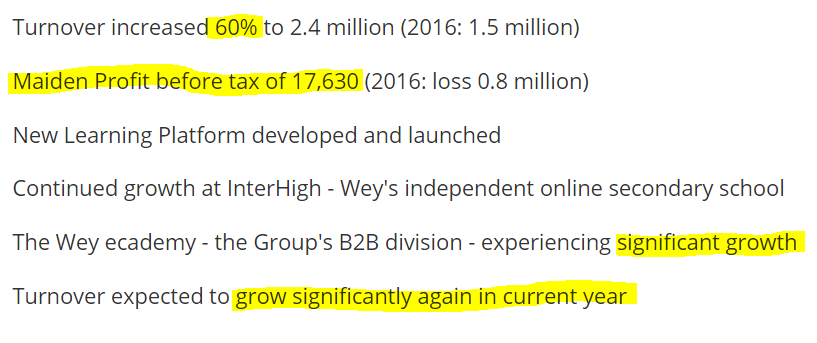
Whilst the growth is very good, these are still tiny numbers, for a £25.4m market cap. So clearly the market is pricing in continued growth. Moving from a loss of £0.8m last year, to a tiny profit this year, is impressive though - that suggests good operational gearing. If the business can scale up decently, then this could become a much more profitable company. This share is clearly a growth type share, not a value share - so the valuation won't make sense on a PER basis.
A word of caution though, it always pays to look at the full numbers, as often highlights can be misleading! In this case, a positive exceptional item this year, and a negative one last year, has skewed the operating profit improvement quite a lot;
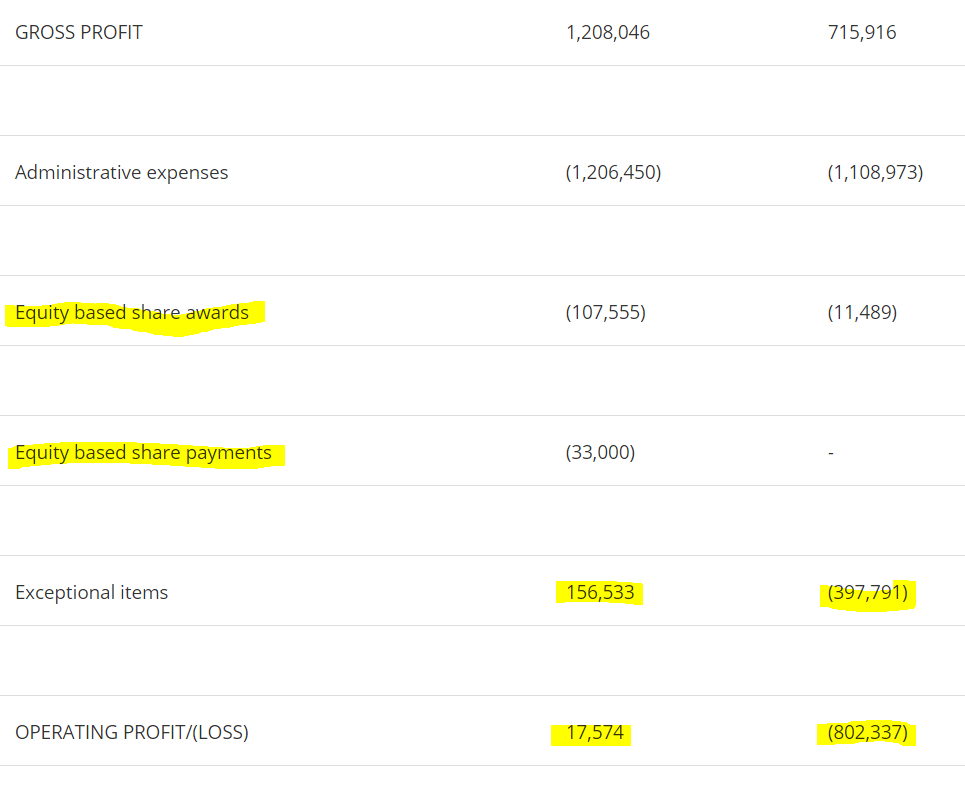
If we strip out the exceptional items, then the adjusted figures would be;
y/e 8/2017: loss of -£139k
y/e 8/2016: loss of -£405k
That's clearly still an improvement, but a much smaller improvement of £266k, as opposed to the £0.8m improvement trumpeted in the highlights! That's a little bit naughty really. I think maybe this announcement has been a bit over-PR'd!
Balance sheet - as you would expect, this is a capital-light business model. Tangible fixed assets are only £102k. It's remarkable that a secondary school with over 1,000 pupils (WH Ireland estimate) can operate online with only £102k in tangible fixed assets.
Overall, the balance sheet looks OK to me. It's small, but has an adequate net cash balance of £1.0m (up from £0.9m a year earlier). Total liabilities are very low, at just £0.65m.
So providing the company doesn't incur losses in future, then I don't see any need for further fundraisings, hence probably no more dilution.
Cashflow statement - I don't see anything untoward. Note that development costs of £267k were capitalised. This is not too far away from the amortisation charge of £160k.
Outlook - sounds positive;
The Group's turnover grew 60% this year and the Board's ambition is to at least maintain that rate of growth in the current year and beyond.
More detail is given for each division, so see the RNS for that.
I do wonder if 60%+ growth is manageable? There's a risk that if the company expands too fast, quality & control could drop.
My opinion - this looks potentially interesting, in my view. I'm going to do some more research on it. My initial reaction is favourable towards the business model, but sceptical about the current valuation. That said, as we know, if you want strong growth in a bull market, you have to cough up for it.
Key questions for me, are to try and get hold of independent reviews of the company from pupils/parents/teachers - is it any good? Are there any problems? What is the pupil churn rate? What are the backgrounds of the Directors?
I see (from the company's website) that the fees are only £2,700 per annum, which is clearly much more affordable than bricks & mortar private schools (which admittedly provide a much more rounded service). For kids who need to be home schooled for whatever reason, I can see how WEY could be an interesting option.
That's all for today. Sorry I didn't get round to looking at Cerillion (LON:CER) .
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
Paul, you mention minervinis book. I have just finished william j o neil book how to make money in stocks.
I have read minervinis book and its easy to read. O neils book is good too if you take out 100 charts at the start and his self promotion website in chapter 16. I,m always open to learning
But my goal is to read as many of the books on stockopedias guru screens. So far I have read 9
So far the best 3 in this order are minervini, o neil (canslim approach), David Dreman
I have read these:-
. Benjamin graham intelligent investor, o shaughnessy what works on wall street(zz), robbie burns, pat dorsey the little book that builds wealth, david dreman contrarian investment strategies ,nicolas darvas how i made $2 mill in the stock market, (zzzzzzzz), g m loeb battle for investment survival (zzzzzzzz) , how to lie with statistics darrell huff (eds recomendation), Van vlet , high returns from low risk
Need to order some more books. Its addictive and stops my twitchy finger buying and selling. Its Definitely improved my trading.. Losing less on spreads, commision and not buying and selling like some crazy demon.
Think I have held a share (BUR) for other a year now which is a record for me as I used to sell after a month or so, and Im up over 100% with it..
You and Graham keep up the good work
ULS has legs, don't worry about any potential slowdown in the housing market. They currently have circa 2% of the total conveyancing business. Its target is to grow this to 10%, I think this target is very achievable. Do the numbers, this stock has a lot of upside yet.
Hi Paul, I'm running a bit late and only just read the article about your antique clock radio, so forgive me chipping in today.
Regarding clocks linked to the MSF atomic clock transmitter, I have had two and both suffered the same drawback so I don't know if it's universal, that is regarding the changeover to BST and back to GMT. The clock signal as far as I'm aware synchronises only at 0000 hrs daily whereas BST/GMT switchover happens at 0200 hrs so my clocks don't actually synch until 22 hrs later. So no good for an alarm call on the sunday unless you make an allowance in setting the time. I always rely on the phone clock for alarm calls for this reason.
The radio function, I also get via the phone on WiFi linked to a portable bluetooth speaker. i have just purchased a Sony SRS-XB20, get yourself to Currys for a listen, my local had a demo all set up, you'll be amazed at the sound from such a small size and impressive bass too. Shut your eyes and you'll think you are back in a club. It's part of a range which include a compatible sound bar for home cinema wireless surround sound. Treat yourself for Christmas.
PS you can download all your disco music to you phone too :-)
Hi Apad,
I've looked at a few online learning businesses and the first task is to build a scalable online platform with non-plagiarised content, a call centre for sales, marketing and general enquiries and a 'tutor' support network (usually contracted as flexible staff / cost base). It is worth checking out the Wey Education (LON:WEY) online reviews to check that they've nailed this piece and that the offering is 'high quality' before they look to scale.
I don't know enough about the WEY proposition but I agree that the market size is far too niche if they are focused only on home schooled children as an alternative to mainstream education.
My opinion on the upside potentially available to the business is:
i) despite what we may think, the British education system is still revered globally with large growth in international schools (in the Middle East / Asia especially) which are built on the English curriculum Distance learning can provide a credible alternative for Parent's abroad who want to get access to the British system.
ii) there are students who get through school / university and find out they need a Maths / English GCSE or A level to get a job, Distance learning appeals to jobseekers or employees looking to 'up-skill' on the side or 'fill in' a gap in their qualifications from a previous period in life.
iii) once the platform and infrastructure is built, you can look at expanding the range of course and qualifications you offer with little additional investment spend. The value is in the brand name and reputation. One problem is the amount of online marketing spend (PPC and keyword) you need to protect your market position.
Anyway, I have no idea whether any of these 'strategies' are in management's business plan or not but thought it may get others thinking!
Nico
Apad, if you read the WEY RNS you will see that the group is about far more than a simple school for children, albeit that has been the core business before the recent additions (Wey ecademy (B2B), Infinity (service to enable entry to Oxbridge, MIT, Harvard etc), Quoralexis (English as a foreign language and later expanding to more languages). The world educated population is essentially the target market and there is money around there.
On the subject of the UK state school system, it is a broken and partially bankrupt edifice and plenty of evidence exists to show that parents and children want a way out not to mention the lack of funds available to serve every child as parents would like.
There seems to me a couple of inevitabilities here. One is that regardless of the views of “older types” like us, online communication is the language of the young. Two, government is strapped for cash and it is not improving. It seems inevitable that education will piece by piece be outsourced online.
WEY
Hi Paul,
The market in parents educating at home must be extremely small.
Poor social areas are unlikely to generate much in the way of customers either.
There must be something else for such a company to succeed and I cannot see what.
BTW research shows that the most important influence on children is their parents until they reach puberty, when it switches to their peer group. Makes sense really.
Regards,
apad
Paul, you say that you have reported incorrect data for referral to Thomson Reuters. I have reported what I believe to be incorrect data to Stockopedia, and also Morningstar which I also use, on several occasions. Perhaps we too frequently make investment decisions on the summary data without questioning its accuracy. Morningstar also use Thomson Reuters data and I have sometimes found the figures for the same metric differ between Morningstar and Stockopedia. I think it pays to be cautious using summary figures, especially derived metrics like PE etc.
On your ChipsAway experience, difficult to believe that a serious company like that does not carry a small onboard generator!
As always, excellent commentary, thanks.
Hi cic,
I was discussing the issue of data errors from Thomson Reuters with Ed, at our meeting last week at Stockopedia HQ. The situation has dramatically improved over the last year or two. I used to raise loads of tickets for data errors, but it's now quite rare.
Apparently TR have put in place better processes, plus Stockopedia staff & readers have helped clean up their data by pointing out errors. Clearly not ideal, but things are now tons better than they were.
I agree with you though, when using any financial site, we should always double-check key items to the Annual Report, and/or RNS announcements, rather than relying 100% on data which might only be 99.9% accurate.
A long time ago I gave up using any fundamental data on advfn, as it was absolutely riddled with errors.
Regards, Paul.
WEY
It's too easy to think that social activities can be done over the internet.
Distance education has to be supported or people get disheartened and leave.
The problem with support is that it is expensive.
Take the Open University as an example. At the start it had regional offices, part time tutors and summer schools. These were easy to cut because they were expensive.
Now it is under existential threat because students don't stay and they are implementing 25% redundancies.
The VC is saying that it will become "the university of the cloud"
Hi apad,
It's too easy to think that social activities can be done over the internet.
True. I think distance learning via Wey Education (LON:WEY) could work if there is a parent or guardian around to supervise, and manage the process. - making sure the child is up & doing the classes online.
WEY's teaching staff seem to work from home, and their website blurb says that they have contact with each individual pupil. I'd like to find some third party evidence that this approach actually works.
My other thought is that children are often so vile towards each other, that distance learning might actually be a better option, if the only affordable conventional option is some hideous local comprehensive in a bad area, which will turn your child into a chav.
Regards, Paul.
Re: ULS Technology (LON:ULS) . and housing slow down, in terms of transactions it is already happening hence estate agents share prices cratering over the last couple of years.
ULS have made reference to this, today saying:
"This growth was achieved against the backdrop of a housing market where overall transaction numbers continue to remain markedly below long-term averages."
And the same form of words in their full year results in June.
I think it is impressive that they can grow organically and with select acquisitions in a slow housing market, clearly offering something that makes sense to their customers even in more difficult markets.
That said, any material downturn in prices could test that resilience.
I was quite tempted by ULS Technology (LON:ULS) this morning but was but off by the conveyancing, I take it any slow down in the housing market will affect them? At the moment I not looking invest in construction or any related sectors until Brexit is sorted out.
A potential slow down in the housing market puts me off ULS Technology (LON:ULS) too. Shame because, as Paul mentioned, it has a good chart (meets Minervini's trend template).
Graham had a look at Wey Education (LON:WEY) at the end of August:
https://www.stockopedia.com/content/small-cap-value-report-31-aug-2017-rtn-trak-pres-esl-wey-chh-213888/
How did you get on with ChipsAway?
Hi nbeeny,
How did you get on with ChipsAway?
The chap from ChipsAway came over yesterday. Very affable & knowledgeable. However, due to the lack of parking space & outside power at my flat, he wasn't able to do the repair. He said it's a common problem with people who live in flats. He did recommend another ChipsAway franchise, who apparently has his own unit, but that was too far away for me unfortunately.
I used ChipsAway about 10 years ago, and they did a repair to another vehicle I had at the time, and I found them very good.
Regards, Paul.
Wey Education (LON:WEY) - three readers have asked me to look at this one, so your wish is my command! That's next on my agenda.
Regards, Paul.
Surely, something is more sophisticated is going on behind the scenes.
Also, the company remind me of the financial investment firm Nugget, a theme of successful fundraising and lack of profits.
Earthport (LON:EPO) also seems to have similarities with £ESV, which also has years of losses, £95 million market cap - but where its main potential value is a 35% stake in HomeSend, which does cross-border payments. Eserv Global has just done a £20 million institutional fund raise too. Here there is some comfort that Mastercard is the largest shareholder in HomeSend, but the financials don't inspire me.
My take on this is that institutional investors are very close to EPO's customers, and understand that the current global payment system is ripe for change (expensive, slow, inefficient) and the potential market is extremely large. This is where the investment case rests - now that the tech is built and driving revenue growth, operational gearing will kick in and network effects will put an effective moat around EPO's business. It has been on crazy high valuations in the past, granted, but at around 18p today, with plenty of cash, fair value is quite a bit higher IMO, especially given its out-of-favour status is deterring investors who might otherwise buy. I think EPO is a classic "the story's changed" situation, and the market is slow to realise this.
I do think WEY should be on Paul's radar given its potential to be an internet disrupter over the next few years. Today's outlook seems to suggest 60% annual growth is foreseen going forward. The profits should come tumbling in on that basis as the level of investment required is not that high now that the infrastructure (IT especially) is in place. Marketing costs should start ramping up but that's the secret to the likes of BOO, G4M, AMZN and so on.
Wey Education (LON:WEY) seconded! I hold.
Plus500 (LON:PLUS) continues to rocket. To think that the board were happy to accept £4 per share as a buyout by Playtech. It pays decent divi's and continues to out perform yet I still think 'red flag red flag' every time I see it mentioned
On Earthport (LON:EPO), I see you are using a sharecount of 920 million - this is the figure given on Stocko. But company reported, following the placement, reported 613 million shares out and N+1 Singer in today's research report use the same figure to give a MCap of £119million and an EV of 95 million.
Hi Wimbledonsprinter,
Thanks for pointing out the anomaly on issued shares at Earthport (LON:EPO) .
I've looked into it, and the difference of 307m shares which you flag up ties in with the 307.4m deferred shares in issue, shown in note 18 of EPO's 2017 Annual Report.
Deferred shares are worthless of course - it's just a backdoor mechanism to do a share consolidation.
I will raise a support ticket on Stockopedia for them to get this data corrected by Thomson Reuters. Many thanks for flagging this (what I believe to be) a data error.
Regards, Paul.
P.S. I note that the market cap field on Stockopedia is actually correct. So that field does ignore the deferred shares. What I do with the SCVRs is to manually recalculate the market cap, to take into account price movements (which tend to happen when results & trading updates are out, which is what the SCVRs are based on). So in this case, I've picked up a technically correct, but in the real world incorrect figure of 920.6m shares.
I've already raised a support ticket for this, and hopefully Thomson Reuters will change the no. shares in issue figure to disregard the worthless deferred shares.
Wey Education (LON:WEY) looks interesting today. Maiden profit, though there's an unexplained positive exceptional item that should be worth a footnote.
My morning smallcap tweet:
ULS Technology (LON:ULS), Earthport (LON:EPO), Getech (LON:GTC)
ULS Technology (ULS) H1 trading revenue and profit before tax ahead of the Board's expectations. Rev up 56%, U/L pretax up 42%.
Earthport (EPO) FY Pretax -£12.6m (-£7.2m) "mainly due to unrealised fair value loss of £4.8m, compared to a gain of £8.2 million in FY2016." "Current trading, including core operational metrics in the first quarter of FY 2018, are broadly in-line with management's expectations and ahead of the same period in FY 2017." I'm short.
GETECH Group (GTC) 12 month interim (FY end moved to Dec 31). Rev £7.7m (£7m). Pretax -£154k (+£671k). EPS 0.41p (3.25p). Net cash £1m but £1m recieved after period end. Outlook "a continuation of 2017's buoyant market for data, and we have a strong pipeline of pre-funded work."