Small Cap Value Report (Tue 4 Aug 2020) - AA., R4E, BKS, BRCK, NWF

Good morning! It's Paul here with the SCVR for Tuesday.
Please see the header above for companies reporting today that I will be reviewing.
As usual, it's initially a blank article, which I put up about 7am, so that readers can add any comments you have about the 7am RNS releases. I then write up the main report throughout the morning, section by section. Assuming I can manage to avoid accidentally deleting any of them!
Estimated timings - I have to write today's report early today, due to needing to travel back to Bournemouth this afternoon, from London. It will be interesting to see how the city centre looks these days. It was like a ghost town last time I walked through the City, towards Waterloo. It's difficult to predict what is likely to happen to all those fancy offices, if companies decide to have staff permanently based from home. Or will companies & staff gradually return, once treatment/vaccines have resolved covid-19 (whenever that might be)? My feeling is that humans don't have terribly long memories, and it often surprises how quickly things do return to normal. after e.g. natural disasters, terrorist attacks, wars, etc..
Today's report is now finished.
AA.
Share price: 25p (pre-market open)
No. shares: 620.8m
Market cap: £155.2m
Possible Offer & Update on Refinancing Progress
Possible Offer for AA
The Board of Directors of AA plc (the "Company" or the "Group") notes the recent press speculation regarding a potential refinancing of the Group's indebtedness and the possibility of an offer being made for the Company in connection with such a refinancing.
The Company confirms that it is currently in discussions with a number of parties in relation to a wide range of potential refinancing options.
This is particularly interesting, because the AA's balance sheet was wrecked by financial engineers, who came up with the ridiculous idea to load it up with massive debt that would never be repaid. It was therefore only a matter of time before the company ran into a financial crisis. The scale of the problem is mind-boggling, given it's only now a £155m market cap company;
As stated in its preliminary results announcement on 7 May 2020, while the Group continues to remain well within its financial covenants, at the end of the last financial year the Group had approximately £2.65 billion of total net debt, of which £913 million is scheduled to fall due for repayment within the next two years.
Debt reduction is therefore a key priority and the Group continues to proactively manage its capital structure and to seek to reduce its indebtedness well ahead of the upcoming maturity dates on its outstanding indebtedness.
Today's announcement goes on to say that 3 (named) private equity organisations are sniffing around, saying;
The Potential Offerors have each indicated that any possible offer would involve a significant amount of new equity capital being injected into the Group, in order to reduce indebtedness following completion.
That makes complete sense, but it does raise the question as to why an offer would be generous to existing shareholders? The financial incentive would be for an acquirer to make a lowball offer for the equity, on the basis that the company could otherwise become insolvent if it were not able to refinance its huge debt pile.
Management is also considering an equity raise separately. Note the use of the word "stakeholders" below, which is often code for existing equity being worth little to nothing;
Separately and in parallel with the discussions relating to a potential offer for the Company, the Board intends to continue assessing a range of other potential refinancing options including the possibility of raising new equity. In considering the different potential refinancing options available, the Board wishes to ensure that the Group has a stable, long-term capital structure and that the proposed refinancing enhances the long-term viability of the business and is in the best interests of the Company and its wider stakeholders.
My opinion - I think this could go either way. There's so much private equity money sloshing about, that maybe someone might be prepared to pay top whack? Or, there's a possibility that a bid could be below the current share price, maybe a lot below, and debt holders could be asked to take a haircut in return for the injection of fresh equity? At this stage we don't know, but I'm wary that this might not necessarily be a good deal for existing shareholders. In massively over-indebted company refinancings, the existing equity can be all-but wiped out. Hence I'm not tempted to buy on the opening bell, as it's too risky without knowing what the approach of the potential bidders is going to be.
.
Reach4entertainment Enterprises (LON:R4E)
0.13p (down 48% today) - mkt cap £1.65m
Delisting
The company says 2019 was strong, but it's seen a severe impact from covid. It does marketing for West End shows, etc, so it's understandable that business must have dried up. Not the company's fault, it's just unlucky to be operating in the wrong space.
After careful consideration, it is the Board's belief that in a time where prospects for the future are uncertain and where cash management is paramount, the costs of maintaining a London listing outweigh the benefits afforded by operating as a public company...
Even for the smallest companies, an AIM listing can cost £100k+ p.a., so what's the point, if there's little market liquidity, and no appetite to provide more funding? I've heard from other sources too, that there's so much money sloshing around, that private investment (e.g. from family offices) is more readily available than from AIM investors. Hardly surprising really, considering that we've had so much junk floated on AIM over the years, that investors are more wary these days.
I do think it's a good idea to review our portfolios for rubbish that's likely to de-list. Even if it's only worth a couple of hundred quid, I'd rather salvage something, than throw it away. After all, if there was £200 cash lying on the floor, you wouldn't disregard it as immaterial to your portfolio! So why do the same with failed investments?
By the time a market cap goes below about £5m, companies are at high risk of de-listing. Then you have usually an instant 50% loss on the de-listing news, and a scramble to sell at any price. Although occasionally, something interesting can happen, so it's not always clear-cut. Sometimes a more interesting speculative business gets reversed into an existing AIM listing.
.
Beeks Financial Cloud (LON:BKS)
Share price: 96.5p (down 2% today, at 08:55)
No. shares: 51.2m
Market cap: £49.4m
Beeks Financial Cloud Group Plc (AIM: BKS), a cloud computing and connectivity provider for financial markets, is pleased to provide an update on trading for the year ended 30 June 2020.
The Group has continued to make good progress against its strategic objectives and expects to announce trading results within the range of market expectations.
What a pity the company & its advisers didn't include a footnote, to disclose what market expectations are. I can't find any broker research, and the trouble with consensus figures is that we don't know if they're still current forecasts, or have been withdrawn?
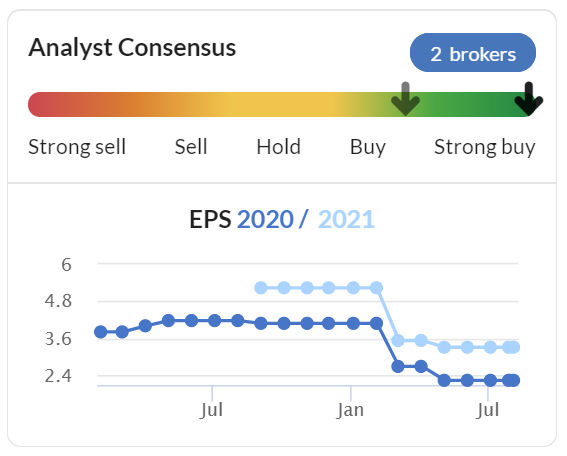
The Stockopedia broker consensus graph is usually a good guide - if forecasts dropped sharply in Feb-Apr 2020, then that's a good indication covid impact was being baked into the figures, so they're probably OK to rely on. Here we have;
.
.
I therefore surmise that the 2.22p forecast EPS for FY 06/2020 must be relevant. That's a PER of 43.5.
Note how much forecasts were reduced this spring - from 4.08p to 2.22p, a reduction of 46% in forecast earnings for FY 06/2020. That's a big reduction in earnings, and makes me feel less positive about the company than before.
Today's update strikes a positive tone, and says covid had little impact, pipeline strong, etc. But that's not reflected in the big reduction in forecasts.
My opinion - I hadn't realised that forecasts had come down so much. If the company had been on track to achieve 4-5p EPS, then the current share price would look justifiable. However, given the much lower forecasts, I think the valuation is looking a bit toppy. It's still an interesting niche company though, so I'll keep it on my watch list.
.
Brickability (LON:BRCK)
Share price: 96.5p (up 3% today, at 09:26)
No. shares: 230.5m
Market cap: £222.4m
Brickability Group plc ("Brickability" or "the Company" or "the Group"), the leading construction materials distributor, is pleased to provide the following update on trading for the three months ended 30 June 2020.
I can't remember much about this company, and have only covered it here once before, so to refresh our memories, here are my notes from Nov 2019.
The update today reflects the brief shutdown of the building sector in April & May. It's a hopefully one-off impact, as being outdoors, the building sector is probably one of the lower risk areas of facing a renewed lockdown if we get a second wave of covid. It sounds like the impact wasn't too bad, helped by the furlough scheme;
Revenues for the 3 months ended 30th June 2020 were £23.8m and encouragingly, June revenues returned to 83% of June 2019 and this trend has continued throughout July. While April's reduced trading levels resulted in a loss in that month the Group returned to profit in May and produced a pleasing EBITDA* of £1.6m in June.
Note that BRCK seems to drop-ship a lot of product, so there shouldn't be a problem with inventories.
Liquidity - sounds fine;
The Group's liquidity continues to be strong with a net debt of £1m as at 30th June 2020. Cash balance as at 30th June 2020 was £24m with £25m revolving credit facility drawn. In addition, the Group has an unutilised overdraft of £5m and an accordion of a further £5m available.
Outlook - nothing to worry about here;
While it is still too early to predict the level and sustainability of market recovery the Group remains confident in the underlying demand for UK housing. Recent government initiatives along with the SDLT "holiday" have further reinforced that confidence.
The Group can also confirm that its acquisition strategy remains on track and that it is currently evaluating a number of value-creating opportunities.
A time of crisis can be a good time to pounce on financially distressed competitors.
My opinion - the consensus forecasts look like they might pre-date covid, so I'm not going to rely on them. I cannot find any recent broker notes, so am in the dark when it comes to forecasts. Without that information, I can't take this any further unfortunately.
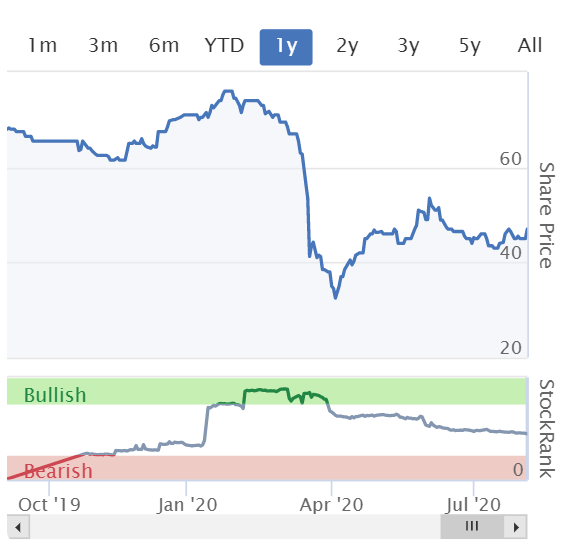
The share price chart below looks very similar in shape to the housebuilders, so it looks like BRCK shares are just tracking the sector. There could be upside here, as I think housebuilding (and hence their suppliers) could see a sustained recovery. There's plenty of demand for new houses.
.
.
Nwf (LON:NWF)
Share price: 213p (up 4% today, at 10:07)
No. shares: 48.75m
Market cap: £103.8m
There was a strong update which I reported on here on 29 April 2020. Although the uncertain outlook comments worried me at the time.
Moving forwards to today;
NWF Group plc ('NWF' or 'the Group'), the specialist distributor of fuel, food and feed across the UK, today announces its audited final results for the year ended 31 May 2020.
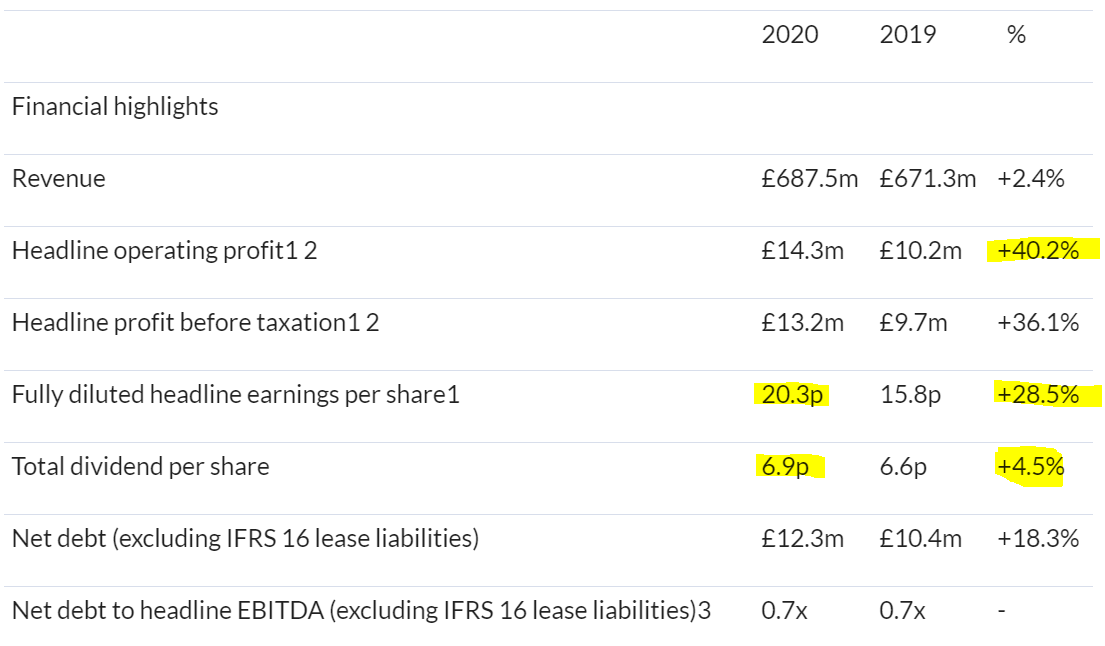
The headlines look excellent;
.
Not many companies are increasing divis this year, so a good positive move there.
20.3p EPS looks like a beat against forecast of 18.6p shown on the StockReport.
Based on a share price of 213p, and 20.3p EPS, the PER is 10.5. Historically that would have looked about the right price for this type of low margin business, but in this new era of apparently permanently low interest rates, maybe PERs should be higher?
The fuels division makes most of the group profit, and there is a one-off benefit here. Therefore, I think caution is needed re chasing up the share price;
A dramatic fall in the oil price and an increase in demand for heating oil from domestic customers during lockdown delivered substantial one-off gains.
Outlook - this looks fine, the key part says;
Performance to date in the current financial year has been in line with the Board's expectations. Overall, the Board continues to remain confident about the Group's future prospects.
Balance sheet - looks adequate. NAV: £51.1m, less intangibles of £31.4 = NTAV £19.7m
Note the pension deficit has risen to £21.0m.
My opinion - it's performed well, and seems resilient re covid.
Overall, the valuation looks about right to me.
.
I have to leave it there for today. See you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

38 comments
Oversight by me to ignore the Cleveland Square 10%. This is a private vehicle of billionaire Gary Klesch https://en.wikipedia.org/wiki/A._Gary_Klesch (my rush to print made me forget about this guy...I did know)
Another interesting holder. So updating para in original to...
"Me, Albert Bridge Capital, Davidson Kempner, Cleveland Square and Parvus own 46% of the equity (0%, 16%, 15%, 10% and 5% respectively - obviously I've rounded my sizeable stake to the nearest whole number). Now we are some hard hitting mofos at the negotiation table."
This combo is interesting .
Approx average acquisition prices (done by v crude some eyeball averaging):
Albert Bridge 45p
Davidson Kempner 25p
Cleveland Square 100p
Parvus 220p
To some extent Parvus are so far out of the money and their stake at 5% is way reduced from 25% that perhaps they are just passengers.
The rest are pretty actively engaged on what the price can be. A lot depends on whether this cohort wants to seek informal price alliance....and it adds to the potential for public equity value creating recap rather than take private.
My wife and I went to our local cafe today. I am keen to support it anyway. It was rather busy albeit within the covid rules for a Tuesday; I ordered two breakfasts and two coffees to have in. That's £6 please in total. What? Of course.... its a Tuesday in August. So the Government is picking up half of the tab. I noticed that more of the usual staff were back working too. Thumbs up from the owner.
So maybe this innovative little scheme will help small businesses like this keep afloat. I hope to see this idea both extended in time and to other types of smaller retail too. Good one Rishi Sunak.
barnetpeter
So maybe this innovative little scheme will help small businesses like this keep afloat. I hope to see this idea both extended in time and to other types of smaller retail too. Good one Rishi Sunak.
Yes i think this is a very very good idea (social distancing sensibilities ignored) - money targetted exactly where it is needed at present with the scheme giving a fighting chance that marginal staff may be able to keep their jobs (ditto for the buisness staying afloat) . Unfortunately for me i had my mega mixed grill lined up for tonight at my local Trukish restaurant only to find out that they are not participating in the scheme so i will have to make do with sometjing not so drool worthy elsewhere - bizarre that some are choosing to turn down this free cash ogger- i guess fair play to this business if they feel they don't need to take the freebie on offer for whatever reason.
Hi out of interest did you have to use apps and go on websites ?
I went out last night to a local eatery it was rammed but mass confusion on scanning codes on tables then downloading apps which only worked on i-phones, going on web sites to apply goverment discount.
The waiters/ress were generally all hunched over the tables sorting out the IT problems to get the orders through which defeated the idea of it all helping with social distancing. So much easier to just have someone stand a metre away note down the order then pay contactless.
Ate out at the pub yesterday and no IT involved, just got half the usual bill. My main concern with the scheme is whether it's just moved the rush - will there be tumbleweed blowing through on Thursday? We're using it as an excuse to try lots of local eateries to see whether we'd be interested in using them at full price in the future. For the owners I see it as a no-brainer to sign up.
I did my MSc dissertation on the AA. The way it has been treated does not reflect well on free-market capitalism.
AA was founded in 1905. It was demutualised in 1999, at which point it had zero long-term debt. In 2004 Centrica sold the business to private equity firms CVC and Permira. By the time it listed in 2014, after 15 years of private ownership, AA’s debt pile was £3.3bn.
During CVC & Permira’s ownership, they attached subordinated preference certificates to the company, generating compound interest of 16% pa. The table below also shows a £2.57bn dividend paid to the holding company, Acromas, immediately prior to IPO, funded by new debt.
Permira claim to have made a 4.6x return on investment, with the AA and Saga. Good for them.
By my estimates, Permira & CVC extracted around £4.3bn from the business across 10 years. I consider it little more than corporate thievery. It is fairly disgusting and should be outlawed, in my opinion.
They paid a purchase price of £1.75bn to Centrica in 2004, managed to recoup £1.39bn at IPO in 2014, and now the true devastation is apparent, with AA having a market cap of only £150m.
I sincerely hope some sort of deal is reached, so the debt may be paid off and one of the UK’s best known brands may continue as a viable business for decades longer.
If the AA goes bust and 7,500 jobs are lost, I’m sure the usual generalisms will be trotted out, about poor management, failure to adapt, too much debt. Yes, too much debt, but I doubt Permira and CVC will face any ramifications.
"Corporate thievery" - indeed! A good example of why the tax treatment of interest needs re-thinking.
I agree with you, and it's worth looking out for these companies to avoid at all costs. Any time there's an IPO from private equity with huge debts, it's probably because they've extracted everything they could from it.
I agree with what you say Chris Brown. I looked into all this too ahead of taking a position.
IMO blame attaches to more than private equity though...ie the rest of us idiots that thought this structure was okay. Some debt on balance sheet is fine for AA....a decent amount but half of what they did saddle if with.
Jobs will go at AA as old practices and systems have been updated since IPO and particularly under the current CEO (who hopefully has repointed some prior duff investment).
IMO the old CFO was part of the problem too and created a byzantine reporting and financial management approach that obfuscated (he came from the PE firm).
But even if the company goes into default on bonds the brand and most of the people will carry on
Chris,
Re: LON:AA
The real "villans" of this sorry saga (no pun intended) are:
These "professional" managers of other people's savings are the muppets who grossly overpaid the private equity groups for this - only weeks after the IPO of SAGA where the share price sat well below the 185p offer price and it's now 15p!
See: Speed to Exit
"Buy the fund managers not the funds"
Bonitabeach
Im not disagreeing but the enterprise value includes the debt. If it goes bust it will survive. The equity will be wiped and the business will emerge. It wont go away.
Very good post - while decent companies like this can be milked like this the system is clearly rotten. Such short term financial sleight of hand works firmly against the interests of the AA, it’s employees and the national interest while only benefiting those making the money. The AA provides an essential service that could have/still might be killed off by such unrestrained greed
"By the time it listed in 2014, after 15 years of private ownership, AA’s debt pile was £3.3bn".
Looking at the AA's website - it boasts 2900 mobile mechanics.
So, it's managed to borrow over £1m for each mechanic. Wow!
This post definitely exceeded expectations. Nice work!
I did my MSc dissertation on the Aa (LON:AA.) The way it has been treated does not reflect well on free-market capitalism.
The AA was founded in 1905. It was demutualised in 1999, at which point it had zero long-term debt. In 2004 Centrica sold the business to private equity firms CVC and Permira. By the time it listed in 2014, after 15 years of private ownership, AA’s debt pile was £3.3bn.
During CVC & Permira’s ownership, they attached subordinated preference certificates to the company, generating compound interest of 16% pa. The table below also shows a £2.57bn dividend paid to the holding company, Acromas, immediately prior to IPO.
Permira claim to have made a 4.6x return on investment, with the AA and Saga. Good for them. I consider it little more than corporate thievery. It is fairly disgusting and should be outlawed, in my opinion.
By my estimates, Permira & CVC extracted around £4.3bn from the business across 10 years.
They paid a purchase price of £1.75bn to Centrica in 2004, managed to recoup £1.39bn at IPO in 2014, and now the true devastation is apparent, with AA having a market cap of only £150m. Those who helped the IPO get away are also complicit, to an extent.
I sincerely hope some sort of deal is reached, so the debt may be paid off and one of the UK’s best known brands may continue as a viable business for decades to come.
If the AA goes bust and 7,500 jobs are lost, I’m sure the usual generalisms will be trotted out, about poor management, failure to adapt, too much debt. Yes, too much debt, but I doubt Permira and CVC will face any ramifications.
Thank you for providing all that detail Chris. And yes, that seems to be the usual private equity formula. Nothing to do with improving the operational performance of the business. Just load it up with debt, take out lots of money, make an obscene level of profit and then float it again to unwitting investors. If it goes bust, so what. Definitely the worst face of capitalism. And a good reason for avoiding any IPOs coming out of private equity.
Operationally AA is a very good business. I have been rescued several time by the AA van. The staff are always, knowledgeable, capable and friendly. Let's hope someone can rescue this good business from what has been left by the vultures
Apologies for the duplicate post - the original seemed to vanish on the first attempt.
I agree with the comments - those involved with the IPO and indeed the bond financings are also complicit. The underlying business itself is fantastic as you say Julianh - very high margins and ROCE, a defensive revenue stream, lots of operating cash flow.
I did hold if for a brief period and would like to take the optimistic view: that if debt was repaid, then it would be valued on a high multiple and be able to pay a substantial dividend stream.
AA (LON:AA.)
Chris.Brown
I did my MSc dissertation on the Aa (LON:AA.) The way it has been treated does not reflect well on free-market capitalism.
excellent post Chris great example of ultimate capitalism at work !!
I think in defence of free market capitalism the AA. debt situation has not exactly been hidden - there has been enough time since floating where the shareprice didn't collapse that there was plenty of willing takers for the shares and it was not obviously a bad un (still isnt really looking at core business) - the fact that those bods may have lost part of the shirt 5 years later to me is the age old adage buyer beware. I would though guess unfortunately that many pension funds may be big holders of this share which is a shame. You pays you money and you take your chance though.
The stupidity here lies with the numpty millionaire directors who decided it was prudent to pay chomping dividends while the debt was going nowhere - presumably thinking that profits would never reduce we would never have a financial crisis or any other similar incident that would mean the profits would take a hit - orperhaps they ha d acunning plan all along.
If the AA goes bust and 7,500 jobs are lost, I’m sure the usual generalisms will be trotted out, about poor management, failure to adapt, too much debt. Yes, too much debt, but I doubt Permira and CVC will face any ramifications.
Thankfully its very unlikely to be the case - the underlying business has sound profits that have excellent value as a going concern (way more than market cap which is presumably a good point being made by mojomogoz above) so other than a natural decision to close parts of the business which could happen anytime anyway i see aalmost nil chance that the core profit earning machine would be shut down anytime soon (thankfully).
Not a small cap, and certainly not in Paul's remit, but I thought the interim results from Rotork (LON:ROR) were better than expected, considering that about 50% of its business is to the oil and gas sector. "Adjusted operating profit" down 9% yoy, and "real" eps down 5%, are surely good in the circumstances. This had been on my "should I be selling this list", on the grounds of lacklustre performance over the past three years, but it is looking much more positive now. Reminder to myself of the factors that indicate a good business - ROCE, cash generation, market position.
AA (LON:AA.)
That makes complete sense, but it does raise the question as to why an offer would be generous to existing shareholders? The financial incentive would be for an acquirer to make a lowball offer for the equity, on the basis that the company could otherwise become insolvent if it were not able to refinance its huge debt pile.
I think the AA. has now reached the point where what would have been perceived as a low ball up to only very recently is probably now at a premium to the current price. So there is potential for current shareholders to be happy (*caveat) and also for the private equity to pick up a cheap deal.
The shareprice here has halved from 200p to 100p - then halved from 100p to 50p and then halved again pretty much to the 27p - that seems probably enough lowballing to make a 35p offer perhaps be enough?
* - the big caveat here is that long term holders who were happy to hold to tough it out will probably be incensed that the directors won't play the long game that they presumably kinda promised they would play by paying down debt and that would restore price to higher levels. That's the problem with directors they often pay lip service to long term buy and hold shareholders who have supported the company through thick and thin.
the defence the directors use forchanging tack is a complete joke
However, whilst the Group is now beginning to reap the benefits of its strategy and operational improvement, the business remains constrained by a significant debt burden and the Board believes this may prove to be an impediment to the Group's future progress and longer-term success.
errrrrr - the company is judged mostly by the value of its shareprice and that has declined by 2/3 in the last 12 months so not sure exactly what benefits they are reaping other than a potential whopping bonus or them from the private equity if the can offload the company on the "cheap"
Hopefully all holders know the risk they take by holding here the debt makes this a crapshoot - hopefully with options on the table current shareholders could get perhaps a pleasant surprise compared to current lowly price - but any positive ref bids is probably matched by the dreaded we need to refinance soon comments aligned with historically low shareprice.
I took a full position in Aa (LON:AA.) at 50p before the pricing on its debt started undermining it....I then topped up at 15p mid Covid. Its not been my finest investment to date.
AA was always a bit unusual for me as I wouldn't normally take a full position in something with clear and present catastrophe risk....but I believed I could see a manageable debt deleveraging story to >10x over 7 years. That vision has been struggling to raise its head since yields in general backed up last year and then Covid crapped from a height to.
Its a super reflexive situation. Price deteriorates and everything looks multiples worse. Price improves and its looks multiples better.
With a £1bn debt for equity swap the AA suddenly would potentially look like a high quality low to moderate growth company. In fact, it wouldn't be embarrassing to stack it up against Diageo (LON:DGE) -> it would look a bit over levered relative to Diageo but not ridiculously so and with similar margins, potential for greater growth/return from investment, more dominance of its area and less volatility in returns. (Clearly £1.3bn is a better number than £1bn but trade offs etc...and reaching for the sky)
Price that £1bn+ at 25p and its a tsunami of dilution (4bn shares added to current c.650m). £120m annual profit (estimate based on reducing interest payments and other debt maintenance 'exceptionals' that spring from the whole business securitisation structure) and you get c.2.6p per share earnings. 25p is 9.6x....probably deserves a teen multiple at least and if it got to 20x (discount for size and bit more leverage to Diageo) then 52p per share. Nice 100% return for new equity and old ...with a really good forward return story from moderate top line growth and significant 5+ years gradual deleveraging.
How about they raise the £1bn at 125p....bear with me...I know that sounds outrageous!...
Well dilution is not nearly so bad. 800m new shares and total shares in issuance now 1.45bn. Take the same £120m annual profit and we get 8.3p eps. Put 20x on we get 166p per share. Old shareholders like me party as we get 564% return!....New shareholders ain't so exuberant as they only get 33%
Ummm. Okay...lets do 75p -> 2bn shares total. 6p eps -> 120p per share -> 380% return to me and 60% to new guys.
Aaaannnddd....50p -> 2.65nb shares. 4.5p eps -> 90p per share -> 260% for me, 80% for the new guys.
Me, Albert Bridge Capital, Davidson Kempner and Parvus own 36% of the equity (0%, 16%, 15% and 5% respectively - obviously I've rounded my sizeable stake to the nearest whole number). Now we are some hard hitting mofos at the negotiation table.
(Seriously, DK are players...hardcore mofos....and Albert Bridge and Parvus no pushovers either...and then there's a bunch of other institutions that will happily ride the coattails of these guys)
Want to do something other than wait for slow death through debt strangulation then you going to have to throw us a bone. I don't know about the other guys...they haven't called me yet :) ....but I ain't barking at 25p. But where do I start to roll over and let them tickle my tummy?...
I think its north of 50p. How far depends on how much the blocking quartet are willing to stump up as part of any D4E swap. Collectively we are talking something >$60bn in AUM so pockets are deep enough to play a decent wedge of £1bn in.
I'd guess enough to play the price to at least 75p on the raise? Its all rather complex and super super reflexive.
In addition, the above simplified thoughts underplay the value created in a number of dimensions;
1) Investment grade issued debt pricing goes back to the floor and most/all of high costing high yield debt is repaid then the earnings pick up is larger than assumed above
2) AA has gone through a rather earnings deleterious investment program in last few years and capex/opex associated with it reduces
3) There's a high ongoing 'exceptionals' charge that comes from continual refinancing of the debt pile. That's no longer necessary
4) FCF should be a bit better than earnings going forward as level of investment moderates and amortisation > ongoing investment
All in all a reasonable modeller might think £120m profit is too low and that >£150m is not unreasonable. That starts to make 100p possible (80% upside for new equity)
Anyway. There's so much that can happen here....but as the game is now in play in earnest stuff could move really quick. There's scope for people to make loads of money through some compromise rather than pushing to an explosion...so that gives decent chance of compromise.
Maybe the stock goes private....but my guess is that the 40p rumoured current bid is too low and that the minimum is at least 60p and probably most of the way to 100p given who PE need to wrestle control from.
The biggest downside risk to me would be if DK wanted to take it private...then they could squeeze a lowish number for takeout...say the 40p gets Albert Bridge to bail with a profit and then everyone else is running scarred. But why would DK do that when they can make a lot of sure money quick?
DYOR....hairy and risky
mojo out
Mojo - good/interesting analysis. I have no position but the special situation intrigues me a little. What is to stop ABC, DK & Parvus doing the whole fundraise at 25p though. They wouldn't worry too much about their existing equity as the new money would more than make up the shortfall. Is that not a feasible scenario?
My own view on AA (LON:AA.) is that the core business - breakdown recovery - has been treated as a cash cow to spend on entry into other, highly competitive businesses. Has not gone well, and I think it would take drastic action for them to survive at all. Not investible. Don't think it is an indictment of private equity as such - some of them have been very successful as corporate stewards - I see it as management with their heads in the clouds.
I'm long here and do not believe the board will sell out the shareholders. This a a good traditional business with low PE.
It helps if you mention the name of the company you're talking about!
Paul, Where is a good site to visit to read all of these as I assume you cherry pick ones of interest. Thanks in advance
Try this link
https://www.investegate.co.uk/...
Thank-you Jeff and David, very much appreciated. I had been using this site of late which seems to collate quite a bit of information on companies each day 'www.stockmarketwire.com' . I cant say if its good or bad but the daily email giving the stock broker movements has been really helpful!! I have submitted that as an innovation request to Stockopedia for the company pages so people know when the broker updates are made so they have some context in what is a turbulent market right now :-)
Thanks, Lee. That's a really useful link.
investegate.co.uk was the one Paul recommended to me some years ago.
Does anyone know of any equivalent information service / platform for the USA market?
The best solution I have found for my US holdings is to set up a portfolio on seekingalpha.com and then the earnings announcements and call transcripts and presentations get forwarded to my email. There can be a fair number of emails generated so it’s worth setting up a dedicated folder and rules in your email account to control it.
Thank you John. I really appreciate your advice and will certainly explore using seekingalpha.com.
Hi Lee, Jeff and David.
Would you like me to include a investegate link to the direct announcement in my news clippings so there’s no need to manually find it?
I had thought about it, but
it might look messy with long URLs
kinda thought people would click on the stockopedia company link and view it there
didn’t want to push people away from this site :)
I ‘might’ try this tomorrow to see if it’s practical, but if there’s ideas about saving time and make the process of news reading easier, please let me know!
HollandSmith,
Thank-you for the offer, completely up to you, I don't want too add to what is already a plentiful amount of information you put up each day. If you are looking to remove the 'noise' of a link, I am not sure if the comment section allows you to wrap the hyperlink into a single word so it doesn't take over the page, but that may be a lot of effort to go through.
Hi Holland,
If you wanted to include the links to the RNS, you wouldn't have to make the text too untidy you could just include as a short form link
It would be pretty easy to semi-automate this by prepping the data in a spreadsheet - which I'm guessing you might be doing already, but happy to give any pointers if you are stuck. Feel free to drop me a PM if I can help.
My morning smallcap tweet:
AA (LON:AA.) Active Energy (LON:AEG) Applied Graphene Materials (LON:AGM) Brickability (LON:BRCK) Pelatro (LON:PTRO) Open Orphan (LON:ORPH) Malvern International (LON:MLVN) Physiomics (LON:PYC) Futura Medical (LON:FUM) £R4E Filtronic (LON:FTC) NWF (LON:NWF), Beeks Financial Cloud (LON:BKS)
AA (AA.) possible offers from three bidders. Offerors say they would inject a significant amount of new equity to cut the huge debt pile. I hold.
Active Energy Group (AEG) gets construction and air permit for US biomass pellet factory.
Applied Graphene Materials (AGM) distribution agreement with leading European chemical distributor Arpadis Benelux.
Brickability (BRCK) encouraged by June rev down only 17%. All sites open.
Pelatro (PTRO) £2.1m placing at 47p, a 12% discount. for sales & marketing plus working capital for Managed Services, which the Directors believe will enable the Company to tender for larger contracts.
Open Orphan (ORPH) contract with Carna Bioscience for a "First In Human Clinical pharmacology trial." Expected to deliver significant revenue over 12 months.
Malvern International (MLVN) serial disappointer will close its Singapore operations which been loss making for some time. There was no hope of profit any time soon due to covid. FY19 loss was SG$1.34m = £0.74m.
Physiomics (PYC) year has "has started well". Increased volume of introductory calls with potential new clients, "some of which the Board hopes will be converted into further projects." Hope of jam tomorrow.
Futura Medical (FUM) ompletion of initial laboratory and optimisation on a Dermasys cannabidiol gel shows highly efficient penetration of CBD into and through the skin, superior to an established product.
Reach4Entertainment (R4E) proposes to delist. "In a time where prospects for the future are uncertain and where cash management is paramount, the costs of maintaining a London listing outweigh the benefits."
Filtronic (FTC) FY(May). Outlook slightly reduced order book, "there remains considerable uncertainty within our end markets. This uncertainty is compounded by the imminent conclusion of the Brexit transitional period."
NWF (NWF) FY(May) EPS yp 29%, div up 4.5%. Recent trading in line.
In line: Beeks Financial Cloud (LON:BKS)
Good Morning,