Small Cap Value Report (Tue 4 Dec 2018) - TAP, QTX

Good morning! It's Paul here.
I'll start Tuesday's article with an interesting announcement from after-hours on Monday:
Taptica International (LON:TAP)
Taptica (AIM: TAP), a global leader in advertising technologies for performance-based mobile marketing and brand advertising...
This is an Israeli-based tech company. I avoid all of these, as it seems to me there can sometimes be something wrong with them, lurking under the surface.
Taptica's CEO seems to have been found guilty of lying;
Hagai Tal, CEO of the Company, has today been found liable for certain statements made in relation to the sale of Plimus Inc, a company of which he was both a shareholder and chief executive officer at its time of sale in August 2011. The plaintiffs in the case are entitled to restitution for breaches of certain representations and warranties.
From what I can make out, this does not seem to have any financial impact on Taptica itself.
He has resigned as CEO of Taptica. His LinkedIn profile indicates that he was CEO of Taptica from Jan 2014 until yesterday. So the problem with Plimus pre-dates his involvement in Taptica by over 3 years.
As Monday's RNS states, the legal action against him was disclosed in Taptica's Admission Document. I wonder how many investors actually spotted it though? It just shows, those Admission Documents really are important, and need to be scrutinised closely, as that's often the only time that important negative information will be disclosed. Especially in the notes near the back of the Admission Document, as many people will have given up reading it by that late stage!
Details of the claim were disclosed in the Company's admission document on page 85 (section 7.9 of Part IV), which is available on the Company's website.
Let's have a look then! This is what section 7.9 says;
7.9 In September 2012, Great Hill Equity Partners IV LP, Great Hill Investors LLC, Fremont Holdco, Inc and Bluesnap Inc (formerly Plimus Inc), (collectively “Great Hill”), filed a complaint in the Court of Chancery of the State of Delaware against SIG Growth Equity Fund I LLP, SIG Growth Equity
Management LLC, Hagai Tal and others (collectively the “Defendants”) arising out of the acquisition by Great Hill in August 2011 of Plimus Inc (“Plimus”), a provider of mobile and internet payment solutions. Great Hill filed a further amended complaint in April 2014.
The Defendants include the principal selling shareholders of Plimus and certain members of its management team at the time of the sale to Great Hill. Hagai Tal was both a selling shareholder (owning approximately 8% of the company) and the chief executive officer of Plimus at the relevant time.
In its complaint (as amended) Great Hill alleges that the Defendants deliberately and fraudulently concealed material facts regarding Plimus's relationships with its payment processors and its compliance with various credit card regulations and seek judgment either that the transaction be rescinded and the US$115 million consideration be returned to Great Hill together with interest, or that damages and costs be assessed and awarded by the court.
The Defendants deny any liability and intend to vigorously defend themselves against the claim. However, there can be no guarantee that, should the claim proceed to trial, their defence would be successful.
Any judgment against Mr Tal could have an adverse effect on the Company, its reputation and its relationships with its customers.
My opinion - clearly then, this is quite serious for the (now former) CEO. It may not have any direct financial impact on Taptica, but indirectly it reflects very badly. If the CEO has acted in this way, then how can we believe anything else he's since said?
Lots of investors (myself included) are suspicious of Israeli tech companies. This type of announcement just reinforces that we're right to be suspicious.
The company no doubt will be on damage control duties from now on. Indeed, it has put out a trading update to accompany the bombshell news of its CEO departure, as follows;
Since announcing its interim results in September 2018, the Company has continued to perform well and execute on its strategy to deliver higher-margin revenue. As a result, the Company expects to report EBITDA growth in line with market expectations, demonstrating a higher-than-expected EBITDA margin, and revenue below expectations due to the forgoing of some lower-margin sales. Cash generation within the business is also as expected.
There are 2 ways of looking at this. Some investors are likely to want out in the morning, so I expect the share price to drop sharply early on. I expect the PR & broker have probably been ringing round the major shareholders today, to try to reassure them that this is all historic, and no reflection on Taptica.
The other way to see it, is that this share is already incredibly cheap, and that any drop on this news could be a buying opportunity, if you believe that there's nothing wrong with Taptica.
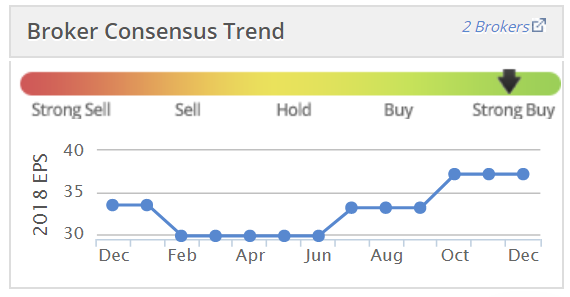
Recent trading updates have been good, and the broker forecasts have been rising too;
Personally, I'll just be watching from a safe distance - I don't want to get involved in this.
Quartix Holdings (LON:QTX)
Share price: 260p (up 8.3% today)
No. shares: 47.8m
Market cap: £124.3m
Quartix Holdings plc, one of Europe's leading suppliers of subscription-based vehicle tracking systems, software and services, is pleased to provide an update on trading for the 10-month period to 31 October 2018.
It starts off sounding rather exciting;
The Board believes that profit (adjusted EBITDA) is likely to exceed market expectations* for the year to 31 December 2018 by between 10 and 15 per cent...
It should be pointed out that adjusted EBITDA is not the same thing as profit! I'm perplexed as to why Quartix refers to adjusted EBITDA? It's often used by technology companies which capitalise a lot of development spend, to present an artificially high impression of profitability. Yet in this case, Quartix doesn't seem to capitalise any development spending. Its figures are completely clean, so quoting EBITDA is an own-goal, in my view.
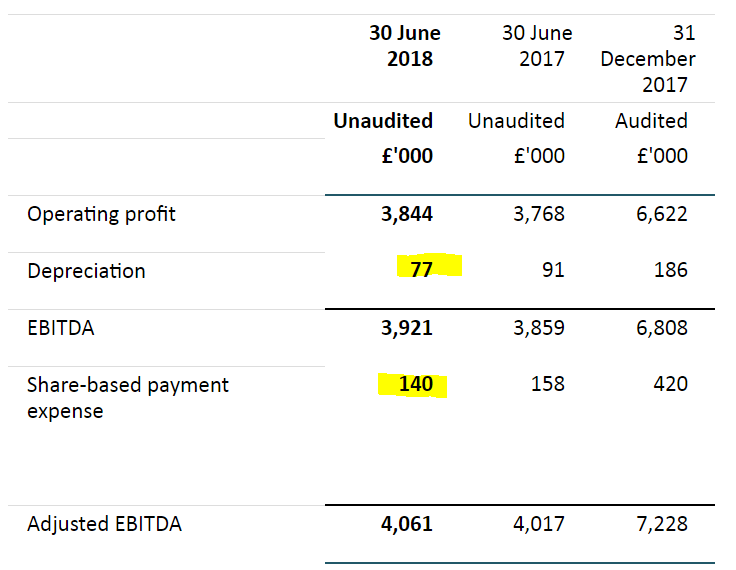
In the H1 2018 results, profit before tax was £3,858k. Whereas adjusted EBITDA was only slightly higher, at £4,061k. So why quote adjusted EBITDA at all? There's really no need. Here is the reconciliation from the H1 results, to show you what the adjustments are - there is no amortisation at all, it's just share-based payments being adjusted;
Going back to the trading update today, unfortunately the increased profit is largely as a result of accounting changes, so isn't very exciting after all;
This is largely as a result of the Group's adoption of IFRS15 (Revenue from Contracts with Customers), which has increased profit and revenue in 2018 as noted in the trading statement on 2 July 2018.
Looking back at the 2 July 2018 trading update, it did indeed mention IFRS15 as a positive factor, but didn't quantify it. Perhaps today's announcement shows a bigger benefit than people imagined? It strikes me as odd that analysts hadn't already factored this into their forecasts. Maybe nobody had worked out the numbers until now?
Anyway, it's better to have forecasts going up, than down.
Investors very much appreciate it when companies include a footnote, specifying what market expectations are. All companies should do this. Bravo to Quartix & its advisers, this is very helpful;
* The Board believes that consensus market expectations for 2018, prior to this announcement, were as follows: revenue: £24.6m; adjusted EBITDA £7.5m; free cash flow: £5.4m.
Other points;
- Estimates are still dependent on trading in Nov & Dec 2018 (fairly obviously)
- Revenue & free cashflow are expected to be slightly ahead of market expectations
- Strong progress in USA & France, and UK sounds like it's picking up
- Expectations for next year FY 12/2019 are unchanged
- Next trading update will be in mid-January 2019
My opinion - I view this company favourably, because it is highly profitable & cash generative, paying good divis, and with recurring revenues. The balance sheet has net cash.
The only problem is that it looks almost ex-growth on the existing forecasts. Some of that is due to investing in growth in USA. If that works, it could trigger a new wave of growth, and a positive share price re-rating.
I tried to buy some of these shares a while back, but found it hopelessly illiquid, and gave up. The recent share price weakness has brought the valuation down to a level which looks sensible (in the high teens, rather than the twenties, for PER).
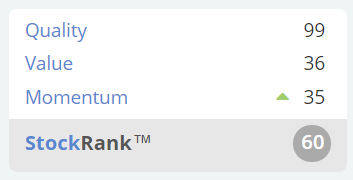
I think this share qualifies as a QARP (quality at reasonable price) - the approach favoured by popular & highly successful investor, Leon Boros. The Stockopedia quality scores are excellent. Note that the momentum score is pulling down the StockRank. However, we can probably anticipate that rising, once new broker forecasts are out;
That was all I had time for in the end. See you tomorrow.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

68 comments
Tomorrow might be a fun day.The US is down over 3% today / tonight.
Hold onto your (tin) hats, it could be a bumpy ride.
... and the FTSE 250 hit a new 12-month low at 18329. Russian roulette would be less fun than being in the equity markets these days.
It would be interesting to know Graham's thoughts on IG Group (LON:IGG) if he's lurking.
I thought the reaction today was overdone on my understanding of the update. To me it just looked like they confirmed what they'd already intimated.
Group revenues down 10% due to regulatory changes. Wasn't that what everyone expected?
Paul,
I've only just started reading the SCVR from yesterday, and noted the following which stood out for me:
"Unusually high profit margins, with no obvious reason as to why that should be (with hindsight this was the "tell" at Patisserie Holdings (LON:CAKE) )."
I've subscribed for the AJ Bell IPO, and on much of the views/analysis, there's a comparison with Hargreaves Lansdown (LON:HL.) which isn't surprising. What jumped out at me was the high margin of HL in comparison. I'm NOT suggesting anything untoward, but it's surprising how a recent 'shock' (Patisserie Holdings (LON:CAKE) holder) can focus ones mind on something that would have normally been ignored, or passed over.
"For this reason, I've decided to do some reading on the matter of uncovering dodgy accounts. I'm pretty good at it, but not good enough, as I didn't spot CAKE. Mind you, did anyone?"
If you read other BBs, there are many woodworms* NOW pointing out the dodgy accounts :o)
*Those who come out of the woodwork, ONCE the nice shiny varnish has gone ;^)
You mentioned re Plastics Capital (LON:PLA)
"Name change - reflecting the fact that "plastic" is regarded in an extremely negative way these days, the company is changing its name to "Synnovia". I rather like that, it rolls off the tongue nicely."
I'm sure SCVR reader(s) recently mentioned the increase/decrease in value of companies changing their name to something non-informative. (p.s. you should see a doctor if Synnovia is rolling off your tongue ! lol)
FINALLY (you'll be glad to read), I would also like to thank both you and Graham for the SCVR. I'm quite sure I'm moving to a more conservative investor (Graham), as opposed to your ... errr ... polite word for flamboyant, ;^) attitude ! (This is not meant to be critical of either of you). Holding Duke Royalty (LON:DUKE) and Volvere (LON:VLE) but not Sosandar (LON:SOS) (yet!) has more than bought this home !
I've also learned NOT to 'hold-on' to wishful thinking. I lost money but did sell out early, and therefore didn't get butchered by Crawshaw (LON:CRAW) or hooked by Fishing Republic (LON:FISH) . I do still have an occasional speculative punt, but now have a timeline as to when to bail-out regardless - i.e. >10% in x months, wait for next trading update, etc.
Any thoughts on IG Group?
Started the day off well but the share price has gone down 10%.
Almost thinking we are safer on the short size at the moment - bad news seems to be punished twice. I am sure they already guided revenues lower.
IG Group (LON:IGG) starting to look good value to me sub-£5.50. EV of £1.7b and even with -6% revenue for the HY they should be able to generate £80-90m FCF barring any major investments. This is a EV/FCF multiple of c10 and unless you think the business will decline much further due to regulation this should be fairly sustainable over the long-term. My own view is the main bulk of the regulatory impact has hit and we will start to see stabilisation, although probably a while before they see any growth again. Interested in other views though if someone has more experience with regulatory impact in the financial space.
dangersimpson
IG Group (LON:IGG) presented a useful slide to calculate the impact of higher leverage limits at their Capital Markets Day back in May:
IG Group (LON:IGG) stated today that "around 70% of UK and EU revenue in the four months since all the measures were introduced has been generated by professional clients."
Such revenue is unaffected by the new ESMA leverage limits.
So only 30% of UK/EU revenue will be affected, or £79million (30% * (132m+132m)).
If this revenue drops by 34% as previously assumed then IG Group (LON:IGG) will suffer a revenue decline of just £27million in the current Financial Year. Assuming this all drops through to the bottom line (given that this is a largely fixed cost business) then Net Profit in the current year will be around £200million.
This represents a FCF Yield of around 12% based on todays EV of £1.65bn.
The beauty of buying IG Group (LON:IGG) CMC Markets (LON:CMCX) or Plus500 (LON:PLUS) at the current stage of the economic cycle is they uniquely benefit from higher market volatility.
http://www.iggroup.com/sites/i...
Plus500 (LON:PLUS) IG Group (LON:IGG) CMC Markets (LON:CMCX)
We're in for another interesting day tomorrow with the US indeces all down 3% as I write. But it does seem to me, whatever your poison, as you say spreadbetters should be raking it in. The VIX index is up 27% to 21.
The real surprise I've noted recently is both IG Group (LON:IGG) and CMC Markets (LON:CMCX) have not referred to the recent increased volatility. Plus500 (LON:PLUS) did and I suspect will do again before Xmas - the baton being passed on ????
Edit : Now 32% and 22.
CMC Markets (LON:CMCX) made some understated comments on the pick up in volatility since the end of September in their Interim results two weeks ago :
" the second quarter (July-Sep) was particularly difficult. Volatility was low, and unusually the majority of asset classes traded in tight ranges.... as we enter the second half, which is typically stronger than the first, we have seen an improvement in market conditions and encouragingly an increase in activity across retail, professional and institutional client categories."
Thanks HM,
If your £27m estimate is ballpark accurate the 70% is above expectations from earlier in the year and we could see IG Group (LON:IGG) beat broker consensus for this year (assuming stockopedia numbers reflect consensus.)
Extra stock market volatility should help the spreadbetting side although may also provide a headwind to the nascent stockbroking business. Crypto currencies seem to be heading monotonically towards intrinsic value at the moment so may act as another headwind. But overall I can't see a bit more stock market vol harming the business.
Whats happening with Impellam share price?
610-640 as a lie quote £ipel
re: Impellam (LON:IPEL) This is one of Stocko's quirks that I have moaned about before. The current quote is 610-640 and everyone else quotes the mid price 625. Stocko, however, always quotes the last trade reported, in this case 10k @ 75.5 @ 12 02.
Thank you sharw, good to know. But now i have that knowledge, i dont know if its a good or bad quirk. :)
Hi
For those interested Duke Royalty (LON:DUKE) have a positive interim update.
Graham has posted several positive reports on Duke Royalty (LON:DUKE) over the past months (just look at Duke Royalty (LON:DUKE) Stock Report and follow the 'Discuss' link).
Some highlights from today's RNS which caught my eye:
Rev £2.7m (H1 2017*: £0.6 million), increase of 350%. Inaugural net profit before tax £1.1 million (H1 2017: loss before tax of £0.4 million). Cash flow £1.3 million (H1 2017: cash outflow of £0.1 million). Raised £44 million of new equity in an oversubscribed placing at 44 pence per share. Two quarterly dividends paid, 0.6p on 12 April 2018 and 0.7p on 12 July 2018. Based on the previous quarter payment, Duke continues to be ranked amongst the top AIM companies based on dividend yield. Positive adjustment factors achieved from Duke's first two investments, Temarca B.V. and Lynx Equity (U.K.) Limited and encouraging sales growth also being shown by Trimite Global Coatings Limited and Brownhills Investments Limited
That previous point is quite important as Duke Royalty (LON:DUKE) can raise their royalty revenue from an investment if the investee's performance lifts during the period of the investment. This can occur each year if things go well (a rise or a fall is capped at 6% - so some downside protection as well if performance drops).
RNS closing remarks: Neil Johnson, CEO of Duke Royalty, said: "I am delighted to report that, in the period under review, Duke has been able to post significant revenue growth as well as its inaugural net profit. As the Company continues to deploy capital and benefit from the participation in the growth of its partner companies, I expect both revenues and profits to increase in subsequent reporting periods.
"The Company is focused on deploying its capital raised in the summer into new royalty partners who are under exclusivity to Duke whilst we conduct due diligence. I remain confident Duke will be in a position to close more than one transaction should they pass our due diligence process by the end of the financial year. With this in mind, I look forward to the remainder of the financial year with optimism."
RNS here https://www.investegate.co.uk/duke-royalty-limited--duke-/rns/interim-results-and-dividend-declaration/201812040700123023J/
Disclosure: I hold small starter position as Graham's reports had caught my eye and I attended Duke Royalty (LON:DUKE) s Mello presentation after having watched this clip posted on PiWorld https://www.piworld.co.uk/2018/11/12/duke-royalty-investment-case-by-james-lynch-downing-strategic-micro-cap-it/
If your interest gets pricked do have a trawl of their website and presentations to get a deeper insight into them. My early impressions are that Duke Royalty (LON:DUKE) could be akin to another Burford Capital (LON:BUR) type of investment but this is only my humble opinion, others are likely to be less optimistic I posit.
Regards
Howard
Hi Paul - any thoughts on whether giving hugs is the kiss of death for the Ted Baker (LON:TED) brand? Just as we might choose to be wary about CEOs that are economical with the truth (Taptica International (LON:TAP) today, who knows which of the other overseas-listed companies tomorrow?) should we be nervous about founder-CEOs that act in a strange/unconventional way? Or will the shares stand alone on the financial merits of the company in the long run? Does the fact that the brand is so tied up with Ray Kelvin mean that it will be difficult to ring-fence any fall-out? Trading update out on Thursday so perhaps you would prefer to play it safe and wait till then?
Ted Baker (LON:TED) getting hammered still, institutional investors running for the hills.
I don’t hold Taptica International (LON:TAP) but do hold RhythmOne (LON:RTHM) - a somewhat comparator - which will come out with H1 numbers on 13 Dec. RhythmOne has its own dirty baggage (from when it was called Blinkx) but I think recent numbers are clean (if for no other reason than they have been rubbish). But if forecasts for the current year and for FY20 are half correct, then the share price looks very cheap. While £RHTM is certainly not a “unblemished”!valuation - I think it is relevant when thinking where Taptica International (LON:TAP) could trade if no further disclosures come out.
RhythmOne (LON:RTHM) is another one worthy of a case-study. I have a small holding of same and it is a great example of the long shadow of reputational damage. As for comparators, I have read in the past of holding RhythmOne (LON:RTHM) up to Taptica International (LON:TAP) as a reason for why RhythmOne (LON:RTHM) should rally... well one had to come to the other according to the analyst. Looks like it may have been the case but in the other direction.
Worth noting that RhythmOne (LON:RTHM) ,when it was called Blinkx, was sloppy in its acquisition and allowed some nefarious click harvesting to boost its metrics. What I find very ironic is the self-appointed Sheriff of the "Internet Wild West" , Harvard's Ben Edelman who Winnifrith paraded on the exposing of Blinkx's wrong-doings : went on to be debunked himself for aggressively threatening litigation on small Chinese restaurants. Glasshouses and stones collided there
Worth noting also that Mike Lynch was once on the board of Blinkx and a major shareholder in RhythmOne (LON:RTHM)..;... the shadow of Autonomy and the HP litigation hasn't helped here either
In all this quant sometimes the qual of management remains the key determinant
FWIW, I was long Avast (LON:AVST) until I used their products and found (amongst other issues not least the very fragmented nature of the acquired businesses) aggressive guerrilla marketing and effective browser-hijacking via Avast secure browser very reminiscent of the bad old days of internet practices: sold for a small profit and watch with interest but no appetite
I know Rightmove and OnTheMarket are quite often discussed here. The FT is reporting that the leading UK housebuuilders Barratt Developments (LON:BDEV) Redrow (LON:RDW) Persimmon (LON:PSN) and Redrow (LON:RDW) are backing a new start-up website “Rummage4Property”. The new start up is aiming to undercut the existing players and will be a “membership organisation”. (I hold no position in this sector.)
A membership organisation ? like otm was at launch ? there have been various attempts do do this going back 20 years, there was a company called ask daisy, and several attempts until recently otm was owned in part by the members, but they found it didn't work, they ran out of money and decided to float to turn themselves into a rightmove type organisation, It will be interesting to see how this works out, perhaps if they're home builders and focus on new properties, it could work. Perhaps end up being bought by righmore or another ? Seems to me getting all the developers together, would be much much easier than getting all the estate agents together. BTW rightmove started with companies being induced to join, in return for shares in the company. I worked in a company who did connells website before they jumped to rightmove as founding share holders. So it can work, if it can work with such a strongly established companies, I am not sure, It must help that they're targeting a niche,
Taptica International (LON:TAP) I found out about the CEO's past by googling his name. I feel that it is important to trust management and major shareholders, so I routinely do a bit of research on the past of these people before committing to a purchase. Not doing so has proved expensive in the past; I can attribute a large percentage of historical portfolio losses to fraud and other dubious failings of management, some of which could have been prevented by more research on my part. While I do not insist, as a shareholder, on blameless pasts, certain types of financial fraud and disrespect for shareholders will keep me from becoming involved with a company.
Stockopedia is a good source of information on directors of companies. This morning, as an experiment, I entered "Hagai Tal Stockopedia" into Duckduckgo (a search engine...it avoids some of the pitfalls of Google). The warnings about the CEO's past were there. "Hagai Tal Winnifrith" was less effective, but I have found Mr Winnifrith quite useful as a starting point for research on other directors.
-an investor with a long barge-pole list
MS International (LON:MSI) once held these but sold in late 2013 after a profit warning tucked away at the end of an rns in a poor attempt to hide the truth. Also my recollection is that management were over rewarding themselves. Havent bothered to revisit but might all have changed.
Hi Paul, interested in your thoughts on Oxford Metrics (LON:OMG). EPS up by 27% and Cash increased by 33%. They've announced a special divi; the CEO is happy that investments are bearing fruit.
MS International (LON:MSI)
This share seems to be completely overlooked. I am expecting full year EPS at 30p+ after todays half year results. Net cash is now 50% of market cap !! so it is trading on a cash adjusted PE of 3.5* with a 4.1% dividend yield. They will add another £1m to that cash pile by year end too.
Businesses are performing. Strikes me they are unlikely to be affected particularly negatively demand or location wise by any Brexit scenario. In fact I could see a case for the UK defence spend to go up in their favour on a tough Brexit
This has to be a ridiculous valuation surely? even £3 would look a bit light to me but never seems to go up there!
Anyone see something I am missing? I am long and considering whether I should be longer :)
I think exactly the same as you, David. I wonder why MS International (LON:MSI) don't do a special dividend from time to time as the market seems to completely ignore their cash pile.
MS International (LON:MSI)
I would argue that it is only recently that the company has started to perform and therefore the market will start to wake-up to it attractions. In fact if they can continue to improve the forging result further - now got close to B/E - and get all divisions profitable this will improve its rating I feel.
Y/E 2017 net profits were only £1.5m which then increased to £3.4m in Y/E 2018 and could close to double this year based on today's interims. My point being, at today's price, 2017 represents a PER of 20 .
Never been a believer in cash adjusted PER's - if they don't need it (investment for a return) they should return to shareholders - the logic that this gives a lower PER seems flawed.
Phil
There's nothing flawed about it. They could afford to give back half their market cap in cash to shareholders at which point the business would trade at 110p and be cash generative trading on a PE of 3.5.
You can't ignore the cash pile - it is a fundamental part of the companies valuation. I agree you can argue that it should be given back to shareholders if they can't invest it at attractive rates of return but you can't just discount it from the valuation as if it doesn't exist!
You wouldn't ignore debt on the balance sheet either and just say the business has a PE of x because that ignores the fact that you have to pay it back.
Except that CAKE ....amongst others....was supposed to have this large cash pile. But instead it had a large overdraft. This is the worry and why the shares (TAP) are down to 190p. The company is cheap if all the cash is there...but if not? We have seen a stack of Chinese frauds over the last few years and investors are getting nervy about many overseas companies in some other places.
We are talking about MS International (LON:MSI), which is UK based and not Taptica International (LON:TAP), which is something completely different.
I am looking at MS International (LON:MSI) - seems to good to be true which is bothering me and especially why they didn't just increase the divi.
Management are well entrenched (little old maybe) and don't appear all that independent but Lord Lee has been a non executive in the past (and a shareholder) so I would suggest this is not a wild west type share (could have said same re Patisserie Holdings (LON:CAKE) )
On valuation, I would do cash adjusted although would reduce some of the cash for committed CAPEX. That said if we do full year operating profit to EV adding pension, I still make it at something between 3 and 4 x op profit. With a healthy dividend to boot. Also, call me crazy but fuel forecourt is probably a growth area since they will probably need to convert to charging stations.
A lot that I would look for but again just seems a little too good to be true.
Paul - be very grateful for your thoughts on this and Water Intelligence (LON:WATR) (I hold).
Water Intelligence (LON:WATR) results good (bordering on great) commentary very bullish (when is it not) - all seems set up to carry on and given recent malaise, think it is looking like a decent GARP share (been considering a top up for a while and nothing in these results would change that view, other than the price anchor!)
Finally may I second the motion for your expertise on Ted Baker (LON:TED) (hold 4th largest after topping up yesterday) long term cinpond hold for me, but today I have doubts since the price seems to have no floor. I am looking at mid single digit earnings/ revenue growth, trading at 10x forward with strong brands and margin.
Personally I think it is back the truck time given that the reason Ray Kelvin hugs is his arthritis (surely disability tops sexism in the new liberal order) but I think founder/mgt risk is substantial, which is preventing me from adding more, pending Thursday
MS International (LON:MSI)
The company is not a high flyer, so to compare with Patisserie Holdings (LON:CAKE) on a PER of 20+ seems a bit odd - it doesn't seem to have a reason to massage the figures.
I could counter "too good to be true" with "don't look a gift horse in the mouth" - however, I have looked in the mouth and not found anything apparently wrong.
It has been pointed out in the past, and mentioned briefly above, that directors pay is high. At £1.4m in 2018 everyone has to make their own decision on this - but I would be tempted to say it was worth it if things continue like this and I've seen worse.
Phil
Edit: Meant to add - I suspect that this fell out of favour with the profitability decline from 2013 - 2015.
Interestingly, Smithson has released its first monthly factsheet of its small/medium cap holdings. Quite focused at 29 holdings only. I gather there's some surprise that he got fully invested so quickly in these turbulent times, but manager isn't a market-timer. Looks a nice geographic spread with UK at 18%. 45% in the IT sector sounds high. Only UK stock I recognise in the top 10 holdings is Rightmove https://www.smithson.co.uk/fund-factsheet
Largest holding Verisk is a Nasdaq 100/S&P500 company - not quite sure how that qualifies for small/mid cap status! Wonder if it was harder than expected to invest c£800m in smaller companies?
Halma is another UK holding, in the FTSE250.
Terry Smith's definition of small cap in the IPO prospectus for Smithson Investment Trust (LON:SSON) was up to £7 billion - by small and mid cap he appears to mean 'smaller' than his investments in the Fundsmith vehicle! Consequently don't think he has had difficulty in finding stock as the original universe identified was only c. 85. Given the recent market volatility he may have picked up some bargains too though surprised he has gone for £CHKP (I use to hold) as seen by some as a 'legacy' internet security company which has done well in the past but may not be one for the future. It has never paid dividends and is an Israeli company (!) listed on NASDAQ. On the subject of Israeli companies given Paul's comments re Taptica International (LON:TAP) is it just sour grapes on my part (having sold out much too early) but the financials for Plus500 (LON:PLUS), another Israeli company, just look too good to be true particularly when compared with the poor results reported by IG Group (LON:IGG) and £CMC. I know they are generating loads of cash and paying significant dividends but is this another potential disaster just around the corner?
"Terry Smith's definition of small cap in the IPO prospectus for Smithson Investment Trust (LON:SSON) was up to £7 billion"
That's what makes the largest holding Verisk Analytics stick out - it has a market cap of over £15bn, way over the prospectus guidelines. Which is why I wonder if he struggled to find attractive stocks per his criteria in the stated universe.
The £7bn was the top of the small cap range for Smithson Investment Trust (LON:SSON). He goes up to £15bn for mid caps. Verisk may have been right at the top of that range when purchased.
Halma is on the list. UK listed. Great company but expensive
Halma (LON:HLMA) is also on the list. This has been a favourite of long term investors for some time.
Paul,
The perhaps forgotten Vianet (LON:VNET) please - I like their diversification into vending machines etc - chunky dividend and decent increase in profits...
Vianet (LON:VNET)
I started writing this earlier in the day, but the succumbed to man-flu and fell asleep on the sofa under a duvet and laptop.
It might also have made me a little grumpy.
Growth
I am deeply unimpressed with the presentation of the comparatives here.
They fail to clearly indicate that the prior year H1 numbers do not included Vendman (Acquired Oct-17) whereas obviously this years H1 do.
We know that in the year to March-17 Vendman did £1.8m revenue and £0.27m Operating Profit.
So, I would assume roughly £1m /£0.15m in the HY to Sep-17.
Taking this into account the ‘underlying’ figures look less stellar.
Revenues
Smart Zones -5.3%
Smart Machines +13.2%
Overall -0.4%
Underlying profits in the two segments therefor look quite flat.
I’m also not too impressed that whilst private investors get access to a (quite informative) pre-recorded results presentation, the analysts get a live presentation with the opportunity to ask the management question (like why do you misrepresent your growth numbers? Perhaps.) It doesn’t look like that session is being recorded and distributed, so we wont know what clever questions the analysts have asked.
Dividend
The interim dividend is maintained at 1.7p giving the prospect of 5.7p for the full year (>5% yield) , but as the dividend has been 5.7p for the last SIX years that’s getting a little tired.
Outlook
I could get excited about the fact that “the overall prospects for the second half look increasingly assured”, if only I could understand what that means. I think it is equivalent to “comfortably in line”, but I’m not totally sure.
Medium term outlook is perhaps more encouraging.
“The Board believes that Vianet's medium to long term prospects are exciting as we are increasingly demonstrating that our strategy of leveraging the power of our cutting edge technology platform to bring valuable business insight to our customers is the right one.”
That would be great were it not for the fact I’ve read the last dozen or so statements and the board is in a near constant state of rapture about the medium to long term prospects.
But
I’m actually still holding and probably feel more confident about this being the right decision than I have for a while (my finger has been hovering over the sell button for about a year and with the benefit of hindsight that would not have been a bad call at any time).
So why the optimism?
Well because these relatively lack-lustre H1 results were against the background some interesting headwinds.
Smart Zones – The beer monitoring business.
Smart Machines
So overall there is a degree of “jam tomorrow” and execution risk here, although they are relatively cheap even without the growth.
The earnings forecasts have been increasing since the spring & I think they have been increased again today, yet in fact the 2019 figures in particular look quite conservative to me.
This has been frankly quite a frustrating holding, but I at least am optimistic that it will start to bear fruit of the next year or so.
Oh, and for good measure Stockopedia ranks this as a "super stock" (although to be honest it hasn't really felt like it has had momentum with it!)
Gromley - fantastic write up - bought in yesterday as think the share price is now too cheap but in this climate it may well drop more. Happy with c5.5% div while we wait though...
Re. Taptica International (LON:TAP) I guess with israeli or indian or chinese companies, we have to accept a higher risk of possible financial irregularities than UK based companies. That is not to say that they are uninvestable. Just that in assessing risk/ reward ratio, you have to allow a higher probability that it may be a scam.
I have in the past traded Taptica, not invested in the company precisely for this reason.
Today's news about Taptica is that the person at the helm has in the past committed fraud and has been found guilty. This is unrelated to Taptica. So now the worry is, can we trust the Taptica accounts? have they been doctored to make them look good (i.e. crossing the line between aggressive accounting and out-and-out fraud)?
This suspicion will linger on and will affect the share price, whether or not Hagai Tal stays.
To my mind, the board needs to do three things.
1. Accept Tal's resignation with immediate effect and put as much distance as possible between him and the company.
2. Appoint a new CEO with a squeaky clean background
3. Appoint an independent auditor specifically to look for possible fraudulent activities at Taptica in the past few years. As Warren Buffet would say, 'other cockroaches'.
Just my ten cents worth. No position.
On Taptica International (LON:TAP) "I'll just be watching from a safe distance - I don't want to get involved in this"
Another time I should have followed your advice Paul and watched from the sidelines. I did on Globo and got out with a £600 profit (on a small investment) why oh why did not do so here. It has been an expensive (far more that £600) lesson
We live and learn.
Thank you for your analysis.
Michael
...
Fulcrum Utility Services (LON:FCRM) please - they don't state adjusted eps before the significant amortisation figure which is a bit annoying, and as this is a non-cash cost I would have thought that would have highlighted more progress at that level. LFL growth looks quite good.
Marlowe (LON:MRL) too please, which look quite interesting (I don't hold). A 12 month run rate of 130m revenue and seeing results ahead of expectations sounds quite good, though only thing bothering me is that they are extremely acquisitive and there is quite an amount of restructuring costs which headline eps is stated before taking into account, but this is a cash cost surely.
SRT Marine Systems (LON:SRT) welcome news of the Phillipines contract award. It is indeed the same contract previously won but cancelled because the original financing was to have come from the French government who made it a condition that the contract should go to a French company. Somehow that is not considered bribery. When SRT won the contract, the French withdrew the loan offer and internally budgetted funds had to be approved and the contract re_tendered. No wonder such contracts are not easily won. However this is proof if ever anyone doubted it that SRT is a leader in its field and with a number of similar large projects in late stage development I expect more good news before too long. I hold SRT.
MS International (LON:MSI)
Interim PBT virtually doubled, seems to be on track for a record year with a trailing PER of 9.
Balance sheet includes £16m of cash (@ half market capitalisation) and looks very solid to me.
Seems to have low visability (no broker coverage) but looks very interesting.
Phil
Just what I was going to say !
Paul,
Would be grateful for your thoughts on Water Intelligence. Water Intelligence (LON:WATR). Revenue growth of 40%, comfortably in line and great balance sheet. Works in an exciting area which can only grow in my opinion. Every update recently shows fabulous growth and yet it is still very small. I see this as a great and safe growth stock.
Finncap are reiterating forecast EPS of 49.4p for 2018, and they do hold a lot of cash. So I can only see 2 options here: the whole thing is a scam and there is more to come out, or it is incredibly cheap.
A very good q3 trading update from Water Intelligence (LON:WATR) this morning. 40% growth in revenue over first nine months and PTP "comfortably in line with expectations".
https://www.investegate.co.uk/water-intelligence--watr-/rns/trading-statement/201812040700163068J/
Morning Paul, thanks vm for (LON:TAP) if you get a chance can you have a look at (LON:OMG), look like a very decent set of results at first glance.
Cheers
My morning smallcap tweet: Jam seen at SRT, but this jar was snatched away once...
SRT Marine Systems (LON:SRT), Surface Transforms (LON:SCE), IXICO (LON:IXI), Marlowe (LON:MRL), Quartix Holdings (LON:QTX), Pelatro (LON:PTRO)
SRT Marine Systems (SRT) wins £31m 4 year contract from Philippines. This is the same project which the company previously announced had been cancelled and delayed due to a change of budget source from a foreign loan to Philippine government cash funds. I hold.
Surface Transforms (SCE) H1 trading. Rev down 3% at £509k. Commentary topped with a garnish of good news under which is a sickly fish. Customer 'OEM6' may delay production, may hit FY rev by £500k.
Ixico (IXI) FY up 32%. EPS -2.0p (-5.7p). The Financial Review is headed Ahead of expectations but there's nothing in the body about this. Rev matches F/C, EPS is worse than -1.5p F/C. Guides current FY in line.
Marlowe (MRL) H1 rev up 57%, EPS 8.8p up 41%. Guides FY ahead of current market expectations.
Quartix (QTX) guides FY adjusted EBITDA head of market expectations by 10-15% but "This is largely as a result of the Group's adoption of IFRS15 (Revenue from Contracts with Customers), which has increased profit and revenue in 2018 as noted in the trading statement on 2 July 2018." So broker(s) asleep at the wheel? Why did QTX not nudge them? Revenue and free cashflow guided slightly ahead of market expectations which were rev: £24.6m; adjusted EBITDA £7.5m; free cash flow: £5.4m.
Pelatro (PTRO) wins contract to provide Campaign Management Solution to NCell of Nepal. No £££.
Sadly I own Taptica International (LON:TAP) - quite a disappointment for me as I doubled down and missed the comment on the fraud mentioned above - caveat emptor. If it opens very far down this will be incredibly cheap with a wide spread and I suspect I may as well hold on for a takeover now... without giving advice, what would (conditional tense) other investors personally do?
Taptica International (LON:TAP)
Got an offer starting with a two so sold - decided to treat like a profit warning - I suspect the doom mongers can make hay with this.
May revisit.
Good Luck
Phil
Taptica International (LON:TAP) is a fairly low liquidity share with just 288K as a normal daily volume: assuming this is a fairly concerted rush for the door and assuming this is indeed historic and not material to the Taptica International (LON:TAP) operations, then expect the price to recover after the crowd have left (volume today is around 1.8m so far) . It was the biggest gap-down in the whole LSE this am with a gulf from 310p down to 235 so price may well recover to touch the lower bound of that gap around 230p . assuming it makes that there is likely a raft of sellers happy not to take the full loss so this will languish for weeks or months without a favourable catalyst to boost (or one to sink). If it doesn't recover then the wisdom of crowds probably prevails and there is more bad news to come
Might be prudent to trade your way out and no longer view this as an investment: clearly governance is a major issue if better character judgements weren't made at C-suite level .
current market environment is incredibly punishing: many fairly "safe" companies like Thomas Cook (LON:TCG) and Kier (LON:KIE) are down 60-70% over the past couple of weeks and are still cratering
So SRT Marine Systems (LON:SRT) have finally won a significant contract - jam tomorrow becoming jam over the next four years. The strong price action over the last couple of trading days might I guess be due to them dropping a hint with a photo of fishing boats in the Phillipines on their website gallery on the 28th. I do hold some, and I'm hoping that my holding might even be in profit by the end of the day.
The several "Second Price Monitoring Extn" RNSs at 07:02 today amused me...
I’m no legal eagle and am more than happy to be corrected, but I think it’s a bit harsh to say this is an Israeli problem given the Autonomy (think I got the right name) / HP case, and we’ve had several listed UK companies go to the wall this year for, er choose words carefully time, director mistakes of different kinds.
Some comments I read on various fora speculate that American companies seem to rely on the courts to absolve their directors of foolish decisions, I’m not enough in the know to make a judgement one way or the other, and would be grateful if more learned posters could add clarity.
Hi IGPJ.
The conspiracy theorist in me does feel there’s a strong sense of “America first” in the way the US judiciary works.
In addition to the pending Mike Lynch/Autonomy/HP situation you mention, the treatment of BP over the Deepwater Horizon incident (contrasted to that of some of the US contractors such as Halliburton that were involved), Indivior (LON:INDV) ‘s ongoing opioid patent dispute, the treatment of Barclays/RBS and Deutsche compared to that of the likes of home players such as Goldman’s and Citi over the sub prime MBS market abuse etc., all seem to be examples of the away team getting the rough end of the system. I’m no legal eagle either and there may be counter examples of US firms losing out to foreign plaintiffs via the courts (though I can’t immediately think of any). It may simply be that US companies are better able to understand/game the US legal system. Either way, as a private investor we’re in no position to affect US due process, so it’s just another risk we need to assess and take on board.
On the specifics of Taptica International (LON:TAP) , the wording of the RNS suggests that while Tal has offered to resign the board hasn’t (yet) accepted it. Not quite sure how to interpret that,
Gus.
Gus
what about the treatment of the Gypsy King if you want to see US bias
Hi HornBlower.
Not familiar with Gypsy King situation that you mention. Google seems to offer me either Romany culture or a French flamenco/salsa pop ensemble which I presume is not what you had in mind. Could you give a bit more background please?
Thanks,
Gus.
—————
Edit: Sorry, my bad. Just realised your talking about Saturday’s boxing! A bit too lateral for me, and in that case wasn’t the “rogue” judge Mexican?
Gus
CAKE mentioned yesterday. I think this will be delisted early next year after 6 months of suspension. It is going to take some time to resolve what went on and restate the accounts and cash position. It cannot all be done in a few more weeks. I suspect there are a few in the company who would welcome this....it would mean the media would lose interest and of course the new private company would not need to report as much as currently.
I have two many former shares that are now private. One in particular is booming but with no trading facility all that has happened is that the directors have increased their remuneration. Not great! “Lion” is another former favourite of many small cap punters that suspended and is now delisted. No one knows what is going on there and of course the company does not need to say. This risk is something that is rarely talked away and especially by the stock exchange!
Taptica International (LON:TAP)
Extract from Taptica website-
"Hagai Tal joined Taptica in 2010 as a major shareholder and became the Company’s Chief Executive Officer in December 2013. Mr Tal has invested in, led and developed a number of companies through successful growth, continued investment and the IPO/disposal process. These companies include Kontera, Amadesa, Payoneer, BlueSnap (formerly Plimus) and Spark Networks (NYSE:LOV). Mr Tal’s previous positions include Chief Executive Officer at BlueSnap "
So he was at TAP from 2010 as a major shareholder but only became CEO Dec2013. Marvellous that he claims Blue Snap (formerley Plimus) as a success story!
He owns (directly & indirectly) 14% of TAP and assuming no appeal route, will presumably need to sell sooner or later to make restitution?
Re Taptica International (LON:TAP)
I highlighted my concern regarding the ongoing lawsuit involving Taptica's CEO Hagai Tal in this Stockopedia comment on 19 May 2018.
I concluded:
"After digging deeper into this claim (which I believe is still ongoing), and in particular after reviewing this Delaware Chancery Court opinion, I reluctantly sold all of my holding in Taptica last month at a 6% loss.
"I appreciate that as a consequence I may be missing out on a great growth story, but the above issue undermined my faith in the veracity of any of the company's claims, and this applies to the Q&A RNS released on Thursday."
gus 1065 gave a considered counter to my concerns in the same thread, and it remains to be seen how material an issue this is for the company going forward. As it stands though, I'm happy with my original decision to sell all of my holdings in the company despite the attractive prospects.
Taptica International (LON:TAP) - the court judgement is here:
https://courts.delaware.gov/Op...
Key sentence on page 2:
Why would Taptica hold investor days and refuse to put the slides on its website. Why would it raise funds for M&A and not do m&A. Why was there no financial disclosure on Termor vs Taptica so how do we know they did not cover up extremely poor Tremor results. If Taptica had truly been performing well it would be exceeding expectations on sales like TTD.