Small Cap Value Report (Tue 4 Jun 2019) - LGRS, CALL, AO., GHH

Good morning, this is the placeholder for Tuesday morning. It's Paul here.
Many thanks for the positive comments about my video review of the AIM admission document for Loungers (LON:LGRS) - hopefully this might encourage subscribers here to delve into these large documents, which can seem quite daunting. I tend to get about half way through reading them (if that!) normally, and then abandon them on any flat surface in my office. Never to be completed.
To properly read an admission document is quite a big time & effort though. I'd estimate that to properly read, and think about the LGRS AIM admission document probably took me about 5 hours of quality time - i.e. time when there's nothing else going on - so it has to be outside market hours, TV switched off, and nobody else in the vicinity making any noise. In practice then, unless you're superhuman, the only time to properly immerse yourself in an admission document is at weekends, and only if you're a hermit, or an insomaniac!
No wonder that, very often, many of us make quite significant investments, without having properly read the admission document, or not having read any of it.
I finished off reading the rest of the LGRS admission document yesterday afternoon. So I'm aiming to record Part 2 of the video at some point in the next few days. That seemed a better use of my time than reporting on Kier, or Fulcrum, which were on my to do list, but seemed things where I didn't have any value add.
See you in the morning!
7-8am quick comments
Cloudcall (LON:CALL)
(I hold a long position in this share)
Contract win - "significant new contract with a major U.S. staffing firm".
Contract value is for a minimum of £1.1m over 3 years, so almost £400k p.a.
That's say £367k next full year FY 12/2020, which is 2.4% of £15.3m forecast revenues. So not material in terms of revenues, but being a high gross margin business, there's a leveraged impact on the bottom line from new business. Revenues are mostly recurring, and customer churn is low.
Buried in this announcement is an upbeat-sounding trading update;
This major contract win continues what has been a strong start to 2019 for new contract bookings and net new user growth, particularly in the US where we are seeing more traction from our new integrated SMS and IM products.
My opinion - this company has disappointed in the past, but has I believe reached a tipping point where things are starting to work.
This was one of my small cap ideas at the recent Mello London conference - see page 8 of my presentation slides here.
After a few false starts in recent years, I think this share could re-rate nicely if sales momentum continues. I see good upside here. Strongly growing SaaS businesses tend to be highly rated, especially in the US. £26m market cap at circa 100p per share, looks cheap to me.
AO World (LON:AO.)
Results for FY 03/2020
Still loss-making, but that's due to losses in Europe offsetting decent profits in the UK.
Gushing commentary from the exuberant founder, who returned to run the business - as seems to happen quite often with entrepreneurial-type businesses.
Targeting run-rate profitability in Europe in FY 03/2021 (i.e. next financial year). If it achieves this, then the £519m market cap (at 110p per share current price) might begin to make sense.
My opinion - I remain negative on this - it's not a good business model, selling low margin electrical products online. People just search for the best deals, meaning AO will always be facing margin pressure.
After 8am comments
Gooch & Housego (LON:GHH)
Share price: 1030p (down 24% today, at 12:26)
No. shares: 24.96m
Market cap: £257.1m
Gooch & Housego PLC (AIM:GHH) ("Gooch & Housego", "G&H", the "Company" or the "Group"), the specialist manufacturer of optical components and systems, today announces its interim results for the six months ended 31 March 2019.
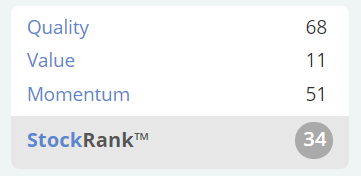
I'm not terribly familiar with this share, having last written about it here in 2014. I recall that it's always seemed a good quality, but rather expensive share. That's reflected in last night's (pre profit warning today) StockRank;
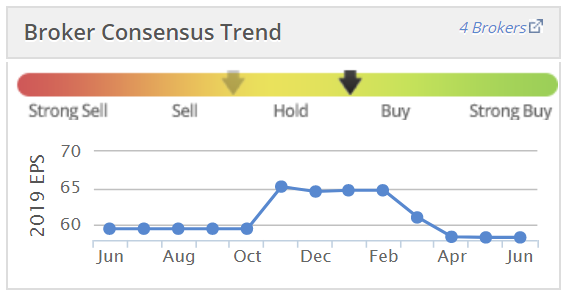
Also I note that the broker consensus forecast has been reducing in recent months - a precursor of trouble ahead sometimes. So it's important to keep an eye on this chart for all positions one holds;
Graham wrote a piece here on 20 Feb 2019, when the company warned on profits. He picked up on the H2 weighting, and correctly highlighted the risk of another profit warning to come, so kudos to Graham!
Interim results - these have clearly disappointed, with the share price down 24% today, albeit on low volume (only £150k-worth of trades printed so far today). Although there can be background orders being worked which don't print until later.
Key numbers;
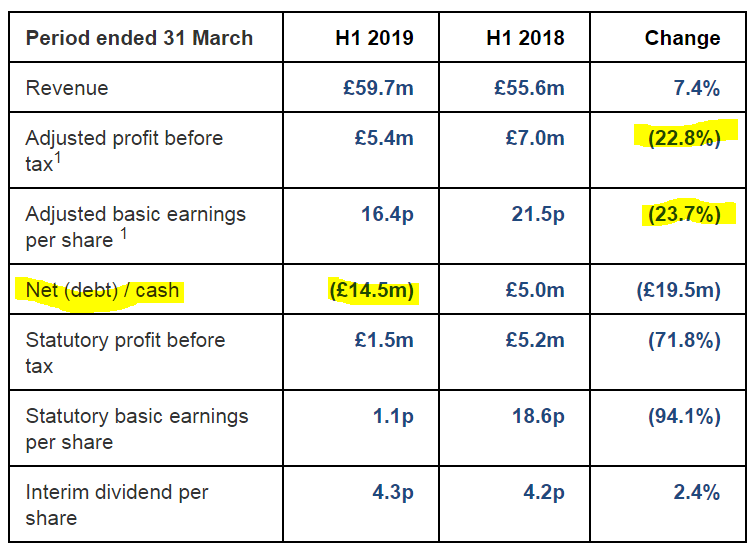
Note profit well down on H1 LY, and a sharp deterioration in the cash position (probably from an acquisition).
Commentary key points;
- challenging industrial laser market, due to cyclical downturn and continued US/ China trade dispute
- Industrial laser orders have increased since our last update, but we are now assuming that industrial laser business will not return to 'normal' levels in FY 2019 and instead we only supply known / high certainty orders. This segment is 50% of revenues.
- We anticipate non- industrial laser business will perform in line with our expectations
- Expectations reduced - Given revised industrial laser outlook, Board's expectations for the Group's adjusted PBT for FY 2019 now reduced by circa £3.5- 4.0 million
- Order book up 10% at £93.2m (Q2 improved on Q1)
- Cost reductions being implemented
To save me crunching the numbers, I'm delighted to report that Research Tree has updated numbers from Finncap, with a nice one page summary of the situation.
Revised forecasts - a hefty reduction today, in the full year broker forecasts;
FY 09/2019: EPS reduced 22% to 45.3p - PER of 22.7
FY 09/2019: EPS reduced 19% to 53.8p - PER of 19.1
That really doesn't look cheap, does it? And I've calculated those PERs based on today's sharply lower share price.
Outlook - mostly repeats comments already mentioned above, adding;
... That said, significant technological innovation in 5G, folding phones and the greater use of industrial lasers in manufacturing, coupled with our market leading position means supply of critical components to industrial lasers will be an important source of growth for G&H into the foreseeable future.
During FY 2019 we have prepared for significant capacity growth in fibre optics generally and hi- reliability fibre couplers specifically, as they undergo a multi-year growth phase.
We remain confident in the potential of the industrial laser sector and our other target markets to provide attractive long term growth.
Balance sheet - the current ratio is very strong, at 2.60. This includes £15.6m in cash.
Long-term creditors includes £30.0m borrowings, which seems rather inefficient (why hold cash, and debt?)
NAV: £106.9m, less £62.1m intangibles, gives:
NTAV: £44.8m
That's fine overall I think. No solvency issues here.
Cashflow statement - looks as it should. In H2 last year, the group increased borrowings by £17.3m in order to finance acquisitions totalling £24.0m last year.
Paying modest divis.
My opinion - this situation is a straightforward one. If you think this is a great business, that will recover from a temporary slowdown in business, then this might be a good entry point.
If you think that the problems are more serious, then it's best avoided.
Personally I don't have the knowledge to make that judgement, so it would really just be a punt were I to get involved here. Bearing that in mind, I'd want a price considerably lower, to tempt me in, than a current year PER of 22.7 - that doesn't give any margin of safety for anything else that might go wrong.
All done for today. Sorry I didn't get round to looking at VP.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
I cannot claim to know why 888 Holdings (LON:888) poker took the hit it did. But I can explain why I stopped playing poker on 888 after several years as a near daily player.
They changed the system under which a player joined a table. It had previously been possible to identify players one considered relatively weak and then to queue to join the table(s) where such players were sitting and playing. The new system in effect removed this element of choice and allocated the arriving player to a seat on a take-it or leave-it basis. That radically reduced my edge (never huge, but I never added to my initial deposit). I wrote to them protesting at the change. On receiving no response, I withdrew the balance of my account and have not looked at the site since. It may be that I was not the only one to feel disadvantaged and to vote with his feet (or mouse). If that is the case, I doubt very much if they will get those customers back. That is a serious blow to their poker business, which is indifferent to the success of individual players and wholly dependent on taking a cut of the betting turnover.
Thanks very much for the Loungers video. Very enlightening.
Raven Property (LON:RAV) Looks interesting to me, Russian warehouses at a reasonable discount to NAV. Woodford I think has a large stake. It is a bet on the Russian economy with good odds, after my recent trip there I thought the economy appeared stable.
I think that Raven Property (LON:RAV) is rather more than just a punt on the Russian economy: it is (or certainly was a year or so back) invested in warehouses with rents denominated in US Dollars. So it is also a punt on the USD-Rouble exchange rate (and I was concerned that if the rouble weakened, those rents would be increasing for the tenants, who would have to pay a lot more for their dollars just to pay the rent.) Then add in the politics - sanctions, oil potentially weakening with Trade Wars etc.
Good luck if you decide to risk it. I wouldn't!
Ricardo
Raven Property (LON:RAV) - I think those days of tenants paying rents in dollars have been and gone, or at least in many cases.
I do hold some of their prefs - Raven Property (LON:RAVP). Glutton for the yield.
The hit has been taken and NAV has been substantially lowered. Borrowings are now in Roubles. If the economy is ok then so should the Rouble be.
I only own a few waiting for Woidford outcome.
Any views on Driver (LON:DRV) ? Poor interim results today but "...whilst activity levels during the fourth quarter will be critical to the outcome for the year as a whole, we currently expect to deliver underlying* profit before taxation for the year broadly in line with the guidance set out in our March trading update"
The problem with this one is that the flow of opportunities (contract disputes) is very lumpy.
After the trading statement in March Keith Ashworth-Lord reduced his fund's stake from 19,68% to 15.99%
The sp was down 10p earlier but now 7p following a noon announcement that the share buyback programme would be resumed (net cash £5m)..
I decided that I would never invest in any of Woodford's funds when I read that his Patient Capital Investment Trust has a large holding in a firm called Industrial Heat:
https://citywire.co.uk/investment-trust-insider/news/woodford-patient-leaps-on-spike-from-industrial-heat/a1157456
Industrial Heat claims to be developing cold fusion, but any competent physicist could have told Woodford that the probability of that ever being successful is very close to zero because it is against all our current knowledge of physics. It really made me question his judgement.
According to the above article: 'Link Fund Solutions, the trust’s appointed alternative investment fund managers, dramatically upgraded the value of Industrial Heat by 357% to $112.9 million (£85.2 million)'. As Industrial Heat is an unquoted firm and has, in my opinion, zero probability of ever making a profit, I don't understand on what basis they did that.
Eservglobal (LON:ESG) proposed sale of eServeGlobal core business and name change announced today.
Here's an interview with John Conoley, Executive Chairman who gives us a little narrative.
ESG signed a conditional sale and purchase agreement to sell the core ESG business & associated assets to Seamless Distribution Systems AB, leaving just HomeSend. Purchase prices is Eu2m.
Re Woodford Equity Income Fund
Reading the full list makes me feel like I know what I'm doing! It's an astonishing array of long shot punts. He really should read Paul & Graham more. I mean, he even has Purplebricks (LON:PURP) in both his Woodford Patient Capital Trust (1.48%) and also in his LF Woodford Equity Income Fund (1.87%). The stand out component of his LF Woodford Equity Income Fund, that I'm sure many readers here may have a holding in is, Burford Capital (LON:BUR) which is his 2nd biggest holding at 5.78%. I notice that Burford Capital (LON:BUR) are 6% down as I write this which may or not be related.
I expect Woodford focus has come under a lot of selling pressure as well - especially since HL took it of their top funds and I imagine their multi manager will also need to redeem it's holdings in income focus.
Looking at Woodford holds that are taking a hit, it seems Newriver Reit (LON:NRR) , Redde (LON:REDD) , Burford Capital (LON:BUR) and £TEn are taking a hit and I am not aware of anything stock specific.
I expect he has been a fairly persistent seller of British American Tobacco (LON:BATS) and Imperial Brands (LON:IMB) and the homebuilders.
I sold out of focus this morning, several mornings too late - fortunately didn't hold the flagship. Tempted to take a punt on Woodford Patient Capital Trust (LON:WPCT) . Was hoping Strix (LON:KETL) would take a battering to initiate a position. And considering an addition to Burford Capital (LON:BUR)
Hold above mentioned stocks except Newriver Reit (LON:NRR), Woodford Patient Capital Trust (LON:WPCT) and homebuilders.
Omg what a punters list of holdings. Just shows what these supposed experts buy!
Agree that he should read Paul & Graham’s reports. It’s almost like Woodford chose mostly long shots in an effort to try and get a few multi-baggers in a vain attempt to make up for the rest of some of the dross he holds. And surprised it’s called an income fund when many of the holdings don’t even pay a dividend!
I’ve only one crossover - Breedon (LON:BREE), which probably explains why they’re off today.
Personally I would rather buy an ETF than pay his charges, or buy into a much smaller fund like those run by Mark Slater.
Mello perennial Eservglobal (LON:ESG) has announced mid-morning the long-awaited sale for c Eur 2 million of its core business, which will leave it holding just its stake in HomeSend. Looks a fairly clean transaction - the RNS interestingly goes into some detail of the warranties it needed to sign. (No position.)
Re Woodford Equity Income Fund
This link seems to be available without registration: https://woodfordfunds.com/funds/weif/fund-facts/
Under the top-ten holdings list is a chart called "Performance contribution". By moving your mouse over the dots you can read many of the other companies invested and see the weighting. It might help to zoom-in with your browser ("ctl" "+" keys at the same time, "ctl" "0" to reset)
I only noticed a couple of duplications with my fifty or so current holdings. I'm probably going to hold on to those for two reasons, first I'm holding for the longer term, secondly even Woodford has to get it right occasionally.I hope!
The Bestinvest web site has a list of Woodford Equity Income Fund's top 10 holdings at the end of February.
888 Holdings (LON:888)
I have looked at the chart and can confirm you are mad!!!!!! Maybe you caught the bottom. Best of luck!
Lets hope so (bottom reached rather than me being mad) - probably quite apt that its a mad gamble being a gambling stock.
Being honest sometimes i do look at charts like this now (firm downtrend?) and stay well clear - particularly if i don't see the company news being positive in the short term - to me here though the news is positive enough to go directly against the grain so as to speak.
re 888 Holdings (LON:888) @ rmillaree you should have blagged you were going for a reversal: good evidence from the chart for same if a bit premature
- been basing for a few of weeks with support back to 2015
- intraday price reversal and doji on high volume with a positive catalyst today
- very recession-proof line of business
- good fundamentals with strong Q and V scores
- city accumulation over the past few months (+23%)
- broker consensus buy with a price target of 230p so loads of headroom from your entry
- despite the very poor price action, no listed open short interest
It is categorically a reversal position and extremely counter-trend so much achtung
I'll wait for a close or two above the 21EMA (134p) but it has a very good asymmetric risk profile...
Set a stop below 120p and you have a super risk :reward with a nice divi in between though on 1.3 cover
I hold and have thought long and hard about adding over the recent days and even today - may still do once I have had a chance to read the capital markets presentation.
Their investment in marketing might hold back results, but gives them a bigger customer base for next year which is a busier sporting calendar - same would apply to their expansion in Europe where they can take advantage of customer base. Good balance sheet, earnings growth on a 2 year view, brand name, excellent return metrics and cash generation with limited CapEx, growth on the top and bottom line on 10x earnings with a covered 7% yield - other than the chart what's not to like
Would be keen to understand why poker took such a big hit
There is Support at 113p approx.
That price was Support in June 2014 and Resistance Dec 2009 and 2012. So Pivot point.
First Resistance is 150p then 173p.
It will be heavy going after that because there will always be supply from people who bought higher up.
I hold, am pleased with the price improvement but am not adding today. Considered it when cheaper a few days ago.
It is better relative value and stronger growth rate for me than some other Gambling stocks like RNK (Rank), XLM (XLMedia), IGG and CMCX which I also hold. Stocko does not agree. DYOR!
I find it amusing that the list of Woodford investments is copyright constrained, as presumably they do not want others to copy their investment ideas- I seem to recall that the FCA or similar had something to say about this.
However, it seems to have served as a useful means of avoiding fairly awful pitfalls, so an an inadvertent blessing.
Uk Copyright
You are fine posting information with copyright provided it is for fair use.
If the use is for the purposes of research or private study;
If it is used for the purposes of criticism, review or quotation;
Where it is utilised for the purposes of reporting current events (this does not apply to photographs)
Ref: https://www.bl.uk/business-and-ip-centre/articles/fair-use-copyright-explained
Thanks, Carcosa, but
Copyright
Except where indicated otherwise, all information, text and images are our exclusive property. You are only permitted to print, copy, download or temporarily store extracts from this website for your personal use, provided that you do not change or remove any copyright notices. All intellectual and other property information shall continue to be held by us and no rights of any kind in it shall pass to you.
from the site's terms and conditions
As I am unaware if the Terms and Conditions override Fair Use Copyright, AND the information concerned may be construed to be not in the public domain because it is behind an obligation to register, AND, conceivably, Woodford could be said to be financially disadvantaged because all of us would be selling the smaller holdings, I choose to take the coward's path and not publish the list.
regretfully,
L
When Woodford launched his funds he made a big thing of being completely transparent with publishing all his holdings, not just the usual top ten.
Then you had to register on the site to be able to download the spreadsheet and it became a bit less obvious how to find it on the site.
Now you have to confirm you are an active investor to get to the information.
I looked on it as a symptom of being in denial about the fund performance.
By contrast Keith Ashworth-Lord at Buffetology writes openly about his errors and lessons learnt. I guess it’s easier to do that when the overall performance is good.
Re The Copyright discussion
Laurie, the extract you quote is practically on all websites (google the phrase). It's standard boiler plate prose. It is even on the RNS website! Just agreeing to T&C's does not make those T&C's enforceable.
There is no doubt that copyright and associated 'laws' are not fit for purpose in the digital age.
What still holds true however is defamation and slander. Bulletin board postings more likely slander than libel. Proving either is somewhat onerous and the short term nature and audience of bulletin boards makes it highly unlikely that anything will be taken that far. If it was, ADVFN would have been closed down years ago!
Nonetheless if you feel uncomfortable posting links and comments then that is your right.
Any views on Draper Esprit (LON:GROW) please? I hold, and am pleased enough with the results today. For me, the important metric is NAV which is up 26% to 524p - thus at 482p the company trades on a discount. Gross portfolio is quoted at 594m +144%; cash and other resources are available for further investment.
I'm one of the few to have made a profit from Woodford Patient Capital Trust (LON:WPCT), because when I looked in to some of the companies he was buying I was horrified (and said so on his blog) and bailed out near the top.
Everything has its price and I'm told there are some promising companies in the portfolio so there may be a contrarian opportunity to buy in at a large discount, but I would say to look under the hood to check what you are buying. Top ten holdings according to HL:
Benevolentai 9.81%
Oxford Nanopore Tech Ord 8.32%
Autolus Therapeutics PLC ADR 8.26%
Crossco (1337) Plc 8.07%
Proton Partners Int Ltd ORD GBP0.001 7.34%
IH HLDGS INTL LTD 6.74%
Immunocore Ltd Series 5.64%
Oxford Sciences Plc 4.62%
IH HLDGS INTL LTD 2.97%
Mission Therapeutics 'c' 2.15%
888 Holdings (LON:888)
I have bought in today , todays update wasn't as bad as i feared it may be based on the recent price action. Although it does look like there has been consistent reduction in earnings estimates this year that does sort of explain the weak shareprice. No doubt the chartists will call me mad if this is a stage 4 minervini type situation - (its red rag to a bull with chartists going against the chart :))
Ref 888 positives decent solid brand - they could be bought out - cheap pe - decent balance sheet.
Negatives - poker results woeful but that's small enough element of this business to be overlooked and i don't think poker is as popular as it used to be. Their betting website isn't great compared to some of the others - they won't take a decent wager either - although that may be good risk analysis on their part.
Camtab
Ref the sin aspects of gambling - yes it won't be for some - shouldn't be allowed for some too - i have always found that compulsive gamblers will always find something to loose their shirt on. They have always existed and always will exists - to me its no different to smoking/drinking/extreme sports/extreme gaming/dieting/gyms/drugs/social media - where a small element of bods will take things to excess that its not healthy for them - IMHO thats just a human trait. So you may not want this business not to exist but i would say the 95% of bods who don't have such problems should be left in peace to enjoy their thing.
rmillaree - I have looked at the chart and can confirm you are mad!!!!!! Maybe you caught the bottom. Best of luck!
I have issues with 888 and their ilk. Personal and subjective, but I believe there is a significant issue in our society. The people getting hit are those who can't afford it or those who are addicted (probably same subset of people). As an experiment I thought I would sign up. Absolute money making machine but ever since have a had email after email encouraging me back. Sure standard business behaviour but that is why these businesses shouldn't exist. If I am addicted getting regular emails is like taking a sip of wine for an alcoholic. Anyway I have said my bit good luck with your investment I am sure it will do well.
Hi Paul. If you get a chance, I'd be interested in your views on Vianet (LON:VNET) which you've covered a few times in the past. There's lots of management waffle in the final results but it does look like a small beat on forecasts and it feels like a company making pretty steady headway in a profitable sector (Gross margin stable at 68%). They seem to be aligned for some break out performance in coming years (jam tomorrow perhaps but the dividend whilst we wait is a healthy 5.70 pence per share (4.5%). I have a small holding and I'm tempted to increase. The pub division is facing headwinds but they maintained a decent performance despite pub closures. Progress in the states seems to be slow but forecast to make a maiden profit next year. The future growth appears to be in their Smart Machines division (includes recently acquired Vendman) which forms a smaller part of their revenue and profits but appears to be growing fast even if you discount the Vendman contribution. Contactless payments for vending machines is driving growth (something I've personally experienced at airports where I have made contactless vending purchases that I would not have otherwise made due to lack of suitable shrapnel). I'd really appreciate your take on the numbers. Many thanks.
I've quipped in the past that the Vianet (LON:VNET) management seem to live in a constant state of excitement.(exciting features 5 times in today's announcement!)
Although only a modest 'beat' I'm tempted to get a bit excited myself.
I need to run through the numbers later and watch the, but my initial thought is that the 2020 forecast is significantly low.
Any broker updates today?
Hi johnsmith68,
I had a rummage through the Vianet (LON:VNET) figures, but didn't see anything in them worth reporting on.
It's more of the same really - not much growth, and lots of positive-sounding commentary that never really translates into improved financial performance - that's been the case for years now.
It's not clear to me why the group is listed. Management are lacklustre, in my view - I don't see them turning this into a major success.
Divis maintained again, so the yield is a reasonably good 4.5%
The share price looks about right, but I'm struggling to see any catalyst to make it go up meaningfully.
Regards, Paul.
Thanks Paul, I appreciate the feedback. Thanks for the incredible time and dedication you put into these reports.
I recall Paul, that it was you that first alerted me to the ‘merits’ of Vianet (LON:VNET), a good few years ago. Aside from the value credentials, at that time there was an interesting potential upside arising from their efforts to roll out the iDraught product to the much larger potential market in the USA.
It was ironic then to read in the latest results that, after all this time, they made some more modest progress in the US and expect to deliver a maiden profit in the US next year! Beer tomorrow as it were – I long since stopped expecting anything much from the US, so this is not part of my interest these days.
In fact the old brulines (now known as “Smart Zones” is ticking along pretty flat and makes up c. ¾ of the overall turnover, there are some potentially interesting developments but its not going to set the world on fire.
What is possibly of interest though is the Smart Machines business (including the Vendman acquisition of Sept 17).
Here they grew the top line by 50% to £4.68m and claimed they would have doubled it were it not for the effective headwind of moving from a sales to a rental model . I haven’t fully checked the numbers yet, but I think that “doubling” is flattered by the FY impact of the acquired vendman revenues; nevertheless things seem to be going well here. Plus they expect the “global coffee contract” (pretty sure this is Costa, but I cannot recall if this was formally confirmed anywhere) to add momentum over the near term.
So whilst somewhat a case of beer and coffee tomorrow, there’s still enough here to, just about, keep me interested.
I’ve been near to selling out from sheet boredom on a few occasions and perhaps I should have, although my quick back of fag-packet calculations are that I’ve made c. 8% pa (mostly in dividend) on holding here so if disappointing it at least has not been a disaster.
I’ll try and work up the numbers in due course and perhaps add to this, meantime though I still think the current year forecast looks light, we shall see.
Bought into 888 Holdings (LON:888) recently on the share price weakness, I think it's undervalued.
That being said, not sure what the markets will make of this update. The decline in poker seems rather alarming. The result in sports is good, but the next update will almost certainly show a large like-for-like decline because of no World Cup this year.
The price is such that I don't see much downside, and I think it'd be a good acquisition for the likes of Paddy Power/Will Hill.
Loungers (LON:LGRS) Peel Hunt starts coverage with 'buy'
* Peel Hunt initiates coverage of British high street pub, bar, hotel operator Loungers Plc with "Buy" rating and PT of 285p
* "We believe the company has substantial opportunities to maintain its rapid pace of growth over the long term" - Peel Hunt
* Peel Hunt adds that although LGRS trades along with rival Wetherspoon's pubs and coffee shops, it does not lose trade when competitors open stores near it
* Liberum also initiated coverage on LGRS with a "buy" rating on June 3 and set PT at 275p...
My morning smallcap tweet: UK's most agreeable NED?
Cloudcall (LON:CALL), Billington Holdings (LON:BILN), Haynes Publishing (LON:HYNS), Mirriad Advertising (LON:MIRI), AO World (LON:AO.), Northbridge Industrial Services (LON:NBI)
Cloudcall (CALL) wins contract, worth minimum £1.1m over three years. Says it's 'significant' but that's only 3% of F/C rev.
Billington (BILN) wins two contracts worth £30m tot.
Haynes Publishing (HYNS) guides FY adj pretax to exceed market expectations by c.10% and up c. 24% YoY.
Mirriad Advertising (MIRI) appoints the perfectly named Bob Head as NED.
AO World (AO.) FY loss natch'. The returning king John Roberts puts rhetoric on max spin: "The AO model is an eco-system of complementary competencies across retail, mobile, recycling and logistics through to financial services and B2B trade. We have huge structural advantages when these capabilities operate in harmony."
Northbridge Industrial Services (NBI) AGM stmt reiterates improving market (see 11Apr RNS). 12 month trailing EBITDA up 78% at end April.
I see Woodford has suspended his flagship fund due to amount of redemptions.
The firm said the suspension would give it "time to reposition the element of the fund's portfolio invested in unquoted and less liquid stocks, in to more liquid investments"
Worth looking into what he's holding small cap wise as this could affect prices.
Here is the list of Mr Woodford's holdings within the affected fund as of April 30th:
Link removed as there are prohibitions on Woodford's website...
Search services will be helpful, but there is a registration process.
Hi Laurie, could you post the list here save us all having to register?
Many thanks.
Hi Paul, ipo video very useful, thanks.
Re Woodford
Sorry--I took the list of holdings down... they have copyright
Wow - I have absolutely no overlap at all with Mr Woodford. Interesting.
Is that why Woodford Patient Capital Trust (LON:WPCT) is getting a pounding or just investor sentiment perhaps. Could be a god buying op for those with a long term horizon.
It will be interesting to see how this pans out in the longrun. When the Woodford Patient Capital Trust was set up it indicated a 10 year time horizon. I was already invested so when the price fell by almost 20% this morning and was at a record discount to NAV I just felt it was a good time to buy.
888 Holdings (LON:888)
trading update covering the period from 1 January 2019 to 18 May 2019.
Revenue increased by 6% on a like for like basis* (2% increase on a reported basis).
Strong momentum has continued across a number of the Group's global regulated markets.
Reports encouraging growth and remains confident that the outcome for the full year will be in line with its expectations.
Later this afternoon the Company will host a Capital Markets Event for investors and sell-side analysts in London. The presentation materials and a webcast of the event will be available on the Company's corporate website later today.