Small Cap Value Report (Tue 4 June 2024) - TIDE/CKT, GHH, CHG, ELCO, VLG

Good morning from Paul & Graham!
Graham writes: For readers who are interested in Ramsdens Holdings (LON:RFX), I have a management call with them tomorrow morning. Instead of asking my own questions as I did last time, I'd like to ask the community here for any questions you might like me to put them. Please let me know in the comments. Thank you in advance!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Summaries
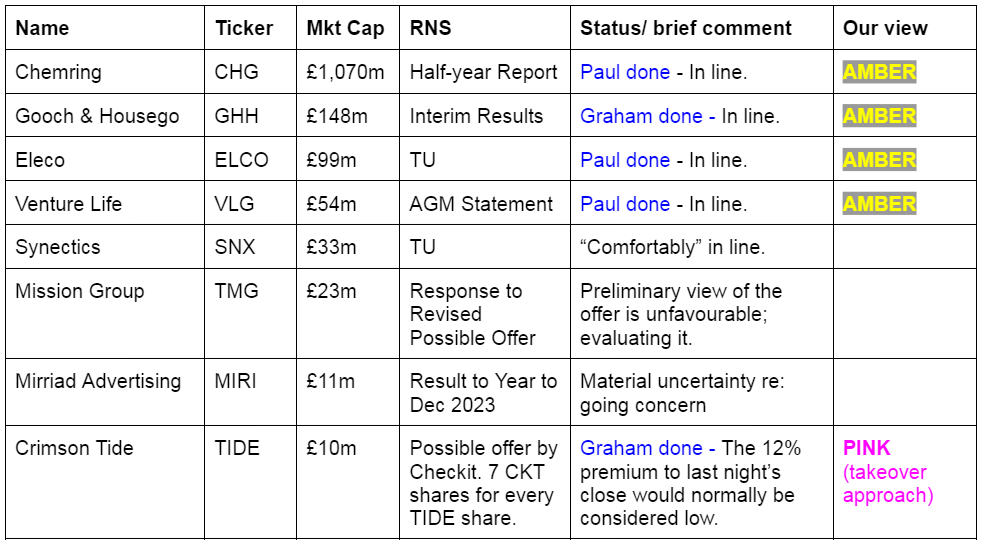
Checkit (LON:CKT) / Crimson Tide (LON:TIDE) - up 10% to 179p (£12m) - Possible offer for Crimson Tide - Graham - AMBER
An interesting suggestion from Checkit that they merge on an all-share basis with Crimson Tide. It does seem that the two companies may have potential synergies but the emphasis on stock market valuation multiples, liquidity and the investor base suggest to me that Checkit is at least partly motivated by possible future fundraising efforts. I agree with TIDE's Board decision to reject the proposal. It's now up to TIDE shareholders to have their say.
Gooch & Housego (LON:GHH) - down 4% to 550p (£142m) - Interim Results - Graham - AMBER
This photonics company posts weak-looking interim results but it's important to point out that full-year expectations are unchanged. The company continues to pay out dividends, despite net debt, even slightly increasing their interim dividend due to confidence in the medium-term outlook. For investors who share their confidence now could be a fine entry point. Personally I'd maintain caution after several years of lacklustre financial performance.
Chemring (LON:CHG) - 395p (£1.07bn) - Half Year Report - Paul - AMBER
Shares have shot up recently as the defence sector gets re-rated up. H1 figures are not brilliant, with profit down 10%, but a very large order book and positive outlook suggest a better H2. PER of almost 20x looks up with events to me. Balance sheet is surprisingly capital-intensive with particularly large fixed assets and inventories. Big shareholder returns funded from increased debt upsets me. Bright future considering European countries are now re-arming. Price now up with events I think.
Eleco (LON:ELCO) - 117p (£97m) - Q1 2023 [sic] Trading Update - Paul - AMBER
In line with expectations, which isn't enough for me, given how expensive the shares are now looking. It's a nice business, showing reasonable growth, and a high proportion of recurring revenues. My only quibble is with the valuation, that doesn't offer me good enough upside to want to get involved.
Venture Life (LON:VLG) - 41p (£52m) - Trading Update (AGM) - Paul - AMBER
In line with expectations update. I've never been keen on this share, but it's starting to look a bit more interesting now.
Paul’s Section:
Chemring (LON:CHG)
395p (£1.07bn) - Half Year Report - Paul - AMBER
Shares of this defence group have reached a new 5-year high.
The £1,041m order book certainly jumps out of the page at me.
Record order book, full year expectations unchanged, strong long-term prospects
H1 revenue is up 8% to £223m
Adj PBT £22.7m (down 10%)
Adj diluted EPS down 11% to 6.6p
Net debt has shot up to £75.3m (from £25.0m a year earlier) which it says is due to capex, but it has also been doing a big share buyback.
Outlook - aspiration to raise revenue to £1bn by 2030, about double forecast FY 10/2024, which includes assumptions about further bolt-on acquisitions.
The Board's expectations for 2024 are unchanged, with heavier H2 weighting of operating profit as previously communicated in February 2024. Approximately 93% (H1 2023: 90%) of expected H2 revenue was in the order book at 30 April 2024
Valuation - broker consensus is shown on the StockReport as 20.2p for FY 102/2024, giving a PER of 19.6x
Balance sheet - is surprisingly large, so this is quite a capital-intensive business.
NAV is £351m, and becomes NTAV of £226m after deducting the 3 types of intangible assets (mostly goodwill from acquisitions, but also includes £17.5m in capitalised development spend).
Fixed assets (property, plant & equipment) is very large at £261m.
Inventories seem excessive at £124m, so asking management why is a key question for any webinar or meeting.
Cashflow statement - H1 saw operating cash inflow (after tax) of £19.1m, which was more than all absorbed by heavy capex of £34.2m (a big increase on the £11.6m in H1 LY). It also spent a lot on shareholder returns, which surprises me, given that it generated negative free cashflow due to the heavy capex. £12.5m was paid out in divis in H1, and a large £29.7m spent on buybacks, funded by increased debt - not something I approve of. Buybacks should only be done from surplus cashflow in my view, not funded by debt.
Overall then I do have concerns over management strategy to fund shareholder returns from debt, whilst also spending heavily on capex.
Paul’s opinion - only a brief look, but I can see why the shares are doing well, given the large order intake and £1bn order book, giving nice visibility. Defence-related shares have been buoyant lately, due to the ongoing Ukraine war, and the well-publicised need for hollowed out militaries in Europe to be rebuilt.
That said, the H1 figures in isolation are not particularly good, with profit down, but the longer term trend looks good -
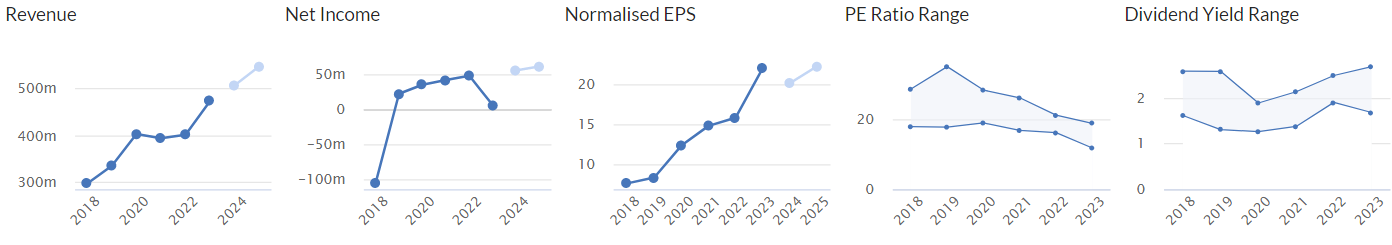
I’d say the price now looks up with events, and it needs an ahead of expectations trading update in future to propel it further, in my opinion.
So good company, but a PER of about 20x seems fully priced to me. We’ve seen a similar thing with my favourite defence sector pick, Cohort (LON:CHRT) which has moved up from a PER of about 12 to also about 20x. Therefore this looks like a big sector move where personally I’d probably be banking the profits, having made a nice and fast profit. So let’s go with AMBER.
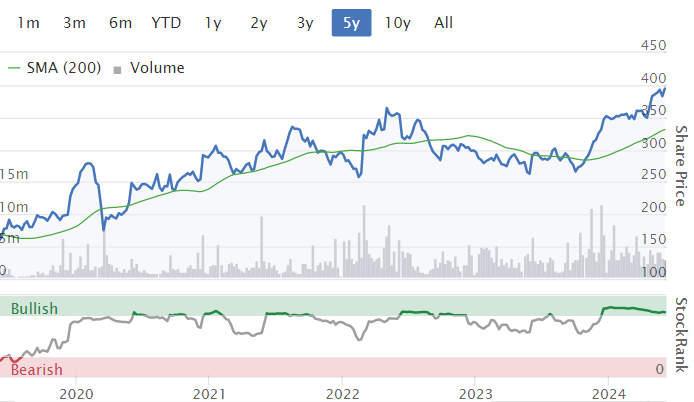
Eleco (LON:ELCO)
117p (£97m) - Q1 2023 [sic] Trading Update - Paul - AMBER
There’s obviously a typo in the heading and the main body of the text, which says it’s a Q1 2023 update, which of course should say Q1 2024. This is sloppy, and to me indicates that there isn’t a proper review process for issuing correct RNSs. They don’t seem to have issued a replacement RNS correcting it either. What other financial controls are weak, I wonder?
Eleco is a niche software business, for the building industry. It’s always struck me as a nice enough business, with a decent track record, but a puzzlingly high valuation. Software businesses are often valued highly, particularly where they have good recurring revenues, which ELCO does. There are frequent takeovers too, so private equity and trade buyers are often happy to pay up for growing software companies.
Results for FY 12/2023 were good, with adj PBT up 17% to £4.2m, and adj EPS up 11% to 4.0p (2023 PER of 29.3x)
Trading so far in FY 12/2024 is in line with expectations -
"We are pleased to report that the business continues to perform well with a solid trading performance over the first four months of the financial year. The Board remains confident in the outlook and trading remains in line with market expectations for the full year.
Share price - an unusual comment here on its own share price, which is not really the done thing. I prefer the line that we run the business, you set the share price, which is what most companies say to investors -
It is good to see that the hard work and delivery has started to be recognised in the share price, with a 45% increase over the past 12 months. We look forward to driving further growth across the Group in the years ahead."
Balance sheet - I checked back to FY 12/2023, and it’s not great, with c.zero NTAV. The cash pile of £10.9m has come from customers paying up-front, as is often the case for recurring revenues software companies. So not a concern, but if the company keeps doing more acquisitions without raising equity, then they're in danger of hollowing out the balance sheet, and leaving even less scope for divis (which are small).
Cashflow statement - also for FY 12/2023 is OK, but note that post-tax operating cash generation of £5.9m (less £0.6m leases further down, so it’s really £5.3m) was all spent on capitalised development spending of £2.26m, and acquisitions of £3.8m. This is why the divis are so modest at a yield of only 0.8%, because shares are expensive, and there’s not much available cashflow. Although the acquisition spending of £3.8m is discretionary, so theoretically if it doesn’t do any more acquisitions then it could afford to maybe double or triple the divis, but at this hefty PER, this is not likely to be an income stock. It’s more about growth.
Paul’s opinion - we’re told it’s in line with expectations for FY 12/2024, with consensus at 4.4p, rising to 5.5p in FY 12/2025, the PERs are 26.6x and 21.3x, so effectively we’re being asked to pay in full, up-front for the next c.18 months growth. Software companies are often valued highly, on stretched multiples of EBITDA, but that’s not a valuation method I’m comfortable with, I'll stick with PER.
Growth is good, but not spectacular.
Overall then I think ELCO looks a good business, but the shares seem expensive to me. I’d want an ahead of expectations update to justify the strong recent share price rise. Hence it has to be AMBER, but good luck to holders.
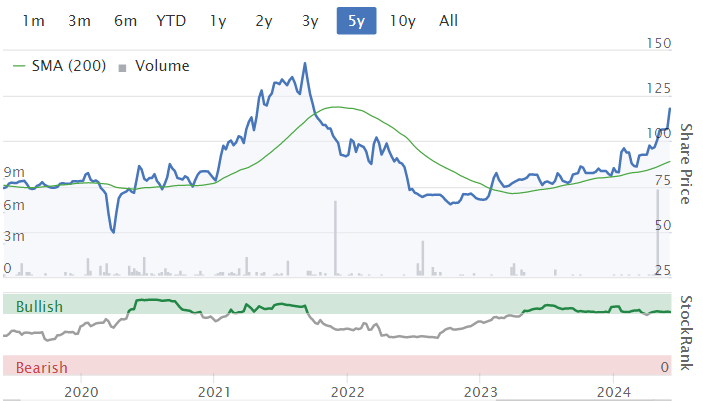
Venture Life (LON:VLG)
41p (£52m) - Trading Update (AGM) - Paul - AMBER
Venture Life (AIM: VLG), a leader in developing, manufacturing and commercialising products for the self-care market…
Trading is in line -
The business continues to perform well and our increased focus on promoting the VLG owned brands is delivering pleasing results, with an additional 35 new listings secured within UK retail since the beginning of the year. We remain confident about the outlook for the year ahead and our ability to deliver full year performance in line with management's expectations.
Broker forecasts - have been increased previously, which is usually a good sign -
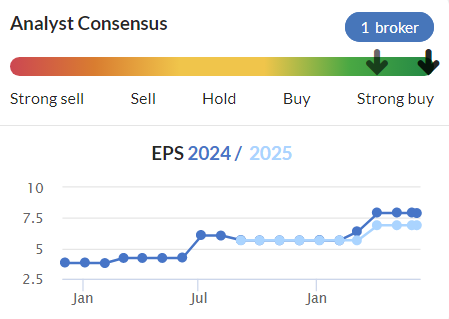
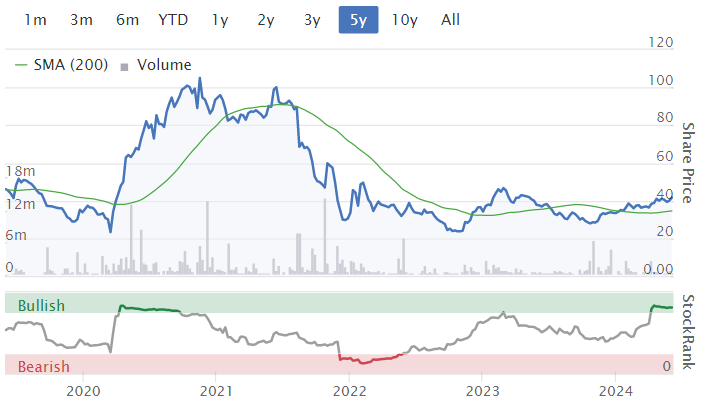
Paul’s opinion - neither Graham or I have thought much of this company in the past, due to figures being dominated by large adjustments, and it having too much debt. Borrowings are quite large, and shown within current liabilities, although an update on 19/4/2024 stated that they have been renewed for 3 years, which reassures me. Forecasts are now showing a nice trend of growth, and a low forward PER.
So maybe it’s time to give this share a fresh look? It’s always struck me as a rather peculiar company with opaque numbers, but on a fresh look today, it looks better than I expected. For now we’ll stick at AMBER, but if it gets another decent update under its belt, I might flirt with the idea of moving up a notch to amber/green.
Graham's Section
Crimson Tide (LON:TIDE)
Up 10% to 179p (£12m) - Possible offer for Crimson Tide - Graham - AMBER
This is an announcement by Checkit (LON:CKT), “the augmented workflow and smart sensor automation company for frontline workers”.
From a value perspective, I didn’t find Checkit particularly enticing when I looked at it back in September, due to ongoing cash burn. Income statement overview:
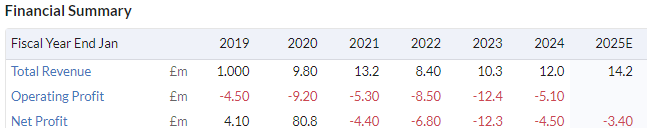
I’m surprised to find that it’s on the acquisition trail. Less surprising, given Checkit’s cash burn, is that there is no cash on the table for the bid target: only more Checkit shares.
It has been a while since we covered Crimson Tide (LON:TIDE), too: Paul was neutral on it last year. It owns mpro5, “a leading provider of personalised mobile workforce and field service management software solutions”.
The possible offer values each TIDE share at 7 CKT shares. In money terms that’s 182p, a 12% premium to last night’s close. TIDE shareholders would own 30% of the enlarged group.
Strategic rationale
At first glance, I’m inclined to believe that the two companies might be a good fit together. Here’s what Checkit have to say:
The board of directors of Checkit (the "Checkit Board") believes that the combination of Crimson Tide and Checkit presents a compelling strategic opportunity to create a scaled workflow software company and furthermore believes that a company of this increased scale would present a more attractive investment opportunity for all shareholders than either business as a standalone entity.
They go on to suggest that there could be “higher valuation multiples” for the enlarged company and improved liquidity.
But what about synergies between the company’s products? Checkit see cross-selling/upselling opportunities, and also:
The Checkit Board believes that the combination of Crimson Tide's and Checkit's product sets will, in due course, provide an enhanced product offering that will benefit both companies' customers.
Previous talks: some bombshell information is given regarding previous attempted talks. Here’s the timeline:
Jan 2024: Checkit submitted a similar proposal to Crimson Tide. TIDE rejected it.
April 2024: Checkit asked Crimson Tide for talks; TIDE said no.
Today: Checkit goes public to enable shareholder discussions.
Checkit CEO’s comment:
"The Checkit Board has long believed that the combination of Checkit and Crimson Tide is an obvious and positive strategic step for both companies. We believe it will position the enlarged entity as a market leader in workflow software solutions, leveraging the strengths of both organisations for enhanced profitability and competitive advantage whilst being more attractive to existing and potential new investors. Most importantly, the Checkit Board believes that the combination of the two businesses has the potential to deliver value for both sets of shareholders…
Graham’s view
The main point for me is that the two companies seem to have quite different risk profiles.
Checkit is the riskier of the two, and is more dependent on the stock market for fundraising.
Crimson Tide is more stable, with smaller losses. Its cash balance is limited at just £3.3m (Dec 2023), but they haven’t been burning it very quickly in recent years..
From Checkit’s point of view, thinking about valuation multiples (and maybe future fundraisings?) it makes sense to want increased scale and liquidity, and a broader investor base.
But from Crimson Tide’s point of view, it makes sense to me that they would want to carry on with their existing plans, instead of being 30% of a larger, probably riskier group.
So if I was a TIDE shareholder or board member, I’d be inclined to reject this proposal.
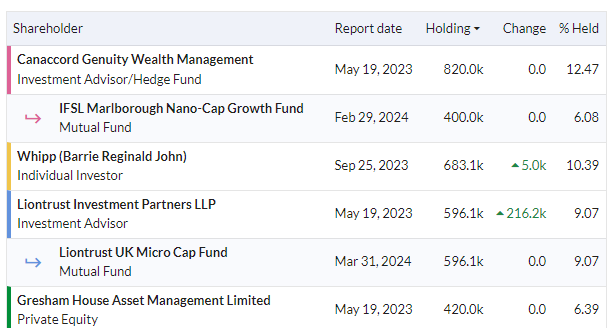
TIDE’s Chairman Mr. Whipp is a 10% shareholder, and it sounds like his answer is a definite NO.
Perhaps Checkit will be able to convince some fund managers of the merits of their proposal?
TIDE’s top shareholders:
Gooch & Housego (LON:GHH)
Down 4% to 550p (£142m) - Interim Results - Graham - AMBER
Gooch & Housego PLC (AIM: GHH), the specialist manufacturer of optical components and systems, today announces its interim results for the six months ended 31 March 2024.
This company is still quite disappointing in financial terms, with low profit margins only getting lower:
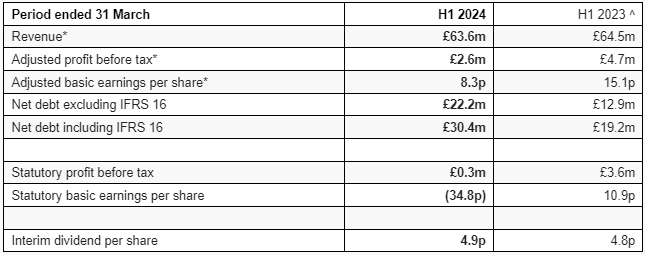
It’s an interesting choice to pay an increased dividend despite the net debt figures shown above. They do this “given the Board's confidence in the outlook for the Group and our plans to improve operating profit returns to mid-teens over the medium term”.
Key bullet points for H1:
Revenue down 5.3% on an organic constant currency basis. Destocking is blamed (GN note: this problem seems to have been resolved in several other industries, but not yet for GHH.)
Order book grew very slightly in H1, and “continues to grow, substantially de-risking H2 revenue”.
Full year expectations are unchanged; execution risks to H2 remain but have been reduced
CEO comment:
"Despite the reduced demand in our industrial and medical laser markets persisting longer than expected, the medium term outlook remains positive underpinned by a strong order book and healthy pipeline with the Group well positioned to benefit from increased demand levels as a result of operational and supply chain improvements.
"The market dynamics for G&H's technologies and capabilities remains strong in all our target sectors supported by the focused progress the Group has made to establish the foundations to accelerate the delivery of our strategy."
Outlook
Whilst reduced demand levels from our industrial and medical laser markets have persisted longer than we had expected we are well positioned to benefit from recovering demand levels which are now expected in the early part of FY2025…
In the first half of the year the Group started to reduce its borrowings which were increased in the second half of FY2023 to fund the acquisitions of GS Optics and Artemis. We have reduced our inventory holdings and expect to make further progress in this area in the second half of the year allowing us to reduce our borrowings further.
Our order book remains at a healthy level and we have substantially all of the orders needed to support the expected increase in revenues and profitability. The Group is involved in complex development and production programmes some of which are dependent upon inputs from both our customers and suppliers in order to progress to their expected timescales. Nevertheless, our expectations for FY2024 are unchanged.
Graham’s view
I’ve really wanted this company to come good for a long time, but the promised land of high margins and fat profits remains elusive.
Directors remain confident, continuing to pay out dividends and laying out in some detail their strategic plans for the future.
For investors tempted to nibble at it, here are the latest value metrics according to Stockopedia:
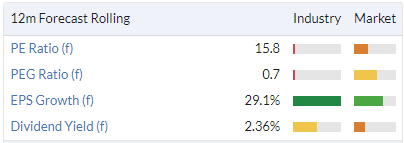
Once again, I can’t avoid a neutral stance on this one.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

90 comments
Surprised ARB is not down more on these numbers (I am short).
I had modelled a best case scenario of $5.6 million, and based this on 3 EH/s (the company has 2.7 EH/s) and an average of $60 hashrate (the hashrate was well below $60 for the month of May).
Even at those numbers the company isn't capable of operating without the begging bowl, and revenue for May was $2.9 million. It's entirely possible I've missed something so certainly open to hearing it.
.
Surprised to see Michelmersh Brick Holdings (LON:MBH) going below £1 with ex div date on thurs… anyone got any ideas?
Hi Graham.
Perhaps you could ask whether they see any risk to their business model from a prospective Labour Government clamping down on expensive lenders. I must admit to having been badly burnt by Morses Club!
Raspberry Pi IPO
One of my children has a Pi, and I can vouch for them being fiddly - I was quite surprised at the level of IT expertise required for what I had assumed was an "educational" product, but also impressed by how powerful they are.
Looking through the prospectus it is interesting to see that in their agreement with the Raspberry Pi Foundation they are obliged to maintain availability and are margin-capped on the retail units at manufactured cost + 20%.
The trading outlook has the H2 bias which is interesting for an IPO:
Since 1 January 2024, the Group has continued to trade in
line with the Directors’ expectations. Following significant
purchases in the last part of 2023 by customers, notably
from Raspberry Pi’s ARs and the Licensee, 2024 has seen
expected volatility in their demand, and in the case of some
channel participants and Raspberry Pi, this has led to higher
than usual levels of inventory. The Directors expect this to
normalise over the course of 2024, resulting in stronger
results in the second half of the year than in the first half.
260-280p is $600m-$650m, and 2023 proft after tax was $31.5m (up from $17m in 2022, so I would look at those late 2023 purchases carefully - is it AR's loading up on initial stocks of the Pi 5?).
Unit sales (of the main single board computer products) are actually down in 2023 from 2 years prior (7.39m in 2023 vs 8.47m in 2021). The finances have improved because they've switched away from resellers (terminating sales via RS in 2022) to selling direct for higher margin. Is there really strong growth to come?
I'd love the IPO to go well, and if they can milk their enthusiast base like Games Workshop (LON:GAW) then hats off to them (Pi users will get the joke...), I'm less convinced about them taking the industrial world by storm.
Question is whether you'd be better off buying Broadcom at a fwd P/E of 25x? I have to say I feel more enthusiasm for the product than the shares after a first glance through the numbers.
Graham,
In reply to your request for question for Ramsdens Holdings (LON:RFX). I have a very small holding, just based on the valuation being so low. I do not have high conviction however, I am fairly conflicted about the long term future of the business. So some questions / thoughts from me,
- The travel card does fit well with their foreign exchange part of the business. However I dont see any moat for them in this field. Holiday payment cards are now available from everyone & their dog. If the choice is price, then I am sure lots of the fincap / online banking can offer lower costs (although I think that many of these cards are mastercard backed, and I wonder whether there is any differentiation at all). If it is a question of trust & support, then there are also bigger and better names than Ramsdens.
- Cost of staff ? This is probably one of their big costs, and wage inflation might well be an issue - what changes have their (edit: there - doh) been in the past 12 months (and do they have any insight into the next year ? - this might well have a wider read across for retail businesses)
- Demographics of the pawnbroking business. To be fair, I have never used a pawnbroker in my life, so this business seems so alien to me that I can imagine anyone doing it on a regular basis apart from under real duress. The cost of living issue & increase in foodbank use may well give them a tailwind at the moment, but do they see this activity in a long term growth trend ? I can see the increase in the 'buy now, pay later' trends, are the young generation going to turn to pawnbrokers when they need cash ?
- Competition with H & T (LON:HAT). How do they see this developing ? Obviously they have their own strength of brand in the north east, are they targeting towns where competition is already established, or do they see enough opportunities to go around ? (I think that smaller operators / family businesses are probably in decline that might provide opportunities)
Ramsdens Holdings (LON:RFX)
I would add the note about the foreign travel cards, there was an article in Which - it was part of their weekly email, about the £billions that are left on the pre-paid foreign currency cards and how difficult it was for people to get the money back and the high fees involved for refunds. Opportunity for earning interest, but potential future risk?
Personal note on foreign travel cards. Barclays Rewards Visa card is a credit card that makes no foreign transaction charges (most charge up to 3%!) and gives a 25 bps cashback. Recommended by Martin Lewis I can't really see why anyone would want anything else (except, I suppose, the hard 'credit' limit of a pre-pay card).
cards for foreign transactions.
I agree the Barclays rewards card does not charge a transaction fee. They probably have higher exchange rate compare to Monzo which I prefer. Unless I use both simultaneously, it would be difficult to compare like for like overall costs.
Hello Graham.
Adding to cheeky_minnows questions on Ramsdens Holdings (LON:RFX) I seem to remember the Ceo in some recent public forum that they were disappointed with the expectations on the money they make from punters bringing back foreign currency and cashing them in. Ramsdens Holdings (LON:RFX) apparently have made good money on this in the past, though the CEO seemed to eb saying that punters were spending all their currency purchases and £TFX were losing out on what had been a significant profit source.....so please add this to the questions you put to the CEO tomorrow.
Going back to Graham again, I would like to get to the bottom of why you are so positive on Ramsdens Holdings (LON:RFX) because the share price is going nowhere, the forecasts are going nowehere. I can understand that you consider them to be safe and have some holding qualities...but no more. Please put me straight if I am missing something.
PS I quite recently sold them at a significantly higher price than current, after having held them for some time hoping they were going to show a higher SP projectory.
Hi ridavies, your question regarding currency purchases/sales was covered in the interim report published on Wednesday so I didn't include it, but many thanks for the suggestion! I'm personally positive on RFX because I like the company and the industry and I like the valuation at 8x PER. Of course that doesn't mean the share price is going to go anywhere in particular. The weak share price is what has brought it to this valuation! Cheers.
The FT published an interesting article on the number of hedge funds - often US-based - who have been badly burned by recent shorts in the UK market. Millenium Management, GLG and Gladstone Capital Management have lost as much as 50% of the nominal value of their shorts on Darktrace (LON:DARK; Hargreaves Lansdown (LON:HL.); and Keywords Studios (LON:KWS).
From the FT:
"Shorting any UK mid-cap is insane, literally insane", said one hedge fund manager who specialises in shorting stocks.
"The numbers (valuations) are just so low in the vast majority of cases, that a USD2 bn UK company is peanuts for any mid-sized American company. Your sell case has to be unbelievably compelling and feature the stock going down at least 50%, or there is a risk you lose 50% if the stocks is bid for".
The LSE reports bid activity 84% higher the first 6 months of 2024 compared to 2023. The FOOTSIE 100 trades at 12 forward earnings compared to 21.8 for the S&P500.
The most heavily shorted UK stocks are (in decreasing order):
BT Group 15.9%
Abrdn 14.7% (with a name like that they deserve to be shorted IMO)
Hargreave Landsdown 10.3%
Ocado 9.0%
Diversified Energy Co 8.9%
Pure Tech Health 8.4%
Auction Technology Group 8.2%
St James Place 8.1%
Smurfit Kappa Group 7.7%
Kingfisher 7.6%
Happy to keep buying the UK
(and Poland, Argentina, Sweden, Denmark and Norway, but not the US)
Presumably these hedgies have a strategy that generally works - i suspect if there is generally little direction of travel in shareprice their blunt force attacks are probably likely to win most of the time even if the rationale as to why they think companies are overvalued may be wrong from time time. Albeit no one wants to be left holding the shorting baby when shares soar. Being frank i suspect even then people running these hedge funds have their own ulterier motive to take risks if upside results in great bonus and downside is that they walk away and someone else picks up the bill.
Plus seems the common theme "going with the trend sell your losers " and that if you buy shares cheap and they go down on no news you should sell. whereas if you think share is flying and goes up more than you may expect then you should expect more (run your winners) - that strategy probably does work on brute force go with the flow basis - until well it doesnt and reality returns. It is amazing though for how long that carpet company share (carpetright?) was perennially overvalued - well until it wasnt years later - by which time most shorts had probably given up and moved onto shorting ocado or tesla.
Fitting that they missed off Marshall Wace, who seem to short anything with a pulse. 7 increases to short positions reported in today's short tracker data, including continuing to up their Burberry short to 2,31%, despite the shares being sat at 10 year support. I'd punt that Wace likely hold shorts in ~10% of LSE shares, perhaps even higher.
I don't know if anyone is following Incanthera (OFEX:INC)... They announced another increase in the pre-launch order for Austria and Switzerland (launch September). This is the second time the order has been increased. Tim McCarthy is saying (as of yesterday) they will comfortably exceed broker targets for YE 03/2025 which Stanford Capital Partners have down as £10M revenue. EBITDA 30%. They have also raised funds at 17,403, 681 shares at 15p a share plus warrants. ImmuPharma (LON:IMM) have sold their shares to an institution but retain their warrants. This has been discussed previously. I hold.
I've now been in quite deep with INC for a while. News and prospects keep getting better although it is annoying as retail to have been left out of the 15p raise. Of course it is still somewhat speculative since ultimately fhe initial Marionnaud orders still have to be following by strong consumer buying, however I believe it is rare to see such asymmettical risk/reward in an investor's favour even after a bit of a bounce form the 8p flatline and even without considerd the potential move from consumer to pharma or new applications for the delivery tech.
I agree. I'm in quite deep too. As you say, somewhat speculative without confirmation of sales and stock replenishment volumes. We'll know one way or the other by Christmas I expect.
I've held a small stake in Incanthera (OFEX:INC) since 2021 (13p) and first mentioned it here after the December RNS, when I topped up at 6p. There's clearly a risk, but the risk / reward seems to be getting better by the day and it has serious multi bag potential if all goes to plan. I've added several times this year from 10p to 18p and its now at my maximum investment size (8% of PF).
Today's interview by the Chairman is oozing with confidence. Lets hope its real and not misplaced.
https://audioboom.com/posts/85...
I would be wary of Tim McCarthy's positivity after having witnessed similar behaviour at Immupharma. Several years ago he made some very bullish public statements about their lead drug candidate which turned out to be worse than a placebo. The long term share price graph tells the story in all of its misleading hype and subsequent exposure.
Thank you for the cautionary note. Will keep in mind.
Apologies for OT post. However, I discovered something I was not aware of yesterday and wanted to alert others that use FCF metrics on Stockopedia. In particular, I was looking at the FY24 Burberry (LON:BRBY) cashflow statement and could not reconcile it with the FCF per share figure of 81.4p shown in the StockReport. It seems this figure is grossly inflated because Stockopedia do not include lease payments in the calculation of FCF. Just another warning that if something doesn't look right it's best to go back to the source, but it will effect screen results and possibly the Stock Ranking (assuming P/FCF is included in the V score).
Burberry (LON:BRBY)
only had a quick look but are you sure ?
per annual report free cashflow 63 mill bottom line (page 26)
addback capital expenditure 208 mill
thats 271 mill - used 366 mill shares per stocky (may be lower if buybacks?) that 74p per share - which to within 10% of the quoted figure - to get to 63 mill figur, e 235 mill of lease payments has been deducted so that line item is materially more than 10% difference. Per notes on stokcy it appears that capital expenditure is excluded from calcs not sure if that may be reason why you may have different numbers ?
I don’t understand what you’re doing here? If FCF is £63m and the market cap is £3.75bn then P/FCF = 3750/63 = 59.5 and FCF per share = 17.2p. Not the 81.4p shown on the SR.
Burberry (LON:BRBY)
you are correct in my haste i completely misread the stocky notes , my prior post was nonsense- lets have attempt number 2 here.
What is the definition of Free Cashflow ps?
Free Cash Flow Per Share is calculated from the Statement of Cash Flows as Cash From Operations minus Capital Expenditures, divided by the Diluted Number of Ordinary Shares Outstanding.
per page 26 of report 2023/24
1- Cash generated from operating activities £665 million in 2024
2- minu s capital expenditure £208 million
3- that leaves us with £457 mill free cashflow
As at 30 March 2024, the Company had 363,815,743 Shares in
issue, including 5,232,720 held in treasury
to get amounts per share
1- 665 mill divided by 359 mill shares = 185 pence per share
2- 208 mill divided by 359 mill shares = 58 pence per share
3- 457 mill divided by 359 mill shares = 127p per share
that still doesnt match stocky figure - doh - bad hair day here
ok the quoted £665 million cashflow is before Payment of lease principal and related
cash flows
that line item is £235 million - so if we were to include this line item as "operating activity expense" even though the acocunts dont do that
that would reduce 1 and 3 above by 65p per share each - that would be closer to stocky numbers - but lower than stocky - at 62p per share that is lower than the 81p quoted by stocky
perhaps i should give up here ?? - nothing would suprirse me ref any adjustments that may be deemed reasonable. what is the figure you calculated simoan out of interest ?
A brief looks seems that you have missed the cash flow from investing activities (rather big one and one needed for the company to operate!) and also any exchange rate outflows.
Operating Cash Flow 665m
=Free Cash Flow 63m
Divide by 363m shares = 17.3p
I always Add back dividends and buybacks as these are distributed to shareholders
All the best
Burberry (LON:BRBY)
I was simply trying to get back to the stocky cals and was following the very brief notes that stocky gave me to work on which seemed very specific (Cash Flows as Cash From Operations minus Capital Expenditures) - heck i dont even know what difference simoan had when they were trying to reconcile the figures. the problem with stuff like this is there can be any number of different ways of calculating metrics so i am shooting blind even if havent made any basic errors like i did in my first attempt - i would always say to anyone with doubts look at the annual report and that should somewhat clarify - i was working from annual report and i see wolf has been kind enough to provide all the workings i was trying to get back from so hopefully soem genius will work it be able to succceed where i have obviously failed . hey ho all good fun and games
I presume Stockopedia doesnt remove Repayment of Leases, as Simoan said, -231m so would come to free cash flow of 294m
Divide by 363m shares = 81p FCF ps which I think is the number on stocko
I am looking forward to seeing your view Paul on Synectics (LON:SNX, providing you get the time. The update is short and just says inline which does not make it a priority for a report.
Currently it is 5% down today. The rational for this is to me, the statement that the company expects a more evenly weighted financial performance in FY 2024. My first thought was, the second half of the year was not going to be as good as usual as it has traditionally been weighted to the second half. And so the share price has dropped. But I am thinking this is wrong. The second half will still be good, it is just that the first half was better than usual and that has made it more even. I think they could of worded it better. Over all there are a lot of parts to Synectics (LON:SNX, Oil and gas, Casinos, bus service security as well as some major city security. There is still a lot of potential for new growth, cash is good, an undemanding PE of 9 and a good Stock rank at 93. PEG at just 0.4
The company has a small market cap of just £32m. I do not think it will light up the world in terms of the share price movement, but will be a steady grower. One thing to watch out for is the liquidity, having only 17m shares in issue and just 28% of that in the public domain. EMS is just 500. Saying all this, any significant drop could well actually be a buying opportunity. Nav is 218p and the stock brokers target is between 230p and 280p. Currently you can buy at about 180p, so potentially there is a 28% - 55% increase in the SP to the current stock broker targets. I have to ask now whether this should be seen as a steady stock, that will grow slowly and at a reasonable price. They did go through a very rocky time during covid, but showed great resilience in controlling their costs without share dilution. Any thoughts appreciated.
Comfortably in line sounds reassuring to me with the possibility of an upgrade when results released. Here’s hoping . Could be a buying opportunity
Surprising drop in Synectics (LON:SNX) after comfortably in line statement this morning.
Probably only profit taking after a great run. IMHO.
Run your winners. V. Top slice. V. Cut your losers ??
In a bit of a pickle .
Am fully invested but now need to get some cash together for other project so have to do a little bit of forced selling .
I’ve got a couple of runaway winners that show no sign of abating (Filtronic and Transense ) but could top slice
I’ve a couple a couple where they’ve going sideways (avingtrans , vertu , wynstay )
Plus a few where I’ve been buying but are still on the lows (pennant , SDG)
I’ve never really had a runaway winner like filtronic so the temptation is to cut that by 5-10% but it keeps heading north with no sign of stopping so maybe “run your winners” is the golden rule .
mmmm, Might just nibble a few % off each so can’t make a wrong decision .
Or maybe let the winners run , and just slice the non performers .
Anyone got a strategy they’ve used ??
I tend to look at the bottom of the pile first if I want to raise some cash, so things in the red, maybe haven't moved while the market has been rallying, earnings downgrades, no news due for a couple of months etc.
Something like Filtronic I'd be loathed to sell before a dud, good price and earnings momentum, not overly expensive for the growth, trading update due this month?
That's probably wrecked the rally now :)
I'd also take into account June has been a hopeless month for AIM in the last decade, need to double check but I'm sure it's 10/10 for losses in June. Maybe different this year of course, certainly momentum is much better.
A dilemma we all face - If you were a FUND manager you are obliged to sell when a share tops 10% valuation - so many mangers must have been cursing for the past few months forced to sell Nvidia but yes at some point it makes sense to top slice. Good luck
Oh planetx, this is the 100m dollar question! I am in a similar boat to you. Normally when i sell, it's a mistake. And when I don't it's a mistake too! Currently I am sitting on a 63% increase in my PF for the last two years. I think you have to just look at the individual stocks you hold and ask yourself if you think it is over or under valued and whether you see if there is still more growth to come. A lot will also depend on whether you are going for growth companies or are just buying stock because they are under valued at the time. The stock you hold I would not like to comment on as I do not hold them and do not really know enough about them to comment. You may want to trim some though if you see greater potential in some other stocks. Best of luck with your decision.
Hello gmtrader,
Wow 63% up in a bear market, that's some going!
Regards
I've had the same thoughts. But - following a rethink, where when I started investing in my 20's 20 years ago or so, the basket of shares I bought included Microsoft, Google, Amazon, BAE, Unilever and Shell. Obviously, my amazing stock picking skills meant that within about 3-5 years I had turned 15k into about 60k.
I often think I should do an analysis and see how much that portfolio would be if I did nothing. But I think I would hate myself!
So, off I went sold, reinvested in some utter tripe and then had to restart my portfolio. I think Paul has mentioned that picking good stocks AND patience is what marks a good investor, as many get bored with sp drift and find something more racy as we want to make money quickly.
I'm firmly in the let your runners run so have a concentrated portfolio (under 20 shares), some are racy like Filtronic (LON:FTC) Beeks Financial Cloud (LON:BKS) . Some are plain boring, which I'm waiting for them to rerate whilst taking big divs, Reach (LON:RCH), Smiths News (LON:SNWS), Liontrust Asset Management (LON:LIO).
Obviously, there were drawbacks, see Shoe Zone (LON:SHOE) I've held for the divi (IIRC 26%), but have seen the price zoom up and zoom back down even faster, which I've then doubled down on, but I kept this on the basis I could suffer a profit warning and still be in the black.
That said, with interest rates where they are - I'm comfortable in keeping cash and holding it for opportunities, wherever they may lie, although I do find Sanderson Design (LON:SDG) and Card Factory (LON:CARD) too cheap as are various IT's and some IC's, Chrysalis Investments (LON:CHRY) and GCP Infrastructure Investments (LON:GCP) which also pays a decent divi.
I do also keep all of my investments in ISAs between the family, so aren't keen to invest outside of them so am 'limited' to around 50k pa, so your circumstances will vary greatly from me!
"many get bored with sp drift and find something more racy as we want to make money quickly."
Pulak Prasad talked about this in his book., "What I Learned About Investing from Darwin". It's an interesting easy read. I recommend it. He said that quality shares don't go up in a linear orderly fashion. They're prone to have dull periods interspersed with breakouts. The real gains are made during those breakouts. You can't time them, though. You have to hold and let chance take its course.
I felt that this was the case of BMY earlier this year. The news was good and the stock put on a good gain. A prominent investor declared its good quality, which further fuelled the gains. The sentiment changes a little, and someone declares that prices are up with events. Acting cautiously, the market brings the price down. Then BMY announces a major acquisition which ignites a little interest again.
Then the brokers upgrade their forecasts. In May, the 2026 forecasts were 30.58p. Now they're 40.41p, a major uplift. Then you start having a situation where the valuation don't look so stretched after all.
I don't know if the acquisition will ultimately prove a good idea or not, although I do hold shares in BMY, so obviously I'm bullish.
I think it boils down to this: do I think I own a good quality company is liable to grow over the next few years? If so, then impatience is likely to be your enemy. It means being able to hold when the shares have been going sideways for awhile.
I think a good heuristic is: if you think valuations are a little high, then you should continue to hold. Only sell when you think valuations are egregiously high, or you think you have mis-evaluated the quality of the company, or if that quality has materially deteriorated (like taking on too much debt, poor prospects, etc.).
I would keep the shares going north and cut your losses on the losers. I recently cut my losses on 'BEG' (Begbies Traynor), 'HEAD' (Headlam) & 'WJG' (Watkins Jones) and used the money to buy into those shares repeatedly going north - ie. 'W7L' (Warpaint London), 'ZTF' (Zotefoams) and 'CHRT' (Cohort) and feel a lot better for it.
I put my losers in a folio, 1st May, folio is up 9% now. It did have Keywords Studios (LON:KWS), but even excluding that it is up 5.4%, this has outperformed my other folios. I feel a lot of my winners are levelling off and the laggards are catching up.
Mind you, Watkin Jones (LON:WJG)'s recovered quite a bit from that fall last week.
I keep Watkin Jones (LON:WJG) in the part of my portfolio for companies which i think stand a good chance of multibagging back to nearer historical norms.But anywhere in the next 5 years hopefully.So backburners that i like but can't be bothered to try time and keep an eye on (ie. probably can't do it well and personally sometimes i totally lose interest in following markets as a hobby) and could move in fast spurts when/if they do.And if that happens i wouldn't say no to a potential couple of bags in a few years.
I always run my winners ... sometimes for years. I don't own Filtronic (LON:FTC) but I would run it. Why "cut your flowers and water the weeds"? (apologies to Peter Lynch for the possible misquote). The only reason to sell for me is diminishing metrics (I sold Judges Scientific (LON:JDG) for this reason ... several years of declining ROCE); the story changes; there is change at the top that you don't have faith in; or there is some cataclysmic change in the market that was unforeseen. I never sell on valuation grounds and if I see a better opportunity I will always sell the underperformer in my portfolio.
Ohhh planetx it’s the ever present conundrum…..Recently after reading here I wanted to buy into QQ……No spare ISA cash so what to sell ….So looked at losers….EXR out (down 50%)….but LGEN (well it’s a decent divi) so keep,, AV. same sentiments ..keep….Ok let’s top slice then..CCL…up 37% , RR. Up 312%….why sell so keep…..Not doing very well here…..HBR down a bit and like a yo-yo but excellent divi and due in the next few weeks…so keep…..What’s left ..BP. Nice divi but share at roughly the same price as when bought 2 +years ago…Just gone XD …….So sold all and bought as many QQ as I could …It’s an odd number of shares x950….but if they keep flying up (already up 20p) I can sell the 950 as a top slice for a decent re-investable amount and retain the x,000 and run them………Is this a strategy ….I doubt it very much but so far it’s worked on this occasion …….Good luck and Happy decision making …..Penny
I would sell the smallest holdings first . They are small either for lack of conviction or because they were big in my earlier life!
They do not contribute much to the portfolio and take a disproportionate share of my time.
My personal experience is that, invariably, whichever strategy I choose it's the wrong one. Therefore if selling a holding it is best to never again look at the share price.
A "strategic" offer today from Checkit (LON:CKT) for Crimson Tide (LON:TIDE). I hold Crimson Tide (LON:TIDE). I don't know if anyone else here is interested in either of these companies. The bidder thinks he is buying lots of cross-selling opportunities. The biddee is not playing and presumably thinks that the Crimson Tide (LON:TIDE) software will have second place in the enlarged group. Crimson Tide (LON:TIDE) share price has gone nowhere slowly during the past decade, on the other hand they have built what looks like a business with prospects during that time. The proposed terms look to me cheapskate. Anyone else have an opinion?
This is really interesting on several levels.
I know Checkit (LON:CKT) but not Crimson Tide (LON:TIDE) . I know Checkit clients are mainly hospitality businesses, and fairly large businesses. Is it the same with Crimson Tide?
The cynic in me thinks this is somewhat a last roll of the dice?
Checkit was heavily loss-making, and not expected to break-even for a few years. Has a cash pile that will sustain burn for another 2-3 years.
I see Crimson Tide isn't exactly super profitable either, also cash burning?
Not quite sure I want to back the combination of two massively loss-making companies, unless the cost stripping plan is sound or there's a quick acceleration of the growth rate.
Also I am curious that Daley would give up quite a bit of control with this extra share dilution. Maybe the situation is quite grim and desperate at Checkit...
Don’t think the situation is remotely grim at Checkit (LON:CKT) Boon. The ARR and growth alone is excellent and they will be cash flow positive long before they run out of money. The projected low point still leaves them with a couple of years of runway.
The strategic logic is obvious to me - this is about two businesses that are too small to be on any radars and with Crimson Tide (LON:TIDE) they can cut substantial costs and accelerate profitability. So if you bolt them together and move to cash flow positive quickly you’ll have a £50m+ market cap which opens up a much richer array of opportunities. Do it now before the market turns any further upward. And really you are giving away 30% to achieve it. Assuming you consider the Crimson Tide (LON:TIDE) software good then that’s not a terrible idea.
I agree that on the current management plan, while break-even/profitable for Checkit (LON:CKT) is a few years away (2026? 2027?) they should have enough cash runway. But I am a pessimist, that there will always be something that comes along that derails the nice Powerpoint management plan....
And for me, that thing to derail could be this acquisition of Crimson Tide (LON:TIDE) . For this acquisition to make sense, I also believe it is about the synergies. That means some cost rationalisation (ie cutting roles) and also training each other's sales and marketing staff to sell both brands.
Growth / new acquisition of clients is already such a big time-consuming job for all divisions in a company. Now we add on the turmoil of a transformation to cut costs, rejig operations.... can they juggle both successfully?
Checkit (LON:CKT) (I hold) is the result of the renaming of Elektron, back in 2019, following the sale of its Bulgin subsidiary and acquisition of Next (not that one). That made a handsome return for shareholders (I held). The driving force behind Elektron and Checkit is Keith Daley, 19.9% shareholding in Checkit, so an investment in the business is both a belief that it has a viable offering in a potentially large market and a belief that he can maintain the business success he has delivered previously. Checkit's share price performance has been poor, as it builds up scale. Unlike Crimson Tide (LON:TIDE) it has a significant USA presence, so that offers a potential widening and deepening of the addressable customer base, in addition to the apparent synergies that exist from a combined group in their UK operations.
Yes, I held Elektron back then. I made some money, but not as much as I should have done because quite a large slice of the Bulgin proceeds was paid as a signing on bonus to the Elektron chief exec for moving with the business. Outrageous, but true! I sold out at that point in the belief that the 'crown jewels' had been sold (the Bulgin business), leaving a 'blue sky' load of nonsense behind. Nothing that has happened since then has changed my mind. Putting two cash burners together looks a bit desperate to me, as Boon says. Do the two businesses even operate in the same space?
I hold Crimson Tide (LON:TIDE) and like the chairman am against the offer. While loss making in 2023, it was cash flow positive and although they intend to use some of the £3.3m cash to invest in marketing, it's clear that they have enough cash to see them through to profitability and so as Graham says above, it has a much lower risk profile. Checkit (LON:CKT) , while having stronger growth in FY24, was also both significantly loss making and cash flow negative. They also only claim to have enough cash to see them through to cash flow breakeven (not profitability) in FY27, so there seems little attraction in the much riskier CKT paper.
There remains execution risk to Crimson Tide (LON:TIDE)'s growth plans but profits are forecast to grow from just above breakeven at £0.1m in FY24 to £1.9m in FY26, with earnings of 31p. The latter is of course a long way out but it illustrates the gearing from having gross margins of 86% in 2023.
Also TIDE's strategy is to sell through partners and it's not clear what Checkit (LON:CKT)'s approach would be, so until '... the significant potential revenue and cost synergies identified' are clarified, I am wary of the claim.
Perhaps the most damming side of the offer is that with CKT's shares down 2p to 24p, the premium has evaporated and if the shares were to fall further, Crimson Tide (LON:TIDE) shareholders would be selling their shares at a discount to the pre-offer price
I also hold TIDE and am very unhappy about this move. Barrie Whipp, after spending some time out helping Wey Education get sold off, returned toTide. He had been overseeing a SAAS-based expansion that can be accomplished within their cash resources, and the steady if unspectacular moves continue to show progress. I believe that a sale is in TIDE’s future but at a price more like double the current level.
To be fair to TIDE the announcement does say '... the Checkit Board notes that the Crimson Tide Board has on multiple occasions refused to engage in constructive discussions regarding the Possible Offer.'
That does tell you that TIDE's board don't think much of the offer and that's likely to be for the reasons set out above.
The decision to go public seems intended as an appeal to large shareholders to cajole management into talks but without a cash element to the bid, I don't see any reason to hold CKT's paper over that of TIDE's, so the RNS seems a little desperate to me and also alienates TIDE's management further
Liontrust Asset Management (LON:LIO) Deutsche Bank cuts to sell, target 600p.
Interesting timing! Doubt it'll make the 250 now? Also interesting as DB has been banging out buy recommendations for loads of UK companies last 2 months.
Also thanks Wolf
Seems odd and, as you say, interesting timing given the 250 was just about to roll……
Liontrust Asset Management (LON:LIO) with these retail-focused fund managers, it's worth looking at their largest funds to see how they're performing as that will be a key factor in driving flows. LIO doesn't look great with many of their key funds 3rd and 4th quartile over most periods - their last trading update actually has a table showing all this.
My main issue with LIO is their funds look very generic, and in the fund management space you really need to stand out with more specialist funds - Polar Capital Holdings (LON:POLR) and Impax Asset Management (LON:IPX) look good in this regard. From what I can see LIO are still experiencing quite heavy outflows, and while they could see a short-term pick up if sentiment improves, I do feel this sort of company will face longer-term headwinds from the rise of passives and pressure on fees.
Northern Bear (LON:NTBR)
Ok looks like Jeff Baryshnik has exited the building here with announcement today that his shareholding has gone from over 8% down to zilch.
Its not news that Jeff was selling down as this had been flaged up previously with the company even doinga tender offer to assist his exit - he turned up in 2019 bought big slug of shares and he was appointed to then board with hopes of the company being more investor friendly. I think he paid just over 70p for his main chunk so looks like he has thrown in the towel and either got bored or perhaps satisfied himself that for whatever reason he would rather be invested elsewhere. It was alla bit random as i think he is based in canada so it was rather an odd choice of company to take an interest in.
Its perhaps somewhat surprising the shareprice hasnt been on its knees whilst he has been selling down , although perhaps the recent tender assisted there - im not convinced the share will "pop" now the overhang has gone - but perhaps his flagged selling up may have perhaps put lid on price? Stocky has the p/e at 4.1 which is pretty undemanding for company that has delivered reasonably consistent clean numbers over the last 10 years if we ignore intangible w/offs - note they have spent a bit on acquisitions over that time so they have had to splash the cash a bit to stand still.
i suspect it will be pretty much business as usual here - perhaps Jeff Baryshnik leaving removes one unecessary complicating factor that may have put others off investing.
Most recent trading update here was very much tickover - company doing fine albeit results affected somehwat by high rainfall.
Very weird drop in Liontrust Asset Management (LON:LIO) by 5% this morning on no volume and for no reason. Seems strange - did it not make FTSE250 perhaps and dropping back on that?
Agree, very strange. Finals not due until the 26th.
Liontrust Asset Management (LON:LIO) Deutsche Bank cuts to sell from hold apparently
Deutsche Bank today downgraded Liontrust Asset Management (LON:LIO) to ‘Sell’
Price target now 600p
This alongside it’s potential miss in the FTSE250 reshuffle later today may be contributory factors
Thanks AstonGirl.
Drop makes sense now. Bizarre Sell note from DB imo. Asset Managers trade mid cycle on 13* PER and Liontrust Asset Management (LON:LIO) are currently on 9
So DB must think that EPS is going down yet the forecasts are for it to go up which makes more sense given AuM is on the increase.
A 600p price target against an eps of 75p+ would be very unusual rating for an Asset manager and as we move into a bullish market even more so.
The sceptic in me wonders about the timing of that research note.
EDIT : and just goes to show how people can vary : I have a personal PT of 1100p+ :D
It does feel like market manipulation to me given the timing of Deutsche Bank's downgrade of Liontrust Asset Management (LON:LIO) as they were/are expected to join the FTSE 250 today. This call is also contrary to the majority of brokers who cover Liontrust and who are generally positive.
Although there has been net withdrawals from AUM I understand that these have been more than offset by increases in their equity prices.
Given the downgrade it does also feel like a bet against the British economy. However this feels mistaken to me bearing in mind the recent good figures for GDP and Inflation; which suggest that the opposite is true and that the economy is turning a corner. This will be very much to the benefit of economically sensitive firms like Liontrust.
Absolutely feels like dark market forces at work at Liontrust Asset Management (LON:LIO)
They won't be able of keep it out of ftse250 for long as inflows to the UK have recommenced now. Read the HSBC piece I posted in an earlier SCVR.
I'm happy to grab the 9%+ yield on offer here.
Very unusual, I've had a look online and can't see anything. I think you are correct David and it is linked to missing out on the FTSE250. Some weird price action the last few days, it almost appeared as if the price was being manipulated down in advance of the date to ensure it missed out. Got me thinking who might want want to keep the price down... maybe a big player wants to load up prior to them getting back in! Always impossible to predict what is going on behind the scenes. I think its a good opportunity to top up myself.
Edit - Thanks all for the Deutsche Bank info. That would explain the drop
what are your thoughts on the Raspberry Pi IPO?
I looked into this yesterday and could find nothing definitive. I was concerned about cheap chinese knockoffs. What I could glean is that the chips (broadcom), are hard to get unless you are an approved customer.
So I have taken a punt on it, not a huge one. we'll see what happens.
"Revenge travel is losing its appeal.
After three years of rushing to book trips in the wake of pandemic-era restrictions, sharply higher fares, protests against tourism, fatigue from endless hours spent in airports and incomes squeezed by inflation are all taking their toll.
Travel demand is far from falling off a cliff. But there are signs that our wanderlust is downshifting from never-ending to a more normal pattern."
"European consumers are still prepared to pay as much for their package holiday – well almost. TUI’s summer pricing is up 4%, close to the 5% increase reported a year earlier. But budget airlines Ryanair Holdings Plc and EasyJet Plc show that when it comes to air fares, consumers are reaching their limit."
"Michael O’Leary, chief executive officer of Ryanair, forecast that fares across its network this summer would be flat to 5% ahead, down from his previous prediction of a 5% to 10% increase, surprising given that capacity is constrained by delays to Boeing deliveries. Europe’s largest low-cost carrier has begun to cut ticket prices to fill its fleet."
Source: Bloomberg https://www.bloomberg.com/opin...
A subscription site but I believe there are three free article views per month.
My limited view doesn't really see this. Business demand seems very strong and my company are seeing significant inflation on both airfares and hotels. I think it continues to be mainly supply side though and given you can't suddenly find a few thousand planes it'll take a few years to sort out. I don't like Airlines as investments as I see them as a boom bust industry but I would imagine these are the boom times.
Air fares are up a lot and the airports have been a nightmare with various strikes. I like travelling but wont be doing so much this year.
As a frequent flyer with Easyjet to Faro, I am seeing price of flights rising and the costs of things like cabin and hold luggage going up hugely in percentage terms.
The total costs of recent flight quotes from Easyjet meant BA has actually coming out cheaper on numerous occasions.
Raspberry Pi, the U.K. maker of low-cost computers, is expected to be worth up to 540 million pounds ($688 million) when it floats on the London Stock Exchange next week.
Peel Hunt said Monday that the price range for shares will be 260 pence to 280 pence and that the final price will be outlined on June 11, when the company will start conditional trading on the London Stock Exchange. Unconditional trading is expected to start on June 14.
https://www.morningstar.com/ne...
Hi eParo, On AJBell and ii I have had info with a 10/6 (IIRC) closing date for Raspberry Pi
edit: I read 'Any news', instead of 'Any views' - can offer no excuse!
Raspberry Pi IPO open. Price range 260p to 280p value between $600m -$£650m, with a turnover of $266m that gives a price to turnover ratio of 2.2 - 2.4, which seems reasonable for an IPO as most of the time it's a lot higher.
Raspberry Pi - I was so amazed at their reported high turnover, I had to have a look at the website to see what else they sell other than the mini computers. I've come away still puzzled how the turnover is so high for such a limited appeal, very select product. My son has one and they are fine but his interest soon waned. The websites reported 'industrial' application for the PI also has massive competition for a whole raft of huge household names.
I know a few people who use Raspberry PIs for streaming music, they are cheap if a bit fiddly to set up. Here are some uses: https://www.pcworld.com/articl...
I don't find the revenue that high. These are worldwide not just the UK. Only sold 5m Pis last year because of a chip shortage.
Response moved to a primary post given other comments scattered around
The Raspberry Pi foundation started off as an educational org to educate the young in computing and programming. It's so much more now, I use them for servers in my homelab, the single board computer and the system on module have industrial uses. The foundation will still exist as a charity after the IPO. What gives Raspberry n advantage is the open source community that develops and sort problems out, which other products lack.
My morning smallcap tweet: Fool injectioned performance
Mission (LON:TMG) Checkit (LON:CKT) Deltex Medical (LON:DEMG) Plant Health Care (LON:PHC) Quantum Blockchain Technologies (LON:QBT), Synectics (LON:SNX), Eleco (LON:ELCO), Venture Life (LON:VLG), Gooch & Housego (LON:GHH)
◄Mission (TMG)► Brave Bison's revised offer (equivalent to 35p) undervalues Mission but it is evaluating it. [SP=24.8 Cap=23m]
◄Checkit (CKT)► makes possible all-share offer for Crimson Tide worth 182p. [SP=24.6 Cap=27m]
◄Deltex Medical (DEMG)► new TrueVue System selected by NHS Supply Chain as a pre-approved device that can be purchased by NHS hospitals. [SP=0.12 Cap=2m]
◄Plant Health Care (PHC)► a range of new crops approved for foliar applications of Employ in California BY Wilbur-Ellis, one of the largest U.S. retailers of agricultural products. [SP=6.25 Cap=21m]
◄Quantum Blockchain Technologies (QBT)► receives the €700k First Sipiem Settlement. Pays €170k to the Receiver. [SP=0.95 Cap=13m]
In line: SNX, ELCO, VLG, GHH
Tritax EuroBox (LON:BOXE) RNS landed late yesterday confirming Brookfield Capital sniffing around. EuroBox confirm they've not yet been approached. Always strange how share prices rise before the RNS announcements land. Still seems very cheap with decent dividend.
Big refinancing delta with this one. Debt is currently around 1.25% and will jump 3-4x at refi, albeit I think they have a few years before they’ll need to,
Tritax EuroBox (LON:BOXE) Quite large debts to refinance though which at the moment are at very low rates. Divi not sustainable after refinancing IMO. I hold
The potential acquirer has a $100bn warchest so this sounds very promising. https://bam.brookfield.com/press-releases/brookfield-asset-management-announces-strong-first-quarter-results-0
And the chairman of Brookfield, a Canadian by the name of Mark Carney, knows his way around London I believe ;)
Tritax EuroBox (LON:EBOX) H2 presentation on IMC here if you missed it a couple of weeks ago. I did! As Robert W says there is a looming debt to sort out just like Saga (LON:SAGA) and Regional REIT (LON:RGL) which is probably suppressing the share price and creating the discount but therein lies the opportunity if the property market has bottomed out…(I hold)
https://presentations.investor...
which other companies are trading at huge bargains and could attract such interest i wonder?