Small Cap Value Report (Tue 5 Feb 2019) - WATR, AMO, RM., OTMP, CPR, EKT, SSTY, GMAA

Morning all! Paul here.
Sosandar interview
Just to say, my interview with Sosandar (LON:SOS) management (in which I hold a long position) has been delayed until next week, due to delays from my side collating all the questions & planning the thing. Sorry about that. So there's a window for any late questions from you - please add any additional questions into the comments section below. Thanks.
Buying opportunities?
I've been mentioning for a while, how the recent market sell-off seems to have been fairly indiscriminate in nature. This has created (selectively) some smashing buying opportunities. Indeed, we're seeing strong rebounds in some shares recently, on reporting good news.
Some people like to imagine that the chart tells us everything about the company. Sometimes it does (e.g. if insiders are selling, due to a poor outlook), but sometimes it really doesn't, especially with small caps. All the chart is actually telling us, is a gauge of the current balance of investor sentiment. In a small cap that can be the actions of just a handful of people transacting in the marketplace. Everyone else is doing nothing - as the bulk of the shareholder base will not be transacting at all, most of the time. Institutions generally don't buy in the market for small caps, because there's inadequate liquidity. Buyers & sellers could be backed up, unable to trade in the size they want.
Put this together, and it means that, at times of high investor anxiety over macro factors, small cap prices can deviate considerably from what is logical. Therein lies our opportunity.
Here's a great example of what I'm talking about;
Water Intelligence (LON:WATR)
Share price: 396p (up 10.0% today, at 08:19)
No. shares: 15.23m
Market cap: £60.3m
January corporate transactions & technology update
Water Intelligence plc (AIM: WATR.L), a leading multinational provider of precision, minimally-invasive leak detection and remediation solutions for both potable and non-potable water is pleased to announce a series of corporate transactions that reinforce its growth trajectory for 2019 and beyond.
Several actions re franchises are mentioned. I like the bit I've bolded below;
These transactions underscore that American Leak Detection ("ALD") and UK-based Water Intelligence International ("WII") business lines are complementary and growth is accelerating.
New product launch - this sounds intriguing, I'd like to find out more about this, to assess the potential scale of the opportunity ;
Formal launch of ORCA municipal sewer product into the United States following trials at a UK water utility
Trading update - it sounds like they're not quite ready to put out FY 12/2018 figures, but give a positive steer;
A broader discussion will be set out in the next few weeks with a 2018 Trading Update that reinforces our previous strong guidance. The Company is currently closing its December franchisee royalty reporting on schedule.
Directorspeak - the Exec Chairman sounds very upbeat today. When management make very bullish comments, it's important to check back and verify their track record - i.e. what did they say in the past, and how did reality actually pan out? Serial over-optimists are best avoided. I don't know what the track record is like here, perhaps any readers who are more au fait with the company could comment on this?
Dr. Patrick DeSouza, Executive Chairman, commented: "We are off to a fast start in 2019. These transactions unlock significant shareholder value both from synergies and expansion into new offerings.
Water Intelligence is scaling operationally with multiple business lines and can execute such complementary transactions again and again going forward to reinforce sustainable growth - an objective that I have previously stated.
It is important to remember that given the size of the global water and infrastructure market that we are just at the beginning of creating significant shareholder value with a great company and brand. I look forward to updating the market on our 2018 results."
Bold words! Let's hope it pans out as well as Mr DeSouza suggests.
My opinion - the share price already factors in a lot of good news - the PER is very high, at 33.6 times 2019 forecast earnings. That leaves no room for disappointment. Investors clearly like, and believe, the growth story. A PE rating in the 30s is getting into territory where investors are pricing in above expectations earnings growth.
It would be good to find out more about the new sewer product. If that has potential to become a major, highly profitable product, then the current PER looking high doesn't matter.
Going back to my point in the intro, here's a chart which dropped in the broad market sell-off, but should not have done so. Well done to holders who ignored the market's background noise! How about this for a rebound;
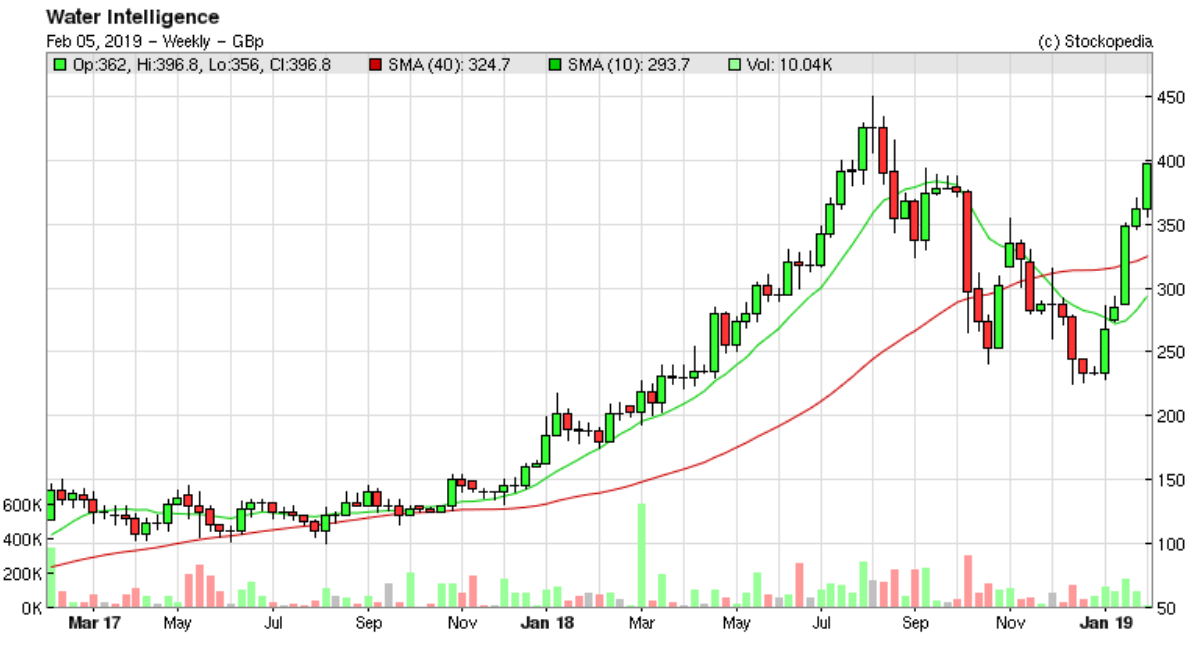
This is a great example of how, in small, illquid shares, the chart can at times become completely detached from fundamental reality. Only traders dealing in the tiniest quantities, would have been able to sell, and buy back at the right times - and only then if they were lucky with regard to timing. Plus 2 lots of the wide bid:offer spread would make it hardly worthwhile.
This is why, if I'm absolutely certain about a company being a long-term winner, then I tend to just ignore the market price gyrations, and suffer the pain of any drawdowns.
Amino Technologies (LON:AMO)
Share price: 91.5p (down 15% today, at 09:28)
No. shares: 72.8m
Market cap: £66.6m
Final results (and 2019 mild profit warning)
Amino, the global provider of media and entertainment technology solutions to network operators, announces audited consolidated results for the year ended 30 November 2018.
Poor figures for 2018 are out today, but this is as expected. FinnCap says today in an update note, that the numbers are in line with the Oct 2018 profit warning (see chart below), and an update in Dec 2018.
I've double-checked to my notes on the profit warning, here on 8 Oct 2018, and the figures & comments are indeed very similar to what's in today's results announcement. Good thing I decided not to catch that falling knife, as the share price has fallen from 148p (down 30% on the day) on the morning of the Oct 2018 profit warning, down a further 38% from 148p to 91.5p today. Is it starting to get into interesting territory, valuation-wise? I think it's starting to look potentially interesting. Let's go through the figures.
Dividends - this is the main reason to take an interest in Amino. As they promised, the dividend has been raised 10% to 7.32p. That must be the small interim divi and the larger final divi combined. At 91.5p the yield is a delicious 8.0%. It's still covered by both adjusted and statutory earnings too.
Ability to pay divis is probably more important than the actual level of divis. In this case, Amino has plenty of cash - year end net cash is $20.3m, up 17%
Dividend policy;
The Board has recommended a full year dividend of 7.32 GBP pence per share, a 10% increase over the prior year. The Board also intends to continue this level of dividend for at least two years.
Put another way, anyone buying now, should get back about a quarter of their investment in divis, over the next 2 years and 3 months. That's an attractive proposition, especially for shares held in a tax-free wrapper such as SIPP or ISA.
Balance sheet - looks fine, even when you write off intangibles.
2019 profit warning - given that 2018 figures reported today are as expected, the 15% share price fall must be due to outlook comments being adverse.
Forecasts for 2019 have been reduced from consensus of $0.15, being flat on 2018, to a revised figure today of $0.129 for 2019, and a similar figure $0.13 for 2020 (source: house broker update note, out today)
That's a 14% drop in 2019 forecast earnings today, so the 15% fall in share price this morning makes sense. Although the big dividend yield is probably now supporting the share price - so I would guess that there might be only limited downside now, as income seekers become more attracted to the share. That's providing nothing else goes wrong, of course.
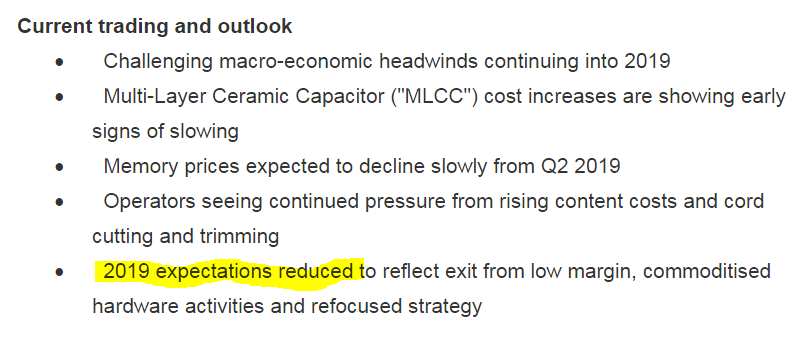
Cost savings - of $4.4m annualised have already been implemented. Additional $5.0m annualised savings identified.
Transformation programme - I cringe when that phrase is used, as it usually means things are going wrong, and a whole heap of exceptional costs need to be incurred.
To summarise;
- Exit from low margin hardware activities
- Focusing on software, added value services, and recurring revenues - organic, and by acquisition
- More cost savings, as mentioned above
- Simplified product portfolio
- Changes will be complete by April 2019
My opinion - I'm getting increasingly tempted by the very high dividend yield - which looks fairly safe, as it's covered by earnings, and cash in the bank.
Amino has a good track record of cash generation & decent divis.
My main worry, is that I know nothing about the sector it operates in. Therefore I could be attracted to a superficially cheap share, only to find out later that the company was withering away due to competitive pressures. With this is mind, it would be great to hear from any readers who are sector experts in Amino's space, to get a feel for how its products measure up versus the competition.
RM (LON:RM.)
Share price: 243p (up 6.6% today, at 11:34)
No. shares: 83.9m
Market cap: £203.9m
RM plc ("RM"), a leading supplier of technology and resources to the education sector, reports its final results for the year ended 30 November 2018.
Several readers have asked me to look at this, so suppose I ought to oblige. My last review of the company here was in May 2014, so arguably we're overdue an update! Graham reviewed its last interim results here in July 2018. He pointed out positive trading. Also that the company claims to have a strong balance sheet, which it doesn't (negative NTAV). It's surprising how often that is the case - hence why narrative claiming to have a strong balance sheet is an amber flag for me.
The highlights figures look great, as you can see below. Note that organic revenue growth was only 2%, with the bulk of the total 19% growth coming from an acquisition.
Also note from this table that net debt, and the pension deficit, are nicely down;
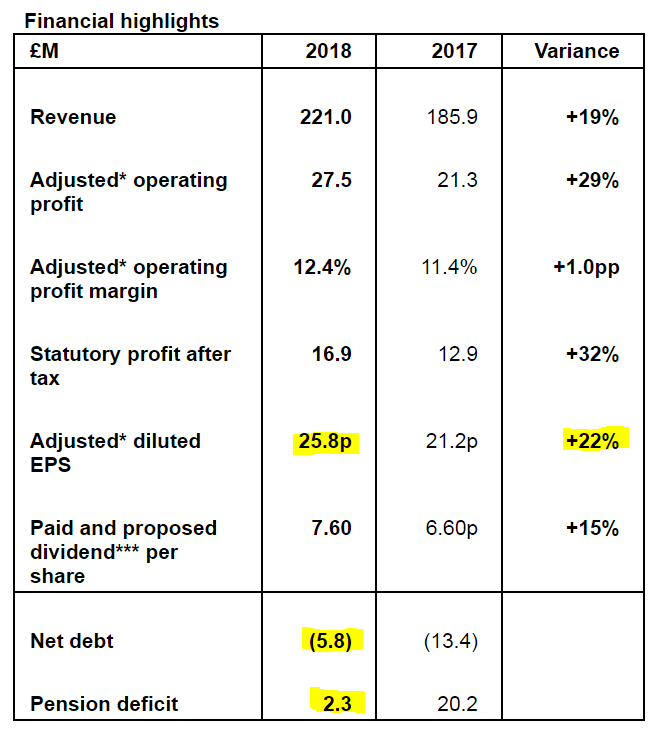
Valuation - based on today's 243p share price, and the adjusted EPS number highlighted above, the PER is only 9.4.
Dividends - up 15% on prior year, to 7.6p - yielding 3.1%
Outlook - it's difficult to ascertain much from this;
The RM Group has undergone substantial change in recent years. The newly consolidated RM Resources stands to benefit from distribution synergies to counteract anticipated price pressure as customers move increasingly online, RM Results is much invigorated both in UK and overseas, and RM Education, having dealt with substantial legacy issues, has developed its continuing businesses.
Notwithstanding macroeconomic uncertainties, the Group enters 2019 in a good position.
Pension deficit - has dropped considerably on an accounting basis, from £20.2m last year, to only £2.3m this year. Whilst good news, the cash contributions may not necessarily fall so much, as they're worked out differently. Cash contributions are hefty, at £4.6m p.a. presently. Agreement on the next triennial valuation (which will determine cash payments) is expected soon.
Remember that cash payments into pension schemes is money that would otherwise be paid out in divis. Hence probably why the divi yield here is only 3.1%.
Net cash/debt - year end net debt was only £5.8m, however it turns out this is not a typical figure. As we know, balance sheet cash/debt positions are often window-dressed to look better than reality at other times of the year.
RM is to be commended for addressing this point, and telling us the full truth;
The average net debt position during the year was £24.1m with the highest borrowing point being £32.8m.
I feel very strongly about this - all companies should be compelled to report the average & highest points of net debt throughout the year. These are key numbers that investors need to know, but are rarely reported. Top marks to RM & its advisers for being so transparent.
The only way enterprise value makes sense, is by using the average cash/debt number, yet this is not usually available for most companies - which makes enterprise value based on year end cash/debt snapshots a very shaky concept in valuing companies.
Balance sheet - overall it's weak, with negative NTAV of -£8.7m.
However, given the group's strong profitability & cash generation, the balance sheet looks sustainable, and hence is not a concern.
My opinion - this looks rather interesting, I like it! Thank you to the readers who pointed me in the direction of this share. It certainly looks worthy of further research. From what I can see, it seems a modestly valued group, which is performing well.
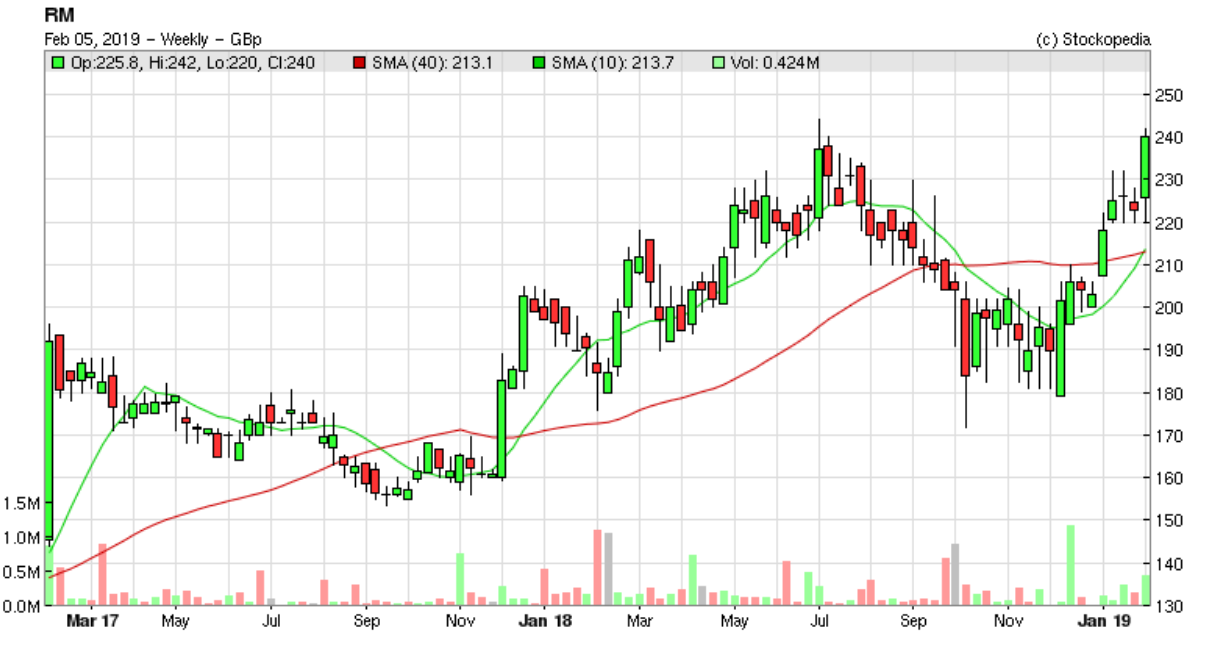
Stockopedia loves it, with a "Super Stock" classification, and a StockRank of 96. As we know, this is not infallible, but it is proven to move the chances of success in the right direction;
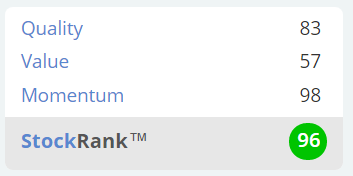
Note how the 2 year chart looks so similar to that of WATR above - a spurious sell-off in H2 of 2018, now completely reversed in a thundering recent rebound!
OnTheMarket (LON:OTMP)
Share price: 93p (up 0.5% today, at 16:28)
No. shares: 61.5m
Market cap: £57.2m
(at the time of writing, I hold a long position in this share)
This is a residential property portal, challenging the dominance of Rightmove & Zoopla. The point of difference is that it is part-owned by estate agents, who will therefore benefit if it succeeds.
Rapid growth is being achieved, by using free trials to entice agents to use it initially.
The company keeps putting out RNSs, saying how rapidly the number of agents is growing - hardly surprising, when the service is offered free of charge. These announcements don't seem to be impressing the stock market at all, as you can see from the chart below.
This is what it said today, which has put all of 0.5p on to the share price;
OnTheMarket plc, the agent-backed company which operates theOnTheMarket.com property portal, is pleased to announce that, as of 31 January 2019, it has listing agreements with UK estate and letting agents with more than 12,500 branches. This is an increase of more than 7,000 branches in just under a year since Admission to AIM in February 2018.
It remains to be seen whether the free trials will convert into paying customers.
As a punt, it looks interesting, in my view. Any sign of real commercial traction, and the lowly market cap could really zoom up. Whether or not that happens, who knows? The broker forecast, suggesting a sudden move from heavy losses into big profits, don't look realistic to me.
Carpetright (LON:CPR)
Share price: 19.75p (down 6.1% today)
No. shares: 303.8m
Market cap: £60.0m
Carpetright plc, Europe's leading specialist carpet and floor coverings retailer, today announces a trading update for the 13 week period to 26 January 2019.
In line with expectations
- Negative LFL sales in UK, but improving trend (no figures given, so probably pretty bad)
- Europe doing better, especially the Netherlands
- Cost savings of £19m oin track, per CVA
- Long-serving CFO is stepping down. Sounds amicable. New CFO lined up
Tapi - Carpetright is struggling particularly because its retired founder's son, set up a direct competitor, Tapi, which strikes me as being a bit off. Here's an interesting article on that subject.
This article indicated that Tapi is heavily loss-making, but that fact was swatted away by Tapi's management as expected startup losses. I'm having a rummage at Companies House, and note that Tapi has 25 active Directors, which seems odd. Maybe the strategy is to lock in key people with shareholdings & Directorships? Ah yes, note 6 of the 2017 accounts, says - "There are no key management personnel other than the directors".
The latest figures at Companies House for Tapi are for FY 12/2017, so a bit dated now (that's the trouble with private company accounts). However, this section in the commentary is rather revealing - clearly Tapi is eating a fair chunk of Carpetright's lunch, at high gross margins too;
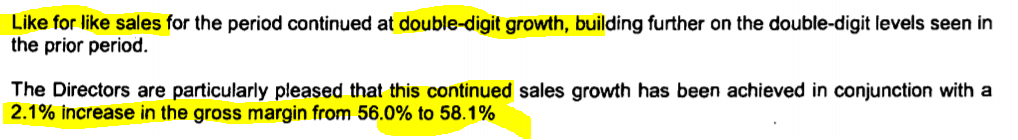
So Carpetright can bellyache as much as it likes about weak consumer confidence - that's clearly not the problem - a new, national competitor is its main problem. There's also the issue of losing good staff to Tapi.
The fact that Tapi has founders with very deep pockets, made from their Carpetright shares, who can afford to run Tapi at a loss, is a big concern. Tapi reported revenues of £57.0m in 2017, generating a £10.9m loss before tax.
Tapi's operating lease expense (disclosed in note 4 of its 2017 accounts) looks extremely high, at £13.9m. That's over 24% of revenues. Could it be that Tapi may have made the same mistake as the pre-CVA Carpetright, in signing up for excessively rented stores?
Employee costs (see note 5) of £13.2m in 2017 at Tapi also looks excessive. That's a massive 23% of revenues, which as any retailer will tell you, is far too high. That would include all wages though, including warehouse & head office, not just the stores.
The "other creditors" in note 12 are enormous at £17.7m, and are spread in tranches over 1-5 years. That suggests to me these might well be capital contributions from landlords, which have to be parked on the balance sheet and amortised. This suggests to me that Tapi might have signed leases with high rents, but huge cash bungs (reverse premiums), to fund its capex. That helps cashflow in the short term, but makes it difficult to trade profitably,, as rents are too high.
Overall then what do I make of Tapi's accounts? They look pretty awful to me. Maybe the Harris's have created a monster here, running at big losses, with apparently uneconomic rents & staff costs? The only logic I can see for doing this, is if they think they can run Carpetright into the ground, so that it goes bust, and Tapi gets all its business, which would then make Tapi profitable. That strikes me as a shabby way to behave. Most families that have made a fortune from a business would just retire to a warmer climate, and enjoy the fruits of their labour.
My opinion - I see CVAs as usually deferring the inevitable failure of declining companies. Carpetright probably fits into that bracket, for as long as Tapi can keep going, and eating its lunch.
I'm really glad I reviewed Tapi's accounts, as that has completely put me off investing in Carpetright (which wasn't high up on my list of priorities in the first place).
It seems to me we could see this as carpet wars - a grudge match, with two struggling companies slugging it out, until one of them goes bust. Tapi's founders have got the deeper pockets, so providing they're happy to keep pouring cash into loss-making Tapi, then ultimately they're the likely victor.
Therefore, to me CPR shares have to be viewed as currently uninvestable.
The wild card would be if Tapi's backers pull the plug on it. That would then make CPR look a lot more interesting.
Elektron Technology (LON:EKT)
Share price: 44p (unchanged today)
No. shares: 186.1m
Market cap: £81.9m
Elektron Technology plc, the global technology group, is pleased to provide updates on trading for the financial year ended 31 January 2019 (FY19) and a strategic update for the Group.
Group trading - this all sounds pretty solid;
The Board expects performance for the full year to be line with the upgraded market forecasts notified in the trading update on 1 November 2018.
Group revenue from continuing operations (on a like for like basis) for the full year is expected to be approximately £33.7m (unaudited) a 13% increase compared with £29.8m for FY18, building on the strong, double-digit growth of 11% in FY18 compared with the prior year.
Revenue in the second half of the year of £17.8m was substantially stronger than the first half (£15.9m) as a result of the conversion of Bulgin's strong H1 order book to sales revenue.
Cash - has risen from £5.2m a year ago, to £10.1m at 31 Jan 2019.
Order book - is bulgin' (sorry, couldn't resist that!);
Bulgin ended the period with both sales and orders significantly ahead of the prior year driven by the continued successful implementation of Bulgin's high margin product growth strategy, aided by operational gearing and in-house capacity improvements.
Bid approach - this made me sit upright and pay attention;
During the second half of the year, the Board received an unsolicited indicative offer for the Bulgin business at a substantial premium to the Group's current market capitalisation.
The Board engaged with the potential overseas buyer, incurring in the region of £200k of due diligence related costs. Following this extensive due diligence which confirmed the business's trading performance and prospects, the offeror decided not to proceed for its own strategic reasons.
Call me old fashioned, but if a bidder does due diligence, and then pulls out, then they've probably decided that the original approach was not such a good idea, for whatever reason.
Outlook - limited in timeframe, but positive;
The order book has continued strongly into the new financial year and Q1 sales are expected to set a new record.
US-China trade tariffs sound like a good opportunity;
With Bulgin manufacturing predominantly in Tunisia, Bulgin is well placed to capitalise on the current 25% tariff for Chinese electronic component goods imported to the United States, Bulgin's largest market.
My opinion - this share looks quite good.
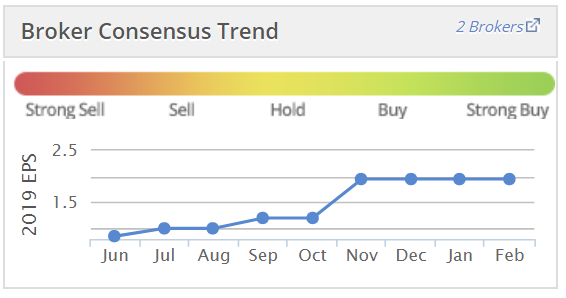
I see that broker forecasts have been steadily raised over the last year, which is a positive thing to look for;
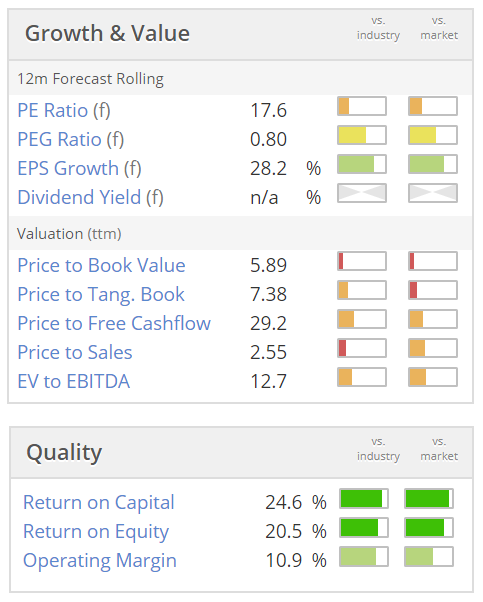
Valuation looks a bit toppy, for an electronics component manufacturer - not a sector that interests me anyway, and certainly not at an elevated price;
The big problem with this sector, is that there's a huge amount of competition. So companies which find a high margin niche, can end up seeing new entrants copying their products & selling them cheaper.
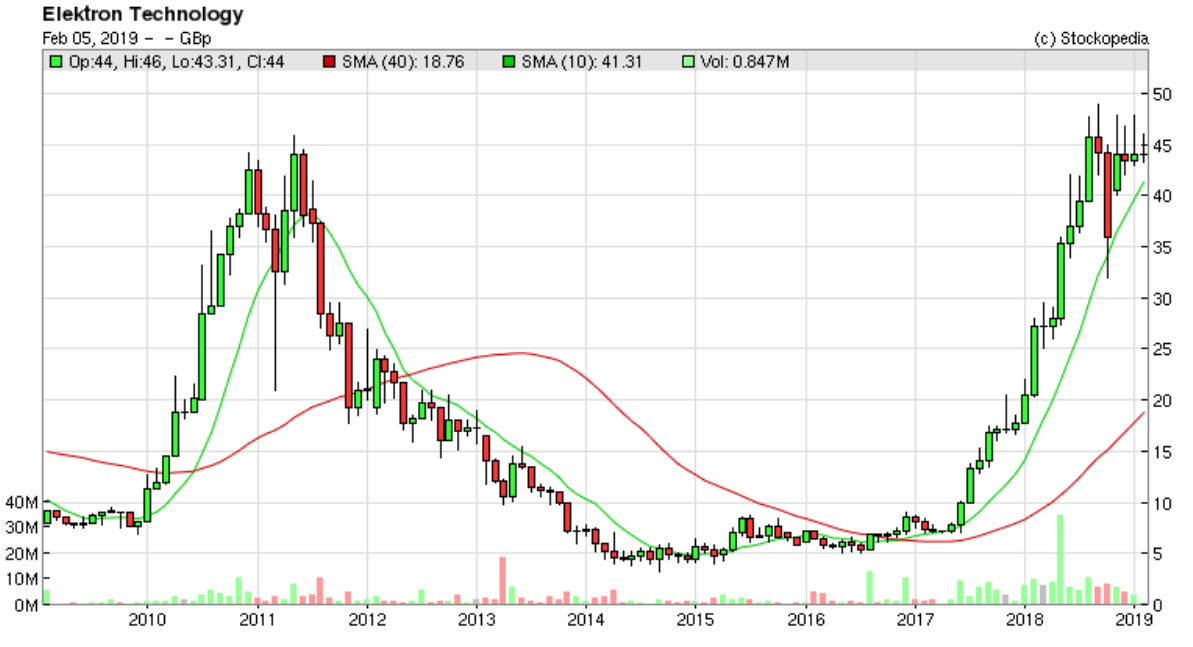
You can see from the 10 year chart below, that there seems to be a cycle, of product innovation, growing profits, then those products going into decline, as competition erodes the profits. I vaguely recall this happening about 14 or 15 years ago too, when I was offered some shares in a placing, to refinance the original group which had gone bust. My memory's a bit hazy on that, due to the passage of time.
There are no dividends from Elektron either, which is a problem for me. This type of business would only interest me if profits were sustainable, and it was on a low PER, and throwing off big divis. Good luck to holders, but it's not of any interest to me. Although the bid approach does sound intriguing! Maybe I'll keep half an eye on it.
A couple of quickies before I pop out for some dinner & a couple of pints.
Safestay (LON:SSTY) - nicely branded hostels. Says it traded positively in 2018, but only mentions EBITDA not profits, of £3.4m (barely higher than £3.2m in 2017).
Poised for European roll-out.
Says it will become "self-funding" when it reaches 20 sites (currently has 13).
To me, this just seems a lousy business model - requiring huge amounts of capital, to generate (so far) no return at all for investors. It has to repeatedly dilute investors, to continue expanding.
The upside case is if it gets really established as a brand, and occupancy levels rise from the current 75.6%.
Gama Aviation (LON:GMAA) - I last looked at this in Oct 2018 when it fell 20% to 121p on a profit warning. It's since plunged to only 67p - yet another one where selling at the first sign of trouble would have been wise. That's often the case, apart from when it's not.
Today's RNS is titled "Receipt of overpayments" - surely that's a good thing? So why is the share price down 23% today?
The reason is that this looks very bad;
Gama Aviation Plc today announces that it has identified the receipt of two overpayments, in error, from Gama Aviation LLC, its US Air associate. $5.75m and approximately $2m were received in June 2018 and December 2017 respectively and were reported in cash and trade creditors in the respective half and full year reporting periods. Both of these overpayments have been re-paid in full.
A strange coincidence that the cash balance got inflated just before two balance sheet dates, isn't it? By accident.
That's me done for today! See you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

41 comments
I should have read the news feed first as it turns out the are in the Smart TV system space
https://www.stockopedia.com/share-prices/amino-technologies-LON:AMO/news/rcs-amino-technologies-google-certification-for-next-generation-devices-urn:newsml:reuters.com:20190401:nRSA5466Ua/
I may have a punt given their past success they no how to operate effectively with these systems.
Great summary from JWebster on Amino Technologies. The future of smart TV has to be easy to use operating systems with no set top boxes. Many of the Smart TV producers must already be working on this and it would be good to know if Amino are in on this development or whether they will just be edged out.
It's made me think, I have some of these and was hoping that the brains in Cambridge could tackle their fall in sales.I have no crystal ball on their move to more software focus.
Looking at Amino Technologies (LON:AMO) due to huge dividend 9% market cap of £59m yet holding £20m in cash
Last few days since reporting revenue reduction on 5-Feb in their final results, we can see a very high level of share transactions. AMO has a free float of 72m shares yet around 7m changed hands, which is quite the distribution.
Management have committed to pay this level of dividend through 2020. Is it a value trap or bargain ?
AMO provide set top boxes and software to mid/small pay-TV companies. From the results, of their $88.9m 2018 revenue $79.6m came from 'Devices including integrated software' and the rest from Software and Services. Now the problem is, as their commentary alluded to, hardware is a bad business to be in, so they want to pivot to software and services. Good thinking, but can they do it, given the vast majority of their income has come from devices? It will depend if they can successfully unbundle the OS software in the devices, let clients buy their own hardware but licence their OS into the third party hardware.
It's possible, but I can't see how to confirm this, other than 'wait and see'
The other negative of course, is in the long term these smaller content providers will all have to move to major platforms, like Android TV or be wiped out - no-one will pay for niche content or set top boxes once the big players control device streaming. AMO recognise this, as they discuss their premium wrapper service for Android TV to support their clients moving to this new platform.
So the bull case is AMO management seem to see the winds of change and are talking the right ideas. The bear case is the majority of their revenue is at risk if they don't make the pivot to software successfully, or, Android TV becomes so good, their clients just move to that and don't need AMO any more.
Me, I think they might get away with paying the dividend next two years, they have the cash, but after that some media platform, e.g. Android TV could kill them off as the smart TV manufacturers pick it up. Otherwise if the market remains fragmented, they have a business supporting the various content vendors.
Many thanks Paul. I was tempted by Elektron Technology (LON:EKT) until I remembered a word of advice - can't remember from where but I think an article on Hargreaves Lansdown - that one should never buy an AIM share that doesn't pay a dividend. You mentioned the lack of dividend in your report and for. that reason I'm no longer tempted.
Best wishes, William
Sosandar (LON:SOS) questions
1) Customer footprint is still very small. How much is the current business development focused on satisfying the preferences of a fairly narrow customer base rather than a broader spectrum of 25-55 yr olds?
2) Is the customer base more affluent than expected at launch?
3) If 1 and/or 2 above are correct then what is the implication for growth trajectory? How has it changed your future plans? Stay niche and higher margin with lower complexity in terms of design, manufacture, distribution and marketing? Or expand into a broader catalogue, customer base and lower margin 'faster' fashions? The trade off will be between faster but lower profit growth and slower but more profitable.
4) Sosandar seems as if it has a UK centric sensibility that may not internationalise easily. Is there an international plan and if yes what do you need to do to adapt?
5) The Sosandar image seems to sit somewhere in a fashion and lifestyle context. Do you see commercial value in developing the lifestyle element further or will it always be merely part of marketing? What kind of offerings could you envisage as part of a Sosandar lifestyle offering? For example, non clothing products, experiences, etc. With the high street and associated brands being decimated there is a space emerging for replacement brands....anything that Sosandar can monetise?
Thank you
Not sure this answers question #1, but Sosandar (LON:SOS) currently achieve 49% of their sales from age groups outside of their core 35-54 demographic:
As for market opportunity, there's a consistently high spend across all demographics 15-74:
Re Sosandar (LON:SOS) I note that the models seem to be young and attractive. Not sure the average buyer is in the same league. Is the company selling an idealised reality product?
Firstly, I used to own Amino AMO but felt the share had gone up too much and the earnings were too uneven. I was just reading yesterday's release as a matter of interest when it struck me that so many of the younger generation seem to be watching TV on smartphones and tablets. Doesn't this mean that the day of the set-top box (or similar) is shortening, or does the emergence of Amazon TV etc bode well? I simply don't know and whilst the comments on the trading seemed to suggest that Amino was at the front of the technology pack I would like to hear from a real expert in the area to see whether their offering remains l-t releveant.
Secondly a very good point on the release of net cash data within the comments on Water Intelligence. I simply take the end period figure released and base ratios on it. Silly, really. Very sensible comments - but how do we get them actioned?
RE: Sosander
Pau, given the current media pressure on fast fashion and its environmental impact, can you ask their approach and strategy regarding this please
Thanks Karl
Re Sosander:
My wife asks why so few dresses with sleeves!
Good luck with the interview.
RT
Re Sosandar (LON:SOS) my missus noticed the same thing
"why so few dresses with sleeves!"
Re Sosandar (LON:SOS)
It might be my age but I notice that the more mature women like sleeves
I believe it's that they start to worry about "Bingo Wings" (Look it up)
Seriously - Lots of "no sleeves" will alienate a section of the market
Once that is their view of the brand they won't browse it again
Perhaps they are not the target!
Hi treen,
Nearly all Sosandar's dresses DO have sleeves!
Regards, Paul.
A couple of observations on Elektron Technology (LON:EKT) . I saw them present last year.
They covered a bit of the history. Several years ago they decided to move production from China to Morocco. When the equipment arrived in Morocco, the insides had been stripped of the electricals. Somebody sabotaged all the equipment. It took a long time to recover from that. The business has also been reshaped in the intervening period.
It's important to bear in mind this is currently a collection of businesses on an aggregate high teens P/E. EET makes eye checking equipment; makes about £0.1m contribution to EBITA; and is being sold. Bulgin produces £9.0m of 1/19 EBITA and Checkit about -£4.5m 1/19 EBITA. These are Equity Development estimates for period ending 1/19.
Bulgin is a very good business with very high returns. It makes electrical and other connectors for harsh environments. Watch some of the videos here - https://twitter.com/EKT_Bulgin. They sell through distributors but have agreements to receive end-user order data. Average order value is about £250. They said that about 66% of the revenue comes from their product having been designed in to the drawings. They believe their customers are not particularly price sensitive. If you have to hire a ship and a diving robot to replace a connector in a deep sea cable, an extra fiver on the cost of the connector is the least or your worries.
Checkit does electronic checklist keeping/updating mostly (at the moment) for restaurants and foodservice. There are new regulations that will drive demand here. The example they gave was that of checking the temperature of the chilled foods in a restaurant. At the moment there's a piece of paper taped to the walk in where the employee writes down the temp every few hours. Apparently these are mandatory. The Checkit solution is to combine a temp sensor in the walk in and software to measure it continuously. Added features like an alert to the restaurant manager's phone if the temp goes above a limit (better call the repair person). They see lots of opportunity to create customised checklists that can be kept/updated on phones that could be combined to create management dashboards and/or supporting documentation in regulated industries (did you clean the rods in the reactor, Homer?). It's a SaaS business so creates nice subscription revenues.
Management have very high hopes for the Checkit business but it's not due to be breakeven until year ending 1/23 and there's lots that can happen in the meantime.
Very interesting Elektron Technology (LON:EKT) comment:
They said that about 66% of the (Bulgin) revenue comes from their product having been designed in to the drawings. They believe their customers are not particularly price sensitive. If you have to hire a ship and a diving robot to replace a connector in a deep sea cable, an extra fiver on the cost of the connector is the least or your worries.
The excellent Elektron group return numbers (ROCE 25%/ROE 20%) lead me to believe that they must (somewhere) have an Economic Moat - Now I see where and why it is. Having a reputation for high reliability and such a high proportion future Bulgin division sales specified by project designers is a tremendous advantage.
If the the breakeven Eye division is to be sold and new Temp monitoring division is loss making, their impact will be diluting average group return numbers, so the Bulgin component return numbers must be tremendous.
The Elektron Technology (LON:EKT) group may turn out to conform to one of Buffett's cliches; I try to buy stock in a business that are so wonderful that an idiot can run them. Because sooner or later one will. I hold. Ian
I checked my notes from the Elektron Technology (LON:EKT) meeting. The designed in element of sales was said to be 55-60% which I inadvertently overstated. The ROCE on Bulgin was said to be 160% aided by the fact they had 1,500 fully depreciated moulds.
Re Eleckron - Thanks for the clarification, but >50% of the Bulgin division sales as project specification is still remarkable. The 160% ROCE number is outstanding. A little gem! Ian
I simply observe that there is never any objection to references (sometimes approving) to Simon Thompson's tips in the IC. I subscribe to several "tipsheets" not because I value them as tipsters but because I find them a useful source/summary of information which is often difficult/cumbersome to come by elsewhere.
Re Amino, trying to understand the decline in sales and whether this is permanent, I picked out (my bold and italics) the following from the RNS.
"In North America (56% of group revenue) approximately two thirds of sales are made via distribution to smaller Tier 3 and 4 operators. Sales to these operators, fulfilled via our distribution channel, were broadly flat in 2018 compared to 2017. However, overall our revenue into North America declined by 18% as our distributors reduced stocking levels compared to the previous year. This reflects the impact of planned trade tariffs in the US, which have not impacted Amino's products directly, but have created confusion and concern among our customers, which has translated into delayed buying decisions."
This surprised me. My presumption would be that, if this really is the case, once tariffs are no longer a threat, the distributors would simply need to restock - after all the sales to the operators (end users?) were broadly flat for the year. This would therefore create higher sales next year
Additionally from the RNS:
"In EMEA (32% of group revenue) sales increased by 25% after a period of decline."
This seemed very positive to me.
So overall, I am not feeling so negative about this stock as I was when I first scanned the RNS. However, I take on board that they talk about headwinds and transforming the business, which does make me concerned there may be another profit warning in the near future.
I would appreciate any one else comments, as to whether I am misreading this.
Thanks in advance
Chris
Water Intelligence was a big writeup tip in November issue of Small Company Share Watch, which has been running for over 25 years at £2.53 . Also tipped again at £2.68 for one of its shares for 2019. One of best tipsheets ever I have been with them for 20 years. Will be interesting to see how high they go ….
It seems a bit harsh to have given 11 red thumbs (at the time of writing) and to have reported a post when the poster merely pointed out a company has been tipped by SCSW and shared a personal opinion that SCSW is a good "tipsheet".
Like many here, I don't have much time for tipsheets, but as it goes their medium term record (albeit not updated recently) is pretty good.
What I have seen, though, is their tips are often marked up sharply on the morning following publication, so subscribers cannot buy near the quoted tip price. The share price often falls back over the few weeks following publication.
Indeed this was pretty much the pattern that played out with Water Intelligence (LON:WATR) back in November.
For this reason I am always interested (as a potentially negative short term indicator) to know what SCSW has tipped, but equally I can see that others might want to understand and perhaps follow their tips.
The number of down-votes for this post therefore I feel is totally OTT.
down-votes seem to be getting more common on the SCVR: there is a cadre of devout followers and a cult of personality at play. Woe betide those who speak ill for upon them shall be cast down votes 'til they and their wayward thinking be smote and group think is restored.
The post is "under review" no doubt for heresy
Re: Downvotes
I think your post is disingenuous. You make it sound like there is some sort of weird cult culture here. I think the reasons JLHammo got so many downvotes are more prosaic.
Firstly, he didn't put the £sign before the stock name he/she was commenting upon which is annoying to all readers here
Secondly, he makes no other observation about the Water Intelligence (LON:WATR), so no one learnt anything more other than it had been tipped
Thirdly, the enthusiasm he/she showed for Small Company Share Watch seemed to me to be the point of the post. And no one likes people ramping things here.
That's why I voted him down anyway
cheers
Francis
A few questions for the team at Sosandar (LON:SOS) if you can please Paul. I hope they're not too direct:
1) They claim that they target an untapped market, but I don't really buy this as there are so many similar brands out there (at least to my very untrained male eye). One simply needs to check out some of the Sosandar-tagged posts on Instagram - like this one - to see that the influencers they are targeting wear loads of different brands.
So my question is, are they really unique, or are they just one of many players in a very fast growing market, and their "uniqueness" is actually having the contacts to get celebrities to try their clothes on in the first place?
2) Is the growth in Instagram/Facebook followers purely organic, or do they spend a lot on advertising? The reason I ask is because many brands spend a lot on advertising and attract lots of new users, many of whom are often disguised as click farms (I say this from wider reading and some personal experience) and then have no further engagement with the brand. This then dilutes the impact of any future posts. So whilst the brand looks like it's growing its social channels, underlying growth might in fact be minimal.
3) Do they have long term worries about the rise of ethical fashion? I personally have seen worries crop up from several sources recently (though all the below are interlinked):
So I'm curious if any fashion firms are taking note (might be a more pertinent question for £BOO)
Thanks!
Great questions, thanks Abtan!
I will definitely include those in the things I ask Sosandar (LON:SOS) management.
Good comments abtan. The issue of ethical fashion is growing. There's just been a Parliamentary inquiry into the wastefulness of fast fashion: https://www.parliament.uk/business/committees/committees-a-z/commons-select/environmental-audit-committee/inquiries/parliament-2017/sustainability-of-the-fashion-industry-17-19/
So there's a question about whether this sector will be affected by regulatory change at some point. I am not really clear what that might look like that - some kind of tax maybe.
Also agree with you about rival brands. Sezane is pretty popular and aimed at the same age group(ish) although they may be targeting a richer demographic than Sosandar.
Any views on Safestay (SSTY) shares showing a mini recovery this morning based on improved revenues and profits. Share price around 50% below its summer peak
It is interesting that 2 persons have already voted down my honest observations on how I frequently use charts. It would be even more interesting if they could provide their own experiences.. Of course, I don't always observe the chart as I described because I suspect like many people I sometimes become emotionally too attached to a share and hold for far too long. Having said that I have loved charts since I first became acquainted with David Fuller's Chart Analysis in around 1968. David advised private investors and institutions throughout the world.
He died last month and I am indebted to him. I am glad I learned about charts and his subject of behavioural technical analysis.
Paul - with regard to your opening comments share prices in the long run are obviously ultimately driven by fundamentals. Looking at your Water Intelligence chart had I been so lucky to have been a holder from 150 to almost 450 I would have been well aware of the accelerating upward trend and I would have been on warning during the first downward candle and certainly during the following downward candle which finished somewhere near 350. I would definitely have been out by 375. When it went down to the 250 region I would have been very relieved and to me the chart would have done its job. A time to buy again may have been around 325 on the way back up but I often have a reluctance to revisiting a share so cannot say that I would have done so. Also, as you say, the spread may have made reinvestment unattractive. By using charts in this way I have avoided numerous substantial losses although at the same time I have undoubtedly missed possibly significant gains. How it all balances out I don't know but it has certainly saved me some anguish!
Picking up on Paul's 'directorspeak' comment on Water Intelligence (LON:WATR), it has to be acknowledged that Patrick DeSouza is always upbeat in his pronouncements on the company. So far, however, he has always delivered on his optimism.
Any thoughts on Numis (LON:NUM) Paul not much in the way of figures from this mornings statement other than income from institutions off 25% and challenging current conditions we have also had the recent demise of Daniel Stewart, but Stocko still rates it with a high overall stock rank.
Thanks
....and another RM (LON:RM.) request...any more for anymore?...
It's a really dull company in a tough sector that's been doing really well executing a multi year repositioning into higher margin business and exiting lower quality revenue. Its anti-zeitgeist in many respects...but isn't that what works prospectively when the investing winds change?
One more vote for RM (LON:RM.). This was one of the first small caps that I bought into based largely on Stocko ratings.
A further vote for RM (LON:RM.) impressive results and remains conservatively priced on a number of metrics.
My morning smallcap tweet: Amino anemia in '19
MaxCyte Inc (LON:MXCT), Numis (LON:NUM), Elektron Technology (LON:EKT), Amino Technologies (LON:AMO)
MaxCyte (MXCT) placing to raise £10m min at 170, an 8% discount.
Numis Corporation (NUM) downbeat AGM stmt. "Average deal fees remain in line with the prior year, however, transaction volumes are significantly lower across the market and, as a consequence, we have completed approximately 25% fewer deals compared to the first four months of the prior year. Equities has been similarly impacted, Institutional income is approximately 25% lower than the comparative period reflecting depressed market activity levels, and our trading book is marginally loss making for the period."
Elektron Technology (EKT) FY trading in line. Received an unsolicited indicative offer for Bulgin at a 'substantial' premium to EKT's current market capitalisation. Buyer changed mind 'for its own strategic reasons'. Puts Elektron Eye Technology up for sale "due to the growth opportunities presented by both Checkit and Bulgin, EET is not core to the Group's future plans."
Amino Technologies (AMO) FY in line. $5m annualised reduction in cost base identified. "To support a higher quality of earnings and de-risk the business, we are accelerating our strategy to improve growth in recurring revenues from software and services, reinforce our focus on value-add hardware, and remove our exposure to low margin hardware activities." Will hit FGY19 rev by c.20%, and adjusted operating profit by 10%.
An encouraging update from Water Intelligence (LON:WATR) this morning, and to add a bit more comment to Howard's post above.
1.Buy-back of the Ontario franchise, adding $400k+ to 2019 revenue and establishing first presence in Canada.
2.Expansion of the franchise network with the sale of franchise territory in Youngstown, Ohio. Step in a strategy of expanding into greenfield locations to make the business more attractive to insurance partners with national coverage.
3.Financial support to the Idaho franchisee to accelerate addition of leak repair and municipal capabilities, beyond simple leak detection. The one-stop-shop solution again being attractive to insurance partners.
4.UK-developed diagnostic sewer technology being rolled out to the US franchise network.
The announcement also hints at a favourable 2018 q4 update, which is expected some time in the next few weeks.
RM (LON:RM.)
Results look good. Seems to have beaten revised forecasts following its December TU.
Still looks good value with a high SR.
Phil
I hold
Hi
Anyone interested in Water Intelligence (LON:WATR). Up 10% as I type.
Extract from RNS very interesting.
Water Intelligence plc (AIM: WATR.L), a leading multinational provider of precision, minimally-invasive leak detection and remediation solutions for both potable and non-potable water is pleased to announce a series of corporate transactions that reinforce its growth trajectory for 2019 and beyond.
Highlights
· Acquisition of Ontario (Niagara), Canada franchise, expanding corporate presence into Canada and Upstate New York
· Sale of a new franchise territory for Youngstown, Ohio (US)
· Financial support to an Idaho (US) franchise accelerating expansion into municipal offerings
· Formal launch of ORCA municipal sewer product into the United States following trials at a UK water utility
Full RNS here https://www.investegate.co.uk/water-intelligence--watr-/rns/corporate-transactions-and-technology-update/201902050700030416P/
I added to my small holding this morning.
Regards
Howard
Elektron Technology plc (AIM: EKT)
Updates on trading for the financial year ended 31 January 2019 (FY19) and a strategic update for the Group.
Elektron conceives, designs and markets innovative products and services for business that connect, monitor and control. We have a multi skilled team of engineers, software and product line specialists based in Cambridge focused on the opportunities created by global growth in the following areas:
- Demand for ubiquitous power and data: Bulgin
- Real-time operations management using Internet of Things (IoT) technology: Checkit
The Board expects performance for the full year to be line with the upgraded market forecasts notified in the trading update on 1 November 2018.
Group revenue from continuing operations (on a like for like basis) for the full year is expected to be approximately £33.7m (unaudited) a 13% increase compared with £29.8m for FY18, building on the strong, double-digit growth of 11% in FY18 compared with the prior year. Revenue in the second half of the year of £17.8m was substantially stronger than the first half (£15.9m) as a result of the conversion of Bulgin's strong H1 order book to sales revenue.
Group net cash was approximately £10.1m at 31 January 2019 (31 January 2018: £5.2m)
Brexit and US-China Trade Tariffs mentioned.
John Wilson, Chief Executive Officer of Elektron, said:
"The underlying performance of the Group during the last financial year has been outstanding and it is expected that profits, notwithstanding incurring £200k of aborted transaction costs, will remain in line with the most recent, upgraded, market forecasts for the year."
Elektron Technology (LON:EKT) has a hint of Avesco about it. It has a few trading divisions, one is storming ahead of the others (Bulgin/Creative Technology), non-core divisions are being turned profitable and/or then sold (Elektron Eye/Presteigne), and talk of a trade sale is being talked up (the approach on Bulgin/the purchase of Avesco group).
It's difficult to know how much to read in to the "unsolicited indicative offer for the Bulgin business at a substantial premium to the Group's current market capitalisation", and the subsequent decision by the prospective buyer not to proceed. Was that a one-off, never to be repeated, or the start of a sale process?
The good news is that if you buy into this now, hoping for some sort of windfall from a sale of the whole group, or just Bulgin, then you also buy into a decent quality company that appears to be on a roll.
I don't currently hold but I'm very tempted.
Ta
Chris