Small Cap Value Report (Tue 3 July 2018) - FDEV, MCB, CHRT, RM.

Good morning!
It's been a tricky morning for me so far, as my computer is preoccupied with a Windows Update..
Fortunately, I've managed to commandeer a computer (temporarily) from someone else.
Let's see what's on the menu today:
- Frontier Developments (LON:FDEV) - trading statement
- McBride (LON:MCB) - trading update
- Cohort (LON:CHRT) - final results
- RM (LON:RM.) - interim results
Cheers,
Graham
Frontier Developments (LON:FDEV)
- Share price: 1485p (+9%)
- No. of shares: 38.7 million
- Market cap: £575 million
A super update from this video games publisher. Not only is it upgrading expectations again, but it has quantified these expectations with numbers (something that is suprisingly rare!)
The Board's expectations for the current financial year have increased as a result of the initial sales performance of Jurassic World Evolution. Although it's very early in terms of both Frontier's financial year and the life-cycle of Jurassic World Evolution, current Board projections indicate that Frontier could achieve total revenue for the year ending 31 May 2019 towards the upper end of the current market analyst range (of £58 million to £88 million).
Note how wide the range of analyst forecasts was: £58 million - £88 million. That indicates to me a great deal of uncertainty as to how the company might do.
If the company achieves toward the upper end of that range, I would expect a huge increase in the bottom line.
Gross margin is over 70% (the marginal cost of selling an additional video game is low) and the degree of operating leverage remains quite high. This means that additional sales should have a disproportionate impact on profitability.
This stock deserves a high rating, in my view. As I've said many times, I think there are larger and more diversified games publishers who are probably safer bets. But let's not take away from the achievements at Frontier.
Frontier is hoping to become more diversified over time. It currently has three franchises.
CEO comment:
We already have future franchises in different phases of internal development and we will continue to explore other models to accelerate our scale-up.
Activision Blizzard ($ATVI) is currently trading at a forward P/E ratio of 28x, and EV/EBITDA of 26x.
Prior to today's update, Frontier was trading at forecast P/E ratio of 38x, and EV/EBITDA of 37x.
Given the strength of today's update, I wonder if these valuation multiples could possibly reduce for Frontier? Or perhaps the trading momentum is more than fully offset by the share price increase.
I would like to own a video games publisher, as I think the economics of the industry are very favourable to investors.
One of the fund managers I follow, Nick Train, has been a long-term holder of Nintendo (TYO:7974). That's a good example of a stock with unique and precious intellectual property.
I've just run a quick comparison, and found that Nintendo might be offering decent value at the moment, relative to Activision:
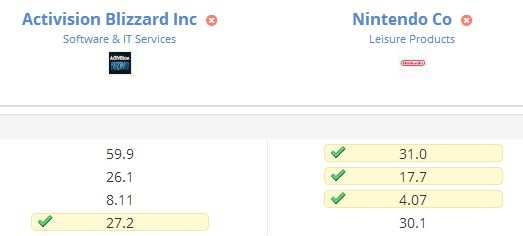
(These metrics are trailing P/E ratio, EV/EBITDA, Price to Sales and Price to Cashflow.)
Given the strength of Frontier's momentum, it might be able to challenge these two giants on some of these metrics soon.
And when it is more diversified, e.g. with 5+ strong franchises, then it could feel safe enough for me to buy.
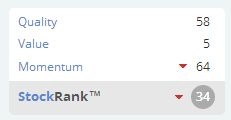
The StockRank summarises:
McBride (LON:MCB)
- Share price: 124p (-6%)
- No. of shares: 182.6 million
- Market cap: £226 million
McBride plc, the leading European manufacturer and supplier of Co-manufactured and Private Label products for the Household and Personal Care market, provides the following trading update for the twelve months ending 30 June 2018.
This is a double-bad update. It's a profit warning, and it fails to show the numbers.
Following weaker than expected sales levels in May and June 2018, the Group now expects full year adjusted Profit Before Tax to be marginally below the lower end of analyst expectations.
Personally, I can see a PBT forecast of £34 million, but I don't know what the lower end of expectations was.
Sales were weaker than expected in May. Strangely, the company also says that it has struggled with increased volumes, causing:
...higher distribution and warehousing costs and some short term inefficiencies at certain factories.
Perhaps this ia bit of indigestion arising from its acquisition last year?
My view
I've had a look at the archives to see what Paul was highlighting about this stock last year.
Apparently, it had guided shareholders to expect an H2 weighting at the very beginning of the financial year (ending June 2018).
Unfortunately, we have another instance of an H2 weighting failing to materialise properly, and are getting a profit warning instead.
Paul was cautious on the shares at 215p, citing the debt load, the fact that the company acts as a supplier to supermarkets, and the H2 weighting.
With the share price at 124p, the stock has sunk even further into "value" territory"
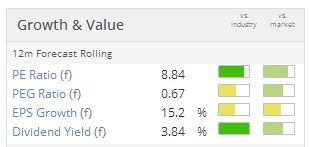
The dividend yield is now at level which would be material for many investors, and the P/E ratio is back in the single-digits.
If PBT turned out to be £30 million, for example (I don't know what the updated estimate will actually be), then at a 19% tax rate that is £24.3 million in net income.
It would feel uncomfortable owning shares in this - it's definitely a contrarian play. Either sales or margins (or both) are likely to remain under pressure. Owning shares in supermarket suppliers is never going to be entirely comfortable.
Is the doom and gloom sufficiently priced in? I was going to provide a positive response to that question, but I've just checked the last-recorded level of net debt: £123 million.
That means the stock isn't really trading at a single-digit P/E ratio. When you take the net debt into account, we are back in double digits.
So I don't think it's offering an exceptional amount of value, to compensate for the weak performance.
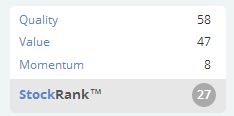
Meanwhile, its Momentum Rank is merely 8/100.
The thing about momentum is that it tends to persist. In other words, things are likely to get worse before they get better.
There is a level where this would become an attractive value investment. I'm not convinced we are quite there yet.
Neither are the StockRanks:
Cohort (LON:CHRT)
- Share price: 357.5p (-2%)
- No. of shares: 41 million
- Market cap: £147 million
From its website:
Cohort is the parent company of four innovative, agile and responsive businesses providing a wide range of services and products for British, Portuguese and international customers in defence and related markets.
Results are ok, overall, and in line with expectations. Adjusted operating profit has reached its highest ever level. Though the order book closed 25% down compared to the prior year.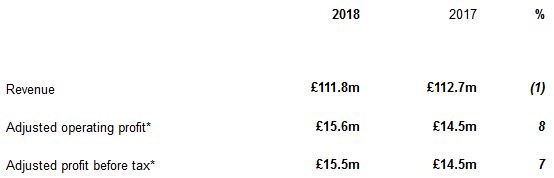
In the same way that a rising order book doesn't necessarily lead to an increase in sales (it depends on when the revenues are recognised), a falling order book doesn't necessarily spell disaster, either.
Cohort says there are "important order opportunities in 2018/2019", and it has a "reasonable underpinning" for sales this year, based on order activity since year-end and its pipeline of opportunities.
The results are very detailed, with lots of numbers around each of the four subsidiaries.
I need to try to understand what the subsidiaries do:
- EID - advanced high performance electronic equipment and systems primarily for the worldwide defence community.
MASS - trusted services and solutions that improve the security, efficiency and effectiveness of operations in government, industry and educational establishments.
- Marlborough Communications Ltd (MCL) - advanced electronic and surveillance technology
- Systems Engineering & Assessment Ltd (SEA) - electronic systems to the defence, transport and offshore energy markets
Outlook
In the outlook statement, the company reiterates some confidence that the sales outlook is not as bad as the order book reduction suggests:
Lower order intake in 2017/18 was substantially due to delays rather than losses or a lack of opportunities, and there is a larger than normal concentration of opportunities in 2018/19.
That seems reasonable. Business is always going to be lumpy for contract-driven businesses like this.
I like this snippet:
The responsibility of the Cohort Board is to manage our affairs so that our businesses prosper whatever the political and economic backdrop.
That's music to my ears: a Board taking responsibility for what happens, regardless of macro conditions. It's so common to see the opposite happening - macro conditions being used as an excuse to avoid responsibility.
I don't have the time to study all of Cohort's moving parts, however. And I have never taken much interest in the defence sector, reliant as it is on government contracts and lumpy orders.
Returns doesn't seem particularly strong at first glance, either:
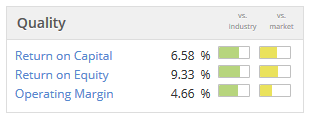
Having said that, the company's overall metrics are encouraging, and its track record of profitability is quite good. And it passes the Stocko Neglected Firms Screen.
So if you happen to take an interest in defence, this stock does appear to be worth investigating further.
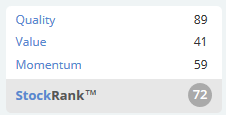
The StockRank is above average:
RM (LON:RM.)
- Share price: 236p (+5%)
- No. of shares: 83 million
- Market cap: £195 million
RM plc ("RM"), a leading supplier of technology and resources to the education sector, reports its interim results for the period ending 31 May 2018.
Some very strong growth rates reported by this educational businesses, boosted by an acquisition within its Resources division (providing physical resources to schools).
The Board is confident of "at least meeting full year expectations" - this means we will perhaps get an out-performance, against those expectations. The 5% share price gain today makes sense.
Drilling into it a little bit, the acquired business generated £24 million of revenue for the enlarged group. Revenue for the entire group increased by £23.6 million, so I think the pre-existing businesses were in aggregate flat or marginally lower.
Synergies of £4 million are being targeted - sounds good. Hopefully, this is one of those instances when an acquisition creates rather than destroys value.
The Statement of Comprehensive Income shows a £9.4 million gain (gross of tax) from re-measurement of the pension deficit.
That provides a helpful improvement to the shape of the balance sheet, and the company points out a couple of times in today's statement that its balance sheet is "strong".
I don't think the balance sheet is necessarily weak, but I do think I should point out that it has negative net tangible assets. There are net assets of £40 million, more than offset by more than £65 million of intangibles.
The company is financed by its customers and suppliers: there is a huge £50.6 million balance within payables, in current liabilities. This figure includes cash due to suppliers, services due to customers, and miscellaneous other items.
That's fine - I presume the company's business model supports this structure? It apparently enjoys very favourable terms of trade. I'd want to have a look into this and make sure I was happy with it and that it was unlikely to change for the worse, if I was considering buying these shares.
Despite excellent share price gains, RM continues to trade on a single-digit P/E ratio and offers a mighty StockRank:
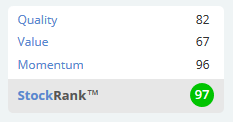
So I do think this is worth looking into.
All done for today. I was distracted by a few technical-logistical issues - apologies.
Oh, good luck to England tonight vs. Colombia. I routinely check the odds before a big match like this, and the latest odds say that England are about 6/5 to win, with a draw being the next most likely outcome (followed by extra time). I hope we get winning goals in open play, rather than penalties!
Cheers,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

23 comments
Hi Graham,
I've been following (LON:FDEV) very closely for some time because there is no doubt that the company trading in a very strong growth sector and has the potential scale up significantly and very profitably.
In this report I think you have highlighted very accurately the pros and cons for shareholders based on the latest update. The one thing that is certain is that the sales of their latest offering in JWE are extremely important for Frontier at this point in their development because sales from the two other core titles, Elite Dangerous and Planet
Coaster are estimated to be not more than £20m in 2019 (reduced from £23m).
However, I think that today's very bullish update may be masking a problem which has led them to accelerate the development of two more titles and which is the reason for the wide the range in the analyst forecast.
There is no doubt that JWE had a very successful launch and that,with the help of significant marketing spend, initial sales have been very encouraging especially with digital downloads yielding high margins. However, Liberium have dropped the average selling price from £38 to £33 going forwards due to "price promotions and lower margins on physical disc sales" for the remainder of the year and revised unit sales to 1.8m copies.
Here is why:
1) Compared to ED and PC the new JWE title sold very well initially and this is proven by figures from the Steam severs. (Steam is probably the largest digital distribution platform for Frontier Developments). In the first week at over 60,000 peak users the title sat at no.7 in the charts, one position ahead of Ark: Survival Evolved (another dinosaur themed title).
https://1drv.ms/u/s!ApfJej54wSbFheZkvNc4LthOD_LOIg
Ark launched in October 2014 and within a month of its early access release on Steam, ARK had sold over one million digital copies.By August 2016, the game had over 5.5 million sales across both Windows and Xbox One, with about 1.5 million from the Xbox One platform.[40] It sold 20,941 digital copies in Japan between September 25 and October 29, 2017.
So JWE launching in the top 10 is a very big deal so long as it can sustain the momentum, sell users more DLC content over the next few years, and stay high in the charts. After all we don't want users flogging their unwanted games on Ebay at a fraction of the cost of a new title.
2) Wind forward a few weeks and JWE has not only disappeared out of the top 10 but out of the top 50 in the Steam charts with a hugely reduced user count. (ARK is still number 8).
https://steamcharts.com/top
So after a hugely successful launch the user numbers appear to have flopped and I'm not surprised that they are having to bring forward to new titles and reduce the average selling price forecast for the remainder of the year. At the current P/E I think holders have to be careful that this dinosaur doesn't come back and bite them.
Very interesting observations - thanks!
You may very well be right about the apparent popularity on Steam at the moment, but another reason may well be that the game is being listed at full RRP (£45). Having been a gamer for many years, I can't think of the last time I paid that price for a PC/Mac game on Steam. A price sub-£30 is much more realistic and I suspect it would rise in the popularity charts off the back of that; I would be surprised if Frontier based their models on selling it on PC at the price of £45 but am very happy to be corrected (console prices are usually of course higher and a price of £45 is more realistic).
I'd also note that at the time of posting, JWE is topseller on PS4 on Amazon, and second on XboxOne.
Not a current holder in Frontier Developments (LON:FDEV), but looking at it with interest at the moment.
Morning all,
As I advised on twitter (@InvestedGeordie) I am more than happy to respond to this.
"sales of their latest offering in JWE are extremely important for Frontier"
Absolutely. It is important for a number of reasons. It's their first multi-platform release, it's their first IP related release (Universal is obviously massive, so they want to knock this out of the park) & it's now the first time the company has been working simultaneously on 3 live game worlds (i.e. they have to patch, update, fix bugs and, most importantly, create a number of paid for expansions).
"However, I think that today's very bullish update may be masking a problem which has led them to accelerate the development of two more titles and which is the reason for the wide the range in the analyst forecast. "
So lets try and unpick this a wee bit. The Liberium forecast I am assuming you are referring to is £55M-£80M I agree is it wide. We now know Frontier Developments (LON:FDEV) have guided us towards the top end of that range. However - the forecast is based purely on existing releases. Given the other two games being worked on have not been announced, they won't form part of this forecast. So the question then becomes: "Was Jurassic World: Evolution hamstrung by development of 2 as yet unannounced titles?" As an investor - If it was, its a fantastic decision. Why? Reviews are broadly very good, having a rating of 77 for Xbox http://www.metacritic.com/game... 71 Pc, 69 for PS4. In broad strokes, this was the Jurassic Park building game the customer wanted, and sales have backed this up. They will already be working on add-on content (Water Dinosaurs, flying dinosaurs will almost certainly be 2) all the while the core engine improves. They have already hinted at licensing the engine out.
There is no doubt that JWE had a very successful launch and that,with the help of significant marketing spend, initial sales have been very encouraging especially with digital downloads yielding high margins. However, Liberium have dropped the average selling price from £38 to £33 going forwards due to "price promotions and lower margins on physical disc sales" for the remainder of the year and revised unit sales to 1.8m copies.
£38 is a lot to pay, I think £35 is fine. Digitally it was £49.99 across PS4 on release. They delayed the physical release which was clever. Those who were desperate to play had to pay up. What I find really interesting is the pricing of the physical release. I was under the impression it would be £39.99 or £34.99 - Completely wrong - https://www.amazon.co.uk/Sold-... £44.99 across the major retailers, for now. We may well also see another new physical release once all paid content is released, and they'll bundle it all together (this would make sense, and is often done perhaps within 18months of initial release). I would like to see a roadmap released to the community to show them what the possibilities are.
1) Compared to ED and PC the new JWE title sold very well initially and this is proven by figures from the Steam severs. (Steam is probably the largest digital distribution platform for Frontier Developments). In the first week at over 60,000 peak users the title sat at no.7 in the charts, one position ahead of Ark: Survival Evolved (another dinosaur themed title).
https://1drv.ms/u/s!ApfJej54wSbFheZkvNc4LthOD_LOIg
Couple of things here. For info, TenCent's WeGame is roughly twice the size of Steam. You'll note TenCent own 9% of Frontier Developments (LON:FDEV) & have a man on the board. The comparison to Ark is highly inappropriate as they are both completely different games (Park Building SIm vs FPS Survival). The only vague commonality is 'Dinosaurs'. FPS' are very popular. It would be fairer to compare Ark: Survival Evolved to Rust, Fortnite or the upcoming Fallout 76. Frontier has not yet made an FPS.
"So JWE launching in the top 10 is a very big deal so long as it can sustain the momentum, sell users more DLC content over the next few years, and stay high in the charts. After all we don't want users flogging their unwanted games on Ebay at a fraction of the cost of a new title."
Again this is somewhat misleading. momentum is important, but true momentum cannot be measured accurately using live player numbers from steam during the sale imo. They, sensibly in my view, released the game before the Steam Summer sale. This got the big sale numbers which have lead to the top end guidance by the Board. If I had purchased, then the sale started, I might well have played Jurassic World: Evolution a lot already, if another game I had my eye on is suddenly -33% I might play that for a bit, and come back to JW;E.
2) Wind forward a few weeks and JWE has not only disappeared out of the top 10 but out of the top 50 in the Steam charts with a hugely reduced user count. (ARK is still number 8).
https://steamcharts.com/top
So after a hugely successful launch the user numbers appear to have flopped and I'm not surprised that they are having to bring forward to new titles and reduce the average selling price forecast for the remainder of the year.
Again, your comparison to Ark is inappropriate as highlighted. Secondly, the steam sale is on which will dramatically affect live player numbers, thirdly we know the sales numbers have been solid regardless of live player numbers, fourthly TenCent's WeGame platform is twice the size (so your sample size isn't accurate) & finally, the physical game was only released this week and has impressed me with it's strong initial price tag. Remember this across three platforms! Saying numbers 'have flopped' is silly as you are only looking at PC on the Steam platform. So maybe you're looking at live player numbers, during a major sale, for what, 15-30% of global PC players? So this, possibly, could be less than 8% of global players once you bring in PS4, XBox & WeGame? Something to think about.
At the current P/E I think holders have to be careful that this dinosaur doesn't come back and bite them.
At a PEG of 0.49, holders will be reassured that this is a company who have shown they are able to develop global multi-platform releases to tight timescales demanded by a global IP holder. The risk profile attached to this company may well not suit everyone, but as a long term investor, I am excited by what the future holds for Frontier Developments (LON:FDEV) and look forward not only to JW:E Add-Ons, but also Franchises 4 & 5 which are said to be well advanced.
Thanks,
IG
Thanks IG ..great response ..makes me realise how totally out of my depth I am in trying to evaluate investment in the sector
Hello Graham,
Thanks for your comments on Frontier Developments. Like you, I tend to be safety first investor and I am also attracted to the economics of video games publishers. I was also wary of Frontier because it is so highly rated but I spent quite a few hours investigating the long term record of this company and I came to the conclusion that the CEO, David Braben, (who was a founding shareholder about 24 years ago) has helped the company demonstrate technical and financial abilitieswhich actually make it investible for me, so you may also want to look at the historical record in case of any interest. I wanted to check that Jurassic World Evolution showed signs of success before investing any more, but following the announcement today, I have now topped up to my normal investment amount. I have a feeling that Frontier is the type of company which will always look expensive using the metrics you quote in your analysis. The other point I would make is that the Activision is about 50 times as big as Frontier and Nintendo even bigger so I would expect Frontier to find it easier to grow more rapidly than these two companies purely on the basis of size, particularly as Frontier's relationship with Tencent should help access to the Chinese market, so perhaps the metrics are justifiable for Frontier.
Thanks for the feedback on Frontier Developments (LON:FDEV), Peter. Good luck and perhaps I will join you on the shareholder register some day. G
Hi Graham. I realise that some metrics will be skewed by the nature of Frontier Developments (LON:FDEV) business but I wondered if you would be able to provide some insight into the significance or otherwise of the high Earnings Manipulation Risk score? Many thanks.
McBride - I would not touch any company whose main activity is manufacturing goods for supermarkets own label. Your own quality brand is essential when supplying supermarkets.
Funny enough article on bbc news site today
https://www.bbc.co.uk/news/business-44684306
Hi Graham , UDG, yes its not a Small Cap but its in your backyard, any brief passing thoughts on the purchase of two US businesses for $82.4 million? Thanks John
Hi JK, UDG has not been on my radar at all. Sorry, I would need to research it a bit before making any comments! G
RM (LON:RM.) please Graham. An overlooked, well managed company, that pays a good dividend, does what is says and goes about its business in a quiet and efficient manner. Good return on capital and free cashflow. I hold and may add.
Operating margins have reduced slightly as a result of profit seasonality at RM resources, although they are expected to recover due to a seasonally stronger second. The outlook statement is positive with management stating that it is confident of at least meeting full year expectations. The inference perhaps being that they may be beaten.
All the best
Jonno
Hi Jonno, thanks for the suggestion. I am planning to cover RM (LON:RM.) G
Jolly Good. Interested in your thoughts. A combo of product death, acquisition, turnaround and underlying growth make it a messy story...I've held for a bit over 2 years now (140p)...some dodgy banalysis here https://www.stockopedia.com/content/vvvvvvrrrmmmmmm-250993/
Thanks Graham; look forward to your views.
Jonno
Not sure what to make of Microgen (LON:MCGN) selling off a business today. It may be niche but it also looks highly profitable
Certainly, If they had bought it instead of sold it at these figures I'd have been quite happy.
I would trust the management here. My guess this has happened for one of two reasons. Either the cash is required for a large (and very profitable) acquisition,; or they are streamlining the business ready for another takeover offer. My money is on the latter.
Morning Graham,
You'll see the Frontier Developments (LON:FDEV) announcement, this morning. Digital sales of Jurassic World Evolution have been 'strong across all three platforms'. The game is launched 'physically' i.e. on disc, today. The board are guiding us towards the upper end of analysts range (£58M - £88M).
Liberium have changes their unit sales estimates from 1M to 1.8M, revenue from £39M to £59M and now have a share price target of £18.
The note ends: "well advanced with Franchises 4 and 5 and that Frontier have a platform and strategy that can support an accelerated development cycle both organically and potentially through M&A (our recent visit to the E3 Expo in LA highlighted that within the industry FDEV is viewed as a world class games publisher). Numerically that adds up to a gaming business that in the medium term can deliver £100m+ of annual revenue and margins of 30%+"
Thanks,
IG
Disclosure: I hold Frontier Developments (LON:FDEV)
Just worried that FDEV is massively overvalued, or do you think there is the potential to overtake its valuation? Thanks for the heads up but I think I will sit on the sidelines to see how it shakes down. Charles (Geordie, we met on the boat)
Hi Charles!!!
Yes, the valuation does seem astronomical, and it would depend on risk profile really as to whether one would invest or not.
The Bull case would say 'look at what we know':
1) Management have shown they are capable of delivery on a multi-platform, global release
2) Management keep beating forcasts
3) Consumers like the product
4) Tencent have invested heavily, and have a man on the board
5) Franchises 4 & 5 are well advanced
Ultimately, this all becomes irrelevant should we enter a Bear market, and valuation would be called into question.
Thanks,
IG
In case you missed it, posted over the weekend:
Creightons (LON:CRL) results presentation: http://www.piworld.co.uk/2018/06/30/creightons-crl-full-year-preliminary-results-presentation-june-2018/
Ten Lifestyle (LON:TENG) presentation at Mello Hever - sounds interesting http://www.piworld.co.uk/2018/07/01/ten-lifestyle-group-teng-investor-presentation-at-mello-south-june-2018/
Corero Network Security (LON:CNS) presentation at Mello Hever - helpful view on DDoS and how CNS operates in the sector
My morning smallcap tweet: McBride slide.
Utilitywise (LON:UTW), Marshall Motor Holdings (LON:MMH), McBride (LON:MCB)
Utilitywise (UTW) -collaboration with Vodafone and Dell EMC to launch an innovative Internet of Things (IoT) energy and building management platform. Lots of leveraging synergy speak. "This is a truly ground-breaking technology...a great example of how IoT is being used to disrupt and innovate...advanced data ingestion." It's giving me indigestion. No numbers.
Marshall Motor Holdings (MMH) CFO off as soon as new one hired. Kind words
McBride (MCB) warns FY adj pretax marginally below lowest forecast. Blames weak May and June. Does not say what F/C is. Peel Hunt (not house) is lowest of most recent pair at £34m and EPS 13p. Consensus 13.1p.
Re: Utilitywise (LON:UTW)
" It's giving me indigestion."
Do I detect a hint of cynicism? ;)
"No numbers."
I'm surpised they hadn't made some numbers up. They seem to be quitegood at that.
I should have thought that IoT is full enough of hyped-up garbage without Utilitywise (LON:UTW) adding to the mix.
It's all explained in this video:
https://youtu.be/TIhW61FMNIc
Remember, this post is only a bit of fun.