Small Cap Value Report (Tue 6 April 2021) - RCN, MTC, WIN

Good morning, it's Paul here with the SCVR for Tuesday. Hopefully you had an enjoyable long weekend.
Timing - should be done by 1pm today. Today's report is now finished.
Agenda -
It's very quiet for news today, so I'll cover a few stragglers left over from last week, in addition to today's relevant news.
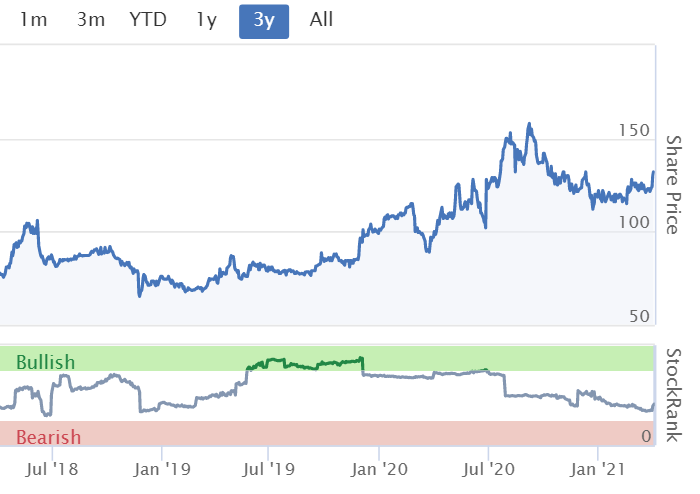
Redcentric (LON:RCN) - in line with expectations trading update for FY 03/2021. Upbeat tone to commentary. PER of about 19 - difficult to see much upside from here.
Mothercare (LON:MTC) (I hold) - several readers have asked me to review this share. Looks potentially interesting, but beware the huge agreed amounts to be paid into the pension scheme. Not enough info for me to form a sensible opinion here.
Wincanton (LON:WIN) - Positive trading update from last week. Lovely company, but big pension scheme cash outflows.
.
Redcentric (LON:RCN)
132p (pre market open) - mkt cap £206m
Redcentric plc (AIM: RCN), a leading UK IT managed services provider, today announces a trading update for the year ended 31 March 2021 and the sale of a non-core business unit.
This update is worded in very upbeat-sounding language, but it’s only in line with expectations, so logically shouldn’t have much, if any, effect on the share price. Mind you, logic went out of the window a while back, this is a roaring bull market now, so anything could happen.
Revenue and adjusted EBITDA for the financial year ended 31 March 2021 are expected to be in line with the board's expectations...
As an aside, I do want to stress that we’re not trying to predict short-term share prices in these reports. That’s down to unpredictable market sentiment. In markets this bullish, there are often a lot of new entrants (e.g. spread betting companies are reporting large numbers of new account openings). Inexperienced punters tend to chase stories, fad stocks (e.g. anything bitcoin-related, or cannabis, etc), and often have no idea how to value companies, just following prices up, buying on tips, unaware that they’re often participating in a bubble. A lot of money can be made from that type of speculation in a bull market, so good luck to them. The trouble is, people learn a lot of bad habits, which result in them losing the money afterwards, usually, when market conditions suddenly turn bearish.
Going back to Redcentric,
Net debt - better than expected. Usually companies report net debt excluding IFRS 16 lease liabilities (which makes sense to me). But in this case, Redentric includes (unspecified) IFRS 16 lease liabilities in its reported net debt. I’m not sure why they report like this. I’d rather see a table, with both figures given, for clarity.
Net debt was reduced by an impressive £19.0m, and the RCF bank borrowings paid off in full.
... net debt of approximately £15.6m (including £16.5m of IFRS-16 liabilities & supplier loans) being better than the board's expectations.
Redcentric seems to have been resilient throughout covid, and customers needing remote working support seems to have helped. Large scale projects were deferred though.
Cost savings (annualised) of £4m achieved (more than £2.8m originally announced)
Replaced ERP software with a unified system (to replace 5 separate systems) - sounds positive. Benefits include faster, and more accurate invoicing of customers. Further efficiency gains expected. Whilst good, this does worry me a little, in that it sounds as if financial controls were not very good to start with.
Diary date - 24 June 2021 for FY 03/2021 results.
Disposal - a small, non-core contract team has transferred to customer, Thales, re nuclear power station maintenance. Receiving £5.75m proceeds, and losing £0.72m EBITDA from profits in future, on the expiry of this contract.
My opinion - looking at an old broker note from late last year, and comparing that with the broker consensus shown on the StockReport, it seems to be about 6.95p EPS forecast for FY 03/2021. At 132p per share, that gives a PER of 19.
Given the company’s rather patchy historical track record, it’s difficult to understand why I would want to chase the price up above the current level.
I can’t see anything particularly exciting here, so let’s move on.
.
.
Mothercare (LON:MTC)
(I hold)
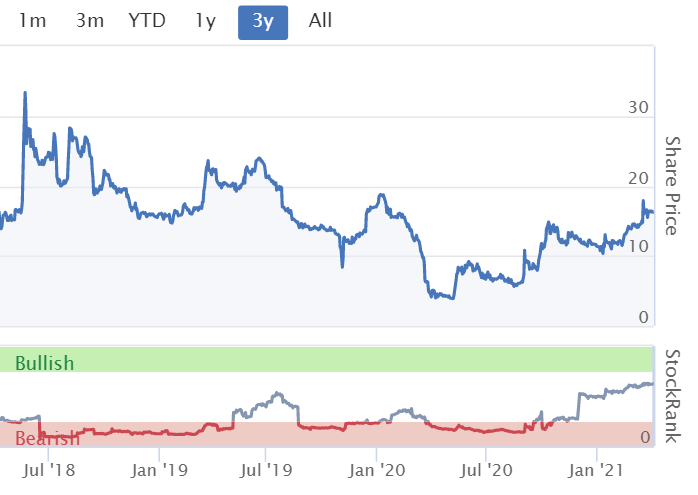
Share price: 16.4p
No. shares: 563.8m + potential dilution from warrants
Market cap: £92.5m
Several readers have been asking me to look at Mothercare. I should point out that I bought a small opening position a few weeks ago, on the recommendation of a smart investor friend, who told me it looks good. I trust his judgement, because of a very good track record. Probably like many readers, I often swap investing ideas with a wide network of investor friends. It’s interesting, and enjoyable, to jointly research things, and debate the pros & cons. A bit like we do in the comments section of these reports.
I’ve spent some time this morning reading through the RNSs over the last 6 months or so, and here are my notes -
Half Year Results - 28 weeks to 10 Oct 2020.
Key point 1: new business model, capital-light, international franchise brand. UK business was put into administration. Now all stores (over 1,000, in 40 territories) are operated by franchisees. So a greatly improved, lower risk business model.
Key point 2 - large pension scheme liabilities & substantial over-payments scheduled as follows:
FY 03/2021: £3.2m
FY 03/2022: £4.1m
FY 03/2023: £9.0m
FY 03/2024: £10.5m
FY 03/2025: £12.0m
FY 03/2026: £15.0m
FY 03/2027: £15.0m
FY 03/2028: £15.0m
FY 03/2029: £15.0m
FY 03/2030: £5.7m
Total: £104.5m
This is a huge issue, because the £104.5m agreed pension recovery payments above exceeds the £92.5m market cap. Therefore I would be inclined to add the two numbers together, to give an adjusted market cap (enterprise value) of £197m, in calculating my valuation.
The pension scheme outflows are therefore highly material, and cannot be ignored. These are huge future cash outflows, with money that could otherwise have been used to pay divis.
Pension scheme accounting is just ludicrous - under current rules, only £28.8m was shown on the balance sheet as a pension scheme liability. How can that possibly be signed off by the auditors as showing a true & fair view, when it clearly doesn’t! There’s an additional £75.7m of agreed liabilities that are not on the balance sheet, when they clearly should be. This area of pension scheme accounting badly needs reform, as real world liabilities are being under-reported often, as in this case.
Bank borrowings paid off with a £19.5m loan from Gordon Brothers Brands LLC. Terms need to be checked.
Franchise agreements - key ones are:
10 year agreement with Boots, for exclusive retail of Mothercare products in UK & Ireland
20 year agreement with Alshaya Group, its most significant franchise partner.
Profitability - despite covid major disruption, it achieved EBITDA near breakeven at £(0.1)m - very good in the circumstances I think, and it shows the beauty of a franchising model - i.e. the franchisees have to worry about the fixed costs, Mothercare is not liable. MTC’s revenues are mainly royalties from a % of franchisee revenues.
Franchisees buy stock direct from factories, not from MTC - I really like this business model, it’s very clever, as it removes working capital & all the hassle of handling stock, invoicing, etc. A very attractive business model.
Steady state post covid, company says it should be profitable (but doesn’t say how much)
Growth - with restructuring done, management can focus on expanding into untapped international growth markets.
Moved to AIM in March 2021, from main market.
Shareholder loans - extinguished, by conversion into new shares, on 16 March 2021. Two key shareholders are :
Richard Griffiths (well known shrewd investor): 33.2% of equity +8.6m warrants (check the terms, and total potential dilution)
Lombard Odier: 16.4% + 4.17 warrants.
Total shares now outstanding: 563.8m + warrants
Waiver of rule 9 of Takeover Code, so shareholders going over 30% does not trigger a mandatory full takeover bid.
Trading update - the most recent update is from 25 Jan 2021.
Net worldwide retail sales were £258m for Q1-3, down 38% on LY, obviously hit hard due to covid. This is the franchisees’ sales, so MTC earns a cut on this.
Guidance on revenues is £320m for FY 03/2021 + c.£80m of invoiced shipments - possible delays due to container freight problems.
Excluding Boots, c.90% of franchisee stores now trading.
Improved picture expected for Q4 of FY 03/2021.
Overall revenues down by a third for FY 03/2021, and should then recover back to more normal levels post covid.
Profit guidance - small EBITDA loss for FY 03/2021, which means H2 should be similar to H1. Not a bad outcome in the circumstances, although I wonder if any franchisees are under financial pressure & could go under?
Brighter & stable future expected, cash generative & profitable.
My opinion - looks interesting as a special situation, but I cannot value it because I’m missing key information, primarily how much profit & cashflow it’s likely to generate in future? Also, what excess (if any) would there be after making the huge payments into the pension scheme over the next 10 years?
Could the pension scheme liability reduce as bonds yields rise (if they continue to do), therefore I wonder if the pension scheme over-payments might be revised down in future?
I like that MTC has 2 cornerstone investors who have supported its restructuring. I also like the low risk franchising model.
We need to find out the likely level of profits & cashflow, and whether that’s enough to pay shareholders decent divis. I can’t find any current broker research unfortunately.
.
.
Wincanton (LON:WIN)
407p - mkt cap £507m
Wincanton, a leading supply chain partner for UK business, today provides an update on Q4 trading performance in advance of the release of its full year results on 20 May.
WIN’s year end is 31 March 2021, so Q4 is Jan-Mar 2021.
Wincanton delivers strong trading performance & expands eCommerce capacity
I’m impressed with the highlights in this update -

There’s lots more detail provided in the announcement, which I won’t regurgitate here, see the RNS.
My opinion - trading seems to keep getting better, every time Wincanton reports. It put out a bullish update in Jan 2021 too, and is now saying it’s trading ahead of that. The reason it looks cheap (still) on a PER basis, is because of the pension scheme liabilities, which is a large cash drain out of the company. See my report here on 2 Oct 2020 when I covered that issue.
This does seem a very well-run company, performing strongly. If there’s another pandemic, then we must remember to buy bombed out shares in logistics companies.
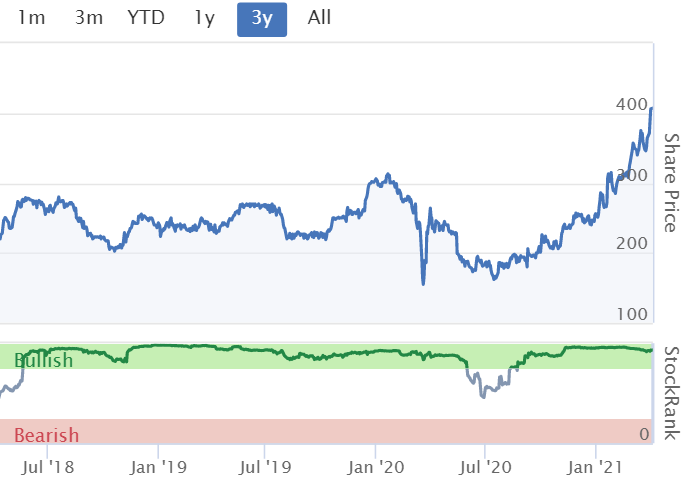
It's now well above the pre-pandemic valuation. Note the high StockRank.
When I see a chart like the one below, I do wonder if it might need to have a pullback & a period of consolidation maybe? Who knows, anything can happen.
.
.
That's it for today, see you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

92 comments
Let's hang Boohoo for getting three items wrong in their hundreds of thousands of items.
Three items.
{sigh}
Yes johnny just three items , that accidentality :
There are potentially plausible and defensible explanations for what has gone on; but if you believe that this is about "just three items" I think you need to take a breath and sit and think in a darkened room.
On Mothercare (LON:MTC), one tip I would advise anyone looking to buy, is to check out the birth rates in their key markets.
I know in some countries birth rates have gone down in early 2021, and expected to stay low for the rest of 2021, due to COVID.
However, I have also read hypothesis/theories that birth rates would be going up, due to so many people having time on their hands at home...
Either way, birth rates are important as they will be the macro drivers for demand for Mothercare products in the next year or two.
Wincanton have a new management team with apparent good pedigrees. I reviewed their recent webcast and was more than impressed with their grasp of the business, their understanding of where the best margins lie in their 4 sectors and the growth of their B to C business. I believe they have the opportunity to enhance their PBIT as a % of sales which could result in a substantial increase in EPS? It may take awhile but , in the meantime, very solid basic business.
RNS now up for Xlmedia (LON:XLM)
EGM All Resolutions passed.
Open Offer over-subscribed.
£27M raised
New shares enter the Market tomorrow 07/04/2021.
Its going to be interesting / err exciting for Xlmedia (LON:XLM) long share holders.
I would never invest in Mothercare while they have a male CEO and a male Chair which they have always had. In fact at various times they have had no woman on their Board at all which probably accounts for their poor performance over the years. I remember one instance where a mother of twins complained that her local Mothercare branch (I think it was Reading) had a front door that was too small for a twin buggy to enter so she went somewhere else. The manager was probably male too! Chris
re Mothercare (LON:MTC) - I find the share analysis page by Paul and Jack very useful to understand accounts and how to evaluate shares. But of course, there are thousands of shares where we only have the Stocko screens and info. So looking at Mothercare (LON:MTC) and the stocko screen in isolation we see a massive red flag i.e its Z score/bankruptcy risk is off the charts ie badly in the red. @PaulScott or the accountants who contribute here: can someone explain what we need to look at in the accounts to evaluate if the flag above is correct or a false positive flag???? Is MTC really carrying such high bankruptcy risk? I assume not by Paul's write up??
As I flagged up in the article about Mothercare (LON:MTC) , debt for equity swap (conversion of shareholder loans into new shares), and a new facility used to repay the bank facility, are good signs of improving financial stability.
We would really need to see all the numbers in the next set of results to be sure. But it looks to me as if the restructuring, supported by 2 major shareholders, has probably removed the insolvency risk.
Z-scores are a useful flag, but in a special situation like MTC, they tend to be trailing indicators, and the situation looks to have already moved on, in a positive way. That should feed through into an improving Z-score when the FY 03/2021 results are published.
Another point to consider is how current trading is going. If a company is losing money heavily, then logically the bankruptcy risk is probably getting worse. In the case of MTC, it has guided towards a small EBITDA loss for F Y03/2021, which is reassuring, as the cash position should then be fairly stable.
In my experience, if 2 large shareholders have just shown confidence in a company by converting their loans into shares, then that's a very good signal that the company is well supported, and not likely to go bust.
That's a really important point actually. We've seen with a number of pubs groups lately, that the key major shareholders have proven ready & willing to pump in more cash at a price quite favourable for other minority shareholders. Whereas Revolution Bars (LON:RBG) (I hold) in contrast didn't have strong supportive shareholders, so it had to deeply discount its equity fundraising last year.
Therefore I think we need to focus on that point at financially distressed companies - a dominant, supportive major shareholder or two, can be very positive. But it's also a risk, as they might stuff minority shareholders by diluting us to nothing, or do a lowball takeover bid. Difficult isn't it, as no two situations are the same.
Regards, Paul.
TKs for a fast and very thorough response.
Thanks for taking the time to respond to this post with such detail, really useful and interesting insight
Considering other comments this morning this may not be the time or place but i just wondered what other peoples experiences have been . . .
I am not a trader , more a medium to long term investor but with this mornings bullish mood in the market i thought it an opportunity to sell out of a couple of positions where i didnt see much more upside. On each occasion looking at Level2 whilst placing orders i have 10 seconds left on my sell option and i see the price drop and as i press the button i get the 'out of time' message . This was in my HL isa . I know MMs and Institutions have the odds in their favour but i am not impressed. The first one was just after 8am so i expect some unusual movements but the other was after 10am .
I am not impressed or am i expecting too much ??
It does happen, HL are not too bad, orders usually go through but you can leave a limited order, which should trigger when your price is reached, this saves watching the prices all the time.
Or you can accept as soon as the price is quoted, then less likely to be filled by others.
herbie ,
thank you,
To be honest i have had a couple of very good buys through limit orders this year, where my price has been filled in an intraday dip so i suppose it is swings and roundabouts but when i have 10 seconds left on the clock i think that is a bit much.
Richard
I think HL were struggling this morning. Bought a couple of stocks in a new ISA subscription and it took over an hour for them to show. I put it down to the start of a new tax year and positive news from the weekend (particularly the US)
Stocko was slow this morning too.
Maybe first day of the New Tax after a long weekend shutdown after a sort-of lockdown releasing announcement with corporate news excited the investortariate?
"Stocko was slow this morning too."
Don't forget, it was very cold.
As far as I know, HL do not provide Level 2 prices. They do provide live prices, but my understanding of Level 2 pricing is that it provides bid and offer prices for a share, plus a history of recent trades.
With ISA contributions for the 21/22 tax possible from today, I presume volumes are higher than usual. IMHO, as somebody who has used Hargreaves Lansdown (LON:HL.) for many years, they are consistently pretty hopeless at providing a reliable trading interface if dealing volumes are at all elevated. Essentially, since its a perpetual problem, one can only conclude that they have made a conscious decision not to invest properly in their trading platform; at least that's the conclusion I have drawn.
This contrasts greatly with say Cmc Markets (LON:CMCX) which has happily paraded their 99.97% platform availability through the pandemic, as per https://www.investegate.co.uk/...
...but AIUI do not yet support ISAs or SIPPS. I am hoping this will change as they roll out new functionality.
Its not just Hargreaves Lansdown (LON:HL.) that is deficient. Ig Group (LON:IGG) has also come in for a lot of stick over the last year or so but that's not a platform I have ever used.
Blimey, this is not a Woke site where subscribers get to dictate what is and is not up for inclusion in daily output or subsequent discussion. If there's something of interest going on in any setion of the market, particularly in areas where they have expertise, Paul and Jack should be free to write about whatever they like.
No, absolutely not a woke site dedicated to equality.
Just Investments information here.
BSV
I get the point about migrating the Boohoo (LON:BOO) (I hold) chat onto a separate thread. That's a good idea, as it does tend to take over here sometimes! I think we'll do that in future, thanks for the nudge on that point. I can always put up a link in the main reports, whenever anything relevant comes up (e.g. trading updates, etc.)
Regards, Paul.
I disagree with hiving it off - I am more in agreement with your comments this morning and I quote
Hence why I do (usually!) enjoy the discussions here with readers, it's fascinating to see a range of opinions, then we can weigh up the pros & cons.
Paul, I hope giving us a rundown of your top 20 holdings hasn't fallen off your to-do list ......
Paul, I hope giving us a rundown of your top 20 holdings hasn't fallen off your to-do list ......
I know, it's one of many jobs I need to look at. It's a big job, and I don't want to feel like it's a chore, so will do it when inspiration suddenly kicks in. Timing uncertain.
Twenty in one hit is a big ask. How about a few when the time is available? I will certainly be interested to see your holdings and assessment of them, Paul
I do wonder if it is a good idea printing your top 20 holdings Paul. Forgive me everyone but the point is Paul gives us insight and considered reflection on these shares. A top 20 list makes it feel like a tip sheet and in my experience people just buy those stocks and then complain like mad when they don't perform. We are supposed to be doing our own research and investment.
Big jump on no news for £TRCS
Does anyone know why it might be up nearly 10% this morning? Tipped maybe?
SCSW tip at the weekend.
Tipped by a respected tip sheet, hoping they may post an upbeat statement soon.
You can register for a PI World session with the management this month, if you are interested
Small Company Sharewatch tip over the weekend, along with Xlmedia (LON:XLM) and Lookers (LON:LOOK), all 10% up as they generally are after a SCSW monthly report.
Trading update from Argentex (LON:AGFX) for the year to March suggests that business has recovered from the fall in f/x activity it experienced in the first half, unlike the share price.
Tbh - Argentex (LON:AGFX) is valued roughly a few % off from where it was before it fell off the cliff. I picked it up at the bargain price (or so I thought at the time) at 140p ish - only for a bad write up by SCSW (apparently) to lead to sell off to 130ish level - just before the nose dive. Interesting sector ....with a few players trying to knick clients from banks .....Alpha Fx (LON:AFX) , Equals (LON:EQLS) , Transferwise (about to ipo)
I'm not a Boohoo (LON:BOO) holder and think that the strategy underway (strategy shift to be more UK centric for next leg of growth suggesting that international growth has limitations and/or that it requires significantly more investment?!) may be more tricky and reflective of some growing pains than seems commonly assumed as I summarised here last year -> https://www.stockopedia.com/co...
Obviously I see their past success and future potential. They are clearly capable and have achieved a lot. This current Karen Millen v Coast v Dorothy Perkins etc pricing problems perhaps plays to the view that they are having growing pains due to their past success, current size and (IMO) switch of strategy?
But hey, snipping stories in the press ain't going to do much to the share price of such a sizeable business unless they signal something substantial. I suggest that the effective sideways movement through covageddon perhaps reflects a bit of angst re strategy....a show us the money thing. Price could move meaningfully either way and I'd guess it all revolves around how need for investment plays against UK growth metrics plus a dash of what was sustained top line from covageddon.
Welcome everyone to Boohoo-opedia
This is the place to come to complain that the company’s Delboy practices are fine because other companies are pulling off the same dodgy dealings.
Also, please feel free to register your displeasure at any media outlet that happens to mention this company in a less than flattering light. It is clearly the result of bias, racism, the British disease of knocking anyone successful, the weather, Brexit, the government, Trump, or them just picking on the company like playground bullies.
Personally, I lament the decline and demise of Flat Earth Monthly, Superstitious Times and the much loved Lefty Leanings, though I am assured by some that these once great publications live on in some way on a completely unbiased publication called The Social Meedya.
Fast fashion is uninvestable due to its terrible environmental record so I don’t hold, but oops, I find I do hold via collective investment. So, yeah, how dare anyone say anything nasty about this wonderful company.
I tend to agree with your last paragraph as I think these stories will not be going away any time soon and could even escalate. This could prove very costly and distracting, while deterring institutional investors on ESG grounds which could be a big technical headwind that could linger for some time. No position either way.
I think the point about this Graham, is that the media has largely done it's job and the Company has responded. It doesn't make them lovely , but it is market forces in action.
Sadly, the media has a habit of being cheap and lazy...so the BBC for instance runs a headline story on how a reporter bought a coat at a different price than her friend. That's just cheap shot, easy , non-journalism.
It's just easier to keep kicking anything (Celebs, Companies, whatever) than do journalism. If the activists wish to have long term integrity, then they need to encourage when co's put their house in order...not just keep kicking. Which are you? kicking ? or genuinely encouraging change for the better ?
Re: Boohoo (LON:BOO)
Sadly, the media has a habit of being cheap and lazy...so the BBC for instance runs a headline story on how a reporter bought a coat at a different price than her friend. That's just cheap shot, easy , non-journalism.
Surely the question for this board is whether it matters to Boohoo as an investment?
If it doesn't then the worst thing that happens is a short-time share price drop that gives people who believe in the story an opportunity to buy in cheaper. That's not a bad thing, for an investor. If it does then it's additional data to use to assess whether the company is being well managed.
On the face of it, the story indicates something between poor operational controls and poor brand management. Trying to pass off one brand as another, in an amateurish manner, is a really stupid thing to do for a company that relies on its brands. Good retail companies can destroy themselves by damaging their customer reputation, ask Gerald Ratner.
Operationally if you compare the way that Boohoo have integrated their new brands with the way that ASOS have dealt with Top Shop it's chalk and cheese. ASOS shut down the Top Shop website and ported all stock over to their own platform - that's a bold move, but a sensible one if you want to keep control of your brands and inventory.
Overall, I doubt any of this matters. The drive to online fashion retailing is unstoppable. But while the company keeps on scoring own goals it will keep them on the front pages. Investors should focus their ire on Boohoo's management, not the media coverage.
timarr
Hi timarr,
Good, balanced comments there on Boohoo (LON:BOO)
As a former industry insider, I can tell you that re-labelling of clothing is widespread, and perfectly legal. What would happen is that (say) New Look would cancel an order -maybe because it was late, or because they'd realised it wasn't going to sell well. The supplier is then stuffed with a lorry load of imported clothes with New Look labels on them. They ring up Pilot (my old employer), who buys the stock cheaply, and sends it to a re-labelling firm in Devon, who cut out the New Look labels, and sew in Pilot labels. The stock is then delivered to our warehouse, tagged with freshly printed Pilot barcodes, and goes out to the shops.
The main point is, it doesn't matter! The customer makes a free choice to buy a product or not. If they don't like it, they return it for a full refund.
In the case of BooHoo's latest PR slip-up, it seems they clumsily handled it, cutting off the Dorothy Perkins label with scissors. Obliterating the Oasis label with marker pen, or something like that. That is sloppy. But there's absolutely nothing wrong with selling the same or similar products with different brand names, at different prices.
I think what they've done wrong here is being clumsy, being found out, and upsetting one customer who unfortunately was a journalist, and thought great I've got another BooHoo bashing story! That said, if one customer has been upset by this, then probably others have too, and in the social media world, it's best not to upset customers, as they broadcast it around to everyone they know very often.
What also frustrates me, is that instead of just saying, hands up, we're clearing stock left over from closing the stores, so we spread it around the group. Sorry if that upset anyone. Instead, mgt at BOO seem to have a go-to response of denying things, launching an investigation, etc.
There are still some rough edges at Boohoo (LON:BOO) , no doubt about that - there can't be a single investor who isn't already aware of that!
But ultimately, the figures will do the talking, all this is background noise. Let's see what the results look like soon.
Regards, Paul.
While I agree that Boohoo (LON:BOO) is doing the right things to trade well - ie leveraging multiple brand websites to shift stock - this whole episode has made me realise that they're focused too much on short term trading and not enough on long term brand.
It is absolutely right that Oasis quality would feel out of place in Karen Millen. It feels like Boohoo are buying brands, just to milk whatever brand equity and customer loyalty there is, for short term revenues and profits. Rather than buying brands, and aiming to keep building and growing them for the future.
In the past, I've always seen Boohoo (LON:BOO) as a potential coffee can stock, but now my view is that it'll be a good short term trade for the next year or two, as they milk to death the acquired brands for all they are worth, to deliver the high growth FY22 and FY23 expectations.
I see things a little differently. I offer this for comment:
When I was in my 20s I was OK shopping at M&S and Jeager etc - and so were my parents
People in their 20s now tend to not shop at ASOS / SuperDry _because_ their parents do.
IMO fashion brands have a shorter lifecycle and so I think it is easy to get hung up on BooHoo (the brand) as it's value will diminish over the next 10 years. The thing to focus on is PLT and what comes after that.
There is a durable moat that can be built from the ability to provide fast fashion and build fast fashion labels - a much more durable business model than Top Man, Jaeger, Dunn&co...
RE: Boohoo (LON:BOO)
Hi Paul
But ultimately, the figures will do the talking, all this is background noise. Let's see what the results look like soon.
Agreed. From what I can tell the Gangmasters and NCA investigations haven't uncovered anything major - some book fiddling and labour rule violations, but nothing that would lead to criminal charges. If that stays the same then I think they'll come out the other side of this OK.
I do wonder, though, whether the time for edgy entrepreneurial leadership is over? What the company needs now is solid operational progress - migration of the new brands onto the core platform, sorting out the EU shipping issues, management of the new factory and working arrangements and clearly addressing the ESG issues.
Given the repeated own goals and the fact that Kamani and Kane have relatively small stakes I would imagine that institutional investors will be giving this some thought.
timarr
timarr
Mahmud Kamani owns nearly 13% of Boohoo shares. That is certainly not a small stake. Mahmud Kamani has the majority of his own personal wealth invested in Boohoo shares.
Nerdy Analysis alert!
Certainly his stake is not trivial, but your statement did cause me to have a quick look.
The Liverpool Echo reporting on the Times 2020 rich list (I don't have a Times subscription to check the source) reports that Kamani and family were worth £1,030m; £929m of which was Booho shares.
Other info in the short piece infers a share price of c. £2.16 which suggests a valuation date in either March 2020 or July 2020.
On that basis I cannot make sense of the £929m valuation (implying about 33% of the shares - 430m shares) .
Anyway it looks to me superficially that the Rich List may have arrived at their "net worth" calculation by taking their valuation of the shares and adding it to the c. £100m that Mahmud received from selling shares in December 2019.
If so then the Rich List calculations assume that Kamani has no other assets (property etc) and received nothing from the flotation of Boohoo in 2014.
Actually I had not intended to go off in such a forensic analysis, but I got drawn in by the numbers!
The point that I was trying to look at was whether it was safe to assume that the large director shareholding meant that directors interest were aligned to those of other shareholders. I have made the mistake of assuming that in the past.
The anomalies I note above, mean that I cannot really validate whether it is true that the majority of Kamani's wealth is tied up with Boohoo shares (but I doubt it given that there is so much that the Rich List does not see). So I cannot easily establish how closely Mr Kamani's interests are aligned with ordinary shareholders.
I'm sure that some will read this as an attempt to dig up some dirt and failing to find it, if so fair enough; I genuinely have no skin in the game in any direction here. I just get curious when I see signs of blind group-think emerging.
Mahmud Kamani owns nearly 13% of Boohoo shares. That is certainly not a small stake. Mahmud Kamani has the majority of his own personal wealth invested in Boohoo shares.
That's nothing to do with the point I was making, which was that he doesn't hold anything close to a controlling stake.
timarr
Well Paul, after all the 'stand up for Boohoo (LON:BOO) at any price, run to the defences', you are the one to deliver a balanced, fair assessment. Thank you and protect us all from the emotional ravers, here or anywhere,
How kind, thanks ridavies.
I do try to be rational & think things through, but am not always successful in that - after all, we're all human, and hence are driven mainly by emotions, often without realising it! :-)
Hence why I do (usually!) enjoy the discussions here with readers, it's fascinating to see a range of opinions, then we can weigh up the pros & cons.
Best wishes, Paul.
Paul,
Surely in the example you cite, Pilot would only have been happy to take on the New Look stock if they were happy that the quality matched their portfolio? And also that New Look were not also selling the same brand at the same time?
That's not what happen here, which could be characterised (in the case of the skirt) as passing off cheap Oasis tat as higher quality Karen Millen items.
Going back to an analogy earlier in the thread, I would be pretty peeved in my four pack of Punk IPA turned out to be Tesco's own brand with a fake label crudely pasted on it.
I'm not especially interested in the "morality" of this, but there is no point in buying a brand if you are then going to debase it to make a quick buck.
What I find especially disappointing however is this from the Beeb article.
OMG how did this happen.
To save them spending 18 months on an investigation, I can offer up the two most likely explanations.
1. It is company policy coming straight from the top.
or
2. The person making the decision is incentivised to 'do the numbers' at whatever cost.
Dodgy management / corporate culture can be very hard to shake off, even if there is a will to do so.
I once worked for an organisation that had a 'do the numbers whatever it takes' mentality.
At one stage a couple of senior managers were fired for aggressive accounting (to describe it generously) in order to make the numbers look good. A significant restatement to the parent company accounts followed and a new management team was brought in to clean up the act.
Around seven year later some relatively senior staff were fired for accounting fraud (not for direct personal gain, but to make the numbers look good). Most of the rest of the senior management team were dispensed with, not because they were directly implicated but because they didn't know (or didn't care to know) what was happening on their watch.
As best I know, the organisation is still as dysfunctional as ever and lets just say that shareholders that have remained loyal to the parent company have not been richly rewarded.
Now I am not suggesting that Boohoo does have a corrupt corporate culture, I have no idea. I do however guard against blindly assuming that it does not.
Paul
Maybe Boohoo sent this stock for re-labelling and three items weren't re-labelled properly. It is three items only.
I genuinely don't understand why BooHoo-heads are upset at the reporting of goings on at BooHoo in 'the media'. Whether the dreaded Beeb report the fact that they are selling Oasis products under the Karen Millen brand or not, brand devaluing still happened.
Bad press is good for Boohoo holders in the long-term as it is seemingly the only way to get the company to clean up their act. The report by Levitt QC found that Boohoo knew full well about working practices in Leicester, but not until the story broke in the British press who can't help but drag down a homegrown success built on quasi-slave labour, did Boohoo move to do anything.
One of my holdings, Serabi Gold (LON:SRB) was recently engulfed in bad press wherein a mine worker had died. I was not angry at mining.com for reporting the story, but the company, for allowing it to happen. I hemmed and hawed on selling my stake, but decided against (because gold price!). Lo and behold, an RNS today reveals that this years books will be late as local managers have allegedly been embezzling, and wait while we're at it, the gold content is lower than assayed. I can't be mad, the death of the mine worker told me all I needed to know about Serabi, but I held on.
The same goes for Boohoo, time and again they've shown who they are. We can't say we weren't warned ( I sold my whole stake in Feb).
Brilliant! I remember the days people used to complain about excessive discussions about B**xit, and it pretty much became a bad word on here. I wish the same could happen with another B-word - B**hoo unless there’s real news like trading updates or results. Maybe Stockopedia could add a ticker filter?!
Steady on – you’ll be pointing out Boohoo (LON:BOO) is a Large Cap next ! Seriously, I can appreciate the history and why the company is frequently mentioned in SCVR but I feel numerous topics are raised here as it’s seen to be the ‘best’ place on Stocko to do so (I know threads can be set up under Discuss). I have suggested to ED & Co that SCVR should ‘do what it says on the tin’ and stick to Paul and Jack commenting on Small Cap results and RNSs with additional comments / discussions from subscribers. I proposed a daily ‘General Forum’ (with no lead author) be set up where subscribers can post comments and ask for opinions on any other Stocko relevant subjects – no action as yet.
Personally, I like that everything is discussed in one place as it makes life simpler. I have one of those mice that have a wheel on it to bypass the less interesting posts.
you forgot to include global warming!
Cunard cruise line which is owned by £CCL has reported its busiest day of bookings in the last decade following its launch of UK-waters cruising. Good news for Saga (LON:SAGA) owners as Saga is offering similar UK-waters cruises from June and will be experiencing the same high demand. My view is that when the boats are back sailing the shares will be much higher. Between now and then it’s insurance business is producing good cashflow to cover the losses from the travel business.
On bearish side, Norwegian Cruise has given up running any cruises departing the UK this year.
Is it just me that can’t access folios today?
Hi, no I can't either I'm afraid. It must be a glitch. I was trying to update a position and when I clicked save it wouldn't let me. Follios are blank on the Today screen too. Hopefully it will be fixed soon.
I'm accessing mine with no problems. Response is a little slow across the whole site though.
Old Stocko site is poor when I tried it earlier.
I have my own independent system for live share tracking.
BOOM!
Xlmedia (LON:XLM) has surged to 60p today as the "Offering" of 2 weeks ago appears to have been committed to the market, and a rumoured favourable write up over the weekend in another investors publication.
(Now +62% up for me...). Some rumours suggest Xlmedia (LON:XLM) is targeting 100p.
Ig Group (LON:IGG) has blown off its wobble of 2 months ago re., its US Tasty Trade purchase and expansion, with complimentary actions and results from its competitor Cmc Markets (LON:CMCX) doing the same.
You could have topped up Ig Group (LON:IGG) @780p a few weeks ago... back to 920p with some targeting the 1000p. (+60% for me and a generous dividend stream.)
Big for me (+54%), International Personal Finance (LON:IPF) continues to hold around the 105p. Steady, mature, organic growth, over the medium term, I expect from this sector-leading "SuperStock".
Its finally the new HMRC tax year. ISAs, allowances, tax bands and threshold's all reset today. I intend to pay my taxes due as soon as I can.
StockRank + Magic Formula + "SuperStock" status / Time * Quantity Invested = Winner
Certain "public relations" companies (Prime Minister Harold Wilson called PR practitioners "organised liars") are paid sometimes not only to promote clients but to denigrate their client's competitors as well. I suggest that there are firms out their paid to do damage to Boo Hoo at every opportunity.
First it's 'the British Press' now it's shadowy forces arrayed against beloved Boohoo that are responsible for revelations about yet another cock-up* (this time brand devaluation). No need for outsiders to damage Boohoo's image, they do a good enough job of that all on their own.
*let's be very generous and assume an error.
RE Boohoo (LON:BOO) comment on bbc.co.uk over the weekend, clearly the company is in the spotlight. The following kind of situation may well occur when on an occasional basis when acquired brands and their sites and products are integrated into the Boohoo (LON:BOO) family. However, this one is particularly clumsy, and hopefully this can be stopped. I'm a great supporter of Boohoo (LON:BOO) and it's future, but shooting themselves in the foot like this will at best only slow things down.
'
A woman who bought a skirt from Karen Millen said she "felt lied to" as it had an Oasis label covered with pen.
Joanna Sikora got in touch with the BBC after we revealed that Boohoo-owned brands had sold the same clothes at different prices.
Boohoo said it was investigating how this had happened and the "miscommunication was not intentional".
But a company insider told the BBC "it happens all the time". Boohoo is yet to respond to these claims.
Miss Sikora sent the company photographs of the altered labels and she received a refund.
This is typical of the self loathing British press. Why can't we celebrate a successful British business? It is not ideal but is it particularly newsworthy? I don't think so.
From an investors perspective I think Boohoo will 'keep their head down', say the right things and blow everyone out of the water when they release their next trading update.
What a fuss! BooHoo behaved correctly by refunding the difference and to the customer's satisfaction - I assume as pricing was the substance of the complaint. They are also attending to the problem. The refund action would make me think more of the Company - not less.
As usual with the UK press - let's ignore that and continue knocking the Company. Why not celebrate the outstanding value they gave?
Perhaps Boohoo (LON:BOO) could celebrate being such a great British success story by including a free flag with every order?
Then their customers would all be able to join in by waving their Boohoo Union Jacks (made in China).
Perhaps we should be worrying more about Brits waving Chinese flags.
Is that a self loathing reply to Camraid ;-)
@JohnEustace - I remember going to a presentation by Digby Jones discussing what we do in Britain and what we should be proud of. Manufacturing in China for low cost goods is really nothing to be ashamed of. We do the design, branding, etc.. Of a £20 sale price circa £1 will go to China in some instances. We focus on high level engineering and manufacturing of which we are amongst the best in the world.
This country has an opportunity to be brilliant in so many ways. Those poking fun at flag waving make me laugh. There was a social media post criticising a union flag on some porridge. The poster was criticising flag waving whilst his own profile was adorned with an EU flag.
Anyway, back to the investment case for Boohoo. Manufacturers in China, Turkey and elsewhere will make clothes for a variety of retailers. This really was a non story - especially for the business section of the BBC website. Boohoo have a challenge of integrating the various brands and supply chains. I think they will do so. Their earnings will be hard to resist.
Onwards and upwards.
Presumably the BBC will also be investigating why the difference in Shell petrol near me can differ by up to 16p per litre and that Tesco Extra prices are frequently cheaper than Tesco express .
Supermarket pricing power and petrol pricing are occasional topics for the Competition and Markets Authority and it's predecessors so be careful what you wish for...
Also I think in this context the issue is trust rather than price per se. The goods had one label taken off and another written on so the brand image of a differential in quality was clearly a nonsense.
Supermarket pricing power ?
Within a 20 minute drive, I have Tesco, Sainsburys, Morrisons, Asda, Waitrose, M&S, Lidl, Aldi, Budgens, CoOp plus a range of specialist shops. The customer can very easily move from one to the other.
Compare with stock brokers, where once I have my account, complete with just "nominee" holdings, it's pretty difficult to move accounts if they put the fees up. Yet nothing ever gets done about competition in this sector.
Arguably they ought to legislate for either overnight in-specie transfers when changing brijers, or better still abolish the nominee systems and make direct holding standard.
It was actually the second similar Boohoo (LON:BOO) (I hold) bashing BBC story in three days - the first was with a coat. The most interesting point for me was that lady who bought the skirt said she would 'never shop at Karen Millen again'. A reasonable reaction, but she might well buy cosmetics from Debenhams along with the brand's 6m other beauty shoppers including 1.4m on line Beauty Club members now run by Boohoo. That's the power of multi brand market platforms and why a number of companies are so keen to build them up. I only hope this broad global on line presence, plus Boo's passion and persistence will find its way into the share price.
Yes I agree it's a storm in a tea cup, but the press are on to this now, and they'll be like a dog with a bone, so I think however convenient it would be to sell the same stuff across all websites at different pricing, we're going to need to get on top of this, and not keep feeding these stories. There may come a day when they can do this, perhaps they can even get clothes made with multiple tags, and just remove the ones of the other brands leaving the correct one, today isn't that day, I think they're going to need to try to maintain different lines across the different brands they've bought otherwise this kind of story will run and run, until the new brands have no value, which I'm sure we all agree would be a shame.
but if £boo are managing to get rid of all this stock for inflated prices and in the main are getting it sold , then the bottom line is going to bulge, selling £10 coats for £40 is a huge profit , but ultimately it could kill the very brands that they have bought.
I personally think Boohoo (LON:BOO) figures are going to be significantly ahead in their next update, will all eyes on ESG, the US and new brand channels like beauty and debs brands.
I worry about the effect of Brexit on their ability to service the EU market quickly and cost-effectively. I'm reading a lot, as I'm sure we all are, on the various barriers that UK companies are facing in the absence of an EU based distribution centre. Please someone correct me if BOO are not distributing to the EU from a UK warehouse,
The same "BBC" who consumes 10% of UK Courts time, disproportionately targets women and the poor, imprisons people over a minor media subscription, treats news shows like an Islington Labour party rally.
... They are the racket who need to be shutdown.
Sorry. Have I accidentally found my way to the website of the British Journalism Review, or is this still an investment site?
Its only an Investment site... if you Invest... otherwise technically its a "no advice" data site with commentary.
I invest.
Journalists rock investors' boats as they tease sentiment that is the basis of momentum so hence the noise
Another semi storm in a tea cup, I well remember Sainsbury’s having a problem with items at different prices to those charged by Argos in the same store, they soon sorted it out.
Ofcourse it's newsworthy! The brands that Boohoo have purchased have quality perceptions by the general public so if you bought from Karen Millen or Coast you should expect a better quality garment/material than from Oasis for example. By selling the same item at different prices will destroy brand loyalty to the more expensive brands so they need to be careful and stamp on it quickly.
Had a few beers in the park with some friends from work last week.
I went to Tesco and bought four cans of Punk IPA for £5.75. One of my colleagues went to M&S and bought four cans of Punk IPA for £6.75.
Does anybody have the contact details for the BBC so I can report this scandal to them?
Do you think Tesco and M&S are two brands under common ownership, Chris? Whilst that would obviously be wrong, it would at least draw some sort of vaguely relevant parallel with Boohoo (LON:BOO), which is presumably your aim. What you have described is the basis of commerce, so would hardly be newsworthy.
And yet, from the BBC link to the photos of the offending article labels, it appears that they have the same (identical ) 21 digit inventory number....
Sumo (LON:SUMO) FY20 results webinar with management today 6.4.21, 1pm, incl Q&A. Results ahead of upgraded expectations although acquisitions muddy the picture, so it will be good to hear more. Zeus Capital upgraded 2022 forecasts & 2021 forecasts stay the same. Register.
Tomorrow 7.4.21, 6pm, don't miss the Stockopedia / piworld StockSlam. Ten illustrious investors present their best stock idea in just 3 minutes, followed by Q&A. Fast-paced, fun and informative. Register here.
Paul, if time allows would you be able to give us your assessment of Mothercare (LON:MTC) ?
OK, seeing as there's nothing of interest in today's news, I'll look at Mothercare (LON:MTC) (I hold) next, it has been on the to do list for a while!
My morning smallcap tweet:
Ilika (LON:IKA) Oncimmune Holdings (LON:ONC) Ethernity Networks (LON:ENET) Argentex (LON:AGFX) NMCN (LON:NMCN) Impact Healthcare REIT (LON:IHR) Avacta (LON:AVCT) Totally (LON:TLY) Spaceandpeople (LON:SAL) Rosslyn Data Technologies (LON:RDT), Redcentric (LON:RCN)
Ilika (IKA) collaborating with Comau, part Fiat, to scale up Ilika's existing Goliath pre pilot line. £235k grant for design study. [SP=190.03 Cap=264m]
Oncimmune (ONC) agreements with Roche and Cedars-Sinai to profile patients using Oncimmune's novel Infectious Disease panel. SeroTag research panel has been tailored to predict COVID-19 disease severity and therapeutic response to the virus and the effectiveness of vaccines and other repurposed therapeutics as treatment against the disease. Both of these substantial new contracts will utilise this research tool to profile patient samples in search of immune related signatures in COVID-19 patients." [SP=190 Cap=131m]
Ethernity Networks (ENET) has started receiving production orders for its ENET Flow Processor FPGA systems-on-chip. Initial $400k for delivery early Q3. [SP=29.8 Cap=15m]
Argentex (AGFX) guides FY(Mar) rev down 3%, in line. [SP=127.5 Cap=145m]
NMCN (NMCN) new £12.5m overdraft. Also expects finance package to close this month/ [SP=265.55 Cap=28m]
Impact Healthcare (IHR) £50m placing at 111.5p, a 2.5% discount, to repay amounts drawn under its revolving credit facilities and to fund new investments. [SP=114.4 Cap=365m]
Avacta (AVCT) global distribution agreement with ABCAM o sell the Group's recently developed covid research ELISA Affimer reagents. "As far as we are aware, our spike protein ELISA test is the most sensitive test of its kind." [SP=233 Cap=590m]
Totally (TLY) wins contract extensions worth a total of c. £17.8m. [SP=30.25 Cap=55m]
SpaceandPeople (SAL) accident prone co extends Landsec contact to 2026. Covers 35 sites. [SP=9.5 Cap=2m]
Rosslyn Data Technologies (RDT) CEO resigns but will remain available to the board for transition .He is thanked. Chief Customer Officer becomes CEO. [SP=6.2 Cap=21m]
In line: Redcentric (LON:RCN)
Also
Q-AI (IQAI) Imaging Biometrics subsidiary wins (part of?) $3m grant to accelerate the development and commercialisation of IB CAD which uses AI to improve MRI. [SP=7.53 Cap=13m]
Zoetic (ZOE) UK Food Standards Agency allows its CBD products to remain on slae pending toxicological studies on CBD, expected in the coming months.. [SP=82.2 Cap=162m]
Yes thanks Paul, studiously not following the News has worked for me. Now looking forward to some interesting company news and views.