Small Cap Value Report (Tue 8 Mar 2022) - HEAD, NWF, MADE, RWA, TAST, HAT

Good morning, it's Paul & Jack here with the SCVR for Tuesday.
Appalling market conditions continue, there's not really a lot we can add to all the commentary out there. Obviously the Ukraine situation is just terrible in human terms. In economic terms it's triggered a deepening fuel problem, and as has been widely reported there are other commodities which are also spiking in price due to possible curtailment in supply from Russia/Ukraine. Therefore the inflation problem is likely to get worse, and squeeze many companies' earnings (and household disposable incomes) probably. Hence there is logic to falling markets, although overlaid on that is clearly plenty of panic selling too.
Anyway, we'll keep plugging away here on trading updates/results, because even if you're not ready to buy yet, it pays to be prepared with a list of bargains when the turning point is reached. I wish we knew when that is likely to be, but your guess is probably better than ours.
Agenda -
Paul's section:
Headlam (LON:HEAD) - Management changes are announced, but of more interest is an "in line" current trading update. Looks a bargain to me.
Nwf (LON:NWF) - a positive trading update from this agricultural & fuel distributer. A key point is that it has been able to pass on cost inflation to customers. A very resilient share, in a sea of red, in recent months.
Tasty (LON:TAST) - a micro cap restaurant group. It's traded through covid, thanks to Govt support. It's not clear how the business is likely to perform in future, once Govt support measures have ended. Market cap = net cash (even after normalising for stretched creditors) which does look interesting in valuation terms.
Jack's section:
Made.com (LON:MADE) - revenue up 50% but freight costs hit gross margin and adjusted EBITDA, which has declined from -£5.1m to -£14.3m. The group has some bold FY25 targets but the near term risks have obviously increased. Consumer confidence is most likely poor right now, and the group no longer expects helpful market conditions in the year ahead. Shares have fallen a lot already, but that is understandable given the immediate outlook.
Robert Walters (LON:RWA) - record results and strong trading across all markets. This is an international recruitment specialist, with 81% of revenue coming from outside of the UK. Positive conditions might change at some point, but for now the outlook is more robust that the recent share price falls might otherwise suggest in my view.
H & T (LON:HAT) - recovering results, with further progress forecast for FY22. The prospect of a strong gold price and higher demand for H&T’s services due to the higher cost of living suggests scope for upgrades, so at the current valuation I think there’s potential for a rerating.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Headlam (LON:HEAD)
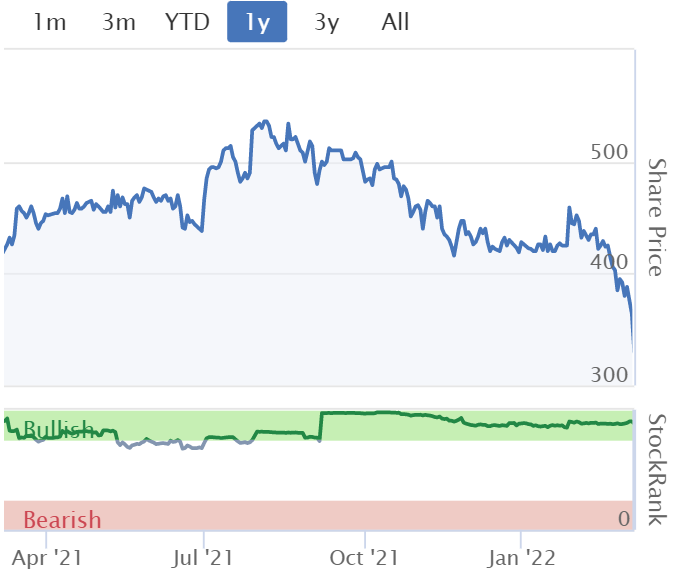
330p (Monday’s close) - mkt cap £282m
Headlam Group plc (LSE: HEAD), Europe's leading floorcoverings distributor…
Interim CEO, Chris Payne, has been appointed permanent CEO.
An interim CFO is expected to be appointed.
The Chairman is stepping down at the AGM in May 2022, being replaced by an existing NED, Keith Edelman.
Final results for FY 12/2021 are being published tomorrow, with profit “slightly ahead of expectations”, as previously announced in Jan 2022.
Current trading - this is the most interesting bit, saying -
…trading performance in 2022 has continued to be in line with plan.
My opinion - it’s a bit disconcerting that the 3 top Board positions have seen departures of late.
However, the statement that current trading is in line, is very reassuring, given that the share price has plummeted in recent days.
Anyone brave enough to buy HEAD shares now, is locking in an excellent, well covered dividend yield of about 5.5%. HEAD also has an excellent balance sheet, with freehold property making up over a third of the market cap.
A turnaround plan has seen lots of operational improvements made, and the business has been recovering well from the pandemic.
Looks an excellent bargain to me, on a forward PER of 8.9, if you’re brave enough to buy when the shares are cheap.
.
.
Nwf (LON:NWF)
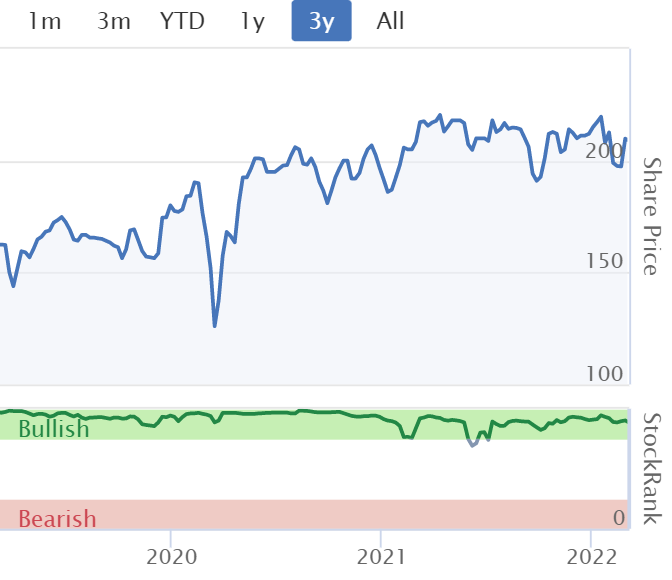
209p (Monday’s close) - market cap £103m
NWF Group plc ('NWF' or 'the Group'), the specialist distributor of fuel, food and feed across the UK, today announces a trading update for the current year ending 31 May 2022.
Good news for shareholders here -
As set out in the interim results on 1 February 2022, the Group delivered a very strong performance in the first six months of the year and carried over positive momentum going into the second half.
Since then, overall trading performance has continued to be strong, with demand conditions in the Fuels business accelerating to the extent that we now anticipate full year results will be significantly ahead of the Board's previous expectations.
Cash generation remains strong with lower net debt anticipated at year end.
Cost inflation - this is exactly the kind of comment that investors should be looking for -
…In Feeds with price increases continuing to be implemented, cost inflation has been recovered
I seem to recall that the fuels business is a mark-up on cost anyway, so passing on price rises there is automatic.
Ukraine - the first such statement that I’ve seen, no doubt we’ll see many more of these in relevant sectors -
Impact of the conflict in Ukraine
Since the start of the conflict on 24 February the impact to date has been most significant in Fuels, with the price of Brent Crude over $120 per barrel and with very significant volatility leading to elevated levels of demand. To date, there have been no major supply issues and we continue to meet demand across the country.
Feeds commodity prices, including wheat and barley, have increased to unprecedented highs, but with most raw materials now purchased for the winter period this impact will be most keenly felt as we move into May and the summer trading period.
My opinion - this share has been remarkably resilient in dire small caps market conditions.
What I’m searching for at the moment, are companies which have pricing power, and are hence able to pass on inflationary pressures. That does seem to be the case with NWF.
Incidentally, I attended an investor lunch last week, and sat next to a farmer. I asked him about market conditions, and he said that fertiliser has doubled in price, and that would feed through to much higher prices for food later in 2022. Similar comments have appeared in the press recently too.
.
.
Tasty (LON:TAST)
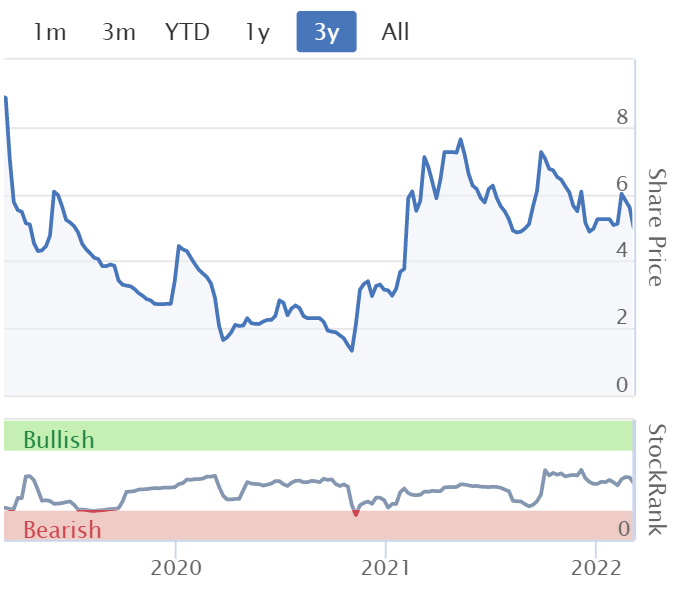
4.75p (down 5%, at 09:18) - market cap £6.7m
Tasty (AIM: TAST), the owner and operator of restaurants in the casual dining sector, announces the following unaudited trading update for the 52 week period ended 26 December 2021.
Tiny market cap, but a reader asked me to take a look and I’ve covered it before.
It’s very difficult to draw conclusions from this update, because it was a year heavily disrupted by covid, and further distorted with Govt support measures (e.g. grants, business rates relief, temporary VAT reduction, etc).
I think we need more information to determine what the future holds.
On the upside, TAST has survived, albeit with a higher share count - now 141m shares in issue, up considerably from 62m in 2018. Note that the business was already in trouble pre-pandemic, with heavy losses. So it’s really not a very good restaurant format, in my view. I’d rather invest in something that has a firm track record of profitability (e.g. Hostmore (LON:MORE) [I hold] which now looks stunningly cheap).
On the downside, the whole sector could be vulnerable to consumers reining in discretionary spending, as we have a very obvious squeeze on household incomes beginning (average wages rising by about 4%, but inflation heading for maybe 8%, or even higher?)
TAST generated positive adj EBITDA (on the old basis, before IFRS 16 messed up the figures) of £3.9m. It says £1.9m was from Govt grants in a footnote, but it’s not clear if that is the only Govt support, or if additional support helped the numbers.
Net cash was £11.0m, including the benefit of stretched creditors, but adjusting for those it still had £6.8m net cash - the same as the market cap! The commentary talks about some new sites, and head office recruitment, so this doesn’t sound like a business on the back foot.
My opinion - it’s a pretty low quality business, but priced at par with net cash, the valuation does look interesting.
The key question, which I don’t know the answer to, is whether this is likely to be a profitable business once everything has normalised?
.
.
Jack's section
Made.com (LON:MADE)
Share price: 69.4p (-2.8%)
Shares in issue: 391,499,661
Market cap: £271.7m
Preliminary results for the year to 31 December 2021
Against a backdrop of indiscriminate selling pretty much across the board, it’s notable that Made shares were up 5% yesterday, ahead of these results.
This is a furniture retailer, but a digitally native one, with a more agile business model that allows it to stock smaller, quirkier ranges that it can change more quickly given its small-batch production model.
That sounds good on paper, but it’s not all been plain sailing. Supply chain issues led to a revenue warning a couple of months ago. Couple that with the present conditions, and the result is a c65% decline in share price since IPO. Yet another in a long list of what look like poorly priced floats, and just one example of the brutal small cap conditions, unfortunately.

Revenue is up 50% for the year to £371.9m but gross margin has fallen by some 694bps to 46.3%, resulting in adjusted EBITDA of -£14.3m (FY20: -£5.1m) and a loss before tax of £31.4m (FY20: -£14.6m). That means basic earnings per share has reduced by 5.3p, from -2.6p to -7.9p.
Net cash was £107m at the end of the period. Free cash flow was -£32.1m, compared to £22.2m in 2020 as inventory intake normalised towards the end of 2021.
Gross margin was impacted by global freight inflationary pressures. Excluding freight costs, gross margin excluding freight would have been up from 56.5% to 58.5%.
This and supply chain disruption impacting revenue recognition timing during the final quarter of 2021 are the two main drivers of the negative performance.
Outlook
Perhaps the most important part given the share price drop. Is it worth buying in, or is there more pain to come?
Following the softness of consumer demand so far in 2022, we are no longer anticipating any tailwind from the market in 2022. Growth will be driven by our dramatically improved customer proposition, through improved experience, broader product choice and through enhanced reach. On this basis, we expect gross sales £500-540m (~+15-25% year-on-year), with higher growth in H2 than H1 due to 2021 comparative phasing.
So growth is still targeted across a range of metrics, but a reduced rate of revenue growth and the language has softened. Made wants to increase SKUs fromc9,500 to c11,500 and is looking for a 25-35% increase in revenue to £465m-£500m with adjusted EBITDA of between £5m and £15m (assuming normalised supply chains but ongoing higher freight costs).
Its ambition to achieve £1.2bn in gross sales and low teens adjusted EBITDA margin by 2025 remains unchanged ‘as the large and underpenetrated furniture and homeware market shifts online’.
Conclusion
The CEO comments that ‘We have seen a meaningful shift of consumption moving online during the pandemic, especially in our home furnishings category.’ But I think there’s a question there. Other furniture retailers have said that consumers still want an in-store experience, so that they can see and feel the product before buying.
It’s in their interest to say that, but we’ve seen before that we can’t just assume lockdown dynamics will persist in normal periods.
It’s hard to argue with Made’s revenue growth so far though.

And the group has more than £100m in net cash post-IPO. Cash burn is significant but hopefully the £42.3m increase in inventories is a one-off, in which case the group has a few years runway to grow revenue and reach profitability.
I’m not sure the market is in the mood to entertain loss-making growth stocks at the moment though. With the macro picture finely balanced and rapidly changing, I can understand why you might be wary of big ticket retail. Consumer confidence was falling before Russia-Ukraine, and it certainly won’t have improved over the past couple of weeks.
The group’s FY25 target of £1.2bn in revenue and a mid teen adjusted EBITDA margin (implying roughly between £150m and £200m) would make the shares very attractive if we could be sure of meeting those expectations. So there is material potential upside which means it is worth keeping tabs on.
But it’s unlikely to be a smooth ride in this sector over the next few months to a year. Made is already a loss-maker, so any further deterioration in consumer confidence could easily derail the group’s medium term ambitions. The net cash provides some security, and a lot of downside is now priced in. My concern is that, given the conditions, this is now justified by the increased risk.
Robert Walters (LON:RWA)
Share price: 577.08p (+6.47%)
Shares in issue: 76,633,030
Market cap: £442.2m
Results reported on constant currency basis.
- Revenue +6% to £970.7m,
- Gross profit (net fee income) +21% to £353.6m,
- Operating profit +285% to £54.1m,
- Profit before tax +339% to £50.2m,
- Basic earnings per share +482% to 46.3p.
The proposed final dividend per share is up 36% to 15p, and RWA spent £12.3m on share buybacks in the year. After year-end, a further 363,723 shares were purchased at an average price of £7.50 for £2.7m.
Group headcount increased by 11% to 3,484 (2020: 3,147).
FY21 is a record performance for the company, with operating profit at an all-time high.
Fierce competition for talent and significant wage inflation across all geographic locations and specialist disciplines.
This is an international business, with 81% (2020: 78%) of group net fee income now derived from overseas.
Asia Pacific net fee income grew by 32% to £164.2m and operating profit increased by 336% to £36.5m. Europe net fee income increased by 11% to £95.3m and operating profit rose by 192% to £13.7m. UK net fee income was up 3% to £68.7m and operating profit up 146% to £3.3m. Finally, Other International (the Americas, South Africa and the Middle East) net fee income was down 1% (but up 5% at constant currency) to £25.4m and operating profit increased by 43% to £0.6m.
Balance sheet is healthy, with net cash of £126.6m as at 31 December 2021 (31 December 2020: £155.5m).
Robert Walters, Chief Executive, said:
The jobs market is strong, wage inflation is increasing everywhere and candidate and client confidence is high. Together with the Group's strong brand, global international footprint covering both well-established and emerging recruitment markets and blend of permanent, interim, contract and recruitment process outsourcing revenue streams it serves to create clear opportunities across the recruitment market.
We are however mindful of the macro-economic and political uncertainties that do exist. To date, early 2022 trading is in line with Board expectations.
Diary date - a trading update for the first quarter ending 31 March 2022 will be published on 7 April 2022.
Conclusion
Strong trading, diversified markets, net cash, increasing dividends, share buybacks, and the founder still in charge after nearly three decades. Quite a few positive signs here. While recruitment can be cyclical, labour markets remain tight and so tailwinds could remain in place for some time.
You could, of course, take a more skeptical view. The group itself prudently notes ‘macro-economic and political uncertainties’. So for how long wage inflation and tight labour markets persist is a key question. Liquidity could also be an issue for some, with the StockReport suggesting that market makers are only compelled to trade 750 shares at a time at quoted prices.
For now, the group is trading well with the new year in line with expectations following a series of upgrades. Robert Walters looks like one of the better operators in this space. It’s a stock I’m more likely to consider amid the widespread sell off given the share price is now back to pre-Covid levels.

And, for all that talk of market cycles, the company has done a good job of returning cash to shareholders over the years.

H & T (LON:HAT)
Share price: 284.32p (+2.46%)
Shares in issue: 39,864,077
Market cap: £113.3m
Preliminary results for the year to 31 December 2021
£10.0m adjusted profit before tax (2020: £15.6m) in line with expectations ‘with strong segmental contribution from core business of pawnbroking and retail, and a significant recovery from the impact of Covid-19 trading restrictions and reduced footfall’.
Adjusted basic earnings per share was 20.8p (2020: 32.1p), and basic earnings per share was 15.4p (2020: 32.1p). That’s slightly ahead of forecasts, with a continued recovery expected in FY22.

The pledge book increased 38.5% to £66.9m (2020: £48.3m), with demand now back to pre-pandemic levels. Q4 was particularly strong and the group reported record lending volumes in December, so it looks like an improving trend.
The group ended the year with cash balances of £17.6m (2020: £34.5m) after using £16.8m to restore the pledge book.
Retail sales were up 21.5% to £36.2m (2020: £29.8m) with positive momentum across both the store estate and online platforms since May, at improved gross margin of 45.9% (2020: 37.9%).
Net revenue from unsecured personal lending reduced to £4.3m (2020: £8.1m) as the group refocused on growth opportunities within the core businesses.
Balance sheet - net asset value of £136.6m (2020: £134.5m) and NAV per share of 348.9p (2020: 343.9p). You can see the group is trading at around tangible book value currently.

Proposed full year dividend per share of 12.0p (2020: 8.5p)
Regulatory review of the Group's unsecured high-cost short term (HCST) loans business progressed and a provision of £2.1m raised ahead of anticipated confirmation by the FCA that H&T can proceed to implementation of required past book review and subsequent redress programme.
Good to have some clarity there.
Conclusion
I think H & T (LON:HAT) offers reasonable value at these levels, although it has never really been afforded a high valuation. It strikes me as quite a defensive proposition: cash generative, dividend paying, net cash, restrained equity dilution, strong liquidity ratios, and a modest valuation.
It qualifies for two Guru screens - one Bargain and one Value - despite double digit margins and ROCE.

The resurgent gold price is also presumably a tailwind. And, unfortunately, higher inflation could drive more demand for the group’s services. If that happens at sustained higher gold prices, there could be a considerable uplift in profitability.
It looks like the unsecured high-cost short-term loans business review will not materially impact the group. All in all, I think there’s a decent chance of a rerating here in time.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
Thank you Paul for covering Tasty, it's not so Tasty at all. I followed my friend Maynard P (who you may know) into this a few years ago, he'd had great success with the founders in an earlier venture. Some go wrong. I still hold in fading hope.
Good day for your Gulf Marine Paul. Wish I had given that one more thought!!
Hi Camtab,
Good day for your Gulf Marine Paul. Wish I had given that one more thought!!
What can I say? Hardly claiming victory, in a sea of destruction.
Jesus wept, my SIPP must be down about 30% YTD, that's a heavy kick in the bollocks, it really is. Seriously painful. BUT, I decline the price the market is offering me. They're long term holdings, so mark to market is irrelevant.
Lucky I dont need the money now. Probably time to reduce to house wine, and boiled cabbage.
P.
Nice to see a few shares rising for a change today. In particular Harvest Minerals (LON:HMI) continues its exponential rise. I hold - small but getting more significant each day and to be honest I haven't made a note of when I bought it (3.6p) or what first brought it to my attention (possibly a Gervais Williams comment). I'm certainly interested if anyone cleverer than me has a view on where this is going?
I think that there is a peril in relying on these screens, tends to create a false sense of security, stops a more thorough research. Take H & T - hard to asess HAT without mentioning the 11% dilution over the past 5 years, but hey, it comes out well on the Guru screen, so who is looking!
Bought some Headlam (LON:HEAD) - results tomorrow I think will be fantastic with loads of net cash on the balance sheet. I smell a special div or share buyback, which I would be happy with at this price.
I'm tempted by Headlam (LON:HEAD) too, after reading comments above, thanks Paul. but I don't understand the bit about brave buyers locking in a divi of 5.5%. It looks to be about half that to me. (ii says 2.36%) Am I missing something?
Stockopedia is showing estimates of 14.4p for 21FY and 18.4 for 22FY; i.e. circa 4.3% and 5.5% yield. As someone mentions below, they are due to announce tomorrow what they will do with the surplus capital they flagged in the January trading update. I suspect it'll be a special dividend so you can increase the potential yield for this year as well. Headlam (LON:HEAD)
this years is around 2.5% but next years div and for 2023 is forecast to be circa 5%....i guess we'll know tomorrow !
Hi Roger
It was 7.8p for 2021, but is forecast to go to 14. 4p and 18.4p over the next two years, so returning towards the historical dividends, but still down from 2019 and with a cover of >2 so that is a good thing.
Tommy
ps. I hold Headlam (LON:HEAD)
I like Headlam (LON:HEAD) and also took opportunity to buy some after recent fall. Compared to others in the home improvement sector, they should be less exposed to rising costs and margin pressures - as a distributor I would except price rises to be automatically passed on. They are also very much the dominant player in their particular space, and the scale should give them a competitive advantage. Growth has always been a bit pedestrian, but if the new management team are successful in their turnaround plans then things should hopefully pick up.
Re Robert Walters (LON:RWA) - these look good value at today's price but Sthree (LON:STEM) is a screaming buy. SP has nearly halved since November and EV/EBITDA is at levels associated with an illiquid private sale price.
Yet every tech firm on the planet has put a rider in their latest earnings report that they can't find enough staff right now and wage inflation is through the roof. Obviously some caution will enter hiring practices in this quarter but the structural shortage of tech talent is so intense that any fall in demand will only put IT recruiters in a goldilocks scenario where demand, while down from peak levels, remains high and supply, or rather availability, of candidates actually improves owing to a drop in competition for skills. The shares look seriously undervalued.
The CEO leaving STEM, I think spooked a lot of investors, but from what I have read the new one seems good...waiting on his first set of results.
They came out on 31st Jan already. The next set of results won't shed much light on Timo's capabilities. That's not really how recruitment works - each consultant is a business unto him/herself after all. You'll have to wait for strategic moves like M&A, new territories or new sectors to see where he hopes to take the business.
Paul, are you planning on a look at Johnson Service today as I see they have a trading update out ? Thanks again for the hard work from you and Jack
I was happy with the Bango (LON:BGO) results - slightly ahead of the market expectations, profitable and well set for future growth. Recent developments indicate that attracting US investors seems to be their priority now that they're well established worldwide and it makes sense to change reporting to $ even though that is annoying for a London listing. Shareprice stagnant for a long time though, bought these in May 2018 at £1.71. Whilst still priced for perfection, management have proved over years that they can execute in this space and create innovative products around the low revenue payments technologies, hopefully we can finally see some decent and sustained price appreciation from here.
Bango (LON:BGO)
"Whilst still priced for perfection"
hopefully we can finally see some decent and sustained price appreciation from here.
if its priced for perfection why are you expect price to show sustained rise on modest beat - when most other stocks are being decimated?
Note based on stocky figures which were for expectations for £17.7 mill GBP sales i am struggling to see how $20.7 mill is much of a beat if any - kinda looks the opposite to me.
Note the trending numbers ref eps on stocky have just been downgraded for year just finished and current year too. Is it posible beat is compared to recent downgrade - hmmmm.
Based on these numbers this company seems to be doing fairly well to keep sharepirce where it is compared to simialr us listed companies many of which have tanked recent,y.
Note i don't doubt the prospects here - the growth is not to be sniffed at and its clear they are investing for the future so nubers probably don't reflect underlying profitability and they have some top notch relationships in place with the big boys.
Suffering from serve shock. Some of my shares have actually gone up today. Is this a dead cat bounce?
Who really knows but I have my spread bet account ready for shorting weak and expensive shares when they put in a bearish pullback near the daily 50EMA. Mcbride (LON:MCB) is on my radar.
Hi Goronwy
It is probably everything that I have sold over the last few days weeks rocketing upwards :( on my buy high, sell low, buy higher, sell even lower...
Good luck!
Tommy
Headlam (LON:HEAD) the new CEO, Chris Payne (was CFO) will hold a webinar tomorrow 9th March at 11.30am. Register here. As Paul says, business seems to be going well, based on the 'slightly ahead' statement in January.
Made.com (LON:MADE) results overview. Like many, they were hit by crippling freight costs, to put that into context, if they had been the same as the year before it would have added £33m to the bottom line. Current market conditions rely on their strategy rather than market tailwinds. For the outlook, in 2022, expect gross sales £500-540m. Rev £146-500m. EBITDA moving positive to £5-15m. They target £1.2bn gross sales by 2025. Video & podcast.
Other webinars coming up, register for them all here (scroll through the list):
Somero Enterprises Inc (LON:SOM) FY21 results, Monday 14th March, 1.30pm
Litigation Capital Management (LON:LIT) H1 results, Wednesday 16th March, 9am
Pebble (LON:PEBB) FY21 results, Thursday 24th March, 1pm
Personal Group (LON:PGH) FY21 results, Friday 1st April, 12 noon
From a couple of weeks ago, here's an Introduction to £WIND who IPO'd last year. It's a maritime AI platform; SaaS business with 99% recurring revenues; 38% growth in ACV last year; loss making but lots of money in the bank following the IPO. Blue chip clients. Chairman is Lord Browne. Video & podcast.
Also, if you missed it, an interesting interview with Larry Zulch, CEO of Invinity Energy Systems (LON:IES) discussing the transition to renewable energy. IES supply vanadium flow batteries (VFBs) which store energy supplied by wind and solar, and unlike lithium batteries their lifetime is similar to that of a wind turbine. He covers the sector generally and the government funding they are seeing and specifically the VFB market. IES have tied up with Siemens Gamesa and separately EDF energy. It's another helpful insight to the sector. Video & podcast.
A few companies announcing share buybacks this morning (Howden, Dominos, Direct Line, Foxtons). Companies with no exposure to Russia/Ukraine and the knock-on global consequences are starting to see big opportunities in the price of their own shares.
Yes and for those of us who re-invest our dividends there's upside of buying more now than before. I suspect over the next set of earnings the markets will be able to start to determine which companies are being impacted by the Russia conflict/inflation and which will be largely unaffected.
Tasty looks interesting Paul and Jack if you have time to look at the statement.
Thanks JASVFS,
I see the update from TAST looks interesting. I remain of the view that hospitality looks set to continue with a strong post-covid recovery, so plummeting shares could be a great entry point in that sector. It's a tiny market cap, but I might do a quick section on TAST.
Regards, Paul.
My concern around all leisure/retail stocks is the energy crisis will mean spending once destined here will instead be spent on electricity and petrol. Average income families will not be able to pay for a trebling of their electricity and go out for a meal.