Small Cap Value Report (Tue 8 May 2018) - WEY, CAMB, IDE, BMY, TET, TERN

Morning!
A few updates which have caught my eye:
- Wey Education (LON:WEY) - interim results. "...we remain on track to meet our expectations for adjusted profitability for the year although this is likely to be achieved on lower than previously planned revenues."
- Cambria Automobiles (LON:CAMB) - interim results. "The Board remains confident that Cambria will maintain its momentum in the second half and deliver a financial performance in line with market expectations for the year as a whole."
- IDE Group (LON:IDE) - final results for 2017. "Profitability in 2018 is expected to be significantly lower than 2017, but is expected to improve steadily throughout 2018 and beyond following implementation of the operational review."
- Bloomsbury Publishing (LON:BMY) - Bloomsbury and Spotify announce audio storytelling partnership.
Thanks for your requests, specifically Treatt (LON:TET) and Tern (LON:TERN). I will cover them if I have time.
Wey Education (LON:WEY)
- Share price: 20.5p (-25%)
- No. of shares: 126 million
- Market cap: £26 million
A strongly negative reaction to this interim report, despite the company reiterating that it would meet expectations for adjusted profitability for the full-year.
Wey is an educational provider which runs an online secondary school and provides teaching materials to schools. It made a UK acquisition last year ("Academy 21", or "A21") and is now planning to expand its international activities.
The bad news today can be summarised as: UK growth not as high as originally hoped, lots of costs anticipated from international activities, and an operating loss after all is said and done.
"Core" revenues (i.e. excluding the acquisition) are up 23% year-on-year. Not bad, but it is difficult to support a market cap of £30 million+ with trailing twelve month sales in the region of £3 million.
Investors are asked to be patient:
In accordance with the strategy adopted at the time of the Company's £5 million placing in November 2017, emphasis has been put on development of the Company's business for the medium term at some short-term cost.
There's nothing wrong with that, but I think that investors had already shown a lot of patience by awarding a valuation of 10x sales to the stock.
The company is hoping to teach English language courses in China through a joint venture with a small Chinese partner.
I've been trying to find out more about its Chinese partner. I think that this is its website, translated into English using Google.
I would see this as a highly speculative activity. Defending your intellectual property in China is hard enough. And learning/teaching English is a commodity activity for everyone involved. Maybe Wey's course will be special in some way, but I don't see how they could prevent it from being replicated by others.
The other problem is that due to China's approach to economics, Wey will not have full control over its joint venture. Success will be dependent on the goodwill of its Chinese partner.
Perhaps the attempt to move into Nigeria will meet with better luck - I don't know.
The other noteworthy feature of today's results is the adjustment to the results: adjusted profits of £145k versus a statutory loss of £150k.
A reader in the comments below suggests that the adjustments are too much, and I agree:
Adjusted profits were £145,000 (2017: £75,000) in line with our expectations for the first half. The figure represents profit before tax adjusted for share based payments (£18,000), amortisation of intangibles (£95,000), acquisition costs (£43,000) and the higher than trend expenditure on marketing and other matters flagged up at the time of the November placing to substantially boost group revenues and underlying profits over the next three years (£143,000).
"Marketing and other matters" is a bit too broad as a category. Any old expenses could be chucked in here, and investors would be none the wiser.
So for a variety of reasons, I remain very wary about investing in this one.
Last time I covered it, I said the valuation looked too punchy, relative to the company's size.
I now also have concerns around probable difficulties in China, and the heavy adjustments to the results. Good luck to everyone invested in it, but it's definitely not for me.
Cambria Automobiles (LON:CAMB)
- Share price: 60.5p (-1%)
- No. of shares: 100 million
- Market cap: £60.5 million
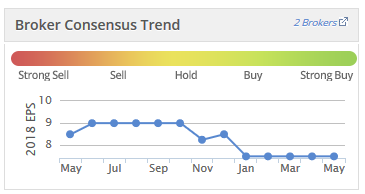
Motor dealers generally are trading at lowly valuations, and Cambria is no exception. One of the valid reasons for this is that earnings expectations have been reducing:
Today's highlights:
- Revenue reduced by 4.5% to £295.1m (H1 2017: £309.1m)
- Underlying profit before tax down 14.3% at £4.8m (H1 2017: £5.6m)
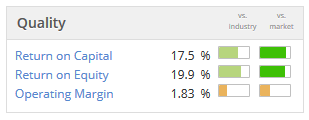
- Rolling twelve month return on equity of 17.4% (H1 2017: 21.8%)
The return on equity result sounds good in the circumstances. It uses "underlying profit after tax", rather than statutory net income, but the adjustment made is only worth £300k. So the statutory numbers are nearly as good as the adjusted numbers.
Stocko confirms that ROE is strong:
The operational highlights show plenty of movement in the portfolio. There are new or acquired Bentley, Lamborghini and McLaren dealerships.
New vehicle sales are down 14.1% like-for-like. Fortunately, margins improved both for new and used vehicles, and aftersales revenue was up 6.1% like-for-like, so the end result was ok.
CEO comment:
I am pleased that the Group has delivered a solid financial performance in the first half which gives us confidence that wewill maintain momentumin the second half and deliver a financial performance which is in line with current market expectations for the year as a whole. This is a notable achievement given the economic backdrop, consumer uncertainty, diesel demonisation and cost pressures.
I can also get behind the strategy:
Cambria's medium term ambition is to create a £1 billion turnover business with a balanced Brand portfolio producing attractive returns on capital.
It has been a super steward of shareholder capital:
Since the Group's inception in 2006, it has remained focused on driving growth for shareholders, taking the original £10.8m of share capital, with no further equity raised subsequently and reinvesting the earnings in property and franchises.
Balance sheet
Cambria finished the period with cash of £16 million offsetting gross debts of £16.5 million, so the net debt position was close to zero.
There are capital commitments of c. £20 million to fund property projects, and Cambria has a new £40 million credit facility to help pay for this.
Overall, the balance sheet is strong but the debt facility looks like it will play an important role in the upcoming projects.
Importance of aftersales
I thought I'd paste this table here. It illustrates how aftersales produces more gross profit than each category of vehicle sales, thanks to vastly higher margins:
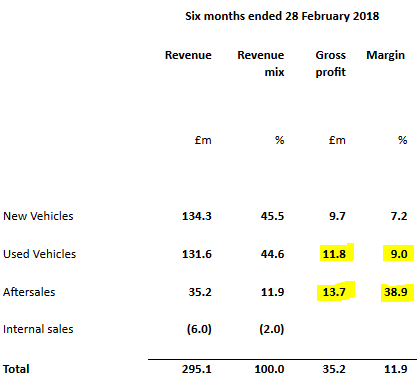
Hopefully, the aftersales category can remain resilient even if car sales (especially new car sales) remain difficult. There is a presumably a knock-on effect to aftersales when car sales are weak in the short-term, but I'm guessing that it's a delayed effect and perhaps small relative to the entire aftersales result.
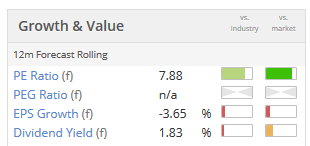
The stock has a Value Rank of 91 from Stocko. If I didn't already own a couple of shares which are exposed to the auto market, I would be open to the idea of opening a position in this:
IDE Group (LON:IDE)
- Share price: 14.5p (-3%)
- No. of shares: 201 million
- Market cap: £29 million
This is a special situation with an operational review ongoing and likely Board changes coming up.
It has two divisions: Platform Services (cloud hosting, communications, etc.) and traditional Managed Services.
Bringing out 2017 results in May seems rather late - not a great sign.
I am mentioning it only for the reason that change is afoot and maybe it will be worth revisiting during or after the changes. The Chairman stepped down (for health reasons) in January, and the CEO moved on in March.
Cash generation has been disappointing and Q1 closed with net debt at £10.3 million.
The "going concern" statement references the support the company has received from equity investors, implying that this support may be called upon in future:
Based on the level of support demonstrated by the equity raised to acquire 365 ITMS and consolidating bank facilities during the year, the Directors have a reasonable expectation that the Group has adequate resources to continue in operational existence for the foreseeable future.
I don't see any reason to invest currently, but I like to keep track of special situations so will watch out for the result of the operational review.
Bloomsbury Publishing (LON:BMY)
- Share price: 179.25p (+1%)
- No. of shares: 75 million
- Market cap: £135 million
Bloomsbury & Spotify announce partnership
This is perhaps not a significant announcement in the grand scheme of things but an astute fellow investor mentioned this company to me some time ago, and I am trying to keep up to speed with its developments.
Bloomsbury is an independent publishing house with a diversified set of interests in adult publishing, children's, professional/academic, etc.
This announcement helps to showcase how publishers can do well in the digital age - in this instance, by publishing some short books on Spotify, the music streaming service.
Checking the relevant website, I believe many of these books were already available on audible.com and on iTunes. So like I said, today's announcement is not a game-changer.
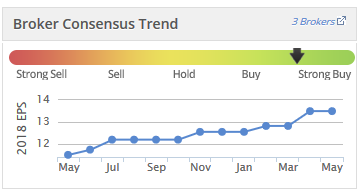
But for what it's worthy, Bloomsbury passes four Stocko screens - the Screen of Screens (Quality Investing), Low Price to Cash Flow (Value Investing), Earnings Surprise Screen (Momentum Investing) and the Naked Trader-esque Screen (Growth Investing).
So it's worth investigating, I think:
Treatt (LON:TET)
- Share price: 482p (+4%)
- No. of shares: 57.6 million
- Market cap: £278 million
This popular share provides ingredients to the "flavour, fragrance, beverage and consumer products industries".
A nice H1 result:
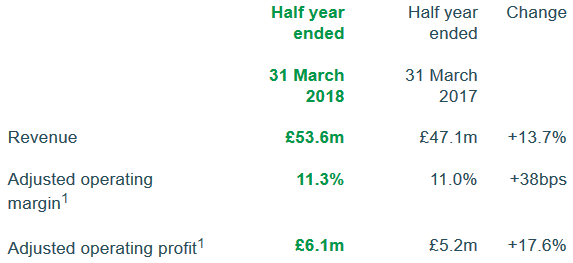
Constant-currency sales growth is even better than what is shown above: 18%.
The adjustments to operating profit are only worth £200k - no big deal. I don't worry about adjustments which are small compared to the overall result.
Outlook is in line with expectations for the current year:
Whilst there is still much to do to complete the year, and movements in exchange rates or raw material prices can impact results, the Board is currently confident that the Group will meet its expectations for the financial year ending 30 September 2018."
Sales in the "tea" category were up 38.5% in H1 - superb. Sales trends in sugar reduction, citrus and beverage flavouring were all good, too.
Besides building new UK premises at Bury St Edmunds, Treatt is growing its capacity in the US. A £20.8 million share placing has helped to pay for this:
A key part of our strategy revolves around our investment plans to build a scalable business for future long-term growth. Work on our US capacity expansion continues apace with construction work well under way and we look forward to this being completed by the end of 2018 as planned. This expansion will bring on line significant additional capacity for our fast-growing tea and sugar reduction categories as well as expanding and modernising our scientific infrastructure.
ROCE has fallen:
Following the fund raise in the period, capital employed increased by 11% from £56.7m to £62.9m. As a consequence, return on capital employed1,2 for the period was lower than in 2017 at 10.8% (2017: 12.0%), but is expected to grow as the impact from the Group's capital investment programme takes effect.
I'm entirely comfortable with this. When a company raises fresh capital, it takes some time to deploy it and to earn a return.
For factory firms like this, their new equipment tends to depreciate in value rather rapidly, and there is usually some delay before the equipment is used at full capacity. So I would expect ROCE to be poor at first during an investment programme, and Treatt's ROCE to be under pressure for the next couple of years.
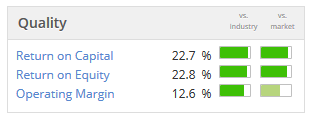
That said, ROCE in six months of 10.8% is still excellent. See the full-year metrics below:
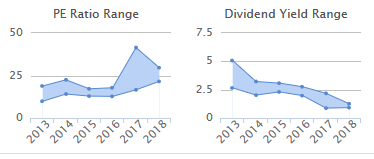
Treatt has grown its earnings per share very strongly over the years - and share price appreciation has resulted in a higher valuation range and a lower yield:
Thank you to readers for mentioning Lord Lee's position in Treatt. He has enjoyed dozens of takeovers in his portfolio over the years and I can imagine that a US food group might find this attractive sooner or later. It will be more visible than ever in the US, from now on.
I could justify opening a small position in this, despite the heavy valuation.
Tern (LON:TERN)
- Share price: 25p (-6%)
- No. of shares: 212 million (before 9.5 million new shares)
- Market cap: £53 million (before new shares)
Tern has raised £1.75 million (gross) at 18.5p - a huge discount to yesterday's share price.
CEO comment:
This Placing provides us with capital to continue delivering on our strategy to add to our portfolio of IoT businesses, and establish Tern as a leading IoT investment company
This might come across as unnecessarily harsh, but I am currently doing my best to avoid buying anything with the following labels or using the following terminology (this list is not exhaustive):
- Internet of Things/IoT
- SaaS/Software-as-a-Service
- Cloud-based
- Technological ecosystem
- Blockchain
My reasoning is simple enough: I believe that there is a substantial cohort of investors who are throwing money at these "hot" ideas, and the contrarian in me knows that staying away from popular sectors is a good way to gain an immediate advantage as a long-term investor.
So it might be unfair on Tern and on others, but a wall of money has been thrown into developing these sorts of technologies and I'd rather find some less crowded trades.
If I close my eyes to the sector it's in for a moment and consider its merits as an investment company only, I am immediately drawn to the last-reported NAV per share of 7.4p (versus the latest share price of 25p).
I would consider paying a premium to NAV for an investment company when NAV is understated and/or when the management team has a brilliant and consistent track record. A 10% or 20% premium would not be extraordinary in those circumstances. But I am immediately very cautious when I see a share such as this trading at a >200% premium to NAV.
Ok, time's up for today. Paul will be back again tomorrow. Cheers!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

49 comments
On Wey Education (LON:WEY), someone mentioned low barriers to entry to teach TEFL in China.
Yes, there are many TEFL providers. But from my reading, it looks like Wey is doing something different - and they should call it out - they are using UK based teachers. Native speakers. so this is a premium service, and not easily replicated by TEFL providers based in China - it is a high barrier to entry, as those China-based TEFL providers will have to create an operation in the UK, just to recruit local native English speakers.
I can see affluent Chinese parents paying a premium for their son or daughter (only child policy!) to learn "proper" English, along with the right accent.
However, I still feel that management have made a complete hash of the recent results, not fessed up about loads of things (marketing spend, InterHigh, etc) and just looks like they have contempt for investors. Why bother investing here with such type of management?
I was at the investor event yesterday as was leo - very nice to meet you Leo.
I certainly would not characterise mgt as trying to pull the wool over the eyes. Refreshingly transparent I thought, who admitted to mistakes.
Whether you want to forgive / punish mistakes is your decision as an investor.
Obviously we can have different views, but I enjoyed meeting with them. Would be more comfortable with less fluff type mgt, but for me that is less indication of competence, more indication of personality.
No change to position here
Hi dahokolomoki,
I think I need to question the view that using native speakers to teach TEFL is a premium service.
I spent a year in China and as far as I can tell, the place is awash with native English speakers teaching English. Teaching English is the standard job which everyone from the UK, US, Australia, etc. can do and immediately earn more than the average local salary. In general, teaching English is considered equivalent to flipping burgers in terms of its prestige for a Westerner in China. It is absolutely standard.
If you are a Chinese parent sending your child to a decent school, you expect your child to be taught by a native English speaker. Some schools do skimp on costs and hire European-looking non-natives, but in general it is normal to have a couple of native English speakers in any good school.
Not sure about this, I have been to many countries in SE asia and there does seem to be a demand for English speakers, in particular from the UK. Many local teachers can't pronounce some words correctly. I think there will be demand from the ex-pat community especially from British parents who prefer an English accent to a local or American/Australian one. Countries such as Thailand could be one where there is demand as English is not widely spoken there. Good schools cost a lot of money?
Wey Education (LON:WEY) - I have written up some answers to questions raised in yesterday's investors meeting here: https://www.stockopedia.com/content/wey-education-private-investor-evening-may-2018-362148/
Thanks Leo.
Regarding Tern ... and I have to admit I have a reasonably sized holding ... I think you have to do a little bit of research to understand where the stock has come from, where it is and where it might be heading.
The management team are very strong and experienced (Ian Ritchie of Iomart is the Chairman and Al Sisto who has huge experience in technology is the CEO).
They are NOT hugely cash burning nor admittedly cash generative. The £1.75m raise will allow them to invest further in InVma and also new opportunities. Unlike several similar organisations they are NOT paying excessive salaries or options packages.
So why valued at £40m (approx raise value) to £50m (approx current price) ?
Main reason is their main underlying investment ... Device Authority in which they have the controlling interest. Google it alongside names such as Microsoft Azure, Comodo, Intel, Thales, Gemalto, and research Device Authority's website. Essentially DA looks to have become the defacto standard for the authentication of devices that are linked to the internet. Like many companies before they have gone teething issues such as time to market / time to integrate with customers / funding issues ... but really dig deep I think they could be on the verge of something very special indeed. Look at the areas they are involved in ... medical, industrial, consumer, smart cities, the list goes on. I'm not going to attempt valuations because these are always wrong !
Their other main investments InVMA (recent deal / collaboration with GEC for medical device authentication and security) and Wyld (Mesh networking technologies) have the potential to be massive also.
DYOR though but it is worth the time. Superficial analysis can sometimes be dangerous !
But as I said at start I would say all of this as I hold a good few shares ...
Hi meganxmas
I completely agree with your advice about Tern (LON:TERN) that it requires quite a lot of digging to begin to gain an insight into the potential. (I bought in last week, but fully expect a very bouncy ride).
If anyone's interest has been pricked, below are some things I encountered during my analysis.
I think this is one of the Tern (LON:TERN) initiatives which is generating some of the buzz.
https://www.invma.co.uk/case-studies/gce-healthcare
This is GCE
http://www.gcegroup.com/en/about
I guess if this inVMA/GCE project goes well, then GCE may extend the inVMA relationship.
These are other inVMA case studies you might like to browse into
https://www.invma.co.uk/case-studies
We have all seen a buzz from an emerging IT technology before, so no point in getting too excited.
But, that noted, Tern (LON:TERN) are in effect beginning to tap into a technology called 'Thingworx' which is technology to support the industrial 'Internet of Things (IoT)'.
These links provide some background to this technological development.
PTC Inc is the company behind Thingworx
https://www.stockopedia.com/share-prices/ptc-inc-NSQ:PTC/
https://www.ptc.com/en/about
Should you be interested this Vid offers a description of Thingworx and the industrial IoT
https://www.youtube.com/watch?v=f2lB9uvP_B4
Of course this could be jam tomorrow, but as meganxmas has pointed out some of the people involved are highly experienced in this field. The ecosystem of technologies and companies is substantial.
Thus, the perceived value is all about evolving connectivity across a multiplicity of 'things', technologies, organisations, processes and industrial sectors. Therefore scalability is present. If that occurs then (IMO) I sense an interesting investment potential (but not for the less risk averse I would suggest - see barnetpeter's post #27 above).
Regards
Howard
Here's the next Electric Vehicles – the opportunities and challenges for the investor
2. The evolution of battery technology
By Stephen Irish, MD, Commercial, Hyperdrive Innovation
Hyperdrive Innovation designs and builds lithium-ion battery systems for powering electric cars, off-highway vehicles, autonomous vehicles and home energy storage. They work in collaboration with Nissan and others to design & develop innovative battery systems that it aims to commercialise in the near term. Stephen follows on neatly from Chris Jones’s presentation, to indicate how developments are playing out for suppliers to the industry.
http://www.piworld.co.uk/2018/05/09/redleaf-ev-conference-2-hyperdrive-innovation-the-evolution-of-battery-technology/
I have a little knowledge of on-line learning, having worked in the area for a few years. I would NEVER invest in any company in this field, other than those which supply the software packages used. Wey Education (LON:WEY) offers various levels of qualification, through providing resourses and instruction on-line. The problem is that many US universities, and some in the UK, offer comparable courses and qualifications for free. These offerings will only increase as institutions seek to attract students and to justify their educational mission. Vocational training is a different matter, but the academic field really is something worth avoiding.
Glad Graham felt able to take a swing at Wey Education (LON:WEY), even though it is one of Paul's BMUS holdings.
Wey...Looks like the short term lows have been broken and I can now see a fall to about 13p....which would be about 15m mkt cap. That still might be too high if the UK is ex growth. Holding from 21p but can see plenty of red flags after today
Hi Graham, thanks for your comments on Bloomsbury Publishing (LON:BMY).
It may also be worth mentioning that on 19th March in a pre-close TU that the company said:
"Bloomsbury Publishing Plc is pleased to report that for the year ended 28 February 2018, while revenues are slightly ahead of expectations, profits will be well ahead of the Board's expectations.
In addition, the Group's net cash balance is now expected to be around £25m, significantly ahead of expectations."
The company is therefore currently on a positive trajectory and year end results should contain some nice highlights. Given that the company have traded within a range for the past 4 years, peaking more recently at the turn of the year, it will be interesting to see if it can break out convincingly of this range if the positive news can continue. (I currently am holding BMY).
There's an in-line update from Ideagen (LON:IDEA) today with some sensible-looking board changes. If the broker forecast is right, that means a big increase in normalised EPS.
£Treatt (LON:TET)
Another vote for Treatt. Very niche market but hints of being the supplier of flavourings to Fevertree lured me in. I have been a holder for three years and wondering if I should have bought more after its recent dip and consolidation.
I see Safestyle UK (LON:SFE) have appointed Mike Gallacher, a turnaround specialist, as CEO.
I worked with him years back, and he's not someone who will faff about. So for better or worse I expect we will see some decisive actions here.
https://www.investegate.co.uk/safestyle-uk-plc/rns/directorate-change/201805010700066544M/
If your trying to understand the electric vehicle market, from an investor perspective, we're publishing 6 presentations given at a Redleaf Seminar. These will apprear over the next 6 days. The objective of the seminar was to inform the investor of what's going on from the different perspectives of the industry, and what the opportunities might be.
Here, we kick off with a presentation by Canalys, who research and analyse trends impacting the automotive sector. They outline the past, present and future of EVs. It gives great insight to how the EV market might evolve.
http://www.piworld.co.uk/2018/05/08/redleaf-ev-conference-1-canalys-the-automotive-revolution/
We filmed these purely for the benefit of the investor. Tim and I were interested to hear the 6 presentations, and we though a wider audience of investors might also appreciate the opportunity.
Thanks tomps3, an interesting 30 odd minutes. Will you be reminding us when subsequent presentations are posted?
Laughton, yes I'll post a note here to say what's been posted. Basically there will be one EV seminar presentation posted a day. They are good. Chargemaster was especially interesting. They run a network of charging points. (Presentation 5).
tomps3,
Your mention of Chargemaster jogged my (vague?) memory.
IIRC, they nearly listed, and I contacted their FD for further details and updates, with the eventual outcome that BMW (?) invested in them, so they didn't need an IPO to raise funds for their roll-out. If it is the same company, I should go back over their accounts and see how they've progressed since, for that 'if only I could have invested' moment :o)
DJCP - wasn't aware Chargemaster were formerly IIRC. The presentation is on Chargemaster's view of the charging infrastructure, based on their experience. Tom's a great speaker, and has much insight. It wasn't on the company, or their history.
We're just about to post the second Electric Vehicle presentation (in the next hour): 2.The evolution of battery technology. By Stephen Irish, MD, Commercial, Hyperdrive Innovation. Hyperdrive Innovation designs and builds lithium-ion battery systems for powering electric cars, off-highway vehicles, autonomous vehicles and home energy storage.
I'll post on today's SCVR (9.5.18) when it's published.
Tomps3 Re post 38 - think he means IIRC - if I recall correctly
Hi Graham et al,
Not a small cap request, but was wondering if you had any thoughts on the £VM CYBG (LON:CYBG) announcement.
Holder of VM - personally, I think CYBG are getting the better deal - buying in my opinion a better bank for a discount to their own valuation.
That said, challenger banks do need to consolidate or more scale to compete, and this, as far as deals go, seems to have strategic fit (if you believe what you read on £CYBG), hopefully less regulatory capital, cheaper funding and other cost reductions with potential for revenue synergies too - A real competitor focussed on the North of England?
Would value any thoughts time allowing given your expertise / interest in the sector?
Wey Education (LON:WEY)
Will they be able to compete abroad with Pearson (LON:PSON) . Extract from Pearson's website-
"We know online learning, and we know a thing or two about A level courses as well.
Pearson has been successfully delivering online courses to primary and secondary students in the US for over 15 years. We teach courses to 65,000 students a year in America and 48 other countries around the globe. We have applied our thousands of hours of online learning experience, combined with our expertise in A level teaching and learning materials, to develop something that’s right for UK students.
Whether you have one student, or 20 who might be interested in this service, we can help."
I have not compared the two online offers but sold WEY a few months back.
Wey Education (LON:WEY)
This:-
"......and the higher than trend expenditure on marketing and other matters flagged up at the time of the November placing to substantially boost group revenues and underlying profits over the next three years (£143,000)."
is taking things too far.
Phil
Totally agree, Phil. re: Wey Education (LON:WEY). "Marketing and other matters" is not a reasonable category for adjusted expenses.
Regarding Wey Education (LON:WEY) 's exceptional marketing costs, I think possibly this could be justified if the said marketing was a big failure. In those circumstances it is never to be repeated and more like a write-down than a marketing cost.
I will try to ask all the questions that have been raised, including about the success (or otherwise) of the Waterloo advertising and also their Net Promoter Scores which should give some guidance about future advertising requirements.
Education will continue to be mainly provided in traditional schools so I cannot see a huge market for WEY in the UK or anywhere else for that matter, except for a minority, niche, demand for people who cannot fit into schools. In any case, there are already other products out there so I am not surprised that WEY are not achieving their aims.
Hi
As mentioned in Mr Contrarian (post 4 of 7), Tern (LON:TERN) have done a placing.
Tern (LON:TERN) have not had much coverage on Stocko so far but the stock might be beginning to appear on momentum watchers screens, I picked up on it last week (I have very small holding now).
Here's a little of what I discovered.
Looking on Investigate.com Tern (LON:TERN) has had a substantial newsflow throughout 2017 (and in 2016) https://www.investegate.co.uk/Index.aspx?searchtype=3&words=TERN
In simple terms if you buy shares in Tern (LON:TERN) you are buying management expertise in the Internet of Things (IoT). Specifically then, interests in six of Tern (LON:TERN)s portfolio companies. Tern (LON:TERN) hold 100% of flexiOPS which owns 90% of Wyld Research http://www.flexiops.com/.
But the important interests lie in two other holdings. 56.8% in Device Authority https://www.deviceauthority.com/ Then 50% in InVMA https://www.invma.co.uk/.
Tern (LON:TERN) explain that they are setting out to glue together investors (eg these from San Fran. who have invested in Device Authority https://www.alsop-louie.com/), innovating companies and skilled management experience in the IoT.
Tern (LON:TERN)s recent RNSs (from March onwards) are indicating that both these (invested in) companies are making progress and that the integration of partnerships and customers is gaining speed.
The latest example being this update about InVMA https://www.investegate.co.uk/tern-plc--tern-/eqs/gce-healthcare-launches-platform-developed-by-i---/20180503070008EUDZJ/.
Tern (LON:TERN) added to their investment in InVMA 25/04/18 https://www.investegate.co.uk/tern-plc--tern-/eqs/additional-investment-in-invma/20180425070005ETRHC/
I found a lot more in my digging but have tried to pick out salient points. I started from their Shareholder Conference Call update and followed the trail from their presentation pack https://www.investegate.co.uk/tern-plc--tern-/eqs/update-following-the-shareholder-conference-call/20180430090441ELEBF/.
IMO Tern (LON:TERN) could interest those with quite a strong technical background, or those for an eye for following investment type/VCT type companies. In particular Tern (LON:TERN) seems to be focussing towards the industrial IoT technology based on 'Thingworx' from PTC https://www.ptc.com/en/about.
This placing suggests institutions are increasingly interested in Tern (LON:TERN). This is a positive flag from a Minervini investing perspective. To date, insiders hold 22.4% of shares (4 individuals and an institution). Plus, according to IC three other institutions hold 7.38%. This fits pretty well to the Stocko free float figure of 79.8%. This new placing adds to this 7.38% holding.
My apologies if this got too long-winded. As is often the case with these types of companies its a spiders web of connections, and I think that is part of the reason the price is spiking so much. Others are beginning to see the possibilities if some of these links develop. I've no idea if they will and would not put too much in this but it might interest a few on Stocko. Anyway Tern (LON:TERN) could fizzle out after this initial excitement. Who knows?
Regards
Howard
EDIT: Tamzin from PI World posted two vids July 2017 here https://www.stockopedia.com/co...
Tern..do remember that some (including lucky me!) were buying this at 1.88p in January this year. So although I have cashed in some, plenty like me are sitting on massive percentage profits of well over 1000 per cent on this stock. So the stock is likely to be very volatile. Previously it hit 30p from 0.88 before reversing all the way back.
I like the stock (lol) and it looks very promising if the "internet of things" is worth as much as some say....and I have seen valuations of over £4 by some interested parties.....but at this stage it really is gambling money only I think. I have been 90 per cent down and 1500 per cent up on various holdings of tern at various stages over the last few years so not for the nervous or stop losses.
Hi barnetpeter
Many thanks for the response about Tern (LON:TERN) ..... I have no idea why someone has given you a thumbs down though .....
I think your comments are enlightening and useful.
I would have thought you flagging up the way the Tern (LON:TERN) stock behaves would be useful particularly given that it is a relatively new stock to the market and to the Stocko community.
I am expecting the price to fall for a bit as this new issue is out at 30% below the price (the other day). But, on a plus side (IMO) it is adding another quite committed institutional investor to the mix so I think there could be some upside to the overall evolution of Tern (LON:TERN) in the medium term as I assume that buyer had quite a lot of insight into forward prospects.
That all said, I concur with your insights that is likely to be a rather bouncy holding - its an investment company, its technology, its small, its a bouncy market.
Regards
Howard
I would appreciate some comment on Tern (LON:TERN), if it is big enough. Could not get any at the open but could open a small spread bet which is already in profit. Seems at cursory glance potentially massive, but potentially victim to any better IoT mousetrap that may come along...
I too have concerns about today's statement from Wey Education (LON:WEY) . The Chinese venture appears to be TEFL (Teaching English as a Foreign Language) for which there is massive competition and presumably low margins and little moat. They have effectively issued a growth warning for their core UK business for 2017/18 and not given any guidance for growth in students for 2018/19. They have not broken down revenue / costs across different sectors making it difficult to see quite what is going on.
On the other hand the Nigerian business seems more promising. Here they are teaching the whole UK curriculum from the UK to students in Nigeria but also taking the opportunity to provide the Nigerian curriculum from Nigeria to students outside of Nigeria - this is a model I could see being rolled out to other countries. Moving into primary education also makes sense, and while starting at the top has its disadvantages, I can see how it better leverages their existing staff and expertise.
Doing business in both China and Nigeria is of course both highly risky and potentially highly rewarding.
I am going to their Private Investor Evening later today so if anybody who can't make it has any questions in addition to those implied by the above, please let me know.
Thanks @leoleo can you please ask Wey Education (LON:WEY) how teacher recruitment is going, if not covered?
I would have liked to have come to the Wey Education (LON:WEY) investor evening today. I am in Austria this week enjoying the sunshine and beautiful countryside instead. Will you post a summary of your conclusions from the presentation? I would be very interested to read it. I don't have any specific questions to ask but would be interested in your assessment of:
* the appropriateness of all their adjustments to reported EPS - are they really exceptional / one off or just part of the cost of growing the business
* expected growth in the core UK online education business and how they will achieve this
* competitive advantage / barriers to entry
* the overall competence / naivety of the management team (c.f. Carcosa above).
Enjoy the evening. I hope they provide good canapés.
Thanks @leoleo
Re Wey Education (LON:WEY)
If you get a chance, and no-one else asks, would you mind asking what became of their marketing "experiments" in the last 6 months. Given how much they banged on about it at the time (advertising at London Waterloo) I would have thought they would have provided some some of feedback today.
Cheers
I kept an eye on WEY's statistics on a free web traffic site. They've actually fallen in rankings (no idea if I have found an accurate source of data mind you) since last year. There was a bump in January (when they hired the big screen at Waterloo), but traffic halved in Feb.
I also was unimpressed by this firm - they seem to be a play on the govt's own education policy and educational methods, rather than having their own truly independent philosophy.
Interesting to hear that a free traffic site has, seemingly quite accurately, followed the trend one would expect from Wey Education (LON:WEY) over the last few months.
I've tried in the past to use those kind of sites to predict web traffic, but things never quite tallied up...until I read this blog post
Long story short for those who don't have the time to click through, EVERY web traffic tracker reported significantly varied traffic vs actual traffic (the top 2 trackers respectively over- and under-estimated by 17% actual web traffic numbers).
So it's probably worth using those services alongside a healthy dose of scepticism.
Hi Leoleo,
I was planning on going, but I don't think I will be make it there on time, since it is kind of clashing with work, and they pay me to be here!
I imagine most of this will be covered but these are the questions I have (sorry, it does repeat some of the ones others and you have already detailed):
What is the driver for revenue being behind expectations - is it pricing or student numbers or both?
Why are they going into China / Nigeria when they are behind target on UK.
Why are they adjusting marketing expenses - what element of the £143k is above trend and where do they expect this to be as a % of revenue in next 3 years.
Does being in line with profit expectations rely on marketing expense being adjusted - and how do they identify what is above trend?
What kind of promoter scores are they getting from existing students and more importantly I think, parents?
Are there any subjects / demographics where they are performing better versus others (eg rich white males / Asian girls / Maths / German)
What would be cash requirements for international expansion - what is current cash burn / requirement over next three years?
Morning Graham,
Another vote, should you have time available, for Treatt (LON:TET) As announced at Mello2018, Treatt (LON:TET) has exceeded 30% of Lord Lee's ISA and he meets management once a year for tea at the House of Lords. If they have been 'good' Lord Lee will offer them scones with Jam & cream, but if not - No scones. :)
DIsclosure: I hold shares in £TET
Hi IG - yep, I think I'll be able to cover Treatt (LON:TET) shortly. G
Graham,
As you cover financials perhaps you could look at Duke Royalty (LON:DUKE) a somewhat unusual company in that the royalty model whilst big in the USA, particularly with MLP's in the oil industry, has never really been tried in the UK. They have issued an RNS confirming how the first two investments appear to be trading well.
Duke invest mainly in longstanding family or large private companies who are looking for very long term finance, often 20-25 years without the hassle of banking covenants. They take a first charge over the assets. I believe they expect to be yielding around 8-9% within a year or so once they get the full annual run rate on the loan portfolio.
Duke has leverage potential now that most of the funds they raised are invested at around 10-11%.
I hold.
Dave
My morning smallcap tweet:
MTI Wireless Edge (LON:MWE), IDE Group (LON:IDE), 4imprint (LON:FOUR), Tern (LON:TERN), Yolo Leisure and Technology (LON:YOLO), Ideagen (LON:IDEA)
MTI Wireless Edge (MWE) - some merger hurdles satisfied.
IDE Group Holdings (IDE) FY rev up 50%, pretax loss tripled to £12.8m. "Profitability in 2018 is expected to be significantly lower than 2017, but is expected to improve steadily throughout 2018 and beyond following implementation of the operational review." Going concern "Directors have a reasonable expectation that the Group has adequate resources to continue in operational existence for the foreseeable future."
4imprint (FOUR) AGM stmt: first 4 months has been above the Board's expectations, with revenue growth of 16% and order intake up 15% over prior year.
Tern (TERN) placing at 18.5p, a tasty 30% disc. for the 'single institutional investor' even though it's a measly 4.5% of total shares.
YOLO Leisure and Technology (YOLO) H1 EPS 0.18p but NAV 9.9p, a 0.3p reduction in half due to dilution.
Ideagen (IDEA) FY guided in line.. CEO becomes Exec chmn, Chief Customer Officer becomes CEO and Exec chmn becomes NED.
Could you look at the results from Treatt,please Graham ?
Trading statement from Tharisa (LON:THS) went down like a lead balloon (Or should that be chrome?) on Friday.
Tharisa is currently preparing its interim financial statements for the half year ended 31 March 2018, with the financial results expected to be released on or about 16 May 2018. Shareholders are advised that with the normalisation of the average contracted metallurgical grade chrome prices from US$278/t in H1 FY2017 to US$193/t in H1 FY2018, the strengthening of the South African Rand against the US Dollar and the planned increase in costs as a result of the transition to owner mining, Tharisa's basic earnings per share (EPS) and headline earnings per share (HEPS) for the half year ended 31 March 2018 are expected to be between US$ 9 cents per share and US$ 11 cents per share. This is a decrease of between 43.75% and 31.25% relative to the EPS and HEPS of US$ 16 cents per share for the half year ended 31 March 2017.
"Higher volume sales for both PGMs and chrome concentrate, were offset by lower spot chrome prices and an increase in costs associated with the transition to owner mining. The benefits of the owner mining model and the central focus on improving recoveries are expected to reflect in the second half," said Tharisa CEO Phoevos Pouroulis.
Wey Education (LON:WEY) put out their interims today. I sold out of this company in January. I recall thinking management came across somewhat naive. Today they are all agog over China related business. Anyone who has worked in China will probably see they have been sold the idea that the market there is huge and a great deal of money is to be made. Lambs to the slaughter more like; wait and see how the costs are going to balloon over the next 2-3 years before they pull the plug.
Other than that the interims failed to impress me.
No doubt others will disagree!
Re. Wey Education (LON:WEY)
Actually, I think your analysis looks spot on Carcosa. The core UK education business looks to have lots of potential - a much needed service with generally good feedback from generally satisfied customers. First mover advantage and a real focus on perfecting their home schooling offering could generate high barriers to entry. But all this extra activity looks like a huge distraction. Can management keep delivering good services while expanding into China, Nigeria, business to business, the moon, the rings of Saturn? And today's results are far from impressive - just look at all the adjustments needed to make the EPS figures look good.
I sold today (should have done so before or done more analysis before buying). I will keep this on my watchlist with the hope of buying back in if/when the business model proves itself.
Very much looking forward to Graham's analysis.
I never bought in as I can't see how you can do an A level science practical online. I was also a bit bemused when it became flavour of the month!