Small Cap Value Report (Tue 9 June 2020) - CER, SOS, VLG

Hi, it's Paul here with the SCVR for Tuesday.
Today's report is now finished.
To get you started today, I wrote 4 more sections to yesterday's report in the afternoon, covering:
Tt Electronics (LON:TTG)
Solid State (LON:SOLI)
Actual Experience (LON:ACT)
Speedy Hire (LON:SDY)
It's good to see the first 2 companies in that list trading relatively well, despite covid.
Cerillion (LON:CER)
Directors sold a hefty lump of shares yesterday;
- 2.74m existing shares, or 9.3% of the company sold to institutions
- 255p per share, a deep discount to the 319p share price
- Guy O'Connor is selling his entire holding, of 2.39m shares (retirement-related)
- Oliver Gilchrist is selling half his holding, and retains 1.2% of the company
Graham introduced me to this share, and we both think the company is very good. This disposal of shares by Directors is mainly retirement-related, which seems a reasonable explanation.
EDIT: Just to clarify, Graham's just messaged to say that he doesn't have a strong view on CER, and that "it doesn't particularly stand out to me at all". So my apologies for putting words into his mouth which were inaccurate as it turns out, hence the strikethrough above. End of edit.
I'm a bit concerned at the placing price, being only 255p, which suggests that the market price of 319p could be a bit toppy perhaps? Although when buying an illiquid stock, I understand why instis want a discount, as they're locked in for the duration.
.
Sosandar (LON:SOS)
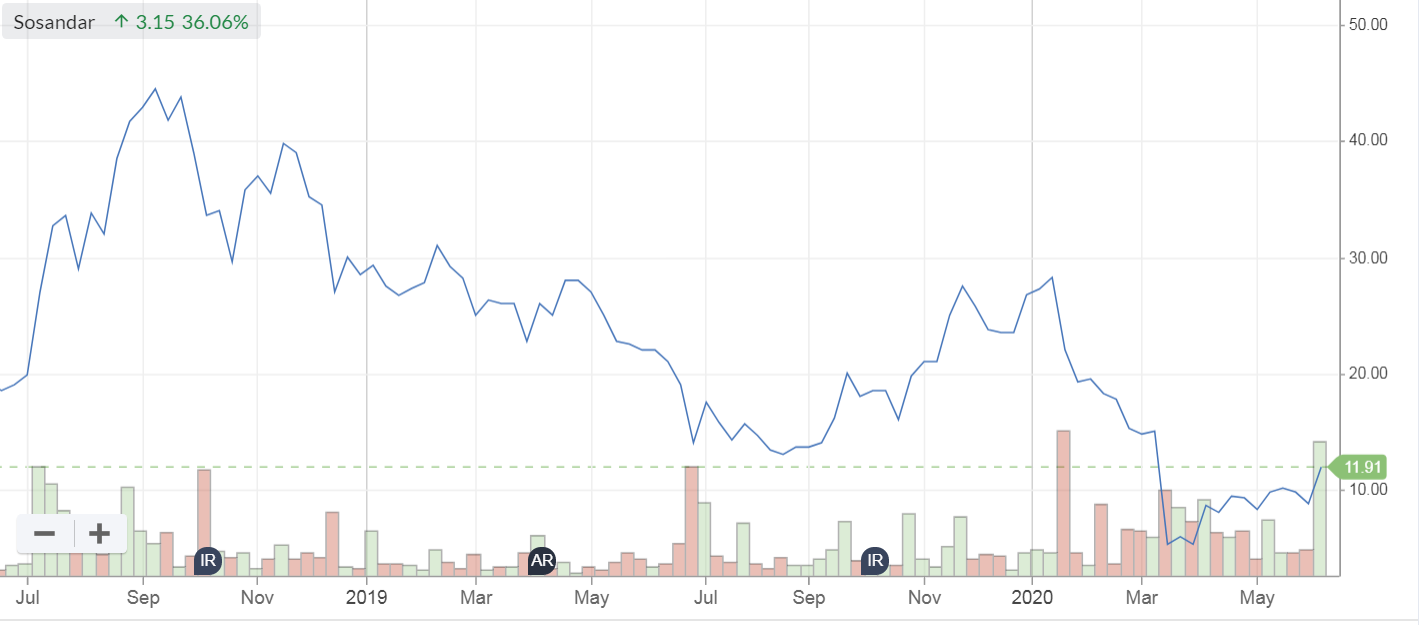
Share price: 8.75p
No. shares: 192.3m
Market cap: £16.8m
(I hold a long position, at the time of writing)
This online ladieswear brand provides an update for FT 03/2020, and on current trading.
Current trading (April & May) - this section reads well. Key points;
- Revenue up 62% vs LY - although bear in mind this is up against soft comparatives LY. It demonstrates that the heavy marketing spend late last year has continued to benefit sales this year, which is what the company indicated it believed would be the case.
- Growth achieved despite marketing spend down 69% on LY
- Returns down to c.33% - that's a huge reduction from c.50% in the past. Explained by selling more stretchy fabrics (e.g. focus on denim), and other styles which are less dependent on having a perfect fit. This was a stated aim of management when we last spoke, so good to see this is working well
- Loss for the 2 months reduced by 55% (no figure given)
EDIT: a friend has kindly messaged me to point out that the low returns rate in April/May could have benefited from Sosandar's more flexible returns policy, and customers not wanting to venture out to the Post Office or Collect+ branch. I checked its website, which says;
Extended Returns Policy – COVID-19:
The last thing we want you to be worrying about during these uncertain times is how you will return your Sosandar order! So to help we’ve extended our returns policy.
For any orders placed on or after 1st June, you will have 30 days from receipt of your order to return for a refund.
For orders placed between 23rd March - 31st May, you will have until 30th June to return your order for a refund. We will of course make additional exceptions on a case-by-case basis where necessary.
This strikes me as important, in that there could be a backlog of customer returns between now and the end of June, thus driving the returns rate back up again, from an abnormally low level reported today, possibly. Many thanks for pointing out this important point. End of edit.
Next/ John Lewis - Sosandar is going live on their online platforms from this autumn. This could be very significant longer term, if Next/ John Lewis heavily promote Sosandar product to their existing customer databases - especially Next, which is huge.
Klarna extended payment option added to website - might help sales, but probably only in a small way, as Sosandar's customer base is probably quite affluent, so wouldn't need extended payment terms.
Margins - promotions & discounts used to kick-start sales in early part of lockdown. Since moved back to full price.
All the above sounds good to me. Now on to the not so good stuff;
Cash - was £5.2m at 31 Mar 2020 year end. Fell to £4.4m a month later, as stock had to be paid for. Flat in May, which is encouraging. Says it can continue running the business at this significantly reduced cash burn level.
Cash burn is the big issue with Sosandar. The original business plan drastically under-estimated how much cash would be required to drive growth. Growth has been impressive, but it's come at a heavy cost. To be fair, several things did change - e.g. factories are now reluctant to give credit, due to UK retail insolvencies. Hence cash is now required up-front for purchases of inventories. Also, marketing spend was cranked up heavily in 2019 to accelerate growth. In reality though, this has just hauled growth back up to what was originally planned, instead of a shortfall occurring.
I've looked back through the last year's RNSs, and this is how it panned out;
Cash as at 31 Mar 2019: £3.6m
July 2019 fundraising at 15p: £7m
Cash used in H1: £(3.7m)
Cash as at 30 Sep 2019: £6.9m
Feb 2020 fundraising at 17p: £5m
Cash used in H2: £(6.7m) - big marketing spend (e.g. TV ads)
Cash as at 31 Mar 2020: £5.2m
That's an eye-watering £10.4m of cash used in the FY 03/2020. That seems extremely high, and I had to double-check my figures. However, there are 3 things to bear in mind;
- Fees relating to the two fundraisings are likely to be about £1m of the cash burn, and
- Inventories rose significantly, and trade creditors likely to have come down (as credit not available from suppliers). Hence I estimate these working capital movements might have absorbed c.£2m cash over this period.
- Marketing spending was deliberately cranked up big time in autumn/winter 2019, to drive sales growth - which was a policy decision, and has since been reversed.
The operational cash burn is therefore less than £10.4m, and is probably something like £7-8m for FY 03/2020 - still a scary number, given that there's only £4.4m cash left at end May 2020. Therefore, yet another fundraising looks likely for later this year. Each time they raise more cash, it dilutes existing holders, and the share count is likely to be about double what it was when Sosandar floated, once the next fundraising is done. Plus fundraisings hurt the share price.
This wording below clearly leaves the door open to more fundraising at a later date. Still, at least there is no immediate funding problem, in terms of the next few months anyway. I suspect more cash would be needed in order to fully stock-up ahead of the busiest autumn/winter season;
Given this and the strength of its balance sheet, the Company is confident that its existing finances are sufficiently resilient to withstand the current crisis and means it is well placed to resume investment in growth at the appropriate time.
Cost reductions - these are surprisingly drastic;
- Big reduction in planned marketing spending. Focus is on repeat orders from existing customers. This is the big advantage that online retailers have - the cost base is mostly variable.
- Carefully managing stock levels
- Discretionary spending frozen
- c.60% of staff furloughed - this is a surprise. The company must be running on a skeleton staff, and my worry is that this might impact plans for the autumn/winter season, and possibly harm customer service
- Unspecified reductions to Board remuneration. The key people (Julie Lavington and Ali Hall) were not paid very much to start with, so I hope they don't lose their motivation
.
Trading update for FY 03/2020 - Sosandar announcements tend to try to bury the bad news at the end. I don't like that. Hence the reverse format of today's update (current trading & all the positive things at the start) suggest there's likely to be a sting in the tail.
Revenue of "at least £9m". This is over 100% up on LY, but below original forecast, as indicated in the profit warning on 18 Mar 2020, which said;
The current expectation is that, given recent developments, this trend will continue in the immediate future and the Company's performance in March will be well below forecast. Accordingly, for the year ended 31 March 2020, the Company expects its revenue to be between £9.0m and £9.3m and net loss for the year to be between £6.5m and £6.8m. [from RNS dated 18 March 2020]
Returns were 50% for the year. Hence the recent reduction to 33% in Apr-May 2020 is very good (see edit above - this is likely to have benefited from the relaxation of returns policy due to covid), but possibly not sustainable at that level, once dresses become a larger part of the sales mix in A/W season, maybe?
Stock provision - an "increased and prudent stock provision" is presented as if it's something to do with covid-19! This seems misleading to me. I noticed in the last accounts that inventories seemed unusually high, and was fobbed off with unconvincing explanations. After further probing, it transpired that there was an overhang of unsold autumn/winter 2019 stock, which was being mothballed in order to re-introduce it for sale in autumn 2020.
Clearly the auditors must have looked at the inventories, and decided that the company should make a provision against this unsold stock. That has nothing to do with covid-19. It's more a case of trying to bury the bad news at the end of the RNS, with a lame explanation. Much though I like the people at Sosandar, I cannot help feeling that the over-embellishment of the company's announcements is counter-productive, and undermines investor trust, by trying to gloss over bad news, instead of being honest.
I much prefer the approach of getting bad news out early, and clearly, then move on. Not concealing the bad news, and it then only becoming transparent later. Investors tend to respect an open approach, with balanced presentation of newsflow, not a one-sided version of events, buffing up the positives, and covering up the negatives. Let's hope future announcements are more balanced.
Here's the sting in the tail, right at the end of the announcement today;
The discounting used during the initial period of lock-down and stock provision, alongside the planned first order discounting following the period of intense customer acquisition in Q2 & Q3, is expected to result in the Company reporting a gross margin decrease of 555bps.
The Company also saw higher than anticipated returns on sales immediately prior to the announcement of the lock down.
As a result, the Company now expects to report a loss for the year which is slightly higher than anticipated in its announcement on 18 March 2020.
Slightly higher than the previous range of £(6.5m) to £(6.8m) suggests we're looking at a loss of maybe £(7m) for FY 03/2020. That's a poor result, there's no getting away from it. That's a considerable reduction in gross margin too - although for a small player in this sector, Sosandar's gross margin is still very good.
My opinion - as mentioned previously here, I cooled somewhat on Sosandar after the poor update on 18 March 2020.
Today's update has some good stuff in it, especially the decent sales growth (despite little marketing spend) in April & May 2020. Plus the big reduction in cash burn (neutral in May 2020) is good, but costs are going to rise again once staff come back from furlough. I also like the big reduction in the returns rate, from 50% to 33%, even if that's probably not sustainable for a full year.
Another fundraising seems inevitable, which means more dilution, which limits the potential for the share price to rise.
That said, Sosandar is getting close to achieving the scale it needs to become a viable, self-supporting business. Overall then, I'm happy to continue holding, albeit it's only a medium-sized position in my portfolio these days. I think the stellar upside potential is looking less likely than originally, due to the share count rising from each fundraising.
The update today is an improvement on the last update in Mar 2020, hence I think the share price rise today makes sense.
I appreciate that opinions differ on this one. Some investors are fatigued with repeated misses against forecast & fundraisings. Others can see that there's potential once it achieves scale. I think the current valuation reflects that fairly.
.
.
Venture Life (LON:VLG)
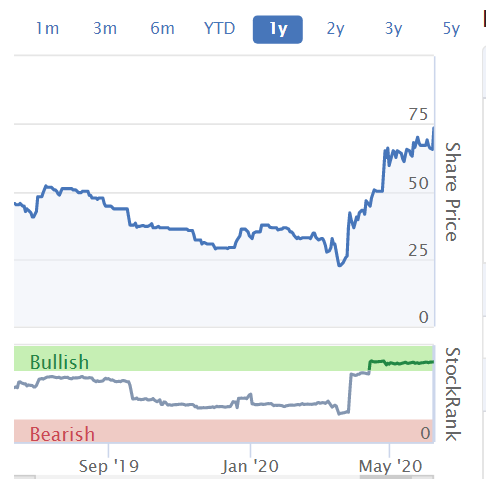
Share price: 73p (up 12% today, at 12:45)
No. shares: 83.7m
Market cap: £61.1m
I'm not familiar with this company, but Graham has written about it 6 times, in the archive.
The share price has been a stellar performer recently, so well done to holders.
.
According to the description on the StockReport this company specialises in treatments for the ageing population. So we know where to go when our haemorrhoids flare up, and dentures work loose (it sells products for both, apparently). Incidentally, I've asked for these company descriptions to be updated by Thomson Reuters, as some are showing signs of age).
Today's update starts with a recap of previous updates;
- Positive trading
- Order book significantly ahead of last year
- Exclusive contract with existing Chinese partner for £168m (spread over 15 years), including over £7m orders in 2020. It sounds like the Chinese partner is buying product from VLG, not the other way around, if I've understood that correctly.
- All other areas trading well
- Good demand for hand sanitising gel called Disinpluso
Today's news;
Extended scope of relationship with Alliance Pharma (LON:APH) which runs to end 2026, and
The best bit is next;
Taking these positive developments together, the Company is pleased to announce that it is confident that it will comfortably exceed market expectations for this year.
Excellent news for shareholders.
Broker update - there's a very useful update today from Cenkos, available on Research Tree. I've had a quick thumb through, and it all looks excellent to me. Forecast adj EPS is up nearly 28% today, to 5.45p. That puts it on a 2020 PER of 13.4 - which looks cheap, given the strong growth being achieved.
My opinion - this looks terrific, I wish I'd looked at it a few months ago! Providing nothing goes wrong, then it's probably not to late to buy some now. Earnings upgrades justify the share price move, in my view.
I've also had a quick look at balance sheet, and cashflow, which look OK to me. There is some debt, to fund 2 acquisitions, but it doesn't look excessive. More capex will be needed to ramp up production, but again not excessive.
VLG gets a thumbs up from me. Looks a nice growth at reasonable price type of share. Providing earnings are sustainable of course.
I'll leave it there for today. I had a quick look at Cml Microsystems (LON:CML) results, but they seem lacklustre, and I don't have any knowledge or insights about semiconductor companies.
Signing off, see you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Hi Paul
I appreciate your caution re CML Microsystems (LON:CML) - this company is driven by industry specific factors, but I thought the tone of the 2020 report was fairly upbeat - much more so than over the past two years where they have been having to adjust to industry trends. This could be a situation where the tide is turning.
My thanks to everyone who responded yesterday to my post regarding why the number of new virus cases in London has fallen to such a low level - now about 20 a day.. If anyone comes across explanations they are welcome to contact me at ires@dlmi.ie.
Sorry for going off topic but if the virus is dying out in the western world it helps explain the current strength of markets
Thanks for the Venture Life (LON:VLG) write-up, Paul. I think that you have summed it up nicely.
To try and play devils advocate. I appreciate that margins will be down on sales thru Next and J Lewis as they want a "heavy" cut, but equally won't their marketing spend be down as that cut goes to pay for brand recognition. Therefore won't these relationships reduce the liklihood of another raise given the significant cost is marketing spend.
The 60% furlough doesn’t totally surprise but feels a bit high. Marketing, PR etc could all have been furloughed without huge impact, but does feel like they reduced their numbers in buying and core commercial too. I know of a discount high retailer that remained open with a clothing offer and they reduced their headcount by 40%.
Surprised by the stock provision. Auditors must have had concerns and decided to be super cautious, no doubt inspired by Ted Baker’s overly aggressive stock accounting and subsequent write down.
I don't know whether this becomes official WHO guidance as more data come out but surely this is very important if true. Asymptomatic spreading has been one of the great scare stories and key differentiators with normal flu. I don't think this includes people who are asymptomatic in the incubation period and then develop symptoms later which would be the best possible news. Another reason to buy those "recovery play rentals" though of course the UK Government won't make any policy changes until the idea gets reflected back to them in a focus group mid-Autumn
https://www.independent.co.uk/...
I'm no expert on Sosandar (LON:SOS), but the 60% furlough comment seems more than slightly worrying to me. They are an online only retailer, so many of the restrictions caused by lockdown won't affect them. Of course, it's true that people are less likely to spend money on new clothes to stay at home, or appear on Zoom, and that will affect sales. Also possibly, their warehouses may be arranged so that social distancing is difficult or impossible, but that would not be good news, and some comment should have been expected if it's true, as it would clearly impact on possible sales. But 60% seems like a very large number. It would make sense for a company that's struggling and can see a useful source of short term support, but it certainly doesn't ring of the confidence of a rapidly growing retailer to me.
They don't have a warehouse - they contract it out to Clipper.
No news out today, and trading on very thin volume; but does anyone have an opinion on Nucleus Financial (LON:NUC) ? I see alot of asset management stocks recovered from their march lows to go to all-time highs (£LIO), so wondering if this is next on the radar?
EV - £100M
REV - £50M
NETP - £5M
Do these clients have a high retention rate to platforms like this?
And if so, is it hard to win new business from other "sticky" platforms?
Would these clients stay if the prices rise to organically grow profits?
Cheers
Morning Paul, re Sosandar (LON:SOS), what a mature (Another year beckons) informed and well measured piece from you
Amazed that you make it clear you never TIP ANYTHING but a 35% rise today on huge volumes "May" have something to do with how well your views are received
(YES I can hear you saying it already DYOR)
Text book analysis, well worth a long w/e
No, I don't think my views affected the share price at all. It's not helpful to speculate on that anyway, as it could attract unwelcome attention.
I just tell it how I see it, on every stock covered. Because these reports focus on trading updates & results statements, these are by definition the days that the share prices move the most. My views have very little, if anything, to do with those price moves.
Does anyone know why Sosandar (LON:SOS) are unable to give a more accurate revenue figure for a financial year that ended >2 months ago? Seems off/worrying.
FYI this morning they quoted revenue for the year ended 31st March 2020 of "at least £9m"
As an aside, someone asked about Next (LON:NXT) margins for 3rd party sales. From memory I believe Next aim to make a 16% margin from 3rd party sales and give any excess back. They could charge more but don't want to stifle companies who wish to use their platform.
No position in either of the above
Sosandar (LON:SOS)
Does anyone know why Sosandar (LON:SOS) are unable to give a more accurate revenue figure for a financial year that ended >2 months ago? Seems off/worrying.
I have always presumed sketchiness is due to the fact that the accounts need to be audited (can anyone confirm?) - they could end up with egg on their face if the auditor demands a revision to end of year returns provisions made which would likely be adjusted via sales(?) - do we give them a covid related cop out that the auditor may not have been able to do their thing or they internally havent be able to do do their thing to confirm the total if they need to check with auditor?. I do though see this as a mini red flag that they don't at least have the confidence to nail more specific number however it could be though to the nearest material number (100k?) that the number is simply 9 mill this year - it would be my guess that the sales fuigure will turn out to be my 9.0 mill.
They don't book returns as sales.
They don't book returns as sales.
Well yes they would. If a customer returns an item previously sold, then the original sale has to be reversed out of revenues.
Sosandar (LON:SOS) bankers will be scrambling around their home offices at break neck speed after current share price reaction getting preparations for the next placing underway! These guys have form, talk up revenue growth to juice the stock and then get the next placing out.
European markets didn't get the memo this morning, or just decided not to take their cue from the S&P 500!
Yes the markets seem to have got a bit nervy today after day after day of going ever higher with the Nasdaq hitting another all time high last night. Dire economic figures, company after company announcing job cuts...investors just taking a bit off the table today I think.
Re £SOS - Overall, results look OK for a share priced at current levels . Still selling products their customers want and business model intact. As a retail investor, I was indeed very pleased they are going on Next/John Lewis online websites; I think this is exactly the right target audience for them.
Let's hope they can at least trade from current cash long enough and demonstrate enough growth for the share price to recover before they have to do another equity raise. (Disc. I hold)
BTW: What did this mean : "Improvement in unit economics, with positive order contributions for the first time in April and May"
Re Sosandar (LON:SOS) - Overall, results look OK for a share priced at current levels .
It must just be me being old fashioned then. What share price should a company that has never made a profit or generated any cash be? Why should it be higher than 0p?
Revenue is vanity, profit is sanity.
All the best, Si
Sosandar (LON:SOS)
Share price nearly up 50% on yesterday with traded shares of 9m or so.
It would seem someone is encouraged by the RNS. Its not one for the faint hearted though, and whether this share should ever have been on the market at this point in its development life cycle is
doubtful.
Sosandar (LON:SOS)
Call me cynical but having 60% of the staff furloughed strikes me as a bit off for an online growth business with no physical stores. Doubtless there's a perfectly innocent explanation.
guess you wouldn’t have bought Amazon then .
There is a new Cenkos note out on Venture Life (LON:VLG) today (I hold). They highlight the following progress in 2020 (so far):
The company is confident that it "will comfortably exceed market expectations for the year". Accordingly, Cenkos have increased their 2020 revenue forecast from £25.3m to £30.3m and their adjusted EPS forecast from 4.3p to 5.45p.
Ilika (LON:IKA) ....i remember you writing in December last year that if the share 4-bagged after their investor meeting you'd sell yours. Well it's 2 bagged, they've raised some money and announced today that at long last they are about to get a product into 3rd party manufacture. And there's another investor/analyst meeting in July!. Science remains compelling to me. Any updated thoughts ...perhaps not for today.
It would be good to hear your views on Venture Life (LON:VLG) if you get chance Paul
It will be interesting to see what the market makes of the trading update from Sosandar (LON:SOS)
Will private investors be swooning at the prospect of Sosandar clothing appearing on the Next and John Lewis platforms in the autumn? If anyone knows the typical financial terms for these listings it would be good to hear. My guess is that Next and JL will want a hefty share of the margin, perhaps some initial listing fee too (you may have to buy your way on) and perhaps also designs only available to them (adding further costs).
The car market is also interesting right now and so the update from S&U (LON:SUS) quite interesting. People may be more interested in getting a replacement or new car to commute to work to avoid using public transport if that’s their current mode of travel (although if many people do this clearly the congestion on the roads will be a deterrent). There’s also the rumour that the government may offer some incentives to buy electric or hybrid vehicles. Not clear to me how that will effect the market either.
In the round, I still think that the rag-trade, retailers and car vendors (and by extension car financiers) are areas that are very high risk and so best avoided unless the opportunity is exceptional. And right now I don’t see Sosandar and S&U as exceptional.
Sosandar (LON:SOS)
Will private investors be swooning at the prospect of Sosandar clothing appearing on the Next and John Lewis platforms in the autumn?
That's interesting question - i would say the news has to be good news - even if they don't make money (or much money should i say) it's improving the brand recognition and that's what its all about at present (?))- presumably kinda like just eat the necessary evil to build up the customer base. It should be easy peasy for customers to switch over to ordering direct if the customers like what they buy i am guesing the enhanced offering on the sosander website should hopefully be enough to tempt them over. I don;t know enough though to know if tjis makes any measurable difference overall or if its that easy to signup that it may not bring in any material amount of sales or advertising.
I quite like the look of S&u (LON:SUS) but only 18% free float puts me off buying
(I am long on this share)
Its not a share to trade but hold for a fairly good dividend and a slowly increasing share price (in normal times.) I like their prudent approach and whilst that means there isn't stellar returns, at times like this they have an advantage when things normalize and potentially some more aggressive competitors might not be around.
Sosandar (LON:SOS)
Hard to get a handle of whether todays news is good or bad , bit of a mixed bag probably enough for everyone to be happy that their prior convictions are correct. i remainly firmly on the sideline - i still get the impression they are struggling to get the critical mass they needd to prove the business model will be a "winner winner chicken dinner" type - rather than something that struggles to generate positive free cash. That's realy all factored in to the bargain shareprice though (they still have decent sales growth) - although low shareprice is bad news for current shareholders if they will need to raies "More" funds - they do have that Oilver streak in them i think unfortunately.
slight niggle that they need to do stock provisions - for fast growing company like them you would think shifting stock would not be a problem - and i would like to think stock is evenly monitored constantly so margins aren't overstated for 6/12/18/24/36 months then for it all to be taken away by a sneaky one line adjustment later on.
These actions include an expected increased and prudent stock provision with the full year results due to uncertainties of the continued impact of COVID-19,
On the plus side revenue growth is up 62% for april and may - note last year q1 was very week growth so these and comparisons against weak numbers. They good news this increase is on massively reduced marketing Reduction in marketing expenditure of 69% year on year.
Note they also advised the previos year at a similar time that they were spending less in this area - so perhaps this number is pimped due to their being so little spend in the period anyway that they can furether turn off the tap without that making a difference and trot out a nice fancy sounding stat.
Last year in july
This revenue growth has been achieved through strong repeat business with deliberately less emphasis on new customer acquisition as external factors resulted in a tougher acquisition environment.
I guess the question i have is if they are reducing expenses to the bone getting back to basics and still increasing sales materially thats brilliant - but should that not now be enough to put them in at least a breakeven situation? - ok i guess they are looking 2-3 years ahead and probably have costs aligned to gearing up to 25-30 mill plus sales - so kinda makes sense that they cant breakeven. Would be interested to see what expected profits and cash burn are for current year. I am much less likely to be picking up shares if they will be back in oliver mode again in the next 3-12 month - ie self funding going forward.
After some thought I decided the report for Sosandar (LON:SOS) was on the side of bad. Probably another fund raising and dilution on the way. So I have lost patience and sold out. A bit of loss, but so be it.
Any holders of City Of London Investment (LON:CLIG) have a view on the merger announced today? From a quick read I was originally disappointed when I saw PBT for Karpus was just $1.3m last year. But then I read this:
"The Circular to be published shortly in connection with the transaction will contain pro forma statements of net assets and profit before tax of the Enlarged Group.
The pro forma net assets of the Enlarged Group were £19.1 million as at 31 December 2019 and the pro forma income statement shows a profit before tax of the Enlarged Group for the six months ended 31 December 2019 of approximately £7.4 million (£4.5 million after transaction costs). In the year ended 30 June 2019, KMI recorded remuneration to the highest paid member of key management, its Chairman, Chief Investment Strategist and 66.1 per cent. stockholder, of US$15.5 million. The Chairman will resign from KMI on Completion although the Board currently proposes to offer him a position as consultant to KMI in consideration for a fee of US$100,000 per annum. The reduction in his remuneration would, to the extent that earnings continue to be made by KMI in future years, be available to enhance the earnings of the Enlarged Group."
So we're almost doubling the share count but getting 160% more profit. Not without risk given the chief investment strategist of Karpus is moved on and bringing together two companies of the same size may be tricky, but the deal sounds reasonable.
The market reaction seems to be positive. CLIG share price is currently up.
I have a decent sized holding in CLIG. I'm not a big fan of M&A in this sector, because it's a people business and good people can leave. But...these are not huge firms, they both operate in a small niche, they both seem to make good returns if you exclude the remuneration to the departing Chairman.
On balance I'm happy to sit tight. Neither add nor sell until the dust settles. I'll be watching to make sure that the KMI profit doesn't decline; it has been a little variable. Biggest risk in my view is the high multiple of the US market.
Patrick, I agree that there could be for City of London Inv Group some EPS enhancement, but by my calculations is a lot lower than your figures. Making the assumption that the full George Karpus bonus can be added back (without affecting revenues or other costs), PTP of Karpus Management Inc in the year to June 2019 would have been approx $16m (£12.7m). This compares with a CLIG PTP in the same period of £11.4m. So combined PTP could rise to around £24m (2.1x) on a 1.9x increase in the share count to 50.679m shares.
I don’t think we are given any guidance on tax - but I doubt blended tax rate would be lower than the UK one.
I see that there is now a positive 8 page note out by Hardman - available to all - forecasting a 14%/ 15% uplift to EPS in both FY 21 and FY22 from the merger -overall the EPS rise by more from Hardman’s previous estimates because of new market assumptions.
The Karpus business seems to have a similar net income to AUM of around 75bps - so its higher profitably (stripping out the bonus) must be due to a lower cost base. Either, you could view this as a positive, where CLIG might learn from Karpus - or wonder if this low cost base will be maintainable.
(I also hold).
Hi Patrick,
The City Of London Investment (LON:CLIG) imply that the transaction should be earnings enhancing. I suspect there on some overhead savings and KMI will take profit in the future as Dividends, Still plan to hold until the next reporting event.
BSV
Panoply Holdings (LON:TPX) Investor Presentation June 2020, (given as a webinar last week), just published here. Neal Gandhi, CEO & Oliver Rigby (CFO) present an update on the group, the structure, how it's performing, the impact of CV19, and how the business will grow. They are sounding very positive.
piworld webinars this week:
Tr Property Investment Trust (LON:TRY) today, 9th June, 5pm. Marcus Phayre-Mudge, Fund Manager is superb. He will give an interesting insight into commercial property generally. The fund gives 4% yield. has a 12% discount to NAV. TRY was mentioned by Reg Hoare in his excellent webinar Investment Trusts: An Investing Panacea for Pandemics. To register for the webinar, click here.
This Thursday's piworld webinar, 11th June, 1pm. Our guest is Robin Griffiths, who was recommended by a listener. Robin will give his insight to the macro picture and markets. Robin uses technical analysis, economic forecasting models and behavioural factors to guide investors on when to buy what. His newsletter is expensive, but we will get some great nuggets of his thinking in this hour, for free! I spoke to him yesterday, he's got a lot a wealth of knowledge to share. It will be a goodie. Register via this link.
Great - very interested in the Panoply presentation. Thanks Tamzin.
Morning all, its not macro Monday so I will keep it short.
For those interested in all the free podcasts you can access - Moneyweek interview with Hugh Hendry plus Macro Voices with Luke Grownman. Inflation V deflation - after each one I am convinced they are right - but both cant be right. They both like Gold which also cant be right. Anyway its there so listen if interested.
The market is in inflation mode, and inflation is positive. If the $ strengthens and/or Treas yields fall...this inflationary trend will falter. Its a tug of war - inflation V deflation ... the $ measures who is winning.
B.P. Marsh & Partners (LON:BPM) final resuts out today (31/3/20)
Net asset value increased by £10.7 mill - 8.5% increase net of dividend
Net asset value 380p
curent shareprice is 190p with market cap of £71 mill
It's all about the outlook though - how affected are they by covid?
The anticipated trading impact of Covid-19 will be factored into our interim results to 31 July 2020. The impact of the virus is being closely monitored and all investee companies have prepared response plans and proposed measures have been shared across the portfolio. At this juncture Covid-19 appears unlikely to negatively influence the portfolio as a whole in a material fashion, and we remain confident that our investment strategy and sector focus will prove resilient during this period of disruption.
in some respects they have kicked the can down the street somewhat, but i would take this is positive enough for me to think that the current shareprice seems a nice tempting addition point - although i guess a small downtrend in operating results might be valued in investment valuations perhaps? - one would hope that a reversion to norm is probable though. The stock was trading mostly abolve 260p pre covid and they have added more asset value in the last 6 months. They did have a little a bit of a wobble last year with issues at LEBC holdings (2/9/19 update) - so with that issue included the end of year results are somewhat pleasing
Note they do also point out that their investments aren't primarily risk takers themselves.
The Group's investment criteria are focused on the Financial Services Intermediary Sector with a particular interest and knowledge in Insurance Intermediaries. This means that companies with which the Group partners do not involve themselves in primary risk-taking activities.
Overall thumbs up on my sketchy look this morning - haven;t really gone into the detail so i could be misisng something here.
B.p. Marsh & Partners (LON:BPM) are one of my larger holdings in my buy and keep in the draw group. I expect never to get a huge multibagger but over time they will produce decent results. In Nexus they also have a company which at some point will go to the market which I expect will generate quite a paycheck for shareholders. The discount to NAV at the moment is huge even taking into account some impact from COVID. I bought a few more this morning as the market was opening.
Hi Paul, I know that these aren't very popular because of the long run of low inflation rates, but with all of the borrowing going on at the moment, what is your thoughts on ILBs?
@dbosomworth
I have held £INXG since 2014 and despite selling some too early and buying back at a higher price, they show a gain of 20% overall. I have had some reasonable dividends along the way too because (wrongly with hindsight) I bought the distribution ETF not the accumulation. I recently bought some £SGIL (accumulation) thinking that inflation was a possibility in the USA and that the dollar might appreciate against sterling.
I have found Index linked Gilt ETFs (and sterling denominated physical gold through £PHGP ) a useful diversification for an equity portfolio. They often move in opposite directions, which has given a smoother ride in the past few years, though that may not say anything useful about the future.
I'll keep these through the BREXIT denouement. Otherwise, I'm heading back into cash, fearing trouble as the market anticiates the results season and small cap illiquidity.
EDIT: Why didn't the EPIC codes expand as they usually do?
Ive been trying to get some research for a few weeks - if I find something I will post. I can tell you IL tracker around late Feb March was +2-3% YTD. It is now +10% and peaked at 13%. Since the market moves recently imply higher inflation expectations ... the market has sold off. Make of that what you will, but basically inflation is good but not higher rates.
My morning smallcap tweet: Telit escapes rap on knuckles
Avacta (LON:AVCT) Omega Diagnostics (LON:ODX) Venture Life (LON:VLG) S&U (LON:SUS) Sigmaroc (LON:SRC) Sosandar (LON:SOS) Telit Communications (LON:TCM) Ilika (LON:IKA) Redcentric (LON:RCN)
Avacta (AVCT) covid infection test developed with its partner Adeptrix has reached prototype stage and can detect the coronavirus spike protein in model samples in the concentration range appropriate for a clinical diagnostic test.
Omega Diagnostics (ODX) has shipped first order for COVID ELISA test to Senegal worth ~£0.1m. Registration and evaluation activities in 15 countries which is expected to lead to orders in the near future. Guides FY(Mar) EBITDA £850k-900k, slightly ahead of market expectations.
Venture Life (VLG) will comfortably exceed FY(Dec) market expectations. Extends commercial relationship with Alliance Pharma and has been appointed as a second manufacturer of Alliance's Kelo-Cote product.
S & U (SUS) motor finance transactions at 40% of normal from a low of 15%. Collections have fallen in the most recent month by about 20%. Bridging finance transactions less than 25% of budget but recent applications have been robust allowing a good quality pipeline to increase. Cash: " As predicted, recent cash generation has seen group borrowings fall to GBP98m, some GBP30m less than budget. Gearing is now around 55%."
SigmaRoc (SRC) rev for 5 months to May down 16% LFL, adj for acquisitions. Cash at hand inc from £11m to £13.5m during 2 months to 31 May. "Resilience of the business through April, together with the recovery in activity levels during May, gives the Board confidence that SigmaRoc will be able to manage effectively through the crisis and maintain progress in its growth strategy." I hold.
Sosandar (SOS) [edit] guides FY(Mar) rev at least £9m, up over 100%. Expects loss slightly higher than guided in March."Rev in Apr & May up 62% but orders up only 44% as marketing expenditure down 69%. Will be listed on John Lewis and Next sites from Autumn. Cash £4.4m end May down £0.8m in 2 months.
Telit Communications (TCM) FCA will not take enforcement action on timeliness & accuracy of stock market announcements. I'm short.
Ilika (IKA) guides FY(Apr) in line with rev £2.8m up 10% and EBITDA loss £2.1m (£2.2m). Plans to implement manufacturing strategy for tiny Stereax solid-state battery remain on track.
Redcentric (RCN) has extended its bank funding facilities into 2022.
Morning birthday week Paul!
Maybe you could take a look at VLG? Has grown to my largest position.
TU today: Alliance Pharma agreement extended, appointed 2nd producer of their products, runs until 2026
Will 'comfortably beat expectations for the year'
Michael
Significant deal announced by CLIG today, a small fund manager in which I have a decent sized holding. I wonder what impact this might have on the (generous) dividend...
This might offer some guidance on dividends
https://www.investopedia.com/a...
City Of London Investment (LON:CLIG) say the following in the RNS:
“For the financial year to 30 June 2019, the Board declared dividends of 40.5 pence per Share (calculated based on the weighted average number of Shares in issue for the year). This included a special dividend of 13.5 pence per Share.
The Board of CLIG attaches great importance to providing Shareholders with a stable flow of dividends, balanced by a policy of prudential capital management. To this end, the Board has for some years adhered to a dividend cover ratio of 1.2 times profit after taxation attributable to Shareholders based on rolling 5-year periods, using accumulated retained earnings to address any short-term profit shortfalls that derive from volatility in the markets in which CLIM invests. The Board of CLIG intends to continue with the same dividend policy on Completion of the Merger.”
So div policy remains the same - you need to take a view on what EPS will do. Numbers are given in the RNS but when you back out the savings from the $15.m annually paid to George Karpus - you are then need to make assumptions whether performance suffers and how much remuneration will now need to be paid to other employees. So I think it is a bit of guesswork on future EPS..
Note the merger values the AuM of Karpus at a higher value per $ than CLIG - for the understandable reason it is less EM focused. Also different investor base (less institutional) maybe more durable.
This announcement does underline why it would be good for RNS' to be published the night before the market opens. Trying to digest and work out this information in an hour (or, in my case this morning, 10 minutes) is not ideal.
Completely agree. Impossible for an investor to understand the deal at short notice.
CLIG was one of my more pleasing holdings where the dividends have more than covered the cost of the purchase. I did sell the bulk of my holding though when Barry Oliff completed his planned sale of shares due to retirement.
It seemed to me that the price was getting a little high and his retirement would probably mean a change in direction.
I think that CLIG is well run with a fairly simple investment model, but it is very difficult to monitor. I seem to recall that its earnings are in dollars whilst costs in sterling. As such, it was a useful pound hedge.
Morning Paul any thoughts on Oxford Instruments (LON:OXIG) net cash well up, £200 mil roughly of head room moving forward, interim divi cancelled to save costs. Minimal forward guidance but seems well financed to ride out the storm.
Regards Andy
Hi Paul - thanks for keeping up the good work during this difficult time. I guess the Sosandar update has got to be on your list for today and your thoughts would be appreciated.
Yup, Sosandar (LON:SOS) is top of the list, am looking at it now.