Small Cap Value Report (Tue 9 Mar 2021) - RBGP, SNWS, HEAD, SAG, DFS, MMH

Good morning, it's Paul & Jack here with the SCVR for Tuesday.
Timing - today's report is now finished.
Agenda -
Comments from last night's Mello Monday, re Rbg Holdings (LON:RBGP) (I hold) and Smiths News (LON:SNWS) (I hold)
Headlam (LON:HEAD) (I hold) - Final results for FT 12/2020 - good H2 recovery, and shares still look good value
Science (LON:SAG) - Audited results for FY 12/2020 - looks an interesting company, trading well
Dfs Furniture (LON:DFS) - interims to 31 Dec 2020 - trading really well, but balance sheet still terrible! Positive read-across forScs (LON:SCS) (I hold)
Marshall Motor Holdings (LON:MMH) - Full year results (this section written by Jack)
.
Mello Monday
Last night was excellent, with some interesting presentations. The CEO of Rbg Holdings (LON:RBGP) (I hold) said something that stuck in my mind. Namely that the M&A division was now completing deals which had been done entirely online - i.e. selling businesses where the buyers & sellers had never met! It's now all done through Zoom or Teams, email, phone, etc. This reinforces to me how things have permanently changed in the last year. It's dawning on many of us, that it's actually so much more efficient to have meetings online, instead of taking a whole day to travel in & out of London. Having said that, I really miss the de-briefings at the Lord Aberconway, after meetings at Finncap, so whilst Zooms are great, I can't wait to participate in actual meetings again - just perhaps not as many as previously.
.
Smiths News (LON:SNWS)
(I hold)
My stock pick in the BASH session at Mello Monday last night, was the turnaround at Smiths News (LON:SNWS) (I hold). Click here for the presentation slides I referred to, which give details on the main points. I have a 1-2 year timeframe on the turnaround here. I reported on it here in last week's SCVR, with an in line trading update, and a remarkably low PER of about 3.
Note that the StockRank is strong, at 90. I think the net debt could halve in the next year, from strong free cashflow, plus the deferred disposal consideration re Tuffnells and a possible pension surplus payout. If that happens, then it should transform investor perception of the company, and resumption of dividends would be a further catalyst fora re-rating.
Its CFO described the business as "boringly resilient", generating c.£10m EBITDA per quarter, and little capex required (outsourced business model) going forwards. The stock market has begun recognising these improvements, but it seems to be lagging behind in my view.
.
Paul’s Section
Headlam (LON:HEAD)
(I hold)
422p (pre market open) - mkt cap £359m
Headlam Group plc (LSE: HEAD), Europe's leading floorcoverings distributor, today announces its final results for the year ended 31 December 2020.
I’m going to watch the results presentation video here, then comment on it below later:
.
Profitability - H1 was badly impacted by covid in Q2, leading to a small loss of £1.2m in H1. There’s been a strong recovery in H2, giving overall underlying PBT of £15.9m. In other words, in H2 the business pretty much returned to its previous run rate of c.£40m p.a., assuming no further covid problems. Therefore, I’m valuing the business on the likely future run-rate of profits.
Note there was a £5.5m bad debt provision, a hit to profits absorbed within the underlying figures. Hopefully that should be a one-off, giving another reason to expect a bounce back in future years. It sounds from the results video as if the FD is being prudent, and expects for some of this to be collected in, which would help 2021 profits. Non-underlying items are mostly non-cash, being a goodwill write-off, plus some cash restructuring costs.
Current trading - soft, due to the latest lockdown, but I don’t think this matters, because everything’s opening up shortly. Valuing shares is about looking forwards, not backwards -
Trading in January and February 2021, typically the quietest trading months, soft given lockdowns and non-essential retail businesses being closed. The busier months ahead to benefit from easing of restrictions, reopening of retail businesses, and the OIP improving performance and revenue growth opportunities
Cost-cutting & efficiency gains - covid has accelerated changes that were already underway to make the business more efficient. Hence future profits could not only match historic levels, but end up higher than before. I think the current broker forecasts of 26.8p for 2021, and 30.9p for 2022 seem far too low. Without covid disruption in future (hopefully) then 40p+ EPS seems more likely, or possibly higher, given the efficiency improvements being implemented.
The benefit from efficiency measures is £4m in 2021, and £8m in 2022 - increased profits, which is quite material in the context of a business with a normal run rate of about £40m p.a. profit. Headlam is targeting a UK operating margin of 7.5% by 2023.
Dividends - are starting up again. Only 2p, which is nothing compared with the pre-covid level of c.25p p.a.. Given that Headlam received £11m benefit from furlough in 2020, perhaps it was considered prudent to hold back on rewarding shareholders, to prevent an outcry?
I’m more interested in dividend paying capacity, which in this case is very good. The business has net cash, lots of freehold property, and is back to generating reliable cashflows again. Therefore, it seems highly likely to me that dividends should get back to previous levels gradually. I can’t see any reason why they wouldn’t. What else is the company going to do with the positive cashflows? I always look forward a couple of years with shares I buy, and in this case, I reckon buying now should lock in a future dividend yield of about 6% - very attractive in a low interest rate environment.
Some commentators reckon that the recent 10% correction in NASDAQ, and the re-opening of economies, could herald a shift in focus from tech shares, towards value, possibly? I think that’s a persuasive argument, given the absolute gulf in valuations from cheap recovery things like HEAD, where the broker forecasts look too low, and there’s the prospect of decent dividends resuming. I think that’s bound to be attractive to some investors, especially people who think a bit longer term, like myself, and who enjoy receiving dividends from cash generative businesses.
.
Net cash/debt - top marks to Headlam for this excellent disclosure - it reports average daily net cash at the bank. This is far more meaningful than just giving period end cash figures, which are only a snapshot, and often don’t reflect the typical level. That’s one reason why enterprise value is such a flawed measure to use when valuing companies, because it relies on an erratic & easily manipulated year end cash balance. I hope to see more companies reporting average daily cash/debt as well as year end balances. It’s a good indicator of how transparent (or not) a company is in its reporting.
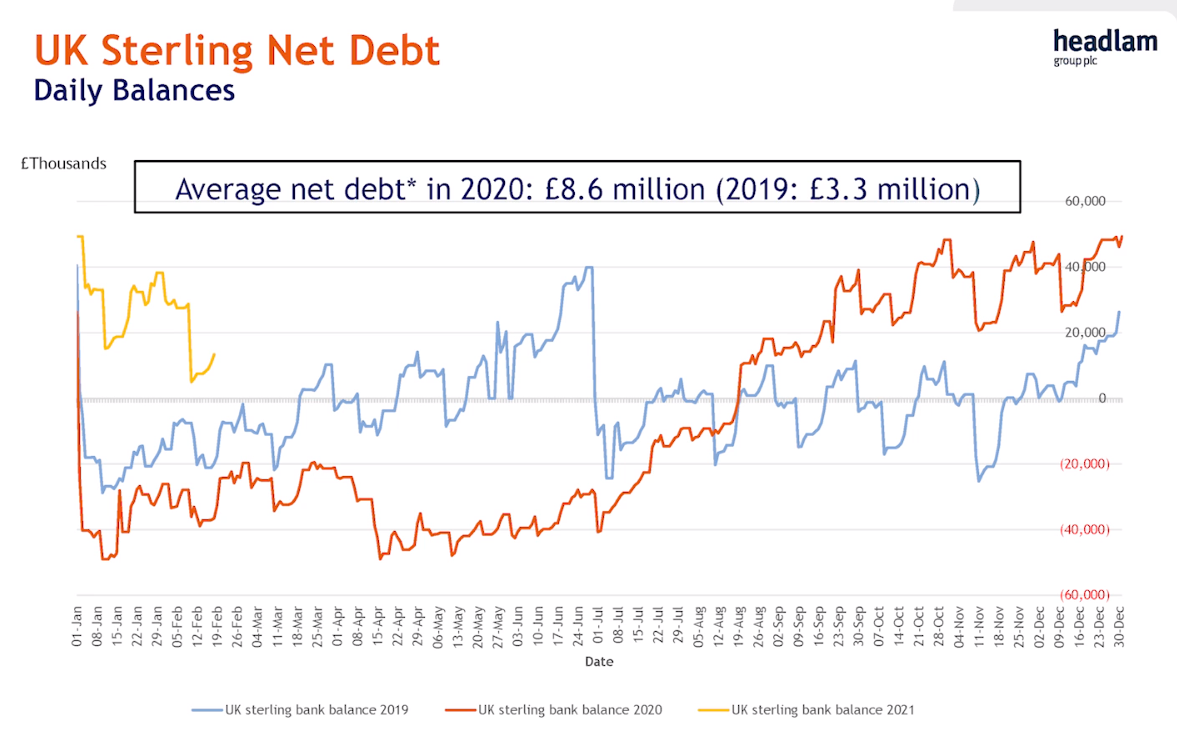
What we can see from the graph above, is the blue line (in the centre, trending sideways) is net cash/debt in FY 12/2019. It trends upwards, but then drops sharply down mid-year, which reflects payment of the dividend.
In FY 12/2020 (the orange line which rises strongly in the middle of the year) we can clearly see that it benefits from withdrawal of the usual dividend, plus strong measures to improve working capital in H2 - mainly focusing on reducing slow-moving stock lines.
Finally, the short, yellow line is 2021 to date, which obviously stops in late February.
I really like this slide, as it shows us the overall trend of cash balances, utilisation of debt facilities, and even the intra-month volatility. Excellent stuff!
Balance sheet - I’m very happy with this. Remember it includes c.£100m of freehold property, effectively thrown in for free. Although you could argue that this boosts profits by maybe £5-7m, given that if the property were leased, that would be the likely rental cost.
NTAV is c.£200m, which is really excellent.
The pandemic has shown how companies with strong balance sheets, especially those with freeholds, easily retain the support of the bank, and can concentrate on dealing with trading, as opposed to being forced into emergency, dilutive fundraising. This is so important in lowering investment risk, but is often overlooked (especially in a bull market). Headlam did not dilute shareholders in 2020, since no fundraising was necessary, very positive.
Cashflow - very good. Despite reduced profitability in 2020, the company has streamlined its inventories, by clearing out slow-moving stock lines, and focusing more on best sellers, which has caused quite a large favourable move in working capital. There’s £12m of deferred VAT to take into account, which will reverse at some point.
As you can see, the overall picture is very positive, and there will be a useful interest cost saving from not utilising the borrowing facilities much, if at all, this year. Although remember there will be a £12m lurch down in cash, when the VAT arrears are paid.
My opinion - I’ve only skimmed through the key parts of the results announcement, because I already know that this company ticks the boxes for my investment criteria. I think it’s modestly priced still (PER of 10 maybe, or even lower, once trading has fully returned to normal), with a good recovery underway.
The business model makes a lot of sense - offering outsourced bulk buying supply, and warehousing to smaller carpet retailers, who can order lots of typically small orders on a just-in-time basis from HEAD’s extensive ranges.
I like the measures being taken to make the business more efficient, which look set to provide upside surprise on current forecasts.
Divis could return to a yield of up to 6%, if we’re patient.
There’s a lot to like here.
Management strike me as down-to-earth, and focused on improving the basics of the business.
Overall, this looks a nice safe, value share, that should be a decent long-term investment, providing an income again in due course. It won’t set our portfolios on fire, and probably won’t be exciting enough for many people in this bull market, but for people who like decent companies at modest valuations, then I think this fits the bill, despite a strong recent recovery from the completely irrational lows of last autumn.
This share is surprisingly illiquid, perhaps investors buy & hold?
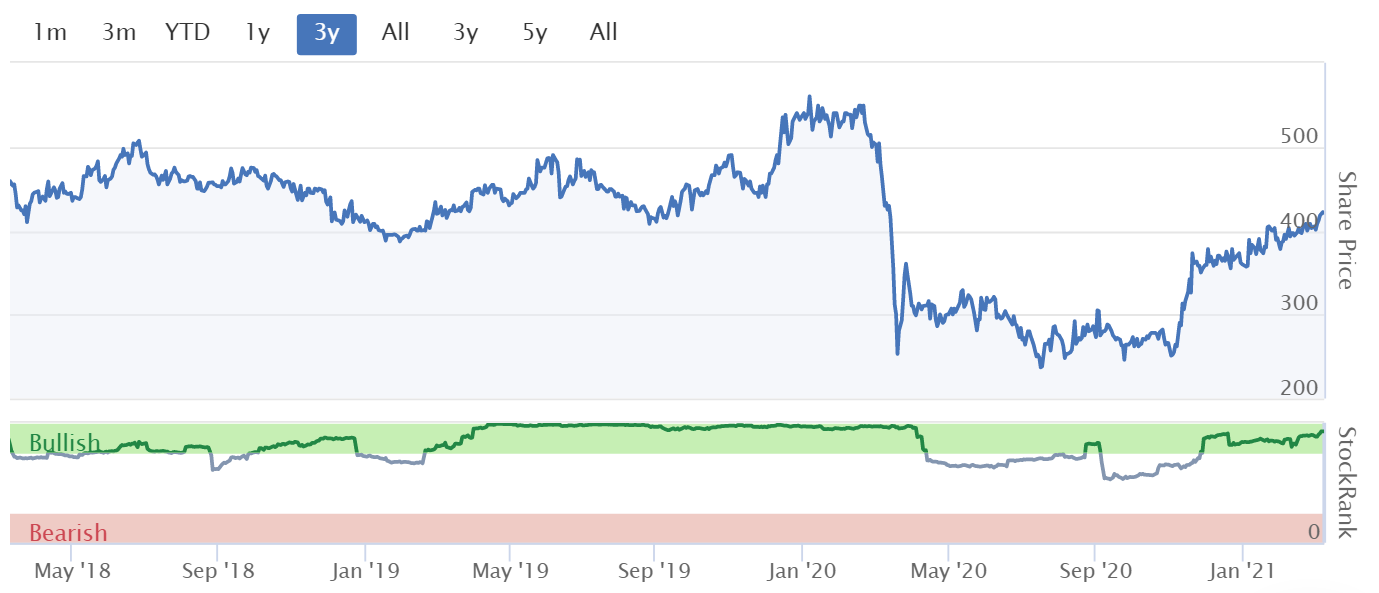
Note the consistently strong StockRank, shown below, under the share price chart.
What's the upside? I think it's worth 500-600p, so I see the price of c.410p as still being attractive.
.
.
Resumption of cruises
The Telegraph is reporting today that the maritime minister has told a group of MPs that cruises in English waters will be allowed to resume from 17 May 2021.
P&O has already announced that it's planning "staycation" cruises in UK waters
This looks a good stop-gap, whilst other countries catch up with the highly successful UK vaccine rollout.
.
Science (LON:SAG)
339p (up 8% at 12:42) - mkt cap £140m
Several readers have flagged up the results published today for FY 12/2020, with some interesting comments and analysis which engaged my interest. SAG is a slightly odd collection of consultancy businesses and a maker of digital radio components (Frontier).
I reviewed the FY 12/2020 year end trading update here on 12 Jan 2021. The year ended with a flourish, with expectations raised to £10m adj operating profit, or 18.1p EPS. It's beaten those numbers today a bit.
Audited results - for the year ended 31 Dec 2020.
Revenues are £73.7m, which is 1% above the guidance given in January - always good to slightly over-deliver.
Adj diluted EPS came in at 19.1p, a PER of 17.7 which is usefully above the most recent guidance of 18.1p, it looks as if the negative tax charge helped there. SAG has plenty of tax losses, and also gets R&D tax credits (see note 3), which boosts EPS (since EPS is always stated post-tax).
Very strong rise in profitability vs LY, up 62% at adj operating profit level. Note 2 shows how this has mainly come from the big turnaround at Frontier, which improved from a £(1.3)m adj operating loss in 2019, to a profit of £3.25m in 2020 - very impressive, but a key issue to research is whether this is sustainable? Possible supply shortages are mentioned, which could be an issue in 2021. The commentary says management is still considering its options re Frontier (might be sold, maybe a separate float?)
Dividend - of 4.0p is declared. That’s not much, only a yield of just over 1%, but seems to be double what was expected
A key theme for me is backing founders/owner/managers with big shareholdings, which this share is. They usually tend to make better capital allocation decisions, and avoid mistakes made by empire-building hired hands, plus they’re usually more financially prudent. This is evidenced at SAG with the strong statement that it has grown considerably since 2010, but has the same share count in issue. Although a cynic might point out that £1.7m share buybacks in 2020 masked the generous £1.2m (same LY) in share based payments to management.
Acquisitions - more are being evaluated. Given the good track record there, I think this is more opportunity than threat.
Balance sheet - is nowhere near as strong as the commentary makes out! NAV: £41.4m, less intangible assets of £24.2m, gives NTAV of £17.2m - that’s OK, but not amazing by any means, for a £140m mkt cap company.
The balance sheet structure is interesting though. Note there is hardly anything in inventories, only £1.3m, which is because the main business is services, not physical goods, hence it ties up less capital than a manufacturer or distributor of physical goods.
Own cash of £27.1m looks great, but bear in mind that note 11 shows that £13.8m is “Payments received on account”, which are shown within creditors until the work has been invoiced. Hence about half the cash pile has come about because of getting cash up-front from customers. Nothing wrong with that, in fact it’s a good thing, but personally I tend to deduct this creditor off the cash balance, to arrive at what cash is truly the company’s own surplus funds.
Freehold property is in the books at cost of £21.2m, with current valuations being £22.6-33.9m, so there could be some additional value there. Most of this is funded by mortgages.
Overall then, I can’t get excited about the balance sheet. It’s solid, but nothing special.
Cashflow - highly cash generative, helped by a favourable movement in working capital in 2020, which could possibly unwind next year maybe?
My opinion - the consultancy businesses look really good - generating very high profit margins, although about three quarters of revenue is non-recurring. These look very good, quality, niche businesses. Frontier, I don’t know enough about to judge, but the turnaround from losses into a decent profit is certainly impressive. It makes me feel that management seem backable, and know what they’re doing, in creating shareholder value.
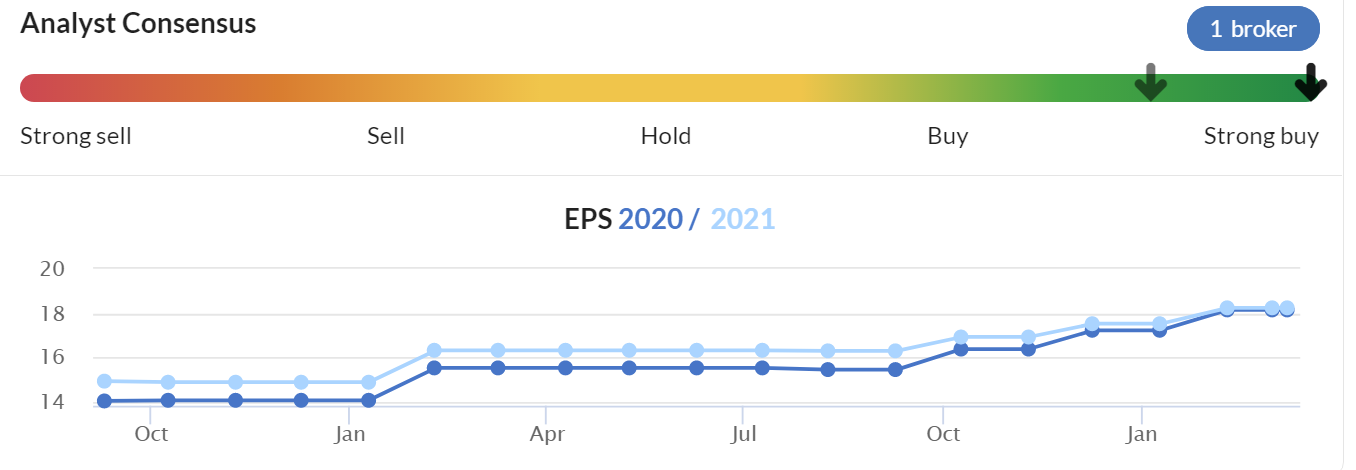
As I concluded last time in Jan 2021, this share is very straightforward, in that it looks priced about right if you think earnings forecasts are accurate. However, the broker consensus graph below shows that the company tends to out-perform. Therefore, this share might end up looking cheap, if a similar trend pans out in the future.
More M&A looks likely, although I’ve heard from several sources that private equity is bidding up prices of potential targets to high levels which can’t be matched by acquisitive groups looking for bargains. So perhaps a more creative approach is needed to entice target companies to sell up for the right price? Or maybe more distressed turnaround targets could be found, since a very good job seems to have been done by SAG with Frontier. There could be rich pickings here maybe, given the economic turmoil we’ve had in the last year.
All in all, I continue to think this share looks interesting.
.
Dfs Furniture (LON:DFS)
245p (up 6.5% at 15:18) - mkt cap £633m
DFS Furniture plc (the "Group"), the market leading retailer of living room and upholstered furniture in the United Kingdom, today announces its interim results for the 26 weeks ended 27 December 2020 (prior year comparative period is the 26 weeks ended 29 December 2019).
A couple of members have mentioned this in the comments below, which jogged my memory to take a look. As mentioned numerous times before, I consider this share uninvestable because of its terrible balance sheet. So rather than raking over the coals on that yet again, I just want to have a quick look at how it’s trading, mainly for possible read-across to smaller rival, the much more solidly financed Scs (LON:SCS) (I hold). SCS shares have risen 10% today, which is very unusual for a share which seems permanently tethered to 200p! It’s risen to 230p today, which is rather exciting, although personally it’s a long-term holding for me, as I think SCS is probably worth 300-400p on fundamentals.
Back to DFS. The H1 figures (July-Dec 2020) look fantastic! Revenues up 17.3% vs LY, and underlying PBT up 361% to £76.5m. There must be a fair bit of catching up from sales lost in Feb-Jun 2020, but even so, these are still very impressive numbers.
Digital is 25.7% of revenues, which to me seems surprisingly high for furniture.
Order book is strong. Note that furniture retailers have weathered lockdowns well, because when they can open, customers place orders, which then give a backlog which tides them over during subsequent lockdowns. Plus more people are buying furniture online too, which does surprise me a lot. But I suppose if you trust the brand, then you might be prepared to buy online, on the basis that the actual product should be similar to the website pictures. That must be what’s happening.
Outlook - also sounds upbeat, despite the latest lockdown -
The investments we've made in our digital channels have generated exceptional revenue growth. Consequently our order bank remains well above normal levels and, subject to showrooms reopening by 12 April 2020, our central planning scenario is for an expected full year profit before tax outcome of approximately £105m, with further benefits to be realised in next year's financial results.
Special mention must be made for the excellent guidance which DFS gives us. It even provides a table (below) giving 3 possible outcomes for the remainder of FY 06/2021, and how that would affect profit & net debt. How brilliant is this! All companies should be doing this, as it helps manage investor expectations, and ultimately makes the share more attractive for us to buy/hold, because it reduces uncertainty & helps us assess risk & performance. Bravo to DFS!

I really hope other companies take up this excellent format for reporting guidance. After all, it’s ridiculous to just home in one one number for profit forecasts. It should be a range of possible outcomes, because the future is inherently uncertain. All companies have this information internally, so there's no reason at all why it can't be shared with investors.
Balance sheet - I wasn’t going to comment on this, but whilst writing the above have been pondering whether I should drop my aversion to DFS’s balance sheet, given that it’s trading so strongly, then the balance sheet will be repairing itself somewhat. Plus when profits & cashflow are pouring in, there shouldn’t be much risk of the company being forced into doing another placing.
No scrap that idea, the balance sheet is still horrendous! An example - current assets are £100.7m, current liabilities are £376.1m! How is it possible to run a business with so little working capital? There's no slack in there, in case of emergencies. Hence why DFS had to an emergency placing in 2020, but SCS (I hold) didn't. So it does make a difference.
NAV is £246.4m, take off £532.6m intangible assets, at NTAV is negative £(286.2)m.
That’s a really precarious situation, so it’s still uninvestable for me.
My opinion - great performance, but the awful balance sheet wouldn’t allow me to sleep at night. Read-across to SCS (I hold) is positive, although DFS points out that accordingly to Barclaycard data, it has gained some market share, on top of consumers wanting to spend on furniture, in the well-known trend to revamp our homes.
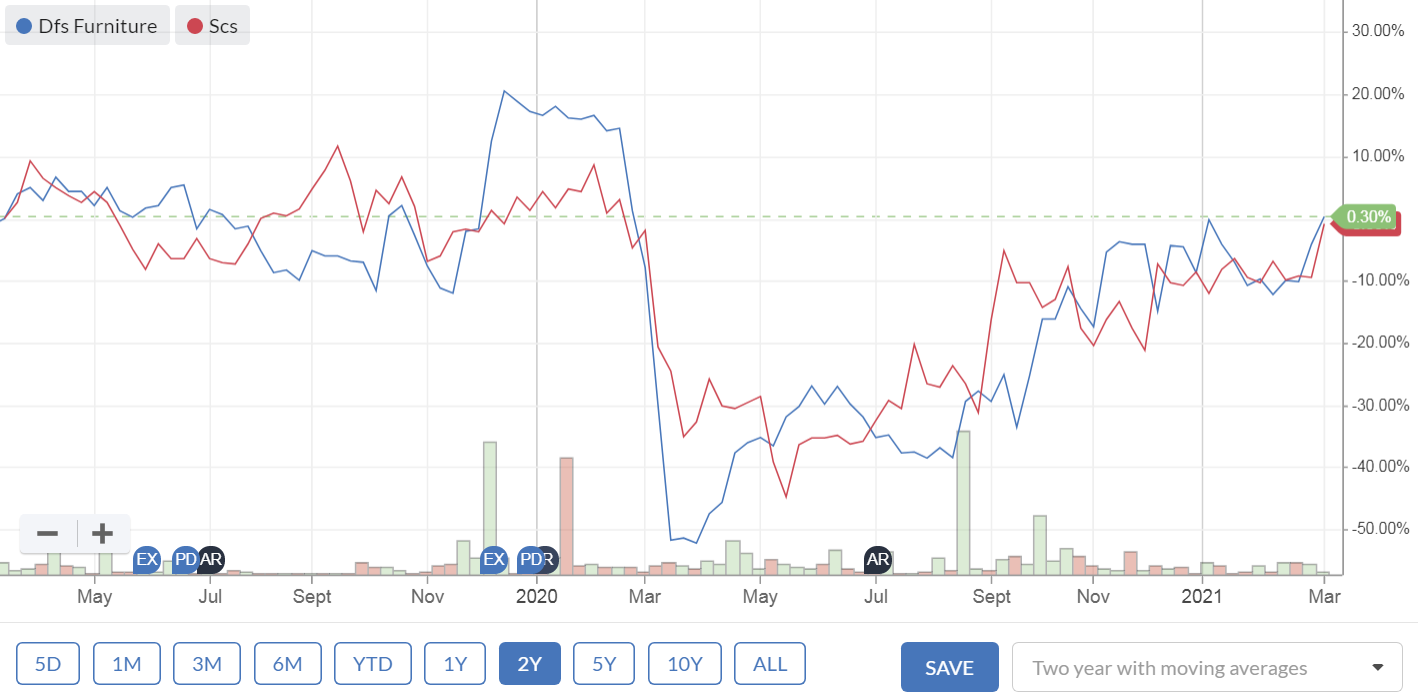
How have DFS and SCS shares performed? Over a 1 year period, DFS seems to have greatly out-performed. However, the devil is in the detail, and this time last year saw DFS take a much deeper dive in price when covid struck, than better-funded SCS. I think the 2-year chart is more meaningful, as it strips out this distortion. As you can see below, they've performed exactly the same (ignoring divis)! However, DFS nearly went bust a year ago, whereas SCS sailed through with pots of cash in the bank. The same return, for taking huge risk with DFS, and little to no risk with SCS. Therefore, SCS is the clear winner, when you factor in risk as well as reward.
.
 .
Jack’s section
Marshall Motor Holdings (LON:MMH)
Share price: 154p (+6%)
Shares in issue: 78,232,237
Market cap: £120.5m
Marshall Motor Holdings (LON:MMH) is the 7th largest motor dealer group in the UK. The group operates 113 franchise dealerships representing 22 different brand partners and has put together an encouraging track record of top line growth over the years.

But, with their razor thin margins, general industry headwinds, and a world increasingly focused on reducing pollution, car dealers have at times suffered from poor share price momentum. And that’s before you begin to talk about the impact of lockdowns.
A one-year chart shows share prices have now recovered fairly strongly amid market expectations of reopening economies (the FTSE All Share is orange, MMH is blue).

So perhaps the bulk of the rerating has played out here.
That said, MMH is still cheap across a range of metrics including a forecast PE of 8x and a price to sales ratio of just 0.06x. Together these metrics are a reminder of just how low operating margins can get in this space. The 2020 profit margin was forecast to be just 0.6% and today we find out it is 0.65%.
But the macro picture is improving and MMH has proven itself as a quality operator over the years. So there might be further to run if Marshall can hit the ground running and take market share in a post-lockdown environment.
Highlights:
- Revenue: reported -5.3% to £2,154.4m; underlying -13.5% to £1,866.4m
- Profit before tax: reported +3.7% to £20.4m; underlying -5.4% to £20.9m
- Earnings per share: reported -10.6% to 17.8p; underlying -7.9% to 21.1p
- Dividend cancelled but, with last year’s interim payment of 2.85p typically about one third of the final dividend, we might expect future payments of around 8.55p or a yield of 5.9%
- Reported net debt down from £138.6m to £70.5m, helped by government support measures, working capital control, and other cash preservation measures.
These financial results strike me as fairly resilient and reinforce my view of Marshall as a quality operator in a brutal, competitive, low margin sector.
It’s been a tough backdrop for operators in this space and that has unsurprisingly continued over the past year.
Total new vehicle unit sales at MMH fell 9.2% with like-for-like total new vehicle unit sales down 19.4% - but that makes for double-digit outperformance against a UK new vehicle registration decline of some 29.4%.
Total used vehicle unit sales dropped 5.3% with like-for-like unit sales down 14.6%, compared with used vehicle transactions down 14.9%. So not too bad given car room closures. Aftersales total revenue was down 5.2% and like-for-like revenue declined by 13.5%.
Back in April or May of last year, I would have been tentatively penciling in much steeper lockdown-related falls in the full year figures.
CEO Daksh Gupta comments:
Through a combination of support received from both the Government and our business partners, a number of one-off sector tailwinds and our continued and significant outperformance of the wider market, we are pleased to report an underlying profit before tax for the Year of £20.9m. Our financial position also remains strong, with adjusted net cash at 31 December 2020 of £28.8m.
Our resilient business model, ability to adapt to changing consumer behaviours, such as those enforced by showroom closures, together with our exceptionally strong relationships with our brand partners, gives us confidence in the Group’s future prospects and success.
Conclusion
I’ve talked with the CEO here before and Gupta comes across as knowledgeable, competent, and enthusiastic. He’s been heading MMH for a long time now - in fact I believe he is the longest serving CEO in the sector.
The group has a clear identity and strategy at the premium end of the market, it associates with aspirational brands, and it has grown from a small player in 2008 to become one of the premier automotive group’s in the UK and one of the fastest growing in Europe.
And it looks like the group continues to outperform the rest of the sector.
Marshall works hard to differentiate itself in a difficult sector: it is now in its eleventh consecutive year of having the Great Place to Work status and sixth consecutive year of being ranked as one of the UK’s best workplaces. It is big on social media and has spent years building up a proprietary tech dashboard to give it deeper insights into its show rooms and customers. And it continues to spend on TV advertising.
There is much more detail and colour included in the full year results so do take a look. My view is that Marshall is one of the better operators in this space so if you are interested in car dealers, it should certainly be on the list.
It’s a shame share prices have already recovered so convincingly. Mind you, at 154p, it is around its IPO price in 2015 despite revenue having doubled over that period. Profits have made far less progress over that time frame, which does bring us back to the fact that car dealers are low margin and prone to shocks.
A low sector multiple is probably warranted but MMH is one of the better operators and has a good opportunity to win market share going forwards. On that basis, it is worth a look as a potential longer term sector winner.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Isn't this just classical operational gearing abtan? I appreciate I'm looking at profit rather than cash-flow (you'd hope they are somehow related).
They did £16.4m more revenue in 2020 at a broadly consistent 40% GM so that's £6.5m additional Gross Profit.
At the same time they brought overheads down by nearly £1m (4%) .
So that is pretty much in the zone of the £7.5m cashflow improvement you mention.
I'm not sure there is anything more complicated than that?
Science (LON:SAG)
Hi Gromley
Thanks for taking the time respond.
I did think about the impact of Frontier Smart Technologies solution and looked into it, but I still couldn't grasp the trajectory of the improvement.
It's effectively moved from:
That's quite a turnaround and to be honest I'm sort of in disbelief that it's real.
It's why I started looking at the tax losses carried forward with the acquisition (see my earlier post).
Were $1.6m tax losses carried forward, or $21.4m?
With the latter they claim it's a trading loss, but then they start equating it to deferred tax assets, which implies to me that it is a tax loss.
I'm no tax expert, but if anyone can explain it would be most appreciated, although I imagine I'm just making a mountain out of a mole hill.
Cheers again
A
I should have said in my initial comment that I know next to nothing about Science (LON:SAG) .
But it still strikes me that even if the step change occurs in the £FST acquisition; it still looks to be the case that the big change is in Gross Profit (Revenue less Cost of Goods Sold) so I *think* the tax losses are a red herring.
Sorry - I probably went off on a tangent.
Science (LON:SAG) (no position)
I can't get my head around the remarkable change in cash generation.
Underlying cash generation (by my own method of stripping out working capital movements, acquisitions, dividends, etc...) in 2018 and 2019 were c£4m and c£2.5m respectively.
In 2020 it was c£10m
Why such a marked increase?
I had 2 thoughts on this:
I must be missing something. Can the company really have increased it's cash generation by £7.5m (£2.5m ---> £10m) in just 1 year?
Thoughts would be appreciated.
Cheers
A
Thanks for the Science Update Paul. Bought a few of these at 85p a few years ago when they were Sagentia - when my daughter was doing a Uni placement there. Glad I didn't sell when she finished her year there!
Paul - I watched Mello Monday last night and boy were you the star of the show!!!
Very kind fred, but I have huge respect for Leon & Alan, who are full of insights, so it was a great pleasure to be on the panel with them!
Actually, I should add that I generally hate being on any kind of show. It's incredibly stressful, and takes so much time to prepare. Doing that on top of the usual day's time-pressured work is a PITA, and you're not paid for it either. When people say, it will help you raise your profile, I want to tell them where to stick it, and sometimes do.
Mello (David) and PIWorld (Tamzin) are different though. They're mates, and are doing great stuff for our community, which I'm happy to support. So I cannot say no to either. Hence if I'm on Mello, it's because everyone else has said no, and there's an empty seat that needs filling at a late stage, not because I'm trying to push myself forward. Quite the opposite, I've usually tried very hard to avoid it. It's quite enough having to field all the onslaught of things from elsewhere, let alone do another thing in the evening.
But having made the decision to do it, I try to give it my best shot.
Anyone else who is scared to public speaking - my advice is, just get on with it! Do it, but prepare something interesting and well-researched to say, then you can run on autopilot if the anxiety does overcome you on the day. The worst thing to do, is get up and do some public speaking without preparation, as it will look poor quality, or just boring & repetitive.
I like talking about shares, but there's always hours of preparation behind it, otherwise why get up and speak?
Hi Paul, would you be able to take a look at eEnergy who came out with excellent 6 months figures today? Thanks.
Have a look at the PI World interview with Charles Morris. He recommends opening an account with Revolut.
piworld interview – Charlie Morris: All about bitcoin – piworld.co.uk
Sorry, I replied to the wrong poster.
Likewise, I would welcome Paul's thoughts on Eenergy (LON:EAAS)
It looks like a really positive update to me. Building a subscription based income model with the ability to access funding when required.
Hi Chris!
I've run out of time & energy for today, sorry about that.
I don't know Eenergy (LON:EAAS) but have just had a very quick look at its interims to 31 Dec 2020. The highlights look interesting - very strong revenue growth, both organic & acquisitions. Achieved just above breakeven, improved from a £1m loss H1 LY.
Floated on AIM in Jan 2020. I've not come across it before. Interesting idea, to provide LED lighting upgrades to schools, at no up-front cost to the customer. I can see why that would appeal to schools with tight budgets.
Guidance - breakeven result for FY 6/2021 - not madly impressive for a market cap that's now about £45m after today's 8% rise.
Balance sheet looks weak, once intangibles are written off.
I see it has a buy & build M&A strategy, so the key issue for me is what the track record of management is? Do they have previous M&A experience, and how did they perform in previous ventures?
It looks a little too speculative for me, but that's on the quickest of reviews.
Good luck with it!
Regards, Paul.
Thanks Paul.
Off topic
Hi Paul
I am concerned not only about Vix volatility but also the reported huge transfer of capital to cryptocurrencies. I wonder if you and/ or Roland could discuss this and how investors like us can safely invest in cryptos without having to spend 50K. I could probably do that but I would not risk that as a new stake in a new investment. I have not used any of this year's ISA allowance.
There may be other places on this site where we could get this information for ourselves if so please could you direct me to them.
Thanks
Hi 23jez,
... how investors like us can safely invest in cryptos...
That's a contradiction in terms I'm afraid;
I don't give advice, but the Bank of England and the FCA do, and they've warned people to only gamble with money you can afford to lose (e.g. never, ever borrow money to gamble on these things).
https://www.bankofengland.co.u...
https://www.theguardian.com/bu...
Also, doing some reading up on previous financial manias, will demonstrate very clearly to you that this is just the latest in many centuries of financial manias, which always end the same way - boom and bust.
Please be careful whatever you decide.
Regards, Paul.
Thank you for that. I always try to be careful.
Personally I like to invest in companies which produce something tangible. I have made most money from oil, particularly during the Arab-Israeli wars, and computer chips. I sold Buford Capital when I ceased to fully understand their Business Model.
I have read all of Daniel Yergin's and most of Nassim N Taleb's and Micheal Lewis's books and many more.
I bought some Augmentum Fintech shares a few years ago on the basis they were supported by Hargreaves Lansdown who are by no means stupid. Currently up 7%. on my investment this is my only exposure.
My query related to to recent reports that some large companies are accepting payment in bitcoin. Given the current disillusionment with conventional banks what are the chances of it becoming an alternative currency.
I am sorry I did not make myself clear but open questions tend to elicit the most interesting responses. For the avoidance of doubt I was asking for information not advice.
23Jez
The trading update from DFS today (which was good!) augurs very well for SCS.
Thanks for the reminder, I'll take a quick look at DFS next.
I am happy for the thumbs down option to have been removed but in recent days could frequently have made use of an option to use the "thumbs up" option multiple times due to the quality writing on multiple topics in the day's SVCR.
How lovely, thanks shanklin!
We do our best, trying to produce some thought-provoking & different commentary & opinions on topical issues & company updates.
It's just opinions at the end of the day, so we'll be right about some things, and wrong about others. What I love about markets, is the constant uncertainty, and huge complexity, such that every day we're wondering how to make sense of such a vast amount of data and views. I love it, it's a never-ending puzzle! If we can make a bit of money along the way, then that's quite helpful too.
Best wishes, Paul.
Hi, not related to the companies you are covering today, but I see that BOO are saying the are going to build their own factory in Leicester. I am a bit confused about the US situation.
As I understand it, manufacturing in Leicester is more expensive but much more responsive than in the far east. However Leicester isn't near the US, so it looses those advantages, surely boo aren't manufacturing in Leicester for the US market ? Surely there's Leicesters in the US or at least in Mexico, that would give the local advantages ?
How then can the US be looking into claims about manufacture elsewhere in the world for products for sale elsewhere ?
This idea of them having their own factories seems like a bit of a departure for me , I know they have a clothes/fashion background, but do they really want to start running their own factories ? are the margins so good, that they want to do the manufacturing too ? It seems unlikely, is this perhaps a pr exercise to show it can be done ??
cheers K
Hi kenobi, I think the Boohoo (LON:BOO) factory in Leicester serves multiple purposes and the actual output of products that the workers will make is almost the least important. The main one is to be a demonstration and training centre for improving supply-chain skills, open to Boohoo (LON:BOO) supplier companies to send their apprentices and existing workforce. Then you have the value of a tangible commitment to Leicester, tidying up what looks like a fairly derelict site and showing that Boohoo (LON:BOO) is a responsible corporate citizen. If this can help to preserve Boohoo's competitive advantage while maintaining acceptable labour standards, it will have been a good investment IMHO.
Completely agree that this does not affect the US imports situation. That will be addressed by undertaking proper supply chain audits, which Boohoo (LON:BOO) have now put in place. Once you can show that all supplies are traceable and all suppliers are audited, then you have the evidence to refute any allegations of exploitation or human rights abuses.
(I hold, currently around breakeven)
re, Boohoo (LON:BOO) (I hold)
From a PR perspective I can see the benefits of them becoming a local employer of medium-skilled workers - persecution in the press would potentially then be putting UK jobs at risk.
A factory employing 95 employees with what doesn't look like a large footprint doesn't sound as though it will be big enough to meet a high proportion of their production needs, though, but I don't know how automated modern clothing factories are, so I could be wrong on that. Maybe there wouldn't be a big cost penalty versus the existing elements of the supply chain in Leicester.
Presumably any investment in plant & machinery would qualify for the 'super deduction'.
Here are my SCVR heat maps for today (prices as at ~10:05am).
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
PS: See my main heat map thread for more (non-SCVR specific) heat maps, and keys to the heat maps contents
Hi Paul, agree with you that 100 Baggers by Christopher Mayer is an interesting read
Hi AliG,
Yes I agree, I'm enjoying 100 Baggers very much, and have nearly finished it now. Literally every chapter is like a refresher course to me, to remind me of the things that matter the most, plus learning plenty of new things too. It's a very light read too, conversational in writing style, and explains concepts very clearly, and with short stories. So I think this book is ideal for investors of all levels of knowledge & experience. Very highly recommended!
I've just got to the bit where Benjamin Graham and John Maynard Keynes almost blew up their portfolios in the early 1930s, after using too much leverage! That certainly made me feel a bit less muppet-like about my own catastrophes in 2008-9. Both of them learned the lessons from their mistakes after the 1929 crash, de-geared, stopped trying to trade, and instead focused on identifying under-priced investments, and stuck with them for the long term. That's very much what I'm also trying to do these days, so hopefully am now on the right track. Like a lot of people, I've spent years exhausting all the other options, before settling on a sensible long-term investment strategy!
Regards, Paul.
I just finished this book last week and agree that is was very informative and enjoyable. One of the key takeaways for me was the considerable difference in attitudes towards dividends in the US and the UK.
Mayer repeatedly highlights how the key characteristic of these '100 baggers' is the ability to generate high returns on capital and then re-invest those returns at equally high rates. In the UK there is a fascination with paying out a huge proportion of earnings as dividends which means we often miss out on this compounding effect.
An example in the UK is Fonix Mobile (LON:FNX) (I hold) and believe this to be one of the better recent IPO's we have seen. In the admissions document however they state:
‘It is currently anticipated that a dividend will be declared in the first year after Admission at a pay-out ratio of 75 per cent. of adjusted earnings per share.’
This is a company with a an ROCE of over 200%! Why on earth would we as investors want dividend income from them, certainly at that level. As Mayers states the central role of management is good capital allocation (William Thorndike's The Outliers is another great book on this) Paying out most of your earnings in dividends when you are able to achieve such significant returns doesn't seem very sensible.
Much is said about the out-performance of the US relative to the UK over the past 20 years and it is generally and to an extent correctly attributed to the lack of technology companies based over here and the heavy weighting of banks/mining stocks. I think we also have to consider the fact that the general aversion to retaining and re-investing earnings has been a major drag on growth.
Maybe we should start asking more of management here in the UK when it comes to capital allocation and understand that whilst it is nice to have a steady stream of dividend income, maybe it is coming at a significant detriment to our long term wealth.
Hi Luke
I also read 100 Baggers recently and enjoyed it.
One thing to add on dividends if I may - I completely agree with you with 1 caveat...
I like dividend yields of <1%, simply to give me that little bit of re-assurance that cash flows are real. Beyond that, if the company is growing well, I'm happy for them to keep the cash and use it for growth or to buy back their own shares.
Cheers
A
I'm not so bothered about dividends, $AAPL pay about 0.7%, MSFT is about 1%. $AMZN does not paid one at all. Can be misleading because of growth.
If you had bought BP (LON:BP.) and $MSFT 5 years ago, you will probably find that now the dividend on $MSFT is larger, if you disregard the tax issues on US shares, BP (LON:BP.) shares are down around 20% and $MCSF are up around 5x.
Hi Herbie
I'm not bothered about dividends either to be honest.
In fact if I do look at the yield it's more as a possible indication that a share is undervalued and the share price will rise to correct itself and bring that yield down.
My point on wanting a small dividend to confirm cash is being generated was, of course, more directed to smaller companies, not the Apples and Microsofts of this world.
Though of course, it's not always a good indicator - I believe Patisserie Valerie paid dividends.
Cheers
Yes I understand your point. But in young growth companies, I would not expect a dividend. Boohoo (LON:BOO) does not pay one. Even ASOS (LON:ASC) does not pay one. It maybe safer but does not make sense to me in some situations, I would rather they paid off debt first if applicable, or invest the money in growing the business.
If Fonix Mobile (LON:FNX) can grow to $250bn, which I believe was roughly the size of Microsoft when they started paying dividends in the early 2000's, I will let them off. My issue specifically relates to small UK companies with returns of capital above 20% committing to paying out 50%+ of their earnings. (I do very much agree with abtan that a small dividend is helpful in indicating real income)
I know little about Fonix Mobile (LON:FNX) , but more generally I think this is a very common misconception about RoCE.
Do you really believe that they could 'Employ' a further £10m (say) of Capital and as a direct result achieve an extra 'Return' of £20m pa ?
If you do believe this you also ask yourself why the original owners offered you a chance to share in their magic money tree by listing the shares less than 6 months ago.
I should stress that I am NOT inferring that there is anything wrong with Fonix Mobile (LON:FNX) - it may well prove to be great investment, but you need much better reasons than apparent and historic 200% RoCE.
EDIT
To look at this from the other side of the fence; the fact that they propose to pay out 75% of profits as dividend tells you quite clearly that they do not believe that they can make meaningful returns from deploying extra capital.
This does not mean, however, that they cannot grow - there are other paths to growth than shovelling more bank notes in to the furnace.
Great points Gromley, and others. A business like Fonix Mobile (LON:FNX) or say Best Of The Best (LON:BOTB) (I hold) doesn't actually need to deploy any capital at all, to grow. So they can pay out earnings as divis, and grow, because they're using almost nothing in fixed assets.
Is it more about their expertise in winning new contracts (FNX) or spending their digital marketing budget wisely (BOTB)? That seems more important these days, than conventional logic on what return can be generated from spending £x on building a factory.
I know ROCE is important, but for me it's not something I've found it fruitful to chase after, or screen for. It's obvious when you find a business that is growing because it has a great product that sells itself. Also look at companies that outsource the production, e.g. Fevertree Drinks (LON:FEVR) - that skews the ROCE figures greatly, because a lot of the CE is off balance sheet.
Interesting topic to bounce ideas around, I don't have the answers.
Regards, Paul.
Ali G
Thanks for the reminder. I had meant to purchase this a little while ago and forgot. I have just finished the Jesse Livermore 'How To Trade In Stocks' which i found a bit heavy , although it is talking about a period very removed from now the principles have not changed. It is just a shame that he and his family ended up the way they did.
Richard
Racal was the very first stock I bought in the mid 60’s. Unfortunately sold about ten years later to put down deposit on my first house. Should just have kept the Racal position and rented :)
Science (LON:SAG) Audited FY results (I hold - in a small way)
Mcap 130m SP 340p
Some figures from the results:
Revenue £73.7m (57.2m) +29%
Adj Op Profit £10.9m (6.7m) +62%
Adj eps 19.4 (11.6) +67%
Basic Profit before tax 6.4m (-1.6m)
Basic Profit after tax 7.0m (-1.8m)
Basic eps 16.9p (-4.5p)
Net cash £10.6m (-2.3m)
Dividend 6p (2019 – withheld – 2018 4.6p)
Formerly known as Sagentia? From the report - Science Group is an international, science-led services and product development organisation with a significant freehold property asset base. Following the Frontier acquisition in 2019 and the natural evolution of the services operations, the Group now comprises three divisions: R&D Consultancy; Regulatory & Compliance; and Frontier Smart Technologies ('Frontier').
Frontier provides digital radio chips and was acquired and was loss making in 2019 – the successful turnaround in 2020 is behind the big boost to profits. Also makes the forecasting more difficult.
There is also in essence a fourth division – the property services company which owns Great Burgh near Leatherhead renting it to the subsidiary companies and third parties and will soon own Harston Mill near Cambridge (postponed during the pandemic due to the tax arising on the event) where Frontier has been relocated.
I’ve not been a holder for long and my holding is small – I am not yet completely at home with the figures as the company has a slightly complicated setup – but not necessarily in a bad way.
Science Group is an acquisitive company, and operates in R&D consultancy as well as food, chemical and medical regulation, compliance and testing.
These are areas that I see as growth areas post brexit and indeed post pandemic – both in terms of market and in terms of the number of potential acquisitions in the market.
Although the bulk of the revenue increase is due to the inclusion of 12 months figures from Frontier, and the turnaround in profits is due to the turnaround at Frontier – the other divisions have also organically increased both sales and turnover. A very creditable performance in the circumstances – and shows the future potential in the science consultancy area.
What a difference a few months make. Back last summer things did not look so clear. There seemed considerable risk to the rapid turnaround at Frontier, particularly as its an entirely different technology entity from the rest of the group - and the ability of the rest of the group to growth both sales and profits during the pandemic also seemed much riskier. As a result I did not buy many shares – something that looks like a mistake now with my new improved hindsight!
I am naturally suspicious of companies that grow by acquisition – it needs management that can cope and to demonstrate organic growth in the acquired companies not just growth by bolting on sales and debt. It seems that the company is showing both organic growth and reduction in debt – all acquisitions to date have been made by using cash generated in the business. I particularly like the unusual structure which ties the long term debt against the properties and allows cash to be utilised for acquisition when appropriate. The management here seems to have what it takes?
Current results put the shares on a P/E of around 20x – not cheap? Investment depends upon forecast growth and with the turnaround at Frontier, various tax losses (hence tax credit larger than tax paid) and the pandemic – it’s not easy to see in the short term. Stocko currently pencils in a net profit for 2021 of 7m – but they’ve done that this year – so it looks as if the figures stemming from the brokers are basically missing in action?
In the consultancy businesses – which makes up 65% of revenue - sales were up by 3% in 2020 and operating profit by 12%. The prospects for this year are probably improving as we learn to live with the new normal/emerge into the post pandemic world. Anyway – I don’t see the medium or long term future of this group in organic growth – by its own admission the group is acquisitive.
With cash piling up (small government assistance paid back – but trade payables look a bit stretched) the group probably has around £20m of cash resources to make acquisitions – and growing month by month - before any share based payments.
They are also very open that they have a decision to make whether to sell on the now highly profitable Frontier, scale it up by acquisition or just continue to run it. Which could complicate the dynamics of the acquisitions and sales on the future value of the company.
How to value this company?
In my view 20x is a reasonable price, but not cheap these companies rarely are cheap, for a company operating in science consultancy with organic growth prospects of over 10% sales and profit growth annually.
I should also mention currency risk. Currently most of the group revenue is in USD and a considerable level of costs as well. Unhedged but held under review. 2021 results will have a considerable currency headwind to overcome.
But it does looks cheap if you can factor in the likely benefits of continuing acquisition to scale, and potentially the sale of non-core parts of the business over time. Clearly assigning a level of risk to this is key – but the management in the last year have shown an impressive ability to manage this?
I don’t like paying more than 20x for any business, but I am beginning to like this company and its management and would like to increase my holding here – so I shall be watching carefully to top up on any weakness – and need to convince myself that it is potentially a very valuable company in the long term?
I apologise for the rather waffly nature of this review – its complicated to get to grips with - but potentially very worth understanding fullt and in my view the future value of this company mainly rests on its ability to acquire and integrate at the right price – not so amenable to value calculations?
Cheers
Mark
Hi Mark,
Good analysis! I really think forecasts will need to be upgraded though, can see 20-22 EPS for FY'22, which would make 400-440p possible.
Return on equity has come in at around 17% this year, and Martyn Ratcliffe holds a healthy 27% ( shareholder interests should be aligned! ).
Spread is a bit of an issue, like you am considering adding.
Regards.
Thanks JohnDoe,
Science (LON:SAG) - I agree - the forecasts vere wrong, it's amazing that after a year of Covid more sensible forecasts are still missing in action, though I acknowledge that in this case there are a lot of moving parts.
RoE of 17% is in line with what I'd be looking for - The value and quality figures on the stock report should make more sense once the new results are updated as well?
Thank you for pointing out the 27% Chairman holding, useful to know, and the kind of thing I like to see.
As the price barely moved this morning I've bought a few more to back up my claims. Doubled my holding from - tiny toe in the water = to very small!
cheers
Mark
Hi Mark,
I have a very small holding also, picked some up at 230p last year.
Like you, one of my rules is not to buy any company where the forward PE is greater than 20. Also don't like to buy when spread is more than 3% either!
But certain exceptions can be made!
Regards.
Hi Mark & John Doe,
Science Group (SAG.L)
Noted your comments on Science Group, I have held since £1.20 days and picked up originally on good fundamentals via Digital Look and Stockopedia (great).
Must admit I was surprised when share price fell back after initial increase on trading update 11th January 2021. The shares tend to be thinly traded and there is quite a spread generally which might put some traders off.
I might be wrong but with 26m cash, properties circa 30m (debt 19M) and I don't think anybody is factoring the possible proceeds from a disposal of Frontier which if you look at its value historically (and potential) it would be worth a lot more I consider now with the turnaround than when purchased. Given possibility for acquisitions and relatively low price earnings projections then I consider a future price of £5 could be easily attained. Just my opinion DYOR.
Kind regards
Nigel
hi Paul - would you look at Gamesys (LON:GYS) today - Final results out and this company has turned profitable nicely approx 18 months ago if I recall, but now building some nice momentum. Becoming a strong mid cap perhaps.
Morning Phil,
Sorry, at £1.5bn, Gamesys (LON:GYS) is outside my small caps remit. I tend to stick to things up to a (flexible) market cap upper limit of about £400m, or sometimes more if it's a company we've covered here before, that has done well & risen above that level.
I'm not familiar with Gamesys at all, and have never covered it before. Curiosity got the better of me, so I've just had a quick gander at the highlights, and the numbers out today look very good, so it could be a nice one for readers to look at possibly.
Regards, Paul.
hi paul any comment on DFS results I know you love its balance sheet not
Morning Paul/Jack,
You are probably extremely busy this morning, but could you look at excellent results from Science (LON:SAG) please?
Earnings beat, excellent cash conversion and strong balance sheet, including freehold property.
Regards.
Hi JohnDoe,
You are probably extremely busy this morning, but could you look at excellent results from Science (LON:SAG) please?
Earnings beat, excellent cash conversion and strong balance sheet, including freehold property.
OK, you've made an interesting case there, so I'll take a look at it next. Leave it with me!
Regards, Paul.
Brand Architekts (LON:BAR) H1 results today, perhaps less striking is this current set of results which were CV19 impacted, and work of the old management, and more striking the new management team and their forward plans. (Note Roger McDowell is now Non Exec Chair). They have big cash pile of £19m. They're looking to grow to this to a £50m revenue business within 5 years, (currently £9m).
Quentin Higham, CEO & Tom Carter, CFO, are giving a webinar followed by Q&A at 2pm today, register here.
Hi Paul
Whilst I absolutely appreciate your longing for physical investor meetings and especially the post event social (cheers!) Zoom has enabled PIs to get a lot more of this first-hand on our screens. I also hope the companies and brokers have seen some benefit in engaging with us in this way too. It would certainly be a regressive step if company updates went back behind closed doors or were only available if you make a journey.
Yes, I agree Chris.
Rest assured, behind the scenes, I'm urging every company & advisor I speak to, to get them on InvestorMeetCompany, Mello Monday, and PI World, so they can engage with PIs. When they do, the result is always positive, with many companies saying they're impressed with the intelligent questions & understanding of the business from PIs.
I feel that the poor quality bulletin boards, like advfn & LSE, do immense damage. Companies read them, and understandably come away with the impression that PIs are abusive muppets! Whereas (as always with the internet) that noisy minority are not at all representative of most PIs.
The other thing I always say to every company I speak with (several per week), is that they need to get broker research out to us, via Research Tree, or direct.
So if you all do the same, when you talk to companies as well, then it would be great. Between us we are making a difference, and I don't see things going back behind closed doors again in future, as many companies have seen the merits of engaging with PIs online, and enjoy it too.
Regards, Paul.
Greensill collapsed yesterday. This has raised concerns about the stability of GFG Alliance. On the face of it far too big to concern us here. However, small renewable energy company SIMEC Atlantis Energy (LON:SAE) are part of Simec who are part of GFG Alliance. Not possible to know how that all shakes down but some have suggested that GFG may have to sell off assets in haste at a discount. (No position for me these days).
Actually a positive article re Boohoo on the BBC news. Makes a change.
https://www.bbc.co.uk/news/uk-...
My morning smallcap tweet:
WANdisco (LON:WAND) Kanabo (LON:KNB) Zoetic International (LON:ZOE) Braemar Shipping Services (LON:BMS) Invinity Energy Systems (LON:IES) Kromek (LON:KMK) Open Orphan (LON:ORPH) Shield Therapeutics (LON:STX) Marshall Motor Holdings (LON:MMH)
WANdisco (WAND) $45m placing at 446p, a 7% premium, to be able to make acquisitions. Guides FY(Dec) rev at least $10.5m. "With the Q4 2020 launch of LiveData Migrator on AWS and the LiveData Platform on Azure, 2021 marks the beginning of the growth phase for the company." [SP=416 Cap=219m]
Kanabo (KNB) to supply medicinal cannabis to PharmaCann Polska. Parties will establish a dedicated production line. No £££. [SP=18.5 Cap=67m]
Zoetic (ZOE) up to £35m financing from LDA Capital via a put option. Shares will be issued at 90% of the average price over a flexible pricing period, with a maximum of 30 days. Co pays 2% fee. A cynic might think 'death spiral'. [SP=102 Cap=199m]. I'm short.
Braemar Shipping Services (BMS) guides FY(Feb) U/L opm profit at least £8.7m ($9.6m), above finnCap f/c (not given). Will rationalise business towards the development of a new strategy centred on Shipbroking. Will look to strengthen its balance sheet. FY22 "expected to show revenue growth in original currency terms, if the exchange rate remains at current levels, it will mean a reduction in Sterling terms. A hedging program is in place, which provides a significant protection of the Sterling value worth £1.7m at current levels but is not expected to close the gap in full." [SP=254 Cap=81m]
Invinity Energy Systems (IES) trading: closed deals up 5%, pipeline up 18%. [SP=137 Cap=119m]
Kromek (KMK) wins $960k Nuclear Detection order, $150k this FY. [SP=15.81 Cap=68m]
Open Orphan (ORPH) another contract win, for a study. No £££. Cathal Friel will RNS a study of his own navel if it helps the SP. [SP=29 Cap=194m]
Shield Therapeutics (STX) Australia approves Feraccru to treat iron deficiency. Already approved in the UK, EU, Switzerland and USA. [SP=39 Cap=46m]
Marshall Motor Holdings (MMH) FY(Dec) U/L pretax £20.9m down 5% but above guided min of £19m. No div. Jan-Feb trading: "encouraged by demand for remote and 'click and collect' vehicle sales and the Group continued to outperform the wider new car market." [SP=144 Cap=113m]
Thanks Mr.C - As always good to run through your quick list. So yet another FundRaise at Wandisco (LON:WAND) and surprise surprise the price goes up today - what is going on...(and yes for my sins I do hold!)
Open Orphan (LON:ORPH)
This did make me chuckle "Cathal Friel will RNS a study of his own navel if it helps the SP" thank you MrC for your daily dose of sanity.
Also fully agree on Zoetic International (LON:ZOE) hard to see how this ends profitably for anyone buying around the current SP
Thanks Paul, your reports are invaluable, especially to a novice like me. I look forward to learning from you daily.
Will you be reporting on HEAD today, after they published their final results?
Hi LAdyInvestor,
Thanks, I'm glad you find my reports useful!
Yes, I always cover Headlam (LON:HEAD) (I hold), it's a very nice company, and still good value, in my view. Am just watching the results video presentation as we speak.
Regards, Paul.
I agree ... your reports are a valuable learning tool. I also wanted to ask how you dog is doing; I hope he is well?
Hi 55555,
Yes my dog's fine now thanks! In the end, he fully recovered from the op to remove the cancer, so is now enjoying a relaxing retirement, spending about 90% of his life resting! LOL. Not dissimilar to me at the weekends!!
Best wishes, Paul.
Thanks for the speedy reply Paul!
Regards