Small Cap Value Report (Tues 13 July 2021) - SNWS, CIR, SOLI, HOTC

Good morning, it's Paul & Jack here with the SCVR for Tuesday.
Timing - TBC
Disclaimer -
A friendly reminder that we don’t recommend any stocks. We aim to cover notable trading updates & results of the day and offer our opinions on them as possible candidates for further research if they pique your interest. We tend to stick to companies that have news out on the day, and market caps up to about £700m. We avoid the smallest, blue sky type companies, and a few specialist sectors (e.g. resources, pharma/biotech).
A central assumption is that readers then DYOR (do your own research) and discuss in the comments below. The comments, incidentally, sometimes add just as much value as the articles. We welcome all rational views, whether bull or bear!
It's helpful if you include the company name or ticker within reader comments, otherwise some readers may not be aware of what company you are commenting on.
Agenda -
Paul's Section:
Smiths News (LON:SNWS) (I hold) - an unexpectedly positive trading update, from this distributor of newspapers & magazines. Obviously an activity in structural decline, but it's now a cash cow, with lucrative dividends in the pipeline. PER of just above 4 looks too low, now that legacy issues have been fixed. One for value investors.
Hotel Chocolat (LON:HOTC) - an impressive update, with performance ahead of expectations for FY 06/2021. Lots more detail about growth plans. A little light on numbers, but there's no doubt the company is trading well, and making impressive gains online & internationally. Still expensive, but I'm warming to this share.
Jack's Section:
Circassia (LON:CIR) - Ex-pharma co (now medical devices) in turnaround mode but with costs reduced and EBITDA to be ahead of expectations. Still loss-making and market cap is well ahead of continuing revenue, but the group has a dominant asthma testing product in the form of NIOX that it can now focus fully on.
Solid State (LON:SOLI) - shares down on today's update. You might argue that the price got a little ahead of itself in recent weeks but this strikes me as a well run company with potential for steady long term growth.
Paul’s Section
Smiths News (LON:SNWS)
(I hold)
42.5p (last night’s close) - mkt cap £105m
Background - this is UK’s largest distributor of newspapers and magazines. It’s a structurally declining business (although rising cover prices offset some of the decline in volume), but still a substantial size (over £1bn revenues), bolstered by long-term contracts (with major publishers), variable costs, and decent cash generation.
A botched acquisition policy under previous management has now been sorted out (successful disposal of Tuffnells), as has the pension scheme (now in surplus, with a receipt expected fairly soon). Problem bank debt has also been reduced, and is set to hit c.1x EBITDA within 6 months, at which point the company has indicated it will pay out future cashflows in normal (and possibly special) dividends.
Hence I think there’s an opportunity for value investors here, because the (credible) forward PER of just 4.4 seems too low, and it seems to me that market hasn’t yet fully grasped that the business has been comprehensively sorted out.
Today’s update - the current financial year ends 08/2021.
It’s positive news -
Smiths News is pleased to report a strong operational and financial performance for the 43-week period to 26 June 2021, with trading expected to be ahead of market expectations for the 52 week period ending 28 August 2021.
- Sales of newspapers & magazines have “continued to stabilise”
- Positive Y-on-Y sales against soft comparatives for lockdown 1
- One-off boost from European Football Championship of £1m EBITDA (re sales of stickers, albums, etc)
- Cash generation & other key financial metrics are in line with the Board’s expectations
Given the continued strong performance of the business, together with the one-off benefit to sticker and album sales this year, the Board expects full year adjusted EBITDA to be ahead of market expectations.
"Our performance since the half-year has been pleasing, with robust operational control securing the benefits of the improving sales and stability in our core markets. We remain focused on delivering for all stakeholders and are confident that the business is well placed to build upon recent progress as the remaining restrictions on social movement are lifted."
My opinion - I wasn’t expecting this, so it’s encouraging news.
Current forecast is 9.2p EPS, so we’re above that. Maybe 9.4p to 10.0p could be in the offing for FY 08/2021? Compare that with a share price of only 42.5p!
There are restrictions on dividend payments until net debt has reduced further, which should happen when the pension scheme surplus, and Tuffnells deferred consideration are received. From next year then, I reckon the divis could shoot up, with the possibility of a double-digit dividend yield, well covered.
As mentioned before, it’s not something I want to own forever, but by my calculations the current share price looks far too low. I’m planning on holding for at least a year, or until the share re-rates to a more appropriate valuation (I’d be happy to start top-slicing if it gets over 60p, with a target of about 80p - a PER of 8, hardly demanding).
There was no dilution to shareholders during the pandemic.
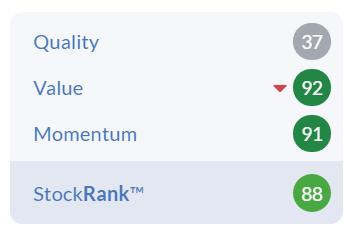
As you can see, the value metrics are at levels we rarely see for a solvent, cash generative business, which could also attract a bidder perhaps? -

.

.
.
Hotel Chocolat (LON:HOTC)
385p (up 3%, at 08:51) - mkt cap £485m
Hotel Chocolat Group plc, a premium British chocolatier and digital-led retailer, today announces a post-close trading update for the 52 weeks ended 27 June 2021 ("FY21"), an update on recent trading, the Group's financial position and outlook.
Lots of upbeat-sounding comments in this update.
- Revenue for FY 06/2021 is £165m - which is nearly 2% above the £162m forecast shown on the StockReport
- Revenue up 21% vs last year - that’s impressive, because FY 06/2021 would have been impacted a fair bit from lockdown closures, although FY 06/2020 would also have caught about 3 months of the most severe lockdown 1, so it’s difficult to compare.
- Revenue is up 24% on the pre-pandemic year of FY 06/2019, probably a better comparator.
I remember saying here in previous updates that HOTC was only delivering a modest growth rate, considering how expensive the PER was. However, it now looks as if more convincing growth is coming through, which is impressive given pandemic conditions - see graph 1 below (and bear in mind actual revenues are £3m higher than the forecast of £162m, the lighter colour blobs are forecasts, more solid blobs actuals) -
.

.
Although the above figures do look small, for a company valued at nearly £500m - we’re being asked to pay up-front for several years' growth, well into the future.
Re-opening trading - impressive figures here, although it doesn’t say what the growth in store numbers has been over these periods, so it may not be like-for-like -
Since the previous trading update in May, Group trading has remained strong. With all channels open, Group sales for the 10 weeks from 19 April 2021 to 27 June 2021 grew 34 per cent compared to the same period in 2019, and 63 per cent compared to the same period in 2020 when all physical locations were closed.
Digital & subscription - the most interesting part of the business. The 3m database of UK customers isn’t the same as active customers though -
Having grown the UK customer database by 66 per cent to 3 million in the 18 months since December 2019, digital and subscription sales are now a substantially larger proportion of the Group's total revenue and have remained so after full store channel reopening. Increases in visits, conversion, and average order value have combined to substantially increase customer lifetime value (LTV).
Strong % growth in USA & Japanese markets, but no actual figures.
UK stores - strong trading smaller towns/cities, largely offsetting weaker trading in commuter & tourist locations - makes sense, and probably the same for many other retailers/hospitality chains.
UK store rents - 30% of sites renegotiated to lower rents. Remaining 70% have lease renegotiation possible in next 24 months - encouraging.
Growth projects explained - new products, increased production, distribution centre almost doubled in size, etc.
Overall profitability - no figures given, but it’s positive -
The Board now anticipates underlying pre-tax profit will be higher than its previous expectations. Preliminary results are scheduled for 28 September 2021.
Liquidity - cash on hand (no figure provided), and access to £25m undrawn bank facility, expires Dec 2021.
Outlook - expecting more than half sales this year to come via digital. Step change in growth from USA & Japan (JV). Creating >250 jobs in the UK this year - that’s a lot extra overhead.
My opinion - HOTC is looking a lot more interesting now that growth has stepped up a gear, and more seems to be in the pipeline. I’m warming to this share. Maybe it’s expensive for a good reason? It’s quite tempting to pick up a small starter position, to tuck away for 5 years. HOTC is starting to look like it could be a long-term success, with international growth & strong online performance making it stand out. With such a big planned increase in overheads, there could be a long wait for profitability to achieve a level that justifies the valuation.
.

.
Jack’s section
Circassia (LON:CIR)
Share price: 32.95p (+9.83%)
Shares in issue: 418,203,781
Market cap: £137.8m
This is a pharmaceutical company that is streamlining its operations to focus on its core NIOX asthma product, with a new management team spearheaded by executive chairman Ian Johnson and including CFO Michael Roller. Both formerly worked at Bioquell.
NIOX is a medical device for fractional exhaled nitric oxide (FENO), which is a market of airway inflammation. This patented technology helps with point-of-care asthma diagnosis and management and ‘is the device of choice for both Clinical and Research use’.

It’s a huge market - 340m people are affected worldwide and the number is growing, while 50% of asthma is either misdiagnosed or not spotted at all.
The group has been heavily loss making in the past but reduced and refocused operations are expected to significantly close this gap in the coming years. The headcount has reduced from 385 to 150 and operating losses fell from £64m to £17m in FY20.

The emphasis now shifts from pharmaceuticals to medical devices. Circassia made the decision to hand back its COPD business to AZ, resulting in some $150m of debt getting written off and a balance sheet free of debt.

… the Board believes that, notwithstanding revenue visibility continuing to be limited, the Company's full year EBITDA performance is likely to be ahead of current market expectations.
Highlights:
- Revenue +27% to £14.5m
- NIOX business EBITDA positive for first time (excluding corporate costs)
- Net cash £11.3m
- Completion of runoff period for Tudorza and Duaklir
- Settlement of Beyond Air dispute, with potential upside to Circassia
Clinical revenues were up 16% to approximately £12.1m and up 10% on H2 2020, as more patients were able to visit their physician. Clinical sales in the first half of 2021 were around 84% of H1 2019 underlying sales.
H1 2021 Clinical revenue included a one-off £0.6m benefit arising from the final unwinding of certain historical trading arrangements in China. Stripping this out indicates revenue growth of just over 10%.
The Research business made a strong start to the year as clinical studies resumed. Revenues here more than doubled to £2.4m (H1 2020: £0.9m), were up 50% on H2 2020 (£1.6m), and up 9% on the first half of 2019 (£2.2m).
The COPD business was transferred back to AstraZeneca on 31 March 2021.
Fixed costs have been reduced in the sales and marketing strategy, with more emphasis on third party distribution. This has resulted in a 34% reduction in overheads, from almost £14.0m in H1 2020 to approximately £9.2m in H1 2021.
H1 2021 EBITDA has improved to approximately £0.5m for the Niox business (before corporate overheads) compared with an EBITDA loss of £4.8m in H1 2020.
Unaudited net cash at 30 June 2021 was £11.3m (31 December 2020: £7.4m) with a net cash outflow of £1.1m in the period. A total of £5.0m was raised in equity in March 2021.
ASubject to FDA approval of their product, the settlement reached with Beyond Air, Inc. will provide further cash resources of up to $16.5m over time.
Interim results are expected on the 16th of September 2021.
Conclusion
The continuing revenue of the reduced business is quite small compared to Circassia’s market cap of nearly £140m, so the aim now is top line growth and to take advantage of its significantly reduced cost base in the second half.
It’s still loss-making, but with a valuable product in a large market, and a wider IP portfolio behind that. NIOX is registered and reimbursed in all major markets and has close to 40m tests to date, with worldwide sales of more than 17,000 devices. The group says this is a dominant market position.
Meanwhile, around 90% of Circassia’s revenue comes from recurring sales of consumables. So top line growth should then provide good visibility for further investment. Gross margins are high - 50% for devices and 80% for consumables - and capex is low due to 3rd party manufacture.
So there’s clearly value here beneath the mountain of historic losses and the group’s evolving profile. Directors have bought a bit of stock.
Trading was hit by the pandemic but has steadily recovered.

This isn’t your usual financial profile of a high quality stock. It’s all buried underneath the wreckage of what appears to have been a mismanaged company until recently. But if Johnson et al. can complete the turnaround and reshaping of the business, Circassia looks to have a very strong product to invest in in the form of NIOX, so it’s worth keeping an eye on.

Source: Company Presentation
Solid State (LON:SOLI)
Share price: 902p (-9.8%)
Shares in issue: 8,553,504
Market cap: £77.2m
In terms of StockRanks, Solid State has been up there with the best of them for some time. It’s another one where had you bought in at the tail end of 2018 when the Ranks ticked up, you’d be sitting on a handsome profit by now.

It’s high QM in terms of factor profile.

The company itself is characterized more by a consistent strategy of organic investment, niche acquisitions, and steady growth over time - but that steady growth is more impressive when paired with the recent improving margins & returns on capital, and excellent cash conversion.

The group provides customers broad-based access to trusted electronic technology for demanding applications and extreme environments and has a commercial focus on high growth markets including security & defence, medical, green energy, transport, communications and industrial.
It has an operating track record stretching back 50 years and has been a listed company for more than two decades now.
Highlights:
- Revenue -1.6% to £66.3m,
- Operating margin +40bps to 6.5%; adjusted operating margin +110bps to 8.3%,
- Reported profit before tax +5% to £4.2m; adjusted PBT +14.9% to £5.4m,
- Reported earnings per share +15.7% to 46.4p; adjusted diluted EPS +18.1% to 54.7p,
- Underlying cash flow from operations -13.8% to £6.9m,
- Net cash -237.5% to -£4.4m,
- Dividend +28% to 16p,
- Open order book at 31 May +34.6% to £51m.
Adjustments relate to: non-cash charges arising from share-based payments and the amortisation of acquisition intangibles, non-recurring cash costs relating to the re-organisation of the Manufacturing division and acquisition costs, non-recurring profit from the sale of fully written down stock, and non-recurring tax credits arising primarily from prior year R&D claims and tax deductions on share options.
Stable revenue and increased profits is a good result over the Covid period relative to many other enterprises. There’s also a notable 28% increase in dividend - a far cry from the placings and temporary net losses we’ve come to expect elsewhere. The open order book increase of 34.6% provides further grounds for optimism.
There were two acquisitions in the year: Willow Technologies and Active Silicon, bringing with them enhanced technology to the portfolio and better international sales capabilities across the USA and Europe.
Internal development also continues, with the Solid State's battery pack and Battery Management Systems (BMS) offering, own brand computing products and portfolio of communications products. In-house Electromagnetic Compatibility (EMC) testing capabilities have also been established through its capital investment programme.
The group comments:
The Board is confident that the achievements of the last year and the post period end growth in open orders are a very good foundation going into the current financial year. The experience of our team, focus on structural growth markets and the balance sheet strength set Solid State aside from many in our sector, giving the Directors confidence in the mid-term prospects.
Conclusion
This continues to look like a well-run, growing small cap regardless of today’s share price reaction in my view.
The medium-term financial objective is to double fully diluted adjusted earnings from 30p to 60p per share over a five year period to March 2022 is on track. That would give an FY22 PE ratio of 16.35x.
Not particularly cheap, and after a strong run you could argue that the share price got a little ahead of itself given the more modest compound annual growth rates. But on the other hand, that run up is partially justified by a good track record and scope for upside earnings surprises.
On the whole, I find it a more interesting proposition with the shares marked down slightly.
There has been an accelerated growth rate recently, and management references ‘the significant opportunities for continued growth’ that lay ahead. As with other operators, there are currently short term supply challenges - this could be another reason for the market’s reaction to today’s announcement. It’s not the first company to be punished for flagging supply chain issues.
But the demand outlook for customised electronic solutions is robust and Solid State has a strong portfolio with scope for further investment in specialist skills and knowledge both through internal development and acquisition. International expansion is on the agenda, which signals a degree of ambition from the management.
However the share price reacts in the short term, this company strikes me as having the potential for steady longer term growth. It’s an illiquid stock so that makes it harder to anticipate how the share price will react in the coming days and weeks - all the more reason to keep tabs on it.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
always interested in anything Richard Leonard has to say
Seems to be some very strange price action today - don't usually bother about short term movement's but see Redde Northgate (LON:REDD) just went from 453 to 413 in a few hours (a drop of 9%). A few other of my holdings seen similarly inexplicable falls - Vertu Motors (LON:VTU) was down 6%.
I noticed same for Sylvania Platinum (LON:SLP) a drop of 6% on no news. I can only think it's re-opening jitters (Netherlands recently tried a 'big bang' re-opening and R number went to c.6), but I would think prospect of further restrictions would help Redde Northgate (LON:REDD)
Sylvania Platinum seems to be taking a beating over the last few months, again on no news. The price of Rhodium has dropped by nearly 50% from its highs earlier this year but still, the business remains significantly undervalued.
I know there is political instability in South Africa at the moment which will no doubt make some investors nervous. AA might be selling in the background too. Lots going on without any real news from the BoD at SLP.
Either way, business is ridiculously cheap considering EV stands at £260m with £60m cash in bank, generating £90m net profit this year potentially and even more cash.
Ahhhh right, the SA violence is probably the cause. Good shout.
There were posts on a couple of bulletin boards about takeover rumours earlier in the day. It sounded like twiddle twaddle. Hopefully so as I want to keep REDD in my portfolio for the long-term.
Yes Redde Northgate (LON:REDD) speculation is here but I have no idea of the legitimacy of this website
I think Betaville is an ex FT Alphaville writer and I regard the site as credible. Unfortunately so as a Redde holder who wants to keep holding.
The Vertu Motors PI presentation was rescheduled from today to 17th August without any comment on why and has probably spooked a few people. Hopefully completely innocuous
I wondered if it was the actual prices or the reporting that was erratic. Something was odd - I was getting quite different prices from different sources on a few shares.
I noticed Belvoir (LON:BLV) was down about 4% as I watched their very upbeat presentation on Yellowstone at noon. I added a few and happily they closed up a little on the day.
Given how quiet it is today.... anyone given any thought to the new Lords Group IPO?
A mini version of Travis Perkins albeit with a diverging strategy given the latter sale of the plumbing business and de-merger of the Wickes DIY business and Lords Groups plans to consolidate.
Has been well received and oversubscribed by institutions, raising £30m for future expansion and £20m for existing shareholders so doesn't seem like a top of the market grab for cash. CEO is largest shareholder I think so still plenty of skin in the game.
Haven't found any road show or IPO docs on it yet so not sure of profitability levels - if anyone can point me in direction that would be helpful and any informed thoughts on it?
Smiths News (LON:SNWS) I hold.
Revenues are down by 11% and an organic decline of 5% was anticipated as more news moves on line. Most of the decline has come from the non operation of their travel outlets during lockdown. Set against that there has been some very strong and effective cost reductions and the company is clearly very resilient, EBITDA is down by £1.25 Million. There is a limit as to how much cost can be taken out of any business. However, the business model is strong with 43 distribution centres to over 30,000 retail outlets and this is adaptable to other products. Apparently they do have some very advanced IT to manage their newspaper and books delivery services. They have a long term contract with the largest newspaper publisher News International. Voted top media supplier in the UK for the last 5 years.
I bought in May 2020 and the share value has increased by 89% over the last 15 months. I would probably not buy now as I do not expect a repeat of the share value gain this year, but I will hold for a further 6 months.
LPeC (Listed Private Capital) event featuring:
LPeC are an organisation whose members are investment companies that provide investors with access to high-performing PE and credit investments not normally accessible to retail, but offering (sometimes) greater growth opportunities than publicly listed assets. This is the first of a two part series. NB Private Equity and Gimv are particularly interesting. Video & podcast.
Part 2 will be available shortly, featuring BMO Global Asset Management, CVC Credit Partners Investment Management, and Oakley Capital Investments.
Other forthcoming PIWORLD webinars, register for all below here:
Accrol Group (LON:ACRL) full-year results webinar with Q&A, Thursday 15th July, 1.15pm.
Sosandar (LON:SOS) full-year results webinar with Q&A, Wednesday 21st July, 11.30am
Tekmar (LON:TGP) Capital Markest Day, Thursday 22nd July, 4.30pm
REARRANGED Vertu Motors (LON:VTU) investor presentation, Tuesday 17th August, 4.30pm
Stockopedia/PIWORLD StockSlam, Wednesday 8th September, 6pm
Richard Leonard's interview got a lot of attention this weekend, in spite of tennis and football, but do look at past PIWORLD interviews here. I think Stuart Widdowson and Edmund Shing (good for all investors, not just your kids!) are particularly good. There are over 100 interviews to enjoy. Doing these comes down to the amount of interest there is in them ...
Nb Private Equity Partners (LON:NBPE) today reported a 6.5% increase in latest NAV to continue their very strong run. Looks very good value on an almost 30% discount.
Hi Tamzin,
All of your investor interviews have been great and I always look forward to the next one being published. Please keep them coming - even if they don't always give some great ideas for further investigation the wisdom and experience of the interviewees always leaves me with a few points of learning and some great macro overviews.
K
Good to see the expected positive trading update from Vianet (Vnet:Lon). The company seems very well placed for upgrades as the lockdown ends on Monday and it's exposure to the hospitality sector puts it in a good place. A news release yesterday also seems to have gone unnoticed as the link is only visible to those watching developments in the sector like myself. Quote:
Pub group Young & Co's Brewery fell 0.3% to £16.10 following news that it had agreed to sell most of its tenanted estate in the Ram Pub Company to Punch Pubs & Co. for £53 million.
The deal would see Young's sell 56 of the 63 pubs in the Ram Pub Company and retain the other seven pubs for the long term.
This should be good news to Vianet since it's iDraught monitoring systems are used throughout the Punch group and should be rolled out in house. Assuming that the systems are not in place which I believe they are not. Vianet have done a great deal of work in preparation for the opening up from lockdown. They have worked with the sector to ensure contract continuity and have engineered software to capture a wealth of consumer information to help adopters in the sector use that data to thrive. One to watch and one I have taken a token stake in myself.
Solid State (LON:SOLI) final results in:
Revenue year on year at £66.3m (2020: £67.4m), profitability 110bps to 8.3%, adjusted fully diluted EPS up 18% to 54.7p (2020: 46.3p).
Dividend increased 28%
Order book reflecting 9.2% organic growth
But revenue down 1.6%
For a solid company on a PE 18 with a strong balance sheet, I think the market is being a bit cruel marking it down almost 10% this morning.
Interested in others views.
Solid State (LON:SOLI) but the profits and EPS are below forecasts? Even with in line profits, shares have been marked down on results day.
(I hold)
I was a little disappointed in these results given previous trading statements in Feb/Apr that were suggesting results were going to be ahead of expectations. I suppose they may have met those expectations (just), however the y-o-y comparison looks mediocre compared to their previous track record of revenue / profit growth and that may have spooked the market. They may be a victim of their previous success in this regard.
Over the medium/long term, I am still positive given the order book looks healthy / growing and hopefully COVID/Brexit disruption subsides. It will also be interesting if the acquisitions they made in FY21 can be shown to augment the business. That being said, another mediocre trading update in the near term could weigh on the share price heavily; will be monitoring closely!
Solid State (LON:SOLI) superbly run company in my opinion. Held them for a while. Results were fine, pretty much as expected and creditable given the pandemic issues, but order book for this coming year looks really strong. Research suggests 60p for this year, which would achieve their EPS doubling goal.
Trading a good 30% below peer group average though and yet I'd argue they are perhaps of higher quality than most so should be at least in line, if not commanding a premium. By end of this year forecast 15* earnings and back to net cash position doesn't feel demanding.
I like the way they grow using net cash to buy businesses, go moderately in debt and then straight to net cash the following year. This strategy plus a 2% dividend seems to work very well long term with no significant leverage ever taken on, so risk of a dud deal is limited. Appears to be a good use of shareholder funds. Management is original family linked with no intention of ruining their legacy.
Bear in mind the mark down this morning is on 35,000 shares total volume traded so that shows illiquidity of the stock : £350k worth of stock traded moving the market cap by £8m !! but actually I think this is just a few small shareholders taking profits after the recent leg up rather than anything else more significant. Fairly typical share price behaviour.
Solid State (LON:SOLI) FY results are out today, seem to be below forecasts at first glance, shares are down 10%.
Shield Therapeutics dropping like a stone, any thoughts on this please?
Hi Paul, I want to thank you for mentioning the book The Art of Execution, just finished reading it and it is probably the best investment book I have read (believe me I have read so many). It says on the cover “I wish I had read it 30 years ago” - couldn’t agree more. Keep up the fantastic work.
Mark
I read The Art of Execution last year and really enjoyed it. I also recommend Excellent Investing by Mark Simpson, which offers practical guidance for building and maintaining a portfolio.
Smiths News (LON:SNWS) - "one-off" £1m boost from the Euros may well be repeated (or even beaten) next year with the football world cup, and perhaps (likely to a lesser extent) with the Olympics starting soon. I hold.
Wasn't Circassia (LON:CIR) one of Woodford's ? or am i confusing it with something else ? I do know it has bitten me before.
Are you intending to look at Omega Diagnostics (LON:ODX) today (i hold) Thanks
Circassia (LON:CIR) was indeed in the Woodford stable and caused investors some heart ache.
https://portfolio-adviser.com/...
Position was sold down in the scramble for liquidity and is no longer in the Schroder Uk Public Private Trust (LON:SUPP) portfolio so far as I can tell.
Gus
I thought Circassia was an honest failure. Their cat allergy treatment appeared to work - it was just that the placebo worked equally well in the trials.
My theory is that some people who said they had cat allergies didn’t really but needed an excuse to stop their other half getting one. Easier to say they have an allergy than to admit they hate cats. Either way the placebo effect is often surprising strong.
That’s not how clinical trials work. You have to have demonstrable allergic response (caused by investigators- minor) to be included in first place.
More likely explanation is the drug didn’t work.
Agree on Smiths News (LON:SNWS)
Publishers are steadily increasing cover prices to mitigate volume reductions. Those who like print are willing to pay for it, so it means there is life in the old dog yet! Smiths News (LON:SNWS) gets a fixed percentage of that cover price. Therefore, any slowdown in print sales decline coupled with price increases will be great news for £SNWS. But, as you rightly say, this can't last forever.
Worth also exploring Menzies Distribution, the other player in this market. Not listed and PE backed, they are steadily buying up other distributors of food etc. Andy Clarke, former ASDA CEO is chairman, and Charles Wilson of Booker cash and carry fame has invested and joined the board. Their aim will be to be the sole distributor which will stray into regulated monopoly territory but this does imply an interesting exit for Smiths News (LON:SNWS)
Smiths News (LON:SNWS)
I’ve looked at the Radio Times before - the key metric is the increase in cover price to offset the death rate of the underlying customer base !
Renold (LON:RNO) contract award - not sure how pleased to be (I hold). It’s ‘in line with expectations’ but also ‘represents a significant extension’.
Good but not sparkling results from £ECSC. Chief Technical Officer goes on part time.
Ecsc (LON:ECSC) cannot quite seem to reach takeoff. Cash burn has been significantly reduced - hopefully the company can continue to grow without the need to come back for shareholders for more funds now. But growth seems lacklustre, with H1 revenues flat on H2 last last year, despite the seemingly positive background of continued cyber attacks. I hold given the cheap valuation and the chance for the share price to rise sharply, if the company can show sustained strong growth.
Redde Northgate (LON:REDD) - as a shareholder I was wondering about the effect that the changeover to electric vehicles may have on their fleet. They have announced today that they have acquired what I presume is a fairly small business at present which can be seen at www.chargedev.co.uk. It shows they at least have these developments in mind and it could be another source of income going forward.
Redde Northgate (LON:REDD) I think this is a positive step to move into the EV charging space. Following other recent acquisitions, this management team is pursuing cross-selling opportunities to its customer base and having expertise in the EV charging space will be important going forward.
It looks like a small acquisition as the acquired business only has 20 staff. As a holder, it's always disappointing to see an RNS without detailing the price paid. It is probably more about securing expertise and know-how in this rapidly changing area.
Redde Northgate (LON:REDD) I agree. Charged EV grew from a small family business so well done to the founders. It looks like an “acquihire” to me - the sort of thing the Apples of this world do to buy in capabilities. As a Redde holder I’m pleased to see it.
Redde Northgate (LON:REDD) also nice to see the 99 stockrank now the latest results are in!
For shareholders it's good to see Redde Northgate (LON:REDD) progress in this area. Firstly from a practical point of view for fleet managers and also Redde manages their data which helps them optimise their EVs, plus their ESG credentials are seen to be good, which is ever more important today. Plc A no longer wants to deal with Plc B unless they have good ESG. Redde ticks the boxes here.
I really like Eenergy (LON:EAAS)
The trading update is positive and it is showing good trends in terms of revenue, adjusted EBITDA and adjusted PBT.
They look to have the right people on board. A very strong CFO in Ric Williams who I believe was the M&A partner at Deloitte. They have also brought on another guy with a very strong M&A background.
The recruitment suggests to me that the M&A activity will ramp up and they have good organic growth within the business.
I hold this and will continue to do so.
My morning smallcap tweet: Lots of beats
Zoo Digital (LON:ZOO) Eenergy (LON:EAAS) Craneware (LON:CRW) Vianet (LON:VNET) DP Poland (LON:DPP) Hotel Chocolat (LON:HOTC) ECSC (LON:ECSC) Smiths News (LON:SNWS) City of London Investment (LON:CLIG) Kier (LON:KIE) Circassia (LON:CIR) Renold (LON:RNO) Proton Motor Power Systems (LON:PPS) EMIS (LON:EMIS) Omega Diagnostics (LON:ODX), Symphony Environmental Technologies (LON:SYM), Ebiquity (LON:EBQ)
Zoo Digital (ZOO) FY(Mar) rev up 33%, op profit $1m (-$0.6m) but pretax -$3.6m (breakeven) after non-cash fair value movement on embedded derivative of $3.5m. Outlook: "Trading in the first quarter of FY22 has been strong and ahead of the prior year period. Based on current visibility, we expect to deliver significant growth in the first half of FY22." [SP=125.58 Cap=102m]
eEnergy (EAAS) guides FY(June) in line and FY22 rev materially ahead of market expectations but FY22 adj pretax c.10% below market expectations because it has "brought forward investment in group management capability alongside investing in the development of MyZeERO, as well as committing to additional sales and marketing expense." [SP=20.64 Cap=51m]
Craneware (CRW) guides FY(June) rev up >5% and adj EBITDA >6%. Outlook: "New Sales of approximately 40% to over $42m (FY20: $30.4m). In accordance with Craneware's revenue recognition policy, the majority of the revenue resulting from both new sales and existing contract renewal will be recognised over future period." [SP=2180 Cap=714m]
Vianet (VNET) AGM stmt: Q1 profits higher than anticipated. Both divisions expected to return to more normal trading during H2. [SP=102.08 Cap=30m]
DP Poland (DPP) June Dine-in business up 25% but down 24% on 2019. LFL System sales up 5% but down 2% on 2019. [SP=8.44 Cap=49m]
Hotel Chocolat (HOTC) guides FY(June) underlying pretax higher than its previous expectations. Rev up 21% and 24% on 2019. [SP=374 Cap=471m]
ECSC (ECSC) guides H1(june) rev up 15% to £3m. [SP=81.6 Cap=8m]
Smiths News (SNWS) guides FY(Aug) adj EBITDA ahead of market expectations with footie giving a one-off benefit of c. £1m. [SP=42.5 Cap=105m]. I hold.
City of London Investment Group (CLIG) guides FY(June) EPS up 30% and final div 22p up 10%. [SP=540 Cap=274m]
Kier (KIE) guides FY(June) moderately ahead of mgmt expectations. "Group is confident that it now has the platform to achieve its medium-term targets of: Revenue: £4.0 - 4.5bn; Adjusted operating profit margin: c. 3.5%; Cash conversion of operating profit: c. 90%." [SP=129.8 Cap=579m]
Circassia (CIR) guides FY(Dec) EBITDA ahead of market expectations. H1 rev up 27%. [SP=30 Cap=125m]
Renold (RNO) £11m contract over 8 years from the Royal Navy. [SP=23 Cap=52m]
Proton Motor Power (PPS) wins a fifth order from GKN Powder Metallurgy. No £££. [SP=51.4 Cap=398m]
EMIS (EMIS) guides H1(June) slightly ahead of mgmt expectations. [SP=1196 Cap=757m]
Omega Diagnostics (ODX) FY(Mar) rev £8.7m, broadly in line. [SP=47.5 Cap=87m]
In line: Symphony Environmental Technologies (LON:SYM) Ebiquity (LON:EBQ)
Webinar today with management of Belvoir (LON:BLV) at 12pm.
Find out about the state of the housing market, prospects for further growth and how important financial services could be going forward. This stock has been a great performer over the past year - find out what's in store going forward.
Register here
paul - It is indeed time for new photos, personally I thought the wild look suited you well !
Pre close trading update out of CLIG today. Incredible clarity as we have come to expect from this company. I hold.
Diluted EPS 38.8p v 29.5p for the full year; a fine result but below what analysts were forecasting.
Full year divi 33p v 30p.
This is a cyclical stock, so for me the valuation is fair. There seem to be signs of rotation out of emerging markets, despite superior growth rates.
I do like City Of London Investment (LON:CLIG) but worth highlighting that they are seeing outflows across all their strategies, albeit fairly modest. On the positive side, performance seems to be good so they should hopefully see a return to positive flows at some point.
Decent trust but the spread can be wide at times but occasionally nearer 1% bid offer so timing the buy/sell can be tricky
Yes agree with the clarity on City Of London Investment (LON:CLIG) - we are basically told the key results 13 days after year end! Well done to the company on that.
I am a bit surprised to see this below analysts' expectations given Hardman & Co for example only stuck out their last note in April. What I don't know from this update though is whether the analysts and the company were using the same measure for 'underlying' - you would have thought so given the main exceptional charge is relating to the merger, but I would need to see any analyst updates today.
Hopefully we see a big increase in EPS for FY22 when the full impact of the merger is felt but even at c.39p EPS this is reasonably priced at about 14x for a lovely sustainable dividend.
The transparency and the 6% dividend make this a long-term hold for me.
Just checking the numbers, the outflows were actually 8.5% of opening AUM so not insignificant - is this not a concern? CLIG are essentially a fund of funds manager so not particularly niche. Asset allocators increasingly tend to favour either very low costs passive or more specialist/higher fee strategies - CLIG seem to fall somewhere down the middle.
I wonder if the CLIG outflow is from the US business Karpus that they merged with last summer. Reverse synergies?
No if you look at the table in today's update there are outflows across all strategies (Karpus are broken out as separate strategy so you can see it wasn't just that part of the business).